
- Home
- »
- Advanced Interior Materials
- »
-
Pipe Insulation Market Size, Share, Trends Report 2026-2033GVR Report cover
![Pipe Insulation Market (2026 - 2033)Report]()
Pipe Insulation Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (Cellular Glass, Elastomeric Foam, Fiberglass, Others), By Application (Industrial, Building & Construction, District Energy System), By Region, And Segment Forecasts
Market Size, 2025
$10.5BMarket Estimate, 2026
$11.0BMarket Forecast, 2033
$16.4BCAGR, 2026–2033
5.8%Pipe Insulation Market Summary
The global pipe insulation market size was valued at USD 10.5 billion in 2025 and is projected to grow from USD 11.0 billion in 2026 to USD 16.4 billion in 2033, at a CAGR of 5.8% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 34.0% in 2025. Rising awareness pertaining to energy conservation among consumers is expected to drive the market over the forecast period.
Key Market Trends & Insights
- By material: The polyurethane & polyisocyanurate foam segment held the largest market share of around 22.0% in 2025.
- By application: The industrial segment held the largest market share of over 39.0% in 2025.
Regional Insights
- Largest regional market: Europe (34.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 10.5 Billion
- Estimated market size in 2026: USD 11.0 Billion
- Projected market size by 2033: USD 16.4 Billion
- CAGR (2026-2033): 5.8%
The market witnessed a severe downfall in investments in the industrial sector owing to the pandemic, thereby impacting overall growth. In addition, a dramatic fall in crude oil prices led to a drop in fiscal resources for oil-producing countries, which affected the product demand from the oil & gas sector. The market in Asia Pacific is expected to witness exponential growth over the forecast period on account of the rising number of industries in economies, such as China and India.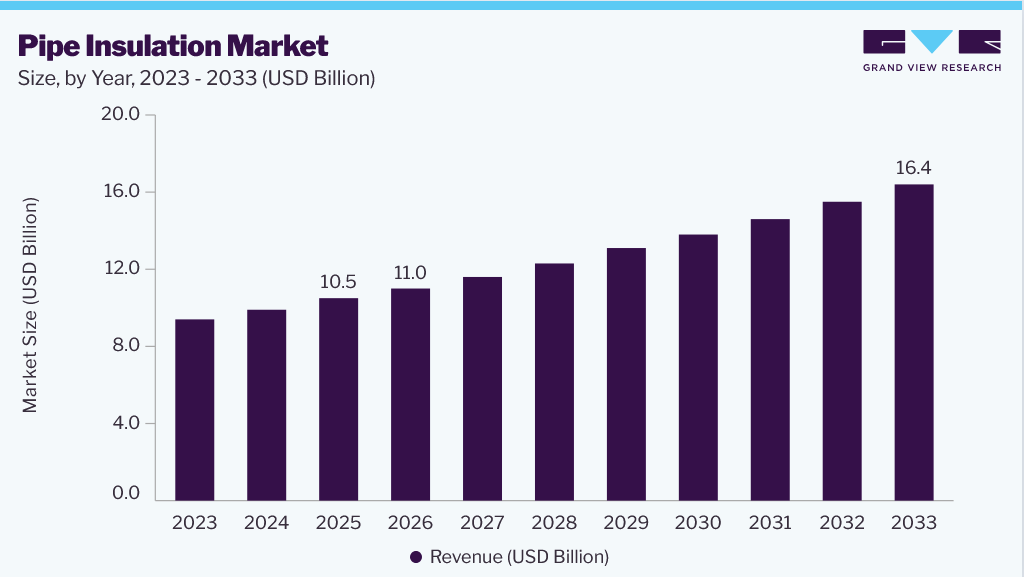
Rapid urbanization coupled with the rising demand for residential and commercial construction is anticipated to further fuel the market growth. Increasing adoption of district heating systems, driven by rising electricity tariffs, rising environmental awareness, and technological advances is expected to propel market growth in the U.S. In addition, rising investments in the expansion of gas liquefaction terminals are expected to drive the demand for pipe insulations over the forecast period. The presence of a large number of manufacturers and service providers, coupled with the easy availability of raw materials and easy installation processes, has resulted in intense market competition.
The price structure for pipe insulation varies with respect to production processes and raw materials used. The growing demand for pharmaceutical and cosmetic products is driving the expenditure on capacity additions by major pharmaceutical companies. Process pipes form an integral component in these production facilities and are expected to generate significant demand for pipe insulation over the forecast period. Corrosion under insulation has been one of the major challenges faced by the industry. It is a localized form of external corrosion that occurs on carbon, low alloy steel, and stainless-steel pipes operating at temperatures above 80° Celsius.
If not detected and prevented in time, CUI may cause the pipe to leak and lead to piping failure. The manufacturers are largely dependent on reliable suppliers with high goodwill on account of past product procurement, making it moderately difficult for new entrants to penetrate the market. In addition, the industry has a presence of several well-established players with a strong financial base. This is anticipated to limit the entry of new players. Moreover, high initial investments required to set up the business are expected to further restrict new entrants.
Market Dynamics
The increasing emphasis on energy efficiency across the industrial, commercial, and residential sectors is significantly driving global demand for pipe insulation materials. Pipe insulation plays a critical role in minimizing heat loss and energy consumption in HVAC systems, process industries, refrigeration systems, and district heating networks. Rising energy costs and stringent regulations on building energy performance are prompting industries and infrastructure developers to adopt advanced insulation solutions to improve operational efficiency and reduce carbon emissions. In addition, growing investments in green buildings and sustainable construction practices are further supporting market growth.
The expansion of industrial infrastructure across sectors such as oil & gas, chemicals, power generation, food processing, and pharmaceuticals is also driving increased demand for pipe insulation. Rapid urbanization and infrastructure modernization in emerging economies are driving the installation of heating, cooling, and plumbing systems that require efficient thermal insulation. Furthermore, the increasing development of LNG facilities, data centers, and cold chain logistics infrastructure is accelerating the adoption of high-performance insulation materials capable of operating under extreme temperature conditions. Continuous advancements in insulation technologies, including low-thermal-conductivity materials and moisture-resistant solutions, are further enhancing product adoption across end-use industries.
The pipe insulation market faces challenges associated with volatility in raw material prices, particularly for petrochemical-based insulation materials such as polyurethane foam, elastomeric foam, and polystyrene products. Variations in crude oil prices and supply chain disruptions can significantly impact manufacturing costs and product pricing. In addition, pipe insulation installation often requires skilled labor and regular maintenance to ensure long-term thermal performance and moisture protection, particularly in complex industrial systems. These factors, along with competition from low-cost alternatives and project cost sensitivity in developing markets, may restrain market growth to a certain extent.
Analyst Perspective
The pipe insulation market is on a stable growth path, boosted by increased demand from industries for enhanced efficiency (energy, emission control) and thermal control of industrial & building infrastructure. It is witnessing strong growth from segments such as oil and gas, chemicals, HVAC and district energy systems due to the need for heat conservation. Increased urbanization and development in the developing countries such China, India etc., also serve as a primary growth driver and Asia Pacific region is emerging as the fastest growing market. Price volatility of raw materials and challenging installation requirements pose to be key concerns, the industries are shifting toward newer and cost effective insulation solutions.
Material Insights
Polyurethane & polyisocyanurate foam led the market and accounted for over 22.0% share of the revenue in 2025. The product is typically used in pipe insulation applications as it can restrict the absorption of air, water, and gas. The material is commonly used in applications below 50°F as it offers excellent dimensional stability over a wide temperature range. Cellular glass is used in various applications, such as in heat transfer fluid systems, chemical processing systems, ductwork & commercial pipework, storage tanks, and in many other application areas. The material exhibits consistent insulating efficiency, low vapor permeability, fire protection, and high compressive strength.
Fiberglass is widely used in insulation systems due to its lower cost and easy installation. The material is used in the automotive and construction industries in providing insulation solutions. The material is widely used to insulate copper, iron, and PVC pipes in industrial, commercial, and institutional buildings. The demand for elastomeric foam insulation is expected to grow owing to its properties, such as moisture retention and strong water vapor permeability. The demand for elastomeric foam has witnessed an upward trend over the past few years due to rising environmental concerns and strict government regulations regarding reducing carbon emissions since the material does not contain any formaldehyde or fibers and has low VOC emission levels.
Application Insights
The industrial application segment led the market and accounted for about 39.0% share of the revenue in 2025. Escalating demand for piping systems in various industries, such as petrochemical, oil & gas, power generation, chemical, and wastewater treatment, is estimated to augment segment growth. The product is used in oil pipelines to provide enhanced safety, particularly in onshore pipelines. The increasing population, coupled with rapid urbanization, is likely to propel the product demand in building & construction applications. The growth of the construction sector and stricter energy-efficiency norms are projected to positively influence the demand further. In addition, the emerging trend of sustainable buildings is one of the primary factors driving the growth of pipe insulation in buildings.
District energy systems have been adopted across the globe as an effective solution to connect thermal storage, renewables, power grids, waste heat, and heat pumps, thus ensuring sustainable heating and cooling. The systems use pre-insulated pipes for the distribution of produced streams and supply steam or hot water for cooling building spaces. Insulated piping systems are the major components of district energy systems. Insulated pipes used in these systems are made from eco-friendly materials. With the rapid growth of district energy systems, the demand for pipe insulation is also expected to grow over the forecast period.
Regional Insights
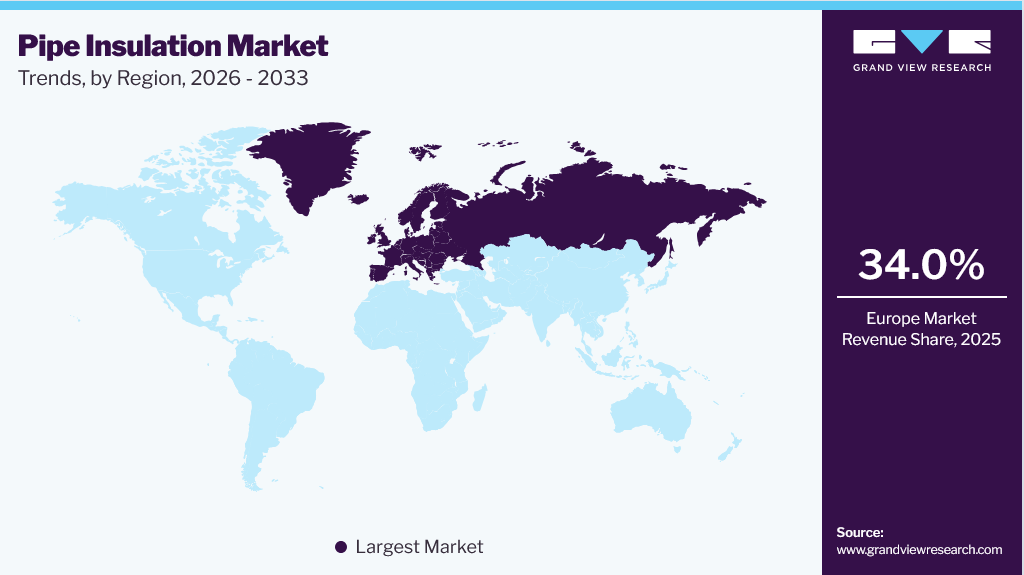
Europe dominated the market and accounted for more than 34.0% of the total revenue share in 2025. This can be attributed to the rapidly increasing number of construction and infrastructural activities coupled with the rising installation of district energy systems in economies, such as Germany, the UK, and Spain. Growing domestic consumption of food & beverages and pharmaceutical products is driving investments in the respective manufacturing sectors, thereby propelling the demand for process pipes and pipe insulation materials in North America. In addition, rising product demand for residential applications due to climatic conditions is anticipated to benefit the industry growth.
Asia Pacific Pipe Insulation Market Trends
Asia Pacific is expected to witness the fastest growth rate over the forecast period owing to the growing investments in the chemical processing industry. In addition, rising demand from the oil & gas sector, coupled with their increasing LNG regasification capacities to meet future demand, is expected to propel the market growth. Though the chemical industry holds an important position in the manufacturing sector of Brazil, the prevailing stagnant economic conditions have negatively impacted the overall investments in the manufacturing sector, thereby affecting the demand for pipe insulation. In addition, the global pandemic delayed the economic recovery and affected the investment scenario.
Key Pipe Insulation Market Company Insights
The industry is highly fragmented owing to the presence of various players. Key companies are highly focused on providing eco-friendly and diversified product portfolios to their customers. The companies also emphasize the adoption of raw materials to maintain a steady supply coupled with the cost-effectiveness of the overall pipe insulation system. Small companies often rely on channel intermediates, such as brokers and suppliers, to perform many of the marketing functions due to a lack of resources. Established players have their distribution and sales channel through which they supply products to end-users.
Key Pipe Insulation Companies
The following key companies have been profiled for this study on the pipe insulation market.
-
Armacell
-
Lydall, Inc.
-
Kingspan Group
-
Owens Corning
-
Huntsman International LLC
-
Saint-Gobain Group
-
ROCKWOOL A/S
-
Johns Manville
-
Knauf Insulation
-
BASF
-
Covestro AG
-
Beijing Coowor Network Technology Co., Ltd.
-
NMC International SA
-
Gilsulate International, Inc.
-
Sekisui Foam International
-
Omkar Puf Insulation Pvt. Ltd.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Armacell, Kingspan Group, Huntsman International LLC, Saint-Gobain Group
- Focus on large-scale insulation production and global expansion.
- Investment in energy-efficient and high-performance insulation solutions.
- Strong global presence and established distribution networks.
- Broad product portfolio and strong brand recognition.
- Exposure to raw material price fluctuations.
- Dependence on construction and industrial sector demand.
Emerging Players: Wincell Insulation Co., Ltd., NMC International SA, Gilsulate International, Inc.
- Focus on regional expansion and customized insulation solutions.
- Emphasis on niche applications and flexible manufacturing.
- Strong focus on specialized and energy-efficient insulation products.
- Greater flexibility in addressing regional demand.
- Limited global market presence and production scale.
- Challenges in competing with established multinational players.
Recent Developments
-
In April 2025, Knauf Insulation announced expansion of its portfolio with the addition of novel pipe and pipe & tank insulation products, featuring low emissions of volatile organic compounds, low dust levels post installation and more.
Pipe Insulation Market Report Scope
Report Attribute
Details
Market size in 2025
USD 10.5 billion
Estimated market size in 2026
USD 11.0 billion
Projected market size by 2033
USD 16.4 billion
Growth rate
CAGR of 5.8% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, application, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Brazil; Argentina
Key companies profiled
Armacell; Lydall, Inc.; Kingspan Group; Owens Corning; Huntsman International LLC; Saint-Gobain Group; Rockwool A/S; Johns Manville; Knauf Insulation; BASF ; Covestro AG, Beijing Coowor Network Technology Co., Ltd.; NMC International SA; Gilsulate International, Inc.; Sekisui Foam International; Omkar Puf Insulation Pvt. Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Pipe Insulation Market Report Segmentation
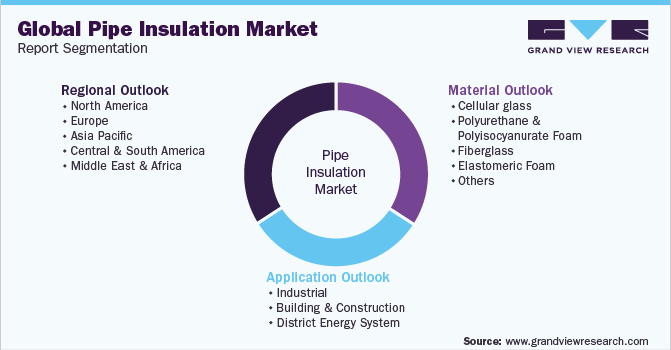
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global pipe insulation market report on the basis of material, application, and region:
-
Material Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cellular glass
-
Polyurethane & Polyisocyanurate Foam
-
Fiberglass
-
Elastomeric Foam
-
Others
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Industrial
-
Building & Construction
-
District Energy System
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Analysis
Benchmarking of key pipe insulation manufacturers based on product portfolio, insulation material type, production capacity, geographic presence, pricing strategy, distribution network, and strategic developments.
Enable comparison of competitive positioning, identification of strategic gaps, and assessment of product differentiation and expansion strategies across the pipe insulation market.
Regional Extension
Expanded regional analysis of the pipe insulation market covering industrial infrastructure development, energy efficiency regulations, construction activity, and insulation adoption patterns across key regions and countries.
Support identification of high-growth regional markets and infrastructure investment hubs. Enable understanding of region-specific demand trends, regulatory frameworks, and growth opportunities.
Opportunity Analysis
Evaluation of growth opportunities across industrial processing, oil & gas, district energy networks, refrigeration, and commercial construction applications. Analysis includes demand outlook by end-use industry and insulation material adoption trends.
Identify high-growth applications and emerging demand sectors. Support strategic expansion planning, product development initiatives, and investment prioritization in the pipe insulation market.
Frequently Asked Questions About This Report
The global pipe insulation market size was estimated at USD 10.5 billion in 2025 and is expected to reach USD 11.0 billion in 2026.
The global pipe insulation market is expected to grow at a compound annual growth rate a CAGR of 5.8% from 2026 to 2033 to reach USD 16.4 billion by 2033.
industrial application dominated the pipe insulation market with a share of 39.0% in 2025.
Key players include Armacell; Lydall, Inc.; Kingspan Group; Owens Corning; Huntsman International LLC; Saint-Gobain Group; Rockwool A/S; Johns Manville; Knauf Insulation; BASF ; Covestro AG, Beijing Coowor Network Technology Co., Ltd.; NMC International SA; Gilsulate International, Inc.; Sekisui Foam International; Omkar Puf Insulation Pvt. Ltd.
Europe dominated with a 34.0% revenue share in 2025.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs — add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


