
- Home
- »
- Sensors & Controls
- »
-
Power Management IC Market Size & Share Report, 2033GVR Report cover

Power Management IC Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Linear Regulators, Switching Regulators, Battery Management ICs, Power Supply ICs), By Industry Vertical (Consumer Electronics, Automotive), By Region, And Segment Forecasts
Market Size, 2025
$42.6BMarket Estimate, 2026
$45.2BMarket Forecast, 2033
$75.0BCAGR, 2026–2033
7.5%Power Management IC Market Summary
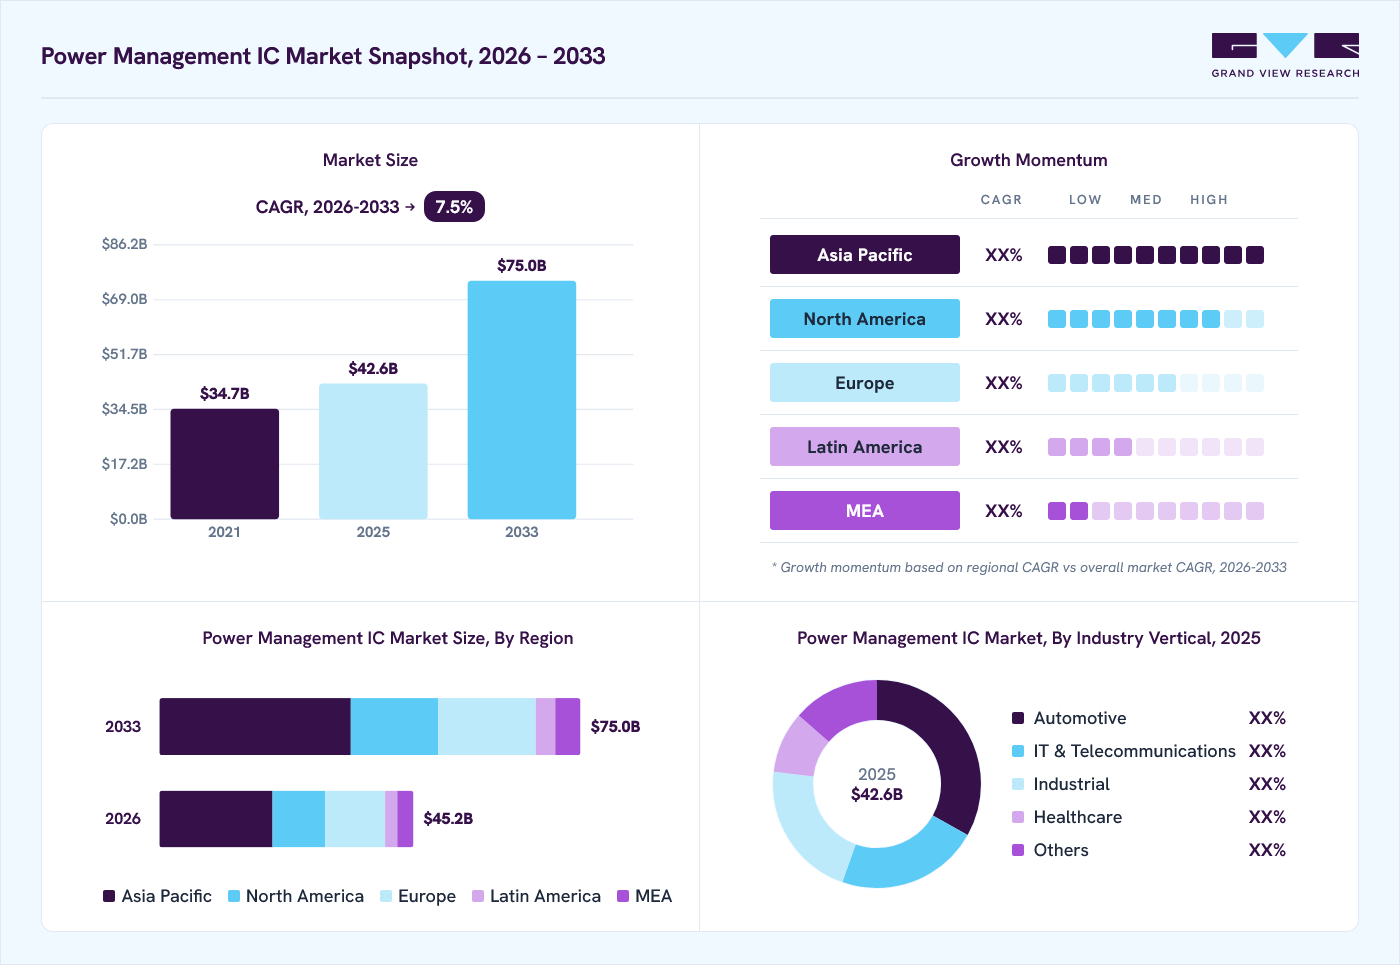
The global power management IC market size was valued at USD 42.6 billion in 2025 and is projected to grow from USD 45.2 billion in 2026 to USD 75.0 billion by 2033, at a CAGR of 7.5% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 44.3% in 2025. Power management integrated circuits (PMICs) are essential components in electronic devices that efficiently manage and control the flow of electrical power.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Switching regulators segment dominated the market, with a revenue share of 25.2% in 2025.
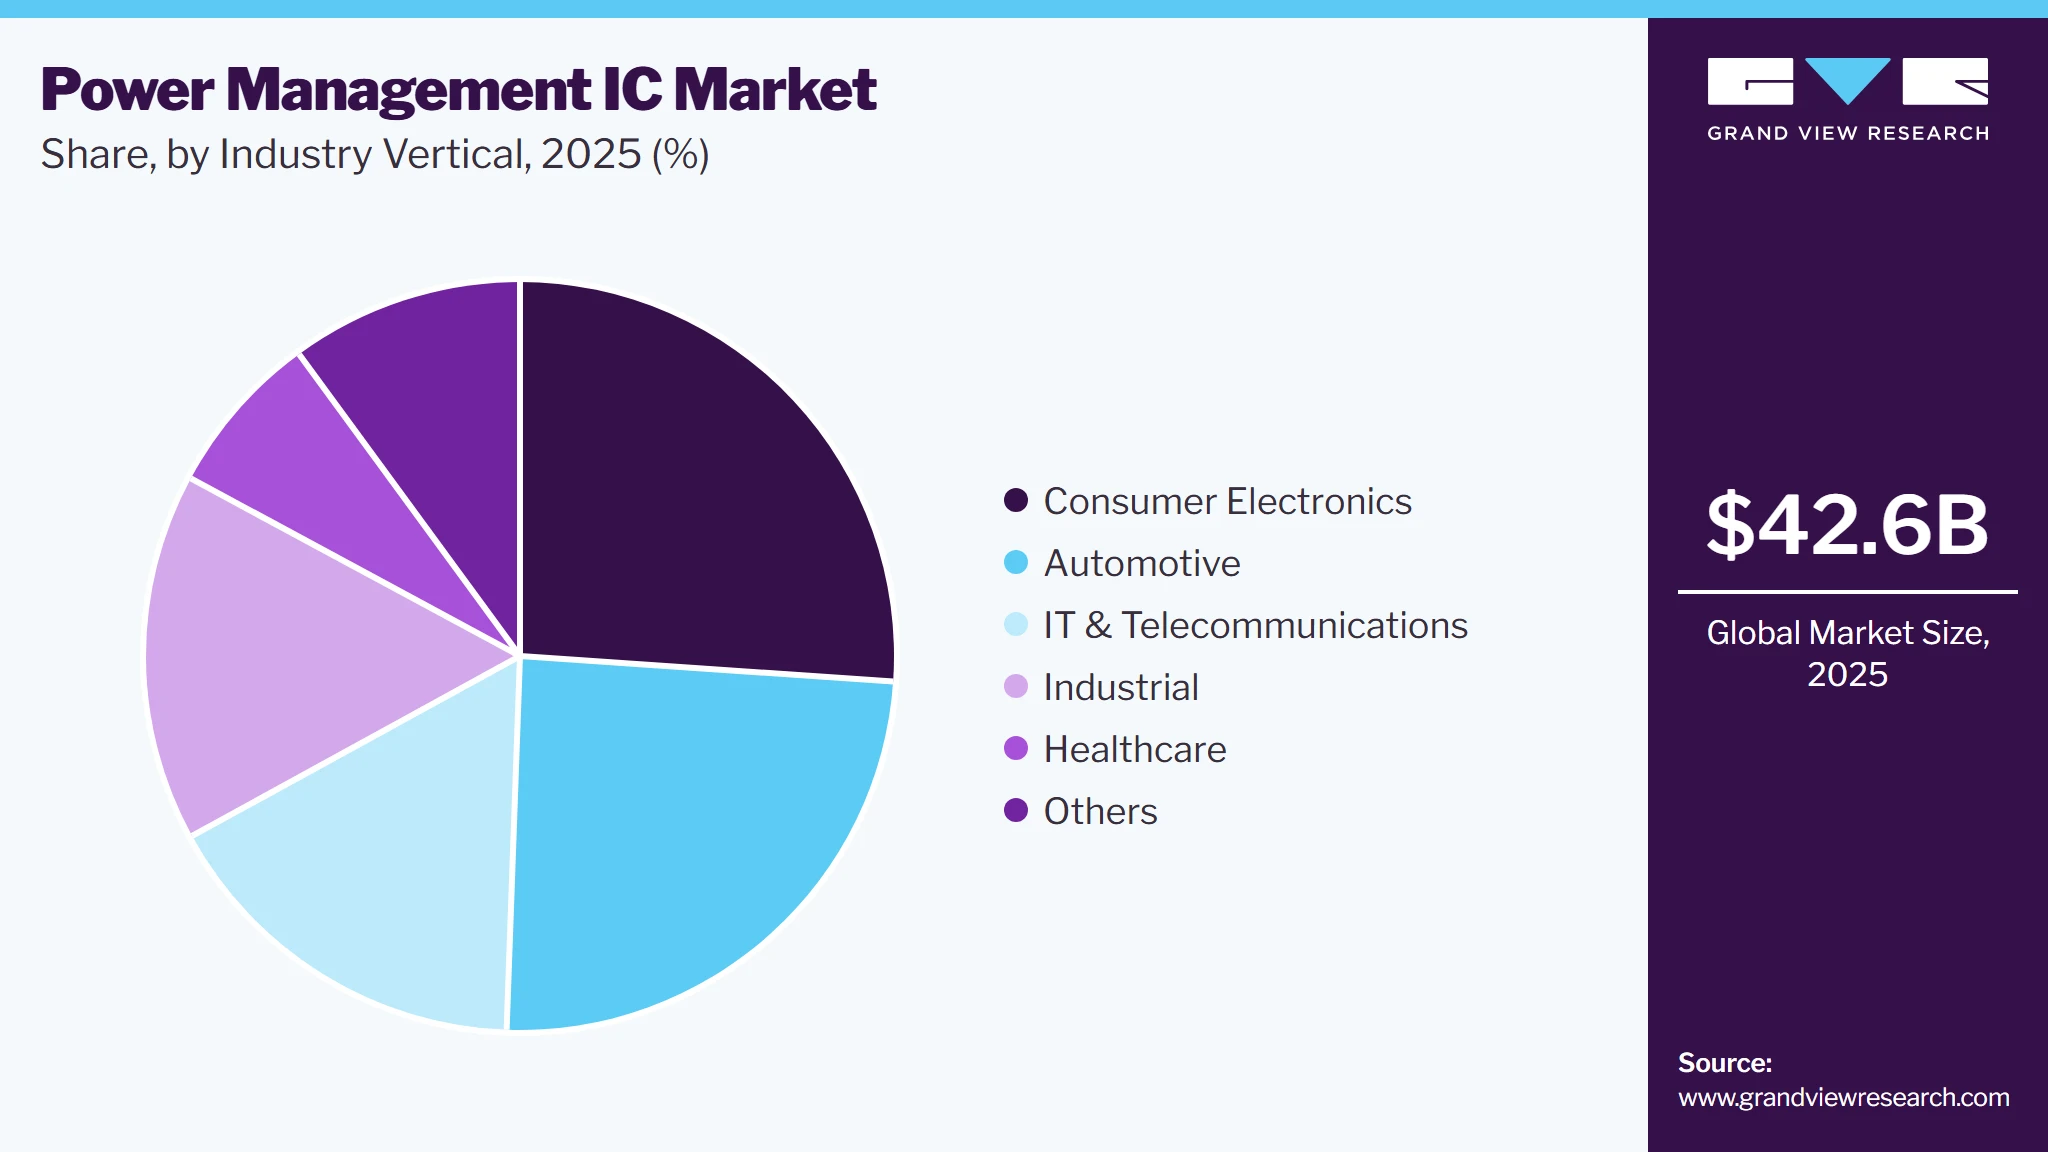
- By industry vertical: Consumer electronics segment held the largest market share of 26.1% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (44.3% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 42.6 Billion
- Estimated market size in 2026: USD 45.2 Billion
- Projected market size by 2033: USD 75.0 Billion
- CAGR (2026-2033): 7.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
They play a crucial role in optimizing battery life, improving device performance, and ensuring safe operation. PMICs are used in a wide range of applications, including smartphones, laptops, tablets, wearable devices, automotive electronics, industrial equipment, and consumer appliances. The power management integrated circuit market is experiencing rapid growth due to several key trends. The demand for smaller, more portable electronic devices has driven the development of PMICs with reduced form factors and increased integration. As electronic systems become more complex, PMICs are required to handle diverse power requirements and provide advanced features such as fast charging and battery management. The growing focus on energy efficiency has led to the development of PMICs with higher efficiency and lower power consumption. In addition, the proliferation of IoT devices and the rapid growth of the EV market have created significant demand for PMICs to power various components and manage complex power requirements.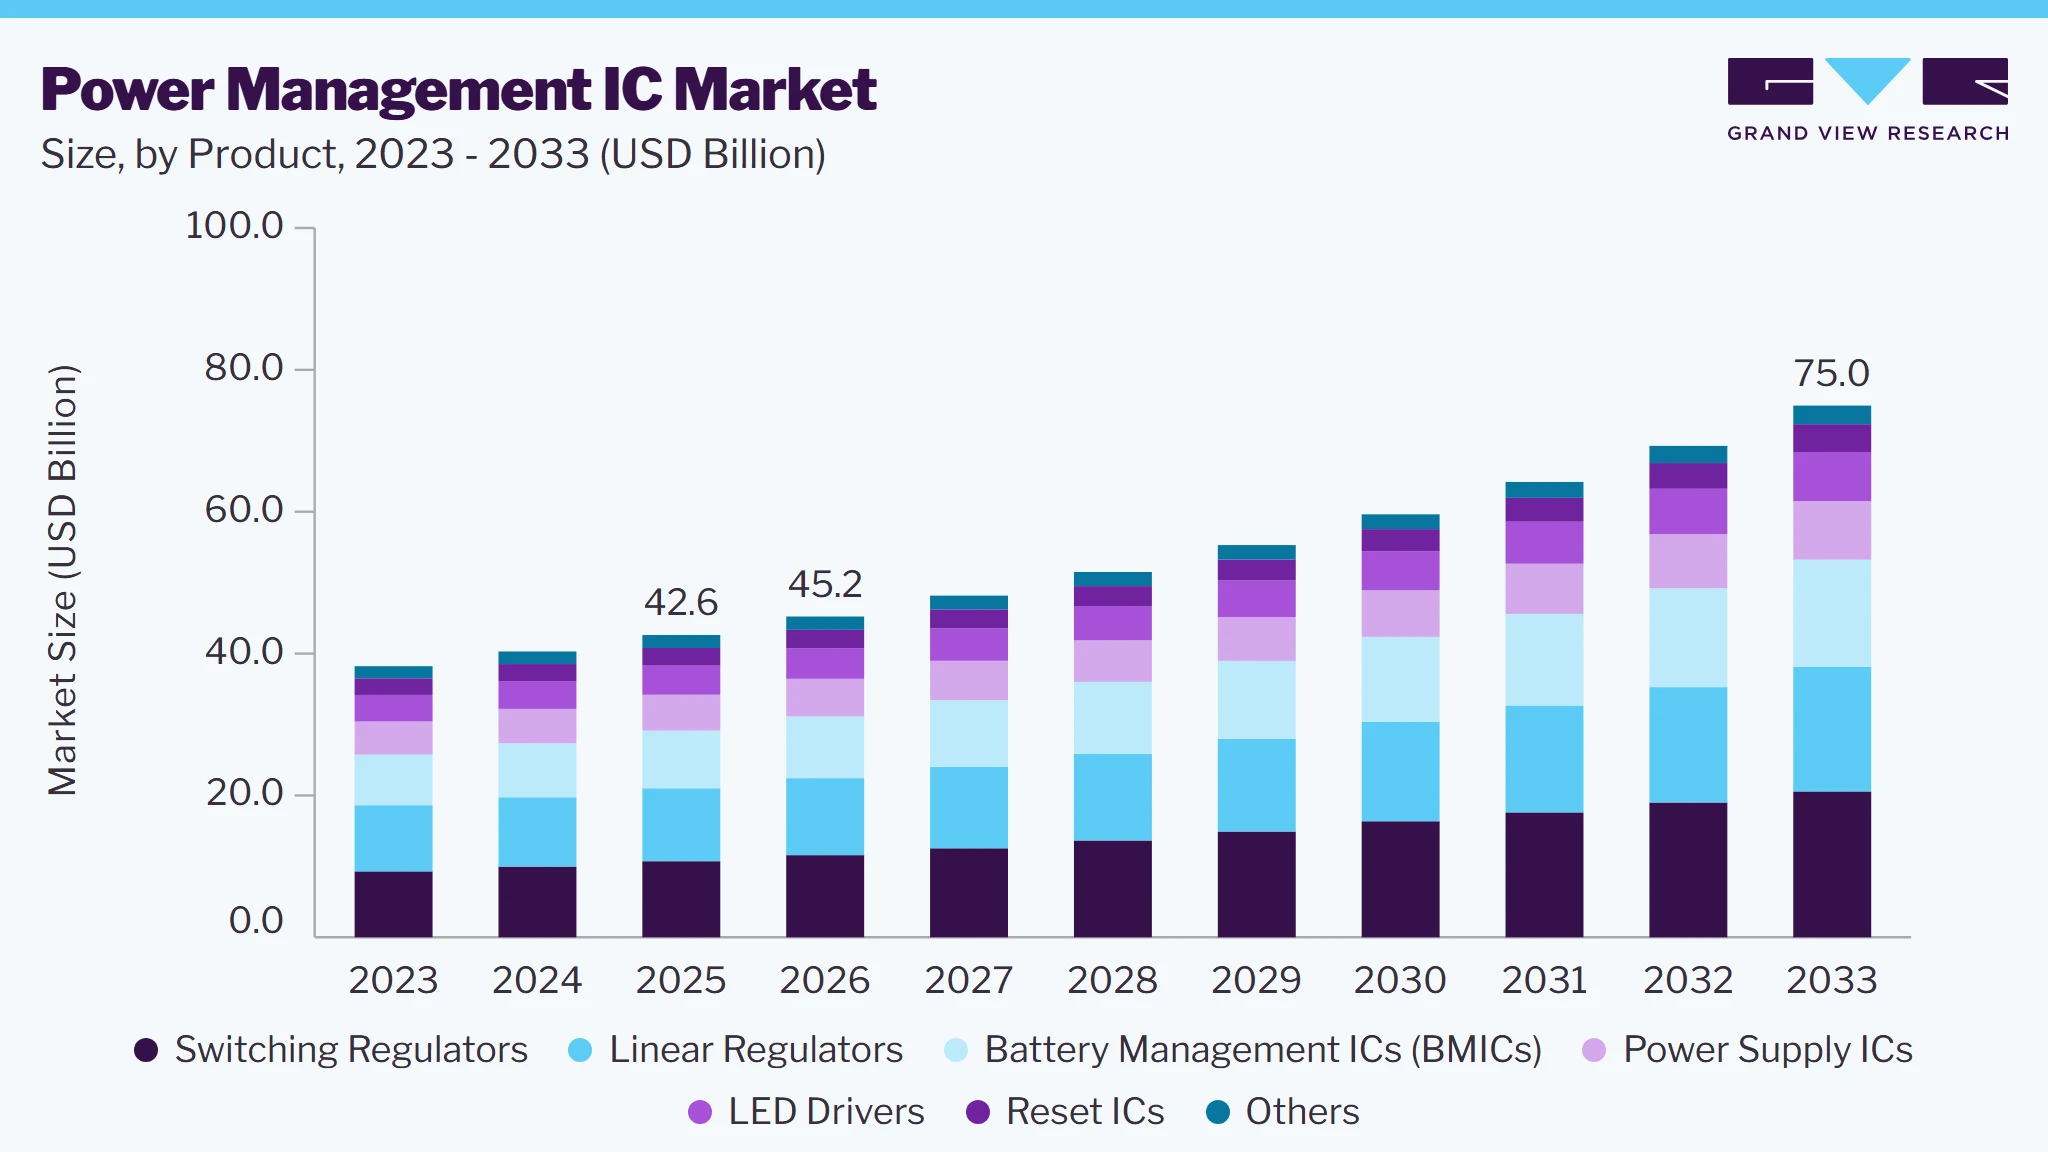 To learn more about this report, Download Free Sample Report
The power management IC market is subject to various regulations, including energy efficiency, safety, and electromagnetic compatibility (EMC). Manufacturers must ensure their products comply with these regulations to obtain market access. The Energy Star program sets energy efficiency standards for electronic products, including those using PMICs. Safety standards are essential to prevent electrical hazards, and organizations like UL and TÜV provide safety certifications. To minimize electromagnetic interference and ensure compatibility, PMICs must adhere to EMC standards governed by international standards like IEC 61000.
The power management IC market is driven by several factors. Technological advancements in semiconductor technology are enabling the development of PMICs with higher performance, lower power consumption, and smaller form factors. The increasing penetration of smartphones, tablets, laptops, and other electronic devices is driving the demand for PMICs. The trend towards electric vehicles and the increasing complexity of automotive electronics are creating new opportunities for PMICs to manage the power requirements of these systems. In addition, the shift towards renewable energy sources, such as solar and wind power, is driving the demand for PMICs to manage energy storage and distribution.
The power management IC market is witnessing significant growth opportunities driven by various trends. The Internet of Things (IoT) is expanding rapidly, creating a demand for PMICs to power a wide range of connected devices. Wearable technology, such as smartwatches and fitness trackers, is gaining popularity, requiring PMICs with small form factors and low power consumption. The transition to electric vehicles is driving the demand for high-performance PMICs to manage battery systems and other components. In addition, the increasing adoption of wireless charging technology is creating opportunities for PMICs with integrated wireless charging capabilities.
Market Dynamics
The power management IC (PMIC) market is shaped by rising electrification across consumer, automotive, industrial, and data-centric applications, alongside increasing system-level requirements for energy efficiency, thermal control, and miniaturization. Advances in semiconductor process nodes, heterogeneous integration, and power architectures enabling higher functional density and improved conversion efficiency. At the macro level, growth in connected devices, electric vehicles, renewable energy systems, and hyperscale computing is reinforcing sustained demand for integrated power management solutions. The market is evolving toward highly integrated, application-specific PMIC platforms that balance performance, reliability, and cost across diverse end-use environments.
The rapid expansion of power-dense electronic systems, particularly smartphones, wearables, electric vehicles, and industrial automation equipment, has intensified the challenge of managing power consumption, heat dissipation, and battery life within constrained form factors. Device manufacturers are under pressure to deliver higher performance and longer operating time while complying with stricter energy efficiency and safety standards. These requirements have elevated power management from a discrete design consideration to a core system-level differentiator, directly driving demand for advanced PMIC solutions.
Power management ICs address this driver by integrating voltage regulation, power sequencing, battery protection, and monitoring functions into compact, optimized architectures. Advanced PMIC designs improve conversion efficiency, reduce leakage losses, and enable dynamic power scaling based on workload conditions. As a result, OEMs can shorten design cycles, reduce bill-of-materials complexity, and enhance product reliability, accelerating PMIC adoption across high-growth electronics and mobility segments.
The increasing functional integration of PMICs has significantly raised design complexity, validation timelines, and qualification costs, particularly for automotive and industrial-grade applications. Power ICs must operate reliably across wide temperature ranges, high-voltage conditions, and long product lifecycles, requiring extensive testing and compliance with industry-specific standards. These technical and regulatory hurdles increase development costs and extend time-to-market, constraining the rapid deployment of new PMIC platforms.
Downstream, this restraint disproportionately affects cost-sensitive consumer electronics manufacturers and emerging market OEMs with limited in-house power design expertise. Automotive and industrial segments face slower adoption cycles due to stringent qualification processes and long design-in periods. As a result, PMIC market growth is moderated in regions where local semiconductor ecosystems and validation infrastructure remain underdeveloped, limiting near-term penetration despite strong underlying demand.
The accelerating shift toward vehicle electrification, advanced driver-assistance systems, and smart industrial infrastructure presents a significant growth opportunity for the PMIC market. High voltage battery systems, distributed power networks, and functional safety requirements are increasing the need for robust, high-efficiency power management solutions. Government incentives for electric mobility and energy-efficient industrial systems further enable this opportunity.
Power management IC vendors with strong automotive-grade and industrial portfolios are well positioned to capture this growth by offering scalable, safety-certified, and high-voltage PMIC platforms. Segments such as battery management ICs, multi-channel DC-DC regulators, and system power controllers are expected to see elevated adoption. Vendors with deep application expertise, long-term supply commitments, and close OEM collaboration are likely to secure sustained design wins in these high value markets.
Analyst Perspective
The power management IC market is in a structurally strong position, supported by long-term trends in electrification, connectivity, and computing intensity. Increasing requirements for power density and energy efficiency are driving innovation in integrated and application-specific PMIC designs. Automotive electrification and data center expansion are emerging as high-value growth engines, reshaping vendor investment priorities. Competitive dynamics are shifting toward deeper OEM collaboration, platform-based offerings, and long lifecycle support. Moreover, the market is expected to attract sustained R&D and capacity investments aligned with advanced power architecture.
Product Insights
Based on product, the switching regulators segment led the market with the largest revenue share of 25.2% in 2025. These regulators are widely used in low-power applications where efficiency is not the primary concern, such as in consumer electronics, sensors, and small signal processing circuits. Their dominance in the market is largely attributed to their ease of integration into various devices and their ability to provide a stable output voltage with minimal external components. Linear regulators also exhibit low electromagnetic interference (EMI), which is crucial in sensitive analog circuits and communication devices. This makes them a preferred choice in applications where noise can affect performance, such as in medical devices and precision measurement equipment. Furthermore, the increasing demand for compact and energy-efficient devices in the consumer electronics sector continues to drive the market for linear regulators.
The switching regulators segment is projected to expand with the fastest growth rate during the forecast period 2024 to 2030. Unlike linear regulators, switching regulators can maintain high efficiency across a wide load range, making them ideal for battery-powered devices, high-power applications, and energy-sensitive systems such as those found in automotive, industrial, and communication sectors.
The growing emphasis on energy efficiency and the increasing adoption of renewable energy systems have further accelerated the demand for switching regulators. These regulators are capable of stepping up (boost), stepping down (buck), or inverting voltage levels, offering greater flexibility in power management solutions. As more devices, from smartphones to electric vehicles, require efficient power conversion with minimal heat generation, the market for switching regulators is expanding rapidly. Technological advancements in semiconductor manufacturing have also contributed to this growth, enabling more compact and efficient designs that can be integrated into increasingly smaller devices.
Industry Vertical Insights
Based on industry vertical, the consumer electronics segment led the market with the largest revenue share of 26.1% in 2025, due to the proliferation of portable electronic devices such as smartphones, tablets, wearables, and laptops. The continuous demand for longer battery life, faster charging times, and compact form factors in these devices has led to significant advancements in PMIC technology. Manufacturers are increasingly integrating sophisticated power management solutions to optimize energy usage, reduce heat generation, and enhance overall device performance. The widespread adoption of smart devices and the Internet of Things (IoT) has further fueled the demand for efficient PMICs in consumer electronics. Moreover, the shift towards more powerful, feature-rich devices with high processing capabilities and advanced displays requires more complex power management solutions, reinforcing the dominance of this sector in the market. In addition, the trend towards wireless charging and the development of new power delivery standards, such as USB-C and fast charging protocols, have created new opportunities for PMICs tailored for these applications.
 To learn more about this report, Download Free Sample Report
The automotive segment is projected to grow at the fastest growth rate during the forecast period 2024 to 2030, driven by the increasing electrification of vehicles, the rise of electric vehicles (EVs), and the integration of advanced driver-assistance systems (ADAS). The shift towards EVs and hybrid vehicles has created a substantial demand for efficient power management solutions to optimize battery usage, manage power distribution, and ensure reliable operation of various electronic components under varying conditions. In addition, the adoption of ADAS, infotainment systems, and in-vehicle networking requires sophisticated PMICs that can handle the high-power demands and provide stable operation across a wide temperature range. As vehicles become more connected and autonomous, the complexity of onboard electronic systems increases, driving the need for more advanced power management solutions that can support these functions while ensuring energy efficiency and safety. The growing emphasis on reducing carbon emissions and improving fuel efficiency is also contributing to the accelerated adoption of PMICs in the automotive sector.
Regional Insights
The power management IC market in North Americais expected to grow at a significant CAGR from 2024 to 2030, driven by the region's technological leadership, advanced industrial base, and strong focus on energy efficiency. The U.S. and Canada, being key players in the global technology landscape, have a high demand for power management solutions across various industries, including consumer electronics, automotive, and industrial automation. The rapid adoption of electric vehicles, coupled with increasing investments in renewable energy projects, particularly in solar and wind energy, has further accelerated the demand for PMICs. In addition, the proliferation of IoT devices, smart homes, and advanced communication networks in North America requires efficient power management to ensure reliable and sustainable operation. The region's focus on reducing carbon emissions and enhancing energy efficiency continues to drive the market's growth, making North America a significant player in the global PMIC market.
U.S. Power Management IC Market Trends
The power management IC market in the U.S. is expected to grow at the fastest CAGR from 2024 to 2030. The country’s robust consumer electronics market, driven by high demand for smartphones, laptops, and other portable devices, requires advanced power management solutions to enhance battery life and performance. In addition, the U.S. is at the forefront of electric vehicle adoption and renewable energy deployment, particularly in solar and wind power, which has led to increased demand for PMICs. The country's emphasis on sustainability, coupled with government incentives for green technologies, has further accelerated the market's growth. Moreover, the rapid expansion of the IoT ecosystem and smart infrastructure projects in the U.S. necessitates efficient power management, contributing to the sustained growth of the PMIC market in the country.
Asia Pacific Power Management IC Market Trends
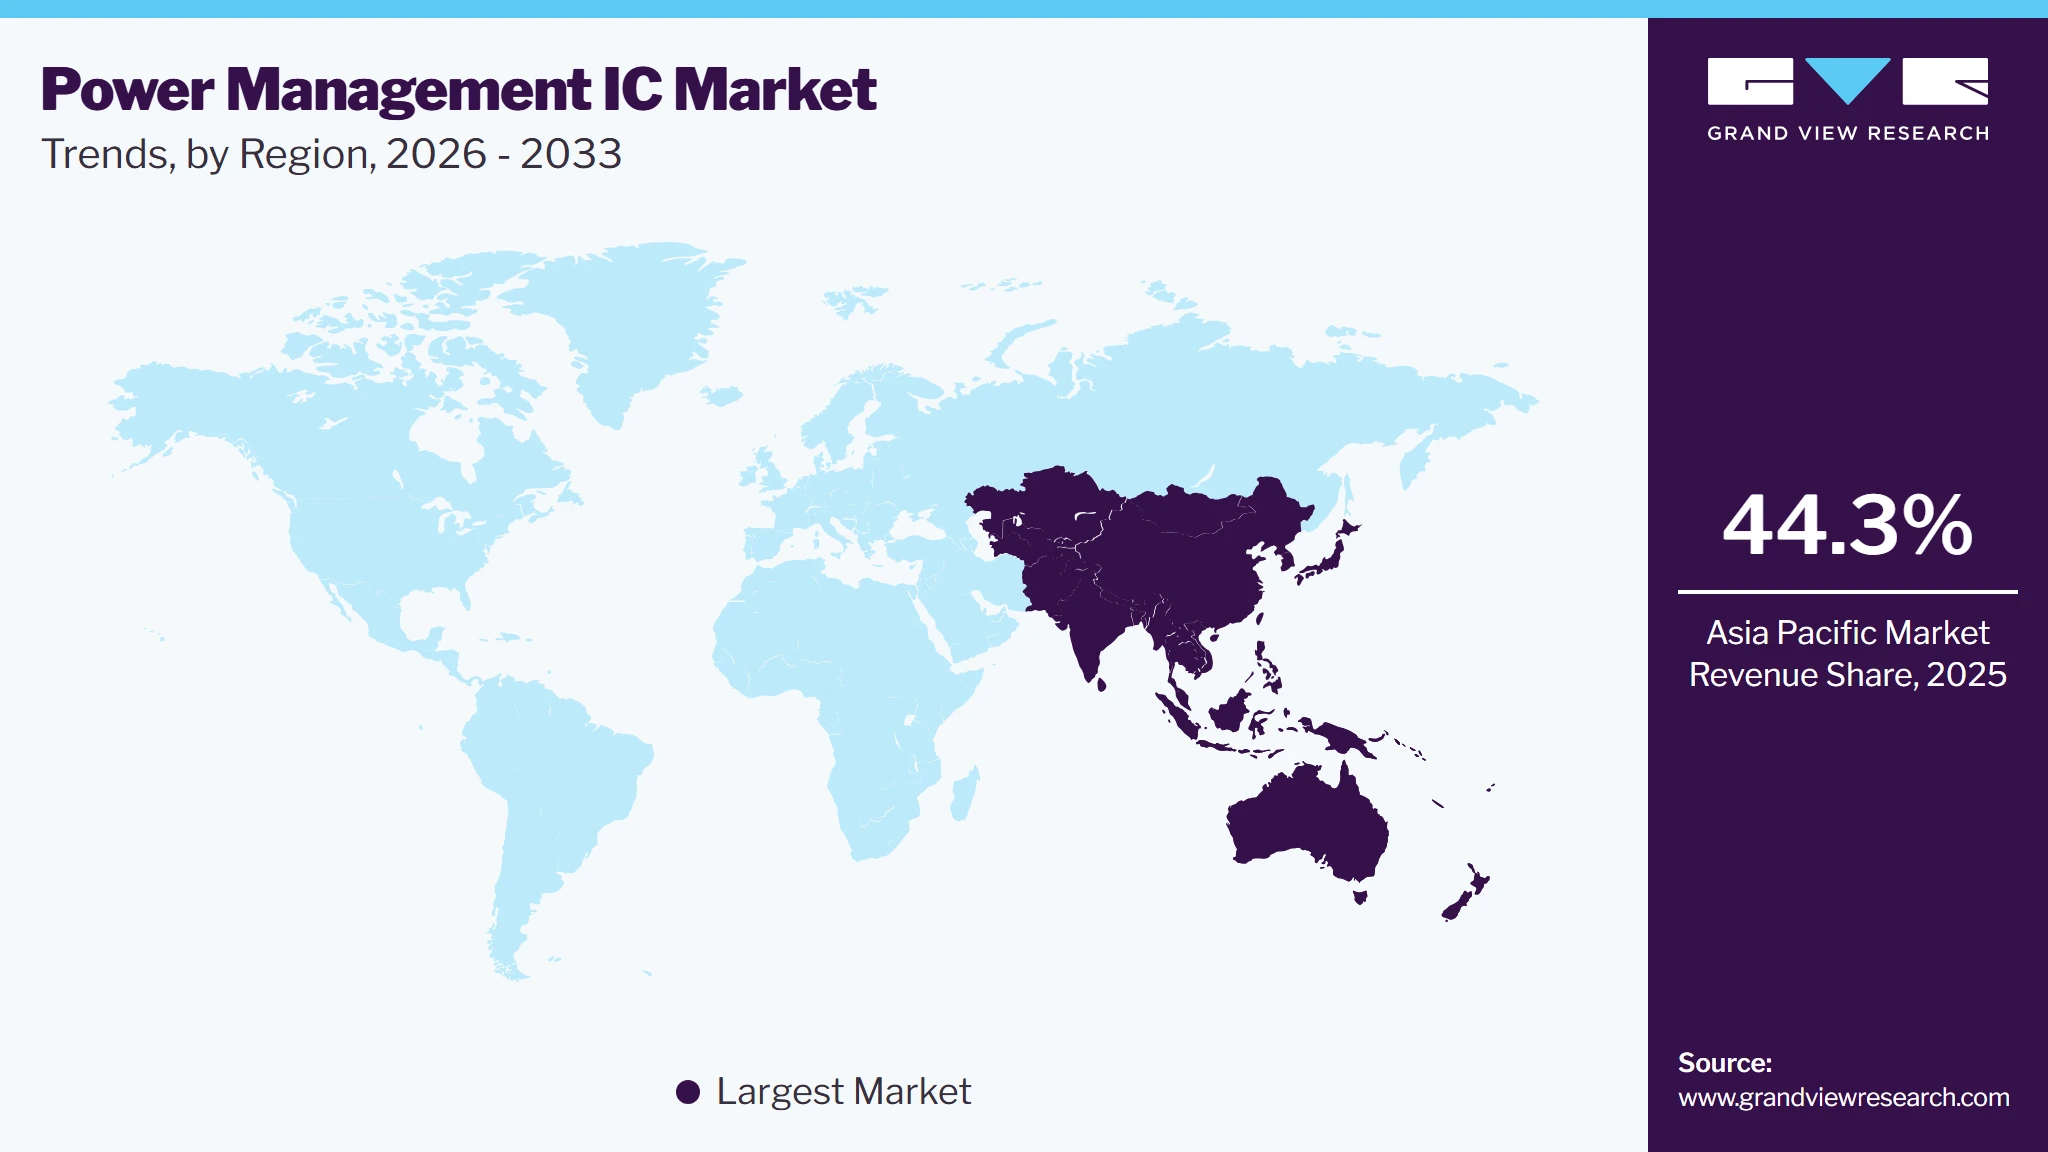
Asia Pacific dominated the global power management IC market with the largest revenue share of 44.3% in 2025, driven by the region's rapid industrialization, technological advancements, and burgeoning consumer electronics sector. Countries such as China, Japan, South Korea, and India are major hubs for electronics manufacturing, which significantly boosts the demand for PMICs. The increasing adoption of smartphones, tablets, and other portable devices in these countries, coupled with the growing popularity of electric vehicles (EVs), has accelerated the need for advanced power management solutions. Moreover, the region's strong focus on renewable energy and energy-efficient technologies is further propelling the market's growth. The availability of skilled labor, advanced manufacturing facilities, and supportive government policies in several Asia Pacific countries are also contributing to the region's dominance.
 To learn more about this report, Download Free Sample Report
The power management IC market in the China held the largest share in the Asia Pacific region in 2025, driven by rapid urbanization, an expanding middle class, and a surge in the consumption of consumer electronics. The government's push towards digitization, coupled with initiatives such as "Make in India," has encouraged both domestic and international companies to set up manufacturing units in the country. The growing penetration of smartphones, tablets, and other IoT devices has significantly increased the demand for efficient power management solutions. In addition, India's emphasis on renewable energy and electric mobility, reflected in ambitious targets for solar power and electric vehicles, is creating new opportunities for the PMIC market. The burgeoning automotive sector, with a shift towards electric and hybrid vehicles, also contributes to the rising demand for advanced power management solutions.
Europe Power Management IC Market Trends
The power management IC market in Europe is expected to witness steady growth from 2024 to 2030. The European Union's stringent regulations on energy consumption and carbon emissions have led to increased demand for energy-efficient power management solutions in industries such as automotive, industrial automation, and renewable energy. The region's leadership in automotive innovation, particularly in electric and hybrid vehicles, has driven the need for sophisticated PMICs that can manage complex power requirements. Moreover, the growing investment in smart grids and renewable energy sources, such as wind and solar power, further boosts the market's growth. Europe’s commitment to sustainability and its ongoing transition to a low-carbon economy continue to drive the adoption of advanced power management technologies, contributing to the region's significant growth in the global PMIC market.
The power management IC market in France is expected to grow at a significant CAGR from 2024 to 2030. France is leading the way in terms of growth within the European Power Management IC market, propelled by the country's robust automotive sector and its strong emphasis on renewable energy. France’s automotive industry, which is increasingly focusing on electric and hybrid vehicles, demands advanced power management solutions to optimize battery performance and energy efficiency. In addition, France’s aggressive goals for reducing carbon emissions and expanding its renewable energy capacity have spurred investments in technologies that require efficient power management, such as solar and wind energy systems. The French government’s support for innovation and technological advancement, particularly in the energy and transportation sectors, has also contributed to the growing demand for PMICs.
Key Power Management IC Company Insights
The competitive landscape of the power management IC market is characterized by intense competition among several key players, ranging from established semiconductor giants to innovative startups. Major companies like Texas Instruments, Analog Devices, Infineon Technologies, and ON Semiconductor dominate the market, leveraging their extensive product portfolios, strong research and development capabilities, and global distribution networks. These companies continually innovate to introduce more efficient, compact, and cost-effective PMICs to meet the evolving demands of various industries, including consumer electronics, automotive, and industrial sectors.
The market is also seeing increasing competition from emerging players who focus on niche applications or advanced technologies such as GaN (Gallium Nitride) and SiC (Silicon Carbide) power devices. These materials offer superior performance in high-frequency and high-voltage applications, giving these new entrants a competitive edge in specific segments of the market. In addition, strategic partnerships, mergers, and acquisitions are common as companies aim to expand their market share, enhance their technological capabilities, and enter new markets. The growing demand for energy-efficient and compact devices, coupled with the rapid adoption of electric vehicles and renewable energy systems, continues to drive innovation in the PMIC market. This dynamic and competitive environment pushes companies to continuously innovate, adapt, and optimize their product offerings to maintain and grow their market position.
-
In July 2024, Renesas Electronics partnered with AMD to launch a space-qualified power management solution for AMD's Versal AI Edge Adaptive SOC. The design integrates vital space-grade components to boost power management performance. Designed for affordable AI Edge applications, it includes comprehensive qualification, a PMBus interface, and telemetry readouts, ensuring seamless integration into satellite payload systems.
-
In May 2024, Yageo Corporation is set to acquire a significant stake in uPI Semiconductor Corp for USD 162.35 million (NT$5.31 billion). This acquisition is intended to strengthen Yageo's position in the AI and HPC applications market. Once the deal is finalized, Yageo will own a 20.23 percent share in uPI.
-
In March 2024, Infinix Mobile launched its first power management chip, the Cheetah X1. This chip will be used in the Infinix NOTE 40 series smartphones and supports All-Round FastCharge 2.0 technology. The Cheetah X1 integrates three powerful modules to adapt to eight different charging scenarios and includes features like high-precision power monitoring and security measures.
Key Power Management IC Companies
The following key companies have been profiled for this study on the power management IC market.
-
Analog Devices, Inc.,
-
Diodes Incorporated
-
Infineon Technologies AG
-
Microchip Technology Inc.
-
NXP Semiconductors
-
Renesas Electronics Corporation
-
ROHM Co., Ltd.
-
Semiconductor Components Industries, LLC (onsemi)
-
Semtech Corporation
-
Texas Instruments Incorporated
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Texas Instruments Incorporated, Infineon Technologies AG, Analog Devices, Inc., NXP Semiconductors)
- These players are focused on broad portfolio coverage, long-term OEM partnerships, and continuous platform innovation
- These players have strong brand trust, automotive and industrial-grade expertise, global manufacturing scale
- Higher cost structures and longer product development cycles
Emerging Players (Diodes Incorporated, Semtech Corporation, ROHM Co., Ltd.)
- These players are focused on product strategies, selective vertical specialization, agile design-in support.
- Competitive pricing, niche power solutions, faster customization
- Limited portfolio breadth and lower penetration in high-volume automotive platforms
Power Management IC Market Report Scope
Report Attribute
Details
Market size in 2025
USD 42.6 billion
Estimated market size in 2026
USD 45.2 billion
Projected market size by 2033
USD 75.0 billion
Growth rate
CAGR of 7.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Product, industry vertical, region
Regional scope
North America; Europe; North America; Central & South America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; and South Africa
Key companies profiled
Analog Devices, Inc.; Diodes Incorporated; Infineon Technologies AG; Microchip Technology Inc.; NXP Semiconductors; Renesas Electronics Corporation; ROHM Co., Ltd.; Semiconductor Components Industries, LLC (onsemi); Semtech Corporation; Texas Instruments Incorporated
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Power Management IC Market Report Segmentation
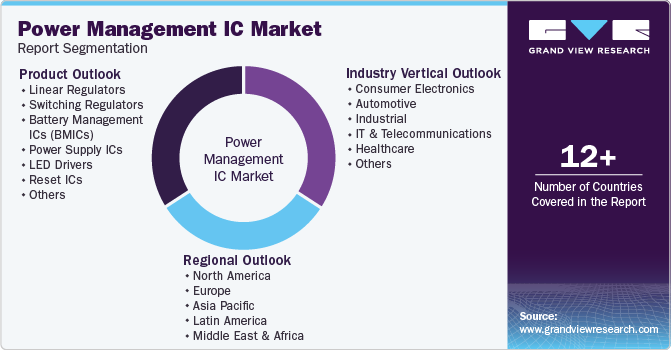
The report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the power management IC market based on product, industry vertical, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Linear Regulators
-
Switching Regulators
-
Battery Management ICs (BMICs)
-
Power Supply ICs
-
LED Drivers
-
Reset ICs
-
Others
-
-
Industry Vertical Outlook (Revenue, USD Billion, 2021 - 2033)
-
Consumer Electronics
-
Smartphones and Tablets
-
Laptops
-
Televisions
-
Wearables
-
Others
-
-
Automotive
-
Engine Management
-
Infotainment Systems
-
Others
-
-
Industrial
-
Factory Automation
-
Energy Management Systems
-
Others
-
-
IT & Telecommunications
-
Servers
-
Data Centers
-
Networking Equipment
-
Others
-
-
Healthcare
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa (MEA)
-
United Arab Emirates (UAE)
-
Kingdom of Saudi Arabia (KSA)
-
South Africa
-
-
Research Methodology
The power management IC market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each power management IC segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Linear Regulators
Revenue from low-dropout regulators (LDOs) and linear voltage regulators used for noise-sensitive and low-power applications across consumer, industrial, and automotive systems.
Switching Regulators
Revenue from DC-DC converters, buck, boost, and buck-boost regulators deployed in high-efficiency power conversion and multi-rail power architectures.
Battery Management ICs (BMICs)
Revenue from ICs providing battery charging, protection, monitoring, balancing, and fuel gauging for rechargeable battery systems.
Power Supply ICs
Revenue from controller ICs, power factor correction ICs, and integrated power stages used in AC-DC and isolated power supply designs.
LED Drivers
Revenue from constant-current and constant-voltage driver ICs for display backlighting, general lighting, and automotive lighting systems.
Reset ICs
Revenue from voltage supervisors, watchdog timers, and reset controllers ensure system stability and fault recovery.
Others
Revenue from power monitors, hot-swap controllers, power multiplexers, and application-specific power ICs.
Segment - Industry Vertical
Revenue capture definition
Consumer Electronics
Revenue generated from the sale of power management ICs, including PMICs, voltage regulators, battery charging ICs, LED drivers, and power controllers, is integrated into smartphones and tablets, laptops, televisions, wearables, and other consumer electronics.
- Smartphones and Tablets: PMIC revenue from highly integrated power solutions for mobile computing and communication devices.
- Laptops: Revenue from multi-rail and battery charging PMICs used in portable PCs.
- Televisions: Revenue from power supply ICs and LED drivers used in display and backlight systems.
- Wearables: Revenue from ultra-low-power PMICs optimized for compact, battery-operated devices.
- Others: Revenue from PMICs used in gaming consoles and home electronics.
Automotive
Revenue from automotive-grade power management ICs supplied for engine management, infotainment systems, and others. Captured revenues include qualified PMICs, DC-DC converters, battery management ICs, and power controllers designed for high reliability, functional safety, and long lifecycle automotive applications.
- Engine Management: Revenue from power ICs supporting engine control units and powertrain electronics.
- Infotainment Systems: Revenue from PMICs used in in-vehicle infotainment and digital cockpit platforms.
- Others: Revenue from power ICs in ADAS, body electronics, and battery systems.
Industrial
Revenue derived from power management ICs used in factory automation, energy management systems, and others. This segment captures revenue from high-voltage regulators, isolated power ICs, power monitoring ICs, and robust PMICs that support continuous operation, wide temperature ranges, and long deployment cycles.
- Factory Automation: Revenue from PMICs used in PLCs, robotics, and motion control systems.
- Energy Management Systems: Revenue from power ICs supporting smart grids and energy storage systems.
- Others: Revenue from PMICs in instrumentation and industrial controls.
IT & Telecommunications
Revenue from power management ICs deployed in servers, data centers, networking equipment, and others. This segment includes sales of high-current voltage regulators, power controllers, hot-swap controllers, and power monitoring ICs supporting high-performance computing, hyperscale data centers, and communication networks.
- Servers: Revenue from high-current PMICs used in server power architecture.
- Data Centers: Revenue from power controllers and regulators supporting hyperscale infrastructure.
- Networking Equipment: Revenue from PMICs used in switches, routers, and base stations.
- Others: Revenue from telecom infrastructure electronics.
Healthcare
Revenue from PMICs used in diagnostic, monitoring, and medical imaging devices.
Others
Revenue from PMICs deployed in aerospace, defense, and specialty electronics.
Estimation Model
Layer Name
Key Question
Description
End-Use Demand Mapping
Where is PMIC demand generated?
This layer maps PMIC demand across consumer, automotive, industrial, IT & telecom, and healthcare sectors. It assesses device shipment volumes and power architecture requirements. Application-level power complexity is a key determinant.
Product-Level Penetration
Which PMIC types are used?
This layer evaluates adoption of linear regulators, switching regulators, BMICs, and power supply ICs within each end-use. It considers voltage levels, integration requirements, and efficiency targets.
Pricing and Integration Analysis
What is the value per device?
This layer estimates average selling prices based on integration level, process node, and qualification grade. Automotive and industrial PMICs command higher value due to reliability requirements.
Regional and Channel Adjustment
How does geography affect revenue?
This layer adjusts market size by regional manufacturing intensity, supply chain localization, and OEM sourcing strategies. Asia Pacific and North America show distinct demand and pricing dynamics.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Power Management IC Market Opportunity Assessment
Country/region-wise market sizing and forecasts
Analysis of demand, adoption trends, and regulatory landscape
Identification of high-growth regions and investment hotspots
Identified region-specific growth opportunities
Supported expansion and go-to-market strategy
Enabled informed regional investment decisions
Cross-Segmentation Analysis for the Power Management IC Market
Criss-cross market analysis by product, and industry vertical
Demand and adoption assessment across key segments
Segment attractiveness and growth potential benchmarking
Identified high-potential market segments
Supported targeted product positioning and marketing strategy
Improved customer and segment prioritization
Competitive Benchmarking and Strategic Positioning in the Power Management IC Market
Benchmarking of key competitors across products, pricing, partnerships, and innovation
Comparative assessment of market share, capabilities, and strategies
Analysis of competitive strengths, gaps, and differentiation areas
Identified competitive white spaces and growth gaps
Supported strategic positioning and differentiation
Enabled data-driven competitive strategy development
Frequently Asked Questions About This Report
The global power management IC market size was estimated at USD 42.6 billion in 2025 and is expected to reach USD 45.2 billion in 2026.
Some key players operating in the power management IC market include Analog Devices, Inc., Diodes Incorporated, Infineon Technologies AG, Microchip Technology Inc., NXP Semiconductors, Renesas Electronics Corporation, ROHM Co., Ltd., Semiconductor Components Industries, LLC (onsemi), Semtech Corporation, and Texas Instruments Incorporated.
North America dominated with a 44.3% revenue share in 2025.
Switching regulators segment dominated the market, with a revenue share of 25.2% in 2025.
Consumer electronics segment held the largest market share of 26.1% in 2025, while automotive is the fastest growing segment.
The global power management IC market is expected to grow at a compound annual growth rate of 7.5% from 2026 to 2033, reaching USD 75.0 billion by 2033.
The power management integrated circuit market is experiencing rapid growth due to several key trends. The demand for smaller, more portable electronic devices has driven the development of PMICs with reduced form factors and increased integration.
About the Author(s)
Sensors & Controls Research Team
Semiconductors & Electronics · Sensors & ControlsThis report was authored by the sensors & controls research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the sensors & controls segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


