
- Home
- »
- Pharmaceuticals
- »
-
Rare Diseases Treatment Market Size & Share Report, 2033GVR Report cover

Rare Diseases Treatment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Therapeutic Area (Cancer, Musculoskeletal Conditions), By Route Of Administration, By Drug Type, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$216.2BMarket Estimate, 2026
$241.9BMarket Forecast, 2033
$483.4BCAGR, 2026–2033
10.4%Rare Diseases Treatment Market Summary
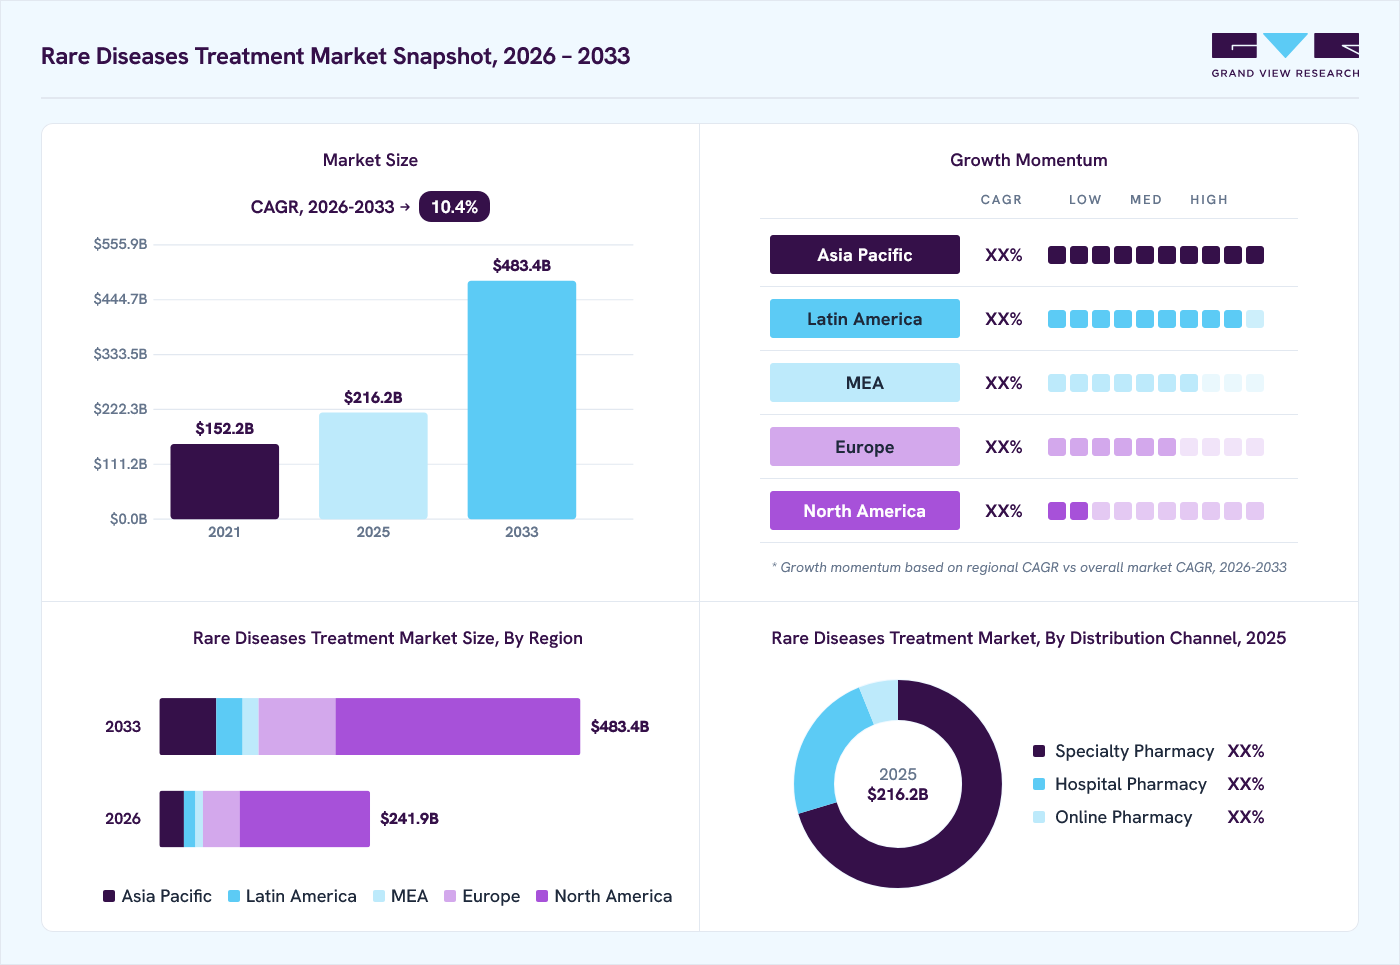
The global rare diseases treatment market size was valued at USD 216.2 billion in 2025 and is projected to grow from USD 241.9 billion in 2026 to USD 483.4 billion by 2033, growing at a CAGR of 10.4% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 62.4% in 2025. The presence of a strong product pipeline and their expected launches are expected to drive market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By therapeutic area: Cancer segment held the largest revenue share of 28.1% in 2025.
- By drug type: Biologics segment held the largest revenue share of 57.9% in 2025.
- By route of administration: Injectable segment held the largest share of 65.5% in 2025.
- By distribution Channel: Specialty pharmacy segment held the largest share of 70.3% in 2025.
Regional Highlights
- Largest regional market: North America (62.4% revenue share, 2025)
- Fastest-growing regional market: Asia pacific (fastest CAGR, 2026-2033)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 216.2 Billion
- Estimated market size in 2026: USD 241.9 Billion
- Projected market size by 2033: USD 483.4 Billion
- CAGR (2026-2033): 10.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
For instance, in October 2024, FDA announced seven new clinical trial grants for advancement in research on rare disease treatments, which are often overlooked. These new projects include the treatment for Cancer, Cushing’s syndrome, lymphatic malformations, inherited eye disease, and blood disorders. Increased funding for such research projects fuels the launch of new drugs and treatments for diseases and further boosts the market growth.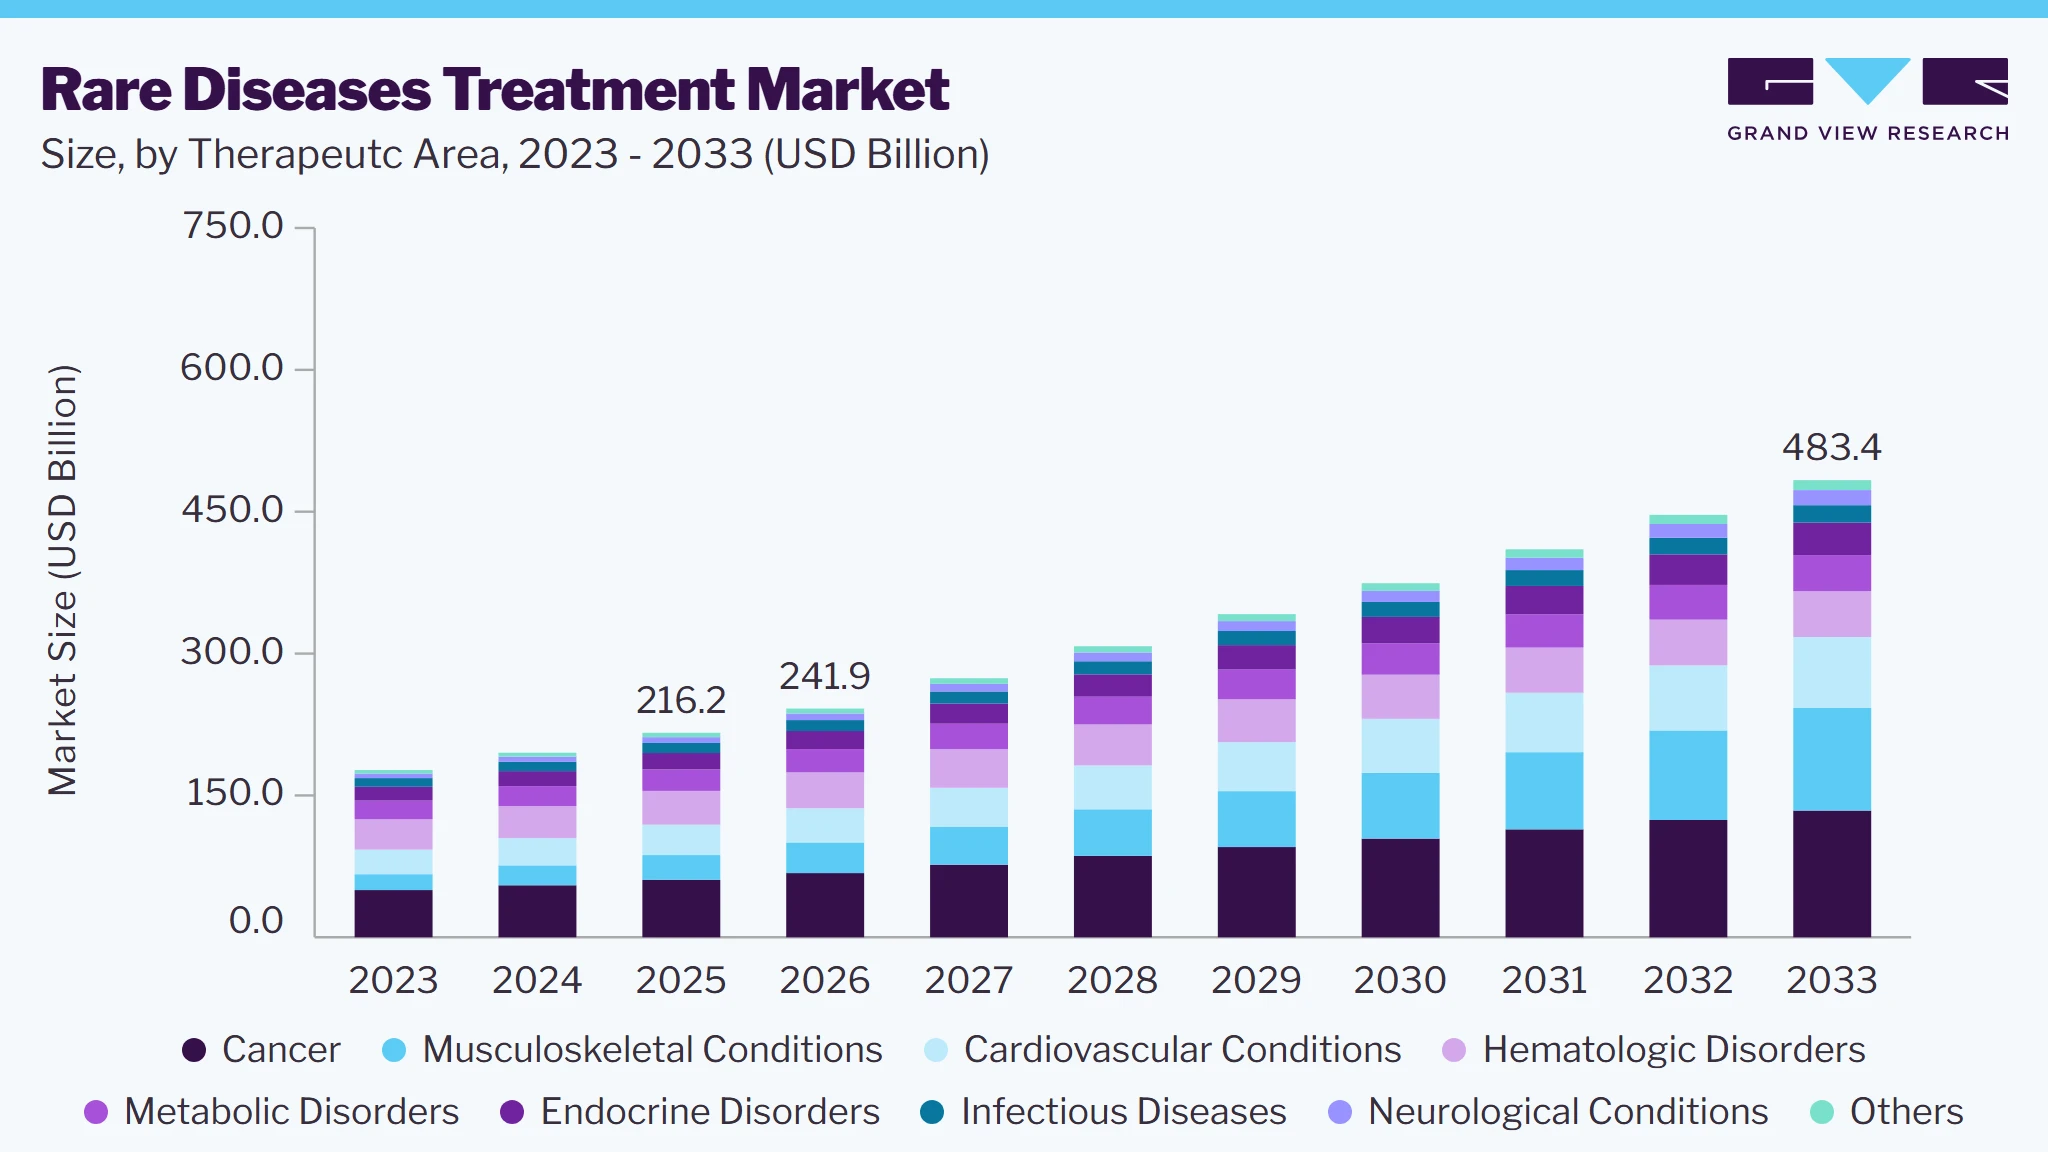 To learn more about this report, Download Free Sample Report
Governments of several countries, especially developed nations, are taking efforts to support the development of orphan drugs. Many organizations, including governmental and non-governmental institutions are providing incentives, exemptions from certain fees, and other benefits in order to boost the availability of treatments for such unusual medical conditions. For instance, according to the data published in August 2024, by the Centre for Innovation in Regulatory Science, major regulatory authorities observed an exponential growth in the proportion of new active substances receiving orphan designation. The numbers found were as follows, EMA approved 38% drugs in 2022 as compared to 33% in 2017, FDA approved 55% of orphan drugs as compared to 44% in 2017. These increasing numbers of drug approvals for orphan designation are attributed to the growing incentives for R&D in diseases.
Furthermore, technological advancements play a pivotal role in the growth of the market. Innovations in next-generation sequencing (NGS), bioinformatics, and gene therapies have revolutionized the healthcare industry. For instance, as per the information published in January 2024 by Drug Discovery World (DDW), researchers have found potential use of mRNA in a preclinical study to effectively treat a unusual liver disease named as “argininosuccinic aciduria.” These technologies enable diagnostic accuracy, identification of uncommon disease, and treatment choice. Such advancements in the pharmaceutical industry are expected to surge rare diseases treatment industry growth during the forecast period.
Moreover, the growing emphasis on patient-centric healthcare models is shaping the market. As healthcare systems move towards more individualized approaches, there is an increased focus on understanding patients' unique biological profiles. This trend is leading to the development of more precise therapeutics that can enhance treatment efficacy and minimize adverse effects. By tailoring medical interventions to individual patients, healthcare providers can improve overall patient satisfaction and outcomes, further propelling the growth of the market.
Market Dynamics
The rare diseases treatment market is driven by increasing diagnosis rates, expanded newborn screening programs, and continued investment in orphan drug development. Advances in genetic testing and precision medicine are supporting earlier identification of rare disorders, enabling targeted treatment approaches for conditions that previously had limited therapeutic options. Regulatory incentives for orphan drug development across major markets continue to support research activity and product approvals. The market is also benefiting from growing adoption of gene therapies, enzyme replacement therapies, and RNA based treatments for inherited diseases. Increasing collaboration between biotechnology companies, academic institutions, and patient advocacy organizations is supporting clinical development and patient access initiatives. Growing awareness among healthcare providers and patients is contributing to earlier treatment initiation and improved disease management. Rising healthcare expenditure and expanding reimbursement support for high value rare disease therapies continue to contribute to market growth across North America, Europe, and selected Asia Pacific countries. Ongoing clinical research focused on addressing unmet medical needs across rare disease indications remains a key factor supporting market expansion.
The Rare Diseases Treatment Market is driven by the increasing number of orphan drug approvals and continued advances in targeted therapies for genetically defined disorders. Improvements in genomic sequencing and molecular diagnostics are enabling earlier and more accurate diagnosis, supporting the development of treatments that address specific disease mechanisms. Regulatory incentives such as market exclusivity, accelerated review pathways, and research support continue to encourage pharmaceutical and biotechnology companies to invest in rare disease programs. Growing adoption of gene therapies, RNA based therapies, enzyme replacement therapies, and monoclonal antibodies is expanding treatment options across a broad range of rare disorders. In addition, increasing collaboration between research institutions, patient advocacy groups, and drug developers is supporting clinical development activities and improving patient access to innovative treatments. The growing number of approved therapies for previously underserved patient populations continues to strengthen market growth. For instance, in March 2025, Sanofi received U.S. FDA approval for Qfitlia (fitusiran) for routine prophylaxis in hemophilia A and hemophilia B patients aged 12 years and older with or without factor VIII or factor IX inhibitors. Clinical studies demonstrated up to a 90% reduction in annualized bleeding rates compared with on demand treatment controls.
Delayed diagnosis and challenges in patient identification remain significant restraints for the rare diseases treatment market. Many rare diseases present with symptoms that resemble more common disorders, often resulting in prolonged diagnostic pathways and delayed treatment initiation. Limited awareness among healthcare professionals, restricted access to advanced genetic testing in several countries, and variations in healthcare infrastructure continue to affect diagnosis rates. Small patient populations also create challenges for clinical trial recruitment and evidence generation, which can extend development timelines and delay regulatory approvals. In addition, patients frequently experience referrals across multiple specialists before receiving an accurate diagnosis, reducing opportunities for early intervention. The absence of standardized screening programs for many rare conditions further contributes to underdiagnosis and undertreatment. Reimbursement limitations for diagnostic tests and specialized therapies in certain healthcare systems also create barriers to access. These factors continue to restrict timely treatment adoption despite the growing availability of innovative therapies and ongoing advancements in rare disease research.
The expansion of gene therapy and precision medicine programs presents a significant opportunity for the Rare Diseases Treatment Market. Advances in genetic engineering, vector technologies, and disease specific biomarkers are enabling the development of therapies that address the underlying causes of rare genetic disorders. Pharmaceutical companies are increasingly prioritizing rare disease pipelines due to unmet clinical needs and supportive regulatory frameworks. Continued progress in cell and gene therapy manufacturing capabilities is also improving the feasibility of developing treatments for ultra rare conditions. Furthermore, increasing integration of genomic medicine into clinical practice is expected to improve patient identification and facilitate broader adoption of targeted therapies. These developments are creating opportunities for new product development across multiple therapeutic areas. For instance, in March 2026, Denali Therapeutics received U.S. FDA approval for Avlayah (tividenofusp alfa-eknm) for the treatment of Hunter syndrome with neurological manifestations. The approval marked the first therapy specifically designed to address neurological symptoms associated with the disease and provided a treatment option for a disorder affecting approximately 1 in 100,000 to 170,000 male births globally.
Analyst Perspective
The rare diseases treatment market is evolving from a specialized therapeutic segment into a strategic focus area for pharmaceutical and biotechnology companies, supported by advances in genetic medicine, orphan drug development, and precision therapies. The market is increasingly centered around companies with strong rare disease research capabilities, established regulatory expertise, and specialized commercial infrastructure. Takeda, Roche, and Novartis continue to strengthen their positions through broad rare disease portfolios and continued investment in targeted therapies. AstraZeneca has expanded its presence through its Alexion business, while Pfizer and Bristol Myers Squibb are leveraging expertise in biologics and advanced therapeutics to address unmet medical needs. Gene therapies, RNA based therapies, and enzyme replacement therapies are expected to remain key areas of development across multiple rare disease indications.
Therapeutic Area Insights
Based on therapeutic area, the cancer segment led the market with the largest revenue share of 28.1% in 2025. This dominance can be attributed to the high prevalence and recurrence rate of rare cancer indications. Cancers such as hepatoblastoma, thymic carcinoma, and essential thrombocythaemia are considered uncommon but are equally fatal and need to be addressed with potential treatment. The incidences of such cases are increasing every year for instance, according to the data mentioned in Orphanet heapatoblastoma comprises of 0 to 5% of all pediatric tumors. It is observed that the case of this disease is increasing every year by 5% in children, which will in turn boost the demand for cancer treatments over the forecast period.
Musculoskeletal conditions segment is expected to grow at a significant CAGR rate over the forecast period. The growth of this segment can be attributed to the increasing prevalence of musculoskeletal disorders and new product approvals for treatment. For instance, in August 2024 , U.S. FDA approved axatilimab-csfr for the treatment of chronic graft-versus-host disease (cGVHD) which is a fatal condition that can occur after a bone marrow or stem cell transplant. This approval is expected to boost the segment growth during the forecast period.
Drug Insights
Based on drug type, the biologics segment led the market with the largest revenue share of 57.9% in 2025, due to its ability to address complex and previously untreatable conditions. Their high specificity and efficacy make them particularly suitable for treating uncommon genetic and metabolic disorders. Owing to numerous benefits key players in the market are developing novel therapies to treat unusual diseases. For instance, in September 2024 , Sanofi announced that Dupixent- a biologic met all the secondary end points in a pivotal study to treat bullous pemphigoid (BP) in adults. It has received orphan drug designation by U.S. FDA and if approved, it will be the first and only targeted medicine to treat BP. Such remarkable developments in the sector fuel the market growth.
Biosimilar segment is expected to grow at a significant CAGR rate over the forecast period. The patents expiration of orphan biologics and supportive regulatory policies is expected to pave the way for new players to enter the market and drive competition, reducing the drug price used for treatment of various unique diseases, thereby driving segment growth. Extensive research and product launch also contribute in the growth of the biosimilar sector. For instance, according to the data released in May 2024 , FDA approved Bkemv and Soliris which are the first interchangeable biosimilars for two rare diseases paroxysmal nocturnal hemoglobinuria (PNH) and atypical hemolytic uremic syndrome (aHUS).
Route of Administration Insights
Based on route of administration, the injectable segment led the market with the largest revenue share of 65.5% in 2025, driven by its effectiveness in delivering drug directly into the bloodstream or targeted tissues. Key players in the market are launching new injectables for maximum therapeutic effect in the treatment of several chronic diseases. For instance, in October 2024, U.S. FDA approved Pfizer’s HYMPAVZI, a subcutaneous injection for the treatment of Hemophilia A or B which is a rare hematological disease. This approval is expected to boost injectable segment during the forecast period.
Others segment is expected to grow at a significant CAGR rate over the forecast period. Many treatments administered through other routes including topical treatments, intranasal therapy, inhalation therapy among many others is included under this segment. With rising research and development of pharmaceuticals to treat rare diseases, the segment is anticipated to grow in the coming years. For instance, in January 2023, Mankind Corporation announced the advancement of clofazimine inhalation suspension to Phase 2/3 study to efficiently treat rare lung disease. This product approval is anticipated to boost the rare diseases treatment industry growth.
Distribution Channel Insights
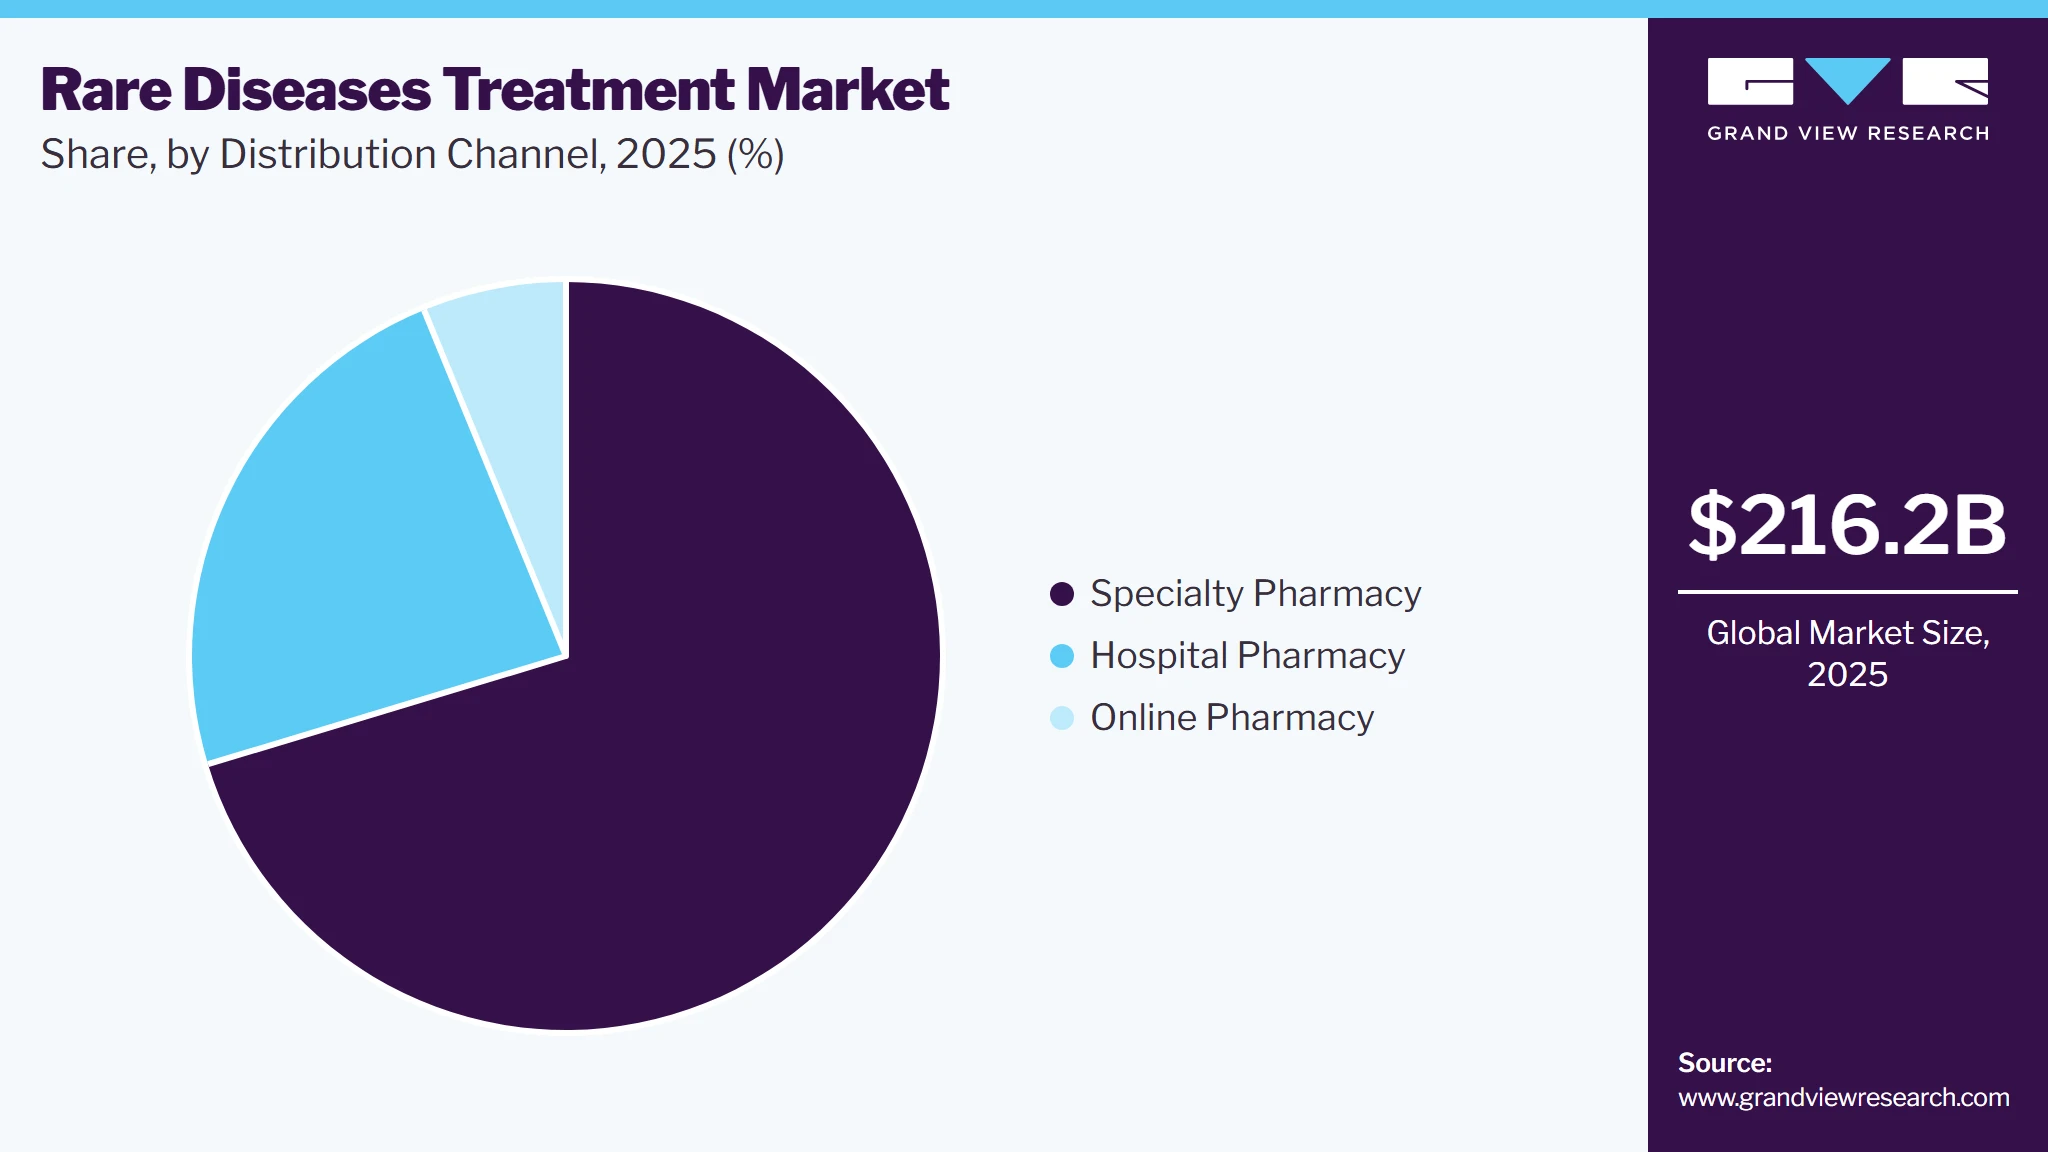
Based on distribution Channel, the specialty pharmacy segment led the market with the largest revenue share of 70.3% in 2025, due to their expertise in managing complex therapies that require specialized handling, storage, and administration. Market players in the industry are involving in strategic collaborations with such specialty pharmacies for substantial distribution of their orphan drugs. For instance, in September 2024, Calliditas Therapeutics announced the selection of PANTHERx Rare, a specialty pharmacy for the distribution of their TARPEYO- a delayed release capsule to treat kidney disease. These collaborations entrust more people and boost adoption, thus propelling rare diseases treatment industry growth.
 To learn more about this report, Download Free Sample Report
Hospital pharmacy segment is the fastest-growing segment and is expected to grow at a CAGR rate over the forecast period driven by the growing prevalence of rare diseases diagnosed and treated in hospitals. In addition, rare disease patients frequently require biologics, gene therapies, or enzyme replacement therapies that demand expert handling and administration, which hospital pharmacies are well-equipped to provide. These pharmacies also play a crucial role in ensuring seamless access to high-cost and specialty drugs through institutional frameworks and reimbursement programs.
Regional Insights
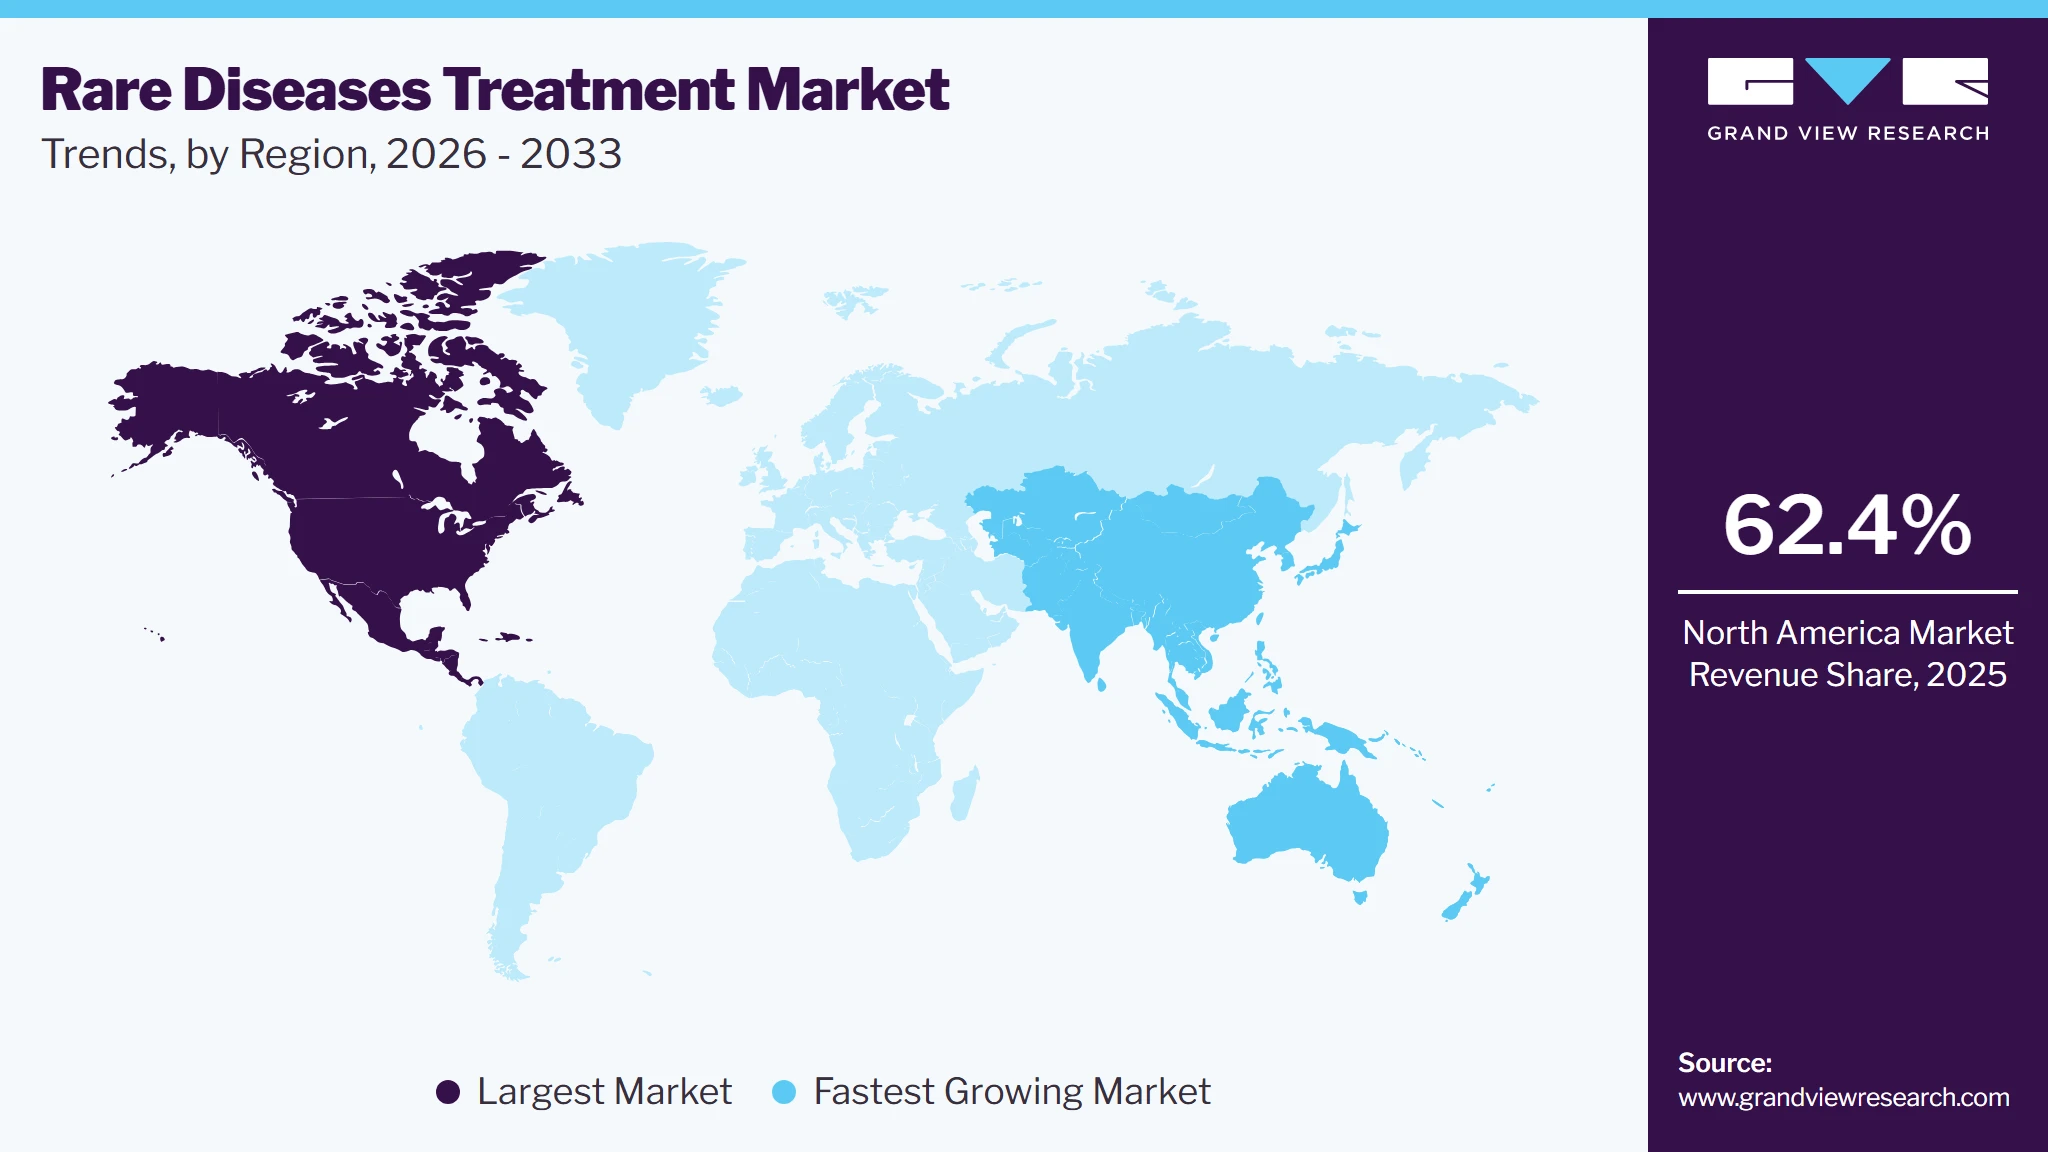
North America dominated the rare diseases treatment market with the largest revenue share of 62.4%in 2025, which can be attributed to high burden of disease, favorable healthcare infrastructure, and new product approvals for treatment. For instance, in September 2024 FDA approved Miplyffa- an oral medication to treat neurological symptoms related to Niemann-Pick disease, type C (NPC). It is also the first FDA approved drug for the treatment of NPC.
 To learn more about this report, Download Free Sample Report
U.S. Rare Disease Treatment Market Trends
The rare diseases treatment market in the U.S. held the largest share in the North America region in 2025, driven by advancements in genomics and increased demand for targeted therapies. Rising investments in research, regulatory support for orphan drugs, and a growing emphasis on precision medicine in oncology and other chronic disease management are further propelling market expansion in this sector.
Europe Rare Disease Treatment Market Trends
The Europe rare disease treatment market driven by supportive regulatory framework, increased investment in research and innovation, and rising awareness of rare conditions. For instance, as per the news published in November 2024, Oranda Therapeutics, a rare disease company based in Ireland announced the launch of their Series A Funding round to gain commercial EMEA license for a treatment intended to treat hyperphagia in patients with Prader-Willi syndrome.
The UK rare disease treatment market is expected to show significant growth driven by increasing research and development investments and enhanced funding for innovative projects. This financial support is facilitating the discovery of novel drugs and advancing precision medicine initiatives, leading to improved and targeted therapies, ultimately enhancing patient outcomes across the region.
The Germany rare disease treatment market is experiencing significant growth, largely due to the rising prevalence of chronic disorders such as cancer, and cardiovascular diseases. This increasing burden on healthcare systems is driving demand for targeted treatments and tailored therapies, fostering advancements in personalized medicine and enhancing patient care in the region.
The rare disease treatment market in France is driven by a diverse array of therapeutic areas, reflecting the complex landscape of unmet medical needs. Cancer therapies lead the way, as advancements in precision medicine and targeted treatments address the unique challenges posed by rare oncological conditions. Neurological disorders are another critical area, where innovative approaches for diseases such as amyotrophic lateral sclerosis (ALS) and rare epileptic syndromes are gaining traction. Similarly, cardiovascular conditions, including rare genetic heart diseases, are witnessing a surge in research and development initiatives aimed at offering life-saving solutions.
Asia Pacific Rare Disease Treatment Market Trends
The Asia Pacific rare disease treatment market is expected to grow at the fastest CAGR over the forecast period. The growth of the market in the region is owing to growing healthcare reforms in the region aided by improved healthcare infrastructure, a growing population, and an increase in the number of companies entering the market. The Asia Pacific region has a large population and high cancer prevalence. Thus, the demand of novel treatments for rare cancers, musculoskeletal disorders, and others has increased in the past few years owing to growing government initiatives, collaborations for the distribution and supply of these drugs. For instance, as per the data published in June 2024 , Delhi high court demanded 11.84 Lakh rupees to AIIMS for the treatment of rare disease.
The China rare disease treatment market is growing at a lucrative rate. Presence of government funding and initiatives in the region further fuels regional growth. The cumulative demand across therapeutic areas underscores the total growth potential of the rare disease treatment industry in China, driven by continued innovation, regulatory incentives, and patient advocacy efforts.
The rare disease treatment market in Japan is witnessing notable growth, driven by advancements across multiple therapeutic areas and reinforced by supportive government initiatives. In Japan, the government’s focus on addressing unmet medical needs, particularly in oncology, has bolstered the development of targeted therapies for rare cancers. Neurological conditions, such as rare forms of dementia and epilepsy, are gaining significant attention, supported by Japan’s robust healthcare infrastructure and innovation in biopharmaceutical research. Cardiovascular conditions, including rare congenital heart diseases, and musculoskeletal disorders, such as osteogenesis imperfecta, also represent key growth segments, with advancements in gene therapies and regenerative medicine leading the charge.
Latin America Rare Disease Treatment Market Trends
The Latin America rare disease treatment market exhibits high growth potential for the market. driven by improvements in healthcare infrastructure and strong government support. Many countries in the region are investing in modernizing their healthcare systems, which enhances access to advanced diagnostic tools and personalized treatment options.
The Brazil rare disease treatment market is anticipated to grow significantly in the forecast owing to Rare hematologic disorders, such as hemophilia and sickle cell disease, are a critical focus area, supported by public health programs aimed at improving diagnostics and treatments. The rising prevalence of infectious diseases, including certain rare tropical diseases, also drives the need for specialized treatments in Brazil. Moreover, metabolic and endocrine disorders, such as Gaucher’s disease and rare types of diabetes, are experiencing growing awareness and improved access to therapies, aided by collaborations between the government and pharmaceutical companies.
Middle East & Africa Rare Disease Treatment Market Trends
The MEA rare disease treatment market is anticipated to grow significantly in the forecast period. Governments in the region, particularly in the Gulf Cooperation Council (GCC) countries, are prioritizing healthcare advancements and rare disease initiatives through policies, subsidies, and partnerships with global pharmaceutical companies. For instance, in June 2024, the Department of Health-Abu Dhabi and AstraZeneca have joined hands to establish a center for rare diseases in Abu Dhabi to improve the diagnosis and treatment for such diseases.
Saudi Arabia Rare Disease Treatment Market Trends
The Saudi Arabia rare disease treatment market growth is driving the market, largely supported by government funding aimed at enhancing healthcare innovation. Increased investment in research initiatives and the establishment of advanced healthcare facilities are fostering the development of novel therapies, which are essential for improving disease treatment strategies and patient care in the region.
Key Rare Disease Treatment Company Insights
Key players in the rare disease treatment market include Bayer AG, AstraZeneca, Pfizer Inc., and Bristol Myers Squibb Company These leading pharmaceutical companies are at the forefront of developing and manufacturing drugs for disease. With their extensive product portfolios and global market reach, they are well-positioned to address the growing demand for safer and more effective rare disease treatments. By expanding access to affordable options and fostering innovation in drug development, these companies are playing a crucial role in enhancing patient care and improving treatment outcomes in the rare disease management landscape.
Key Rare Disease Treatment Companies:
The following key companies have been profiled for this study on the rare disease treatment market.
-
F. Hoffmann-La Roche Ltd.
-
Pfizer, Inc.
-
PTC Therapeutics Inc.
-
AstraZeneca
-
Novartis AG
-
Takeda Pharmaceutical Company Ltd
-
Bayer AG
-
AbbVie Inc.
-
Merck & Co. Inc.
-
Bristol Myers Squibb Company
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (F. Hoffmann-La Roche Ltd., Pfizer, Inc., Novartis AG, Takeda Pharmaceutical Company Ltd., AstraZeneca)
- Focus on expanding rare disease portfolios through orphan drug development, strategic acquisitions, lifecycle management, and global regulatory approvals. Strengthen market presence through investments in gene therapies, precision medicine, and partnerships with research institutions, patient advocacy groups, and specialized treatment centers.
- Strong orphan drug portfolios supported by extensive clinical development capabilities and global regulatory expertise. Broad commercial infrastructure, established reimbursement relationships, and strong presence across major healthcare markets enable rapid adoption of approved therapies.
- High research and development costs associated with rare disease programs and advanced therapies. Dependence on a limited number of high value products can increase exposure to patent expirations, pricing pressure, and reimbursement challenges.
Emerging and Specialized Players (PTC Therapeutics Inc., Bayer AG, AbbVie Inc., Merck & Co., Inc., Bristol Myers Squibb Company)
- Focus on expanding presence in high unmet need rare disease segments through targeted therapies, gene based treatments, and selective portfolio acquisitions. Emphasize development of therapies for niche patient populations and leverage collaborations with biotechnology companies and academic research organizations to strengthen pipeline assets.
- Strong focus on innovation in specific rare disease indications enables differentiated product positioning. Greater flexibility in pursuing targeted development programs and addressing underserved patient populations compared with larger diversified pharmaceutical companies.
- More limited rare disease product portfolios and lower market penetration across multiple orphan indications compared with established leaders. Dependence on successful clinical outcomes and regulatory approvals for pipeline assets can increase business risk and revenue variability.
Recent Developments
-
In September 2024, the U.S. FDA approved arimoclomol (Miplyffa) drug developed by Zevra Therapeutics for treatment of patient with Niemann-Pick disease type C. This drug is used in combination with Johsnon & Johnson’s Zavesca drug.
-
In June 2024, ANI Pharmaceuticals, Inc. signed an agreement to acquire Alimera Sciences, Inc. to foster their rare disease infrastructure and expand business. ILUVIEN and YUTIQ are two commercial products that have significant growth potential in the market.
-
In January 2024, Sanofi planned to acquire Inhibrx, Inc. to enhance Sanofi’s rare disease portfolio by addition of best-in-class Alpha-1 Antitrypsin Deficiency to pipeline. INBRX-101 is used in the treatment of rare lung infection which will further strengthen company’s position in the market.
Rare Disease Treatment Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 216.2 billion
Market size value in 2026
USD 241.9 billion
Revenue forecast in 2033
USD 483.4 billion
Growth rate
CAGR of 10.4% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Therapeutic area, drug, route of administration, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
F. Hoffmann-La Roche Ltd.; Pfizer, Inc.; PTC Therapeutics Inc.; AstraZeneca, Novartis AG; Takeda Pharmaceutical Company Ltd; Bayer AG; AbbVie Inc.; Merck & Co. Inc.; Bristol Myers Squibb Company.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Rare Diseases Treatment Market Report Segmentation
This report forecasts revenue growth and provides an analysis on the latest trends in each of the sub-segments from 2021 to 2033. For the purpose of this report, Grand View Research has segmented the rare disease treatment market on the basis of therapeutic area, drug, route of administration, distribution channel, and regions.
-
Therapeutic Area Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cancer
-
Neurological Conditions
-
Cardiovascular Conditions
-
Musculoskeletal Conditions
-
Hematologic Disorders
-
Infectious Diseases
-
Metabolic Disorders
-
Endocrine Disorders
-
Others
-
-
Drug Outlook (Revenue, USD Billion, 2021 - 2033)
-
Biologics
-
Biosimilar
-
Small molecules
-
-
Route of Administration Outlook (Revenue, USD Billion, 2021 - 2033)
-
Oral
-
Injectable
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospital Pharmacy
-
Specialty Pharmacy
-
Online Pharmacy
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The rare diseases treatment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each rare diseases treatment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Therapeutic Area
Revenue capture definition
Cancer
Includes therapies used for the treatment of rare malignant diseases, including rare solid tumors and rare hematologic cancers. Products are classified in this segment when the primary treatment objective is cancer management.
Neurological Conditions
Includes therapies used to manage rare disorders affecting the central and peripheral nervous systems. Conditions covered include rare neurodegenerative, neuromuscular, genetic, and developmental neurological disorders.
Cardiovascular Conditions
Includes therapies indicated for rare diseases affecting the heart, blood vessels, pulmonary circulation, and inherited cardiovascular systems. This segment excludes blood disorders classified under hematologic disorders.
Musculoskeletal Conditions
Includes therapies used for rare diseases affecting muscles, bones, joints, connective tissues, and skeletal development. The segment covers inherited and acquired rare musculoskeletal disorders.
Hematologic Disorders
Includes therapies indicated for rare non-oncological blood disorders affecting coagulation, hemoglobin production, platelet function, bone marrow activity, and other hematopoietic processes. This segment excludes rare hematologic cancers classified under Cancer.
Infectious Diseases
Includes therapies used for the treatment and management of rare infectious diseases caused by bacterial, viral, fungal, or parasitic pathogens. Products are classified here when the primary indication is a rare infectious condition.
Metabolic Disorders
Includes therapies used to treat rare inherited or acquired metabolic diseases resulting from enzyme deficiencies, substrate accumulation, or metabolic pathway abnormalities. This segment includes enzyme replacement, substrate reduction, and metabolic correction therapies.
Endocrine Disorders
Includes therapies used for rare diseases affecting hormone production, secretion, regulation, or endocrine gland function. Conditions may involve pituitary, adrenal, thyroid, parathyroid, or other endocrine system abnormalities.
Others
Includes therapies for rare diseases not classified under cancer, neurological, cardiovascular, musculoskeletal, hematologic, infectious, metabolic, or endocrine conditions, including rare dermatological, ophthalmic, respiratory, immunological, renal, and multisystem disorders.
Segment - Drug
Revenue capture definition
Biologics
Includes therapeutic products derived from living organisms or biological processes, including monoclonal antibodies, recombinant proteins, gene therapies, cell therapies, enzyme replacement therapies, and RNA based therapies used for rare diseases.
Biosimilar
Includes biologic products approved as highly similar versions of reference biologics used in rare disease treatment. These products demonstrate no clinically meaningful differences in safety, purity, and efficacy compared with the reference product.
Small Molecules
Includes chemically synthesized therapeutic compounds with defined molecular structures used for the treatment of rare diseases. This segment covers pharmaceutical products that are distinct from biologics and biosimilars.
Segment - Route of Administration
Revenue capture definition
Oral
Includes rare disease therapies administered through the oral route in the form of tablets, capsules, powders, granules, solutions, or suspensions intended for systemic absorption through the gastrointestinal tract.
Injectable
Includes rare disease therapies administered through intravenous, subcutaneous, intramuscular, intrathecal, or other parenteral injection routes. This segment includes biologics, gene therapies, enzyme replacement therapies, and injectable small molecule products.
Others
Includes rare disease therapies administered through nonoral and noninjectable routes, including topical, inhalational, transdermal, ophthalmic, nasal, rectal, and implantable delivery systems.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacy
Includes rare disease therapies dispensed directly through hospital owned pharmacies, academic medical centers, specialty treatment centers, and inpatient healthcare facilities. This segment primarily covers therapies administered or prescribed within hospital based care pathways, including high complexity biologics, gene therapies, enzyme replacement therapies, and injectable treatments requiring clinical supervision.
Specialty Pharmacy
Includes rare disease therapies distributed through specialty pharmacy providers that manage high cost, high complexity, or chronic treatments requiring specialized handling, patient monitoring, reimbursement support, adherence programs, and care coordination. This segment excludes products dispensed through hospital pharmacies and online pharmacies.
Online Pharmacy
Includes rare disease therapies dispensed through licensed digital pharmacy platforms that facilitate prescription fulfillment, home delivery, refill management, and remote patient access. This segment covers products purchased and distributed through online pharmacy channels and excludes therapies supplied through hospital or specialty pharmacy networks.
Estimation Model
 To learn more about this report, Download Free Sample Report
The study incorporated a combination of primary and secondary research methodologies to evaluate the global rare diseases treatment market. Secondary research involved the review of company annual reports, investor presentations, regulatory filings, orphan drug databases, rare disease registries, clinical trial databases, scientific publications, industry journals, and information from pharmaceutical companies, healthcare agencies, and regulatory authorities. Primary research included interviews with rare disease specialists, geneticists, healthcare providers, pharmaceutical executives, researchers, and key opinion leaders to validate disease prevalence, treatment patterns, therapy utilization, and competitive developments.
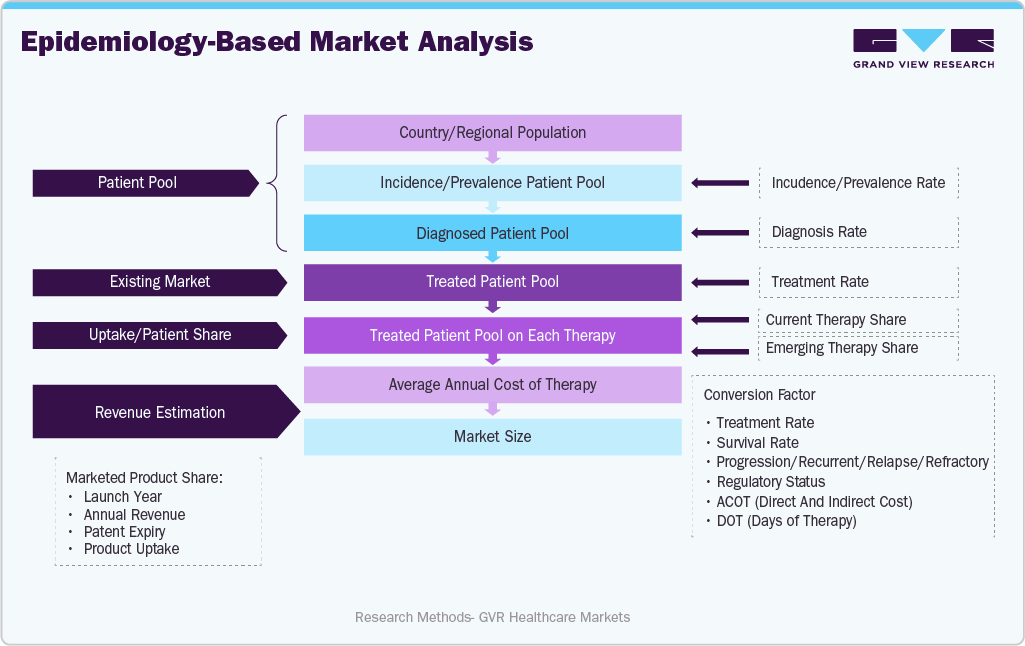
Market estimates were developed using an epidemiology based approach. Disease specific prevalence and incidence data were assessed across major rare disease categories to establish the addressable patient population. Diagnosis rates, treatment eligibility rates, and treatment adoption rates were applied to determine the treated patient pool. Revenue estimates were generated using therapy specific patient volumes, annual treatment costs, dosing patterns, and utilization rates, with findings validated through company sales data and competitive benchmarking.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Orphan Drug Adoption Analysis
Assessment of adoption trends across biologics, gene therapies, enzyme replacement therapies, RNA based therapies, and small molecules, including prescribing patterns, treatment utilization, patient access, and reimbursement dynamics across major rare disease indications and geographic markets.
Helps identify high growth therapeutic segments, treatment shifts, patient access barriers, and opportunities associated with emerging rare disease therapies across key markets.
Patient Identification and Treatment Journey Assessment
Analysis of patient progression from symptom onset through diagnosis, genetic testing, treatment eligibility, therapy initiation, and long-term disease management, including factors affecting treatment access and continuity of care.
Supports identification of diagnostic gaps, treatment delays, patient retention opportunities, and strategies to improve treatment penetration across rare disease populations.
Diagnostic and Genetic Testing Landscape Evaluation
Evaluation of diagnostic trends, genetic screening programs, biomarker testing, newborn screening initiatives, referral pathways, and disease awareness programs influencing rare disease diagnosis and treatment initiation.
Tracks opportunities related to earlier patient identification, improved diagnosis rates, expansion of eligible patient populations, and increased utilization of approved therapies.
Pipeline and Innovation Landscape Assessment
Assessment of emerging therapies, gene editing technologies, cell therapies, RNA based treatments, clinical development activity, regulatory designations, and innovation trends across major rare disease categories.
Identifies future growth opportunities, pipeline maturity, competitive differentiation factors, and therapeutic areas with significant unmet medical needs.
Competitive Benchmarking and Portfolio Analysis
Comparative assessment of approved products, clinical evidence, orphan drug designations, pipeline strength, regulatory approvals, geographic presence, pricing strategies, and strategic initiatives of leading rare disease treatment companies.
Supports competitive intelligence, partnership evaluation, product positioning, acquisition assessment, and strategic decision making within the rare diseases treatment market.
Frequently Asked Questions About This Report
The global rare diseases treatment market size was valued at USD 216.2 billion in 2025 and is estimated at USD 241.9 billion for 2026.
The global rare diseases treatment market is expected to grow at a CAGR of 10.4% from 2026 to 2033, reaching USD 483.4 billion by 2033.
The presence of a strong product pipeline and their expected launches are expected to drive the rare disease treatment market growth.
The cancer segment led with a 28.1% revenue share in 2025.
The biologics segment led with a 57.9% revenue share in 2025.
The injectable segment led with a 65.5% revenue share in 2025.
North America dominated with a 62.4% revenue share in 2025.
Asia pacific is the fastest-growing region over the forecast period.
Key players include Some key players operating in the rare disease treatment market include companies such as F. Hoffmann-La Roche Ltd.; Pfizer, Inc.; PTC Therapeutics Inc.; AstraZeneca, Novartis AG; Takeda Pharmaceutical Company Ltd; Bayer AG; AbbVie Inc.; Merck & Co. Inc.; Bristol Myers Squibb Company.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


