
- Home
- »
- Plastics, Polymers & Resins
- »
-
Recycled Engineering Plastics Market Report, 2026-2033GVR Report cover

Recycled Engineering Plastics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (PC, ABS, Nylon, PET, PBT), By Recycling Process (Mechanical Recycling, Chemical Recycling), By Application, By Region, And Segment Forecasts
Market Size, 2025
$4.9BMarket Estimate, 2026
$5.2BMarket Forecast, 2033
$7.4BCAGR, 2026–2033
7.3%Recycled Engineering Plastics Market Summary
The global recycled engineering plastics market size was valued at USD 4.9 billion in 2025 and is projected to grow from USD 5.2 billion in 2026 to USD 7.4 billion by 2033, at a CAGR of 7.3% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 47.4% in 2025. Industries such as automotive, electronics, and packaging are increasingly using recycled engineering plastics to meet sustainability goals and reduce carbon footprints.
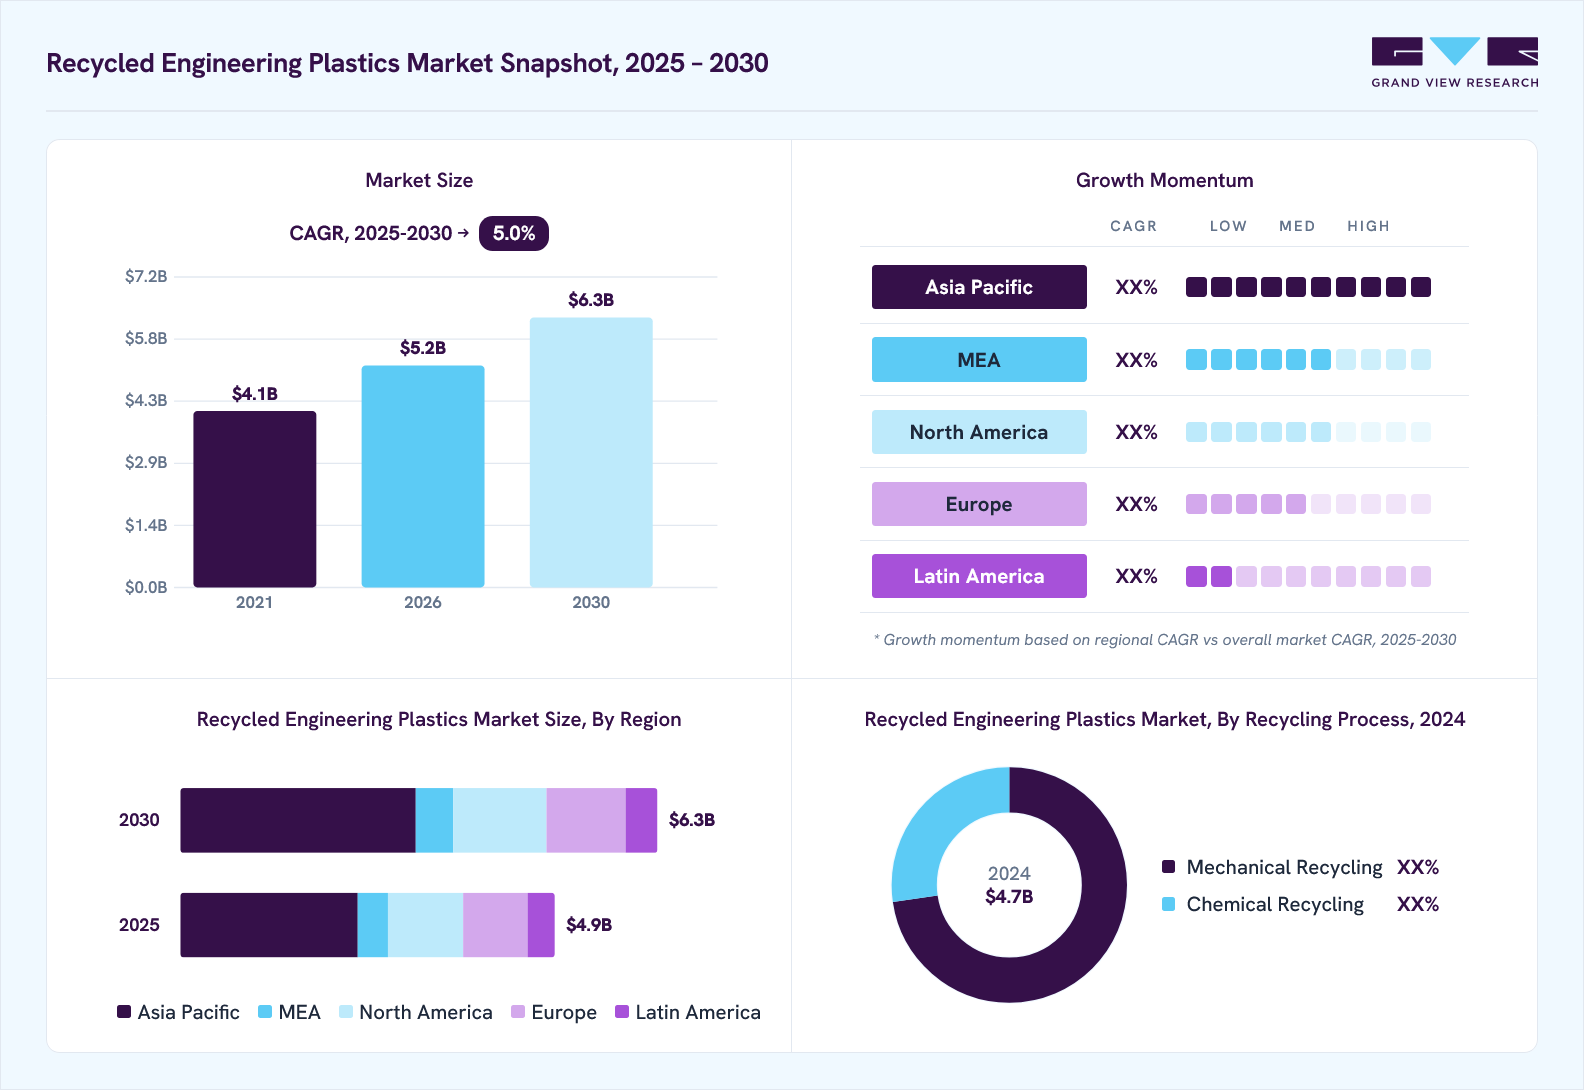 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product type: Polycarbonate (PC) segment held the largest market share of 27.8% in 2025.
- By recycling process: Mechanical recycling segment held the largest market share of 72.9% in 2025.
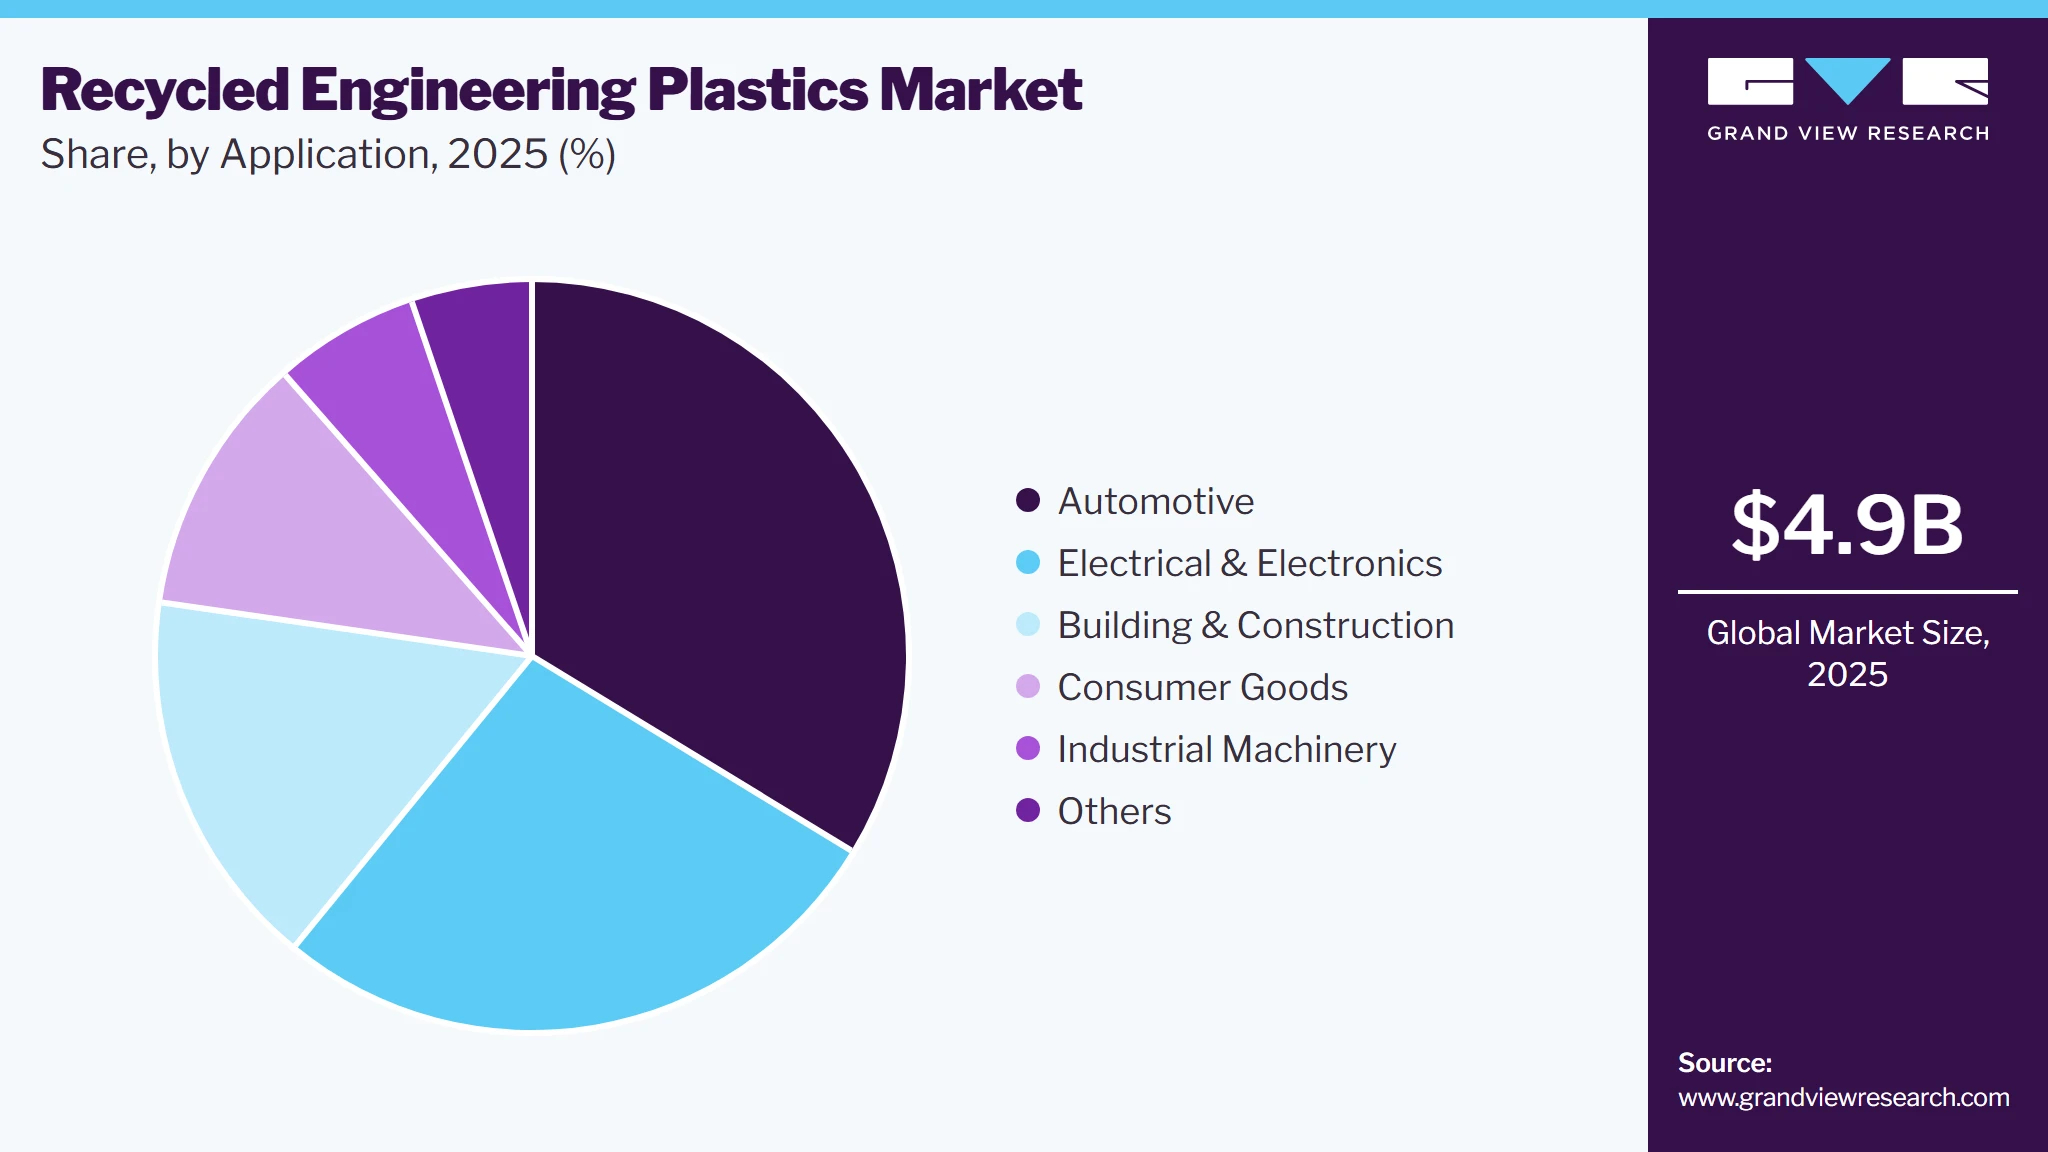
- By application: Automotive segment held the largest market share of 33.7% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (47.4% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 4.9 Billion
- Estimated market size in 2026: USD 5.2 Billion
- Projected market size by 2033: USD 7.4 Billion
- CAGR (2026-2033): 7.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
This shift is driven by corporate ESG commitments and consumer preference for eco-friendly products. A significant trend shaping the recycling of engineering plastics is the increasing adoption of circular economy principles. Governments and multinational corporations are shifting towards closed-loop recycling systems, where high-performance plastics are collected, processed, and reintegrated into new products with minimal degradation.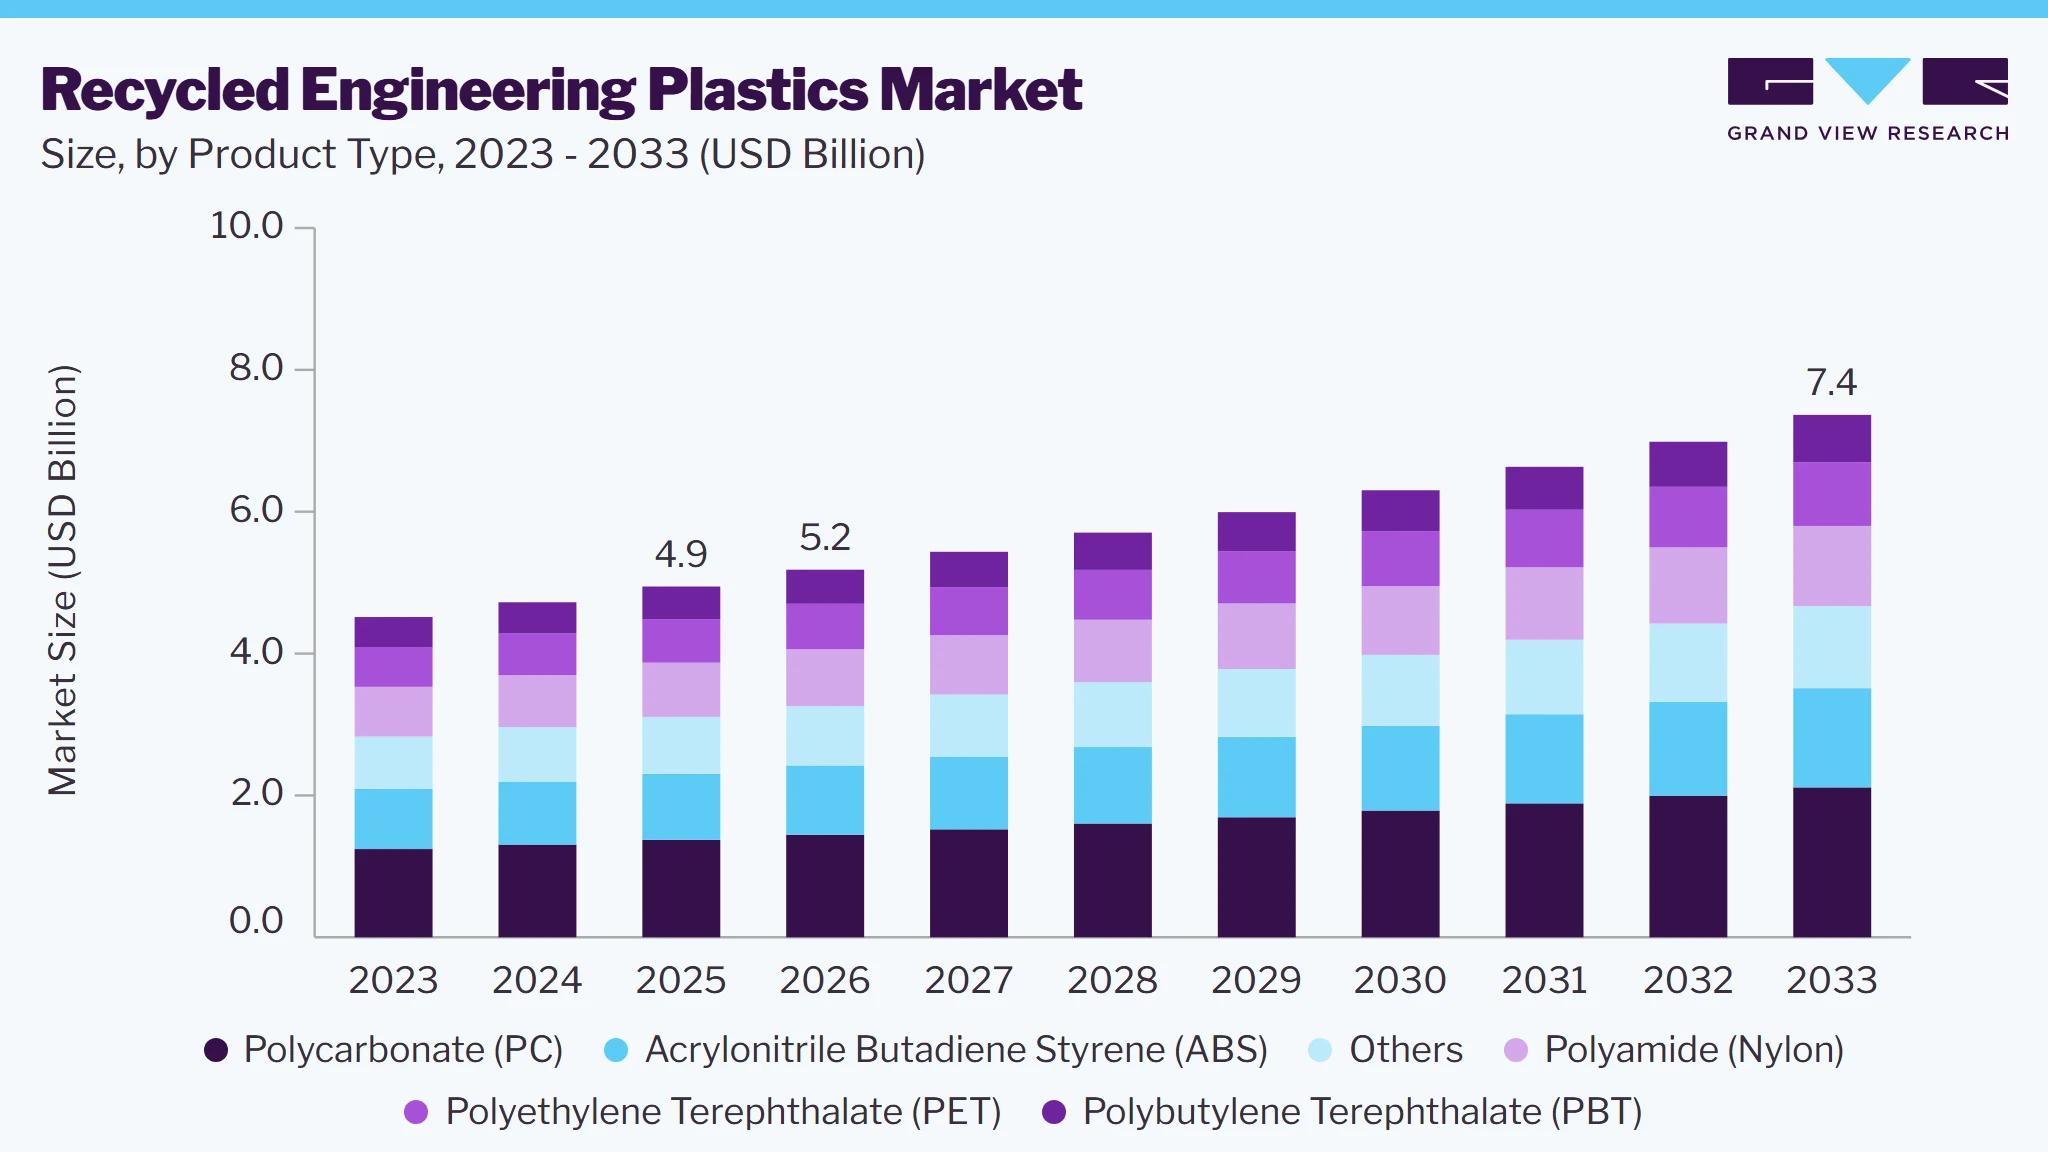 To learn more about this report, Download Free Sample Report
The European Union’s Circular Plastics Alliance and similar programs in North America and Asia are promoting advanced mechanical and chemical recycling technologies to ensure that high-value engineering plastics such as polycarbonates (PC), polyamides (PA), and polyether ether ketone (PEEK) retain their structural integrity for reuse. This trend is accelerating due to regulatory pressures, corporate sustainability targets, and growing consumer demand for eco-friendly materials, fostering innovation in material recovery and reuse.
Market Dynamics
The recycled engineering plastics market is witnessing significant growth, driven by increasing demand for sustainable materials, stringent regulations promoting plastic recycling, and the rising adoption of circular economy practices across industries. Recycled engineering plastics offer comparable mechanical strength, thermal stability, and chemical resistance to virgin engineering plastics while reducing carbon emissions and dependence on fossil-based raw materials. Industries such as automotive, electrical & electronics, consumer goods, industrial equipment, and construction are increasingly utilizing recycled engineering plastics to meet sustainability targets and regulatory requirements. Furthermore, advancements in mechanical and chemical recycling technologies, improved material sorting systems, and enhanced polymer purification processes are improving the quality and performance of recycled engineering plastics, expanding their application across high-value engineering products.
The increasing emphasis on sustainability and resource efficiency is a major driver of the recycled engineering plastics market. Automotive manufacturers, electronics companies, and industrial equipment producers are actively incorporating recycled engineering plastics into their products to reduce environmental impact, lower carbon footprints, and comply with evolving environmental regulations. Governments worldwide are also implementing stricter recycling mandates, extended producer responsibility (EPR) policies, and recycled content requirements, encouraging manufacturers to increase the use of recycled polymers in high-performance applications.
In addition to regulatory support, continuous improvements in recycling technologies have significantly enhanced the quality, consistency, and mechanical properties of recycled engineering plastics. Advanced sorting, compounding, and chemical recycling processes enable manufacturers to produce recycled materials that meet stringent performance standards for automotive components, electrical housings, consumer electronics, and industrial applications. As industries continue to prioritize sustainable manufacturing while maintaining product performance, demand for recycled engineering plastics is expected to grow steadily.
One of the key restraints affecting the recycled engineering plastics market is the inconsistency in recycled material quality and the limited availability of high-grade post-consumer and post-industrial feedstock. Variations in polymer composition, contamination levels, and degradation during recycling can affect mechanical performance, limiting the use of recycled engineering plastics in critical applications. Additionally, advanced recycling, sorting, and purification technologies require substantial investment, increasing production costs and creating challenges for manufacturers seeking consistent material quality at competitive prices.
The growing adoption of advanced chemical recycling technologies and closed-loop manufacturing systems presents a significant opportunity for the recycled engineering plastics market. Chemical recycling enables the recovery of high-purity polymers from complex plastic waste streams, producing recycled engineering plastics with properties comparable to virgin materials. At the same time, manufacturers are increasingly establishing closed-loop recycling partnerships to recover production waste and end-of-life products for reuse in new applications. As investments in recycling infrastructure, digital material traceability, and circular economy initiatives continue to increase, the market is expected to create substantial growth opportunities across automotive, electronics, consumer goods, and industrial manufacturing sectors.
Analyst Perspective
The recycled engineering plastics market has evolved from serving primarily low-value applications to becoming a strategic segment of the advanced materials industry, driven by increasing environmental regulations, corporate sustainability commitments, and significant improvements in recycling technologies. In the past, concerns over inconsistent material quality limited the adoption of recycled engineering plastics in performance-critical applications. However, advancements in mechanical and chemical recycling processes have enabled manufacturers to produce high-quality recycled polymers that meet the stringent performance requirements of automotive, electrical & electronics, industrial machinery, and consumer goods industries. Looking ahead, the market is expected to witness robust growth, supported by expanding circular economy initiatives, rising demand for low-carbon materials, stricter recycled-content mandates, and continuous investments in advanced recycling infrastructure, positioning recycled engineering plastics as a vital component of sustainable manufacturing and next-generation engineering applications.
Product Type Insights
Based on product type, the polycarbonate (PC) segment led the market with the largest revenue share of 27.8% in 2025. The demand for recycled PC is gaining momentum, particularly in high-performance optical and automotive applications where durability, transparency, and heat resistance are crucial. With increasing sustainability mandates, manufacturers are integrating recycled PC into headlamp lenses, electronic display panels, and lightweight vehicle components to reduce carbon footprints without compromising on quality. Companies such as Covestro and SABIC are advancing post-consumer and post-industrial PC recycling to create eco-friendly alternatives that meet stringent regulatory and performance standards. As industries push for greener material solutions, the adoption of recycled PC is expected to accelerate, particularly in Europe and North America, where circular economy frameworks are strongest.
Recycled Acrylonitrile Butadiene Styrene (ABS) is experiencing rising demand, particularly from the consumer electronics sector, as brands transition to circular manufacturing models. Major technology firms, including Apple, Dell, and HP, are incorporating recycled ABS into laptops, keyboards, and home appliances to reduce reliance on virgin plastics and align with sustainability goals. With regulatory bodies such as the EU pushing for higher post-consumer recycled content in electronics, companies are increasingly investing in advanced ABS recycling technologies. This shift is creating a strong market for high-quality recycled ABS, particularly in Asia-Pacific, where large-scale electronics manufacturing hubs are adapting to evolving sustainability requirements.
Recycling Process Insights
Based on recycling process, the mechanical recycling segment led the market with the largest revenue share of 72.9% in 20254, driven by the need for cost-effective and scalable solutions to manage high-volume plastic waste. Mechanical recycling processes, such as shredding, washing, and re-extrusion, provide a more economical alternative to chemical recycling, especially for applications where minor material degradation is acceptable. With governments and industries aiming to increase the proportion of recycled content in consumer goods and industrial components, investment in mechanical recycling infrastructure is growing. Advances in automated sorting and purification technologies are further improving the efficiency of mechanical recycling, making it a viable solution for industries that require sustainable yet cost-efficient material recovery.
Chemical recycling is emerging as a key driver in the engineering plastics market, primarily because it enables the recovery of virgin-quality materials from complex and contaminated plastic waste. Unlike mechanical recycling, which degrades polymer properties over multiple cycles, chemical processes such as solvolysis, depolymerization, and pyrolysis allow plastics to be broken down into their original monomers and repolymerized into high-performance materials. This is particularly beneficial for applications in aerospace, medical, and electronics industries where material purity is critical. As investments in chemical recycling scale up, companies are developing more energy-efficient and commercially viable solutions, expanding the market potential for chemically recycled engineering plastics.
Application Insights
Based on application, automotive segment led the market with the largest revenue share of 33.7% in 2025. The automotive industry's push for lightweight and fuel-efficient vehicles is driving demand for recycled engineering plastics, particularly in interior and structural components. Automakers are replacing traditional metal parts with recycled polyamides, polycarbonates, and ABS to achieve weight reduction while meeting stringent emission standards. In addition, regulatory frameworks such as the EU’s End-of-Life Vehicle Directive (ELV) are mandating higher recycled content in automotive manufacturing, accelerating the adoption of recycled plastics. As electric vehicle (EV) production grows, manufacturers are increasingly turning to sustainable polymer solutions to enhance performance while aligning with sustainability goals.
 To learn more about this report, Download Free Sample Report
The electrical and electronics sector is driving demand for recycled engineering plastics due to increasing regulations on electronic waste (e-waste) disposal and sustainability-focused manufacturing. Governments worldwide are enforcing stricter recycling mandates, requiring manufacturers to incorporate post-consumer recycled content into products such as circuit housings, laptop casings, and connectors. Companies like Lenovo and Samsung are actively integrating recycled ABS and polycarbonate into their product lines to enhance sustainability credentials and comply with regulations such as the EU’s Waste Electrical and Electronic Equipment (WEEE) Directive. With the growing pressure on brands to reduce environmental impact, the use of recycled engineering plastics in electronics manufacturing is becoming a competitive differentiator.
Regional Insights
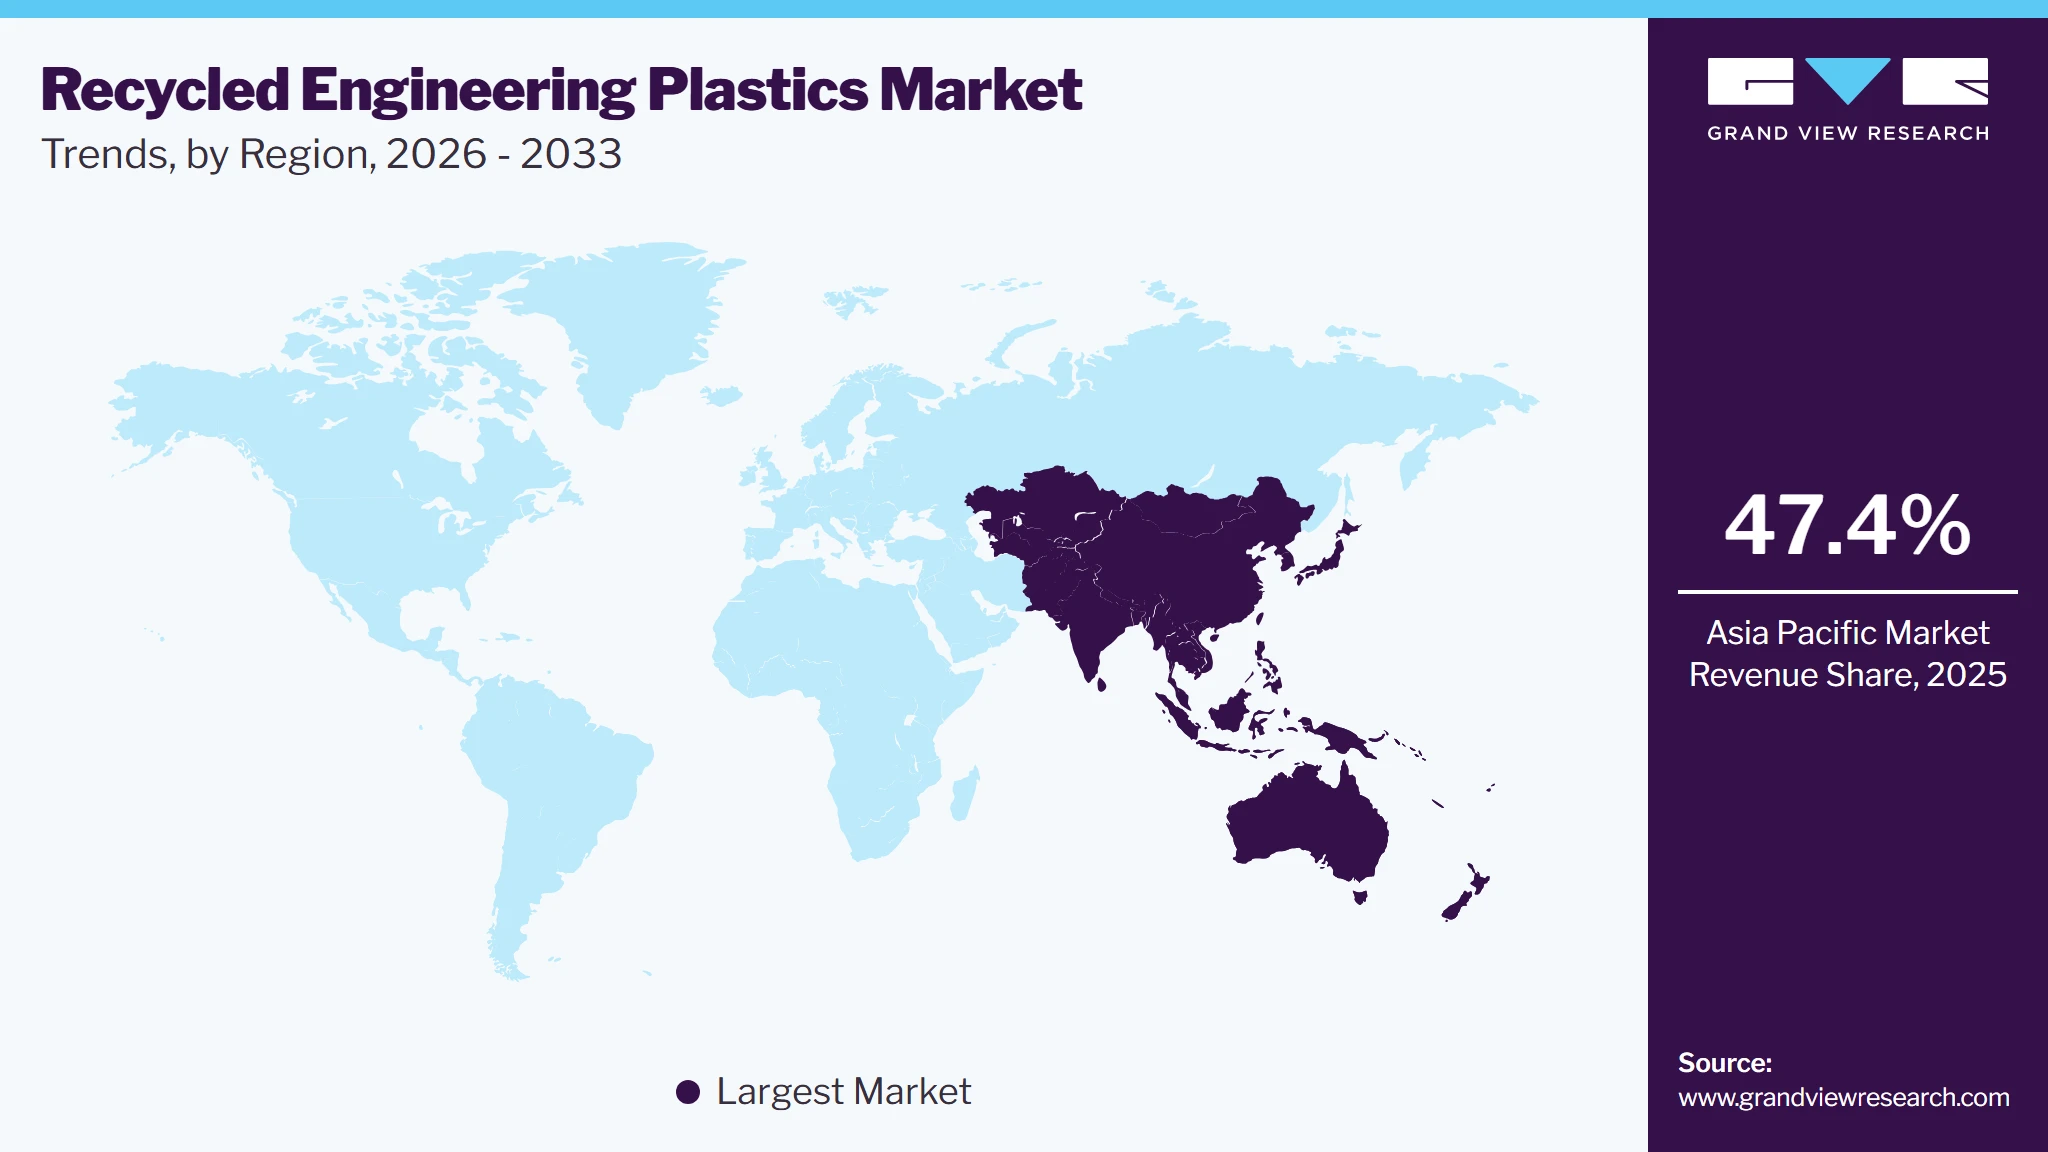
Asia Pacific dominated the recycled engineering plastics market with the largest revenue share of 47.4% in 2025. Asia Pacific is experiencing strong demand for recycled engineering plastics due to the rapid expansion of the electronics and automotive industries. Countries such as India, Japan, and South Korea are increasingly mandating the use of recycled materials in consumer electronics, batteries, and vehicle components to meet sustainability goals. In particular, Japan’s “3R” (Reduce, Reuse, Recycle) initiative and South Korea’s Resource Circulation Act are pushing industries to adopt higher recycled content in production.
 To learn more about this report, Download Free Sample Report
China Recycled Engineering Plastics Market Trends
The recycled engineering plastics market in China held the largest share in the Asia Pacific region in 2025. China’s recycled engineering plastics market is expanding as the country focuses on domestic recycling infrastructure following its National Sword policy, which banned the import of foreign plastic waste. To meet growing domestic demand for sustainable materials, China is investing heavily in mechanical and chemical recycling facilities, particularly for engineering plastics used in automotive and consumer electronics. In addition, the country’s push for electric vehicle (EV) production is driving the need for lightweight, high-performance recycled plastics in battery casings and interior components. With stricter waste management policies and local industries prioritizing recycled content, the market for engineering plastic recycling is set for rapid growth.
North America Recycled Engineering Plastics Market Trends
In North America, the recycled engineering plastics market is expanding due to major corporations committing to circular economy initiatives. Leading automotive, electronics, and packaging companies are integrating recycled polymers into their product lines to meet sustainability targets and address consumer demand for eco-friendly materials. The region is also witnessing increasing investments in advanced recycling infrastructure, with companies such as Eastman and Loop Industries developing chemical recycling plants to convert plastic waste into high-quality resins. With regulatory frameworks such as the Canada Plastics Pact and extended producer responsibility (EPR) programs gaining traction, industries across North America are being pushed to enhance the adoption of recycled engineering plastics.
The U.S. recycled engineering plastics market is being driven by government-backed initiatives and technological advancements in recycling processes. Federal and state-level programs, such as the Bipartisan Infrastructure Law, are allocating funds to improve waste management and recycling technologies, promoting higher recycled content in manufacturing. In addition, private sector investments in advanced sorting, depolymerization, and molecular recycling are enhancing the viability of recycled engineering plastics in industries such as aerospace, automotive, and consumer electronics. Major corporations such as Coca-Cola and Ford are setting aggressive sustainability goals, further increasing the demand for recycled high-performance polymers, including polycarbonates and polyamides.
Europe Recycled Engineering Plastics Market Trends
Europe is at the forefront of the recycled engineering plastics market due to its stringent environmental regulations and circular economy policies. The European Union’s Green Deal and Circular Plastics Alliance are driving industries to incorporate a higher percentage of recycled plastics in manufacturing processes. Directives such as the Waste Framework Directive and the Single-Use Plastics Directive are putting pressure on manufacturers to enhance recyclability and reduce plastic waste. Leading companies in automotive, electronics, and packaging are investing in closed-loop recycling models, while innovations in chemical recycling are allowing high-performance engineering plastics to be reused in critical applications without quality degradation.
Key Recycled Engineering Plastics Company Insights
The recycled engineering plastics market is highly competitive, with several key players dominating the landscape. Major companies include MBA Polymers, Inc., Banyan Nation, Polyplastics Group, Covestro AG, Eastman Chemical Company, Trinseo, Veolia Environnement S.A., Borealis, Dow Inc. and Polyvisions Inc. The recycled engineering plastics market is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their Products.
Key Recycled Engineering Plastics Companies:
The following are the leading companies in the recycled engineering plastics market.
-
MBA Polymers, Inc.
-
Banyan Nation
-
Polyplastics Group
-
Covestro AG
-
Eastman Chemical Company
-
Trinseo
-
Veolia Environnement S.A.
-
Borealis
-
Dow Inc.
-
Polyvisions Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF SE; SABIC; Covestro AG; LyondellBasell Industries N.V.; Ascend Performance Materials; Avient Corporation; Mitsubishi Chemical Group)
- Focus on expanding recycled engineering plastics portfolios, including recycled polycarbonate (PC), ABS, polyamide (PA), PET, PBT, and specialty engineering compounds for automotive, electrical & electronics, consumer goods, industrial machinery, and construction applications. Invest in advanced mechanical and chemical recycling technologies, circular economy initiatives, sustainable material innovation, and strategic collaborations with OEMs, recyclers, and brand owners to increase recycled content in high-performance applications.
- Strong global manufacturing footprint, advanced R&D capabilities, integrated supply chains, and extensive product portfolios enable the supply of high-quality recycled engineering plastics across multiple industries. Established customer relationships, strong sustainability commitments, and continuous investments in advanced recycling technologies strengthen their competitive position in global markets.
- High capital investment requirements for recycling infrastructure, advanced processing technologies, and regulatory compliance increase operational costs. Dependence on the availability of high-quality recycled feedstock, fluctuating raw material prices, and stringent product performance requirements may affect production efficiency and profitability.
Emerging Players (MBA Polymers Inc.; Sirmax Group; Trinseo PLC; Envision Plastics; Genox Recycling Tech Co., Ltd.; B&B Compounds; Quality Circular Polymers (QCP))
- Focus on developing cost-effective recycled engineering plastic compounds tailored to regional automotive, electronics, industrial, and consumer goods manufacturers. Expand market presence through specialized recycling technologies, customized material formulations, strategic partnerships with waste management companies, and investments in mechanical and chemical recycling capabilities to meet growing demand for sustainable engineering materials.
- Greater operational flexibility enables rapid product customization, faster response to customer requirements, and development of application-specific recycled engineering compounds. Strong regional market expertise, competitive pricing, and specialized recycling capabilities help these companies establish long-term relationships with manufacturers seeking sustainable material solutions.
- Limited global manufacturing capacity, smaller geographic presence, and comparatively lower financial resources restrict expansion into large-scale international supply contracts. Lower brand recognition and relatively limited investments in advanced R&D, chemical recycling technologies, and global distribution networks may reduce competitiveness against established multinational engineering plastics manufacturers.
Recent Developments
-
In February 2025, Polyplastics Co., Ltd. announced the launch of a new 40% glass-filled recycled PPS (polyphenylene sulfide) compound. The material aimed to meet rising demand for sustainable materials in automotive and other applications. Polyplastics emphasized strict quality control during production. They also hinted at plans to release higher glass-filled grades in the future.
-
In August 2023, Polyplastics, a Japanese engineering plastics manufacturer, announced the launch of its "Duracircle" recycling service, which was scheduled to commence in March 2024. This service enables Polyplastics' customers to recycle industrial waste materials from their production processes by re-compounding them.
Recycled Engineering Plastics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.9 billion
Estimated market size in 2026
USD 5.2 billion
Projected market size by 2033
USD 7.4 billion
Growth rate
CAGR of 7.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, Volume(kilotons) and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product type, recycling process, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; India; Japan; South Korea; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
MBA Polymers, Inc., Banyan Nation, Polyplastics Group, Covestro AG, Eastman Chemical Company, Trinseo, Veolia Environnement S.A., Borealis, Dow Inc., Polyvisions Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Recycled Engineering Plastics Market Report Segmentation
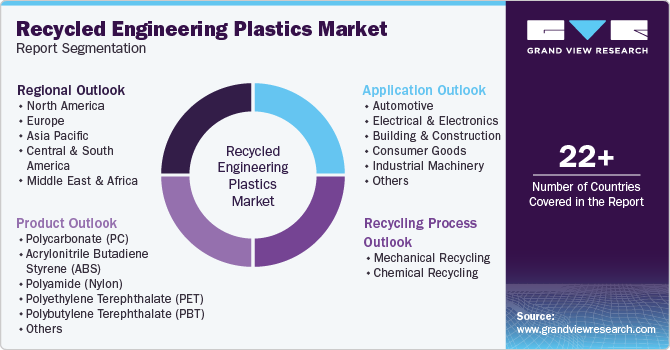
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented recycled engineering plastics market report on the basis of product, recycling process, application, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Polycarbonate (PC)
-
Acrylonitrile Butadiene Styrene (ABS)
-
Polyamide (Nylon)
-
Polyethylene Terephthalate (PET)
-
Polybutylene Terephthalate (PBT)
-
Others
-
-
Recycling Process Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Mechanical Recycling
-
Chemical Recycling
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Automotive
-
Electrical & Electronics
-
Building & Construction
-
Consumer Goods
-
Industrial Machinery
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The recycled engineering plastics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each recycled engineering plastics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product Type
Revenue capture definition
Polycarbonate (PC)
Revenue generated from recycled polycarbonate (PC) engineering plastics used in high-performance applications requiring impact resistance, transparency, and heat stability. Includes materials supplied for automotive components, electrical & electronics housings, consumer goods, industrial equipment, lighting systems, and construction applications.
Acrylonitrile Butadiene Styrene (ABS)
Revenue generated from recycled acrylonitrile butadiene styrene (ABS) engineering plastics used in automotive interiors, consumer electronics, electrical appliances, industrial products, and household goods. Includes recycled ABS compounds, pellets, and customized formulations designed to provide durability, toughness, and dimensional stability.
Polyamide (Nylon)
Revenue generated from recycled polyamide (nylon) engineering plastics used in automotive parts, electrical connectors, industrial machinery, consumer products, and engineering components. Includes recycled nylon resins and compounds offering high mechanical strength, wear resistance, and thermal performance.
Polyethylene Terephthalate (PET)
Revenue generated from recycled polyethylene terephthalate (PET) engineering plastics used in automotive components, electrical & electronics, packaging, textile fibers, industrial products, and consumer goods. Includes recycled PET resins and engineering-grade compounds manufactured from post-consumer and post-industrial PET waste.
Polybutylene Terephthalate (PBT)
Revenue generated from recycled polybutylene terephthalate (PBT) engineering plastics used in electrical & electronic components, automotive systems, industrial equipment, and precision engineering applications. Includes recycled PBT compounds and resins offering excellent electrical insulation, chemical resistance, and dimensional stability.
Others
Revenue generated from recycled engineering plastics not classified under polycarbonate, ABS, polyamide, PET, or PBT. Includes recycled polyoxymethylene (POM), polyphenylene oxide (PPO), polyphenylene sulfide (PPS), thermoplastic polyesters, and other specialty engineering plastics used in automotive, aerospace, industrial, medical, and electrical applications.
Segment - Recycling Process
Revenue capture definition
Mechanical Recycling
Revenue generated from recycled engineering plastics produced through mechanical recycling processes, including collection, sorting, cleaning, shredding, melting, and reprocessing of post-consumer and post-industrial plastic waste. Includes recycled engineering plastic pellets, granules, and compounds used in automotive, electrical & electronics, industrial equipment, consumer goods, and construction applications.
Chemical Recycling
Revenue generated from recycled engineering plastics produced through chemical recycling technologies, including depolymerization, pyrolysis, solvolysis, and other advanced recycling processes that recover high-purity polymer feedstocks. Includes engineering-grade recycled resins and compounds used in high-performance automotive, electronics, industrial, medical, and consumer applications requiring properties comparable to virgin engineering plastics.
Segment - Application
Revenue capture definition
Automotive
Revenue generated from recycled engineering plastics used in automotive applications, including interior and exterior components, under-the-hood parts, lighting systems, bumpers, dashboards, engine covers, connectors, and structural components requiring high strength, durability, and thermal resistance.
Electrical & Electronics
Revenue generated from recycled engineering plastics used in electrical and electronic applications, including connectors, circuit breaker housings, electrical enclosures, switches, sockets, consumer electronics, electrical appliances, and electronic device components requiring excellent insulation and dimensional stability.
Building & Construction
Revenue generated from recycled engineering plastics used in building and construction applications, including pipes, fittings, insulation components, cable management systems, panels, profiles, window systems, and other structural and non-structural construction products requiring durability and environmental resistance.
Consumer Goods
Revenue generated from recycled engineering plastics used in consumer goods, including household appliances, furniture, sports equipment, luggage, storage products, personal care products, toys, and other durable consumer products manufactured using recycled engineering-grade polymers.
Industrial Machinery
Revenue generated from recycled engineering plastics used in industrial machinery and equipment, including gears, bearings, machine housings, conveyor components, rollers, pump parts, valves, and precision engineering components requiring high mechanical strength, wear resistance, and chemical resistance.
Others
Revenue generated from recycled engineering plastics used in other applications not covered under the above categories. Includes aerospace, healthcare, agriculture, telecommunications, packaging, renewable energy, marine, and specialty engineering applications utilizing recycled engineering-grade plastic materials.
Estimation Model
Layer Name
Key Question
Description
Engineering Plastics Demand Base Layer
What forms the demand base?
Identify the global demand generated by industries including automotive, electrical & electronics, building & construction, consumer goods, industrial machinery, healthcare, and aerospace that require high-performance engineering plastics. This layer establishes the total addressable market based on manufacturing output, industrial production, vehicle manufacturing, electronics production, infrastructure development, and the increasing adoption of sustainable materials across developed and emerging economies.
Recycled Engineering Plastics Adoption Layer
Where are recycled engineering plastics utilized?
Estimate the adoption of recycled engineering plastics across major application industries, including automotive, electrical & electronics, building & construction, consumer goods, industrial machinery, and other engineering applications. Assess the penetration of recycled polycarbonate (PC), ABS, polyamide (nylon), PET, PBT, and other engineering plastics based on performance requirements, sustainability initiatives, recycled content targets, and regulatory compliance.
Material Utilization Intensity Layer
How much recycled engineering plastic is utilized?
Analyze the volume of recycled engineering plastics consumed based on production volumes, component weight, recycled content requirements, product lifecycle, and application-specific material demand. Material utilization is influenced by manufacturing capacity, recycling efficiency, availability of post-consumer and post-industrial feedstock, advancements in mechanical and chemical recycling technologies, and increasing investments in circular economy initiatives.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of recycled engineering plastics manufactured using mechanical and chemical recycling processes, including recycled polycarbonate (PC), ABS, polyamide (nylon), PET, PBT, and other specialty engineering plastics. Revenue is generated from demand across automotive, electrical & electronics, building & construction, consumer goods, industrial machinery, and other industrial sectors seeking high-performance, sustainable materials that reduce environmental impact while meeting engineering and regulatory requirements.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed regional analysis of the Recycled Engineering Plastics Market across North America, Europe, Asia Pacific, Central & South America, and the Middle East & Africa. Includes market size, revenue forecasts, recycling infrastructure, regulatory landscape, feedstock availability, end-use demand, and growth opportunities by country and region.
Enables identification of high-growth regional markets, supports geographic expansion strategies, optimizes investment decisions, and assists stakeholders in prioritizing regions based on demand, recycling capabilities, and regulatory developments.
Competitive Benchmarking
Comprehensive benchmarking of leading recycled engineering plastics manufacturers based on product portfolio, recycling technologies (mechanical and chemical), production capacity, geographic presence, sustainability initiatives, strategic partnerships, mergers & acquisitions, R&D capabilities, and innovation pipeline.
Helps evaluate competitive positioning, identify technology and product gaps, support strategic planning, and benchmark organizational capabilities against key industry participants.
Pricing Analysis
In-depth pricing analysis of recycled engineering plastics across product types (PC, ABS, Polyamide, PET, PBT, and others), recycling processes (mechanical and chemical), and major regional markets. Includes feedstock price trends, processing costs, regional price variations, virgin versus recycled material price comparisons, and competitive pricing analysis.
Supports pricing optimization, procurement planning, supplier evaluation, cost competitiveness analysis, and informed decision-making for sourcing, product positioning, and long-term contract negotiations.
Frequently Asked Questions About This Report
Key players in the recycled engineering plastics market include MBA Polymers, Inc., Banyan Nation, Polyplastics Group, Covestro AG, Eastman Chemical Company, Trinseo, Veolia Environnement S.A., Borealis, Dow Inc., and Polyvisions Inc..
The recycled engineering plastics market is primarily driven by increasing demand for sustainable materials, stringent environmental regulations promoting plastic recycling, growing adoption of circular economy practices, rising recycled-content requirements in the automotive and electronics industries, and advancements in mechanical and chemical recycling technologies.
The global recycled engineering plastics market size was valued at USD 4.9 billion in 2025 and is estimated at USD 5.2 billion for 2026.
Asia Pacific is the fastest-growing region in the recycled engineering plastics market, registering a CAGR of 8.5% over the forecast period.
The Polycarbonate segment led the recycled engineering plastics market with a revenue share of 27.8%in 2025, driven by its widespread availability, excellent recyclability, and growing demand across packaging, automotive, consumer goods, and industrial applications.
The Mechanical Recycling segment led the recycled engineering plastics market with a revenue share of 72.9% in 2025, owing to its cost-effectiveness, established recycling infrastructure, and extensive adoption for processing post-consumer and post-industrial engineering plastics.
The Automotive segment led the recycled engineering plastics market with a revenue share of 33.7% in 2025, driven by increasing demand for lightweight, high-performance, and sustainable materials to improve vehicle fuel efficiency and meet environmental regulations.
The global recycled engineering plastics market is expected to grow at a CAGR of 7.3% from 2026 to 2033, reaching USD 7.4 billion by 2033.
Asia Pacific dominated the recycled engineering plastics market with a revenue share of 47.4% in 2025.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


