
- Home
- »
- Digital Media
- »
-
Retail Media Networks Market Size & Share Report, 2033GVR Report cover

Retail Media Networks Market (2026 - 2033)
Size, Share, & Trends Analysis Report By Advertising Format (Display Ads, Video Ads, Sponsored Products), By Platform Type (Retailer-Owned Networks, Third-Party Networks), By End Use, And Segment Forecasts
Market Size, 2025
$30.7BMarket Estimate, 2026
$34.2BMarket Forecast, 2033
$68.8BCAGR, 2026–2033
10.5%Retail Media Networks Market Summary
The global retail media networks market size was valued at USD 30.7 billion in 2025 and is projected to grow from USD 34.2 billion in 2026 to USD 68.8 billion by 2033, at a CAGR of 10.5% from 2026 to 2033. The market in North America dominated with a revenue share of 35.3% in 2025. This growth is driven by rising shift of digital advertising budgets toward retail-owned media platforms.
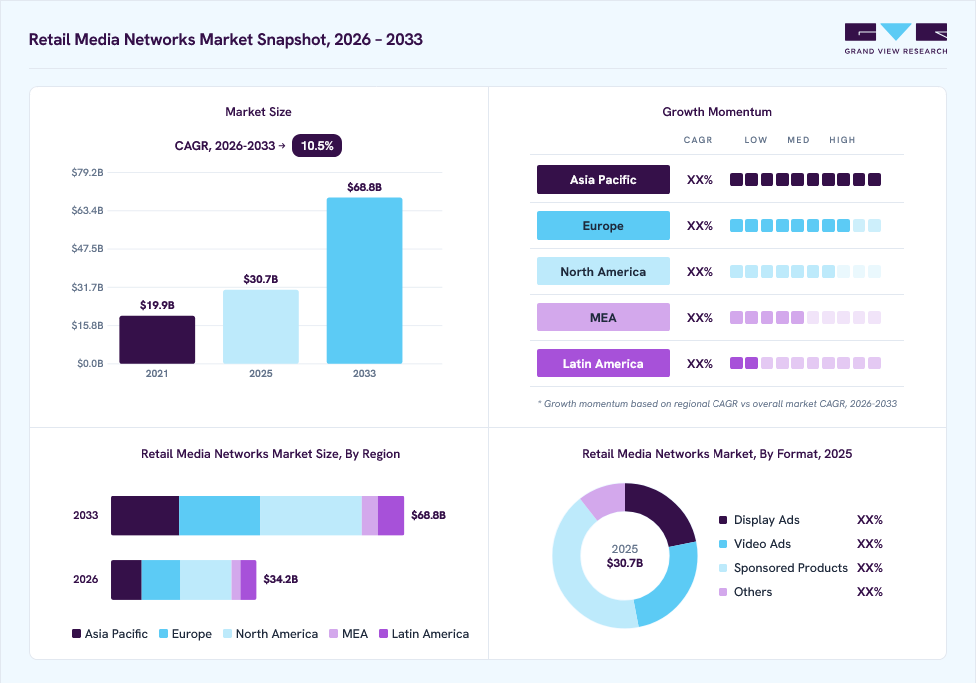 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By platform type: Retailer-owned networks segment held the largest market share of 70.0% in 2025.
- By advertising format: Sponsored products segment held the largest market share of 42.4% in 2025.
- By end use: Consumer packaged goods segment held the largest market share of 24.9% in 2025.
Regional Highlights
- Largest regional market: North America (35.3% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 30.7 Billion
- Estimated market size in 2026: USD 34.2 Billion
- Projected market size by 2033: USD 68.8 Billion
- CAGR (2026-2033): 10.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
This trend has been accelerated by the convenience and variety offered by online platforms, prompting brands to leverage retail media networks to maintain visibility and engagement with their target audiences. Moreover, changing consumer shopping habits, including increased reliance on mobile devices and online platforms, are prompting retailers to invest in retail media networks to connect with consumers.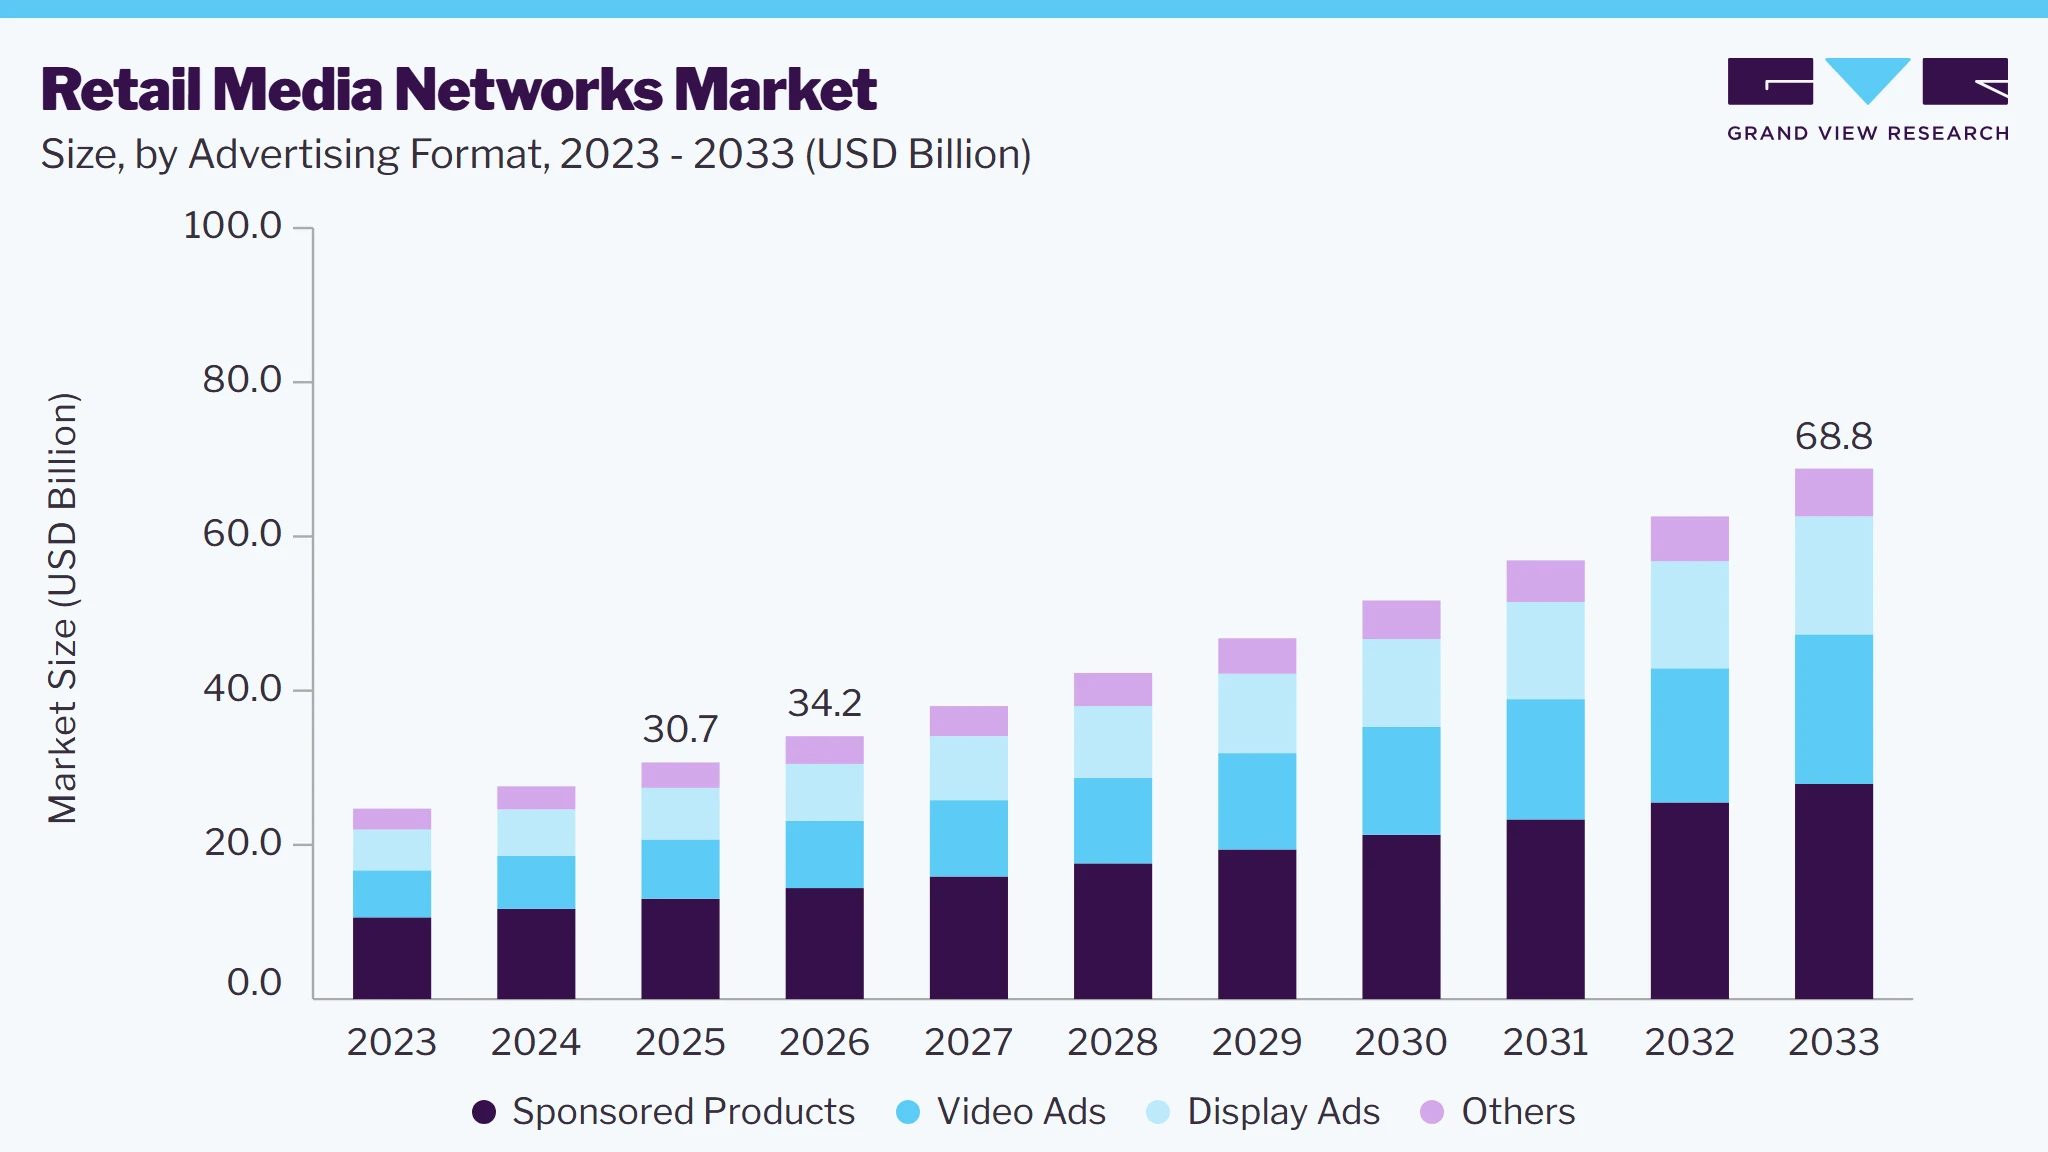 To learn more about this report, Download Free Sample Report
Retailers have access to vast amounts of first-party data, enabling more precise targeting of ads based on customer behavior and preferences. This level of personalization improves the effectiveness of ads, helping brands reach their ideal audience while enhancing the shopping experience for consumers. In an era where third-party cookies are being phased out, retailers' proprietary data becomes a key asset in digital advertising.
The shift in advertising budgets from traditional media to digital platforms also supports retail media networks (RMN) growth. Brands are increasingly allocating more resources to retail media as they seek higher returns on investment. Since RMNs offer a clear path to purchase, they provide better attribution for ad spend, driving demand for this advertising model.
The expansion of retail ecosystems and the integration of physical and digital channels play a crucial role in the growth of RMNs. Retailers are creating seamless omnichannel experiences, allowing them to reach customers both in-store and online. This enhances the potential for cross-channel advertising campaigns, further boosting the RMN market.
Moreover, the increasing need for first-party data utilization in retail media is boosting the market growth. As third-party cookies decline, retailers are seeking innovative solutions to capitalize on their vast consumer data, enabling more personalized and effective advertising strategies that drive higher returns on ad spend. For instance, in September 2024, Pentaleap GmbH, a retail media technology provider, announced the launch of its modular retail media platform. The platform aims to maximize the potential of retail media networks (RMNs) for onsite monetization and fosters an open and efficient ecosystem for both RMNs and advertisers. The Publisher Manager portal provides complete control over site monetization through tools, enabling increased revenue without compromising relevance for RMNs.
Market Dynamics
The retail media networks market is experiencing rapid growth as retailers increasingly monetize their digital platforms by offering targeted advertising opportunities to brands across websites, mobile applications, and in-store digital channels. The availability of first-party consumer data enables advertisers to deliver highly personalized campaigns, measure performance more accurately, and directly connect advertising spend with purchasing behavior. Growing concerns about third-party cookie deprecation, combined with the continued expansion of e-commerce and omnichannel retailing, are encouraging brands to shift a larger share of their digital advertising budgets toward retail media platforms. Additionally, advances in programmatic advertising, AI-driven audience targeting, and closed-loop measurement capabilities are further accelerating market adoption.
The rapid expansion of online grocery and quick commerce platforms is driving growth in the retail media networks market by creating high-frequency digital shopping environments where brands can engage consumers at the point of purchase. Grocery and quick commerce applications are accessed regularly for everyday essentials, resulting in repeated customer interactions and a continuous stream of purchase-intent data. Retail media networks leverage this valuable first-party data to deliver highly targeted advertisements, sponsored product listings, personalized promotions, and brand recommendations based on customer preferences and buying behavior. This level of precision significantly improves advertising effectiveness compared to traditional digital advertising channels while increasing conversion rates for advertisers. As online grocery and rapid-delivery platforms continue to expand their customer bases, demand for retail media advertising solutions continues to accelerate.
According to a 2025 report by the Food Industry Association, online sales accounted for approximately 72% of total grocery dollar growth, highlighting the expanding role of e-commerce in the grocery sector. Additionally, 49% of shoppers now purchase through both online and in-store channels, reflecting the widespread adoption of omnichannel shopping. While in-store grocery sales are projected to grow at a modest 0.62% CAGR between 2026 and 2028, e-commerce fulfillment continues to shift toward delivery and shipping, which accounted for nearly 80% of online grocery sales in 2025, increasing by approximately 2% points from the previous year, whereas pickup's share declined by around 2% points during the same period.
Data privacy regulations that affect customer data utilization and targeting capabilities are constraining growth in the retail media networks market by limiting how retailers collect, process, store, and activate consumer information for advertising purposes. Retail media platforms rely heavily on first-party customer data generated through online purchases, loyalty programs, mobile applications, browsing behavior, and in-store transactions to deliver highly personalized advertisements. As data privacy requirements become more comprehensive across jurisdictions, retailers must obtain explicit customer consent, maintain transparent data governance practices, and provide greater control over the use of personal information. These compliance obligations reduce the volume of customer data available for advertising segmentation and campaign optimization. The increasing complexity of privacy requirements creates operational challenges that slow the expansion of highly targeted retail media strategies.
The expansion of omnichannel retail ecosystems is propelling market growth by allowing retail media networks to deliver seamless advertising experiences across connected shopping environments. Retailers increasingly combine online stores, mobile applications, physical outlets, loyalty programs, in-store digital displays, self-checkout systems, and customer relationship management platforms into unified operational ecosystems. Retail media platforms can utilize data generated from these interconnected channels to deliver highly relevant advertisements at different stages of the customer journey. Consumers receive personalized product recommendations whether they are browsing online, shopping in physical stores, or using retailer mobile applications. The continuous evolution of omnichannel retail infrastructure contributes to market growth by expanding advertising opportunities beyond traditional digital channels.
Analyst Perspective
The retail media networks market is reshaping the digital advertising landscape by positioning retailers as media owners rather than solely product distributors. Competitive advantage is increasingly determined by the quality of first-party shopper data, the scale of retail audiences, and the ability to demonstrate measurable sales attribution instead of traditional advertising metrics such as impressions and clicks. As brands demand greater accountability for marketing investments, retail media platforms that can provide transparent performance measurement, seamless omnichannel campaign execution, and self-service advertising capabilities are likely to attract higher advertising budgets. Over the long term, the market is expected to evolve into a strategic profit center for retailers, with advertising revenues becoming an increasingly important contributor alongside conventional merchandising and retail operations.
Advertising Format Insights
Based on advertising format, the sponsored products segment led the market with the largest revenue share of 42.4% in 2025. The growing importance of SKU-level marketing is driving growth in Sponsored Products as advertisers increasingly promote individual products rather than relying solely on broad brand campaigns. Product-level advertising allows brands to assign advertising budgets to specific SKUs, product categories, price points, seasonal products, and inventory priorities. This approach creates a closer relationship between advertising decisions and merchandising strategies. Retailers can provide advertisers with placement environments that correspond directly with individual products and shopping categories. The growing need to coordinate advertising with product portfolios contributes to market growth for Sponsored Products within retail media networks. The market impact includes increased demand for SKU-level campaign management, product-specific bidding, keyword targeting, and automated product promotion tools.
The video ads segment is anticipated to grow at the significant CAGR over the forecast period. The surge in online shopping has created more opportunities for video ad placements across digital retail environments, such as product pages, checkout screens, and homepages. As more consumers spend time browsing e-commerce platforms, video ads serve as a medium to provide product demonstrations, tutorials, or brand stories, making them highly influential in the consumer decision-making process.
Platform Type Insights
Based on platform type, the retailer-owned networks segment led the market with the largest revenue share of 70.0% in 2025.The rise of privacy regulations, such as the General Data Protection Regulation (GDPR) and the phasing out of third-party cookies, has made first-party data more critical than ever. Retailers, who already have direct relationships with consumers, are well-positioned to capitalize on this regulatory shift. Brands are increasingly turning to retailer-owned networks to reach audiences in a compliant manner, as these networks provide access to first-party data without infringing on privacy rules.
The third-party networks segment is anticipated to grow at the significant CAGR over the forecast period. Brands are increasingly looking for seamless integration across various platforms to maintain consistent messaging and branding across both retailer-owned media and third-party networks. As retailers collaborate with third-party networks, they create an ecosystem where advertisers can manage their campaigns more holistically, ensuring that ad messaging aligns across the entire digital landscape. This approach not only strengthens brand recall but also improves conversion rates as consumers encounter ads at multiple touchpoints
End Use Insights
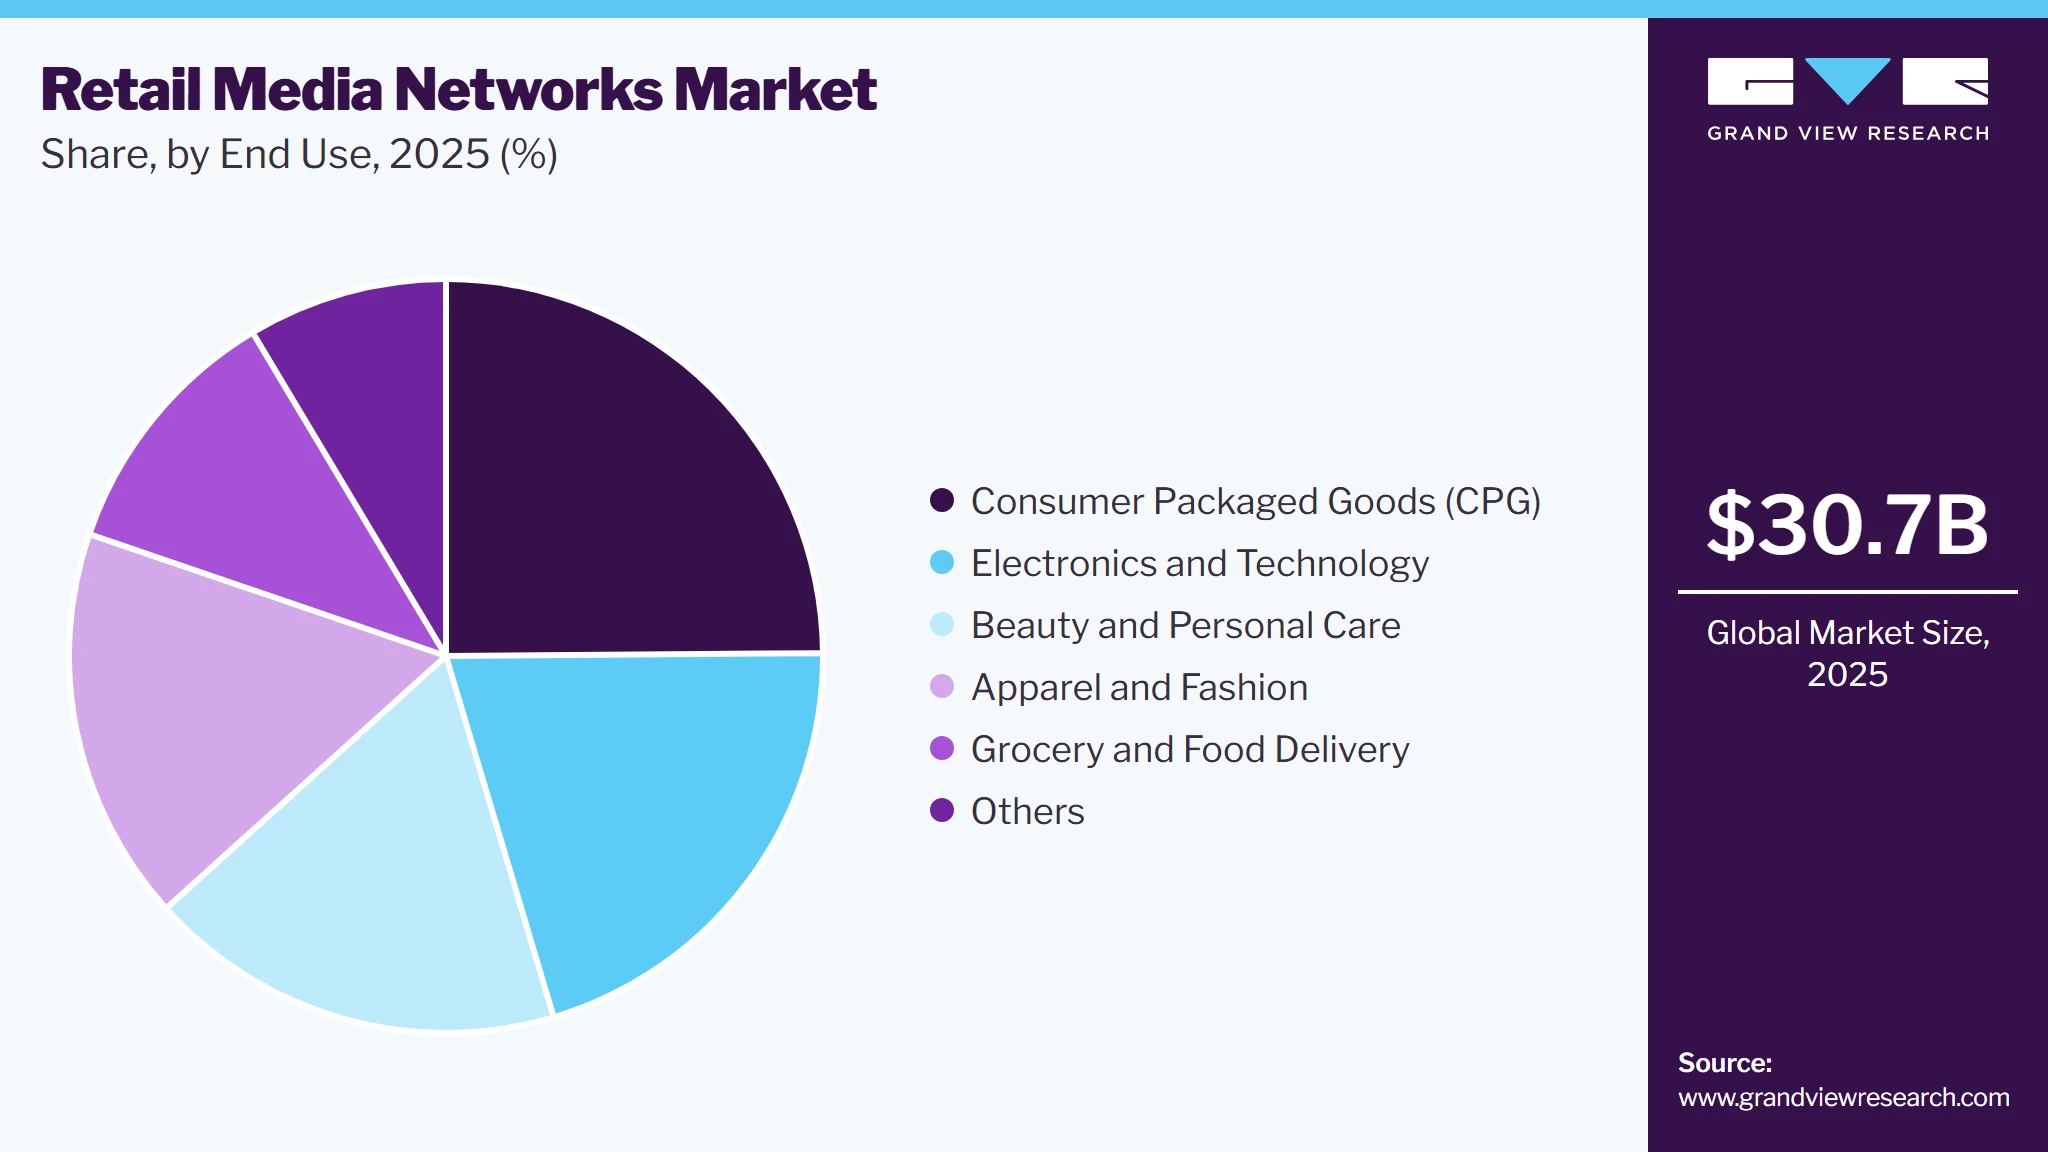
Based on end use, the consumer packaged goods segment led the market with the largest revenue share of 24.9% in 2025. The increasing adoption of direct-to-consumer strategies by CPG brands is a key driver for RMN growth. By partnering with retailers through RMNs, CPG brands can replicate some of the benefits of D2C models, such as owning a direct channel for communication with customers. RMNs give CPG companies access to consumer data that helps in understanding shopping behavior and tailoring offers, similar to D2C platforms.
 To learn more about this report, Download Free Sample Report
The beauty and personal care segment is anticipated to grow at the significant CAGR over the forecast period owing to the increasing influence of social commerce and influencer marketing in the beauty industry. RMNs integrate these trends by offering advertisers the ability to run interactive, shoppable ads that combine the appeal of influencer-driven content with the convenience of direct purchasing options. This approach boosts brand visibility and encourages impulse purchases, particularly in the beauty and personal care category, where product trial and experimentation are common consumer behaviors.
Regional Insights
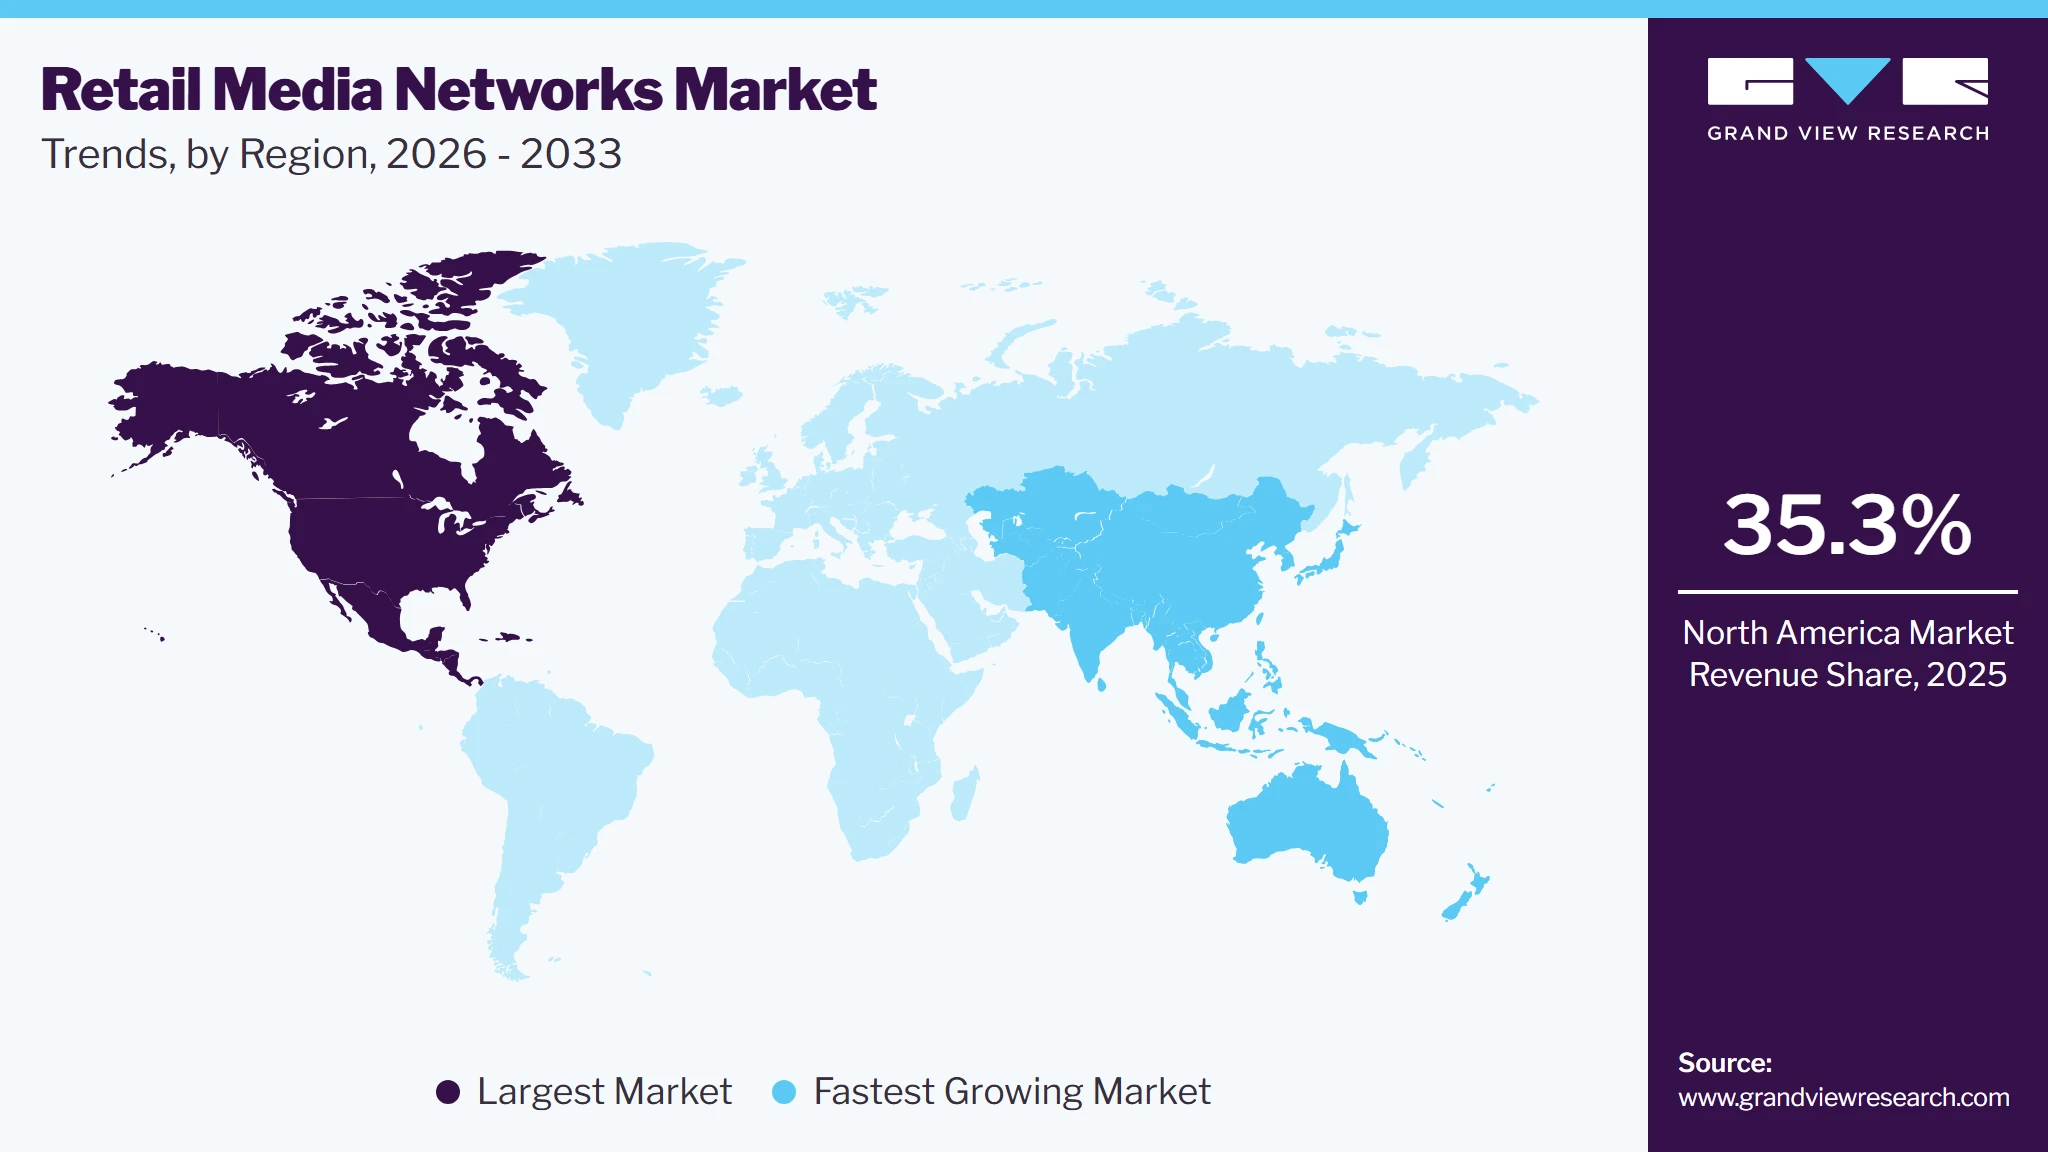
North America dominated the global retail media networks market with the largest revenue share of 35.3% in 2025. Programmatic advertising is becoming more prevalent within RMNs in North America. By automating the ad-buying process, programmatic tools allow retailers and brands to run more efficient, data-driven campaigns. Real-time bidding (RTB) and advanced audience segmentation ensure that ads are served to the right shoppers at the right time, improving both the relevance of ads and return on investment (ROI). Retailers are also integrating AI and machine learning to optimize ad placements and performance. For instance, in April 2024, Walmart, a leading U.S. retailer, revealed its expansion plans for its Retail Media Network, Walmart Connect. These plans aim to boost advertiser participation, introduce new ad formats, and enhance measurement tools to better demonstrate the platform's effectiveness.
 To learn more about this report, Download Free Sample Report
U.S. Retail Media Networks Trends
The retail media networks market in the U.S. held the largest share in the North America region in 2025. Many U.S. retailers are creating their own media properties and ecosystems to support RMN growth. These include custom content platforms, shoppable ads, and branded content opportunities. For example, Kroger Precision Marketing (KPM) offers brands access to targeted digital and programmatic advertising across its network of grocery platforms. Retailers are positioning themselves as both commerce and media companies, offering brands comprehensive solutions that go beyond traditional advertising.
Europe Retail Media Networks Trends
The retail media networks market in Europe is growing significantly at a CAGR of 11.1% from 2026 to 2033. Retailers in the region are increasingly leveraging first-party data to offer precise targeting and measurement capabilities, enhancing the effectiveness of advertising campaigns. According to IAB Europe, European-level association for the digital marketing and advertising ecosystem over 90% of advertisers are partnering with retailers to reach consumers at critical points in their purchasing journey.
Asia Pacific Retail Media Networks Trends
The retail media networks market in Asia Pacific is expected to grow at the fastest CAGR of 12.1% from 2026 to 2033. Increasing disposable incomes across the Asia Pacific region are enabling consumers to spend more on goods and services, thereby boosting retail activity and creating a favorable environment for retail media networks. Moreover, the region has a vast mobile user base, allowing retailers to engage consumers directly through mobile devices with tailored advertising. This mobile-centric approach is crucial for reaching tech-savvy consumers who prefer shopping on their smartphones.
Key Retail Media Networks Company Insights
Key players operating in the retail media networks market include Amazon, Best Buy, eBay Inc., Target, and Walmart. The companies are focusing on various strategic initiatives, including new product development, partnerships & collaborations, and agreements to gain a competitive advantage over their rivals. The following are some instances of such initiatives.
-
In March 2024, Lowe's partnered with Google to create a new retail media solution that combines Lowe's extensive customer data with Google's advertising technology. This collaboration aims to provide targeted advertising opportunities for brands in the home improvement sector, allowing them to engage effectively with consumers across Google Search and Shopping platforms. The initiative is part of a closed beta program, marking Lowe's as one of the first retailers to test this approach to advertising.
-
In April 2024, Home Depot rebranded its advertising division from Retail Media+ to Orange Apron Media. This change reflects the company's commitment to enhancing its retail media network and attracting more brands to advertise on its platform. The new name draws inspiration from the orange aprons worn by employees, symbolizing service and expertise, and aims to differentiate Home Depot in the competitive retail media landscape.
-
In May 2023, Instacart, partnered with independent grocers to help them establish and grow their retail media networks using Carrot Ads, an on-site advertising technology. This collaboration allows advertisers to more easily and effectively promote their products across a wide network of local grocery stores, supporting the communities they serve by driving sales for both the retailers and brands.
Key Retail Media Networks Companies
The following key companies have been profiled for this study on the retail media networks market.
-
Amazon
-
Albertsons
-
Best Buy
-
Carrefour
-
CVS Health
-
eBay Inc.
-
Home Depot
-
Instacart
-
Kroger
-
Lowe’s
-
Sephora
-
Target
-
Walmart
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (Amazon Ads; Walmart Connect; Criteo; The Trade Desk; Instacart Ads)
- Mature players focus on expanding retailer-owned advertising ecosystems by integrating first-party shopper data, omnichannel advertising solutions, and advanced campaign measurement capabilities.
- They emphasize AI-driven audience targeting, closed-loop attribution, and strategic partnerships with retailers, brands, and agencies to improve advertising effectiveness and maximize monetization across digital and physical retail channels.
- These companies benefit from extensive relationships with retailers, large volumes of first-party consumer data, and mature advertising platforms that deliver measurable campaign performance.
- Their global presence, advanced analytics capabilities, and strong advertiser networks enable scalable, data-driven advertising solutions with high customer trust.
- Large-scale operations often create challenges in integrating data across multiple retail ecosystems and adapting quickly to changing advertiser requirements.
- Compliance with evolving privacy regulations, dependence on retailer partnerships, and increasing competition from specialized platforms can also affect operational flexibility.
Emerging Players (CitrusAd; Koddi; Pentaleap; Topsort; Moloco Commerce Media)
- Emerging players focus on delivering cloud-based retail media platforms, self-service advertising solutions, and AI-powered campaign optimization technologies.
- They prioritize flexible deployment, rapid platform integration, and innovative advertising capabilities that enable retailers to efficiently monetize digital traffic and improve campaign performance.
- These companies offer highly customizable and scalable solutions that support faster implementation and lower deployment costs for retailers.
- Their innovation-focused approach enables quick adaptation to changing retail advertising trends, while AI-driven optimization enhances targeting efficiency and operational agility.
- Emerging players have relatively smaller advertiser ecosystems and limited access to large-scale first-party consumer data compared with established competitors.
- Lower brand recognition, fewer strategic retail partnerships, and limited financial resources can slow enterprise adoption and broader market expansion.
Retail Media Network Report Scope
Report Attribute
Details
Market size in 2025
USD 30.7 billion
Estimated market size in 2026
USD 34.2 billion
Projected market size by 2033
USD 68.8 billion
Growth rate
CAGR of 10.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share analysis, competitive landscape, growth factors, and trends
Segments covered
Advertising format, platform type, end use, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; India; Japan; Australia; South Korea; Brazil; UAE; Saudi Arabia; South Africa
Key companies profiled
Amazon; Albertsons; Best Buy; Carrefour; CVS Health; eBay Inc.; Home Depot; Instacart; Kroger; Lowe’s; Sephora; Target; Walmart
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Retail Media Networks Market Report Segmentation
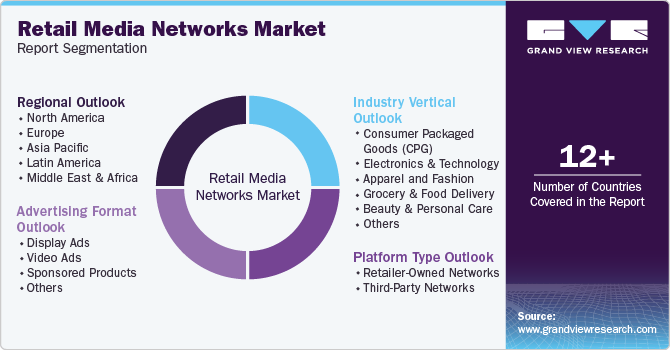
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the retail media network market report based on advertising format, platform advertising format, end use, and region.
 To learn more about this report, Download Free Sample Report
-
Advertising Format Outlook (Revenue, USD Billion, 2021 - 2033)
-
Display Ads
-
Video Ads
-
Sponsored Products
-
Others
-
-
Platform Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Retailer-Owned Networks
-
Third-Party Networks
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Consumer Packaged Goods (CPG)
-
Electronics and Technology
-
Apparel and Fashion
-
Grocery and Food Delivery
-
Beauty and Personal Care
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
U.A.E
-
Kingdom of Saudi Arabia
-
South Africa
-
-
Research Methodology
The retail media networks market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each retail media networks segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Advertising Format
Revenue capture definition
Display Ads
The largest revenue-generating format, display advertising, captures advertiser spending through banner placements, homepage promotions, category page visibility, and personalized product recommendations across retailer digital properties. Pricing is typically based on impressions, programmatic auctions, premium placements, and audience targeting capabilities.
Video Ads
Market value is created through short-form promotional videos, product demonstrations, livestream shopping content, and interactive brand campaigns delivered across retailer websites and mobile applications. Premium pricing is supported by higher engagement rates, richer storytelling opportunities, and stronger conversion potential.
Sponsored Products
Revenue is earned from paid product placements that increase item visibility within search results, category listings, and recommendation engines. Retail media operators monetize through cost-per-click (CPC), cost-per-acquisition (CPA), and auction-based bidding models, enabling brands to directly influence purchase decisions at the point of sale.
Others
This segment includes sponsored brand pages, native advertising, digital coupons, email promotions, shoppable content, and in-store digital media. Growth is supported by retailers expanding their advertising inventory and offering omnichannel engagement opportunities to brand partners.
Segment – Platform Type
Revenue capture definition
Retailer-Owned Networks
The dominant platform segment derives value from first-party consumer data, onsite advertising inventory, loyalty programs, and closed-loop measurement capabilities. Retailers strengthen monetization by enabling advertisers to target high-intent shoppers while providing measurable attribution from ad exposure to completed purchases.
Third-Party Networks
Revenue opportunities arise from advertising technology providers that extend retail audience targeting beyond retailer-owned platforms to external websites, mobile applications, connected TV, and social media channels. These networks help brands expand campaign reach while leveraging retailer transaction data for audience segmentation.
Segment – End Use
Revenue capture definition
Consumer Packaged Goods (CPG)
The largest advertising spend comes from food, beverage, household products, and personal care brands competing for visibility in digital retail environments. Continuous product launches, promotional campaigns, and category competition sustain significant investment in retail media advertising.
Electronics and Technology
Consumer electronics manufacturers allocate substantial budgets to sponsored listings, product-comparison placements, launch campaigns, and seasonal promotions. Retail media enables brands to influence purchase decisions for high-value products where consumers actively research before buying.
Grocery and Food Delivery
Investment is driven by supermarkets, quick-commerce platforms, and food delivery providers seeking to promote products, increase basket size, and strengthen customer retention. Real-time promotions and personalized recommendations play an important role in campaign performance within this segment.
Beauty and Personal Care
Cosmetics, skincare, fragrance, and wellness brands use retail media to improve product discovery, showcase new launches, and target shoppers based on their purchasing behavior. Premium advertising placements are particularly valuable during seasonal campaigns and promotional events.
Apparel and Fashion
Fashion retailers and brands leverage sponsored campaigns, personalized recommendations, and digital storefront promotions to increase product visibility and drive online conversions. Frequent collection updates, seasonal trends, and promotional events contribute to continuous advertising activity throughout the year.
Estimation Model
Layer Name
Key Question
Description
Retail Audience Layer
Where is retail media inventory created?
Identify retail ecosystems that generate valuable first-party shopper data and digital advertising opportunities. These include e-commerce marketplaces, grocery platforms, pharmacy chains, consumer electronics retailers, home improvement stores, quick commerce applications, and omnichannel retail networks. This layer defines the market based on retailers that can monetize consumer traffic across websites, mobile applications, in-store digital displays, and connected shopping experiences.
Advertiser Participation Layer
Who invests in retail media networks and why?
Assess the participation of consumer packaged goods (CPG) companies, electronics brands, fashion labels, beauty manufacturers, food and beverage companies, and marketplace sellers seeking measurable advertising performance. Investment decisions are influenced by access to first-party customer data, closed-loop attribution, campaign performance transparency, audience targeting capabilities, and the ability to influence purchasing decisions at the point of sale.
Campaign Execution Layer
How are retail media campaigns activated and optimized?
Analyze the deployment of sponsored product listings, display advertising, video advertisements, search-based promotions, off-site retail media, programmatic advertising, and AI-driven campaign optimization tools. This layer evaluates how retailers and advertisers leverage audience segmentation, real-time bidding, personalized recommendations, and performance analytics to maximize campaign effectiveness, improve conversion rates, and optimize advertising spend across digital retail channels.
Media Monetization Layer
How is revenue generated within the retail media ecosystem?
Evaluate revenue creation through advertising placements, auction-based sponsored listings, premium brand promotions, self-service advertising platforms, retail media management services, audience data monetization, and campaign measurement solutions. Additional value is generated through analytics subscriptions, retailer–brand partnerships, and omnichannel advertising programs that enable retailers to diversify revenue beyond product sales while providing advertisers with highly measurable marketing outcomes.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Retail Advertising Monetization & First-Party Data Strategy Trends
Conducted a focused analysis of retail media network adoption across e-commerce marketplaces, omnichannel retailers, grocery platforms, and quick commerce providers, focusing on first-party data monetization, sponsored advertising, and digital shelf optimization.
Helps stakeholders identify high-growth advertising revenue streams, evaluate retailer monetization strategies, and assess commercialization opportunities in first-party data-driven advertising ecosystems.
Omnichannel Retail Media & Brand Engagement Adoption Trends
Evaluated adoption trends for sponsored product ads, display advertising, video advertising, off-site media activation, and in-store digital media, including campaign measurement, audience targeting, and closed-loop attribution capabilities.
Provides insights into evolving advertiser requirements, media performance optimization, and commercially attractive advertising formats supporting measurable return on ad spend (ROAS).
Retail Media Platform Ecosystem & Advertiser Collaboration Opportunity Assessment
Assessed demand for self-service advertising platforms, AI-powered campaign optimization, retail media analytics, demand-side platform integration, and retail measurement solutions, along with challenges related to data privacy, campaign standardization, inventory scalability, and cross-channel attribution.
Supports investment and expansion strategies by identifying emerging retailer and brand partnership opportunities, evaluating platform readiness, and strengthening long-term growth potential in omnichannel retail media ecosystems.
Frequently Asked Questions About This Report
The global retail media networks market size was valued at USD 30.7 billion in 2025 and is estimated at USD 34.2 billion for 2026.
The global retail media networks market is expected to grow at a CAGR of 10.5% from 2026 to 2033, reaching USD 68.8 billion by 2033.
Key factors include rising shift of digital advertising budgets toward retail-owned media platforms, rising expansion of online grocery and quick commerce platforms, and increasing demand for cross-channel advertising across online and offline retail touchpoints.
North America dominated with 35.3% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The retailer-owned networks segment led with an 70.0% revenue share in 2025, while third-party networks segment is the fastest-growing segment.
The consumer packaged goods held the largest share (over 24%) in 2025, while beauty and personal care segment is the fastest-growing segment.
Key players operating in the retail media networks market include Amazon; Albertsons; Best Buy; Carrefour; CVS Health; eBay Inc.; Home Depot; Instacart; Kroger; Lowe’s; Sephora; Target; Walmart.
The sponsored products segment led with a 42.4% revenue share in 2025, while the video ads segment is the fastest-growing.
About the Author(s)
Digital Media Research Team
Technology · Digital MediaThis report was authored by the digital media research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the digital media segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


