
- Home
- »
- Pharmaceuticals
- »
-
Rheumatoid Arthritis Therapeutics Market Report, 2026-2033GVR Report cover

Rheumatoid Arthritis Therapeutics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Molecule (Pharmaceuticals, Biopharmaceuticals), By Sales Channel (Prescription, Over-the-Counter), By Region, And Segment Forecasts
Market Size, 2025
$26.9BMarket Estimate, 2026
$28.3BMarket Forecast, 2033
$45.2BCAGR, 2026–2033
6.9%Rheumatoid Arthritis Therapeutics Market Summary
The global rheumatoid arthritis therapeutics market size was valued at USD 26.9 billion in 2025 and is projected to grow from USD 28.3 billion in 2026 to USD 45.2 billion by 2033, at a CAGR of 6.9% from 2026 to 2033. The market in North America dominated with a revenue share of 51.8% in 2025. The introduction of innovative therapeutics for rheumatoid arthritis (RA) is playing a key role in boosting market growth.
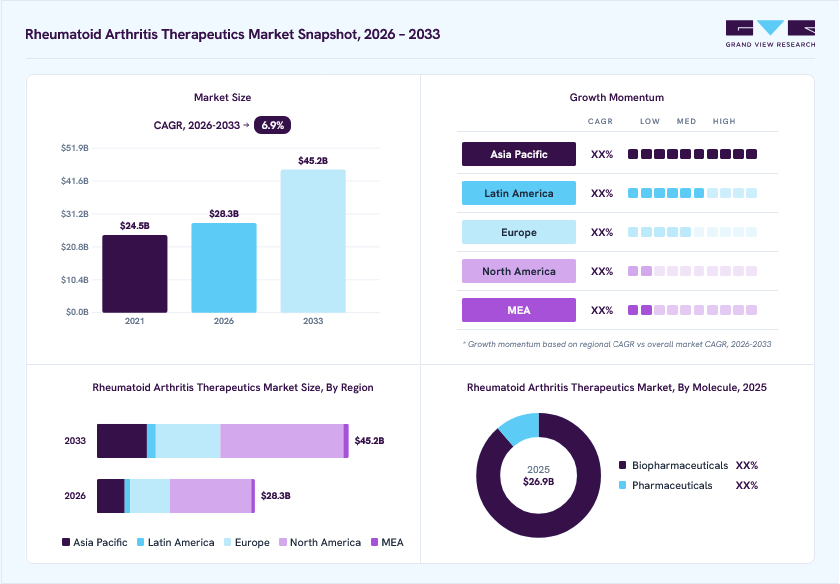 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
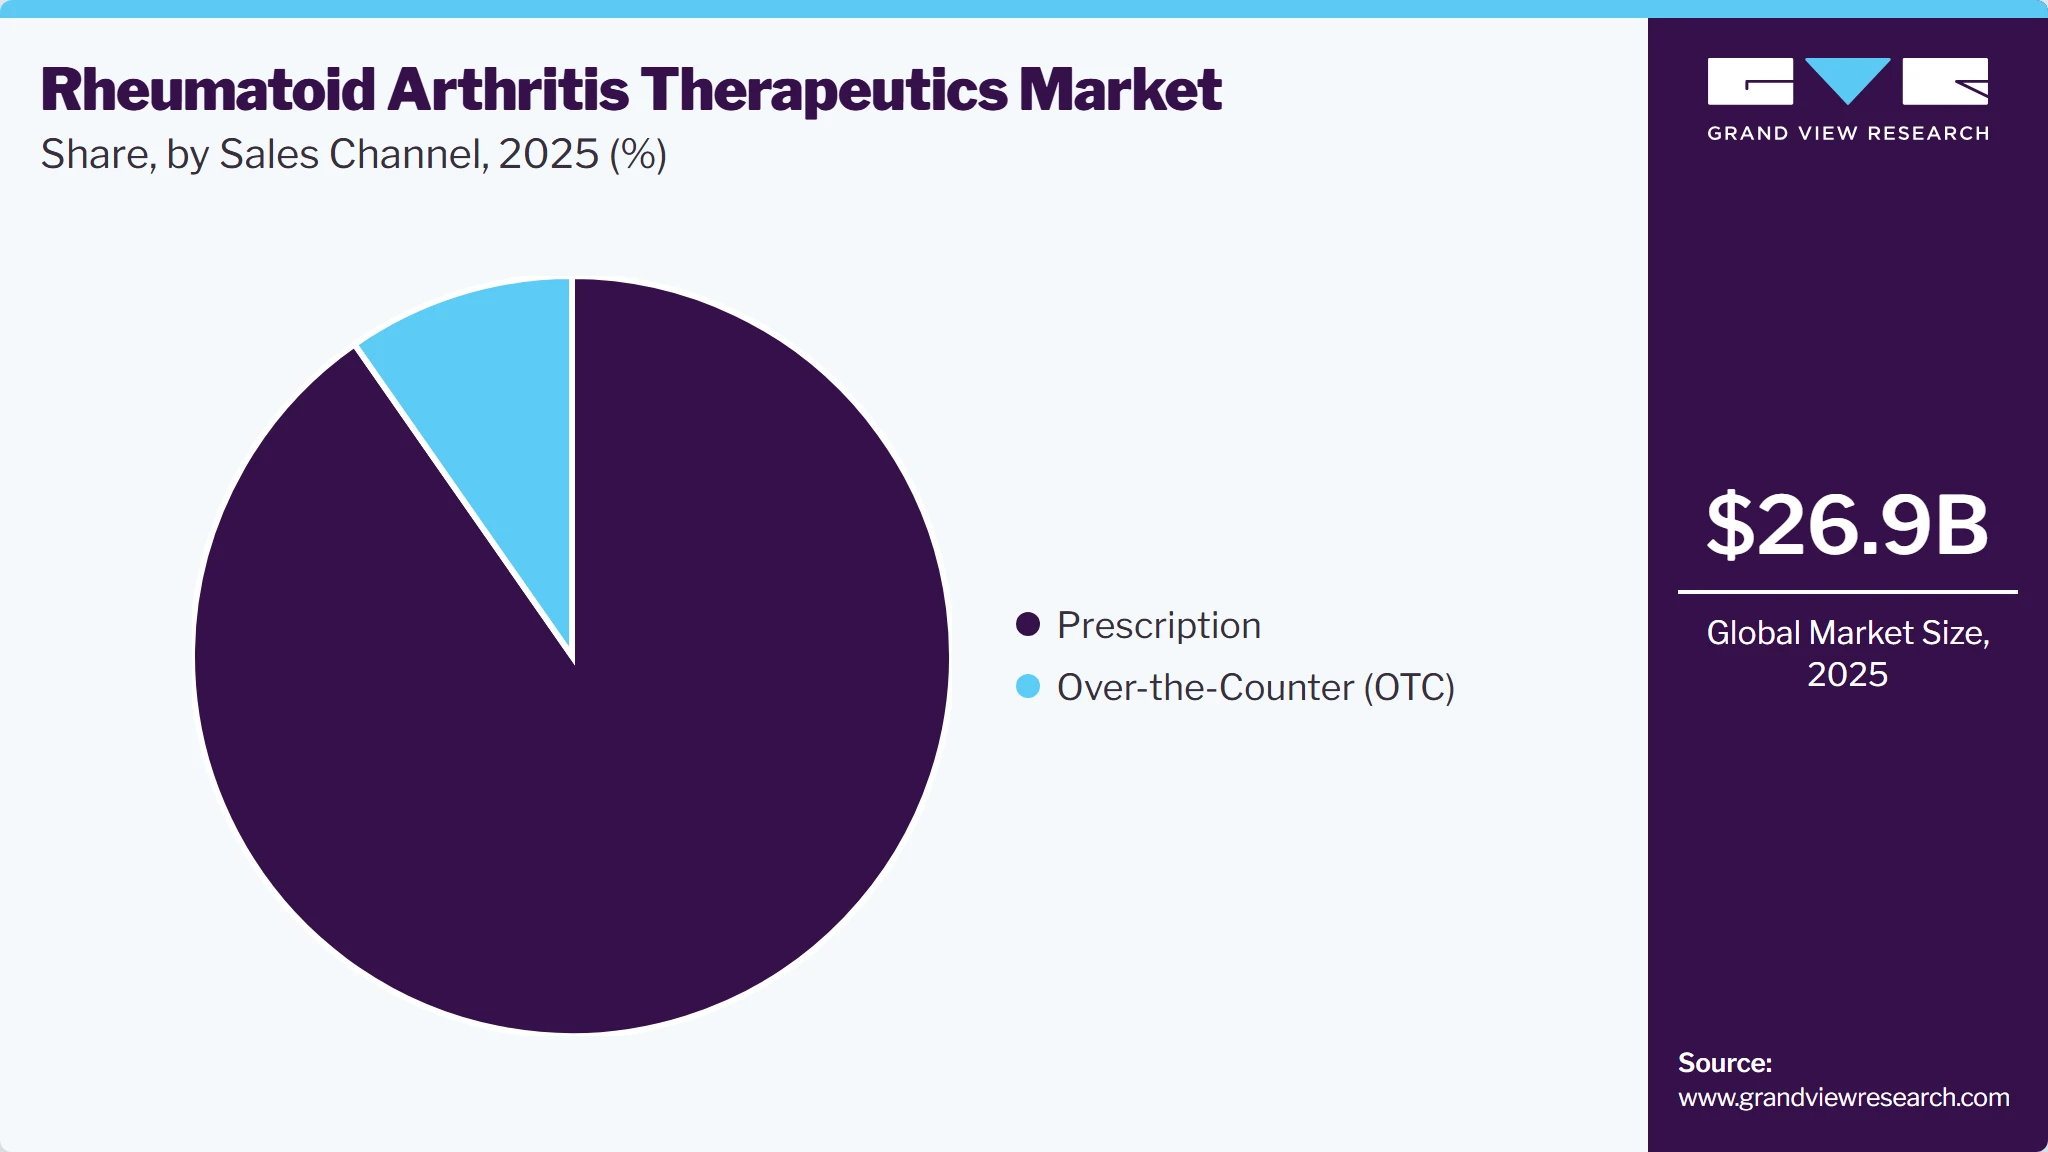
- By sales channel: Prescription segment held the largest market share of 90.3% in 2025.
- By molecule: Biopharmaceuticals segment held the largest market share of 88.5% in 2025.
Regional Highlights
- Largest regional market: North America (51.8% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 26.9 Billion
- Estimated market size in 2026: USD 28.3 Billion
- Projected market size by 2033: USD 45.2 Billion
- CAGR (2026-2033): 6.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The launch of new biosimilars such as Cyltezo, Hyrimoz, Amgevita, Erelzi, Avsola, and Rituximab by leading pharmaceutical companies including Amgen Inc., Pfizer Inc., Genentech, Inc., and Novartis has significantly reshaped the RA treatment landscape. For instance, In May 2024, Boehringer Ingelheim announced that the U.S. Food and Drug Administration had approved a high-concentration, citrate-free formulation of Cyltezo (adalimumab-adbm) the company’s interchangeable biosimilar to Humira for treating multiple chronic inflammatory diseases including rheumatoid arthritis, Crohn’s disease, ulcerative colitis, psoriasis, psoriatic arthritis, hidradenitis suppurativa, ankylosing spondylitis, moderate-to-severe plaque psoriasis, and non-infectious uveitis.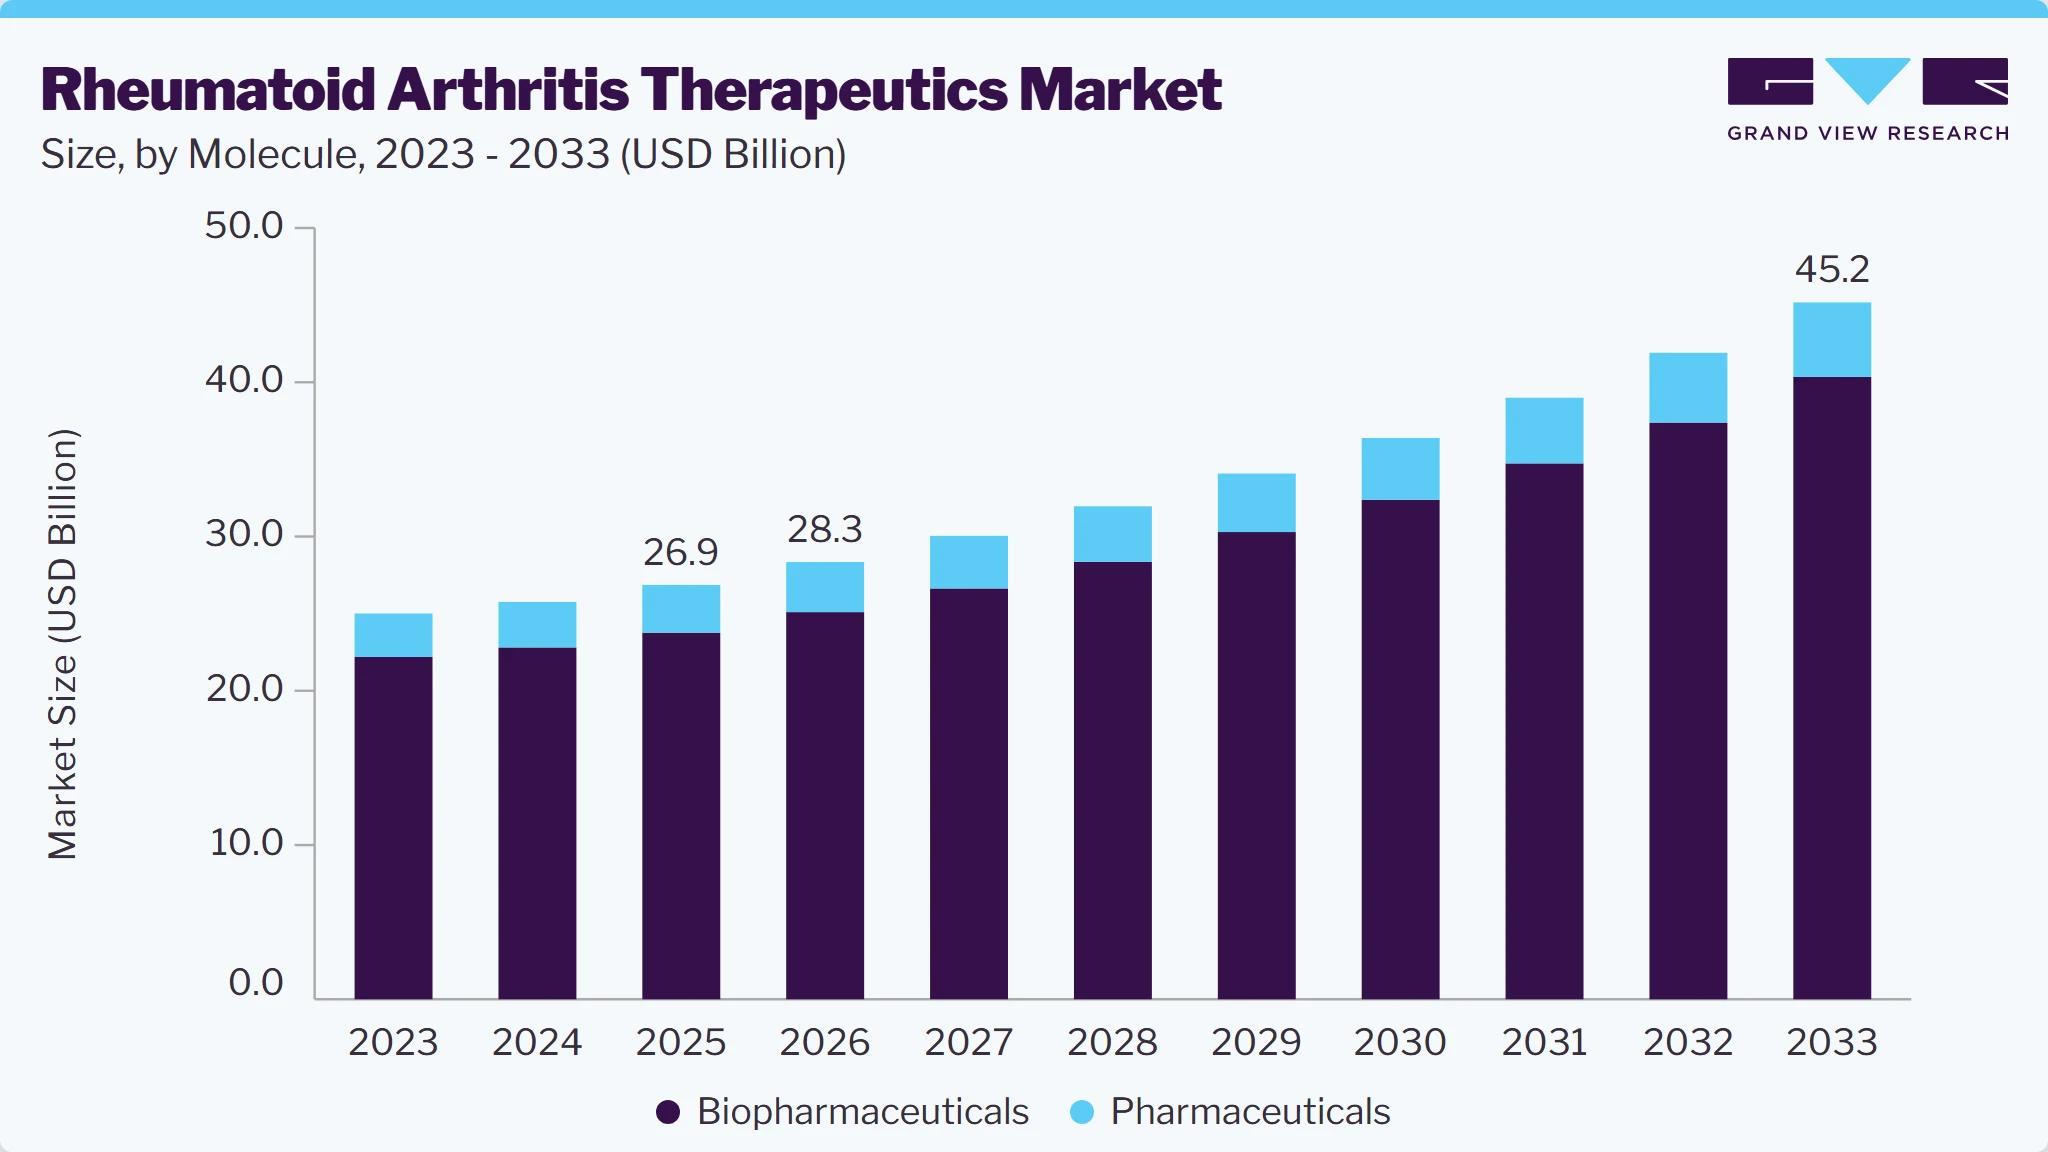 To learn more about this report, Download Free Sample Report
In a similar development, January 2023 saw Novartis AG secure marketing authorization from the European Medicines Agency’s Committee for Medicinal Products for Human Use (CHMP) for Sandoz’s citrate-free, high-concentration formulation (HCF) of Hyrimoz (adalimumab). This approval extends to all indications of the reference medicine, including RA, uveitis, ulcerative colitis, and plaque psoriasis. These next-generation biologics and biosimilars are designed to act on specific immune system molecules or receptors responsible for joint pain and inflammation, resulting in improved treatment outcomes. Rising demand for such targeted and efficient therapies is expected to further drive advancements in biologic treatments for RA.
In recent years, RA treatment strategies have shifted toward newer molecules capable of inducing disease remission. This evolution stems from a deeper understanding of RA’s underlying mechanisms, leading to the creation of targeted biologic and synthetic disease-modifying antirheumatic drugs (DMARDs). While first-line treatment still includes small-molecule DMARDs, corticosteroids, analgesics, and nonsteroidal anti-inflammatory drugs (NSAIDs), these options primarily slow disease progression and manage inflammation rather than curing the condition. Moreover, they can cause notable side effects, such as gastrointestinal ulcers, immunosuppression, osteoporosis, nausea, cytopenia, fatigue, skin rashes, liver damage, psoriasis, and an increased risk of infections.
Market Dynamics
The rheumatoid arthritis therapeutics market is driven by increasing emphasis on early diagnosis, effective disease control, and long-term management of autoimmune conditions. Demand for advanced treatment options continues to rise as biologics and targeted therapies demonstrate improved clinical outcomes in patients with moderate to severe rheumatoid arthritis. Market growth is supported by ongoing investments in immunology research, expansion of biologic manufacturing capabilities, and increasing availability of biosimilars that improve treatment accessibility. Regulatory frameworks across major markets continue to encourage innovation while maintaining strict safety and efficacy standards for advanced therapies. Distribution channels are evolving through greater utilization of specialty pharmacies and patient support programs that enhance treatment adherence and access. In addition, improving reimbursement coverage and broader physician awareness of treat to target approaches are contributing to therapy adoption. The market is expected to maintain steady growth as innovation in biologics, targeted therapies, and biosimilars continue to reshape rheumatoid arthritis treatment strategies globally.
The rheumatoid arthritis therapeutics market is being driven by the increasing adoption of targeted immunology therapies that provide improved disease control and long-term management compared with conventional treatment approaches. Healthcare providers are increasingly implementing treat to target strategies that focus on achieving remission or low disease activity, resulting in greater utilization of biologics and JAK inhibitors among patients who do not respond adequately to conventional DMARDs. Growing clinical evidence, increasing physician familiarity with advanced therapies, and expanding reimbursement support are strengthening treatment adoption across major healthcare markets. Pharmaceutical companies continue to invest in clinical development, indication expansion, and lifecycle management initiatives to strengthen their immunology portfolios and address evolving patient requirements. These factors continue to support broader utilization of advanced rheumatoid arthritis therapies and contribute to market expansion. For instance, in April 2025, AbbVie announced that the European Commission approved RINVOQ (upadacitinib) for the treatment of adults with giant cell arteritis, making it the first and only oral JAK inhibitor approved for this indication across the European Union, Iceland, Liechtenstein, and Norway. The approval was supported by Phase 3 clinical data and reinforced confidence in targeted immunology therapies across immune mediated diseases.
The rheumatoid arthritis therapeutics market faces challenges associated with safety monitoring requirements and extensive regulatory oversight of advanced immunomodulatory therapies. Biologics and JAK inhibitors require continuous evaluation for potential risks including serious infections, cardiovascular events, malignancies, and other adverse outcomes. Regulatory authorities often require extensive post marketing surveillance and additional clinical evidence to assess long term safety profiles. These requirements increase development complexity, extend commercialization timelines, and create caution among healthcare providers when selecting therapies for specific patient populations. In addition, payer organizations frequently implement utilization management measures and reimbursement restrictions that can limit patient access to advanced therapies. These factors collectively act as barriers to broader adoption despite the clinical benefits offered by innovative rheumatoid arthritis treatments. For instance, in April 2025, AbbVie received U.S. FDA approval for RINVOQ in giant cell arteritis based on results from the Phase 3 SELECT GCA study, which enrolled 428 patients, including 209 patients receiving RINVOQ 15 mg, 107 patients receiving RINVOQ 7.5 mg, and 112 patients receiving placebo. The approval process highlighted the extensive clinical trial requirements, long term safety evaluations, and regulatory scrutiny necessary for advanced immunology therapies.
The growing adoption of biosimilars represents a significant opportunity for the rheumatoid arthritis therapeutics market as healthcare systems seek to improve treatment accessibility while managing healthcare expenditures. Biosimilars provide clinically comparable alternatives to originator biologics and support broader patient access to advanced therapies. Increasing regulatory support, improving physician confidence, and stronger payer acceptance are accelerating biosimilar penetration across developed and emerging markets. As more biologic products face patent expiry, manufacturers are expanding biosimilar portfolios and geographic reach to capitalize on growing demand. This trend is expected to improve affordability, enhance treatment coverage, and support long term market expansion. For instance, in February 2026, Reuters reported that AbbVie highlighted continued market expansion of its immunology portfolio as biosimilar competition increased across established biologic categories. The company indicated that newer immunology therapies were expected to play a larger role in treatment adoption as healthcare providers increasingly incorporated alternative biologic options into clinical practice. The development demonstrated how biosimilar adoption is reshaping competitive dynamics while creating opportunities to improve patient access to advanced therapies.
Market Concentration & Characteristics
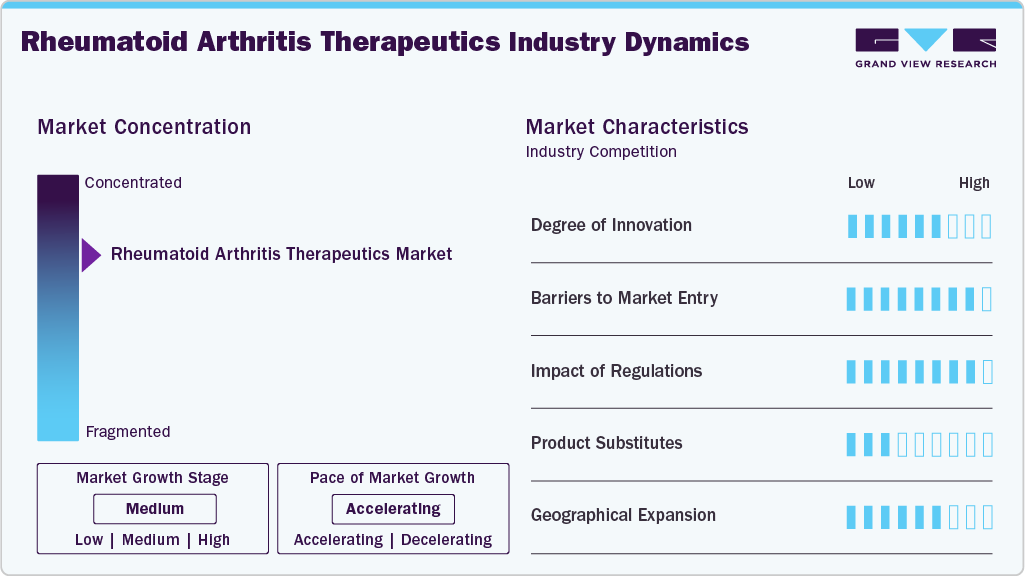
Innovation in the rheumatoid arthritis therapeutics industry remains strong, fueled by the advent of biosimilars and breakthrough treatment approaches. The launch of biosimilars for drugs such as infliximab, etanercept, adalimumab, and rituximab marks a major step toward providing more cost-effective and widely accessible therapy options. Alongside these commercial developments, academic research is also contributing significantly such as the work by engineers at the University of California, San Diego, who have created a biodegradable polymer system designed to harness the body’s own immune response to combat RA. This technique involves delivering encapsulated all-trans retinoic acid (ATRA) directly into affected joints, reprogramming harmful immune cells into regulatory T cells.
Entering the rheumatoid arthritis therapeutics industry is challenging due to high R&D costs, lengthy clinical trial processes, and stringent regulatory requirements for safety and efficacy. The dominance of established players like AbbVie, Johnson & Johnson, and Roche creates intense brand loyalty, making market penetration difficult for new entrants. Biologic manufacturing requires significant technological expertise and infrastructure investment, which acts as a barrier for smaller firms. Intellectual property protections for leading biologics, alongside complex patent landscapes, further delay generic and biosimilar competition. In addition, high marketing and distribution costs limit the ability of emerging companies to compete effectively in this space.
 To learn more about this report, Download Free Sample Report
The rheumatoid arthritis therapeutics industry is heavily influenced by global and regional regulatory frameworks that govern drug approvals, pricing, and marketing. Agencies such as the U.S. FDA and EMA enforce rigorous clinical trial standards, ensuring patient safety but also extending product development timelines. Regulatory bodies also manage biosimilar approvals through specific pathways, encouraging competition while maintaining quality benchmarks. In some regions, price control measures and reimbursement policies directly affect market accessibility and profitability. Post-marketing surveillance requirements add further operational responsibilities for manufacturers, impacting product lifecycle management.
Although biologics and targeted synthetic DMARDs dominate the rheumatoid arthritis therapeutics industry, substitutes such as NSAIDs, glucocorticoids, and analgesics remain widely used for symptom management. These alternatives are generally more affordable and accessible, making them common in early-stage treatment or in cost-sensitive markets. Physical therapy, lifestyle modifications, and complementary medicine also act as indirect substitutes, particularly in regions with limited access to advanced therapies. However, these options primarily address symptom relief rather than disease modification. The availability of biosimilars is gradually becoming a preferred substitute for costly branded biologics, improving affordability while maintaining therapeutic outcomes.
The rheumatoid arthritis therapeutics industry is set for notable regional growth, in line with the global push to meet the rising healthcare needs of an aging population and the increasing incidence of RA. This trend highlights the critical role of region-specific strategies in advancing the development and delivery of RA treatments. For instnace, in August 2023, Zydus Lifesciences Ltd obtained final approval from the U.S. FDA to produce and commercialize its generic Indomethacin suppositories for the management of moderate to severe RA. The approval included 180-day Competitive Generic Therapy (CGT) exclusivity, enabling Zydus to market the 50 mg formulation during this period exclusively. This milestone not only broadened the company’s therapeutic portfolio but also introduced a more cost-effective option for RA patients in India and potentially in global markets, supporting improved access to essential treatments.
Analyst Perspective
The rheumatoid arthritis therapeutics market continues to evolve toward advanced immunology treatments that emphasize long term disease control, remission achievement, and improved patient outcomes. Biologics and targeted therapies are increasingly becoming integral components of treatment strategies, while biosimilars are expanding access through improved affordability and broader payer acceptance. Market participants are focusing on indication expansion, clinical differentiation, and lifecycle management to strengthen competitive positioning. Although safety monitoring requirements and reimbursement pressures remain key challenges, ongoing innovation and increasing adoption of precision treatment approaches support a favorable growth outlook. The market is expected to remain commercially attractive as demand for effective disease modifying therapies continues to increase globally.
Molecule Insights
Based on molecule, the biopharmaceuticals segment led the market with the largest revenue share of 88.5% in 2025, driven by the rising adoption of targeted biologics and biosimilars. Increasing clinical preference for TNF-α antagonists, JAK inhibitors, and anti-IL6 biologics has strengthened market penetration. Advancements in molecular engineering have enabled improved drug specificity and reduced adverse effects, enhancing patient adherence. In August 2024, the European Commission granted approval for Ituxredi, a biosimilar to rituximab developed by Dr. Reddy’s Laboratories, for the treatment of rheumatoid arthritis among other immune-mediated conditions-marking a fresh advance in expanding access to targeted therapies via biosimilars. Expanding availability of such biosimilars is further supporting broader treatment access, particularly in cost-sensitive regions. Continuous pipeline innovations from major players such as AbbVie, Pfizer, and Johnson & Johnson are introducing novel mechanisms of action to address treatment resistance. Higher diagnosis rates and earlier initiation of biologic therapy are accelerating prescription volumes, setting new standards in efficacy, safety, and long-term disease control for RA patients.
The pharmaceuticals segment is projected to grow at the fastest CAGR of 5.8% over the forecast period, fueled by the sustained demand for NSAIDs, analgesics, DMARDs, and glucocorticoids in early-stage and maintenance therapy. Oral formulations and established safety profiles are encouraging continuous use in both acute and chronic disease management. In May 2023, researchers at the University of Connecticut (UConn) introduced a novel long-acting injectable NSAID delivery system specifically designed for rheumatoid arthritis and osteoarthritis. This innovative in situ–forming biodegradable implant offers sustained drug release over several months, significantly reducing gastrointestinal side effects associated with traditional oral NSAIDs and improving treatment adherence. Expanding generic drug availability is increasing affordability, enabling broader patient coverage. Physicians often initiate treatment with these agents before progressing to high-cost biologics, ensuring their continued relevance in treatment algorithms. Rising awareness of RA symptoms and the importance of early intervention is leading to higher prescription rates. The segment’s growth is also supported by its critical role in combination therapy for advanced RA cases.
Sales Channel Insights
Based on sales channel, the prescription segment led the market with the largest revenue share of 90.3% in 2025, attributed to the clinical requirement for specialist-supervised drug administration. Most biologics and advanced DMARDs require physician oversight due to potential adverse events and dosing complexities. Strong reliance on hospital and specialty clinic distribution networks ensures high treatment compliance. The increasing use of personalized treatment plans based on patient response patterns supports prescription-driven demand. Physician preference for long-term monitoring of disease progression and therapy effectiveness strengthens this channel’s market share. The emergence of patient assistance programs from leading pharmaceutical companies is facilitating continued prescription renewals. Overall, the prescription segment remains central to delivering high-efficacy and targeted RA treatments.
 To learn more about this report, Download Free Sample Report
The over-the-counter (OTC) segment is projected to grow at the fastest CAGR of 3.1% over the forecast period, due to increasing self-management of mild RA symptoms and joint discomfort. Easy accessibility to NSAIDs and pain relief medications in retail and online pharmacies is driving product uptake. Growing consumer awareness of early symptom relief options is supporting higher sales volumes. Advancements in topical and oral OTC formulations are improving convenience and reducing side effects. The expanding e-commerce landscape is enabling broader reach and faster product availability to consumers. Marketing efforts emphasizing active lifestyles and mobility support are influencing purchase decisions. As patients seek non-prescription alternatives for symptom control, the OTC segment is expected to maintain strong growth momentum.
Regional Insights
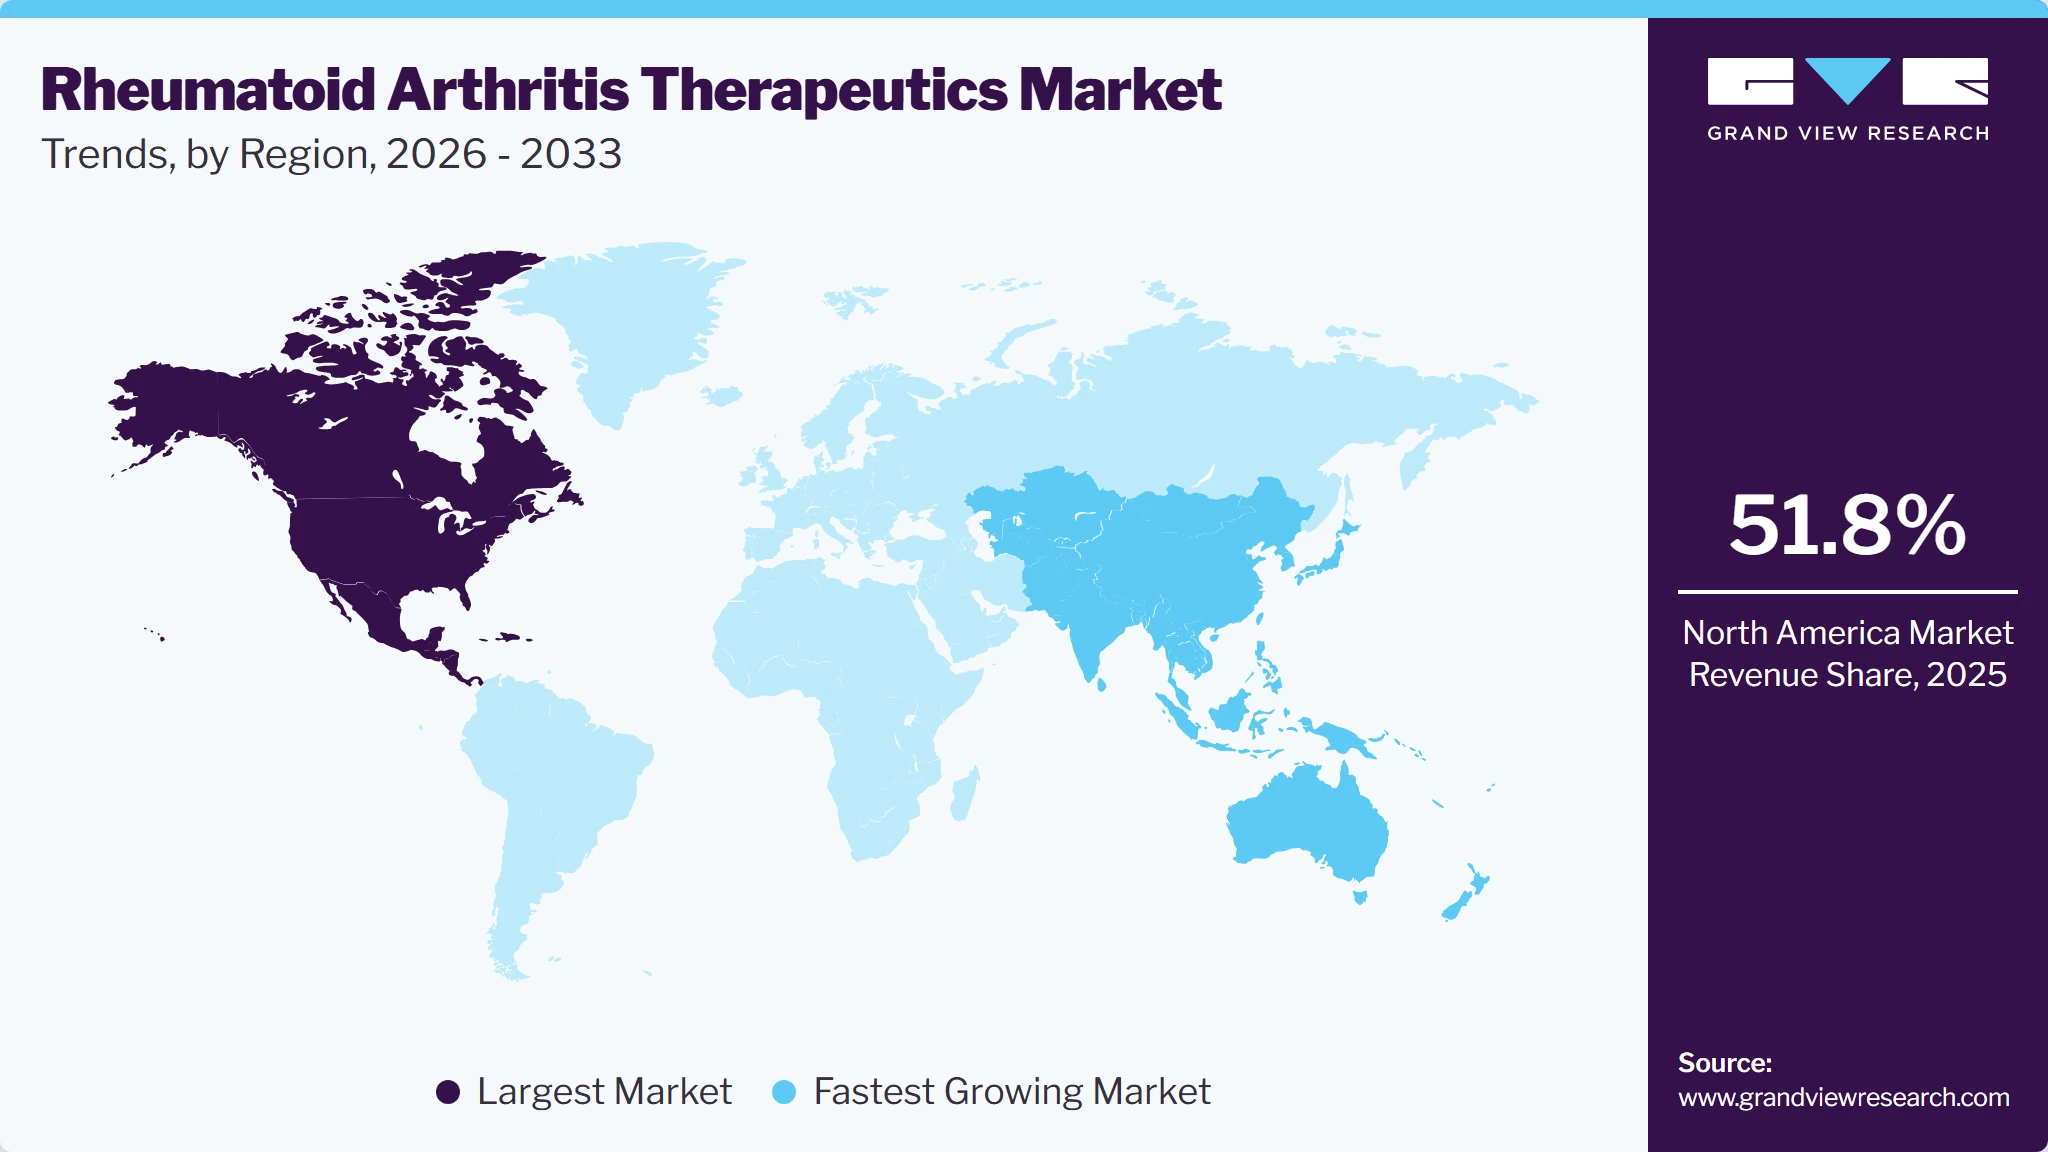
North America dominated the rheumatoid arthritis therapeutics market with the largest revenue share of 51.8% in 2025, driven by the high prevalence of RA and the widespread adoption of biologics and targeted therapies. Strong clinical infrastructure supports early diagnosis and optimized treatment plans. Leading pharmaceutical companies maintain robust product portfolios with continuous therapy advancements. High healthcare expenditure enables greater patient access to advanced and combination treatments. Patient preference for innovative biologics has strengthened market revenue. The presence of strong distribution channels across hospital and retail pharmacies further enhances regional market penetration.
 To learn more about this report, Download Free Sample Report
U.S. Rheumatoid Arthritis Therapeutics Market Trends
The rheumatoid arthritis therapeutics market in the U.S. held the largest share in the North America region in 2025, due to its well-established specialty care network and advanced diagnostic capabilities. Rapid uptake of next-generation biologics and JAK inhibitors is accelerating market growth. Strong engagement from rheumatologists in clinical trials ensures early adoption of pipeline drugs. A large base of insured patients supports consistent prescription volumes. Increasing use of digital health tools is enabling better treatment adherence. Major industry players are prioritizing U.S. launches for new RA therapies due to favorable market conditions.
Europe Rheumatoid Arthritis Therapeutics Market Trends
The rheumatoid arthritis therapeutics market in Europe is anticipated to grow at a substantial CAGR during the forecast period. The region has a diverse therapeutic landscape, including both innovative biologics and cost-effective biosimilars. High treatment awareness among patients drives steady uptake of advanced therapies. The market benefits from collaborative research initiatives among academic and industry players. Widespread use of combination therapy is improving treatment outcomes. Strategic partnerships between pharmaceutical companies and specialty clinics continue to expand patient access.
The UK rheumatoid arthritis therapeutics market is experiencing rising demand, driven by strong clinical adoption of biosimilars and a focus on cost-effective treatment protocols. High physician familiarity with advanced RA therapies ensures consistent prescription patterns. Ongoing clinical research within university hospitals is fostering innovation in treatment approaches. The expansion of specialty pharmacy services is improving drug distribution efficiency. Digital patient monitoring platforms are being integrated into RA management programs. Increased awareness campaigns by healthcare providers are enhancing early diagnosis rates.
The rheumatoid arthritis therapeutics market in Germany is a key contributor to the European market due to its high biologic penetration rates and strong domestic pharmaceutical manufacturing base. Hospitals and specialty clinics are well equipped to handle complex RA treatment regimens. The country’s strong clinical research activity contributes to the rapid adoption of new drug classes. Patient preference for subcutaneous formulations is influencing product demand. Strategic alliances between pharmaceutical companies and healthcare providers are improving patient follow-up. The availability of biosimilars at competitive pricing is stimulating treatment uptake.
The France rheumatoid arthritis therapeutics market is witnessing steady growth. The country shows strong uptake of targeted DMARDs and newer biologics for patients unresponsive to conventional therapy. Multidisciplinary treatment approaches are being adopted in leading hospitals. Pharmaceutical companies are investing in localized manufacturing to ensure a steady supply. The use of telehealth services for RA follow-ups is becoming increasingly common. Continuous physician education programs support advanced therapy utilization.
Asia Pacific Rheumatoid Arthritis Therapeutics Market Trends
The rheumatoid arthritis therapeutics market in the Asia Pacific is expected to register at the fastest CAGR of 8.7% over the forecast period, due to increasing diagnosis rates and improving healthcare infrastructure. Expanding access to biologics in urban areas is accelerating treatment adoption. Pharmaceutical companies are strengthening distribution networks in emerging economies. Rising awareness of RA’s impact on quality of life is prompting earlier intervention. Local manufacturing initiatives are improving the availability of biosimilars. The growing middle-class population is contributing to higher expenditure on chronic disease management.
The Japan rheumatoid arthritis therapeutics market represents a mature RA within Asia Pacific, supported by high adoption of targeted therapies. Strong focus on personalized medicine is influencing treatment decisions. The country’s aging population is expanding the patient base for RA drugs. Continuous product innovation by domestic pharmaceutical companies is sustaining growth. High patient compliance with prescribed regimens contributes to better treatment outcomes. Increasing collaborations with global biopharma players are enhancing drug availability.
The rheumatoid arthritis therapeutics market in China is rapidly expanding, driven by the rising prevalence of RA and improving access to advanced therapeutics. Expansion of specialty clinics in urban centers is facilitating early diagnosis and treatment. Domestic pharmaceutical manufacturers are entering the biologics and biosimilars segment. Growing investment in clinical research is fostering innovation in RA therapy. Increasing affordability of targeted treatments is boosting patient adoption. The e-commerce healthcare sector is emerging as a significant distribution channel.
Latin America Rheumatoid Arthritis Therapeutics Market Trends
The rheumatoid arthritis therapeutics market in Latin America is emerging as a growth region, due to the expanding with the gradual introduction of biologics and biosimilars. Urban centers have better access to advanced therapies compared to rural areas. Local manufacturing agreements are enhancing drug supply consistency. Rising patient education efforts are encouraging earlier treatment initiation. The presence of multinational pharmaceutical companies is improving therapy availability. Increasing investment in specialty clinics is supporting market growth.
The Brazil rheumatoid arthritis therapeutics market holds a major share of the Latin American market, driven by its high patient population and growing adoption of biologics. Urban hospitals are leading in the administration of advanced RA treatments. Local production of biosimilars is helping reduce therapy costs. Physician training programs are improving the quality of RA care. Expanding private healthcare coverage is increasing treatment accessibility. Active participation in multinational clinical trials is fostering innovation.
Middle East & Africa Rheumatoid Arthritis Therapeutics Market Trends
The rheumatoid arthritis therapeutics market in the Middle East & Africa is witnessing gradual growth due to the rising prevalence of RA and improving access to specialty healthcare facilities. Urban hubs are witnessing higher adoption of biologics and biosimilars. Pharmaceutical companies are expanding partnerships with regional distributors. Increasing physician awareness of new treatment protocols is supporting uptake. Expansion of private clinics is facilitating patient access to advanced care. Multinational drug launches are progressively targeting high-demand urban markets.
The Saudi Arabia rheumatoid arthritis therapeutics market is making notable progress in the MEA market due to strong private healthcare investment and a growing patient base. Specialty hospitals in major cities are introducing advanced biologic and targeted therapies. Physician-led initiatives are promoting early RA diagnosis. Local distribution agreements are improving product availability. Rising use of digital health tools is enhancing treatment adherence. Ongoing clinical collaborations with global pharmaceutical companies are supporting therapy innovation.
Key Rheumatoid Arthritis Therapeutics Company Insights
AbbVie, Inc. and Johnson & Johnson Services, Inc. are influencing the rheumatoid arthritis therapeutics industry through extensive biologics portfolios and robust commercialization strategies. Amgen Inc. and UCB S.A. sustain competitive positions with targeted monoclonal antibody therapies and proven expertise in chronic inflammatory diseases. Pfizer Inc. and Bristol-Myers Squibb Company are advancing innovative treatment regimens with strong R&D pipelines aimed at enhancing therapeutic efficacy and patient adherence.
Novartis AG and F. Hoffmann-La Roche Ltd. are leveraging advanced immunology research and diversified drug platforms to expand market reach. Regeneron Pharmaceuticals Inc. and Boehringer Ingelheim International GmbH are focusing on precision-targeted biologics and biosimilars to address unmet clinical needs. Lilly (Eli Lilly and Company) continues to strengthen its footprint with JAK inhibitors and novel small molecules, driving therapeutic diversity and fueling competitive growth across key global markets.
Key Rheumatoid Arthritis Therapeutics Companies
The following key companies have been profiled for this study on the rheumatoid arthritis therapeutics market.
-
AbbVie, Inc.
-
Boehringer Ingelheim International GmbH
-
Novartis AG
-
Regeneron Pharmaceuticals Inc.
-
Pfizer, Inc.
-
Bristol-Myers Squibb Company
-
F. Hoffmann-La Roche Ltd.
-
UCB S.A.
-
Johnson & Johnson Services, Inc.
-
Amgen, Inc.
-
Lilly (Eli Lilly and Company)
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (AbbVie, Inc.; Johnson & Johnson Services, Inc.; F. Hoffmann-La Roche Ltd.; Pfizer, Inc.; Bristol-Myers Squibb Company; Amgen, Inc.; Novartis AG)
- Focus on expanding immunology portfolios through biologics, targeted therapies, and lifecycle management strategies.
- Invest in clinical trials, indication expansions, physician engagement programs, and strategic partnerships to strengthen positioning in autoimmune disease treatment.
- Enhance global market presence through established commercialization infrastructure and continuous investment in research and development.
- Strong brand recognition among rheumatologists and healthcare providers.
- Extensive global distribution networks established regulatory expertise, broad product portfolios, advanced manufacturing capabilities, and significant financial resources support sustained market leadership.
- Deep relationships with healthcare systems and payers facilitate market access and reimbursement coverage.
- High research and development expenditures and complex regulatory requirements increase operational costs.
- Exposure to biosimilar competition, patent expiration risks, pricing pressures, and reimbursement scrutiny may impact market performance.
- Large organizational structures can reduce operational flexibility and slow decision-making processes.
Emerging Players (UCB S.A.; Regeneron Pharmaceuticals Inc.; Boehringer Ingelheim International GmbH; Eli Lilly and Company)
- Focus on targeted innovation within immunology and autoimmune diseases through differentiated therapies, pipeline expansion, and selective geographic growth.
- Emphasize strategic collaborations, precision medicine approaches, and investment in next generation biologics and targeted therapies to strengthen competitive positioning.
- Pursue opportunities in underserved patient populations and emerging treatment segments.
- Greater organizational agility and ability to respond quickly to evolving market trends.
- Strong scientific expertise in specific therapeutic areas, focused innovation strategies, and differentiated product development capabilities support competitive positioning.
- Ability to address niche treatment requirements and emerging clinical needs.
- Smaller commercial footprint compared with established market leaders in certain regions.
- Lower scale advantages in distribution and market access may limit penetration across some markets.
- Dependence on a narrower product portfolio can increase exposure to competitive, clinical, and regulatory risks.
Recent Developments
-
In March 2024, Bristol Myers Squibb has launched a USD 1.8 million effort to address Socioeconomic Determinants of Health (SDoH) in four countries-Brazil, India, Thailand, and the UK-with underserved patient needs. The new health equity grants extend the company's long-term commitment to invest USD 150 million in health equity by 2025.
-
In October 2023, Alfasigma S.p.A. agreed to acquire the Jyseleca business from Galapagos, a multinational biotechnology firm headquartered in Belgium specializing in developing revolutionary immunology and oncology treatments.
-
In July 2023, Boehringer Ingelheim International GmbH received U.S. FDA approved for Cyltezo (adalimumab-adbm), an interchangeable biosimilar to HUMIRA, for treating various chronic inflammatory diseases, including RA, in the U.S.
Rheumatoid Arthritis Therapeutics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 26.9 billion
Estimated market size in 2026
USD 28.3 billion
Projected market size by 2033
USD 45.2 billion
Growth rate
CAGR of 6.9% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Molecule, sales channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
AbbVie, Inc.; Boehringer Ingelheim International GmbH; Novartis AG; Regeneron Pharmaceuticals Inc.; Pfizer, Inc.; Bristol-Myers Squibb Company; F. Hoffmann-La Roche Ltd.; UCB S.A.; Johnson & Johnson Services, Inc.; Amgen, Inc.; Lilly (Eli Lilly and Company).
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Rheumatoid Arthritis Therapeutics Market Report Segmentation
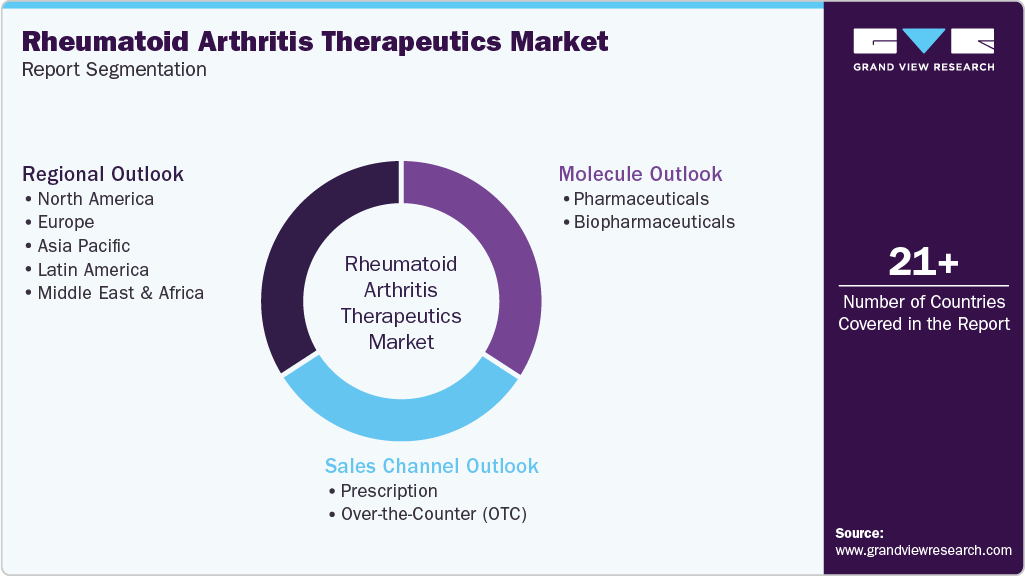
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global rheumatoid arthritis therapeutics market report based on molecule, sales channel, and region:
 To learn more about this report, Download Free Sample Report
-
Molecule Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmaceuticals
-
NSAIDs
-
Analgesics
-
DMARDs
-
Glucocorticoids
-
-
Biopharmaceuticals
-
Biologics
-
TNF-α antagonists
-
T-cell inhibitors
-
CD20 antigen
-
JAK inhibitors
-
Anti-IL6 biologics
-
-
Biosimilars
-
CD20 antigen
-
TNF-α antagonists
-
-
-
-
Sales Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Prescription
-
Over-the-Counter (OTC)
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The rheumatoid arthritis therapeutics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each rheumatoid arthritis therapeutics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment -Molecule
Revenue capture definition
Pharmaceuticals
Revenue generated from conventional rheumatoid arthritis therapies, including NSAIDs, analgesics, disease modifying antirheumatic drugs (DMARDs), and glucocorticoids prescribed or purchased for disease management and symptom control. This segment includes all sales associated with non-biologic pharmaceutical treatments irrespective of treatment duration, disease severity, or distribution channel. Revenue attributable to these therapies is reported exclusively within this segment and excluded from biologic and biosimilar categories.
Biopharmaceuticals
Revenue generated from biologic and biosimilar therapies used in the treatment of rheumatoid arthritis, including TNF alpha antagonists, T cell inhibitors, CD20 antigen therapies, JAK inhibitors, Anti IL6 biologics, CD20 antigen biosimilars, and TNF alpha antagonist biosimilars. All sales associated with these advanced immunology therapies are classified exclusively within this segment irrespective of manufacturer, geography, or sales channel. Revenue from these therapies is excluded from the pharmaceuticals segment.
Segment - Sales Channel
Revenue capture definition
Prescription
Revenue generated from rheumatoid arthritis therapeutics dispensed through physician authorized prescriptions, including pharmaceuticals, biologics, and biosimilars distributed through hospitals, specialty pharmacies, retail pharmacies, mail order pharmacies, and other regulated healthcare channels. Revenue is assigned to this segment when a valid prescription is required for product dispensing and use.
Over the Counter (OTC)
Revenue generated from non-prescription rheumatoid arthritis symptom management products available directly to consumers without physician authorization. This segment primarily includes OTC NSAIDs and selected analgesics used for pain relief and inflammation management. Revenue is allocated exclusively to this segment when products are purchased through consumer retail channels without prescription requirements.
Estimation Model
 To learn more about this report, Download Free Sample Report
The Rheumatoid Arthritis Therapeutics Market was estimated using a commodity flow and revenue-based market analysis approach. The methodology began with the identification of key manufacturers and commercially available therapies used in rheumatoid arthritis treatment. Major products across pharmaceuticals and biopharmaceuticals were benchmarked based on annual revenues, prescription volumes, treatment adoption rates, pricing trends, patent status, and geographic presence. Key therapy categories including NSAIDs, analgesics, disease modifying antirheumatic drugs, glucocorticoids, TNF alpha antagonists, T cell inhibitors, CD20 antigen therapies, JAK inhibitors, Anti IL6 biologics, and biosimilars were evaluated to determine their contribution to the market. Revenue generated from leading products was assessed using company annual reports, investor presentations, regulatory filings, prescription databases, and healthcare expenditure records.
The market estimates were further validated through an assessment of diagnosed rheumatoid arthritis patient populations, treatment utilization rates, biologic penetration, biosimilar adoption, and long-term therapy requirements. Current prescribing patterns, therapy switching trends, and utilization across hospitals, specialty clinics, and outpatient care settings were analyzed to evaluate demand side dynamics. Market shares of leading manufacturers were assessed based on product portfolios, commercial presence, and penetration within rheumatoid arthritis treatment pathways. Data triangulation was performed by comparing manufacturer revenues, prescription volumes, patient treatment rates, and therapy utilization trends to ensure consistency across market estimates. Forecast projections incorporated disease prevalence trends, diagnosis rates, biosimilar adoption, pricing dynamics, reimbursement developments, and advancements in targeted immunology therapies designed to improve disease control and long-term patient outcomes.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Advanced Therapy Adoption Analysis
Assessment of adoption trends across TNF inhibitors, JAK inhibitors, IL-6 inhibitors, T-cell inhibitors, CD20-targeted therapies, and emerging immunology treatments, including prescribing patterns, treatment sequencing, switching behavior, and utilization across major healthcare markets.
Helps identify high growth therapeutic segments, evolving treatment preferences, physician adoption trends, and commercialization opportunities across the rheumatoid arthritis treatment landscape.
Treatment Pathway and Patient Journey Assessment
Analysis of patient progression from diagnosis through conventional DMARD therapy, biologic initiation, targeted therapy adoption, treatment escalation, and therapy switching patterns, including factors influencing treatment selection and persistence.
Supports identification of unmet clinical needs, patient retention opportunities, treatment optimization strategies, and market expansion opportunities across different stages of rheumatoid arthritis management.
Diagnostic and Early Disease Management Landscape Evaluation
Evaluation of diagnostic practices, referral pathways, biomarker utilization, disease activity assessment tools, imaging approaches, and early intervention initiatives influencing rheumatoid arthritis diagnosis and treatment initiation.
Tracks opportunities related to earlier patient identification, improved treatment penetration, reduced disease progression, and expansion of the addressable patient population.
Pipeline and Innovation Landscape Assessment
Assessment of emerging therapies, novel mechanisms of action, next generation biologics, biosimilar developments, clinical pipeline activity, and advancements in immunology research relevant to rheumatoid arthritis treatment.
Identifies future growth opportunities, competitive differentiation factors, innovation driven areas, and pipeline assets expected to influence market evolution.
Frequently Asked Questions About This Report
The key players in the rheumatoid arthritis therapeutics market include AbbVie, Inc., Boehringer Ingelheim International GmbH, Novartis AG, Regeneron Pharmaceuticals Inc., and Pfizer, Inc., recognized for their strong portfolios in biologics, targeted synthetic DMARDs, and immunotherapies. Bristol-Myers Squibb Company, F. Hoffmann-La Roche Ltd., UCB S.A., Johnson & Johnson Services, Inc., Amgen, Inc., and Eli Lilly and Company further strengthen the market through innovation, biosimilars, and global distribution networks.
The rheumatoid arthritis therapeutics market is driven by the rising prevalence of RA globally, particularly in aging populations, creating strong demand for advanced treatments. Continuous innovation in biologics, JAK inhibitors, and targeted synthetic DMARDs has improved disease management and patient outcomes.
Based on sales channel, the prescription segment led the market with the largest revenue share of 90.3% in 2025.
North America dominated the rheumatoid arthritis therapeutics market with the largest revenue share of 51.8% in 2025.
Based on molecule, the biopharmaceuticals segment led the market with the largest revenue share of 88.5% in 2025..
The global rheumatoid arthritis therapeutics market size was estimated at USD 26.9 billion in 2025 and is projected to grow to USD 28.3 billion in 2026
The global rheumatoid arthritis therapeutics market is projected to grow at a CAGR of 6.9% from 2026 to 2033 to reach USD 45.2 billion by 2033.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


