
- Home
- »
- Next Generation Technologies
- »
-
Shortwave Infrared Market Size & Share Report, 2026-2033GVR Report cover

Shortwave Infrared Market (2026 - 2033)
Size, Share & Trends Analysis Report By Offering, By Imaging Type (Spectral Imaging, Thermal Imaging, Hyperspectral Imaging), By Technology, By Vertical, By Region, And Segment Forecasts
Market Size, 2025
$670.0MMarket Estimate, 2026
$746.3MMarket Forecast, 2033
$1,684.0MCAGR, 2026–2033
12.3%Shortwave Infrared Market Summary
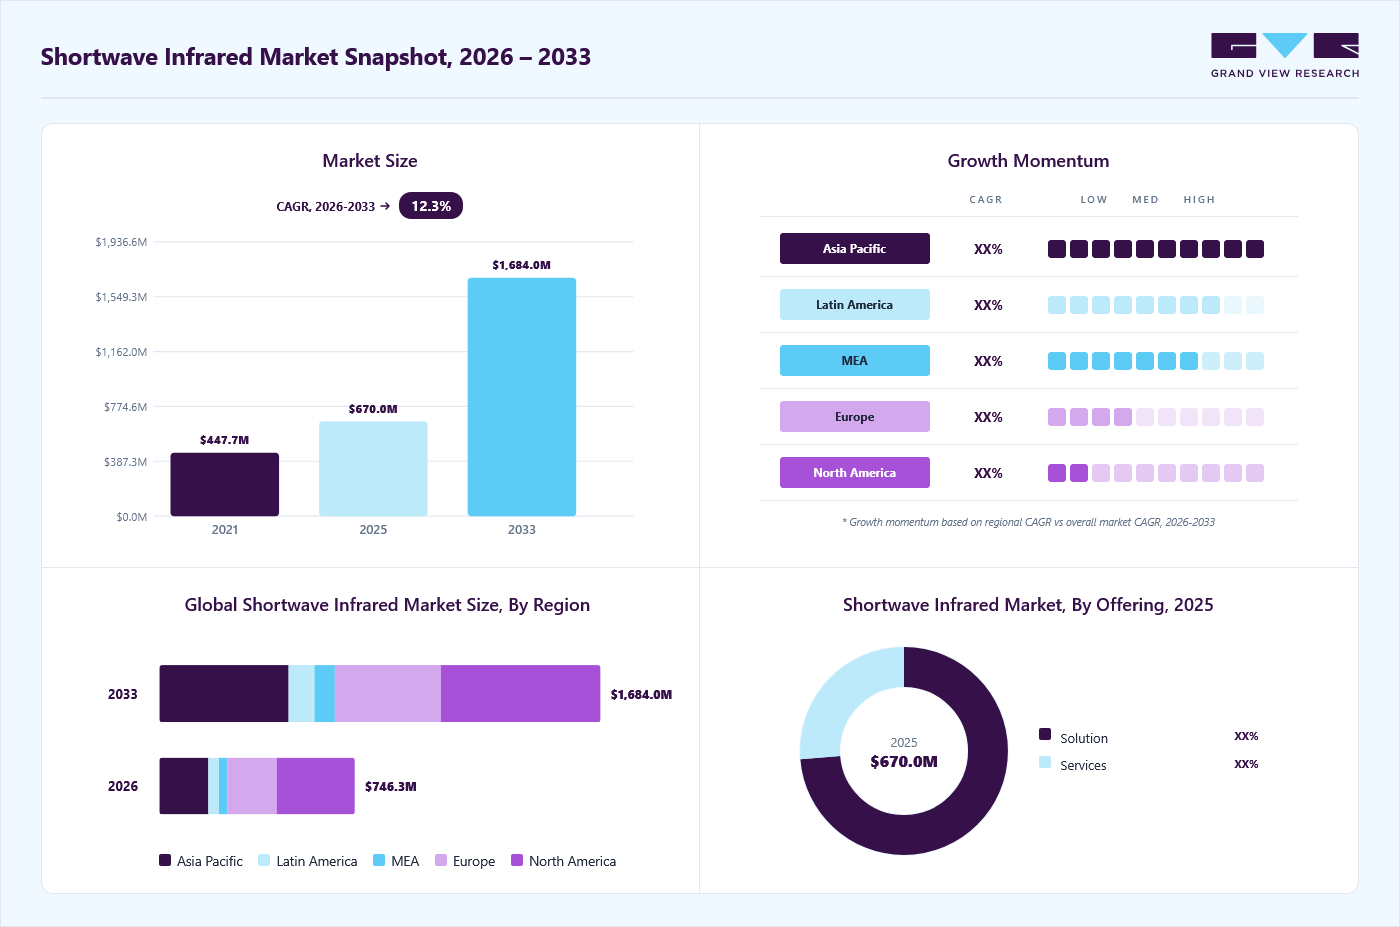
The global shortwave infrared market size was estimated at USD 670.0 million in 2025 and is projected to grow from USD 746.3 million in 2026 to USD 1,684.0 million by 2033, growing at a CAGR of 12.3% from 2026 to 2033. North America dominated the shortwave infrared market with the largest revenue share of 40.5% in 2025. The market is witnessing strong momentum from the increasing integration of SWIR imaging technologies into AI-powered machine vision systems, advanced industrial inspection platforms, and next-generation defense surveillance applications.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By offering: Solution segment dominated the market, with a revenue share of 73.7% in 2025.
- By imaging type: Spectral Imaging segment held the largest market share of 49.2% in 2025.
- By technology: Uncooled segment held the largest revenue share in 2025.
- By vertical: Military and Defense segment held the largest revenue share in 2025.
Regional Highlights
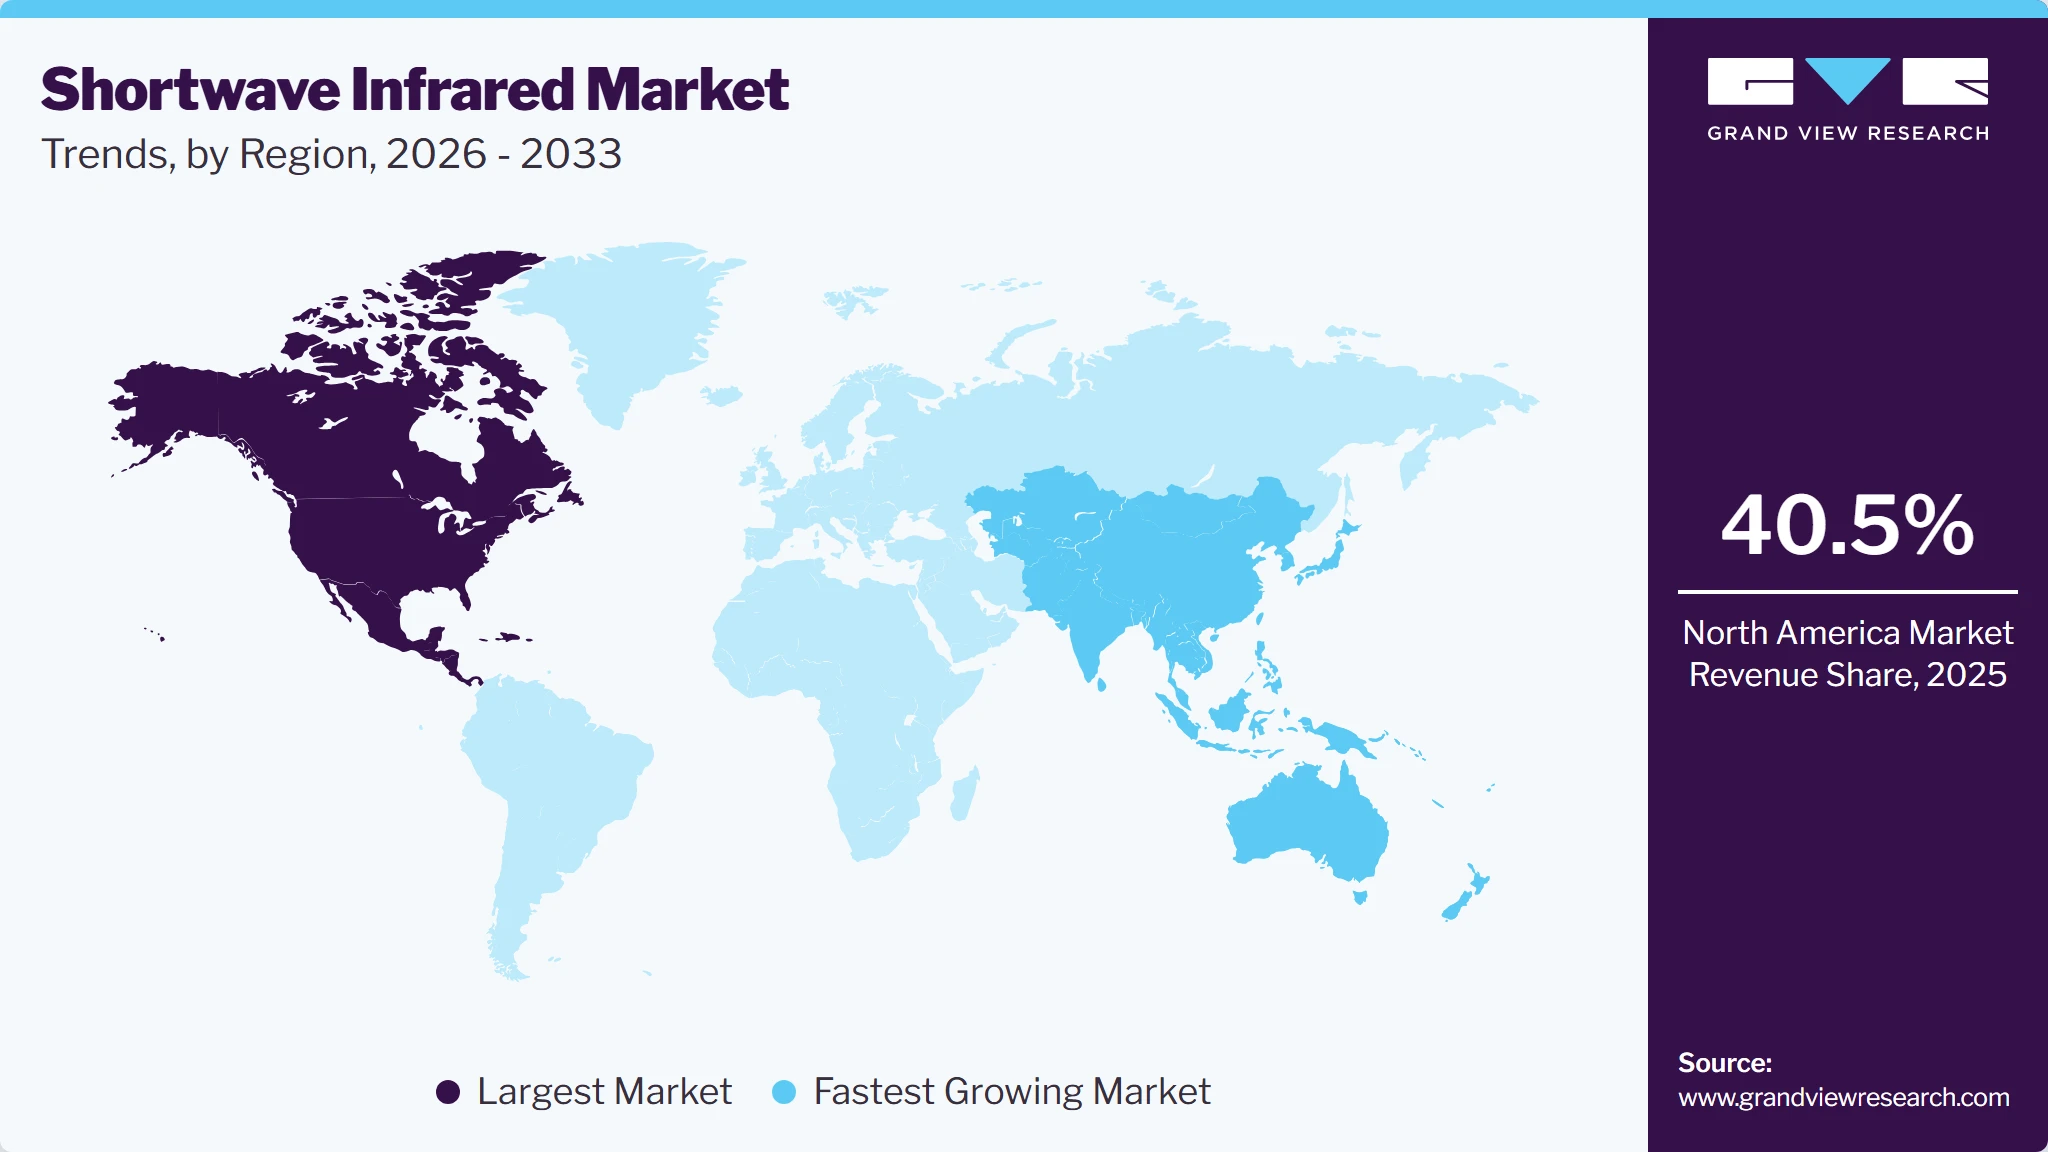
- Largest regional market: North America (40.5% revenue share, 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 670.0 Million
- Estimated market size in 2026: USD 746.3 Million
- Projected market size by 2033: USD 1,684.0 Million
- CAGR (2026-2033): 12.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market growth is driven by expanding applications across industries such as defense, industrial inspection, healthcare, and security. SWIR refers to the wavelength range between 1.0 and 3.0 microns, which offers unique imaging advantages due to its ability to penetrate materials and capture high-contrast images even in low-light conditions. As industries increasingly demand enhanced imaging and sensing solutions, SWIR technology is becoming essential for applications such as surveillance, agriculture, electronics inspection, and scientific research. For instance, in April 2024, Quantum Solutions, a leader in quantum dot technology, announced the launch of its Q.Eye SWIR (short-wave infrared) image sensors. These cutting-edge sensors, with an impressive spectral range of 400-1700 nm, are poised to revolutionize imaging capabilities in machine vision and robotics applications.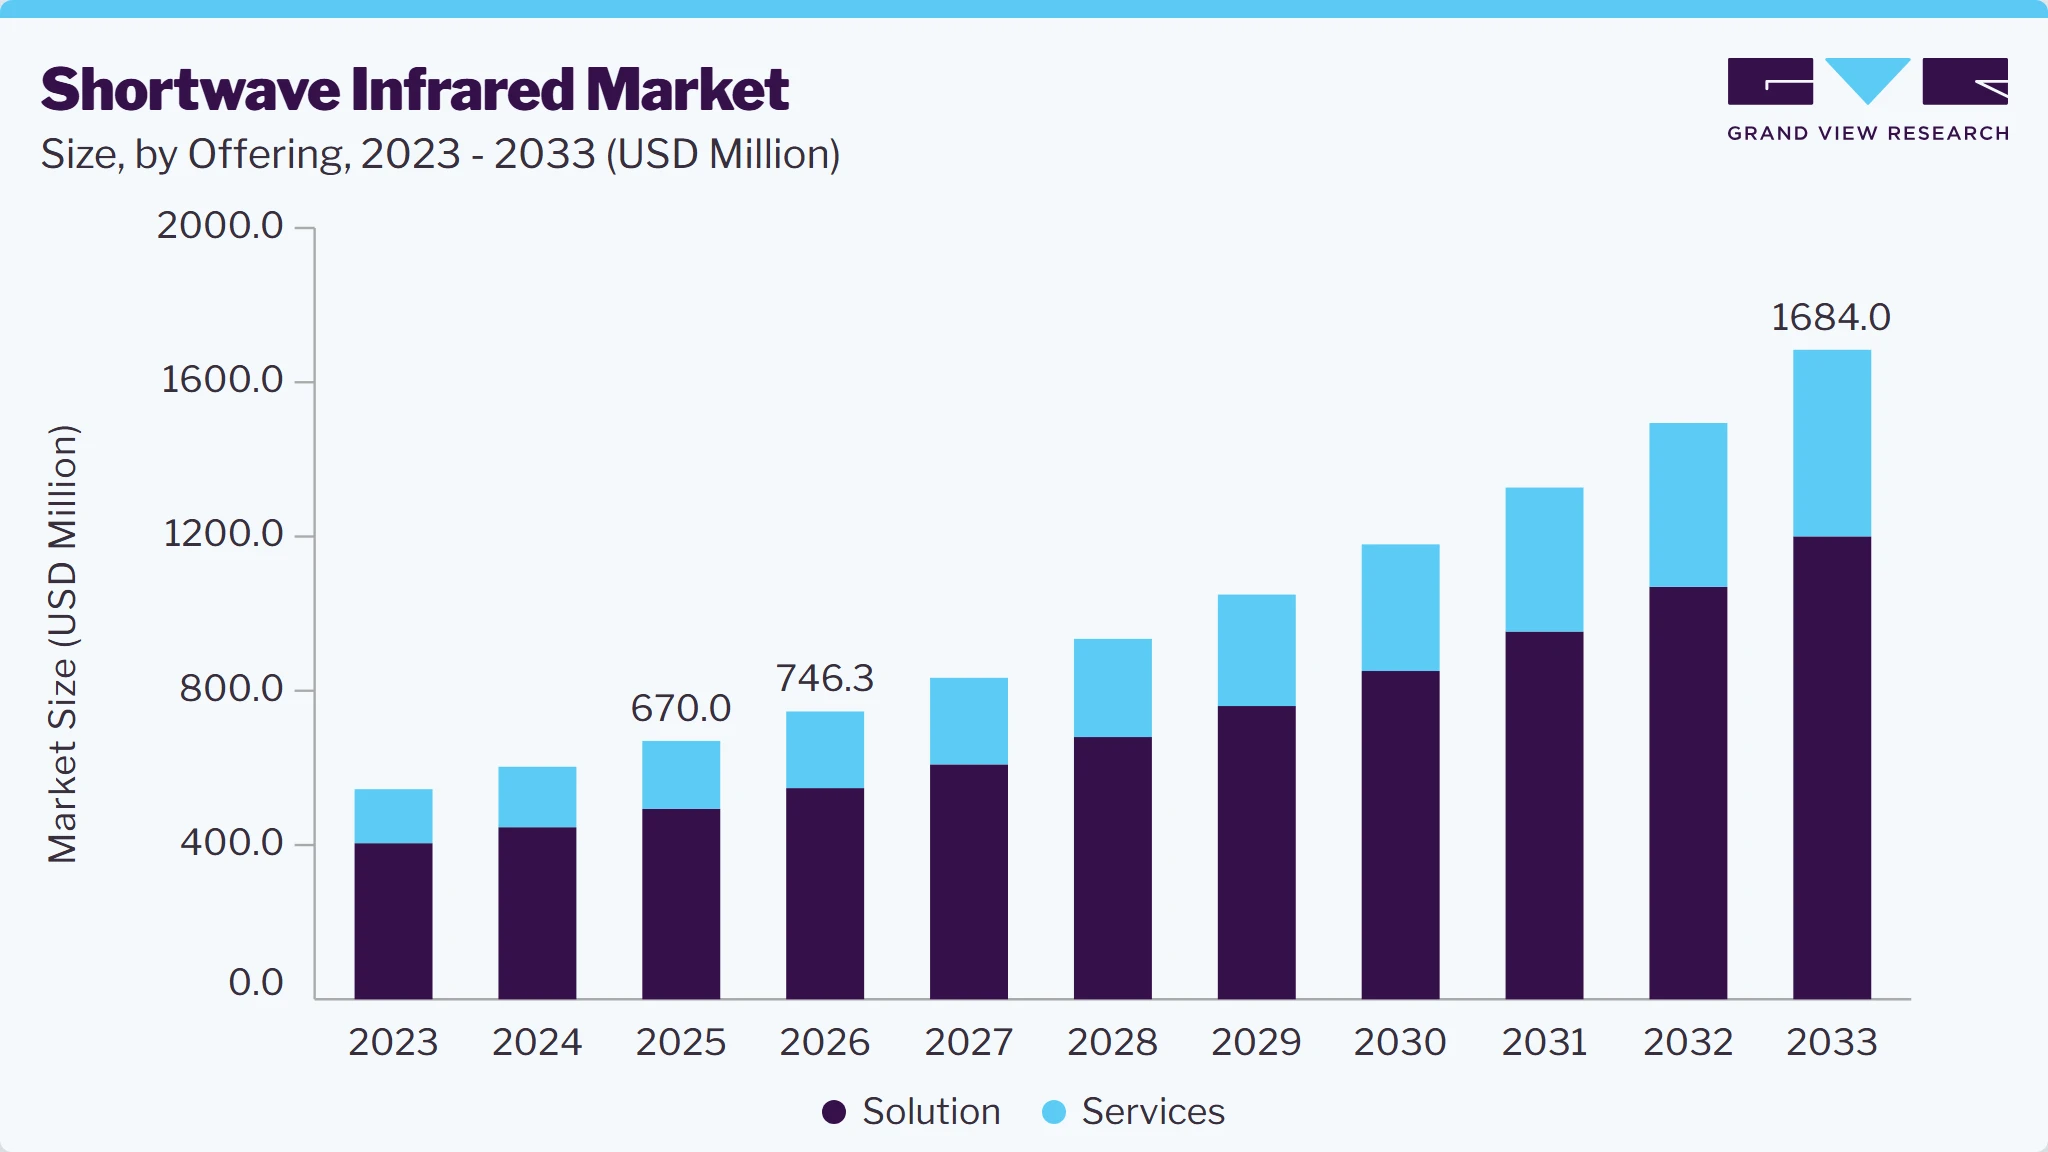 To learn more about this report, Download Free Sample Report
One of the primary growth drivers in the shortwave infrared (SWIR) industry is its rising adoption in defense and military operations. SWIR imaging systems provide enhanced visibility during night operations and through adverse weather conditions, aiding in target detection, navigation, and situational awareness. The market is also seeing robust growth in the industrial sector, where SWIR cameras are used for quality control, non-destructive testing, and material identification, particularly in semiconductors and pharmaceuticals. Additionally, advancements in SWIR sensor technology, such as reduced costs and miniaturization, are fueling wider adoption in consumer electronics, autonomous vehicles, and environmental monitoring. The growing need for sophisticated surveillance and security systems in both public and private sectors further supports market expansion.
SWIR cameras are now utilized across a wide range of applications, including vehicle navigation, where demand has surged. These cameras are highly effective in navigating challenging conditions like fog, snow, or dust. SWIR technology's ability to distinguish between colors and analyze material properties, such as water vapor, air temperature, and chemical composition, makes it ideal for applications like spectrometry, aircraft inspection, and astronomy. The technology is also witnessing increased use in scientific research areas, such as ecosystem evaluation, climate change studies, ergonomics, microbe and disease assessment, and psychology.
Market Dynamics
The shortwave infrared (SWIR) market is experiencing strong growth driven by the increasing adoption of advanced imaging technologies across defense, industrial automation, semiconductor manufacturing, scientific research, and machine vision applications. Organizations are increasingly deploying SWIR cameras, SWIR sensors, and infrared imaging systems to achieve superior visibility in low-light, foggy, smoky, and challenging environmental conditions where conventional imaging technologies face limitations. The growing integration of artificial intelligence, automation, and smart manufacturing initiatives is further expanding the use of SWIR solutions for real-time monitoring, quality inspection, and predictive maintenance. However, high equipment costs, complex system integration requirements, and the need for specialized sensor technologies remain key challenges affecting broader market penetration.
The growing deployment of shortwave infrared imaging systems across defense and security applications is a major driver for market growth. Military organizations and border security agencies are increasingly utilizing SWIR cameras for surveillance, target detection, reconnaissance, and situational awareness due to their ability to capture high-contrast images under adverse weather conditions and low-light environments. Unlike visible-light cameras, SWIR technology can detect objects through haze, smoke, and fog, making it highly valuable for mission-critical operations. Rising investments in defense modernization programs and advanced surveillance infrastructure are further strengthening demand for SWIR solutions worldwide.
Industrial sectors are also accelerating the adoption of SWIR cameras and sensors for machine vision, semiconductor inspection, food sorting, solar panel inspection, and quality control applications. Manufacturers require advanced imaging technologies capable of identifying defects and material inconsistencies that are difficult to detect using conventional imaging systems. As industrial automation and smart manufacturing initiatives continue to expand, the need for accurate, real-time inspection systems is increasing significantly. This trend is positioning SWIR technology as a critical component in next-generation industrial monitoring and process optimization strategies.
One of the primary restraints affecting the SWIR market is the high cost of InGaAs sensors, specialized optics, and advanced image-processing components. SWIR imaging systems require sophisticated sensor technologies and precision-engineered optical assemblies, resulting in significantly higher acquisition costs compared to visible-spectrum imaging solutions. These cost barriers can limit adoption among small and medium-sized enterprises and organizations operating under constrained capital expenditure budgets. As a result, many potential users continue to rely on alternative imaging technologies despite the superior capabilities offered by SWIR systems.
In addition to hardware expenses, deployment often involves complex integration with existing surveillance, inspection, and automation infrastructure. Organizations must invest in system calibration, software customization, operator training, and ongoing maintenance to ensure optimal performance. The need for specialized technical expertise can further increase implementation costs and project timelines. These challenges can slow down adoption rates, particularly in emerging markets where budget constraints and limited technical resources remain significant considerations.
The increasing convergence of artificial intelligence (AI), machine learning, and SWIR imaging technology presents a significant growth opportunity for the market. AI-enabled SWIR systems can analyze large volumes of visual data in real time, enabling advanced capabilities such as automated defect detection, object classification, anomaly identification, and predictive maintenance. These capabilities are becoming increasingly valuable across manufacturing, semiconductor production, logistics, and security applications where operational efficiency and accuracy are critical. As organizations seek to automate decision-making processes, demand for intelligent SWIR-based imaging solutions is expected to grow substantially.
The expansion of Industry 4.0, smart factories, and autonomous inspection systems is creating additional opportunities for SWIR technology providers. Manufacturers are increasingly investing in advanced machine vision platforms that combine SWIR imaging with AI analytics to improve productivity, reduce waste, and enhance product quality. Furthermore, the emergence of edge computing and intelligent sensing technologies is enabling faster processing of SWIR image data directly at the source. These developments are expected to broaden the application scope of SWIR solutions and support long-term market growth across multiple industry verticals.
Market Concentration & Characteristics
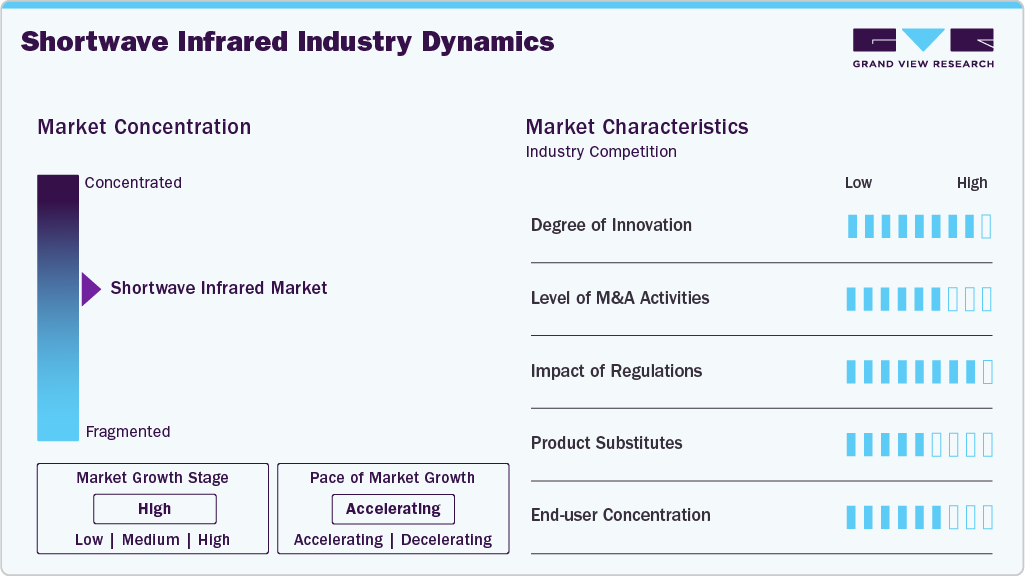
The Shortwave Infrared (SWIR) market exhibits a moderately concentrated competitive structure, with a select group of established manufacturers maintaining strong positions in SWIR sensors, InGaAs detectors, infrared cameras, and optical imaging solutions. These companies benefit from extensive research and development capabilities, proprietary technologies, and long-standing relationships with defense, industrial, and semiconductor customers. The market is characterized by a high degree of innovation, driven by continuous advancements in sensor performance, image processing capabilities, hyperspectral imaging, and AI-enabled machine vision systems. Consequently, competition remains technology-focused, with market participants emphasizing product differentiation, imaging accuracy, and application-specific performance improvements.
 To learn more about this report, Download Free Sample Report
Despite the presence of leading technology providers, the market remains partially fragmented due to the participation of specialized vendors serving niche applications across industrial inspection, scientific research, food sorting, surveillance, and semiconductor manufacturing. Regulatory influence is relatively high, particularly in defense and security applications, where export controls and compliance requirements impact technology deployment and cross-border trade. The availability of alternative imaging technologies such as thermal and visible-spectrum cameras provides some competitive pressure; however, these solutions often lack the unique imaging capabilities offered by SWIR systems. Supported by expanding adoption across automation, defense modernization, and advanced sensing applications, the market is currently in a high-growth stage with an accelerating pace of expansion.
Analyst Perspective
The shortwave infrared market is poised for strong growth, driven by increasing demand for advanced imaging solutions across defense, industrial automation, semiconductor inspection, and machine vision applications. Continuous advancements in InGaAs sensor technology, image processing capabilities, and AI-enabled analytics are expanding the performance and commercial viability of SWIR systems. The growing adoption of smart manufacturing, autonomous systems, and surveillance technologies is further accelerating market penetration across both commercial and government sectors. In addition, rising investments in defense modernization and semiconductor manufacturing are creating new opportunities for SWIR camera and sensor providers. As end users increasingly prioritize high-precision imaging and real-time monitoring capabilities, the market is expected to witness sustained innovation and long-term expansion over the forecast period.
Offering Insights
Based on Offering, the solution segment led the market with the largest revenue share of 73.7% in 2025, primarily due to the growing demand for advanced imaging and sensing technologies across multiple industries. Solutions, including SWIR cameras, sensors, and related software, are increasingly sought after for their ability to enhance visibility in challenging environments, such as fog, smoke, and low light. Additionally, advancements in SWIR technology, such as improved resolution and cost efficiency, have made these solutions more accessible. In September 2024, TriEye LTD, a pioneer in cost-effective, mass-market SWIR sensing technology, unveiled the TES200, a 1.3MP SWIR image sensor. Operating within the 700nm to 1650nm wavelength range, the TES200 delivers exceptional sensitivity and high-resolution imaging. Featuring a high frame rate, large format, and low power consumption, it offers enhanced sensitivity and dynamic range. This makes the TES200 an ideal solution for imaging and sensing applications across industries such as industrial, automotive, robotics, and biometrics.
The services segment is predicted to foresee significant growth in the coming years, largely due to increasing demand for installation, maintenance, and customization services. As more industries adopt SWIR technologies for applications such as surveillance, industrial inspection, and environmental monitoring, the need for expert support in system integration and optimization is rising. Additionally, ongoing advancements in SWIR technologies require continuous technical assistance and training, further driving growth in the services sector. The expansion of tailored solutions for specific industries, such as defense, healthcare, and agriculture, also contributes to the heightened demand for consulting and support services, positioning this segment for robust growth throughout the forecast period.
Imaging Type Insights
The thermal imaging segment accounted for the largest market revenue share in 2024. The ability of SWIR thermal imaging to detect heat signatures and capture high-contrast images in challenging conditions like darkness, smoke, or extreme temperatures makes it invaluable for security and military operations. Additionally, industries such as manufacturing and energy are adopting thermal imaging for equipment monitoring, fault detection, and predictive maintenance. The rising focus on safety, along with advancements in sensor technology and cost efficiency, is further propelling the adoption of SWIR thermal imaging solutions across various sectors.
The spectral imaging segment led the market with the largest revenue share of 49.2% in 2025. Spectral imaging in the SWIR range allows for the identification of chemical compositions, moisture content, and material properties, making it invaluable in industries like agriculture, pharmaceuticals, and environmental monitoring. The growing demand for advanced imaging in areas such as food quality inspection, mineral mapping, and medical diagnostics is further boosting its adoption. Additionally, technological advancements in SWIR sensors and cameras, which enhance resolution and spectral sensitivity, are contributing to the rapid growth of this segment as industries seek more accurate and efficient imaging solutions.
Technology Insights
Based on technology, the uncooled segment led the market with the largest revenue share of 53.9% in 202. Unlike cooled SWIR systems, uncooled SWIR cameras do not require cryogenic cooling, making them more affordable, energy-efficient, and easier to integrate into various applications. This technology is particularly attractive for sectors like industrial inspection, automotive, and security, where lower costs and ease of use are key factors. Additionally, advancements in uncooled sensor performance, such as improved sensitivity and durability, are enabling broader adoption in diverse fields, including agriculture and environmental monitoring.
The cooled segment is anticipated to witness significant growth in the coming years. Cooled SWIR cameras, which use cryogenic cooling to minimize thermal noise, offer enhanced sensitivity and image clarity, making them ideal for critical uses in defense, astronomy, and scientific research. These systems excel in long-range detection, low-light environments, and extreme temperature conditions, which are essential for tasks like missile tracking, space exploration, and environmental monitoring. For instance, in March 2024, SVS-Vistek GmbH expanded its FXO Series of machine vision cameras with the launch of two new SWIR models, the fxo992 and fxo993. These cameras are specifically designed for high-resolution SWIR imaging at high speed, making them ideal for machine vision applications, particularly in inspection tasks. Both models also feature thermoelectric (TEC) cooling options for enhanced performance.
Vertical Insights
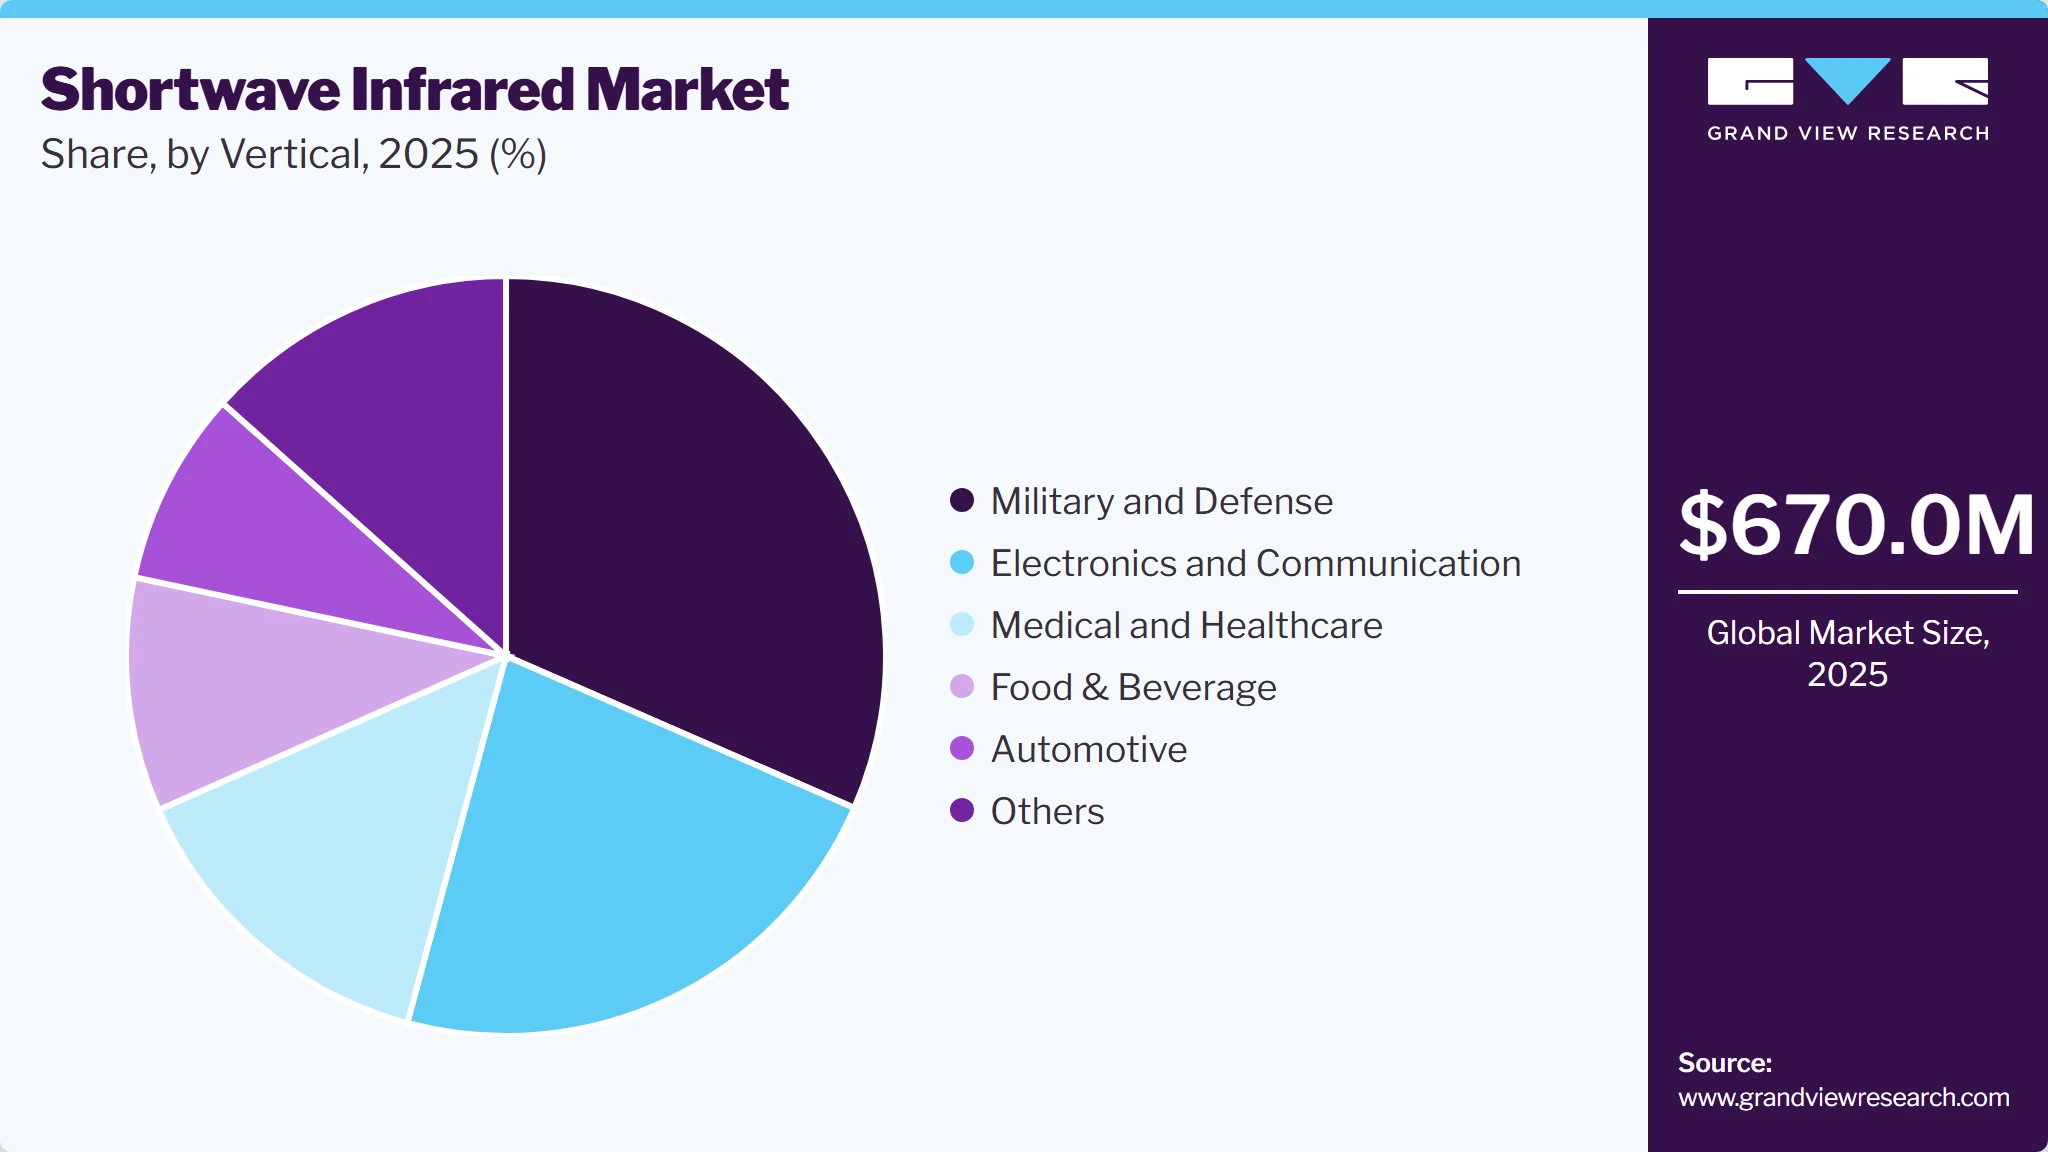
Based on vertical, the military and defense segment led the market with the largest revenue share of 31.5% in 2025. SWIR technology offers enhanced imaging performance in challenging conditions, such as low-light environments and through atmospheric obscurants, making it invaluable for military applications. Furthermore, the rise in defense budgets across various countries, coupled with the need for modernized equipment, is driving investment in SWIR systems for applications like target acquisition, intelligence gathering, and situational awareness. This growth is further supported by technological advancements in SWIR sensors, which improve detection range and image quality, strengthening their critical role in military operations. For instance, in October 2024, Lynred, a manufacturer and designer of IR sensors for aerospace, defense, and commercial applications, made a strategic move to strengthen its position in the IR sensor market by acquiring Paris-based New Imaging Technologies (NIT). This acquisition allows Lynred to expand its portfolio to include HD large-array SWIR sensors with small pixel pitch, further enhancing its product offerings across all wavelength bands, from shortwave to very longwave infrared.
 To learn more about this report, Download Free Sample Report
The medical and healthcare segment is anticipated to exhibit the fastest CAGR over the forecast period, driven by the increasing adoption of advanced imaging techniques and diagnostic tools. SWIR technology provides superior imaging capabilities for various medical applications, including tissue analysis, cancer detection, and monitoring of physiological parameters. Its ability to penetrate biological tissues with minimal damage enables non-invasive diagnostics, enhancing patient safety and comfort. Furthermore, the growing emphasis on early disease detection and personalized medicine is fueling demand for SWIR imaging systems in healthcare settings.
Regional Insights
North America dominated the shortwave infrared market with the largest revenue share of 40.5% in 2025. The region’s strong focus on military and defense applications drives demand for SWIR systems, particularly for surveillance and reconnaissance purposes. Additionally, the burgeoning medical and healthcare sectors are increasingly adopting SWIR technology for non-invasive diagnostics and imaging solutions. Government initiatives to enhance research and development in photonics and imaging systems further bolster market growth.
 To learn more about this report, Download Free Sample Report
U.S. Shortwave Infrared Market Trends
TThe shortwave infrared market in the U.S. held the largest share in the North America region in 2025. The country’s substantial investments in military and defense applications significantly boost the demand for SWIR technology, particularly for advanced surveillance, reconnaissance, and target identification systems. Additionally, the increasing use of SWIR in the medical and healthcare sectors for diagnostic imaging and monitoring further fuels market growth.
Europe Shortwave Infrared Market Trends
The SWIR market in Europe is expected to witness significant growth over the forecast period, primarily due to increasing investments in advanced imaging technologies across various sectors. The region’s emphasis on research and development, particularly in military and defense applications, is driving demand for SWIR systems used in surveillance, reconnaissance, and target acquisition.
Asia Pacific Shortwave Infrared Market Trends
The SWIR market in Asia Pacific is anticipated to register rapid growth over the forecast period. The rising defense budgets in countries like China and India are fueling investments in advanced imaging systems for surveillance and reconnaissance. The growing focus on research and development, along with supportive government initiatives, further accelerates the adoption of SWIR technology across various applications, positioning APAC as a vital growth market.
Key Shortwave Infrared Company Insights
Some key companies in the SWIR market include Teledyne FLIR LLC, Corning Incorporated, Collins Aerospace, Allied Vision Technologies GmbH, and Leonardo DRS.
-
Teledyne FLIR LLC, formerly FLIR Systems Inc., is an American manufacturer specializing in thermal imaging cameras and sensors. Teledyne FLIR offers a range of products, including handheld and fixed-mount thermal security cameras, cameras, machine vision cameras, thermography cameras, and gas detection cameras. These advanced imaging solutions serve various applications across industries such as security, law enforcement, defense, and industrial inspection, enhancing perception and awareness in challenging environments.
-
Corning Incorporated, a prominent American technology company, is a key player in the SWIR market. Leveraging its extensive expertise in materials science and optics, the company develops advanced SWIR technologies for various applications, including aerospace and defense. Notably, the company collaborated with Orbital Sidekick on the Aurora Hyperspectral Imaging satellite, utilizing high-resolution SWIR capabilities to enhance imaging performance. Corning Incorporated's innovations in SWIR technology contribute significantly to the growth and diversification of the SWIR market.
Key Shortwave Infrared Companies
The following key companies have been profiled for this study on the shortwave infrared market.
-
Teledyne FLIR LLC
-
Corning Incorporated
-
Collins Aerospace
-
Allied Vision Technologies GmbH
-
Leonardo DRS
-
Hamamatsu Photonics K.K.
-
Fluke Corporation
-
New Imaging Technologies (NIT)
-
Raptor Photonics
-
Lynred
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Teledyne FLIR LLC, Collins Aerospace, Leonardo DRS, Hamamatsu Photonics K.K., and Lynred
- Mature players focus on advanced SWIR imaging systems, defense surveillance solutions, high-performance sensors, and long-term government and industrial partnerships. Their strategies emphasize continuous innovation, product reliability, and expansion across defense, aerospace, and industrial inspection applications.
- Their competitive advantage is supported by strong R&D capabilities, proprietary sensor technologies, established customer relationships, and global distribution networks. These strengths enable them to serve high-value and mission-critical applications effectively.
- Longer product development cycles and high dependence on defense and large industrial projects can limit flexibility. Regulatory requirements and complex procurement processes may also slow market responsiveness.
Emerging Players: Allied Vision Technologies GmbH, New Imaging Technologies (NIT), Raptor Photonics, Corning Incorporated, and Fluke Corporation
- Emerging players are focused on compact SWIR cameras, machine vision systems, industrial inspection solutions, and niche imaging applications. Their strategies prioritize rapid innovation, customized solutions, and expansion into emerging commercial markets.
- Their competitive edge comes from specialized expertise, agile product development, and strong application-specific capabilities. This enables them to respond quickly to evolving customer and industry requirements.
- Limited global presence and smaller financial resources compared to established market leaders may restrict large-scale expansion. Lower brand recognition can also impact participation in major defense and enterprise projects.
Recent Developments
-
In July 2024, onsemi (Semiconductor Components Industries, LLC) acquired SWIR VISION SYSTEMS, INC., a company known for its advanced SWIR technology based on colloidal quantum dots (CQD). This technology allows sensors to capture images beyond the typical visible spectrum, enhancing imaging in areas like industrial automation, surveillance, and autonomous vehicles. By integrating SWIR with its CMOS sensors, onsemi aims to provide more cost-effective, high-performance imaging solutions for various sectors, including automotive and defense.
-
In April 2024, New Imaging Technologies (NIT) launched its latest advancement in SWIR imaging technology: the high-resolution SWIR InGaAs sensor precisely engineered to tackle the industry's toughest challenges. NSC2101, the new SWIR, features a high-performance InGaAs sensor with an 8µm pixel pitch, offering an impressive resolution of 2 MPIX at 1920x1080px. With an ultra-low noise level of just 25e-, it ensures outstanding image clarity even in demanding conditions.
-
In October 2023, Omron Corporation launched a new line of SWIR cameras aimed at enhancing precision inspection in manufacturing. These cameras enable visibility beyond the capabilities of standard vision systems, making them ideal for detecting defects in materials like glass, silicon, and plastics. The SWIR technology allows for higher accuracy in inspecting products during various manufacturing stages, improving quality control and reducing waste.
Shortwave Infrared Market Report Scope
Report Attribute
Details
Market size in 2025
USD 670.0 million
Estimated market size in 2026
USD 746.3 million
Projected market size by 2033
USD 1,648.0 million
Growth rate
CAGR of 12.3% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Offering, imaging type, technology, vertical, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
Teledyne FLIR LLC; Corning Incorporated; Collins Aerospace; Allied Vision Technologies GmbH; Leonardo DRS; Hamamatsu Photonics K.K.; Fluke Corporation; New Imaging Technologies (NIT); Raptor Photonics; Lynred
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Shortwave Infrared Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global SWIR market report based on offering, imaging type, technology, vertical, and region:
-
Offering Outlook (Revenue, USD Million, 2021 - 2033)
-
Solution
-
Services
-
-
Imaging Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Spectral Imaging
-
Thermal Imaging
-
Hyperspectral Imaging
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Cooled
-
Uncooled
-
-
Vertical Outlook (Revenue, USD Million, 2021 - 2033)
-
Electronics and Communication
-
Military and Defence
-
Medical and Healthcare
-
Food & Beverage
-
Automotive
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
MEA
-
UAE
-
South Africa
-
KSA
-
-
Research Methodology
The shortwave infrared market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each shortwave infrared segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Offering
Revenue capture definition
Solution
The solution segment comprises SWIR cameras, sensors, imaging systems, optical components, and software platforms used for image acquisition, processing, and analysis. These solutions enable high-performance imaging capabilities across defense, industrial inspection, semiconductor manufacturing, surveillance, and scientific research applications.
Services
This segment includes consulting, system integration, installation, maintenance, calibration, training, and technical support services associated with SWIR technologies. Service providers help organizations optimize system performance, ensure operational reliability, and maximize the return on investment of SWIR deployments.
Segment - Imaging Type
Revenue capture definition
Spectral Imaging
The spectral imaging segment involves the capture and analysis of image data across selected wavelength bands within the shortwave infrared spectrum. It is widely utilized for material identification, quality inspection, agricultural monitoring, and industrial process control applications.
Thermal Imaging
This segment refers to SWIR-based imaging technologies that support thermal analysis and temperature-related monitoring in specialized applications. These systems are deployed in industrial diagnostics, defense operations, and equipment inspection where enhanced visibility and thermal information are required.
Hyperspectral Imaging
Hyperspectral Imaging combines imaging and spectroscopy to capture detailed spectral information for every pixel within an image. Technology enables precise material characterization and is increasingly used in semiconductor inspection, food quality assessment, pharmaceuticals, and scientific research.
Segment - Technology
Revenue capture definition
Uncooled
The uncooled segment consists of SWIR imaging systems that operate without dedicated cooling mechanisms, resulting in lower cost, reduced complexity, and improved portability. These solutions are commonly adopted in commercial, industrial, and machine vision applications where cost efficiency and ease of deployment are important considerations.
Cooled
Cooled SWIR systems utilize specialized cooling technologies to enhance sensor sensitivity, image quality, and detection range. They are primarily deployed in defense, aerospace, surveillance, and scientific applications that require superior performance under demanding operating conditions.
Segment - Vertical
Revenue capture definition
Electronics and Communication
The electronics and communication segment utilizes SWIR technology for semiconductor inspection, printed circuit board analysis, wafer inspection, and advanced manufacturing processes. Growing investments in semiconductor fabrication and electronics quality assurance continue to support demand within this segment.
Medical and Healthcare
This segment encompasses the use of SWIR imaging systems in medical diagnostics, biomedical research, surgical visualization, and healthcare monitoring applications. Technology offers enhanced tissue imaging capabilities and supports the development of advanced diagnostic procedures.
Food & Beverage
The food & beverage segment leverages SWIR imaging for product inspection, contamination detection, sorting, grading, and quality assurance processes. Its ability to identify moisture content and material composition makes it valuable across food processing and packaging operations.
Automotive
The automotive segment incorporates SWIR technology into advanced driver assistance systems (ADAS), autonomous vehicle development, manufacturing inspection, and safety applications. Increasing investments in intelligent mobility and vehicle automation are driving adoption across the industry.
Military and Defense
Military and defense represent one of the most significant application areas for SWIR technology, supporting surveillance, reconnaissance, target acquisition, border security, and night vision operations. The technology provides enhanced imaging performance in low-light and adverse environmental conditions, making it critical for mission-sensitive applications.
Others
The others segment includes applications across scientific research, agriculture, energy and utilities, mining, environmental monitoring, and industrial process control. Expanding use cases and technological advancements continue to create new opportunities for SWIR deployment across diverse end-user industries.
Estimation Model
Layer Name
Key Questions
Description
SWIR Application Industry Layer
Who utilizes SWIR imaging technologies across end-use industries?
Identify industries with active adoption of SWIR solutions, including defense & military, semiconductor manufacturing, industrial automation, electronics & communication, healthcare, automotive, food & beverage, scientific research, and surveillance. This layer establishes the total addressable demand base for SWIR cameras, sensors, and imaging systems.
SWIR Imaging System Adoption Layer
Who deploys SWIR-enabled imaging and sensing solutions?
Apply adoption rates of SWIR cameras, InGaAs sensors, machine vision systems, hyperspectral imaging platforms, industrial inspection equipment, and surveillance systems across target industries. This layer estimates the transition from conventional imaging technologies to advanced SWIR-based solutions.
Advanced Imaging & Intelligence Integration Layer
Who integrates AI-enabled and high-performance SWIR technologies?
Apply penetration rates for AI-powered machine vision, automated inspection systems, hyperspectral imaging, predictive analytics, autonomous surveillance, and advanced sensing applications. This layer captures deployment of next-generation SWIR technologies that enhance image analysis, operational efficiency, and decision-making capabilities.
SWIR Market Value Realization Layer
How much value is generated through SWIR technology deployment?
Estimate market revenue by multiplying active SWIR deployments by average spending on cameras, sensors, optics, imaging software, system integration, maintenance services, and related solutions. This layer captures total SWIR market revenue generated across hardware, software, and service components.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Shortwave Infrared Technology Adoption & Growth Assessment
Performed a comprehensive analysis of the Shortwave Infrared (SWIR) market, including advancements in InGaAs sensors, SWIR cameras, hyperspectral imaging, machine vision systems, industrial inspection technologies, defense surveillance solutions, and AI-enabled imaging platforms across key industry verticals.
This assessment enables stakeholders to identify high-growth technology segments, evaluate emerging imaging trends, prioritize product development initiatives, and strengthen competitive positioning within the evolving SWIR ecosystem.
Industry-Specific SWIR Deployment Analysis
Assessed demand for SWIR solutions across defense & military, semiconductor manufacturing, electronics & communication, automotive, healthcare, food & beverage, industrial automation, and scientific research sectors, including surveillance systems, quality inspection platforms, and advanced sensing applications.
Provides strategic insights into industry-specific adoption patterns, application requirements, and long-term revenue opportunities, supporting market expansion strategies and targeted investment decisions.
AI-Enabled Imaging & Advanced Sensing Opportunity Assessment
Evaluated adoption trends for AI-powered machine vision, automated defect detection, hyperspectral imaging, predictive maintenance systems, smart manufacturing platforms, and next-generation surveillance technologies utilizing SWIR imaging capabilities across global markets.
Supports innovation and investment strategies by identifying emerging application opportunities, accelerating technology roadmaps, and enabling data-driven decision-making in high-growth segments of the SWIR market.
Frequently Asked Questions About This Report
Some key players operating in the SWIR market include Teledyne FLIR LLC, Corning Incorporated, Collins Aerospace, Allied Vision Technologies GmbH, Leonardo DRS, Hamamatsu Photonics K.K., Fluke Corporation, New Imaging Technologies (NIT), Raptor Photonics, Lynred
Key factors that are driving the SWIR market growth include growing demand in industrial applications, and technological advancements.
The global shortwave infrared market size was valued at 670.0 million in 2025 and is expected to reach USD 746.3 million in 2026.
The global shortwave infrared market is expected to grow at a compound annual growth rate of 12.3% from 2026 to 2033 to reach USD 1,684.0 million by 2033.
North America dominated the shortwave infrared market with the largest revenue share of 40.5% in 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


