
- Home
- »
- Medical Devices
- »
-
Skincare Devices Market Size, Share Report, 2026-2033GVR Report cover

Skincare Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product, By Application (Diagnostic Devices, Treatment Devices,) By End-use (Hospitals, Clinics), By Region (North America, Europe, Asia Pacific), And Segment Forecasts
Market Size, 2025
$17.8BMarket Estimate, 2026
$19.5BMarket Forecast, 2033
$41.3BCAGR, 2026–2033
11.3%Skincare Devices Market Summary
The skincare devices market size was valued at USD 17.8 billion in 2025 and is projected to grow from USD 19.5 billion in 2026 to USD 41.3 billion by 2033, at a CAGR of 11.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 42.9% in 2025. The increasing prevalence of skin cancer and other skin diseases is contributing largely to the high demand for skincare devices.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Treatment devices segment led the market with the largest revenue share of 80.1% in 2025.
- By end use: Hospital segment led the market with the largest revenue share of 53.7% in 2025.
- By application: Treatment devices segment led the market with the largest revenue share in 2025.
Regional Highlights
- Largest regional market: North America (42.9% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 17.8 Billion
- Estimated market size in 2026: USD 19.5 Billion
- Projected market size by 2033: USD 41.3 Billion
- CAGR (2026-2033): 11.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Furthermore, factors such as the increasing awareness and interest of people about the aesthetic appeal coupled with technological advancements in skincare devices and a rise in disposable income are also increasing the adoption of these devices significantly. The prevalence of skin cancer such as melanoma and non-melanoma skin cancers is growing significantly. According to the American Cancer Society, melanoma skin cancer accounts for only 1% of total skin cancer cases, however, it is responsible for the highest number of cancer deaths. It further suggests that approximately 97,610 more people are expected to be diagnosed with melanomas in 2023. Meanwhile, the American Academy of Dermatology (AAD) estimated that 1 in 3 Americans visit dermatologists, and 1 in every 4 are diagnosed with skin disease every year. This increases the need for rapid and efficient diagnostics devices to facilitate early diagnosis and treatment.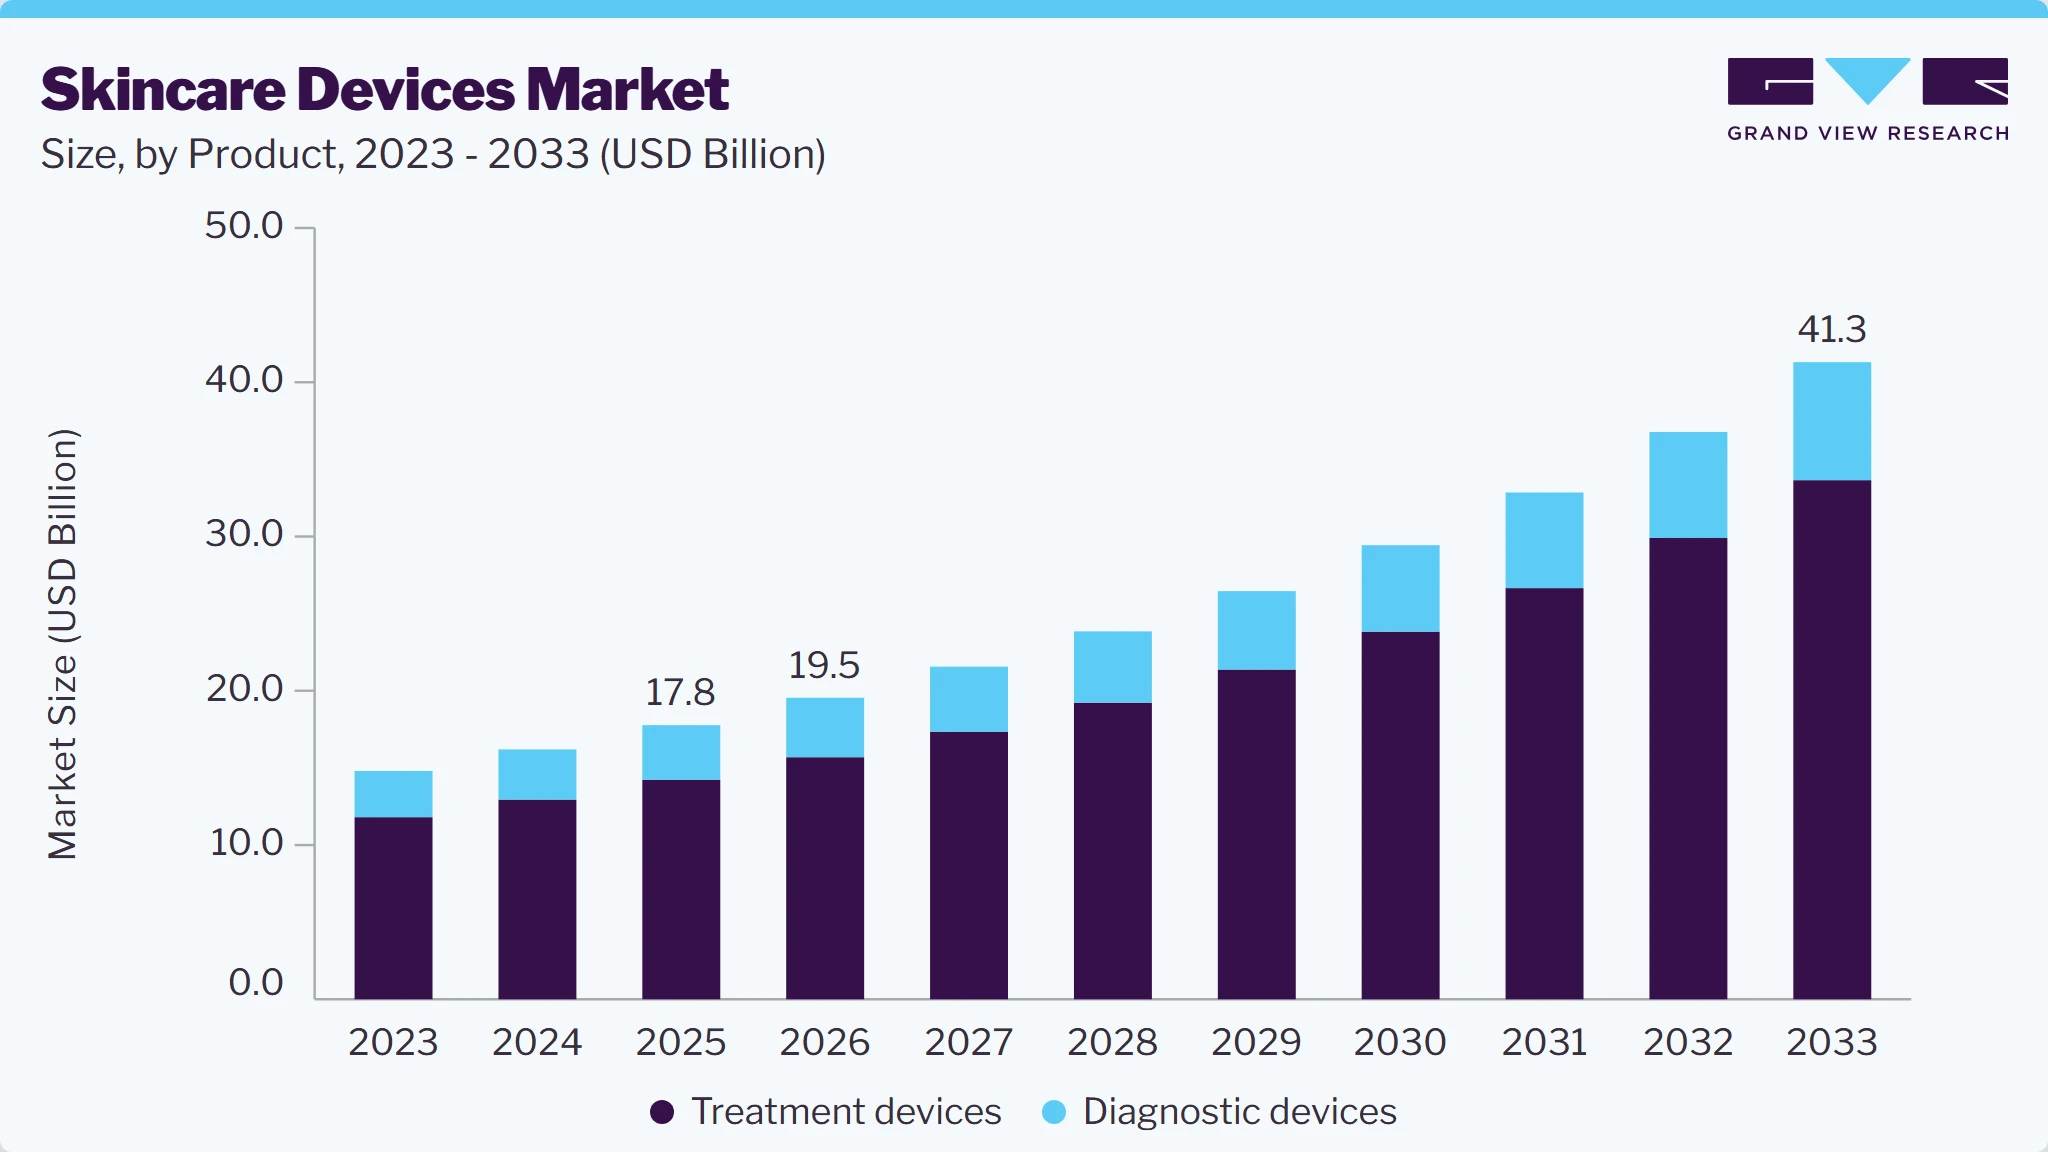 To learn more about this report, Download Free Sample Report
Another important driver for the skincare device market is the growing awareness regarding aesthetic appeals. In the present scenario, people from all age groups are interested in enhancing their aesthetic appeal, which can be facilitated through complete skin rejuvenation. This has led to the increasing use of technologically advanced products over conventional products that can assist in better diagnosis and treatment of skin diseases as well as improve one’s aesthetic appeal. Technological advancements in the field of skin care have also led to an increase in the market for skincare devices. People have gained confidence and started trusting such treatments. Improved laser therapy is one such advancement.
The COVID-19 pandemic significantly affected the market for skincare devices due to the lockdown and supply chain disruptions. Short-term negative growth was observed in the market due to the suspension of almost all non-COVID-19 related surgeries, limited operations of manufacturing, and disruption in the supply chain. With the successful rollout of vaccines in all regions, the volume of dermatological devices began to recover to its pre-pandemic levels. In 2021, the market witnessed high demand due to the backlog of surgeries from 2020 and increased interest from people related to dermatological procedures.
Market Dynamics
The skincare devices market is experiencing strong growth driven by the increasing emphasis on skin health, aesthetic enhancement, and preventive skincare across both clinical and consumer settings. The market is further supported by rising demand for non-invasive cosmetic procedures, growing prevalence of skin-related concerns, and continuous technological advancements in energy-based treatment platforms. Skincare device solutions enable dermatology clinics, aesthetic centers, medical spas, hospitals, and consumers to address a broad range of skin conditions and cosmetic concerns through targeted, technology-driven treatment approaches. These devices are widely utilized for skin rejuvenation, acne management, wrinkle reduction, skin tightening, pigmentation correction, hair removal, cellulite reduction, body contouring, and overall skin health optimization, providing effective alternatives to invasive cosmetic procedures. Modern skincare devices incorporate advanced technologies such as laser systems, intense pulsed light (IPL), radiofrequency (RF), ultrasound, LED light therapy, microcurrent stimulation, and microneedling platforms to deliver controlled and predictable therapeutic outcomes.
The growing preference for non-invasive and minimally invasive aesthetic procedures is a major factor driving the growth of the skincare devices market. According to the International Society of Aesthetic Plastic Surgery (ISAPS) Global Survey 2024, which reported more than 20.5 million non-surgical aesthetic procedures performed worldwide in 2024, contributing to a 42.5% increase in total aesthetic procedures over the last four years. Additionally, non-surgical skin tightening procedures ranked among the most commonly performed aesthetic treatments globally, underscoring the increasing demand for energy-based skincare technologies and non-invasive aesthetic solutions. Consumers are increasingly seeking cosmetic treatments that deliver visible skin rejuvenation, tightening, acne reduction, pigmentation correction, and anti-aging benefits without the risks, discomfort, scarring, or prolonged recovery periods associated with surgical interventions. This shift in consumer preference has accelerated the adoption of advanced skincare technologies such as laser systems, intense pulsed light (IPL) devices, radiofrequency (RF) platforms, ultrasound-based skin tightening systems, LED light therapy devices, and microneedling technologies across dermatology clinics, medical spas, and aesthetic centers.
The high cost associated with advanced skincare devices remains a significant restraint to the growth of the global skincare devices market. Professional-grade aesthetic platforms, including laser systems, radiofrequency (RF) devices, ultrasound-based skin tightening systems, intense pulsed light (IPL) equipment, and multifunctional skin rejuvenation workstations, often require substantial upfront capital investment, making them less accessible for small dermatology clinics, independent aesthetic practices, and emerging medical spas. In addition to acquisition costs, healthcare providers and aesthetic centers must incur ongoing expenses related to maintenance contracts, consumables, software upgrades, practitioner training, and regulatory compliance, further increasing the total cost of ownership. These financial barriers can delay equipment replacement cycles and limit the adoption of technologically advanced platforms, particularly in developing and price-sensitive markets.
Analyst Perspective
The global skincare devices market is driven by rising demand for non-invasive cosmetic procedures, increasing awareness of skin health, and continuous advancements in energy-based and digital skincare technologies. Growing concerns related to acne, wrinkles, hyperpigmentation, skin laxity, and photoaging are boosting the adoption of laser, IPL, radiofrequency (RF), ultrasound, LED light therapy, microcurrent, and microneedling devices across both professional and home-use settings. Additionally, the expansion of dermatology clinics, medical spas, and personalized skincare solutions is further supporting market growth by improving access to safe, effective, and minimally invasive treatments.
Product Insights
Based on product, the treatment devices segment led the market with the largest revenue share of 80.1% in 2025. The treatment devices segment accounted for the largest revenue share of 79.6% in 2025 and is expected to grow at the highest CAGR of 12.5% over the forecast period. This is mainly due to the availability of wide applications of dermatology treatment. In addition, the launch of novel technologies in the laser device category is also attributed to the significant growth of the segment.
Among the treatment devices, the laser devices segment held the largest revenue share of 24.2% in 2025 and is expected to grow with the fastest CAGR of 14.0% over the forecast period. The use of lasers to treat cosmetic skin conditions such as acne, scars, and wrinkles is the major reason for the growth of this segment. The government and worldwide bodies around the world are now working to improve awareness among people about various skin problems.
Application Insights
Based on application, the treatment devices segment led the market with the largest revenue share in 2025. The market is segmented into treatments such as hair removal, skin rejuvenation, wrinkle removal and skin resurfacing, acne, psoriasis, and tattoo removal, body contouring and fat removal, cellulite reduction, and vascular and pigmented lesion removal. The hair removal application segment dominated the market for skincare devices and held the largest revenue share of about 16.1% in 2025. Hair removal devices, particularly, laser devices have been proven to be safer for all skin tones and hair colors and facilitate less painful treatment procedures, thereby fostering market growth.
A rise in demand for cosmetic laser treatments like tattoo removal, skin resurfacing, and skin tightening has significantly increased the adoption of dermatology devices. According to the International Society of Aesthetic Plastic Surgery, treatments like non-invasive fat reduction witnessed a 21.1% increase, laser hair removal witnessed a 76.1% increase and Photo Rejuvenation saw a 32.3% increase in 2020 as compared to 2019. This indicates that the demand for aesthetic treatments is increasing and this will directly impact the adoption of technologically advanced and efficient dermatology devices
The launch of new and technologically advanced products is further expected to boost the growth of this segment. For instance, in June 2022, Cynosure launched the Elite iQ platform in the U.S., Europe, and Australia. It is designed with patented Skintel technology that offers customized laser hair removal and skin revitalization treatments. Such treatments can encourage new customers to opt for skincare treatments and boost the market share.
The skin rejuvenation segment is expected to grow at the fastest CAGR of 14.3 % over the forecast period. People are becoming more concerned about their looks; and thus, treatments related to face and skin to appear more youthful are on the rise. This factor is anticipated to contribute to the growth of the segment in the forthcoming years.
End-use Insights
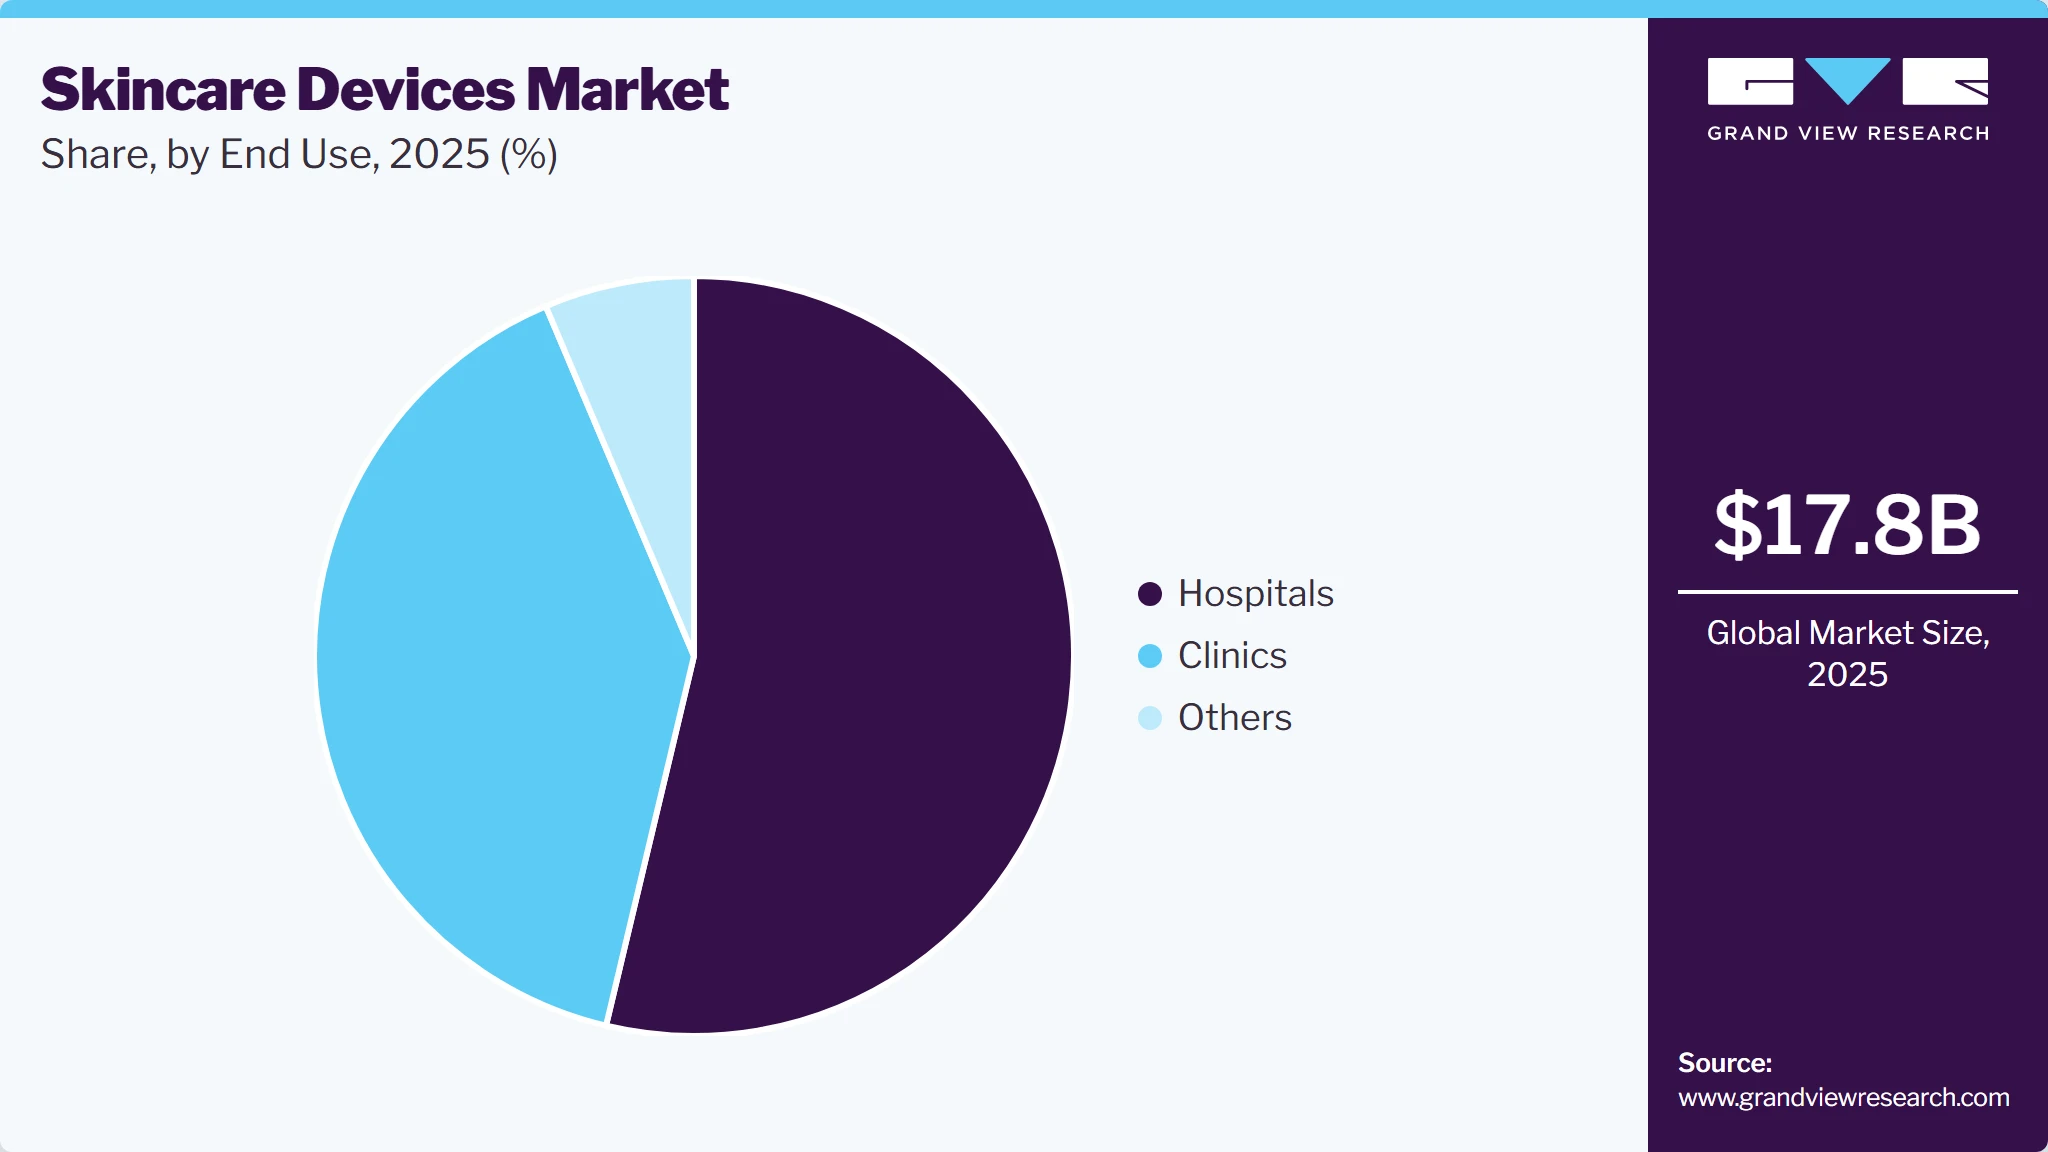
Based on end use, the hospital segment led the market with the largest revenue share of 53.7% in 2025. The hospital segment dominated the market and held the largest revenue of about 54.4% in 2025 owing to the presence of advanced skincare equipment in hospital settings. In addition, the availability of wide treatment options has also increased the number of visits for skin disease diagnosis and treatments in these facilities.
 To learn more about this report, Download Free Sample Report
The clinic segment is anticipated to grow at the fastest CAGR of 13.2% over the forecast period from 2025 to 2033 owing to the increased number of clinics offering dermatology services across countries. Another driver for the growth of this segment is the lower cost of treatments in clinics compared to hospitals, which has led to an increase in the number of patients visiting clinics.In dermatology clinics, both surgical and nonsurgical services are offered by certified plastic surgeons. According to TripleTree, as of 2020, there were 9,000 dermatology practices and 14,000 dermatologists in the U.S. Among the total number of practices, 34.0% were solo practices and 48.0% of practices included three or more physicians.
Regional Insights
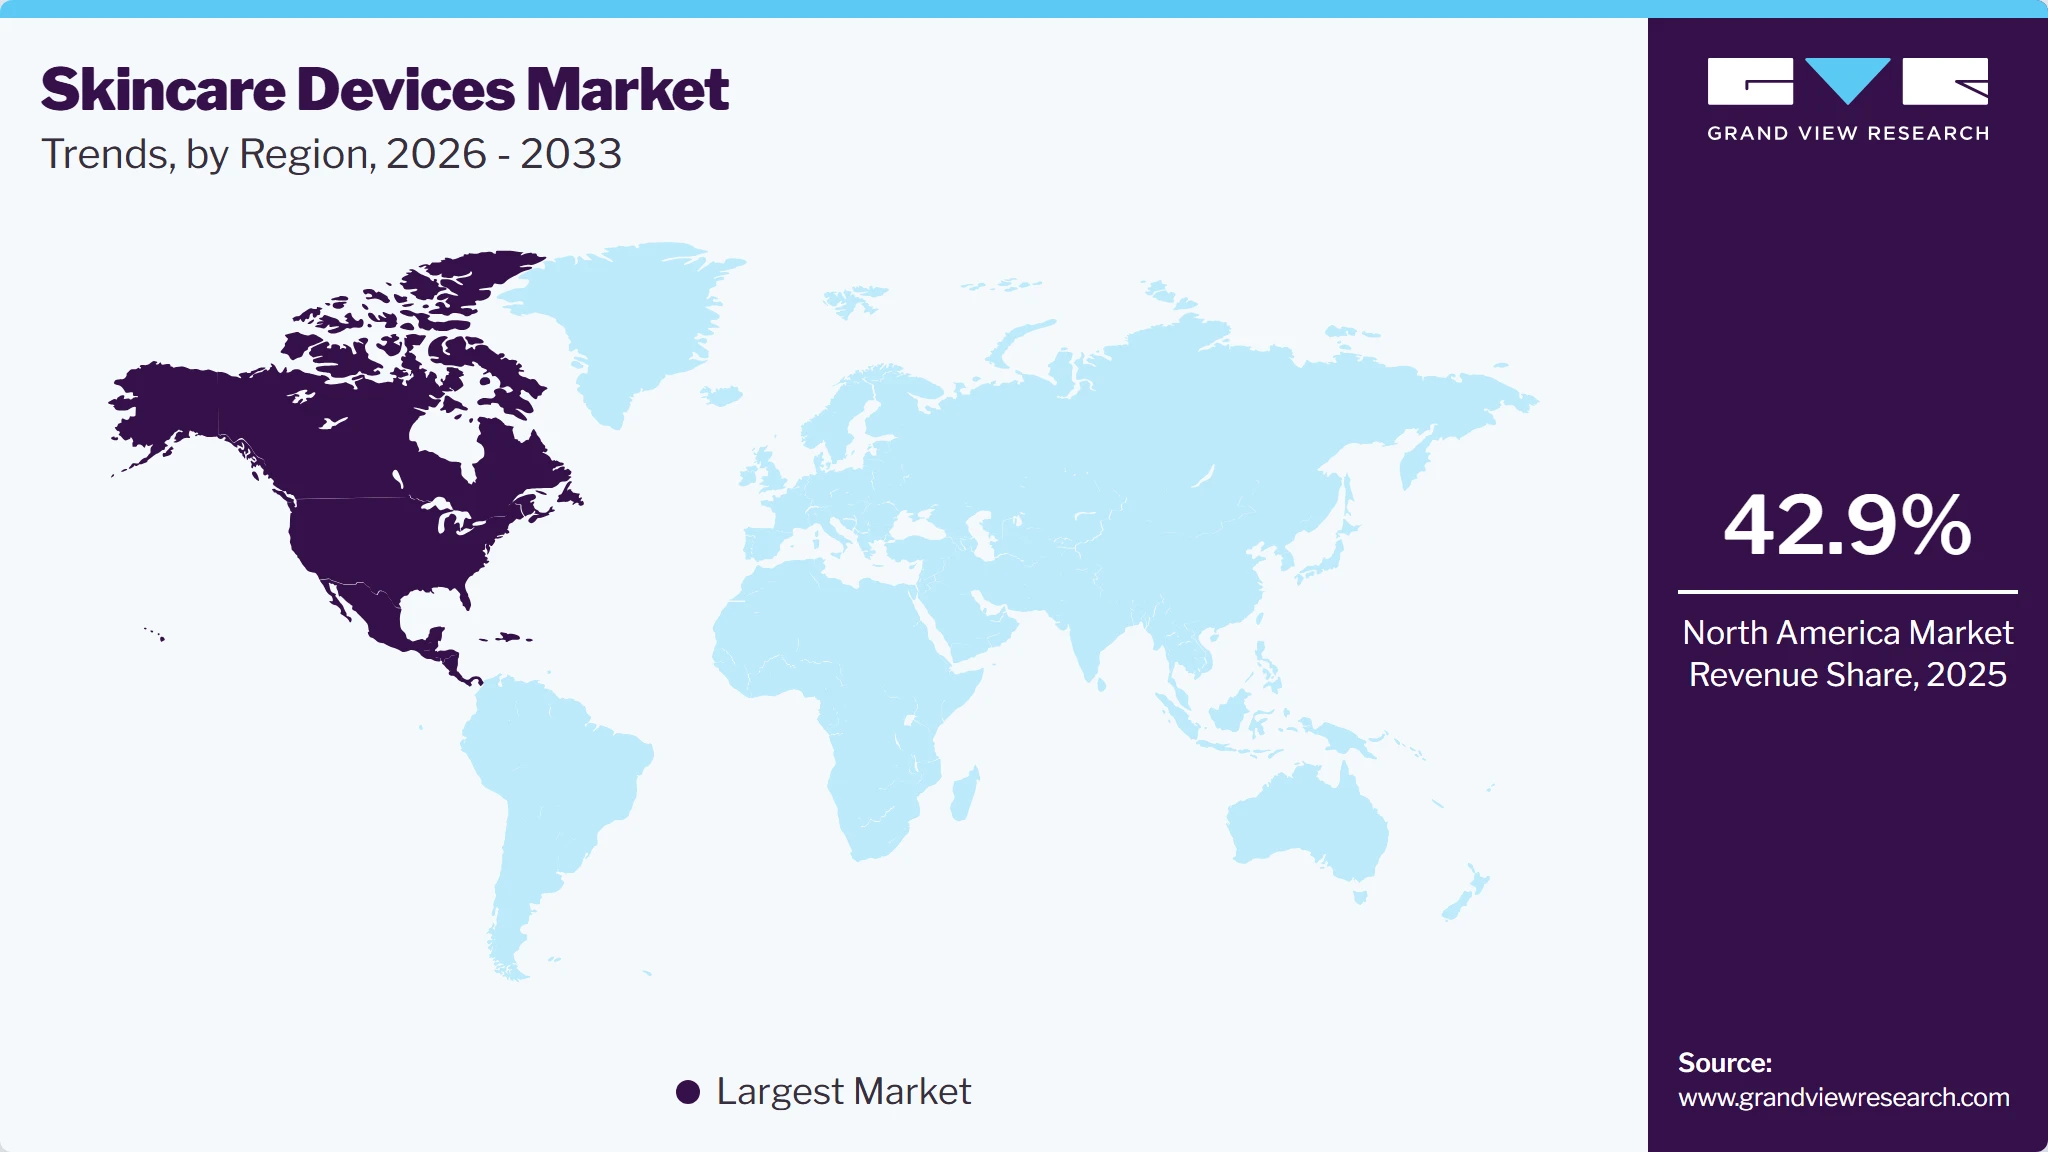
North America dominated the skincare devices market with the largest revenue share of 42.9% in 2025. The skincare devices market in the U.S. held the largest share in the North America region in 2025. The increasing prevalence of skin cancer and other skin diseases such as acne, rosacea, and eczema and the increasing adoption of different cosmetic procedures are some of the major factors contributing to the growth of the market in this region. According to the American Academy of Dermatology Association, acne is the most common skin condition in the U.S., affecting up to 50 million American citizens annually. Approximately 85% of people between the ages of 12 and 24 experience at least minor acne.
 To learn more about this report, Download Free Sample Report
Asia Pacific is expected to grow at the fastest CAGR of 14.3% during the forecast period from 2025 to 2033 owing to the growth of medical tourism in the region. Advancements in medical technologies and the availability of affordable treatment options are expected to be major factors driving the growth of this market.Moreover, rising beauty consciousness amongst men and women is anticipated to further drive the regional market.
Key Companies & Market Share Insights
The key companies in the market are concentrating on strategic initiatives such as mergers and acquisitions, new product development, and geographical expansions. In October 2022, Promoitalia, a cosmetic product company announced the launch of iWave, which is a one-of-a-kind, body microwave contouring device. The device has shown safe and effective results in the process of fat reduction.
In November 2021, Lancer Skincare the premier Beverly Hills-based international skincare brand teamed up with the tech startup ByondXR to launch The Virtual Lancer Dermatology Shop. Lancer Skincare's new virtual store will provide customers with the in-home benefits of a Lancer dermatology practice through a curated, digital experience that moves across the newly growing digitized world.
Key Skincare Devices Companies
The following key companies have been profiled for this study on the skincare devices market:
-
Alma Lasers GmbH
-
Cynosure, Inc.
-
Solta Medical, Inc.
-
Cutera, Inc.
-
Syneron Medical Ltd.
-
Canfield Scientific, Inc.
-
3Gen
-
Aesthetic Group
-
Ambicare Health
-
Image Derm, Inc.
-
Fotona
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Established Players (Alma Lasers GmbH, Cynosure, Inc., Solta Medical, Inc., Cutera, Inc., Syneron Medical Ltd.)
- These companies focus on continuous product innovation, regulatory approvals, physician training programs, strategic acquisitions, and geographic expansion to strengthen their positions across dermatology clinics, aesthetic centers, hospitals, and medical spas.
- Strong distribution networks and established customer relationships enable sustained revenue growth and market leadership.
- Established players benefit from strong brand equity, large installed device bases, extensive clinical validation, and broad global commercialization capabilities.
- Their investments in R&D, practitioner education, digital treatment ecosystems, and integrated aesthetic solutions support high customer retention and recurring revenue generation through consumables, maintenance services, and software-enabled treatment platforms.
Emerging Players (Aesthetic Group, Ambicare Health, Image Derm, Inc., Fotona)
- Emerging companies prioritize innovation in connected beauty devices, AI-enabled skin analysis, portable skincare technologies, and direct-to-consumer (DTC) business models.
- They focus on launching affordable, user-friendly, and multifunctional skincare devices that address growing consumer demand for at-home aesthetic treatments.
- Emerging players gain competitive advantages through rapid innovation cycles, digital-first marketing strategies, strong social media engagement, and agile product development.
- Their ability to quickly incorporate new technologies such as AI-driven personalization, app-connected skincare monitoring, and multifunctional treatment capabilities enables them to capture younger consumer demographics and rapidly growing home-use skincare segments.
Skincare Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 17.8 billion
Estimated market size in 2026
USD 19.5 billion
Projected market size by 2033
USD 41.3 billion
Growth rate
CAGR of 11.3% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait;
Key companies profiled
Alma Lasers GmbH; Cynosure, Inc.; Solta Medical, Inc.; Cutera, Inc.; Syneron Medical Ltd.; Canfield Scientific, Inc.; 3Gen; Aesthetic Group; Ambicare Health; Image Derm, Inc.; Fotona
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Skincare Devices Market Report Segmentation
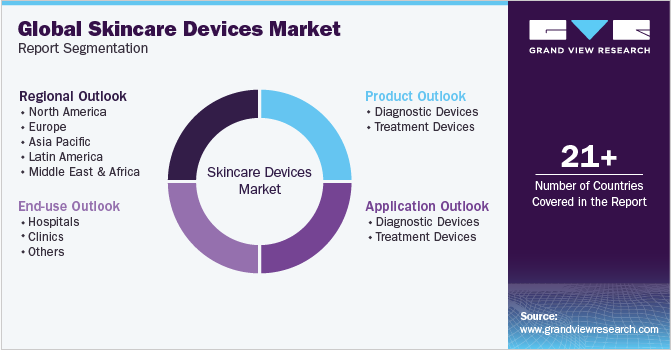
This report forecasts revenue growth at global, regional, and country levels and analyzes the latest industry trends in each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global skincare devices market report based on product, application, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Diagnostic Devices
-
Dermatoscopes
-
Microscopes
-
Other Imaging Devices
-
Biopsy Devices
-
-
Treatment Devices
-
Light Therapy Devices
-
Lasers
-
Electrosurgical Equipment
-
Liposuction Devices
-
Microdermabrasion Devices
-
Cryotherapy Devices
-
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Diagnostic Devices
-
Skin Cancer Diagnosis
-
Other
-
-
Treatment Devices
-
Hair Removal
-
Skin Rejuvenation
-
Acne, Psoriasis, and Tattoo Removal
-
Wrinkle Removal and Skin Resurfacing
-
Body Contouring and Fat Removal
-
Cellulite Reduction
-
Vascular and Pigmented Lesion Removal
-
Others
-
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Clinics
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Mexico
-
Argentina
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The skincare devices market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each skincare devices segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Dermatoscopes
Revenue is generated through the capital sale of handheld optical or digital dermoscopic visualization instruments equipped with specialized lens systems and polarized/non-polarized LED lighting assemblies. Manufacturers earn upfront revenue from hardware unit sales, alongside recurring purchases of high-volume consumables, including disposable contact caps, polarization plates, sanitizing lens covers, and smartphone/tablet mounting clips.
Microscopes
Revenue flows from the procurement of advanced optical and digital magnifying setups utilized for deep cellular skin analysis. This includes specialized capital equipment sales of benchtop laboratory microscopes and premium Confocal Laser Scanning Microscopes (CLSM) used for real-time, non-invasive optical biopsies of the epidermis and dermis.
Other Imaging Devices
Revenue is captured through the commercialization of macro-imaging platforms, multi-spectral facial scanners, high-frequency cutaneous ultrasound platforms, and 3D whole-body photography grids used for baseline skin mapping. Manufacturers derive capital income from the sale of these multi-modal diagnostic stations, alongside consistent recurring revenue from cloud storage expansion fees, facial analysis software updates, and proprietary artificial intelligence (AI)-driven skin anomaly screening tool licenses.
Biopsy Devices
Revenue is generated via a high-volume, highly predictable consumable-driven model centered on tools designed to harvest cutaneous tissue samples. Manufacturers capture steady revenue through the distribution of single-use, sterile disposable punch biopsy tools, shave biopsy blades, and specialized aspiration needles.
Light Therapy Devices
Revenue is derived from the distribution of non-laser phototherapy platforms, including Intense Pulsed Light (IPL) devices, Light Emitting Diode (LED) panels, and targeted ultraviolet (UVB/UVA) cabins. Equipment manufacturers capture upfront revenue from hardware placement, which is supported by a recurring downstream flow from finite-lifespan replacement lamps/bulbs, multi-wavelength optical filters, safety goggles, and targeted software treatment cards or activation codes.
Lasers
Revenue flows from the premium capital placement of solid-state, gas, or liquid aesthetic and medical laser towers. This high-value segment generates immense upfront cash injections from console sales, which are continuously supplemented over time by recurring revenues from optical fiber replacements, handpiece overhauls, cryogen cooling gas canisters, and comprehensive annual service contracts.
Electrosurgical Equipment
Revenue is captured through the sale of radiofrequency (RF) and high-frequency electrical current generator units designed for cutting, coagulation, and electrodesiccation of cutaneous lesions. Income is structured around a capital-and-consumable split: manufacturers profit from the initial generator console placement, while capturing high-margin, recurring revenue from single-use electrosurgical active electrodes, grounding pads, and smoke-evacuation filter kits.
Liposuction Devices
Revenue is generated through the commercialization of advanced fat-harvesting hardware assemblies, including power-assisted, ultrasound-assisted, and laser-assisted liposuction consoles. Medical device companies earn substantial capital revenues from core motor and vacuum pump unit installations, alongside rapid recurring revenue from single-use sterile cannulas, specialized infiltration lines, suction canister sets, and post-surgical compression accessories.
Microdermabrasion Devices
Revenue flows through the sale of mechanical exfoliating workstations that utilize diamond-tip wands or micro-crystal projection mechanisms to strip dead corneum cells. Manufacturers capture value through the base console sales, paired with a highly consistent stream of recurring consumables, including bulk crystal media canisters, replacement diamond tips, inline vacuum tubing filters, and disposal capture bags.
Cryotherapy Devices
Revenue is derived from the distribution of localized tissue-freezing systems, ranging from portable, multi-use nitrous oxide/liquid nitrogen canister guns to large-scale, automated cryosurgical consoles. Device suppliers capture income through initial hardware shipments, which are heavily supported by recurring revenue from multi-size spray tips, contact probes, and localized liquid gas tank refilling or cartridge replacement networks.
Segment - Application
Revenue capture definition
Skin Cancer Diagnosis
Revenue is captured by formulating and positioning highly precise diagnostic systems to detect malignant skin tumors, including basal cell carcinoma, squamous cell carcinoma, and melanoma. Value is driven by the clinical demand for high-accuracy early lesion mapping and margins definition, monetized through premium hardware tiers and AI-powered diagnostic software add-ons.
Other
Revenue encompasses diagnostic equipment utilized for non-cancer parameters, including monitoring chronic inflammatory diseases (psoriasis, eczema), evaluating hair follicle health (trichoscopy), assessing vascular structure integrity, and tracking cosmetic pigmentation progress.
Hair Removal
Revenue is heavily driven by high-throughput diode, alexandrite, and Nd:YAG laser systems deployed across high-frequency patient demographics. Income is sustained by continuous hardware utilization, translating directly into a predictable replacement velocity for finite-shot handpieces, sapphire cooling tips, and protective apparel consumables.
Skin Rejuvenation
Revenue flows from multi-functional energy devices, IPL systems, and light therapies configured to improve non-ablative skin texture, reduce pore size, and boost overall radiance. Volume is driven by consistent, year-round patient routines, generating steady recurring revenue for facilities through multi-session treatment cards and complementary topical product attachment sales.
Acne, Psoriasis, and Tattoo Removal
Revenue is generated through specialized clinical hardware, such as narrow-band UVB lamps for psoriasis, blue-light arrays for inflammatory acne, and high-peak-power picosecond/Q-switched lasers for breaking down tattoo ink. Income is secured by marketing highly targeted, indication-specific systems that require specialized handpieces or exact optical wavelengths.
Wrinkle Removal and Skin Resurfacing
Revenue is derived from aggressive, high-margin thermal-remodeling technologies designed to trigger a robust wound-healing response. Manufacturers capture value by charging premium device and tip pricing justified by the intensive, structural anti-aging results achieved per session.
Body Contouring and Fat Removal
Revenue streams develop from advanced fat-reduction technologies, including liposuction hardware and non-invasive fat-freezing or ultrasound devices. Manufacturers monetize this segment through large capital investments per machine and high-margin, single-use patient treatment liners, applicator gel pads, or specialized cannula sets required per procedure zone.
Cellulite Reduction
Revenue is captured through mechanical, thermal, or subcision-based treatment platforms configured to break down fibrous septae and smooth skin dimpling. Revenue is captured through hardware placement and recurring multi-session patient usage kits.
Vascular and Pigmented Lesion Removal
Revenue flows through precision laser wavelengths engineered to selectively target hemoglobin and melanin blocks. Income is captured via specialized small-spot handpieces and targeted cooling cryogen consumables.
Others
Revenue encompasses miscellaneous and niche therapeutic applications, including the removal of benign skin tags and warts, scar revision therapies, stretch mark treatments, and localized sweat gland ablation for hyperhidrosis.
Segment - End Use
Revenue capture definition
Hospital
Revenue is generated through institutional public or private healthcare tenders, corporate multi-site hospital network procurement structures, and rigid group purchasing organization (GPO) supply frameworks. Device manufacturers capture bulk revenue through the wholesale deployment of durable, multi-platform medical workstations, long-term multi-year enterprise service contracts, and steady volume commitments for diagnostic and surgical single-use accessories.
Clinics
Revenue is captured through specialized physician-exclusive accounts, private dermatology practice buying chains, and direct-to-clinic medical sales loops. Income is derived from premium, highly specialized clinical diagnostic lines and advanced treatment lasers backed by rigorous clinical data, regulatory clearances, and peer-reviewed safety records.
Others
Revenue is derived through alternative or emerging end-use channels, including commercial medical spas, franchise beauty clinic networks, cosmetic laser studios, and high-end aesthetic wellness resorts that procure user-friendly, high-throughput non-invasive treatment devices to optimize quick cash-pay consumer service cycles.
Estimation Model
Step
Guiding Question
Process Steps
Data Sources
Scope Definition
What is being studied?
1. Define skincare device product categories. 2. Segment the market by application. 3. Define end-user categories. 4. Establish geographic scope and sampling framework for forecast duration (2020-2030).
Primary research, dermatologists/cosmeticians, regulatory agencies, industry publications
Build the Product Base
How large is the skincare device market?
1. Analyze current skincare system expenditure and beauty technology adoption trends. 2. Estimate the addressable user base across professional and home-use skincare systems. 3. Evaluate product penetration by device type and end-user. 4. Calculate future adoption considering technological advancements, consumer preferences, and affordability.
Primary research, industry reports, distributor sales data, dermatologists, skincare professionals, beauty industry publications
Estimate Penetration
What is the adoption rate of advanced skincare technologies?
1. Quantify the shift from conventional skincare products toward device-based solutions. 2. Assess adoption rates of home-use skincare devices versus professional-grade systems. 3. Evaluate penetration of AI-enabled skin analysis and treatment systems. 4. Analyze distribution and capital trends influencing adoption rates across regions.
Primary research, dermatologists/cosmeticians, skincare professionals, company reports, beauty industry publications
Revenue Conversion
How does volume become revenue?
1. Collect average selling prices (ASPs) for professional and home-use skincare devices. 2. Segment revenues by product application, end-user, and region. 3. Forecast revenue streams from consumables, replacement components, and subscription models. 4. Benchmark revenue estimates with financial disclosures and company statements.
Primary research, industry publications, distributor sales data, dermatologists/cosmeticians, company financial statements
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape Analysis
Conducted a comprehensive competitive landscape assessment of the global skincare devices market, covering leading manufacturers of facial cleansing devices, anti-aging and skin rejuvenation systems, acne treatment devices, hair removal devices, LED light therapy platforms, radiofrequency (RF) skin tightening systems, microdermabrasion devices, and home-use aesthetic technologies. The study evaluated market positioning, product portfolios, pricing strategies, distribution networks, regulatory approvals, technological innovations, strategic partnerships, mergers & acquisitions, and geographic expansion initiatives. Additionally, the analysis tracked advancements in AI enabled skin analysis tools, connected skincare ecosystems, consumer engagement platforms, and emerging product differentiation strategies adopted by both professional and consumer-focused skincare device companies.
Enables stakeholders to understand the competitive dynamics, innovation trends, and strategic positioning of key participants within the global skincare devices market. The study supports informed decision-making regarding product development, channel expansion, partnership opportunities, portfolio optimization, and investment prioritization. It also helps manufacturers identify market gaps, benchmark technological capabilities, evaluate competitor commercialization strategies, and strengthen market presence across professional medical spas, beauty centers, and direct-to-consumer channels.
Parent Market Analysis
Conducted a detailed parent market assessment of the global skincare devices market within the broader skincare products market. The study evaluated the relationship between skincare devices and key dermatology device categories, including treatment systems, cryotherapy devices, laser-based devices, dermatoscopes, and skin imaging systems. The analysis examined the cross-functional adoption of skincare devices across clinical dermatology, aesthetic medicine, and consumer skincare applications. The study also assessed the impact of skincare product innovations, such as serums, creams, and cleansers, on the demand for skincare devices.
Enables stakeholders to gain a comprehensive understanding of how developments within the broader skincare products market influence skincare device adoption and innovation. The analysis supports decision-making by identifying synergistic growth opportunities, cross-category product development strategies, and potential collaborations between skincare product and device manufacturers. It also helps companies align their product portfolios with evolving consumer preferences and dermatological treatment trends.
Macroeconomic Analysis
Conducted a macroeconomic assessment of the global skincare devices market, analyzing factors such as GDP growth, disposable income, healthcare expenditure, consumer spending patterns, inflation rates, and supply chain dynamics across major regions. The study evaluated how macroeconomic conditions influence demand for skincare devices and affect market growth trajectories.
Enables stakeholders to assess the impact of macroeconomic risks affecting market growth, consumer spending patterns, and regional demand variations. The analysis supports strategic planning by helping manufacturers and investors anticipate market fluctuations, optimize pricing strategies, and allocate resources effectively across high-growth regions.
Frequently Asked Questions About This Report
Some of the key players of the skincare devices market include Alma Lasers GmbH; Cynosure, Inc.; Solta Medical, Inc.; Cutera, Inc.; Syneron Medical Ltd.; Canfield Scientific, Inc.; 3Gen; Aesthetic Group; Ambicare Health; and Image Derm, Inc.
The increasing prevalence of skin cancer and other skin diseases is contributing largely to the high demand for the dermatology devices market.
Drug development segment held the largest market share of 55.4% in 2025.
North America dominated the skincare devices market with a share of 42.9% in 2025. This is attributable to rising healthcare awareness coupled with advanced technologies and constant research and development initiatives.
Based on product, the treatment devices segment led the market with the largest revenue share of 80.1% in 2025.
Based on end use, the hospital segment led the market with the largest revenue share of 53.7% in 2025 and clinics is projected to register the fastest growth rate during the forecast period.
The global skincare devices market size was estimated at USD 17.8 billion in 2025 and is expected to reach USD 19.5 billion in 2026.
The global skincare devices market is expected to grow at a compound annual growth rate of 11.3% from 2026 to 2033 to reach USD 41.3 billion by 2033.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


