
- Home
- »
- Medical Devices
- »
-
Smart Healthcare Market Size, Share & Growth Report, 2033GVR Report cover

Smart Healthcare Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product Type (RFID Kanban Systems, RFID Smart Cabinets, Electronic Health Records, Telemedicine, mHealth, Smart Pills, Smart Syringes), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$257.4BMarket Estimate, 2026
$296.8BMarket Forecast, 2033
$667.1BCAGR, 2026–2033
12.3%Smart Healthcare Market Summary
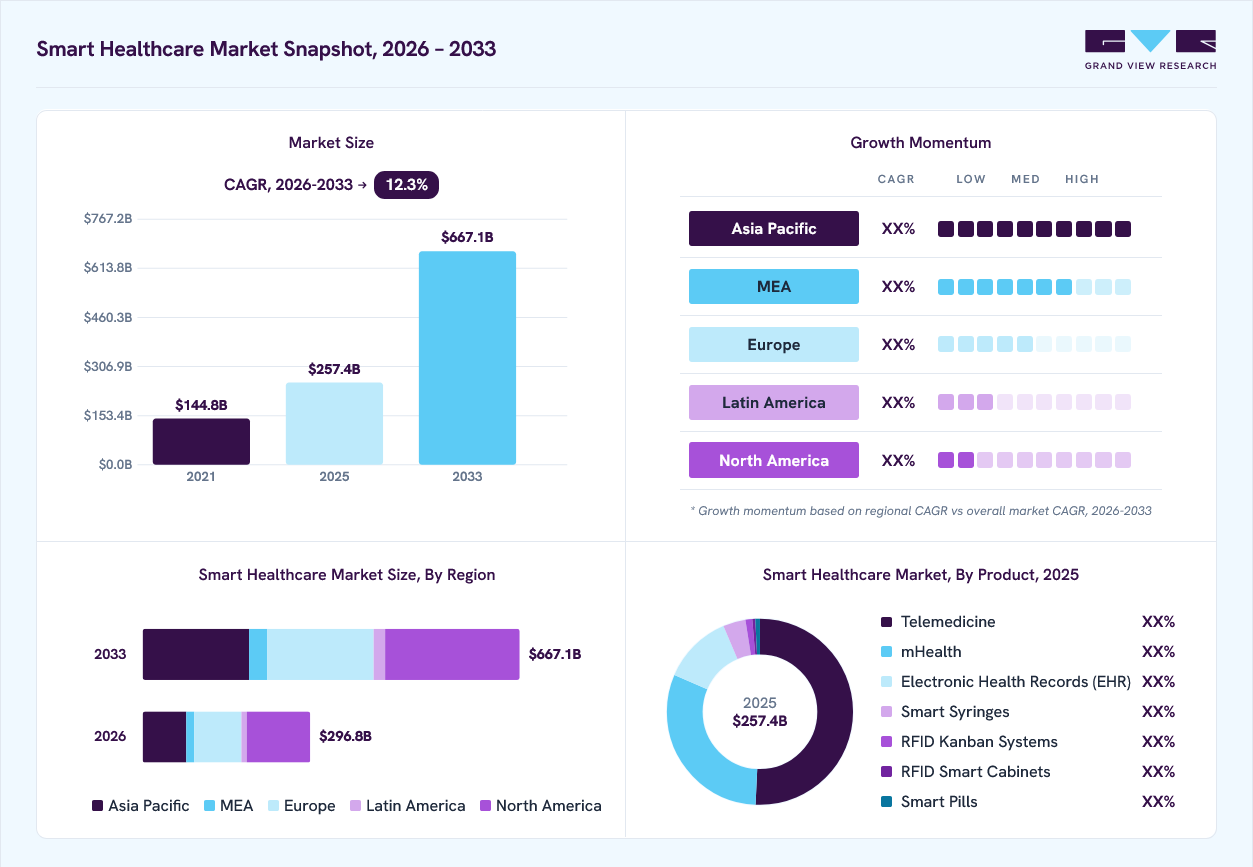
The global smart healthcare market size was valued at USD 257.4 billion in 2025 and is projected to grow from USD 296.8 billion in 2026 to USD 667.1 billion by 2033, at a CAGR of 12.3% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 34.7% in 2025. This growth is attributed to the technological advancements, rising healthcare costs, and the increasing demand for efficient, patient-centric care delivery.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Telemedicine segment held the largest revenue share of 50.7% in 2025.
- By end use: Hospitals held the largest revenue share of 44.5% in 2025.
Regional Highlights
- Largest regional market: North America (34.7% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 257.4 Billion
- Estimated market size in 2026: USD 296.8 Billion
- Projected market size by 2033: USD 667.1 Billion
- CAGR (2026-2033): 12.3%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Innovations across product categories, such as RFID Kanban systems and smart cabinets, are enhancing hospital inventory and supply chain management, reducing errors and wastage. Electronic Health Records (EHRs), especially web-based platforms, are seeing widespread adoption due to their scalability and interoperability, facilitating seamless data sharing and clinical decision-making. Moreover, rising internet penetration significantly drives the telemedicine segment. According to a 2023 report by DemandSage, approximately 82.2% of the U.S. population owned smartphones, which serve as key platforms for accessing mHealth applications. These devices accounted for 70% of the country’s digital media consumption time, highlighting their central role in everyday digital engagement.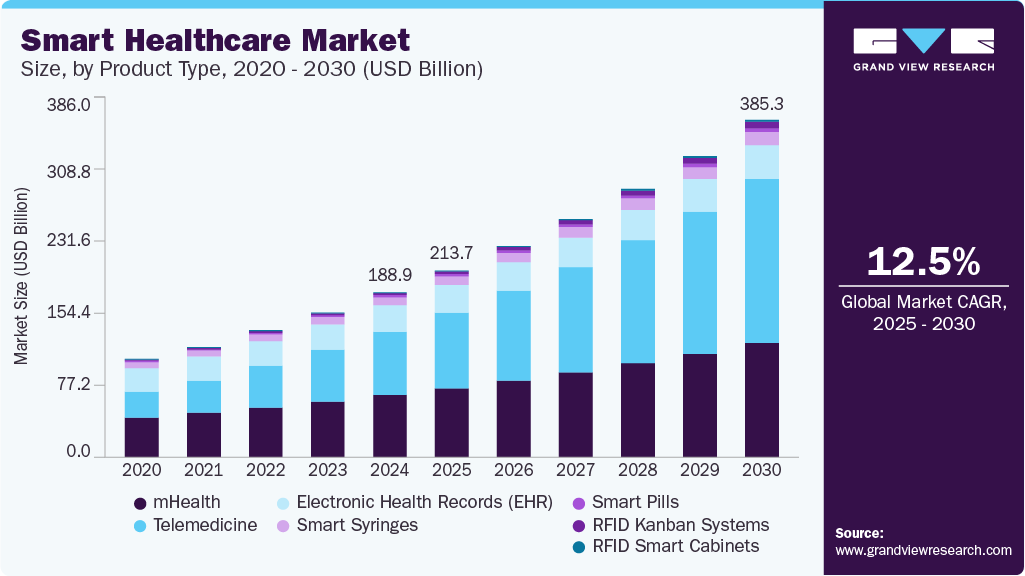 To learn more about this report, Download Free Sample Report
Advancements in telecommunications and integrated medical technologies, such as AI diagnostics, IoT-enabled wearables, and remote monitoring, are revolutionizing telemedicine. These innovations enhance real-time care, improve chronic disease management, and support proactive interventions. Cloud-based EMRs and AI-driven triage tools further streamline operations and improve patient outcomes, making telemedicine a scalable, cost-effective solution for rising healthcare demands. For instance, in May 2024, Apollo Telehealth, in partnership with the Government of Manipur, inaugurated a telemedicine-driven Primary Health Centre (PHC) in Borobeka. This initiative addresses the healthcare challenges faced by communities in conflict-affected and remote areas of Manipur.
Moreover, the demand for mHealth is rising as digital health services gain traction, particularly in remote patient monitoring. Increasing awareness among individuals about the benefits of mHealth solutions, along with supportive government initiatives promoting digital healthcare access, is expected to further accelerate market growth. Moreover, the growing use of smartphones across all age groups, especially among teenagers and adults, is playing a key role in expanding the reach of mHealth technologies. According to The Mobile Economy 2023 report, smartphone penetration stood at 76% in 2022 and is projected to rise to 92% by 2030, indicating a strong foundation for the continued adoption of mobile-based healthcare platforms.
Furthermore, supportive government programs are projected to bode well for the growth of the market for smart healthcare. For instance, the Ayushman Bharat Digital Mission in India aims to create an integrated digital health infrastructure, digitally linking practitioners and patients and promoting structured healthcare nationwide. In addition, the European Union's EU4Health program, launched in 2021, allocates USD 5.78 billion (Euro 5.1 billion) to strengthen healthcare systems and improve access to services. These programs demonstrate a global commitment to enhancing healthcare through digital transformation.
Rising participation from the market players is expected to drive the growth of the smart healthcare industry. For instance, in May 2025, MediBuddy, a digital healthcare platform in India, joined forces with Japanese electronics company ELECOM to bring cutting-edge smart health IoT devices to the Indian market. This strategic collaboration aligns with MediBuddy’s mission to provide quality healthcare access to a billion people by advancing innovation in preventive healthcare. In the initial rollout, ELECOM’s smart devices will be integrated into MediBuddy’s healthcare ecosystem, enhancing the reach and effectiveness of digital health solutions across the country.
“The partnership with MediBuddy is a crucial step towards realising our Healthcare Business Division’s vision of delivering medical and healthcare services. Lifestyle-related diseases have become a significant social issue in India, with experts emphasizing the importance of early prevention and management from a medical perspective. In this initiative, we plan to provide a system for seamlessly managing users’ health data, utilising our IoT technology, including Wi-Fi-enabled and Bluetooth-equipped weight and body composition scales.”
-Dr Kota Hada, CEO Healthcare Division, Elecom
Smart healthcare adoption increased during the pandemic situation, and this adoption rate is further projected to grow in the post-COVID-19 scenario. Consequently, many businesses are expanding their products and services; for instance, in November 2020, Vera Smart Health invested around USD 20 billion to expand its services into home-based tests and diagnostics, remote health services, medication delivery, virtual care, and nutrition consultation services. Therefore, substantial demand for smart healthcare products is anticipated due to the COVID-19 emergency.
Case Study: Total Sense implemented Stock Box Kanban RFID systems and Smart Cabinet in New York Presbyterian Hospital
Background
New York-Presbyterian Queens (a 519-bed hospital) implemented IDENTI Medical’s Total Sense Smart Cabinet and Stock Box Kanban RFID systems to automate and optimize inventory management for medical devices (like stents, catheters, and implants) and consumables in its interventional radiology unit.
Challenge
-
The hospital struggled with excess inventory, expired stock, and manual inventory management, leading to inefficiency, waste, and risk to patient safety.
-
Manual tracking made it difficult to know what was used, by whom, and when, complicating billing and regulatory compliance.
Solution
-
Total Sense Smart Cabinets: Secure, RFID-enabled cabinets that track high-value and time-sensitive items. Staff access items using RFID badges, and the system logs every removal/return automatically.
-
Stock Box Kanban System: RFID-enabled solution for consumables. When supplies reach a reorder point, the system triggers an automated replenishment request.
-
Integration: The IDENTIPlatform AI cloud software integrates inventory data with the hospital’s EHR/ERP systems, supporting automated billing and accurate patient records.
-
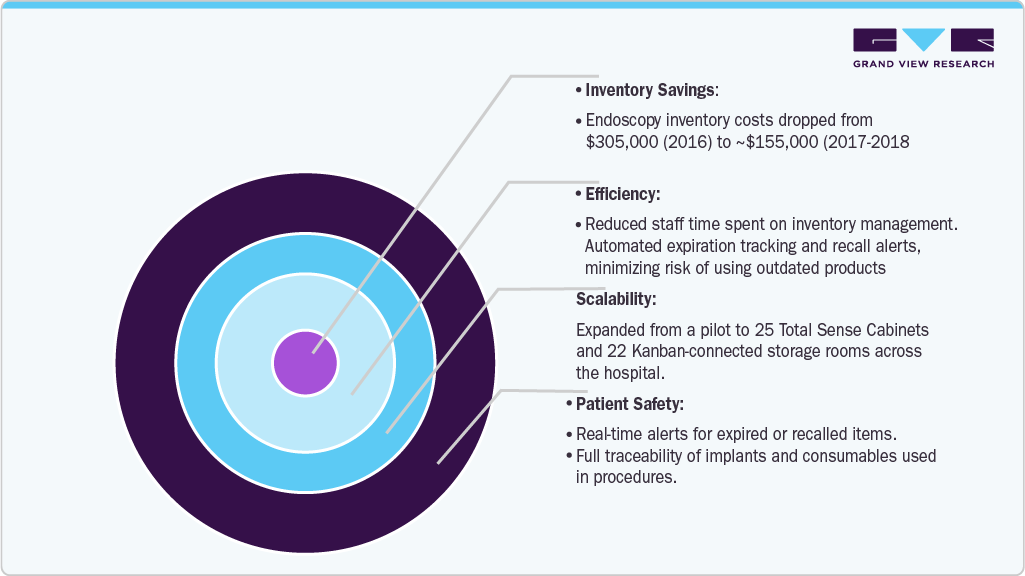
Results & Benefits: The hospital has deployed 25 Total Sense Cabinets to manage high-value inventory and track implants, while 22 core storage rooms are currently integrated with the Kanban system.
 To learn more about this report, Download Free Sample Report
Key Takeaways
-
Digital transformation of inventory management with RFID and AI.
-
Improved operational efficiency, cost savings, and patient safety.
-
Seamless integration with hospital EHR/ERP for accurate billing and traceability.
Market Dynamics
Government-led digital health initiatives and supportive regulatory frameworks are accelerating the adoption of smart healthcare technologies by promoting interoperable health systems, electronic health records (EHRs), telehealth, and secure health data exchange. These programs encourage investments in digital healthcare infrastructure, improve healthcare accessibility, and enable the integration of AI, IoMT, and cloud-based healthcare solutions, thereby driving the growth of the smart healthcare market. For instance,
• In June 2026, The Government of India launched Aarogya Setu 2.0 under the Ayushman Bharat Digital Mission (ABDM), integrating ABHA, personal health records, health insurance services, and digital hospital access into a single platform. The initiative aims to streamline healthcare delivery, improve patient access to digital health services, and reduce healthcare costs, supporting the widespread adoption of smart healthcare solutions.
• In March 2025, European Health Data Space (EHDS) Regulation (European Union): The EHDS Regulation entered into force, establishing a unified framework for the secure exchange and reuse of electronic health data across EU member states. The regulation promotes interoperable EHR systems, facilitates healthcare research and innovation, and accelerates the adoption of digital and smart healthcare technologies.
The high implementation and infrastructure costs associated with smart healthcare solutions are restraining market growth. Deploying advanced technologies such as AI-powered platforms, Internet of Medical Things (IoMT) devices, electronic health records (EHRs), cloud-based healthcare systems, and smart hospital infrastructure requires substantial capital investment in hardware, software, network connectivity, system integration, and staff training. In addition, ongoing expenses related to maintenance, cybersecurity, software upgrades, and regulatory compliance further increase the total cost of ownership. These financial barriers are particularly challenging for small and medium-sized healthcare providers and facilities in developing regions, limiting the widespread adoption of smart healthcare technologies.
The growing emphasis on strategic collaborations, partnerships, mergers, acquisitions, and investments among healthcare providers, technology companies, and medical device manufacturers presents significant growth opportunities for the smart healthcare market. These collaborations enable companies to integrate advanced technologies such as AI, IoMT, cloud computing, and remote patient monitoring into comprehensive digital healthcare ecosystems, expand their geographic presence, and accelerate product innovation.
As healthcare organizations increasingly seek interoperable and patient-centric solutions, strategic alliances are expected to create new revenue opportunities and support the long-term expansion of the smart healthcare market. For instance, in May 2025, MediBuddy partnered with ELECOM to introduce smart health IoT devices in India. Under this collaboration, ELECOM's connected healthcare devices are being integrated into MediBuddy's digital healthcare platform, enhancing access to preventive healthcare services and expanding the availability of smart healthcare solutions
“The partnership with MediBuddy is a crucial step towards realising our Healthcare Business Division’s vision of delivering medical and healthcare services. Lifestyle-related diseases have become a significant social issue in India, with experts emphasizing the importance of early prevention and management from a medical perspective. In this initiative, we plan to provide a system for seamlessly managing users’ health data, utilising our IoT technology, including Wi-Fi-enabled and Bluetooth-equipped weight and body composition scales.”
-Dr Kota Hada, CEO Healthcare Division, Elecom
Market Concentration & Characteristics
The smart healthcare market demonstrates a high degree of innovation, driven by advancements in telemedicine, EHR, and mHealth applications. Telemedicine providers are enhancing virtual care capabilities to improve patient-doctor interactions remotely. For instance, in October 2024, AMD Global Telemedicine collaborated with Carefluence, a provider of interoperability solutions, to strengthen AMD’s telehealth services and ensure seamless continuity of care. This collaboration improves clinical workflows and supports better patient outcomes, which are core objectives of the market.
“By incorporating their cutting-edge interoperability expertise, we are not just expanding our product offerings but significantly enhancing the capabilities of our existing solutions. This strategic partnership aligns with our commitment to innovation and excellence in telehealth, ensuring that our clients have access to the most advanced and effective tools available.”
- Tim Steffl, President of AMD Global Telemedicine
Mergers and acquisitions (M&A) continue to shape the smart healthcare industry dynamics, with companies adopting strategic partnerships to expand their market position. For instance, Google, Inc. bought Sound Life Science Services in October 2022. Sound Life Science Services is a small start-up from the University of Washington that created an app to monitor breathing. Google's acquisition has helped them enhance their application by integrating with Sound Life Science's breathing app.
 To learn more about this report, Download Free Sample Report
Regulations in the market significantly impact the adoption and growth of new technologies. Strict data privacy laws, such as the Health Insurance Portability and Accountability Act (HIPAA) in the U.S. and the General Data Protection Regulation (GDPR) in Europe, influence the design and deployment of healthcare technologies. For instance, compliance with HIPAA is crucial for telemedicine platforms, which must ensure patient data confidentiality. The high level of regulatory oversight encourages innovation in secure systems and creates barriers to entry for new players.
The global smart healthcare market is expanding rapidly, driven by its ability to enhance accessibility, reduce costs, and improve health outcomes. This momentum is being propelled by major industry players entering emerging markets and the rise of local startups. Companies are scaling their operations by setting up new facilities in different regions and pursuing mergers or acquisitions to strengthen their presence. For instance, Telefonica Tech’s acquisition of Incremental, a company specializing in digital transformation and data analytics, enabled both firms to broaden their capabilities and expand their Microsoft technology offerings across the UK.
Analyst Perspective
The smart healthcare market is transitioning from standalone digital health solutions to integrated, data-driven healthcare ecosystems that combine connected medical devices, healthcare IT platforms, and advanced analytics. Healthcare providers are increasingly prioritizing interoperability, workflow automation, and real-time clinical decision-making, driving demand for comprehensive solutions that seamlessly integrate telemedicine, electronic health records (EHRs), mHealth, and smart inventory management systems. As digital transformation becomes a strategic priority, vendors offering interoperable and scalable platforms are expected to gain a competitive advantage.
Product Type Insights
Based on product, the telemedicine segment held the largest revenue share of 50.7% in 2025,and this segment is expected to grow with the fastest CAGR over the forecast period. This growth is attributed to the increasing demand for remote healthcare services, especially post-pandemic. Key drivers include the need for convenient, accessible healthcare, growing adoption of digital health solutions, and advancements in communication technologies. Telemedicine enables virtual consultations, monitoring, and follow-ups, improving healthcare access for patients in remote areas. For instance, in March 2025, Airtel Business and Fortis Healthcare partnered to introduce a Smart Clinics solution powered by Airtel's 5G network, enhancing telemedicine access in urban and rural regions. The Smart Clinics initiative aims to transform telemedicine by offering real-time consultations, integrating connected medical devices, and ensuring secure health data management.
The RFID Kanban Systems segment is expected to grow at the fastest CAGR during the forecast period. This growth is driven by the need for real-time inventory tracking, reduction in stock-outs and overstocking, and improved medication expiration management. The increasing demand for lean inventory practices and enhanced operational efficiency continues to drive the adoption of RFID Kanban systems in healthcare settings. For instance, in August 2023, BlueBin and Avatek partnered to introduce an advanced Kanban system that integrates RFID and voice technology. This collaboration introduces enhanced automation and real-time inventory management capabilities, key benefits of RFID-enabled Kanban systems widely used in healthcare for efficient hospital inventory and supply chain management.
End-use Insights
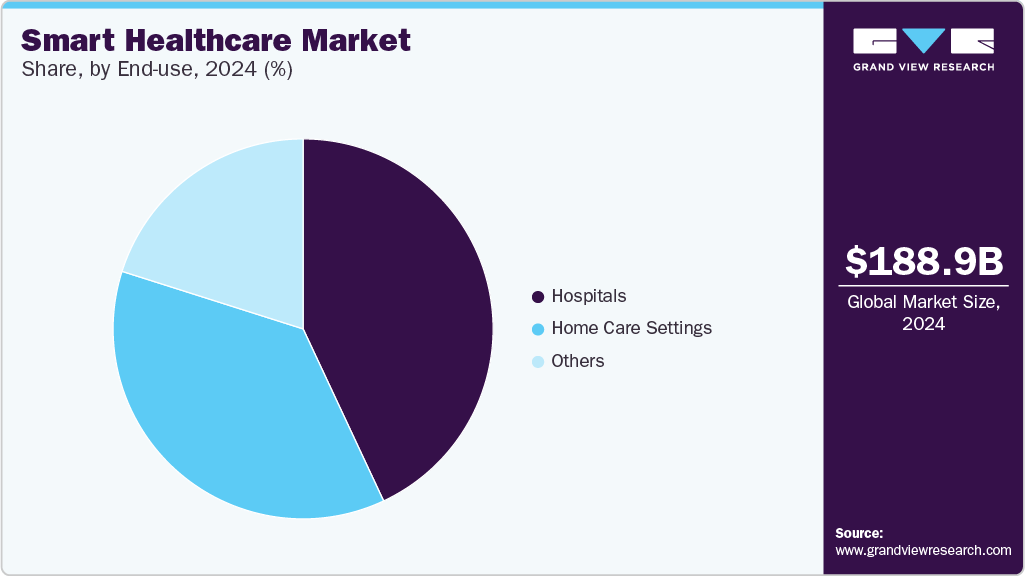
Based on end use, the hospitals held the largest revenue share of 44.5% in 2025, due to the increasing demand for advanced technologies to improve patient care, operational efficiency, and cost reduction. The healthcare industry is experiencing a digital transformation with advancements, enhancing patient care, hospital management, and security. According to an article published in March 2025, with 79% of healthcare organizations investing in rising cybersecurity threats, hospitals must embrace Smart Hospital technologies to remain resilient.
 To learn more about this report, Download Free Sample Report
Home care settings segment is expected to grow with the fastest CAGR over the forecast period, driven by an aging population, increased chronic disease prevalence, and a preference for in-home care. Technologies such as remote patient monitoring and telehealth services enable continuous care and early intervention, reducing hospital readmissions. Innovations enhance patient outcomes and alleviate healthcare system burdens, making home care a central focus in modern healthcare delivery.
Regional Insights
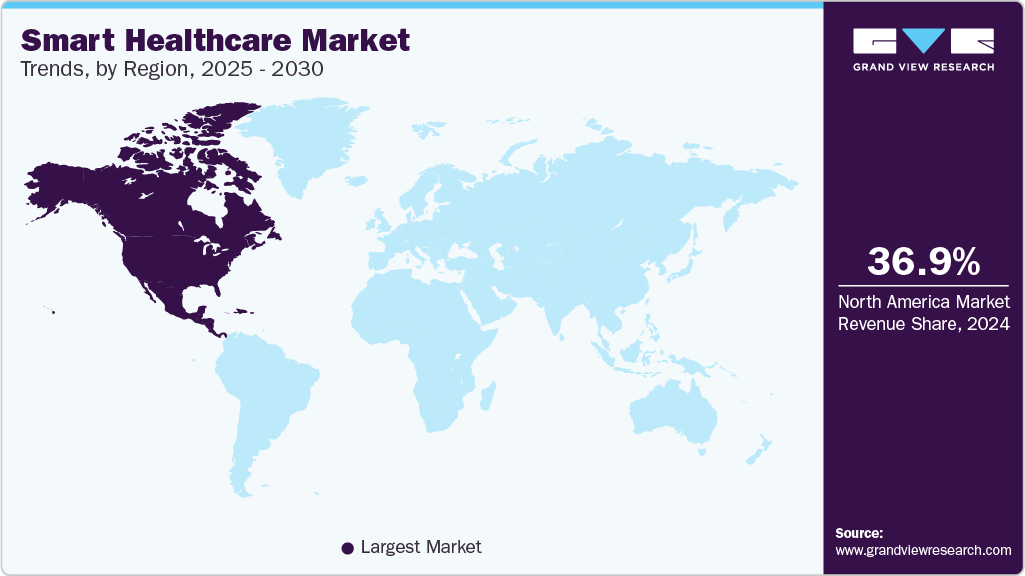
North America dominated the smart healthcare market with the largest revenue share of 34.7% in 2025. The market's growth can be attributed to favorable government policies supporting digital health deployment, accessible infrastructure, and high digital literacy. For instance, in November 2024, the Alliance for Smart Healthcare Excellence was formed to promote the development of smart hospitals by integrating advanced technologies and practices. As an independent nonprofit organization, the Alliance promotes adopting and utilizing advanced innovative healthcare technologies, processes, and practices specifically within hospitals.
 To learn more about this report, Download Free Sample Report
U.S. Smart Healthcare Market Trends
The smart healthcare market in the U.S. held the largest share in the North America region in 2025. The smart healthcare industry in the U.S. is characterized by rapid innovation and a focus on patient-centered care. The adoption of mobile health applications and the implementation of RFID systems for inventory management are notable trends. Regulatory support, such as the Health Information Technology for Economic and Clinical Health (HITECH) Act, has facilitated the widespread use of electronic health records (EHRs) and telehealth services.
Asia Pacific Smart Healthcare Market Trends
The Asia Pacific smart healthcare industry is growing due to technological advancements and rising demand for improved healthcare services. Expanding healthcare infrastructure and investments in health tech startups drove the market's growth. For instance, in December 2024, Mobile-health Network Solutions (MNDR) launched ManaSocial. This healthcare engagement platform allows users, professionals, and organizations to connect, share insights, and support one another on health-related topics. ManaSocial enhances MNDR's telemedicine platform by integrating telehealth services, enabling users to access remote consultations and healthcare support within a connected ecosystem.
“Through the platform’s Communities of Care feature, we are expanding our reach, unlocking new revenue streams, and meeting the evolving needs of healthcare consumers. This launch strengthens MNDR’s ability to deliver value to patients, providers, and shareholders.”
- Dr. Rachel Teoh, co-founder of MNDR.
The smart healthcare market in Japan is shaped by its comprehensive universal health insurance system, which ensures broad access to medical services through a mix of public and private providers. The system emphasizes patient choice, affordability, and regulated medical fees, supporting various healthcare services, including preventive care, chronic disease management, and specialized treatments. Hospitals and clinics are integrated within a highly organized regional and national network, with a significant focus on efficiency and quality of care.
Europe Smart Healthcare Market Trends
The smart healthcare industry in Europe is expected to grow significantly, owing to the technological innovations, introduction of Digital health solutions, such as EHRs and telemedicine, is becoming widespread under the EU's Digital Health Strategy. In April 2025, a new EU project “i2X project,” was launched to connect the health data of 3 million citizens, advancing data interoperability across the region. This project aligns with the EU's Digital Health Strategy, aiming to enhance healthcare delivery and facilitate clinical research by improving the seamless exchange of health information.
The smart healthcare market in the UK is growing, due to the strong push toward digital transformation within the National Health Service (NHS), rising demand for remote patient monitoring, and the government's focus on preventive healthcare. Increasing adoption of technologies such as Electronic Health Records (EHRs), telemedicine platforms, and mobile health (mHealth) apps is enhancing care delivery and patient engagement. The aging population and the growing burden of chronic diseases are also contributing to the need for connected healthcare solutions. Additionally, favorable regulatory support, significant investments in health tech startups, and collaborations between public and private stakeholders are accelerating innovation and deployment of smart healthcare technologies across the country.
Latin America Smart Healthcare Market Trends
The smart healthcare industry in Latin America is experiencing significant growth, driven by advancements in various technologies to enhance healthcare delivery and efficiency. Mobile health (mHealth) applications are being utilized to monitor patient health metrics, facilitate communication between patients and providers, and promote wellness. In addition, the introduction of smart pills and syringes enhances medication adherence and precision in drug delivery. These developments reflect Latin America's integration of innovative technologies into its healthcare system to meet the needs of its diverse population and improve overall healthcare outcomes.
Middle East & Africa Smart Healthcare Market Trends
The smart healthcare industry in the Middle East & Africa (MEA) is set for rapid growth, driven by increased healthcare spending and a focus on advanced technologies. Investment in health tech startups and innovative infrastructure is expanding, while regulatory frameworks evolve to support telemedicine and digital records. In October 2024, the launch of The Global Health Network's MENA Regional Hub aims to strengthen health research across the region. This initiative addresses region-specific public health challenges and promotes the integration of advanced technologies, including digital health tools, contributing to the growth of the innovative healthcare ecosystem in the MEA region.
Key Smart Healthcare Company Insights
Players undertook various strategic initiatives such as mergers and acquisitions, product launches and partnerships, and collaborations to gain more penetration. For instance, in September 2021, MSF introduced free telemedicine helpline for COVID-19 patients in India.
Key Smart Healthcare Companies
The following key companies have been profiled for this study on the smart healthcare market.
-
AirStrip Technologies Inc.
-
Veradigm LLC
-
Apple Inc.
-
AT&T Inc.
-
BROOKS AUTOMATION
-
Oracle (Cerner Corporation)
-
Cisco
-
GE Healthcare
-
Medtronic
-
Hurst Green Plastics Ltd.
-
IBM
-
Logi-Tag
-
McKesson Corporation
-
Olympus Corporation
-
Pepperl&Fuchs Pvt. Ltd.
-
SAMSUNG
-
Siemens Healthcare Private Limited
-
Solstice Medical LLC
-
InnerSpace (Acquired by Solaire Medical)
-
Böllhoff Group
-
Adolf Würth GmbH & Co. KG
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (GE HealthCare, Siemens Healthineers AG, Oracle etc.)
- Focus on continuous product innovation, strategic acquisitions, AI and IoMT integration, expansion of digital health ecosystems, long-term partnerships with healthcare providers, and global market expansion.
- Strong global presence, diversified product portfolios, extensive R&D capabilities, established customer base, regulatory expertise, and integrated healthcare solutions spanning software, medical devices, and connected care.
- High operating costs, complex legacy product portfolios, lengthy product development cycles, and slower adoption of disruptive technologies compared to smaller, agile competitors.
Emerging Players (Teladoc Health, Veradigm LL
. etc.)
- Focus on niche market expansion, cloud-based digital health platforms, remote patient monitoring, RFID-enabled healthcare automation, interoperability solutions, and strategic collaborations to strengthen market presence.
- Agility in innovation, specialized technology offerings, faster deployment of digital solutions, strong expertise in telehealth, healthcare IT, and smart inventory management.
- Limited product diversification, relatively smaller global footprint, dependence on strategic partnerships, and intense competition from established healthcare technology companies.
Recent Developments
-
In October 2024, AMD Global Telemedicine partnered with Carefluence, an innovator in interoperability solutions, to enhance AMD’s robust telehealth solutions, provide continuity of care, and enhance clinical outcomes.
-
In April 2024, MedStar Health, the hospital system based in Columbia, Maryland, announced its collaboration with the in-home care service DispatchHealth. This partnership aimed to deliver acute care services to individuals recently discharged from MedStar facilities in Washington, D.C.
-
In March 2024, RamSoft, a provider of cloud-based PACS /RIS radiology solutions, entered into a 5-year agreement with Premier Radiology Services to utilize RamSoft’s OmegaAI and PowerServer PACS platform across its network of more than 1,000 teleradiology locations.
-
In October 2023, Cedars-Sinai recently launched a mobile health application called Cedars-Sinai Connect app, which utilizes artificial intelligence technology to provide virtual care solutions for different clinical matters. This app enables patients to schedule primary care visits on the same day and offers 24/7 virtual access to medical specialists for urgent treatment.
-
In January 2023, Avery Dennison announced to launch of a new manufacturing unit in Mexico, which aims to expand the company’s production capacity in the country.
Smart Healthcare Market Report Scope
Report Attribute
Details
Market size in 2025
USD 257.4 billion
Estimated market size in 2026
USD 296.8 billion
Projected market size by 2033
USD 667.1 billion
Growth rate
CAGR of 12.3% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Norway, Denmark, Sweden, Japan, China, India, Australia, Thailand, South Korea, Brazil, Argentina, Saudi Arabia, South Africa, UAE, Kuwait
Key companies profiled
Oracle (Cerner), Epic Systems, Teladoc Health, Koninklijke Philips N.V, GE HealthCare, Siemens Healthineers AG, Medtronic, Becton, Dickinson and Company, Apple Inc., Cisco, McKesson Corporation, Veradigm LLC, Zebra Technologies, Olympus Corporation, Omnicell
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Smart Healthcare Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global smart healthcare market report based on product type, end-use, and region.
 To learn more about this report, Download Free Sample Report
-
Product Type Outlook (Revenue, USD Million, 2021 - 2033)
-
RFID Kanban Systems
-
RFID Smart Cabinets
-
Electronic Health Records (EHR)
-
Web-based EHR
-
Client-server Based EHR
-
-
Telemedicine
-
Hardware
-
Software
-
Others
-
-
mHealth
-
Monitoring Services
-
Diagnosis Services
-
Healthcare Systems Strengthening
-
Others
-
-
Smart Pills
-
Smart Syringes
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Home Care Settings
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
UAE
-
Kuwait
-
-
Research Methodology
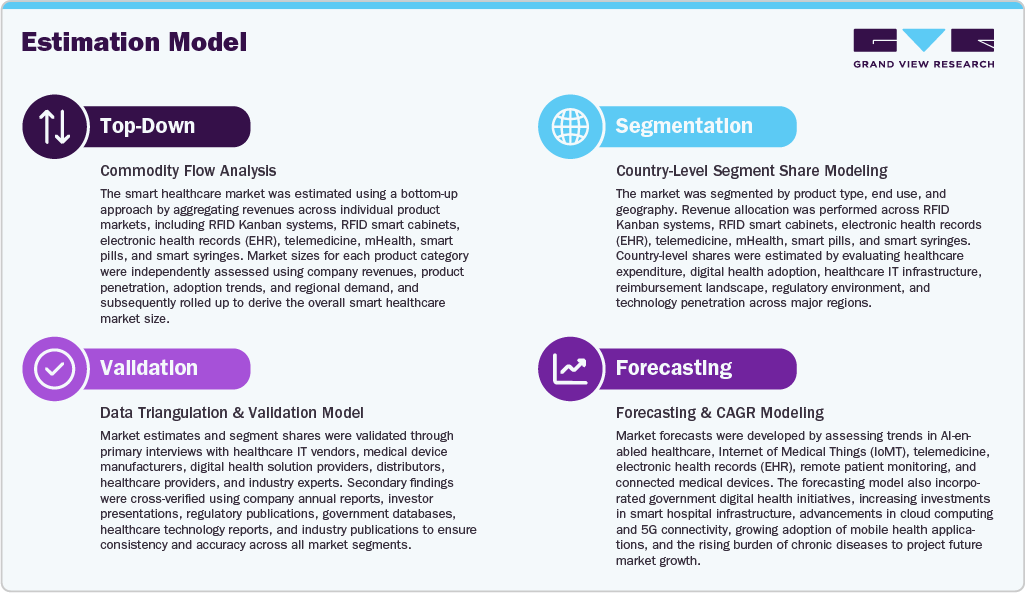
The smart healthcare market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each smart healthcare segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment- Product Type
Revenue Capture Definition
RFID Kanban Systems
Includes revenue derived from RFID-enabled Kanban systems, including RFID tags, readers, antennas, software platforms, and related implementation services used for automated inventory replenishment and supply chain management in healthcare facilities.
RFID Smart Cabinets
Comprises revenue earned through RFID-enabled smart storage cabinets, including hardware, inventory management software, RFID readers, and associated installation and maintenance services for tracking medical supplies and pharmaceuticals.
Electronic Health Records (EHR)
Covers revenue associated with EHR software licenses, subscriptions, implementation, integration, maintenance, upgrades, and support services for digital patient record management.
a) Web-based EHR” :Includes revenue from cloud-based or SaaS EHR platforms, including subscription fees, implementation, hosting, and technical support services.
b) Client-server Based EHR: Encompasses revenue from on-premise client-server EHR solutions, including software licensing, deployment, integration, maintenance, and support services.
Telemedicine
Consists of revenue derived from technologies and platforms enabling remote consultations, virtual care, remote patient monitoring, and digital communication between healthcare providers and patients.
a) Hardware: Includes sales of telemedicine hardware such as cameras, digital diagnostic devices, telemedicine carts, kiosks, remote monitoring devices, and communication equipment.
b) Software: Captures revenue from telemedicine software platforms, including virtual consultation applications, scheduling systems, workflow management software, remote patient monitoring platforms, and video conferencing solutions.
c) Others: Accounts for revenue from implementation, integration, training, maintenance, managed services, and connectivity solutions supporting telemedicine platforms.
mHealth
Represents revenue generated by mobile health applications and services delivered through smartphones, tablets, wearable devices, and connected digital health platforms.
a) Monitoring Services: Includes revenue from mobile solutions used for remote patient monitoring, chronic disease management, medication adherence, and wellness tracking.
b) Diagnosis Services: Comprises revenue derived from mobile applications supporting disease screening, symptom assessment, diagnostic assistance, and AI-enabled clinical decision support.
c) Healthcare Systems Strengthening: Captures revenue associated with mobile health solutions supporting healthcare workforce management, patient engagement, appointment scheduling, electronic data collection, and public health initiatives.
d) Others: Encompasses revenue from fitness and wellness applications, mental health platforms, health education, maternal and child health solutions, and other mobile health services.
Smart Pills
Includes revenue generated by ingestible electronic capsules and smart pill technologies used for capsule endoscopy, medication adherence monitoring, physiological sensing, drug delivery, and related software platforms.
Smart Syringes
Represents revenue earned from safety-engineered and connected smart syringes, including auto-disable syringes, active/passive safety syringes, RFID-enabled syringes, and digitally connected injection devices.
Segment- End Use
Revenue Capture Definition
Hospitals
Includes revenue generated from the adoption and use of smart healthcare solutions by public, private, specialty, and multispecialty hospitals for patient care, clinical workflow management, inventory management, remote monitoring, telemedicine, and digital health applications.
Home Care Settings
Comprises revenue derived from smart healthcare solutions deployed in home care environments, including remote patient monitoring devices, mHealth applications, telemedicine platforms, connected medical devices, smart medication management systems, and other home-based digital healthcare technologies.
Others
Represents revenue earned from the adoption of smart healthcare solutions across ambulatory surgical centers (ASCs), physician clinics, diagnostic laboratories, long-term care facilities, rehabilitation centers, nursing homes, pharmacies, academic and research institutions, and other healthcare settings.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Country-level digital health policy and smart healthcare adoption mapping
Evaluation of country-wise digital health initiatives, healthcare digitization programs, telemedicine regulations, EHR adoption policies, smart hospital initiatives, and funding support across key regions.
Enables identification of high-potential markets, policy-driven growth opportunities, and regulatory environments supporting the adoption of smart healthcare technologies.
Technology adoption analysis by healthcare facility type
Assessment of adoption rates for EHR, telemedicine, mHealth, RFID solutions, smart pills, and smart syringes across hospitals, home care settings, ambulatory surgical centers, clinics, and long-term care facilities.
Helps identify high-growth end-user segments and supports product commercialization and market expansion strategies.
Smart healthcare investment and funding landscape
Analysis of investments, strategic partnerships, mergers & acquisitions, and funding activities across digital health, telemedicine, AI-enabled healthcare, and connected medical devices by region and technology segment.
Provides insights into emerging innovation trends, competitive intensity, and future growth opportunities for investors and market participants.
Frequently Asked Questions About This Report
The global smart healthcare market size was valued at USD 257.4 billion in 2025 and is projected to grow from USD 296.8 billion in 2026.
Key factors that are driving the smart healthcare market growth include the rising adoption of mHealth, government initiatives to digitize healthcare, and the prevalence of chronic disorders.
Asia Pacific is the fastest-growing region over the forecast period.
The telemedicine segment held the largest revenue share of 50.7% in 2025
The hospitals held the largest revenue share of 44.5% in 2025.
North America dominated the market, accounting for a revenue share of 34.7% in 2025.
Some key players operating in the smart healthcare market include Oracle (Cerner), Epic Systems, Teladoc Health, Koninklijke Philips N.V, GE HealthCare, Siemens Healthineers AG, Medtronic, Becton, Dickinson and Company, Apple Inc., Cisco, McKesson Corporation, Veradigm LLC, Zebra Technologies, Olympus Corporation, Omnicell
The global smart healthcare market is expected to grow at a CAGR of 12.3% from 2026 to 2033, reaching USD 667.1 billion by 2033.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


