
- Home
- »
- Semiconductors
- »
-
Solid State Drive Market Size, Share & Trends Report, 2033GVR Report cover

Solid State Drive Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (External, Internal), By Storage (Under 120 GB, 120GB - 320GB, 320GB - 500GB, 500 GB To 1 TB, Above 2 TB), By Region, And Segment Forecasts
Market Size, 2025
$25.6BMarket Estimate, 2026
$29.9BMarket Forecast, 2033
$87.0BCAGR, 2026–2033
16.5%Solid State Drive Market Summary
The global solid state drive market was valued at USD 25.6 billion in 2025 and is projected to grow from USD 29.9 billion in 2026 to USD 87.0 billion in 2033, at a CAGR of 16.5% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of approximately 42.0% in 2025. Solid State Drives (SSDs), which have very high read/write speeds, are increasingly considered a suitable alternative to conventional hard disk drives (HDDs), which have moving parts and comparatively slower read and write speeds.
Key Market Trends & Insights
- By type: The internal SSD segment held the largest market share of around 70.0% in 2025.
- By storage: The 120 GB-320 GB segment held the largest market share of over 21.0% in 2025.
Regional HIghlights
- Largest regional market: North America (42.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 25.6 Billion
- Estimated market size in 2026: USD 29.9 Billion
- Projected market size by 2033: USD 87.0 Billion
- CAGR (2026-2033): 16.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The exponential growth in data generation and the increasing adoption of high-performance cloud computing have necessitated faster, more reliable data storage solutions. SSDs offer significant advantages over traditional hard disk drives in terms of power consumption and access times, making them ideal for data centers. As a result, the industry is expected to witness promising growth in the coming years.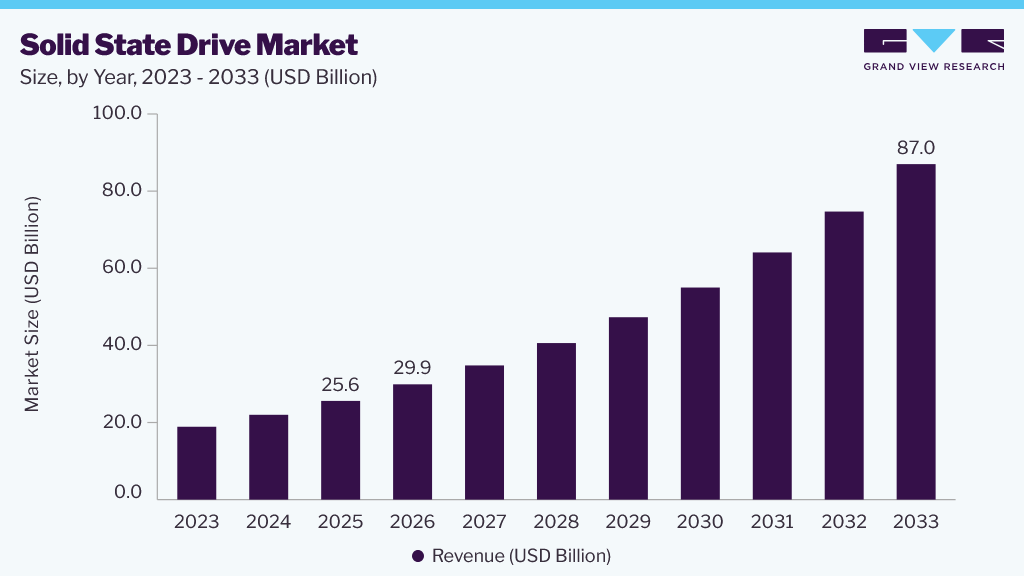 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The increasing demand for portable devices such as smartphones and laptops is fueling the growth of the market. SSDs are becoming a preferred storage solution for consumers due to their compact size, lower power consumption, and faster read and write speeds, thus enhancing user experience in mobile computing. Laptop manufacturers continue to expand SSD adoption across mainstream and budget product portfolios, while the growing availability of PCIe Gen5 SSDs is enabling significantly faster storage performance for consumer and enterprise devices.
The boot up time of SSDs is much lower than that of conventional hard disk drives, typically 10-20 seconds. Professionals working on high end software and gamers playing high resolution games prefer to install the required software on SSDs for faster response times. Addressing these needs, manufacturers are constantly innovating and developing new SSD technologies, such as 3D NAND flash and PCIe interfaces, which are increasingly replacing SATA-based SSDs in high-performance computing applications. These advancements offer increased storage capacity, faster data transfer rates, and lower latency, further propelling the SSD industry forward. In addition, the need for reliable data storage for backup and archiving purposes is fostering SSD adoption within enterprises.
Analyst Perspective
The global market for solid state drive (SSD) is experiencing robust growth, driven by the increasing need for efficient, high speed, and reliable storage systems across consumer electronics, enterprise computing, cloud computing, and artificial intelligence applications. Growing digitalization, rapid data generation, and the emergence of hyperscale data centers have led to increased adoption of advanced SSD technologies, such as PCIe Gen5 and 3D NAND Flash memory, to provide greater storage capacity, lower latency, and higher energy efficiency. Ongoing innovation in new products and manufacturers' investments in next generation SSDs further increase competition and drive market growth. But factors such as price fluctuations in NAND flash memory, the high cost of implementing enterprise SSDs, and supply chain issues may somewhat hinder market growth.
Type Insights
By type, the internal SSD segment held the largest market share, at around 70.0% in 2025. Internal SSDs are the preferred storage solution for various consumer electronics products, including laptops, desktops, and tablets. Their faster boot times, improved application responsiveness, and lower power consumption than traditional HDDs make them ideal for enhancing user experience. Furthermore, the ongoing development of PCIe NVMe technology and the growing demand for fast PCs, AI powered computers, gaming machines, and content production machines are prompting vendors to develop more sophisticated internal SSDs, thereby further boosting this market. For instance, in January 2024, Samsung Electronics announced the Samsung SSD 990 EVO, a new consumer internal NVMe SSD designed for gaming, business, and creative workflows. The SSD delivers improved performance, enhanced power efficiency, and compatibility with both PCIe 4.0 and PCIe 5.0 interfaces, strengthening the adoption of internal SSDs across laptops and desktop PCs.
The external SSDs segment is expected to witness significant growth during the forecast period. External SSDs provide additional storage capacity for laptops and desktops, facilitating the management of growing data volumes without costly internal hardware upgrades. Moreover, their portability makes them ideal for professionals working from remote workspaces, enabling them to carry critical data and applications of varying sizes. This caters to the growing mobile workforce and remote collaboration trend, aiding in promising segment expansion.
Storage Insights
By storage, the 120 GB-320 GB segment held the largest market share of over 21.0% in 2025. This is owing to an optimal balance between performance and affordability offered by this segment. They significantly improve speed and responsiveness compared to traditional HDDs at a price point that is increasingly accessible to budget-conscious consumers and businesses. The growing trend among students and working professionals to complete their assignments on their devices is expected to positively drive this segment's expansion. These devices can boot faster and simultaneously run multiple applications without lagging or slowing down. Furthermore, SSD storage in this range is suitable for various devices, including laptops, desktops, and ultrabooks. This versatility makes it a popular choice for manufacturers seeking to equip their products with fast storage solutions while remaining cost-competitive.
The 320 GB-500 GB segment is expected to register the fastest CAGR during the forecast period. While larger SSDs provide more storage, the 320 GB-500 GB segment offers a significant performance upgrade over traditional HDDs at an affordable price. It caters to a growing demand for data storage driven by the adoption of high-resolution media, complex software, and larger digital file sizes. Moreover, with optimal storage capacity, the segment addresses the needs of individual users and businesses, driving demand growth.
Regional Insights
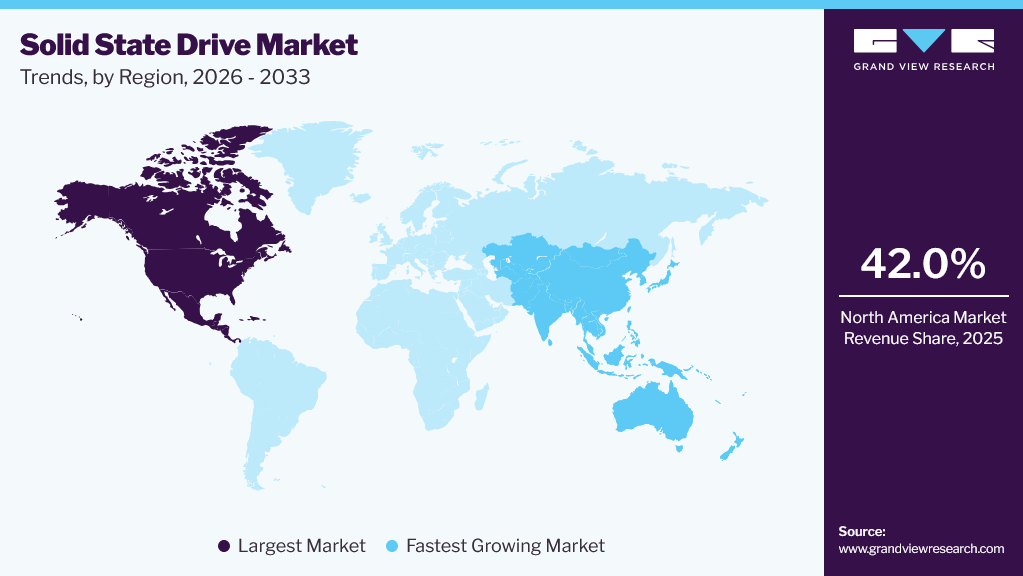
The North America solid state drive market dominated with a revenue share of approximately 42.0% in 2025. The region has a highly developed IT infrastructure and a large base of early adopters of advanced technologies. This region's reliance on data-intensive industries, such as finance, healthcare, and technology, has driven strong demand for high-performance storage solutions, including SSDs. In addition, increased utilization of AI infrastructure, cloud computing systems, and enterprise digital transformation efforts in the region has spurred demand for higher-capacity, high-performance SSDs. For instance, in July 2024, Micron Technology announced the Micron 9550 NVMe SSD, describing it as the world's fastest data center SSD. The PCIe Gen5 SSD is designed for AI, cloud, and enterprise workloads, delivering sequential read speeds of up to 14 GB/s and write speeds of up to 10 GB/s while improving power efficiency for modern data centers.
 To learn more about this report, Download Free Sample Report
U.S. Solid State Drive Market Trends
The U.S. solid state drive industry held the largest share of the regional market in 2025, owing to numerous multinational corporations and data centers in the country. These organizations require skilled employees to work on high end devices, which has fueled the adoption of SSDs in enterprise applications. In addition, high per capita income and strong consumer spending power have supported the demand for consumer oriented SSD products, such as those used in laptops, desktops, and gaming consoles, leading to market expansion in the country.
Europe Solid State Drive Market Trends
Europe solid state drive industry accounted for a notable market share in 2025. This is aided by the presence of a mature market for high end electronics in the region. Economic affluence among consumers drives the demand for performance oriented electronics. The significant advantages of speed and reliability offered by SSDs over HDDs perfectly cater to the requirements of consumers in this region. Moreover, the increasing demand for scalable storage infrastructure for artificial intelligence, cloud services, and enterprise-level computing has prompted vendors to manufacture solid-state drives with greater storage capacity and enhanced data processing features. For instance, in July 2025, KIOXIA announced the LC9 Series 122.88 TB NVMe SSD, developed for generative AI, hyperscale cloud, and data center applications. The SSD utilizes the company's BiCS FLASH 3D flash memory technology and is engineered to deliver ultra-high storage capacity while improving performance for AI-driven enterprise workloads.
The UK solid state drive industry accounted for a significant share of the regional market in 2025, driven by a surge in consumer demand for SSD compatible devices. With advancements in data storage technology, SSDs have become increasingly compact and can be installed in smaller devices for better data transfer rates. The rising demand for compact devices has driven SSD market expansion. A robust business environment in the country is responsible for driving the popularity of SSDs among organizations.
Asia Pacific Solid State Drive Market Trends
Asia Pacific solid state drive industry is expected to register the fastest CAGR over the forecast period. The presence of key semiconductor manufacturers and component suppliers in the region has contributed to a mature and efficient supply chain for SSD production. Moreover, the presence of a large IT workforce drives the heightened demand for SSDs. In addition, the region's strong manufacturing capabilities and skilled workforce have facilitated the production of high-quality SSDs at scale.
The solid state drive industry in India is driven by several factors such as the substantial surge in disposable income among the middle-class population. At the same time, there has been a sharp growth in the number of working professionals and students who prioritize seamless performance on their devices. This has led to an increased demand for personal computers and laptops for educational, professional, and personal uses. In addition, growing digital literacy and the shift of businesses from offline to cloud-based platforms have positively impacted sales of high-performance SSDs in the country.
Key Solid State Drive Market Company Insights
Leading SSD manufacturers are focusing on next-generation NAND technologies, PCIe Gen5 product launches, AI-optimized enterprise storage solutions, manufacturing expansion, and strategic partnerships to strengthen their competitive position.
Key Solid State Drive Companies
The following key companies have been profiled for this study on the solid state drive market:
-
ADATA Technology Co., Ltd.
-
Intel Corporation
-
Kingston Technology Corporation
-
Micron Technology, Inc.
-
Microsemi (Microchip Technology Inc.)
-
SAMSUNG
-
Seagate Technology LLC
-
SK HYNIX INC
-
Western Digital Corporation
-
Kioxia Corporation
Recent Developments
-
In April 2024, Micron Technology, Inc. announced that it had initiated the manufacturing of the world’s first 232 layered QLC NAND. The technology is being leveraged in the company’s Micron 2500 NMVe SSD, offering 28% greater compactness than competing technologies and a 24% improvement in read performance over the previous generation.
-
In March 2024, SK HYNIX announced it had developed PCB01, the 5th generation 8-channel PCIe SSD for on device AI computers. The SSDs are expected to deliver read and write speeds of 14 GB/s and 12 GB/s, respectively, and achieve up to 30% power efficiency over the preceding generation.
Solid State Drive Market Report Scope
Report Attribute
Details
Market size in 2025
USD 25.6 billion
Estimated market size in 2026
USD 29.9 billion
Projected market size by 2033
USD 87.0 billion
Growth rate
CAGR of 16.5% from 2026 to 2033
Base year for estimation
2025
Actual data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, storage, region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Singapore; Taiwan; South Korea; Brazil
Key companies profiled
ADATA Technology Co., Ltd.; Intel Corporation; Kingston Technology Corporation; Micron Technology, Inc.; Microsemi (Microchip Technology Inc.); SAMSUNG; Seagate Technology LLC; SK HYNIX INC.; Western Digital Corporation; Kioxia Corporation
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Solid State Drive Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global solid state drive market report based on type, storage, and region:
- Type Outlook (Revenue, USD Billion, 2021 - 2033)
- External
- Internal
- Storage Outlook (Revenue, USD Billion, 2021 - 2033)
- Under 120 GB
- 120GB-320GB
- 320GB-500GB
- 500GB-1TB
- 1TB-2TB
- Above 2TB
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- UK
- Germany
- France
- Italy
- Spain
- Asia Pacific
- Japan
- India
- China
- Singapore
- South Korea
- Taiwan
- Latin America
- Brazil
- Middle East & Africa
- North America
Frequently Asked Questions About This Report
The global solid state drive market is expected to grow at a CAGR of 16.5% from 2026 to 2033, reaching USD 87.0 billion.
The global solid state drive market size was valued at USD 25.6 billion in 2025 and is estimated at USD 29.9 billion for 2026.
North America dominated with an approximately 42.0% revenue share in 2025.
Key players in the market include ADATA Technology Co., Ltd.; Intel Corporation; Kingston Technology Corporation; Micron Technology, Inc.; Microsemi (Microchip Technology Inc.); SAMSUNG; Seagate Technology LLC; SK HYNIX INC.; Western Digital Corporation; Kioxia Corporation, and others.
The internal SSD solid state drive segment accounted for the largest revenue share of around 70.0% in 2025.
About the Author(s)
Semiconductors Research Team
Semiconductors & Electronics · SemiconductorsThis report was authored by the semiconductors research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the semiconductors segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


