
- Home
- »
- Homecare & Decor
- »
-
Student Accommodation Market Size Report, 2026-2033GVR Report cover

Student Accommodation Market (2026 - 2033)
Size, Share & Trends Analysis Report By Accommodation Type (Purpose-Built Student Accommodation, University-Managed Accommodation), By Education Grade, By Occupancy Type, By Location, By Region, And Segment Forecasts
Market Size, 2025
$12.4BMarket Estimate, 2026
$13.0BMarket Forecast, 2033
$19.1BCAGR, 2026–2033
5.7%Student Accommodation Market Summary
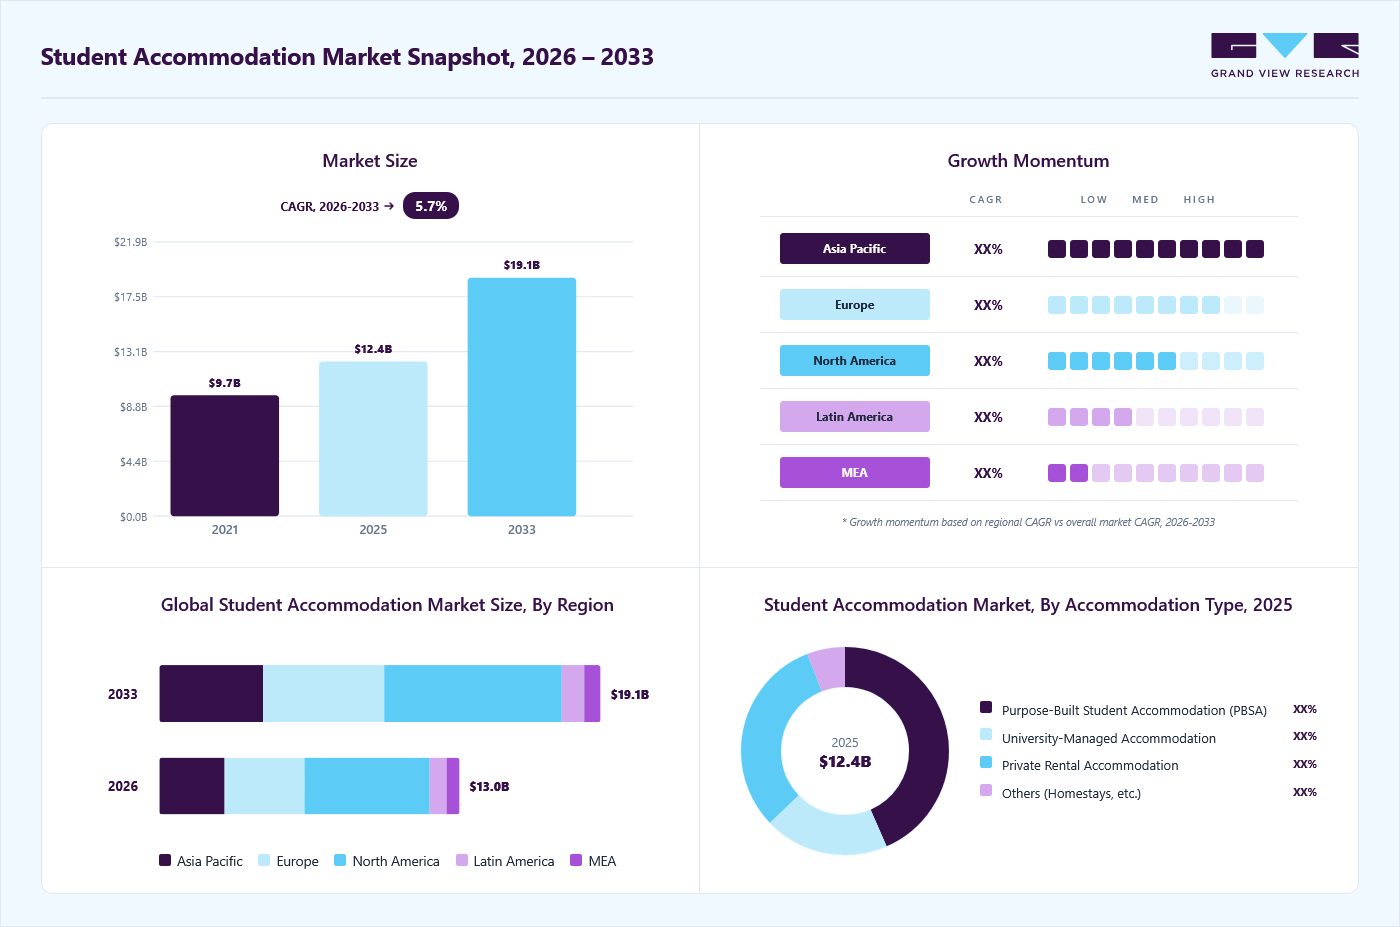
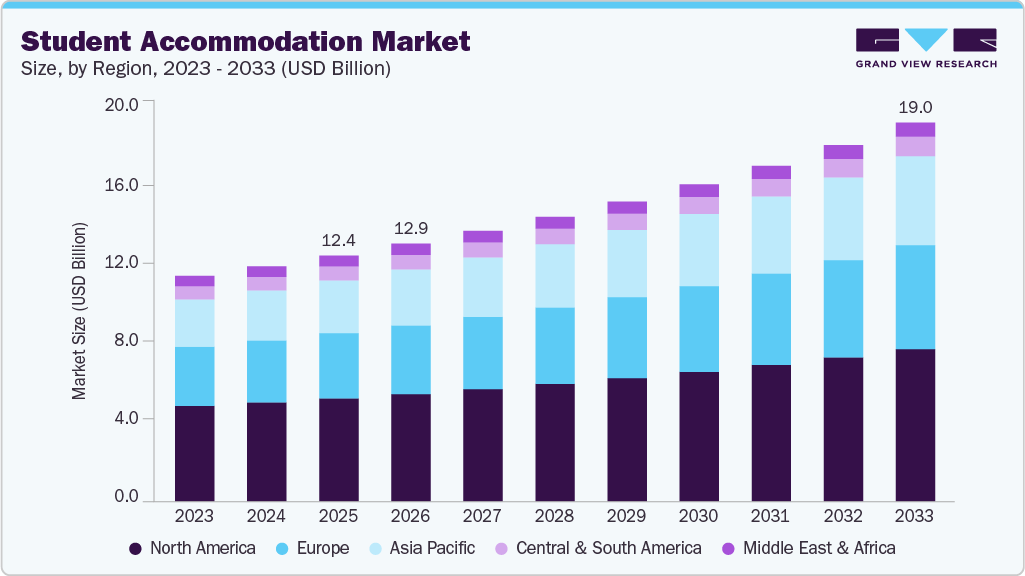
The global student accommodation market size was valued at USD 12.4 billion in 2025 and is projected to grow from USD 13.0 billion in 2026 to USD 19.1 billion by 2033, at a CAGR of 5.7% from 2026 to 2033. The market in North America dominated with a revenue share of 41.9% in 2025. The continuous rise in the global student population, particularly international students, is a significant driver of growth for the market.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By accommodation type: Purpose-built student accommodation (PBSA) segment held the largest market share of 43.4% in 2025.
- By location: Off-campus segment held the largest market share of 72.1% in 2025.
- By occupancy type: Double segment held the largest market share of 45.3% in 2025.
- By education grade: Undergraduate students segment held the largest market share of 61.5% in 2025.
Regional Highlights
- Largest regional market: North America (41.9% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 12.4 Billion
- Estimated market size in 2026: USD 13.0 Billion
- Projected market size by 2033: USD 19.1 Billion
- CAGR (2026-2033): 5.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
With more students pursuing higher education abroad, the demand for quality, safe, and convenient housing has surged. Countries such as the U.S., the UK, Australia, and Canada remain top destinations for international students, leading to increased pressure on existing accommodation infrastructure. Universities, while expanding their intake, are often unable to meet the housing demands of the growing student population, thereby creating opportunities for private developers and investors to step in with PBSA. This trend is expected to continue as the pursuit of global education becomes increasingly popular, fueled by the expanding middle class in developing countries and the growing importance of obtaining international qualifications.The growing number of internationally mobile students remains a key driver of the global Purpose-Built Student Accommodation (PBSA) market. According to the Open Doors 2025 Report by the Institute of International Education, U.S. colleges and universities hosted 1,177,766 international students in the 2024-2025 academic year, a 5% increase from the previous year and one of the highest enrollment levels on record. International students now account for around 6% of total U.S. higher education enrollment, highlighting sustained global demand for overseas education.
 To learn more about this report, Download Free Sample Report
Globally, student mobility is also expanding rapidly. Recent education mobility estimates show that approximately 6.9 million students studied outside their home countries in 2024, the highest level ever recorded, with projections suggesting the number could exceed 10 million by 2030.
In addition, in 2025, UNESCO reported that worldwide higher education participation reached 264 million students, reflecting substantial expansion in tertiary education systems and reinforcing long-term demand for student housing across major study destinations such as the U.S., UK, Canada, Australia, France, and Germany.
Government policies and support play a crucial role in driving market growth. Many governments, particularly in developed countries, actively promote their educational institutions to attract international students, thereby indirectly boosting demand for student housing. In addition, in some regions, governments offer incentives to private developers to invest in student housing and related properties, such as tax breaks or subsidies, to help meet the housing demand. Urban planning policies also increasingly incorporate provisions for student housing, recognizing its importance in supporting the educational infrastructure. This supportive regulatory environment encourages investment and development in the sector, ensuring that student accommodation keeps pace with the growing demand.
The integration of technology into student accommodation is emerging as a strong growth driver, catering to the tech-savvy student population. Smart living features, such as automated climate control, keyless entry, high-speed internet, and digital communication platforms, are becoming standard in modern student housing. These technological advancements not only enhance the living experience but also address safety, security, and convenience concerns, which are top priorities for students and their families. In addition, the use of data analytics and property management software allows for more efficient operations and maintenance, further attracting both students and investors to the market. As students increasingly seek accommodation that meets their digital lifestyle needs, demand for technologically advanced living spaces continues to grow, fueling market expansion.
The evolving preferences and lifestyle changes among students are significantly influencing market growth. Today’s students are increasingly seeking out housing options that offer more than just a place to sleep; they desire spaces that support their academic, social, and personal development. This shift has led to a greater demand for accommodation that offers a balanced mix of private and communal spaces, fostering a sense of community while preserving individual privacy. Amenities such as fitness centers, study lounges, social event spaces, and sustainable living features are becoming crucial determinants of students' housing choices. The preference for high-quality, experience-oriented living environments is driving developers and property managers to innovate and upgrade their offerings, thereby accelerating market growth.
Market Dynamics
The student accommodation market is witnessing steady growth due to rising higher education enrollment, increasing international student mobility, and growing demand for safe, convenient, and well-equipped living spaces. Students are increasingly seeking accommodation options that offer modern amenities such as high-speed internet, study areas, fitness centers, security services, communal spaces, and flexible leasing arrangements. Purpose-built student accommodation (PBSA) providers are expanding their offerings to enhance the student living experience through technology-enabled services and community-focused environments. In addition, rapid urbanization and the concentration of universities in major cities are increasing demand for both on-campus and off-campus housing solutions. The growing participation of institutional investors in student housing, attracted by stable occupancy rates and recurring rental income, is further supporting market expansion.
The increasing number of students pursuing higher education, particularly in countries with established academic institutions, is a major factor driving demand for student accommodation. Growing participation in expanding access to universities and rising cross-border student mobility have created sustained demand for both on-campus and off-campus housing facilities. International students often require accommodation solutions that offer convenience, security, furnished living spaces, and proximity to educational institutions, making purpose-built student accommodation (PBSA) an increasingly attractive option.
The continued growth of global student mobility is further strengthening market expansion. The number of internationally mobile students has increased significantly over the past decade as students seek quality education, global exposure, and better career opportunities. Major study destinations such as the U.S., the UK, Australia, Canada, and Germany continue to attract large volumes of domestic and international students, increasing pressure on existing housing infrastructure. Furthermore, growing urbanization and the expansion of higher education institutions in emerging economies are contributing to rising student migration within countries. As student populations continue to grow globally, the need for safe, professionally managed, and amenity-rich accommodation is expected to remain a key driver of the student accommodation market.
The rising cost of student accommodation, particularly in major university cities, remains a significant restraint for market growth. Purpose-built student accommodation (PBSA) and privately managed housing facilities often offer premium amenities such as furnished rooms, high-speed internet, fitness centers, security services, and communal spaces, resulting in higher rental rates compared to traditional housing options. For many students, especially those from low- and middle-income households, these costs can create financial barriers and limit access to professionally managed accommodation.
The challenge is particularly evident in popular education destinations where strong student demand, limited housing supply, and increasing real estate costs continue to drive rental prices upward. International students, who often face additional expenses related to tuition, travel, and living costs, may be especially affected by rising accommodation fees. Furthermore, inflationary pressures, higher utility costs, and increasing property maintenance expenses have prompted accommodation providers to raise rents in several markets. As affordability becomes a growing concern among students and their families, many opt for shared housing, private rentals, or longer commuting distances to reduce living expenses. These cost-related challenges may constrain occupancy growth in premium accommodation facilities and limit the expansion of the student accommodation market in price-sensitive regions.
The expanding demand for purpose-built student accommodation (PBSA) presents a significant growth opportunity for the student accommodation market. Students are increasingly seeking housing options that offer a combination of convenience, safety, academic support, and lifestyle amenities. Modern PBSA developments are designed specifically for student needs, incorporating features such as furnished rooms, high-speed internet, study lounges, co-working spaces, fitness centers, recreational facilities, and round-the-clock security. As universities continue to experience enrolment growth and international student inflows, demand for professionally managed accommodation is expected to rise substantially.
The growing adoption of smart building technologies is further enhancing the attractiveness of student housing. Accommodation providers are increasingly integrating digital access systems, mobile applications for resident services, online booking platforms, smart energy management systems, and community engagement tools to improve the student living experience. In addition, institutional investors and real estate developers are expanding investments in PBSA assets due to their relatively stable occupancy rates and recurring rental income potential. These trends are expected to support the expansion of modern student accommodation facilities and create long-term growth opportunities for market participants.
Analyst Perspective
The student accommodation market benefits from durable demand drivers, including rising global university enrollment, increasing international student mobility, and persistent housing shortages in major education hubs. The strongest competitive advantage will belong to operators that move beyond providing beds and create integrated living ecosystems combining accommodation, community engagement, digital services, wellness amenities, and academic support. As institutional capital continues to enter the sector, providers capable of maintaining high occupancy, premium pricing, and scalable operations across multiple university markets are expected to capture the greatest long-term value.
Consumer Insights
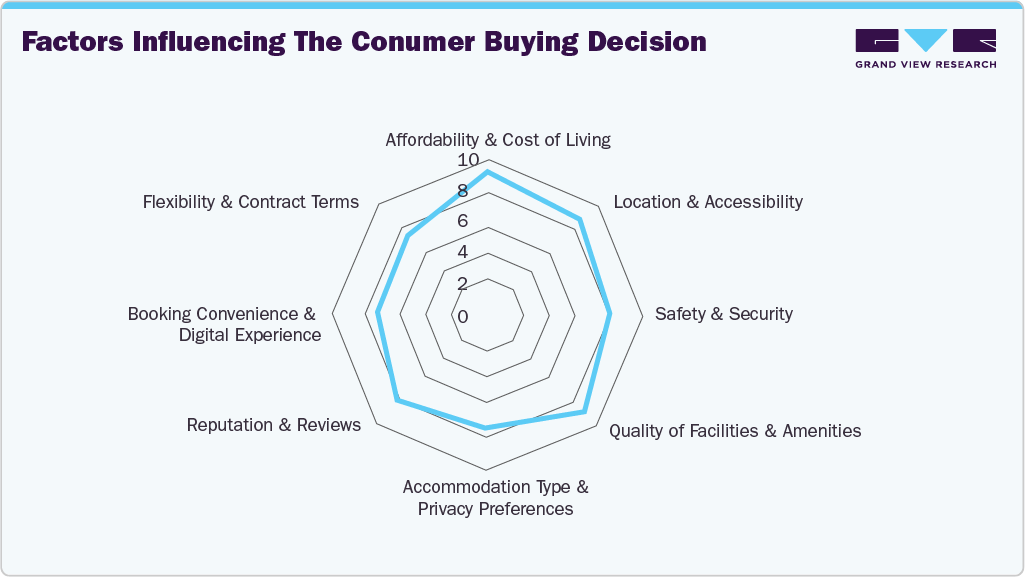
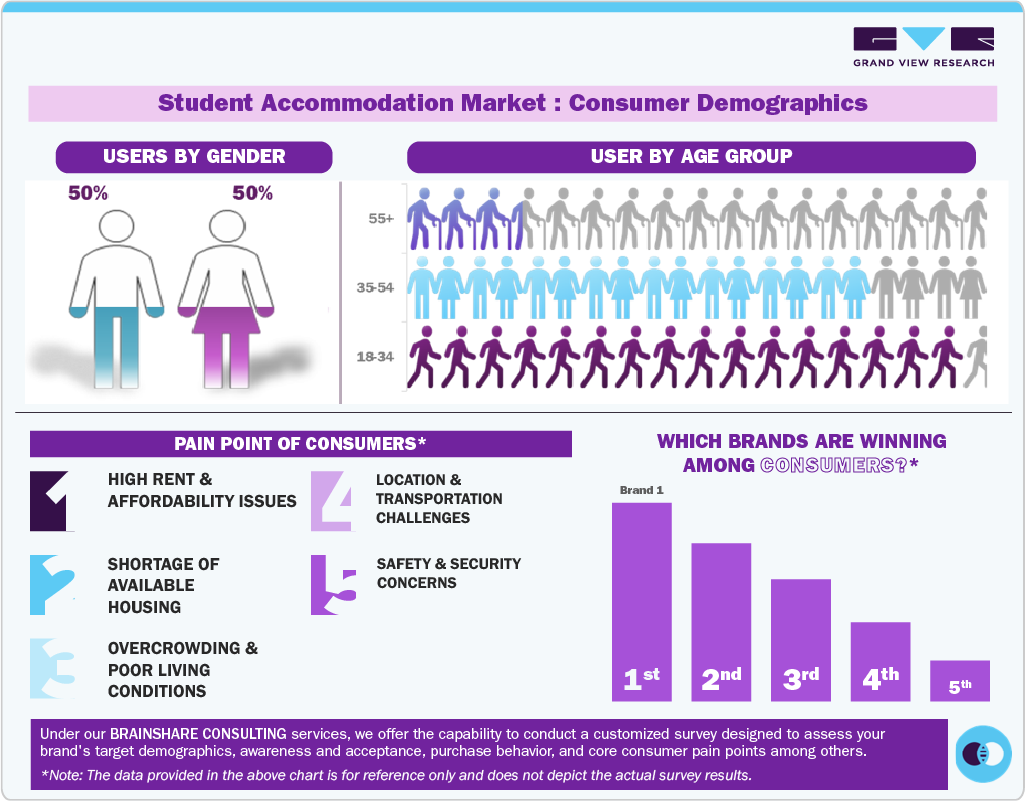
Affordability and the cost of living remain the primary factors influencing student accommodation decisions, as students carefully balance tuition costs with daily living expenses. Rising rental prices and inflation have heightened sensitivity to housing costs, making affordable rents, inclusive utility packages, and flexible payment options highly attractive. Students increasingly evaluate accommodation based on overall value for money, preferring options that combine reasonable pricing with essential facilities such as internet access, furnishings, and maintenance services.
 To learn more about this report, Download Free Sample Report
Location and accessibility also play a crucial role in accommodation selection. Students typically prefer housing situated close to universities, public transportation networks, supermarkets, and social or recreational areas to reduce commuting time and transportation expenses. Safe neighborhoods and convenient access to campus resources enhance comfort and academic productivity, making strategically located accommodations more desirable among both domestic and international students.
 To learn more about this report, Download Free Sample Report
Accommodation Type Insights
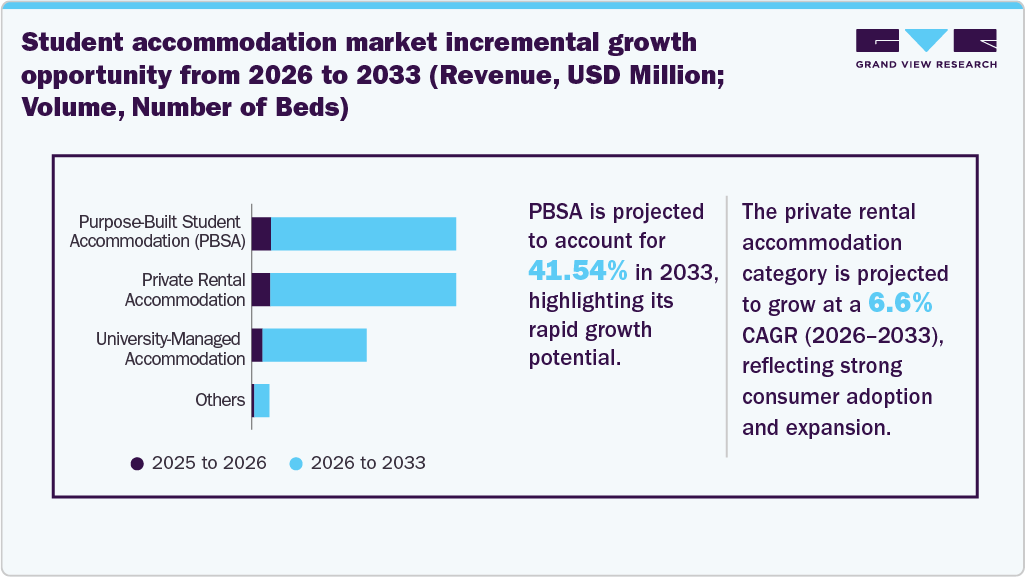
Based on accommodation type, the purpose-built student accommodation (PBSA) segment led the market with the largest revenue share of 43.4% in 2025. PBSAs are specifically designed to meet students' academic, social, and lifestyle needs, making it highly attractive compared to traditional housing options. These accommodations typically offer fully furnished rooms, dedicated study areas, high-speed internet connectivity, communal lounges, and shared facilities that support both learning and social interaction.
 To learn more about this report, Download Free Sample Report
The private rental accommodation segment is expected to grow at the fastest CAGR of 6.6% from 2026 to 2033. The rising number of students pursuing higher education abroad, particularly from emerging economies, has created an unprecedented demand for quality housing that offers both flexibility and independence. Unlike traditional university-managed accommodations, private rentals cater to students' desire for a more personalized living experience, with better amenities, privacy, and proximity to urban centers.
Location Insights
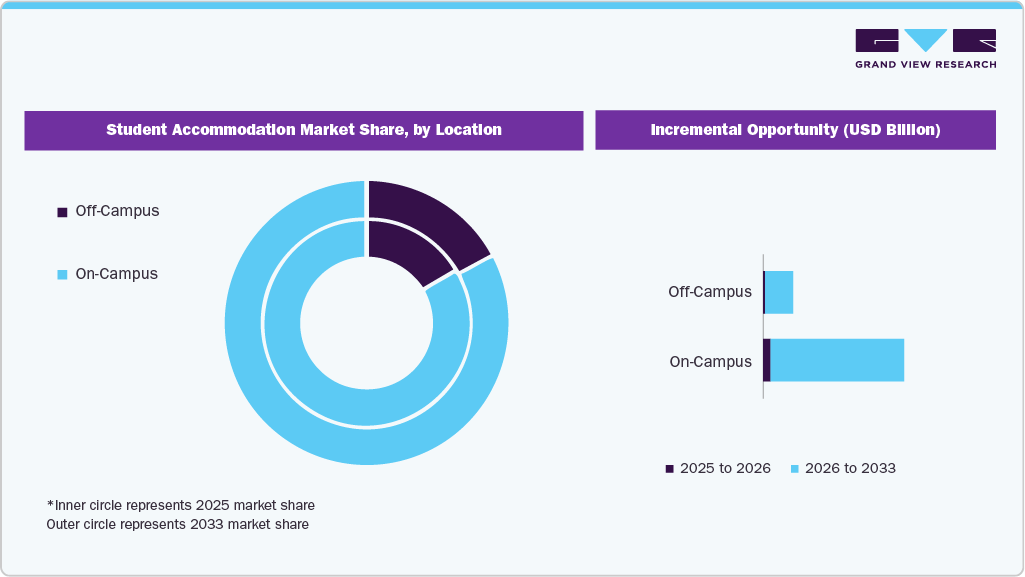
Based on location, the off-campus location segment led the market with the largest revenue share of 72.1% in 2025. Off-campus housing often offers a broader range of rental options, allowing students to select accommodation based on budget, room type, and preferred living arrangements. Sharing apartments or houses with peers also helps reduce individual living costs, given the limited on-campus housing availability. In addition, off-campus living provides students with greater personal freedom and exposure to city life beyond the university environment. Access to public transport, restaurants, retail stores, and entertainment areas enhances convenience and social experience.
 To learn more about this report, Download Free Sample Report
The demand for on-campus accommodation is anticipated to witness the fastest CAGR of 6.7% from 2026 to 2033. Living on campus provides immediate access to classrooms, libraries, laboratories, and university facilities, helping students save time on commuting and focus more on academics. Universities are also expanding residential infrastructure to attract international students who often prefer institution-managed housing during their initial years of study.
Occupancy Type Insights
Based on occupancy type, the double occupancy type segment led the market with the largest revenue share of 45.3% in 2025. Sharing a room allows students to significantly reduce individual rental and utility expenses, making it an attractive option for those managing limited budgets. At the same time, double occupancy encourages social interaction, peer bonding, and collaborative living, helping students build friendships and support networks.
Single occupancy type is anticipated to witness a CAGR of 6.5% from 2026 to 2033. Many students prefer personal space that allows them to focus on academic work without distractions, especially with the rise of hybrid learning and online coursework. Single-occupancy rooms offer quieter study conditions, better mental well-being, and greater control over daily routines, making them attractive to postgraduate, international, and working students.
Education Grade Insights
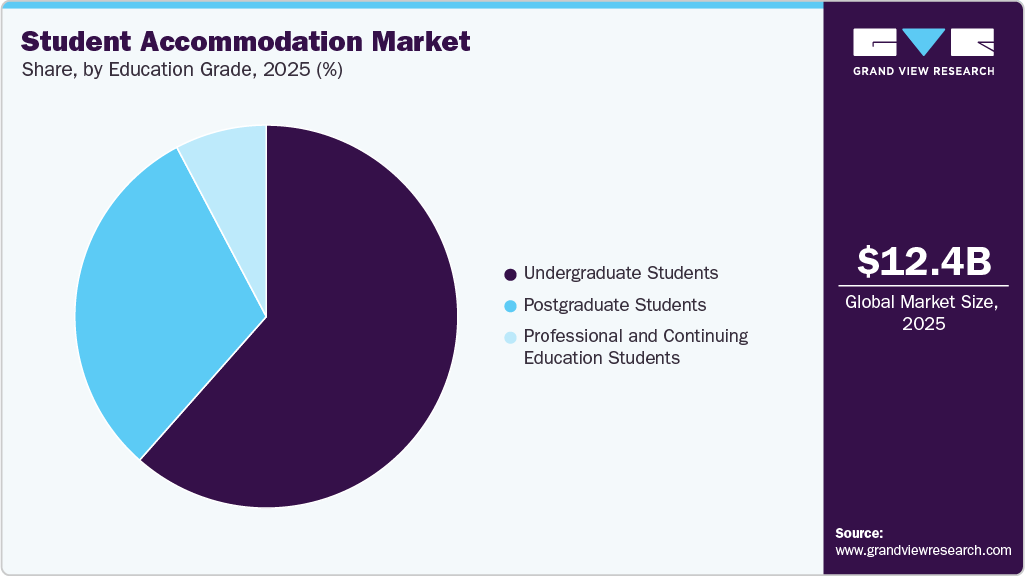
Based on education grade, the undergraduate students segment led the market with the largest revenue share of 61.5% in 2025. The continuous growth in undergraduate enrollment remains a key driver of demand in the student housing market. According to the National Student Clearinghouse Research Center, total U.S. postsecondary enrollment reached 19.4 million students in Fall 2025, including 16.2 million undergraduate students, reflecting a 1.2% year-over-year increase in undergraduate enrollment. This marks another year of recovery and sustained growth following pandemic-related declines in higher education participation.
In addition, the Clearinghouse’s Spring 2025 Current Term Enrollment Estimates reported that undergraduate enrollment rose 3.5% year-on-year, reaching approximately 15.3 million students, indicating renewed interest in higher education pathways.
 To learn more about this report, Download Free Sample Report
The demand for accommodations among postgraduate students is anticipated to witness the fastest CAGR of 6.6% from 2026 to 2033. The increasing enrolment in higher education, particularly among international students pursuing advanced degrees, has driven demand for quality housing solutions that offer convenience, safety, and a conducive environment for academic pursuits. Post-graduates often seek accommodation well-connected to academic institutions and equipped with amenities that support both study and lifestyle needs.
The competitive nature of graduate programs and the demands of research-oriented courses necessitate an environment that minimizes distractions and supports academic excellence. As a result, there is a growing preference among post-graduates for accommodations that offer a balanced combination of privacy, comfort, and proximity to academic resources. The rise in global mobility and the trend of pursuing education abroad have increased the need for reliable, secure housing solutions for post-graduate students, particularly in urban areas with high concentrations of educational institutions. This trend is further reinforced by the increasing recognition of the role of well-designed student accommodation in enhancing the overall academic experience, thereby attracting and retaining top-tier talent.
Regional Insights
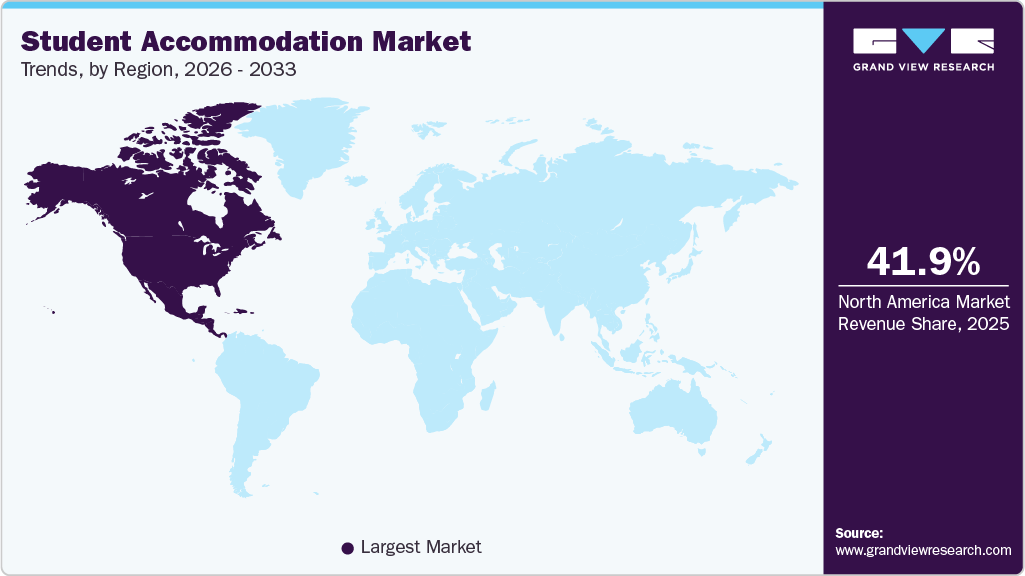
North America dominated the student accommodation market with the largest revenue share of 41.9% in 2025. Universities across the U.S. and Canada continue to attract a growing number of domestic and international students due to high-quality education, diverse academic programs, and strong career opportunities. The recovery and expansion of international student inflows after pandemic disruptions have significantly boosted demand for on-campus and off-campus housing, particularly in major university cities. This steady growth in student populations is creating sustained pressure on housing supply, encouraging investment in purpose-built student accommodation and modern rental solutions.
 To learn more about this report, Download Free Sample Report
U.S. Student Accommodation Market Trends
The student accommodation industry in the U.S. held the largest revenue share of 68.0% in the North American region in 2025. Rising institutional investment is a key driver of growth in the U.S. market, as student housing has emerged as a stable, recession-resistant real estate asset class. Investors, private equity firms, and real estate developers are increasingly allocating capital to purpose-built student accommodation due to consistently high occupancy rates, predictable rental income, and long-term demand tied to stable university enrollment. This substantial interest in investment is accelerating new project development, modernizing existing properties, and expanding portfolios in major university cities, thereby strengthening overall market growth and improving the quality and availability of student housing across the U.S.
The student accommodation industry in Canada is anticipated to witness a CAGR of 5.6% from 2026 to 2033. Purpose-built student accommodation is emerging as the fastest-professionalizing segment. Developers and investors are increasingly focusing on PBSA projects that offer modern amenities, security, and community living environments explicitly tailored to students, helping reduce pressure on traditional rental housing markets.
Asia Pacific Student Accommodation Market Trends
The student accommodation industry in the Asia Pacific is anticipated to witness the highest CAGR of 6.8% from 2026 to 2033. Expanding middle-class populations, improved access to higher education, and government initiatives promoting global education hubs have significantly increased student migration across countries such as Australia, China, India, Singapore, and Malaysia. The growing inflow of international students, along with large domestic student populations relocating to urban education centers, is creating sustained demand for organized, safe, and professionally managed student housing, encouraging the development of purpose-built student accommodation and modern rental solutions across the region.
The student accommodation industry in India held a revenue share of 34.6% in 2025. A growing number of students are relocating from smaller towns to major education hubs such as Bengaluru, Pune, Delhi-NCR, Hyderabad, and Chennai. Over 75% of students live away from their hometowns, creating sustained demand for organized accommodation solutions beyond traditional college hostels. Increasing domestic migration remains the primary demand driver, while international student numbers are also gradually rising.
The student accommodation industry in China is anticipated to witness a CAGR of 4.2% from 2026 to 2033. China’s vast domestic student population is a primary driver of growth in its market. With millions of students enrolled in universities and colleges each year, the continuous expansion of higher education participation is generating strong demand for both on-campus dormitories and off-campus housing. The increasing migration of students from smaller cities and rural regions to major academic hubs such as Beijing, Shanghai, and Guangzhou further intensifies housing demand, prompting universities and private developers to expand accommodation capacity and modernize student living facilities nationwide.
Europe Student Accommodation Market Trends
The student accommodation industry in Europe held a revenue share of 26.5% in 2025. Pension funds, private equity firms, and global real estate investors are actively investing in purpose-built student accommodation due to stable occupancy levels, predictable rental income, and long-term demand supported by strong university enrollment. This rising investment activity is accelerating large-scale developments, modernization of existing properties, and expansion of professionally managed student housing across major European university cities.
The student accommodation industry in the UK held a revenue share of 32.6% in 2025. The country continues to attract students worldwide due to its globally recognized universities, diverse academic programs, and strong post-study work opportunities. Increasing inflows of students from Asia, the Middle East, and Europe are significantly boosting demand for purpose-built student accommodation and private rental housing, particularly in major university cities.
The student accommodation industry in France is anticipated to witness a CAGR of 5.1% from 2026 to 2033. France market is experiencing growth driven by rising domestic and international student enrollments. Major education hubs such as Paris, Lyon, Toulouse, and Nantes continue to attract large student populations, creating sustained pressure on housing availability each academic year.
Central & South America Student Accommodation Market Trends
The student accommodation industry in Central & South America is anticipated to witness a CAGR of 4.2% from 2026 to 2033. Due to limited university-owned housing, students often rely on private rentals, shared apartments, and informal housing arrangements. Private rental accommodation is projected to be the fastest-growing segment as urban student populations expand and flexible living options become more attractive to domestic and international students.
Middle East & Africa Student Accommodation Market Trends
The student accommodation industry in the Middle East & Africa held a revenue share of 4.4% in 2025. The Middle East & Africa (MEA) region is witnessing increasing investment in higher education, driving strong growth in student populations and mobility. Expanding universities, government education initiatives, and growing international student inflows are boosting demand for dedicated student housing across major academic cities.
Key Student Accommodation Company Insights
Leading players in the market include American Campus Communities (ACC), Global Student Accommodation Group, and Campus Living Villages. The global market is highly competitive, characterized by established purpose-built student accommodation (PBSA) operators, real estate developers, university housing providers, private landlords, and emerging co-living and student housing platforms expanding across major education hubs worldwide. Market participants are increasingly focusing on modern infrastructure development, technology-enabled property management, flexible leasing models, and amenity-rich living environments to meet evolving student expectations for affordability, convenience, safety, and community-oriented living.
 To learn more about this report, Download Free Sample Report
Key Student Accommodation Companies
The following key companies have been profiled for this study on the student accommodation market.
-
American Campus Communities (ACC)
-
Global Student Accommodation Group
-
Campus Living Villages
-
The Student Hotel (TSH)
-
The Unite Group
-
Harrison Street
-
Greystar Real Estate Partners
-
APG Asset Management
-
Kohlberg Kravis Roberts & Co. L.P.
-
Mapletree Investments Pte Ltd
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (American Campus Communities, The Unite Group, Campus Living Villages, Greystar Real Estate Partners, Harrison Street)
- Expand PBSA portfolios through acquisitions, new developments, and university partnerships. Invest in digital resident platforms, sustainability initiatives, premium amenities, and expansion into major education hubs to maintain high occupancy rates and strengthen market presence.
- Strong brand recognition, extensive property portfolios, established relationships with universities, access to institutional capital, high occupancy rates, and proven expertise in student housing management across multiple markets.
- High development and maintenance costs, exposure to construction inflation and interest rate fluctuations, dependence on university enrollment trends, and lengthy approval processes for new projects.
Emerging Players (Global Student Accommodation Group, The Student Hotel, Regional PBSA Developers and Local Student Housing Operators)
- Focus on niche student segments, flexible accommodation formats, technology-enabled resident services, community-building initiatives, and expansion into underserved university cities. Leverage modern amenities and innovative living concepts to attract students.
- Faster innovation cycles, greater flexibility in adapting to student preferences, differentiated living experiences, a strong focus on community engagement, and the ability to enter emerging education markets quickly.
- Limited financial resources compared to large operators, smaller property portfolios, lower brand awareness, challenges in scaling internationally, and higher sensitivity to occupancy fluctuations.
Recent Developments
-
In January 2026, New Era Living launched its 2026/27 student accommodation offering, featuring major savings and a city-wide shuttle service, highlighting the growing focus on affordability and convenience in the student housing market. The initiative introduced discounted rental packages along with a dedicated shuttle service connecting key university locations across Sheffield, helping students reduce transportation costs and improve accessibility.
-
In July 2025, Centurion Corporation launched EPIISOD, a new premium, purpose-built student accommodation (PBSA) brand in Sydney, reflecting the growing shift toward high-quality, experience-driven student housing. The flagship EPIISOD Macquarie Park development, located near Macquarie University, will provide approximately 732 student beds and is scheduled to welcome residents by Semester 1 of 2026. The project emphasizes hotel-style living, with modern amenities including wellness facilities, innovative technology, curated community programs, and inclusive lifestyle services designed to enhance academic success and student well-being.
Student Accommodation Market Report Scope
Report Attribute
Details
Market size in 2025
USD 12.4 billion
Estimated market size in 2026
USD 13.0 billion
Projected market size by 2033
USD 19.1 billion
Growth rate
CAGR of 5.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Accommodation type, education grade, occupancy type, location, region
Regional scope
North America; Europe; Asia Pacific; CSA; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia; Brazil; UAE; South Africa
Key companies profiled
American Campus Communities (ACC); Global Student Accommodation Group; Campus Living Villages; The Student Hotel (TSH); The Unite Group; Harrison Street; Greystar Real Estate Partners; APG Asset Management; Kohlberg Kravis Roberts & Co. L.P; Mapletree Investments Pte Ltd
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Student Accommodation Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis of the latest trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the student accommodation market report based on accommodation type, education grade, occupancy type, location, and region.
-
Accommodation Type Outlook (Volume, Number of Beds; Revenue, USD Billion, 2021 - 2033)
-
Purpose-Built Student Accommodation (PBSA)
-
University-Managed Accommodation
-
Private Rental Accommodation
-
Others (Homestays, etc.)
-
-
Education Grade Outlook (Volume, Number of Beds; Revenue, USD Billion, 2021 - 2033)
-
Undergraduate Students
-
Postgraduate Students
-
Professional and Continuing Education Students
-
-
Location Outlook (Volume, Number of Beds; Revenue, USD Billion, 2021 - 2033)
-
Off-campus
-
On-campus
-
-
Occupancy Type Outlook (Volume, Number of Beds; Revenue, USD Billion, 2021 - 2033)
-
Single
-
Double
-
Triple/ Multi
-
-
Regional Outlook (Volume, Number of Beds; Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
-
Central & South America
-
Brazil
-
-
Middle East and Africa
-
UAE
-
South Africa
-
-
Research Methodology
The student accommodation market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each student accommodation segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Accommodation Type
Revenue capture definition
Purpose-Built Student Accommodation (PBSA)
This segment covers the revenues generated through the student accommodation market from purpose-built student accommodation facilities specifically designed and developed for students attending colleges, universities, and other higher education institutions. These properties typically offer fully furnished rooms, shared or private living spaces, study areas, high-speed internet, security services, communal amenities, and flexible lease terms tailored to student needs. PBSA properties are often operated by specialized student housing providers and are located near educational institutions or within major student hubs.
University-Managed Accommodation
This segment covers the revenues generated through the student accommodation market from housing facilities owned, operated, or managed directly by universities and educational institutions. These accommodations are typically located on campus or within proximity to university grounds and are primarily reserved for enrolled students. University-managed accommodation often includes residence halls, student apartments, and shared housing facilities that provide affordable living arrangements along with access to campus resources and student support services.
Private Rental Accommodation
This segment covers the revenues generated through the student accommodation market from privately owned residential properties rented by students. These accommodations may include apartments, flats, houses, shared living spaces, and co-living properties leased directly from landlords, property management companies, or real estate agencies. Private rental accommodation is commonly chosen by students seeking greater independence, flexible living arrangements, or lower-cost alternatives to purpose-built and university-managed housing.
Others (Homestays, etc.)
This segment covers the revenues generated through the student accommodation market from alternative housing arrangements that do not fall under purpose-built, university-managed, or private rental categories. These accommodations include homestays, host family arrangements, boarding houses, temporary student lodging, and other specialized accommodation formats. Such options are often preferred by international students seeking cultural immersion, language development opportunities, or short-term housing solutions.
Estimation Model
Layer Name
Key Question
Description
Student Population Layer
Who requires student accommodation?
Identify the total higher education student population across target countries, including domestic and international students enrolled in universities, colleges, and other tertiary institutions. This establishes the potential addressable student housing population.
Mobility & Housing Demand Layer
Who needs accommodation away from home?
Apply student migration and mobility rates, including international students and domestic students relocating for education. Exclude students living with family to derive the accommodation-seeking student population.
Accommodation Preference Layer
Who chooses organized student housing?
Apply penetration rates for purpose-built student accommodation (PBSA), university-managed accommodation, private rentals, and homestays. Factor in occupancy rates, affordability considerations, and regional housing preferences to estimate active users of student accommodation services.
Revenue Generation Layer
How much revenue is generated?
Multiply the number of accommodated students by the average annual accommodation expenditure per student. Incorporate rental rates across PBSA, university-managed housing, private rentals, and alternative accommodations to derive total market revenue.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Purpose-Built Student Accommodation (PBSA) Demand & Investment Trends
Conducted a focused analysis of PBSA adoption trends covering student housing supply-demand dynamics, occupancy rates, rental growth, amenity preferences, sustainability initiatives, digital resident services, and institutional investment activity across major education hubs.
Helps stakeholders identify high-growth university cities, evaluate investment attractiveness, assess premium accommodation demand, and capitalize on long-term student housing opportunities.
Student Enrollment, Mobility & Occupancy Trends
Evaluated the impact of domestic and international student enrollment growth, cross-border education mobility, undergraduate and postgraduate housing demand, occupancy preferences, and evolving student lifestyle requirements across on-campus and off-campus accommodation segments.
Provides insights into future housing demand patterns, emerging student destinations, occupancy optimization strategies, and market expansion opportunities driven by global education trends.
Accommodation Type & Location Opportunity Assessment
Assessed growth opportunities across university-managed accommodation, private rental accommodation, homestays, and PBSA facilities, along with on-campus and off-campus housing developments. Included analysis of affordability challenges, technology integration, community-focused living concepts, and regional supply gaps.
Supports investment, development, and portfolio expansion strategies by identifying underserved student populations, evaluating accommodation preferences, and uncovering opportunities for differentiated housing solutions.
Frequently Asked Questions About This Report
Some of the key players operating in the student accommodation market include American Campus Communities (ACC), Global Student Accommodation Group, Campus Living Villages, The Student Hotel (TSH), The Unite Group, Harrison Street, Greystar Real Estate Partners, APG Asset Management, Kohlberg Kravis Roberts & Co. L.P., and Mapletree Investments Pte Ltd.
The growth of the global student accommodation market is majorly driven by The continuous rise in the global student population, particularly international students, along with the growing demand for quality, safe, and convenient housing among students.
The global student accommodation market size was valued at USD 12.4 billion in 2025 and is estimated at USD 13.0 billion for 2026.
The global student accommodation market is expected to grow at a CAGR of 5.7% from 2026 to 2033, reaching USD 19.1 billion by 2033.
North America dominated with a 41.9% revenue share in 2025.
The purpose-built student accommodation (PBSA) segment led with a 43.4% revenue share in 2025.
Undergraduate students segment held the largest revenue share 61.5% in 2025.
The off-campus segment led with a 72.1% revenue share in 2025.
Double occupancy held the largest share (over 45.0%) in 2025.
About the Author(s)
Homecare & Decor Research Team
Consumer Goods · Homecare & DecorThis report was authored by the homecare & decor research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the homecare & decor segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


