
- Home
- »
- Next Generation Technologies
- »
-
Surge Protection Devices Market Size Report, 2026-2033GVR Report cover

Surge Protection Devices Market (2026 - 2033) Size, Share & Trends Analysis Report By Product (Hard-wired, Plug-in, Line Cord), By Type, By Power Rating, By End Use (Commercial Complexes, Data Center, Industries & Manufacturing Units), By Region, And Segment Forecasts
Market Size, 2025
$3.5BMarket Estimate, 2026
$3.7BMarket Forecast, 2033
$6.1BCAGR, 2026–2033
7.2%Surge Protection Devices Market Summary
The global surge protection devices market size was valued at USD 3.5 billion in 2025 and is projected to grow from USD 3.7 billion in 2026 to USD 6.1 billion by 2033, at a CAGR of 7.2% from 2026 to 2033. North America held the largest share of 39.5% of the global market in 2025. The market growth can be attributed to the growing demand for surge protection devices (SPD) to protect the new, innovative electrical and electronic gadgets being installed in homes and offices.
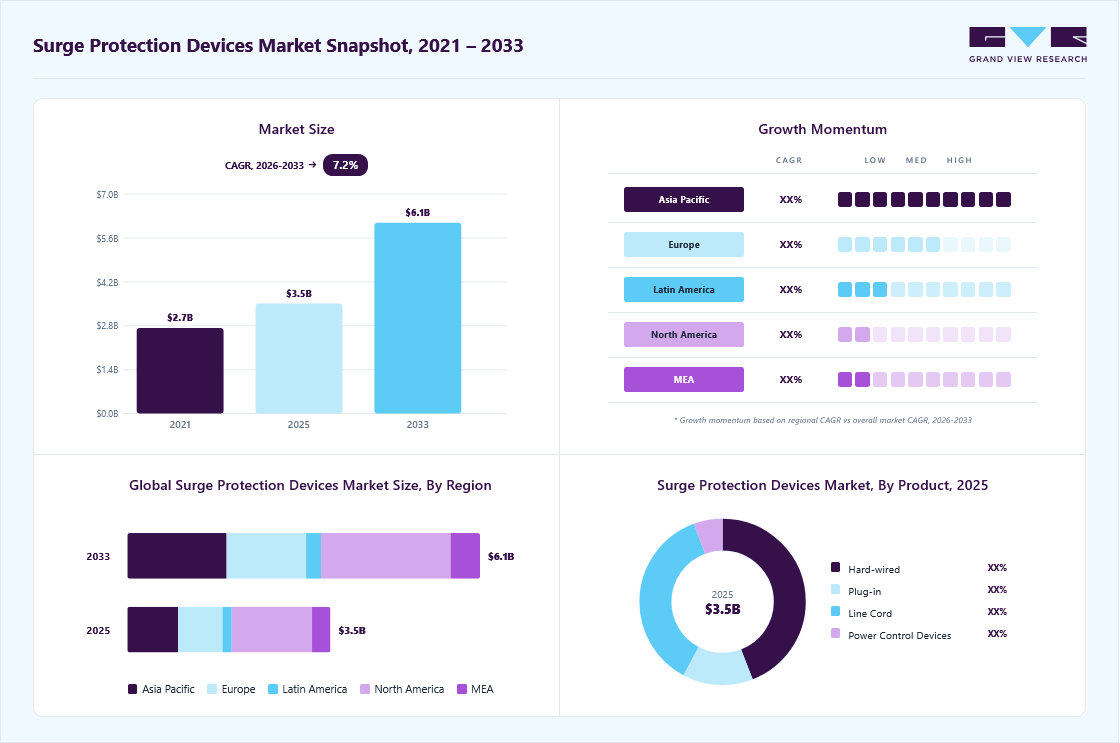 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Hard-wired segment accounted for the largest revenue share of 44.1% in 2025.
- By type: Type 2 segment held the largest share in 2025.
- By power rating: 100.1-200 kA segment accounted for the largest share in 2025.
- By end use: Industries & manufacturing units segment dominated the market in 2025.
Regional Highlights
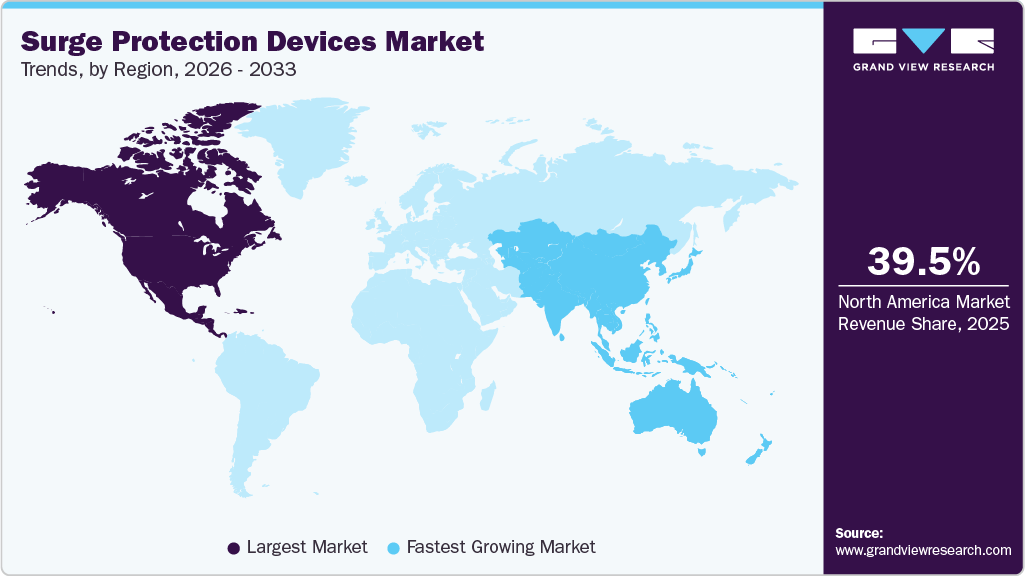
- Largest regional market: North America (39.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR of 8.9%, 2026-2033)
- By country: The U.S. held a dominant position in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.5 Billion
- Estimated market size in 2026: USD 3.7 Billion
- Projected market size by 2033: USD 6.1 Billion
- CAGR (2026-2033): 7.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The surge protection devices market is driven by the growing need to protect electrical and electronic equipment from voltage surges, power disturbances, and equipment damage. The increasing adoption of renewable energy systems, expansion of power infrastructure, and proliferation of sensitive electronic devices across residential, commercial, and industrial applications are creating sustained demand for effective power protection solutions. In addition, rising costs associated with equipment downtime, maintenance, and failures caused by poor power quality are encouraging end users to deploy surge protection devices to improve system reliability and operational continuity. The growing emphasis on energy efficiency and protection of increasingly interconnected electrical systems is further expected to support market growth over the forecast period.The continued amendments various governments are making in their respective regulations for public safety are expected to contribute to the growth of the surge protection devices industry. For instance, in the U.S., the National Electrical Code, published and sponsored by the National Fire Protection Association in Quincy, Massachusetts, is updated every three years in line with the rapid technological advancements. While the new rule applies to new homes, it becomes applicable to the existing homes when the service panel is updated. The revised National Electrical Code envisages protecting the appliances, electronic equipment, and computers from electrical surges.
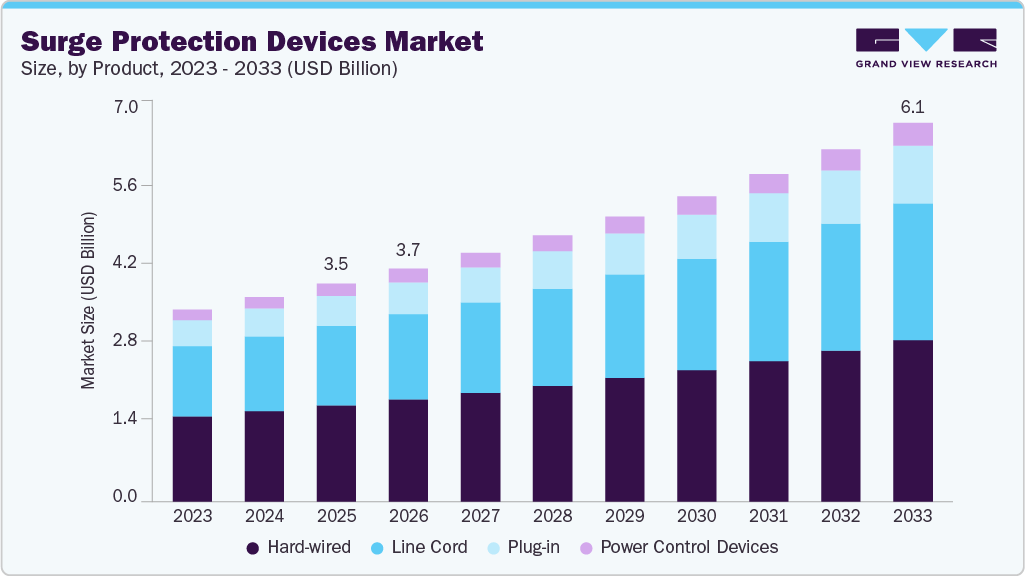 To learn more about this report, Download Free Sample Report
Another major trend fueling market growth is the expansion of renewable energy systems and grid modernization initiatives. Solar PV installations, wind energy systems, and battery storage units are highly susceptible to power surges caused by grid instability and lightning strikes. As countries continue to invest in clean energy transitions and smart grid infrastructure, the integration of SPDs becomes essential to protect these systems and maintain operational reliability. This trend is significantly boosting SPD deployment in energy and utility applications worldwide.
The increasing developments made in smart homes worldwide are expected to boost the demand for smart home-enabled surge protection devices worldwide. According to the statistics provided by Oberlo, 63.43 million households in the U.S. actively use smart home gadgets in 2023. The adoption of smart gadgets in the coming years is expected to grow at a rate of 10.2%. Oberlo predicts that 93.59 million U.S. households will have smart home gadgets by 2027. These smart gadgets are expected to make smart homes more technologically convenient and easier to use.
Surge protection devices are of paramount importance for protecting electrical installations. As such, the growing sales of household electronic devices across the globe are expected to accentuate the growth of the surge protection devices (SPD) market. According to the study conducted by the United States Public Interest Research Group (U.S. PIRG), a nonprofit organization focusing on consumer issues, as of 2021, American households spent about USD 1,767 on buying new electronic products per year. However, lower awareness of surge protection devices in emerging countries and regions is anticipated to hinder the growth of the market.
Market Dynamics
The surge protection devices (SPD) market is primarily driven by the rising integration of highly sensitive semiconductor-based electronics and automation systems across industrial and commercial infrastructure. Modern manufacturing facilities, data centers, telecom towers, and healthcare systems operate with low-voltage digital equipment that is highly vulnerable to transient voltage surges, making surge protection a critical infrastructure requirement rather than an optional safety component.
Another core driver is the rapid expansion of distributed renewable energy systems, such as solar PV and battery energy storage systems, where fluctuating grid conditions and lightning-induced surges pose significant risks to inverters, transformers, and control systems. The increasing deployment of EV charging infrastructure is also accelerating SPD adoption, as fast chargers and power electronics require continuous voltage stabilization and protection against grid disturbances.
The surge protection devices (SPD) market faces a key restraint in the form of high upfront installation and lifecycle maintenance costs, particularly for industrial-grade and utility-scale protection systems. Advanced SPDs integrated with monitoring, remote diagnostics, and high-energy handling capabilities significantly increase overall electrical infrastructure costs, limiting adoption among small and medium-sized enterprises and cost-sensitive residential users.
In many developing economies, end users continue to prioritize basic electrical infrastructure over advanced protection systems, especially in regions with low awareness of transient-voltage risks and the costs of equipment failure. Additionally, improper installation practices and a lack of standardized maintenance protocols can reduce SPD effectiveness and operational lifespan, leading end users to hesitate about the long-term return on investment.
The increasing deployment of smart infrastructure, digital power networks, and electrified transportation systems is creating significant growth opportunities for the surge protection devices (SPD) market. The rapid expansion of smart cities, intelligent buildings, and IoT-enabled industrial facilities is increasing reliance on interconnected electronic systems that require continuous voltage protection and power-quality management.
The accelerating adoption of renewable energy systems, particularly solar PV installations, battery energy storage systems, and microgrids, presents a major opportunity for SPD manufacturers, as these systems require advanced protection against lightning strikes, switching surges, and grid fluctuations. Similarly, the global expansion of EV charging infrastructure is driving strong demand for high-performance SPDs integrated into fast-charging stations and power-conversion equipment.
Market Concentration & Characteristics
The surge protection devices (SPD) market is moderately fragmented, with the presence of several multinational electrical equipment manufacturers, power protection solution providers, and regional component suppliers competing across industrial, commercial, residential, and utility applications. Major players such as ABB Ltd., General Electric Company, Schneider Electric, and Eaton Corporation plc dominate the market through broad product portfolios, global distribution networks, strong brand positioning, and integration capabilities across low-voltage and medium-voltage electrical systems. However, the market also includes numerous regional and local manufacturers offering cost-competitive SPDs for residential buildings, commercial facilities, and small industrial installations.
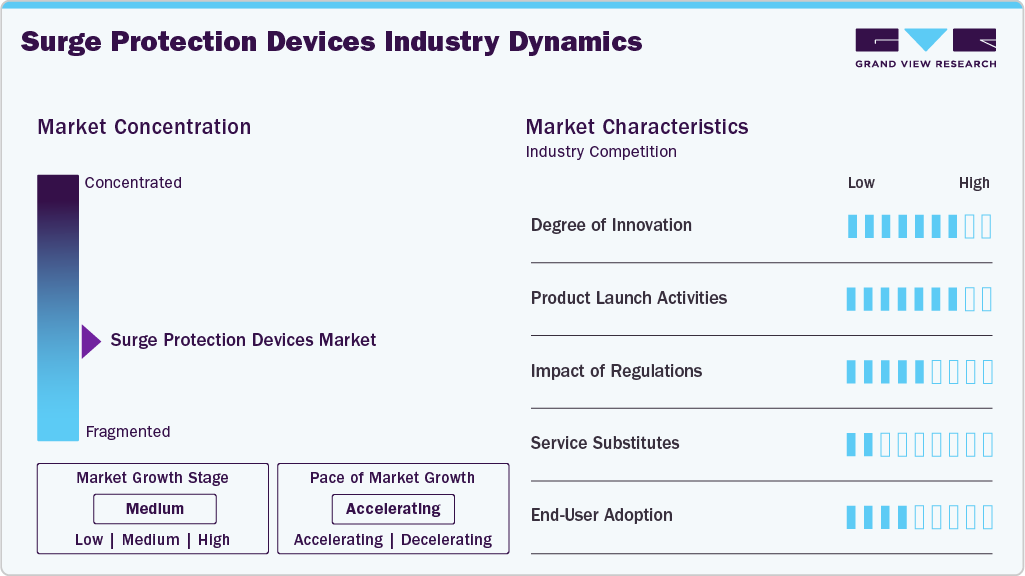 To learn more about this report, Download Free Sample Report
Market fragmentation is further supported by the growing diversity of end-use applications, including renewable energy systems, EV charging infrastructure, industrial automation, data centers, telecom networks, and smart buildings, which create opportunities for specialized vendors focused on application-specific surge protection solutions. Technological advancements such as IoT-enabled SPDs, modular protection systems, and smart monitoring capabilities are enabling emerging companies to differentiate themselves through innovation and customized solutions. Also, the market is witnessing gradual consolidation through strategic acquisitions, partnerships, and the expansion of integrated electrical protection portfolios by large multinational companies. Established players are increasingly focusing on strengthening their presence in high-growth segments such as renewable energy, smart grids, and digital infrastructure, while also expanding manufacturing and distribution capabilities in emerging economies to enhance market penetration and competitive positioning.
Product Insights
The hard-wired segment dominated the surge protection devices market, accounting for the largest share of 44.1% in 2025. The segment is expected to remain dominant throughout the forecast period. Hard-wired SPDs are typically installed on power lines for the protection of devices and outlets downstream from the device. They can also protect AC-powered, connected systems and equipment from the damage stemming from transients, surges, and AC power-induced events. Hard-wired surge protection devices are also used in commercial, industrial, and residential applications, including lighting circuits, motor controllers, and power distribution systems. Hence, hard-wired SPDs can be the most convenient surge protection solution to ensure reliable operations and extended performance.
The plug-in segment is expected to grow at the fastest CAGR during the forecast period. Plug-in SPDs are mainly installed in intermediate panels and at the origin of the network to protect the equipment from indirect lightning strikes. As such, plug-in surge protection devices are used to protect sensitive electrical equipment, such as refrigerators and televisions. The demand for plug-in SPDs is anticipated to increase over the forecast period, driven by the application and the advantages they offer across various endpoints. A plug-in SPD may require external overcurrent protection or may be included within the SPD.
Type Insights
The Type 2 segment held the largest share of the surge protection devices industry in 2025. Type 2 SPDs are designed for industrial and commercial applications. The protection of electrical equipment and distribution panels in a factory or commercial facility is of utmost importance, as power failures or equipment damage can severely hamper productivity. The main function of type 2 surge protection devices is to limit transient voltage and protect sensitive electronics and Mp/Mc-based boards. Hence, type 2 SPDs are mainly installed on the load side of the main service equipment.
The Type 1 segment is expected to register the highest CAGR during the forecast period. Type 1 SPDs are incorporated primarily to protect electronic equipment from lightning surges. Climatic changes over the past few years have led to an increase in lightning strikes. Hence, the growing need to protect electrical equipment used in applications, such as solar plants and smart grids, from lightning surges is expected to drive the growth of the segment over the forecast period. The rise in the installation of type 1 surge protection devices in sump and irrigation pumps, farm controls, and garages, among others, is also expected to drive the growth of the segment.
Power Rating Insights
The 100.1-200 kA segment held the largest surge protection devices market share in 2025. SPDs with a higher kA factor do not provide enhanced protection; rather, they deliver a longer product life. Hence, SPDs with a higher kA factor are ideal for industrial and data center applications. As a result, the demand for SPDs with a 100.1-200 kA power rating is growing worldwide.
The 50.1-100 kA segment is expected to register a notable CAGR during the forecast period.SPDs with power ratings ranging from 50.1 kA to 100 kA are primarily used by manufacturing units and for residential and commercial applications. As SPDs with 50.1-100 kA power ratings can provide the necessary protection and longevity, the use of higher-rated SPDs, such as those rated 100.1 kA and above, is only feasible for applications that are less price-sensitive and subject to frequent high-power surges. Hence, the 50.1-100 kA segment is expected to emerge as the fastest-growing segment over the forecast period.
End Use Insights
The industries & manufacturing units segment dominated the surge protection devices market in 2025. Advances in technology and the strong emphasis on augmenting profitability are prompting companies to deploy various automation systems and high-end electronics. However, companies using electrical equipment are often subject to power line abnormalities and heavy lightning that may lead to the breakdown of the equipment. Such breakdowns typically add to the company’s operational costs. Hence, the adoption of SPDs is expected to increase significantly over the forecast period due to their ability to counter overvoltage in the electrical distribution network.
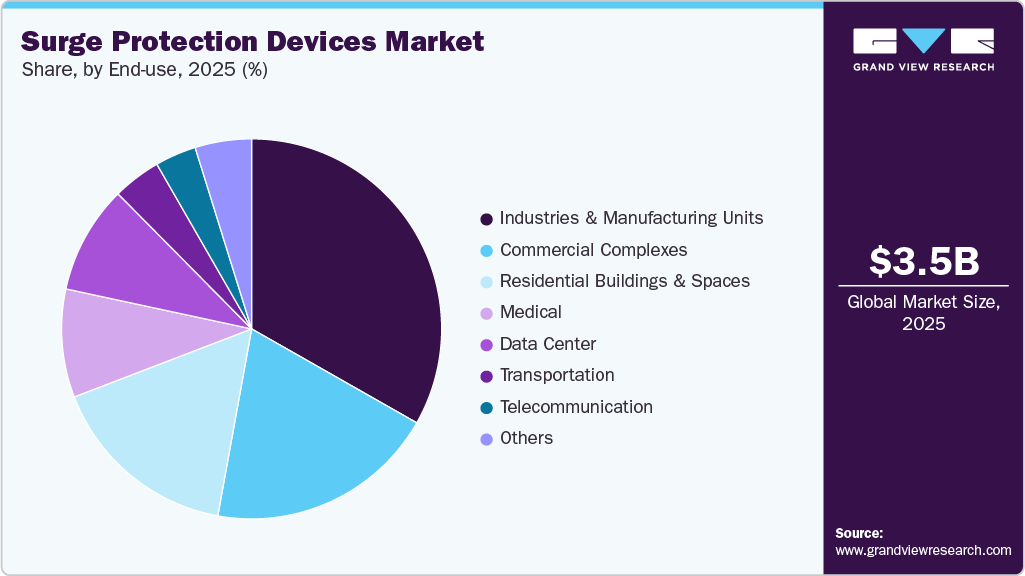 To learn more about this report, Download Free Sample Report
The commercial complexes segment is anticipated to grow at a promising CAGR over the forecast period. The commercial sector in developing economies, such as India, is growing noticeably owing to the favorable policies, such as Make in India and Startup India, being pursued by the government. Competition in the commercial sector is expected to intensify further owing to such encouraging initiatives. Hence, commercial establishments are expected to opt for SPDs to safeguard their equipment, prevent any undesired downtimes, save costs, and augment profitability, thereby driving the growth of the segment over the forecast period. The strong emphasis that electrical designers are putting on ensuring that commercial SPDs are installed in compliance with the regulatory requirements also bodes well for the growth of the segment.
Regional Insights
The North America surge protection devices market held the largest share of 39.54% in 2025. The region is an early adopter of advanced technologies. The level of awareness about the benefits of SPDs is also very high in the region. When it comes to the U.S., electricity consumption for residential and commercial applications accounts for approximately 37% of the total electricity consumption. The U.S. is also home to states such as Florida, Louisiana, Mississippi, and Alabama, which are highly prone to lightning strikes. Hence, the adoption of SPDs to protect electronic appliances from sudden energy fluctuations is very high in these states. As such, North America has emerged as the largest regional market owing to all these factors.
 To learn more about this report, Download Free Sample Report
U.S. Surge Protection Devices Market Trends
The U.S. surge protection devices industry held a dominant position in 2025, supported by a well-established electrical infrastructure, high adoption of advanced electronic systems, and strong regulatory frameworks related to electrical safety.
Europe Surge Protection Devices Market Trends
The Europe surge protection devices industry is expected to register a moderate CAGR from 2026 to 2033, driven by increasing investments in modernizing energy infrastructure and integrating renewable energy. Countries across the region are focusing on strengthening grid resilience and ensuring power quality, which is accelerating the deployment of SPDs. Moreover, stringent electrical safety standards and regulations imposed by regional authorities are encouraging the installation of surge protection systems across residential, commercial, and industrial applications. The rising adoption of electric vehicle (EV) charging infrastructure and smart buildings is further contributing to market expansion.
The UK surge protection devices market is expected to grow at a significant CAGR from 2026 to 2033, supported by the country’s strong focus on sustainable energy and infrastructure upgrades. Increasing deployment of renewable energy systems, including rooftop solar and wind farms, has heightened the need for effective surge protection solutions.
The surge protection devices market in Germany held a substantial share in 2025, driven by its advanced industrial base and strong emphasis on manufacturing excellence. The country’s leadership in automation and industrial digitization, supported by initiatives such as Industry 4.0, has increased the need for reliable power protection systems to ensure uninterrupted operations.
Asia Pacific Surge Protection Devices Market Trends
The Asia Pacific surge protection devices industry is expected to grow at the fastest CAGR of 8.9% during the forecast period. The rapid growth can be attributed to the increased manufacturing activities in the regional industries and sectors, such as automotive and healthcare. The growth of the construction and healthcare verticals in countries such as Japan and India is subsequently driving the regional growth.
India’s surge protection devices market is expected to grow at a notable rate during the forecast period, driven by rapid urbanization, expanding power infrastructure, and increasing digitalization across industries. The rising deployment of data centers, telecom networks, and smart city projects has significantly increased the need for reliable surge protection solutions.
The surge protection devices market in China held a substantial share in 2025, supported by the country’s strong manufacturing base and large-scale infrastructure development. High demand from industries such as electronics, automotive, and industrial manufacturing has led to increased adoption of SPDs to ensure equipment protection and operational continuity.
Key Surge Protection Devices Company Insights
Some of the key companies in the surge protection industry include Schneider Electric, ABB Ltd., Eaton Corporation plc, Siemens AG, among others.In the surge protection devices (SPD) market, companies are increasingly focusing on strengthening their product portfolios and technological capabilities to address the growing demand for reliable power protection solutions. As a result, key players are undertaking a range of strategic initiatives, including mergers and acquisitions, capacity expansions, new product developments, and strategic partnerships. Additionally, manufacturers are investing in advanced technologies such as modular SPDs, IoT-enabled monitoring systems, and high-performance protection solutions to meet the evolving needs of renewable energy, industrial automation, data centers, and smart infrastructure, thereby enhancing their competitive positioning in the market.
-
Schneider Electric SE develops a wide range of energy management and automation solutions, with a strong focus on electrical distribution, industrial automation, and digital transformation. The company offers an extensive portfolio of products and services, including circuit protection devices, switchgear, surge protection devices (SPDs), energy monitoring systems, and smart grid solutions. Through its digital platforms, such as EcoStruxure, the company integrates IoT-enabled solutions to enhance efficiency, reliability, and sustainability across residential, commercial, and industrial applications.
-
ABB Ltd. specializes in electrification and automation technologies, offering advanced solutions for power distribution, industrial automation, and smart infrastructure. The company offers a comprehensive portfolio of surge protection devices, circuit breakers, relays, transformers, and grid automation solutions. ABB also focuses on digitalization through its ABB Ability platform, enabling real-time monitoring, predictive maintenance, and improved operational performance across utilities, industries, and infrastructure sectors.
Key Surge Protection Devices Companies:
The following key companies have been profiled for this study on the surge protection devices market.
- ABB Ltd.
- General Electric Company
- Schneider Electric
- Eaton Corporation plc
- Legrand
- Emerson Electric Co.
- Siemens AG
- CG Power and Industrial Solutions Limited
- Littelfuse, Inc.
- Bourns, Inc.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: Schneider Electric; ABB; Siemens AG; Eaton; Legrand
- Mature players focus on delivering comprehensive surge protection solutions across industrial, commercial, residential, utility, renewable energy, and data center applications.
- Their strategies emphasize broad product portfolios, integration with power distribution and electrical infrastructure systems, and expansion through global distribution and channel partnerships.
- Strong brand recognition and extensive global distribution networks support high market penetration across developed and emerging economies.
- Broad expertise in electrical infrastructure, automation, and power management enables integrated end-to-end protection solutions.
- Large organizational structures can reduce flexibility and slow response to rapidly evolving niche application requirements.
- Premium pricing structures may limit adoption in cost-sensitive residential and small commercial markets.
- Dependence on mature industrial and utility markets can limit growth rates in highly saturated regions.
Emerging Players: CG Power and Industrial Solutions Limited; Littelfuse, Inc.; Bourns, Inc.
- Emerging players are targeting high-growth segments such as solar PV installations, electric vehicle charging networks, and industrial control systems, offering customized surge protection devices designed for specific end-use requirements.
- Higher operational agility and faster innovation cycles enable rapid adaptation to emerging technologies and industry requirements.
- Competitive pricing and flexible product customization support adoption among regional customers and small-to-medium enterprises.
- Limited global presence and smaller distribution networks restrict access to large multinational infrastructure projects.
- Lower brand visibility and limited long-term service capabilities may affect customer confidence compared to established multinational players.
Recent Developments
-
In October 2025, Schneider Electric launched an industry-first plug-and-play surge protection device (SPD) in the U.K, designed for direct integration with Acti9 and KQ Loadcentre distribution boards. The product featured an all-in-one design with an embedded backup fuse, eliminating the need for external disconnectors or additional protective components. It simplified installation by enabling direct plug-in, reducing both installation time and overall costs for contractors. The device was developed to meet growing regulatory requirements under BS 7671:2018 while enhancing protection against transient overvoltage in commercial and industrial applications.
Surge Protection Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.5 billion
Estimated Market size in 2026
USD 3.7 billion
Projected Market size by 2033
USD 6.1 billion
Growth rate
CAGR of 7.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, type, power rating, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; KSA; UAE; South Africa
Key companies profiled
ABB Ltd.; General Electric Company; Schneider Electric; Eaton Corporation plc; Legrand; Emerson Electric Co.; Siemens AG; CG Power and Industrial Solutions Limited; Littelfuse, Inc.; Bourns, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Surge Protection Devices Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest segmental trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global surge protection devices market report based on product, type, power rating, end use, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Hard-wired
-
Plug-in
-
Line Cord
-
Power Control Devices
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Type 1
-
Type 2
-
Type 3
-
Type 4
-
-
Power Rating Outlook (Revenue, USD Million, 2021 - 2033)
-
0-50 kA
-
50.1-100 kA
-
100.1-200 kA
-
200.1 kA and Above
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Commercial Complexes
-
Data Center
-
Industries & Manufacturing Units
-
Medical
-
Residential Buildings & Spaces
-
Telecommunication
-
Transportation
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Surge Protection Devices Market Analysis
- Segmentation of surge protection devices across Type 1, Type 2, and Type 3 categories.
- Application-wise assessment across residential, commercial, industrial, and utility sectors.
- Evaluation of voltage rating trends and installation standards across regions.
- Identified high-growth segments in industrial and commercial infrastructure protection.
- Supported demand forecasting linked to power quality and grid reliability requirements.
Electrical Infrastructure & Risk Protection Study
- Analysis of surge risk exposure across power distribution networks and end-user facilities.
- Assessment of integration with smart electrical panels and renewable energy systems.
- Improved understanding of infrastructure vulnerability and mitigation requirements.
- Enabled alignment of product positioning with regulatory-driven demand.
Competitive Landscape Assessment
- Benchmarking of leading surge protection device manufacturers and solution providers.
- Product portfolio comparison across capacity, response time, and durability parameters.
- Channel strategy analysis, including OEM partnerships and electrical distributors.
- Supported competitive positioning and differentiation strategy.
- Identified growth opportunities in smart SPD systems and integrated protection solutions.
Frequently Asked Questions About This Report
The Type 2 segment held the largest revenue share in 2025.
The 100.1-200 kA segment held the largest surge protection devices market share in 2025.
The industries & manufacturing units segment dominated the market in 2025.
Some key players operating in the SPDs market include ABB Ltd., General Electric Company, Schneider Electric, Eaton Corporation plc, Legrand, Emerson Electric Co., Siemens AG, CG Power and Industrial Solutions Limited, Littelfuse, Inc., and Bourns, Inc.
North America dominated the surge protection devices market with the largest revenue share of 39.5% in 2025.
Key factors that are driving the surge protection devices market growth include the increasing use of electronics in residential and commercial sectors and the high cost associated with electrical equipment downtime.
The global surge protection devices market was estimated at USD 3.5 billion in 2025 and is expected to reach USD 3.7 billion in 2026.
Asia Pacific is expected to be the fastest-growing regional market.
The hard-wired segment accounted for the largest revenue share of 44.1% In 2025.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


