
- Home
- »
- Medical Devices
- »
-
Surgical Lights Market Size, Share & Growth Report, 2033GVR Report cover

Surgical Lights Market (2026 - 2033)
Size, Share & Trends Analysis Report By Technology (LED lights, Halogen Lights), By Application (Cardiac Surgery, Neurosurgery, Gynecological Surgery, ENT Surgery), By End Use, By Region, And Segment Forecasts
Market Size, 2025
$2.1BMarket Estimate, 2026
$2.2BMarket Forecast, 2033
$3.3BCAGR, 2026–2033
5.9%Surgical Lights Market Summary
The global surgical lights market size was valued at USD 2.1 billion in 2025 and is projected to grow from USD 2.2 billion in 2026 to USD 3.3 billion by 2033, growing at a CAGR of 5.9% from 2026 to 2033. North America dominated the market, accounting for the largest share in 2025. The surge in the number of hospitals, the aging population, and the prevalence of lifestyle diseases are some of the factors driving growth. The development of healthcare infrastructure is expected to further fuel the market.
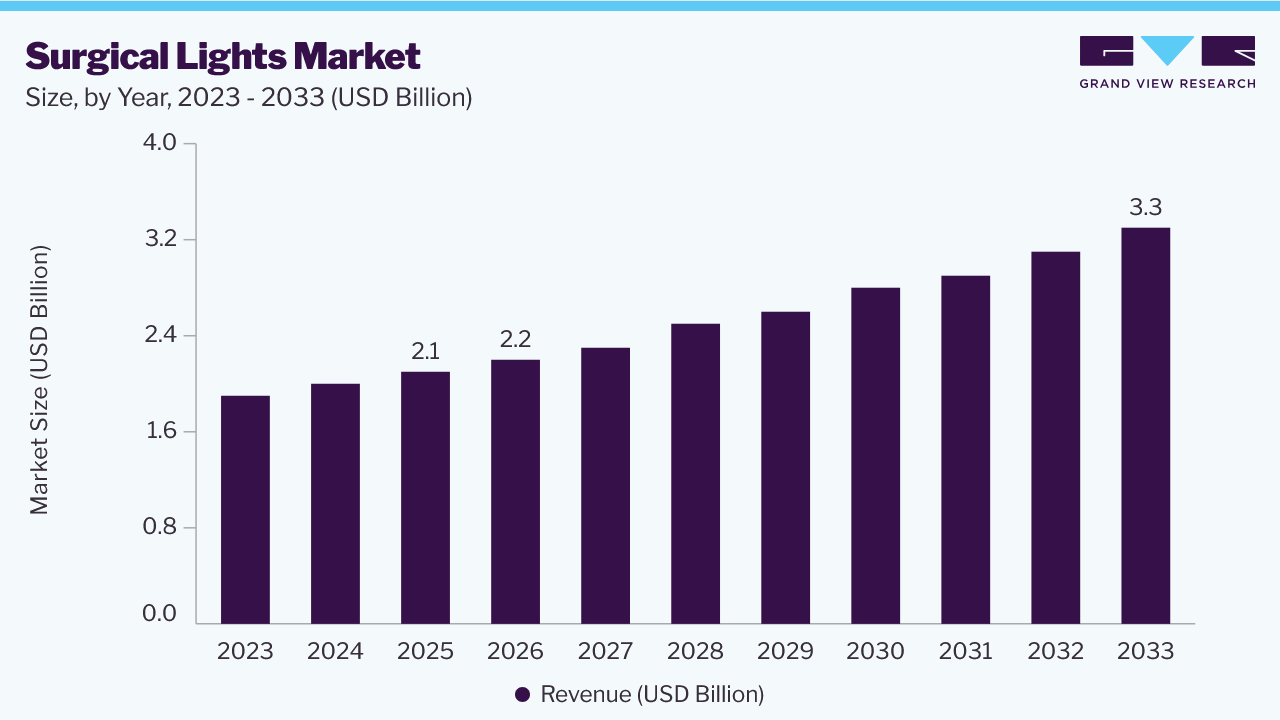 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By technology: The halogen lights segment accounted for the largest market share of 53.0% in 2025.
- By application: The cardiac surgery segment accounted for a significant market share in 2025.
- By end use: The hospital operating rooms segment dominated the market and accounted for the largest share in 2025.
Regional Highlights
- Largest regional market: North America
Market Size & Forecast
- Market size in 2025: USD 2.1 Billion
- Estimated market size in 2026: USD 2.2 Billion
- Projected market size by 2033: USD 3.3 Billion
- CAGR (2026-2033): 5.9%
Prism AI by Grand View Research Free to tryAsk a question about the surgical lights marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →The industry is experiencing steady growth, driven by the rising number of surgical procedures, expanding healthcare infrastructure, and ongoing modernization of operating rooms in hospitals and ambulatory surgical centers. The growing prevalence of chronic diseases, rising geriatric population, and increasing adoption of minimally invasive and robotic-assisted surgeries are creating sustained demand for advanced surgical lighting systems that provide superior illumination, accurate color rendering, and shadow-free visualization.
The development of new hospitals, specialty clinics, and ambulatory surgical centers, particularly in emerging economies, is further fueling demand for surgical lights and other operating room equipment. In addition, healthcare providers are increasingly investing in hybrid operating rooms and energy-efficient LED surgical lighting systems to improve surgical precision, workflow efficiency, and patient safety. Rising regulatory compliance requirements for operating room equipment and the growing emphasis on high-quality surgical care are also encouraging the adoption of technologically advanced surgical lighting solutions.
Furthermore, increasing product availability, continuous technological advancements, and favorable government initiatives to strengthen healthcare infrastructure are supporting market expansion. Investments by governments in countries such as India and China to expand hospitals, medical colleges, and specialized healthcare facilities, along with rising public and private healthcare expenditure, are expected to create significant growth opportunities for manufacturers of surgical lighting systems over the forecast period.
Analyst Perspective
The expanding geriatric population, increasing investments in healthcare infrastructure, and ongoing modernization of operating rooms are accelerating the demand for advanced surgical lighting systems in hospitals, ambulatory surgical centers, and specialty clinics. In addition, the growing emphasis on patient safety, surgical precision, infection control, and energy-efficient healthcare technologies is encouraging the adoption of LED-based surgical lights with enhanced illumination quality, adjustable color temperature, shadow management, and digital integration capabilities. Manufacturers are expected to focus on product innovation by incorporating intelligent lighting controls, camera integration, wireless connectivity, AI-enabled visualization, and ergonomic designs to improve surgical workflow and clinical outcomes.
Technology Insights
The halogen lights segment accounted for the largest market share of 53.0% in 2025, owing to its widespread availability, lower initial cost, and extensive installed base across hospitals and healthcare facilities. The affordability of halogen surgical lights makes them a preferred choice for healthcare providers with budget constraints, particularly in developing regions. In addition, halogen lights provide consistent illumination and excellent color rendering, enabling accurate tissue differentiation and enhanced surgical precision during procedures. Furthermore, their compatibility with existing operating room infrastructure and relatively low maintenance and replacement costs continue to support their adoption, particularly in facilities that have not yet transitioned to LED-based surgical lighting systems.
The LED lights segment is expected to grow significantly during the forecast period, driven by the increasing adoption of energy-efficient, technologically advanced surgical lighting systems. LED surgical lights consume significantly less power than conventional halogen lights, helping healthcare facilities reduce operating costs while supporting sustainability initiatives. In addition, their long operational lifespan minimizes maintenance requirements and equipment downtime, making them a cost-effective solution for hospitals and ambulatory surgical centers. LED lights also offer superior color rendering, adjustable color temperature, high illumination intensity, and reduced heat emission, thereby enhancing tissue visualization and surgeon comfort during prolonged procedures. Furthermore, the increasing replacement of conventional halogen lighting with LED-based systems in operating room modernization projects is accelerating segment growth. For instance, in January 2024, Getinge introduced the Maquet Ezea surgical light, an advanced LED surgical lighting system designed to provide efficient illumination, intuitive handling, flexible color temperature adjustment, low-energy consumption, and compliance with the IEC 60601-2-41 standard, further strengthening the adoption of LED surgical lighting solutions.
Application Insights
The cardiac surgery segment accounted for a significant share of the market in 2025. Cardiac procedures are highly complex and require exceptional illumination, accurate color rendering, and shadow-free visibility to support surgical precision and improve patient outcomes. The growing prevalence of cardiovascular diseases and the increasing number of cardiac surgeries performed worldwide continue to drive demand for advanced surgical lighting systems. According to a study published by the National Library of Medicine, approximately 300,000 cardiac procedures are performed annually in India, highlighting the substantial demand for specialized cardiac surgical care. Furthermore, the increasing adoption of minimally invasive and robotic-assisted cardiac procedures is driving demand for advanced LED surgical lights with adjustable color temperature, high-intensity illumination, and flexible positioning to optimize visualization in confined surgical fields.
The neurosurgery segment is projected to register a significant growth rate during the forecast period. The increasing prevalence of neurological disorders, including brain tumors, Parkinson's disease, epilepsy, and other central nervous system conditions, along with the growing geriatric population, is driving the demand for neurosurgical procedures. In addition, the rising adoption of minimally invasive, image-guided, and robotic-assisted neurosurgeries is increasing the need for high-performance surgical lighting systems that provide superior illumination, accurate color rendering, and shadow-free visualization of delicate anatomical structures. For instance, in September 2024, ZEISS launched the KINEVO 900 S, an advanced robotic visualization system designed for neurosurgery that integrates 4K 3D digital visualization, AI-enabled robotic capabilities, and connected workflow solutions. Such technological advancements are expected to accelerate the adoption of advanced operating room equipment, including high-quality LED surgical lights, thereby supporting growth in the neurosurgery segment.
End Use Insights
The hospital operating rooms segment dominated the market in 2025, driven by the high volume of surgical procedures performed in hospitals, continuous investments in operating room modernization, and the increasing adoption of advanced LED surgical lighting systems. Hospitals are upgrading conventional operating rooms to hybrid and digitally integrated operating suites to improve surgical precision, workflow efficiency, and patient safety. Furthermore, rising healthcare expenditure and ongoing expansion of hospital infrastructure, particularly in emerging economies, continue to support demand for high-performance surgical lighting solutions.
The ambulatory surgical centers (ASCs) segment is expected to register the fastest CAGR during the forecast period. The growing preference for minimally invasive and outpatient procedures, shorter patient recovery times, and lower treatment costs than in hospitals are driving the expansion of ASCs. As the number of outpatient surgical procedures continues to increase, these facilities are investing in modern operating room equipment, including energy-efficient LED surgical lights, to enhance surgical visibility and comply with quality and safety standards. In addition, favorable reimbursement policies and increasing investments in outpatient healthcare infrastructure are further accelerating segment growth.
Regional Insights
The North America surgical lights market dominated in 2025, supported by its well-established healthcare infrastructure, high surgical procedure volumes, and widespread adoption of advanced operating room technologies. The region has a strong network of hospitals, ambulatory surgical centers, and specialty clinics that continuously invest in modern medical equipment to improve surgical outcomes. In addition, favorable healthcare funding and reimbursement policies encourage healthcare providers to upgrade operating room infrastructure. For instance, in August 2024, the U.S. Department of Health and Human Services (HHS), through the Centers for Medicare & Medicaid Services (CMS), finalized the FY 2025 Inpatient Prospective Payment System (IPPS) rule, increasing Medicare payments to hospitals by 2.9%. The additional funding supports investments in healthcare infrastructure, medical technologies, and surgical care capabilities, thereby encouraging the adoption of advanced operating room equipment, including LED surgical lighting systems, across healthcare facilities.
U.S. Surgical Lights Market Trends
The surgical lights market in the U.S. dominated North America in 2025, supported by its well-established healthcare infrastructure, high volume of surgical procedures, and widespread adoption of advanced operating room technologies. The growing number of hospital expansion and renovation projects, coupled with increasing investments in hybrid operating rooms and minimally invasive surgeries, is driving demand for advanced LED surgical lighting systems. In addition, the presence of leading medical device manufacturers and continuous technological advancements in surgical lighting further support market growth.
Europe Surgical Lights Market Trends
The surgical lights market in Europe was identified as a lucrative regional market in 2025, driven by the rising geriatric population, increasing prevalence of chronic diseases, and growing number of surgical interventions. The UK surgical lights market is expected to grow rapidly over the forecast period due to ongoing investments in healthcare infrastructure, including the development and modernization of hospitals and surgical centers. Furthermore, increasing adoption of energy-efficient LED surgical lights with improved illumination quality, shadow control, and infection-control features is contributing to market growth.
Asia Pacific Surgical Lights Market Trends
The surgical lights market in Asia Pacific is anticipated to witness significant growth over the forecast period, driven by increasing investments in healthcare infrastructure and the rising adoption of advanced surgical technologies across the region. The growing number of hospitals, ambulatory surgical centers, and specialty healthcare facilities is creating sustained demand for modern surgical lighting systems. In addition, the increasing volume of surgical procedures, supported by the expanding elderly population and rising prevalence of chronic diseases, is further boosting market growth. For instance, in October 2024, the Indian Government started construction of several infrastructure projects in the health sector worth more than USD 1.5 billion, including hospitals, medical colleges, nursing colleges, critical care blocks, and expansions of AIIMS facilities across the country. These developments are expected to increase operating room capacity and accelerate the adoption of advanced surgical equipment, including surgical lights.
The China surgical lights market is expected to grow rapidly over the forecast period, driven by the increasing volume of surgical procedures and the ongoing expansion of healthcare infrastructure nationwide. Accurate, high-quality illumination in operating rooms enhances surgical precision, improves staff performance, and reduces the risk of complications, supporting the adoption of advanced surgical lighting systems. In addition, rising investments in hospital modernization and the growing installation of technologically advanced hybrid operating rooms equipped with LED surgical lights are further contributing to market growth.
Key Surgical Lights Company Insights
Some key companies in the surgical lights market include STERIS, A-dec Inc., CV Médica, BihlerMed, SKYTRON, LLC, Herbert Waldmann GmbH & Co. KG, Getinge, Integra LifeSciences Corporation, S.I.M.E.O.N. Medical GmbH & Co. KG, and Baxter. These companies focus on strengthening their market presence through strategies such as product innovation, portfolio expansion, partnerships and collaborations, mergers and acquisitions, and geographic expansion to address the growing demand for advanced surgical lighting systems.
- BihlerMed is known for its lighted medical equipment and medical manufacturing. The company leverages advanced assembly and manufacturing automation technologies to develop high-quality medical devices, including specialized surgical lighting solutions.
Key Surgical Lights Companies
The following key companies have been profiled for this study on the surgical lights market:
-
STERIS
-
A-dec Inc.
-
CV Médica
-
BihlerMed
-
SKYTRON, LLC
-
Herbert Waldmann GmbH & Co. KG
-
Getinge
-
Integra LifeSciences Corporation
-
S.I.M.E.O.N. Medical GmbH & Co. KG
-
Baxter
Recent Developments
- In April 2025, Dräger announced the U.S. availability of its next-generation Polaris OR lights, expanding its surgical lighting portfolio with advanced LED technology featuring improved illumination quality, Light Guard safety functionality, and enhanced ergonomic features.
- In June 2024, Kenall Manufacturing introduced KORE (Kenall Optical Radiance Engine) technology into its M4 Indigo-Clean EX surgical suite lighting series, enhancing lens uniformity while improving glare control and contrast reduction for optimal surgical visualization.
Surgical Lights Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.1 billion
Estimated market size in 2026
USD 2.2 billion
Projected market size by 2033
USD 3.3 billion
Growth rate
CAGR of 5.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Technology, application, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; Kuwait; UAE; South Africa
Key companies profiled
STERIS; A-dec Inc.; CV Médica; BihlerMed; SKYTRON, LLC; Herbert Waldmann GmbH & Co. KG; Getinge; Integra LifeSciences Corporation; S.I.M.E.O.N. Medical GmbH & Co. KG; Baxter.
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Surgical Lights Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global surgical lights market report based on technology, application, end-use, and region:
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
LED lights
-
Halogen Lights
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cardiac Surgery
-
Neurosurgery
-
Gynecological Surgery
-
ENT Surgery
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospital Operating Rooms
-
Ambulatory Surgical Centers
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
KSA
-
UAE
-
South Africa
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global surgical lights market size was valued at USD 2.1 billion in 2025 and is estimated at USD 2.2 billion for 2026.
The global surgical lights market is expected to grow at a CAGR of 5.9% from 2026 to 2033, reaching USD 3.3 billion by 2033.
North America dominated the industry in 2025.
The halogen Lights segment accounted for the largest revenue share of approximately 53.0% in 2025.
Key players in the market include STERIS, A-dec Inc., CV Médica, BihlerMed, SKYTRON, LLC, Herbert Waldmann GmbH & Co. KG, Getinge, Integra LifeSciences Corporation, S.I.M.E.O.N. Medical GmbH & Co. KG, and Baxter., and others.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


