
- Home
- »
- Next Generation Technologies
- »
-
Synthetic Aperture Radar Market Size & Share Report, 2033GVR Report cover

Synthetic Aperture Radar Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Receiver, Transmitter, Antenna), By Frequency Band (X, L, C, S), By Platform, By Mode, By Application, By Region, And Segment Forecasts
Market Size, 2025
$5.1BMarket Estimate, 2026
$5.7BMarket Forecast, 2033
$12.9BCAGR, 2026–2033
12.4%Synthetic Aperture Radar Market Summary
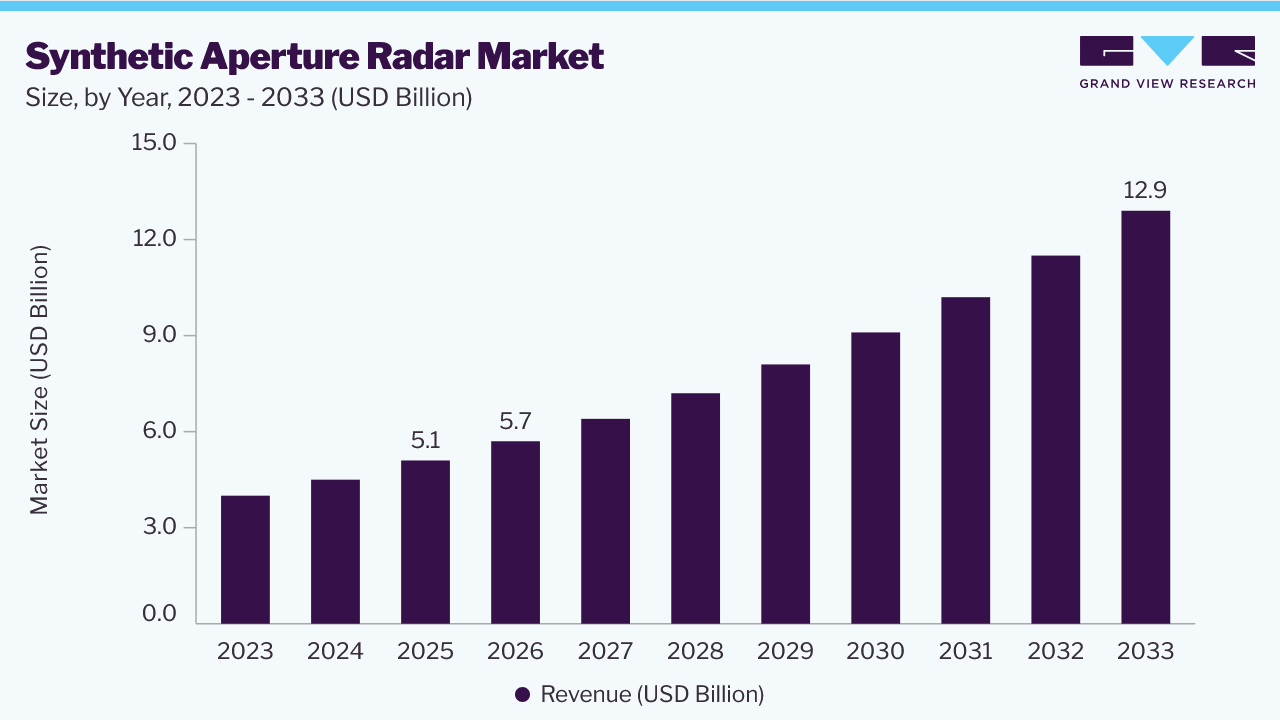
The global synthetic aperture radar market size was valued at USD 5.1 billion in 2025 and is projected to grow from USD 5.7 billion in 2026 to USD 12.9 billion by 2033, at a CAGR of 12.4% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of over 33.5% in 2025. This growth is primarily influenced by large-scale applications in environmental monitoring and earth observation, extensive use by the military and defense, and technological advancements leading to enhanced abilities.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: The receivers segment held the largest market share of 37.5% in 2025.
- By platforms: The airborne segment held the largest market share in 2025.
- By frequency band: The X band segment held the largest market share in 2025.
- By mode: The single mode segment held the largest market share in 2025.
- By application: The defense segment held the largest market share in 2025.
Regional Highlights
- Largest regional market: North America (33.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 5.1 Billion
- Estimated market size in 2026: USD 5.7 Billion
- Projected market size by 2033: USD 12.9 Billion
- CAGR (2026-2033): 12.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Space administration & earth observation industry participants and government agencies working primarily on weather monitoring, geographical mapping, and meteorology prefer synthetic aperture radars for their extraordinary ability to deliver high-resolution images through day and night with the lowest attenuation in weather changes. For instance, in July 2024, NASA, the National Aeronautics and Space Administration agency of the U.S. Federal government, announced that its work on NISAR (NASA-ISRO Synthetic Aperture Radar) is nearing completion. NISAR (NASA-ISRO Synthetic Aperture Radar) is a joint Earth-observation mission of the Indian Space Research Organization and NASA primarily aimed at agricultural monitoring and characterization, the study of Himalayan glaciers, landslides, coastal processes, coastal winds, soil moisture, etc., and monitoring hazards.
As every continent is impacted each year by events rooted in climate change and global warming, technological superiority offered by Synthetic Aperture Radar (SAR) in tracking, monitoring, and predicting large weather change consequences such as floods, rain-triggered landslides, and others is expected to drive growth for this market. Unlike other technologies, such as optical remote sensing, Synthetic Aperture Radar (SAR) can operate under extreme environmental conditions while penetrating cloud cover to provide two-dimensional (2-D) images. These dimensions comprise range (cross-track) and azimuth (or along the track). SAR's ability to present comparatively fine azimuth resolution distinguishes it from others.
Ongoing research & development activities by organizations and institutions, innovation by key companies, and collaboration & partnerships of major market participants with government agencies are expected to drive the growth of this market. For instance, in June 2025, ICEYE signed an agreement with NATO Allied Command Operations to provide Synthetic Aperture Radar (SAR) satellite data under the Alliance Persistent Surveillance from Space (APSS) initiative. The collaboration strengthens NATO's space-based intelligence, surveillance, and reconnaissance (ISR) capabilities by leveraging ICEYE's advanced SAR satellite constellation, highlighting the growing role of strategic partnerships between commercial SAR providers and government agencies in accelerating innovation and adoption.
Analyst Perspective
Governments and commercial organizations are investing in advanced Earth observation and geospatial intelligence capabilities. The growing need for all-weather, round-the-clock imaging services for applications such as disaster management, environment monitoring, border patrolling, and defense operations is accentuating the strategic significance of advanced SAR imaging technology. However, the continuous improvement in terms of satellite miniaturization, sensor technology, and data analytics is also making images more efficient and accessible. In addition, the joint efforts of space agencies, defense organizations, and private satellite operators have been enhancing the future scope and commercial viability of the market.
Component Insights
Based on components, the receivers segment dominated the global market, accounting for a revenue share of around 37.5% in 2025. The receiver is a key component of SARs as it is mainly used in the active imaging function, which creates images of the ground by sending signals and detecting backscattered waves. Innovations such as integrated receivers, which combine RF front ends with analog baseband chains and Analog-to-Digital Converters (ADCs), are expected to enhance the precision of the features provided by SARs. Numerous initiatives by authorities and organizations associated with monitoring and tracking deforestation and observation of natural disasters such as floods and landslides to prevent loss of life or similar complications are expected to fuel demand for SAR receivers. For instance, in August 2025, Texas Instruments announced that its space-grade analog-to-digital converters (ADCs), mixed-signal devices, clocking solutions, and power management semiconductors were enabling the radar imaging payload of the NASA-ISRO Synthetic Aperture Radar (NISAR) mission. These high-precision receiver electronics improve signal sampling, timing synchronization, and data acquisition, enabling the SAR payload to generate high-resolution radar imagery for Earth observation, environmental monitoring, and disaster management. The development highlights the growing importance of advanced receiver technologies in enhancing SAR system performance.
The transmitter segment is expected to experience the fastest CAGR during the forecast period. Technological advancements, such as the use of solid-state transmitters and the increasing application of SARs in various sectors, including military and defense, earth mapping, and civil infrastructure safety and management, mainly drive the growth of this segment. Synthetic aperture radars are also extensively used in the geology industry to explore and monitor terrains.
Platform Insights
The airborne segment dominated the market in 2025, driven by the versatility feature, which allows user industries and organizations to utilize the SAR systems for various purposes such as military surveillance, monitoring environmental changes, earth observations, terrain monitoring, safety and security of urban infrastructures, and monitoring critical infrastructure sites such as dams, gas pipelines, electricity grids, and more. High spatial resolution and performance capabilities with less susceptibility to attenuation caused by weather fluctuations, innovations, and enhancements in signal processing technology are expected to fuel the growth of this segment.
The ground-based synthetic aperture radar (GB-SAR) segment is projected to witness the fastest CAGR from 2026 to 2033. These radars operate with similar principles as airborne radars, however, with an extension of the radar antenna that is mounted on a ground-based track or a linear rail. Advantages offered by the GB-SAR systems include cost-effectiveness, flexibility, continuous monitoring to generate imagery in regular intervals, and more.
Frequency Band Insights
Based on the frequency band, the X band segment accounted for the largest revenue share of the industry in 2025. The X band radars operate at an 8-12 GHz frequency range, mainly to assist institutes, government agencies, organizations, and enterprises with precipitation measurements and monitor land subsidence. Its bandwidth ranges from 500 MHz up to 700 MHz. Innovations such as digital beamforming are driving a growing demand for the X-band SARs. The emergence and use of TanDEM-X satellites equipped with solid-state mass memory (SSMM) have also contributed to growth.
The VHF/UHF band segment is anticipated to experience the fastest CAGR from 2026 to 2033. This is attributed to the extensive use of VHF in wide-area surveillance, automated stationary artificial targets detection, and the ability to deliver high-resolution imagery by penetrating through potential barriers, including vegetation, foliage, and others. The military and defense industry uses synthetic aperture radars operating at Ultra High Frequency (UHF) and Very High Frequency (VHF) bands for effective communications with land forces and airborne deployments.
Mode Insights
The single mode segment accounted for the largest revenue share in 2025. The single mode SAR, or Stripmap (SM) mode, is commonly used to discover imagery of predetermined continuous paths or land. This develops a large strip of imagery with a 5 m by 5 m resolution. The mode is often utilized in urban infrastructure management, flood monitoring, crop assessments, oil spillage detection and tracking, rapid response assistance, surveillance, and more. It is also utilized by security forces and law enforcement agencies to monitor shipping routes continuously to prevent smuggling, fishing in unauthorized areas, and more. For instance, in February 2026, NASA announced new Commercial Satellite Data Acquisition (CSDA) agreements with five commercial SAR providers, Capella Space, ICEYE US, MDA Space, Umbra, and Airbus U.S., to supply high-resolution SAR imagery, including StripMap (single-mode) imaging, for Earth science applications such as flood monitoring, land deformation, sea-ice movement, and infrastructure assessment. The initiative highlights the growing reliance on StripMap SAR mode for continuous, high-resolution Earth observation and environmental monitoring.
The multimode synthetic aperture radar segment is projected to experience the fastest CAGR during the forecast period. The multimode systems enhance the overall capacities of traditional SARs through integration of multiple operational modes. This empowers SARs with versatility, diverse data collection abilities, and expedited real-time processing capabilities. Different modes include Stripmap, Spotlight, Interferometric Wide Swath (IW), Extra Wide Swath (EW), Wave, and others.
Application Insights
Based on application, the defense segment accounted for the largest revenue share of the global market in 2025. As tensions across multiple national borders rise and threats regarding internal security grow rapidly, numerous defense ministries have been deploying synthetic aperture radars for enhanced security, terrain monitoring, and border observations. SARs have become one of the significant aspects of surveillance, reconnaissance, and intelligence in the defense industry. Recent innovations and capacity enhancements have improved the resolution and imaging capabilities of SARs. In addition, its integration with modern technologies such as Artificial intelligence and machine learning has enabled defense forces to monitor targets in real-time. For instance, in May 2025, ICEYE signed an agreement with the Ministry of National Defense of the Republic of Poland to supply an initial batch of three Synthetic Aperture Radar (SAR) satellites under the Polish Armed Forces’ MikroSAR program, with an option for three additional satellites. The agreement also includes a mobile Intelligence, Surveillance, and Reconnaissance (ISR) platform capable of near real-time tasking, data processing, and analysis, highlighting the increasing adoption of advanced SAR systems for defense surveillance, border security, and military intelligence applications.
The natural resource exploration segment is projected to experience the fastest CAGR from 2026 to 2033. This is attributed to factors such as growing advancements in SAR technology used in earth observations and land exploration. The ability of SARs to penetrate clouds, vegetation, and foliage when necessary is driving their increasing applications in this segment.
Regional Insights
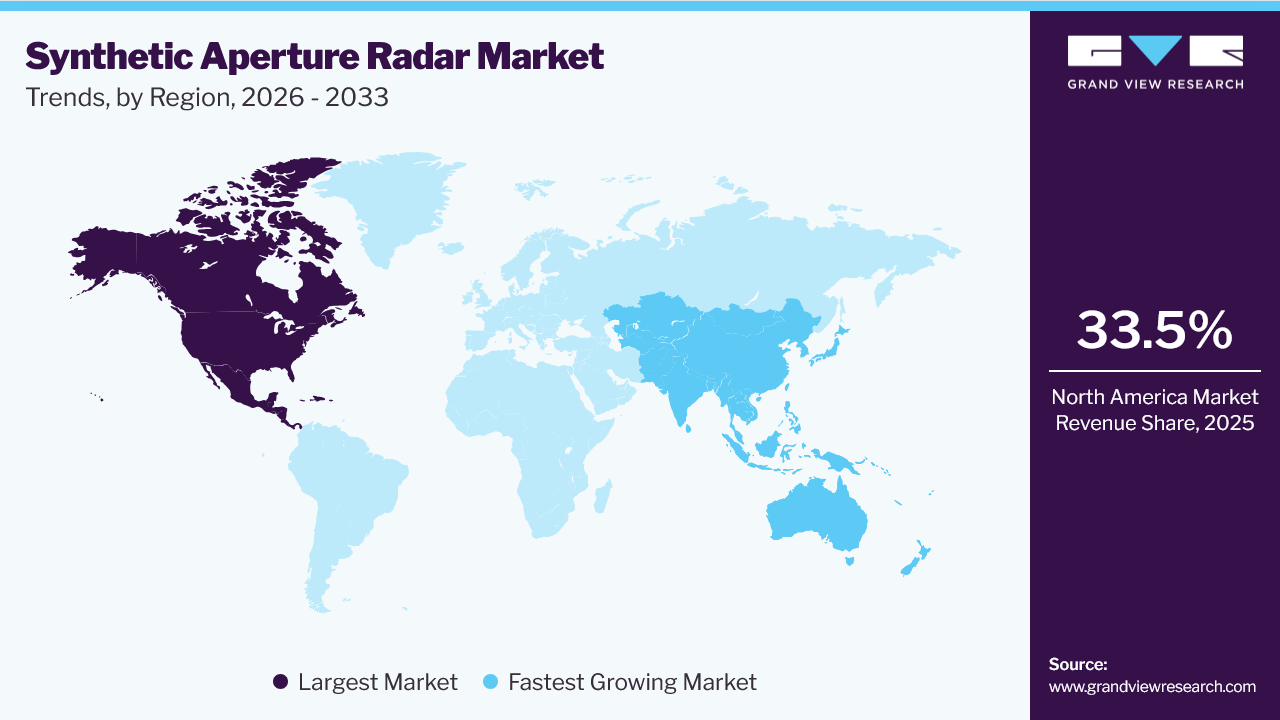
The North America synthetic aperture radar market dominated and accounted for around 33.5% in 2025. This is attributed to factors such as the presence of multiple manufacturers and vendors from the radar development industry in the region, growing demand from space administration and earth monitoring industries, and rising inclusion of SARs in terrain monitoring, surveillance, and related functions. For instance, in March 2025, Capella Space announced that it had been awarded a contract by the U.S. Defense Innovation Unit to develop new Synthetic Aperture Radar (SAR) imaging acquisition modes for the Hybrid Space Architecture (HSA). The project aims to deliver low-latency, broad-area SAR imagery for maritime domain awareness, mapping, and defense surveillance, reinforcing North America's leadership in advanced SAR technology development and government-backed Earth observation capabilities.
 To learn more about this report, Download Free Sample Report
U.S. Synthetic Aperture Radar Market Trends
The synthetic aperture radar market in the U.S. held the largest revenue share of the regional industry in 2025. This market is primarily driven by the presence of numerous key companies in the country, such as Lockheed Martin Corporation, Northrop Grumman, and others. The growing demand from the defense sector for surveillance, monitoring, airborne earth observation, and effective communication is contributing to the growth of this market.
Europe Synthetic Aperture Radar Market Trends
The synthetic aperture radar market in Europe is mainly driven by aspects such as increasing demand from earth observation, space administration, and the surveillance & monitoring sector. The use of SAR technology by the defense, weather monitoring, geology, and meteorology industries is expected to fuel demand for this market during the forecast period.
The Germany synthetic aperture market held a significant revenue share of the regional industry. This is attributed to the presence of SAR technology in defense monitoring and surveillance networks. In addition, the use to track and monitor precipitation, identify changes in weather conditions, and for Disaster Risk Management (DRM) is likely to influence the growth of this market.
Asia Pacific Synthetic Aperture Radar Market Trends
The synthetic aperture radar market in Asia Pacific is anticipated to experience the fastest CAGR from 2026 to 2033. The technology advancements in countries such as India, Japan, China, and others, growing applications in weather monitoring & earth observations, rising inclusion in defense communication systems, and use in space administration by federal space agencies in the region influence this market. For instance, in July 2025, the Indian Space Research Organisation successfully launched the NASA-ISRO Synthetic Aperture Radar (NISAR) mission aboard the GSLV-F16 rocket. Equipped with dual-frequency (L-band and S-band) Synthetic Aperture Radar, NISAR is designed to provide all-weather, day-and-night Earth observation for applications including disaster response, agriculture, coastal monitoring, glacier movement, and infrastructure assessment. The mission highlights Asia Pacific's growing investment in advanced SAR technologies and reinforces the region's leadership in space-based Earth observation and environmental monitoring
The India synthetic aperture radar market held a substantial revenue share of the regional industry in 2025. This is attributed to defense modernization, heavy investments in upgrading surveillance and monitoring capabilities, rising use in disaster management and rapid response assistance, and innovations such as dual-band SAR systems.
Key Synthetic Aperture Radar Market Company Insights
Some of the key companies involved in the synthetic aperture radar market include Lockheed Martin Corporation, AIRBUS, L3Harris Technologies, Inc., BAE Systems, Northrop Grumman, and others. To address growing applications in various industries and rising demand for SAR technology, key market participants in the industry are adopting strategies such as innovation, new product developments, enhanced research & development efforts, and more.
- Lockheed Martin Corporation, a key defense industry participant with a massive global footprint covering more than 300 locations and facilities, offers TRACER, dual-band (UHF/VHF), lightweight SAR, Pilotage Distributed Aperture Sensors(PDAS), and others.
- Northrop Grumman, a major market player in aerospace and defense, offers a range of products for precision surveillance and monitoring, including AN/ZPY-1 STARLite Small Tactical Radar, Trinidad, AN/ASQ-236 Dragon's Eye Radar Pod, and more.
Key Synthetic Aperture Radar Companies
The following are the leading companies in the synthetic aperture radar market. These companies collectively hold the largest market share and dictate industry trends.
-
Lockheed Martin Corporation
-
AIRBUS
-
SDT Space & Defence Technologies Inc.
-
BAE Systems
-
General Atomics
-
L3Harris Technologies, Inc.
-
IMSAR
-
IAI
-
Maxar Technologies
-
Metasensing
-
Northrop Grumman
-
Saab
-
SRC Inc.
Recent Developments
- In March 2025, ICEYE successfully launched four new Synthetic Aperture Radar (SAR) satellites, including its first fourth-generation (Gen4) SAR satellite. The Gen4 satellite features a larger SAR antenna, enhanced imaging capabilities, and wider swath coverage, enabling improved target detection, classification, and high-resolution Earth observation for defense, intelligence, disaster response, and commercial applications. The launch further strengthened ICEYE's position as the operator of the world's largest SAR satellite constellation and reinforced advancements in the market.
Synthetic Aperture Radar Market Report Scope
Report Attribute
Details
Market size in 2025
USD 5.1 billion
Estimated market size in 2026
USD 5.7 billion
Projected market size by 2033
USD 12.9 billion
Growth rate
CAGR of 12.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Component, platform, frequency band, mode, application, and region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Japan; China; India; Australia; South Korea; Brazil; UAE; Saudi Arabia; South Africa
Key companies profiled
Lockheed Martin Corporation; AIRBUS; SDT Space & Defence Technologies Inc.; BAE Systems; General Atomics; L3Harris Technologies, Inc.; IMSAR; IAI; Maxar Technologies; Metasensing; Northrop Grumman; Saab; SRC Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Synthetic Aperture Radar Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global synthetic aperture radar market report based on component, platform, frequency band, mode, application, and region:
-
Component Outlook (Revenue, USD Billion, 2021 - 2033)
-
Receiver
-
Transmitter
-
Antenna
-
-
Platform Outlook (Revenue, USD Billion, 2021 - 2033)
-
Ground
-
Airborne
-
-
Frequency Band Outlook (Revenue, USD Billion, 2021 - 2033)
-
X Band
-
L Band
-
C Band
-
S Band
-
K, Ku, Ka Band
-
VHF/UHF Band
-
Others
-
-
Mode Outlook (Revenue, USD Billion, 2021 - 2033)
-
Single
-
Multi
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Defense
-
Commercial
-
Public Safety
-
Environmental Monitoring
-
Natural Resource Exploration
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Frequently Asked Questions About This Report
The receivers segment accounted for the largest revenue share of over 37.5% in 2025.
The global synthetic aperture radar market size was valued at USD 5.1 billion in 2025 and is estimated at USD 5.7 billion for 2026.
The global synthetic aperture radar market is expected to grow at a CAGR of 12.4% from 2026 to 2033, reaching USD 12.9 billion.
North America dominated with over 33.5% revenue share in 2025.
Key players in the market include Lockheed Martin Corporation; AIRBUS; SDT Space & Defence Technologies Inc.; BAE Systems; General Atomics; L3Harris Technologies, Inc.; IMSAR; IAI; Maxar Technologies; Metasensing; Northrop Grumman; Saab; SRC Inc.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


