
- Home
- »
- Advanced Interior Materials
- »
-
Tool Holder Market Size, Share & Trends Report, 2026-2035GVR Report cover

Tool Holder Market (2026 - 2035)
Size, Share & Trends Analysis Report By Tool Holder (Collet Chucks, Hydraulic, Milling Chucks, Shrink-fit), By Taper (BT Flange Taper, CAT Taper, HSK Taper), By End Use (Automotive, Aerospace & Defense), By Region, And Segment Forecasts
Market Size, 2025
$1.4BMarket Estimate, 2026
$1.5BMarket Forecast, 2035
$2.1BCAGR, 2026–2035
4.2%Tool Holder Market Summary
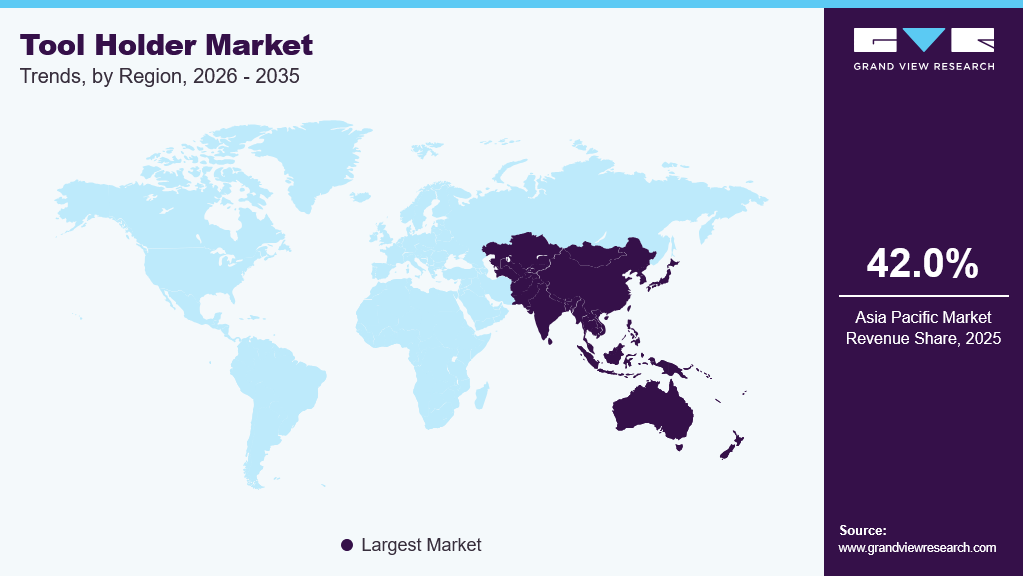
The global tool holder market size was valued at USD 1.4 billion in 2025 and is projected to grow from USD 1.5 billion in 2026 to USD 2.1 billion by 2035, at a CAGR of 4.2% from 2026 to 2035. Asia Pacific dominated the market, accounting for the largest revenue share of approximately 42.0% of revenue in 2025. The tool holder industry is a critical component of the precision machining ecosystem, enabling secure clamping and accurate positioning of cutting tools in CNC machines, machining centers, milling machines, lathes, and drilling equipment. Tool Holders directly influence machining accuracy, spindle performance, surface finish, and tool life, making them essential for high-precision manufacturing operations.
Key Market Trends & Insights
- By tool holder: The collet chucks segment accounted for the largest share of approximately 35.0% in 2025.
- By taper: The BT flange taper segment accounted for the largest share of approximately 52.0% in 2025.
- By end use: The automotive segment accounted for the largest share of approximately 32.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (42.0% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2035)
Market Size & Forecast
- Market size in 2025: USD 1.4 Billion
- Estimated market size in 2026: USD 1.5 Billion
- Projected market size by 2035: USD 2.1 Billion
- CAGR (2026-2035): 4.2%
Prism AI by Grand View Research Free to tryAsk a question about the tool holder marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Constant developments in CNC technology, high-speed machining, and multi-axis manufacturing have raised the need for tool holder systems that can effectively minimize vibrations, improve concentricity, and operate at faster spindle speeds. Tool holders such as hydraulic, shrink-fit, and precision collet tool holders have gained popularity to meet the demands of modern manufacturing industries, where precise machining and cutting are essential.
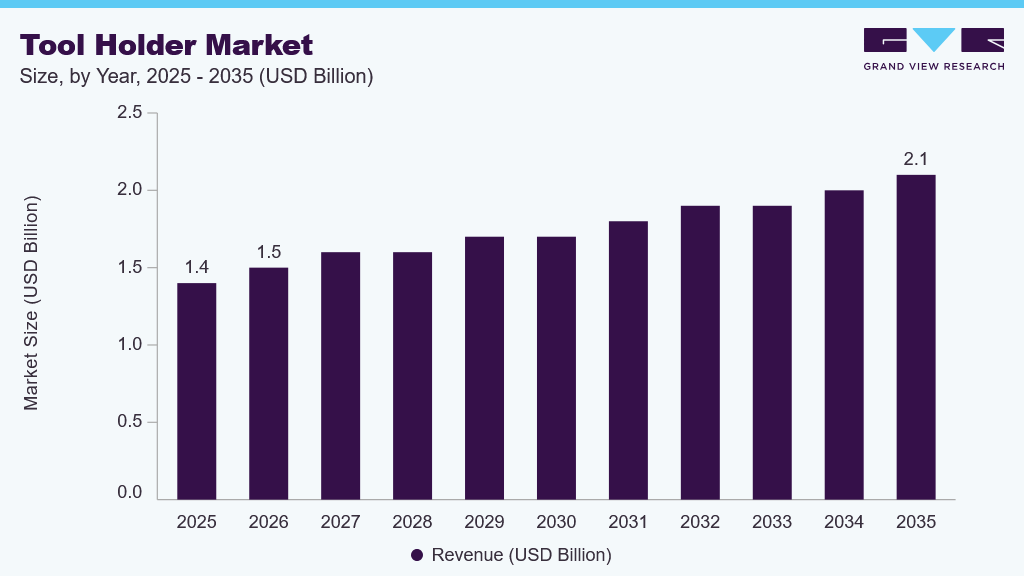 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The demand for tool holders is highly dependent on growth in the manufacturing of automobiles, aircraft, industrial machinery, medical devices, and electronic goods. The widespread adoption of automation, Industry 4.0 technologies, and smart manufacturing is encouraging manufacturers to invest in high-performance tooling systems to enhance productivity and reduce machine downtime. Asia Pacific remains the leading production and consumption hub due to its extensive manufacturing base, expanding CNC machine installations, and strong investments in industrial modernization. Meanwhile, developed economies continue to focus on advanced machining solutions for high-value components used in aerospace, defense, and precision engineering applications.
The market prospects continue to look favorable due to manufacturers' increasing emphasis on efficient machining, process reliability, and cost-effectiveness. The increasing use of electric cars, lightweight materials in aerospace applications, and metal products with intricate designs is creating the need for specialized tool holders that can provide better rigidity and accuracy. Digital tool management, predictive maintenance, and automated tool changes are among the features contributing to greater efficiency in manufacturing units. With the increasing importance of precision engineering in all industries, the future growth prospects of the tool holder market look bright.
Analyst Perspective
The tool holder market is expected to maintain steady growth as manufacturers increasingly prioritize productivity, machining accuracy, process stability, and overall equipment utilization. Rising investments in CNC machining centers, automated production lines, and flexible manufacturing systems are driving demand for advanced tool-holding solutions that deliver high rigidity, concentricity, repeatability, and stability at elevated spindle speeds. The continued adoption of high-speed machining and multi-axis operations is further encouraging manufacturers to develop tool holders with improved vibration damping, balancing characteristics, thermal stability, and service life. Asia Pacific is expected to remain a key growth market, supported by expanding manufacturing capacity, increasing CNC machine installations, and ongoing investments in industrial automation and modernization.
Tool Holder Insights
The collet chucks segment accounted for the largest share of approximately 35.0% of the global tool holder market in 2025. The primary factors driving growth are their versatility, precise clamping capability, and high compatibility with CNC machine centers. The use of collet chucks is very common in activities such as milling, drilling, reaming, and finishing in industries including the automobile, general engineering, electronics, and metals processing industries. The ability of collet chucks to accommodate tools of different sizes and maintain concentricity at relatively low cost makes them the perfect solution for mass production and precision operations. The increase in CNC machine capabilities worldwide has led to a greater need for collet chucks. For instance, in 2024, BIG DAISHOWA introduced additional sizes and configurations for its MEGA NEW BABY CHUCK series, a precision-ground and balanced offering for high-speed machining. All components, including the body, collet, nut, and clamping wrench, are specifically designed for high-speed applications.
The hydraulic tool holders segment is projected to register the fastest growth during the forecast period. Driven by their superior qualities, such as better vibration-damping capacity, accurate run-out performance, and the capability of increasing the longevity of cutting tools during high-speed machining. These tools have been gaining popularity across sectors such as aerospace, automotive, medical devices, and precision engineering, where micron-level accuracy is critical. The hydraulic system employed by these holders helps reduce tool deflection while ensuring stable machining performance, making them ideal for machining difficult materials and geometries. With increased investments in CNC machining technology, these holders will see rising demand in the coming years.
Taper Insights
The BT (BTMAS) flange taper tool holders segment accounted for the largest share of approximately 52.0% of the global tool holder market in 2025, due to the extensive use of such tool holders in CNC machine tools in the Asia Pacific region, which is the largest manufacturing center in the world. BT tool holders offer high rigidity, strong tool-holding capability, and broad adaptability in milling and drilling operations; therefore, they are widely used in the automotive industry, industrial machinery, molds and dies, and general engineering sectors. Standardization of these tool holders allows their easy interchangeability, facilitating high-production activities. The installation of more and more CNC machines in developing countries adds value to the demand for BT flange tapers.
The HSK (hollow shank taper) segment is expected to experience the fastest growth during the forecast period due to its superior performance in high-speed, high-precision machining environments. Contrary to conventional taper systems, HSK holders provide simultaneous face and taper contact, resulting in greater rigidity, improved concentricity, and enhanced stability at high spindle speeds. These advantages make HSK the preferred choice for aerospace, medical device manufacturing, precision engineering, and automated production lines. The rising adoption of multi-axis CNC machining centers, Industry 4.0 technologies, and advanced manufacturing processes is expected to significantly accelerate demand for HSK tool-holding systems.
End Use Insights
The automotive segment accounted for the largest share of approximately 32.0% of the global market in 2025, owing to the heavy use of CNC machining in the production of engine parts, transmission systems, chassis components, electric vehicle parts, and metal assemblies. Tool holders are extremely important for machining accuracy and efficiency, as well as consistent dimensions during mass production. Growing production investments in the electric vehicle industry, light-weight materials, and automation of manufacturing processes are adding additional impetus to the demand for efficient tool holders. Modernization of automotive manufacturing plants across the globe will help the segment retain its market leadership position.
The aerospace & defense segment is projected to register the fastest growth during the forecast period, owing to the increasing manufacture of commercial aircraft, military systems, and space parts that require high machining precision. Advanced materials such as titanium alloys, nickel superalloys, and carbon composites require stiff and vibration-free tool holders to ensure excellent surface finish and accuracy. There are increasing investments in five-axis machining, automation, and precision engineering, accelerating the adoption of high-end hydraulic and HSK tool holders.
Regional Insights
The Asia Pacific tool holder industry accounted for the largest market share of approximately 42.0% in 2025, partly due to the robust manufacturing industry in the region, widespread use of CNC machine tools, and the rising emphasis on industrial automation in the region. China, Japan, India, South Korea, and Taiwan have been the major players in this market because of the well-established automotive, electronics, aerospace, and precision engineering industries present in the region. The existence of some big machine tool manufacturers, besides the presence of a robust value chain for cutting tools and accessories, makes this market more attractive.
 To learn more about this report, Download Free Sample Report
North America Tool Holder Market Trends
The tool holder industry in North America is anticipated to witness significant growth during the forecast period, supported by rising investments in aerospace, defense, medical device manufacturing, and high-value industrial machining. The region is rapidly adopting advanced CNC machining centers, digital manufacturing technologies, and automated production systems that require high-performance tool holders with superior precision and rigidity. Increasing demand for lightweight aerospace components, electric vehicle parts, and complex medical implants is further driving the adoption of hydraulic and HSK tool holding solutions. Continued investments in smart factories and advanced manufacturing capabilities are expected to accelerate market expansion across the region.
Key Tool Holder Company Insights
The global tool holder market is characterized by the presence of established precision tooling manufacturers competing through continuous product innovation, advanced engineering, and global distribution networks. Leading companies are focusing on high-precision hydraulic, shrink-fit, and HSK tool holders, while investing in smart tooling technologies, automation-compatible solutions, and strategic partnerships to strengthen their position in the rapidly evolving precision machining and advanced manufacturing landscape.
Key Tool Holder Companies
The following key companies have been profiled for this study on the tool holder market:
-
BIG DAISHOWA Seiki Co., Ltd.
-
Haimer GmbH
-
SCHUNK SE & Co. KG
-
REGO-FIX AG
-
Sandvik Coromant
-
Kennametal Inc.
-
BIG Kaiser Precision Tooling Inc.
-
NT Tool Corporation
-
MST Corporation
-
MAPAL Dr. Kress KG
Recent Developments
-
July 2025, Mastercam released Mastercam 2026, introducing an enhanced mill tool holder designer, improved tool management, and AI-enabled CAM intelligence to simplify tool assembly, reduce programming time, and improve machining efficiency, supporting broader adoption of advanced tool holder systems in CNC manufacturing
-
September 2024, Kennametal Inc. announced the expansion of its comprehensive product line of tooling and wear protection solutions for mining applications. The new additions include picks to meet diverse customer demands as well as an innovative round drill steel system designed to improve efficiency and safety.
Tool Holder Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.4 billion
Estimated market size in 2026
USD 1.5 billion
Projected market size by 2035
USD 2.1 billion
Growth rate
CAGR of 4.2% from 2026 to 2035
Base year for estimation
2025
Actual data
2021 – 2024
Forecast period
2026 – 2035
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2035
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Tool holder, taper, end use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; Japan; India; Australia; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE.
Key companies profiled
BIG DAISHOWA Seiki Co., Ltd.; Haimer GmbH; SCHUNK SE & Co. KG; REGO-FIX AG; Sandvik Coromant, Kennametal Inc.; BIG Kaiser Precision Tooling Inc.; NT Tool Corporation; MST Corporation; MAPAL Dr. Kress KG.
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Tool Holder Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2035. For this study, Grand View Research has segmented the global tool holder market report based on tool holder, taper, end use, and region:
-
Tool Holder Outlook (Revenue, USD Billion, 2021–2035)
-
Collet Chucks
-
Hydraulic Tool Holders
-
Shrink Fit Tool Holders
-
Milling Chucks
-
Others
-
-
Taper Outlook (Revenue, USD Billion, 2021–2035)
-
BT Flange Taper
-
CAT (V-Flange) Taper
-
HSK (Hollow Shank) Taper
-
SK Taper
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021–2035)
-
Automotive
-
Aerospace & Defense
-
General Machining & Fabrication
-
Electronics
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2035)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Frequently Asked Questions About This Report
The global tool holder market size was valued at USD 1.4 billion in 2025 and is estimated at USD 1.5 billion for 2026.
The global tool holder market is expected to grow at a CAGR of 4.2% from 2026 to 2035, reaching USD 2.1 billion.
Asia Pacific dominated with approximately 42.0% revenue share in 2025.
The collet chucks segment accounted for the largest revenue share of approximately 35.0% in 2025.
Key players in the market include BIG DAISHOWA Seiki Co., Ltd., Haimer GmbH, SCHUNK SE & Co. KG, REGO-FIX AG, Sandvik Coromant, Kennametal Inc., BIG Kaiser Precision Tooling Inc., NT Tool Corporation, MST Corporation, MAPAL Dr. Kress KG, Seco Tools AB, ISCAR Ltd., CERATIZIT S.A., Tungaloy Corporation, YG-1 Co., Ltd.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


