
- Home
- »
- Consumer F&B
- »
-
UK Premium Bottled Water Market Size Report, 2026-2033GVR Report cover

UK Premium Bottled Water Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Still Water, Sparkling Water), By Price Point (Premium, Super- Premium), By Packaging Type, By Distribution Channel, By Pack Size, By Pack Type, And Segment Forecasts
Market Size, 2025
$3.0BMarket Estimate, 2026
$3.1BMarket Forecast, 2033
$4.1BCAGR, 2026–2033
4.1%UK Premium Bottled Water Market Summary
The UK premium bottled water market size was valued at USD 3.0 billion in 2025 and is projected to grow from USD 3.1 billion in 2026 to USD 4.1 billion by 2033, at a CAGR of 4.1% from 2026 to 2033. The industry is driven by rising health, fitness, and wellness participation, with increasing demand for high-quality, convenient hydration as an alternative to sugary beverages. Premiumization and sustainability trends are further supporting growth, with consumers seeking natural mineral content, source provenance, sparkling and functional options, and premium yet environmentally conscious packaging.
Key Market Trends & Insights
- By product: Still water segment led the market and accounted for a share of 30.3% in 2025.
- By price point: Premium segment accounted for a share of 58.6% in 2025.
- By packaging type: PET bottles segment led the market and accounted for a share of 53.3% in 2025.
- By distribution channel: Off-premise segment dominated the market, accounting for a 58.1% share in 2025.
Market Size & Forecasts
- Market Size in 2025: USD 3.0 Billion
- Estimated Market Size in 2026: USD 3.1 Billion
- Projected Market Size by 2033: USD 4.1 Billion
- CAGR (2026-2033): 4.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The UK consumers are treating premium bottled water as a lifestyle beverage rather than a basic hydration product, supported by growing emphasis on health, fitness, wellness, and beverage quality. Active lifestyles are creating frequent hydration occasions, while consumers are seeking alternatives to sugary beverages that offer purity, natural mineral content, source credibility, convenience, and a premium drinking experience. This supports demand for natural mineral and spring waters, as well as sparkling and functional variants and convenient single-serve formats across gyms, workplaces, travel, dining, and other on-the-go occasions.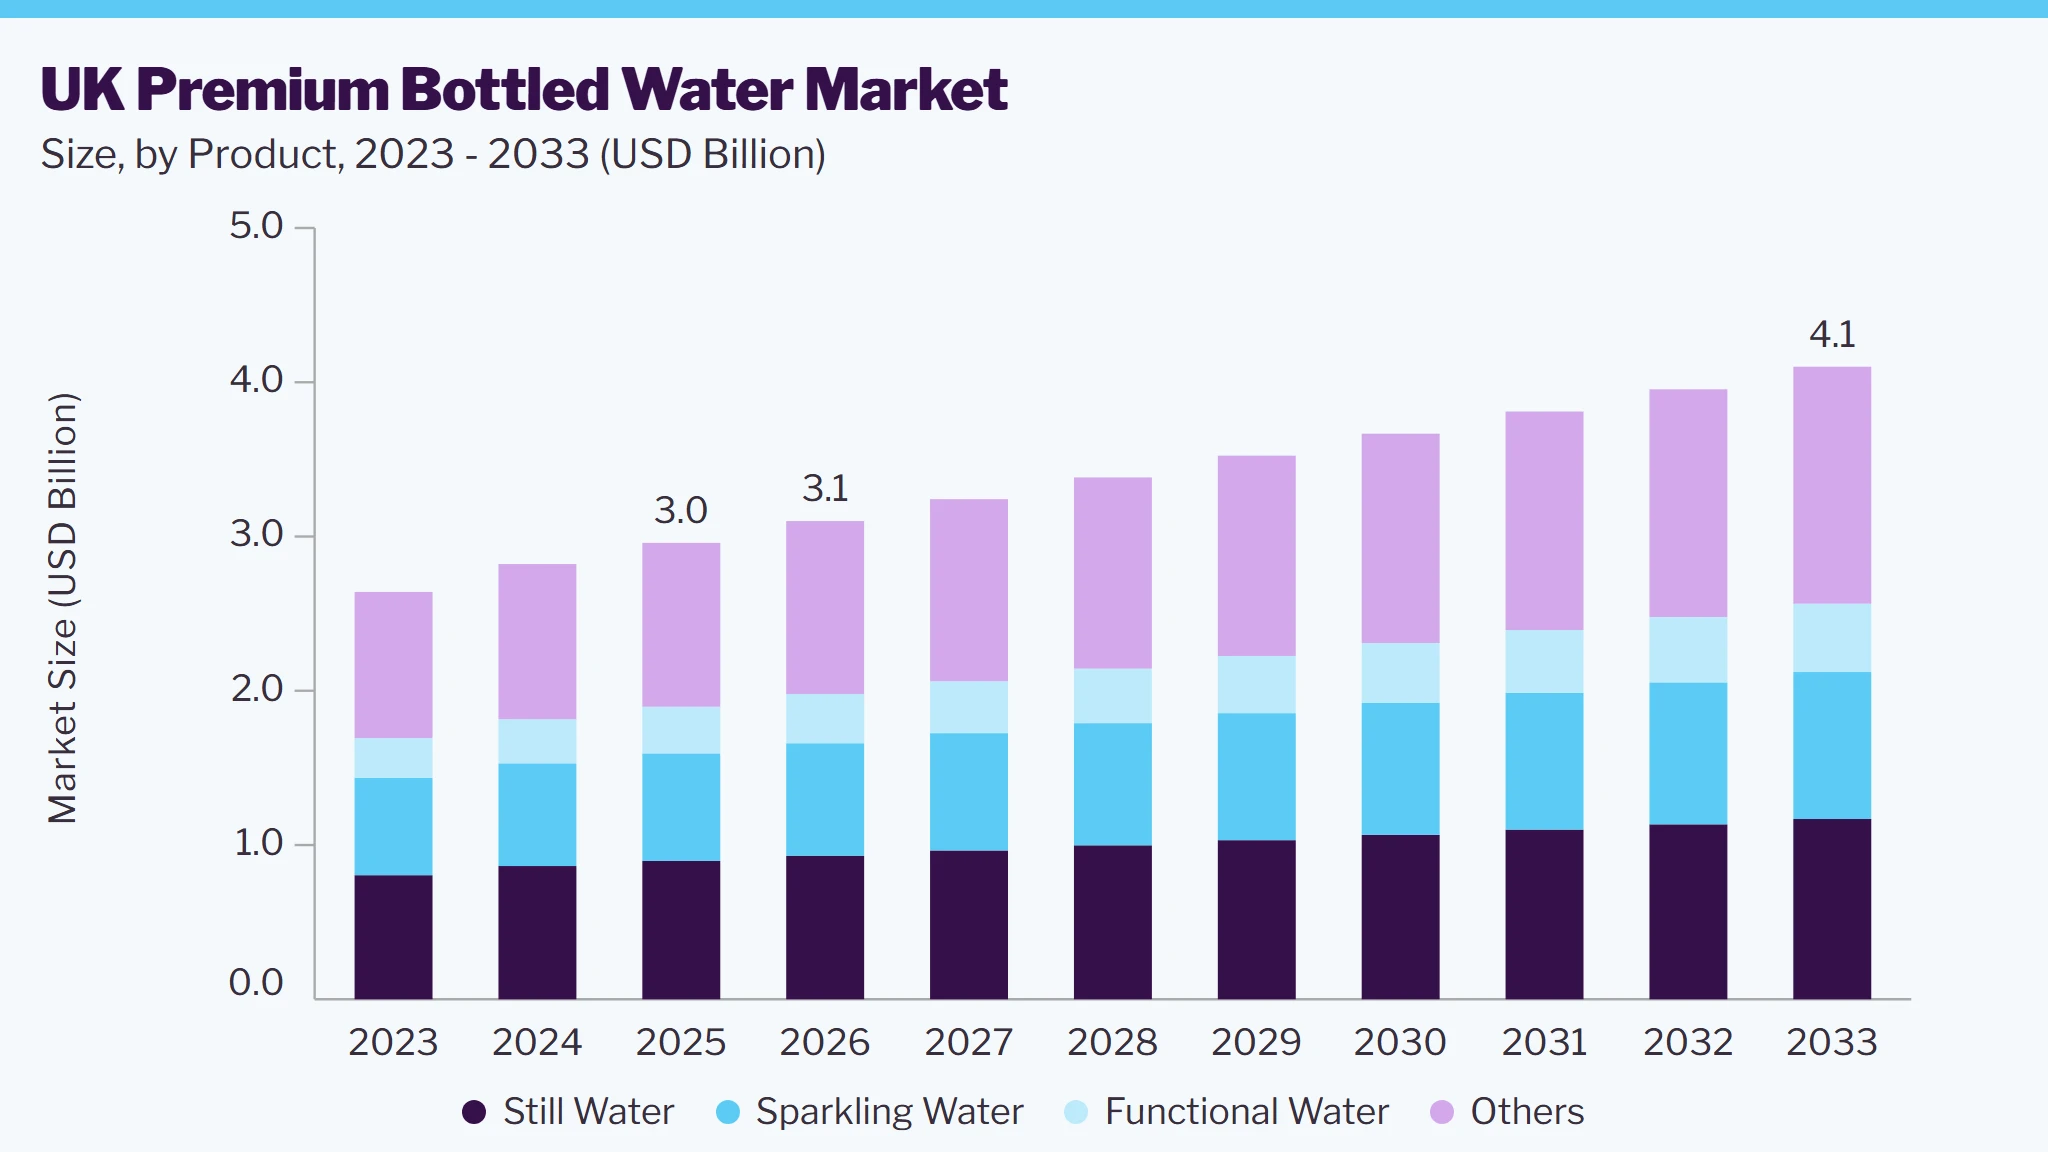 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
At the same time, premiumization is being linked with sustainability, as consumers expect premium products to combine superior quality with responsible packaging. This is encouraging manufacturers to explore recycled PET, lightweight materials, glass, refillable formats, and other packaging solutions with stronger environmental credentials. The UK’s established hospitality and foodservice sector further supports premium bottled water consumption, where distinctive products can enhance dining and guest experiences. Manufacturers are consequently competing through source provenance, mineral composition, functional and sparkling propositions, innovative packaging, sustainability credentials, and premium brand positioning, expanding bottled water’s role from basic hydration to a differentiated lifestyle and hospitality product.
UK bottled water volume sales, million liters
Years
YoY Growth%
2021
6.9%
2022
3.5%
2023
6.0%
2024
4.2%
2025
3.3%
Source: British Soft Drinks Association
 To learn more about this report, Download Free Sample Report
Consumer Insights
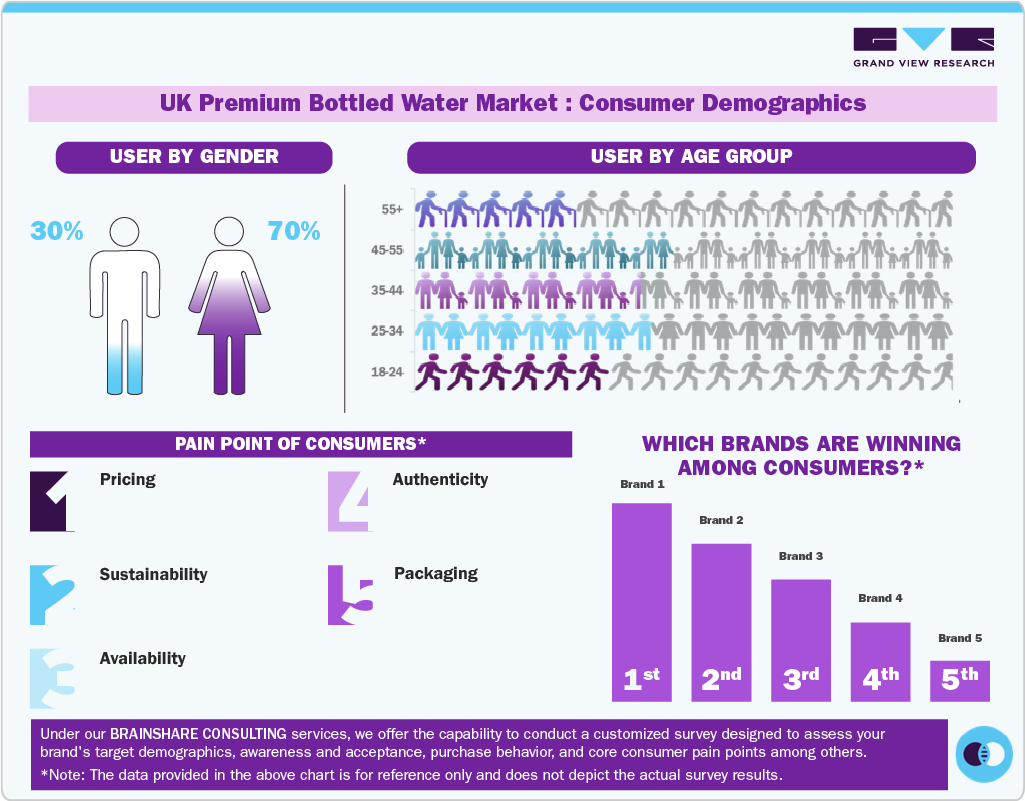
According to Sport England’s Active Lives Adult Survey 2024-25, 64.6% of adults in England achieved at least 150 minutes of moderate-intensity physical activity per week, highlighting a substantial active consumer base and supporting regular demand for convenient hydration. Consumers are also becoming more selective about water quality, mineral content, source provenance, packaging, and brand image, while premium water is increasingly positioned as a healthier and more sophisticated alternative to sugary beverages. This is driving interest in natural mineral, sparkling, functional, convenient, and sustainably packaged waters across fitness, travel, hospitality, dining, and everyday wellness occasions.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The industry is driven by consumer demand for better-quality and more varied hydration options, with health, natural mineral content, taste, and brand image influencing purchase decisions. Consumers are showing greater interest in water that offers flavor and wellness benefits rather than plain hydration, creating opportunities for brands to differentiate their products and support higher price points through added value. For instance, in January 2026, eauYES launched in the UK with six flavored sparkling mineral-water variants, combining naturally mineral-rich water with natural flavors, no sugar, and no calories. The launch shows how brands respond to demand for healthier, flavor-led alternatives to traditional soft drinks while strengthening premium positioning.
The industry is subject to The Natural Mineral Water, Spring Water and Bottled Drinking Water (England) Regulations 2007, as amended, which govern the sourcing, treatment, bottling, classification, and labelling of packaged water. Natural mineral water must meet specific requirements relating to official recognition, purity, and consistent composition, while prescribed product and source information must be provided on labels. These requirements can increase testing, quality-control, recognition, and labelling costs, particularly for premium brands relying on natural-source and mineral-content claims.
The market offers opportunities through sustainable packaging, premium hospitality, and source-led differentiation. Consumers and hospitality operators are increasingly seeking alternatives to single-use bottles, creating space for brands that combine quality with more circular delivery models. For instance, in 2026, British spring-water brand Elder Water launched a refillable glass-bottle system for hospitality, collecting, washing, refilling, and redelivering bottles to restaurants, pubs, and hotels. The model demonstrates how brands can build premium value around British source provenance, reusable packaging, and lower-waste consumption, while creating a differentiated proposition for the hospitality channel.
Analyst Perspective
The market is driven by premiumization, health awareness, convenience, sustainability, and demand from hospitality and foodservice channels. Consumers evaluate products based on source provenance, mineral composition, taste, packaging quality, brand reputation, and environmental performance, viewing premium water as an elevated lifestyle choice rather than a basic beverage. Manufacturers are responding through distinctive source-led positioning, sparkling and differentiated variants, premium glass and recyclable packaging, and innovative formats. Going forward, market growth is expected to favor experience-led products, sustainable solutions, premium packaging, and differentiated offerings that can substantiate higher price points.
Product Insights
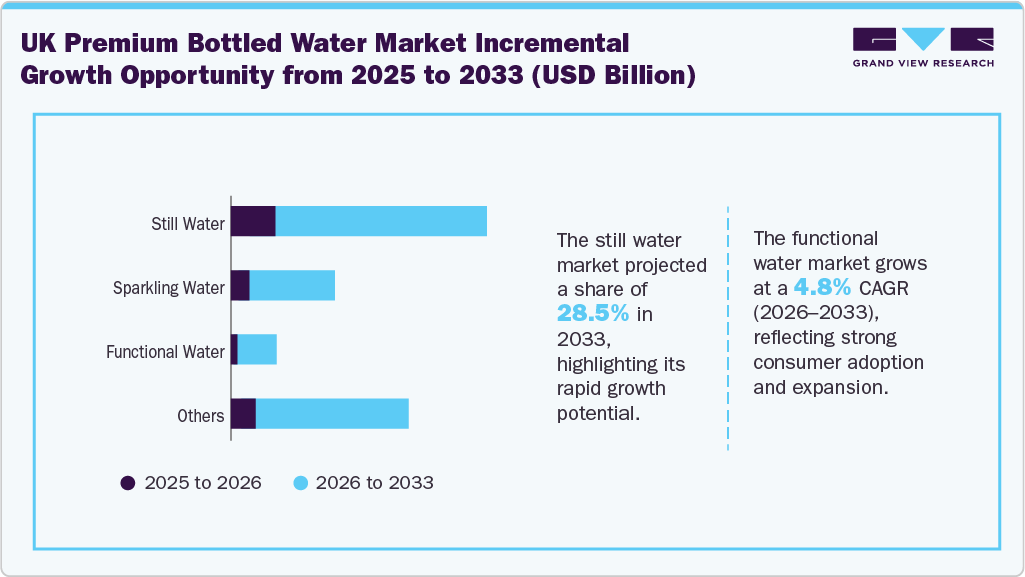
The still water segment accounted for the largest share of 30.3% in 2025, supported by broad consumer acceptance of still water as a convenient, sugar-free, and versatile hydration option across retail, fitness, workplaces, travel, dining, and hospitality. The segment is also benefiting from product innovation and premiumization, as manufacturers introduce differentiated formats and flavor profiles to attract health-conscious consumers while retaining the core benefits of water. For instance, in July 2025, Highland Spring expanded its flavored still-water range with Juicy Strawberry, Apple & Blackcurrant, and Lemon & Lime variants, all sugar-free and made with Scottish spring water from the Ochil Hills. The launch demonstrates how established brands are broadening the still-water proposition through flavor innovation and healthier positioning, creating additional consumption occasions while maintaining natural-source credentials.
 To learn more about this report, Download Free Sample Report
The functional segment is projected to record the fastest CAGR of 4.8% from 2026 to 2033, driven by increasing consumer demand for hydration products that deliver added health and wellness benefits beyond conventional hydration. Growing attention to preventive health, functional nutrition, and convenient wellness solutions is encouraging consumers to seek beverages fortified with vitamins, minerals, electrolytes, and other functional ingredients. For instance, in March 2026, Volvic entered the UK functional water category with the launch of its Vitamin+ range, combining mineral water with added vitamins and minerals, reflecting the growing shift toward health-focused and value-added hydration solutions.
Price Point Insights
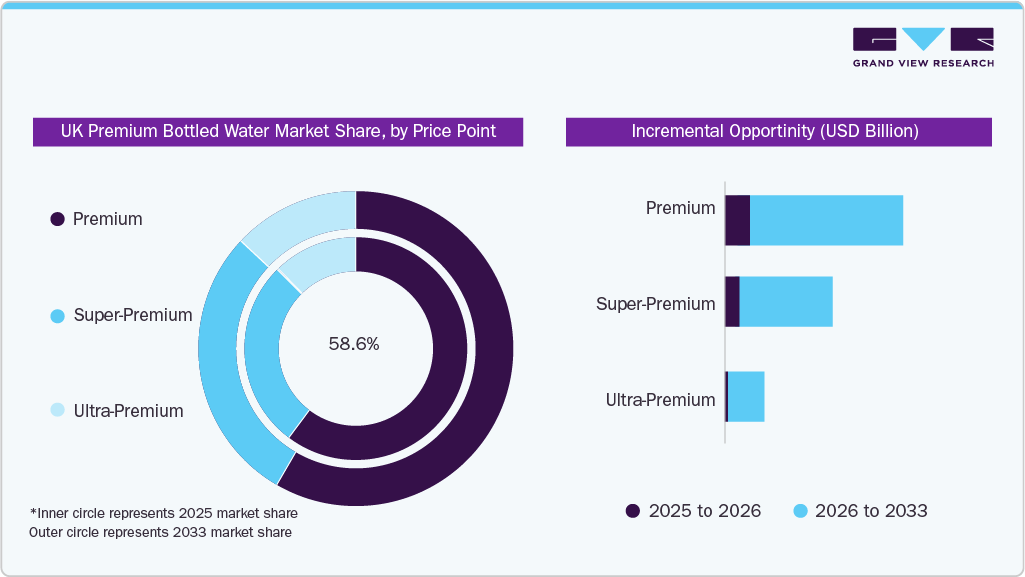
The premium segment accounted for the largest share of 58.6% in 2025. Premium products benefit from their accessibility across supermarkets, restaurants, cafés, workplaces, and fitness-oriented consumption occasions, making them attractive to consumers who want an elevated alternative to standard bottled water without entering the luxury price tier. Demand is also being supported by growing interest in sparkling varieties, natural and mineral waters, convenient premium formats, and environmentally responsible packaging, while brands are using source stories, recognizable quality credentials, packaging innovation, and product differentiation to strengthen perceived value.
 To learn more about this report, Download Free Sample Report
The ultra-premium segment is projected to record the fastest CAGR of 4.8% from 2026 to 2033. The ultra-premium segment is driven by increasing consumer willingness to pay for exceptional source provenance, mineral quality, exclusivity, distinctive packaging, and elevated brand experiences. Growth is further supported by ultra-premium hospitality, fine dining, luxury retail, and wellness consumption, where consumers associate ultra-premium water with quality, status, and sophisticated lifestyles. Brands are strengthening this positioning through rare or prestigious water sources, premium glass bottles, refined visual identities, limited-edition offerings, and sustainability-led packaging, enabling differentiation beyond basic hydration and supporting higher price points.
Packaging Type Insights
The PET segment held the largest share of 53.3% in 2025. Its leading position reflects the widespread use of PET for everyday and active hydration, supported by its low weight, shatter resistance, easy storage, and suitability for a wide range of pack sizes. These characteristics enable premium water brands to serve diverse consumption occasions, from convenience retail and workplaces to gyms, travel, and food service. The shift toward recycled materials is further improving the sustainability profile of PET without materially changing consumer experience. For instance, in April 2026, Highland Spring launched its Summer Berries and Orange & Passionfruit flavored still-water range in recyclable PET bottles, available in 1.25-liter formats and, for Orange & Passionfruit, a 750 mL format. The launch highlights how UK bottled-water manufacturers are leveraging PET to combine convenience, recyclability, and product innovation, while expanding consumption occasions through differentiated flavor offerings.
To learn more about this report, Download Free Sample Report The cans segment is projected to record the fastest CAGR of 4.7% from 2026 to 2033, reflecting increasing interest in alternative packaging formats that combine portability, durability, recyclability, and contemporary visual appeal. Aluminum cans are particularly suited to sparkling and flavored water products, offering a distinctive format for consumers seeking alternatives to traditional plastic bottles and allowing brands to compete more directly within the broader premium soft-drinks landscape. The format is gaining relevance across social occasions, leisure, hospitality, events, and impulse purchases, where compact packaging and strong shelf presence can influence product choice. For instance, in February 2026, Maison Perrier launched in the UK with its Forever range of sugar-free flavored sparkling waters in 330 mL cans, alongside its unflavored sparkling water offering. The launch highlights how premium water brands are using the can format to deliver convenience, sophisticated positioning, and flavor-led differentiation while expanding water into premium soft-drink occasions.
Pack Size Insights
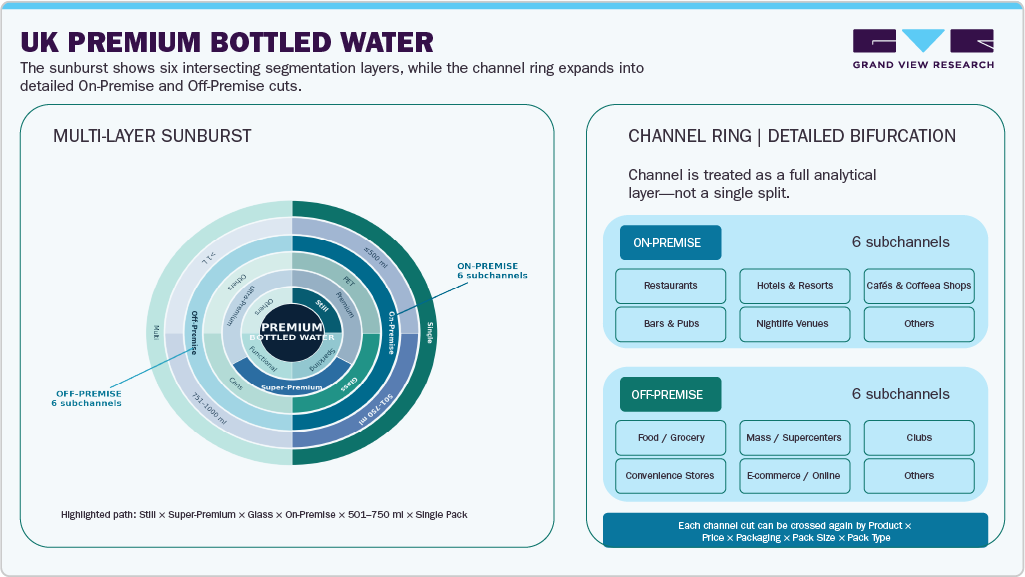
The up to 500 mL segment led the market, representing 41.7% of revenue in 2025. The market is supported by strong demand for portable, single-serve formats suited to on-the-go hydration. Compact bottles are particularly convenient for fitness, commuting, travel, workplaces, hospitality, and outdoor activities, while their portion size supports controlled consumption and easy handling. Premium brands are also using smaller formats to strengthen product accessibility through distinctive packaging, premium materials, and recyclable PET or glass options, enabling consumers to access premium water across a wider range of everyday and lifestyle occasions. For instance, in May 2025, Re: Water launched a 330 mL premium aluminum bottle in the UK, available in both still and sparkling formats, offering a smaller, reusable and recyclable alternative to conventional plastic bottles. The launch reflects the premium segment’s focus on distinctive packaging, sustainability, convenience, and value-added brand positioning.
The 501-750 mL segment is projected to register a CAGR of 4.1% from 2026 to 2033. Growth is supported by consumer preference for mid-sized formats that provide greater hydration capacity while remaining practical for individual consumption. These bottles are well-suited to outdoor activities, travel, fitness, dining, hospitality, and extended periods away from home, offering a balance between portability and volume. Premium brands are responding by expanding into larger single-serve formats that combine functionality with elevated presentation.
Pack Type Insights
The multi-packs segment held the largest position in the market, representing 63.5% of revenue in 2025. Its dominance is supported by the growing preference for value-oriented bulk purchases, household stocking, and regular consumption, particularly among consumers who purchase bottled water for home, workplace, and family use. Multi-pack formats provide greater convenience and reduce the frequency of individual purchases, making them well-suited to routine hydration needs. Demand is further supported by the availability of multi-packs across supermarkets, hypermarkets, wholesale outlets, and online grocery platforms.
The single pack segment is projected to register a CAGR of 3.5% from 2026 to 2033. Growth is supported by increasing demand for convenient, ready-to-consume hydration across commuting, travel, fitness, workplace, and leisure occasions. Single-pack formats allow consumers to purchase premium water according to immediate consumption needs while providing greater portability and ease of handling. Growth is further supported by the expansion of premium bottled water across food service, hospitality, convenience retail, and on-the-go consumption channels.
Distribution Channel Insights
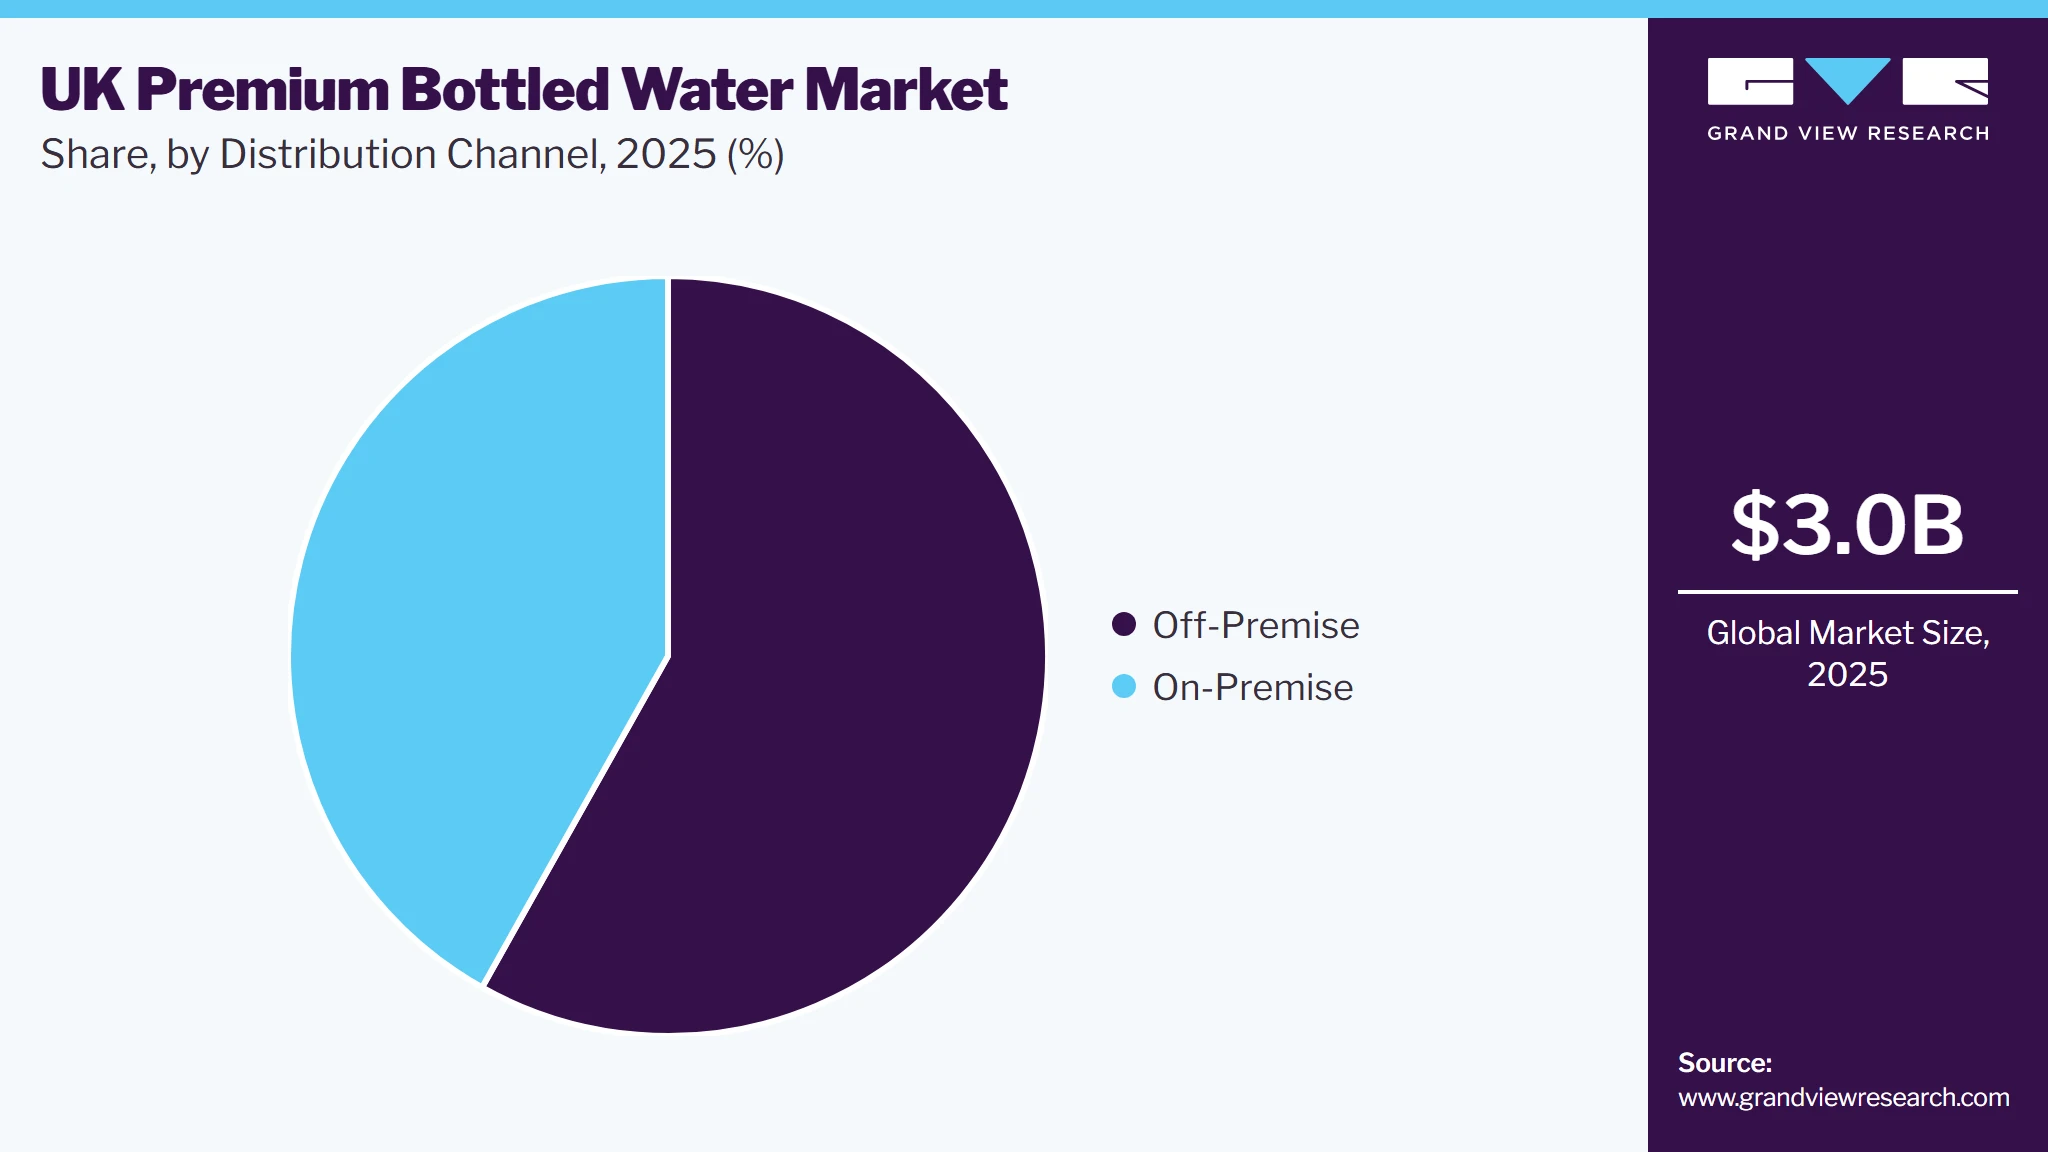
The off-premise segment accounted for the largest share of 58.1% in 2025, supported by the extensive reach of supermarkets, convenience stores, wholesalers, and other retail outlets. These channels provide consumers with convenient access to premium water for home, work, travel, fitness, and on-the-go consumption, while product innovation and broader distribution strengthen brand visibility and premium trade-up opportunities. For instance, in July 2025, Highland Spring expanded nationwide distribution of its Flavors range across independent retailers, convenience stores, and wholesalers, offering three sugar-free flavored still-water variants. The rollout highlights how retail expansion and differentiated products are helping brands capture evolving consumer preferences and broaden premium-water consumption occasions.
 To learn more about this report, Download Free Sample Report
The on-premise segment is projected to register the fastest CAGR of 4.4% from 2026 to 2033, supported by the UK’s expanding luxury hospitality, fine-dining, and premium foodservice sectors. Premium bottled water is being integrated into the overall dining and guest experience, with hotels and restaurants favoring products that offer high quality, distinctive sourcing, premium presentation, and sustainable packaging. The strong growth of upscale hospitality also creates opportunities for exclusive water partnerships and locally bottled solutions tailored to hotel and restaurant requirements. For instance, in 2025, Michelin-listed La Popote in Cheshire introduced a dedicated bottled-water menu featuring seven still and sparkling waters, positioning water as an experiential beverage alongside its food and wine offering. This development highlights the increasing premiumization of water within the UK hospitality sector and creates opportunities for higher-value products through distinctive sources, mineral profiles, presentation, and curated service.
Key UK Premium Bottled Water Company Insights
The UK premium bottled water industry is competitive, with established multinational brands and emerging premium players competing across retail, foodservice, hospitality, and e-commerce channels. Companies are focusing on product innovation, portfolio expansion, sustainable packaging, strategic partnerships, digital marketing, and channel expansion to strengthen market positioning.
 To learn more about this report, Download Free Sample Report
Key UK Premium Bottled Water Companies
The following key companies have been profiled for the study on the UK premium bottled water market
-
Highland Spring
-
Harrogate Spring Water
-
Belu
-
Hildon
-
Tŷ Nant
-
Radnor Hills
-
Brecon Carreg
-
Strathmore Water
-
Shepley Spring
-
Crag Spring Water
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Highland Spring, Harrogate Spring Water, Hildon, Belu, Tŷ Nant, Radnor Hills, Brecon Carreg, Strathmore Water)
- Expand premium bottled water portfolios through distinctive sources, premium packaging, sustainability initiatives, and broad retail and hospitality distribution.
- Strong brand recognition, established distribution, trusted sources, and premium positioning.
- Higher operating costs, regulatory pressures, and intense competition from private-label and specialist brands.
Emerging Players (Shepley Spring, Crag Spring Water)
- Target niche opportunities through flexible production, specialist offerings, differentiated sourcing, and selected retail or hospitality channels.
- Greater flexibility, customer-focused solutions, and differentiated product propositions.
- Limited brand awareness, distribution reach, production scale, and marketing resources.
Recent Developments
- In September 2025, Aqua Libra launched Blueberry & Pomegranate infused sparkling water alongside a refreshed portfolio and a refillable metal bottle, illustrating how brands are responding to demand for more distinctive, health-oriented, and sustainability-conscious beverage propositions.
UK Premium Bottled Water Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.0 billion
Estimated market size in 2026
USD 3.1 billion
Projected market size by 2033
USD 4.1 billion
Growth rate
CAGR of 4.1% from 2026 to 2033
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Volume, million liters; revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Volume & revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, price point, packaging type, distribution channel, pack size, pack type
Country scope
UK
Key companies profiled
Highland Spring; Harrogate Spring Water; Belu; Hildon; Tŷ Nant; Radnor Hills; Brecon Carreg; Strathmore Water; Shepley Spring; Crag Spring Water
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
UK Premium Bottled Water Market Report Segmentation
This report forecasts volume & revenue growth at the country level and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the UK premium bottled water market report on the basis of product, price point, packaging type, distribution channel, pack size, and pack type.
-
Product Outlook (Volume, Million Liters; Revenue, USD Billion, 2021 - 2033)
-
Still Water
-
Sparkling Water
-
Functional Water
-
Others
-
-
Price Point Outlook (Volume, Million Liters; Revenue, USD Billion, 2021 - 2033)
-
Premium
-
Super-Premium
-
Ultra-Premium
-
-
Packaging Type Outlook (Volume, Million Liters; Revenue, USD Billion, 2021 - 2033)
-
PET Bottles
-
Glass
-
Cans
-
Others
-
-
Distribution Channel Outlook (Volume, Million Liters; Revenue, USD Billion, 2021 - 2033)
-
On-Premise
-
Restaurants
-
Hotels & Resorts
-
Cafés & Coffee Shops
-
Bars & Pubs
-
Nightlife Venues
-
Others
-
-
Off-Premise
-
Food / Grocery
-
Mass (incl. supercenters)
-
Clubs
-
Convenience Stores
-
E-commerce / Online
-
Other
-
-
-
Pack Size Outlook (Volume, Million Liters; Revenue, USD Billion, 2021 - 2033)
-
Upto 500 ml
-
501-750 ml
-
751-1000 ml
-
Above 1 Liter
-
-
Pack Type Outlook (Volume, Million Liters; Revenue, USD Billion, 2021 - 2033)
-
Single Pack
-
Multi Pack
-
Research Methodology
The UK premium bottled water market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each UK premium bottled water segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Still Water
This segment includes the sales of premium still water, including natural spring water, mineral water, artesian water, and purified water without carbonation.
Sparkling Water
This segment includes the sales of premium sparkling water, including naturally sparkling and carbonated water products.
Functional Water
This segment includes the sales of premium water enhanced with functional ingredients, such as electrolytes, vitamins, minerals, antioxidants, and other nutrients intended to support hydration and wellness.
Others
This segment includes the sales of other premium bottled water products, including specialty water products differentiated by unique sourcing, processing, or formulation.
Estimation Model
01Consumption Profile Layer
02Market Reach Layer
03Innovation & Differentiation Layer
04Value Generation Layer
Who consumes premium bottled water?
Where are they sold?
How do brands differentiate?
How does consumption convert into market value?
Demand is supported by consumers seeking high-quality hydration, perceived purity, superior taste, natural mineral content, functional benefits, and premium experiences. Wellness awareness, convenience, and interest in sustainable consumption further influence purchasing preferences.
Products reach consumers through retail, e-commerce, restaurants, hotels, foodservice, and specialty channels, with distribution breadth supporting market penetration.
Brands differentiate through source provenance, mineral composition, functional benefits, sparkling formats, premium bottle designs, and sustainable packaging.
Revenue is generated through premium-priced product sales, supported by brand equity, differentiated offerings, packaging value, and consumer willingness to pay.
Customization Table
Client Request
Customization Delivered
Value Adds
Understand premium bottled water consumer preferences and purchasing behavior
Developed a U.K.-specific consumer assessment covering preferences for natural spring water, mineral content, source origin, purity, taste, packaging format, sustainability, and functional benefits. Evaluated purchasing behavior across supermarkets, convenience stores, specialty retailers, foodservice, and e-commerce.
Helps identify high-value consumer segments, key purchase drivers, and attributes that support premium pricing and brand differentiation in the U.K. market.
Benchmark competitive positioning of leading premium bottled water brands
Assessed major U.K. and international brands based on water source, product positioning, packaging, price point, brand image, sustainability initiatives, distribution footprint, and product portfolio. Evaluated how brands differentiate through provenance, purity, functionality, and premium packaging.
Provides a structured competitive benchmark to identify positioning gaps, whitespace opportunities, and potential strategies for strengthening market presence
Identify emerging product categories and innovation opportunities
Evaluated emerging trends, including still water, sparkling water, functional water and other premium water categories. Assessed innovation around ingredients, packaging, sourcing, and consumer experience.
Supports identification of high-potential product opportunities and innovation pathways aligned with evolving U.K. preferences for health, wellness, convenience, sustainability, and premium experiences.
Frequently Asked Questions About This Report
Off-Premise channels accounted for the largest revenue share in 2025, while On-Premise channels are expected to be the fastest-growing segment.
Multi pack bottled water accounted for the largest revenue share in 2025 while single pack bottled water are expected to be the fastest-growing segment.
Key players include Highland Spring; Harrogate Spring Water; Belu; Hildon; Tŷ Nant; Radnor Hills; Brecon Carreg; Strathmore Water; Shepley Spring; Crag Spring Water
Demand is supported by interest in products perceived to offer greater purity, distinctive mineral profiles, natural or protected sources, and added functional benefits.
Still water dominated the U.K. premium bottled water market, accounting for a 30.3% revenue share in 2025, while the functional water is expected to register the fastest growth during the forecast period.
Premium priced bottled water accounted for the largest revenue share in 2025, while ultra-premium priced bottled water are expected to be the fastest-growing segment.
PET bottles accounted for the largest revenue share in 2025, while cans are expected to be the fastest-growing segment.
The U.K. premium bottled water market size was valued at USD 3.0 billion in 2025 and is estimated to reach USD 3.1 billion in 2026.
The U.K. premium bottled water market is expected to grow at a CAGR of 4.1% from 2026 to 2033, reaching USD 4.1 billion by 2033.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


