
- Home
- »
- Renewable Energy
- »
-
Underground Hydrogen Storage Market Size Report, 2033GVR Report cover

Underground Hydrogen Storage Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Porous Media Storage, Salt Caverns, Engineered Cavities), By Region (North America, Europe, Asia Pacific, Latin America, MEA), And Segment Forecasts
Market Size, 2025
$3.1BMarket Estimate, 2026
$3.4BMarket Forecast, 2033
$6.2BCAGR, 2026–2033
9.0%Underground Hydrogen Storage Market Summary
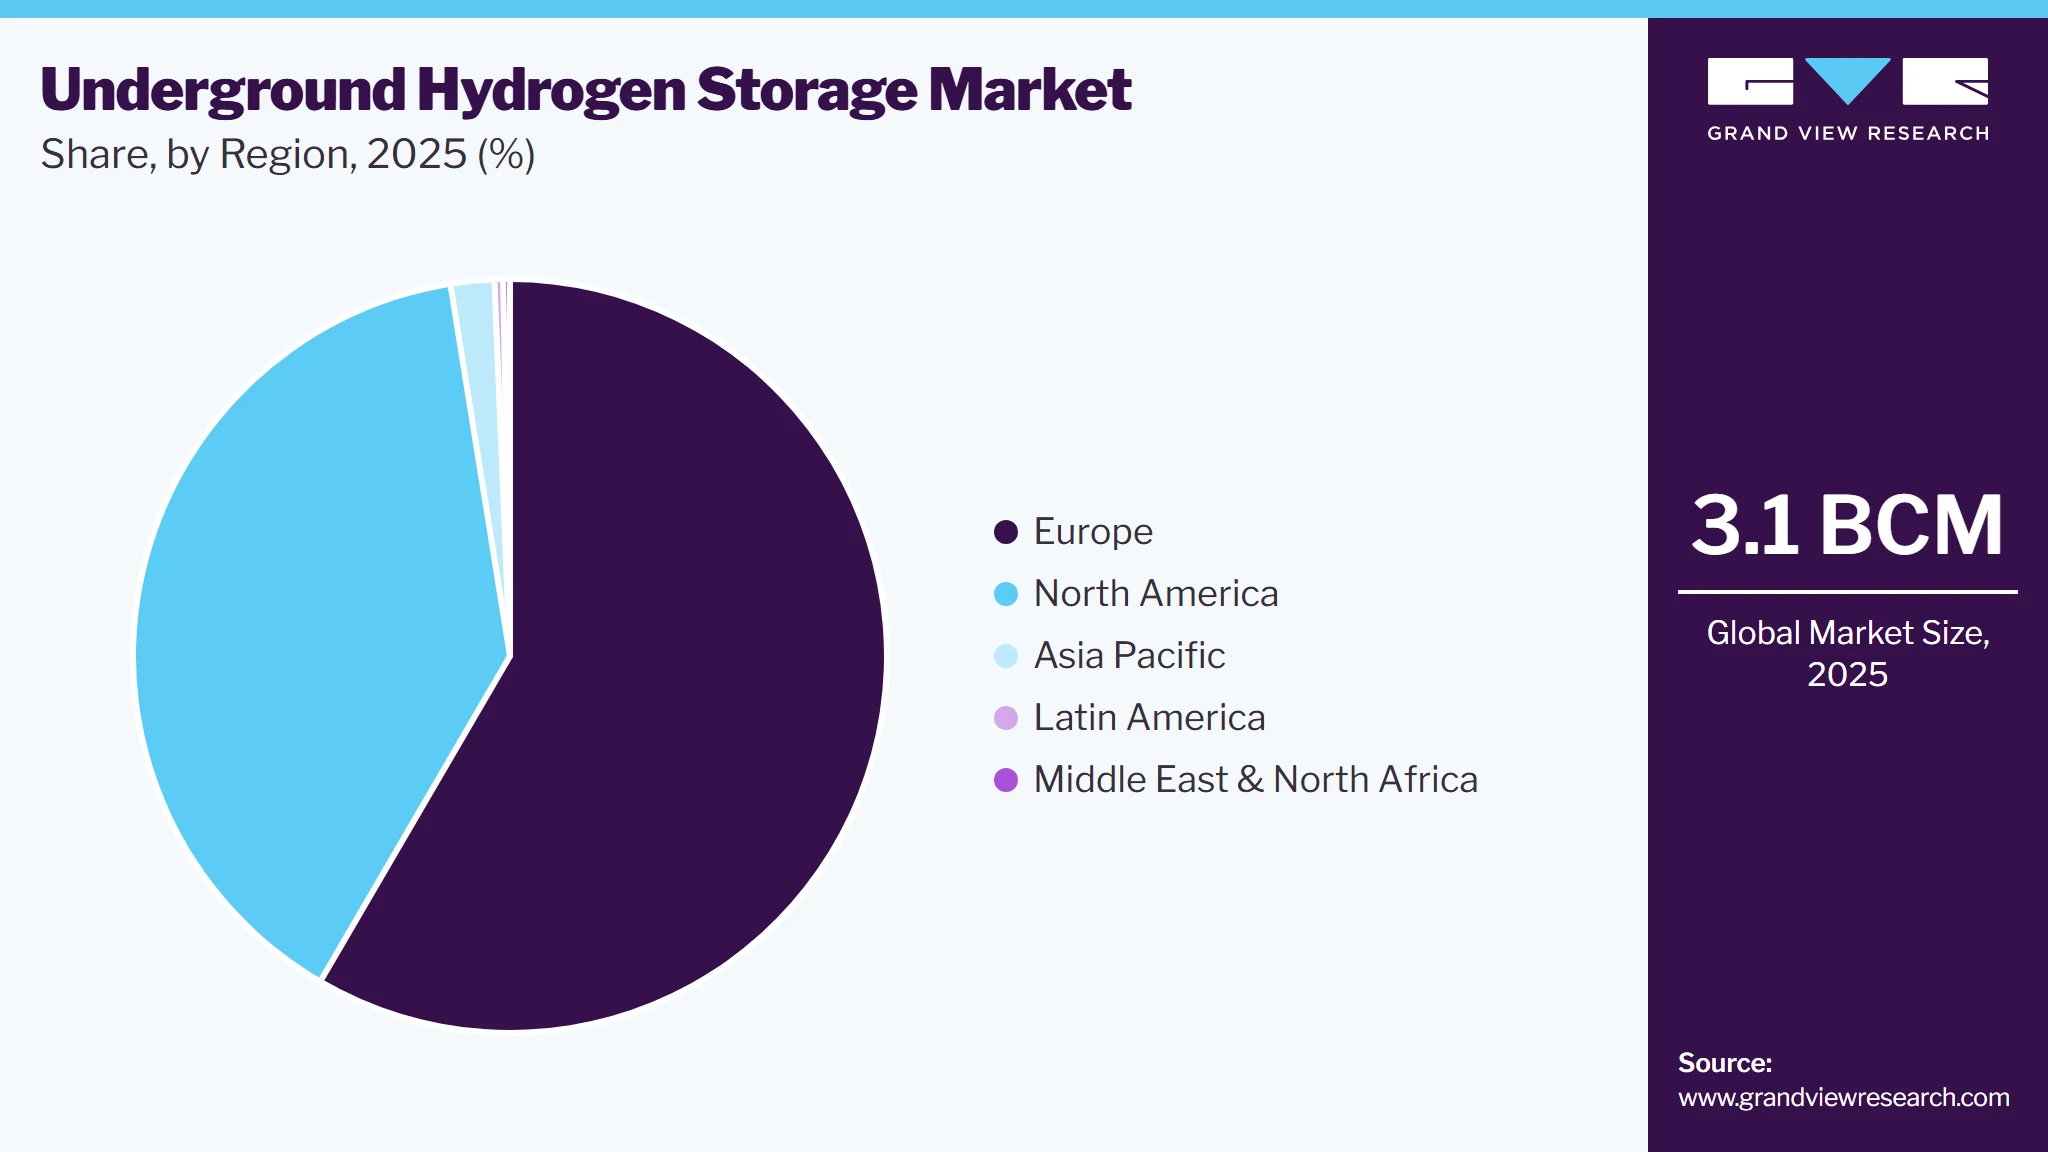
The global underground hydrogen storage market size was valued at 3.1 BCM in 2025 and is projected to grow from 3.4 BCM in 2026 to 6.2 BCM by 2033, at a CAGR of 9.0% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 58.4% in 2025. The market is expected to grow steadily during the forecast period, driven by supportive government policies, increasing net-zero targets, and a heightened focus on hydrogen as a clean energy carrier for industrial, transportation, and power generation applications.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By storage type: Salt caverns dominated the market, accounting for the largest market share of 97.7% in 2025.
Regional Highlights
- Largest regional market: Europe (58.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held a significant position in the underground hydrogen storage market in 2025.
Market Size & Forecast
- Market size in 2025: 3.1 BCM
- Estimated market size in 2026: 3.4 BCM
- Projected market size by 2033: 6.2 BCM
- CAGR (2026-2033): 9.0%
Prism AI by Grand View Research Free to tryAsk a question about the underground hydrogen storage marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Growing investments in green hydrogen infrastructure and rising adoption of renewable energy sources are accelerating the demand for safe and scalable hydrogen storage technologies. Underground hydrogen storage involves storing hydrogen gas in large geological formations such as salt caverns, depleted oil and gas fields, or aquifers, enabling the buffering of supply and demand in large-scale hydrogen energy systems. This method stabilizes hydrogen supply chains by offering long-duration energy storage solutions essential for decarbonized energy grids. Advancements in subsurface engineering and the repurposing of existing gas storage facilities further enhance underground hydrogen storage's commercial viability. To learn more about this report, Download Free Sample Report
Underground hydrogen storage is primarily used to balance supply and demand in hydrogen energy systems and support large-scale hydrogen deployment. While smaller above-ground storage solutions exist, they are not economically viable for handling seasonal fluctuations or industrial-scale volumes. Therefore, geological formations like salt caverns, depleted oil and gas fields, and aquifers are increasingly utilized due to their high capacity and long-duration storage capabilities. Projects integrating underground hydrogen storage with green hydrogen production and fuel cell deployment, particularly in Europe, the United States, and Asia-Pacific countries like Japan and Australia, are gaining momentum. Supportive regulatory frameworks, national hydrogen strategies, and investment in hydrogen hubs are key factors driving the development of underground hydrogen storage infrastructure.
Market Dynamics
The underground hydrogen storage market is growing as countries expand renewable energy capacity and invest in clean hydrogen infrastructure. Growing demand for long-duration energy storage, grid balancing, and reliable hydrogen supply for industrial and transportation applications is driving market growth. Advances in geological assessment, storage technologies, and hydrogen production are improving the feasibility of large-scale underground storage. However, challenges related to high upfront investment, regulatory approvals, and ensuring long-term storage integrity continue to influence market development.
The accelerating global transition toward low-carbon energy systems is the primary driver of the underground hydrogen storage market. As solar and wind power generation continues to expand, the need for long-duration energy storage has become increasingly important to manage fluctuations in renewable electricity supply. Underground hydrogen storage enables surplus renewable energy to be converted into hydrogen, stored in large volumes for extended periods, and used later for power generation, industrial processes, or transportation. This capability supports grid stability, improves energy security, and facilitates the broader adoption of clean hydrogen across multiple sectors.
A key example of this trend occurred in May 2025, when the European Commission selected 15 renewable hydrogen production projects across the European Economic Area under the European Hydrogen Bank's second auction, allocating up to USD 1.1 billion in funding to accelerate hydrogen deployment. The initiative is expected to increase renewable hydrogen production and strengthen the need for large-scale storage infrastructure, including underground hydrogen storage, to balance production with future demand and support Europe's decarbonization goals.
The underground hydrogen storage market is restrained by the high capital investment required to develop and operate storage facilities. Establishing underground storage sites involves extensive geological surveys, drilling, cavern development or reservoir preparation, hydrogen handling infrastructure, and continuous safety monitoring. These high upfront costs, combined with long project development timelines and uncertain returns, limit adoption, particularly in emerging economies where financial support and hydrogen infrastructure are still developing.
The expansion of green hydrogen hubs presents a significant opportunity for the underground hydrogen storage market. As governments and industries develop centralized hydrogen production, storage, and distribution networks, underground hydrogen storage enables large-scale, long-duration storage close to production sites. This helps balance supply and demand, improves energy reliability, and reduces the overall cost of delivering green hydrogen to end-use sectors such as transportation, steel manufacturing, power generation, and ammonia production.
Analyst Perspective
The underground hydrogen storage market is moving from pilot projects toward early commercial deployment as countries expand low-carbon hydrogen production and strengthen energy security initiatives. The growing integration of renewable energy is increasing the need for large-scale, long-duration hydrogen storage to balance seasonal fluctuations in electricity supply and demand. A key trend is the rapid development of salt cavern-based hydrogen storage, driven by its high storage efficiency, fast withdrawal rates, and proven performance in gas storage applications. As hydrogen infrastructure continues to expand, companies with expertise in underground storage, geological assessment, and integrated hydrogen value chains are expected to gain a competitive advantage.
Storage Type Insights
Based on storage type, the salt caverns segment led the market with the largest market share of 97.7% in 2025. It is further projected to be the fastest-growing segment during the assessment period. Salt caverns are preferred due to their excellent sealing capabilities, high cycling rates, and suitability for storing hydrogen at high pressures. The growing need for grid-scale energy storage to support renewable energy integration, combined with increasing hydrogen demand from sectors such as steel, mobility, and chemical processing, is driving the adoption of salt cavern storage. Countries like Germany, the U.S., and the Netherlands are actively developing pilot and commercial-scale projects using salt formations to create large, secure, and flexible hydrogen reserves.
The natural structure of salt caverns allows for relatively low-cost development compared to other geological formations and offers enhanced operational responsiveness. These caverns are particularly well-suited for seasonal or high-frequency cycling applications, making them ideal for balancing variable renewable energy sources like solar and wind. As green hydrogen production scales up, salt caverns will play a central role in enabling stable hydrogen supply chains for energy and industrial users. However, the global availability of suitable salt formations is limited, and site-specific geological assessments are essential. Despite this, their technical advantages and growing policy support make salt caverns the dominant and most promising segment in underground hydrogen storage.
Regional Insights
North America Underground hydrogen storage market is gaining momentum due to clean energy transition efforts and increasing investments in hydrogen production, especially in the United States and Canada. The U.S. Department of Energy's hydrogen hub program and Canada's national hydrogen strategy are driving the development of large-scale geological storage to support decarbonized industrial, transport, and power sectors. Repurposing existing gas storage infrastructure and abundant natural formations, such as salt domes in Texas and the Gulf states, provides technical and economic advantages. As hydrogen adoption scales, North America is poised to expand its underground storage capacity to meet growing regional demand.
 To learn more about this report, Download Free Sample Report
Europe Underground Hydrogen Storage Market Trends
Europe dominated the underground hydrogen storage market with the largest market share of 58.4% in 2025. The underground hydrogen storage market in the UK held the second largest share in the Europe region in 2025. The region leads underground hydrogen development, backed by ambitious decarbonization goals under the EU Green Deal and REPowerEU. Countries such as Germany, the Netherlands, France, and the UK are actively developing hydrogen valleys and pilot-scale salt cavern projects to create a resilient hydrogen backbone for industrial and energy use. Regulatory clarity, public-private partnerships, and funding from EU initiatives are accelerating underground storage deployment. Europe also benefits from mature gas infrastructure, advanced geological mapping, and strong OEM presence, reinforcing its role as a frontrunner in scaling and commercializing hydrogen storage technologies.
Asia Pacific Underground Hydrogen Storage Market Trends
Rising hydrogen demand from industrial decarbonization, mobility sectors, and national hydrogen strategies in China, Japan, Australia, and India is a major growth driver for the underground hydrogen storage industry. Regional governments prioritize clean hydrogen infrastructure to support energy security and climate goals, with salt caverns and depleted field projects under active exploration. Investments in renewable energy, coupled with favorable policies encouraging hydrogen storage and transport, further strengthen market growth. APAC's strong manufacturing ecosystem and growing pipeline of hydrogen production hubs position the region as a key player in global underground hydrogen infrastructure development.
Latin America Underground Hydrogen Storage Market Trends
The Latin American underground hydrogen storage industry is in early development, but growing momentum around renewable hydrogen production and regional energy diversification efforts is fueling interest. Countries like Chile and Brazil are exploring geological storage potential to complement large-scale green hydrogen projects driven by strong solar and wind resources. Underground storage is a key enabler to ensure a continuous hydrogen supply for export and domestic use. Though challenges such as infrastructure gaps and regulatory frameworks persist, supportive government policies and international collaboration are laying the groundwork for future growth in the region.
Middle East & Africa Underground Hydrogen Storage Market Trends
The Middle East and Africa (MEA) underground hydrogen storage industry is emerging as countries look to leverage their vast renewable and natural gas resources to build global-scale hydrogen economies. Nations like Algeria, the UAE, Oman, and South Africa are investing in green and blue hydrogen production, with underground storage identified as critical for supply reliability and export readiness. While geological assessment is ongoing, initial feasibility studies in salt formations and depleted fields offer promise. Government-backed energy diversification strategies, coupled with interest from international investors, are likely to drive underground hydrogen storage development across MEA in the coming years.
Key Underground Hydrogen Storage Company Insights
Some of the key players operating in the underground hydrogen storage industry include Air Liquide; Air Products and Chemicals, Inc.; Engie, Linde plc; and Texas Brine Company, LLC. These companies are actively engaged in developing large-scale underground hydrogen storage projects, particularly in salt caverns and depleted gas fields, to support the transition toward low-carbon energy systems.
Key Underground Hydrogen Storage Companies:
The following are the leading companies in the underground hydrogen storage market. These companies collectively hold the largest market share and dictate industry trends.
- Air Liquide
- Air Products and Chemicals, Inc.
- Engie
- Linde plc
- Texas Brine Company, LLC
- Uniper SE
- WSP
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Air Liquide, ENGIE, Linde plc, Uniper SE, WSP, Geostock, Snam SPA, VNG AG)
- Focus on developing large-scale underground hydrogen storage projects integrated with hydrogen production, transmission, and distribution infrastructure.
- Invest in salt cavern and porous reservoir storage technologies to support seasonal and long-duration hydrogen storage.
- Strengthen partnerships with governments, utilities, and industrial customers to accelerate commercial hydrogen ecosystem development.
- Expand engineering, consulting, and project execution capabilities for hydrogen storage and related energy transition projects.
- Strong financial resources enabling investment in capital-intensive underground hydrogen storage projects.
- Extensive expertise in gas storage, hydrogen handling, and large-scale energy infrastructure development.
- Established customer relationships and long-term contracts with industrial, utility, and energy sector clients.
- Global presence with diversified project portfolios and access to multiple regional hydrogen markets.
- High capital expenditure requirements increase project development costs and extend payback periods.
- Large organizational structures can slow decision-making and technology deployment.
- Significant dependence on supportive government policies, subsidies, and hydrogen market growth.
- Existing legacy natural gas assets may require costly upgrades for hydrogen compatibility.
Emerging Players (Texas Brine Company, LLC, HyStock)
- Focus on niche underground hydrogen storage projects using specialized expertise in salt cavern development and pilot-scale demonstrations.
- Collaborate with technology developers, research institutions, and energy companies to validate innovative storage solutions.
- Prioritize flexible and scalable storage projects tailored to regional hydrogen demand.
- Leverage strategic partnerships and public funding to accelerate project development and commercialization.
- Greater operational flexibility enables faster adoption of new storage technologies and project approaches.
- Specialized expertise in underground storage engineering and hydrogen-focused solutions.
- Ability to develop customized projects based on local geological conditions and customer requirements.
- Faster decision-making processes compared to larger multinational competitors.
- Limited financial resources constrain investment in large-scale commercial storage projects.
- Smaller geographic presence and customer base reduce market reach.
- Higher reliance on external funding, strategic partnerships, and government support.
- Limited operational track record in commercial-scale underground hydrogen storage.
Recent Developments
- In March 2025, Air Liquide announced a partnership with a European energy consortium to develop one of the continent’s largest underground hydrogen storage facilities in a salt cavern located in northern Germany. The project aims to secure renewable hydrogen supply for industrial users and mobility applications, supporting the region’s energy independence goals. This development highlights Air Liquide’s strategic commitment to scaling infrastructure along the hydrogen value chain and reinforces its role in enabling long-duration, low-carbon storage solutions in Europe.
Underground Hydrogen Storage Market Report Scope
Report Attribute
Details
Market Definition
The underground hydrogen storage market comprises the total hydrogen storage capacity available in underground geological formations, including porous media storage, salt caverns, and engineered cavities, for the safe and long-term storage of hydrogen.
Market size in 2025
3.1 BCM
Estimated market size in 2026
3.4 BCM
Projected market size by 2033
6.2 BCM
Growth rate
CAGR of 9.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in MCM, and CAGR from 2026 to 2033
Report coverage
Volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Storage type, region
Regional scope
North America, Europe, Asia Pacific, Latin America, Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, UK, France, China, India, Japan, Australia, Brazil, Algeria, Egypt, Libya, UAE; Mexico
Key companies profiled
Air Liquide, ENGIE, Linde plc, Texas Brine Company, LLC, Uniper SE, WSP, Geostock, HyStock, Snam SPA, VNG AG
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Underground Hydrogen Storage Market Report Segmentation
This report forecasts volume growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global underground hydrogen storage market report based on storage type, and region:
 To learn more about this report, Download Free Sample Report
-
Storage Type Outlook (Volume, MCM, 2021 - 2033)
-
Porous Media Storage
-
Salt Caverns
-
Engineered Cavities
-
-
Regional Outlook (Volume, MCM, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East & Africa
-
Algeria
-
Egypt
-
Libya
-
UAE
-
-
Research Methodology
The underground hydrogen storage market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each underground hydrogen storage segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Storage Type
Volume capture definition
Porous Media Storage
Includes the volume of hydrogen stored in natural porous underground formations, such as depleted oil and gas reservoirs and aquifers, for long-duration and large-scale hydrogen storage.
Salt Caverns
Represents the volume of hydrogen stored in underground salt caverns, which provide secure, high-purity, and flexible storage with rapid injection and withdrawal capabilities.
Engineered Cavities
Comprises the volume of hydrogen stored in purpose-built underground engineered cavities, including lined rock caverns and mined storage spaces designed for safe, controlled hydrogen storage.
Estimation Model
Layer Name
Key Question
Description
Hydrogen Storage Demand Layer
What drives the demand for underground hydrogen storage?
Identify the key demand drivers for underground hydrogen storage, including increasing hydrogen production, renewable energy integration, demand for seasonal energy storage, industrial decarbonization, hydrogen hub development, and government support for the hydrogen economy. Assess the impact of energy security initiatives and investments in hydrogen infrastructure on storage demand.
Storage Type Layer
Which underground storage technologies are being adopted?
Analyze market adoption across Porous Media Storage, Salt Caverns, and Engineered Cavities. Assess deployment trends based on geological suitability, storage capacity, containment performance, project investments, infrastructure availability, and operational efficiency.
Application Layer
Where is stored hydrogen utilized?
Evaluate hydrogen storage demand across applications such as industrial, power generation, transportation, and others. Assess storage utilization based on hydrogen supply balancing, industrial feedstock requirements, renewable energy integration, and clean mobility applications.
Storage Capacity (Volume) Layer
How is the market size measured?
Market size is quantified based on the storage capacity and utilization volume (MCM) of underground hydrogen storage facilities across Porous Media Storage, Salt Caverns, and Engineered Cavities. The overall market volume is determined by the hydrogen injected, stored, and withdrawn from underground storage sites to meet demand across end-use applications.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Storage Formation Benchmarking
A detailed benchmarking assessment was conducted comparing salt caverns, porous reservoirs, and engineered cavities based on storage capacity, hydrogen containment performance, geological suitability, capital costs, operational efficiency, scalability, and commercial readiness.
Helps identify the most suitable storage formation for different project requirements and supports investment and technology selection decisions.
Regional Market Assessment
A comprehensive regional analysis was conducted covering North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, evaluating hydrogen policies, underground storage potential, renewable energy integration, infrastructure development, project pipeline, and investment trends.
Provides region-specific growth opportunities, investment hotspots, regulatory outlook, and competitive positioning to support strategic market expansion.
Competitive Landscape Analysis
A comprehensive assessment of leading underground hydrogen storage companies was conducted, covering project portfolios, storage technologies, strategic partnerships, R&D initiatives, geographic presence, and competitive positioning across the hydrogen value chain.
Enables a clear understanding of market competition, company strategies, technology leadership, and opportunities for partnerships or market entry.
Frequently Asked Questions About This Report
The underground hydrogen storage market size was estimated at 3.1 BCM in 2025 and is expected to reach 3.4 BCM in 2026.
The underground hydrogen storage market is expected to grow at a CAGR of 9.0% from 2026 to 2033 to reach 6.2 BCM by 2033.
Based on storage type, the salt caverns segment accounted for the largest market share of 97.7% in 2025.
The key players operating in the underground hydrogen storage market are Air Liquide, ENGIE, Linde plc, Uniper SE, WSP, Geostock, Snam SPA, VNG AG, Texas Brine Company, LLC, HyStock, and others.
The underground hydrogen storage market is primarily driven by the increasing adoption of green hydrogen, growing renewable energy integration, and the need for large-scale, long-duration energy storage to support decarbonization and energy security.
Asia Pacific is anticipated to register the fastest CAGR over the forecast period.
The Europe dominated the underground hydrogen storage market with the market share of 58.4% in 2025.
About the Author(s)
Renewable Energy Research Team
Energy & Power · Renewable EnergyThis report was authored by the renewable energy research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the renewable energy segment of the energy & power industry. All findings are based on proprietary energy & power databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


