
- Home
- »
- Consumer F&B
- »
-
U.S. Beauty Drinks Market Size & Share Report, 2026-2033GVR Report cover
![U.S. Beauty Drinks Market (2026 - 2033)Report]()
U.S. Beauty Drinks Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Functional Shots, RTD Drinks), By Application (Skin hydration & glow, Anti-aging), By Distribution Channel (Supermarkets & hypermarkets, Specialty Stores) And Segment Forecasts
Market Size, 2025
$704.8MMarket Estimate, 2026
$740.7MMarket Forecast, 2033
$1,315.9MCAGR, 2026–2033
8.6%U.S. Beauty Drinks Market Summary
The U.S. beauty drinks market size was valued at USD 704.8 million in 2025 and is projected to grow from USD 740.7 million in 2026 to USD 1,315.9 million by 2033, at a CAGR of 8.6% from 2026 to 2033. The U.S. beauty drinks industry is primarily driven by growing consumer interest in beauty-from-within solutions that support skin, hair, and overall wellness. Demand is boosted by the popularity of collagen, vitamins, antioxidants, and other functional ingredients in convenient beverage formats.
Key Market Trends & Insights
- By type: RTD drinks segment held the largest market share of 50.6% in 2025.
- By application: Skin hydration & glow segment held the largest market share of 35.8% in 2025.
- By distribution channel: Supermarkets & hypermarkets segment held the largest market share of 39.7% in 2025.
Market Size & Forecast
- Market size in 2025: USD 704.8 Million
- Estimated market size in 2026: USD 740.7 Million
- Projected market size by 2033: USD 1,315.9 Million
- CAGR (2026-2033): 8.6%
The U.S. beauty drinks market is also benefiting from premiumization, as consumers are increasingly willing to spend more on innovative and lifestyle-oriented beverages. Rising demand for clean-label, plant-based, and low-sugar formulations is encouraging brands to introduce differentiated products. In addition, wider availability through e-commerce, specialty retailers, and direct-to-consumer channels is improving accessibility and expanding market reach.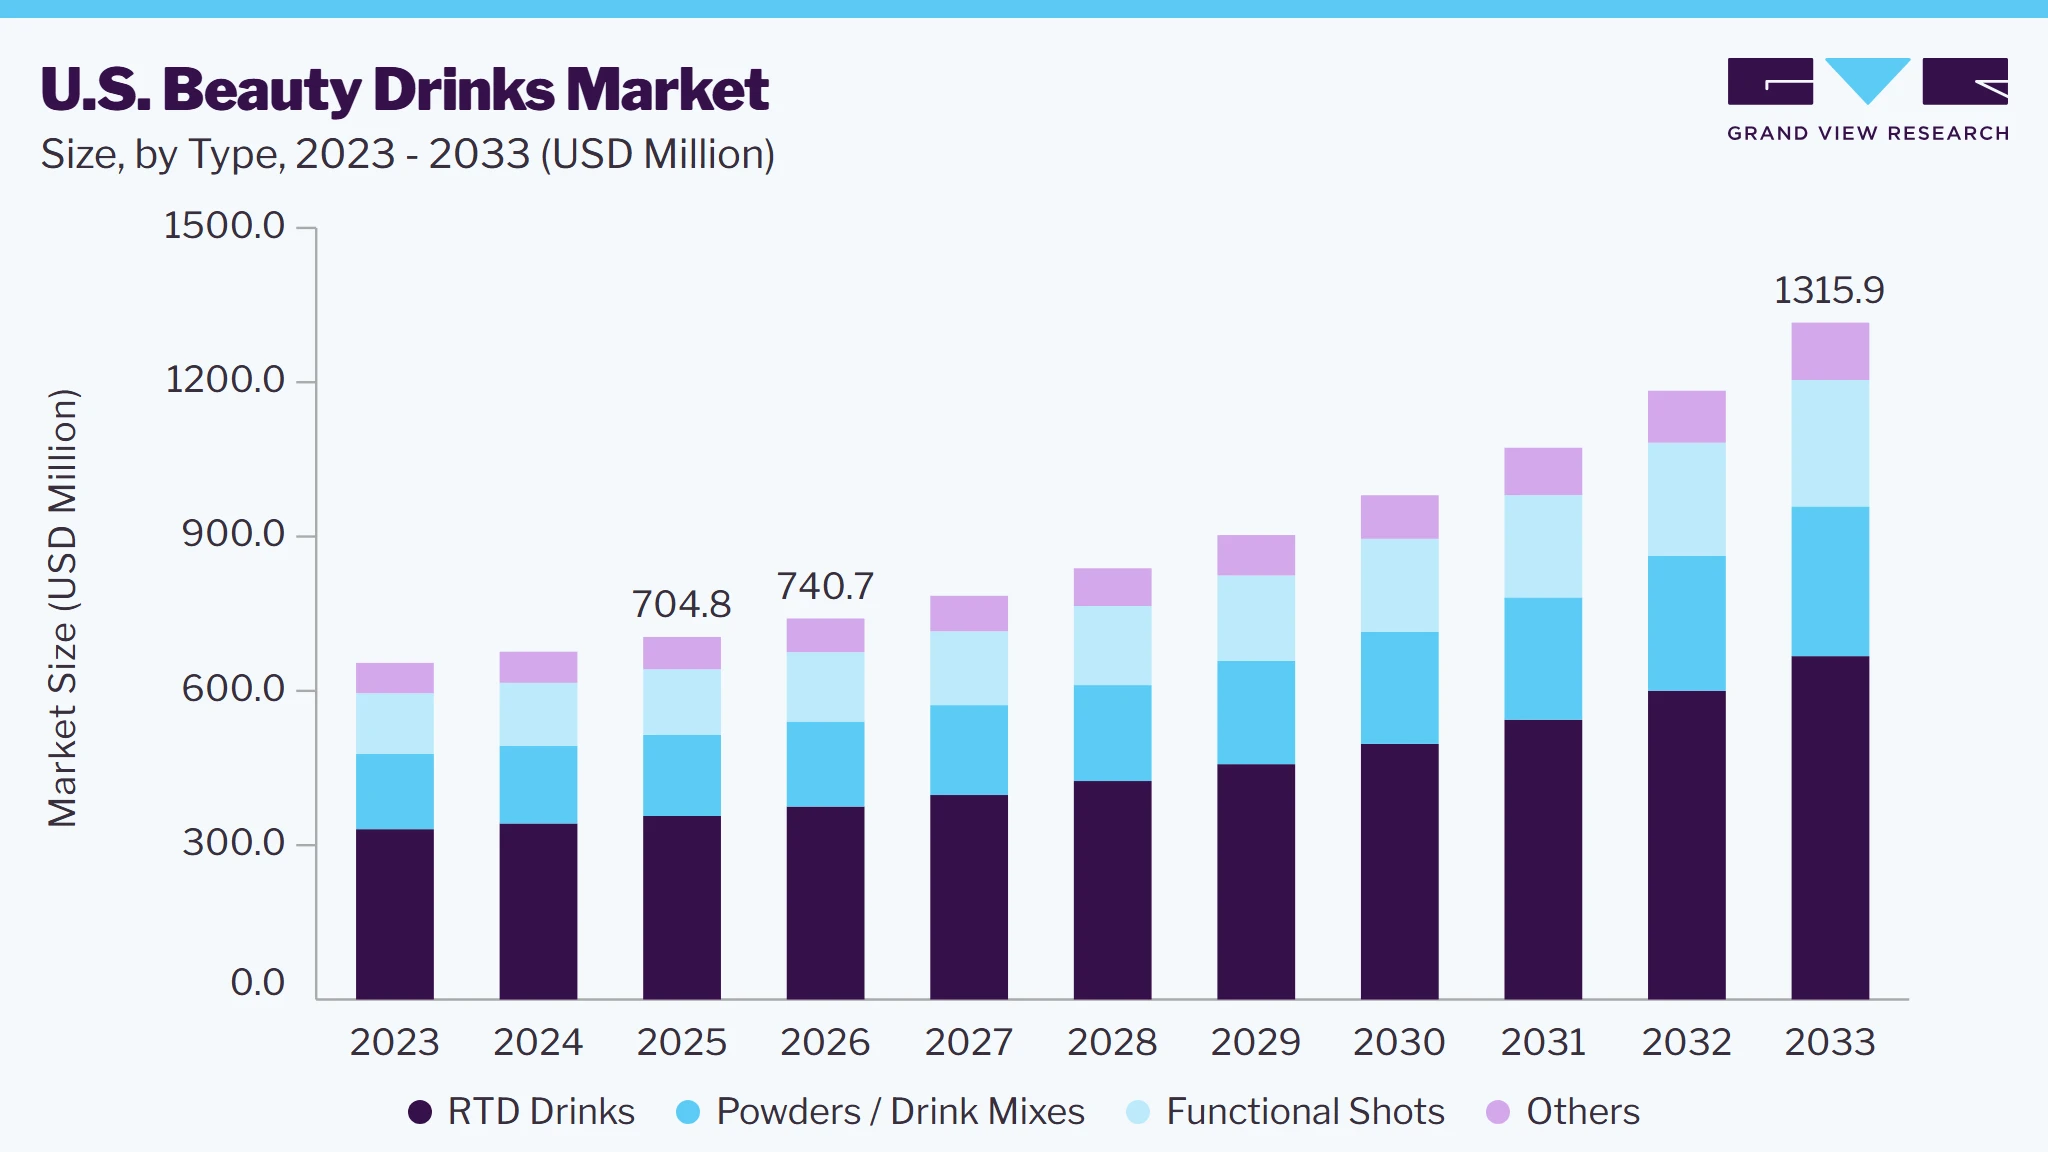
In January 2024, Pretty Tasty launched its ready-to-drink collagen tea in Peach and Raspberry flavors, providing 10g of protein and collagen peptides in a 45-calorie can. The brand also announced plans to expand its range with a Lemon flavor and single-serve stick packs, catering to the growing beauty and wellness beverage market. In addition, wider availability through e-commerce, specialty retailers, and direct-to-consumer channels is improving accessibility and expanding market reach.
Furthermore, the growing integration of beauty drinks into daily routines and preventive wellness habits, particularly among younger consumers. Product innovation in flavors, packaging, and targeted formulations is helping brands appeal to specific lifestyle preferences and consumer needs. Increasing interest in personalized wellness is also creating opportunities for products designed around specific beauty and nutritional goals.
Market Dynamics
Convenience is a major factor supporting the U.S. beauty drinks market, as consumers increasingly seek products that fit easily into busy lifestyles. Ready-to-consume formats offer an alternative to traditional beauty routines that may require multiple products or steps. This makes beauty drinks particularly appealing to consumers who value simplicity and portability. On-the-go consumption also supports their use at work, during travel, or after exercise. In August 2025, Vital Proteins entered the RTD beverage market with its Collagen & Protein Shake, combining 30g of protein and 10g of collagen peptides to support beauty and overall wellness. The 11-ounce, low-sugar shake targets demand for convenient, multifunctional formats. As convenience becomes more important in everyday purchasing decisions, it can support continued category adoption.
The relatively high cost of some beauty drinks can restrict their penetration across broader consumer groups. Premium formulations may require consumers to pay more than they would for conventional beverages. This can make regular consumption less attractive, particularly when buyers are uncertain about the long-term value of the product. Price sensitivity may therefore encourage consumers to purchase these products occasionally rather than routinely.
Personalization presents an opportunity for brands to develop beauty drinks around specific consumer preferences and needs. Products could be differentiated according to factors such as age, lifestyle, dietary preferences, or particular beauty concerns. Such targeted positioning can help brands create clearer value propositions in an increasingly competitive category. It may also encourage stronger consumer engagement by making products feel more relevant to individual users. Greater personalization could therefore help companies build differentiation and strengthen customer loyalty. According to the data published in August 2025, in 2025-26, personalization is emerging as a strategic growth area within beauty and wellness, with Unilever identifying personalization, women's health, longevity and AI-driven wellness among its future priorities.
Analyst Perspective
The U.S. beauty drinks market is expected to benefit from rising consumer interest in products that combine beauty, nutrition, and everyday wellness routines. Demand is increasing for beverages positioned around skin health, hydration, healthy aging, hair wellness, and overall appearance. Innovation in collagen, vitamins, antioxidants, adaptogens, and botanical ingredients is enabling brands to develop differentiated, benefit-focused products. Growth in RTD beverages, functional shots, drink mixes, and e-commerce is expanding product accessibility across diverse consumer groups. Premium positioning, clean-label formulations, and personalized beauty nutrition are likely to support repeat consumption and continued market expansion.
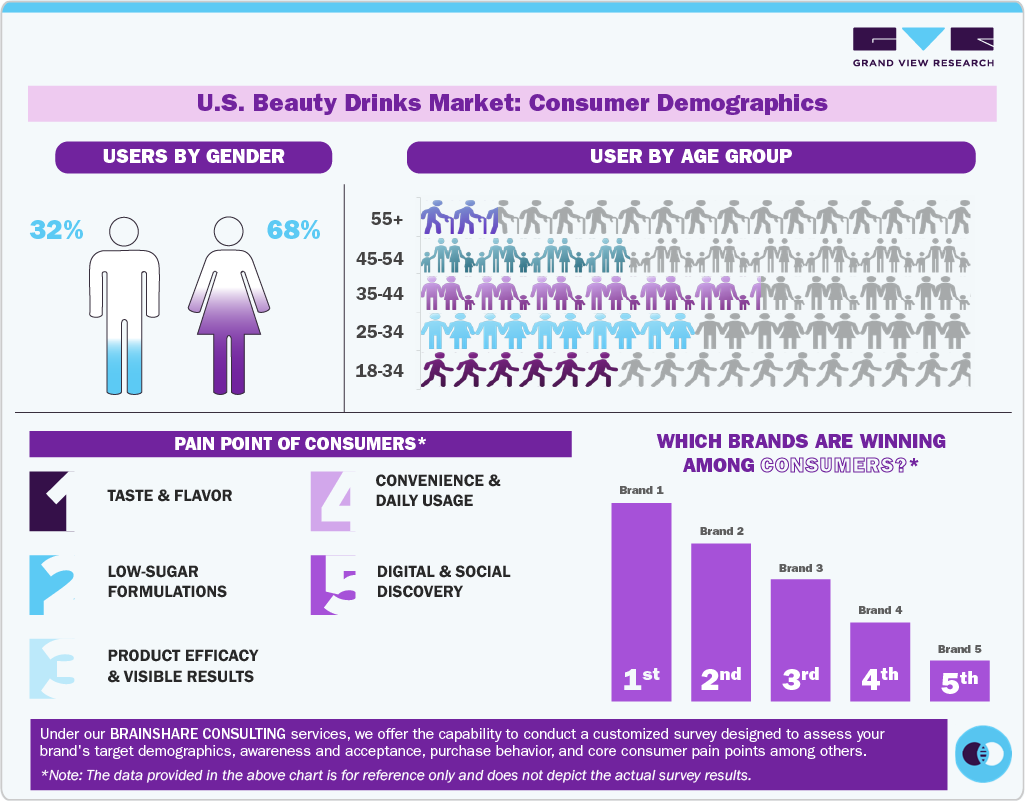
Consumer Insights for the U.S. Beauty Drinks Market
U.S. consumers are increasingly viewing beauty as part of broader wellness routines, creating demand for ingestible products that support appearance alongside everyday nutrition. Convenience is a key factor, with consumers favoring easy-to-consume formats that can fit into busy daily schedules. Collagen remains a major ingredient opportunity, while vitamins, antioxidants, and botanical ingredients are being incorporated to address skin, hair, hydration, and healthy-aging needs.
Type Insights
The RTD drinks market accounted for the largest share of 50.6% of the U.S. beauty drinks industry in 2025. The RTD drinks segment is supported by consumers’ preference for beverages that require no preparation before consumption. Their portability makes them suitable for busy schedules, commuting, travel, and workplace consumption. Attractive flavors and convenient packaging can also encourage trial among consumers who may be new to beauty-focused beverages. In March 2026, Vital Proteins launched Collagen Sparkling Water, combining VERISOL collagen peptides and vitamin C to support skin, hair, nails, and everyday wellness. Available in three fruit-forward flavors with zero sugar and 15 calories, the product targets consumers seeking a convenient, refreshing way to incorporate collagen into their daily hydration routine.
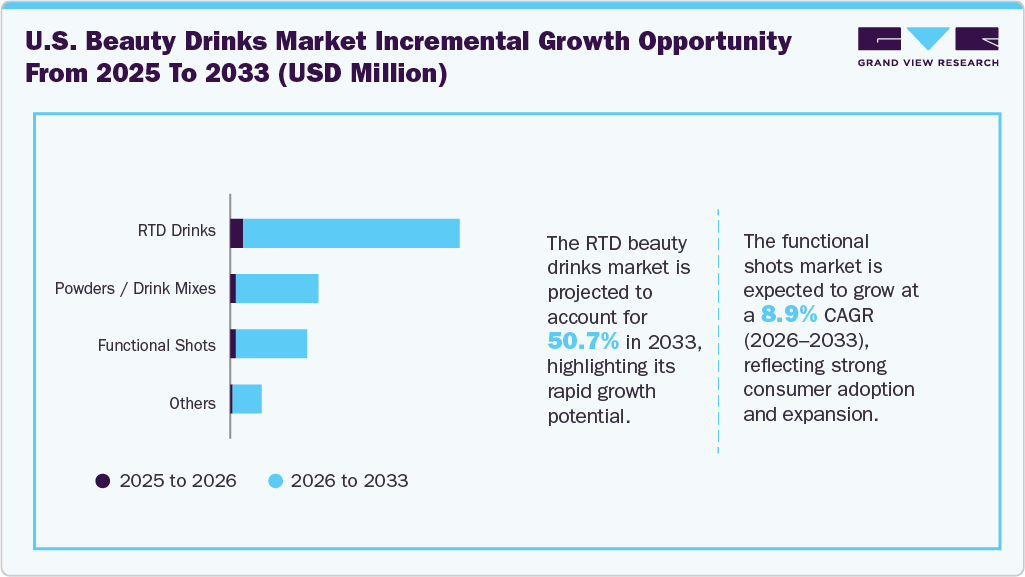
The functional shots is projected to grow at the fastest CAGR of 8.9% from 2026 to 2033 in the U.S. beauty drinks market. Functional shots are gaining interest due to their compact format and concentrated positioning, appealing to consumers seeking a quick consumption option. Their small serving size allows brands to communicate specific functional benefits in a simple and targeted format. The format also supports premium positioning and can encourage consumers to incorporate shots into established daily routines. Convenient packaging makes them easy to carry and consume without significantly disrupting daily activities. Product innovation around ingredients and targeted applications can further strengthen consumer interest in this segment.
Application Insights
The use of beauty drinks for skin hydration & glow accounted for the largest share of 35.8% of the revenue in 2025. The skin hydration and glow segment benefits from consumer interest in achieving visible skin-health benefits alongside everyday hydration and wellness. Beauty drinks can combine hydrating ingredients with nutrients associated with skin appearance, creating a multifunctional proposition for consumers. The segment also aligns with demand for lighter, refreshing formats that can be consumed throughout the day rather than as a traditional beauty supplement. According to the YouGov data published in May 2024, approximately 37% of the 1,148 U.S. adult citizens surveyed identified dry skin as their primary skin concern.
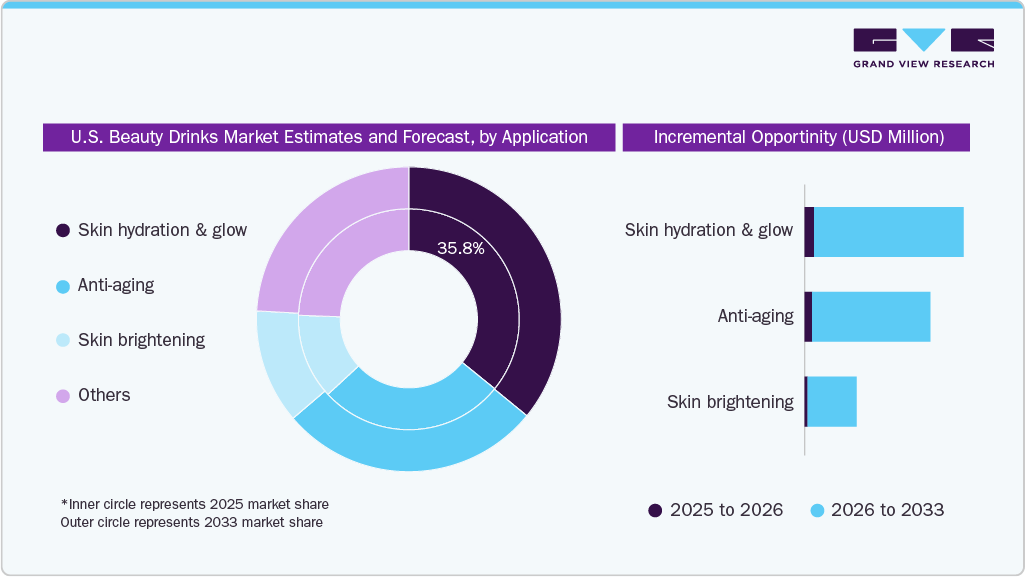
The use of beauty drinks for anti-aging is projected to grow at a CAGR of 8.8% from 2026 to 2033. The anti-aging segment is supported by growing interest in beauty-from-within solutions that complement topical skincare routines. Consumers are increasingly attracted to ingestible formats containing ingredients such as collagen, antioxidants, and other nutrients associated with healthy-looking skin. The convenience of consuming these ingredients through beverages can make anti-aging routines easier to incorporate into everyday lifestyles. Product development is also moving toward formulations addressing specific concerns such as skin elasticity, firmness, and the appearance of fine lines.
Distribution Channel Insights
The sales of U.S. beauty drinks through supermarkets & hypermarkets accounted for the largest share of 39.7% of the revenue in 2025. Supermarkets and hypermarkets benefit from their wide consumer reach and strong physical presence, giving beauty drink brands greater visibility among mainstream shoppers. Placement alongside functional beverages, health products, and personal-care items can encourage consumers to discover beauty drinks during routine shopping trips. In-store promotions, attractive displays, and product sampling can reduce hesitation toward unfamiliar beauty-focused beverage formats. In 2025, Pretty Tasty launched its collagen-infused iced teas at Sprouts Farmers Market, offering Peach, Raspberry, Lemon, and Original Black Tea varieties with 10g of collagen protein.
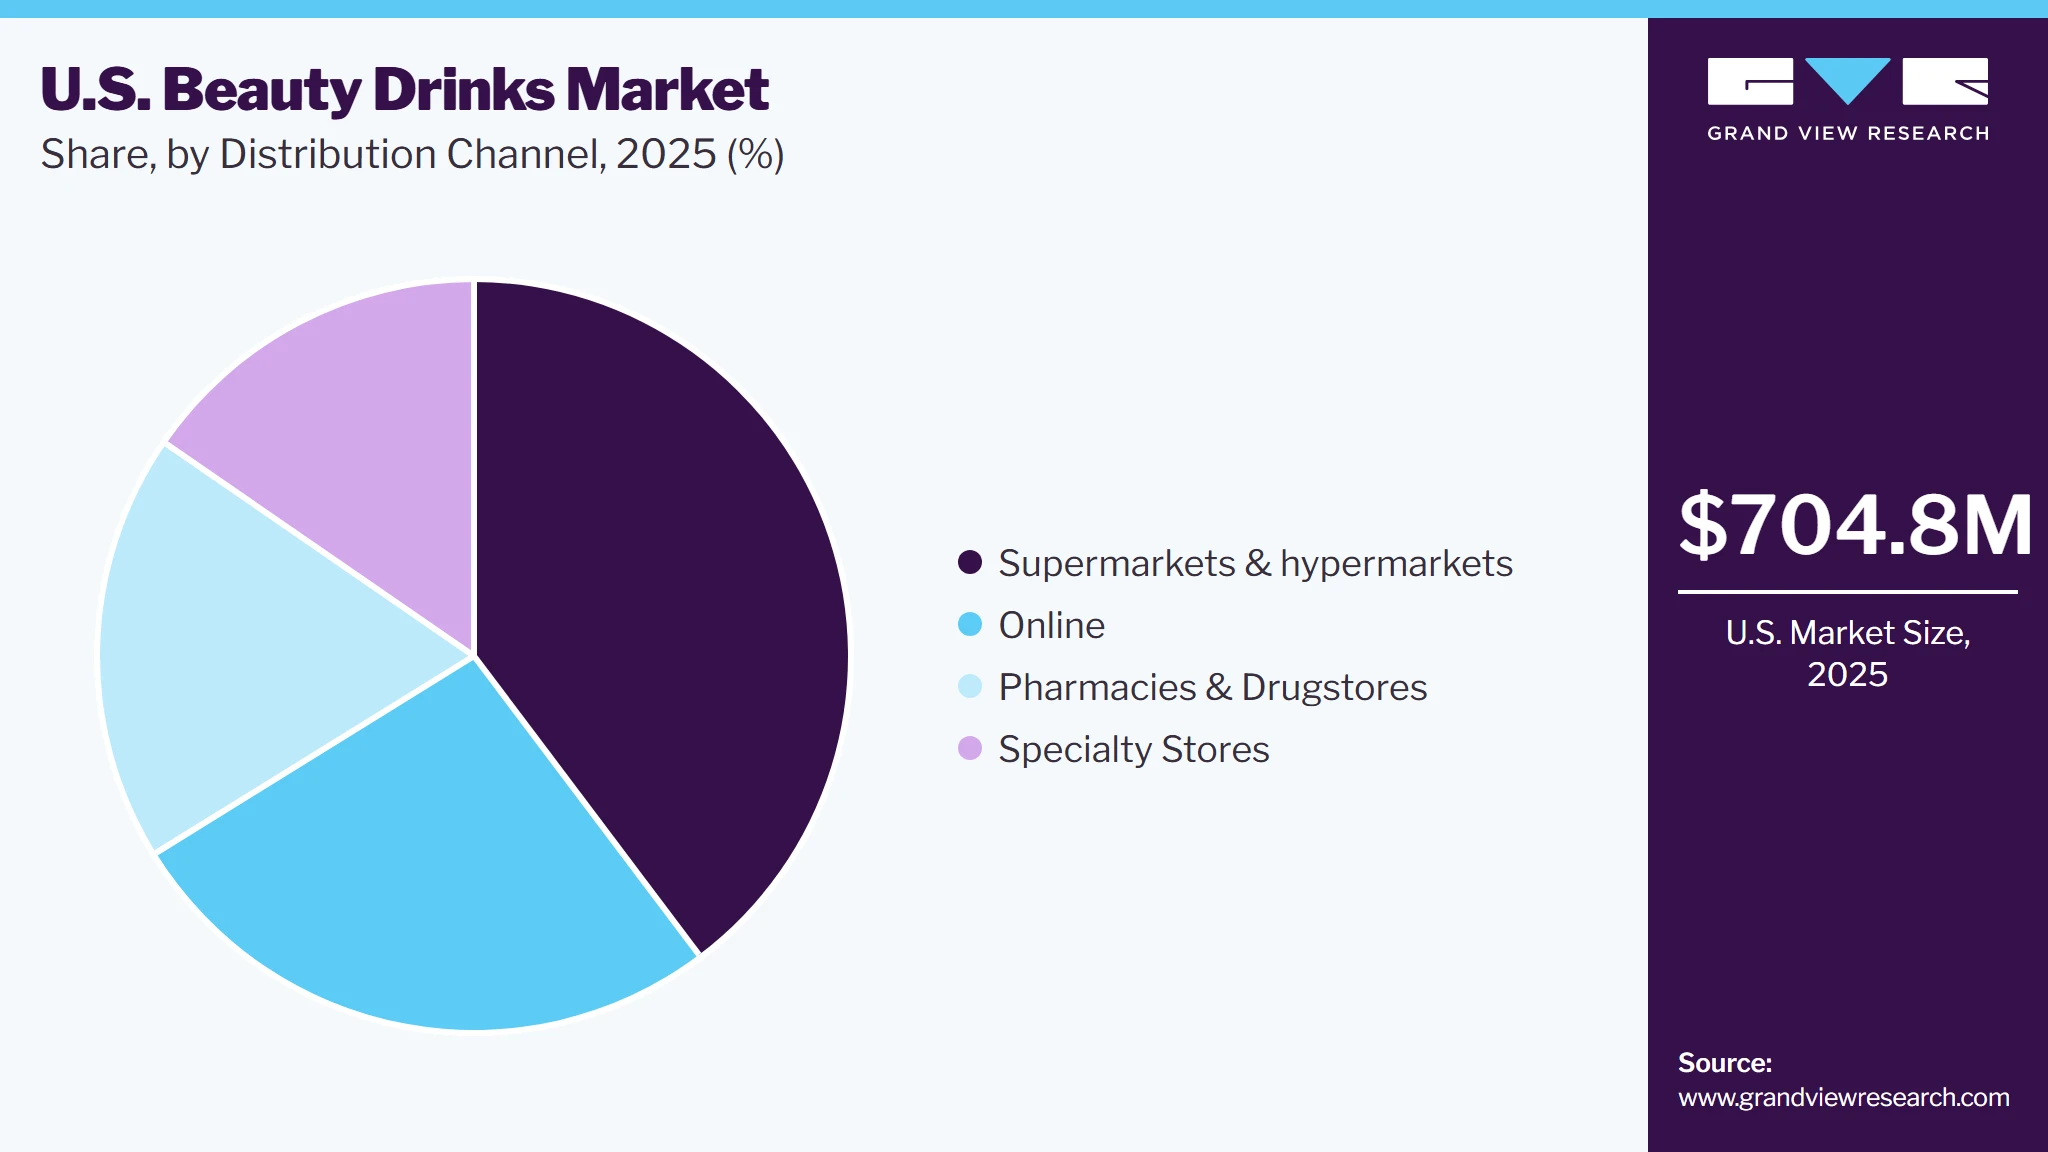
The sales of U.S. beauty drinks through the online distribution channel are projected to grow at a CAGR of 8.9% from 2026 to 2033. Online distribution provides beauty drink brands with an effective platform to present detailed information about ingredients, formulations, benefits, and recommended usage. Consumers can easily compare products according to beauty concerns, dietary requirements, flavors, and formulation preferences before purchasing. Direct-to-consumer websites and subscription options can support recurring purchases for products consumed as part of regular wellness routines.
Key U.S. Beauty Drinks Company Insights
The U.S. beauty drinks industry remains competitive across collagen beverages, functional hydration, nutritional shakes, and beauty-focused drink mixes, with established wellness brands competing against specialized and emerging players. Companies are increasingly using format innovation, multifunctional formulations, and targeted consumer positioning to strengthen differentiation rather than competing solely on traditional collagen products.
Key U.S. Beauty Drinks Companies
-
Nestlé Health Science (Vital Proteins)
-
Pretty Tasty
-
Skinade
-
Shiseido Company, Limited
-
Youtheory
-
Serovital Ingredients
-
Vida Glow
-
sprinter
-
The Collagen Co.
-
Dose & Co
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Nestlé Health Science)
- Broaden beauty beverage ranges, secure major retail placements, and leverage established wellness platforms.
- Strong shelf visibility, broad consumer reach, and diversified product portfolios.
- Portfolio complexity and greater dependence on large retail accounts.
Emerging Players (Vida Glow, sprinter)
- Build specialist beauty positioning, focus on collagen-led formulations, and prioritize DTC and specialty wellness channels.
- Strong product specialization, premium positioning, and closer customer relationships.
- Smaller geographic footprint and limited mainstream retail penetration.
Recent Developments
-
In April 2026, Isagenix launched BĒA Glow, a sparkling collagen and energy beverage containing 10g marine collagen, hyaluronic acid, biotin, and green tea caffeine. The 45-calorie, sugar-free drink combines beauty and energy benefits in a convenient daily format, with responsibly sourced marine collagen and third-party quality testing.
-
In 2025, Pretty Tasty launched its collagen-infused iced teas at Sprouts Farmers Market, offering Peach, Raspberry, Lemon, and Original Black Tea varieties with 10g of collagen protein. The drinks are positioned as a convenient beauty-and-wellness option, featuring zero sugar and stevia.
U.S. Beauty Drinks Market Report Scope
Report Attribute
Details
Market size in 2025
USD 704.8 million
Estimated market size in 2026
USD 740.7 million
Projected market size by 2033
USD 1,315.9 million
Growth rate (Revenue)
CAGR of 8.6% from 2026 to 2033
Actuals
2021 - 2025
Forecast period
2026 - 2033
Quantitative (Revenue) units
Revenue in USD million, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, and distribution channel
Country scope
U.S.
Key companies profiled
Nestlé Health Science (Vital Proteins); Pretty Tasty; Skinade; Shiseido Company, Limited; Youtheory; Serovital; Vida Glow; sprinter; The Collagen Co.; Dose & Co
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Beauty Drinks Market Report Segmentation
This report forecasts revenue growth at the country levels and provides an analysis of the latest industry trends and opportunities in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the U.S. beauty drinks market report on the basis of type, application, and distribution channel.
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Functional Shots
-
RTD Drinks
-
Powders / Drink Mixes
-
Others
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Skin hydration & glow
-
Anti-aging
-
Skin brightening
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Supermarkets & hypermarkets
-
Specialty Stores
-
Pharmacies & Drugstores
-
Online
-
Research Methodology
The U.S. beauty drinks market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each U.S. beauty drinks segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Type
Revenue capture definition
Functional Shots
Functional shots capture revenue through highly targeted, small-volume products positioned around specific beauty and wellness outcomes. Their concentrated format enables brands to incorporate premium ingredients and distinctive functional claims that can justify higher price points. Products may appeal to consumers seeking quick, goal-oriented supplementation rather than conventional beverages. Revenue can be generated through single-shot purchases, bundled packs, repeat-use programs, and premium wellness collections. Strong ingredient storytelling and specialized positioning can further support consumer willingness to pay.
RTD Drinks
RTD beauty drinks capture revenue through ready-to-consume beverages that combine hydration, nutrition, and beauty-oriented functionality in an accessible format. Brands can monetize demand by offering differentiated flavors, formulations, packaging formats, and benefit-led product variants. The broader beverage format creates opportunities for placement across grocery, drug, convenience, fitness, and specialty retail environments. Revenue is supported by single-bottle sales, larger packs, promotional bundles, and frequent replenishment purchases. Product innovation and premium branding can also help increase value per transaction.
Powders / Drink Mixes
Powders and drink mixes capture revenue by offering consumers a customizable way to incorporate beauty-focused ingredients into their daily beverage routines. Brands can create multiple SKUs based on flavor, formulation, ingredient combinations, serving formats, and targeted beauty concerns. The dry format can facilitate economical storage and transportation while enabling products to be sold through both mainstream and specialized wellness outlets. Revenue opportunities include sachets, multi-serving containers, variety packs, and recurring purchase programs. Customization and premium active ingredients can provide additional opportunities for value-based pricing.
Others
Other beauty drink formats capture revenue through emerging or less-standardized products that do not fit conventional shots, RTD beverages, or powdered formulations. These may include innovative beverage formats, concentrates, gummies or hybrid drinkable products positioned around beauty and wellness benefits. Revenue potential is supported by novelty, differentiated delivery mechanisms, and the ability to address specific consumer preferences or usage occasions. Brands can monetize these offerings through specialty retail, direct-to-consumer sales, limited-edition launches, and curated product bundles. Innovation-led positioning can allow differentiated products to command premium pricing and build new consumption occasions.
Estimation Model
Layer Name
Key Question
Description
Consumption Universe Layer
Who consumes beauty drinks in the U.S.?
Captures U.S. consumers interested in beauty, wellness, healthy aging, hydration, and functional nutrition. Includes people seeking benefits related to skin appearance, hair and nails, energy, and overall wellness.
Access & Availability Layer
Who can access beauty drinks?
Covers consumers who encounter beauty-focused beverages through supermarkets, drugstores, specialty wellness retailers, gyms, beauty retailers, direct-to-consumer websites, marketplaces, and other convenient retail channels.
Purchase & Usage Layer
Who regularly purchases beauty drinks?
Focuses on consumers who choose functional beverages as part of their regular routines, such as collagen drinks, beauty waters and other products positioned around skin, hair, hydration, or healthy aging.
Revenue Conversion Layer
How is revenue generated from beauty drinks consumers?
Measures monetization from consumers who purchase beauty drinks across retail and online channels, including ready-to-drink beverages, powders, shots, concentrates, and recurring or subscription-based formats.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
U.S. Beauty Drinks Market Opportunity & Growth Mapping
Quantified the addressable opportunity by product category, consumer adoption stage, price tier, and growth trajectory. Identified where beauty drinks sit within the broader U.S. functional beverage and ingestible wellness ecosystem.
Establishes the most attractive pockets for investment and provides a fact base for sizing the commercial opportunity.
U.S. Route-to-Market & Retail Landscape
Examined how beauty drinks reach U.S. shoppers across mass retail, grocery, pharmacy, beauty specialists, fitness/wellness outlets, DTC, and digital marketplaces. Assessed channel roles, shopper missions, and barriers to distribution expansion.
Reveals the most effective pathways to scale, supports channel prioritization, and helps optimize launch and distribution strategy.
U.S. Pricing, Portfolio & Commercial Strategy
Benchmarked price-pack structures, premiumization, promotional dynamics, repeat-purchase mechanics, and portfolio architectures across relevant beverage and wellness propositions.
Identifies viable price points, monetization levers, and portfolio gaps while informing a commercially attractive market-entry model.
Frequently Asked Questions About This Report
The U.S. beauty drinks market size was valued at USD 704.8 million in 2025 and is estimated at USD 740.7 million for 2026.
Key factors driving the U.S. beauty drinks market include rising consumer interest in functional beverages, growing awareness of beauty-from-within concepts, and increasing demand for products supporting skin, hair, and nail health.
The RTD drinks market led with a 50.6% revenue share in 2025.
The functional shots market is projected to grow at the fastest CAGR of 8.9% from 2026 to 2033.
The use of beauty drinks for skin hydration & glow led the market with a 35.8% revenue share in 2025.
The sale of beauty drinks through supermarkets & hypermarkets accounted for the largest share of 39.7% of the revenue in 2025.
The sale of beauty drinks through online channels is projected to grow at a CAGR of 8.9% from 2026 to 2033.
Key players include Nestlé Health Science (Vital Proteins), Pretty Tasty, Skinade, Shiseido Company, Limited, Youtheory, Serovital, Vida Glow, sprinter, The Collagen Co., and Dose & Co.
The U.S. beauty drinks market is expected to grow at a CAGR of 8.6% from 2026 to 2033, reaching USD 1,315.9 million by 2033.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


