
- Home
- »
- Medical Devices
- »
-
U.S. Over-the-Counter Glucose Biosensors Market, 2030GVR Report cover

U.S. Over-the-Counter Glucose Biosensors Market (2025 - 2030) Size, Share & Trends Analysis Report By End-use (Healthcare Professional Offices (HCPs), Specialty Clinics, Homecare), By Key Companies, Competitive Analysis, And Segment Forecasts
U.S. OTC Glucose Biosensors Market Trends
The U.S. over-the-counter glucose biosensors market size was estimated at USD 105.3 million in 2024 and is anticipated to exhibit a CAGR of 11.5% from 2025 to 2030. This growth is attributed to the increasing prevalence of diabetes and prediabetes, the shift towards preventive healthcare, and the increased adoption of glucose biosensors by athletes are some of the major factors driving market growth. Moreover, the aging population of the country further contributes to this growth as this age group is significantly vulnerable to chronic diseases such as diabetes, which increases the demand for effective solutions such as glucose biosensors.
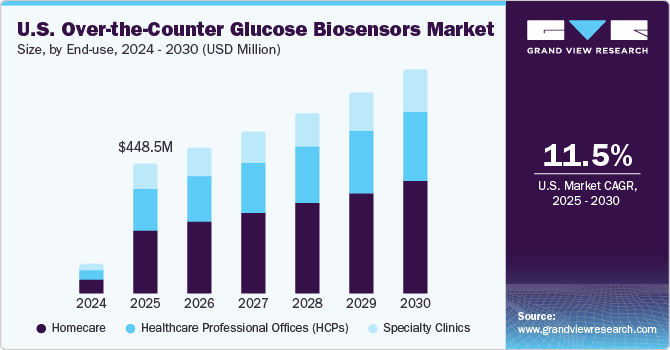 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
The increase in the prevalence of diabetes due to aging, obesity, and unhealthy lifestyle is one of the factors contributing to the growth of the U.S. over-the-counter (OTC) glucose biosensors industry. Obesity is a major factor leading to diabetes. According to CBS News published in September 2024, approximately 30% of adults were classified as obese, with a body mass index (BMI) of 30 or higher in 2020. Furthermore, the CDC reported an increase in the adult obesity rate to 41.9% by 2020. Currently, based on survey data from 2021 to 2023, the CDC estimates that 40.3% of adults are obese. In addition to obesity, diabetes is becoming increasingly prevalent globally. The International Diabetes Federation (IDF) estimates that there were 537 million adults (aged 20-79) living with diabetes in 2021, and this number is expected to increase to 642 million by 2040. The IDF also reports that the prevalence of diabetes is growing globally, with the highest increase witnessed in low- and middle-income countries.
In the U.S., diabetes is a widespread health issue affecting millions of people. According to the CDC, as of 2024, 11.6% of the entire U.S. population-about 38.4 million people of all ages-has been diagnosed with diabetes. The percentage of adults aged 18 or older is even higher, with 14.7% or 38.1 million people affected. Around 8.7 million adults with diabetes were unaware of their condition or did not report it, representing 22.8% of all adults with diabetes and 3.4% of all U.S. adults. The risk of diabetes increases with age, with the percentage of adults with diabetes peaking at 29.2% among those aged 65 or above. These statistics highlight the significant impact that diabetes has on the U.S. population.
Moreover, the shift towards preventive healthcare is also contributing to the growth of the U.S. over-the-counter (OTC) glucose biosensors industry. Consumers increasingly prioritize health management to avoid chronic diseases such as diabetes, driven by rising awareness, government initiatives, and technological advancements. Preventive healthcare emphasizes early detection and continuous monitoring, fueling demand for accessible and user-friendly glucose monitoring devices.
OTC glucose biosensors such as Stelo and Lingo provide individuals with convenient, non-prescription options to monitor blood glucose levels at home. These devices offer ease of use with compact designs and seamless smartphone integration for real-time tracking and data analysis. Stelo and Lingo support proactive health management, enabling users to detect early changes in their glucose levels and take timely action, promoting a preventive approach to diabetes care.
Market Concentration & Characteristics
The U.S. over-the-counter glucose biosensors industry is experiencing high growth, driven by the rising prevalence of diabetes and prediabetes, the increasing shift towards preventive healthcare, and the growing adoption of glucose biosensors by athletes.
The U.S. industry is characterized by a high degree of innovation, owing to the increasing focus of market players to develop user-centric products. Moreover, advancements in wireless connectivity have led to the development of more compact and user-friendly devices that can seamlessly integrate with smartphones. This integration allows for real-time data sharing with healthcare providers, enhancing remote patient monitoring capabilities. Additionally, the competitive landscape among U.S. healthcare technology companies further encourages innovation, as companies focus on developing more accurate, cost-effective, and user-friendly biosensors to meet evolving patient needs.
The industry has not witnessed any notable mergers or acquisitions specifically targeting OTC glucose biosensors, as the market is evolving, with companies focusing on product innovation rather than consolidation. This low M&A activity signifies the early stage of development in this sector, where companies are focusing on the enhancement of sensor accuracy and usability and the development of breakthrough technologies over strategic partnerships or acquisitions.
 To learn more about this report, Download Free Sample Report
The Food and Drug Administration (FDA) is the primary body overseeing the regulatory landscape of the industry. Regulations such as the FDA's 510(k) review process ensure that new devices meet the expected regulatory standards, promoting safety and efficacy. However, stringent approval processes can delay market entry for innovative products, thereby limiting consumer access to advanced monitoring technologies. While these regulations are crucial for ensuring device safety, they also determine how quickly and widely new glucose monitoring technologies consumers can adopt.
The threat of substitutes in the industry is increasingly significant, primarily due to the advent of Continuous Glucose Monitors (CGMs) and alternative monitoring methods. Traditional Self-Monitoring Blood Glucose (SMBG) devices face competition from CGMs such as Dexcom's Stelo and Abbott's Libre Rio, as they have recently received FDA approval for OTC use. The rise of smart wearable technology can offer a further substitute threat. Devices that integrate glucose monitoring with fitness tracking can attract health-conscious consumers who prefer multifunctional gadgets over dedicated glucose meters.
The U.S. industry have a significant end-user concentration, primarily among individuals managing diabetes or prediabetes independently. End-user concentration is notably high among active and technologically aware consumers. Healthcare Professional Offices (HCPs), specialty clinics, and homecare users are some of the major end-users owing to the high accessibility of OTC devices.
End-use Insights
Homecare dominated the market and accounted for the largest revenue share in 2024 and is expected to witness the fastest growth over the forecast period owing to the increasing prevalence of diabetes in the elderly population and the growing demand for convenient, patient-centric healthcare solutions. OTC glucose biosensors, which allow patients to monitor their blood glucose levels without requiring a prescription, are witnessing demand among individuals managing diabetes at home.
The adoption of these devices in the homecare segment is supported by the advancements in sensor technology, which have improved accuracy, ease of use, and affordability. Similarly, the accessibility of OTC glucose biosensors has reduced barriers for underserved populations, including those without significant access to healthcare facilities. Additionally, the increasing shift toward value-based care in the U.S. healthcare system emphasizes cost-effective management, which homecare solutions address effectively.
 To learn more about this report, Download Free Sample Report
The Healthcare Professional Offices (HCPs) segment, which includes private practices and outpatient settings managed by primary care physicians, nurse practitioners (NPs), and physician assistants (PAs), is witnessing significant growth in the U.S. OTC glucose biosensors market. As more patients seek regular monitoring of their blood glucose levels, HCPs are adopting advanced glucose biosensors to enhance patient care. According to the State of the Primary Care Workforce, 2023, there were 268,297 primary care physicians in the U.S in 2021.
Moreover, according to the same source, there were 26,455 PAs and 270,660 NPs working in primary care in the country. This surge in the number of NPs and PAs indicates a significant shift towards a more collaborative and accessible model of healthcare delivery, particularly in managing chronic conditions such as diabetes. With more providers available to implement and utilize advanced glucose biosensors, HCPs are expected to meet the rising demand for effective diabetes management solutions, thereby contributing to the segment growth.
Key U.S. Over-the-Counter Glucose Biosensors Company Insights
Some key providers in the industry are DexCom, Inc., and Abbott. These pioneering companies offer OTC glucose biosensors and have leveraged their technological expertise to establish a foothold in this emerging market. Both companies focus on affordability, ease of use, and accessibility. The increasing consumer awareness and adoption of biosensor technology are expected to intensify the competitive rivalry between the market players.
Key U.S. Over-the-Counter Glucose Biosensors Companies:
- DexCom, Inc.
- Abbott
Prism AI by Grand View Research Free to tryAsk a question about the U.S. Over-the-Counter glucose biosensors marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Recent Developments
-
In June 2024, Abbott received FDA clearance for its two new over-the-counter continuous glucose monitoring systems, Libre Rio and Lingo. Lingo targets consumers seeking to improve their health, while Libre Rio is designed for people aged 18 years and above with Type 2 diabetes who don't use insulin. Both systems leverage Abbott's advanced FreeStyle Libre technology to enhance glucose management and overall wellness.
-
In March 2024, Dexcom received FDA clearance for Stelo, the first OTC glucose biosensor, for adults with Type 2 diabetes not using insulin. This innovation enhances access to continuous glucose monitoring technology in the country.
U.S. Over-the-Counter Glucose Biosensors Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 448.5 million
Revenue forecast in 2030
USD 771.6 million
Growth rate
CAGR of 11.5% from 2025 to 2030
Base year for estimation
2024
Historical data
2018 - 2023
Forecast period
2024 - 2030
Quantitative units
Revenue in USD million and CAGR from 2025 to 2030
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
End-use
Country scope
U.S.
Key companies profiled
Abbott; DexCom, Inc.
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
U.S. Over-the-Counter Glucose Biosensors Market Report Segmentation
This report forecasts revenue growth at country levels and analyzes the latest industry trends in each of the sub-segments from 2018 to 2030. For this study, Grand View Research has segmented the U.S. over-the-counter glucose biosensors market report based on end use:
-
End-use Outlook (Revenue, USD Million, 2018 - 2030)
-
Healthcare Professional Offices (HCPs)
-
Specialty Clinics
-
Homecare
-
Frequently Asked Questions About This Report
The U.S. over-the-counter glucose biosensors market size was estimated at USD 105.3 million in 2024 and is expected to reach USD 448.5 million in 2025.
The U.S. over-the-counter (OTC) glucose biosensors market is expected to grow at a compound annual growth rate (CAGR) of 11.5% from 2025 to 2030 to reach USD 771.6 million by 2030.
In terms of revenue, homecare dominated the market with the largest market share of 48.6% in 2024. This high share is attributable to the increasing prevalence of diabetes in the elderly population and the growing demand for convenient, patient-centric healthcare solutions.
Some key players operating in the U.S. OTC glucose biosensors market include DexCom, Inc.; and Abbott.
Key factors driving the market's growth include the increasing prevalence of diabetes and prediabetes, the shift towards preventive healthcare, and the increased adoption of glucose biosensors by athletes.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


