
- Home
- »
- Animal Health
- »
-
Veterinary Biomarkers Market Size, Share Report 2026-2033GVR Report cover

Veterinary Biomarkers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Animal (Companion Animals, Production Animals), By Product (Biomarkers, Kits & Reagents, Instruments), By Application, By Disease Type, By End Use, By Region, And Segment Forecasts
Market Size, 2025
$1.1BMarket Estimate, 2026
$1.2BMarket Forecast, 2033
$2.6BCAGR, 2026–2033
12.1%Veterinary Biomarkers Market Summary
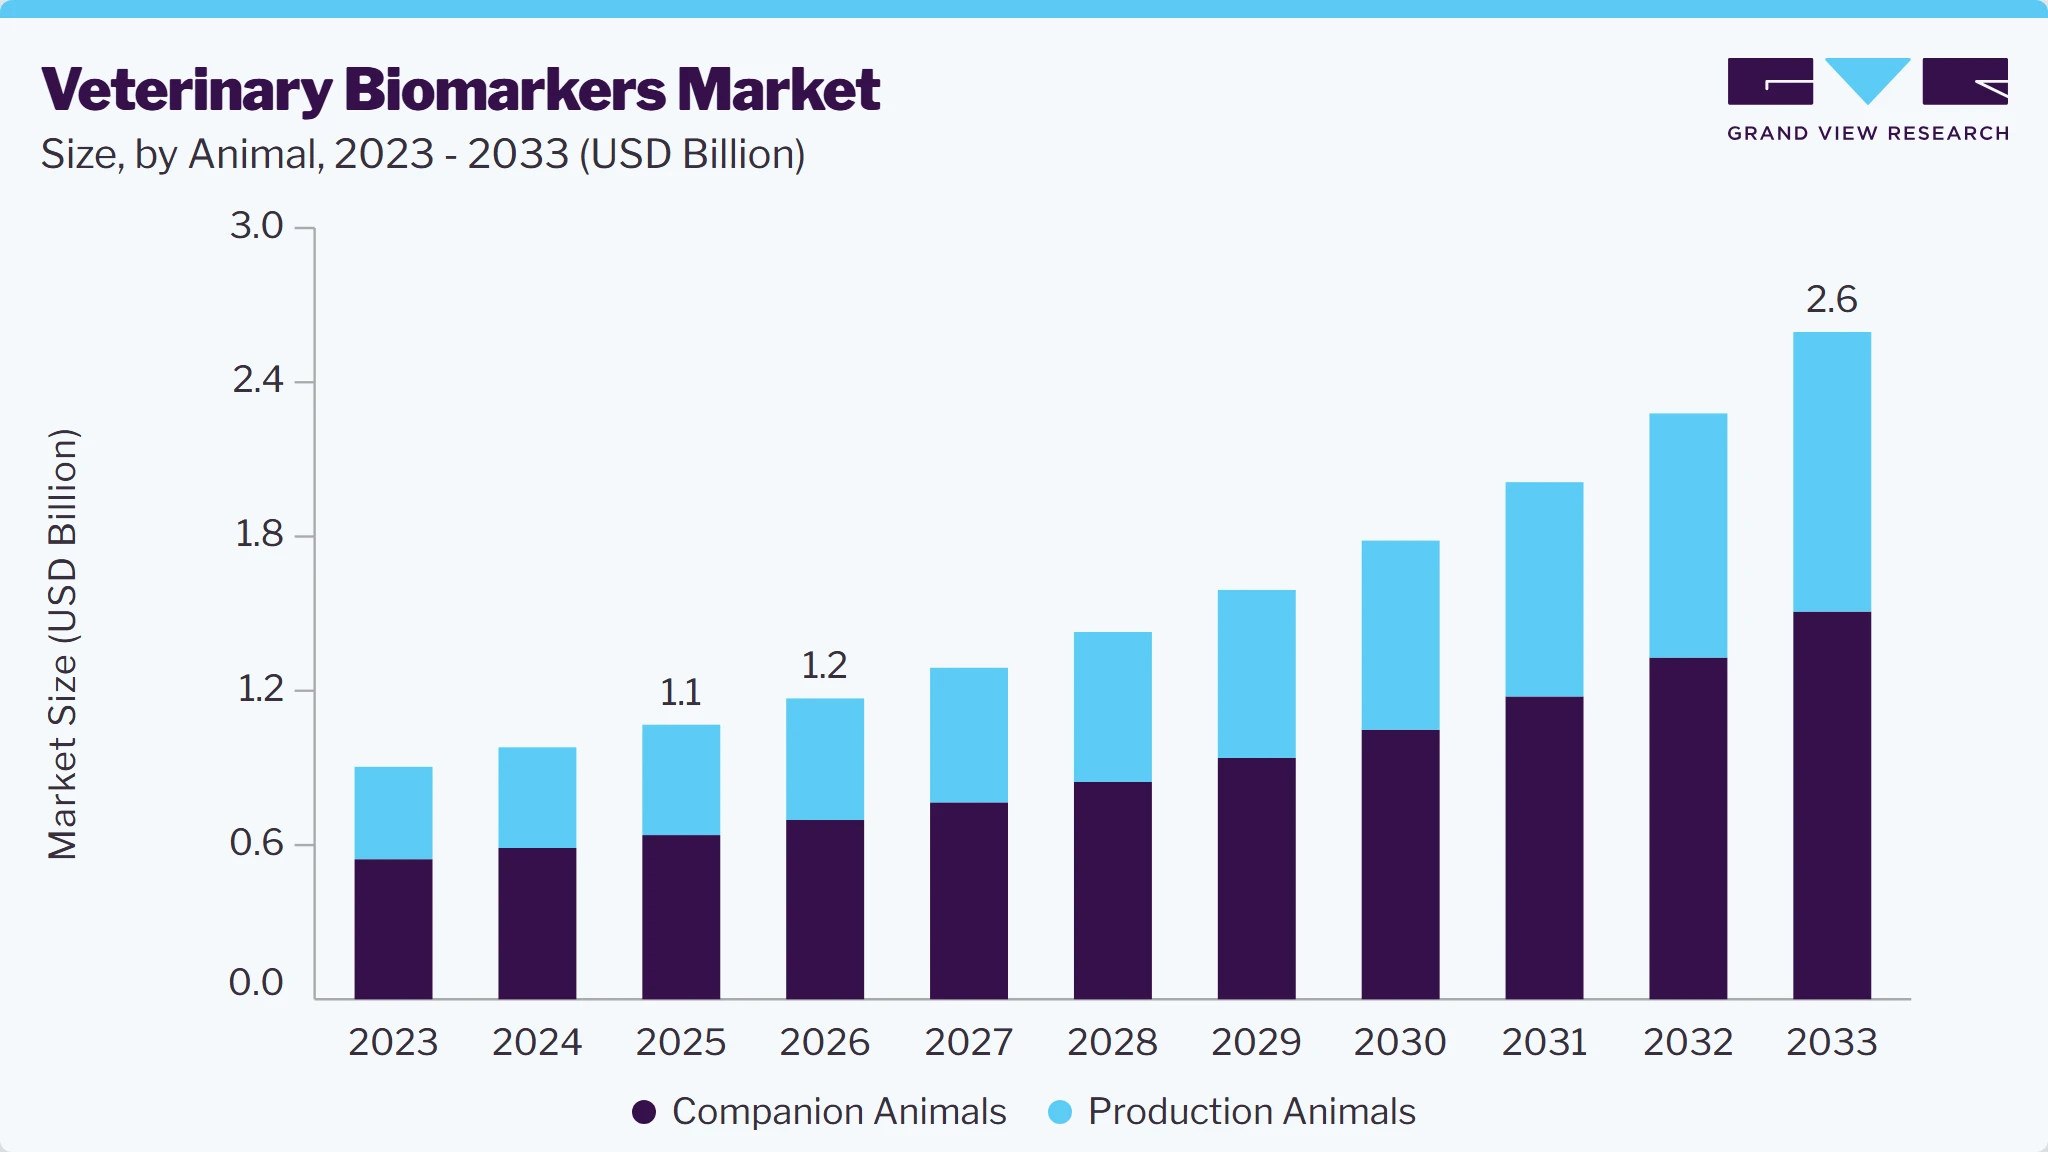
The global veterinary biomarkers market size was valued at USD 1.1 billion in 2025 and is projected to grow from USD 1.2 billion in 2026 to USD 2.6 billion by 2033, at a CAGR of 12.1% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 33.0% in 2025. The increasing prevalence of chronic conditions such as cancer and cardiovascular diseases in animals is significantly increasing the demand for biomarker-based assay diagnostic kits in veterinary applications to predict disease in its early stages.
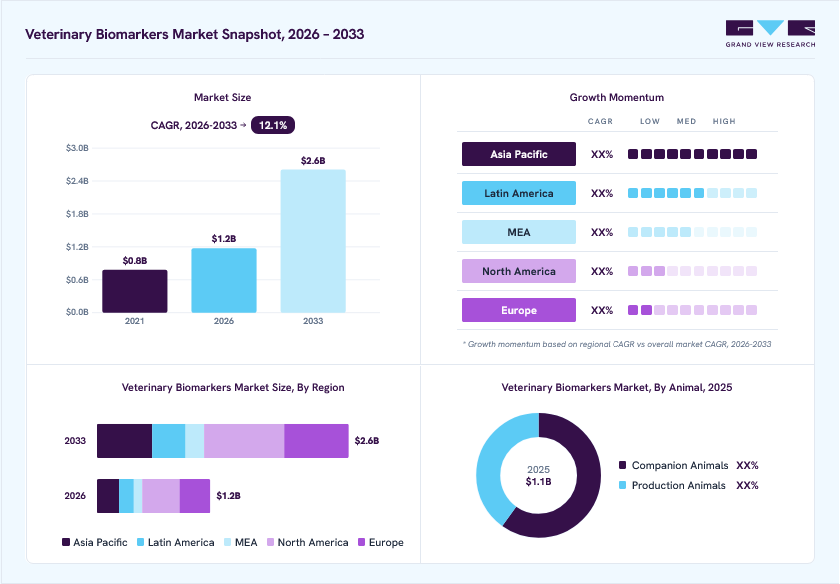 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By animal: Companion animals segment held the largest market share of 59.8% in 2025.
- By product: Biomarkers, kits & reagents segment held the largest market share of 76.3% in 2025.
- By application: Disease diagnostics segment held the largest market share of 48.9% in 2025.
- By disease type: Inflammatory & infectious diseases segment held the largest market share of 33.2% in 2025.
- By end use: Veterinary hospitals & clinics segment held the largest market share of 56.5% in 2025.
Regional Highlights
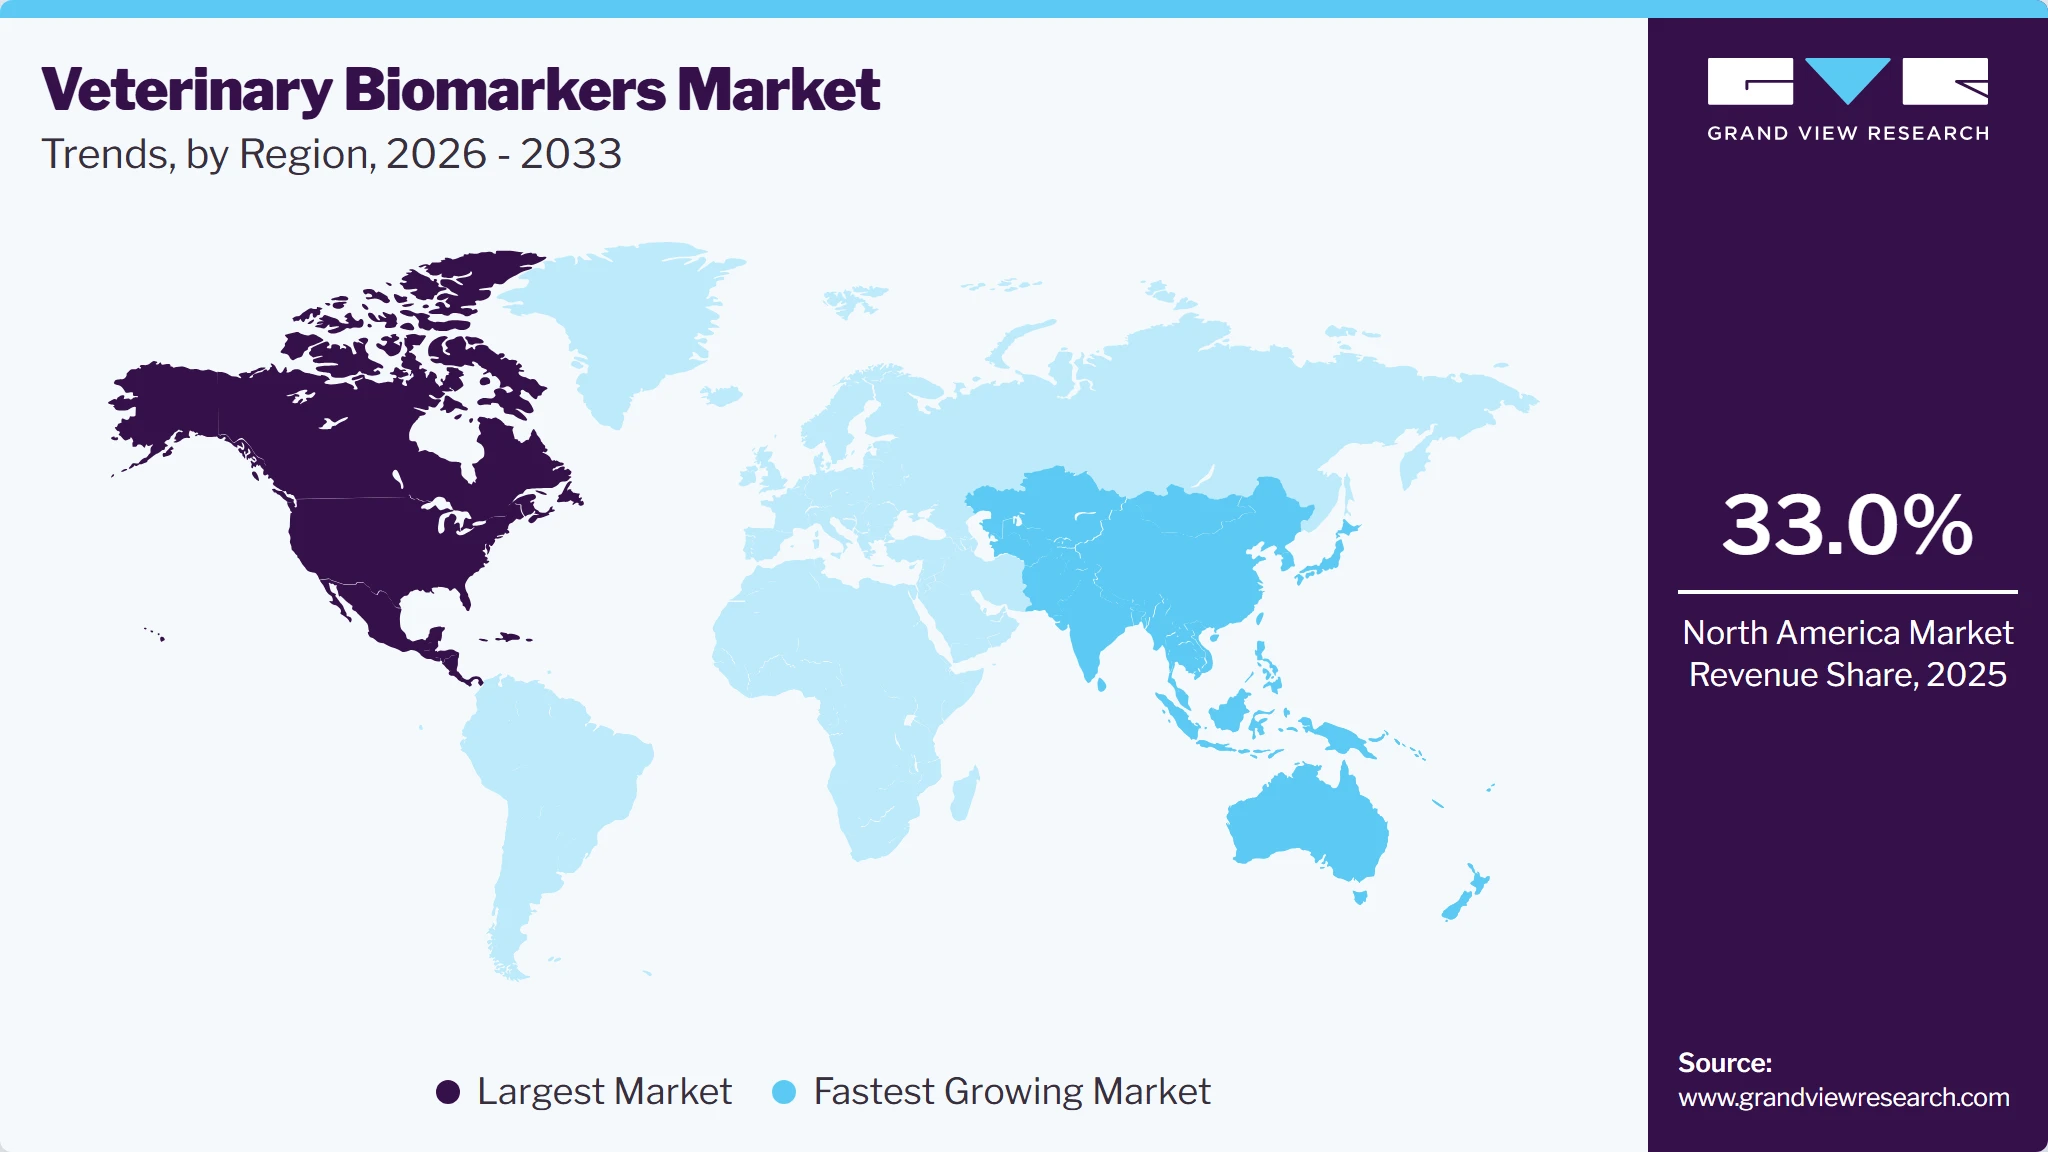
- Largest regional market: North America (33.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 1.1 Billion
- Estimated market size in 2026: USD 1.2 Billion
- Projected market size by 2033: USD 2.6 Billion
- CAGR (2026-2033): 12.1%
Prism AI by Grand View Research Free to tryAsk a question about the veterinary biomarkers market✓Every figure cited from GVR research Prefer the report? Download free sample →The R&D activities implemented by key companies to enhance biomarker portfolios are fueling market growth.
 To learn more about this report, Download Free Sample Report
Market Dynamics
The veterinary biomarkers industry is witnessing significant growth, driven by the rising prevalence of chronic and infectious diseases in companion and production animals, increasing pet humanization, and higher spending on animal healthcare. Pet owners are becoming more proactive in seeking preventive care, routine health screening, and early disease diagnosis, leading to greater adoption of biomarker-based diagnostic tests. The growing emphasis on precision veterinary medicine is further accelerating demand for biomarkers that enable early disease detection, disease monitoring, and personalized treatment strategies, ultimately improving clinical outcomes and quality of animal care.
In addition, increasing expenditure on pet healthcare is creating favorable conditions for the adoption of advanced veterinary diagnostics. According to the American Pet Products Association (APPA), U.S. pet industry expenditures reached USD 158 billion in 2025 and are projected to increase to USD 165 billion in 2026, while pet ownership remained strong with 95 million U.S. households owning at least one pet. Rising investments by pet owners in preventive healthcare, diagnostics, and specialized veterinary services are encouraging veterinary clinics and diagnostic laboratories to adopt biomarker-based testing solutions. Coupled with continuous advancements in molecular diagnostics and growing investments in biomarker research by key industry players, these trends are expected to support the sustained growth of the veterinary biomarkers market.
The increasing prevalence of cardiac disorders in companion animals is driving the demand for veterinary biomarkers, as early and accurate diagnosis is essential for effective disease management. For instance, according to the Purina Institute, cardiac disease affects approximately 10% of dogs and 15% of cats, making it one of the most common health conditions in companion animals. In dogs, myxomatous mitral valve disease (MMVD) is more prevalent in smaller breeds, while larger breeds are more susceptible to dilated cardiomyopathy (DCM). In cats, hypertrophic cardiomyopathy (HCM) is the most frequently diagnosed cardiac condition. Since many affected animals remain asymptomatic during the early stages of disease, advanced biomarker-based diagnostic tests are increasingly being adopted to detect cardiac abnormalities before the onset of clinical signs.
Early identification of heart disease enables veterinarians to classify disease severity, initiate timely treatment, and improve long-term clinical outcomes. Biomarkers such as cardiac troponins (cTnI and cTnT) and N-terminal pro-B-type natriuretic peptide (NT-proBNP) are gaining widespread use for diagnosing cardiac injury, monitoring disease progression, and differentiating cardiac disorders from other conditions. As the incidence of congestive heart failure and other cardiovascular diseases continues to rise among aging companion animals, the growing need for early screening, prognosis, and treatment monitoring is expected to significantly drive the growth of the veterinary biomarkers industry.
The high cost of biomarker discovery, validation, and commercialization remains a significant restraint on the veterinary biomarkers industry. Developing reliable veterinary biomarkers requires extensive research, advanced molecular technologies, clinical validation studies, and regulatory approvals, all of which involve substantial investment and lengthy development timelines. In addition, biomarker-based diagnostic tests often require specialized laboratory equipment and trained personnel, making them expensive for many veterinary clinics, particularly in developing regions. These cost barriers can limit the widespread adoption of advanced biomarker diagnostics and slow market growth, especially among small veterinary practices and price-sensitive end uses.
The increasing penetration of pet insurance presents a significant growth opportunity for the veterinary biomarkers industry by improving pet owners' access to advanced diagnostic services. As insurance providers continue to expand coverage for diagnostic testing, disease screening, and chronic disease management, financial barriers associated with biomarker-based tests are gradually being reduced. This encourages pet owners to opt for early disease detection and routine health monitoring, leading to greater utilization of biomarker-based diagnostics in veterinary clinics and hospitals. Furthermore, the growing awareness of preventive healthcare, coupled with the inclusion of advanced diagnostic procedures in pet insurance plans, is expected to accelerate the adoption of veterinary biomarkers and create new revenue opportunities for diagnostic companies and animal health providers.
Technology Benchmarking Analysis
Technology
Benchmarking Analysis
ELISA (Enzyme-Linked Immunosorbent Assay)
ELISA is the most widely adopted biomarker detection technology due to its high accuracy, affordability, and ease of use. It is extensively used for detecting inflammatory, infectious, hormonal, and metabolic biomarkers in routine veterinary diagnostics.
PCR/qPCR (Polymerase Chain Reaction)
PCR/qPCR offers excellent sensitivity and specificity for detecting genetic and infectious disease biomarkers. Its rapid turnaround time and increasing automation make it the preferred molecular diagnostic technology.
Multiplex Immunoassays
Multiplex assays simultaneously detect multiple biomarkers from a single sample, improving diagnostic efficiency and reducing testing time. They are increasingly adopted in veterinary laboratories and research settings.
Next-Generation Sequencing (NGS)
NGS enables comprehensive genomic analysis for biomarker discovery and precision veterinary medicine. Although relatively expensive, declining sequencing costs are expected to accelerate its adoption.
AI-Integrated Digital Biomarker Platforms AI-enabled platforms combine biomarker data with advanced analytics to improve disease prediction, diagnosis, and treatment monitoring. They represent an emerging technology with strong future growth potential.
Market Characteristics & Concentration
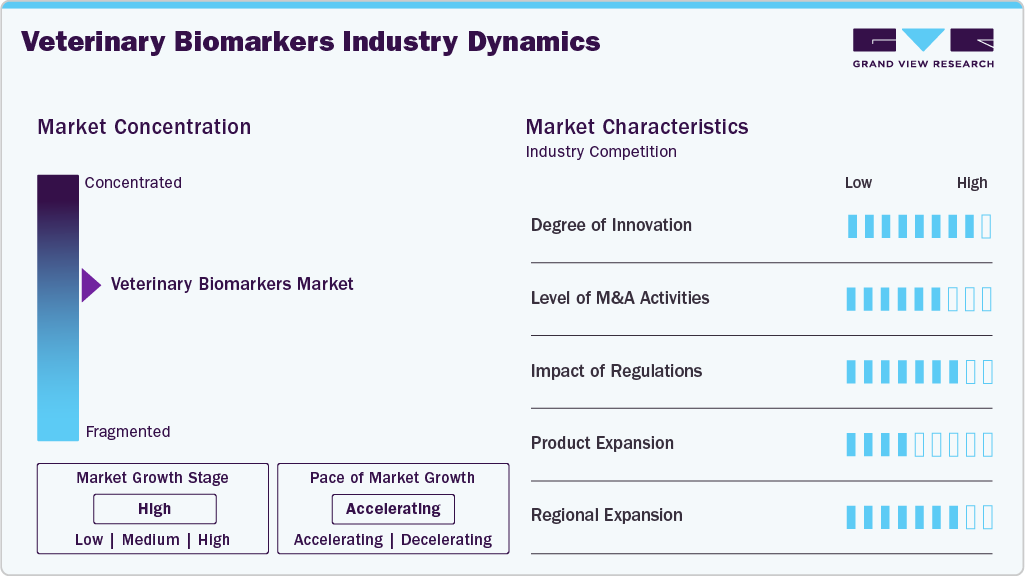
The veterinary biomarkers industry is moderately consolidated, with a mix of established animal health companies and specialized diagnostic firms competing through innovation and product development. Market participants are continuously investing in research and development, strategic collaborations, and technological advancements to improve biomarker accuracy, broaden diagnostic applications, and strengthen their product portfolios, thereby supporting the overall growth of the sector.
The veterinary biomarkers industry is characterized by a high level of innovation, driven by continuous advances in molecular diagnostics, genomics, proteomics, metabolomics, and precision veterinary medicine. Companies are developing novel biomarkers that enable earlier disease detection, improve disease monitoring, and support personalized treatment decisions across companion and production animals.
 To learn more about this report, Download Free Sample Report
The veterinary biomarkers industry has witnessed a moderate level of mergers, acquisitions, and strategic collaborations as companies seek to strengthen their biomarker discovery capabilities and expand their diagnostic portfolios. Established animal health companies are partnering with biotechnology firms, research organizations, and diagnostic laboratories to accelerate product development and commercialize new biomarker-based technologies. These collaborations also help companies gain access to advanced research platforms, expand their geographic presence, and enhance their competitive position within the veterinary diagnostics industry.
Regulations play a significant role in shaping the veterinary biomarkers sector by ensuring the safety, quality, and reliability of diagnostic products. Regulatory agencies such as the U.S. Food and Drug Administration (FDA), the European Medicines Agency (EMA), and other national authorities establish guidelines for the development, validation, and commercialization of veterinary diagnostic tests. Compliance with these standards is essential for product approval and commercialization. Although regulatory requirements can increase development timelines and costs, they also strengthen confidence among veterinarians and animal health professionals regarding the accuracy and clinical value of biomarker-based diagnostics.
The veterinary biomarkers industry faces limited direct substitutes because biomarkers provide objective biological information for early disease detection, prognosis, and treatment monitoring. Conventional diagnostic methods, including physical examinations, imaging techniques, microbiological culture, and routine laboratory tests, continue to play an important role in veterinary practice but often cannot deliver the same level of molecular or disease-specific insights. Consequently, biomarker-based diagnostics are increasingly being used alongside traditional diagnostic approaches to improve diagnostic accuracy and clinical decision-making.
The veterinary biomarkers sector is expanding in both developed and emerging regions, supported by rising pet ownership, increasing livestock production, and growing awareness of preventive animal healthcare. North America and Europe continue to lead the industry due to their well-established veterinary infrastructure, high expenditure on animal healthcare, and strong presence of diagnostic manufacturers.
Analyst Perspective
The veterinary biomarkers industry is expanding steadily, driven by the rising prevalence of chronic and infectious diseases in animals, increasing demand for early and accurate disease detection, and growing adoption of advanced veterinary diagnostics. Technological advancements in molecular diagnostics, immunoassays, genomics, proteomics, and liquid biopsy are expanding the identification and clinical application of disease-specific biomarkers. In addition, increasing veterinary research activities, growing use of biomarkers in drug development and treatment monitoring, and expanding adoption of point-of-care testing are further strengthening market growth, particularly across regions with established veterinary healthcare and research infrastructure.
Animal Insights
The companion animals segment led the market with the largest revenue share of 59.8% in 2025. Rising pet ownership, increasing expenditure on veterinary care, the growing prevalence of chronic diseases and cancer in companion animals, and the demand for early, non-invasive disease detection are driving the adoption of veterinary biomarkers. In addition, advancements in molecular diagnostics and increasing R&D investments are supporting segment growth. For instance, in 2025, IDEXX Laboratories launched IDEXX Cancer Dx, a blood-based diagnostic test that uses biomarker panels and multimodal bioanalytical techniques to detect canine lymphoma, thereby expanding access to biomarker-based cancer diagnostics in dogs. In addition, Cornell University College of Veterinary Medicine conducted a 2025–2026 study evaluating urinary cystatin B as an early biomarker of acute kidney injury in dogs, highlighting continued research into biomarkers for earlier disease detection and improved clinical outcomes.
The production animals segment is expected to grow at the fastest CAGR over the forecast period. Growth is driven by the high burden of infectious and metabolic diseases in livestock, the increasing need for early disease detection, the economic losses associated with livestock diseases, and the growing adoption of molecular and biomarker-based diagnostics for herd health management. For instance, in December 2025, the USDA Agricultural Research Service initiated a research project to develop improved diagnostic tools for theileriosis and babesiosis in livestock, including the use of parasite genome sequences to identify diagnostic targets and develop species-specific molecular and serological assays.
Product Insights
The biomarkers, kits & reagents segment led the market with the largest revenue share of 76.3% in 2025 and is anticipated to grow at the fastest CAGR during the forecast period. Segment growth is driven by the increasing prevalence of infectious and chronic diseases in animals, the growing demand for early and accurate diagnosis, and the wider adoption of immunoassay and molecular diagnostic technologies in veterinary practice. In addition, the availability of species-specific assays and the increasing use of biomarker testing for disease screening and monitoring are supporting demand for diagnostic kits and reagents. For instance, in 2025, DeepScan Diagnostics advanced its circulating cell-free DNA (cfDNA) biomarker testing for canine disease detection, supported by research evaluating cfDNA as a canine health biomarker and studies examining its application in neoplasia, lymphoma remission, splenic disease, and treatment-response monitoring. The company also presented multiple cfDNA studies at ESVONC 2025, highlighting the growing clinical application of molecular biomarkers for early disease detection and monitoring in dogs. Such developments are increasing the demand for specialized biomarker assays, kits, and associated reagents in veterinary diagnostics.
The instruments segment is anticipated to grow at a significant CAGR over the forecast period. Growth is driven by the increasing adoption of advanced veterinary diagnostic platforms, rising demand for rapid and accurate biomarker detection, and growing use of automated analyzers across veterinary hospitals, clinics, and diagnostic laboratories. Technological advancements in immunoassay, molecular diagnostic, and point-of-care platforms are enabling faster sample processing, improved analytical sensitivity, and accurate detection and quantification of disease-associated biomarkers. In addition, rising veterinary testing volumes, increasing adoption of point-of-care diagnostics, and growing investments in veterinary laboratory infrastructure are expected to drive demand for advanced diagnostic instruments over the forecast period.
Application Insights
The disease diagnostics segment led the market with the largest revenue share of over 48.9% in 2025. Segment growth is driven by the increasing emphasis on early disease detection and the growing adoption of rapid, biomarker-based, and molecular diagnostic testing. Increasing veterinary visits and demand for point-of-care testing are further supporting diagnostic applications. For instance, in March 2025, Antech launched trūRapid FOUR, an in-house canine vector-borne disease screening test that detects antibodies against Anaplasma, Ehrlichia, and Lyme C6, and heartworm antigen, using whole blood, serum, or plasma. The introduction of multi-disease screening solutions that enable rapid detection of disease-associated antibodies and antigens is strengthening the role of biomarkers in veterinary disease diagnostics.
The preclinical research segment is expected to grow at the fastest CAGR over the forecast period. Growth is driven by increasing R&D activities in veterinary drug development, expanding biomarker discovery programs, and growing use of molecular and genomic technologies to understand disease mechanisms and evaluate therapeutic response. Biomarkers are increasingly incorporated into research to support early disease detection, treatment response assessment, and the development of targeted therapies. For instance, the University of Minnesota College of Veterinary Medicine was conducting the COED study, which collects blood samples from dogs to develop a test for the early detection of canine osteosarcoma. Such research initiatives are expanding the identification and validation of novel biomarkers and supporting their application in veterinary preclinical and translational research.
Disease Type Insights
The inflammatory & infectious diseases segment led the market with the largest revenue share of 33.2% in 2025. The high burden of bacterial, viral, and parasitic infections in companion and production animals, increased disease surveillance, and the growing demand for rapid, early identification of pathogens and inflammatory responses are primarily driving the market growth. Biomarkers such as antigens, antibodies, acute-phase proteins, and inflammatory markers are increasingly used to support disease diagnosis and monitoring. For instance, in July 2025, ICAR-NIVEDI released three new diagnostic kits, Capripox Detect, FLUKEVEY, and CYSTISURE, for detecting capripox infections, bovine fasciolosis, and porcine cysticercosis, respectively. The expansion of disease-specific diagnostic tools, coupled with strengthened livestock surveillance programs, is supporting the adoption of biomarkers for the management of infectious and inflammatory diseases.
The oncology segment is expected to grow at the fastest CAGR over the forecast period. Growth is driven by the rising burden of cancer in companion animals, the increasing demand for early, non-invasive cancer detection, and the expanding adoption of liquid biopsy, genomic profiling, and tumor-specific biomarkers for diagnosis and treatment monitoring. According to the 2026 AAHA Oncology Guidelines, cancer affects approximately 50% of dogs and 30% of cats over 10 years of age, highlighting a substantial need for improved cancer diagnostics. The guidelines also identify liquid biopsy and precision medicine profiling as emerging approaches in veterinary oncology, using blood, urine, and tumor samples to detect biomarkers and characterize tumors. The growing cancer burden, coupled with advances in molecular diagnostics and precision oncology, is expected to accelerate the adoption of biomarkers in this segment.
End Use Insights
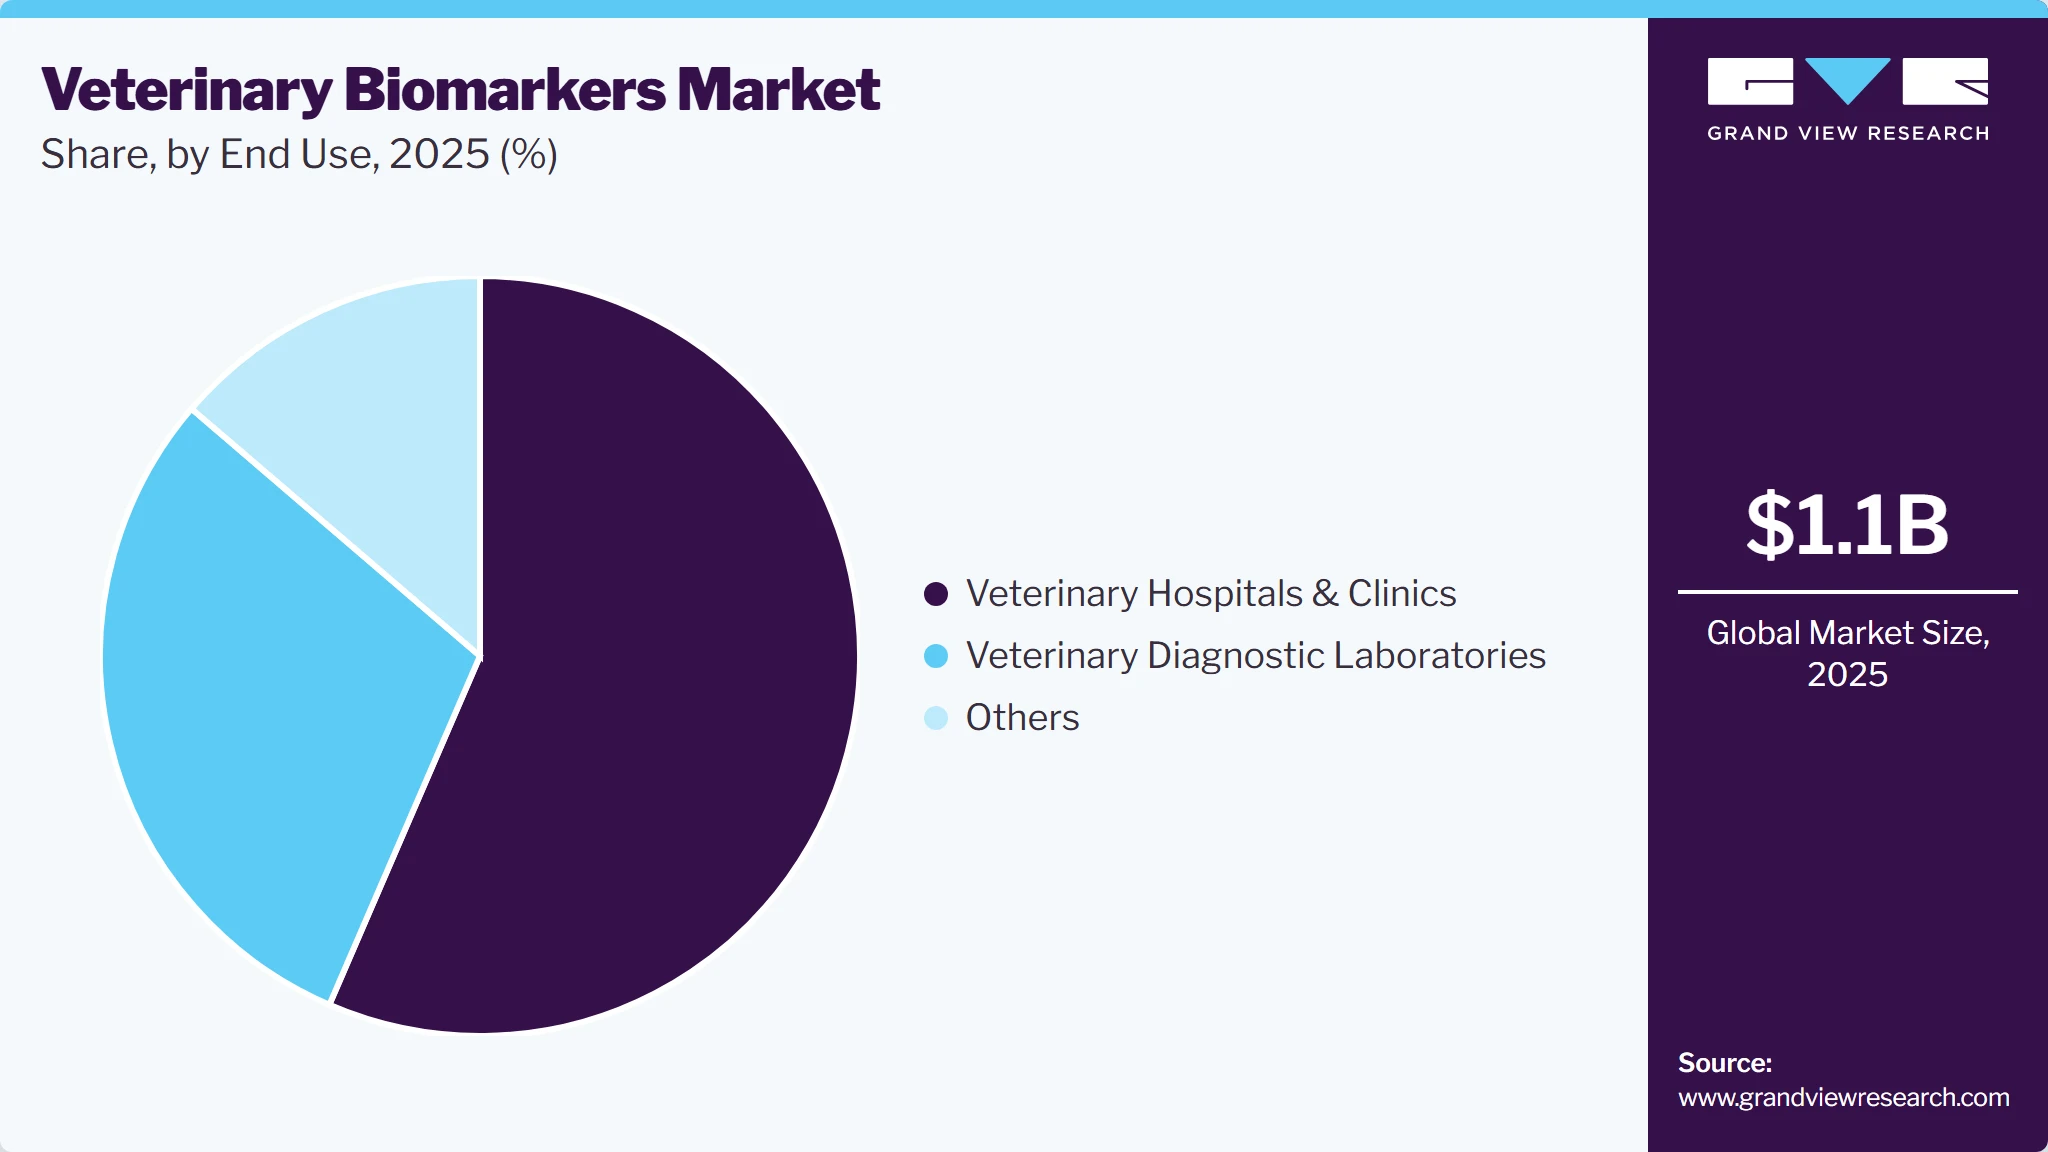
The veterinary hospitals & clinics segment led the market with the largest revenue share of 56.5% in 2025. The high volume of animal consultations, the increasing adoption of point-of-care diagnostics, the rising demand for rapid clinical decision-making, and the growing availability of advanced biomarker tests in veterinary practices are primarily driving segment growth. Hospitals and clinics increasingly use in-house diagnostic platforms to evaluate disease-associated biomarkers and obtain results during patient visits. For instance, in June 2025, IDEXX launched the Catalyst Cortisol Test, enabling veterinarians to quantitatively measure cortisol at the point of care to support the diagnosis and management of Addison’s and Cushing’s diseases in dogs. The test was scheduled for global rollout to an installed base of more than 75,000 Catalyst chemistry analyzers, reflecting the expanding infrastructure for in-clinic biomarker testing and supporting segment growth.
 To learn more about this report, Download Free Sample Report
The others segment is anticipated to grow at the fastest CAGR over the forecast period. The segment includes academic and research institutes, government veterinary laboratories, zoos, wildlife conservation centers, animal shelters, and other organizations involved in animal health research, surveillance, and diagnostics. Growth is driven by increasing veterinary biomarker research, expansion of animal disease surveillance programs, rising government funding for animal health research, and growing collaboration between academic institutions and diagnostic organizations. In addition, the increasing use of biomarkers in drug discovery and preclinical studies, zoonotic disease surveillance, wildlife disease monitoring, and the development and validation of novel veterinary diagnostics is driving demand across these end uses. The growing emphasis on One Health initiatives and the early identification of emerging animal diseases is expected to further accelerate the adoption of biomarker-based technologies across research and surveillance settings.
Regional Insights
North America dominated the global veterinary biomarkers market with the largest revenue share of 33.0% in 2025,driven by the strong presence of veterinary diagnostic companies, high adoption of advanced diagnostic technologies, increasing animal healthcare expenditure, and expanding research on biomarkers for early disease detection and treatment monitoring. The region also benefits from an established network of veterinary hospitals, diagnostic laboratories, and research institutions, supporting the adoption of molecular, immunoassay, and point-of-care biomarker testing. According to the 2025 AVMA Economic State of the Veterinary Profession report, veterinary services accounted for 78.5% of total revenue across U.S. veterinary practices in 2024, including laboratory testing, imaging, examinations, hospitalization, and other medical services. In companion animal-exclusive practices, veterinary services accounted for an even higher share of total revenue at 79.2%, highlighting strong utilization of clinical and diagnostic services that drive demand for veterinary biomarker testing in the region.
 To learn more about this report, Download Free Sample Report
U.S. Veterinary Biomarkers Market Trends
The veterinary biomarkers market in the U.S. accounted for the largest market revenue share in North America in 2025, driven by high pet ownership, substantial veterinary care expenditure, advanced diagnostic infrastructure, and increasing adoption of molecular and biomarker-based tests for early disease detection and monitoring. The presence of leading animal health and veterinary diagnostic companies, coupled with growing research activities and demand for preventive care, further supports market growth. According to the American Pet Products Association (APPA), 95 million U.S. households owned at least one pet in 2025, while total U.S. pet industry expenditure reached USD 158 billion. The large pet population and significant spending on animal health create a strong environment for the adoption of advanced veterinary diagnostics and biomarker-based testing in the country.
Canada veterinary biomarkers marketis driven by growing investments in animal health research, expanding veterinary diagnostic infrastructure, increasing adoption of molecular and omics-based technologies, and strengthening animal disease surveillance programs. The country's large companion animal population and growing emphasis on early disease detection further support biomarker testing. In June 2025, the Governments of Canada and Saskatchewan announced USD 3.4 million in funding over four years to develop two research facilities at the University of Saskatchewan, including an Omics Resource Center at the Western College of Veterinary Medicine. The center is intended to expand genomics, proteomics, and metabolomics research capabilities, supporting advanced animal health research and the identification and analysis of disease-related biomarkers.
Europe Veterinary Biomarkers Market Trends
The veterinary biomarkers market in Europe is growing, driven by increasing adoption of advanced veterinary diagnostics, rising prevalence of chronic and infectious diseases in animals, and growing demand for early and accurate disease detection. The region benefits from well-established veterinary healthcare infrastructure, increasing expenditure on companion animal care, and strong research activities in animal health and life sciences. In addition, expanding use of molecular diagnostics, immunoassays, genomic technologies, and point-of-care testing, coupled with growing disease surveillance and One Health initiatives, is accelerating the integration of biomarkers into veterinary diagnosis, disease monitoring, and research across Europe.
The Germany veterinary biomarkers market held the significant share in Europe in 2025, fueled by the country's large companion animal population, established veterinary laboratory network, strong animal disease surveillance, and increasing adoption of molecular and serological diagnostics. Germany also benefits from extensive government-backed research and reference laboratory infrastructure for infectious diseases and zoonoses. In 2025, the Friedrich-Loeffler-Institut (FLI) authorized several new veterinary infectious-disease diagnostics, including assays for bluetongue virus, foot-and-mouth disease, and African swine fever, reflecting continued expansion of advanced animal disease testing. In addition, Germany had 33.4 million companion animals in 2025, including 15.7 million cats and 10.0 million dogs, creating a substantial population requiring disease screening and diagnostic services. These factors are supporting demand for biomarker-based testing across companion and production animals.
The veterinary biomarkers market in the UK is expected to grow at a significant CAGR over the forecast period. The market is driven by increasing investment in animal disease surveillance, strong veterinary research capabilities, and growing adoption of genomics and molecular diagnostics for pathogen detection and disease monitoring. The country's focus on biosecurity and One Health approaches is further encouraging advanced diagnostic research across livestock, companion animals, and wildlife. For instance, in May 2025, the UK government announced approximately USD 13.3 million in funding for the Genomics for Animal and Plant Disease Consortium (GAP-DC), led by the Animal and Plant Health Agency (APHA). The program uses advanced genome sequencing to detect, identify, and track pathogens across animal, plant, and aquatic environments. Such investment in genomic surveillance and pathogen characterization is expected to support the development and adoption of advanced veterinary biomarkers and molecular diagnostic technologies in the UK.
Asia Pacific Veterinary Biomarkers Market Trends
The veterinary biomarkers market in the Asia Pacific is expected to grow at the fastest CAGR over the forecast period, driven by the region’s large livestock base, intensification of commercial animal farming, recurring outbreaks of transboundary animal diseases, and increasing government focus on livestock productivity and biosecurity. Rapid development of organized dairy, poultry, and swine industries across China, India, and Southeast Asia is increasing the need for disease screening and herd-level health monitoring. In addition, government-led vaccination and disease eradication programs are driving greater demand for serological and molecular testing to assess infection, immunity, and disease prevalence. The expansion of domestic animal-health biotechnology industries and the increasing localization of veterinary diagnostic manufacturing are further improving the availability of biomarker-based tests across the region.
The China veterinary biomarkers marketis accelerating, driven by the modernization of veterinary diagnostic standards, rapid development of the domestic pet healthcare sector, and increasing need for sensitive and standardized testing for economically important animal diseases. Growing regulatory emphasis on diagnostic quality and the expansion of veterinary laboratory capabilities are further encouraging the use of molecular and serological biomarkers. For instance, in May 2025, China released the national standard GB/T 18646-2025 on diagnostic techniques for animal brucellosis, replacing the 2018 standard and taking effect in December 2025. In addition, China's Ministry of Agriculture and Rural Affairs reported 24 major animal diseases in December 2025, affecting approximately 103,035 animals, demonstrating the continued need for reliable disease detection and diagnostic technologies. These developments are supporting greater adoption of veterinary biomarker-based testing across China.
The veterinary biomarkers market in Japanis drivenby the increasing adoption of advanced veterinary diagnostics, growing research on disease-specific biomarkers, and rising demand for early detection and monitoring of chronic diseases in companion animals. Japan's strong capabilities in molecular biology, genomics, and veterinary research are supporting the development of biomarker-based approaches for oncology, renal disorders, infectious diseases, and other animal health conditions. In addition, the presence of specialized veterinary hospitals, university veterinary research centers, and diagnostic laboratories is facilitating the translation of novel biomarkers into clinical testing. The growing use of molecular and immunological techniques for disease characterization and treatment monitoring is expected to further support the adoption of veterinary biomarkers in Japan.
The India veterinary biomarkers marketis experiencing rapid growth, driven by expanding government investment in animal disease diagnostics, strengthening laboratory infrastructure, and increasing use of serological and molecular testing under national livestock disease-control programs. The growing emphasis on monitoring vaccination response and detecting economically important diseases is creating demand for antibodies, antigens, molecular markers, and other diagnostic biomarkers. According to the Department of Animal Husbandry and Dairying’s Annual Report 2024–25, 36,592 samples were analyzed during 2024 across virology, bacteriology, parasitology, pathology, and toxicology laboratories at the Central Disease Diagnostic Laboratory (IVRI). In addition, RT-PCR testing for Newcastle disease, avian influenza, African swine fever, and leptospirosis was initiated at the Northern Regional Disease Diagnostic Laboratory, demonstrating the expansion of molecular diagnostic capabilities supporting veterinary biomarker adoption in India.
Latin America Veterinary Biomarkers Market Trends
The veterinary biomarkers market in the Latin America is expected to grow significantly, due to the region’s large cattle, poultry, and swine industries and increasing need to minimize productivity losses associated with animal diseases. The expansion of export-oriented meat and dairy production is encouraging producers to strengthen herd health monitoring, disease certification, and diagnostic testing to meet international animal health and food safety requirements. In addition, recurring risks posed by transboundary and zoonotic diseases are increasing the need for rapid identification of infections across commercial farms. The modernization of livestock production systems, expansion of veterinary laboratory capacity, and increasing participation of Brazil, Mexico, and Argentina in animal health research are further supporting the adoption of veterinary biomarkers across the region.
The Brazil veterinary biomarkers market is experiencing robust growth, as increasing modernization of federal animal diagnostic laboratories, adoption of standardized molecular testing methods, and rising demand for disease-specific diagnostic kits strengthen the country’s veterinary testing capabilities. Brazil’s extensive livestock industry and strict sanitary requirements for animal production and trade are also increasing the need for reliable laboratory testing and disease monitoring. For instance, in July 2025, Brazil’s Ministry of Agriculture and Livestock (MAPA) initiated procurement of diagnostic kits and biological inputs for the Animal Diagnosis and Genetic Identification Unit at the Federal Agricultural Defense Laboratory in Recife (LFDA-PE). The procurement covers laboratory requirements for 2025 and 2026, demonstrating continued investment in veterinary diagnostic capacity and supporting demand for biomarker-based kits and reagents in Brazil.
Middle East & Africa Veterinary Biomarkers Market Trends
The veterinary biomarkers market in the Middle East & Africa is witnessing steady growth, driven by increasing focus on livestock health, rising demand for improved animal disease management, and gradual expansion of veterinary diagnostic capabilities. The region’s dependence on livestock for meat and dairy production is encouraging greater emphasis on maintaining animal health and productivity. In addition, growing government initiatives to strengthen veterinary services, increasing need to control zoonotic and transboundary animal diseases, and the development of animal health laboratories are supporting the use of biomarkers for disease detection and monitoring. Improving access to molecular and serological testing across emerging markets is further expected to support market growth over the forecast period.
The Saudi Arabia veterinary biomarkers market is rapidly growing, driven by the increasing digitalization of animal health management, the modernization of veterinary laboratories, and a growing emphasis on accurate disease testing for the country’s livestock population. Government efforts to strengthen laboratory quality standards and integrate advanced technologies into disease detection are creating a favorable environment for biomarker-based diagnostics. For instance, in August 2025, the Weqaa Center’s Jazan laboratory received ISO/IEC 17025 accreditation for veterinary testing, covering specialized tests for priority diseases including Rift Valley fever, peste des petits ruminants, foot-and-mouth disease, brucellosis, and toxoplasmosis. The center also established a 2025–2026 plan to expand laboratory accreditation in additional regions, strengthening the country’s capacity for reliable veterinary disease testing and supporting the adoption of veterinary biomarkers.
Key Veterinary Biomarkers Company Insights
The global market is fairly competitive. Key companies deploy strategic initiatives, such as product development, launches, and sales & marketing strategies to increase product awareness and regional expansions and partnerships to strengthen their market share. Market players are also involved in conducting clinical testing of their products, patent applications, and increasing product penetration.
Key Veterinary Biomarkers Companies
The following key companies have been profiled for this study on the veterinary biomarkers market.
-
Zoetis
-
Virbac
-
Life Diagnostics
-
ACUVET BIOTECH
-
Merck
-
IDEXX Laboratories, Inc.
-
MI:RNA Diagnostics Ltd.
-
Mercodia AB
-
Antech Diagnostics, Inc.
-
Avacta Animal Health Limited
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Established Players (Zoetis; Virbac; Merck; IDEXX Laboratories, Inc.; Antech Diagnostics, Inc. and others)
- Established players focus on expanding veterinary diagnostic and biomarker portfolios through product launches, acquisitions, R&D investments, and integration of laboratory and point-of-care testing solutions.
- Companies increasingly develop disease-specific assays for oncology, endocrine disorders, infectious diseases, and chronic conditions while expanding reference laboratory and in-clinic diagnostic capabilities.
- Strategic acquisitions and collaborations with biotechnology companies, veterinary hospitals, and research institutions help strengthen biomarker discovery and commercialization.
- These companies also leverage extensive veterinary distribution networks and installed diagnostic platforms to introduce new assays and expand adoption across major markets.
- Established companies benefit from strong brand recognition, extensive veterinary customer networks, broad diagnostic portfolios, established R&D capabilities, and substantial financial resources.
- Large installed bases of diagnostic instruments and reference laboratory networks enable companies to introduce new biomarker assays to existing customers and support recurring revenue from kits and reagents.
- Their ability to combine laboratory diagnostics, point-of-care testing, software, and clinical expertise provides an advantage in translating new biomarkers into commercially scalable veterinary diagnostic solutions.
- Established players may face higher operating and R&D costs, lengthy biomarker validation and commercialization processes, and greater organizational complexity.
- Maintaining large diagnostic networks and instrument platforms can increase capital and operational requirements.
Emerging Players (Life Diagnostics; Veterinary Biomarkers, Inc.; ACUVET BIOTECH; MI:RNA Diagnostics Ltd.; Mercodia AB; Avacta Animal Health Limited and other players)
- Emerging and specialized players focus on niche biomarker discovery, disease-specific assays, molecular diagnostics, immunoassays, and novel biomarker technologies.
- Their strategies often center on developing highly targeted solutions for oncology, cardiovascular disease, inflammatory conditions, metabolic disorders, and infectious diseases.
- Partnerships with universities, CROs, veterinary research institutions, diagnostic laboratories, and larger animal-health companies can support clinical validation and commercialization.
- These companies may also pursue licensing, technology partnerships, and geographic distribution agreements to expand market access without building extensive infrastructure independently.
- Specialized players benefit from focused scientific expertise, agile R&D structures, and the ability to target unmet diagnostic needs.
- Concentration on specific biomarkers or technology platforms allows them to respond rapidly to advances in genomics, proteomics, miRNA analysis, immunoassays, and precision veterinary medicine.
- Lower organizational complexity can facilitate faster product development and collaboration with academic and clinical research groups.
- Proprietary biomarker technologies and specialized intellectual property can also provide differentiation from broad veterinary diagnostic companies.
- Emerging players often face limited financial resources, smaller commercial footprints, lower brand recognition, and restricted global distribution compared with established companies.
- Biomarker discovery requires substantial clinical validation before widespread veterinary adoption, creating development and funding risks.
Recent Developments
-
In January 2026, IDEXX Laboratories announced the expansion of its Cancer Dx Panel to detect canine mast cell tumors, with availability planned for mid-2026 in North America. In addition to lymphoma detection, the expanded panel is expected to address more than one-third of canine cancer cases and uses proprietary cancer biomarkers for screening.
-
In August 2025, Carus Animal Health launched GIQuest, a clinically validated, patient-side fecal calprotectin lateral-flow test for dogs and cats. Fecal calprotectin is an inflammatory biomarker associated with neutrophilic infiltration of the intestinal mucosa, enabling non-invasive investigation and monitoring of gastrointestinal inflammation.
-
In August 2025, POP launched a 90-day canine health study with Innovative Pet Lab and Embark Veterinary, enrolling up to 100 dogs and combining gut biomarker test kits, DNA testing, nutrition interventions, and activity data to investigate canine immunity and long-term health.
Veterinary Biomarkers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.1 billion
Estimated market size in 2026
USD 1.2 billion
Projected market size by 2033
USD 2.6 billion
Growth rate
CAGR of 12.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Animal, product, application, disease type, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; Thailand; South Korea; Australia; Brazil; Argentina; South Africa; UAE; Saudi Arabia; Kuwait; Qatar; Oman
Key companies profiled
Zoetis; Virbac; Life Diagnostics; ACUVET BIOTECH; Merck; IDEXX Laboratories, Inc.; MI:RNA Diagnostics Ltd.; Mercodia AB; Antech Diagnostics, Inc.; Avacta Animal Health Limited.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Veterinary Biomarkers Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global veterinary biomarkers market report based on animal, product, application, disease type, end use, and region:
-
Animal Outlook (Revenue, USD Million, 2021 - 2033)
-
Companion Animals
-
Dogs
-
Cats
-
Horses
-
Others
-
-
Production Animals
-
Cattle
-
Pigs
-
Poultry
-
Others
-
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Biomarkers, Kits & Reagents
-
Instruments
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Disease Diagnostics
-
Preclinical Research
-
Others
-
-
Disease Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Inflammatory & Infectious Diseases
-
Cardiovascular Diseases
-
Musculoskeletal Diseases
-
Oncology
-
Others
-
-
End Use Outlook (Revenue, USD Million, 2021 - 2033)
-
Veterinary Diagnostic Laboratories
-
Veterinary Hospitals & Clinics
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
Thailand
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
UAE
-
Saudi Arabia
-
Kuwait
-
Qatar
-
Oman
-
-
Research Methodology
The veterinary biomarkers market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each veterinary biomarkers segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Animal
Revenue capture definition
Companion Animals
Revenue generated from veterinary biomarker products and services used for pet animals, including diagnostic procedures, medications, and cardiac care.
Dogs
Revenue derived from biomarker-based diagnostic tests, reagents, kits, and analytical instruments used for canine disease detection, health monitoring, therapeutic evaluation, and veterinary research.
Cats
Revenue attributable to veterinary biomarkers used for diagnosing, monitoring, and managing feline diseases, including assays and biomarker testing solutions for kidney disease, diabetes, infections, oncology, and other health conditions.
Horses
Revenue generated from biomarker products employed in equine health management, including the detection and monitoring of inflammatory, musculoskeletal, cardiovascular, metabolic, and performance-related disorders.
Others (Companion Animals)
Revenue generated from biomarker solutions used in companion animal species other than dogs, cats, and horses, including rabbits, birds, reptiles, ferrets, and other exotic pets.
Production Animals
Revenue generated from veterinary biomarker products and services used for the diagnosis and management of cardiovascular conditions in livestock raised for food and agricultural production.
Cattle
Revenue generated from biomarkers used for detecting infectious diseases, metabolic disorders, mastitis, reproductive health conditions, and production-related diseases in dairy and beef cattle.
Pigs
Revenue derived from biomarker products used for swine disease diagnosis, immune response assessment, herd health monitoring, and veterinary research applications.
Poultry
Revenue generated from biomarker assays and diagnostic solutions used to detect infectious diseases, evaluate vaccination responses, monitor flock health, and assess stress and productivity in poultry.
Others (Production Animals)
Revenue generated from biomarker products used in livestock species such as sheep, goats, aquaculture species, and other food-producing animals.
Segment - Product
Revenue capture definition
Biomarkers, Kits & Reagents
Revenue generated from the sale of biomarker assays, diagnostic kits, antibodies, reagents, calibration materials, controls, and other consumables used for veterinary biomarker detection, quantification, and analysis.
Instruments
Revenue generated from instruments and analytical systems used to detect, measure, and interpret veterinary biomarkers. This includes immunoassay analyzers, ELISA readers, fluorescence readers, multiplex analyzers, and other biomarker detection platforms.
Segment - Application
Revenue capture definition
Disease Diagnostics
Revenue generated from veterinary biomarker products used for identifying, confirming, and monitoring animal diseases in clinical diagnostic settings. This includes biomarkers for infectious, inflammatory, metabolic, cardiovascular, oncological, and other diseases.
Preclinical Research
Revenue derived from veterinary biomarkers used during animal-based research studies to evaluate disease mechanisms, drug safety, therapeutic efficacy, vaccine responses, and biomarker validation before commercialization.
Others (Application)
Revenue generated from biomarker products used in applications beyond disease diagnosis and preclinical research, including treatment monitoring, prognostic assessment, wellness screening, toxicology studies, precision veterinary medicine, and biomarker discovery research.
Segment - Disease Type
Revenue capture definition
Inflammatory & Infectious Diseases
Revenue generated from biomarker products used to detect, diagnose, and monitor bacterial, viral, fungal, parasitic, and inflammatory diseases affecting companion and production animals.
Cardiovascular Diseases
Revenue generated from biomarkers utilized for the assessment, diagnosis, and monitoring of cardiac diseases and heart function in animals, including biomarkers associated with myocardial injury and heart failure.
Musculoskeletal Diseases
Revenue derived from biomarker solutions used to evaluate disorders affecting muscles, bones, joints, tendons, and connective tissues, including osteoarthritis, skeletal injuries, and inflammatory musculoskeletal conditions.
Oncology
Revenue generated from veterinary biomarkers used for cancer detection, Oncology characterization, disease progression monitoring, treatment response evaluation, and oncology research across animal species.
Others (Disease Type)
Revenue generated from biomarker products used in the diagnosis and monitoring of disease areas not covered under the above segments, including renal, hepatic, endocrine, neurological, respiratory, gastrointestinal, and reproductive disorders.
Segment – End Use
Revenue capture definition
Veterinary Diagnostic Laboratories
Revenue generated from veterinary biomarker products purchased and utilized by independent, commercial, and reference diagnostic laboratories to perform biomarker testing, disease diagnosis, and laboratory analysis for veterinary healthcare providers and animal health organizations.
Veterinary Hospitals & Clinics
Revenue generated from biomarker assays, kits, reagents, and readers used within veterinary hospitals and clinics for in-house disease diagnosis, patient monitoring, treatment decision-making, and routine clinical care.
Others (End Use)
Revenue generated from veterinary biomarker products utilized by academic and research institutes, government veterinary laboratories, zoos, wildlife conservation centers, animal shelters, and other organizations involved in animal health research, surveillance, and diagnostic activities.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Customer & End-user Analysis
Detailed evaluation of veterinary hospitals, specialty diagnostic centers, academic veterinary institutions, reference laboratories, research organizations, and contract research services. Covers purchasing behavior, testing patterns, adoption of advanced biomarker technologies, service expectations, pricing sensitivity, and unmet diagnostic requirements across companion and production animal segments.
This supports customer segmentation, strengthens commercialization strategies, improves product and service positioning, identifies high-value customer groups, enhances sales targeting, and facilitates development of customized engagement strategies to improve customer acquisition and retention.
Regional Market Assessment
In-depth assessment of North America, Europe, Asia Pacific, Latin America, and Middle East & Africa covering regional demand drivers, disease prevalence, veterinary infrastructure, research trends, regulatory landscape, technological adoption, biomarker availability, investment activities, and country-level growth opportunities. Includes market attractiveness analysis and future outlook.
It helps organizations prioritize high-growth regions, optimize geographic expansion strategies, allocate commercial resources efficiently, identify underserved markets, and minimize investment risks through region-specific market intelligence and opportunity mapping.
Competitive Benchmarking
Delivered detailed competitive profiling of global and regional market participants covering product portfolios, pricing strategies, technology capabilities, manufacturing footprint, strategic Comprehensive competitive benchmarking of veterinary biomarker companies based on product portfolio, biomarker capabilities, diagnostic applications, geographic presence, partnerships, pricing strategies, technology adoption, research pipeline strength, and recent strategic developments. Includes SWOT analysis, market share assessment, and benchmarking of established and emerging participants., acquisitions, regional expansion initiatives, software integration capabilities, research investments, and innovation pipelines. The analysis also included operating strategies for mature and emerging players, competitive strengths, weaknesses, and differentiation opportunities across hardware, software, and integrated identification ecosystems.
This enables clients to identify competitive gaps, evaluate market positioning, understand differentiation strategies, assess acquisition or partnership opportunities, and formulate effective market entry, expansion, and investment strategies supported by detailed competitive intelligence.
Frequently Asked Questions About This Report
The global veterinary biomarkers market size was valued at USD 1.1 billion in 2025 and is estimated at USD 1.2 billion for 2026.
The global veterinary biomarkers market is expected to grow at a CAGR of 12.1% from 2026 to 2033, reaching USD 2.6 billion by 2033.
Key factors include the rising prevalence of chronic, infectious, and zoonotic diseases in animals; the growing demand for early and accurate disease detection; technological advancements in molecular diagnostics and biomarker discovery; the increasing adoption of point-of-care testing; expanding veterinary research and drug development activities; and growing investment in animal healthcare and diagnostic infrastructure.
The biomarkers, kits & reagents segment led with a 76.3% revenue share in 2025, and is expected to grow at the fastest CAGR over the forecast period.
The companion animals segment led with a 59.8% revenue share in 2025, while the production animals is the fastest-growing segment.
The veterinary hospitals & clinics segment held the largest revenue share of 56.5% in 2025, while the others segment is the fastest-growing end use.
Key players include Zoetis; Virbac; Life Diagnostics; Veterinary Biomarkers, Inc.; ACUVET BIOTECH; Merck; IDEXX Laboratories, Inc.; MI:RNA Diagnostics Ltd.; Mercodia AB; Antech Diagnostics, Inc., and Avacta Animal Health Limited, among others.
North America dominated with a 33.0% revenue share in 2025.
The disease diagnostics segment led with a 48.9% revenue share in 2025, while the preclinical research segment is the fastest-growing application.
Asia Pacific is the fastest-growing region over the forecast period.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


