
- Home
- »
- Animal Health
- »
-
Veterinary Sterilization Container Market Size Report, 2033GVR Report cover

Veterinary Sterilization Container Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Sterilization Containers, Accessories), By Type (Perforated, Non-perforated), By Material, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$91.2MMarket Estimate, 2026
$96.5MMarket Forecast, 2033
$149.6MCAGR, 2026–2033
6.5%Veterinary Sterilization Container Market Summary
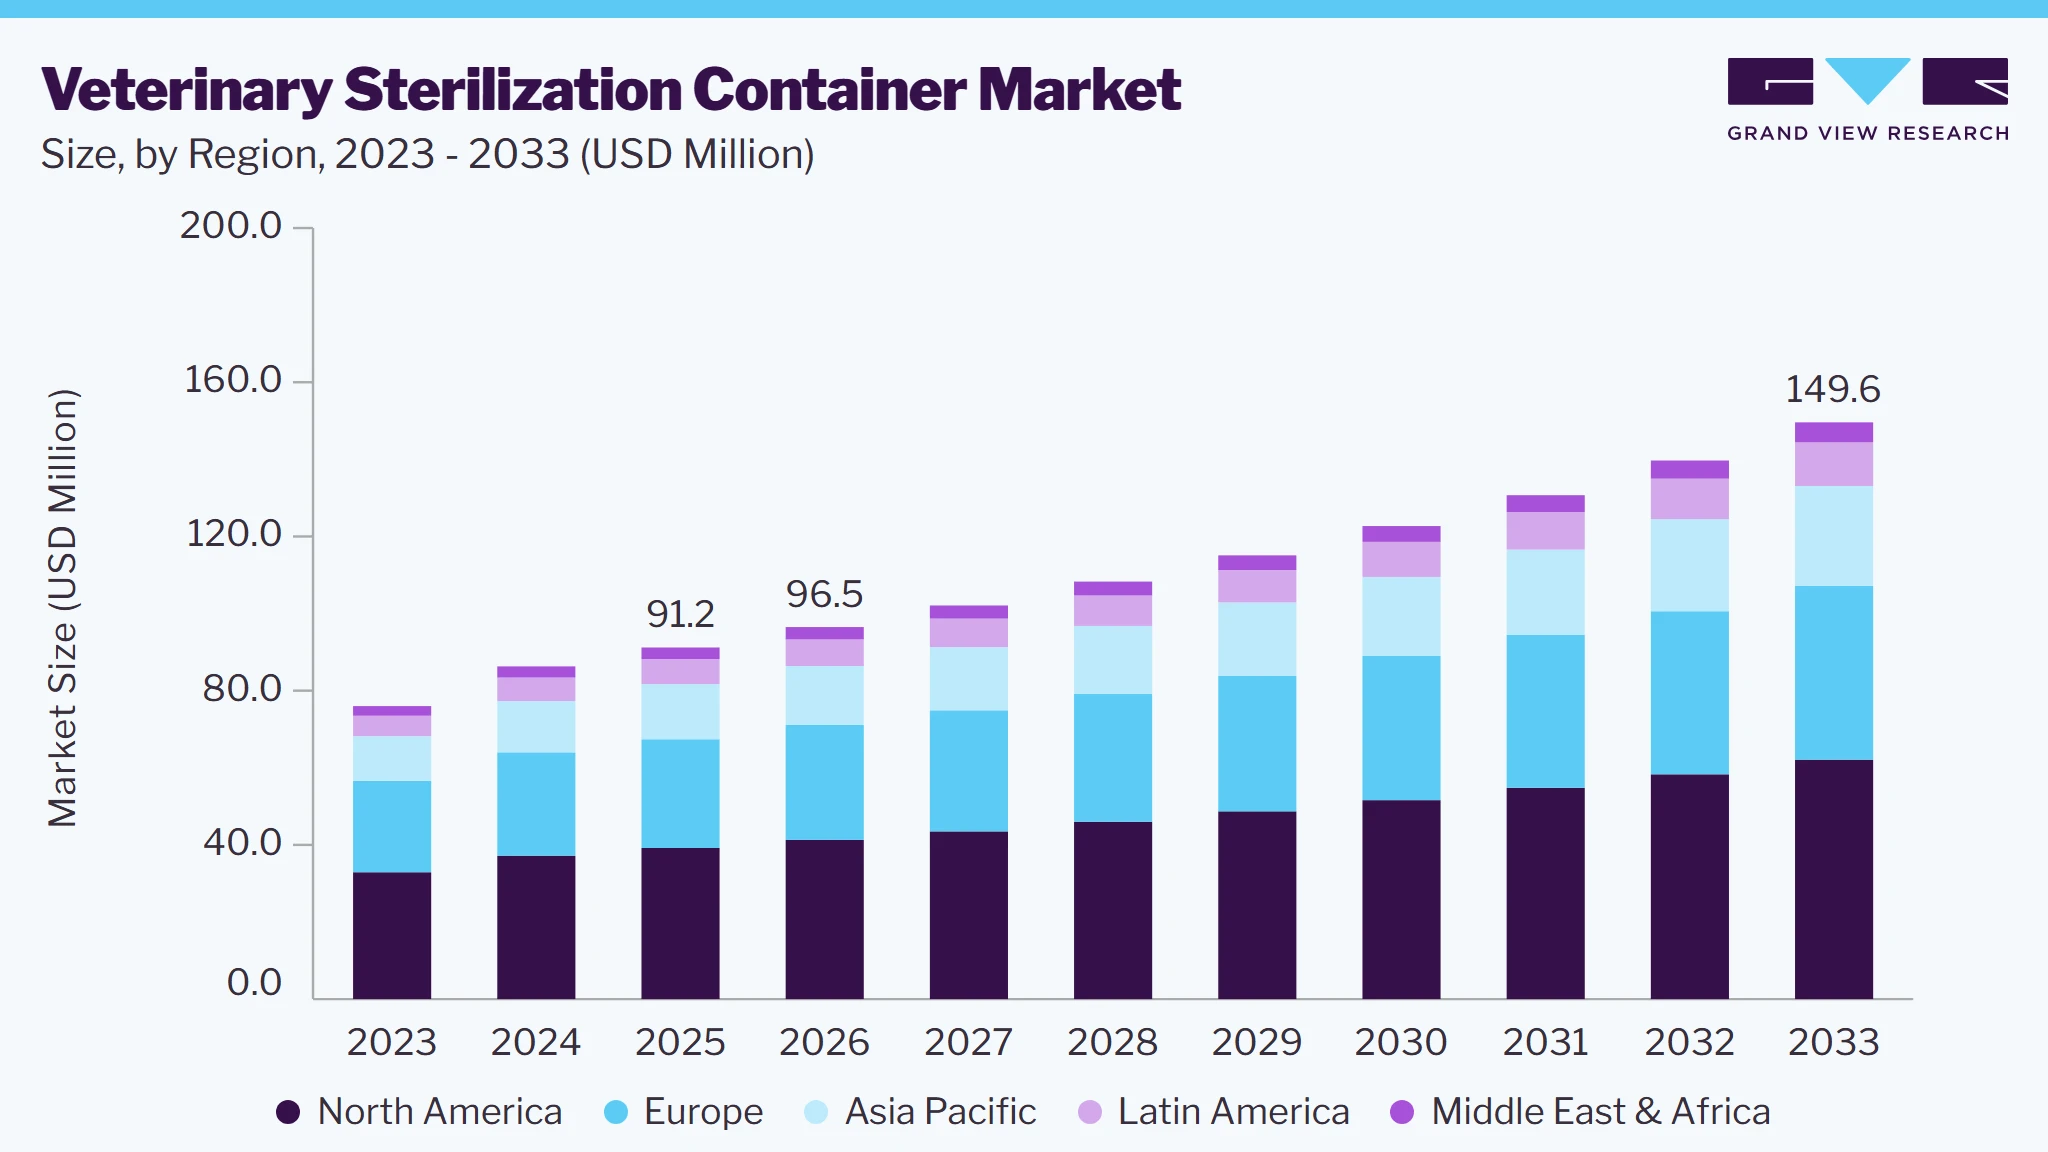
The global veterinary sterilization container market size was valued at USD 91.2 million in 2025 and is projected to grow from USD 96.5 million in 2026 to USD 149.6 million by 2033, growing at a CAGR of 6.5% from 2026 to 2033. North America dominated the market, accounting for the largest global share of 43.0% in 2025. Key factors driving the veterinary sterilization containers market include the rising incidence of hospital-acquired infections (HAIs), the need for effective infection control, and increasing demand for durable, reusable containers.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Sterilization containers segment held the largest revenue share of 62.6% in 2025.
- By material: Aluminium segment held the largest revenue share of 50.9% in 2025.
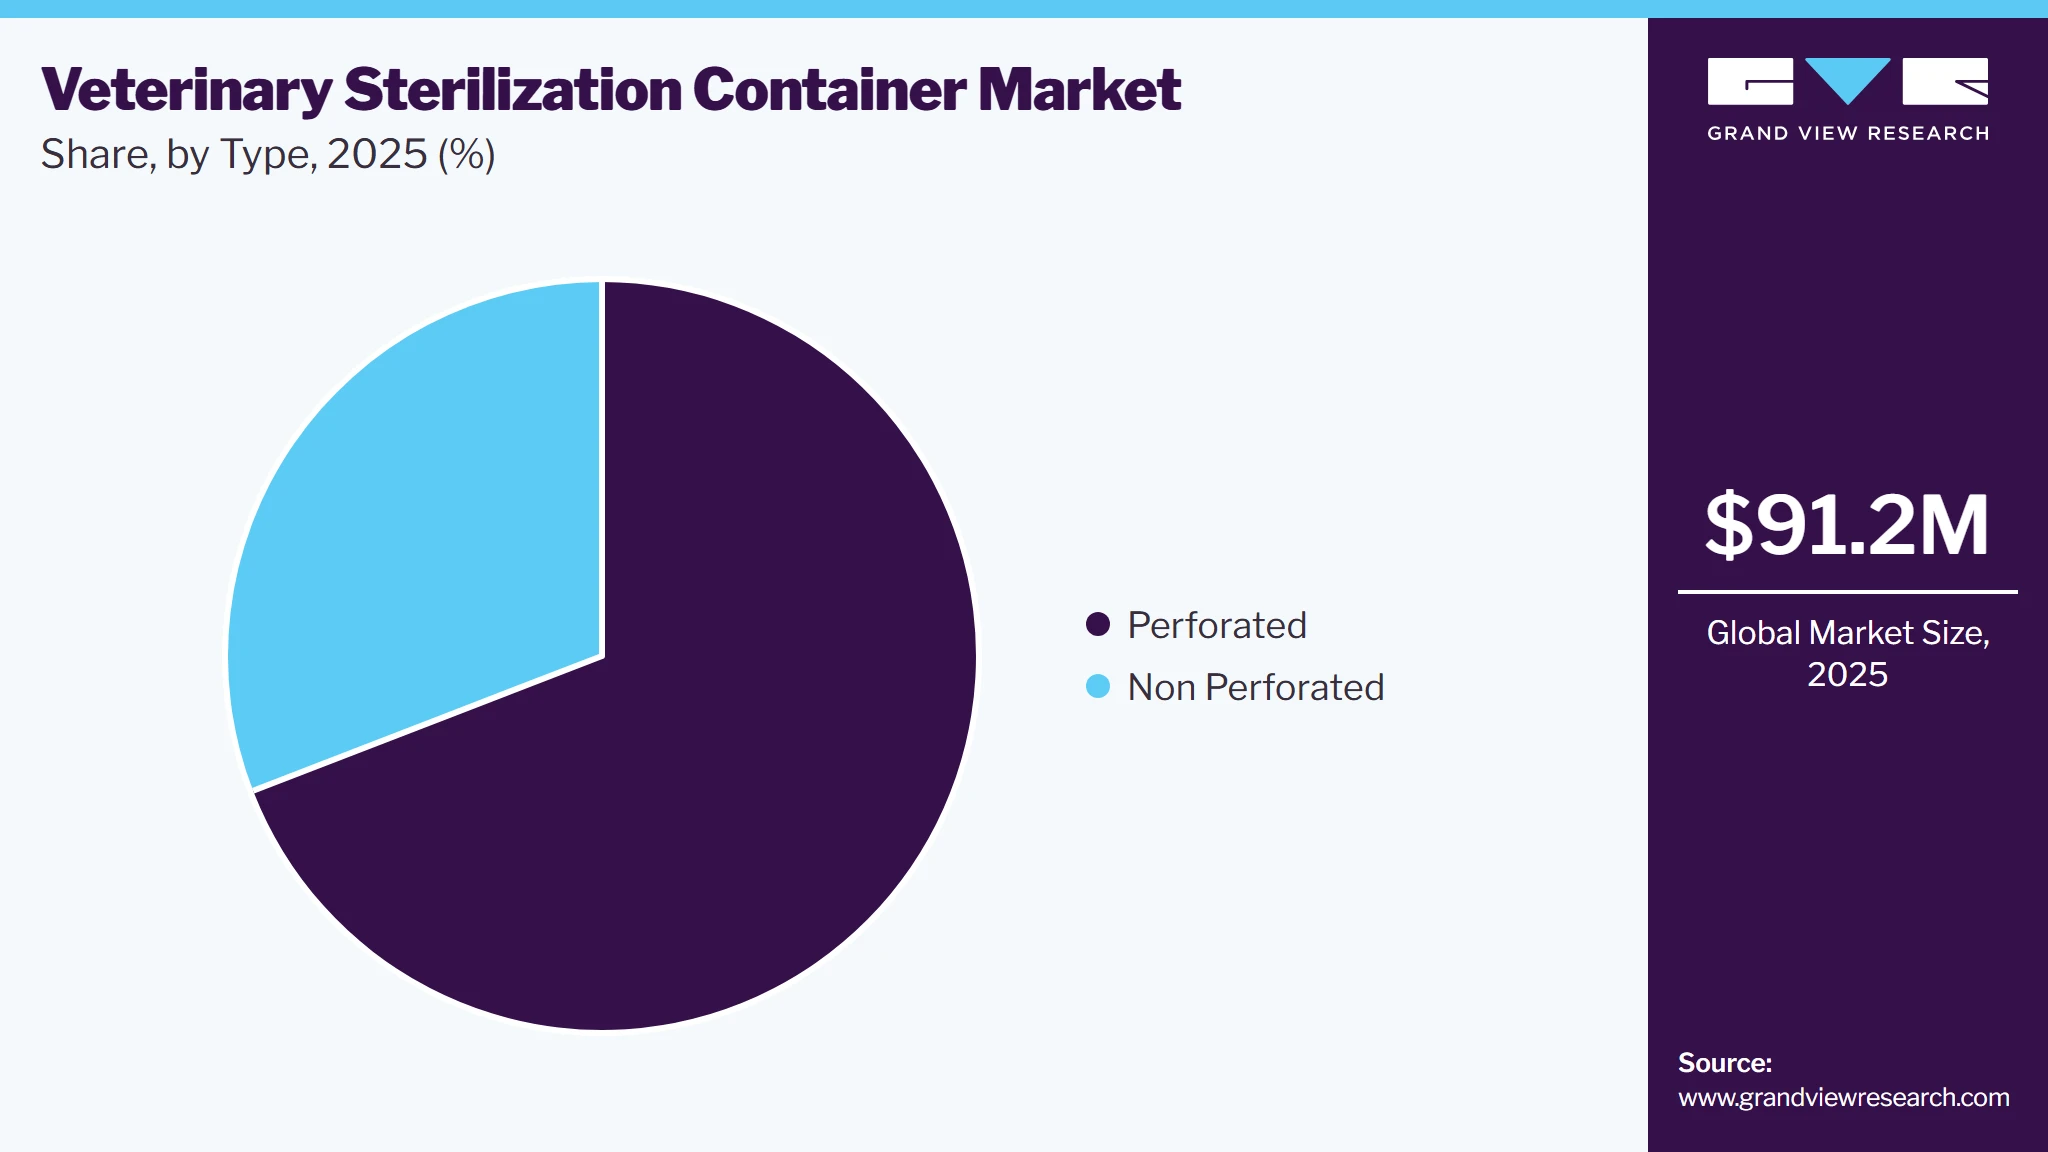
- By type: Perforated segment led the market with the largest revenue share of 69.1% in 2025.
- By end-use: Veterinary hospitals segment held the largest revenue share of 49.9% in 2025.
Regional Highlights
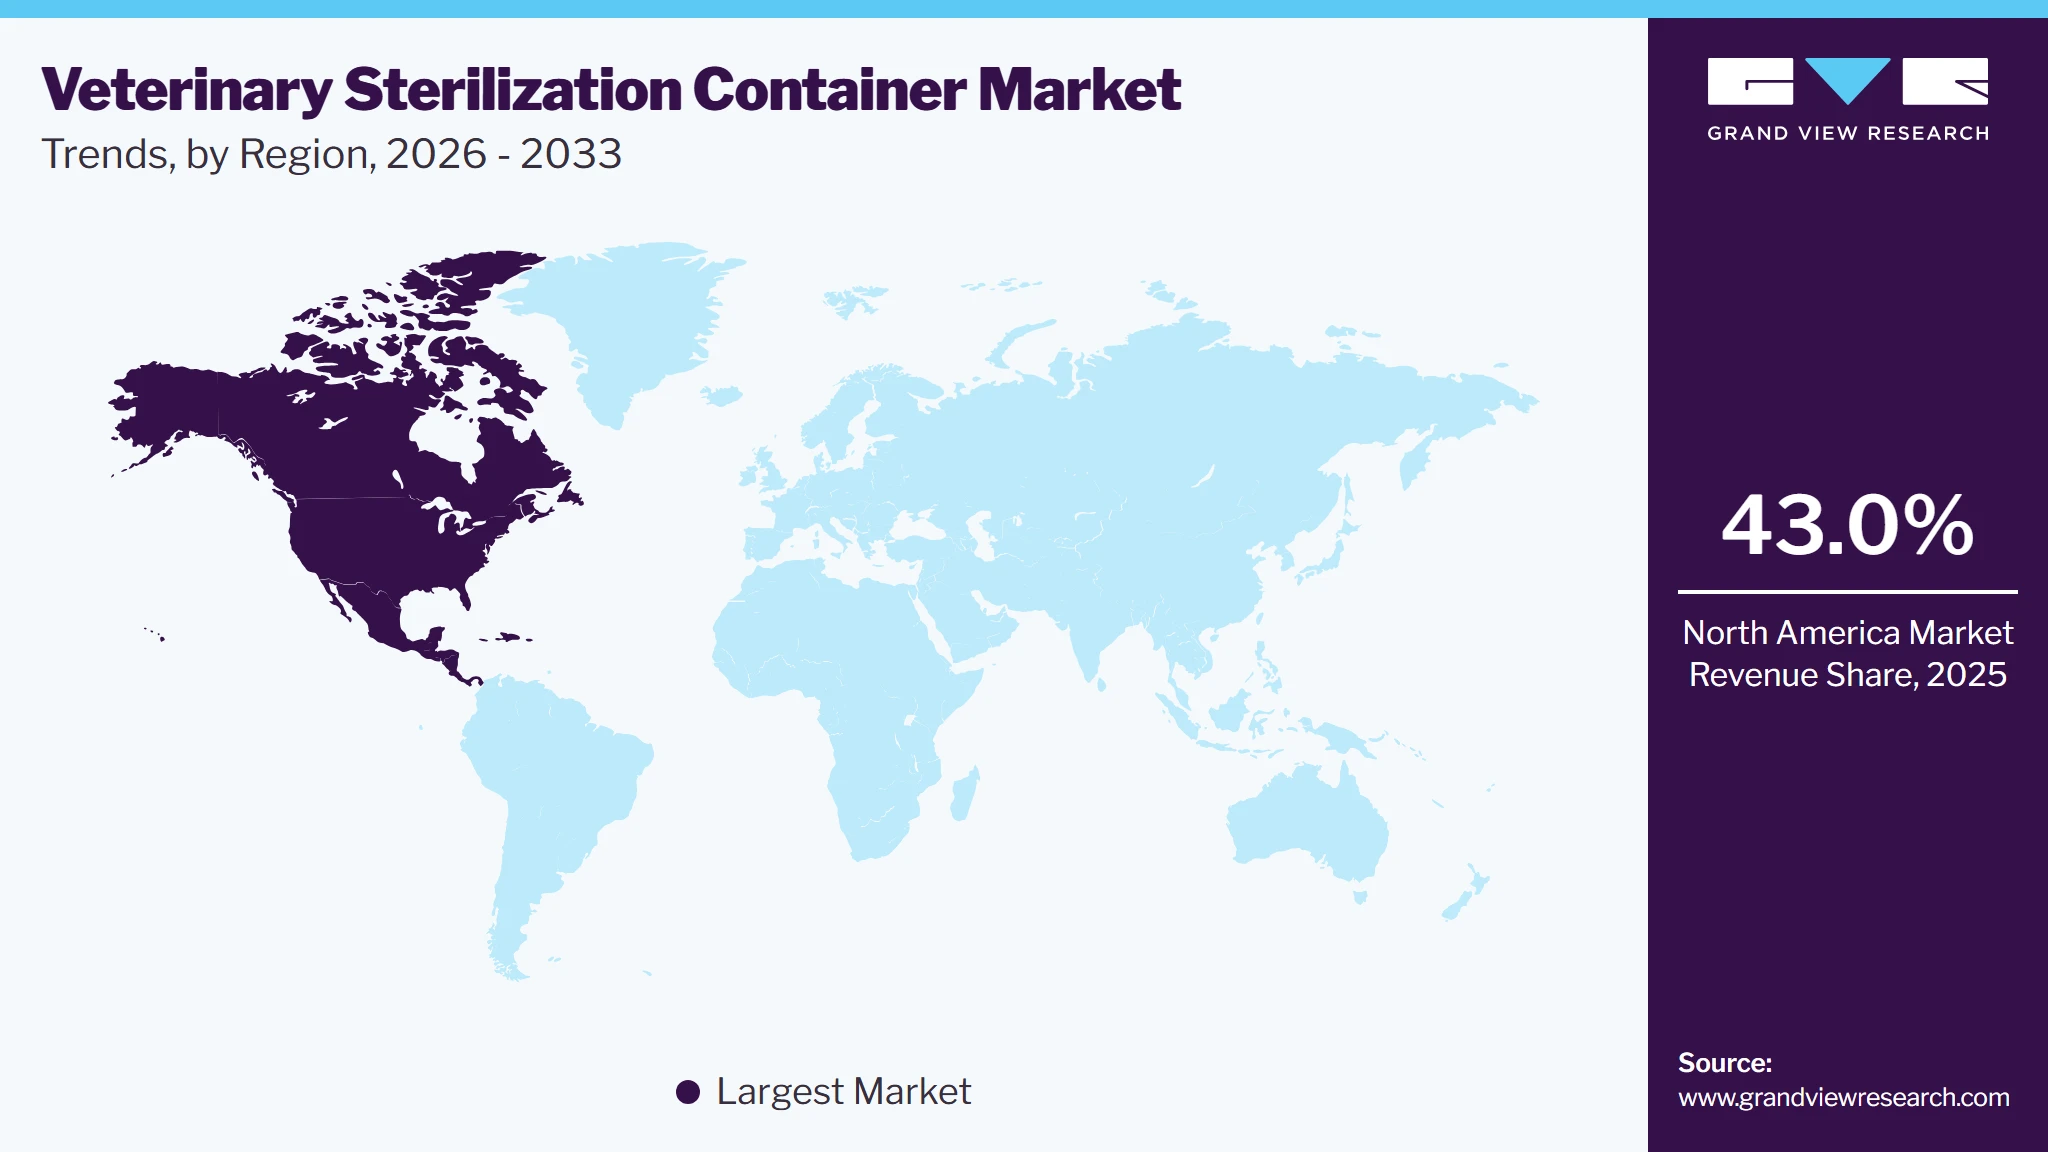
- Largest regional market: North America (43.0% revenue share, 2025)
- By country: The U.S. held the largest share of North America in 2025.
Market Size & Forecast
- Market size in 2025: USD 91.2 Million
- Estimated market size in 2026: USD 96.5 Million
- Projected market size by 2033: USD 149.6 Million
- CAGR (2026-2033): 6.5%
Prism AI by Grand View Research Free to tryAsk a question about the veterinary sterilization container marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Regulatory requirements for improved hygiene standards and the growing prevalence of multidrug-resistant pathogens further boost the adoption of sterilization containers. Their ability to reduce contamination risks, enhance sterilization efficiency, and meet environmental sustainability goals also contributes to market growth. Furthermore, according to a review published in veterinary microbiology, multidrug-resistant infections in veterinary settings are a significant concern, with over 80% of U.S. veterinary teaching hospitals reporting nosocomial infection outbreaks. Common infections include surgical site infections, wound infections, and catheter-associated urinary tract infections. Key pathogens such as methicillin-resistant staphylococci, extended-spectrum beta-lactamase-producing E. coli, and multidrug-resistant Salmonella are responsible for these infections. These infections not only affect animals but also pose risks to human health through zoonotic transmission. Effective infection control in veterinary clinics, including the use of advanced sterilization technologies, is crucial to mitigate these risks. This drives the demand for veterinary sterilization containers, which enhance infection control by ensuring the effective sterilization of medical instruments and reducing the spread of resistant pathogens.
 To learn more about this report, Download Free Sample Report
Innovations such as the SteriCUBE system and EverGreen Containers, which offer more efficient, environmentally friendly, and cost-effective sterilization solutions, are enhancing market growth. These technologies improve workflow efficiency and reduce waste compared to traditional methods.
Market Dynamics
The global veterinary sterilization containers market is influenced by the increasing procedural volume across companion animal and livestock healthcare, growing focus on surgical infection prevention, expansion of veterinary specialty hospitals, and rising adoption of reusable sterilization systems. Furthermore, stricter sterilization protocols in veterinary facilities, increasing investments in advanced surgical infrastructure, and greater preference for standardized instrument management systems continue to support market growth. Veterinary practices are performing a higher number of orthopedic, neurological, dental, soft tissue, and minimally invasive procedures, creating sustained demand for validated sterilization workflows that maintain instrument sterility from processing through storage and transportation.
Sterilization containers offer long service life, improved instrument organization, and reduced dependence on disposable sterilization wraps, contributing to lower operating costs over time. Additionally, veterinary hospitals are adopting centralized sterile processing practices comparable to those used in human healthcare, particularly across developed markets.
Regulatory guidance on infection prevention and increasing awareness regarding multidrug-resistant organisms are encouraging veterinary facilities to adopt reusable container systems that provide consistent sterilization performance and minimize contamination risks. These factors are expected to sustain market expansion throughout the forecast period.
The increasing priority given to infection prevention across veterinary surgical settings is a major factor supporting demand for sterilization containers. Veterinary hospitals and specialty referral centers are performing a growing number of complex orthopedic, oncologic, ophthalmic, and minimally invasive procedures, requiring consistent sterilization of reusable surgical instruments. Sterilization containers provide a validated sterile barrier that protects instruments during sterilization, storage, transport, and handling, thereby reducing the likelihood of contamination before clinical use. Furthermore, reusable rigid container systems improve instrument organization and reduce damage associated with repeated wrapping and unwrapping processes.
The growing adoption of centralized sterile processing departments in large veterinary hospitals has further increased demand for standardized sterilization workflows utilizing container systems. In addition, veterinary organizations are strengthening infection control protocols to reduce surgical site infections and improve procedural outcomes. For instance, in May 2026, European standardization bodies introduced updated requirements for steam sterilizers used in healthcare settings, supporting higher consistency in sterilization validation and processing practices. Similar quality expectations are increasingly influencing veterinary surgical facilities, encouraging wider adoption of validated sterilization container systems.
The relatively high acquisition cost of veterinary sterilization container systems continues to limit adoption among small and independent veterinary clinics. A complete sterilization container system generally includes rigid containers, baskets, instrument organizers, filters, identification accessories, and maintenance components, resulting in higher upfront expenditure compared with conventional sterilization wraps. Smaller veterinary facilities with limited surgical volumes often continue using disposable packaging materials because of lower initial investment requirements. Furthermore, implementation of reusable container systems requires compatibility with existing sterilizers, validation procedures, staff training, and routine inspection of filters, seals, and locking mechanisms to maintain sterilization performance.
These operational requirements increase the overall cost of ownership for facilities with constrained budgets. In developing countries, limited availability of advanced sterilization infrastructure and inconsistent adherence to standardized infection control practices further reduce market penetration. Additionally, many general veterinary clinics perform fewer complex surgical procedures, reducing the economic justification for investing in premium reusable sterilization container systems. These factors are expected to moderate adoption across cost-sensitive healthcare facilities during the forecast period.
The ongoing expansion of advanced veterinary hospitals and specialty referral centers presents significant growth opportunities for manufacturers of sterilization container systems. Increasing investments in orthopedic, neurological, cardiovascular, dental, and minimally invasive veterinary procedures are creating demand for organized, validated instrument management solutions capable of supporting higher procedural throughput. Furthermore, veterinary groups operating multi-hospital networks are increasingly standardizing sterilization protocols across facilities, creating opportunities for large-scale deployment of reusable container systems. Sustainability initiatives are also contributing to future market growth as veterinary hospitals seek to reduce medical waste generated from disposable sterilization wraps while improving operational efficiency.
Reusable sterilization containers support environmental objectives through repeated use over extended service life and lower consumable utilization. Additionally, manufacturers are introducing modular container designs with enhanced airflow characteristics, instrument protection features, and compatibility across multiple sterilization technologies. Growing adoption of digital instrument tracking and sterile processing documentation is expected to further increase demand for standardized container systems capable of integrating with hospital workflow management. These developments are expected to create favorable long-term opportunities across developed as well as emerging veterinary healthcare markets.
Market Concentration & Characteristics
The veterinary sterilization container market exhibits moderate industry concentration, with a few key players dominating the sector. Major companies, such as B. Braun SE (B. Braun Vet Care GmbH) and Vimian Group AB (Movora), lead the market by offering advanced sterilization technologies and innovative products. These industry leaders are focused on expanding their market share through technological advancements and strategic acquisitions. However, the market also includes a range of smaller and emerging firms offering niche products and specialized solutions, contributing to a competitive landscape with opportunities for new entrants and innovation.
The veterinary sterilization container market is witnessing a high degree of innovation, particularly in the design of reusable, airtight containers with advanced filtration systems. Innovative features includes tamper-proof locks and sterilization indicators, increase user confidence in maintaining long-term sterility. As veterinary practices adopt these cutting-edge technologies, the demand for advanced sterilization containers rises, driving market growth and setting new industry standards for infection control.
 To learn more about this report, Download Free Sample Report
The veterinary sterilization container market is experiencing moderate M&A activity as companies acquire innovative and eco-friendly sterilization solutions to expand their portfolios and market presence. These acquisitions focus on reducing biohazardous waste, enhancing efficiency, and meeting the rising demand for safe and effective sterilization, aligning with sustainability and improved infection control standards in veterinary healthcare. For instance, in April 2024, HealthpointCapital acquired a majority stake in SteriCUBE, an FDA-cleared sterilization platform that replaces disposable "blue wraps" with a reusable filtered metal container, enabling simultaneous sterilization of multiple instrument trays. The system reduces biohazardous waste, enhances efficiency, and improves safety, aligning with market trends toward sustainable, cost-effective, and advanced sterilization solutions in the veterinary sector.
Regulations significantly impact the veterinary sterilization container market by ensuring product safety, efficacy, and compliance with sterilization standards. Strict regulatory guidelines from agencies like the FDA and the European Medicines Agency (EMA) mandate that sterilization containers meet rigorous standards for sterility, material use, and environmental safety. These regulations drive innovation, as manufacturers must develop advanced, compliant products while maintaining cost-effectiveness. Non-compliance can lead to product recalls, delays in market approval, and potential financial losses, making regulatory adherence crucial for market success.
The product substitutes include disposable blue wraps, which have traditionally been used for instrument sterilization but are less sustainable and prone to perforation. Other alternatives are chemical sterilization methods and reusable textile wraps. While these substitutes can offer lower initial costs or specific use-case advantages, they often fall short in terms of durability, efficiency, and environmental impact compared to advanced sterilization containers like SteriCUBE, which provide enhanced safety, reduced waste, and improved workflow efficiency.
Strategic initiatives by key players to raise awareness about hospital-associated infections (HAIs) are driving growth in the veterinary sterilization container market. Companies are introducing educational programs, campaigns, and certifications to promote sterilization best practices and infection control. For example, in February 2023, Virox Technologies and NAVTA launched the Infection Prevention Leader Certificate Program, offering RACE-approved courses on disinfection and sterilization, equipping veterinary professionals with tools to reduce HAIs and improve workplace safety. These efforts are fostering the adoption of advanced sterilization containers and contributing to market expansion.
Analyst Perspective
The veterinary sterilization containers market is shifting toward integrated infection prevention and instrument management solutions, driven by advanced veterinary surgeries, standardized procedures, and growing use of reusable instruments. Veterinary facilities increasingly prioritize operational efficiency, instrument protection, lifecycle costs, and sterilization compatibility over initial purchase price. Sustainability efforts are also boosting demand for reusable containers as alternatives to disposable wraps. Manufacturers are focusing on modular designs, better instrument organization, sterilant penetration, and accessory portfolios, while emerging markets offer growth opportunities through expanding veterinary infrastructure and specialty hospitals.
Product Insights
Based on product, the sterilization containers segment led the market with the largest revenue share of 62.6% in 2025 and is expected to grow at fastest CAGR of 7.0% during forecast period due to their higher efficiency in maintaining sterility, compliance with stringent infection control regulations, and durability for repeated use. Unlike single-use alternatives, sterilization containers are designed for multiple uses, which contributes to cost savings and reduces environmental waste. Their durable construction ensures long-term performance, making them a more economical and sustainable option.
Also, veterinary practices are increasingly required to adhere to stringent infection control regulations. Sterilization containers meet these regulatory standards by providing reliable and consistent sterilization, thus making them a preferred choice in compliance with hygiene protocols.
Material Insights
Based on material, the aluminium segment led the market with the largest revenue share of 50.9% in 2025. Aluminum-based containers are widely used due to their durability, excellent heat conductivity, and resistance to corrosion. Their robust construction ensures reliable protection and effective sterilization of instruments while being reusable and cost-effective compared to disposable alternatives.
Whereas other material segment is expected to be fastest-growing segment with the highest CAGR of 7.6% over the forecast period. Other materials such as polycarbonate and high-grade plastic composites are expected to gaining popularity in the market. These materials are valued for their lightweight nature, resistance to chemical corrosion, and cost-effectiveness. They offer an alternative to traditional metals, providing effective sterilization and durability while being easier to handle and maintain.
Type Insights
Based on type, the perforated segment led the market with the largest revenue share of 69.1% in 2025 over the forecast period. Perforated containers are preferred due to their superior efficiency in the sterilization process. Perforated containers allow steam and other sterilizing agents to reach all surfaces of the instruments more effectively, ensuring thorough disinfection. This design reduces the risk of infection and contamination, enhances the effectiveness of sterilization, and supports better airflow and drying, making them the preferred choice in animal hospitals.
Non-perforated containers, on the other hand, do not have these openings and rely on external sterilization methods. They often provide better protection against contamination during storage and transport, as they create a sealed environment. However, they may not be suitable for all sterilization methods and might require additional processing steps to ensure complete sterilization.
End Use Insights
Based on end-use, the veterinary hospitals segment led the market with the largest revenue share of 49.9% in 2025 due to their high volume of surgical procedures and the need for stringent infection control practices. These facilities frequently use sterilization containers to maintain a sterile environment for surgical instruments, reducing the risk of hospital-acquired infections and ensuring the safety of both patients and staff. The continuous demand for effective sterilization solutions in these settings drives the significant market share of this segment.
 To learn more about this report, Download Free Sample Report
On other hand, laboratories segment is expected to grow at highest CAGR of 7.6% during forecast period. Veterinary laboratories are rapidly adopting veterinary sterilization containers due to the increasing need for stringent infection control and contamination prevention in diagnostic and research settings. These containers help ensure the sterilization of equipment and samples, which is crucial for accurate test results and reliable research outcomes. The rise in sophisticated diagnostic procedures and a heightened focus on maintaining a sterile environment to prevent cross-contamination are key factors driving this adoption.
Regional Insights
North America dominated the veterinary sterilization container market with the largest revenue share of 43.0% in 2025 owing to its well-established veterinary healthcare infrastructure, high volume of companion animal surgical procedures, and widespread adoption of advanced infection control protocols across veterinary hospitals and specialty clinics. Moreover, the presence of major manufacturers, increasing expenditure on companion animal healthcare, growing utilization of reusable sterilization systems, and greater availability of centralized sterile processing facilities have supported the adoption of veterinary sterilization containers across the region.
 To learn more about this report, Download Free Sample Report
U.S. Veterinary Sterilization Container Market Trends
The veterinary sterilization container market in the U.S. held the largest share in the North America region in 2025. The rise in veterinary hospitalizations, driven by higher pet ownership and more complex surgical procedures, has increased the need for effective decontamination solutions. The prevalence of MDR pathogens such as methicillin-resistant Staphylococcus aureus (MRSA) and extended-spectrum beta-lactamase (ESBL)-producing bacteria is rising. These pathogens are a major concern in veterinary settings, necessitating enhanced sterilization protocols. For instance, a study in the U.S. found that over 40% of bacterial infections in veterinary hospitals were caused by MDR pathogens, highlighting the urgent need for effective sterilization solutions. Hospital-acquired infections in veterinary hospitals have also been increasing. According to the Centers for Disease Control and Prevention (CDC), about 10% of infections in veterinary hospitals are classified as HAIs. These infections are often linked to inadequate disinfection practices, prompting a greater focus on advanced sterilization containers.
Additionally, stricter regulations and compliance requirements regarding sterilization practices have also fueled market growth. The U.S. Food and Drug Administration (FDA) and other regulatory bodies have enforced higher standards for sterilization, prompting veterinary facilities to invest in upgraded containers to meet these standards.
Europe Veterinary Sterilization Container Market Trends
Europe veterinary sterilization container market is influenced by several trends, driven by increasing pet ownership and awareness of advanced veterinary care, advancements in veterinary sterilization technologies, and rising demand for effective infection control solutions. Similarly, increased canine & feline population and pet care expenditure is fueling market growth. For instance, the number of pet owners is increasing, with 166 million out of Europe's 352 million pets being owned by 50% of European households. Rising pet ownership across Europe leads to higher demand for veterinary services and advanced surgical tools, including sterilization containers. Pet owners and animal healthcare practices seek reliable solutions to ensure the health and safety of animals.
Additionally, Europe has stringent regulations and standards for infection control and hygiene in animal healthcare facilities. Compliance with these regulations necessitates the use of effective sterilization containers, driving market demand.
Germany veterinary sterilization container market held the largest share in Europe in 2025. Germany has a high rate of pet ownership as well as livestock population, leading to increased demand for veterinary services and advanced surgical tools. This surge in pet care drives the need for efficient disinfection solutions. For instance, according to the German Livestock, the country has the largest dairy cattle herd & the second-largest cattle population in the EU. Furthermore, according to the International Committee for Animal Recording (ICAR), 50% of German farms specialize in livestock. Similarly, according to a survey commissioned by Industrieverband Heimtierbedarf (IVH) e.V., 44% of all households in Germany have at least one domestic animal.
Asia Pacific Veterinary Sterilization Container Market Trends
The Asia Pacific veterinary sterilization container market is expanding rapidly, driven by factors such as increasing animal care standards and rising awareness about infection control. Furthermore, there is significant potential for growth in emerging markets within the Asia-Pacific region as small animal practices modernize and adopt advanced sterilization solutions. Opportunities are also arising from increased investments in veterinary infrastructure and expanding healthcare facilities.
Additionally, presence of leading companies like Narang Medical Ltd. is boosting market growth. Narang Medical Ltd. is known for its comprehensive range of veterinary sterilization containers and solutions, which cater to the growing demand for effective infection control in veterinary settings.
The veterinary sterilization container market in India is witnessing notable growth due to a surge in health problems in pets and the need for effective infection control and disinfection measures in veterinary practices. For instance, according to a report published by Times Internet in India, in June 2024, Veterinary clinics in Kolkata have reported a surge in pets, particularly dogs, experiencing health issues such as fur loss, allergies, stomach disorders, and haemoprotozoan infections (babesiosis, theileriosis, and anaplasmosis) due to fluctuating pre-monsoon weather. As clinics address these health challenges and implement stringent disinfection protocols to prevent and manage infections, the demand for veterinary sterilization containers is expected to increase.
Latin America Veterinary Sterilization Container Market Trends
The demand for Latin America veterinary sterilization containers is on the rise, driven by an increasing emphasis on hygiene and infection control in veterinary practices and the need for efficient decontamination solutions. In Brazil, the expanding veterinary care sector, combined with stricter regulatory requirements for higher sterilization standards, is further boosting this demand. As veterinary facilities aim to improve operational efficiency and ensure patient safety, the use of premium sterilization containers is projected to see continued growth.
The Brazil veterinary sterilization market is expanding significantly due to an increase in livestock population and outbreaks of hospital-acquired infections in animals. For instance, according to Agro Concept Management Ltd, Brazil had the second-largest cattle herd, accounting for 232 million heads. Moreover, the country is also the world's largest exporter of beef. As the livestock sector expands, the need for effective sterilization solutions to manage and prevent the spread of infections in veterinary settings grows.
Middle East & Africa Veterinary Sterilization Container Market Trends
The Middle East & Africa veterinary sterilization container market has notable growth potential driven by increasing investments in veterinary healthcare infrastructure, growing awareness of infection control, and rising pet ownership. However, regional economic disparities and varying levels of technology adoption may impact the growth rate.
The veterinary sterilization container market in South Africa is growing slowly due to a lack of awareness and adoption of advanced decontamination technologies, along with budget constraints in many veterinary practices, contributing to the slow growth. Additionally, the relatively small size of the market and lower investment in veterinary infrastructure and infection control compared to other regions further restrain revenue potential.
Key Veterinary Sterilization Container Company Insights
The market is competitive with key players striving to innovate and capture market share. Companies like Movora are leading this trend with new product launches such as advanced disinfection systems that enhance efficiency and safety. Additionally, companies are focusing on improving product features, expanding their portfolios, and establishing strategic partnerships to gain a competitive edge.
Key Veterinary Sterilization Container Companies:
The following key companies have been profiled for this study on the veterinary sterilization container market.
-
B. Braun SE (B. Braun Vet Care GmbH)
-
Vimian Group AB (Movora)
-
Aesculap, Inc.
-
Case Medical, Inc.
-
KYON AG
-
Fine Science Tools, Inc.
-
Changzhou XC Medico Technology Co., Ltd.
-
Erbrich Instrumente GmbH
-
Andersen Sterilizers
-
Vet Direct Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (B. Braun SE (B. Braun Vet Care GmbH), Vimian Group AB (Movora), Aesculap, Inc., Case Medical, Inc., KYON AG)
Established manufacturers focus on expanding their veterinary sterilization container portfolios through product innovation, reusable container technologies, instrument organization systems, and compatibility with multiple sterilization methods. Their strategies include strengthening global distribution networks, collaborating with veterinary hospitals and distributors, expanding after-sales support, and developing accessories that improve sterile processing efficiency and instrument protection.
These companies benefit from strong global brand recognition, broad product portfolios, advanced manufacturing capabilities, established distribution channels, and long-standing relationships with veterinary hospitals, specialty clinics, and academic institutions. Their validated sterilization systems, comprehensive accessory portfolios, and technical support strengthen customer retention and procurement across developed markets.
Premium product pricing, higher manufacturing costs, and extensive regulatory and quality validation requirements may limit adoption among cost-sensitive veterinary practices. Longer product development cycles and lower pricing flexibility compared with regional manufacturers may also restrict penetration in emerging markets.
Emerging Players (Fine Science Tools, Inc., Changzhou XC Medico Technology Co., Ltd., Erbrich Instrumente GmbH, Andersen Sterilizers, Vet Direct Ltd.)
Emerging companies compete by offering cost-effective sterilization containers, specialized accessories, customized instrument organization solutions, and region-specific product portfolios. Their strategies focus on distributor partnerships, product customization, expanding regional sales networks, and serving independent veterinary clinics and specialty practices with flexible procurement options.
These companies offer greater flexibility in customization, competitive pricing, faster product introduction, and stronger responsiveness to regional customer requirements. Their focused product portfolios allow quicker adaptation to changing veterinary surgical practices and procurement trends across niche markets.
Limited global presence, comparatively smaller manufacturing scale, lower R&D investment, and narrower product portfolios may reduce competitiveness against multinational manufacturers. Restricted distribution networks and lower brand recognition can also limit expansion into large veterinary hospital groups and international markets.
Recent Developments
-
In May 2024, Movora launched EverGreen Filtered Sterilization Containers with cost-effective and sustainable solutions for veterinary practices. These containers feature a rigid design with airtight seals and reusable or replaceable filters, maintaining sterility for up to six months. They enhance practice efficiency by eliminating the need for blue wrap, improving autoclave efficacy, and providing secure, long-term storage for surgical instruments and medical equipment.
-
In April 2024, HealthpointCapital acquired a majority stake in SteriCUBE Holdings, Inc., known for its innovative SteriCUBE Multiple Tray Sterilization (MTS) System. The system reduces waste, cuts costs, and enhances workflow in hospitals, with significant implications for the sterilization of surgical instruments.
Veterinary Sterilization Container Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 91.2 million
Market size value in 2026
USD 96.5 million
Revenue forecast in 2033
USD 149.6 million
Growth rate
CAGR of 6.5% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, material, type, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Oman; Qatar.
Key companies profiled
B. Braun SE (B. Braun Vet Care GmbH); Vimian Group AB (Movora); Aesculap, Inc.; Case Medical, Inc.; KYON AG; Fine Science Tools, Inc.; Changzhou XC Medico Technology Co., Ltd.; Erbrich Instrumente GmbH; Andersen Sterilizers; Vet Direct Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Veterinary Sterilization Container Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global veterinary sterilization container market report based on product, material, type, end-use, and region:
-
Product Outlook (Revenue, USD Million; 2021 - 2033)
-
Sterilization Containers
-
Accessories
-
-
Material Outlook (Revenue, USD Million; 2021 - 2033)
-
Stainless Steel
-
Aluminium
-
Other Material
-
-
Type Outlook (Revenue, USD Million; 2021 - 2033)
-
Perforated
-
Non-Perforated
-
-
End-Use Outlook (Revenue, USD Million; 2021 - 2033)
-
Veterinary Hospitals & Clinics
-
Laboratories
-
Others
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The veterinary sterilization Container market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each veterinary sterilization Container segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue Capture Definition
Sterilization Containers
Revenue generated from reusable veterinary sterilization containers designed for sterilizing, protecting, storing, and transporting surgical instruments while maintaining sterility throughout veterinary surgical workflows.
Accessories
Market value derived from accessories used with veterinary sterilization containers, including filters, identification tags, baskets, trays, silicone holders, locking mechanisms, seals, and replacement components that support container functionality and sterilization performance.
Segment - Material
Revenue Capture Definition
Stainless Steel
Revenue generated from veterinary sterilization containers manufactured using stainless steel, offering high mechanical strength, corrosion resistance, and durability for repeated sterilization cycles in veterinary healthcare facilities.
Aluminium
Market value attributed to veterinary sterilization containers manufactured from anodized aluminium, providing lightweight construction, corrosion resistance, and compatibility with repeated steam sterilization procedures.
Other Material
Revenue contributed by veterinary sterilization containers manufactured using alternative materials, including high-performance polymers, composite materials, and specialized alloys developed for specific sterilization methods or operational requirements.
Segment - Type
Revenue Capture Definition
Perforated
Revenue generated from perforated veterinary sterilization containers designed to facilitate sterilant penetration and air removal during sterilization while maintaining sterile storage and transportation of surgical instruments.
Non Perforated
Market value derived from non-perforated veterinary sterilization containers intended for sterilization methods requiring enclosed containment while providing secure storage and protection of reusable surgical instruments.
Segment - End Use
Revenue Capture Definition
Veterinary Hospitals & Clinics
Revenue generated from veterinary sterilization containers utilized across general veterinary practices, specialty hospitals, emergency hospitals, and surgical clinics for sterilization, storage, and transportation of reusable surgical instrument sets.
Laboratories
Market value attributed to veterinary sterilization containers used in veterinary diagnostic laboratories, research laboratories, and academic institutions for sterilizing and maintaining sterile surgical and laboratory instruments used in animal health research and testing.
Others
Revenue contributed by veterinary sterilization containers deployed across animal shelters, zoological parks, government veterinary facilities, military veterinary services, contract research organizations (CROs), livestock healthcare facilities, and other animal healthcare establishments.
Estimation Model
Estimation Model
Points
Bottom-Up Revenue Model
• Market size is estimated by identifying key manufacturers of veterinary sterilization containers, accessories, and instrument management systems.• Revenue contribution is derived from company annual reports, financial disclosures, product portfolios, investor presentations, distributor information, import-export statistics, and management commentary.• Individual company revenues are allocated based on product offerings, regional sales, veterinary customer base, manufacturing capabilities, and estimated revenue contribution from sterilization containers to determine the overall market size.
Veterinary Surgical Infrastructure Model
• Market value is estimated by assessing the installed base of veterinary hospitals, specialty referral centers, academic institutions, research laboratories, and large animal healthcare facilities performing surgical procedures.• Adoption rates are evaluated using veterinary surgical procedure volumes, hospital expansion, operating room capacity, instrument inventory, and sterile processing infrastructure.• Revenue is calculated by estimating sterilization container requirements per surgical facility based on procedure volumes, instrument sets, replacement cycles, and procurement trends across end users.
Veterinary Surgical Procedure & Infection Control Model
• Market value is estimated by assessing increasing veterinary surgical procedures, growth in companion animal healthcare expenditure, expansion of specialty veterinary services, and infection prevention requirements.• Demand is evaluated using surgical case volumes, reusable instrument utilization, operating room expansion, and sterile processing practices across veterinary hospitals and research institutions.• Revenue is calculated by correlating procedure growth, surgical instrument inventory expansion, replacement demand, and sterilization container adoption across key end users.
Product Adoption & Technology Penetration Model
• Market size is estimated by evaluating adoption of reusable rigid sterilization containers, perforated and non-perforated systems, container accessories, and advanced instrument organization solutions.• Parameters such as infection prevention protocols, sterilization standards, reusable device adoption, sustainability initiatives, and replacement demand are analyzed across major regions.• Revenue potential is estimated using product pricing, technology penetration, procurement patterns, and average sterilization container utilization across veterinary healthcare facilities.
Methodology Triangulation & Framework Summary:
This estimation framework combines manufacturer revenues, veterinary surgical infrastructure, technology adoption, and procedural demand assessment to provide a comprehensive evaluation of the global veterinary sterilization containers market. The triangulated methodology captures demand across veterinary hospitals, specialty referral centers, academic institutions, research laboratories, and other animal healthcare facilities. Cross-validation using company revenues, surgical procedure volumes, installed infrastructure, replacement cycles, and procurement trends enables accurate market sizing, competitive benchmarking, identification of growth opportunities, and long-term demand forecasting while minimizing dependence on a single estimation model.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Veterinary Sterilization Infrastructure Assessment
Conducted a comprehensive assessment of the veterinary sterilization container ecosystem covering manufacturers, sterilization container systems, accessories, veterinary hospitals, specialty referral centers, research laboratories, and academic institutions. Evaluated sterilization workflows, surgical infrastructure, infection prevention practices, procurement patterns, regulatory requirements, and reusable container adoption across companion animal and large animal healthcare facilities.
Provides a holistic understanding of the veterinary sterilization ecosystem, technology adoption trends, procurement dynamics, infection prevention requirements, and investment opportunities, enabling stakeholders to identify high-growth applications and optimize business strategies.
Competitive Intelligence & Vendor Benchmarking
Performed detailed benchmarking of leading veterinary sterilization container manufacturers based on product portfolio, container design, material selection, sterilization compatibility, pricing strategy, geographic presence, distribution network, partnerships, after-sales support, and regulatory compliance. Included comparative positioning of established and emerging manufacturers across global markets.
Enables identification of competitive gaps, product differentiation opportunities, partnership and acquisition targets, pricing optimization strategies, and technology leadership while supporting long-term competitive positioning and strategic decision-making.
Regional Market Expansion & Demand Assessment
Evaluated regional growth opportunities by assessing veterinary hospital infrastructure, surgical procedure volumes, companion animal ownership, livestock healthcare development, sterilization protocol adoption, procurement trends, regulatory landscape, and distributor networks. Identified priority countries and recommended market expansion strategies based on demand potential, competitive intensity, and future investment outlook.
Enables companies to prioritize high-potential regions, optimize commercial expansion strategies, allocate investments effectively, reduce market entry risks, and strengthen long-term regional presence through data-driven decision-making.
Frequently Asked Questions About This Report
The global veterinary sterilization container market size was estimated at USD 91.2 million in 2025 and is expected to reach USD 96.5 million in 2026.
The global veterinary sterilization container market is expected to grow at a compound annual growth rate of 6.5% from 2025 to 2030 to reach USD 149.6 million by 2030.
North America dominated the veterinary sterilization container market with the largest revenue share of 43.0% in 2025 owing to its well-established veterinary healthcare infrastructure, high volume of companion animal surgical procedures, and widespread adoption of advanced infection control protocols across veterinary hospitals and specialty clinics
Asia Pacific is the fastest-growing region over the forecast period.
Based on product, the sterilization containers segment led the market with the largest revenue share of 62.6% in 2025 and is expected to grow at fastest CAGR of 7.0% during forecast period.
Based on material, the aluminium segment led the market with the largest revenue share of 50.9% in 2025.
Based on type, the perforated segment led the market with the largest revenue share of 69.1% in 2025.
Some key players operating in the veterinary sterilization container market include B. Braun SE (B. Braun Vet Care GmbH); Vimian Group AB (Movora); Aesculap, Inc.; Case Medical, Inc.; KYON AG; Fine Science Tools, Inc.; Changzhou XC Medico Technology Co., Ltd.; Erbrich Instrumente GmbH; Andersen Sterilizers; Vet Direct Ltd.
Key factors that are driving the market growth include the increasing procedural volume across companion animal and livestock healthcare, growing focus on surgical infection prevention, expansion of veterinary specialty hospitals, and rising adoption of reusable sterilization systems.
About the Author(s)
Animal Health Research Team
Healthcare · Animal HealthThis report was authored by the animal health research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the animal health segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


