
- Home
- »
- Next Generation Technologies
- »
-
Virtual Reality Headset Market Size And Share Report, 2033GVR Report cover

Virtual Reality Headset Market (2026 - 2033)
Size, Share & Trends Analysis Report By End-device (Low-end, Mid-range, High-end), By Product Type (Standalone, Smartphone-enabled), By Application, By Region, And Segments Forecasts
Market Size, 2025
$14.9BMarket Estimate, 2026
$19.7BMarket Forecast, 2033
$125.9BCAGR, 2026–2033
30.4%Virtual Reality Headset Market Summary
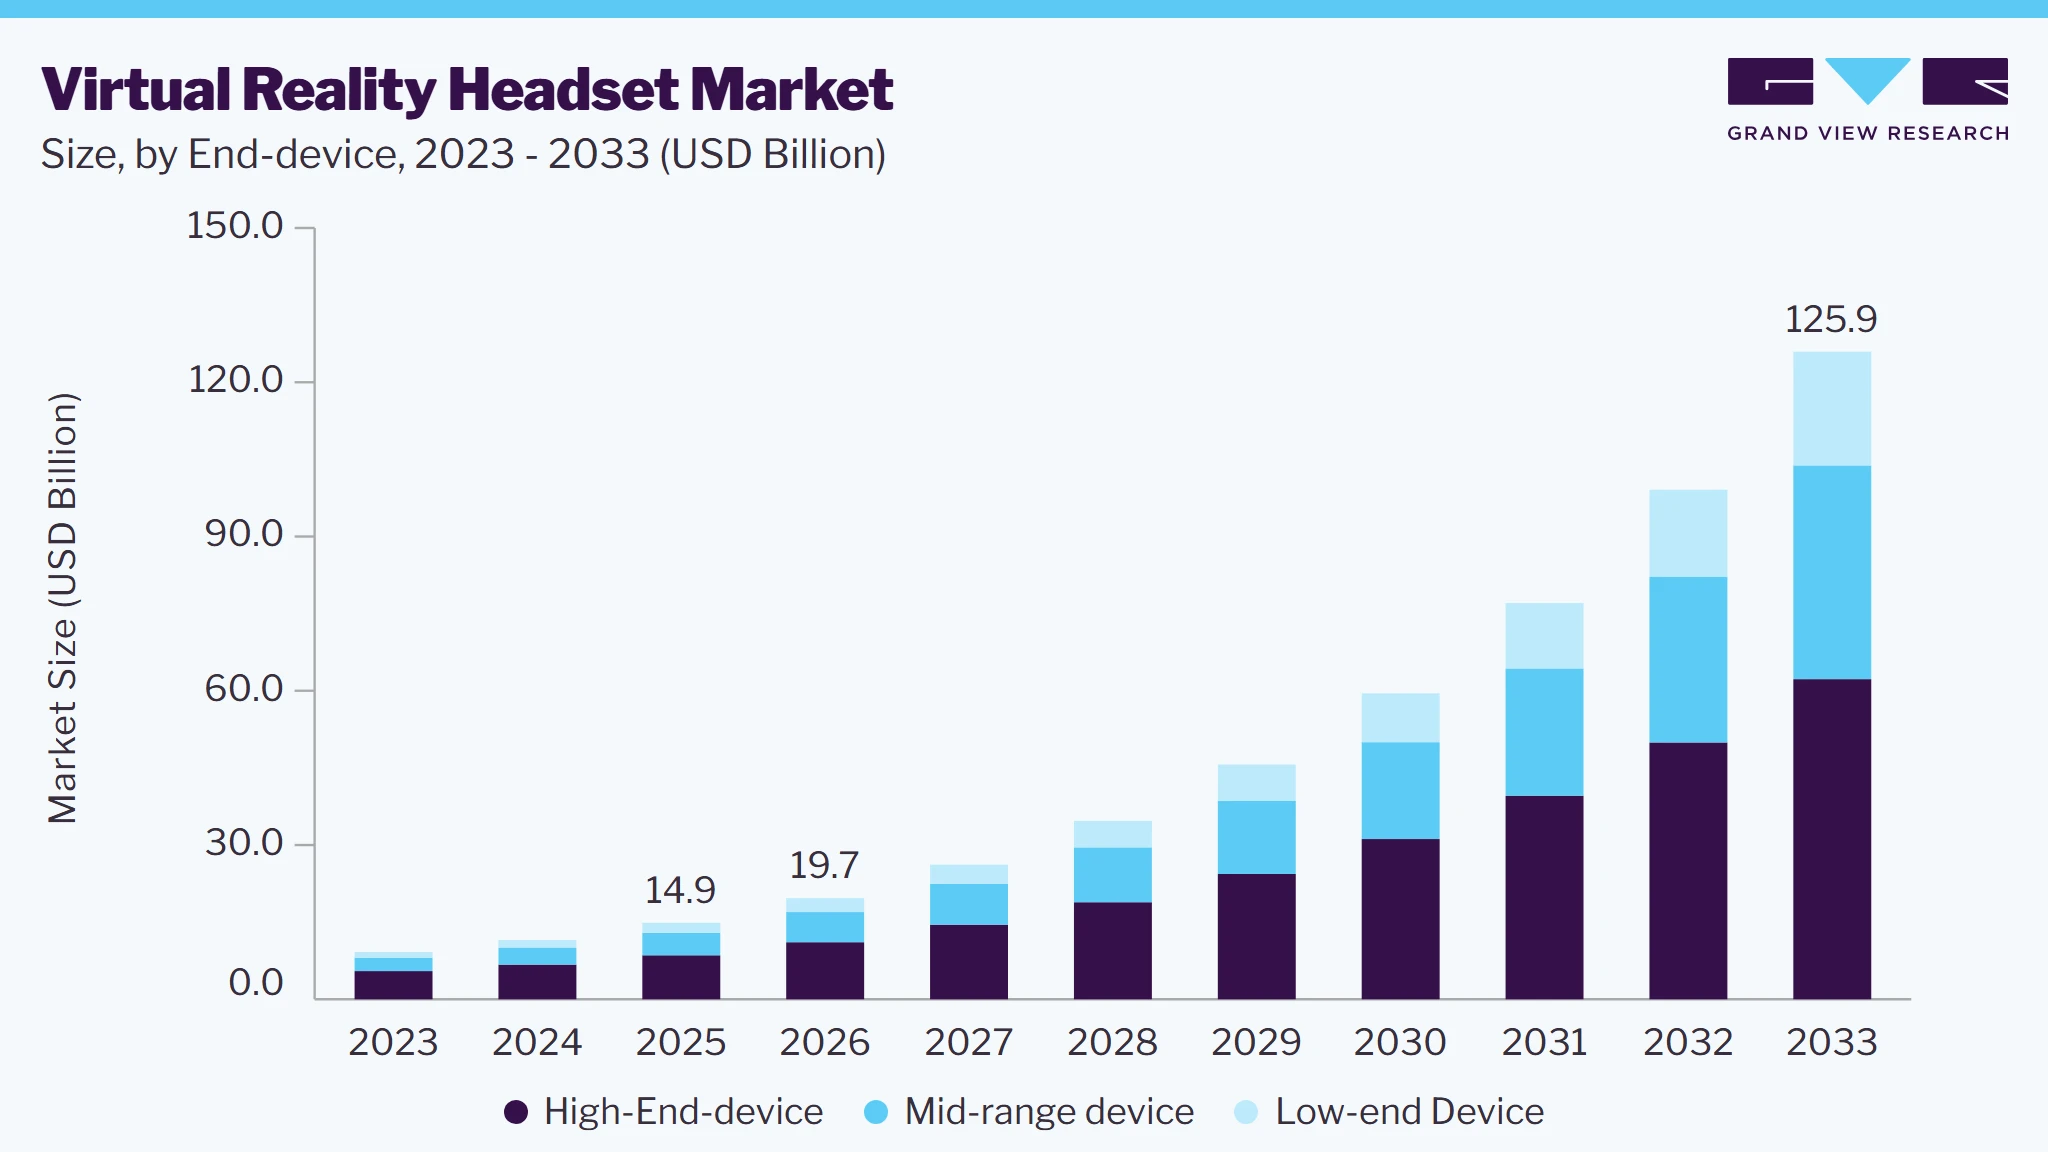
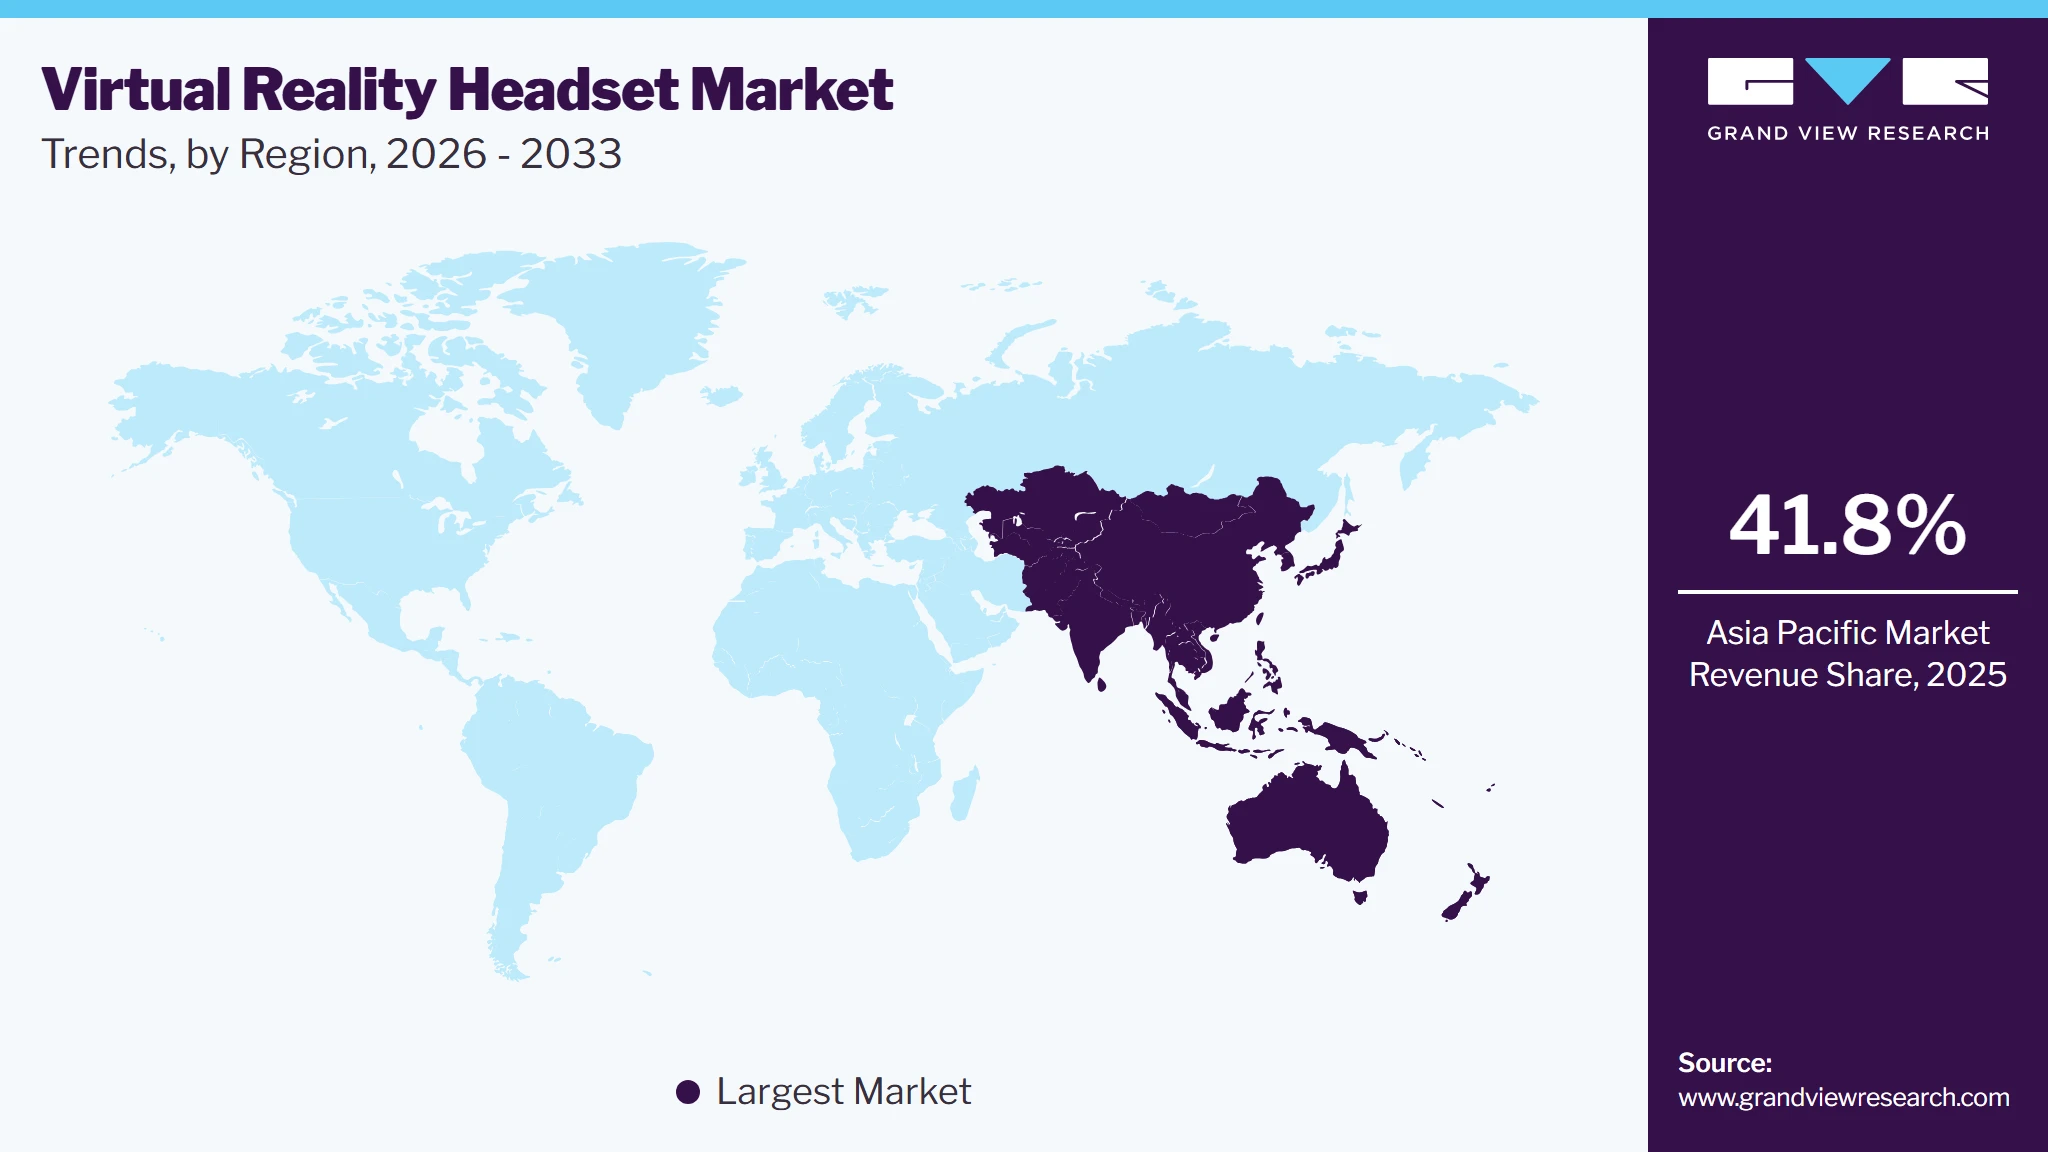
The global virtual reality headset market size was valued at USD 14.9 billion in 2025 and is projected to grow from USD 19.7 billion in 2026 to USD 125.9 billion by 2033, at a CAGR of 30.4% from 2026 to 2033. Asia Pacific dominated the global market, accounting for the largest revenue share of 41.8% in 2025. Virtual reality headset market growth is driven by increasing adoption of immersive technologies across gaming, enterprise training, healthcare simulation, education, and industrial applications.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By end-device: The high-end device segment accounted for the largest market share of 57.5% in 2025.
- By product type: The standalone segment led the market with a share of 44.3% in 2025.
- By application: The gaming segment accounted for the largest market share of 30.4% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (41.8% revenue share in 2025)
- By Country: The China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 14.9 Billion
- Estimated market size in 2026: USD 19.7 Billion
- Projected market size by 2033: USD 125.9 Billion
- CAGR (2026-2033): 30.4%
Prism AI by Grand View Research Free to tryAsk a question about the virtual reality headset marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →Advancements in AI, spatial computing, eye tracking, lightweight hardware, and high-resolution displays are enhancing user experience and expanding VR use cases. Growing investments in metaverse platforms, enterprise digital transformation, and immersive content ecosystems are further accelerating global market adoption. The extensive application of virtual reality technology in the retail and manufacturing sectors is driving market growth. Moreover, the growing demand for gaming consoles is another factor driving the growth of industry. Virtual reality technology has a vast potential to be used in a broad range of applications, such as medical training, industrial prototyping, and education. The growing consumer investments in this technology along with enterprises are expected to fuel the product demand over the forecast period. The emerging trends in virtual reality technology have a direct impact on the developments in the virtual reality headset industry.
 To learn more about this report, Download Free Sample Report
Furthermore, the integration of machine learning and Artificial Intelligence (AI) into virtual reality is likely to augment the product demand. The prominent players in the market are constantly investing in R&D for the development of state-of-the-art devices. In addition, during the Covid-19 pandemic, a large number of companies moved to online platforms to continue their business processes. The rising implementation of virtual reality technology in virtual events, which helps organizations to reach their target customers in their comfort zones by offering a life-like experience of their products and services, is further driving the growth of the market.
The growth in product adoption in the entertainment and gaming industries is enhancing the demand for VR-enabled Head-Mounted Devices (HMDs). Companies are constantly offering innovative devices to give unparalleled immersive experiences across VR entertainment. For instance, in November 2022, Facebook Technologies, LLC (Oculus) launched the XTADIUM application in their Meta Quest, giving an immersive sports experience in 180-degree VR footage of up to 8K quality. The key players in the market are focusing on integration of latest technological advancements to gain a competitive edge and improve their product offerings.
The growing trend of the virtual reality domain is becoming increasingly social and collaborative, along with the rapid penetration of smartphones is anticipated to offer various growth opportunities to the market. The benefits offered by the VR devices, such as the creation of a realistic world, immersive experience, profound visualization, and accessibility to experience different environments, are boosting the market growth. These devices have witnessed a high demand from various industrial sectors, especially for teaching and learning activities, during the Covid-19 pandemic. For instance, the U.K. government, with the help of VR headsets, trained its trauma medical professionals for the medical procedure. Likewise, the National Aeronautics and Space Administration (NASA) deployed VR technology to provide a Virtual Space Station (VSS), a suite of interactive computer-delivered treatment programs, and interactive behavioral health training.
The practical application of virtual reality technology in industries, such as healthcare, real estate, education, automotive, and retail, among others, is helping users in attaining efficient results, which is expected to fuel the market growth during the forecast period. In addition, key automotive industry companies, such as Jaguar Land Rover (JLR) and BMW, have been using virtual reality and its application for years. These companies use the technology to enhance and improve early engineering, and design reviews to check their vehicles' object obscuration and visual design.
Market Dynamics
The virtual reality headset market is experiencing robust growth, driven by the increasing adoption of immersive technologies across gaming, entertainment, healthcare, education, and industrial applications. Advancements in display quality, motion tracking, artificial intelligence, and wireless connectivity have improved user experiences, while declining hardware costs and rising consumer interest are expanding market accessibility. Additionally, growing investments by technology companies in the development of next-generation VR platforms are accelerating innovation and market expansion.
The increasing demand for immersive gaming and entertainment experiences is a major driver of the virtual reality (VR) headset market. Consumers are seeking more interactive and realistic digital experiences, encouraging the adoption of VR headsets for gaming, virtual events, simulations, and media consumption. Advancements in graphics processing, motion tracking, and spatial audio technologies have significantly enhanced the realism of VR environments, attracting both casual users and professional gamers.
Additionally, the expansion of VR content ecosystems and investments by major technology companies are supporting market growth. The availability of advanced VR platforms and a wider range of applications beyond gaming, such as virtual concerts, tourism experiences, and social interaction platforms, is increasing consumer engagement and accelerating the adoption of VR headsets globally.
The high cost of VR headsets and supporting hardware remains a key restraint on market growth. Premium VR devices often require powerful computers, advanced accessories, and additional equipment, making them less affordable for price-sensitive consumers. This cost barrier limits widespread adoption, particularly in emerging markets where consumer purchasing power is comparatively lower.
Moreover, concerns related to user comfort, such as motion sickness, heavy device design, and prolonged usage fatigue, can affect consumer acceptance. These challenges continue to restrict the mass-market penetration of VR headsets.
The growing adoption of VR technology in enterprise and healthcare applications presents significant opportunities for the VR headset market. Businesses are increasingly using VR for employee training, product design, remote collaboration, and simulation-based learning, as it enables cost-effective and risk-free practical experiences. Industries such as manufacturing, aerospace, and automotive are leveraging VR solutions to improve operational efficiency and decision-making processes.
In the healthcare sector, VR headsets are gaining importance for medical training, rehabilitation, mental health therapies, and surgical simulations. The ability of VR to create controlled and immersive environments is driving its adoption among healthcare providers and educational institutions. These new growth opportunities are expected to emerge for headset manufacturers and technology developers.
Market Concentration & Characteristics
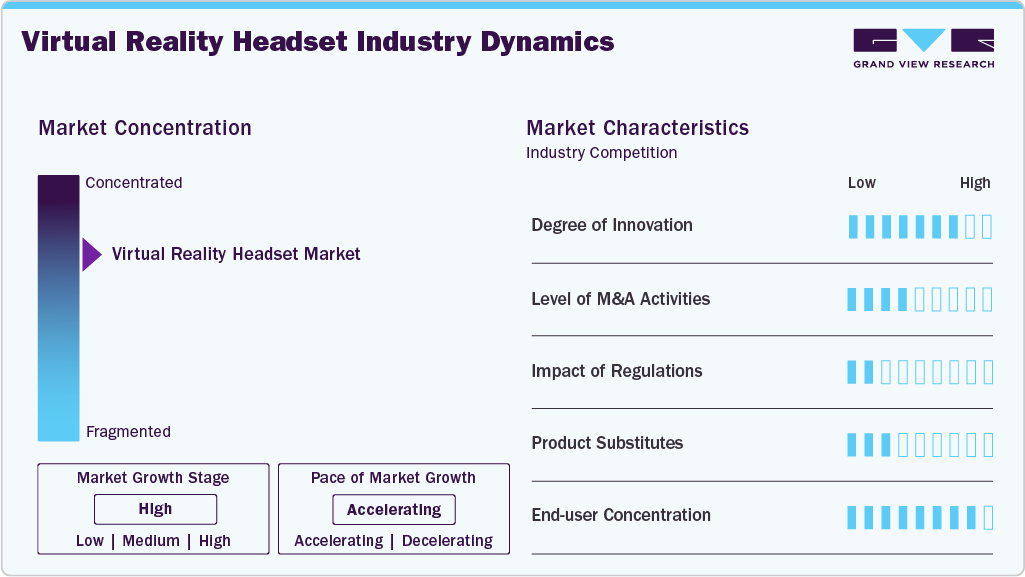
The virtual reality (VR) headset market is moderately concentrated, with established technology companies, gaming hardware manufacturers, and specialized VR solution providers. The market is driven by continuous innovation in display technologies, spatial computing, artificial intelligence (AI), motion tracking, extended reality (XR), and wireless connectivity, enabling more immersive and interactive user experiences. The level of mergers and acquisitions in the VR headset market is moderate, with technology firms investing in startups focused on immersive technologies, software platforms, and AI-based applications to enhance their VR capabilities.
 To learn more about this report, Download Free Sample Report
Regulatory influence is limited to areas such as data privacy, user safety, electromagnetic compliance, and workplace adoption standards for enterprise VR applications. Product substitution is moderate, as augmented reality (AR), mixed reality (MR), and traditional digital solutions provide alternatives for certain use cases. Market demand is diversified across gaming, healthcare, education, defense, real estate, and corporate training sectors, supported by increasing digital transformation initiatives and growing adoption of immersive technologies.
Analyst Perspective
The virtual reality headset market is experiencing strong structural growth, driven by the rising adoption of immersive technologies across gaming, enterprise training, healthcare, education, and industrial applications. Additionally, growing advancements in AI, spatial computing, display technologies, and content ecosystems are accelerating market expansion, while improving affordability and user experience are supporting broader adoption.
End-device Insights
Based on end-device, the high-end device segment dominated the market with the largest revenue share of 57.5% in 2025 and is expected to retain its dominance over the forecast period. The advanced features of these devices, including high-quality visual effects, self-tracking, and elevated performance, are expected to drive the segment growth. High-end devices are majorly used in big corporations to provide better-quality service to their customers and employees. These devices are majorly enclosed with the latest & advanced technologies that offer improved involvement and high resolution to the viewers. Continuous investments in high-end devices by prominent players, such as HP Inc.; Facebook Technologies, LLC (Oculus); and Google LLC, are likely to augment their demand over the forecast years.
The low-end device segment is anticipated to exhibit the highest CAGR of around 35.3% from 2023 to 2033. This growth can be attributed to the benefits of these devices, such as lower costs and considerable immersive experience. The low-end devices are affordable and accessible to common people who are only interested in experiencing the basic VR technology. In addition, users can use their smartphone as a sensor or display and place their smartphone into the holder, and it starts generating virtual reality. This is also expected to fuel the demand for low-end devices over the forecast period.
Product Type Insights
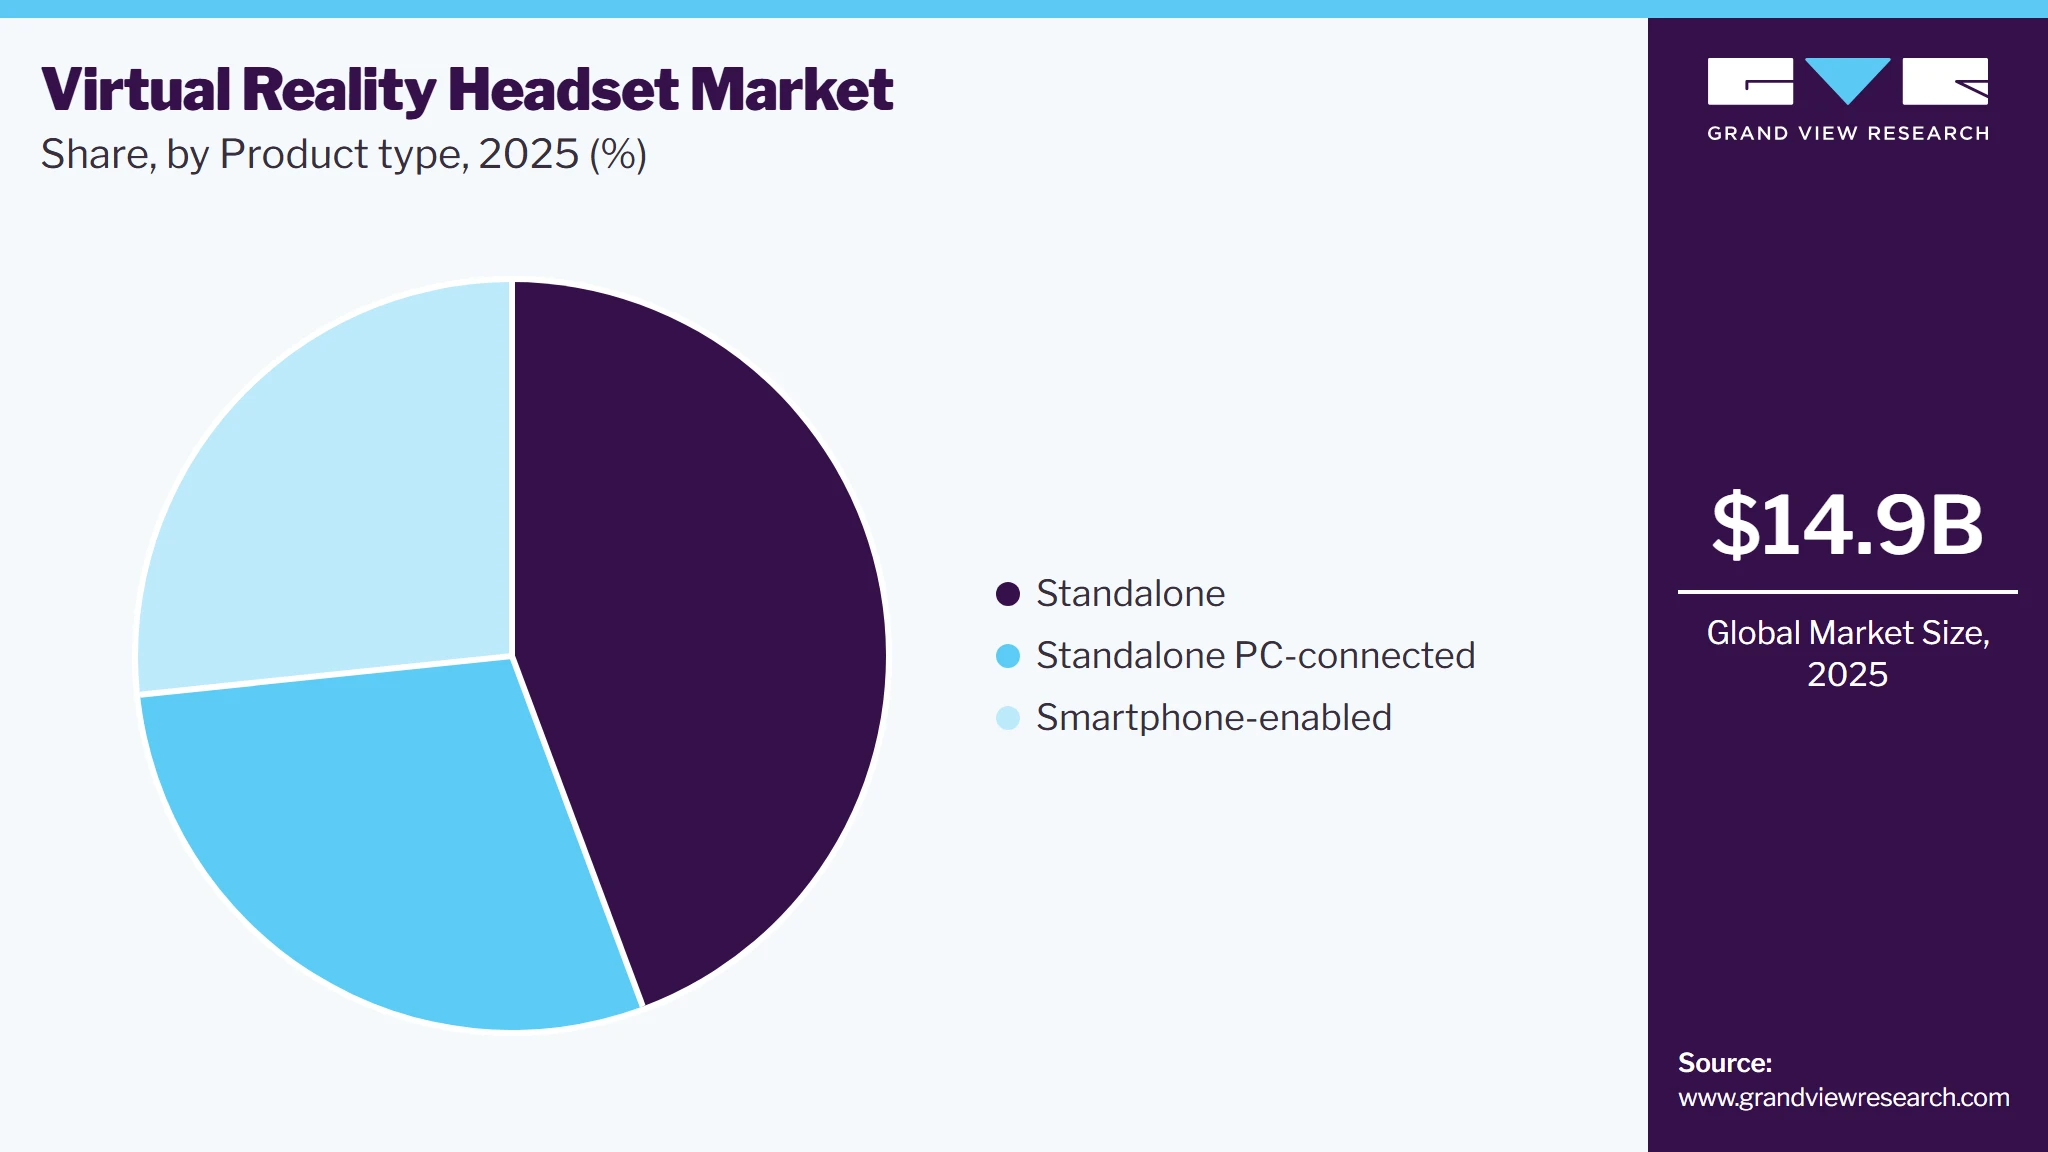
Based on product type, the standalone segment led the market with the largest revenue share of 44.3% in 2025 and is expected to grow at a considerable CAGR over the forecast period. A standalone device offers a high-quality experience at an affordable price. Its fundamental feature is the integration of various mechanisms, including processing control and hardware into a singular system. The key players offer various application-oriented devices with different features and price ranges which is driving the segment growth.
 To learn more about this report, Download Free Sample Report
The smartphone-enabled product type segment is expected to exhibit a significant CAGR of 33.1% during the forecast period. The segment growth can be attributed to the rising penetration of advanced VR-enabled smartphones with the amalgamation of 3D technology and AI. Moreover, the ease in accessibility and large-scale availability of these virtual reality headsets for smartphone users are expected to drive the segment growth during the forecast period.
Application Insights
Based on application, the gaming segment dominated the market with the largest revenue share of 30.4% in 2025 and is anticipated to dominate the global market over the forecast period. Moreover, Gaming VR headsets are equipped with advanced technologies that can even track eye movements and transmit them to the game for a better experience. This, in turn, is projected to drive the segment growth during the forecast period. Gamers have an elevated average price outlay for transforming their gaming consoles or desktops compared to users that are not indulged in gaming. This has encouraged the firms to capitalize on the VR headset games within the reasonable price range for gamers.
The education segment is anticipated to register the fastest CAGR of 33.6% from 2023 to 2033. This is attributed to the increased product deployment in educational institutions and medical schools. Moreover, the advancements in the healthcare sector due to virtual reality technology, along with favorable government regulations for facility enrichment, is promoting the segment growth. The augmented use of these headsets for providing training to medical students and assisting medics and surgeons in patient treatment, robotic surgeries, mental health & psychological therapies, and pain management & physical therapies is further driving the healthcare segment growth.
Regional Insights
Asia-Pacific dominated the virtual reality headset market, accounting for the largest revenue share of 41.8% in 2025, owing to the increased digitalization and virtual reality technology developments, particularly in the gaming and entertainment sector. The virtual reality headset market in the China held the largest share in the Asia Pacific region in 2025. Within the regional market, China captured the largest revenue share. This is attributed to the advent of 5G and policy support for virtual reality progress from the government of China. The major companies in the region are widely utilizing virtual reality technology for several purposes, thus contributing to the regional market growth. For instance, in November 2022, China released their plan dedicated to virtual reality, under which the region is planning to ship over 25 million devices with a total value of over USD 45 million by the end of 2026.
 To learn more about this report, Download Free Sample Report
North America accounted for a significant revenue share in 2022 owing to the high adoption of VR technology in the region due to high disposable income levels and weakening prices of headsets with screens and processors. The U.S. is a major contributor to the regional market growth owing to the presence of key players, such as Microsoft Corporation, Google LLC, and Facebook Technologies, LLC (Oculus), and their large-scale investments in VR technology.
Europe is expected to witness considerable developments in the market due to the substantial integration of smart devices, such as the deployment of VR headsets in various industries, including defense, entertainment, and education, to improve and develop visual experience. The increasing adoption of VR technology in amusement parks, cafes, gaming arcades, and exhibitions is positively impacting the regional market growth as well.
Key Companies & Market Share Insights
Leading companies are constantly investing in R&D for the development of cost-effective devices that offer high quality experience and can be utilized by various end-use industries. Meta Quest Pro, Meta Quest 2, HTC VIVE XR Elite, HTC VIVE Flow, and HTC VIVE Pro 2 Headset are some of the VR headsets that are prominent among several industry sectors. The significant expansion of the market is expected to be supported by gaming consoles from Nintendo, SEGA, and Atari, Inc., among others. Continuous investments in the research & development of virtual reality technology by industry participants are expected to boost the market growth over the forecast period.
The high revenues from the gaming sector guided the virtual reality device manufacturers to capitalize on the virtual reality headset segment by offering related software, hardware, and content services. Many businesses have been adopting several innovative technologies, such as Blu-ray, 4K, motion sensing, self-tracking, HD quality video, and Six Degrees of Freedom (6DoF), to cater to the changing customer demands. Moreover, M&A and partnerships with domestic firms are among the foremost stratagems implemented by the global industry players. For instance, in January 2023, Facebook Technologies, LLC (Oculus) expanded their partnership with NBA and WNBA as league's official virtual reality headset partner. This partnership is expected to offer professional basketball experience in a virtual reality environment. Some of the key players operating in the virtual reality headset market include:
Key Virtual Reality Headset Companies
The following key companies have been profiled for this study on the virtual reality headset market.
-
Carl Zeiss AG
-
Facebook Technologies, LLC (Oculus)
-
Google LLC
-
HTC Corporation
-
LG Electronics, Inc.
-
Microsoft Corporation
-
Razer Inc.
-
FOVE, Inc.
-
Valve Corporation
-
HP Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players rs (Microsoft Corporation, Google LLC, Facebook Technologies, LLC (Oculus), HTC Corporation, HP Inc., LG Electronics, Inc.)
Focus on developing comprehensive virtual reality and mixed reality ecosystems, including standalone VR headsets, enterprise-grade immersive solutions, VR software platforms, developer ecosystems, content partnerships, and cloud-enabled immersive experiences.
Strong emphasis on enterprise adoption, gaming ecosystems, spatial computing, mixed reality applications, AI integration, enterprise collaboration tools, industrial training, healthcare simulation, and professional visualization solutions.
Strong brand recognition, global distribution networks, extensive technology capabilities, large R&D investments, established software ecosystems, strong developer communities, and broad customer reach across consumer and enterprise markets.
Ability to integrate VR hardware with existing ecosystems such as operating systems, cloud platforms, gaming services, productivity tools, and enterprise solutions.
High product development costs, expensive hardware components, dependence on ecosystem adoption, challenges in achieving mass-market consumer penetration, and slower product cycles due to large organizational structures.
High competition from specialized VR companies, limited profitability from hardware sales, privacy concerns related to data collection and tracking technologies, and dependence on third-party content availability.
Emerging & Specialized Players (Carl Zeiss AG, FOVE Inc., Valve Corporation, Razer Inc.)
Focus on specialized VR technologies, including high-quality optical systems, eye-tracking solutions, gaming-focused VR hardware, precision displays, immersive peripherals, and niche applications.
Emphasis on advanced optics, gaming performance, developer-friendly platforms, premium VR experiences, and partnerships with hardware manufacturers and content providers.
Strong technical expertise in specific VR components such as optics, eye tracking, display technologies, gaming hardware, and immersive interfaces.
Ability to innovate quickly, address specialized market requirements, and deliver differentiated solutions compared with mass-market providers.
Limited market reach compared with large technology companies, smaller financial resources for large-scale R&D and marketing, limited product portfolios, and dependence on partnerships for ecosystem expansion.
Higher reliance on niche customer segments and slower mainstream adoption of specialized technologies.Virtual Reality Headset Market Report Scope
Report Attribute
Details
Market size in 2025
USD 14.9 billion
Estimated market size in 2026
USD 19.7 billion
Projected market size by 2033
USD 125.9 billion
Growth rate
CAGR of 30.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
End-device, product type, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; U.K.; Germany; France; Italy; Spain; Russia; Benelux; Nordic Countries; China; Japan; India; South Korea; Australia; Indonesia; Brazil; Argentina; UAE; Saudi Arabia; Egypt; South Africa; Nigeria
Key companies profiled
Carl Zeiss AG; Facebook Technologies, LLC (Oculus); Google LLC; HTC Corporation; LG Electronics, Inc.; Microsoft Corporation; Razer Inc.; FOVE, Inc.; Valve Corporation; HP Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Virtual Reality Headset Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and analyzes the latest market trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global virtual reality headset market report based on end-device, product type, application, and region:
 To learn more about this report, Download Free Sample Report
-
End-device Outlook (Revenue, USD Million, 2021 - 2033)
-
Low-end Device
-
Mid-range Device
-
High-end Device
-
-
Product Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Standalone
-
Smartphone-enabled
-
Standalone PC-connected
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Gaming
-
Healthcare
-
Media & Entertainment
-
Manufacturing
-
Retail
-
Education
-
Telecommunications
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
U.K.
-
Germany
-
France
-
Italy
-
Spain
-
Russia
-
Benelux
-
Nordic Countries
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Indonesia
-
-
South America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
Egypt
-
South Africa
-
Nigeria
-
-
Research Methodology
Virtual Reality Headset Market, Virtual Reality Headset Market Size, Virtual Reality Headset Market Share, Virtual Reality Headset Market Analysis, Virtual Reality Headset Market Trends, Virtual Reality Headset Industry Insights, Virtual Reality Headset Market Report, Virtual Reality Headset Industry Report, Virtual Reality Headset Market Research, Virtual Reality Headset Market Growth, Virtual Reality Headset Industry Growth, Virtual Reality Headset Market Forecast, Virtual Reality Headset Industry Forecast, Virtual Reality Headset Industry Analysis
Segment Definition
Segment - End-device
Revenue capture definition
Low-end device
Revenue is generated through the sale of affordable virtual reality headsets designed for entry-level users, offering basic VR experiences with lower processing capabilities and limited features.
Mid-range device
Revenue is captured from the sale of mid-tier virtual reality headsets that provide enhanced performance, improved displays, better tracking capabilities, and broader compatibility for gaming and consumer applications.
High-end device
Revenue is generated through premium virtual reality headsets equipped with advanced hardware, high-resolution displays, superior tracking systems, and professional-grade features for immersive gaming, enterprise, and specialized applications.
Segment - Product
Revenue capture definition
Standalone
Revenue is captured from standalone virtual reality headsets that operate independently without requiring external devices such as smartphones or PCs, generating sales through integrated processors, displays, sensors, and software ecosystems.
Smartphone-enabled
Revenue is generated through smartphone-compatible virtual reality headsets that use mobile devices as the primary processing and display unit, including sales of VR viewers, accessories, and compatible hardware solutions.
Standalone PC-connected
Revenue is captured from PC-connected virtual reality headsets that rely on computers for processing power and deliver high-performance VR experiences through advanced hardware and connectivity solutions.
Segment - Application
Revenue capture definition
Gaming
Revenue is generated through the adoption of VR headsets for immersive gaming experiences, including hardware sales, gaming accessories, and VR-compatible entertainment ecosystems.
Healthcare
Revenue is captured from the deployment of virtual reality headsets in healthcare applications such as medical training, rehabilitation, therapy, surgical simulation, and patient treatment solutions.
Media & Entertainment
Revenue is generated through the use of VR headsets for immersive content consumption, virtual events, movies, concerts, social experiences, and interactive entertainment platforms.
Manufacturing
Revenue is captured from the adoption of VR headsets in industrial applications, including product design, prototyping, employee training, maintenance simulation, and factory visualization.
Retail
Revenue is generated through the use of VR headsets for virtual shopping experiences, product visualization, customer engagement, virtual showrooms, and retail training applications.
Education
Revenue is captured from the deployment of VR headsets in educational environments for virtual classrooms, interactive learning, simulations, and skill development programs.
Telecommunications
Revenue is generated through the integration of VR headsets with communication services, virtual collaboration platforms, immersive meetings, and next-generation connectivity applications.
Others
Revenue is captured from additional applications of VR headsets across sectors such as tourism, defense, real estate, automotive, sports, and research where immersive visualization and simulation solutions are utilized.
Estimation Model
Layer Name
Key Question
Description
End-User Applications & Demand Generation Layer
Who generates demand for VR headsets?
Represents demand from consumer, enterprise, and institutional users adopting VR headset solutions. Key end users include gaming and entertainment consumers, enterprises for training and simulation, healthcare providers for medical training and therapy, educational institutions for immersive learning, defense and aerospace organizations for simulation and mission training, automotive and industrial companies for design visualization and virtual prototyping, real estate firms for virtual property tours, and content creators developing immersive experiences.
VR Hardware & Immersive Technology Layer
What technologies enable VR headset solutions?
Includes core hardware and enabling technologies such as standalone VR headsets, tethered VR systems, mixed reality (MR) headsets, displays (OLED, LCD, micro-OLED), high-resolution optics, pancake lenses, inside-out tracking, external tracking systems, motion controllers, hand tracking, eye tracking, facial tracking, haptic feedback systems, spatial audio, cameras, depth sensors, LiDAR, processors, GPUs, wireless connectivity, and AI-driven perception technologies that enable immersive virtual experiences.
Software, Content & Experience Platform Layer
How are VR headset solutions developed, deployed, and managed?
Covers software ecosystems, operating platforms, and content development solutions supporting VR adoption. Includes VR operating systems, application stores, gaming platforms, enterprise VR software, simulation and training platforms, 3D content creation tools, game engines such as Unity and Unreal Engine, digital twin platforms, collaboration platforms, virtual meeting solutions, healthcare applications, education platforms, analytics tools, device management software, cloud-based VR services, and integration solutions that connect VR headsets with enterprise systems and digital environments.
Revenue Generation & Monetization Layer
How is revenue generated in the VR headset market?
Revenue is generated through VR headset hardware sales, accessories and peripherals, software licensing, subscription-based VR platforms, enterprise VR solutions, content sales, gaming applications, virtual training services, immersive simulation solutions, professional services, device management subscriptions, enterprise deployment contracts, advertising and virtual commerce opportunities, cloud VR services, and extended support and maintenance agreements.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Market Sizing, Competitive Landscape & Growth Opportunity Assessment
Assessed the global virtual reality headset market size, historical and forecast growth trends, and detailed segmentation by end-device category (low-end, mid-range, high-end devices), product type (standalone, smartphone-enabled, standalone PC-connected), and application (gaming, healthcare, media & entertainment, manufacturing, retail, education, telecommunications, and others). The analysis evaluated adoption trends, technology advancements, consumer preferences, enterprise adoption, and emerging use cases across industries.
Supports market entry and expansion strategies, identifies high-growth segments across consumer and enterprise VR applications, improves investment prioritization within VR hardware and software ecosystems, and enables data-driven product development and commercialization.
Competitive Benchmarking & Strategic Positioning Analysis
Benchmarked leading virtual reality headset providers based on product portfolios, end-device positioning, display and optics technologies, tracking capabilities, AI integration, software ecosystems, content platforms, enterprise solutions, pricing strategies, geographic presence, strategic partnerships, acquisitions, R&D investments, and innovation capabilities.
Supports competitive differentiation, identifies technology and portfolio gaps, strengthens market positioning, improves partnership and acquisition strategies, and enables companies to develop competitive VR solutions aligned with evolving consumer and enterprise requirements.
Regional Market Demand & Application Adoption Analysis
Analyzed regional demand across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa by evaluating gaming adoption, enterprise digital transformation, healthcare technology investments, industrial training requirements, educational technology adoption, 5G infrastructure development, immersive content availability, consumer spending patterns, and government initiatives supporting digital innovation.
Supports geographic expansion planning, identifies high-growth regional markets, improves localization of VR products and services, enables targeted investment strategies, and strengthens long-term growth planning across consumer, enterprise, healthcare, education, and industrial VR applications.
Frequently Asked Questions About This Report
Asia Pacific dominated the global market, accounting for the largest revenue share of 41.8% in 2025.
Some key players operating in the virtual reality headset market include HTC Corporation; Facebook, Inc.; Google LLC; Microsoft Corporation; and Razer Inc.
Key factors that are driving the VR headset market growth include technological advancements, and a wide range of applications in healthcare, education, and industrial prototyping.
The global virtual reality headset market size was estimated at USD 14.9 billion in 2025 and is expected to reach USD 19.7 billion in 2026.
The global virtual reality headset market is expected to grow at a compound annual growth rate of 30.4% from 2026 to 2033 to reach USD 125.9 billion by 2033.
The standalone segment led the market with a share of 44.3% in 2025.
The gaming segment accounted for the largest market share of 30.4% in 2025.
The high-end device segment accounted for the largest market share of 57.5% in 2025.
The virtual reality headset market in the China held the largest share in the Asia Pacific region in 2025
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


