
- Home
- »
- Medical Devices
- »
-
Vital Signs Monitoring Devices Market Report, 2026-2033GVR Report cover

Vital Signs Monitoring Devices Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (BP Monitors, Pulse Oximeters, Temperature Monitoring Devices), By End Use (Hospitals, Ambulatory Centers), By Region (North America, Europe, Asia Pacific), And Segment Forecasts
Market Size, 2025
$10.6BMarket Estimate, 2026
$11.5BMarket Forecast, 2033
$19.3BCAGR, 2026–2033
7.7%Vital Signs Monitoring Devices Market Summary
The global vital signs monitoring devices market was valued at USD 10.6 billion in 2025 and is projected to grow from USD 11.5 billion in 2026 to USD 19.3 billion in 2033, at a CAGR of 7.7% from 2026 to 2033. North America dominated the global market, accounting for the largest revenue share of 40.0% in 2025. Constant innovation in products, increasing demand for home healthcare services, the growing number of healthcare settings, primarily hospitals, and the rising prevalence of chronic disorders are key factors contributing to the market growth.
Key Market Trends & Insights
- By product: The blood pressure monitors segment accounted for the largest share of over 45.5% in 2025.
- By end use: The hospital segment held the dominant revenue share of around 35.0% in 2025
Regional Highlights
- Largest regional market: North America (more than 40.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 10.6 Billion
- Estimated market size in 2026: USD 11.5 Billion
- 2033 Projected Market Size: USD 19.3 Billion
- CAGR (2026-2033): 7.7%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Vital signs monitoring devices have evolved from standalone instruments used to measure blood pressure, pulse rate, and temperature into integrated multi-parameter monitoring systems. In addition, continuous technological advancements and product innovations have contributed to market growth. The market is further supported by increasing demand for personalized healthcare, a growing geriatric population, rising medical insurance penetration, and expanding medical tourism activities in developing countries. Countries such as Singapore, India, Malaysia, South Korea, Thailand, and Turkey continue to attract a significant number of international patients, supporting demand for advanced healthcare infrastructure and patient monitoring technologies, including vital signs monitoring devices.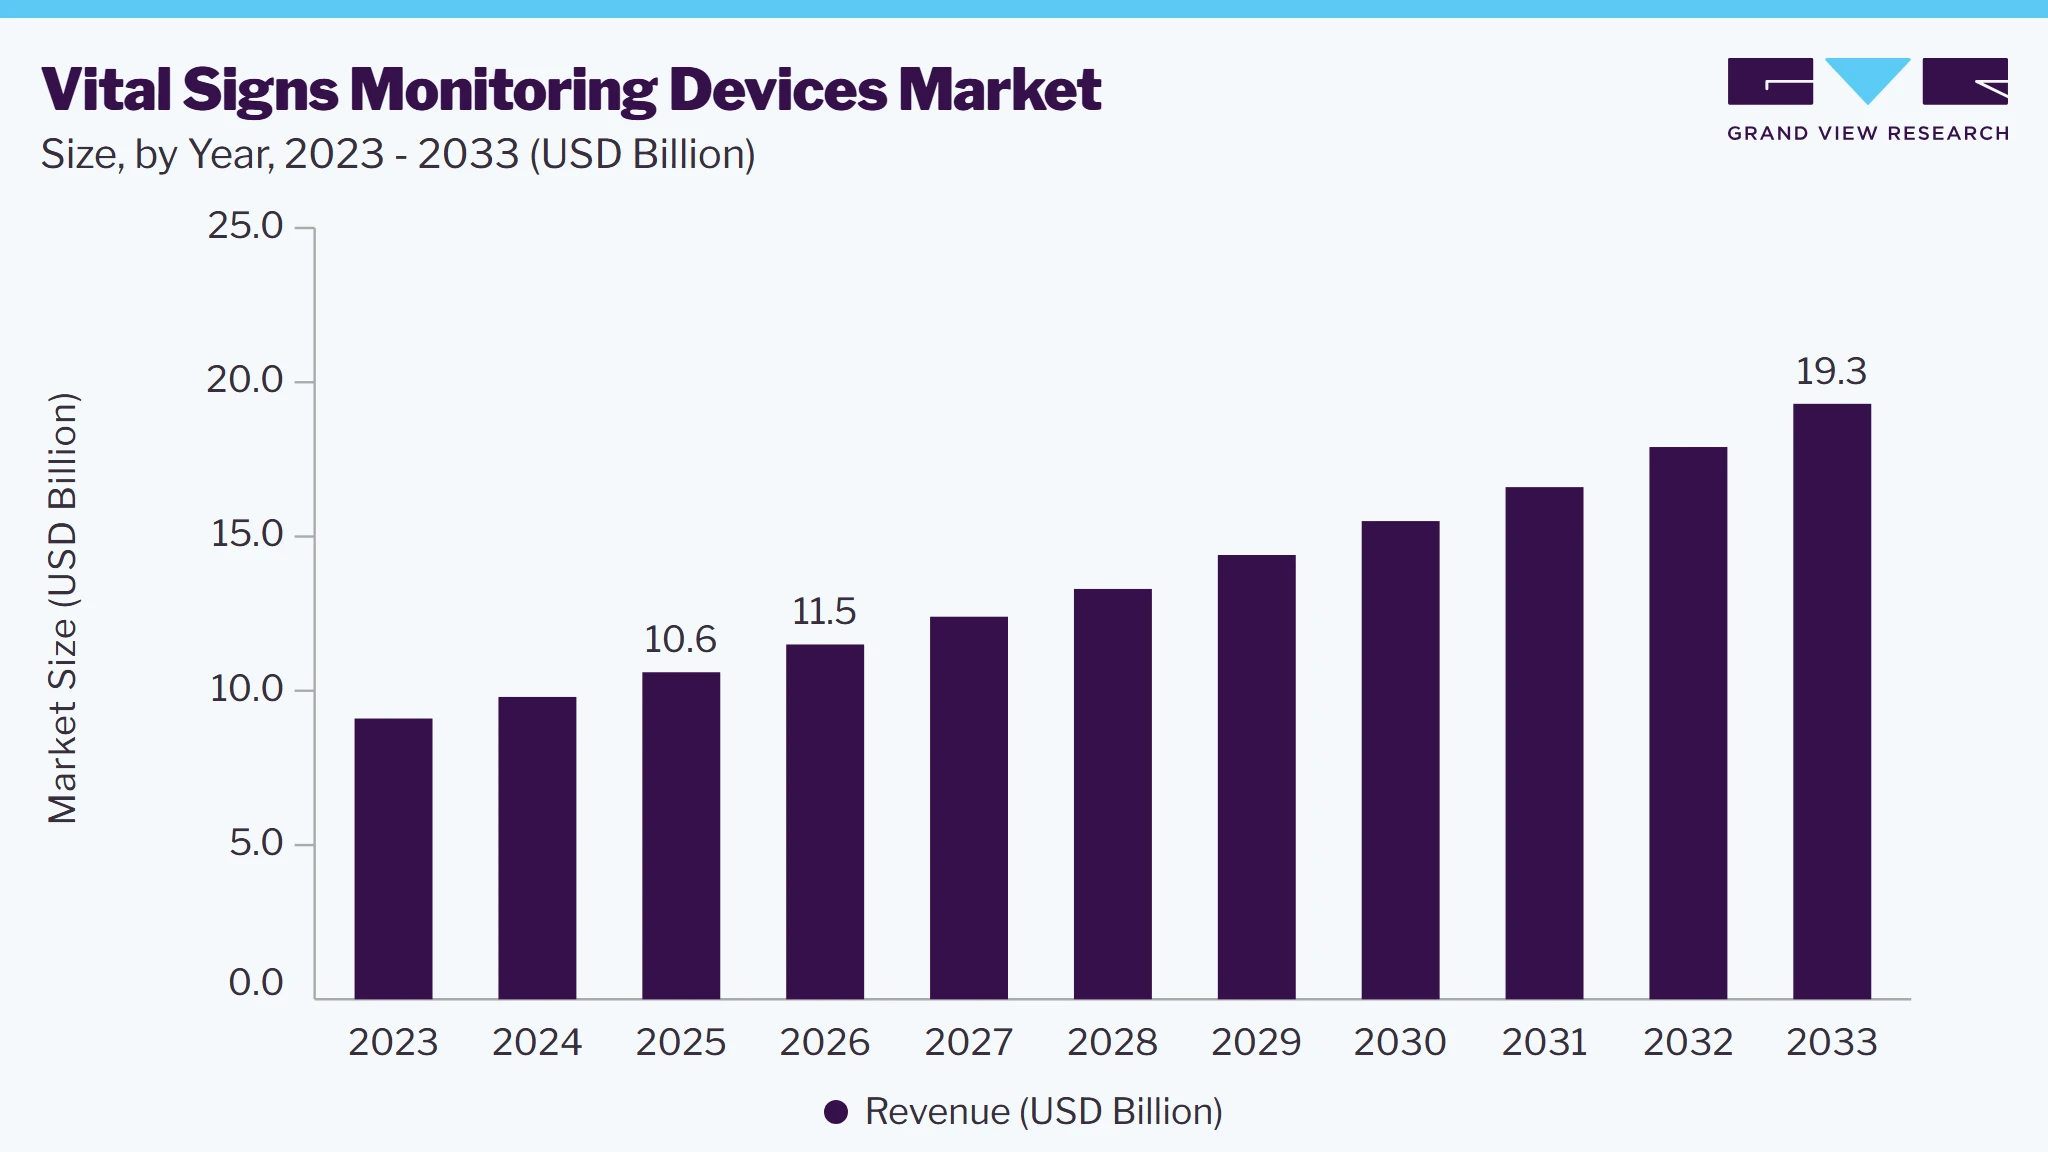 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Market Dynamics
The healthcare industry has been experiencing significant innovations across various domains and applications. The growing use of Electronic Health Record (EHR), Remote Patient Monitoring (RPM) equipment and technologies, AI-powered diagnostic devices, and others has become an integral part of care delivery. These aspects are influencing the vital sign monitoring market. The growing adoption has driven product development and new launches across several markets. For Instance, LiverRight announced a contactless remote patient monitoring platform that enables health measurements such as heart rate, respiratory rate, and blood pressure during virtual visits without the need for wearable devices.
Remote data storage poses a challenge for the vital signs monitoring devices market, as many connected monitoring systems rely on cloud platforms to store and share patient health data. Storing sensitive information on external servers increases the risk of cyberattacks, unauthorized access, and data breaches. Healthcare providers may be cautious about adopting these solutions due to privacy concerns and regulatory compliance requirements. Security incidents can result in financial penalties, reputational damage, and reduced user confidence, potentially limiting the adoption of advanced vital signs monitoring technologies.
Automated Electronic Health Record (EHR) integration is gaining importance in healthcare settings, enabling seamless transfer of patient data from monitoring devices to clinical documentation systems. This reduces manual data entry requirements, minimizes transcription errors, and improves workflow efficiency. Real-time access to accurate patient information supports informed clinical decision-making and enhances care coordination. For instance, a clinical trial on PMC titled “Closing the Loop: A Software-Based Middleware Framework for Automated Vital Sign Integration with Cloud-Based Electronic Medical Records (EMRs)” demonstrated that automated vital sign integration can eliminate redundant documentation workflows and improve operational efficiency.
Analyst Perspective
The vital signs monitoring devices market is expected to grow steadily, driven by the rising prevalence of chronic diseases, an aging population, and increasing demand for continuous patient monitoring. The adoption of connected monitoring solutions integrated with digital health platforms is improving real-time data sharing and remote patient care. Growing emphasis on preventive care and value-based healthcare is further boosting demand for smart monitoring devices. Companies focusing on connected technologies, predictive analytics, and improved patient outcomes are expected to strengthen their market position.
Product Insights
The blood pressure monitors (sphygmomanometers) segment held the largest share, accounting for over 45.5% in 2025, and is expected to grow at a significant CAGR over the forecast period. This can be attributed to the increase in the number of people requiring to monitor BP regularly due to the rapidly rising prevalence of hypertension. In addition, as awareness increases, patients today are monitoring their blood pressure as a preventive measure. This further increased demand for self-operational digital blood pressure monitors.
The segment is further categorized into table-top/bedside, fingertip, hand-held, wrist-worn, pediatric pulse oximeters, and their accessories. Fingertip pulse oximeters are likely to experience robust growth, as these devices are portable and wireless, enabling greater patient compliance. Temperature monitoring devices are categorized into digital thermometers, mercury-filled thermometers, infrared thermometers, liquid crystal thermometers, and accessories for temperature monitoring devices. Due to mercury's hazardous effects on the environment and on patients in the event of accidental breakage in the body cavity, innovations in this product segment have reduced the risk of mercury exposure, leading to digital thermometers that could measure temperature more accurately and safely.
End-use Insights
Based on end use, the hospitals segment led the market with the largest revenue share of around 35.0% in 2025, driven by a large patient pool and greater financial capacity to procure advanced monitoring equipment. Vital signs monitoring devices can be integrated with centralized monitoring platforms, enabling healthcare professionals to efficiently track patient health parameters through a single dashboard. Hospitals use a wide range of vital signs monitoring devices across various care settings, including patient rooms, nurse stations, operating theaters, emergency departments, outpatient clinics, and ambulatory care services. The need for continuous patient monitoring across these settings drives high adoption of devices in hospitals.
Demand for home healthcare services is increasing as patients increasingly prefer receiving treatment, post-surgical recovery, and long-term care in home settings. Home healthcare is often a more cost-effective alternative to extended hospital stays. In addition, developed markets such as the U.S. and the U.K. have established reimbursement frameworks for home healthcare medical devices, including vital signs monitoring devices. As the prevalence of non-communicable diseases (NCDs) continues to rise, demand for these devices in home healthcare settings is expected to increase.
Regional Insights
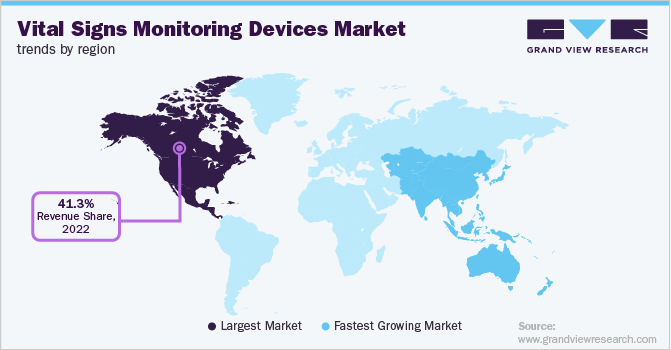
The North America region dominated the global market with a revenue share of more than 40.0% in 2025. Key factors driving market expansion include a rising geriatric population, increasing prevalence of chronic diseases, and growing adoption of remote and wireless monitoring technologies. In addition, favorable reimbursement policies, high healthcare expenditure, and broad access to healthcare services continue to support the adoption of vital signs monitoring devices across the region.
 To learn more about this report, Download Free Sample Report
Europe Vital Signs Monitoring Devices Market Trends
Europe, particularly Western European countries, is projected to remain the second-largest market during the forecast period, supported by an aging population, rising prevalence of chronic diseases, and increasing demand for cost-effective healthcare solutions. Healthcare providers are expanding the use of vital signs monitoring devices to facilitate early disease detection, continuous patient monitoring, and improved patient management. In addition, the growing adoption of remote patient monitoring programs, well-established healthcare infrastructure, and ongoing investments in digital health technologies continue to drive the adoption of vital signs monitoring devices across the region.
Asia Pacific Vital Signs Monitoring Devices Market Trends
The Asia Pacific vital signs monitoring devices market is expected to record the fastest CAGR over the forecast period, driven by large patient populations and the ongoing expansion of healthcare infrastructure in countries such as India and China. Government investments in healthcare modernization, improved healthcare accessibility in underserved areas, and increasing adoption of digital health technologies are supporting the uptake of vital signs monitoring devices. In addition, the rising prevalence of chronic diseases, increasing healthcare expenditure, and growing use of remote patient monitoring and telemedicine services continue to accelerate demand for these devices across the region.
Key Vital Signs Monitoring Devices Company Insights
The vital signs monitoring devices market is moderately consolidated, with leading companies focusing on product innovation, remote monitoring capabilities, and strategic partnerships to strengthen their market presence. Market participants are investing in digital health technologies, connected monitoring solutions, and geographic expansion to address evolving healthcare needs and enhance their competitive positioning.
Key Vital Signs Monitoring Devices Companies
The following key companies have been profiled for this study on the vital signs monitoring devices market.
-
Koninklijke Philips N.V.
-
Medtronic
-
Nihon Kohden Corp.
-
GE Healthcare
-
Masimo
-
Omron Healthcare
-
Contec Medical Systems Co., Ltd.
-
A&D Company Ltd.
-
Nonin Medical Inc.
-
SunTech Medical, Inc.
Recent Developments
-
In July 2024, Philips signed a multi-year strategic collaboration with Bon Secours Mercy Health to expand patient monitoring and connected care across its healthcare network. The agreement includes the deployment of Philips' patient monitoring technologies, software platforms, and integrated monitoring solutions to enhance clinical workflows and patient care.
-
In May 2024, Philips signed a 10-year partnership with Radboud University Medical Center to advance patient monitoring across hospital care settings. The agreement includes the deployment and long-term upgrade of Philips patient monitoring software to keep systems up to date with clinical and digital health developments.
Vital Signs Monitoring Devices Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 10.6 billion
Market size value in 2026
USD 11.5 billion
Revenue forecast in 2033
USD 19.3 billion
Growth Rate
CAGR of 7.7% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Key companies profiled
Koninklijke Philips N.V.; Medtronic; Nihon Kohden Corp.; GE Healthcare; Masimo; Omron Healthcare; Contec Medical Systems Co., Ltd.; A&D Company, Ltd.; Nonin Medical Inc.; SunTech Medical, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Vital Signs Monitoring Devices Market Report Segmentation
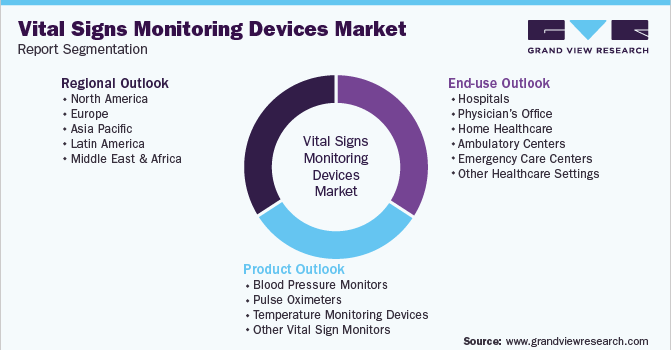
This report forecasts regional and country-level revenue growth and provides an analysis of the latest industry trends and opportunities in each subsegment from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global vital signs monitoring devices market report based on product type, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Blood Pressure Monitors
-
Aneroid Blood Pressure Monitors
-
Digital Blood Pressure Monitor
-
Ambulatory Blood Pressure Monitors
-
Blood Pressure Instrument Accessories
-
Instrument & Accessories
-
-
Pulse Oximeters
-
Table-top/Bedside Pulse Oximeters
-
Fingertip Pulse Oximeter
-
Hand-held Pulse Oximeters
-
Wrist-worn Pulse Oximeters
-
Pediatric Pulse Oximeters
-
Pulse Oximeter Accessories
-
-
Temperature Monitoring Devices
-
Mercury Filled Thermometers
-
Digital Thermometers
-
Infrared Thermometers
-
Liquid Crystal Thermometer
-
Temperature Monitoring Device Accessories
-
-
Other Vital Sign Monitors
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospitals
-
Physician’s Office
-
Home Healthcare
-
Ambulatory Centers
-
Emergency Care Centers
-
Other Healthcare Settings
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
Germany
-
U.K.
-
France
-
Italy
-
Spain
-
Sweden
-
Denmark
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Mexico
-
Brazil
-
Argentina
-
-
MEA
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global vital signs monitoring devices market size was valued at USD 10.6 billion in 2025 and is projected to grow from USD 11.5 billion in 2026.
The global vital signs monitoring devices market is expected to grow at a compound annual growth rate of 7.7% from 2026 to 2033 to reach USD 19.3 billion by 2033.
North America dominated the vital signs monitoring devices market with a share of 40.0% in 2025.
Some key players operating in the vital signs monitoring devices market include Koninklijke Philips N.V., Medtronic, Nihon Kohden Corporation, GE Healthcare, Masimo, Omron Healthcare, Contec Medical Systems Co. Ltd, A&D Company Ltd., Nonin Medical Inc., and SunTech Medical, Inc.
Key factors that are driving the vital signs monitoring devices market growth include increasing innovation, rising number of healthcare settings, increasing prevalence of chronic disorders, leading to needing of constant monitoring, and increasing need for home healthcare devices.
Blood pressure monitors segment accounted for the largest share of over 45.5% in 2025.
Hospital segment held the dominant revenue share of around 35.0% in 2025.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


