
- Home
- »
- Next Generation Technologies
- »
-
Warehouse Robotics Market Size, Share Report, 2026-2033GVR Report cover

Warehouse Robotics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product, By Function (Pick & Place, Transportation, Packaging), By Payload Capacity, By Component, By Software, By Application, By Region, And Segment Forecasts
Market Size, 2025
$7.5BMarket Estimate, 2026
$8.6BMarket Forecast, 2033
$24.2BCAGR, 2026–2033
15.9%Warehouse Robotics Market Summary
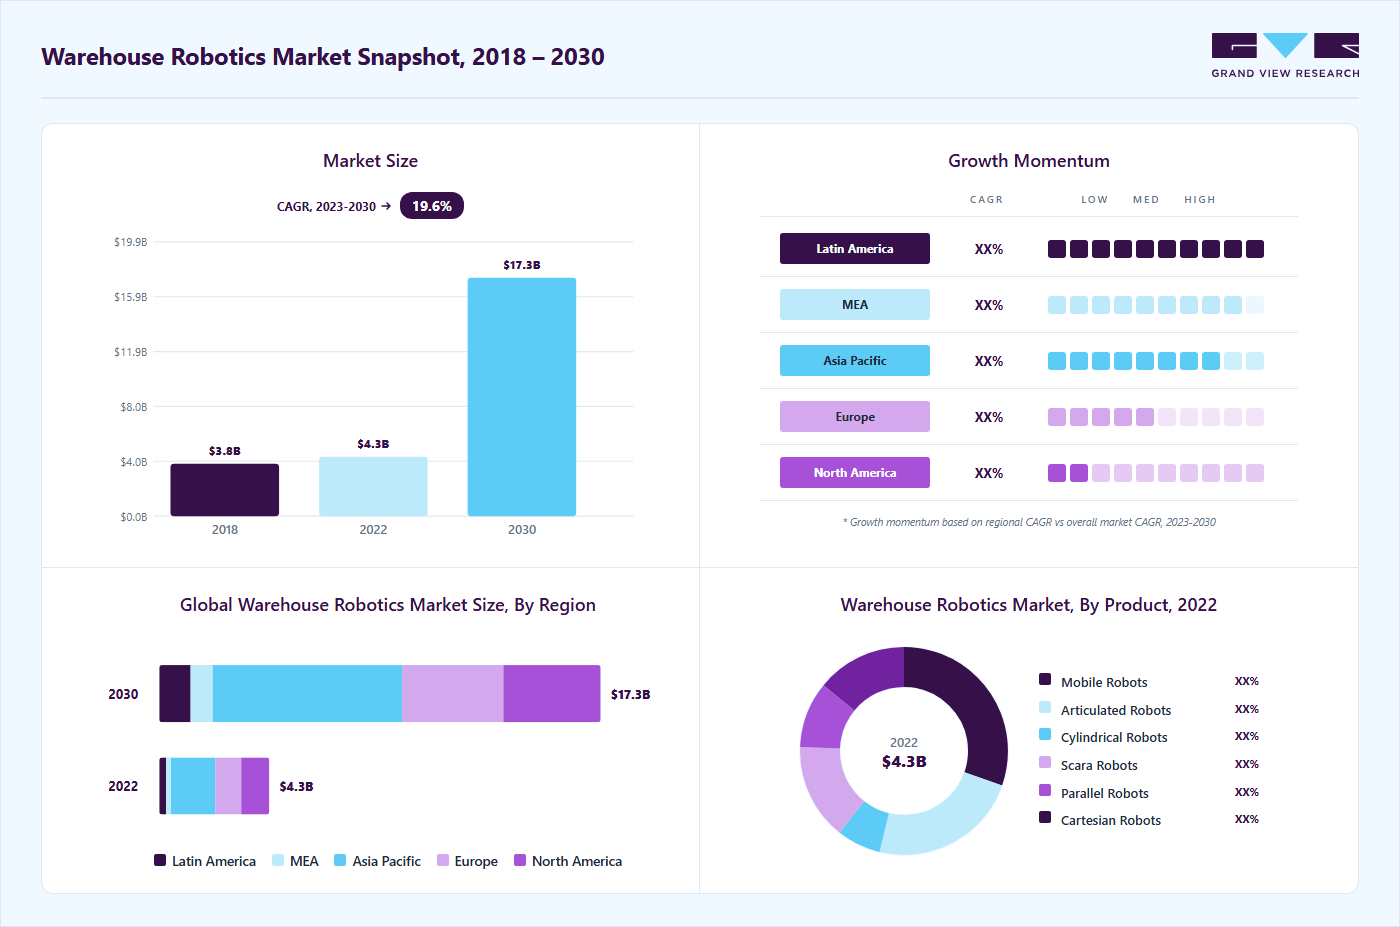
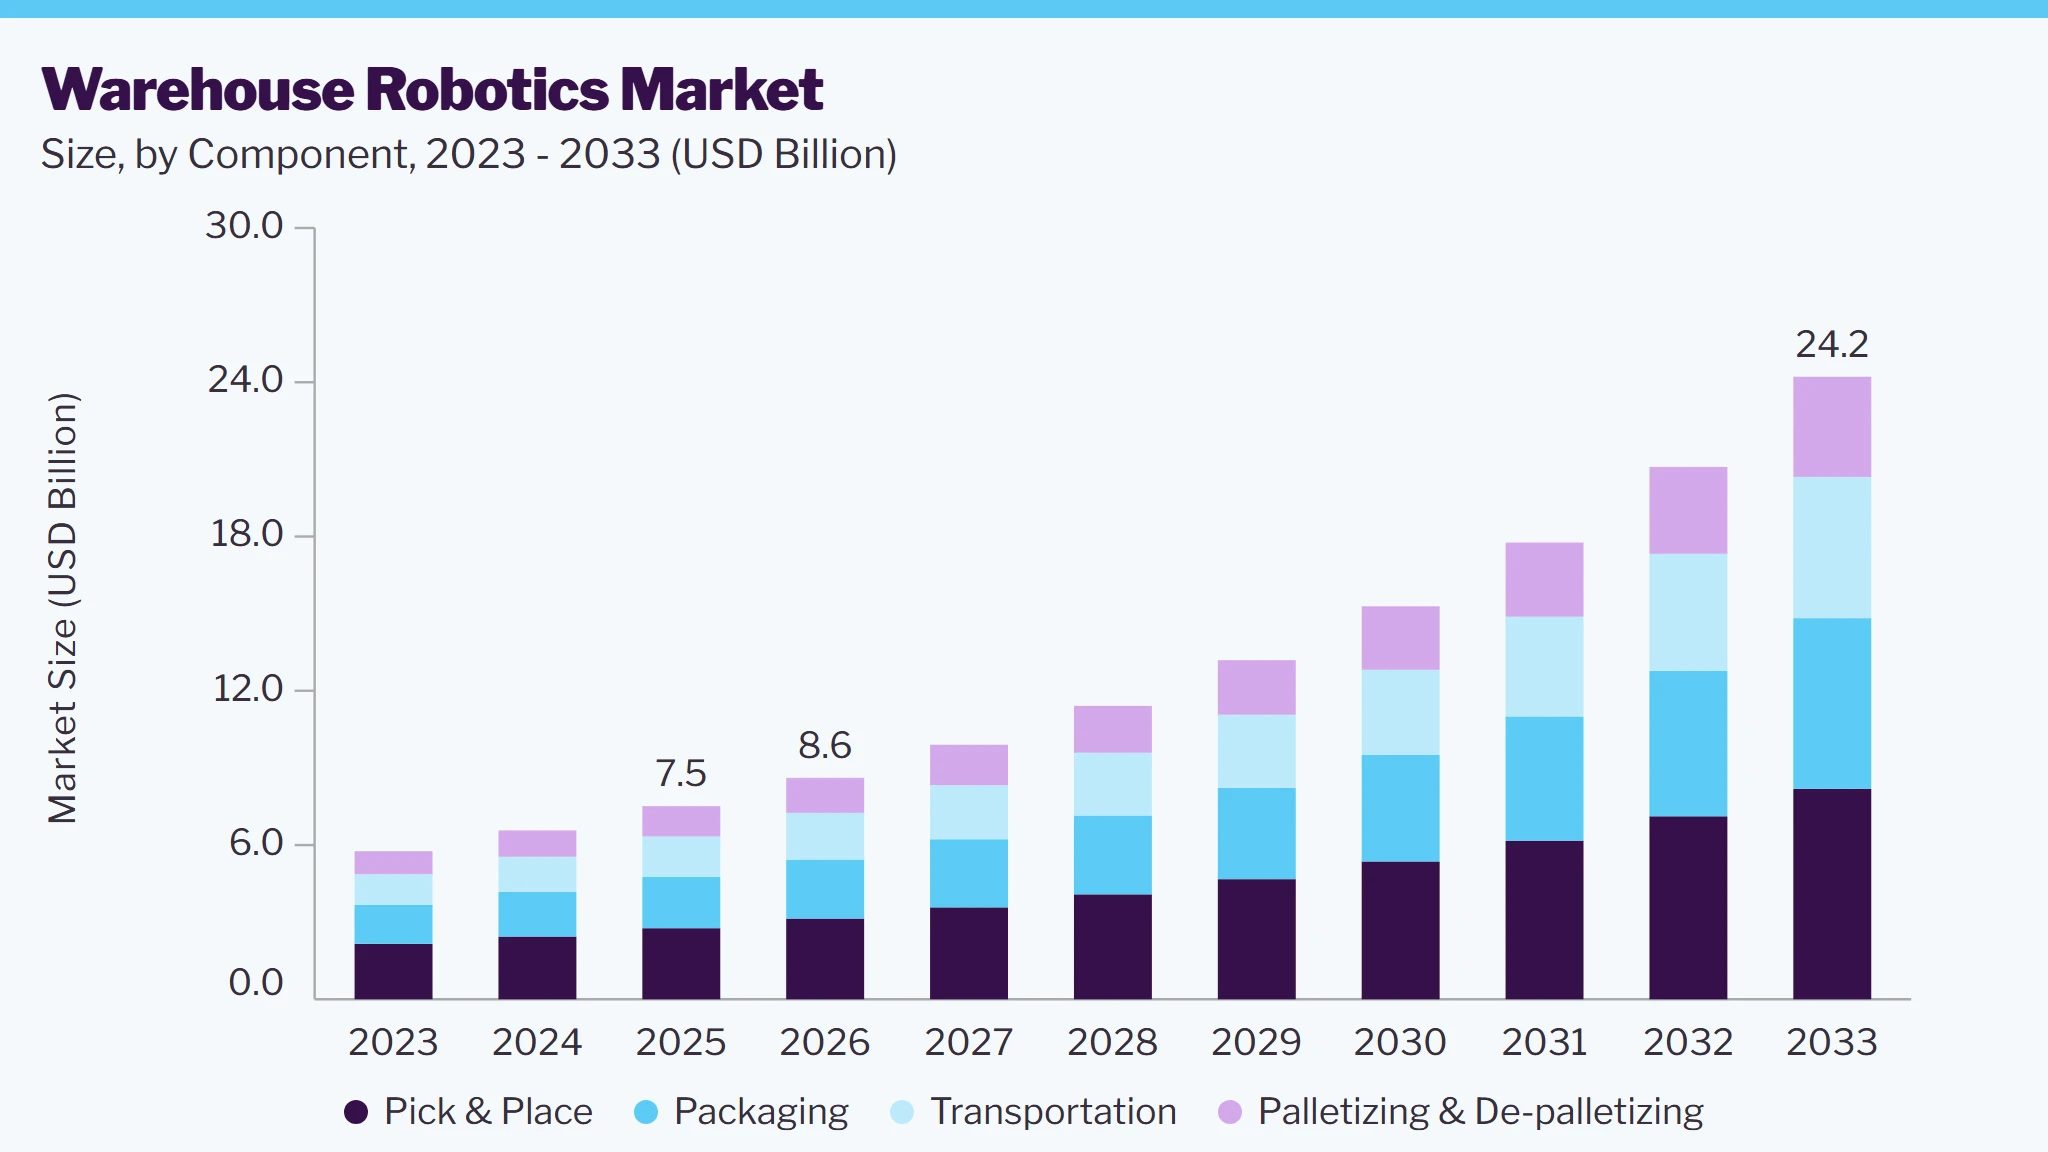
The global warehouse robotics market size was valued at USD 7.5 billion in 2025 and is projected to grow from USD 8.6 billion in 2026 to USD 24.2 billion by 2033, at a CAGR of 15.9% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 40.1% in 2025. The market growth is driven by accelerating adoption of warehouse automation, rising e-commerce penetration, rising labor cost pressures, rapid advancements in autonomous robotics and AI-enabled logistics systems, and growing demand for faster, more accurate, and scalable order fulfillment across global supply chains.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The mobile robots segment accounted for the largest market share of 30.3% in 2025.
- By function: The pick & place segment led the market with a share of 36.8% in 2025.
- By payload capacity: The below 10 kg segment dominated the market, with a share of 32.2% in 2025.
- By component: The software segment dominated the market with a share of 47.4% in 2025.
- By application: The e-commerce segment accounted for the largest market share of 31.1% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (40.1% revenue share in 2025)
- Fastest growing regional market: Asia Pacific (highest CAGR 17.2%, 2026-2033)
- By Country: The China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 7.5 Billion
- Estimated market size in 2026: USD 8.6 Billion
- Projected market size by 2033: USD 24.2 Billion
- CAGR (2026-2033): 15.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These factors are further reinforced by the expansion of omnichannel retail, increasing investments in smart warehouses, and the adoption of Robotics-as-a-Service (RaaS) models that are making automation more accessible across enterprises of all sizes. Warehouse robotics offers enhanced facility safety as it takes over hazardous jobs that put workers at risk.
 To learn more about this report, Download Free Sample Report
The growing e-commerce industry owing wide availability of websites and choices results in technological developments. The technologies such as Virtual Reality (VR), Augmented Reality (AR), blockchain technology, Machine Learning (ML), and Artificial Intelligence (AI) are helping marketers to enhance the shopping experience.
Due to aforementioned reason, the warehouse robotics market players are constantly looking for new methods to reduce operational costs, delivery time, and risks to the workers. Robots offer cost-effective, smart alternatives to human labor by automating warehouses in the e-commerce sector. Thus, the growing e-commerce sector is anticipated to drive the growth of the market.
The robots are implemented to automate various tasks in the packing and shipping sector, such as loading, delivery, and unloading. The warehouse industry players are moving towards automation technologies to reduce dependence on workforces. Moreover, the robots are less prone to errors and reduce time and effort during repetitive tasks that are monotonous to the employees. They assist employees in performing heavy and dangerous tasks while providing strength, efficiency, and expertise to maintain employee safety while increasing productivity.
The market players are focusing on enhanced warehouse operations while reducing costs. Delivery errors, picking errors, and transportation damage consumes a lot of time and budget by increasing operational costs and reducing profitability. Further, companies opt for warehouse automation to reduce complexity of processes and eliminate performance burdens. Warehouse robotics has helped companies meet the quality standards of each order, regulate protocols and procedures based on fundamental criteria for various warehouse operations, and enhance the operational productivity of businesses.
Market Dynamics
The warehouse robotics market is experiencing robust growth, driven by the increasing need for automated, scalable, and intelligent warehouse operations across logistics, retail, manufacturing, and e-commerce sectors. Rising fulfillment complexity, labor shortages, higher throughput requirements, and advancements in autonomous robotics, AI, machine vision, and warehouse software are accelerating adoption. Continued investments in smart warehouses, robotics-as-a-service (RaaS), and digital supply chain transformation are further supporting long-term market expansion across both developed and emerging economies.
The rapid expansion of e-commerce and omnichannel retail is one of the primary drivers of the warehouse robotics market. Rising online order volumes, increasing consumer expectations for same-day and next-day delivery, and the growing complexity of inventory management have encouraged warehouse operators to automate material handling and order fulfillment processes. Warehouse robots, including autonomous mobile robots (AMRs), robotic picking systems, and automated storage and retrieval systems (AS/RS), enable faster order processing, improved inventory accuracy, and higher warehouse throughput.
Additionally, retailers, third-party logistics (3PL) providers, and manufacturers are investing in intelligent warehouse automation to address labor shortages and reduce operational costs. Robotics solutions improve workforce productivity, minimize human error, and enable warehouses to operate continuously with greater efficiency, making them a critical component of modern supply chain and fulfillment operations.
Warehouse robotics systems require substantial upfront capital for robotic hardware, warehouse software, infrastructure modifications, and system integration. Small and medium-sized enterprises (SMEs) often face financial constraints that limit their ability to adopt comprehensive warehouse automation solutions, particularly in developing markets.
Furthermore, integrating warehouse robots with existing Warehouse Management Systems (WMS), Warehouse Control Systems (WCS), Enterprise Resource Planning (ERP) platforms, conveyors, and legacy warehouse infrastructure can be technically complex and time-consuming. The need for customized system design, employee training, and ongoing maintenance further increases implementation costs and extends deployment timelines, slowing adoption among budget-sensitive organizations.
The increasing adoption of artificial intelligence (AI), machine learning, and advanced computer vision technologies is creating significant growth opportunities for the warehouse robotics market. AI-powered robots can dynamically optimize travel routes, intelligently prioritize tasks, recognize products with greater accuracy, and collaborate safely with human workers, significantly improving warehouse productivity and operational flexibility.
Furthermore, the growing adoption of Robotics-as-a-Service (RaaS), cloud-based fleet management, and digital twin technologies is making warehouse automation more accessible to organizations of all sizes. Emerging applications in micro-fulfillment centers, cold-chain logistics, pharmaceutical warehousing, and manufacturing distribution facilities are expected to further expand the addressable market, creating new revenue opportunities for robotics manufacturers and software providers.
Market Concentration & Characteristics
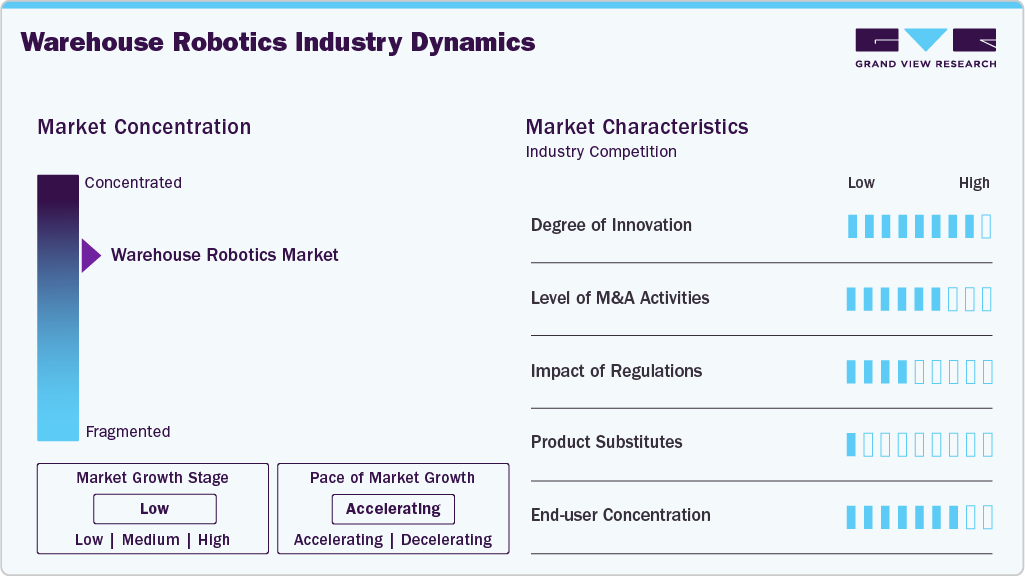
The warehouse robotics market is moderately concentrated, with global industrial automation companies competing alongside specialized warehouse robotics providers and emerging autonomous mobile robot (AMR) developers. The market is highly innovation-driven, supported by advances in artificial intelligence (AI), machine vision, autonomous navigation, collaborative robotics, IoT, cloud robotics, and warehouse execution software, enabling higher warehouse productivity, operational efficiency, and fulfillment accuracy. The level of mergers & acquisitions is high, as established automation companies acquire robotics startups, AI firms, and warehouse software providers to strengthen their automation portfolios, expand autonomous capabilities, and accelerate end-to-end warehouse digitalization. Regulatory influence is moderate, primarily related to workplace safety, industrial robot standards, cybersecurity, functional safety, and autonomous machine operation.
 To learn more about this report, Download Free Sample Report
Product substitution is low, as warehouse robotics provides significant productivity, accuracy, scalability, and labor efficiency benefits that conventional manual warehouse operations cannot easily replicate. Demand is diversified across e-commerce, third-party logistics (3PL), retail distribution, automotive, consumer electronics, food & beverage, pharmaceuticals, and manufacturing sectors, driven by increasing order volumes, labor shortages, omnichannel fulfillment requirements, and growing investments in warehouse automation and smart logistics.
Analyst Perspective
The warehouse robotics market is experiencing strong structural growth, driven by the rapid shift toward warehouse automation, e-commerce fulfillment, omnichannel retail operations, and AI-enabled intralogistics. Increasing labor shortages, rising order volumes, demand for faster delivery, and the need for improved operational efficiency are accelerating the adoption of autonomous mobile robots (AMRs), robotic picking systems, automated storage and retrieval systems (AS/RS), and intelligent warehouse management solutions across industries.
Product Insights
Based on product, the mobile robots segment led the market with the largest revenue share of 30.3% in 2025 and is expected to grow at a considerable CAGR over the forecast period. The growth of the segment is attributed to the increasing demand for automation in the packaging, automotive, and pharmaceutical industries. Cartesian robots are widely adopted in such industries due to their accuracy, precision, and ability to handle heavy loads.
Moreover, demand for automated material handling in the industrial sector due to the need for higher productivity, efficiency, and flexibility in warehouse operations is expected to fuel the further growth of cartesian robots over the forecast period.
The mobile robots accounted for the highest market share in 2022. Ongoing technological advancements in the global wearehouse & logistics industry, including machine learning, computer vision, and artificial intelligence is contributing to the development of smarter mobile robots.
The rising need for efficient and cost-effective solutions in logistics and warehousing to increase productivity and profitability, has inspired companies to adopt mobile robots. Moreover, the adoption of mobile robots is growing in various industries, such as manufacturing, healthcare, retail, and agriculture, due to their features such as easy maneuverability and autonomous operation.
Function Insights
Based on function, the pick & place segment dominated the market with the largest revenue share of 36.8% in 2025. Ongoing growth of the retail and e-commerce sector coupled with the growing demand for automated robots for improved efficiency and reduced costs in logistics has driven growth of the transport segment.
Furthermore, incorporating robots for transport function helps companies overcome labor shortage concerns by automating a variety of tasks. For instance, in November 2022, KNAPP AG collaborated with eMAG.ro, MALL.CZ, HPTRONICS and Alza.cz. This partnership has helped companies to enhance their logistics and operations and hold a strong position as a major technology provider for e-com logistics in Central and South Eastern Europe.
The pick & place accounted for the highest market share in 2022 in the function segment. This growth is attributed to the continuous technological advancements in robots, making them more efficient, accurate, and versatile for pick-and-place activities.
For instance, in December 2022, ABB announced the launch of the SWIFTI CRB1300 industrial collaborative robot; the robot is specially designed for activities from machine tending and palletizing to pick and place and screw driving. Moreover, the cost of pick-and-place robots has decreased over the years; they have become more accessible to smaller businesses and manufacturers, resulting in increased adoption of robots for pick and place activities.
Components Insights
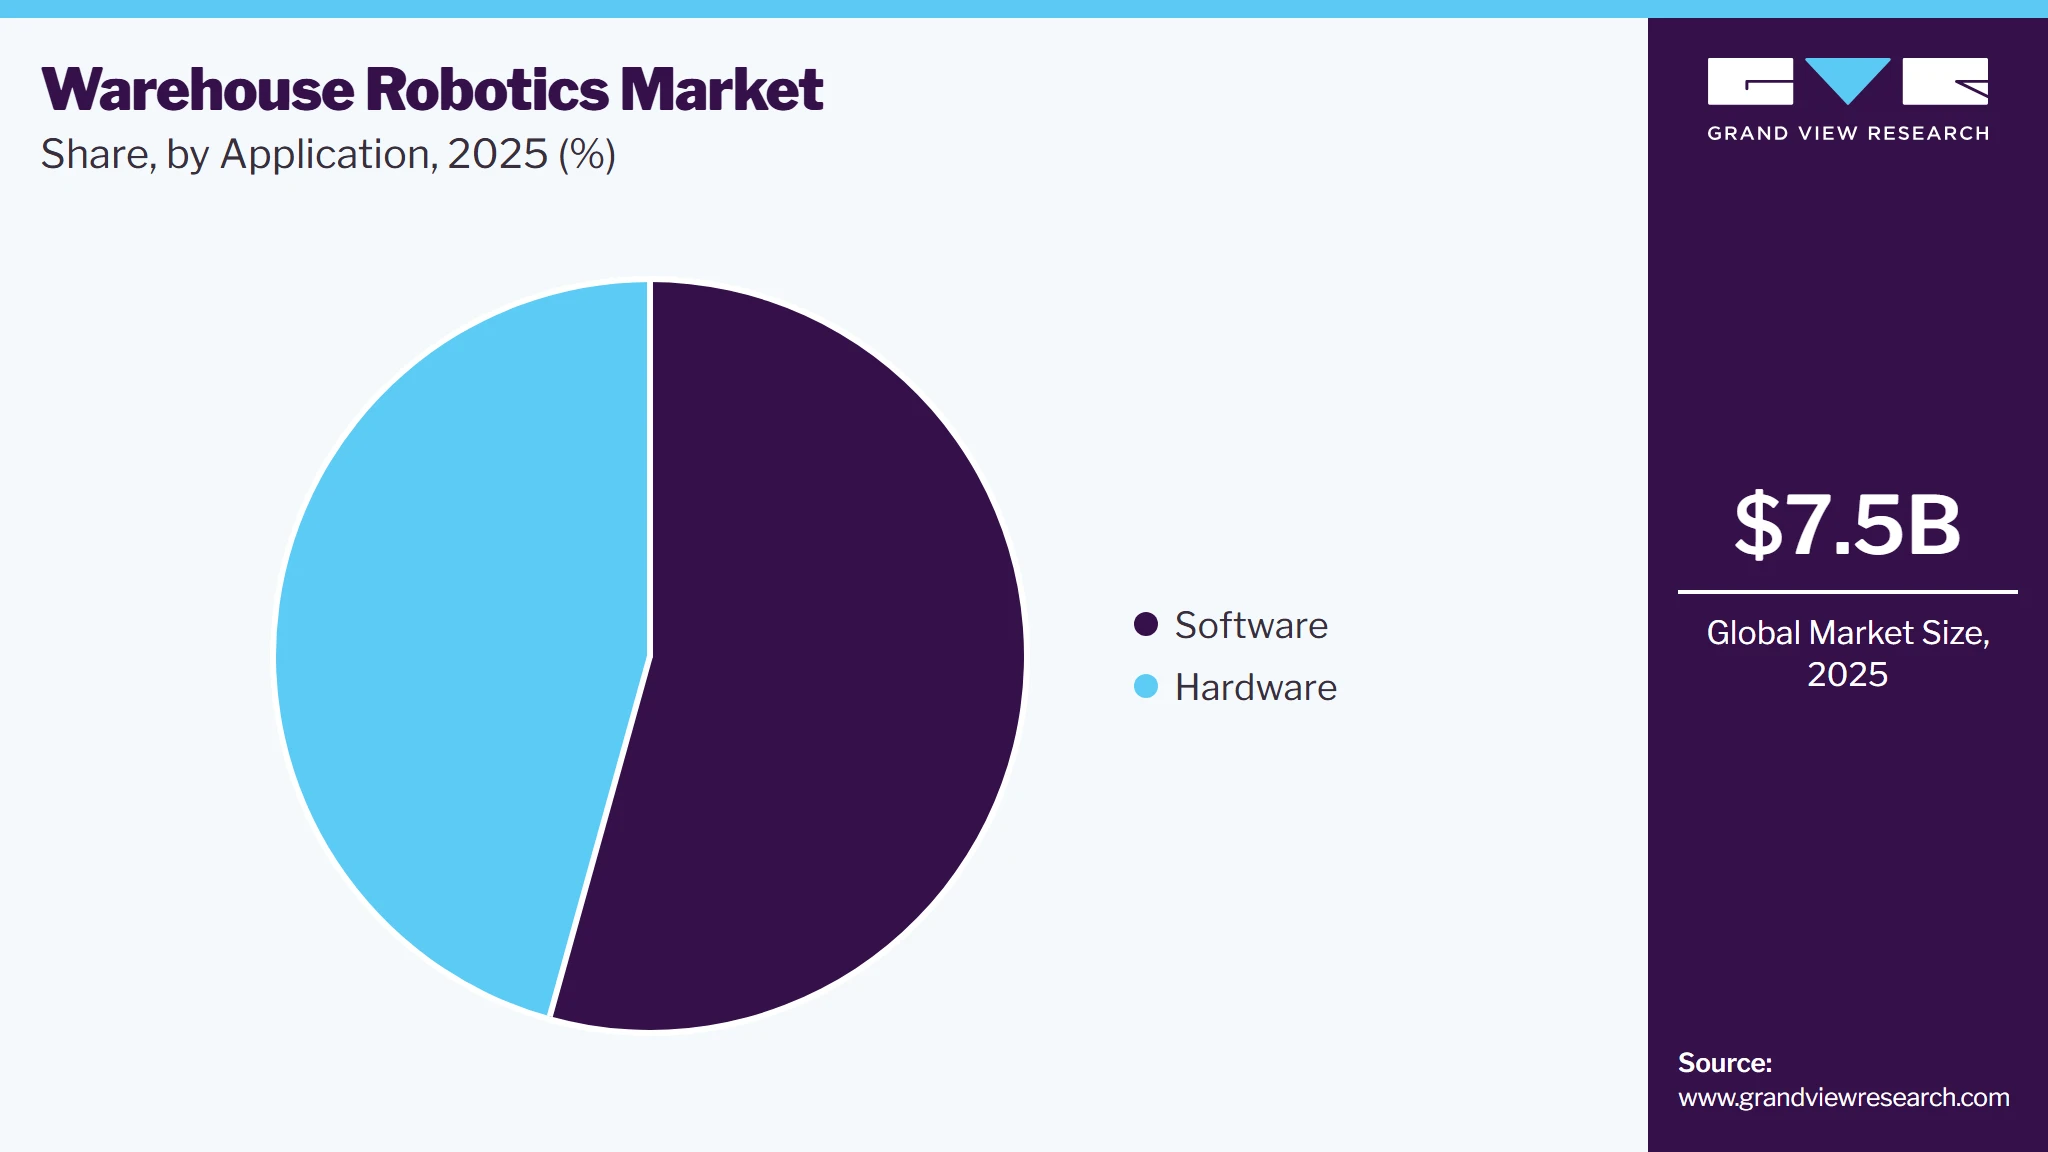
Based on component, the software dominated the market with the largest revenue share of 54.3% in 2025. The segment is divided into a warehouse management system, a warehouse control system, and a warehouse execution system. The software tools helps in reducing the manual tasks necessary across warehouse operations.
Thus, need for increased efficiency in warehouse operations and to reduce human errors has contributed to the growth of the warehouse robotics software segment. Furthermore, the incorporation of Artificial Intelligence (AI) is anticipated to boost the growth in the forthcoming years.
The hardware segment is expected to witness a CAGR of more than 17% from 2023 to 2030. The developments in the hardware of robots, such as foldable robots that can change shape and size, making them more versatile, are becoming increasingly popular. Furthermore, the increasing adoption of collaborative robots in a wide range of industries owing to their variety of advantages compared to traditional robots is expected to fuel the growth of the hardware segment from 2023 to 2030.
Application Insights
Based on application, the e-commerce dominated the market with the largest revenue share of 31.1% in 2025. Technological developments have enabled machines with remarkable machine dexterity, which allows machines to perform delegated tasks with significant ease in healthcare warehouses. Increasing demand for medications and vaccines, pharmaceutical companies are looking for ways to improve their supply chain and reduce errors in medication dispensing. Warehouse robotics can help automate the process to improve efficiency.
 To learn more about this report, Download Free Sample Report
The e-commerce segment accounted for the highest market share in 2022. The growth is attributed to the increased preference for online shopping; the rising demand for fast and efficient order fulfillment has played an important role in automating warehouses and fulfillment centers. E-commerce companies are increasingly adopting warehouse robotics solutions to improve their supply chain management and order fulfillment processes. The increased demand to increase the speed while maintaining accuracy is expected to fuel the further growth of the e-commerce segment over the forecast period.
Payload Capacity Insights
Based on payload capacity, the below 10 kg segment dominated the market with the largest revenue share of 32.2% in 2025. The increasing volume of lightweight and small packages that need to be handled in distribution centers and warehouse options owing to the rising adoption of e-commerce shopping is a major driver for the growth of below 10 kg warehouse robots. The increased adoption of lower payload capacity robots in consumer electronics and food & beverages industries is expected to drive the growth of the below 10 kg warehouse robots segment over the forecast period.
The 11 kg to 80 kg warehouse robots is anticipated to witness a CAGR of approximately 20% from 2023 to 2030. The growth is attributed to their ability to efficiently handle medium to heavy-weight items. Moreover, the demand for robots with higher payload capacity is increasing in warehouses of various applications such as manufacturing, healthcare, food, beverages, and more. The continuous technological developments and rising demand for automation in logistics and warehouse operations are expected to support market growth.
Regional Insights
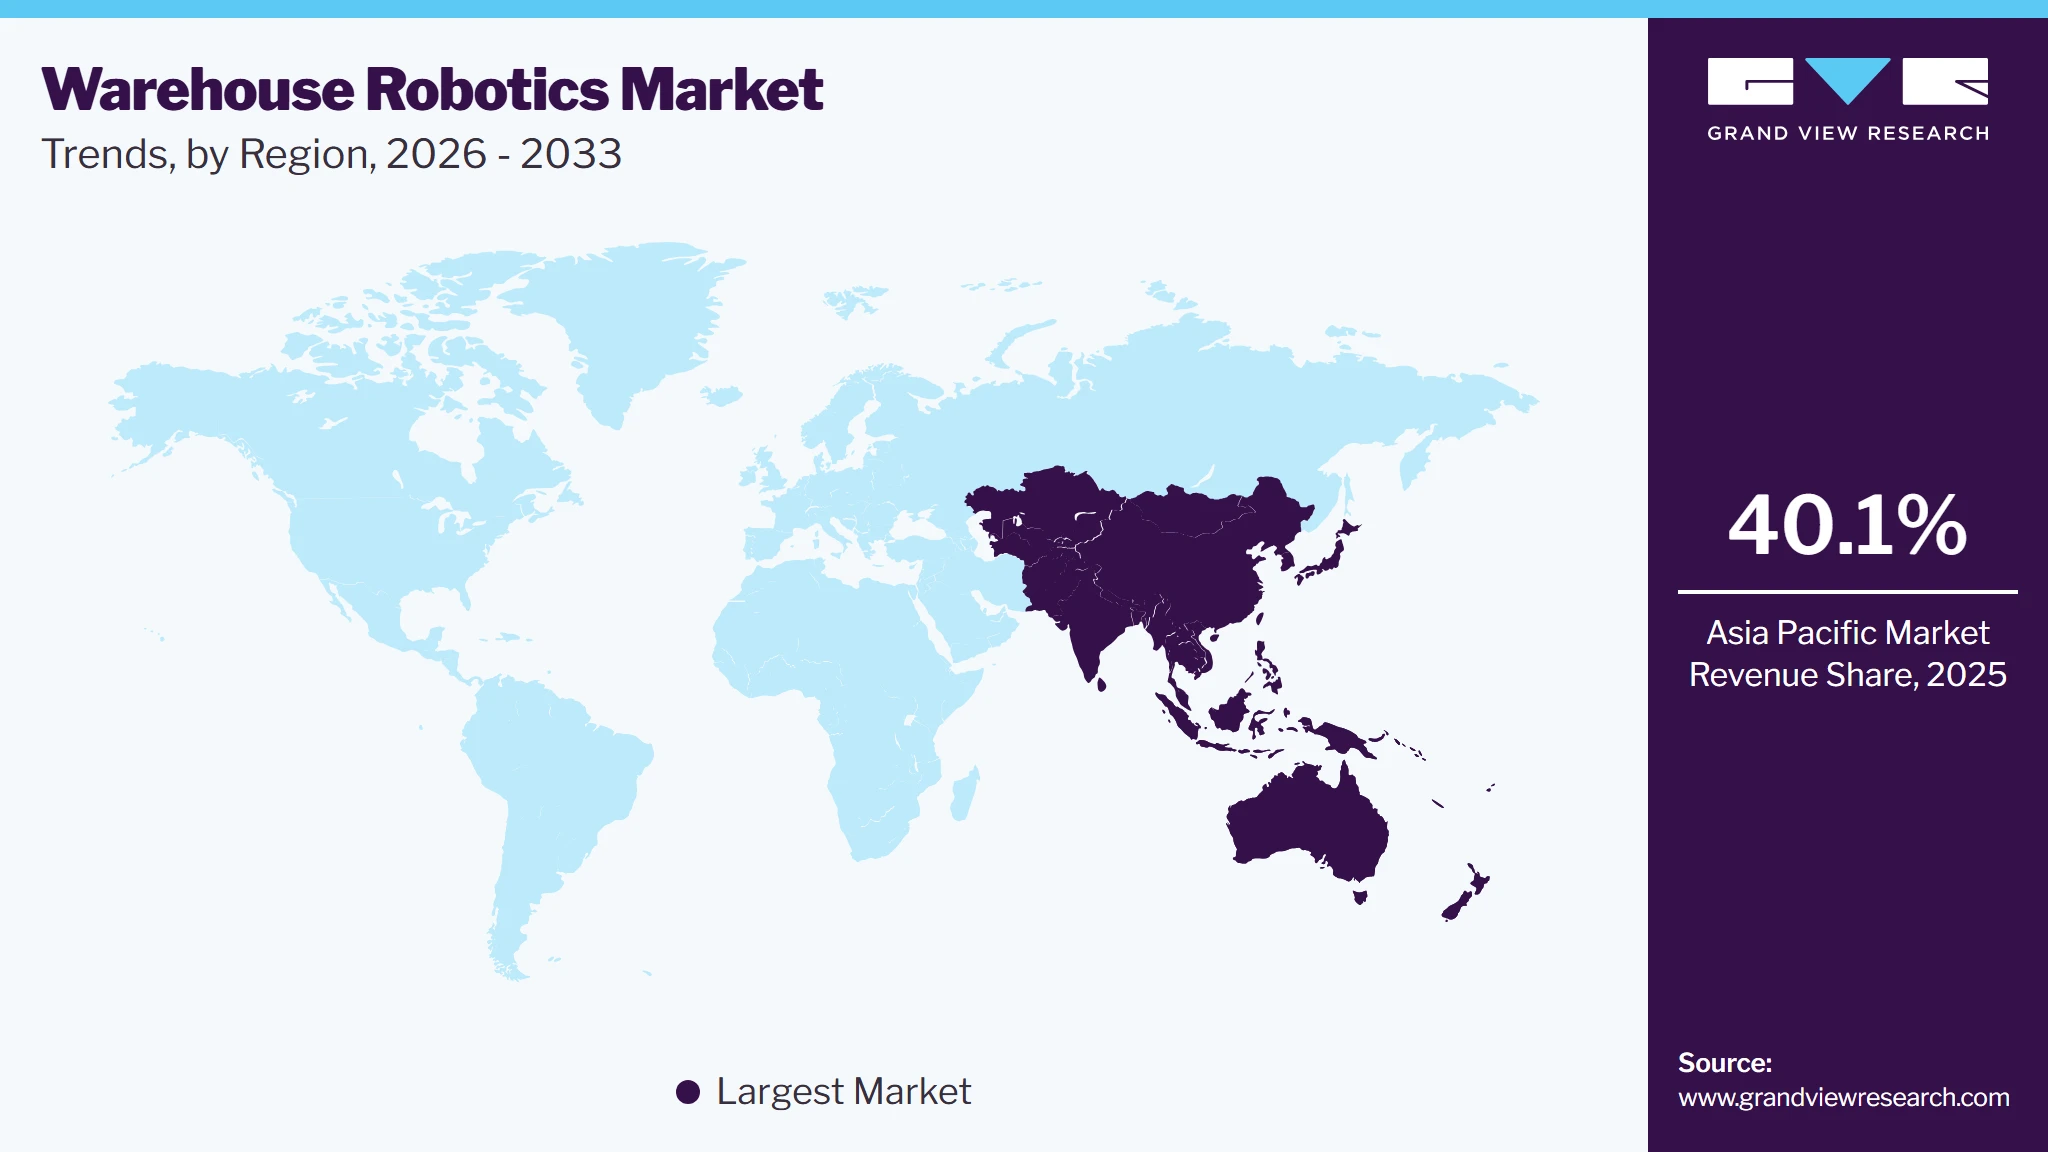
Asia-Pacific dominated the warehouse robotics market, accounting for the largest revenue share of 40.1% in 2025. The increasing installation of warehouse robotics in the region, coupled with the presence of key market players such as Fanuc Corporation, Yaskawa Electric Corporation, Singapore Technologies Engineering Ltd., TOSHIBA CORP., and many others has driven growth of the market. In addition, continuous rise of the retail, manufacturing, and FMCG industries in the region is expected to create lucrative growth opportunities for the market.
 To learn more about this report, Download Free Sample Report
China Warehouse Robotics Market Trends
The warehouse robotics market in the China held the largest share in the Asia Pacific region in 2025.
Latin America Warehouse Robotics Market Trends
The Latin America region is expected to witness the highest CAGR from 2023 to 2030. The region offers lucrative growth opportunities owing to a significant rise in the e-commerce industry. The key players focus on entering a region to add value to the market. For instance, in July 2022, Geek+, the autonomous mobile robot (AMR) technology company, announced a collaboration with Körber Supply Chain to expand into Latin America. The rising research and development investments are expected to create lucrative growth prospects for the market.
Key Players & Market Share Insights
The major players in the market focus on developing innovative collaboration software to attract a more extensive customer base and gain a competitive edge. For instance, in February 2023, Honeywell International Inc. announced the opening of its new research and development facility to advance its technology which helped the warehouse and logistics companies all over Europe. The increasing number of such developments is expected to favor the growth of the market over the forecast period.
Key Warehouse Robotics Companies:
The following key companies have been profiled for this study on the warehouse robotics market.
-
ABB Group
-
Bastian Solutions LLC
-
Daifuku Co. Ltd.
-
Dematic
-
Fetch Robotics Inc.
-
Honeywell International Inc
-
KNAPP AG
-
KUKA AG
-
OMRON Corporation
-
YASKAWA Electric Corporation
-
FANUC Corporation
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players rs (ABB, Daifuku Co. Ltd., Dematic, Honeywell International Inc., KUKA AG, OMRON Corporation, YASKAWA Electric Corporation, FANUC Corporation)
- Focus on delivering end-to-end warehouse automation solutions, including autonomous mobile robots (AMRs), automated guided vehicles (AGVs), robotic picking systems, palletizing robots, automated storage and retrieval systems (AS/RS), warehouse execution software, and system integration services.
- Strong emphasis on Industry 4.0, AI-enabled robotics, Robot-as-a-Service (RaaS), cloud-based fleet management, and long-term service contracts for logistics, retail, manufacturing, and e-commerce customers.
- Strong global presence, extensive product portfolios, advanced robotics and AI capabilities, comprehensive warehouse automation expertise, established customer base, and large-scale manufacturing capabilities.
- Strong R&D investments and extensive partner and system integrator networks.
- High capital investment requirements for customers, lengthy deployment and integration timelines, dependence on large enterprise contracts, complex system customization requirements, and relatively slower innovation cycles due to large organizational structures.
Emerging & Specialized Players (Bastian Solutions LLC, Fetch Robotics Inc.)
- Focus on specialized warehouse automation solutions, including autonomous mobile robots (AMRs), collaborative mobile robots, robotic goods-to-person systems, flexible warehouse automation, AI-driven fleet management, and customized robotic solutions for SMEs and rapidly expanding e-commerce warehouses.
- Emphasis on modular deployments, faster implementation, cloud-native software, and Robotics-as-a-Service (RaaS) business models.
- High flexibility, rapid deployment capabilities, strong expertise in AMRs and collaborative robotics, agile product development, AI-based optimization, and lower deployment complexity.
- Ability to provide scalable automation solutions for dynamic warehouse environments.
- Limited global footprint, smaller product portfolios, lower manufacturing scale, and constrained financial resources for large R&D investments.
- High dependence on partnerships for full warehouse automation projects, and stronger competition from established automation companies offering integrated end-to-end solutions.
Warehouse Robotics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 7.5 billion
Estimated market size in 2026
USD 8.6 billion
Projected market size by 2033
USD 24.2 billion
Growth rate
CAGR of 15.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, function, payload capacity, component, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; China; India; Japan; South Korea; Australia, Brazil; South Africa; Saudi Arabia, UAE
Key companies profiled
ABB Group; Bastian Solutions LLC; Daifuku Co. Ltd.; Dematic; Fetch Robotics Inc.; Honeywell International Inc.; KNAPP AG; KUKA AG; OMRON Corporation; YASKAWA Electric Corporation; FANUC Corporation
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Warehouse Robotics Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global warehouse robotics market report based on product, function, payload capacity, component, software, application, and region:
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Mobile Robots
-
Articulated Robots
-
Cylindrical Robots
-
Scara Robots
-
Parallel Robots
-
Cartesian Robots
-
-
Function Outlook (Revenue, USD Million, 2021 - 2033)
-
Pick & Place
-
Palletizing & De-palletizing
-
Transportation
-
Packaging
-
-
Payload Capacity Outlook (Revenue, USD Million, 2021 - 2033)
-
Below 10 kg
-
11 kg to 80 kg
-
81 kg to 400 kg
-
401 kg to 900 kg
-
Above 900 kg
-
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Hardware
-
Software
-
-
Software Outlook (Revenue, USD Million, 2021 - 2033)
-
Warehouse Management System
-
Warehouse Control System
-
Warehouse Execution System
-
-
Application Capacity Outlook (Revenue, USD Million, 2021 - 2033)
-
E-commerce
-
Automotive
-
Consumer Electronics
-
Food & Beverage
-
Healthcare
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia
-
South Korea
-
Singapore
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East & Africa
-
Research Methodology
The warehouse robotics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each warehouse robotics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Product
Revenue capture definition
Mobile Robots
Revenue is generated through the sale and deployment of autonomous mobile robots (AMRs), automated guided vehicles (AGVs), autonomous forklifts, and mobile robotic platforms used for warehouse material movement.
Articulated Robots
Revenue is generated through the sale and integration of articulated robotic arms used for picking, palletizing, packaging, sorting, and material handling in warehouses.
Cylindrical Robots
Revenue is generated through the sale of cylindrical-coordinate robotic systems used for vertical handling, loading, unloading, and repetitive warehouse operations.
SCARA Robots
Revenue is generated through the sale of SCARA (Selective Compliance Assembly Robot Arm) robots used for high-speed pick-and-place, sorting, packaging, and assembly operations in warehouses.
Parallel Robots
Revenue is generated through the sale of parallel (delta) robots used for ultra-fast picking, sorting, packaging, and lightweight material handling applications.
Cartesian Robots
Revenue is generated through the sale of gantry and Cartesian robotic systems used for palletizing, depalletizing, storage, retrieval, and linear material handling applications.
Segment - Function
Revenue capture definition
Pick & Place
Revenue is captured from robotic systems designed for automated picking, sorting, order fulfillment, and placement of products within warehouse operations.
Palletizing & De-palletizing
Revenue is captured from robotic solutions used for stacking, unstacking, pallet loading, pallet unloading, and bulk material handling.
Transportation
Revenue is captured from robotic systems that automate the movement of goods, pallets, totes, and inventory between warehouse locations.
Packaging
Revenue is captured from robotic solutions used for automated packaging, case packing, wrapping, labeling, sealing, and shipment preparation.
Segment - Payload Capacity
Revenue capture definition
Below 10 kg
Revenue is generated through warehouse robots designed to handle lightweight items weighing less than 10 kg.
11 kg to 80 kg
Revenue is generated through robotic systems capable of handling medium-weight products ranging from 11 kg to 80 kg.
81 kg to 400 kg
Revenue is generated through warehouse robots used for handling heavy cartons, pallets, components, and industrial materials weighing between 81 kg and 400 kg.
401 kg to 900 kg
Revenue is generated through robotic material handling systems designed for transporting and palletizing loads between 401 kg and 900 kg.
Above 900 kg
Revenue is generated through heavy-duty warehouse robotic systems capable of moving oversized pallets, containers, machinery, and loads exceeding 900 kg.
Segment - Component
Revenue capture definition
Hardware
Revenue is generated through the sale of robotic arms, mobile robots, controllers, sensors, actuators, grippers, vision systems, safety equipment, batteries, and other physical robotic components.
Software
Revenue is generated through software licenses, subscriptions, AI algorithms, fleet management platforms, robot control software, analytics solutions, and system integration software for warehouse robotics.
Segment - Application
Revenue capture definition
E-commerce
Revenue is captured from warehouse robotic solutions deployed in e-commerce fulfillment centers for order picking, sorting, packing, inventory movement, and shipment preparation.
Automotive
Revenue is generated from robotic warehouse solutions used to handle automotive parts, manage inventory, sequence, palletize, and support component logistics.
Consumer Electronics
Revenue is captured from warehouse robotics deployed for handling, sorting, packaging, storage, and distribution of consumer electronic products and components.
Food & Beverage
Revenue is captured from warehouse robotic systems used for food handling, cold storage logistics, packaging, palletizing, and inventory movement in food and beverage facilities.
Healthcare
Revenue is captured from warehouse robotic solutions used for pharmaceutical distribution, medical device logistics, hospital inventory management, and healthcare supply chain automation.
Others
Revenue is captured from warehouse robotics deployed across industries, including retail, third-party logistics (3PL), chemicals, aerospace, textiles, paper, and other industrial and commercial warehousing applications.
Estimation Model
Layer Name
Key Question
Description
Warehouse Operations & End-User Demand Layer
Who generates demand for warehouse robotics?
Represents demand generated by e-commerce companies, third-party logistics (3PL) providers, retail distribution centers, manufacturers, food & beverage companies, pharmaceutical firms, consumer electronics companies, and other warehouse operators.
Robotics Technology & Automation Layer
What technologies enable warehouse robotics?
Includes core automation technologies such as autonomous mobile robots (AMRs), automated guided vehicles (AGVs), robotic arms, machine vision systems, AI and machine learning, LiDAR, sensors, SLAM navigation, robotic grippers, edge computing, IoT connectivity, cloud robotics, digital twins, and real-time fleet management systems that enable autonomous warehouse operations.
Software, Integration & Warehouse Execution Layer
How are warehouse robotics solutions deployed and managed?
Covers warehouse software platforms and integration systems, including Warehouse Management Systems (WMS), Warehouse Control Systems (WCS), Warehouse Execution Systems (WES), fleet management software, robot orchestration platforms, warehouse analytics solutions, API-based integration platforms, ERP integration, system integration services, and deployment solutions that enable seamless coordination between robots, warehouse equipment, and enterprise systems.
Revenue Generation & Monetization Layer
How is revenue generated in the warehouse robotics market?
Revenue is generated through the sale of warehouse robots (AMRs, AGVs, robotic arms, palletizing robots), robotics hardware and peripherals, software licensing and SaaS subscriptions for fleet management and warehouse execution platforms, implementation and system integration services, robot-as-a-service (RaaS) subscriptions, maintenance and support contracts, spare parts, upgrades, training services, and long-term managed automation solutions for warehouse operators.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Market Sizing, Competitive Landscape & Growth Opportunity Assessment
Assessed the global warehouse robotics market size, historical and forecast growth trends, and detailed segmentation by product (mobile robots, articulated robots, SCARA robots, cartesian robots, cylindrical robots, parallel robots), function (pick & place, palletizing & de-palletizing, transportation, packaging), payload capacity, component (hardware, software), software (WMS, WCS, WES), and application (e-commerce, automotive, consumer electronics, food & beverage, healthcare, others).
Supports market entry and expansion strategies, identifies high-growth automation opportunities across warehouse operations, improves investment prioritization in robotics technologies, and enables data-driven product portfolio development and warehouse automation planning.
Competitive Benchmarking & Strategic Positioning Analysis
Benchmarked leading warehouse robotics providers based on product portfolio, robotics technologies (AMRs, AGVs, robotic arms, AS/RS), AI and fleet management capabilities, warehouse software integration (WMS/WCS/WES), geographic presence, strategic partnerships, acquisitions, R&D investments, and service capabilities.
Supports competitive differentiation, identifies technology and product portfolio gaps, strengthens strategic positioning, improves partnership and acquisition planning, and enables long-term competitive advantage in warehouse automation and intelligent logistics solutions.
Regional Market Demand & Consumer Engagement Analysis
Analyzed regional demand across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa by evaluating e-commerce growth, warehouse construction, labor availability, manufacturing expansion, logistics infrastructure, Industry 4.0 adoption, automation investments, and government initiatives supporting smart manufacturing and supply chain modernization.
Supports geographic expansion planning, identifies high-growth regional markets for warehouse automation, improves localization of robotics solutions, enables region-specific investment and partnership strategies, and strengthens long-term growth planning across logistics, manufacturing, and retail supply chains.
Frequently Asked Questions About This Report
Asia Pacific dominated the global market, accounting for the largest revenue share of 40.1% in 2025.
Some key players operating in the warehouse robotics market include ABB, Honeywell International Inc., KUKA AG, OMRON Corporation, and YASKAWA ELECTRIC CORPORATION.
Growth of the global retail and e-commerce industry along with the increased demand for automation due to awareness on safety and superior quality production is fueling the market growth.
The mobile robots segment accounted for the largest market share of 30.3% in 2025
The pick & place segment led the market with a share of 36.8% in 2025.
The below 10 kg segment dominated the market, with a share of 32.2% in 2025.
The software segment dominated the market with a share of 47.4% in 2025.
The global warehouse robotics market size was estimated at USD 7.5 billion in 2025 and is expected to reach USD 8.6 billion in 2025.
The global warehouse robotics market is expected to grow at a compound annual growth rate of 15.9% from 2026 to 2033 to reach USD 24.2 billion by 2033.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


