
- Home
- »
- Paints, Coatings & Printing Inks
- »
-
3D Printing Metal Market Size & Share Report, 2026-2033GVR Report cover

3D Printing Metal Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Titanium, Nickel, Stainless Steel, Aluminum), By Form (Powder, Filament), By Application, By Region, And Segment Forecasts
Market Size, 2025
$1.4BMarket Estimate, 2026
$1.7BMarket Forecast, 2033
$4.0BCAGR, 2026–2033
13.2%3D Printing Metal Market Summary
The global 3D printing metal market size was valued at USD 1.4 billion in 2025 and is projected to grow from USD 1.7 billion in 2026 to USD 4.0 billion by 2033, at a CAGR of 13.2% from 2026 to 2033. Europe dominated the market, accounting for a revenue share of 35.0% in 2025. The growth is mainly due to continuous innovations in 3D printing technologies and the rising integration of digital manufacturing processes.
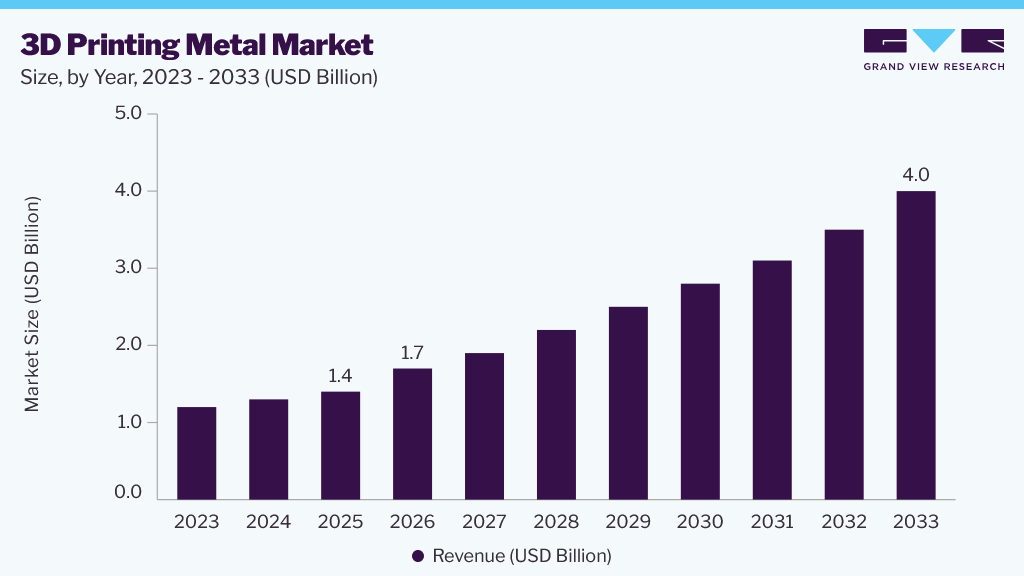 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Titanium segment held the largest market share of around 30.0% in 2025.
- By form: Powder segment led the market with a share of around 85.0% in 2025
- By application: Aerospace and defense segment held the largest market share of over 35.0% in 2025
Regional Highlights
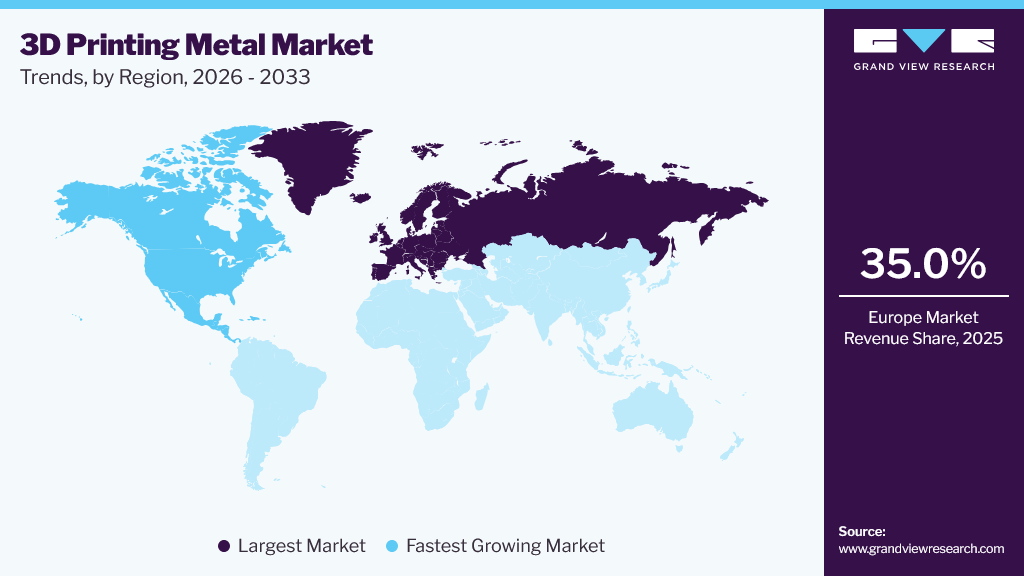
- Largest regional market: Europe (35.0% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 1.4 Billion
- Estimated market size in 2026: USD 1.7 Billion
- Projected market size by 2033: USD 4.0 Billion
- CAGR (2026-2033): 13.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Advancements such as improved print speeds, higher resolution, and the development of new metal alloys enhance the quality and functionality of printed parts. In addition, the seamless integration of 3D printing with digital manufacturing tools enables more efficient design, prototyping, and production, reducing costs and lead times. These innovations make metal 3D printing more accessible and practical, fueling widespread adoption across various industries and expanding market size.Moreover, the shift toward sustainability and the development of high-quality metal alloys are anticipated to accelerate the market expansion. As industries strive for more efficient, eco-friendly production processes, 3D printing offers reduced material waste, energy savings, and the ability to recycle metal powders. The development of advanced, high-performance alloys enhances the capabilities of metal 3D printing, enabling the production of stronger, more durable components. This combination of sustainability and innovation in material science is poised to expand the market across industries.
Analyst Perspective
The 3D-printed metal market is growing as manufacturers adopt additive manufacturing for complex, lightweight, high-performance components. Applications span aerospace, automotive, healthcare, defense, and industry, offering design flexibility, material efficiency, and shorter production cycles. Demand for customization and rapid prototyping, alongside advances in powder bed fusion, directed energy deposition, and binder jetting, is accelerating adoption. Companies with broad material portfolios, advanced technologies, and strong industrial partnerships are well positioned. Future growth depends on lower costs, better materials and reliability, and wider use of metal additive manufacturing for end-use production.
Product Insights
The titanium segment captured the largest share at around 30.0% in 2025, driven by its unique combination of strength, lightweight properties, and high corrosion resistance. These attributes make it ideal for various industries where durability and precision are critical. Titanium’s ability to withstand extreme temperatures and its biocompatibility further enhance its appeal for high-performance applications, especially in the creation of custom implants and components. As demand for advanced manufacturing solutions grows, titanium's versatility continues to drive its dominance in the 3D printing sector. Titanium’s performance advantages continue to support its adoption across demanding metal additive manufacturing applications. For instance, in November 2025, Renishaw highlighted titanium alloys for additive manufacturing in aerospace and medical applications. The company cited strength-to-weight ratio, corrosion resistance, and biocompatibility.
The stainless steel segment is expected to grow at the fastest CAGR over the forecast period, driven by its excellent mechanical properties, corrosion resistance, and versatility across various industries. Its widespread application in the aerospace, automotive, healthcare, and manufacturing sectors drives demand for stainless steel-based 3D-printed parts. As the technology evolves, stainless steel offers cost-effective, high-performance solutions for producing complex geometries, reducing material waste, and accelerating production times.
Form Insights
The powder segment held the largest share at over 85.0% in 2025, owing to its superior compatibility with various additive manufacturing techniques, such as Selective Laser Sintering (SLS) and Direct Metal Laser Sintering (DMLS). Metal powders offer high precision, excellent material properties, and the ability to create intricate, lightweight structures. In addition, the availability of a wide range of metal powders, including titanium, aluminum, and stainless steel, enables diverse industrial applications, driving growth. The cost-effectiveness and flexibility of metal powders further enhance their prominence in this rapidly evolving market. Expanding availability of metal powders is supporting broader adoption across diverse additive manufacturing applications. For instance, in April 2025, Renishaw partnered with Metalpine to develop copper-nickel powders for additive manufacturing. The initiative expands the use of powder-based materials for durable marine components.
The filament segment is expected to grow at the fastest CAGR over the forecast period, driven by its ease of use, cost-effectiveness, and rapid production capabilities. Filaments are increasingly favored for compatibility with a wide range of 3D printers, offering a simpler alternative to powder-based methods. As technology advances, more metal filaments with improved properties, such as stainless steel, copper, and titanium, are becoming available. This growing material diversity, along with increased accessibility and affordability, is driving substantial demand across industries.
Application Insights
The aerospace and defense segment held the largest share at over 35.0% in 2025, driven by the need for lightweight, durable, high-performance components. 3D printing enables the creation of complex, customized parts with reduced material waste, making it ideal for applications such as aircraft engines, structural elements, and defense systems. The ability to rapidly prototype and produce low-volume, high-quality parts at reduced costs further drives adoption in this sector. Moreover, advancements in metal 3D printing technologies continue to enhance performance, fueling further market expansion in aerospace and defense. Aerospace and defense manufacturers are advancing metal additive manufacturing for complex, high-performance components. For instance, in April 2026, Lockheed Martin advanced laser powder-bed fusion for aerospace and defense systems. The technology enables the production of precise, complex metal components with shorter development cycles.
The medical and dental segment is anticipated to expand at the fastest CAGR over the forecast period, driven by surging demand for personalized and complex medical implants, prosthetics, and dental devices. 3D printing enables the production of highly customized solutions that perfectly fit individual patient needs, improving treatment outcomes. Moreover, advancements in biocompatible metal alloys and the rising adoption of additive manufacturing technologies in healthcare are propelling growth. The ability to streamline production and reduce lead times further enhances the appeal of 3D printing in the medical and dental industries.
Regional Insights
Europe 3D printing metal market secured the largest revenue share of around 35.0% in 2025, fueled by its strong industrial base, advanced technological infrastructure, and sizable investments in research and development. The robust aerospace, automotive, and healthcare industries in the region have driven demand for metal 3D printing, with countries including Germany, the UK, and France leading in innovation and manufacturing. Europe’s focus on sustainable production and rapid prototyping, coupled with a rising emphasis on digital manufacturing, has further bolstered the adoption of 3D printing technologies, solidifying its dominant position in the market.
 To learn more about this report, Download Free Sample Report
North America 3D Printing Metal Market Trends
3D printing metal market in North America is witnessing at the fastest CAGR over the forecast period, driven by the adoption of 3D printing for end-use production and growth in healthcare applications. The aerospace and automotive industries are increasingly using 3D printing to manufacture functional parts, enabling greater customization and design flexibility. Besides, the healthcare sector benefits from metal 3D printing for custom implants, prosthetics, and surgical tools, offering personalized solutions that improve patient outcomes. These trends expand the range of applications and contribute to the surging demand for advanced metal 3D printing technologies across the region.
U.S. 3D Printing Metal Market Trends
3D printing metal market in the U.S. held a considerable position in 2025, spurred by the increased focus on sustainability and the integration of automation and AI. 3D printing reduces material waste compared to traditional manufacturing, contributing to more sustainable production processes. Moreover, automation and AI enhance precision, optimize designs, and improve production efficiency, lowering costs and boosting productivity. These advancements enable industries to produce high-quality, complex parts more efficiently, making 3D printing an attractive option for large-scale, eco-friendly manufacturing, fueling market expansion.
3D printing metal market in Canada is projected to achieve a significant CAGR over the forecast period, owing to reduced material waste through 3D printing. This technology enables precise material use, minimizing waste and promoting sustainability, appealing to environmentally conscious manufacturers. In addition, ongoing regulatory and standardization developments are boosting confidence in the industry. As Canada strengthens its framework for 3D-printed metal parts, particularly in the aerospace, healthcare, and automotive sectors, it helps ensure safety, quality, and consistency. These advancements encourage more companies to adopt metal 3D printing, further expanding the market's size and potential.
Asia Pacific 3D Printing Metal Market Trends
3D printing metal market in Asia Pacific is projected to grow at a significant CAGR over the forecast period, spurred by the emergence of local 3D printing service providers and advancements in manufacturing innovation and customization. Local service providers are making metal 3D printing more accessible to various industries, reducing costs and lead times. Besides, the increasing demand for highly customized and complex parts, especially in aerospace, automotive, and healthcare, is fueling innovation in 3D printing technologies. These factors expand the market as industries embrace cost-effective, tailored solutions for end-use production.
3D printing metal market in China is driven by sustainability and waste reduction initiatives and the increasing use of 3D printing for prototyping and low-volume production. 3D printing reduces material waste compared to traditional manufacturing methods, aligning with China's environmental goals and fostering sustainable production practices. The demand for rapid prototyping and cost-effective low-volume production in the aerospace, automotive, and healthcare industries is also surging. This trend enables manufacturers to produce complex parts efficiently and at a lower cost, contributing to the growing adoption of metal 3D printing technologies in China.
3D printing metal market in India is poised to emerge as the fastest-growing country over the forecast period in APAC, due to its rapidly expanding industrial base and increasing adoption of advanced manufacturing technologies. The country’s strong focus on the aerospace, automotive, and healthcare sectors, and a growing startup ecosystem, drives demand for 3D-printed metal components. In addition, government initiatives promoting innovation and digital manufacturing are encouraging investment in 3D printing technologies. As India’s manufacturing capabilities and technological infrastructure continue to improve, the metal 3D printing market is expected to experience notable growth.
Key 3D Printing Metal Market Company Insights
Some of the key companies in the 3D printing metal market include ATI, CNPC Powders, Colibrium Additive (GE Aerospace), CRS Holdings, LLC, GKN Powder Metallurgy, Höganäs AB, INDO-MIM, Kennametal Inc, Materialise NV, OC Oerlikon Management AG, Outokumpu, POLEMA, Powder Alloy Corporation, Rio Tinto Metal Powder, Sandvik, and others.
- Powder Alloy Corporation specializes in producing high-quality metal powders for 3D printing and additive manufacturing. It offers a range of alloys used in industries such as aerospace, automotive, and medical.
- Sandvik provides advanced metal powders and additive manufacturing solutions, focusing on delivering high-performance materials and innovative technologies to enhance the efficiency and precision of 3D printing processes.
Key 3D Printing Metal Companies
The following key companies have been profiled for this study on the 3D printing metal market:
-
ATI
-
CNPC Powders
-
Colibrium Additive (GE Aerospace)
-
CRS Holdings, LLC.
-
GKN Powder Metallurgy
-
Höganäs AB
-
INDO-MIM
-
Kennametal Inc.
-
Materialise NV
-
OC Oerlikon Management AG
-
Outokumpu
-
POLEMA
-
Powder Alloy Corporation
-
Rio Tinto Metal Powder
-
Sandvik
Recent Developments
-
In November 2024, 3D Monotech launched the Markforged FX10 in India, a metal and composite 3D printing system designed to expand access to advanced additive manufacturing for industrial applications.
-
In January 2024, Eplus3D introduced the EP-M2050, a large-format laser powder bed fusion 3D printer equipped with up to 64 lasers, enhancing productivity and precision for large-scale metal additive manufacturing applications.
3D Printing Metal Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.4 billion
Estimated market size in 2026
USD 1.7 billion
Projected market size by 2033
USD 4.0 billion
Growth rate
CAGR of 13.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in Tons; Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, form, application, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; Japan; India; Singapore; South Korea; Brazil
Key companies profiled
ATI; CNPC Powders; Colibrium Additive (GE Aerospace); CRS Holdings, LLC; GKN Powder Metallurgy; Höganäs AB; INDO-MIM; Kennametal Inc.; Materialise NV; OC Oerlikon Management AG; Outokumpu; POLEMA; Powder Alloy Corporation; Rio Tinto Metal Powder; Sandvik
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global 3D printing metal Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global 3D printing metal market report based on product, form, application, and region:
- Product Outlook (Volume, Tons; Revenue, USD Billion, 2021 - 2033)
- Titanium
- Nickel
- Stainless Steel
- Aluminum
- Others
- Form Outlook (Volume, Tons; Revenue, USD Billion, 2021 - 2033)
- Powder
- Filament
- Application Outlook (Volume, Tons; Revenue, USD Billion, 2021 - 2033)
- Aerospace & Defense
- Automotive
- Medical & Dental
- Others
- Regional Outlook (Volume, Tons; Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Asia Pacific
- China
- India
- Japan
- Singapore
- South Korea
- Latin America
- Brazil
- Middle East & Africa
- North America
Frequently Asked Questions About This Report
The global 3D printing metal market size was valued at USD 1.4 billion in 2025 and is estimated at USD 1.7 billion in 2026.
The global 3D printing metal market is expected to grow at a CAGR of 13.2% from 2026 to 2033, reaching USD 4.0 billion.
The Europe region dominated the global 3D printing metal market with an approximately 35.0% revenue share in 2025.
Key players in the market include ATI, CNPC Powders, Colibrium Additive (GE Aerospace), CRS Holdings, LLC, GKN Powder Metallurgy, Höganäs AB, INDO-MIM, Kennametal Inc, Materialise NV, OC Oerlikon Management AG, Outokumpu, POLEMA, Powder Alloy Corporation, Rio Tinto Metal Powder, and Sandvik, among others.
The titanium segment accounted for the largest revenue share in 2025, at around 30.0%.
About the Author(s)
Paints, Coatings & Printing Inks Research Team
Bulk Chemicals · Paints, Coatings & Printing InksThis report was authored by the paints, coatings & printing inks research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the paints, coatings & printing inks segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


