
- Home
- »
- Communications Infrastructure
- »
-
5G Radio Access Network Market Size Report, 2026-2033GVR Report cover

5G Radio Access Network Market (2026 - 2033)
Size, Share & Trends Analysis Report By Component (Hardware, Software, Services), By Architecture Type, By Deployment (Indoor,Outdoor), By End-use, By Region, And Segment Forecasts
Market Size, 2025
$42.5BMarket Estimate, 2026
$52.6BMarket Forecast, 2033
$135.8BCAGR, 2026–2033
14.5%5G Radio Access Network Market Summary
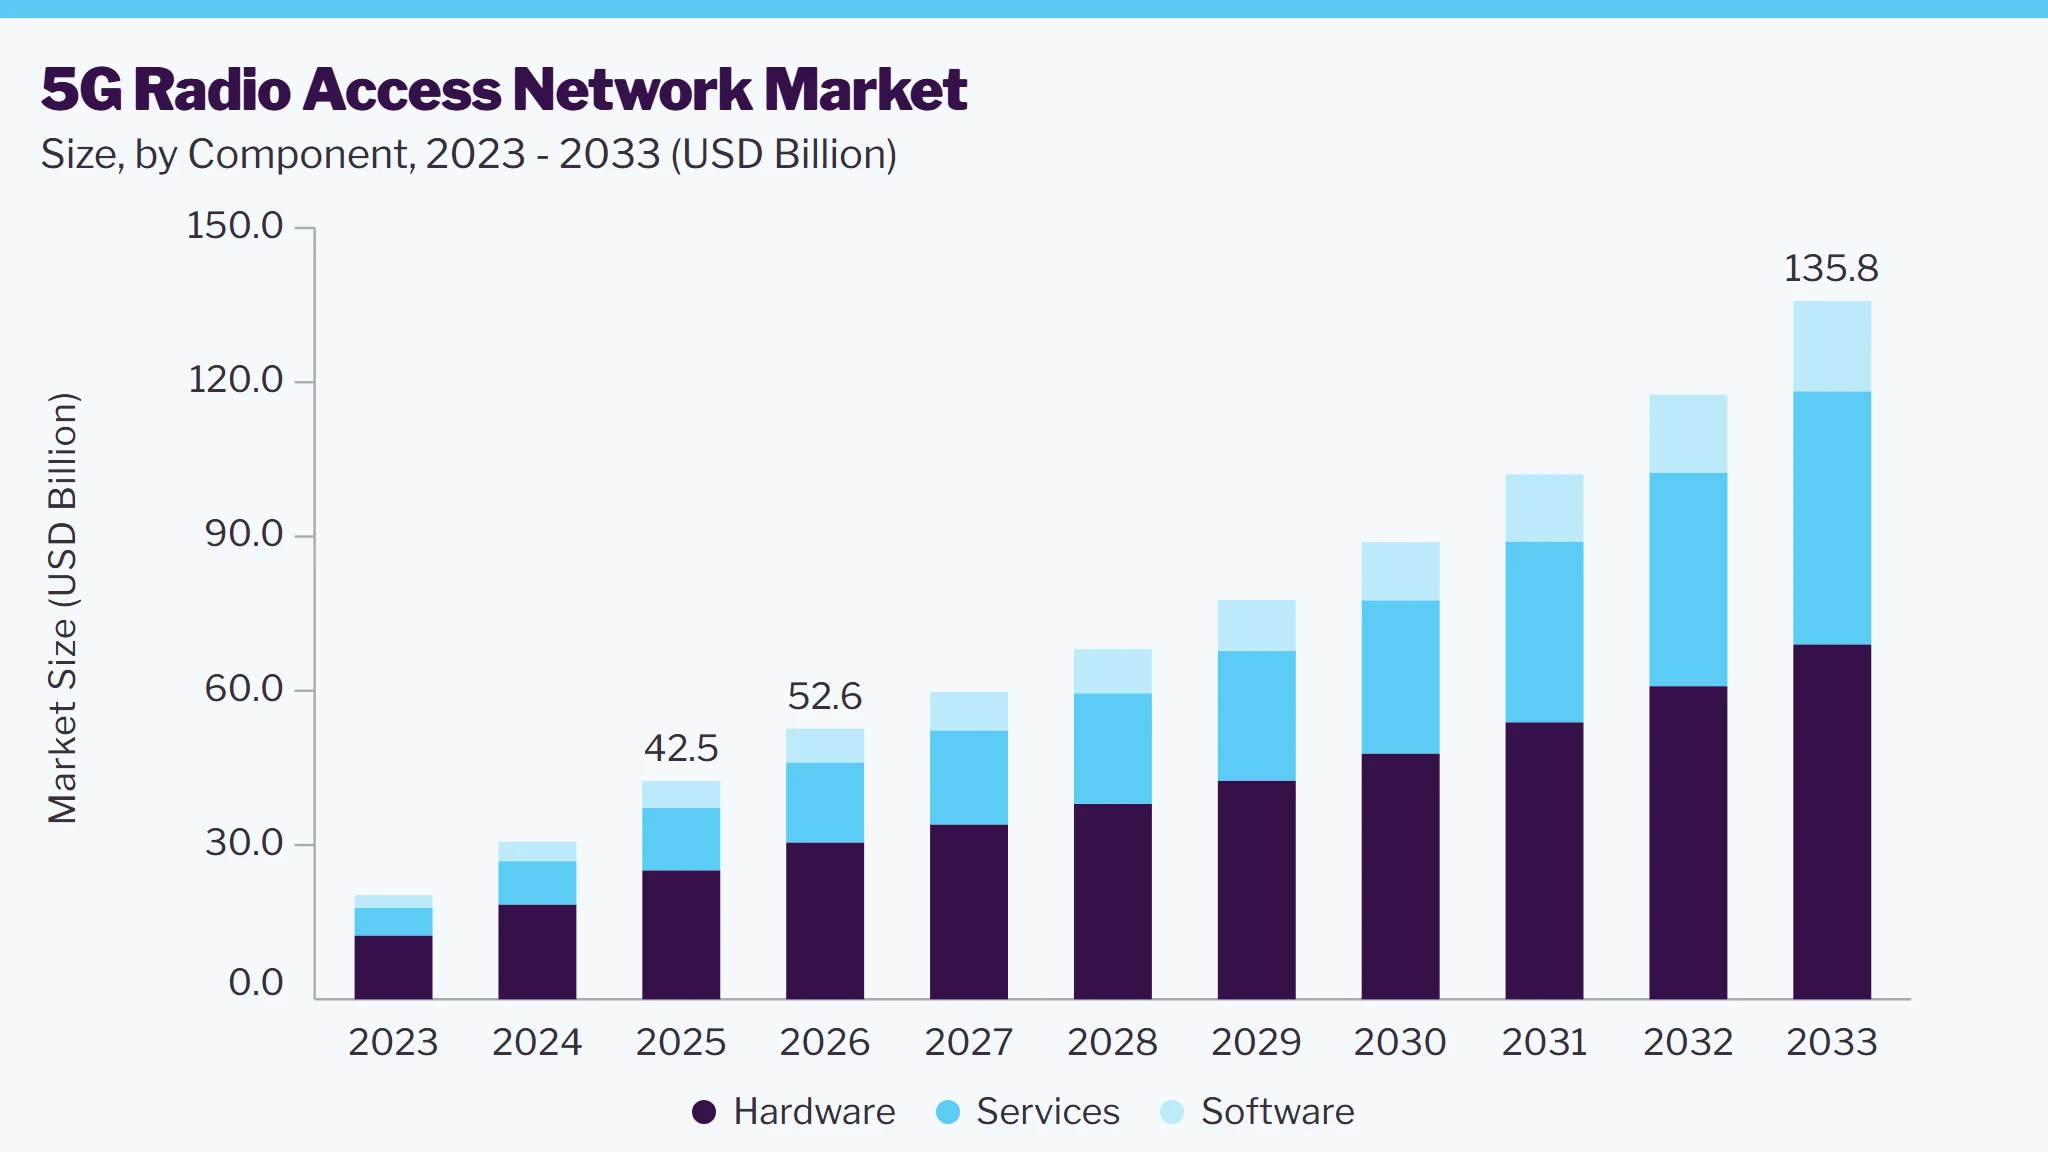
The global 5G radio access network market size was valued at USD 42.5 billion in 2025 and is projected to grow from USD 52.6 billion in 2026 to USD 135.8 billion by 2033, at a CAGR of 14.5% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 41.9% in 2025. The increasing demand for low-latency, high-bandwidth connectivity and the growing focus on research and development activities by key organizations are among the factors fueling market growth.
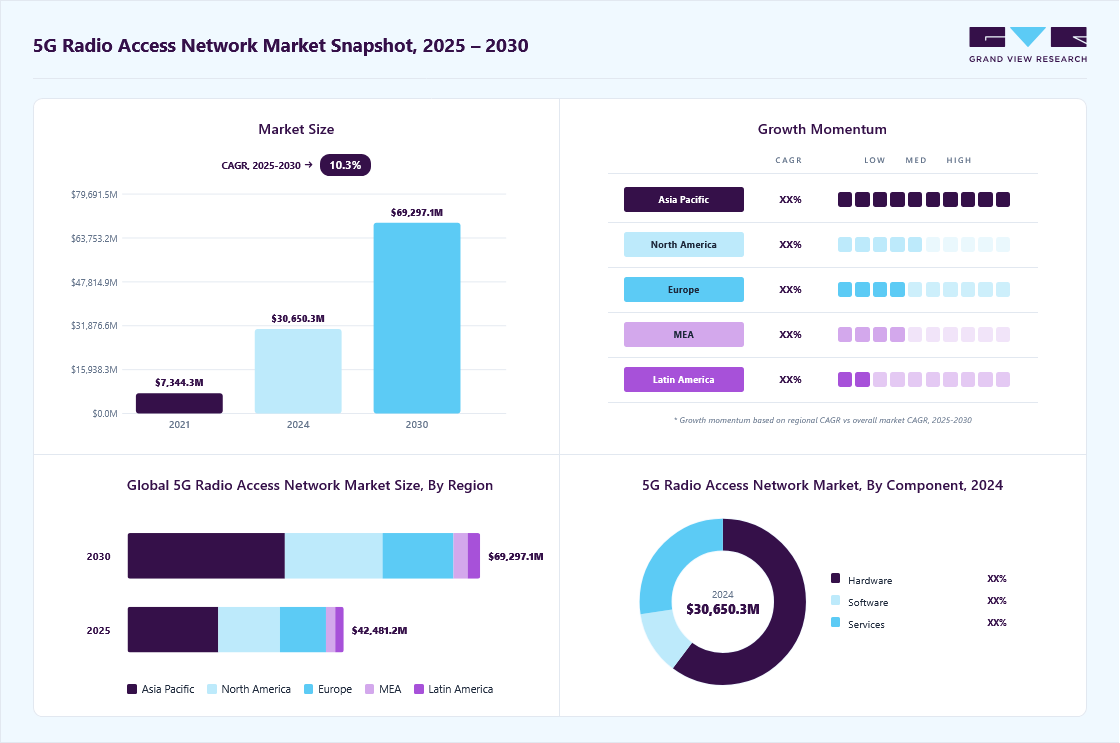 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By component: Hardware segment dominated the market, accounting for a revenue share of 59.0% in 2025.
- By architecture type: VRAN segment held the largest market share of 38.7% in 2025.
- By deployment: Outdoor segment accounted for the largest revenue share in 2025.
- By end-use: Telecom operators segment accounted for the largest revenue share in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (41.9% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 42.5 Billion
- Estimated market size in 2026: USD 52.6 Billion
- Projected market size by 2033: USD 135.8 Billion
- CAGR (2026-2033): 14.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Moreover, the robust deployment of a 5G radio access network (RAN) with several small cells and macrocell base stations worldwide is propelling the growth of the market. The trend of deploying centralized RAN and virtual RAN (VRAN) is rapidly increasing among mobile network operators (MNOs) and network service providers to reduce overall infrastructure costs and network complexities. Furthermore, the RAN enables enterprises and mobile network operators utilizing private 4G or private 5G to offer network slicing solutions assigning capacities to individual enterprises to split network usage within a public mobile network. The industry is expanding at a tremendous growth rate owing to technological innovations coupled with users’ inclination towards 5G RAN solutions.Radio access networks comprise wireless telecommunications systems, including antennas and base stations, to provide high performing 5G network solutions. It utilizes 5G radio frequency division duplex (FDD) frequencies to connect individual devices through radio connections providing wireless connectivity. RAN encompasses different types, viz. evolved universal terrestrial RAN (E-UTRAN), Universal Radio Access Network (UTRAN), Virtualized Radio Access Network (VRAN), and Open Radio Access Network (ORAN), among others. The RAN base stations within a public mobile network are connected to a public mobile core network through microwave or fiber cables to aggregate signals. The latest RANs offer controllers utilizing software-defined networks (SDN), allowing them to control cellular device capacity and coverage.
 To learn more about this report, Download Free Sample Report
This high market size is attributable to the growing deployment of private 5G Radio Access Network and core equipment across several use cases. These use cases include smart cities, remote surgeries, enterprises, wireless cameras, industrial robotics, and autonomous vehicles. Rapidly evolving RAN technologies have enabled several key telecom operators and end-use customers to deploy the virtualized network in order to diminish overall operating expenses. Also, several market players such as Qualcomm Technologies, Inc., Nokia, Verizon, and Cisco Systems, Inc., among others, are significantly focused on providing RAN solutions for private 5G networks, which help clients to transform their existing legacy network infrastructure into the next generation 5G network. For instance, in October 2022, Qualcomm Technologies, Inc. announced a collaboration with Vodafone Group to develop and integrate next-generation 5G radio units and distributed units with massive multiple-input multiple-output capabilities. The companies are also developing 5G ORAN infrastructure solutions powered by Qualcomm QRU100 5G radio access network platform and Qualcomm X100 5G RAN accelerator card.
Market Dynamics
The 5G radio access network (RAN) market is undergoing a structural transformation driven by accelerated 5G rollout programs, increasing network densification, and the shift toward cloud-native and software-centric network architectures. Mobile network operators are prioritizing capacity expansion, latency reduction, and energy efficiency to support advanced use cases such as enhanced mobile broadband, massive IoT, and ultra reliable low latency communications. At the same time, architectural innovation through Open RAN, virtualized RAN, and centralized RAN is reshaping vendor ecosystems and procurement models. These combined technology and investment trends are positioning 5G RAN as a foundational layer for next-generation digital infrastructure globally.
The exponential growth in mobile data traffic, driven by video streaming, cloud applications, and increasing smartphone penetration, has placed sustained pressure on existing 4G infrastructure. Network congestion, spectrum inefficiencies, and inconsistent quality of service have become critical challenges for operators, particularly in urban and high-density environments. As data consumption patterns evolve, operators face the need to support higher throughput, lower latency, and more simultaneous device connections without compromising network reliability.
5G Radio Access Network solutions directly address these challenges through advanced technologies such as massive MIMO, beamforming, and higher-frequency spectrum utilization. These capabilities significantly improve spectral efficiency and network capacity while enabling dynamic traffic management. As operators deploy 5G RAN to meet rising demand, large-scale investments in radio units, baseband processing, and supporting software are accelerating market growth across both developed and emerging regions.
The deployment of 5G Radio Access Networks requires substantial capital investment in new hardware, site upgrades, fiber backhaul, and spectrum acquisition. For many operators, especially those with extensive legacy infrastructure, the cost of operating and integrating networks in parallel increases financial risk. In addition, technical complexity related to network synchronization, interoperability, and site densification slows large-scale rollout.
These challenges disproportionately impact operators in price-sensitive and emerging markets, where return on investment timelines are longer, and average revenue per user remains lower. Rural deployments and indoor coverage expansion are particularly affected due to higher per-site costs. As a result, capital intensity and operational complexity act as moderating factors on market expansion, delaying adoption in certain geographies and deployment segments.
The increasing adoption of Open RAN and virtualized RAN architectures presents a significant opportunity for the 5G Radio Access Network market. Disaggregation of hardware and software, combined with open interfaces, is enabling operators to diversify vendor sourcing and reduce dependency on single-supplier ecosystems. Cloud-native network functions and general-purpose hardware are further lowering long-term operational costs.
This shift creates strong growth potential for software vendors, system integrators, and new ecosystem participants specializing in RAN automation, orchestration, and AI-driven optimization. Vendors with strong virtualization capabilities and Open RAN-compliant portfolios are well positioned to capture incremental demand as operators transition toward flexible, programmable network architectures.
Analyst Perspective
The 5G Radio Access Network market is transitioning from initial rollout to large-scale capacity expansion, supported by sustained operator investment and enterprise adoption. Technology trends such as massive MIMO, Open RAN, and cloud-native RAN are redefining competitive dynamics and cost structures. While capital intensity remains a constraint, architectural flexibility and software-led innovation are improving long-term economics. Moreover, investment is expected to increasingly favor virtualization, automation, and energy-efficient solutions. Strategic partnerships and ecosystem-based competition are likely to intensify as operators pursue scalable and vendor-diverse RAN strategies.
Component Insights
Based on component, the hardware segment led the market with the largest revenue share of 59.0% in 2025. In terms of component, the market is classified into hardware, software, services, and others. The hardware segment is further categorized into antennas, radio units, baseband units, and others. The radio access network antenna systems are based on different frequency ranges that provide increased data-carrying capacity, better coverage, and reduced interference. Antenna systems are designed to receive transmissions from user equipment, such as 5G-enabled smartphones and computers, and send the data to the radio unit. Different types of antennas provide multiple configurations allowing transmission and reception of data with improved network performance and lower operational costs. The antennas are further categorized into multiple input, multiple output (MIMO) antenna, beamforming antenna, and other antenna systems, such as monopole, dipole, microstrip, and patch antennas.
The radio units are placed on top of base stations, receive data transmitted from the antenna, and convert it into digital format to send to the baseband unit. The baseband unit comprises centralized and distributed units. It enables telecom operators to accelerate and streamline the multi-phase cell site deployment process during installation. The growth of the hardware segment is primarily attributed to its ability to deliver massive machine-type communications (mMTC), ultra-reliable low-latency communications (URLLC), and enhanced mobile broadband (eMBB). Moreover, the emerging deployment of hardware equipment and growing use cases is fueling the growth of the market.
The services segment is anticipated to grow at a considerable CAGR of 13.9% throughout the forecast period. The services segment is further categorized into consulting, managed, and professional services. An increase in demand for consulting, maintenance services, design, and development due to the deployment of 5G radio access network telecom operators is anticipated to drive the growth of the market.
Architecture Type Insights
Based on architecture type, the VRAN segment led the market with the largest revenue share of 38.7% in 2025. In terms of architecture type, the market is classified into CRAN, ORAN, and VRAN. The Cloud Radio Access Network (CRAN) segment gained a market share of more than 32% in 2024, witnessing a CAGR of 2.8% during the forecast period. Cloud radio access network (CRAN) maintains stable growth in the market owing to technological advances offered for optical, wireless, and IT communication systems. C-RAN is a cloud-based & centralized radio access network architecture. It utilizes proprietary hardware with embedded software to produce higher spectrum efficiency, flexible network, efficient network enhancements, monitoring, upgrades, testing, & maintenance, and achieve faster data speeds. However, C-RAN can be further categorized into partially centralized, fully centralized, and hybrid centralized as per processing and managed resources. Prominent MNOs are engaged in product developments, collaborations, and acquisitions to develop cloud RAN solutions delivering agility, automation, and sustainability. For instance, in May 2022, Telefonaktiebolaget LM Ericsson announced a strategic partnership with Intel Corporation to launch a C-RAN tech hub in California. The launch of the tech hub aims to accelerate the adoption of C-RAN solutions to improve network performance, create lucrative opportunities such as enterprise applications, reduce time-to-market, and energy-efficient solutions.
The open RAN (ORAN) is expected to grow at a highest CAGR of 24.1% during the forecast period. Open Radio Access Network (ORAN) technology allows the creation of multi-supplier RAN solutions enabling disaggregation or separation of hardware equipment and software platforms with virtualization and open interface. It hosts software to update and control network configurations in the cloud enabling 5G solution flexibility, new capabilities, and supply chain diversity. ORAN is crucial for enterprises employing private 5G in vendor-neutral hardware and software-defined technology for time-sensitive functions, such as load balancing and Quality of Services (QoS) management.
Moreover, the O-RAN Alliance comprises almost 200 telecom operators, research & academic institutions, and vendors in the 5G Radio Access Network (RAN) industry. The alliance specifies next-generation radio access network principles and infrastructure toward building virtualized network elements, standardized interface, and white-box hardware fueling the segment's growth. In September 2022, NEC Corporation announced the launch of an Open RAN innovation hub in New Providence in North America. The creation of an innovation hub aims to develop products offering Open RAN solutions and build a multi-vendor ecosystem.
Deployment Insights
Based on deployment, the outdoor segment led the market with the largest revenue share of 57.6% in 2025. In terms of deployment, the market is classified into indoor and outdoor. Among these, the outdoor segment is expected to dominate in 2023, gaining a market share of more than 58%. It is expected to grow at a CAGR of 8.7% throughout the forecast period. The increasing use cases of 5G, such as smart cities, industrial robotics, autonomous vehicles, smart factories & manufacturing, are propelling the demand for outdoor 5G RAN deployment. The outdoor segment offers extended 5G coverage range support for outdoor deployments at public places such as transport hubs, shopping centers, and stadiums is driving the growth of the market. With the rising deployment of public and private 5G, users can travel with high-speed data connectivity, which results in improved quality of calls and provides real-time traffic information to users.
The indoor segment is anticipated to grow at a considerable CAGR of 16.2% throughout the forecast period. The growth of the segment is attributed to the growing demand for seamless RAN connectivity within closed environments, such as office buildings, enterprise shop floors, meeting rooms, and auditoriums. In addition, improving 5G technology for efficient indoor quality service, low latency, and higher data speeds are fueling the growth of the market. Moreover, the COVID-19 pandemic positively impacted the 5G rollouts and deployment owing to the gradual shift toward online education and remote workplaces. The adoption of the private 5G network and RAN increased significantly with the increasing number of smartphones, internet subscribers, and 5G use cases. In May 2024, MosoLabs introduced Moso Canopy 5GID2, a 5G indoor radio access point for private networks. It uses Qualcomm's FSM200 platform and will be showcased at Connect (X). MosoLabs also announced new partnerships to bring private 5G use cases to life.
End-use Insights
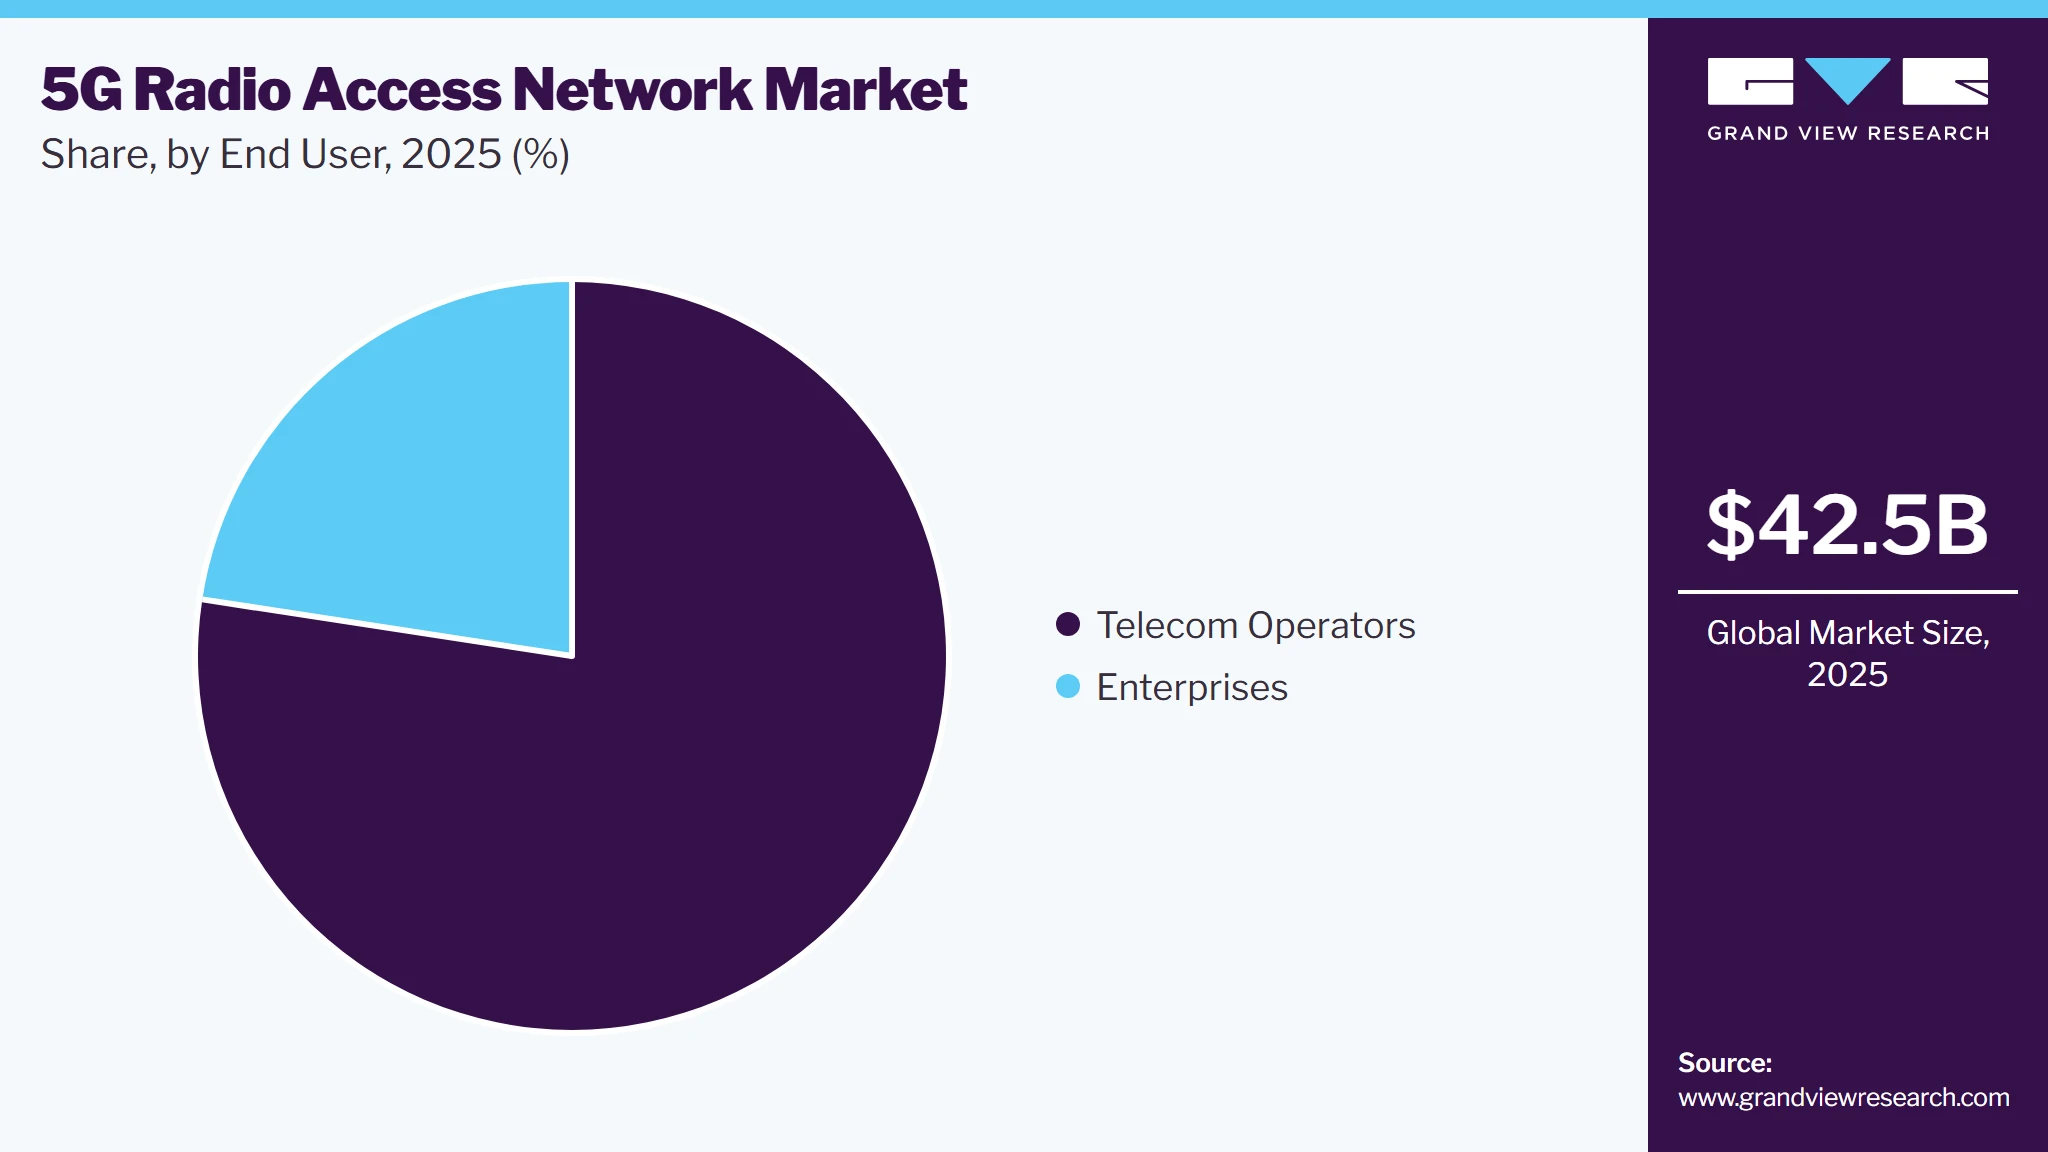
In terms of end-use, the market is classified into telecom operators and enterprises. Among these, the telecom operators 5G RAN market is expected to dominate in 2025, gaining a market share of more than 77.4%. It is expected to grow at a CAGR of 12.2% throughout the forecast period. With the growing telecom industry and IT infrastructure, the adoption of 5G RAN is exponentially expanding worldwide. Telecom operators such as AT&T and Verizon, in order to provide 5G services and RAN, are placing orders for 5G gears. In addition, the growing adoption of smartphones, internet subscribers, and infrastructural developments are anticipated to propel the growth of the market in the forecasted period. Moreover, the rising competition between prominent telecom operators to enable seamless data speeds, accessibility, and efficient bandwidth connectivity is encouraging the adoption of 5G services and RAN in developing countries, fueling the growth of the market.
 To learn more about this report, Download Free Sample Report
The enterprise segment is anticipated to grow at a considerable CAGR of 20.4% throughout the forecast period. The enterprise segment comprises BFSI, healthcare, media & entertainment, smart city, government, retail, manufacturing, transportation & logistics, aerospace & defense. The increasing demand for 5G RAN from the aforementioned enterprise end use is propelling the growth of the market. The utilization of 5G has enabled industry automation, online consultations, streamlined operations, and immersive experiences, among others, in multiple enterprise End use with advanced technologies such as IoT, AR/VR, AI, big data, and machine learning.
Regional Insights
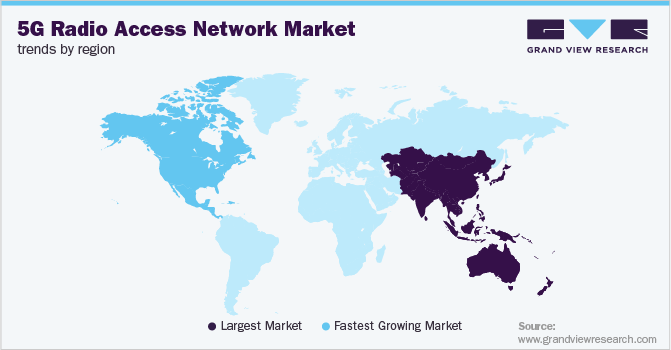
The Asia-Pacific 5G radio access network market dominates with revenue share of 41.9% in 2025 and grow at a CAGR of 11.6%. The growth is attributed to the presence of several manufacturers, such as Huawei Technologies Co., Ltd., and Samsung, coupled with a multitude of investments that are expected toward building automated factories in the region. In addition, huge investments to acquire a 5G spectrum in key countries such as South Korea, China, India, Australia, and Japan are projected to contribute to regional growth. Furthermore, a gradual increase in the number of small and medium IT companies in emerging countries, such as India and South Korea, is projected to propel the adoption of 5G services in the region. In addition, the region's untapped potential is generating new investment opportunities for mobile network operators and communication service providers in the region.
 To learn more about this report, Download Free Sample Report
China 5G Radio Access Network Market Trends
The 5G radio access network market in the China held the largest share in the Asia Pacific region in 2025. China has emerged as a global leader in 5G RAN deployment, showcasing rapid progress and extensive network coverage. The country's major telecom operators, such as China Mobile, China Telecom, and China Unicom, have made significant investments in 5G infrastructure, leveraging both domestic and international technologies. Huawei, a Chinese technology giant, has played a pivotal role in driving 5G development within China, providing end-to-end solutions and contributing to the country's technological advancements. While the US has imposed restrictions on Huawei's involvement in 5G networks, China has continued to expand its 5G footprint, focusing on domestic capabilities and alternative partnerships. The country's 5G deployment has paved the way for a wide range of applications and use cases, from smart cities and industrial automation to virtual reality and augmented reality experiences.
The 5G radio access network (RAN) market in India is expected to grow at a significant CAGR from 2026 to 2033. India's 5G RAN landscape is rapidly evolving, with significant strides being made in network deployment and coverage expansion. The country's major telecom operators, Reliance Jio, Airtel, and Vodafone Idea, have been actively investing in 5G infrastructure, leveraging technologies from various vendors. The government has also played a crucial role in supporting 5G development, allocating spectrum, and implementing favorable policies. While challenges such as spectrum availability and cost considerations persist, India's 5G rollout is gaining momentum. The country's vast population and diverse market present immense opportunities for 5G applications across various sectors, including healthcare, education, agriculture, and smart cities. As India continues to embrace 5G technology, it is poised to unlock new economic growth drivers and improve the quality of life for its citizens.
The 5G radio access network (RAN) market in Japan is expected to grow at a significant CAGR from 2026 to 2033. Japan has been at the forefront of 5G technology adoption, with a focus on providing high-speed and reliable connectivity to its citizens and businesses. The country's major telecom operators, NTT Docomo, KDDI, and Softbank, have made significant investments in 5G infrastructure, leveraging advanced technologies and deploying dense networks to ensure widespread coverage. Japan's 5G rollout has been driven by a strong emphasis on innovation and the development of new applications and services. The country has been a pioneer in areas such as autonomous vehicles, smart factories, and remote healthcare, leveraging 5G's capabilities to enhance efficiency and productivity. While challenges such as spectrum availability and cost considerations remain, Japan's 5G ecosystem is well-positioned to drive economic growth and improve the quality of life for its population.
North America 5G Radio Access Network Market Trends
North America 5G radio access network market gained a significant market share of around 28.6% in year 2025. The region is equipped with a highly developed 5G infrastructure and owns an extensive research and development base, allowing the region to be the top revenue contributor in the worldwide market during the projected period. A well-established 5G infrastructure has allowed the speedier implementation of modern 5G technologies, and substantial government investments in 5G rollouts and deployments have enabled significant adoption of 5G RAN in the U.S. and Canada. The considerable presence of small and medium players in North America, which offer 5G components and services to giants such as Intel Corporation, Verizon, and Mavenir, has also propelled the market growth. The U.S. is expected to retain its dominance over the forecast period owing to the inclination of consumers towards 5G services and growing technological investments in the region.
U.S. 5G Radio Access Network Market Trends
The U.S. 5G radio access network (RAN) market is expected to grow at a significant CAGR from 2026 to 2033. The U.S. 5G RAN landscape is currently undergoing significant transformation, driven by a combination of technological advancements and regulatory initiatives. Major players such as Ericsson, Nokia, and Samsung are actively investing in 5G infrastructure deployment, expanding network coverage and capacity. The introduction of Open RAN architecture has also been a key development, promoting interoperability and reducing vendor lock-in. However, challenges such as spectrum availability, cost considerations, and the need for a skilled workforce remain. Despite these hurdles, the U.S. 5G RAN market is poised for substantial growth, with the potential to drive innovation across various industries and enhance connectivity for consumers and businesses alike.
Key 5G Radio Access Network Company Insights
The market is consolidated and is anticipated to witness increased competition due to several players' presence. Major players are spending heavily on research and development activities to integrate advanced technologies within 5G services and RAN has intensified the competition among these players. Some prominent players in the market include Telefonaktiebolaget LM Ericsson, Qualcomm Technologies, Inc., Nokia, Intel Corporation, Samsung, Verizon, Cisco Systems, Inc., Huawei Technologies Co., Ltd., VMware, Inc., Rakuten Symphony Singapore Pte. Ltd, among others. These companies are also collaborating with local & regional players to gain a competitive edge over their peers and capture a significant market share.
Some of the key companies operating in the 5G radio access network (RAN) include Telefonaktiebolaget LM Ericsson, Qualcomm Technologies, Inc., and Verizon, among others.
-
Telefonaktiebolaget LM Ericsson, a Swedish multinational networking and telecommunications company, has a strong competitive edge in the 5G RAN market due to its extensive global presence, long-standing experience, and comprehensive product portfolio. The company's deep understanding of network infrastructure, coupled with its ability to deliver end-to-end solutions, has enabled it to establish strong partnerships with major telecom operators worldwide. Ericsson's commitment to research and development has also positioned it at the forefront of 5G technology advancements, ensuring that its offerings remain competitive and meet the evolving needs of the market.
-
Qualcomm Technologies, Inc., a U.S.-based semiconductor company, has a significant competitive advantage in the 5G RAN market due to its expertise in mobile chipsets and system-on-a-chip (SoC) technology. The company's innovative 5G modems and RF transceivers have been widely adopted by leading smartphone manufacturers and network equipment providers. Qualcomm's strong research and development capabilities have allowed it to continuously push the boundaries of 5G technology, delivering solutions that enable faster data speeds, lower latency, and enhanced network capacity.
-
Verizon, a major US-based telecommunications company, has a competitive edge in the 5G RAN market due to its extensive network infrastructure and early investments in 5G technology. The company's nationwide 5G coverage and commitment to providing high-quality services have positioned it as a leading player in the US market. Verizon's strategic partnerships with network equipment providers and its focus on developing innovative 5G applications have also contributed to its competitive advantage.
Samsung and VMware, Inc. are some of the emerging companies in the target market.
-
As a leading global technology conglomerate, Samsung has a strong competitive advantage in the 5G RAN market due to its vertical integration capabilities. The company's ability to design, manufacture, and distribute its own components, including modems, RF transceivers, and antennas, provides it with greater control over the entire value chain. This vertical integration allows Samsung to optimize costs, improve product quality, and accelerate time-to-market for its 5G solutions. In addition, Samsung's extensive experience in consumer electronics and semiconductor manufacturing positions it well to leverage its expertise and resources to drive innovation in the 5G RAN market.
-
VMware, a leading provider of virtualization and cloud computing solutions, has a competitive advantage in the 5G RAN market due to its deep expertise in software-defined infrastructure. The company's virtualization technologies can be applied to various components of the 5G network, including radio access networks, core networks, and transport networks. By virtualizing these components, VMware can help network operators reduce costs, improve flexibility, and accelerate the deployment of new services. In addition, VMware's partnerships with leading telecom equipment vendors and its strong presence in the enterprise market position it well to capitalize on the growing demand for 5G solutions.
Key 5G Radio Access Network Companies:
The following key companies have been profiled for this study on the 5G radio access network market.
-
Telefonaktiebolaget LM Ericsson
-
Qualcomm Technologies, Inc.
-
Nokia
-
Rakuten Symphony Singapore Pte. Ltd
-
Intel Corporation
-
Samsung
-
Verizon
-
Cisco Systems, Inc.
-
Huawei Technologies Co., Ltd.
-
VMware, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Telefonaktiebolaget LM Ericsson, Nokia, Huawei Technologies Co., Ltd., Samsung)
- These players are focused on end-to-end RAN portfolios, large-scale contracts with global operators, and continued R&D investment.
- These players have strong installed base, proven performance at scale, broad hardware and software capabilities.
- High dependence on operator capex cycles and exposure to geopolitical constraints.
Emerging Players (Rakuten Symphony Singapore Pte. Ltd, VMware, Inc., Qualcomm Technologies, Inc.)
- These players are focused on Open RAN, virtualization, and software-defined networking.
- These players have agility, cloud-native expertise, and alignment with disaggregated RAN models.
- Limited large-scale deployment track record and reliance on ecosystem partnerships.
Recent Developments
-
In October 2024, Du extended its contract with Nokia to expand its 5G network. The agreement will support Du in incorporating advanced 5G technologies like enhanced mobile broadband, network slicing, and edge computing. These capabilities will enable Du to provide future-ready network services to both consumer and enterprise customers.
-
In October 2024, Software Radio Systems (SRS) launched srsRAN Enterprise 5G, a portable, full-stack software solution for private 5G networks. This Open RAN solution offers flexible deployment options and supports diverse user networks. srsRAN Enterprise 5G is designed for quick deployment using off-the-shelf hardware and is compatible with various compute platforms.
-
In October 2024, Pegatron 5G, an O-RAN provider, launched the PR1450 O-RU and FHM, designed for indoor coverage in enterprise and public deployments. These solutions offer reliable connectivity, simplified network configurations, and flexibility for various 5G environments. The company is committed to supporting India's 5G infrastructure and "Make in India" policy.
5G Radio Access Network Market Report Scope
Report Attribute
Details
Market size in 2025
USD 42.5 billion
Estimated Market size in 2026
USD 52.6 billion
Projected Market size by 2033
USD 135.8 billion
Growth rate
CAGR of 14.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share, competitive landscape, growth factors, and trends
Segments covered
Component, architecture type, deployment, end-use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; UAE; and South Africa
Key companies profiled
Telefonaktiebolaget LM Ericsson; Qualcomm Technologies, Inc.; Nokia; Intel Corporation; Samsung; Verizon; Cisco Systems, Inc.; Huawei Technologies Co., Ltd.; VMware, Inc.; Rakuten Symphony Singapore Pte. Ltd
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global 5G RAN Market Report Segmentation
This report forecasts revenue growths at global, regional, and country levels and provides an analysis of the industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global 5G radio access network market based on component, architecture type, deployment, end-use, and region.
-
Component Outlook (Revenue, USD Million, 2021 - 2033)
-
Hardware
-
Antennas
-
MIMO
-
Beamforming
-
Others (Monopole, Dipole, Microstrip, Patch Antennas)
-
-
Radio Unit
-
Baseband Units
-
-
Software
-
Services
-
Managed Services
-
Consulting Services
-
Professional Services
-
Planning & Design Services
-
Integration & Validation Services
-
Deployment Services
-
Optimization and Performance Improvement Services
-
-
-
-
Architecture Type Outlook (Revenue, USD Million, 2021 - 2033)
-
CRAN
-
ORAN
-
VRAN
-
-
Deployment Outlook (Revenue, USD Million, 2021 - 2033)
-
Indoor
-
Outdoor
-
-
End-use Outlook (Revenue, USD Million, 2021 - 2033)
-
Telecom Operators
-
Enterprises
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
KSA
-
South Africa
-
-
Research Methodology
The 5G radio access network market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each 5G radio access network segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Hardware
Revenue generated from the sale of physical 5G RAN network equipment supplied to telecom operators and infrastructure providers, including antennas, radio units, and baseband processing units, covering both standalone and integrated hardware configurations. The segment includes hardware such as antennas, radio unit, and baseband unit.
Antennas: Revenue generated from the sale and supply of 5G-compatible antenna systems used in radio access networks, including macro cell, small cell, and indoor antennas, sold to telecom operators and enterprises as part of new network deployments, capacity expansions, and technology upgrades. This segment includes antennas such as MIMO, beamforming, and others (such as monopole, dipole, microstrip, and patch antennas)
- MIMO: Revenue from the supply of multi-input multi-output (MIMO) antennas, including massive MIMO systems, used in 5G macro and small cell deployments, covering equipment sales, configuration-specific variants, and capacity-enhancing antenna arrays.
- Beamforming: Revenue derived from active and passive beamforming antennas that dynamically steer radio signals to improve coverage and spectral efficiency, including sales of adaptive antenna systems and integrated antenna-radio solutions.
- Others (Monopole, Dipole, Microstrip, Patch): Revenue from conventional and specialized antenna types used in macro cells, small cells, and indoor deployments, including standalone antenna units and customized antenna designs for specific frequency bands.
Radio Unit: Revenue captured from the sale of radio units responsible for RF signal transmission and reception, including centralized, distributed, and open RAN-compatible radio units across multiple frequency bands.
Baseband Units: Revenue generated from baseband processing equipment that handles signal processing, scheduling, and network control functions, including centralized units (CU), distributed units (DU), and virtualized baseband platforms.
Software
Revenue from licensing, subscriptions, or usage-based fees for 5G RAN software, including virtualized RAN software, network functions, orchestration platforms, AI/ML-based optimization tools, and software upgrades.
Services
Revenue earned from service-based offerings supporting the deployment, operation, and optimization of 5G RAN infrastructure, delivered through recurring contracts or project-based engagements. The segment includes managed services, Consulting Services, and professional services.
- Managed Services: Revenue from long-term contracts for outsourced management of 5G RAN networks, including network monitoring, maintenance, fault management, performance management, and service-level agreement (SLA)-based operations.
- Consulting Services: Revenue generated from advisory engagements focused on 5G RAN strategy, technology selection, network modernization planning, vendor evaluation, and regulatory or spectrum-related consulting.
- Professional Services: Revenue generated from project-based technical services supporting network design, integration, deployment, and optimization activities. The segment includes professional services such as planning & design services, integration & validation services, deployment services, optimization and performance improvement services.
Planning & Design Services: Revenue from network planning and design activities, including radio frequency planning, site design, capacity modeling, and network architecture design for 5G deployments.
Integration & Validation Services: Revenue from integrating 5G RAN components with existing network infrastructure, conducting interoperability testing, system validation, and performance verification before commercial launch.
Deployment Services: Revenue derived from on-site and remote deployment activities, including equipment installation, configuration, commissioning, and initial network rollout for 5G RAN systems.
Optimization and Performance Improvement Services: Revenue from post-deployment optimization services aimed at improving network performance, coverage, latency, and energy efficiency through tuning, analytics, and continuous performance enhancement initiatives.
Segment - Architecture Type
Revenue capture definition
CRAN
Revenue generated from the deployment of centralized baseband processing architectures, including sales of centralized baseband units, fronthaul solutions, supporting software licenses, and associated integration and deployment services for centralized network configurations.
ORAN
Revenue captured from open and interoperable RAN architectures, including sales of disaggregated hardware (open radio units, commercial off-the-shelf servers), open RAN software platforms, system integration, interoperability testing, and vendor-neutral professional services.
VRAN
Revenue generated from virtualized RAN deployments, including software licenses or subscriptions for virtual baseband functions, cloud infrastructure usage, virtualization platforms, orchestration software, and related integration and optimization services.
Segment - Deployment
Revenue capture definition
Indoor
Revenue generated from 5G RAN solutions deployed within buildings and enclosed environments, including indoor small cells, distributed antenna systems (DAS), indoor radio units, software licenses, and deployment and optimization services.
Outdoor
Revenue captured from outdoor 5G RAN deployments, including macro cells and outdoor small cells, encompasses hardware sales, site installation, software, and ongoing network management and maintenance services.
Segment - End-use
Revenue capture definition
Telecom Operators
Revenue generated from sales of 5G RAN hardware, software, and services to mobile network operators for public network deployments, network expansion, modernization, and long-term managed service contracts.
Enterprises
Revenue captured from private and hybrid 5G network deployments for enterprises, including on-premise RAN hardware, private network software licenses, integration services, and ongoing support and optimization services.
Estimation Model
Layer Name
Key Question
Description
Demand Layer
Where is 5G RAN demand generated?
This layer evaluates operator and enterprise demand driven by subscriber growth, data usage, and private network adoption. It considers geographic rollout intensity and spectrum availability. Demand patterns differ significantly between urban, suburban, and industrial zones.
Deployment Layer
How is the network being deployed?
This layer analyzes deployment models such as indoor vs. outdoor and macro vs. small cells. It accounts for densification strategies and coverage objectives. Deployment choices directly influence equipment and service requirements.
Architecture Layer
Which RAN architecture is selected?
This layer assesses adoption of CRAN, ORAN, and VRAN architecture. It captures the impact of virtualization, openness, and cloud integration on cost and scalability. Architecture selection shapes vendor participation.
Component Layer
What components generate revenue?
This layer quantifies revenue across hardware, software, and services. It reflects shifts toward software-driven value and recurring service income. Component mix evolves as networks mature.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional 5G Radio Access Network Market Opportunity Assessment
Country/region-wise market sizing and forecasts
Analysis of demand, adoption trends, and regulatory landscape
Identification of high-growth regions and investment hotspots
Identified region-specific growth opportunities
Supported expansion and go-to-market strategy
Enabled informed regional investment decisions
Cross-Segmentation Analysis for the 5G Radio Access Network Market
Criss-cross market analysis by component, architecture type, deployment, end use
Demand and adoption assessment across key segments
Segment attractiveness and growth potential benchmarking
Identified high-potential market segments
Supported targeted product positioning and marketing strategy
Improved customer and segment prioritization
Competitive Benchmarking and Strategic Positioning in the 5G Radio Access Network Market
Benchmarking of key competitors across products, pricing, partnerships, and innovation
Comparative assessment of market share, capabilities, and strategies
Analysis of competitive strengths, gaps, and differentiation areas
Identified competitive white spaces and growth gaps
Supported strategic positioning and differentiation
Enabled data-driven competitive strategy development
Frequently Asked Questions About This Report
The global 5G radio access network market size was estimated at USD 42.5 billion in 2025 and is expected to reach USD 52.6 billion in 2026.
The global 5G radio access network market is expected to grow at a compound annual growth rate of 14.5% from 2026 to 2033, reaching USD 135.8 billion by 2033.
Hardware segment dominated the market, with a revenue share of 59.0% in 2025. The hardware segment is further categorized into antennas, radio units, baseband units, and others. The radio access network antenna systems are based on different frequency ranges that provide increased data-carrying capacity, better coverage, and reduced interference.
Some key players operating in the 5G RAN market include Telefonaktiebolaget LM Ericsson, Qualcomm Technologies, Inc., Nokia, Intel Corporation, Samsung, Verizon, Cisco Systems, Inc., Huawei Technologies Co., Ltd., VMware, Inc., and Rakuten Symphony Singapore Pte. Ltd, among others
Asia Pacific dominated the global market with the largest revenue share of 41.9% in 2025. The growth is attributed to the presence of several manufacturers, such as Huawei Technologies Co., Ltd. and Samsung, coupled with a multitude of investments expected to build automated factories in the region.
Which architecture type segment held the largest market share in the 5G radio access network market?VRAN segment held the largest market share of 38.7% in 2025, while ORAN is the fastest-growing segment over the forecast period.
Outdoor segment accounted for the largest revenue share of 57.6% in 2025, while indoor is the fastest-growing segment over the forecast period.
Telecom Operators segment accounted for the largest revenue share of 77.4% in 2025, while enterprises is the fastest-growing segment over the forecast period.
The increasing demand for low latency bandwidth connection and increased focus on research and development activities by key organizations are some of the factors fueling the market growth.
About the Author(s)
Communications Infrastructure Research Team
Technology · Communications InfrastructureThis report was authored by the communications infrastructure research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the communications infrastructure segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


