
- Home
- »
- Next Generation Technologies
- »
-
Smart Cities Market Size, Share, Growth Report, 2026-2033GVR Report cover

Smart Cities Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Smart Governance, Smart Building, Smart Healthcare), By Smart Governance, By Smart Utilities, By Smart Transportation, By Smart Healthcare, By Region, And Segment Forecasts
Market Size, 2025
$1.0TMarket Estimate, 2026
$1.3TMarket Forecast, 2033
$8.8TCAGR, 2026–2033
31.9%Smart Cities Market Summary
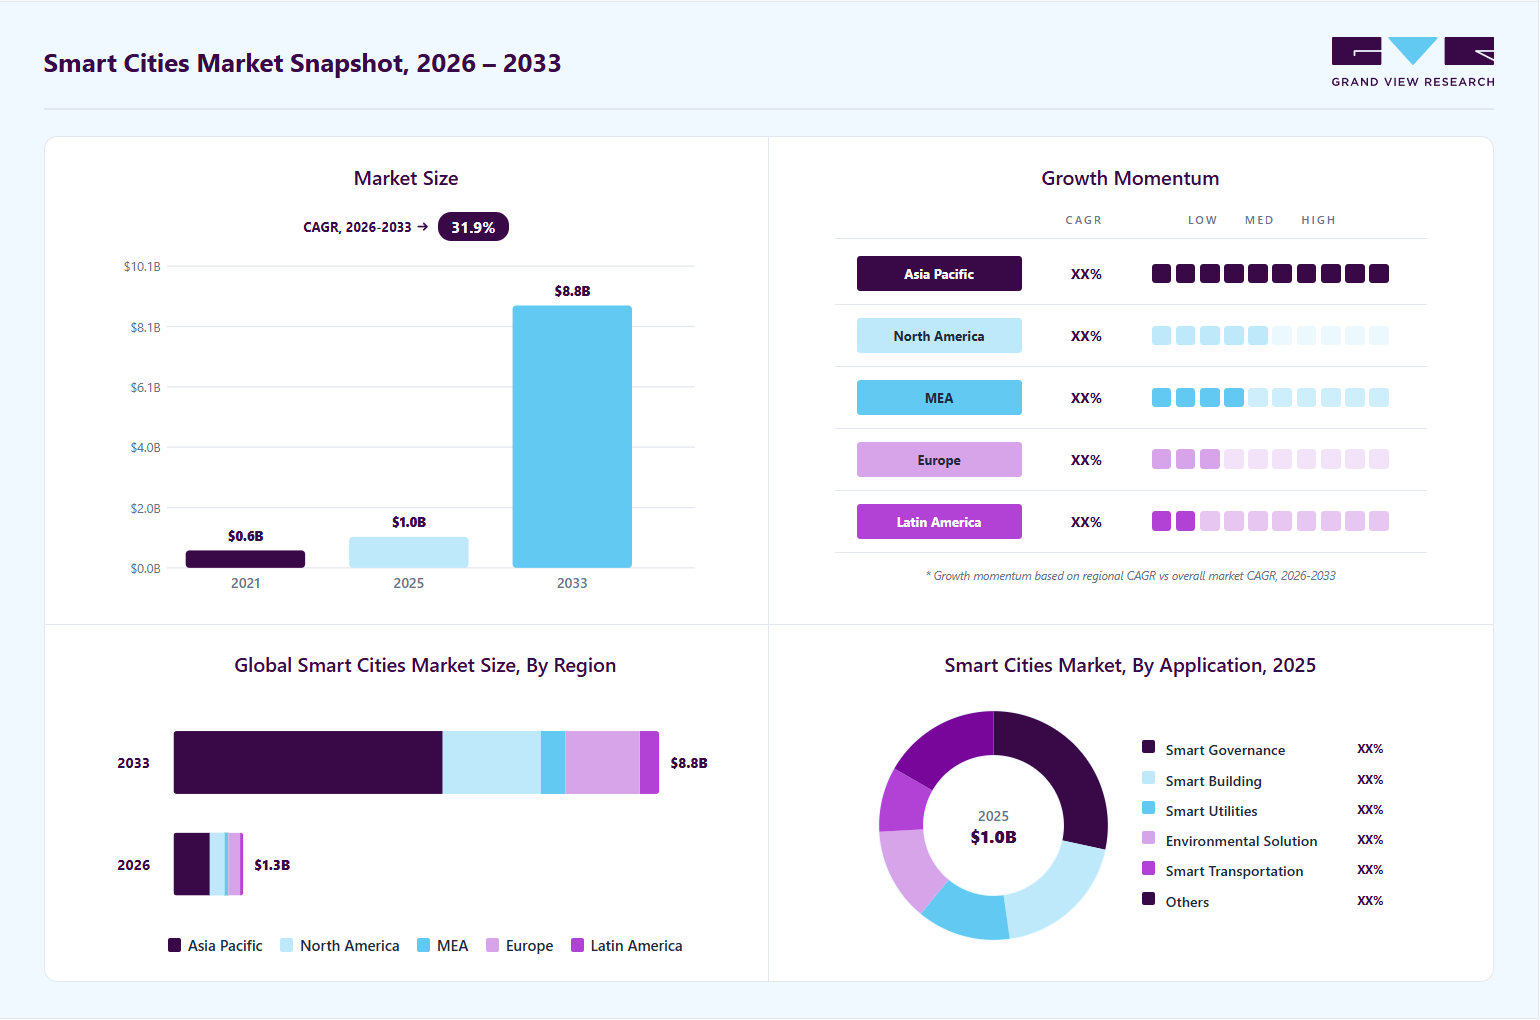
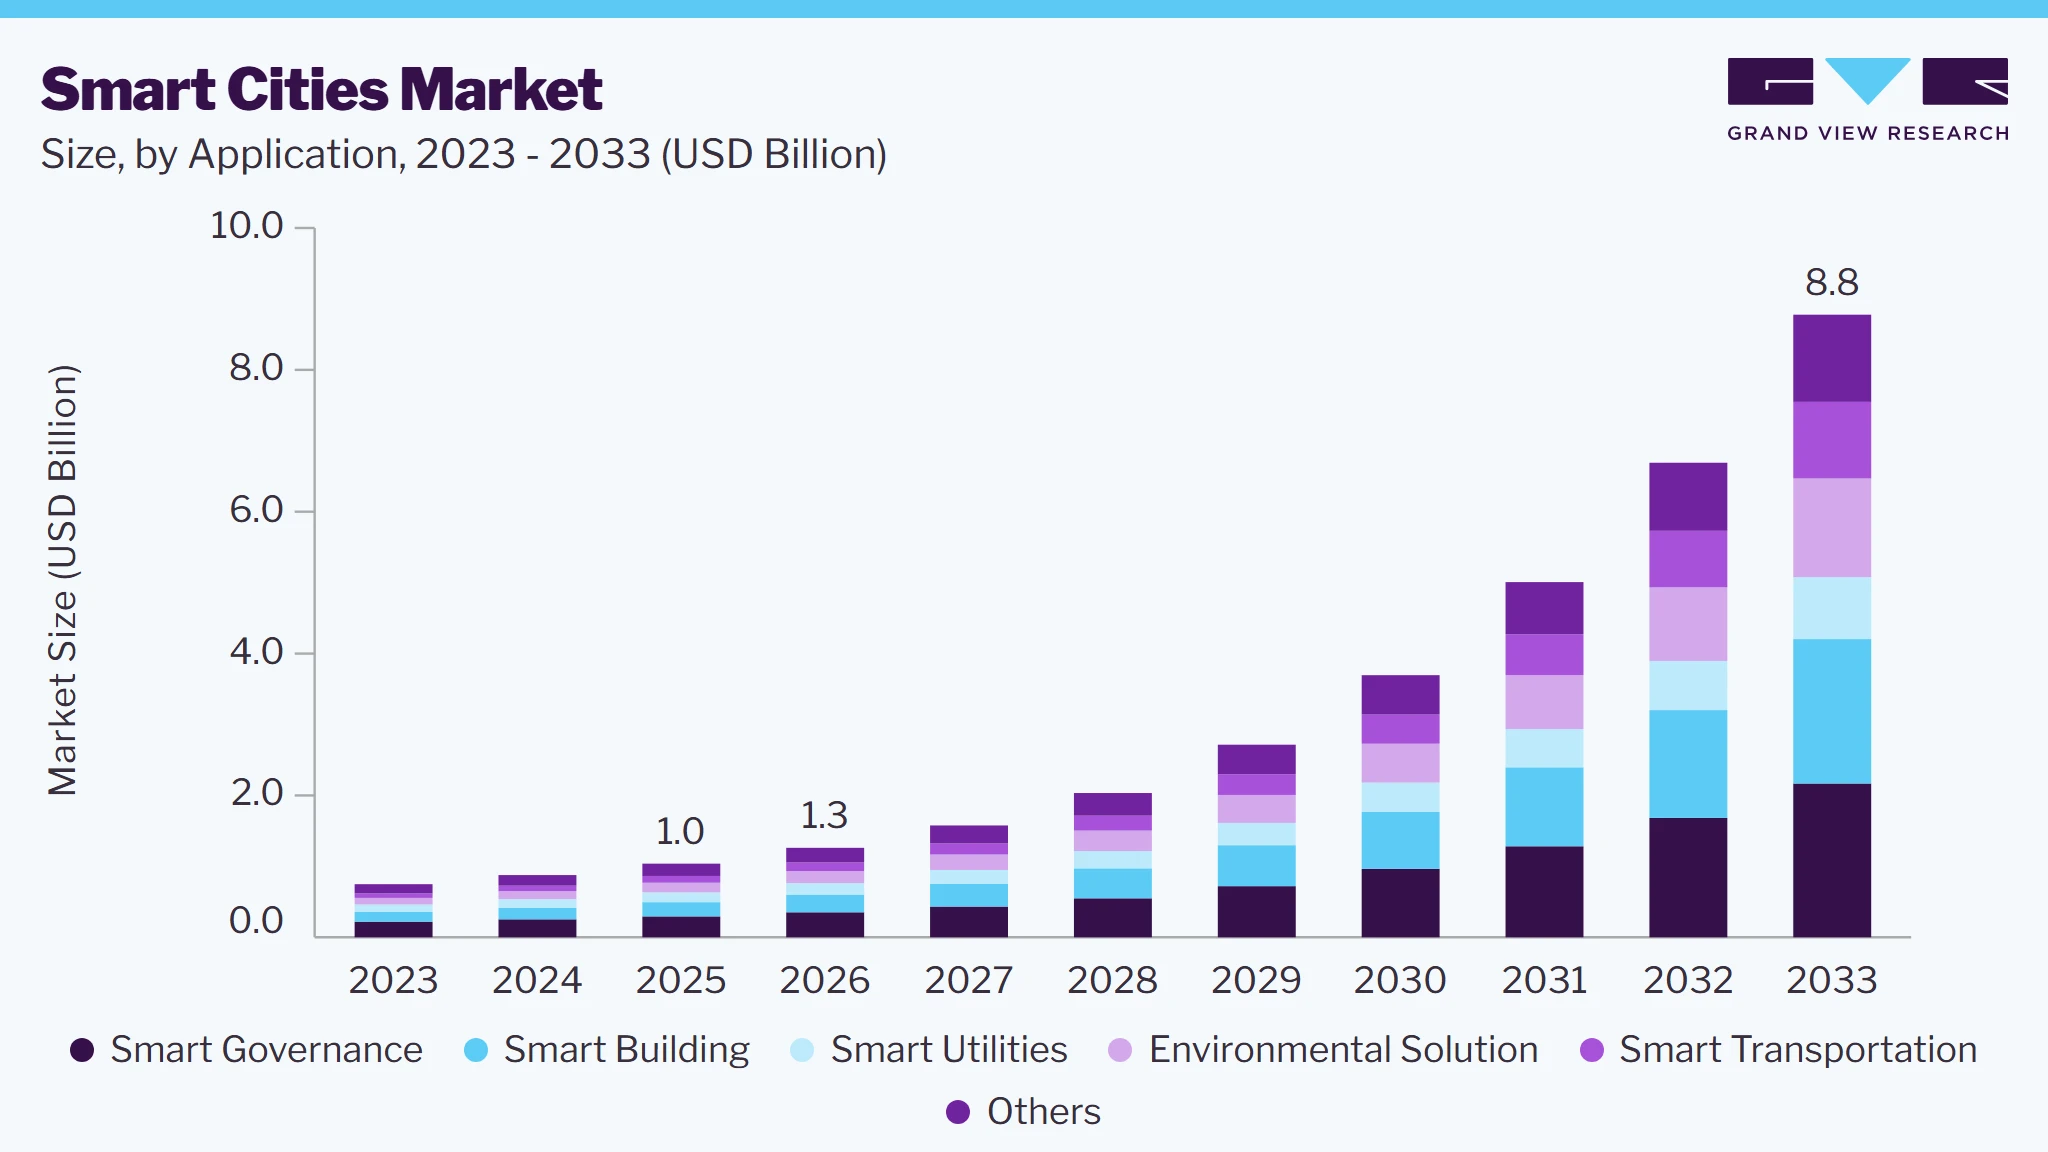
The global smart cities market size was valued at USD 1.0 trillion in 2025 and is projected to grow from USD 1.3 trillion in 2026 to USD 8.8 trillion by 2033, at a CAGR of 31.9% from 2026 to 2033. Asia Pacific dominated the market with a revenue share of 51.3% in 2025. Market growth is primarily driven by rapid urbanization and the increasing pressure on governments and municipalities to develop more sustainable, efficient, and resilient urban environments.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: Smart governance held the largest revenue share of 28.4% in 2025.
- By smart governance: Smart infrastructure held the largest revenue share of 27.6% in 2025.
- By smart utilities: Energy management held the largest market share of 27.2% in 2025.
- By smart transportation: Intelligent transportation system held the largest market share of 29.4% in 2025.
- By smart healthcare: Medical devices held the largest market share of 56.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (51.3% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 1.0 Trillion
- Estimated market size in 2026: USD 1.3 Trillion
- Projected market size by 2033: USD 8.8 Trillion
- CAGR (2026-2033): 31.9%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
As cities become more densely populated, the need for intelligent infrastructure and data-driven solutions is increasing. The growing deployment of IoT-enabled devices and connected infrastructure is allowing cities to collect and analyze real-time data, improving the management of transportation, utilities, public safety, and other essential services. Rising investments in smart infrastructure, including smart grids, intelligent transportation systems, and digital governance platforms, are accelerating the adoption of smart city solutions. Advances in communication and computing technologies, particularly 5G networks and edge computing, are further enhancing connectivity, enabling faster data processing, and supporting the deployment of sophisticated urban applications. These factors are contributing to the continued expansion of the global smart cities industry.The growing emphasis on sustainability and environmental management is reshaping the smart cities landscape, as governments and urban planners increasingly prioritize green infrastructure and resource-efficient solutions. Cities are adopting energy-efficient systems, renewable energy technologies, and green building practices to reduce carbon emissions and improve environmental performance. Initiatives such as smart grids, electric public transportation, and waste-to-energy systems are also gaining traction as cities work toward their sustainability and climate objectives.
 To learn more about this report, Download Free Sample Report
The increasing demand for intelligent transportation systems is another important factor shaping the development of smart cities. Urban areas are deploying solutions such as adaptive traffic signals, real-time transit information, autonomous vehicles, and integrated multimodal transportation platforms to improve mobility and manage growing transportation demands. These technologies can help reduce congestion, optimize traffic flows, lower transportation-related emissions, and improve the overall commuter experience. As cities address increasing traffic volumes and air pollution, intelligent mobility is becoming an integral component of urban planning and infrastructure development.
Public safety and security are also becoming increasingly important components of smart city development. Governments and municipalities are investing in advanced surveillance systems, emergency response technologies, and cybersecurity infrastructure to strengthen urban resilience. AI-powered video analytics, automated threat detection, and integrated communication platforms enable real-time monitoring and facilitate faster incident response. These capabilities support the management of physical security risks and the growing cybersecurity requirements associated with connected urban environments.
The adoption of smart buildings and intelligent infrastructure is further transforming urban development. Cities are increasingly incorporating automated lighting and climate control, energy management systems, and integrating security solutions into commercial, residential, and public buildings. These technologies help optimize energy and resource consumption while improving operational efficiency, occupant comfort, and safety. In addition, the integration of digital twins and Building Information Modeling (BIM) is improving the planning, construction, monitoring, and maintenance of buildings and infrastructure. Together, these technologies are enabling more data-driven approaches to urban development and supporting the broader transition toward connected and efficient cities.
Market Dynamics
The smart cities market is witnessing rapid growth as governments worldwide accelerate digital transformation initiatives through the adoption of IoT, AI, big data analytics, and 5G connectivity. These technologies are enabling cities to improve operational efficiency, enhance public and citizen services, optimize resource utilization, and support sustainable urban development. Increasing focus on environmental sustainability, public safety, and quality of life is further driving investments in smart city solutions. As a result, the development of digitally connected and intelligent urban infrastructure is becoming an increasingly important component of long-term urban planning strategies across both developed and emerging economies.
Rapid urbanization is a major growth driver for the smart cities market, as an increasing proportion of the global population moves to urban areas. This population growth is placing significant pressure on existing infrastructure, including transportation networks, energy systems, water distribution, and waste management. In many urban centers, infrastructure development has struggled to keep pace with population expansion, contributing to traffic congestion, inefficient resource utilization, and challenges in maintaining service quality. These pressures are further intensified by expanding economic activity and the growing demand for faster, more accessible, and reliable urban services.
To address these challenges, governments and municipal authorities are increasingly deploying smart city technologies based on the Internet of Things (IoT), artificial intelligence, cloud computing, and advanced data analytics. These technologies enable real-time monitoring of urban infrastructure, improve resource allocation, and support data-driven decision-making. Applications such as intelligent traffic management, smart energy distribution, predictive infrastructure maintenance, and automated public services are helping cities improve operational efficiency and optimize infrastructure performance. Consequently, smart city solutions are becoming an important tool for managing the growing complexity of urban environments while supporting more sustainable and efficient city development.
The high cost of developing and deploying smart city infrastructure remains a significant barrier to market growth. Implementing connected urban systems requires substantial investment in sensors, communication networks, data management platforms, control centers, and supporting infrastructure. These capital requirements can be particularly challenging for developing economies and municipalities operating under constrained budgets.
Beyond the initial investment, the integration of multiple technologies with existing urban infrastructure adds considerable complexity to implementation. Ensuring interoperability with legacy systems, coordinating multiple stakeholders, and managing large-scale technology deployments can increase project timelines and operational challenges. These financial and technical barriers may delay the adoption of smart city solutions, particularly in cities with limited infrastructure readiness and resources.
The rapid expansion of 5G networks, IoT ecosystems, and AI-powered analytics is creating significant opportunities for the smart cities market. These technologies provide high-speed connectivity, real-time data processing, and intelligent automation, enabling cities to optimize a wide range of urban operations. Applications such as smart mobility, energy management, predictive infrastructure maintenance, and public safety are benefiting from these technological advancements.
Growing government efforts to develop sustainable and digitally connected urban environments are further supporting investments in next-generation infrastructure. Solutions designed to improve energy efficiency, reduce carbon emissions, enhance resource management, and strengthen urban resilience are gaining traction among municipalities worldwide. Additionally, the integration of IoT, AI, cloud computing, and advanced connectivity is enabling unified digital platforms that link transportation, utilities, public safety, and emergency services. This interconnected approach is improving information sharing, coordination, and operational efficiency, creating new opportunities for technology providers, system integrators, and infrastructure developers.
Market Concentration & Characteristics
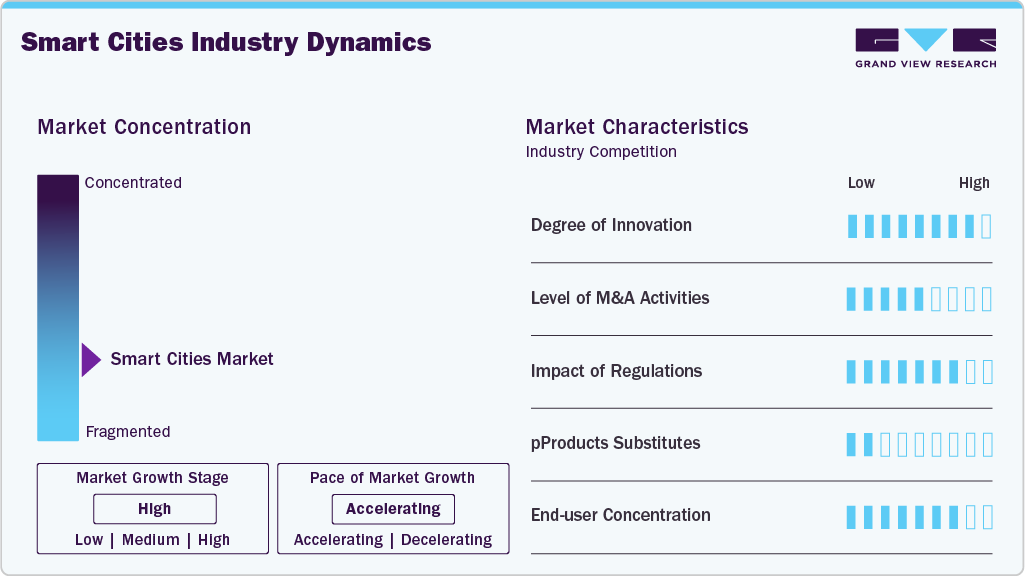
The smart cities market is moderately fragmented, with a diverse range of technology providers, system integrators, infrastructure companies, telecommunications operators, and software developers competing across solution areas such as smart transportation, utilities, digital governance, smart buildings, and public safety. The market is highly innovation-driven, with ongoing advancements in IoT, artificial intelligence, digital twins, edge computing, 5G connectivity, and cloud-based urban management platforms shaping the competitive landscape.
Mergers and acquisitions (M&A) activity is moderate to high, as companies increasingly pursue acquisitions, joint ventures, and strategic partnerships to broaden their technology portfolios, strengthen solution integration, and expand their presence in new markets. Regulatory influence is also high, as smart city projects are closely tied to government policies, public procurement processes, data privacy requirements, cybersecurity standards, environmental regulations, and urban development frameworks. These factors can directly affect project approvals, investment decisions, implementation timelines, and funding availability.
 To learn more about this report, Download Free Sample Report
The threat of substitutes is low to moderate, as conventional urban infrastructure can provide many of the same core services but generally offers lower levels of automation, connectivity, data-driven management, and resource optimization. Meanwhile, end-user concentration remains high, with a significant share of spending originating from municipal governments, public utilities, transportation authorities, and other large public-sector organizations responsible for infrastructure investment and digital transformation initiatives.
Analyst Perspective
The smart cities market is supported by rapid urbanization, rising demand for efficient public services, increasing sustainability initiatives, and continued investment in digital infrastructure. As municipalities face growing pressure to enhance transportation, energy management, public safety, and governance, smart technologies are becoming an increasingly important part of long-term urban development strategies. Competitive differentiation is increasingly centered on integrated platforms that connect multiple urban functions within a unified digital ecosystem. By enabling real-time data exchange and coordinated management across transportation, utilities, public safety, and other city services, these platforms can support data-driven decision-making, improve operational efficiency, optimize resource utilization, and enhance the delivery of citizen services across interconnected urban environments.
Application Insights
Smart governance dominated the smart cities market, accounting for the largest share of 28.4% in 2025. The segment is gaining importance in smart city development as governments adopt digital technologies to improve public administration, urban monitoring, and service delivery. The smart governance segment includes city surveillance, centralized command centers (CCS), e-governance platforms, smart lighting, and connected infrastructure. City surveillance and command centers enable real-time monitoring of public spaces, traffic, emergencies, and critical infrastructure, helping authorities improve coordination and response capabilities. E-governance platforms are facilitating the digital delivery of municipal services, enabling citizens to access information and government services through online and mobile channels while improving administrative efficiency. Smart lighting systems with connected sensors and automated controls help municipalities optimize energy consumption, remotely manage assets, and reduce maintenance requirements. Meanwhile, IoT-enabled infrastructure supports real-time monitoring and efficient management of urban assets. Growing investments in digital public services, public safety, energy efficiency, and connected infrastructure are expected to support the adoption of smart governance solutions and enable more responsive, data-driven urban management.
The smart transportation solution segment is expected to grow at the fastest CAGR of 36.8% from 2026 to 2033. Industry players are increasingly investing in advanced transportation technologies, including connected vehicles, intelligent traffic management systems, and autonomous mobility solutions, to enhance urban mobility and reduce congestion. This strategic focus on smart infrastructure and mobility innovation is fueling the growth of the smart transportation segment.
Smart Transportation Insights
The intelligent transportation systems segment accounted for the largest market share of 29.4% in 2025. The growing number of vehicles in urban areas and increasing traffic congestion are driving the adoption of advanced traffic management technologies. Intelligent transportation systems help optimize traffic flow, reduce travel delays and emissions, and improve overall transportation efficiency. They also enable transportation authorities and public safety agencies to monitor road conditions and respond more quickly to accidents and emergencies. In addition, governments worldwide are investing in intelligent transportation infrastructure to enhance road safety, improve transportation system performance, and reduce the environmental impact of mobility, supporting continued segment growth.
The parking management segment is projected to grow at the fastest CAGR of 37.9% from 2026 to 2033. Growth is being driven by the increasing need to optimize parking space utilization, reduce congestion and emissions, lower operating costs, and improve convenience and safety for users. The rising number of vehicles in urban areas is intensifying parking challenges and placing additional pressure on transportation infrastructure. Consequently, smart city initiatives are increasingly incorporating intelligent parking solutions that enable real-time space monitoring, efficient parking management, and improved traffic circulation, thereby supporting segment expansion.
Smart Governance Insights
The smart infrastructure segment dominated the smart cities industry, accounting for the largest share of 27.6% in 2025. The growing focus of governments on digital transformation and modernization of public and administrative infrastructure is driving demand for smart infrastructure solutions across sectors such as BFSI, healthcare, retail, manufacturing, and food and beverage. Governments are increasingly investing in connected infrastructure to support digital economic development, improve service delivery, and strengthen operational efficiency. In addition, the development of regulatory frameworks for emerging digital financial services, payment systems, and related technologies is supporting the modernization of financial infrastructure and contributing to segment growth.
The smart lighting segment is expected to grow at the fastest CAGR of 31.5% from 2026 to 2033. Smart lighting systems enable cities to improve energy efficiency, reduce electricity and maintenance costs, and remotely monitor lighting infrastructure. Beyond illumination, connected lighting networks can serve as a foundation for applications such as traffic management, public safety, environmental monitoring, smart parking, and wireless connectivity. Technological advancements in LED and OLED lighting, along with growing interest in human-centric lighting solutions, are further supporting the adoption of smart lighting across urban environments.
Smart Healthcare Insights
The medical devices segment dominated the smart cities industry, accounting for a share of 56.6% in 2025, driven by the increasing integration of connected medical devices into urban healthcare infrastructure. These devices enable real-time health monitoring, early diagnosis, and timely medical intervention, helping reduce the burden on healthcare facilities while improving patient outcomes. Governments and urban planners are increasingly incorporating smart healthcare solutions into broader smart city initiatives to enhance the quality of life, reduce healthcare delivery costs, and address the growing demand for medical services in densely populated urban areas. This strong focus on technology-enabled healthcare, combined with advancements in connected medical devices, is supporting the segment's leading position in the market.
The systems & software segment is projected to grow at the fastest CAGR of 29.7% from 2026 to 2033. Growth is primarily driven by the increasing demand for the integration of electronic health records (EHRs), remote diagnostics, and AI-based clinical decision support systems. These solutions help healthcare providers streamline workflows, improve operational efficiency, and enable timely interventions and more accurate diagnoses. As urban populations continue to expand and healthcare infrastructure becomes increasingly digitized, demand for intelligent systems that support patient management, data integration, and healthcare delivery is expected to increase. This trend is likely to accelerate the adoption of advanced software-driven healthcare solutions across smart cities.
Smart Utilities Insights
The energy management segment accounted for the largest market share of 27.2% in 2025. Rising energy demand and the growing need for efficient power management are driving the adoption of advanced solutions such as virtual power plants. These systems leverage artificial intelligence (AI), machine learning, and IoT to optimize energy generation, distribution, and consumption while improving grid reliability and operational efficiency. In addition, leading market participants are strengthening their R&D capabilities to develop advanced energy management and analytics solutions. The integration of emerging technologies, including blockchain, is further supporting the development of secure, decentralized, and data-driven energy systems, contributing to the segment’s continued expansion.
The waste management segment is projected to register a considerable CAGR of 28.1% from 2026 to 2033. Growing urban populations and increasing waste volumes are encouraging municipalities to adopt technology-enabled waste management solutions, including smart garbage bins and connected monitoring systems. Governments are increasingly collaborating with system integrators, technology providers, distributors, and OEMs to implement city-level waste management projects. IoT-enabled bins equipped with fill-level sensors can provide real-time information on waste levels, enabling optimized collection schedules and reducing unnecessary collection trips. Mobile applications and centralized monitoring platforms further improve operational visibility and user convenience. The deployment of smart waste management solutions in high-traffic locations is expected to support continued segment growth.
Regional Insights
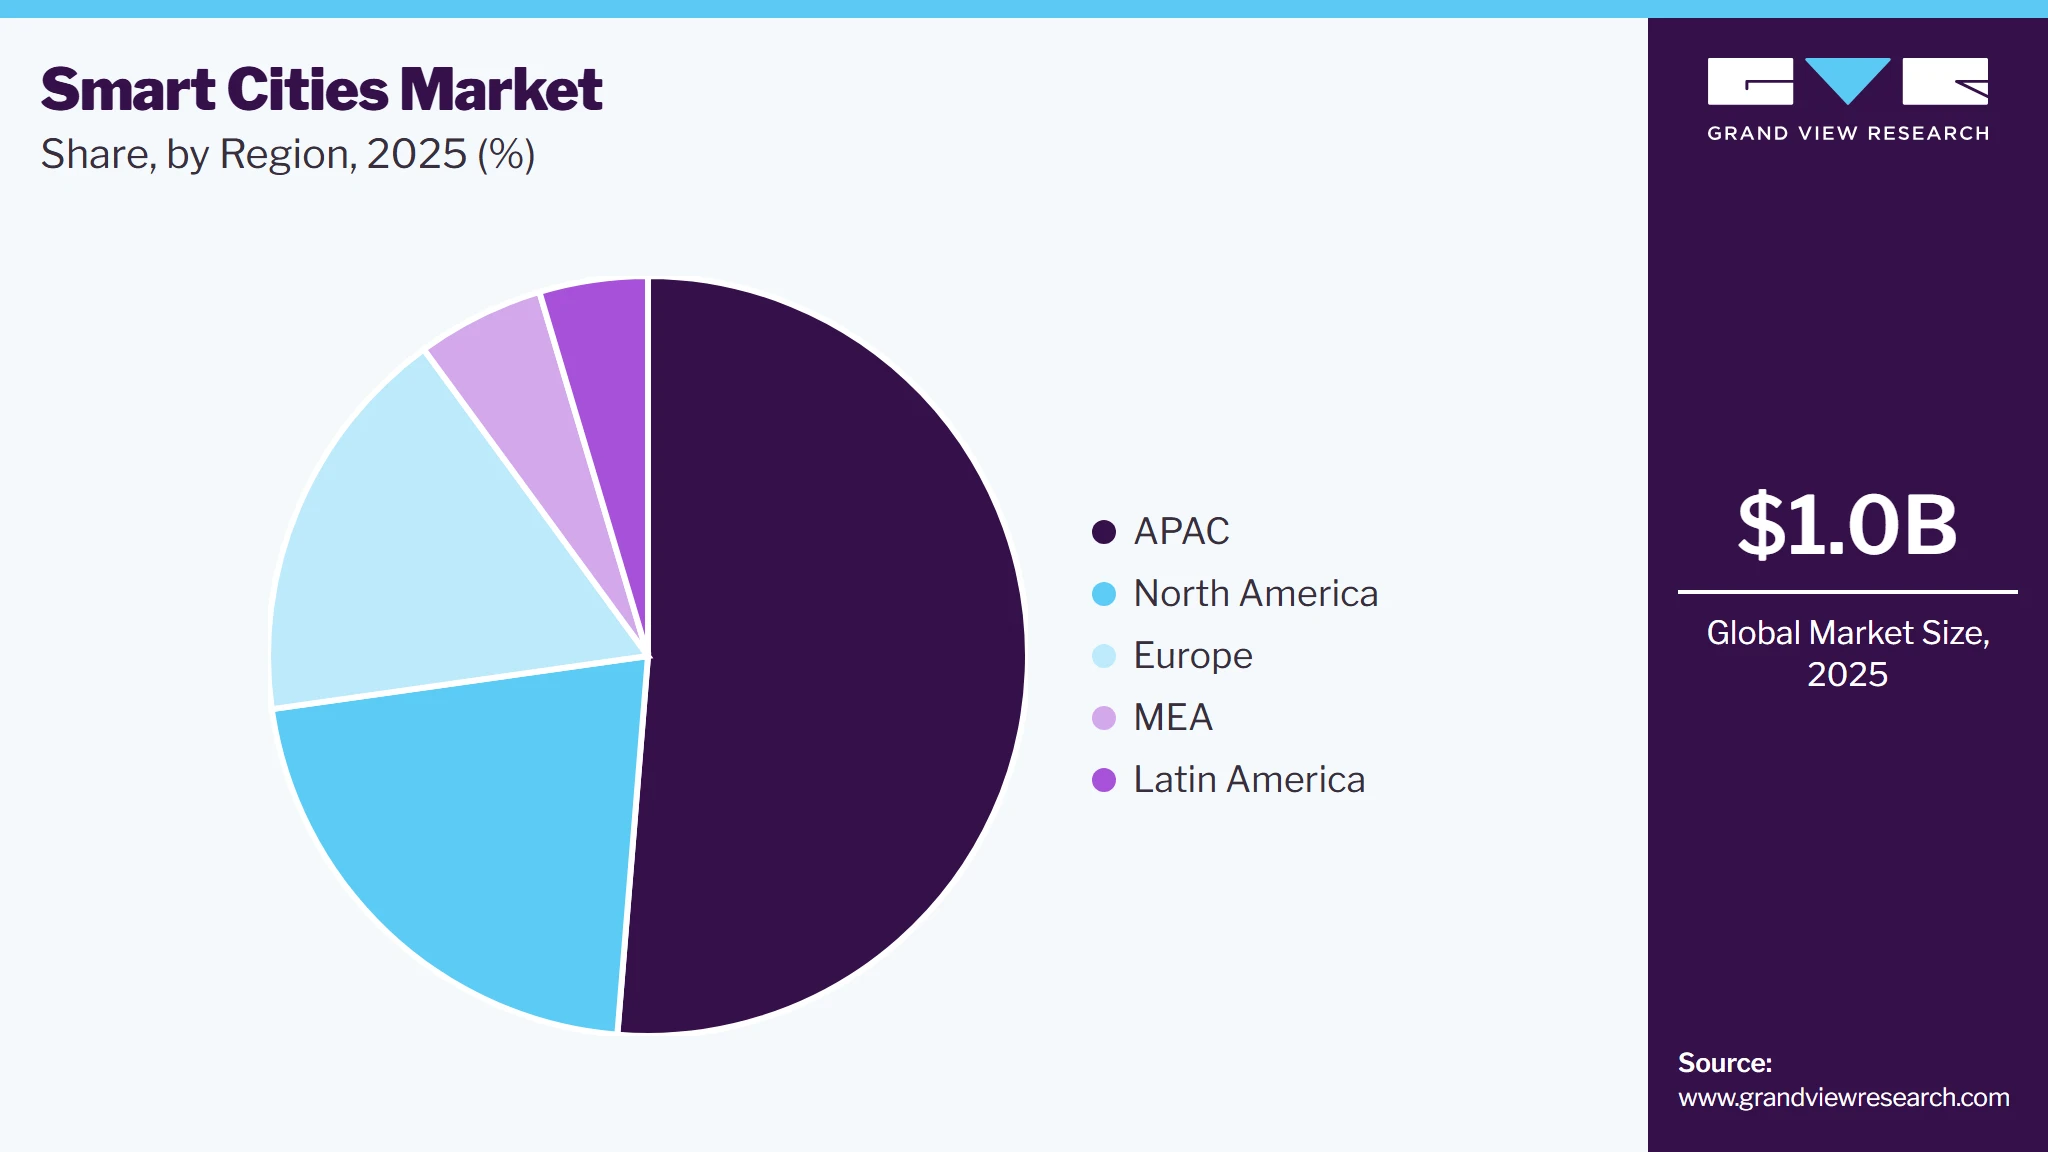
Asia Pacific accounted for the largest share of the global smart cities market, representing 51.3% of total revenue in 2025. The region’s strong market position is supported by rapid urbanization and the growing demand for sustainable and efficient urban development solutions. The increasing adoption of energy-efficient buildings and green infrastructure is encouraging cities across APAC to adopt more environmentally sustainable designs. Additionally, the expansion of smart healthcare solutions, including digital health platforms and AI-powered diagnostics, is enhancing healthcare accessibility in densely populated urban areas. Government initiatives promoting smart mobility, including electric vehicles and autonomous transportation systems, are also supporting the continued development of smart cities across the region.
 To learn more about this report, Download Free Sample Report
China’s smart cities market is experiencing rapid growth, driven by ambitious urban development policies and substantial infrastructure investments. Government initiatives, including the New Infrastructure Plan, are accelerating the deployment of smart transportation, energy management, surveillance, and other digital urban systems. Public-private partnerships are also becoming increasingly important in expanding smart city technologies across both tier-1 and tier-2 cities. The convergence of government policies, technological advancements, and infrastructure investment is strengthening China’s role in the global market.
North America Smart Cities Market Trends
North America accounted for 21.5% of the global smart cities industry in 2025, driven by the region’s strong focus on urban innovation and early adoption of advanced smart city technologies. Key segments, including intelligent transportation systems, energy-efficient utilities, public safety solutions, and digital governance platforms, are witnessing significant development. The widespread integration of artificial intelligence (AI), the Internet of Things (IoT), 5G connectivity, and cloud computing enables cities to enhance service delivery, optimize resource utilization, and improve the overall quality of urban life. These technological advancements are further strengthening North America’s position in the global market.
The U.S. smart cities market dominated North America, with a revenue share of 80.1% in 2025, driven by its strong emphasis on technological innovation, digital infrastructure development, and sustainable urban growth. The presence of established technology companies, combined with a dynamic startup ecosystem, is accelerating the deployment of advanced smart city solutions across transportation, energy management, and urban planning. In addition, growing efforts to enhance climate resilience and achieve carbon-neutrality goals are encouraging cities to adopt green technologies, energy-efficient systems, and integrated infrastructure. These factors are contributing to the continued market expansion.
Europe Smart Cities Market Trends
The Europe smart cities industry is projected to grow at a CAGR of 30.1% from 2026 to 2030. Growth across the region is being supported by strong policy initiatives and funding from the European Union, including programs such as the European Green Deal and Horizon Europe, which are promoting substantial investments in urban innovation, digitalization, and sustainability. High levels of public awareness and civic engagement are also encouraging the adoption of e-governance platforms and citizen-centric smart services. Furthermore, collaboration among government institutions, research organizations, and private-sector companies is creating robust innovation ecosystems that are accelerating the development and deployment of smart city solutions across Europe.
The UK smart cities market is expected to witness significant growth of 27.4% from 2026 to 2033, supported by the increasing adoption of digital governance solutions and citizen-centric public services. Local authorities are increasingly using data analytics, connected platforms, and mobile technologies to provide real-time services and strengthen citizen engagement. The expansion of 5G networks is further improving connectivity and enabling the development of intelligent transportation networks and connected infrastructure. Additionally, growing investments in cybersecurity are helping cities address data protection and security requirements within increasingly connected urban environments. In addition, the expansion of smart housing initiatives and urban regeneration projects is transforming urban development and contributing to the long-term market growth.
Key Smart Cities Company Insights
Some of the key players operating in the market include Cisco Systems, Inc. and Honeywell International Inc.
-
Cisco Systems, Inc. is a global leader in networking and IT infrastructure, providing innovative solutions that form the backbone of Smart Cities. The company enables cities to become more connected and efficient through its smart network architecture, IoT platforms, and cybersecurity solutions. Cisco's Smart+Connected Communities initiative focuses on transforming urban infrastructure by offering intelligent solutions for transportation, energy management, public safety, and digital governance. By leveraging cutting-edge technologies such as edge computing, AI, and 5G, Cisco helps cities gather and analyze real-time data to make informed decisions, improving citizen services and operational efficiency.
-
Honeywell International Inc. is a conglomerate known for its strong presence in industrial automation, smart building technologies, and environmental solutions, all crucial components of smart cities. Honeywell provides integrated systems that enhance building performance, energy efficiency, public safety, and urban mobility. Its offerings include smart thermostats, security systems, and building management tools, all designed to improve comfort, sustainability, and cost-effectiveness in urban environments. With a deep focus on digital transformation and operational intelligence, Honeywell plays a pivotal role in shaping the future of the smart cities industry.
UrbanFootprint, Inc. and Quantela, Inc. are some of the emerging participants in the smart cities market.
-
UrbanFootprint, Inc. is a data intelligence and urban planning company that empowers governments, utilities, and enterprises to build more sustainable and resilient cities. The company provides an advanced location intelligence platform that combines environmental, demographic, and infrastructure data to support smarter urban decision-making. UrbanFootprint’s solutions help cities optimize transportation, land use, energy, and disaster response strategies, using data-driven insights to improve public services and resource allocation. With a strong focus on sustainability and climate resilience, UrbanFootprint enables smart cities to plan future growth more effectively and equitably.
-
Quantela, Inc. is a digital infrastructure and smart cities automation company that delivers AI-powered solutions for urban management and public service efficiency. Its flagship platform, Atlantis, provides centralized, data-driven control for city operations such as traffic, waste management, public safety, and street lighting. Quantela partners with municipalities and governments globally to create intelligent urban ecosystems that are more efficient, responsive, and sustainable. By offering outcome-based solutions and leveraging predictive analytics, the company helps cities optimize resources, reduce operational costs, and enhance citizen experiences in real time.
Key Smart Cities Companies
The following key companies have been profiled for this study of the smart cities market.
Competitive Benchmarking
Operating Strategies
Operating Strategies
Operating Strategies
Mature Players: Cisco Systems, Inc.; NEC Corporation; Huawei Technologies Co., Ltd.; Honeywell International Inc.
- Mature players focus on government contracts, integrated infrastructure projects, and large-scale smart city deployments.
- They invest heavily in AI, IoT, cloud, and digital twin technologies to expand smart city capabilities.
- Strong financial strength, global presence, and technical expertise support large-scale project execution.
- Broad solution portfolios and established government relationships improve market positioning and adoption rates.
- Complex organizational structures can slow innovation and customized solution deployment.
- High implementation costs and reliance on government funding may limit expansion in cost-sensitive regions.
Emerging Players: UrbanFootprint, Inc.; Quantela, Inc.
- Emerging players focus on niche applications such as urban analytics and AI-based city management solutions.
- They use agile models and partnerships to scale solutions across developing urban markets.
- These companies provide flexible and customized solutions with faster deployment capabilities.
- Strong expertise in AI analytics and cloud platforms improves operational efficiency for cities.
- Limited financial strength and lower brand recognition restrict large-scale project opportunities.
- Dependence on partnerships and external funding can create scalability challenges.
Recent Developments
-
In March 2025, Huawei and the Barcelona City Council announced a strategic collaboration at MWC Barcelona 2025 to support the development of smart city initiatives in Barcelona. The agreement focuses on key areas, including the City Command Center, Smart Buildings, Connectivity, Green Energy, and ICT Talent Development. The partnership, supported by Barcelona Activa’s IT Academy, aims to strengthen the city’s digital infrastructure and accelerate the growth of its smart cities industry.
-
In February 2025, IBM announced a collaboration with C40 Cities through its Sustainability Accelerator program to drive innovation in the Smart Cities sector. The initiative focuses on developing AI-driven solutions to enhance urban resiliency and tackle challenges faced by cities worldwide. This partnership aligns with the United Nations Sustainable Development Goal 11 and reflects IBM’s growing commitment to leveraging advanced technologies for smart cities.
-
In February 2025, Quantela Inc. announced a strategic partnership with Connected Kerb Inc. The partnership aims to optimize urban infrastructure for micromobility, Digital Out-of-Home (DOOH) advertising, IoT applications, and electric vehicle (EV) charging, helping cities across the U.S. create future-ready urban environments. This joint effort supports the development of smart cities.
Smart Cities Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.0 trillion
Estimated market size in 2026
USD 1.3 trillion
Projected market size by 2033
USD 8.8 trillion
Growth rate
CAGR of 31.9% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD trillion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market position analysis, competitive landscape, growth factors, and trends
Segments covered
Application, smart governance, smart utilities, smart transportation, smart healthcare, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Germany; UK; France; Italy; Spain; Russia; Nordic Region; China; Japan; India; Australia; ASEAN, Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
Cisco Systems, Inc.; Microsoft Corporation; International Business Machines Corporation (IBM); Huawei Technologies Co., Ltd.; Honeywell International Inc.; Schneider Electric SE; Siemens AG; Hitachi, Ltd.; GE Vernova Inc.; NEC Corporation; UrbanFootprint, Inc.; Quantela, Inc.
Customization scope
Free report customization (equivalent to up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Smart Cities Market Report Segmentation
This report forecasts revenue growth at the global, regional & country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global smart cities market report based on application, smart governance, smart utilities, smart transportation, smart healthcare, and region:
-
Application Outlook (Revenue, USD Trillion, 2021 - 2033)
-
Smart Governance
-
City Surveillance
-
C.C.S.
-
E-governance
-
Smart Lighting
-
Smart Infrastructure
-
-
Smart Building
-
Environmental Solution
-
Smart Utilities
-
Energy Management
-
Water Management
-
Waste Management
-
Meter Data Management
-
Distribution Management System
-
Substation Automation
-
Other Smart Utilities Solutions
-
-
Smart Transportation
-
Intelligent Transportation System
-
Parking Management
-
Smart Ticketing & Travel Assistance
-
Traffic Management
-
Passenger Information
-
Connected Logistics
-
Other Smart Transportation Solutions
-
-
Smart Healthcare
-
Medical Devices
-
Systems & Software
-
-
Smart Public Safety
-
Smart Security
-
Smart Education
-
-
Governance Outlook (Revenue, USD Trillion, 2021 - 2033)
-
City Surveillance
-
C.C.S.
-
E-governance
-
Smart Lighting
-
Smart Infrastructure
-
-
Utilities Outlook (Revenue, USD Trillion, 2021 - 2033)
-
Energy Management
-
Water Management
-
Waste Management
-
Meter Data Management
-
Distribution Management System
-
Substation Automation
-
Other Smart Utilities Solutions
-
-
Transportation Outlook (Revenue, USD Trillion, 2021 - 2033)
-
Intelligent Transportation System
-
Parking Management
-
Smart Ticketing & Travel Assistance
-
Traffic Management
-
Passenger Information
-
Connected Logistics
-
Other Smart Transportation Solutions
-
-
Smart Healthcare Outlook (Revenue, USD Trillion, 2021 - 2033)
-
Medical Devices
-
Systems & Software
-
-
Regional Outlook (Revenue, USD Trillion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Russia
-
Nordic Region
-
Eastern Europe
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
ASEAN
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Scope & Research Methodology
The market study on the smart cities market has been developed using a structured, multi-stage research framework designed to ensure accuracy, consistency, and reliability of the market size estimates and forecasts.
The smart cities market is segmented into two major segments, namely, application and region. In the first level, the market has been split by application, as follows:
● Smart Governance: Revenue is generated through government contracts for digital administration platforms such as e-governance portals, citizen service apps, digital identity systems, and AI-enabled decision-support systems. Monetization comes from project implementation fees, cloud hosting, and recurring maintenance or SaaS subscriptions funded by public sector digital transformation budgets.
● Smart Building: Revenue is generated from environmental monitoring and sustainability platforms tracking air quality, emissions, noise, and climate indicators. Monetization includes sensor deployment contracts, analytics subscriptions, and ESG reporting tools funded through government climate programs, green bonds, and sustainability initiatives.
● Smart Utilities: Revenue comes from the digitization of utilities such as smart grids, water, gas, and waste systems. Vendors earn through large infrastructure contracts, IoT device deployment (smart meters and sensors), and recurring software revenues for monitoring, forecasting, and automated billing in partnership with utility providers.
● Smart Transportation: Revenue is generated from intelligent transport systems, including traffic management, smart ticketing, fleet tracking, and mobility-as-a-service platforms. Monetization includes system integration fees, SaaS analytics subscriptions, per-city deployment contracts, and revenue-sharing models with transport authorities.
● Smart Healthcare: Revenue is captured through connected healthcare systems such as telemedicine platforms, remote patient monitoring, emergency response integration, and urban hospital IoT networks. Monetization includes platform subscriptions, government healthcare digitization contracts, and partnerships with hospitals and insurers.
● Smart Public Safety: Revenue is derived from city emergency response systems, disaster management platforms, surveillance analytics, and incident detection tools. Providers earn via command-and-control system deployments, AI-based predictive safety solutions, and recurring monitoring and integration service contracts.
● Smart Security: Revenue is generated from cybersecurity and physical security solutions protecting smart city infrastructure, including identity management, network security, and critical infrastructure protection. Monetization includes enterprise security subscriptions, managed security services, and government compliance-driven contracts.
● Smart Education: Revenue comes from digital education infrastructure such as smart classrooms, AI-based learning platforms, and connected campuses. Monetization includes government education digitization programs, LMS licensing, device provisioning contracts, and recurring SaaS subscriptions for learning analytics and content delivery.
Based on region, the market has been segmented into North America, Europe, Asia Pacific, Latin America, and Middle East & Africa:
● North America: The North America regional market includes the markets of the U.S. and Canada.
● Europe: The Europe regional market includes the markets of the U.K., Germany, France, Italy, Spain, Russia, the Nordic region, and the Eastern region.
● Asia Pacific: The Asia Pacific regional market includes the markets of China, India, Japan, Australia, ASEAN, and South Korea.
● Latin America: The Latin America market includes the markets of Brazil and Mexico.
● Middle East & Africa: The MEA regional market includes the markets of the UAE, Saudi Arabia, and South Africa
Estimation Model
Layer Name
Key Question
Description
Urban Infrastructure Layer
Which cities are relevant for smart city deployments?
Identify global cities and urban areas investing in digital infrastructure, mobility, sustainability, governance, and public services to define the total addressable market.
Technology Readiness Layer
Which cities can realistically deploy smart city solutions?
Filter the addressable city base across regions using digital readiness factors like broadband, IoT, cloud, 5G, smart utilities, data infrastructure, and e-governance to identify capable cities and define the reachable smart cities market.
Solution Adoption Layer
Which cities adopt smart solutions?
Apply adoption rates across smart city solutions such as transport, energy, water, buildings, public safety, waste management, and e-governance to identify active deployments.
Monetization Layer
How much revenue is generated?
Estimate annual per-city spending across IoT, software, sensors, connectivity, integration, consulting, and managed services, then multiply by active deployments to derive total market revenue.
Delivered Customizations
Client Request
Customization Delivered
Value Adds
Smart Transportation, Utilities & Urban Mobility Trends
Conducted a focused analysis of smart transportation systems, traffic management platforms, mobility-as-a-service (MaaS), smart grids, water and waste management systems, and IoT-enabled utility infrastructure, covering adoption trends, technology integration, and digital transformation across urban services.
Helps stakeholders identify high-growth urban infrastructure segments, evaluate efficiency and sustainability gains, and assess monetization opportunities in data-driven mobility and utility ecosystems.
Smart Governance, Public Services & Citizen Experience Adoption Trends
Evaluated digital governance platforms, including e-governance portals, digital identity systems, citizen engagement apps, AI-driven public service delivery, and integrated urban management dashboards, along with adoption maturity across regions and city tiers.
Provides insights into government digitization priorities, citizen engagement trends, and scalable platform opportunities for improving transparency, efficiency, and service delivery outcomes.
Smart City Infrastructure & Integrated Urban Intelligence Assessment
Assessed demand for integrated smart city platforms combining IoT networks, cloud-based urban data systems, AI analytics, surveillance and public safety infrastructure, and cross-domain city operating systems, along with interoperability, cybersecurity, and data governance challenges.
Supports investment and expansion strategies by identifying high-readiness cities, evaluating digital infrastructure maturity, and highlighting opportunities for unified urban intelligence platforms enabling long-term scalable growth.
Frequently Asked Questions About This Report
The global smart cities market was valued at USD 1.0 trillion in 2025 and is expected to reach USD 1.3 trillion in 2026.
The global smart cities market is expected to grow at a compound annual growth rate of 31.9% from 2026 to 2033, reaching USD 8.8 trillion by 2033.
Asia Pacific dominated the global market with a revenue share of over 51% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The intelligent transportation system segment held the largest revenue share of 29.4% in 2025, while the other smart ticketing & travel assistance segment is the fastest-growing segment.
Some key players operating in the smart cities market include Cisco Systems, Inc., Microsoft, International Business Machines Corporation (IBM), Huawei Technologies Co., Ltd., Honeywell International Inc., Schneider Electric, Siemens, Hitachi, Ltd., GE Vernova Inc., NEC Corporation, and UrbanFootprint, Inc.
The growing urbanization, need for efficient management and utilization of resources, public safety concerns, and increasing demand for a healthy environment with efficient energy consumption are anticipated to be the key driving factors for the growth of the smart cities market.
The smart governance segment dominated with a revenue share of 28.4% in 2025.
The smart infrastructure segment led with a 27.6% revenue share in 2025, while smart lighting is the fastest-growing segment.
The energy management segment dominated with a revenue share of 27.2% in 2025, while the water management segment is the significant-growing area.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


