
- Home
- »
- Next Generation Technologies
- »
-
Agricultural Robots Market Size And Share Report, 2033GVR Report cover

Agricultural Robots Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Milking, Planting & Seeding Management), By Type (Dairy Robots, UAVs), By Offering (Hardware, Software), By Regional Outlook, And Segment Forecasts
Market Size, 2025
$18.5BMarket Estimate, 2026
$22.0BMarket Forecast, 2033
$81.9BCAGR, 2026–2033
20.6%Agricultural Robots Market Summary
The global agricultural robots market size was valued at USD 18.5 billion in 2025 and is projected to grow from USD 22.0 billion in 2026 to USD 81.9 billion by 2033, at a CAGR of 20.6% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 37.5% in 2025. This growth is driven by the growing demand for automated harvesting solutions. These factors are poised to witness remarkable growth in the coming years.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By offering: Hardware segment dominated the market, with a revenue share of 53.6% in 2025
- By type: Dairy robots segment dominated the market, with a revenue share of 38.0% in 2025
- By application: Milking segment held the largest revenue share in 2025
Regional Highlights
- Largest regional market: North America (37.5% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026–2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 18.5 Billion
- Estimated market size in 2026: USD 22.0 Billion
- Projected market size by 2033: USD 81.9 Billion
- CAGR (2026–2033): 20.6%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
These factors are poised to witness remarkable growth in the coming years. As per United Nations projections, the global population is anticipated to grow to 8.6 billion by 2033 and 9.8 billion by 2050. This demographic trend will significantly pressure traditional food production methods to ensure food security.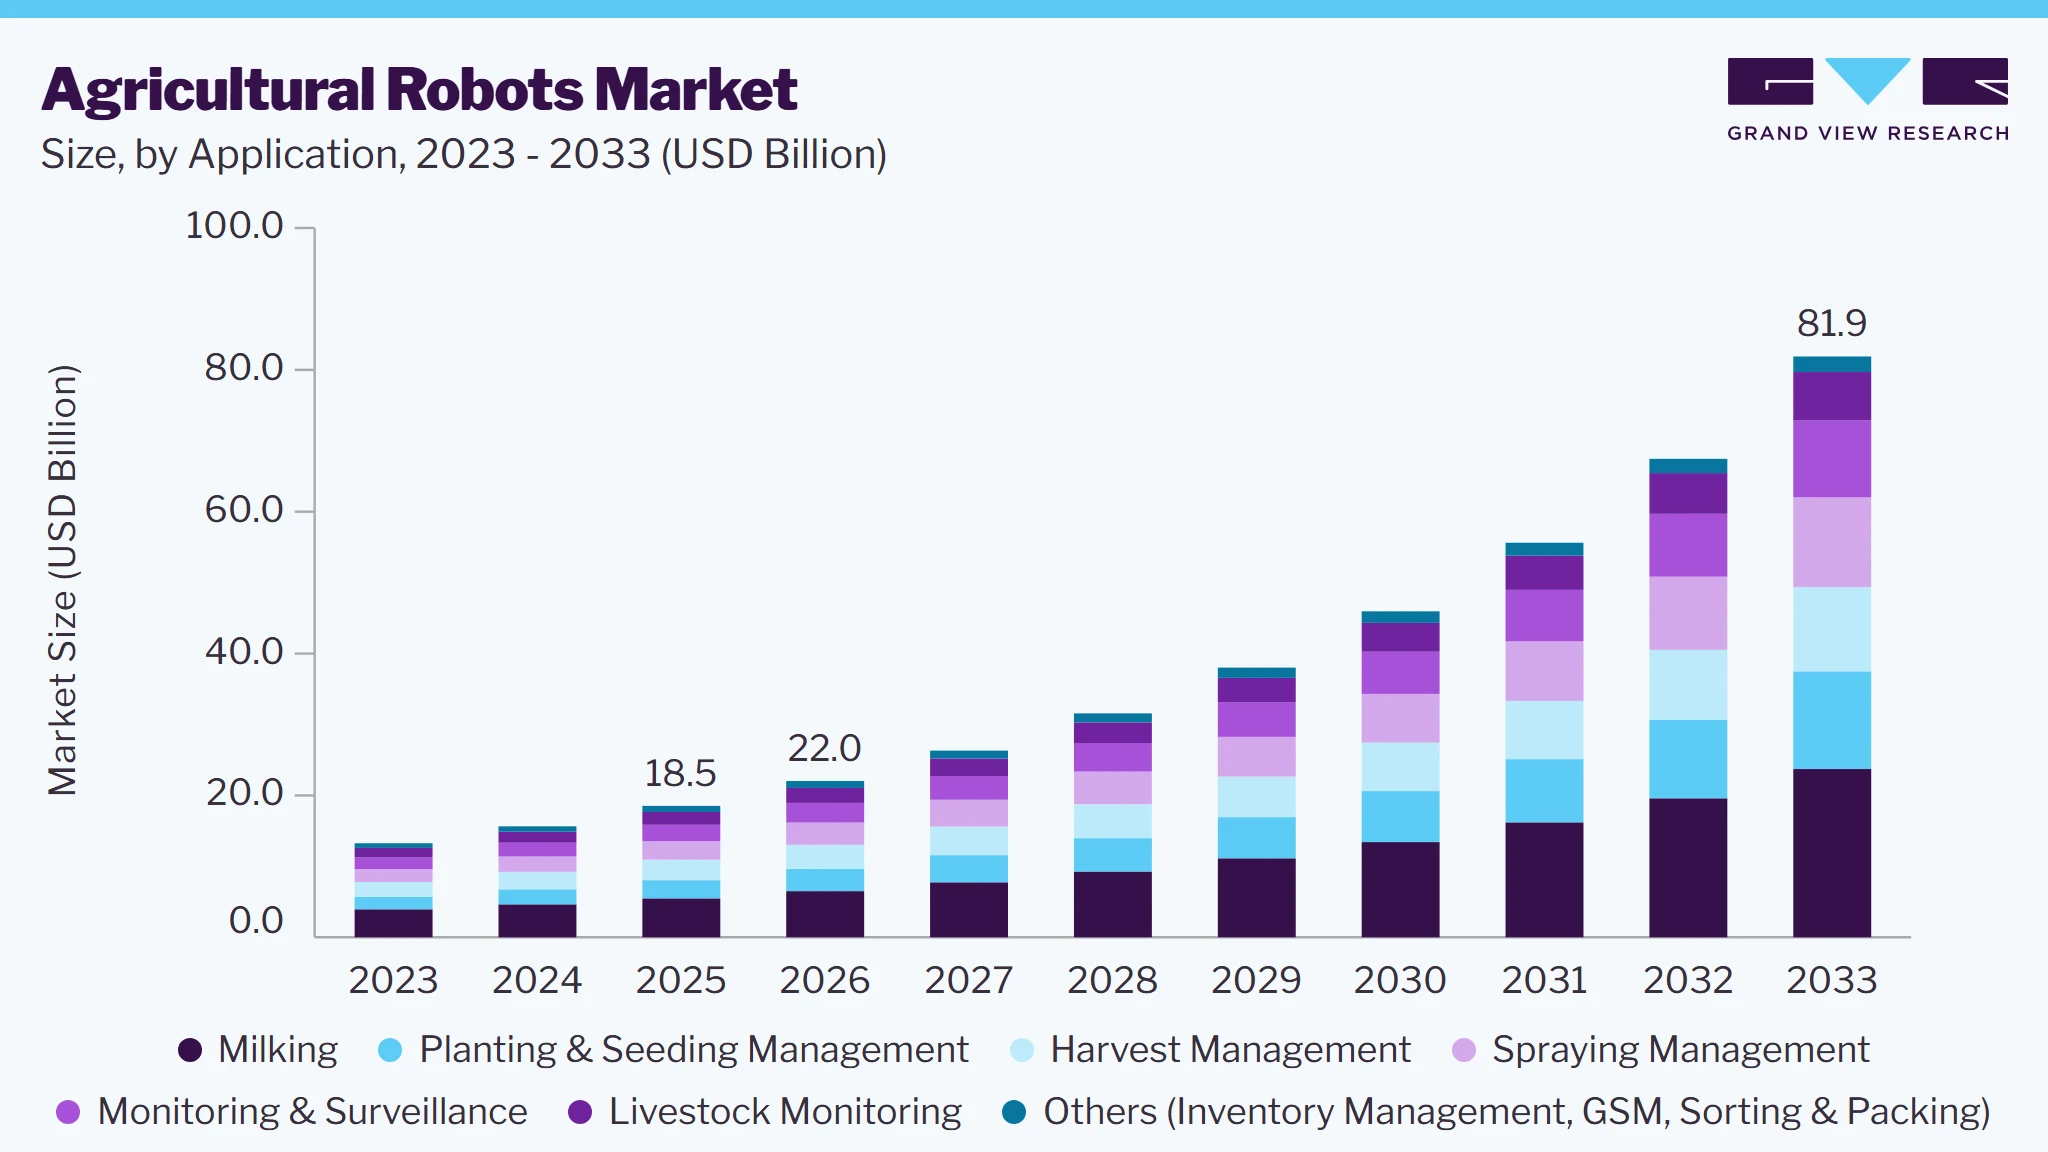 To learn more about this report, Download Free Sample Report
Agricultural robots and drones are emerging as game-changers, offering precision and optimization capabilities that significantly enhance farming practices. Further, the growing population and migration of young individuals from rural to urban areas has resulted in fewer available farm laborers. To overcome this, agricultural robots are adopted to fill the labor gap by automating tasks and reducing the dependency on manual labor. As the need for cost-effective and efficient labor solutions intensifies, the agricultural robots market is poised to expand significantly.
Agricultural robots, equipped with advanced sensors and AI-driven algorithms, are revolutionizing planting, harvesting, and monitoring crop health. These machines reduce labor costs, minimize resource wastage, and increase yield through precise management. On the other hand, drones provide farmers with real-time aerial views of their fields, allowing for early detection of issues like pests, diseases, or irrigation problems. With the ability to cover vast areas quickly, drones enable farmers to take proactive measures, resulting in higher crop yields. As the global population continues to grow, the demand for efficient and sustainable agriculture will intensify, making agricultural robots and drones indispensable tools for modern farming operations. Their ability to optimize farm management, reduce environmental impact, and boost productivity positions them at the forefront of agricultural innovation, driving substantial growth in this sector.
Furthermore, one notable driver is the increasing adoption of agriculture-based software accessible through smartphones. This digital transformation empowers farmers with real-time data and analytics, enabling them to make data-driven decisions about crop management, resource allocation, and overall farm optimization. The ease of use and accessibility of smartphone-based agricultural apps such as Cropin, Kisan Suvidha, Pusa Krishi, and Panorama are revolutionizing the industry by providing farmers, even in remote areas, with powerful tools to enhance productivity and reduce operational costs.
The adoption of agricultural robots can also contribute to the sustainability of farming practices. These robots are adaptable and can be used in both small-scale and large-scale farming operations, which allows farmers to expand their production capabilities to keep up with the demands of a larger population. For instance, Thorvald, a multi-functional, modular, & autonomous robot developed by Saga Robotics AS, can perform various operations such as precision spraying, livestock handling, UV-C light treatment, phenotyping, picking fruits & vegetables, in-field transportation, and cutting grass for forage, among others. This flexibility allows for cost-effective scalability for farmers of all sizes with diverse needs for their farms.
Market Dynamics
The agricultural robots market is witnessing rapid growth as labor shortages, rising agricultural wages, and the need to improve operational efficiency are accelerating the automation of farming activities. Robotic solutions for harvesting, planting, weeding, milking, crop monitoring, and autonomous field navigation are helping farmers perform labor-intensive tasks with greater precision, consistency, and productivity. The expansion of high-value crop cultivation, increasing demand for year-round agricultural output, and advancements in artificial intelligence, machine vision, and autonomous navigation technologies are further driving market adoption. Additionally, growing pressure to optimize input usage and reduce production costs is encouraging farmers to invest in robotic systems that enhance productivity while minimizing manual intervention.
The growing adoption of autonomous farm equipment is driving growth in the agricultural robots market by accelerating the transition from manually operated machinery to intelligent systems that perform farming activities with minimal human intervention. Agricultural producers increasingly seek equipment that can operate continuously with high precision while reducing reliance on constant operator supervision during planting, spraying, harvesting, and field monitoring. Autonomous tractors, robotic harvesters, automated seeders, and intelligent field vehicles create a strong demand for complementary robotic technologies that coordinate seamlessly across multiple farming operations. This shift toward autonomous production environments encourages greater investment in agricultural robotics to improve efficiency throughout the cultivation cycle. The expanding acceptance of self-operating machinery continues to strengthen long-term market development.
High acquisition costs of agricultural robots are a significant restraint on the agricultural robots market, limiting adoption among farms operating on constrained capital budgets. Advanced robotic systems integrate artificial intelligence, precision sensors, machine vision, navigation technologies, autonomous control systems, and sophisticated mechanical components, all of which substantially increase purchase prices compared with conventional agricultural equipment. Many farming businesses carefully evaluate capital expenditures over long investment cycles and often prioritize machinery replacement, irrigation infrastructure, or land improvements before committing to robotic automation. Long investment recovery periods create hesitation among producers who require immediate financial returns from equipment purchases. This financial burden slows the pace of robotic deployment across numerous agricultural operations.
The expansion of Robotics-as-a-Service (RaaS) business models is creating substantial opportunities in the agricultural robots market by making advanced robotic technologies accessible without requiring large upfront capital investments. Many agricultural producers prefer operational expenditure models that allow them to pay for robotic services based on seasonal usage, acreage covered, or completed farming tasks rather than purchasing expensive robotic equipment outright. This flexible commercial structure enables farms of varying sizes to adopt automation while preserving financial resources for other operational priorities. Service providers can continuously upgrade robotic platforms, ensuring customers benefit from the latest technological improvements without having to replace existing equipment. The wider availability of subscription-based robotic services contributes to market growth by accelerating adoption across a broader agricultural customer base.
Market Concentration & Characteristics
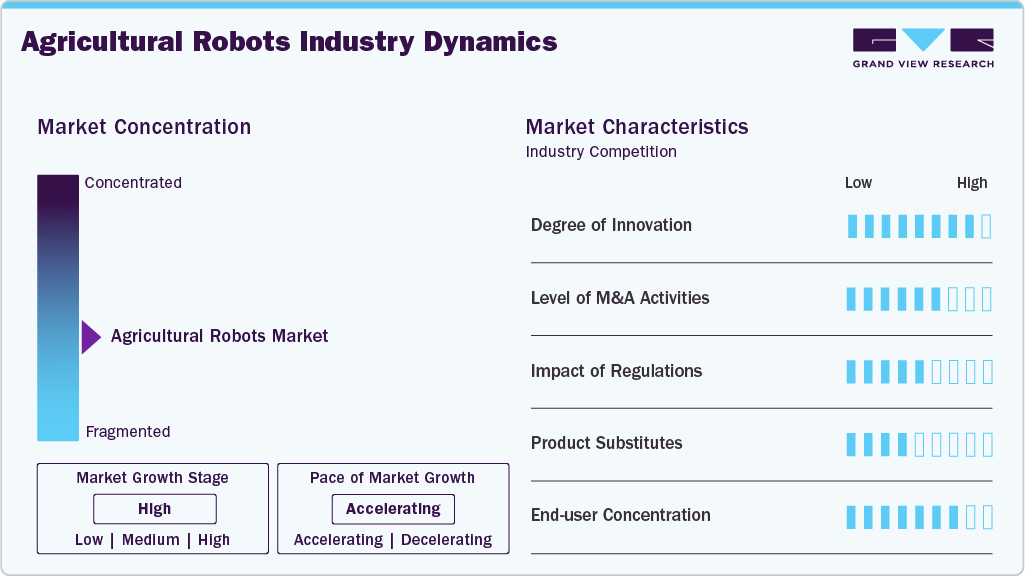
The agricultural robots market is moderately fragmented, with a mix of global agricultural equipment manufacturers, autonomous technology providers, AI-driven robotics companies, and emerging Agri-tech startups competing. The market is witnessing accelerating growth owing to increasing labor shortages, rising adoption of precision agriculture, and growing demand for autonomous farming operations. Companies are actively focusing on strategic partnerships, technology collaborations, and product expansion initiatives to strengthen their smart farming capabilities. Manufacturers are investing heavily in AI-powered navigation systems, robotic harvesting technologies, autonomous tractors, and drone-based crop monitoring solutions to enhance productivity, reduce resource wastage, and support sustainable farming practices.
 To learn more about this report, Download Free Sample Report
The market is characterized by a high degree of innovation supported by rapid advancements in AI, machine vision, IoT-enabled farm analytics, and autonomous mobility technologies. Merger and acquisition activities remain moderately high as established agricultural machinery companies increasingly acquire robotics and automation startups to expand digital agriculture portfolios and strengthen precision farming ecosystems. The threat from product substitutes remains relatively low because agricultural robots provide superior efficiency, accuracy, and labor optimization compared to conventional farming equipment. Regulatory influence remains moderate due to increasing government focus on sustainable agriculture, autonomous equipment safety standards, and precision pesticide application practices. Rising investments in smart agriculture infrastructure and AI-enabled farming technologies are expected to continue supporting the long-term, accelerating growth trajectory of the agricultural robots market.
Analyst Perspective
The agricultural robots market represents a structural shift in farming, where automation is becoming a necessity rather than a technological upgrade. Unlike conventional agricultural machinery, robotic systems are designed to make autonomous decisions, adapt to changing field conditions, and perform repetitive tasks with minimal human supervision. Competitive leadership will increasingly depend on the ability to deliver reliable autonomy, accurate perception systems, and crop-specific robotic solutions that demonstrate clear economic value under real-world farming conditions. As labor availability continues to decline and precision agriculture becomes more widespread, agricultural robots are expected to evolve from specialized equipment into essential operational assets that redefine how farms manage planting, crop care, harvesting, and livestock operations.
Application Insights
Based on application, the milking segment led the market with the largest revenue share of 29.6% in 2025. This automatic milking machine helps increase the milk yield and reduces workforce costs. Milking robots are designed to provide a comfortable and stress-free milking experience for cows. They use sensors and cameras to detect the presence of milking animals, clean their udders, attach the equipment, and monitor the milking process. This reduces the need for physical contact with the cows and helps minimize stress and discomfort during milking. In addition, agricultural robots can detect and address any health issues or abnormalities in the milk, promoting better cow welfare. This automatic milking machine would help increase the milk yield and reduce workforce costs.
The planting and seeding management application segment is anticipated to portray the highest CAGR of 26.0% over the forecast period. The segmental growth can be attributed to several key factors, such as technological advancements, which have played a crucial role in driving this growth. Agricultural robots have become more capable and efficient with the continuous development of robotics, artificial intelligence, and automation technologies. These advancements have increased the adoption and demand for such robots in farming operations.
Environmental concerns are another factor contributing to the growth of the agricultural robot market. There is a growing awareness of the need for sustainable farming practices and reducing the environmental impact of agriculture. Agricultural robots can help achieve these goals by enabling precise application of inputs, reducing chemical usage, and minimizing soil compaction. By adopting robotic planting and seeding systems, farmers can reduce their environmental footprint and contribute to more sustainable agricultural practices.
Type Insights
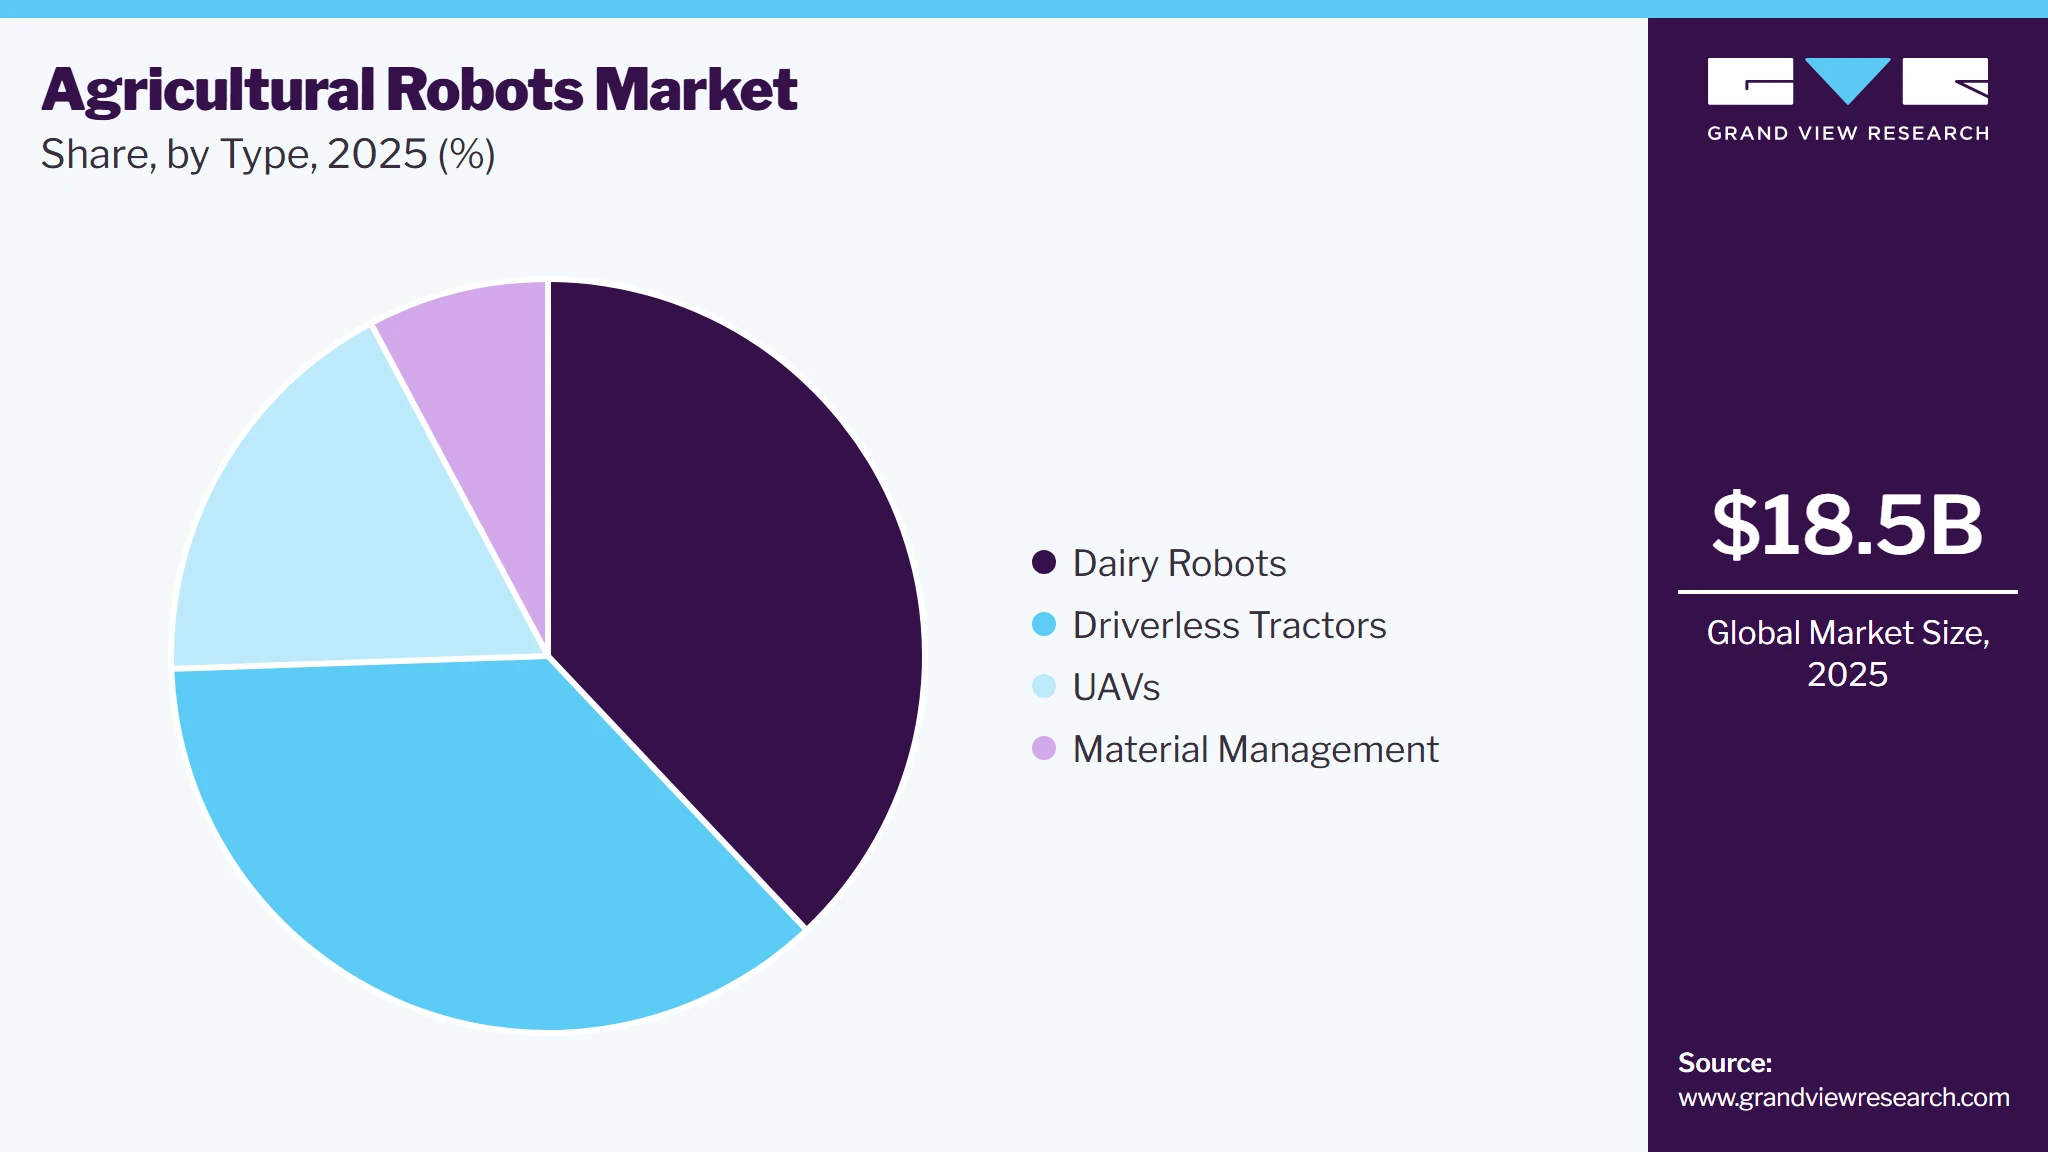
Based on type, the dairy robots segment led the market with the largest revenue share of 38.0% in 2025, driven by the increasing number of dairy farmers worldwide. As the demand for dairy products continues to rise globally, more farmers are entering the dairy industry to meet this growing consumer need. However, this surge in dairy farming has also brought challenges, such as the need for efficient and labor-saving solutions. For instance, in 2021, as per the data published by the International Dairy Federation (IDF), the global dairy sector comprises approximately 133 million dairy farms. Furthermore, the international dairy industry witnesses the annual trade of approximately 9% of global milk production.
 To learn more about this report, Download Free Sample Report
The UAV segment is expected to emerge as the fastest segment with a CAGR of over 24.4% over the forecast period. The increasing demand for UAVs in the market is driven by the need for precision agriculture, efficient pest management, and optimized crop spraying. These aerial robots equipped with advanced sensors and imaging capabilities enable farmers to monitor crop health, detect diseases, and assess yield potential, leading to timely action and resource optimization. Additionally, UAVs offer precise pest and weed management, reducing the use of harmful chemicals and promoting sustainable practices.
For instance, as per an industry expert, revealed that roughly 385 million individuals, with a notable concentration within the farming and agricultural labor force, encounter pesticide-related poisoning on an annual basis, resulting in 11,000 fatalities per year. It's noteworthy that among these tragic incidents, India bears the brunt, accounting for nearly 60% of the annual death toll, which amounts to approximately 6,600 deaths each year. The ability to navigate challenging terrains and operate in adverse conditions makes UAVs an ideal solution for crop spraying, especially during resource constraints. Overall, the adoption of UAVs in agriculture is revolutionizing the industry, providing farmers with greater efficiency, improved yields, and a sustainable approach to farming.
Offering Insights
Based on offering, the hardware segment led the market with the largest revenue share of 53.6% in 2025. The hardware segment plays a pivotal role in the agricultural robots market, serving as the backbone of these advanced farming solutions. It encompasses the physical components and machinery such as motors, and batteries that enable robots to perform various tasks in agricultural settings. Another factor contributing to the dominance of the hardware segment is the capital-intensive nature of agriculture robots components. Developing and manufacturing high-quality hardware requires substantial investments in research, development, and production. The hardware components are often complex and require advanced engineering expertise, precision manufacturing processes, and rigorous quality control measures. Consequently, established players such as CLAAS KGaA mbH, GEA Group with the financial resources and technical capabilities to invest in hardware development have a competitive advantage, leading to the dominance of the hardware segment.
The software segment is expected to grow at the fastest CAGR of 28.9% over the forecast period. One of the primary drivers behind the rapid growth of the software segment is the advancements in artificial intelligence (AI) and machine learning (ML) technologies. These technologies have revolutionized the capabilities of agriculture robots, allowing them to analyze vast amounts of data, make real-time decisions, and adapt to changing conditions. Software algorithms enable robots to identify and classify crops, detect diseases and pests, optimize irrigation and fertilization, and even predict crop yields. The integration of AI and ML in agriculture robots has led to increased productivity, resource efficiency, and cost savings, driving the rapid growth of the software segment.
Regional Insights
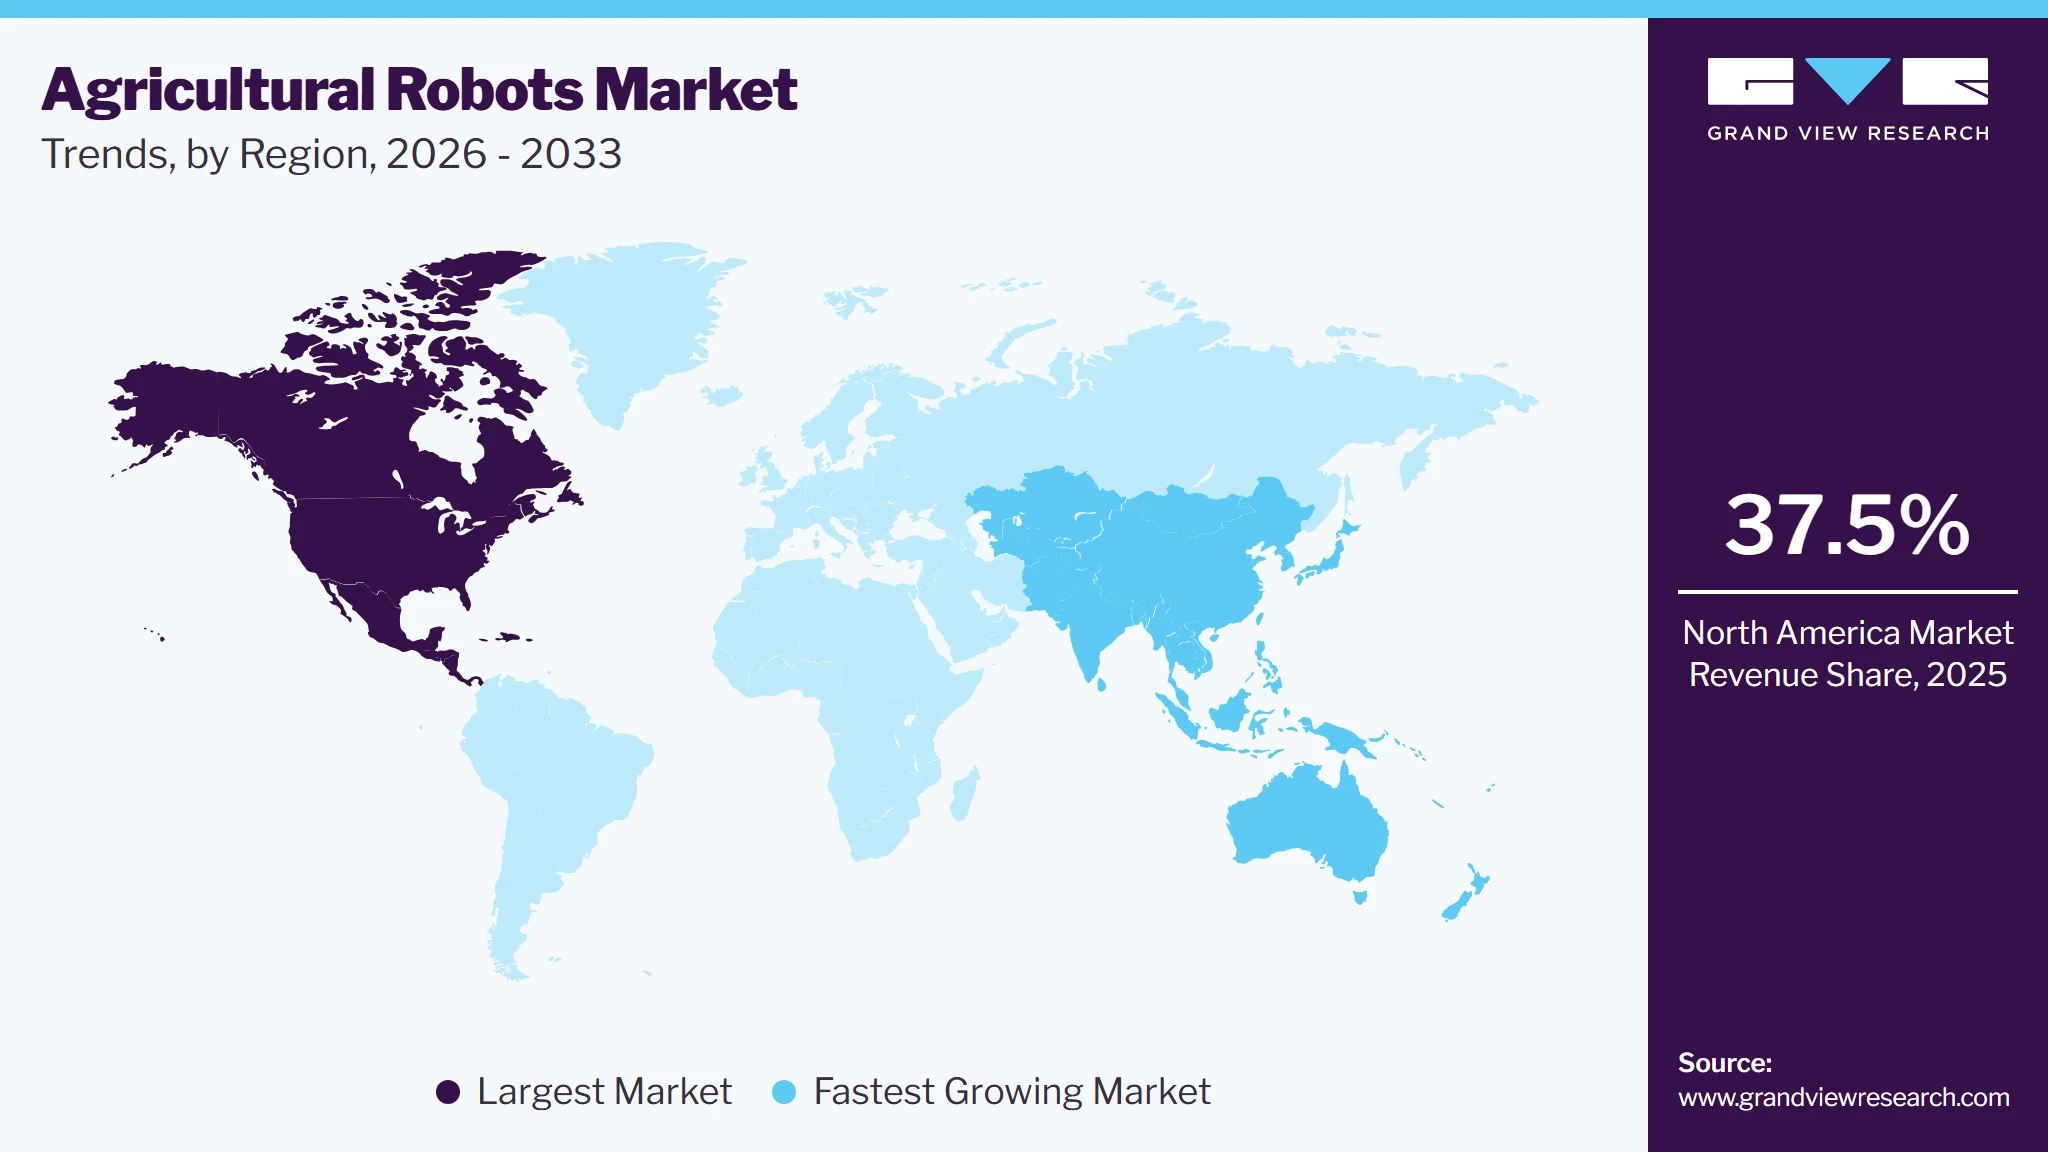
North America dominated the global agricultural robots market with the largest revenue share of 37.5% in 2025. and has become one of the most influential markets. One significant factor is the vast expanse of farmland in the region. For instance, as per the data published by the United States Agriculture Department in February 2022, the typical farm size for 2021 measured at 445 acres, marking a slight increase from the previous year's figure of 444 acres. North America boasts some of the world’s largest average farmland sizes, which can make manual management and monitoring a highly challenging and resource-intensive task. To address this challenge, North American farmers have been quick to embrace agricultural robots and automation technologies, seeking efficiency gains and improved crop yields.
 To learn more about this report, Download Free Sample Report
Moreover, the region benefits from a high level of access to advanced agricultural technologies. North America has a robust ecosystem of tech companies, research institutions, and innovation hubs focused on agriculture. This favorable environment fosters the development and adoption of cutting-edge agricultural robotics solutions. In addition, a strong commitment to sustainable and precision farming practices in North America has driven the demand for precision agriculture tools like autonomous tractors, drones, and robotic harvesters. As a result, North America continues to lead the agricultural robots market in terms of revenue, with its blend of extensive farmland and access to advanced technology driving substantial growth in the sector.
U.S. Agricultural Robots Market Trends
The agricultural robots market in the U.S. held the largest share in the North America region in 2025. The demand for agricultural robots in the U.S. is experiencing significant growth due to a combination of economic, technological, and environmental factors. One of the primary drivers is the persistent labor shortage faced by the agricultural sector. With fewer individuals willing to take on seasonal farm labor, farmers are increasingly turning to automation solutions to ensure that essential tasks, such as planting, harvesting, and crop monitoring, can be completed efficiently. Additionally, government support for agricultural innovation plays a significant role in fostering the growth of the agricultural robotics market. Various initiatives and funding programs encourage technology adoption in farming, providing financial assistance to farmers seeking to integrate robotics into their operations.
Asia Pacific Agricultural Robots Market Trends
Asia Pacific agricultural robots market is expected to achieve the fastest CAGR of 23.6% during the forecast period in the market. Technological advancements and innovation in countries like Japan, India, and China have led to the development of advanced robotics solutions for the agriculture sector. With a growing population and increasing food security concerns, the need for efficient farming practices is paramount. Agriculture robots offer a solution by automating labor-intensive tasks and improving crop yields. In addition, labor shortages and rising wages in the region make robotics an attractive investment for farmers. Strong government support and a diverse agricultural landscape further contribute to the region's potential for agriculture robot growth.
Bottom of FormKey Agricultural Robots Company Insights
Some key players operating in the market include CNH Industrial N.V., and AGCO Corporation, among others.
-
CNH Industrial N.V. is a multinational corporation engaged in the production and distribution of capital goods, primarily focusing on agriculture and construction equipment. The company operates through several key segments, including agriculture, construction, commercial vehicles, and powertrain. The agriculture segment encompasses the design and manufacturing of various agricultural machinery, such as tractors and combines, marketed under well-known brands like Case IH and New Holland Agriculture. The company's manufacturing footprint is extensive, with facilities located in North America, Europe, South America, and Asia.
DeLaval and Lely are some emerging market participants in the target market.
-
DeLaval is an emerging player specializing in dairy farming equipment and solutions. DeLaval offers a comprehensive range of dairy farming solutions, including milking equipment, farm management systems, cow comfort products, and feeding solutions. Key product categories include milking machines, cooling and storage systems, and herd management technologies like the DeLaval DelPro. The company focuses on enhancing milk production, animal welfare, and operational efficiency for dairy farmers.
Key Agricultural Robots Companies
The following key companies have been profiled for this study on the agricultural robots market.
-
AGCO Corporation
-
Autonomous Solutions, Inc.
-
BouMatic
-
CNH Industrial N.V.
-
CLAAS KGaA mbH
-
GEA Group Aktiengesellschaft
-
Harvest Automation, Inc.
-
Trimble, Inc.
-
Agrobot
-
Lely
-
DeLaval
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Deere & Company; AGCO Corporation; CNH Industrial; Kubota Corporation; Yanmar Holdings)
- Mature players focus on integrating autonomous robots with tractors, harvesters, and precision farming systems to automate planting, spraying, harvesting, and field monitoring operations. They invest in robotics, machine vision, AI, and GPS-guided navigation while expanding dealer networks and after-sales support to accelerate commercial adoption.
- Strong manufacturing capabilities, extensive agricultural machinery portfolios, and established relationships with commercial farms enable these companies to deliver reliable robotic solutions for large-scale farming. Their ability to integrate robots with existing farm equipment and digital agriculture platforms improves operational efficiency and builds customer confidence.
- Large-scale robotic systems require significant capital investment and longer purchasing cycles, particularly among small and medium-sized farms. Continuous software upgrades, maintenance requirements, and adaptation to diverse field conditions also increase operational complexity.
Emerging Players (Naïo Technologies; FarmWise; Ecorobotix; Burro; Small Robot Company)
- Emerging players focus on developing lightweight autonomous robots for precision weeding, crop monitoring, selective spraying, and harvesting that address specific agricultural tasks. They prioritize AI-powered perception systems, electric mobility, and modular robotic platforms that improve productivity while reducing labor dependence and chemical usage.
- Their specialized robotic designs enable greater precision, lower operating costs, and faster innovation for niche agricultural applications. Agile product development and a strong focus on automation technologies allow them to respond quickly to evolving precision farming requirements.
- Limited production scale, smaller distribution networks, and restricted financial resources can slow global expansion. Gaining widespread farmer acceptance and demonstrating long-term reliability across different crops and farming environments remain key challenges for commercialization.
Recent Developments
-
In February 2024, CNH Industrial N.V. announced that it had invested in Bem Agro, a Brazilian startup specializing in AI-driven agronomic mapping solutions. This investment aims to enhance the company's agricultural technology offerings, specifically in precision farming, by utilizing Bem Agro's aerial imaging capabilities to improve crop management, reduce herbicide use, and optimize resource allocation.
-
In April 2023, GEA Group Aktiengesellschaft strengthened its collaboration with Kerbl, a supplier of livestock farming products. This partnership aims to enhance the company’s market presence through the GEA Exclusive Program, which facilitates entry into new countries. By leveraging Kerbl's expertise and distribution network, GEA Group Aktiengesellschaft seeks to expand its agricultural solutions and support livestock farmers with innovative technologies.
Agricultural Robots Market Report Scope
Report Attribute
Details
Market size in 2025
USD 18.5 billion
Estimated market size in 2026
USD 22.0 billion
Projected market size by 2033
USD 81.9 billion
Growth rate
CAGR of 20.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share analysis, competitive landscape, growth factors, and trends
Segments covered
Offering, type, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
AGCO Corporation; Autonomous Solutions, Inc.; BouMatic; CNH Industrial N.V.; CLAAS KGaA mbH; GEA Group Aktiengesellschaft; Harvest Automation, Inc.; Trimble, Inc.; Agrobot, Lely; DeLaval
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Agricultural Robots Market Report Segmentation
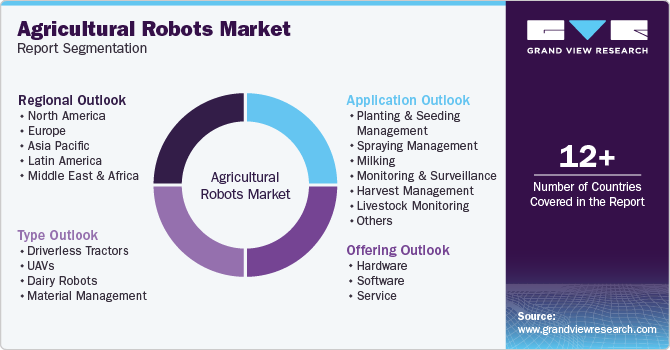
This report forecasts revenue growths at global, regional, as well as at country levels and offers qualitative and quantitative analysis of the market trends for each of the segments and sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global agricultural robots market based on application, type, offering, and region:
 To learn more about this report, Download Free Sample Report
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Planting & Seeding Management
-
Spraying Management
-
Milking
-
Monitoring & Surveillance
-
Harvest Management
-
Livestock Monitoring
-
Others
-
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Driverless Tractors
-
UAVs
-
Dairy Robots
-
Material Management
-
-
Offering Outlook (Revenue, USD Million, 2021 - 2033)
-
Hardware
-
Software
-
Service
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Latin America
-
Brazil
-
Mexico
-
-
Middle East & Africa
-
Research Methodology
The agricultural robots market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each agricultural robots segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment – Offering
Revenue capture definition
Hardware
The largest offering segment, capturing investment in autonomous tractors, robotic harvesters, milking robots, UAVs, robotic arms, navigation systems, cameras, LiDAR, sensors, and control units. Equipment manufacturers benefit from rising farm mechanization, labor shortages, and increasing demand for autonomous field operations.
Software
Commercial value is created through AI-powered farm management platforms, robotic navigation software, machine vision, fleet management systems, mission planning tools, and predictive analytics. Vendors increasingly monetize via subscription-based software, remote updates, and intelligent automation capabilities that continuously improve robot performance.
Services
Revenue opportunities arise from robot installation, system integration, preventive maintenance, calibration, operator training, technical support, and fleet management services. As robotic deployments expand, long-term service contracts are becoming an important source of recurring business for technology providers.
Segment – Type
Revenue capture definition
Driverless Tractors
This segment captures high-value spending on autonomous field machinery capable of performing tillage, planting, spraying, and hauling with minimal human intervention. Adoption is accelerating as large farms seek higher operational efficiency, improved field precision, and reduced dependence on skilled labor.
UAVs
Market demand is driven by drone-based solutions used for crop scouting, precision spraying, aerial mapping, plant health assessment, and field surveillance. Continuous advancements in AI, imaging technologies, and autonomous flight capabilities are expanding commercial opportunities across precision agriculture.
Dairy Robots
Value is generated through robotic milking systems, automated feeding equipment, manure-handling robots, and livestock-care solutions that improve dairy farm productivity. Dairy operators increasingly invest in automation to enhance herd health, optimize milk quality, and reduce labor-intensive daily operations.
Material Management
Commercial activity centers on robotic systems that automate the transport of harvested crops, feed, fertilizers, seeds, and other agricultural inputs throughout farm operations. These solutions improve workflow efficiency, minimize manual handling, and support continuous farm productivity during peak agricultural seasons.
Segment – Application
Revenue capture definition
Planting & Seeding Management
Market value is derived from robotic systems that perform highly accurate seed placement, optimize spacing, and navigate fields autonomously. Farmers invest in these technologies to improve crop establishment, reduce seed wastage, and enhance overall planting efficiency.
Spraying Management
Demand is fueled by robots capable of applying site-specific pesticides, herbicides, and fertilizers using AI-driven crop recognition and precision targeting. These systems help reduce chemical consumption, lower operating costs, and support environmentally sustainable farming practices.
Milking
The largest livestock-focused application is driven by robotic milking systems that automate milk collection, monitor animal health, and maintain consistent milking schedules. Dairy producers adopt these solutions to improve operational efficiency while enhancing animal welfare and the quality of milk production.
Monitoring & Surveillance
Commercial opportunities stem from autonomous robots equipped with cameras, thermal imaging, multispectral sensors, and AI analytics for continuous crop and livestock monitoring. These technologies provide early detection of diseases, pest infestations, equipment issues, and environmental changes, enabling faster management decisions.
Harvest Management
Investment is concentrated on robotic harvesting systems capable of identifying, picking, sorting, and handling crops with minimal crop damage. Increasing labor shortages and the need for faster harvesting cycles continue to strengthen adoption across high-value crop production.
Livestock Monitoring
Value is captured through robotic and autonomous systems that continuously track animal movement, feeding behavior, health conditions, reproductive activity, and environmental parameters. Real-time livestock intelligence enables producers to improve herd management, reduce disease outbreaks, and optimize farm productivity.
Others
This category includes robotic weeding, pruning, fruit thinning, greenhouse automation, autonomous irrigation, crop transportation, and agricultural research applications. Growing investment in AI-enabled specialty robots continues to expand automation opportunities across diverse farming operations.
Estimation Model
Layer No.
Layer
Question
Analysis
01
Farm Automation Opportunity Layer
Which agricultural activities can be automated using robots?
Identify labor-intensive and repetitive farm operations that are suitable for robotic automation, including planting, transplanting, harvesting, weeding, pruning, spraying, milking, crop scouting, fruit picking, and material handling. This layer evaluates where robotic systems can improve operational consistency, increase productivity, and address labor shortages while maintaining precision across diverse agricultural environments.
02
Robotic Capability Layer
What enables robots to perform agricultural tasks effectively?
Assess the technological capabilities required for autonomous farm operations, including machine vision, artificial intelligence, GPS navigation, robotic manipulators, autonomous mobility, sensor fusion, and edge computing. Successful deployment depends on the robot's ability to accurately identify crops, navigate varying field conditions, adapt to changing environments, and perform tasks with minimal human intervention.
03
Autonomous Farm Integration Layer
How are agricultural robots incorporated into farm production systems?
Analyze the integration of robotic platforms with precision farming technologies, farm management software, IoT networks, autonomous tractors, drones, irrigation systems, and harvesting equipment. Farmers increasingly utilize interconnected robotic solutions to coordinate multiple field operations, enable real-time monitoring, optimize resource allocation, and create highly automated agricultural workflows across the production cycle.
04
Robotics Ecosystem Value Layer
How is commercial value generated within the agricultural robotics market?
Evaluate revenue generation through robotic equipment sales, robotics-as-a-service (RaaS) models, software licensing, AI-based navigation platforms, maintenance contracts, fleet management solutions, remote monitoring services, and system upgrades. Additional value is created through improved harvesting efficiency, reduced labor dependency, enhanced crop quality, lower operating costs, and recurring revenues from digital services that support autonomous agricultural operations over the equipment lifecycle.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Autonomous Crop Care & Labor Replacement Trends
Conducted a focused analysis of agricultural robot deployment for autonomous weeding, pruning, thinning, fruit picking, milking, and greenhouse operations across high-value crops and livestock farms, focusing on labor substitution and operational continuity.
Helps stakeholders identify high-impact automation opportunities, evaluate labor-saving technology adoption, and assess commercialization potential in autonomous agricultural operations.
AI Vision, Robotic Navigation & Selective Harvesting Adoption Trends
Evaluated adoption trends for computer vision-enabled robots, autonomous navigation systems, robotic arms, and machine learning algorithms supporting crop identification, maturity assessment, selective harvesting, and precision field operations.
Provides insights into emerging robotic capabilities, technology differentiation opportunities, and commercially attractive solutions that improve harvesting accuracy and crop quality.
Robotic Farm Operations & Autonomous Fleet Management Opportunity Assessment
Assessed demand for multi-robot coordination platforms, robotics fleet management software, remote diagnostics, autonomous charging systems, and Robotics-as-a-Service (RaaS) models, along with challenges related to interoperability, capital investment, field variability, and operator training.
Supports investment and expansion strategies by identifying scalable robotics deployment models, evaluating automation readiness, and strengthening long-term growth opportunities in autonomous farm ecosystems.
Frequently Asked Questions About This Report
The global agricultural robots market size was estimated at USD 18.5 billion in 2025 and is expected to reach USD 22.0 billion in 2026.
The global agricultural robots market is expected to grow at a compound annual growth rate of 20.6% from 2026 to 2033 to reach USD 81.9 billion by 2033.
North America dominated with 37.5% revenue share in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The dairy robots segment led with an 38.0% revenue share in 2025, while UAVs segment is the fastest-growing segment.
The milking held the largest share (over 29%), while planting & seeding management segment is the fastest-growing segment.
The hardware segment led with a 53.6% revenue share in 2025, while software segment is the fastest-growing segment.
Key players operating in the agricultural robots market include AGCO Corporation; Autonomous Solutions, Inc.; BouMatic; CNH Industrial N.V.; CLAAS KGaA mbH; GEA Group Aktiengesellschaft; Harvest Automation, Inc.; Trimble, Inc.; Agrobot, Lely; DeLaval.
Key factors include the growing demand for automated harvesting solutions, growing adoption of autonomous farm equipment, and expansion of Robotics-as-a-Service (RaaS) business models.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


