
- Home
- »
- Agrochemicals & Fertilizers
- »
-
Agricultural Surfactants Market Size, Share Report 2026-2033GVR Report cover

Agricultural Surfactants Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Non-ionic, Anionic), By Substrate (Synthetic, Bio-based), By Crop Type, By Application (Herbicides, Pesticides), By Region, And Segment Forecasts
Market Size, 2024
$1.5BMarket Estimate, 2026
$1.6BMarket Forecast, 2033
$2.3BCAGR, 2025–2033
5.1%Agricultural Surfactants Market Summary
The global agricultural surfactants market size was valued at USD 1.5 billion in 2025 and is projected to grow from USD 1.6 billion in 2026 to USD 2.3 billion by 2033, growing at a CAGR of 5.1% from 2026 to 2033. Asia Pacific accounted for 33.4% of the global market revenue in 2025, making it the largest regional market. The market is primarily driven by the growing demand for crop protection products in agriculture worldwide.
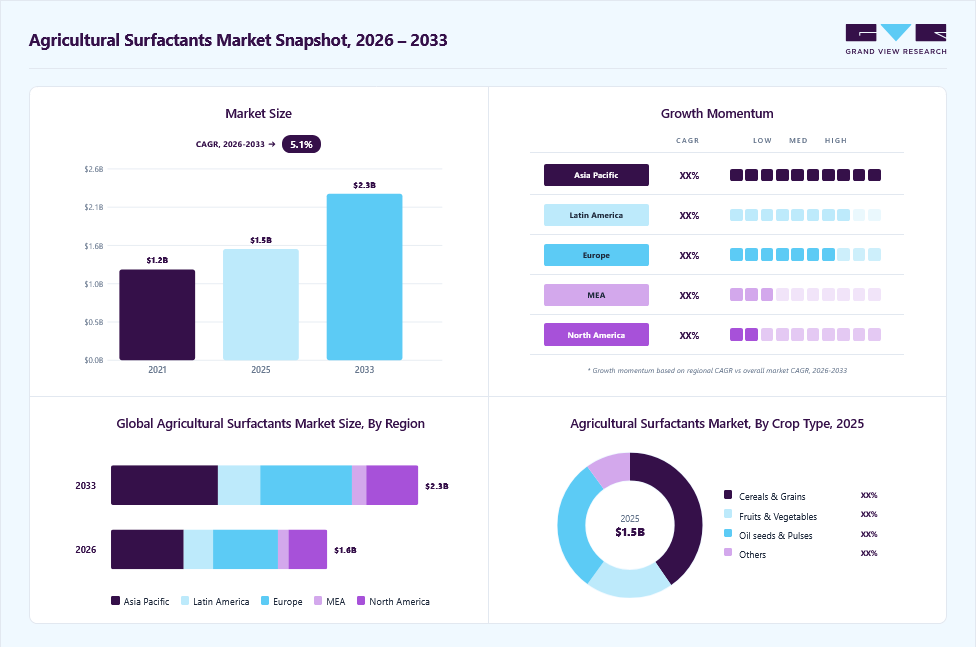 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Cationic segment accounted for the largest share of the agricultural surfactants market, representing 30.8% of total revenue in 2025.
- By Substrate: Synthetic segment accounted for the largest share of the agricultural surfactants market, representing 64.1% of total revenue in 2025.
- By Crop Type: Cereals & grains emerged as the leading crop type segment, accounting for 40.3% of the agricultural surfactants market revenue in 2025.
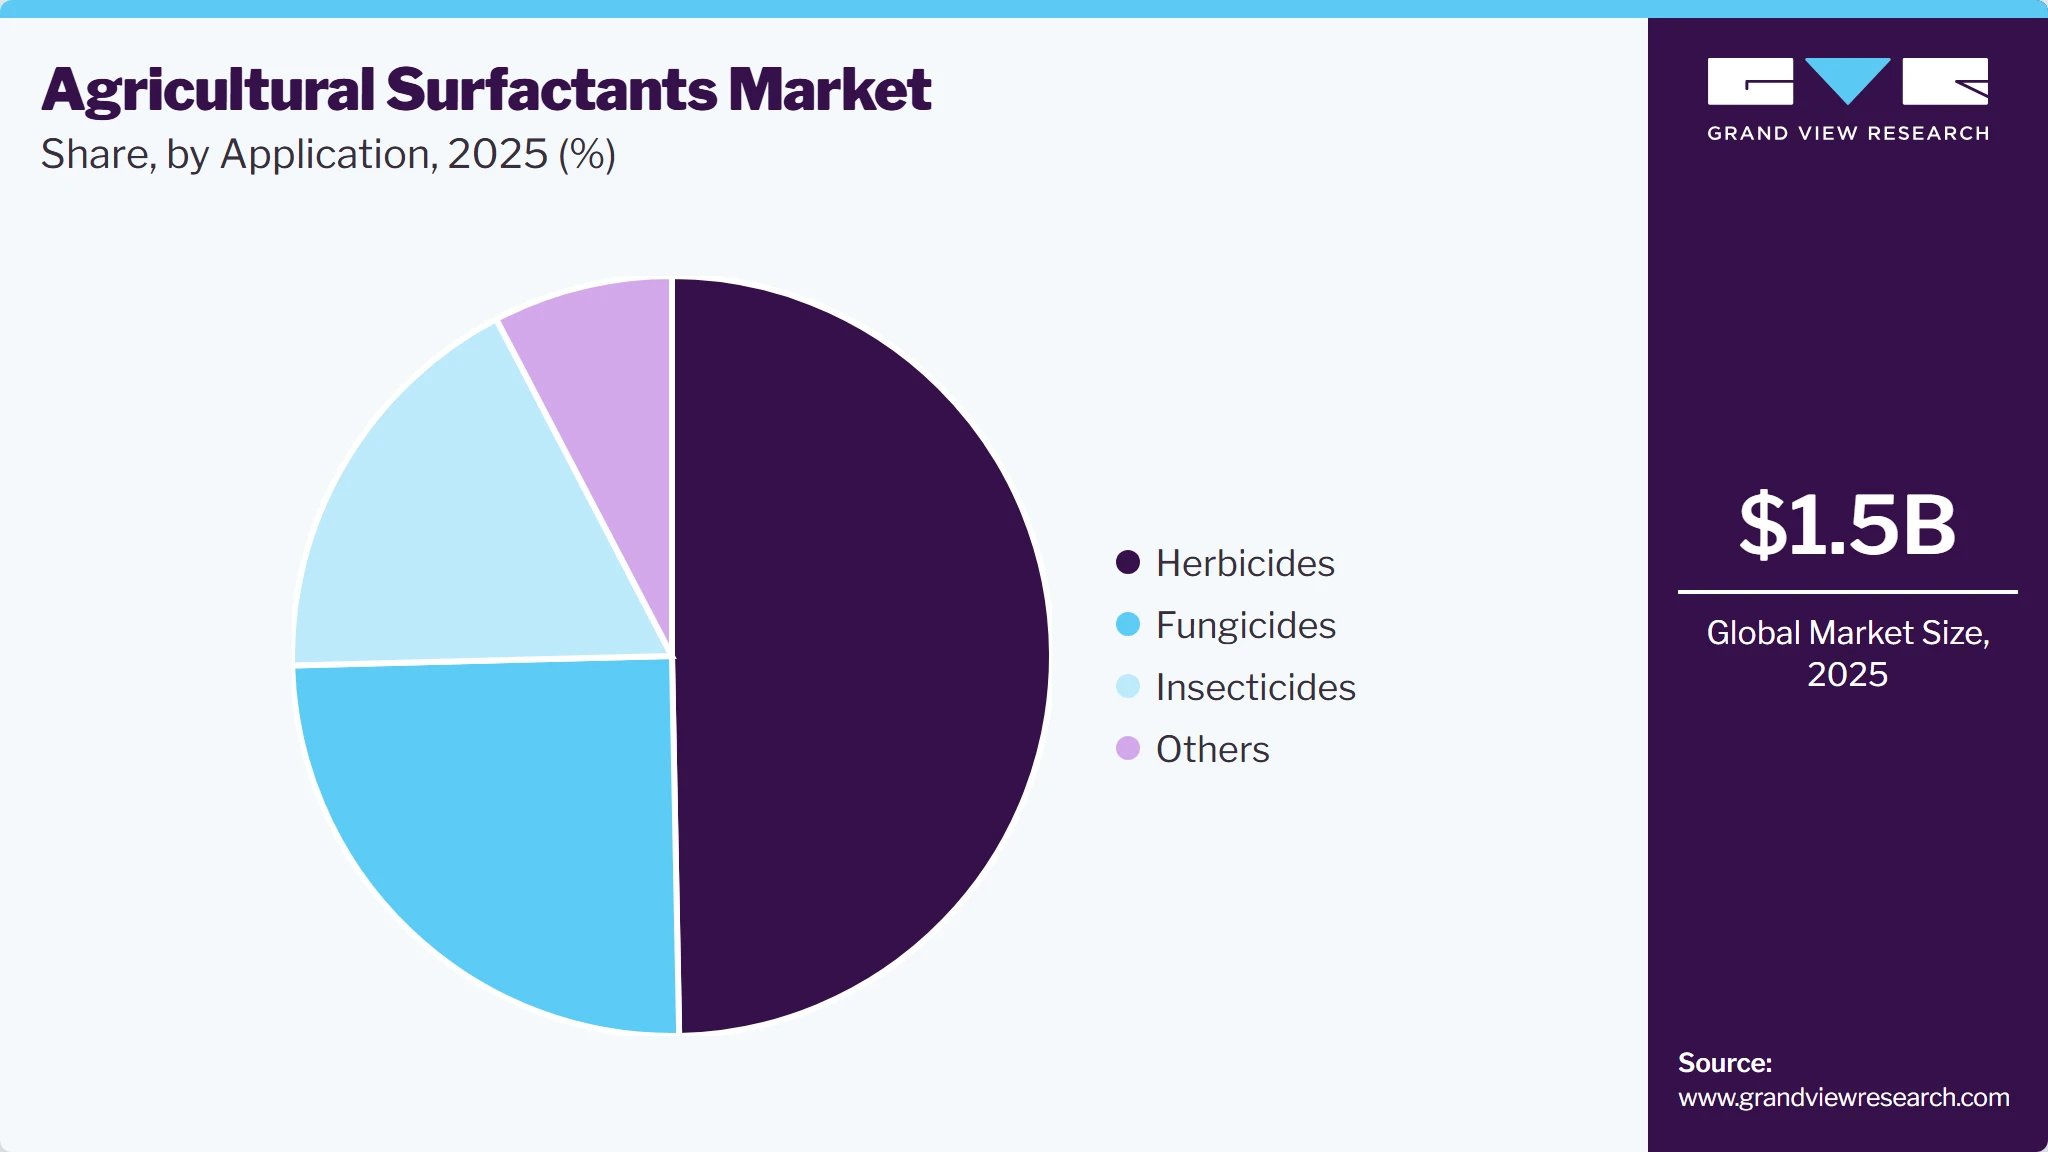
- By Application: Herbicides segment accounted for the largest revenue share of 49.7% in 2025.
Regional Highlights
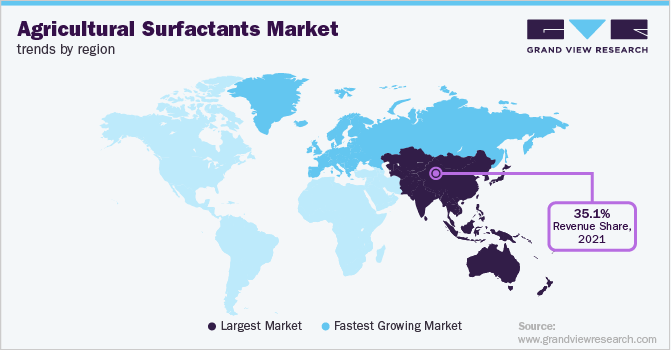
- Largest regional market: Asia Pacific (33.4% revenue share, 2025)
- By country: China maintained a leading position in the Asia Pacific agricultural surfactants market.
Market Size & Forecast
- Market size in 2025: USD 1.5 Billion
- Estimated market size in 2026: USD 1.6 Billion
- Projected market size by 2033: USD 2.3 Billion
- CAGR (2026-2033): 5.1%
Prism AI by Grand View Research Free to tryAsk a question about the agricultural surfactants marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Additionally, the increasing adoption of precision farming methods, the reduction of arable land, and the rising global food demand due to the expanding world population are significant factors influencing the industry. The market covers various chemical elements used to boost the performance and efficacy of agrochemicals, including herbicides, fungicides, and pesticides. Specifically, surfactants improve the growth regulators and foliar uptake of defoliants and herbicides. The product market serves agricultural sectors, such as specialty crops, fruits, vegetables, and row crops. Therefore, it fulfills the need for practical solutions to weed infestations and diseases and combating pests.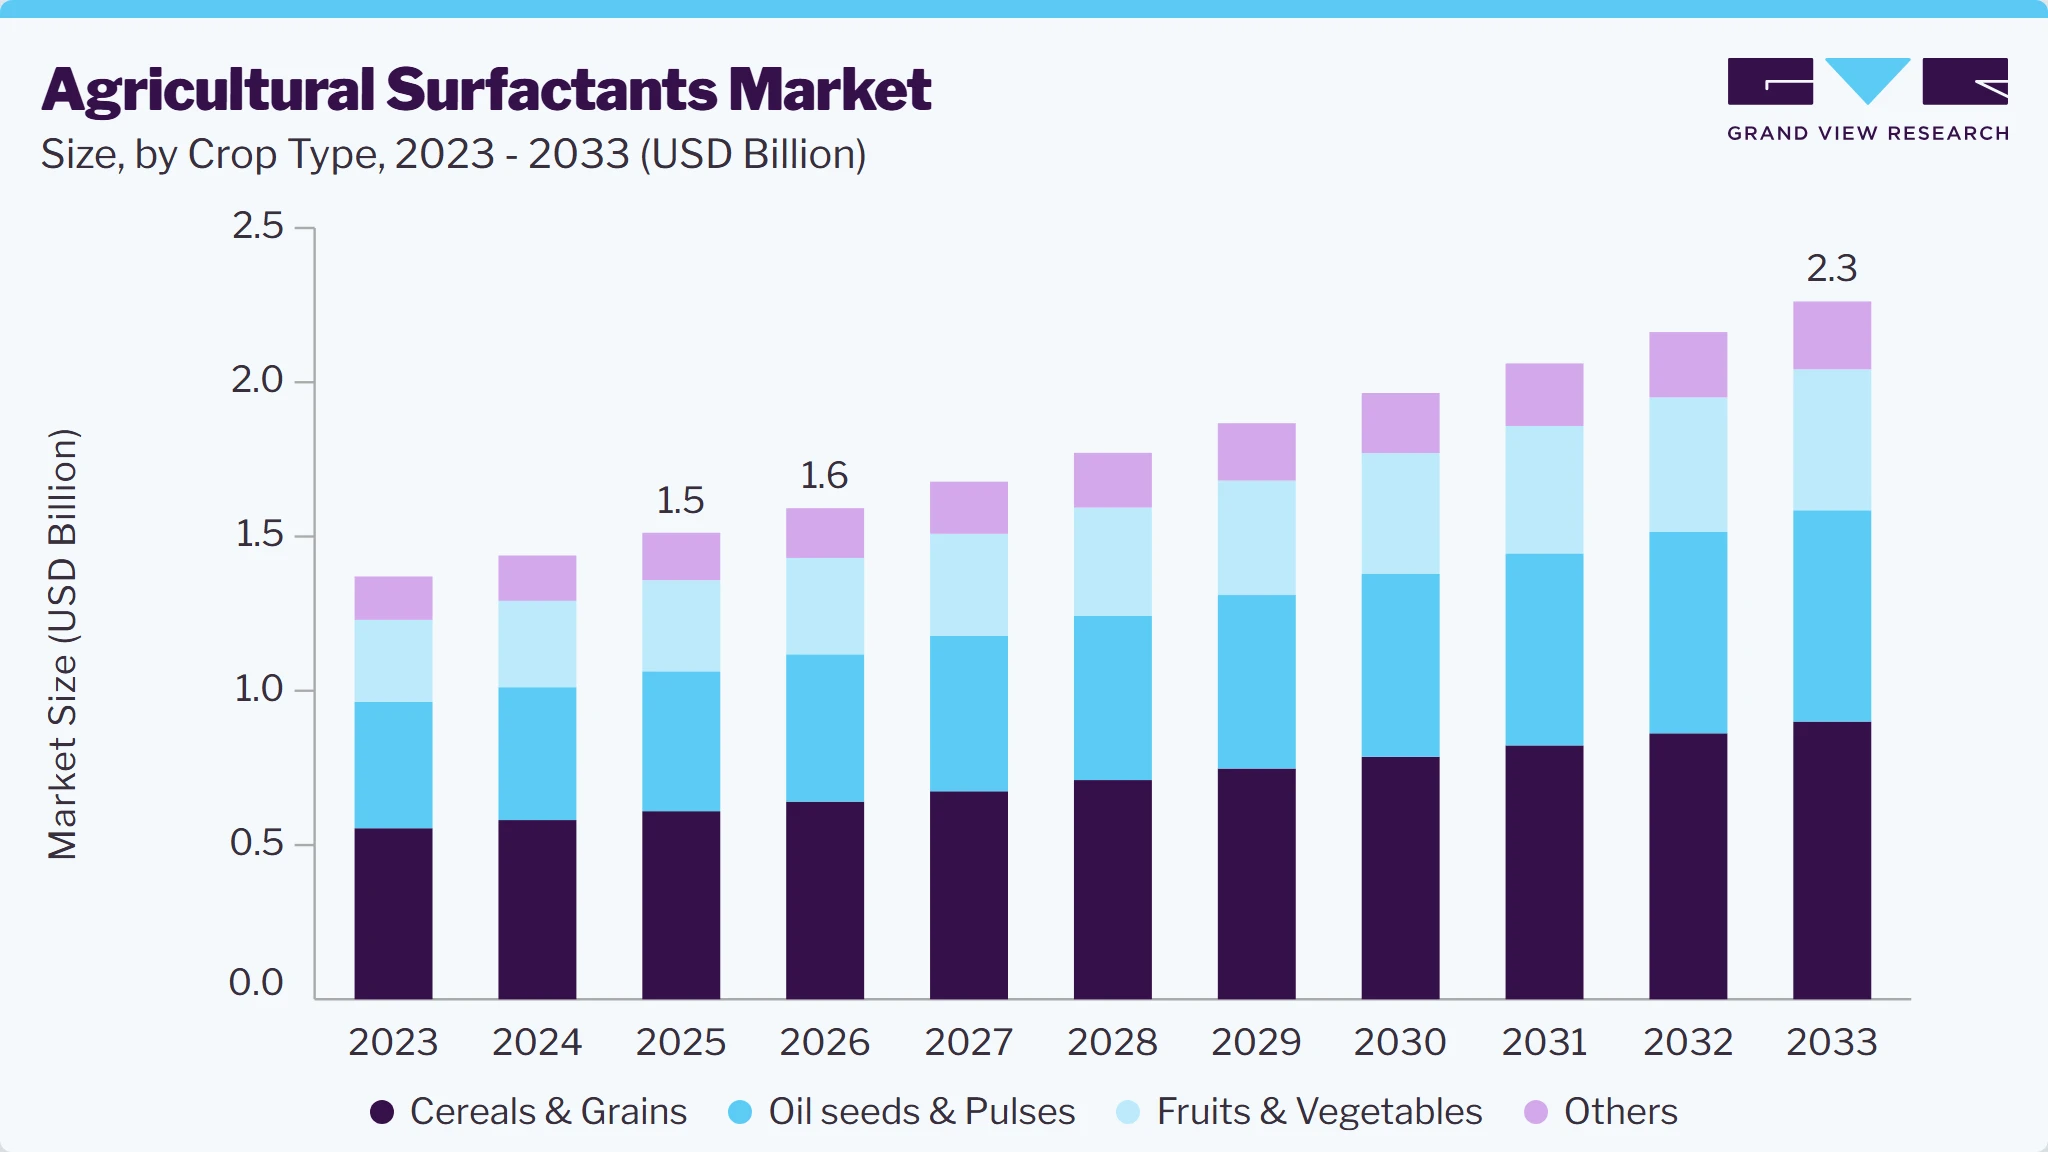 To learn more about this report, Download Free Sample Report
The agricultural surfactant market is vital to global food security and environmental sustainability. It helps reduce environmental impact while optimizing agricultural inputs. Additionally, the growing adoption of integrated pest management contributes to the market's growth.
Market Dynamics
Agricultural surfactants market is growing due to the rising need to improve crop productivity and maximize the effectiveness of agrochemicals. Farmers are increasingly using herbicides, insecticides, and fungicides to protect crops from pests, weeds, and diseases. Surfactants help these products spread evenly, adhere to plant surfaces, and penetrate more effectively, resulting in better performance and reduced chemical wastage. Growing food demand, limited arable land, and the adoption of precision farming practices are encouraging the use of high efficiency crop protection solutions, which is increasing demand for agricultural surfactants across major farming regions.
Rising food consumption is increasing pressure on farmers to produce more from limited agricultural land. Improving crop productivity has become essential for maintaining food supply, farm profitability, and resource efficiency. Agricultural surfactants help herbicides, insecticides, fungicides, and fertilizers perform more effectively by improving spreading, wetting, and penetration on plant surfaces. This allows crops to receive better protection and nutrient uptake while reducing chemical wastage during spraying operations.
Agricultural operations are also adopting precision farming practices that rely on accurate application of crop protection products. Surfactants support these practices by improving spray coverage and helping active ingredients reach target areas more efficiently. Better application performance can contribute to higher yields, improved crop quality, and more consistent results across large farming areas. These benefits are encouraging greater use of agricultural surfactants in both developed and emerging agricultural markets.
Environmental regulations governing agricultural chemicals have become increasingly strict across many countries. Some conventional surfactants face restrictions because of concerns related to biodegradability, aquatic toxicity, and long-term environmental effects. Manufacturers often need additional testing, product reformulation, and regulatory approvals before marketing new or modified surfactant products. These requirements increase development costs and extend commercialization timelines. Farmers and agrochemical companies may also limit the use of formulations that face regulatory uncertainty. Compliance obligations can reduce flexibility in product selection and slow adoption of certain surfactant technologies. As a result, regulatory pressure on chemical ingredients acts as a restraint on the agricultural surfactants market.
Demand for environmentally friendly agricultural inputs is creating strong opportunities for surfactant manufacturers. Bio based surfactants derived from renewable feedstocks such as vegetable oils, sugars, and natural fats are gaining attention because they offer improved biodegradability and reduced environmental impact compared with some conventional alternatives. Agrochemical producers are increasingly seeking sustainable ingredients that can meet regulatory requirements while maintaining product performance. Manufacturers that invest in research, formulation expertise, and large scale production of bio based surfactants can expand their product portfolios and strengthen their market position. Growing adoption of sustainable farming practices across developed and emerging markets is expected to support long-term demand for these advanced surfactant solutions.
Analyst Perspective
The agricultural surfactants market is expected to witness steady growth as farmers increasingly focus on maximizing agrochemical efficiency and improving crop productivity. Demand is shifting toward high-performance formulations that enhance spray coverage, absorption, and overall treatment effectiveness. Sustainability trends are encouraging the development of bio-based surfactants that align with evolving environmental regulations and customer preferences.
Type Insights
The cationic segment accounted for the largest share of the agricultural surfactants market, representing 30.8% of total revenue in 2025. This can be attributed to the increasing demand and use of agricultural surfactants. It is less expensive than other types and contains sulfonates, dispersants, sulfate, and carboxylates.
Non-ionic agricultural surfactants are crucial in improving the efficacy of pesticides and herbicides. Unlike their anionic counterparts, non-ionic surfactants do not carry a charge, making them versatile in various formulations. They enhance agrochemicals' spreading, wetting, and penetration, which can lead to better crop protection. Additionally, non-ionic surfactants are generally less sensitive to water quality, allowing them to perform effectively in varying environmental conditions. Their compatibility with various formulations and lower toxicity profiles also contribute to their growing popularity in agricultural practices.
Substrate Insights
The synthetic segment accounted for the largest share of the agricultural surfactants market, representing 64.1% of total revenue in 2025 as they are specially formulated compounds designed to enhance the effectiveness of crop protection products like pesticides and herbicides. These surfactants modify the surface properties of liquid formulations, improving their spreading and wetting characteristics on plant surfaces. By facilitating better absorption and penetration into plant tissues, synthetic surfactants help ensure that agrochemicals reach their targets more effectively. Additionally, they can be engineered to be compatible with a wide range of formulations, making them versatile options for various agricultural applications. Their tailored properties also allow for improved performance across different environmental conditions.
Bio-based agricultural surfactants are expected to show the highest CAGR over the forecast period. These are derived from natural sources, such as plant oils, sugars, or other renewable materials. Unlike their synthetic counterparts, these surfactants are more environmentally friendly and biodegradable, reducing the risk of long-term soil and water contamination. They improve the effectiveness of crop protection products by enhancing spreading and wetting on plant surfaces, much like synthetic surfactants. Additionally, bio-based surfactants can offer similar performance in absorption and penetration while being compatible with various formulations. Their use supports sustainable agricultural practices and addresses increasing consumer demand for eco-friendly farming solutions.
Crop Type Insights
Cereals & grains emerged as the leading crop type segment, accounting for 40.3% of the agricultural surfactants market revenue in 2025. In cultivating cereals and grains, the product market plays an important role by enhancing the effectiveness of crop protection products. These surfactants improve spray coverage, ensuring that herbicides, fungicides, and insecticides spread evenly across the plant surfaces. This leads to better absorption and penetration of the active ingredients, promoting healthier crops and more effective pest control. Additionally, bio-based surfactants are particularly beneficial, as they are environmentally friendly, biodegradable, and support sustainable agricultural practices, meeting the growing demand for eco-conscious solutions in farming. Their use can ultimately contribute to higher yields and improved crop quality.
The product market plays a significant role in cultivating fruits and vegetables by enhancing the efficacy of crop protection products. They facilitate better coverage of pesticides and fungicides on plant surfaces, ensuring that these solutions spread uniformly and adhere effectively. This improved application leads to better absorption of active ingredients, resulting in stronger plants and more effective pest and disease management. Additionally, bio-based surfactants in this segment support sustainable farming practices, as they are biodegradable and environmentally friendly. Overall, their application contributes to healthier crops and increased fruit and vegetable farming productivity.
Application Insights
The herbicides segment accounted for the largest revenue share of 49.7% in 2025. Agricultural surfactants play a crucial role in the application of herbicides by enhancing their effectiveness. They improve the spreading and adhesion of herbicides on plant surfaces, ensuring more uniform coverage. This leads to better absorption of active ingredients, resulting in improved weed control. Additionally, surfactants can help reduce the herbicide needed, minimizing environmental impact. Their use supports targeted applications, contributing to more efficient and sustainable farming practices. Overall, they are essential for maximizing the performance of herbicides in crop management.
 To learn more about this report, Download Free Sample Report
Agricultural surfactants significantly enhance the effectiveness of insecticides in their application. By improving spreading and adherence on target surfaces, surfactants ensure insecticides distribute more evenly over crops. This results in better coverage and penetration, leading to increased pest absorption of the active ingredients. Moreover, surfactants can help reduce the overall quantity of insecticide required, thus minimizing the potential environmental impact. Their use supports more precise and efficient pest control strategies, ultimately contributing to sustainable agriculture practices.
Regional Insights
North America agricultural surfactants market is growing as the region produces various crops, including specialty crops, vegetables, fruits, oilseeds, and cereals. Agribusinesses and farmers in the region are at the forefront of effective chemical application and employ advanced agricultural techniques.
The agricultural surfactants market in the U.S. is expected to grow. Improving the efficiency of crop safety activities is crucial, especially when dealing with disease challenges and evolving pests. This focus is a key factor driving market growth. Additionally, the United States has a significant trend towards sustainable surfactants and an increasing demand for bio-based products.
Asia Pacific Agricultural Surfactants Market Trends
Asia Pacific accounted for 33.4% of the agricultural surfactants market revenue in 2025, making it the largest regional market. This is due to several factors, including countries with vast arable lands, rising populations, and a high demand for developed crops. Additionally, rapid industrialization and urbanization are contributing to this growth. Key emerging Asian Pacific countries include India, Japan, China, and Australia.
 To learn more about this report, Download Free Sample Report
India agricultural surfactants market is the largest producer of agricultural surfactants, and the pesticide production industry plays a crucial role in ensuring food security and protecting crops. Agricultural surfactants offer a specialized range of products that meet the needs of the Indian pesticide manufacturing sector. These surfactants are produced precisely to ensure compliance with regulations while maintaining high product quality.
China Agricultural Surfactants Market Trends
China maintained a leading position in the Asia Pacific agricultural surfactants market.
Europe Agricultural Surfactants Market Trends
The growing agricultural industry, advancement in farming practices, and increased awareness of healthy eating are some of the major factors driving the demand for agrochemicals in the region. The growing need to improve crop yield and production efficiency drives the market due to the increasing population and diminishing farmlands. This has led to an increase in demand for product markets in the region.
Latin America Agricultural Surfactants Market Trends
The significant growth of the agriculture sector, mainly in Brazil, due to the increasing demand for agrochemicals to enhance the production of Brazilian soybean, is the key driving factor for the growth of the agricultural adjuvants market in Latin America.
Middle East & Africa Agricultural Surfactants Market Trends
The agricultural surfactants market in the Middle East and Africa is expected to grow significantly over the forecast period. The consumption of pesticides is increasing in Saudi Arabia and Oman, and the trend is seen steady for South Africa, Kuwait, and Qatar pesticide consumption. In addition, there is tremendous growth in the consumption of pesticides in Ghana.
Key Agricultural Surfactants Company Insights
Some of the key players operating in the market include Clariant, Dow, and Solvay.
-
Clariant has five business units, including oil and mining services, industrial & consumer specialties, functional minerals, catalysts, and additives. These units are reported in three businesses, namely areas of catalysis, care chemicals, and natural resources. The company offers agricultural adjuvants under the industrial & consumer specialties segment.
-
Dow manufactures agrochemicals, rubber, specialty chemicals, and plastic materials. The company serves its products to several industries, including agricultural, infrastructure, packaging, and consumer care industries, globally. It has a presence in all regions, including North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. Its major markets include North America and Asia Pacific. The company had 106 manufacturing sites, 19 manufacturing sites in 10 Asia Pacific countries, 37 sites in 15 Europe, Middle East, Africa, and India (EMEAI) countries, 15 sites in 4 Latin American countries, and 35 manufacturing sites in the U.S. and Canada.
-
The company has expertise in chemicals, materials, and solutions and offers its products and solutions to various industries such as automotive, healthcare, and water treatment, among others. It focuses on developing safer, cleaner, and sustainable solutions. The company has a presence in 64 countries, and its major markets include Asia Pacific, Europe, and North America. As of 2023, it had 45 production sites in 41 countries and 20 major research & innovation centers.
Key Agricultural Surfactants Companies:
The following key companies have been profiled for this study on the agricultural surfactants market.
-
Clariant
-
Evonik Industries AG
-
Dow
-
DuPont
-
Solvay
-
Bayer AG
-
Nufarm
-
Huntsman International LLC
-
Croda International Plc
-
Helena Agri-Enterprises, LLC
-
Stepan Company
-
Wilbur-Ellis Holding, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Clariant, Evonik Industries AG, Dow, Solvay, Croda International Plc, Stepan Company)
- These companies focus on developing specialized agricultural surfactant portfolios that improve agrochemical formulation performance across diverse crop protection applications. They maintain strong engagement with agrochemical manufacturers to support formulation optimization and application efficiency.
- Their strategies emphasize investment in sustainable surfactant technologies, expansion of bio-based product offerings, and strengthening distribution networks across major agricultural regions to maintain market leadership.
- Strong research capabilities enable these companies to develop high-performance surfactants tailored to evolving crop protection requirements and regulatory expectations. Broad product portfolios allow them to serve multiple agricultural applications and customer segments globally.
- Established customer relationships, technical support expertise, and global market presence provide advantages in securing long-term supply agreements with leading agrochemical formulators.
- Large organizational structures can increase decision-making timelines and slow the commercialization of niche agricultural surfactant solutions designed for rapidly evolving market requirements.
- Dependence on broad specialty chemical businesses may reduce focus on specific agricultural applications, creating opportunities for specialized competitors to address targeted customer needs more effectively.
Emerging Players (Helena Agri-Enterprises, LLC, Wilbur-Ellis Holding, Inc., Nufarm, Bayer AG, Huntsman International LLC, DuPont)
- These companies emphasize market expansion through agricultural distribution networks, crop input portfolios, and customer-focused formulation solutions tailored to regional farming requirements. Their activities are closely aligned with grower needs and field-level performance outcomes.
- Growth strategies include strengthening partnerships with agrochemical suppliers, expanding value-added agricultural services, and increasing participation in specialty crop protection markets.
- Direct relationships with growers, distributors, and agricultural retailers provide valuable market insights and facilitate faster adoption of new surfactant-enhanced crop protection solutions.
- Their operational flexibility allows quicker responses to regional agricultural trends, crop-specific requirements, and evolving customer preferences compared with larger multinational competitors.
- Limited specialization in agricultural surfactant chemistry compared with leading surfactant manufacturers can restrict product differentiation and innovation capabilities in advanced formulations.
- Smaller surfactant-focused portfolios and lower global reach may reduce their ability to compete across all agricultural markets and application segments simultaneously.
Recent Developments
-
In July 2024, Bionema Group, specializing in agricultural agrochemicals and biologicals, launched biodegradable surfactants like Soil Jet BSP 100. Bionema focuses on plant health management and crop protection. Soil Jet BSP100 utilizes Polyether-Modified Polysiloxane technology.
-
In October 2023, Nouryon announced the launch of two innovative products at the annual SEPAWA Congress and Exhibition in Germany. The new offerings include Berol Nexxt, which is a next-generation surfactant and multifunctional hydrotrope, and Dissolvine GL Premium, recognized as the industry’s most concentrated GLDA-based chelating agent.
Agricultural Surfactants Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 1.5 billion
Estimated market size in 2026
USD 1.6 billion
Projected market size by 2033
USD 1.7 billion
Growth rate
CAGR of 5.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Process, product, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; South Korea; Brazil; Argentina; Saudi Arabia; South Africa;
Key companies profiled
Clariant, Evonik Industries AG, Dow, DuPont, Solvay, Bayer AG, Nufarm, Huntsman International LLC, Croda International Plc, Helena Agri-Enterprises, LLC, Stepan Company, Wilbur-Ellis Holding, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Agricultural Surfactants Market Report Segmentation
This report forecasts revenue and volume growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global agricultural surfactants market report on the basis of type, substrate, crop type, application and region.
-
Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Non-ionic
-
Anionic
-
Cationic
-
Amphoteric
-
-
Substrate Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Synthetic
-
Bio-based
-
-
Crop Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Cereals & Grains
-
Oilseeds & Pulses
-
Fruits & Vegetables
-
Other Crop Types
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Herbicides
-
Insecticides
-
Fungicides
-
Other Applications
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The agricultural surfactants market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each agricultural surfactants segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Product
Revenue Capture Definition
Non-ionic
Revenue is captured through the sale of non-ionic surfactants used with a wide range of crop protection products to improve spreading, wetting, and penetration on plant surfaces. Income is generated from recurring purchases by agrochemical manufacturers and agricultural distributors due to their broad compatibility with herbicides, insecticides, and fungicides.
Anionic
Revenue is generated through the supply of anionic surfactants incorporated into agricultural formulations requiring enhanced dispersion, emulsification, and surface activity. Manufacturers capture value through sales to agrochemical producers seeking effective formulation performance across diverse crop protection applications.
Cationic
Revenue is captured through the sale of cationic surfactants utilized in specialized agricultural formulations where adhesion and interaction with plant surfaces are required. Income is derived from niche applications and customized formulations supplied to agrochemical companies and agricultural solution providers.
Amphoteric
Revenue is generated through the supply of amphoteric surfactants that provide formulation stability and performance across varying environmental and pH conditions. Value is captured through sales to manufacturers developing advanced agricultural products requiring versatile surfactant characteristics.
Substrate
Revenue Capture Definition
Synthetic
Revenue is captured through the sale of synthetic surfactants manufactured from petrochemical feedstocks and incorporated into agricultural formulations. Income is generated from high-volume demand by agrochemical producers due to established performance characteristics, scalability, and cost efficiency.
Bio-based
Revenue is generated through the supply of surfactants derived from renewable raw materials such as vegetable oils and natural feedstocks. Manufacturers capture value by serving demand for environmentally responsible agricultural inputs and supporting compliance with sustainability and regulatory requirements.
Crop Type
Revenue Capture Definition
Cereals & Grains
Revenue is captured through surfactant sales associated with crop protection and nutrient management products used in large-scale cultivation of wheat, rice, corn, and other grain crops. Income is supported by extensive acreage and recurring seasonal application requirements.
Oilseeds & Pulses
Revenue is generated through the supply of surfactants used with agrochemicals applied to soybean, sunflower, canola, lentils, and other oilseed and pulse crops. Value is captured through repeated demand for effective pest, disease, and weed management solutions.
Fruits & Vegetables
Revenue is captured through sales of surfactants that enhance the effectiveness of crop protection products used in high-value fruit and vegetable cultivation. Income is supported by intensive farming practices and the need to maintain crop quality and yield.
Other Crop Types
Revenue is generated through the supply of surfactants for plantation crops, forage crops, ornamental plants, and specialty agricultural applications. Manufacturers capture value from diverse cultivation activities requiring efficient agrochemical performance.
Application
Revenue Capture Definition
Herbicides
Revenue is captured through the sale of surfactants used to improve herbicide spreading, retention, and absorption on weed surfaces. Income is generated from widespread herbicide usage across commercial farming operations and recurring seasonal demand.
Insecticides
Revenue is generated through the supply of surfactants incorporated into insecticide formulations to enhance coverage and contact with target pests. Manufacturers capture value through continuous demand for effective insect control across multiple crop categories.
Fungicides
Revenue is captured through sales of surfactants that improve fungicide distribution and adherence on plant surfaces, supporting disease management programs. Income is derived from regular fungicide applications in crops vulnerable to fungal infections.
Other Applications
Revenue is generated through the supply of surfactants used in fertilizers, plant growth regulators, micronutrient formulations, and other agricultural products. Value is captured through diverse agricultural applications requiring improved delivery and performance of active ingredients.
Estimation Model
Layer Name
Key Question
Content
Agricultural Production Base Layer
What forms the demand base?
Identify global cultivation areas, crop production volumes, and agricultural activity across major farming regions. This layer establishes the total addressable agricultural base that drives demand for crop protection products and agricultural inputs used throughout the crop production cycle.
Agrochemical Application Layer
Where are agricultural surfactants consumed?
Estimate the penetration and utilization of agricultural surfactants across herbicides, insecticides, fungicides, fertilizers, plant growth regulators, and other agricultural formulations. Demand is assessed across cereals and grains, oilseeds and pulses, fruits and vegetables, and other crop categories.
Surfactant Consumption Intensity Layer
How much surfactant is used?
Analyze average surfactant consumption rates per unit of agrochemical formulation and treated agricultural area, considering crop type, application method, formulation requirements, pest pressure, climatic conditions, and farming practices. Consumption intensity varies according to product type, active ingredient characteristics, and agricultural production systems.
Revenue Layer
How is market revenue generated?
Market revenue is quantified through the sale of non-ionic, anionic, cationic, amphoteric, synthetic, and bio-based agricultural surfactants supplied for crop protection and agricultural input formulations. Revenue is generated from recurring demand by agrochemical manufacturers, formulation companies, distributors, and agricultural input suppliers serving commercial farming operations worldwide.
Delivered Customizations
This report has been delivered with the following In-depth customization
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Expanded regional analysis covering additional agricultural markets and farming zones beyond the standard study scope, including detailed assessment of crop cultivation patterns, agrochemical usage trends, regulatory environments, adoption of surfactant technologies, and demand potential across selected regions.
Supports geographic expansion planning and market prioritization by providing deeper visibility into untapped demand centers, regional consumption trends, and growth prospects across diverse agricultural ecosystems.
Competitive Benchmarking
Comparative assessment of agricultural surfactant suppliers based on product portfolio diversity, formulation capabilities, sustainability initiatives, application expertise, distribution reach, customer engagement strategies, and recent business developments across target markets.
Assists strategic decision-making through enhanced understanding of competitor positioning, differentiation strategies, market presence, and areas for competitive advantage within the agricultural surfactants industry.
Opportunity Assessment
Evaluation of emerging revenue opportunities linked to bio-based surfactant adoption, precision agriculture expansion, specialty crop cultivation growth, evolving crop protection requirements, and increasing demand for environmentally responsible agricultural formulations.
Helps identify high-potential investment areas, product development priorities, and customer segments that can support long-term revenue growth and strengthen market positioning in evolving agricultural markets.
Frequently Asked Questions About This Report
Some of the key players operating in the agricultural surfactants market include Clariant, Evonik Industries, BASF SE, Dow DuPont, Solvay, Bayer AG, Nufarm, Huntsman International LLC, Croda International Plc, Helena Agri-Enterprises, LLC, Stepan Company, Wilbur-Ellis Holdings, Inc, among others.
The key factors that are driving the global agricultural surfactants market include increasing demand for crop protection products in the agricultural field across the globe. In addition, increasing adoption of precision farming methods, shrinking arable land and growing food demand globally.
Cationic segment accounted for the largest share of the agricultural surfactants market, representing 30.8% of total revenue in 2025.
Synthetic segment accounted for the largest share of the agricultural surfactants market, representing 64.1% of total revenue in 2025.
Cereals & grains emerged as the leading crop type segment, accounting for 40.3% of the agricultural surfactants market revenue in 2025.
Herbicides segment accounted for the largest revenue share of 49.7% in 2025.
The global agricultural surfactants market size was valued at USD 1.5 billion in 2024 and is estimated at USD 1.6 billion for 2026.
The global agricultural surfactants market is expected to grow at a CAGR of 5.1% from 2026 to 2033, reaching USD 2.3 billion by 2033.
Asia Pacific accounted for 33.4% of the global market revenue in 2025.
About the Author(s)
Agrochemicals & Fertilizers Research Team
Bulk Chemicals · Agrochemicals & FertilizersThis report was authored by the agrochemicals & fertilizers research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the agrochemicals & fertilizers segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


