
- Home
- »
- Sensors & Controls
- »
-
Agriculture Sensor Market Size, Share & Trends Report 2033GVR Report cover

Agriculture Sensor Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Airflow Sensors, Pressure Sensors), By Application (Dairy Management, Soil Management, Climate Management, Water Management), By Region, And Segment Forecasts
Market Size, 2025
$3.0BMarket Estimate, 2026
$3.3BMarket Forecast, 2033
$7.6BCAGR, 2026–2033
12.6%Agriculture Sensor Market Summary
The global agriculture sensor market size was valued at USD 3.0 billion in 2025 and is projected to grow from USD 3.3 billion in 2026 to USD 7.6 billion by 2033, at a CAGR of 12.6% from 2026 to 2033. North America market dominated, with a revenue share of 43.1% in 2025. This growth is driven by the rising adoption of precision agriculture practices.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Location sensor segment dominated the market with a revenue share of 13.7% in 2025.
- By application: Soil management segment held the largest revenue share of 24.5% in 2025.
Regional Highlights
- Largest regional market: North America (43.1% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 3.0 Billion
- Estimated market size in 2026: USD 3.3 Billion
- Projected market size by 2033: USD 7.6 Billion
- CAGR (2026-2033): 12.6%
GVR research-powered AIAsk Prism AI about the agriculture sensor marketGet cited answers from GVR research on market growth, segments, regulations and forecasts.Start with✓ Source-linked answers ✓ Market-specific context ✓ Traceable figuresExplore Prism AI ↗
In recent years, the agriculture industry has been experiencing significant growth in demand driven by the increasing need for fresh produce, grains, pulses, and vegetables worldwide. The growing prevalence of lifestyle-driven diseases and chronic health issues such as hypertension, cardiac diseases, diabetes, and others have resulted in increasing consumption of fresh produce and organic agriculture products. Increasing inclination towards consuming food products made with naturally sourced and organically grown materials also adds to the growth of the agriculture industry. These aspects have stimulated the increasing adoption of technology-driven processes, machinery, automation tools, and software support.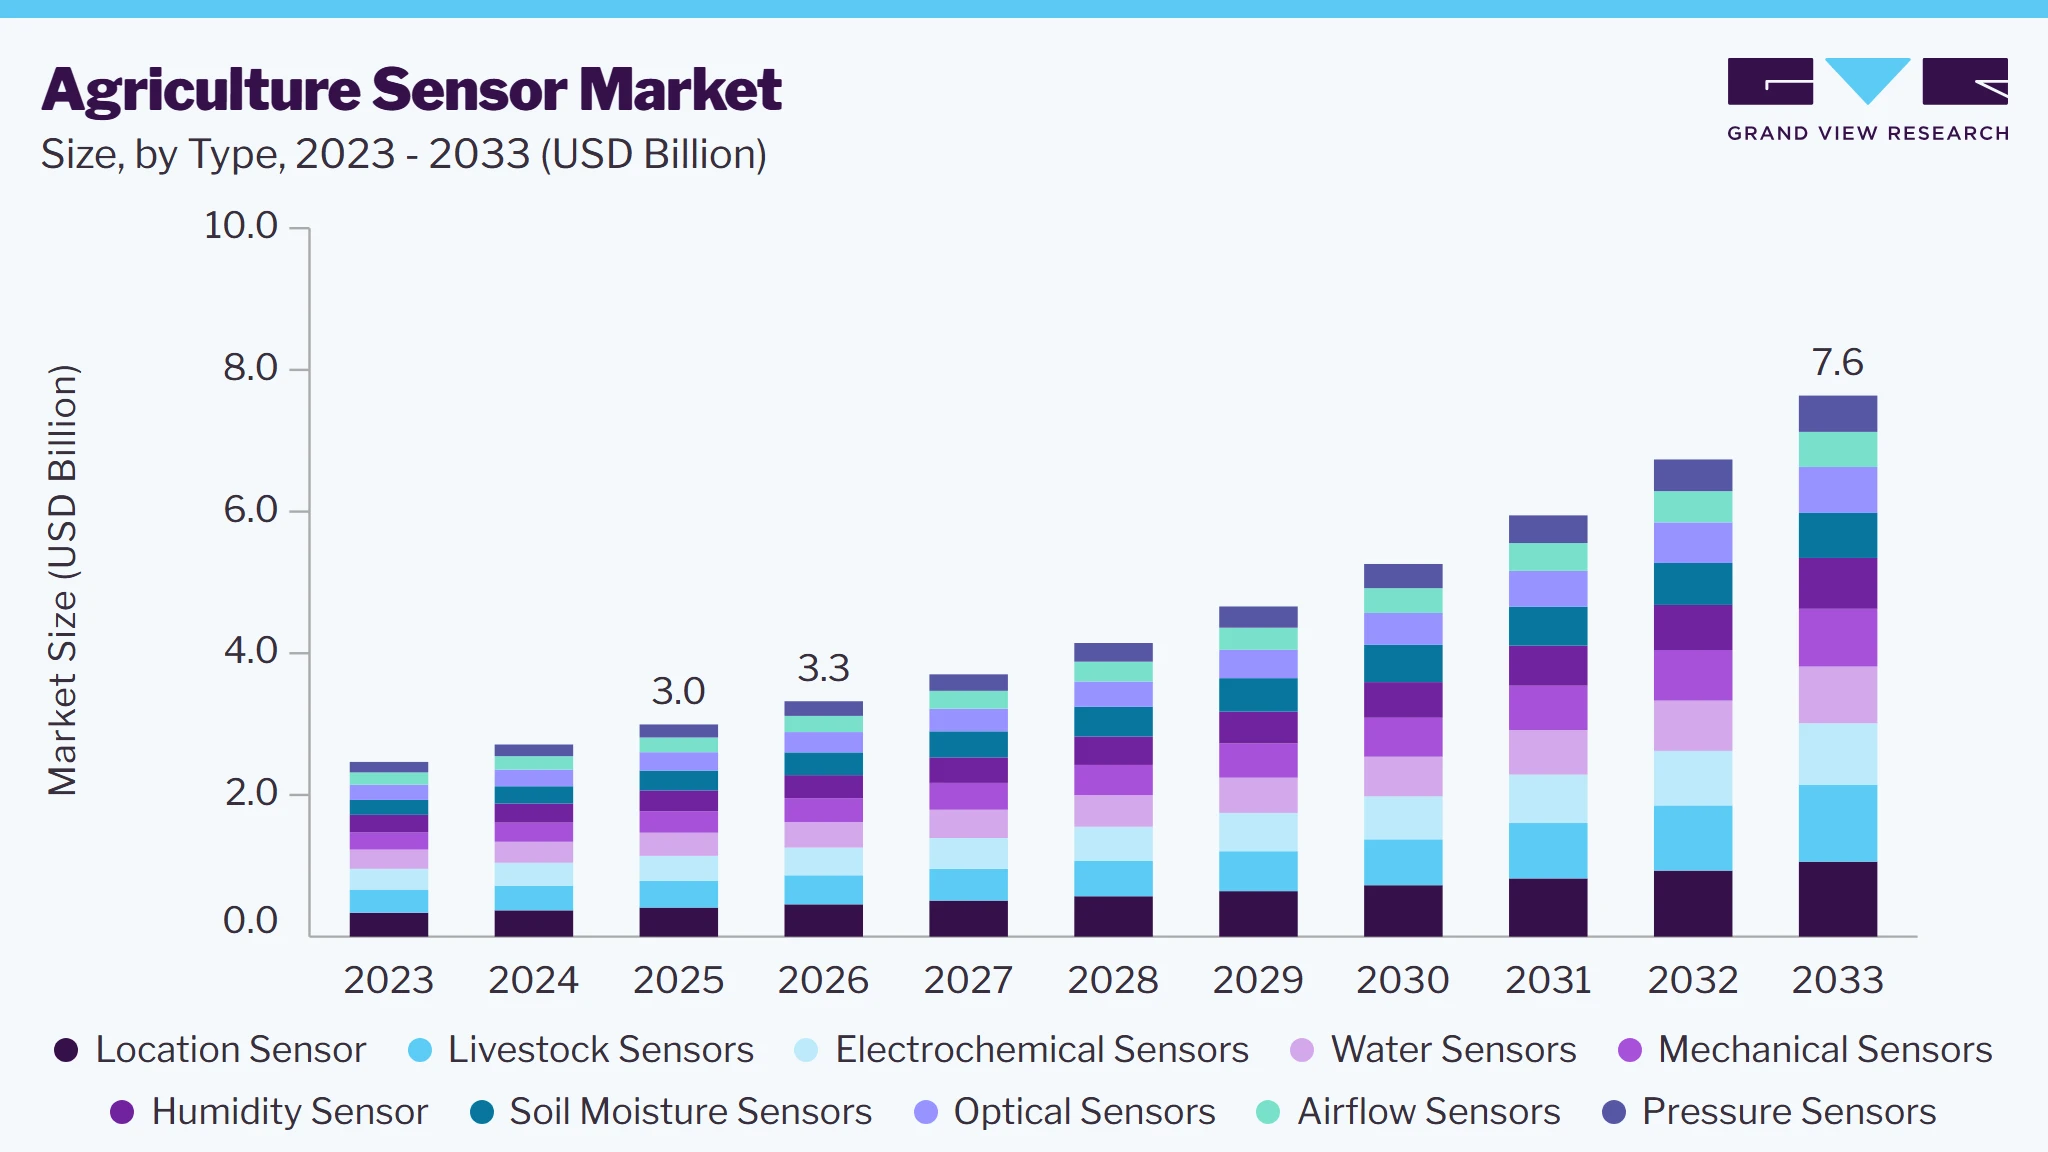 To learn more about this report, Download Free Sample Report
Agriculture sensors are technology equipped with electronic devices that collect complex data associated with various influential factors such as weather changes, soil moisture, water levels, humidity, changes in plant conditions, and more. It assists systems and software technology that process the collected data to provide actionable intelligence and insights to users. These insights include water level indications, weather condition insights, forecasts, post-weather change influence measures, and more. Different types of such sensors include location sensors, electrochemical sensors, airflow sensors, optical sensors, pressure sensors, mechanical sensors, water sensors, and others.
The emergence of modern technologies such as Artificial Intelligence (AI), the Internet of Things (IoT), machine learning, and others have resulted in the availability of advanced agriculture technology solutions. Product launches and collaborations among key market participants in the agriculture technology industry also drive the demand for agriculture sensors. For instance, in February 2024, Syngenta, one seed and crop protection products company, collaborated with digital farm management technology provider CropX Inc. to offer sustainability solutions to its seed suppliers in the American Midwest. The agronomic farm management system provided by CropX is equipped to gather real-time data through satellites, sensors, rain gauges, and other machinery deployed in the field. Such collaborations and partnerships among companies operating in various dynamics of agriculture technology are expected to add lucrative growth opportunities for this market during the forecast period.
Increasing support from multiple governments, the entry of numerous technology and innovation industry participants in this market, and the ease of availability of technology tools are expected to generate growth in the next few years. The launch of technology-based products developed in collaboration related to water management, precision irrigation, and advanced farm monitoring is expected to contribute to growth. For instance, in February 2024, REINKE MANUFACTURING CO., INC. and CropX Technologies jointly introduced Reinke Direct ET by CropX. The innovation-based solution offers cost-effective Actual Evapotranspiration (ETa) measurements with the help of the Reinke Center pivot irrigation system.
Growing awareness regarding benefits associated with the use of technology that collects data, interprets datasets, and provides actionable insights is expected to develop significant growth in demand. Increasing availability of information, strategies deployed by key technology companies and agriculture industry participants to convey the significance of agriculture sensors, and ease of availability are also contributing to the growth experienced by this industry.
Market Dynamics
The agriculture sensor market is experiencing strong growth as farmers increasingly adopt sensor technologies to monitor critical field conditions and improve the efficiency of agricultural operations. Soil moisture sensors, weather sensors, nutrient sensors, temperature sensors, livestock monitoring sensors, and crop health sensors enable continuous data collection that supports timely, informed farming decisions. Growing concerns over water scarcity, rising input costs, and the need to maximize crop yields are accelerating the adoption of sensor-based precision agriculture practices. Additionally, the expansion of IoT-enabled farming, wireless connectivity, and automated irrigation systems is increasing the demand for real-time sensing solutions that optimize resource utilization while improving crop performance.
The increasing adoption of smart farming technologies is driving market growth in the agriculture sensor market by encouraging farmers to make production decisions based on continuously monitored field conditions rather than periodic manual observations. Modern farms increasingly integrate digital technologies to monitor soil properties, crop development, irrigation performance, weather conditions, and equipment activity in real time, optimizing agricultural operations. Agricultural sensors serve as the primary data-collection layer in these smart farming environments, generating accurate field data that supports intelligent farm management. Continuous monitoring improves resource utilization while allowing producers to respond rapidly to changing crop conditions throughout the growing season. The expanding transition toward digitally managed agriculture continues to accelerate demand for advanced agricultural sensors.
High initial investment costs for advanced agricultural sensor systems are restraining growth in the agriculture sensor market by limiting adoption among farms with constrained capital budgets. Modern sensor deployments often require the purchase of multiple sensing devices, communication gateways, power systems, software platforms, installation services, and integration with existing farm equipment to deliver meaningful operational value. The combined expenditure can be substantial, particularly for producers managing large cultivation areas requiring extensive sensor coverage. Many farmers evaluate these investments alongside competing priorities such as machinery upgrades, irrigation infrastructure, seed procurement, and land development, which can delay technology adoption. This financial burden slows the pace at which advanced sensor technologies penetrate the broader agricultural sector.
The rising adoption of edge computing for real-time agricultural monitoring is creating substantial opportunities in the agricultural sensor market by enabling sensor data to be processed directly at the field level rather than relying entirely on centralized cloud infrastructure. Agricultural operations often require immediate responses to changing soil moisture, temperature, humidity, pest activity, irrigation performance, and crop health conditions, where even short communication delays can reduce operational effectiveness. Edge computing allows agriculture sensors to generate instant analytical outputs that support rapid field-level decisions without waiting for continuous cloud connectivity. Faster processing improves irrigation timing, environmental control, and equipment responsiveness across precision farming operations. The growing demand for immediate operational intelligence is driving market growth for advanced sensor technologies designed to operate within edge computing environments.
Analyst Perspective
The agriculture sensor market is evolving from a hardware-driven segment into a data-generation layer that underpins the broader digital agriculture ecosystem. The long-term value of sensors lies not in the devices themselves but in the quality, reliability, and frequency of the field data they generate to support agronomic decision-making. Market leaders are likely to be those that deliver highly accurate, durable, and interoperable sensors that seamlessly integrate with farm management platforms, drones, agricultural machinery, and precision farming technologies. As farmers increasingly shift from reactive to predictive crop management, sensor networks are expected to become indispensable infrastructure for improving productivity, optimizing input usage, and enhancing resilience against changing environmental conditions.
Type Insights
Based on type, the location sensor segment led the market with the largest revenue share of 13.7% in 2025. This is attributed to the growing utilization of numerous activities such as field mapping, enhanced resource allocation, real-time crop monitoring, improved decision-making, sustainable farming practices, etc. Location sensors accurately map field boundaries and provide digitally developed maps. Additionally, these sensors held machinery and other technology tools to identify precise paths and areas for determined performances. Location sensors also assist farmers and users in identifying crops experiencing disruptions in water availability, diseases of any sort, etc., and equipment tracking.
The soil moisture sensors segment is expected to experience the highest growth over the forecast period. The development of this segment is primarily influenced by the increasing adoption of farmers for improved irrigation performances and scheduling. Different soil moisture sensors include capacitance sensors, probes, Time Domain Transmissometry (TDT) Sensors, gypsum blocks, tensiometers, granular matrix sensors, and others. Farmers and organizations engaged in contract farming prefer using soil moisture sensors for improved crop productivity, data-driven decision-making, process enhancements, enhanced irrigation monitoring, and more.
Application Insights
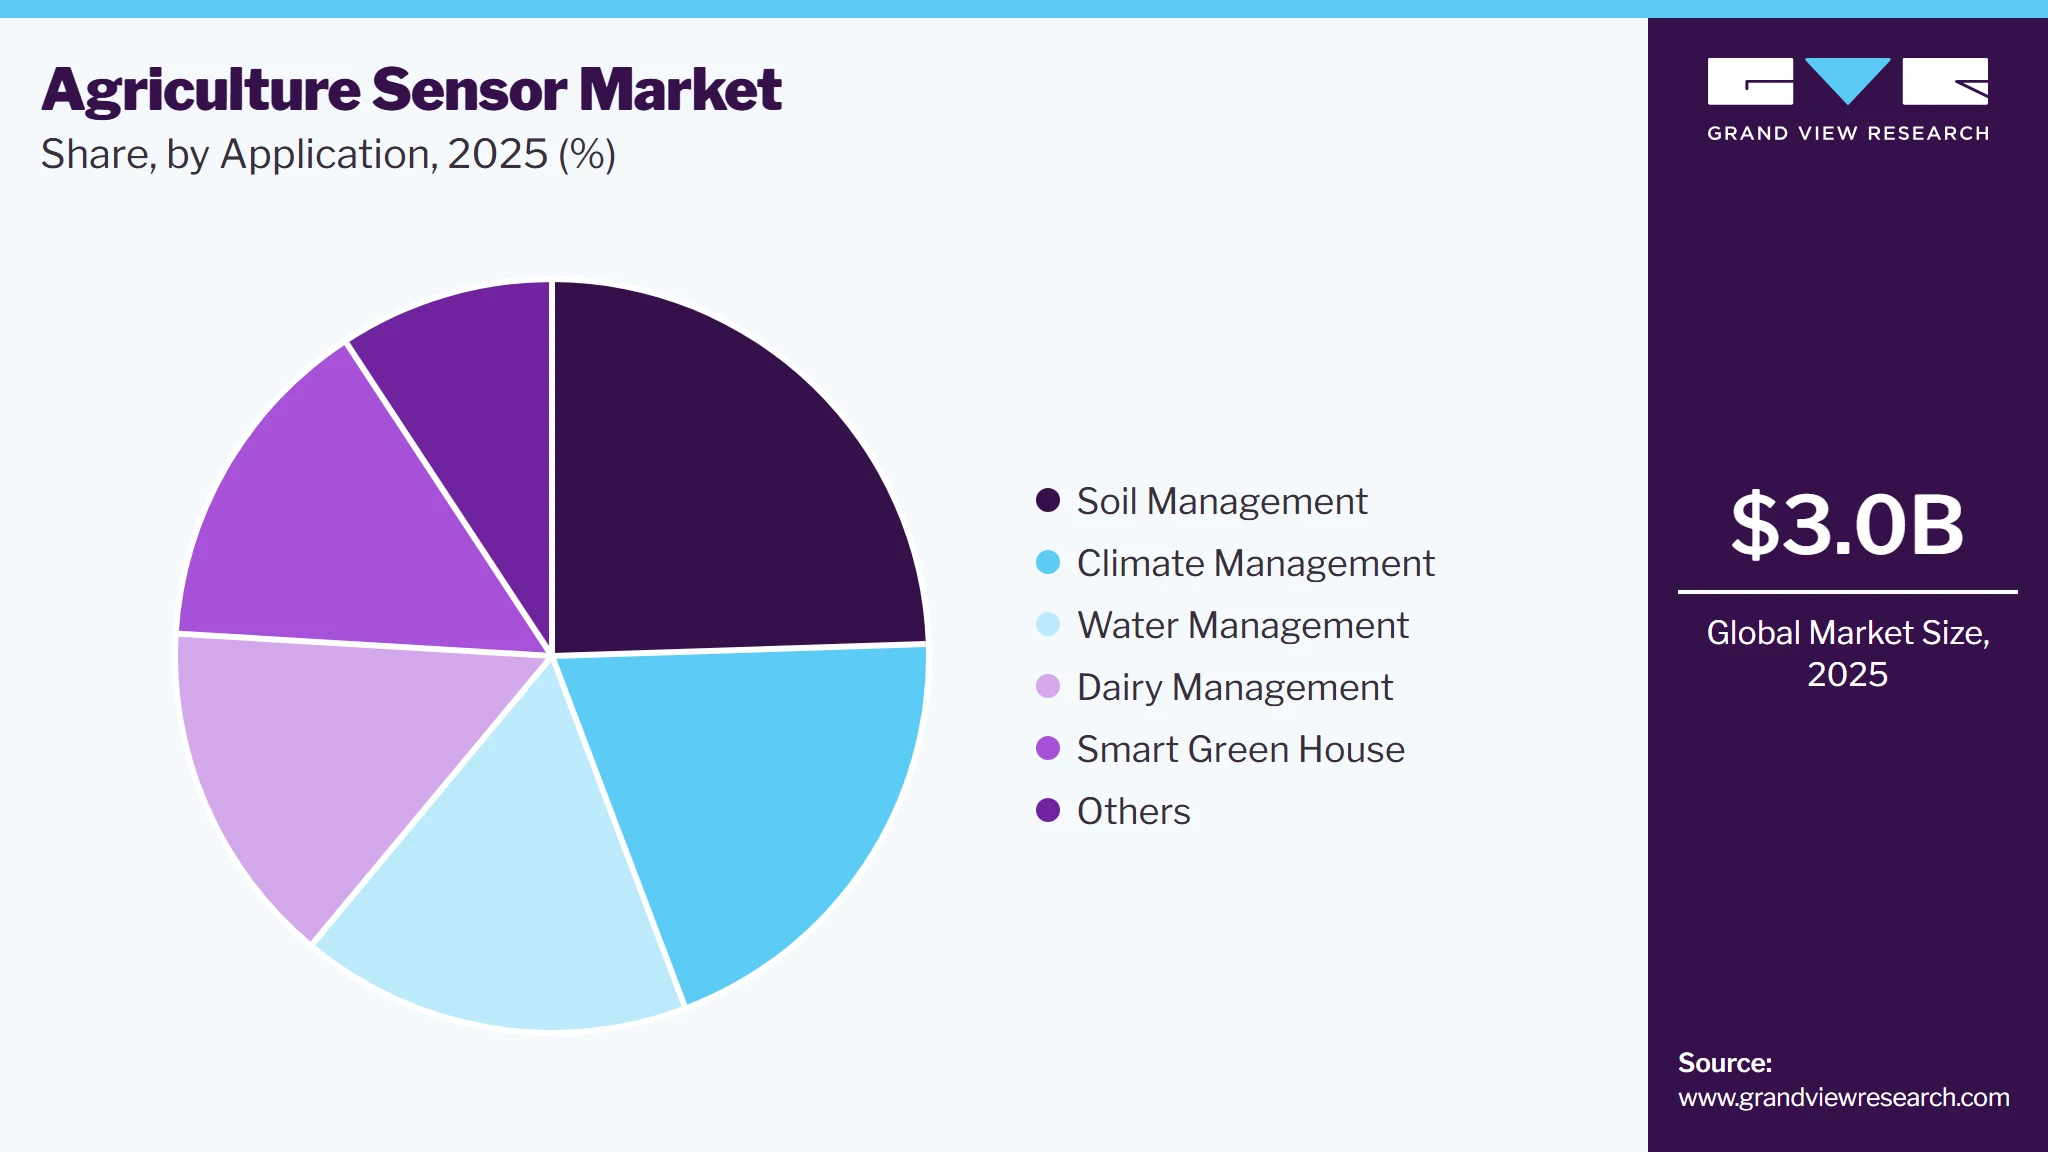
Based on application, the soil management segment led the market with the largest revenue share of 24.5% in 2025. This is attributed to factors such as increasing demand from large land farmers, contract agriculture projects, and other industries. The data provided by the sensors regarding factors such as water retention level, moisture level, soil health, and others enables users to plan further actions associated with a variety of processes such as irrigation, fertilizing soil, crop rotation, tillage, composting, sediment control, regulating water supply to crops, and more.
 To learn more about this report, Download Free Sample Report
The smart green house segment is anticipated to experience the fastest growth from 2025 to 2030. Growth of this segment is mainly driven by the increasing adoption of precision farming practices. The significance of temperature monitoring and soil moisture management in smart green houses, efficient use of water and other resources associated with green house farming, and dependency on data-driven insights are expected to generate growth of this segment.
Regional Insights
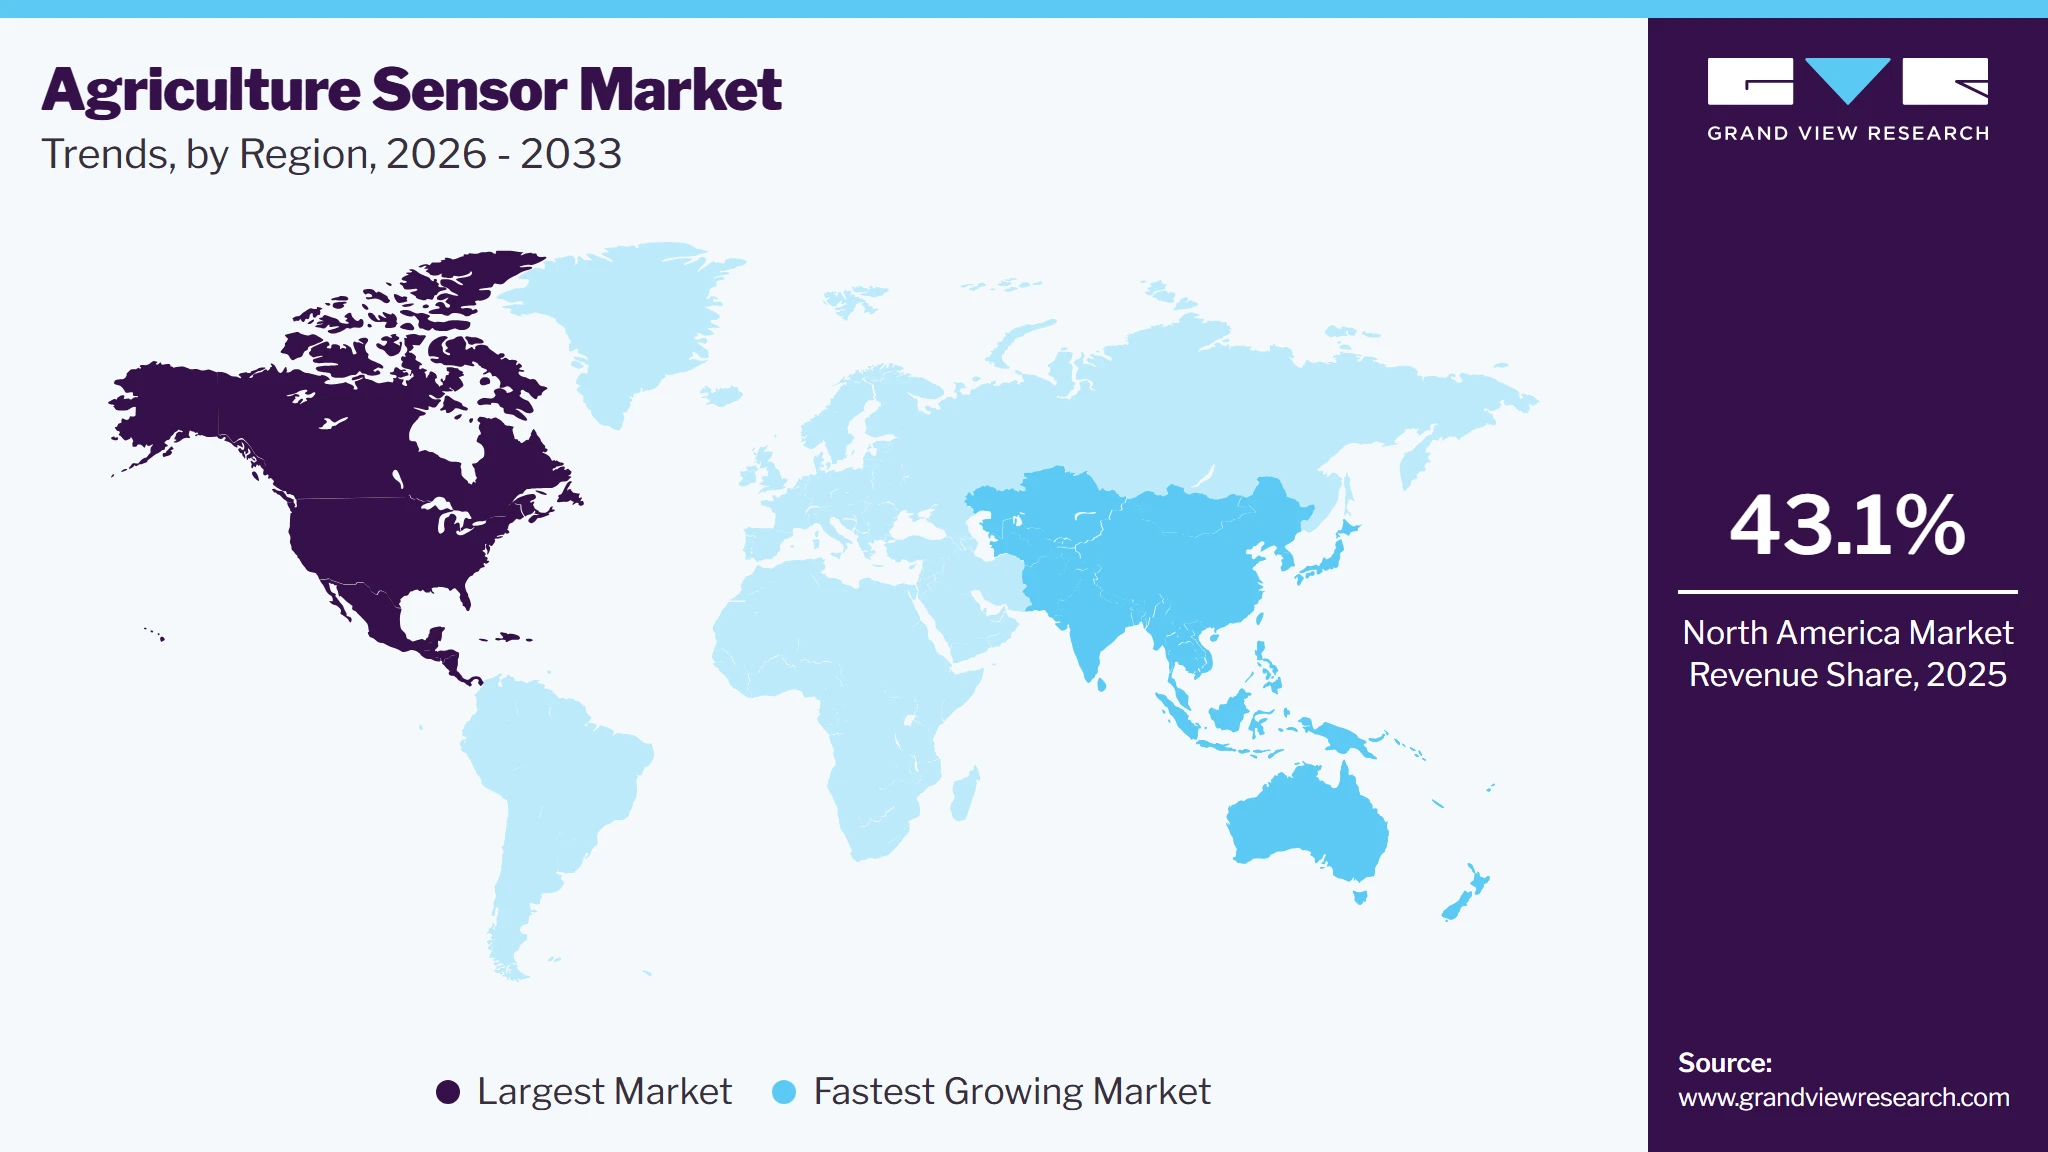
North America dominated the global agriculture sensor market with the largest revenue share of 43.1% in 2025. The growth of this market is mainly driven by the increasing adoption of technology assistance by farmers in the region, the presence of large landowners operating in the agriculture industry, and the presence of multiple agriculture technology product manufacturers in the region. A significant increase in modern farming practices such as precision farming, irrigation automation, and others is likely to add lucrative growth opportunities for this market in the next few years.
 To learn more about this report, Download Free Sample Report
U.S. Agriculture Sensor Market Trends
The agriculture sensor market in the U.S. held the largest share in the North America region in 2025. This market is influenced by factors such as the robust technology industry operating in the country and the increasing availability of agriculture technology systems and solutions that operate with the help of data inputs provided by agriculture sensors. The increasing adoption of software solutions and intelligence systems that offer significant insights derived from the vast amounts of data collected by sensors is expected to generate growth in demand for this market over the forecast period.
Europe Agriculture Sensor Market Trends
Europe was identified as one of the key regions of the global agriculture sensors industry in 2024. An increase in demand for fresh produce, organically grown crops, grains, pulses, and produce used in the development of multiple food products has developed the need for advanced farming technology and practices assisted by modern technology capabilities. This includes agriculture sensors, numerous pieces of equipment, software solutions, and more. Increasing awareness regarding benefits associated with data-driven decision-making and enhanced performances facilitated by improved management and process implementation are anticipated to add growth.
The UK held the largest revenue share of the regional industry in 2024. Increasing precision farming practices in the country, growing sustainability awareness, technology advancements adopted by industry participants, and increasing government support for modern technology-driven agriculture solutions are some of the key growth factors for this market.
Asia Pacific Agriculture Sensor Market Trends
Asia Pacific agriculture sensor market is anticipated to experience the highest growth over the forecast period. Agriculture is one of the most significant industries in countries such as China, India, Australia, and others. Government agencies and organizations have been encouraging farmers to embrace cutting-edge technology-based solutions. Increasing demand for grains and pulses, overall growth in food demand, ease of use and convenience offered by the user-friendly technology tools, and evidence of improved results associated with the use of technology are some of the key factors that are anticipated to influence the growth of this market.
Australia agriculture sensor market dominated the regional industry in 2024. This is attributed to factors such as the increasingly large share of the agriculture industry in domestic production, the increasing focus of farmers on adopting advanced technologies to reduce costs and improve performance, and the enhanced availability of software solutions supported by the data collected through sensors.
Key Agriculture Sensor Company Insights
Some key companies in the global agriculture sensor industry include CropX Inc., Deere & Company, METER, Sentera, Climate LLC and others. To address growing competition and increasing demand for technologically advanced sensors, the market participants have been embracing strategies such as acquisitions, portfolio expansions, geographical expansions, collaborations and others.
-
CropX Inc. is an agricultural technology innovation company that offers a digital agronomy platform equipped with advanced technology capabilities. The platform provided by the company is characterized by a user-friendly interface, data collection and processing capabilities, easy-to-install hardware, and more.
-
Sentera, a precision agriculture innovation-driven organization, offers a wide range of solutions and technology-based products, including sensors. Its sensor portfolio features the 6X sensor series, 65R sensor, Sentera DGR system, Double 4K, custom sensors, PHX fixed wing, single sensor, and others.
Key Agriculture Sensor Companies
The following key companies have been profiled for this study on the agriculture sensor market.
-
Acclima Inc.
-
auroras S.r.l.
-
Climate LLC
-
CropX inc.
-
Deere & Company
-
Libelium Comunicaciones Distribuidas S.L.
-
METER
-
Pycno
-
Sentera
-
Soil Scout Oy
-
SOLCHIP
-
Texas Instruments Incorporated
-
Trimble Inc.
-
Yara
-
Zenvus
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Deere & Company; Bosch; Trimble; Topcon Positioning Systems; TE Connectivity)
- Mature players focus on expanding multi-sensor portfolios for soil, climate, machinery, and crop monitoring while integrating sensor data with precision agriculture platforms and automated farm equipment. They invest heavily in sensor accuracy, rugged hardware, and long-term field reliability to support large-scale commercial farming operations.
- Strong manufacturing capabilities, established agricultural distribution networks, and proven performance in diverse farming environments enable these companies to deliver dependable sensing solutions at scale. Their comprehensive product ecosystems also simplify integration with tractors, irrigation systems, and farm management software.
- Hardware-intensive product development requires high capital investment and extended product validation under varying environmental conditions. Dependence on agricultural equipment sales cycles and replacement demand can also influence revenue growth.
Emerging Players (CropX; Arable; Teralytic; Pycno; AquaSpy)
- Emerging players concentrate on intelligent wireless sensors, AI-based crop diagnostics, and subscription-based farm monitoring services that provide real-time agronomic insights. They emphasize rapid installation, cloud connectivity, and data-driven decision support for precision farming without requiring extensive infrastructure investments.
- Their specialized technologies enable continuous field monitoring, faster deployment, and highly targeted recommendations that improve the efficiency of water, fertilizer, and crop management. Flexible business models and innovation in smart sensing also allow them to respond quickly to evolving precision agriculture requirements.
- Limited global distribution capabilities and smaller production capacity can restrict large-scale commercialization. Building farmer confidence and demonstrating consistent performance across different crops and climatic conditions also remain important adoption challenges.
Recent Developments
-
In September 2024, CropX Inc., one of the market players in agricultural technology, acquired technology application startup, EnGeniousAg. The startup delivered innovation-based nitrogen sensing technique to assist farmers in optimizing nitrogen fertilizer application while reducing the environmental impact.
-
In January 2024, Ethos Connected, a company with a portfolio of environmental and agriculture technology solutions, unveiled its sensor production facility in Lincoln, Nebraska. The strategically located facility is anticipated to assist local farmers and the agriculture ecosystem in the state of Nebraska in continuing to play their crucial role through water conservation, technology advancements, and more.
Agriculture Sensor Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.0 billion
Estimated market size in 2026
USD 3.3 billion
Projected market size by 2033
USD 7.6 billion
Growth rate
CAGR of 12.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company market share analysis, competitive landscape, growth factors, and trends
Segments covered
Type, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; China; Japan; India; South Korea; Australia; Brazil; Saudi Arabia; South Africa; UAE
Key companies profiled
Acclima Inc.; auroras S.r.l.; Climate LLC; CropX inc.; Deere & Company; Libelium Comunicaciones Distribuidas S.L.; METER; Pycno; Sentera; Soil Scout Oy; SOLCHIP; Texas Instruments Incorporated; Trimble Inc.; Yara; Zenvus
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Agriculture Sensor Market Report Segmentation
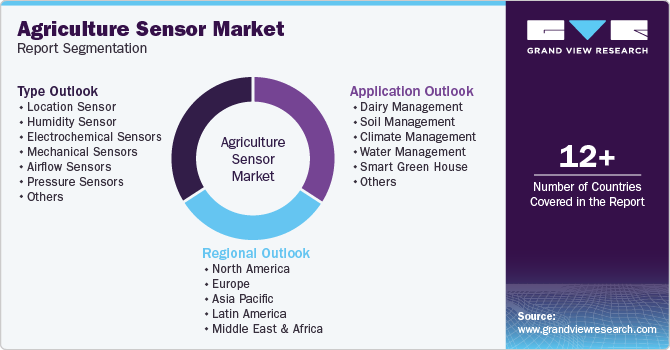
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, grand view research has segmented the global agriculture sensor market report based on type, application, and region.
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Location Sensor
-
Humidity Sensor
-
Electrochemical Sensors
-
Mechanical Sensors
-
Airflow Sensors
-
Pressure Sensors
-
Optical Sensors
-
Water Sensors
-
Soil Moisture Sensors
-
Capacitance Sensors
-
Probes
-
Time Domain Transmissometry (TDT) Sensors
-
Gypsum Blocks
-
Tensiometers
-
Granular Matrix Sensors
-
-
Livestock Sensors
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Dairy Management
-
Soil Management
-
Climate Management
-
Water Management
-
Smart Green House
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Singapore
-
-
Latin America
-
Brazil
-
-
MEA
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The agriculture sensor market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each agriculture sensor segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Location Sensor
Market value is captured through GPS- and GNSS-enabled sensors that provide precise positioning for tractors, drones, autonomous equipment, and field operations. Equipment manufacturers and precision agriculture solution providers integrate these sensors to improve navigation accuracy, field mapping, and operational efficiency.
Humidity Sensor
Commercial demand is driven by the need to continuously monitor ambient and crop humidity to optimize irrigation, disease prevention, and greenhouse climate control. Growers invest in these sensors to maintain ideal growing conditions while minimizing crop losses caused by excessive or insufficient moisture.
Electrochemical Sensors
Value is created by sensors that measure soil nutrients, pH, dissolved oxygen, and chemical composition for precision farming applications. Adoption is increasing as producers seek data-driven fertilizer management and improved soil health monitoring to enhance crop productivity.
Mechanical Sensors
Market activity centers on sensors that detect vibration, force, motion, and equipment performance in agricultural machinery. These devices support predictive maintenance strategies, helping farmers reduce equipment downtime and extend machinery lifespan.
Airflow Sensors
Revenue opportunities arise from monitoring ventilation performance within livestock housing, grain storage facilities, and controlled-environment agriculture. Efficient airflow management contributes to healthier livestock conditions, stable greenhouse climates, and improved post-harvest storage quality.
Pressure Sensors
Demand is supported by applications involving irrigation systems, hydraulic equipment, spraying systems, and fluid management infrastructure. Accurate pressure monitoring enables operators to improve equipment performance, optimize water distribution, and reduce system failures.
Optical Sensors
The largest technology-driven sensor category, supporting crop health assessment, disease detection, canopy analysis, and precision spraying. Suppliers benefit from increasing adoption of AI-enabled imaging, multispectral sensing, and drone-based agricultural monitoring solutions.
Water Sensors
Commercial value is derived from continuous monitoring of water quality, storage levels, irrigation networks, and aquaculture systems. Farmers utilize these sensors to improve water-use efficiency, detect contamination, and support sustainable water resource management.
Segment - Application
Revenue capture definition
Dairy Management
Revenue is generated through sensor deployments that monitor milk yield, animal health, feeding activity, reproductive cycles, and barn conditions. Dairy farms invest in sensor-based automation to improve herd performance, reduce labor requirements, and enhance milk production efficiency.
Soil Management
Market value is created by integrating sensor data into soil fertility assessment, nutrient optimization, moisture monitoring, and precision input application. These technologies help growers make informed agronomic decisions while reducing fertilizer waste and improving long-term soil productivity.
Climate Management
Commercial opportunities stem from solutions that continuously monitor temperature, humidity, solar radiation, and environmental conditions affecting crop growth. Agricultural producers increasingly rely on climate sensing to optimize growing environments and minimize weather-related production risks.
Water Management
Investment is directed toward sensor-enabled irrigation systems that monitor water availability, distribution efficiency, and consumption patterns. These solutions support sustainable farming by improving irrigation precision, conserving water resources, and lowering operational costs.
Smart Green House
The largest controlled-environment application, utilizing integrated sensor networks to automate lighting, ventilation, irrigation, nutrient delivery, and climate regulation. Greenhouse operators prioritize these technologies to maximize crop quality, improve resource efficiency, and achieve consistent year-round production.
Others
This category includes crop storage monitoring, aquaculture management, pest detection, precision spraying, forestry, and agricultural research applications. Expanding digital agriculture initiatives continue to create new opportunities for specialized sensor deployments across diverse farming systems.
Estimation Model
Layer
Question
Analysis
Field Monitoring Layer
What agricultural conditions require sensing and continuous monitoring?
Identify the biological and environmental parameters that influence crop and livestock productivity, including soil moisture, soil nutrients, temperature, humidity, rainfall, leaf wetness, pH levels, water quality, and livestock health indicators. This layer defines demand based on the need for continuous, real-time field intelligence that enables farmers to detect changing conditions before they negatively affect production.
Sensor Deployment Layer
Where and how are agricultural sensors installed?
Assess the deployment of sensors across open fields, greenhouses, orchards, vineyards, irrigation systems, weather stations, storage facilities, and livestock operations. Installation decisions depend on crop type, farm topology, communication infrastructure, power availability, and compatibility with precision agriculture equipment, ensuring that data is collected from the most critical production points.
Data Acquisition & Farm Intelligence Layer
How is sensor data transformed into operational decisions?
Analyze the integration of sensor networks with IoT platforms, farm management software, GPS-enabled machinery, drones, satellite imagery, and AI-based analytics. The collected data supports automated irrigation scheduling, nutrient management, disease and pest forecasting, climate risk assessment, and precision input application, allowing farmers to make timely, evidence-based decisions throughout the growing season.
Precision Farming Value Layer
How is economic value generated from agricultural sensor technologies?
Evaluate revenue streams from sensor hardware, wireless communication modules, monitoring gateways, cloud-based analytics subscriptions, calibration services, and predictive agronomic advisory solutions. Long-term value is created through higher crop productivity, optimized use of water and fertilizers, reduced operational waste, lower environmental impact, and recurring revenues from connected farm monitoring platforms and decision-support services.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Field Sensing & Environmental Monitoring Trends
Conducted a focused analysis of agriculture sensor deployment for soil moisture, soil nutrients, temperature, humidity, pH, leaf wetness, and weather monitoring across open-field farming, greenhouses, and orchards.
Helps stakeholders identify high-demand sensing applications, evaluate precision monitoring trends, and assess commercialization opportunities in real-time agricultural sensing technologies.
Crop Health Detection & Precision Input Management Adoption Trends
Evaluated adoption trends for sensor-based irrigation scheduling, nutrient monitoring, disease detection, and microclimate analysis, including integration with variable-rate application systems and automated farm equipment.
Provides insights into resource optimization requirements, crop health management strategies, and commercially attractive sensor solutions that improve farm productivity while reducing input waste.
Smart Sensor Networks & Farm Connectivity Opportunity Assessment
Assessed demand for wireless sensor networks, edge-enabled sensing devices, LoRaWAN- and NB-IoT-based agricultural monitoring systems, and cloud-connected sensor platforms, along with challenges related to sensor calibration, battery life, rural connectivity, and interoperability with digital farming ecosystems.
Supports investment and expansion strategies by identifying next-generation sensing opportunities, evaluating technology readiness, and strengthening long-term growth potential in connected and intelligent agriculture infrastructure.
Frequently Asked Questions About This Report
The global agriculture sensor market size was valued at USD 3.0 billion in 2025 and is estimated at USD 3.3 billion in 2026.
The global agriculture sensor market is expected to grow at a CAGR of 12.6% from 2026 to 2033 to reach USD 7.6 billion by 2033.
Key factors include the rising adoption of precision agriculture practices, increasing adoption of smart farming technologies, and rising adoption of edge computing for real-time agricultural monitoring.
North America dominated with 43.1% revenue share in 2025.
The location sensor segment led the market with the largest revenue share of 13.7% in 2025.
Asia Pacific is the fastest-growing region over the forecast period.
The soil management segment led the market with the largest revenue share of 24.5% in 2025.
Key players operating in the agriculture sensor market include AGCO Corporation; Autonomous Solutions, Inc.; BouMatic; CNH Industrial N.V.; CLAAS KGaA mbH; GEA Group Aktiengesellschaft; Harvest Automation, Inc.; Trimble, Inc.; Agrobot, Lely; DeLaval.
About the Author(s)
Sensors & Controls Research Team
Semiconductors & Electronics · Sensors & ControlsThis report was authored by the sensors & controls research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the sensors & controls segment of the semiconductors & electronics industry. All findings are based on proprietary semiconductors & electronics databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


