
- Home
- »
- Advanced Interior Materials
- »
-
Air Handling Units Market Size And Share Report, 2026-2033GVR Report cover

Air Handling Units Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Single Flux, Double Flux), By Type (Packaged, Modular), By Capacity (Up To 5,000 m3/h), By Application (Commercial, Industrial), By Region, And Segment Forecasts
Market Size, 2025
$11.3BMarket Estimate, 2026
$11.9BMarket Forecast, 2033
$18.1BCAGR, 2026–2033
6.2%Air Handling Units Market Summary
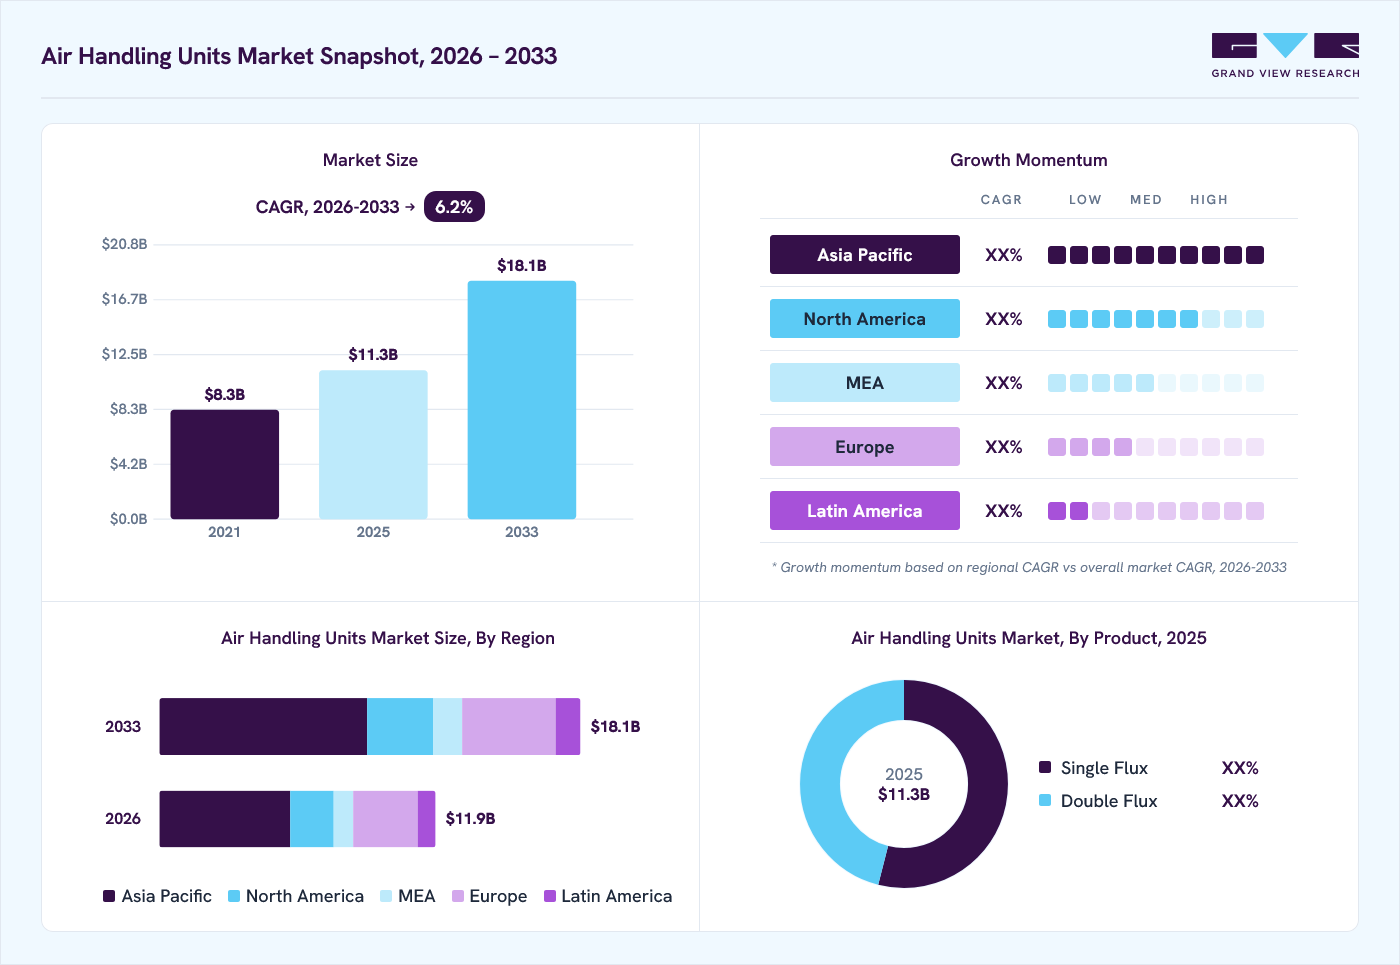
The global air handling units market size was valued at USD 11.3 billion in 2025 and is projected to grow from USD 11.9 billion in 2026 to USD 18.1 billion by 2033, at a CAGR of 6.2% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 47.0% in 2025. The demand for air handling units (AHUs) is rising due to increasing urbanization, growing construction activities, and the need for energy-efficient HVAC systems.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Single flux segment dominated the market, with a revenue share of 53.9% in 2025.
- By type: Packaged segment held the largest market share of 58.5% in 2025.
- By capacity: Up to 5,000 m3/h segment held the largest revenue share of 32.6% in 2025.
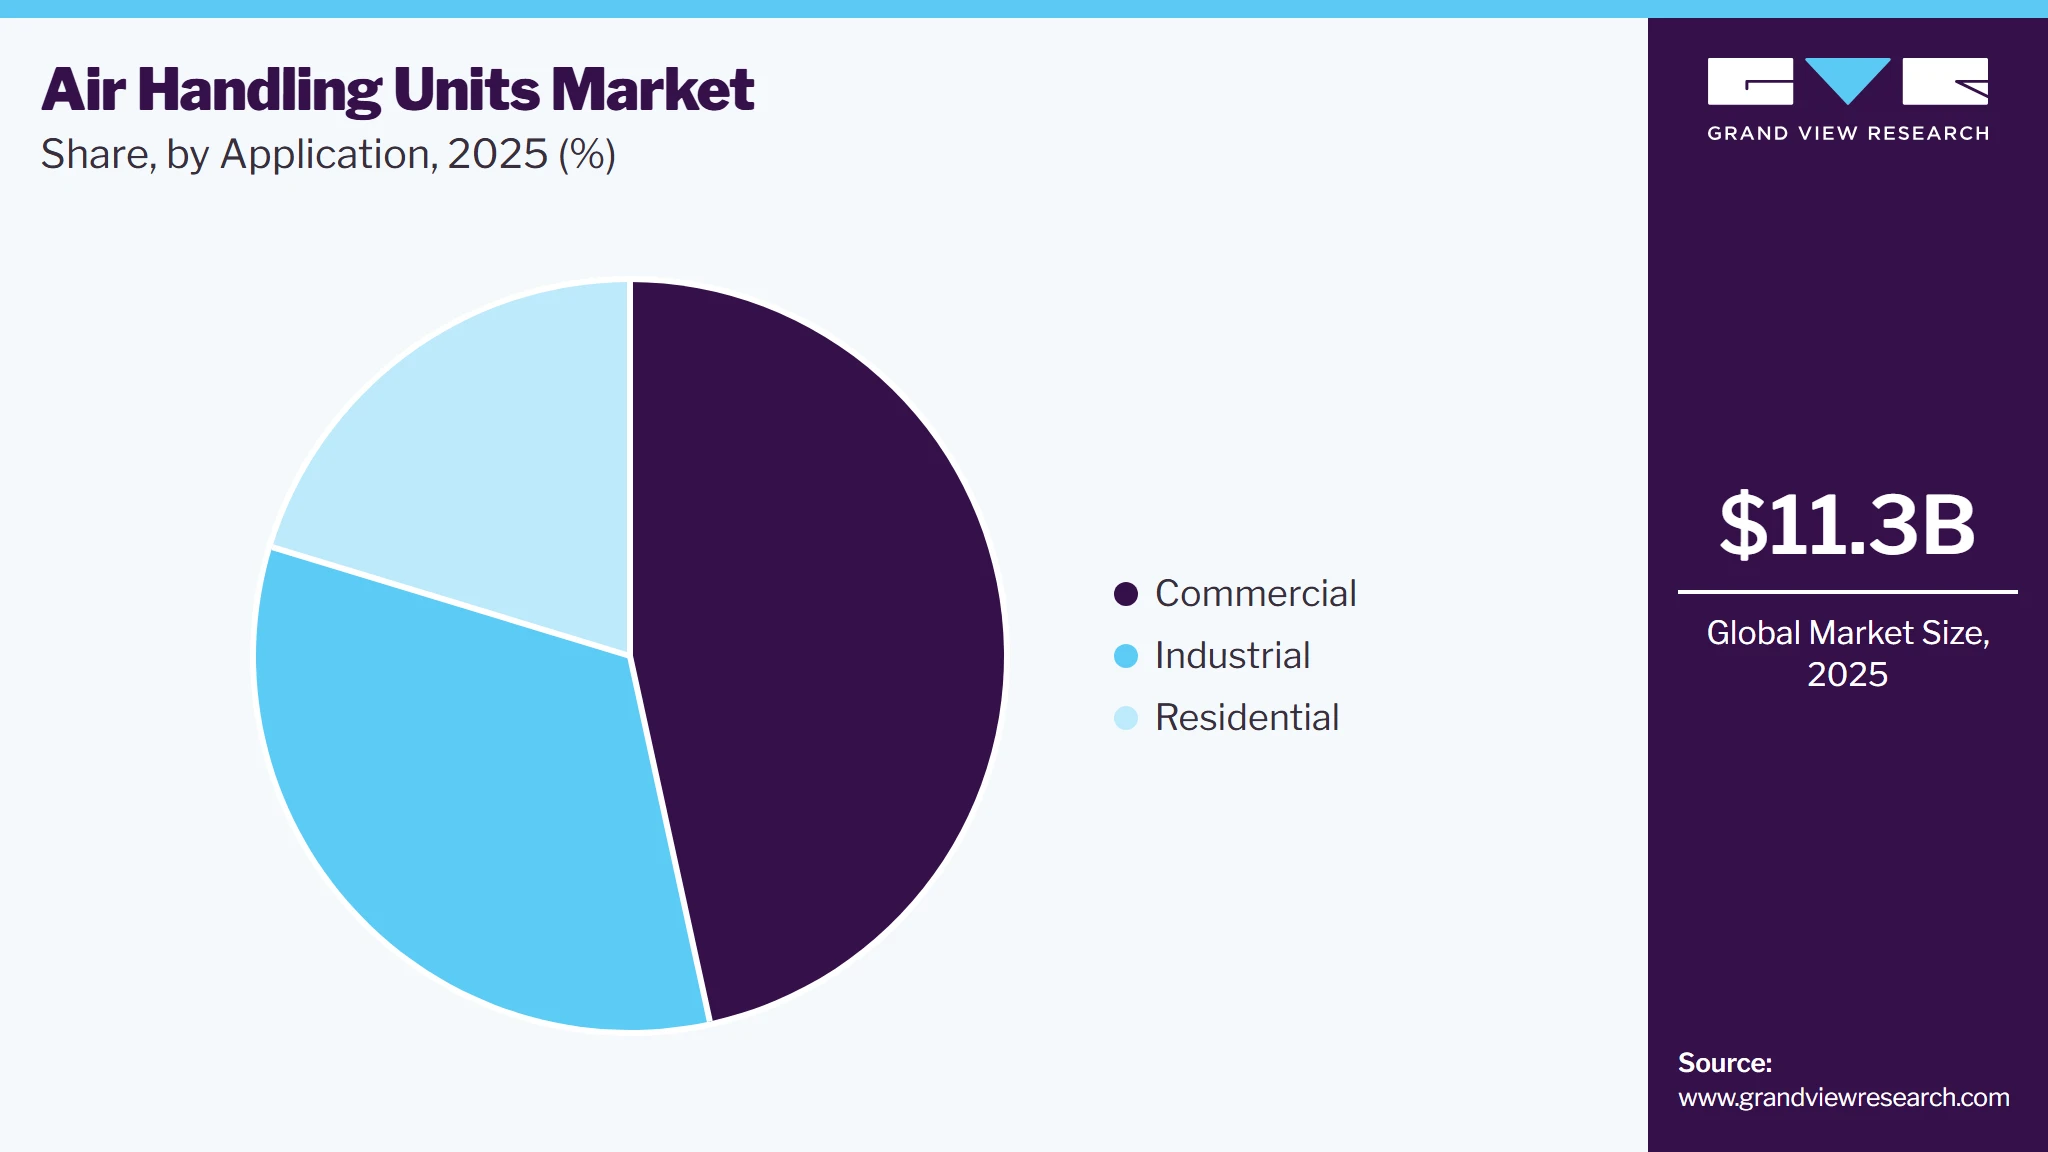
- By application: Commercial segment accounted for the largest revenue share of 46.6% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (47.0% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 11.3 Billion
- Estimated market size in 2026: USD 11.9 Billion
- Projected market size by 2033: USD 18.1 Billion
- CAGR (2026-2033): 6.2%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
According to the World Health Organization (WHO), approximately 55% of the global population currently lives in urban areas, and this figure is expected to increase to 68% by 2050, driving the demand for commercial and residential buildings that require AHUs. Government initiatives like the "National Infrastructure Program" in India boost construction projects, further fueling the need for AHUs. Additionally, the growing awareness of the benefits of AHUs, such as maintaining fresh air quality and thermal comfort in indoor spaces, contributes to their popularity. Furthermore, the growing global population is increasing the requirements for affordable housing units and enhanced commercial infrastructure. According to the United Nations, the global population is expected to reach 9.7 billion in 2050, exhibiting a growth of 2 billion in the next 30 years. This significant increase in the worldwide population is facilitated by the improving standard of living of the masses, increasing lifespan, decreasing mortality rate, and ongoing technological advancements. The growing global population also pressures the real estate sector to provide affordable housing. As such, new housing projects are being launched worldwide. This is expected to positively impact the growth of the market over the forecast period.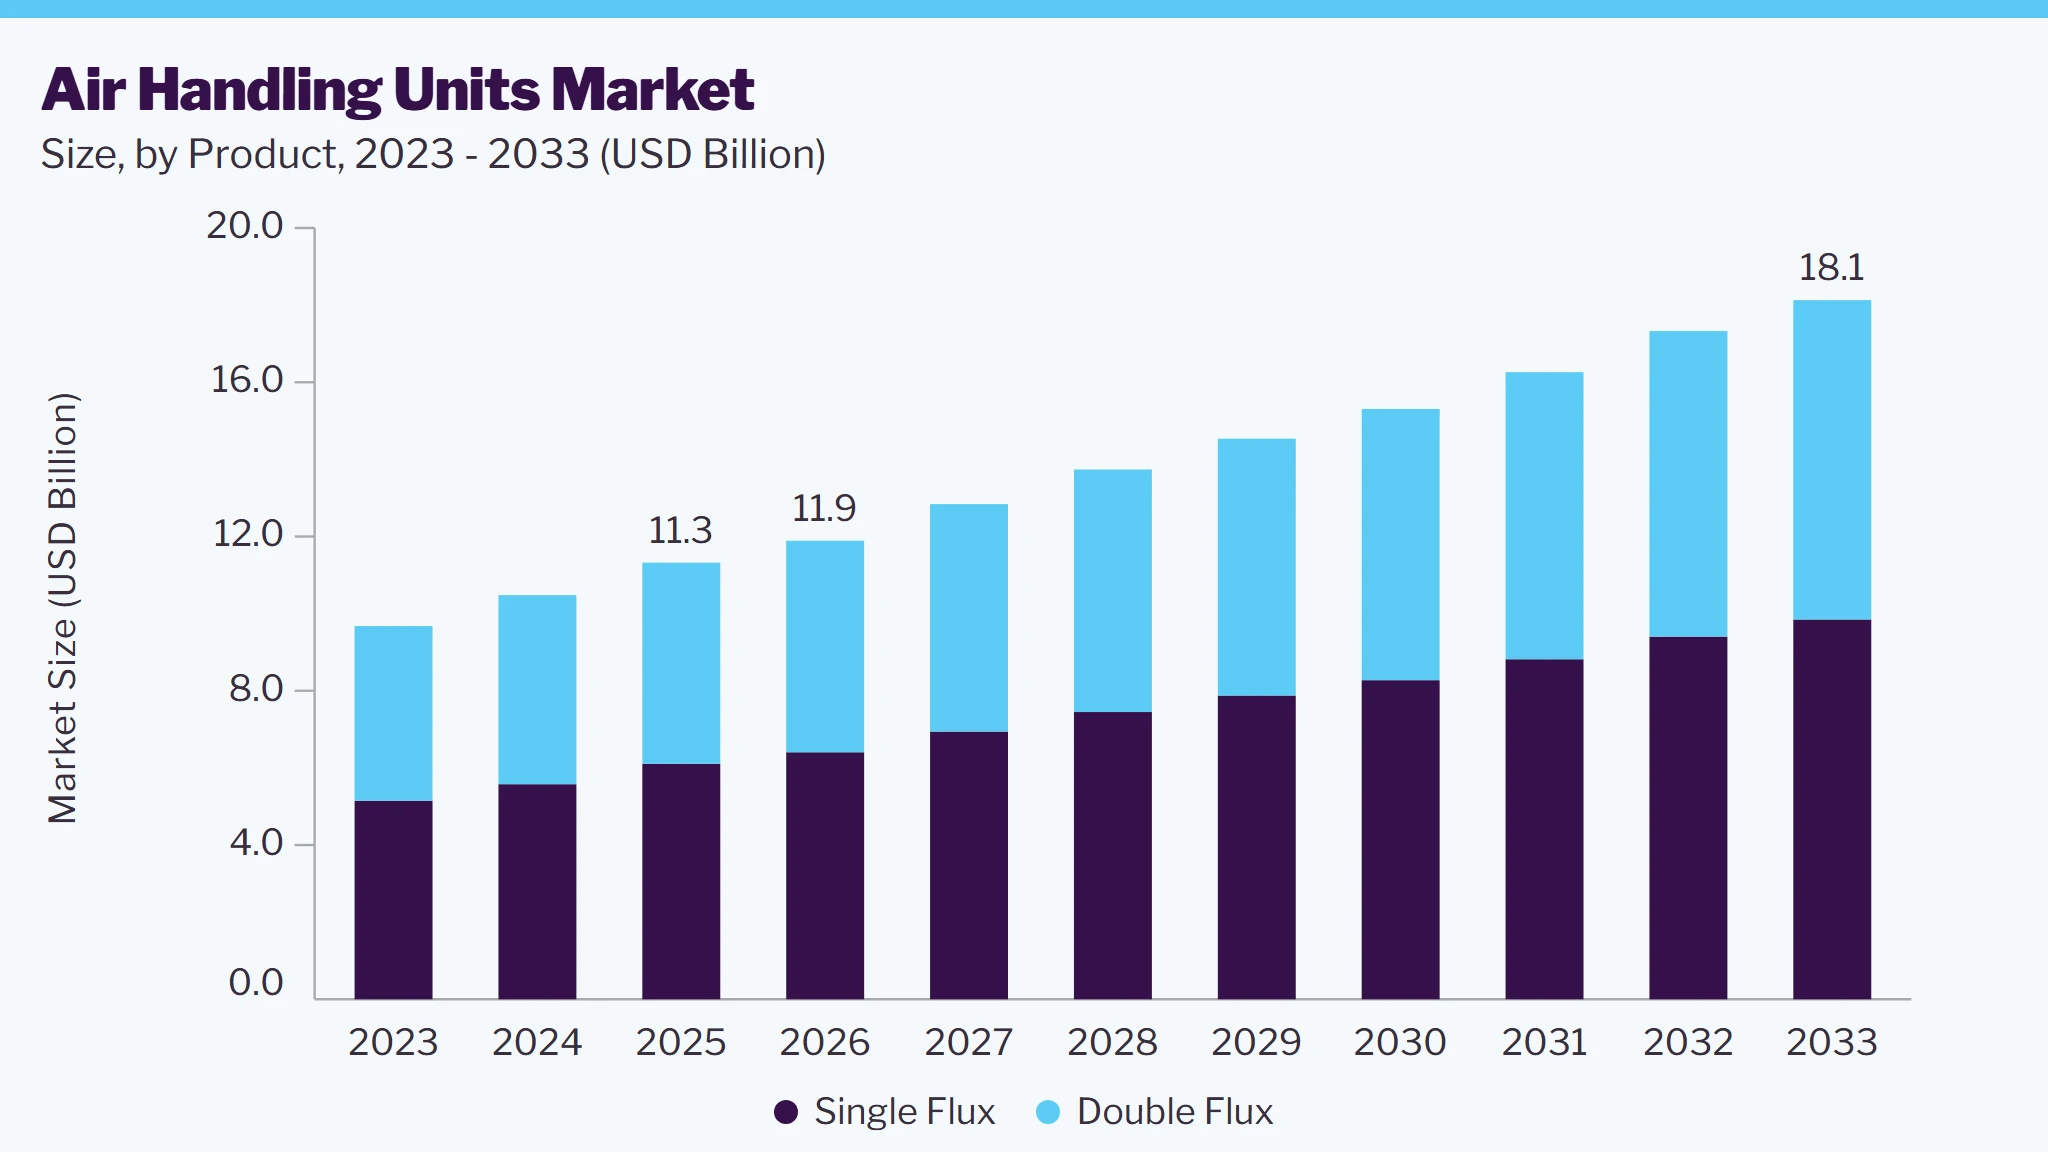 To learn more about this report, Download Free Sample Report
Moreover, governments worldwide provide monetary support to customers by introducing various housing schemes. For instance, the Government of Canada announced through the 2023 Fall Economic Statement a new loan funding worth USD 15 billion, USD 9 billion more than the previous funding. With the increasing support from the governments of different countries and the requirement for affordable housing, the residential construction industry is flourishing worldwide. This is expected to surge the demand for market over the forecast period.
Market Dynamics
The global air handling units (AHU) market is influenced by the growing emphasis on energy-efficient building infrastructure, stricter indoor air quality standards, and the modernization of commercial and industrial HVAC systems. Demand is expanding across healthcare facilities, data centers, educational institutions, manufacturing plants, and commercial buildings where reliable ventilation and climate control are essential. Regulatory frameworks promoting energy conservation and low-emission buildings are encouraging the adoption of high-efficiency AHUs equipped with advanced filtration, heat recovery systems, variable-speed fans, and intelligent control technologies. At the same time, retrofit activities in aging buildings and the integration of building automation systems are creating opportunities for equipment upgrades with enhanced operational efficiency.
The increasing focus on energy-efficient buildings and enhanced indoor air quality is driving the adoption of advanced air handling units across residential, commercial, and industrial facilities. Stricter building energy codes, green building certification programs, and ventilation standards are encouraging the installation of AHUs equipped with high-efficiency fans, energy recovery systems, advanced filtration, and intelligent controls. The expansion of healthcare facilities, data centers, educational institutions, and commercial infrastructure is further contributing to the demand for reliable air handling solutions that improve occupant comfort while reducing energy consumption.
The air handling units market faces challenges associated with high initial investment and the complexity of integrating AHUs into existing building infrastructure. Large-scale systems often require customized designs, structural modifications, ductwork upgrades, and skilled installation, increasing overall project costs. Retrofit projects in aging buildings can involve extended installation timelines and operational disruptions, which may discourage facility owners from replacing conventional ventilation equipment despite the long-term efficiency benefits.
The growing implementation of smart buildings and digital facility management platforms is creating substantial opportunities for the air handling units market. Building owners are increasingly investing in AHUs integrated with IoT-enabled sensors, predictive maintenance capabilities, cloud-based monitoring, and automated airflow control to improve operational efficiency and reduce lifecycle costs. The modernization of commercial buildings, hospitals, airports, manufacturing facilities, and other large infrastructure projects is accelerating the demand for intelligent air handling solutions capable of supporting data-driven energy optimization and sustainable building operations.
Market Concentration & Characteristics
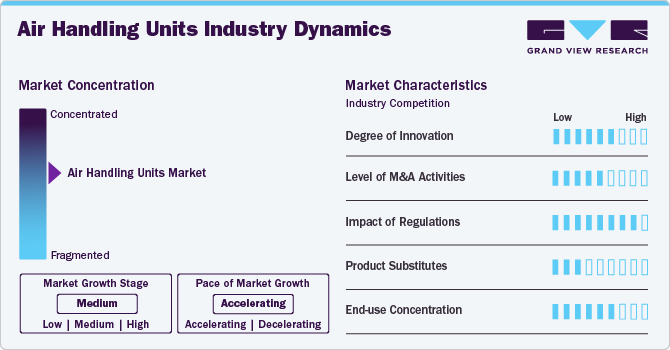
The air handling units industry presents a moderately fragmented competitive landscape, featuring a mix of well-established global manufacturers and emerging regional players. Leading companies such as Johnson Controls, Daikin Industries, Trane Technologies, Carrier Global Corporation, and Systemair AB maintain strong market positions through comprehensive product offerings and expansive global operations. Simultaneously, local manufacturers play a vital role by addressing region-specific demands and ensuring compliance with local building codes and environmental standards.
Market growth is primarily influenced by rising environmental concerns and stringent regulations focused on improving energy efficiency and indoor air quality. Governments and regulatory bodies are increasingly mandating the use of energy-efficient HVAC systems in new constructions and retrofits, driving the adoption of advanced AHUs. These policy measures are not only stimulating demand but also encouraging innovation in design and functionality.
 To learn more about this report, Download Free Sample Report
Technological progress is a key driver shaping the AHU industry, with advancements such as energy recovery systems, smart controls, and variable air volume (VAV) technology enhancing the performance and efficiency of AHUs. These innovations enable units to better adapt to changing indoor climate needs and reduce overall energy consumption, making them more suitable for modern, sustainable buildings.
Regionally, North America commands a significant share of the market due to robust commercial and residential construction activity and supportive regulatory frameworks promoting energy-efficient solutions. Europe follows closely, driven by strong sustainability targets and renovation initiatives. Meanwhile, the Asia-Pacific region is witnessing rapid growth, supported by urbanization, infrastructure expansion, and increasing awareness of indoor air quality in major economies like China and India.
Analyst Perspective
The air handling units market is expanding steadily as demand for energy-efficient HVAC systems and improved indoor air quality continues to increase across commercial, industrial, healthcare, and institutional buildings. Growing investments in commercial construction, data centers, healthcare facilities, and manufacturing plants are encouraging the adoption of advanced air handling units capable of delivering precise air flow control, temperature regulation, and high-performance filtration. In addition, increasingly stringent building energy codes and sustainability initiatives are accelerating the deployment of high-efficiency systems equipped with EC motors, heat recovery technologies, and intelligent building management integration.
Product Insights
Based on product, the single flux segment led the market with the largest revenue share of 53.9% in 2025.. The need for efficient and cost-effective HVAC solutions in various applications drives the demand for single-flux and double-flux air handling units. Single-flux AHUs are commonly used in smaller commercial and residential spaces, providing a simple and economical way to condition the air. For example, single-flux AHUs are often installed in small offices, retail stores, and single-family homes.
Double-flux AHUs, on the other hand, are designed for larger and more complex buildings, as they offer improved energy efficiency and better control over indoor air quality. These units are frequently used in hospitals, schools, and large commercial complexes where precise temperature and humidity control are essential. The growing construction of commercial and residential buildings, particularly in developing regions, is fueling the demand for single-flux and double-flux air handling units to meet the increasing need for comfortable and healthy indoor environments.
Type Insights
Based on type, the packaged segment led the market with the largest revenue share of 58.5% in 2025. Packaged AHUs are pre-assembled units with ease of installation, cost-effectiveness, and compact design. The increasing demand for energy-efficient and space-saving HVAC solutions in commercial and residential applications is driving the growth of packaged AHUs.
The modular air handling units segments are expected to grow significantly due to their flexibility, scalability, and ability to meet specific application requirements. Modular air handling units are increasingly used in commercial and industrial applications due to their flexibility, efficiency, and ability to maintain high indoor air quality. They are commonly found in office buildings, shopping malls, hospitals, hotels, and other large facilities requiring precise temperature and humidity control. These factors above are anticipated to drive the demand for air handling units industry over the forecast period.
Capacity Insights
Based on capacity, the up to 5,000 m3/h segment led the market with the largest revenue share of 32.6% in 2025, owing to the increasing adoption of AHUs in small and large-scale applications such as warehouses, industrial facilities, kitchens, and food service properties. Moreover, smaller capacity AHUs are generally more cost-effective than larger units, making them attractive options for residential and small commercial projects with limited budgets. Their lower upfront costs contribute to their widespread adoption.
The demand for air handling units (AHUs) with capacities ranging from 30,001 to 50,000 m³/h is witnessing steady growth, primarily driven by the expansion of large commercial, industrial, and institutional facilities such as airports, hospitals, data centers, and manufacturing plants. These mid-to-large capacity AHUs are increasingly preferred for their ability to deliver high airflow volumes while integrating advanced energy-saving technologies like energy recovery systems, variable frequency drives (VFDs), and smart control systems. Growing emphasis on indoor air quality and compliance with stringent ventilation and energy efficiency regulations also propels demand, particularly in regions with robust infrastructure development and retrofitting initiatives.
Application Insights
Based on application, the commercial segment led the market with the largest revenue share of 46.6% in 2025. The growing number of commercial spaces such as shopping malls, offices, theatres, and hotels is anticipated to fuel the product demand in commercial applications. Many factors are considered while choosing commercial air handling units, such as air quality, building design, and energy efficiency. The budget and the lifespan of the system are additional factors to consider.
 To learn more about this report, Download Free Sample Report
The demand for AHUs is rising in industrial applications due to the need for precise temperature and humidity control and efficient air filtration and circulation. For instance, in the pharmaceutical industry, AHUs are critical for maintaining clean room environments required for manufacturing sterile drugs and medical devices. These units filter the air to remove particulates, control temperature and humidity, and provide the necessary air changes per hour to meet stringent clean room standards.
Regional Insights
The North America air handling units market is driven by a strong focus on energy efficiency and sustainable construction practices. Increasing indoor air quality awareness prompts upgrades in commercial and residential HVAC systems. Smart building technologies are being integrated with AHUs to optimize performance. Government policies are encouraging the adoption of low-emission systems. The region sees continued growth in both new projects and retrofits.
U.S. Air Handling Units Market Trends
In the U.S., the modernization of infrastructure and the increasing investments in smart buildings are key drivers of demand for AHUs. A push toward energy conservation in the public and private sectors supports the market. Moreover, end-users are seeking customized solutions tailored to regional climate needs. Adoption is also growing in educational, healthcare, and industrial facilities.
The Canada AHU market benefits from a growing emphasis on green buildings and air quality in colder climates. Commercial and institutional sectors actively invest in HVAC upgrades for efficiency and comfort. Regional climate challenges are pushing demand for systems with high thermal efficiency. There's a strong preference for systems that can handle varied seasonal demands. Local regulations continue to shape the direction of system design and usage.
Europe Air Handling Units Market Trends
Stringent environmental regulations and strong energy efficiency goals drive the AHU market in Europe. Demand is high for systems that comply with building performance standards and support decarbonization. Retrofitting old buildings with modern HVAC systems is a major trend. The push for healthier indoor environments is also influencing design choices. Innovation and sustainability are central to market strategies across the region.
The Germany air handling units market is shaped by its commitment to green building practices and energy-efficient technologies. The country places a high value on systems with low noise, compact design, and smart control capabilities. Demand is robust in industrial and commercial construction, especially in cities prioritizing sustainability. Regulatory incentives support the adoption of modern HVAC solutions. Local manufacturers focus on engineering precision and environmental compliance.
The UK air handling units market is driven by a growing focus on indoor air quality and climate-conscious design. Upgrades in the healthcare and education sectors drive demand for advanced ventilation systems. Energy performance certificates and green building codes are key regulatory drivers. There's rising interest in AHUs integrated with smart building management systems. The retrofit market is particularly active due to the older building stock.
Asia Pacific Air Handling Units Market Trends
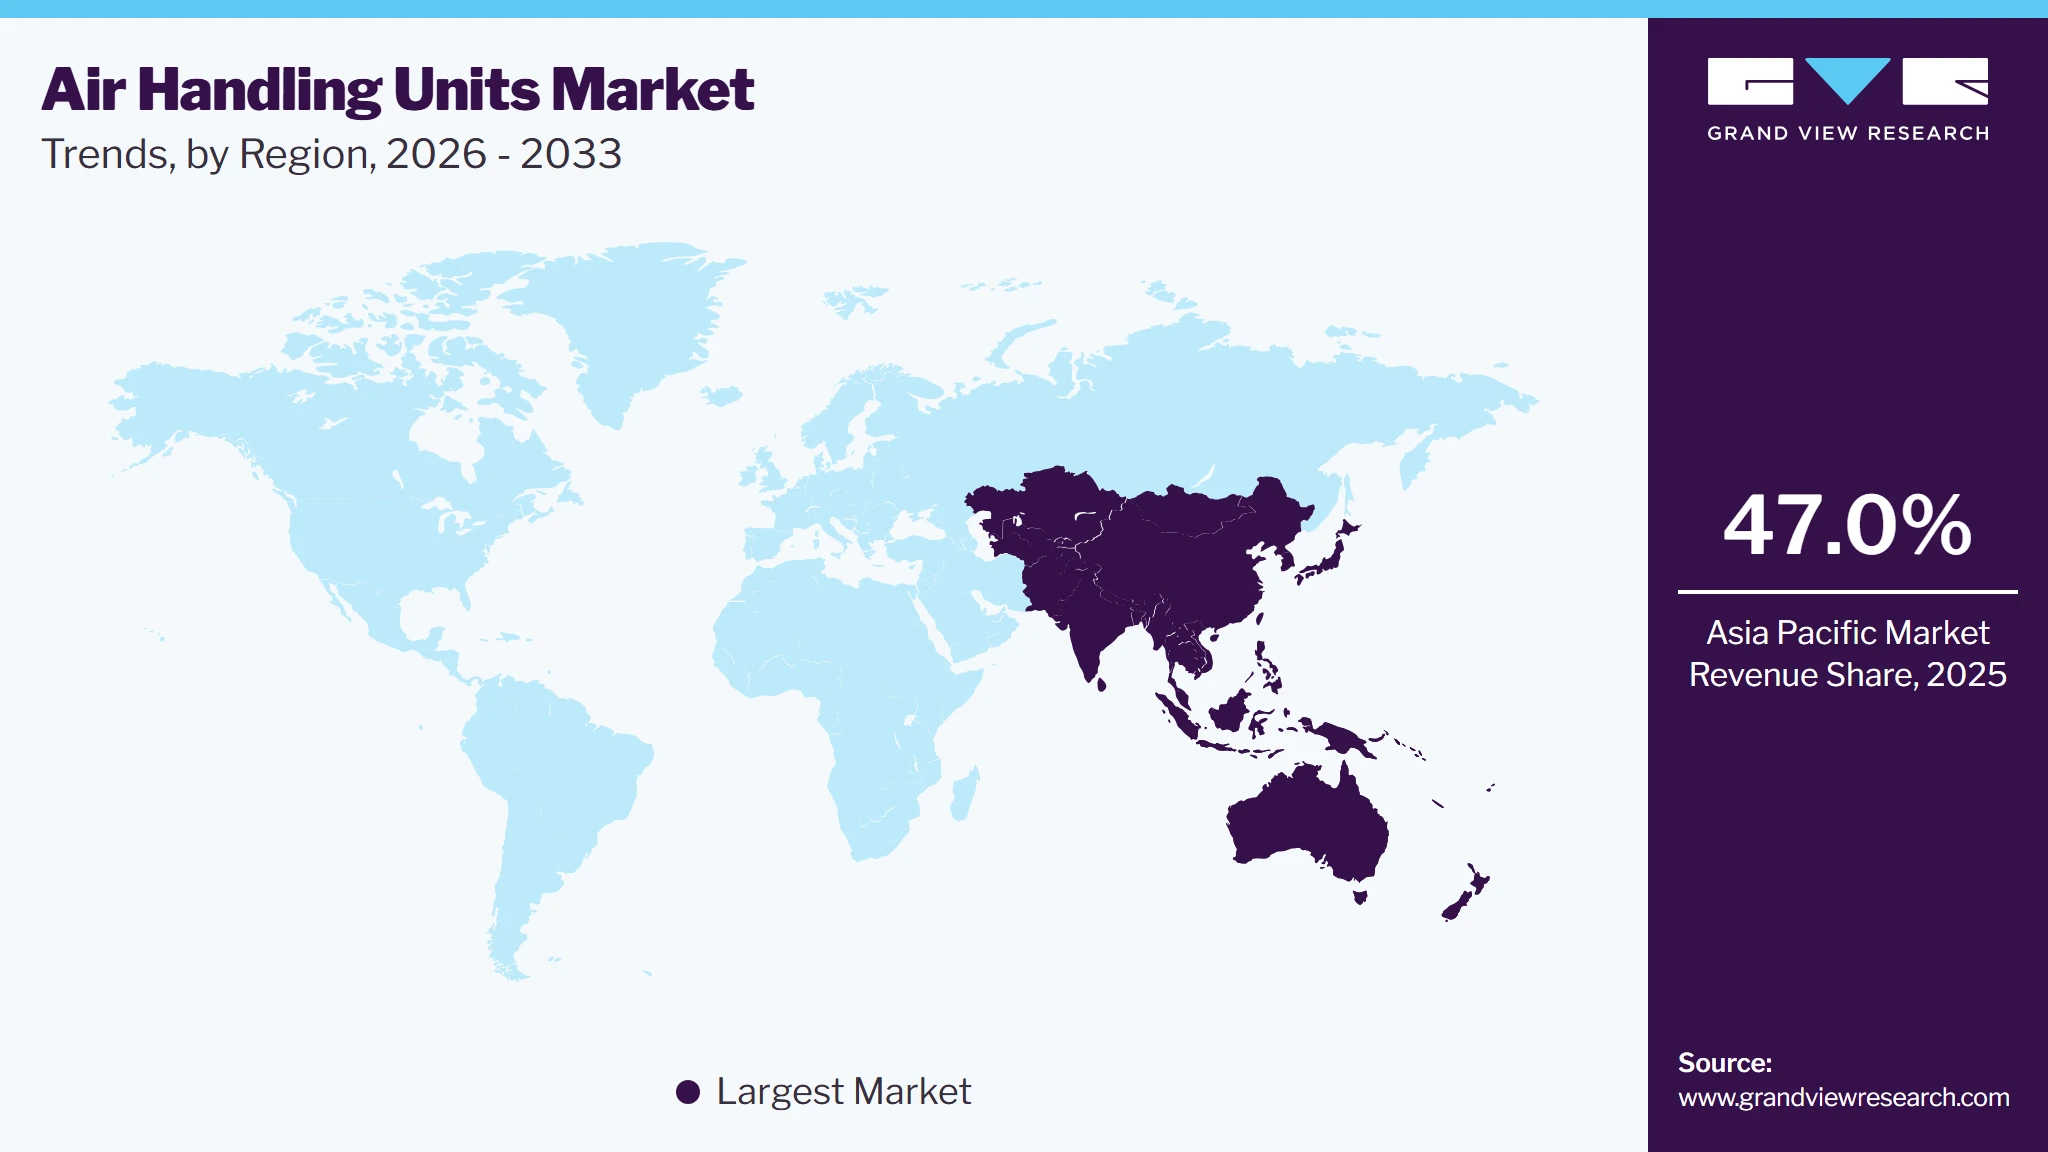
Asia Pacific dominated the air handling units market with the largest revenue share of 47.0% in 2025. The region is experiencing rapid market expansion due to urbanization and industrial growth. Rising construction activity in residential and commercial sectors creates consistent demand for AHUs. Manufacturers are introducing compact and energy-efficient models to cater to space constraints. Growing environmental awareness is encouraging the adoption of eco-friendly systems. Regional diversity leads to varying requirements across different countries.
 To learn more about this report, Download Free Sample Report
The air handling units market in China held the largest share in the Asia Pacific region in 2025. China's AHU market is influenced by large-scale infrastructure development and urban planning initiatives. Government policies promoting sustainable development are driving the shift toward efficient HVAC systems. The commercial real estate boom continues to fuel installations of modern air handling units. Domestic manufacturers are expanding product lines to compete globally. There's growing demand for integrated systems in smart city projects.
The air handling units market in India is expected to grow at a CAGR of 6.5% from 2025 to 2030. In India, increased urbanization and a booming construction sector are major growth drivers for AHUs. There's rising interest in maintaining indoor air quality in offices, malls, and hospitals. Energy-efficient and cost-effective solutions are gaining traction among developers and facility managers. Demand is also supported by expanding awareness of HVAC system benefits.
Middle East & Africa Air Handling Units Market Trends
The AHU market in the Middle East & Africa is driven by the need for effective cooling systems in harsh climates. High temperatures and a focus on energy use reduction are key market influences. Construction of large commercial, hospitality, and healthcare facilities supports market expansion. Regulatory initiatives are promoting green building certifications. Demand varies widely across the region depending on local development.
The Saudi Arabia AHU market is shaped by large-scale construction and infrastructure projects. Cooling and ventilation needs in extreme temperatures make efficient AHU systems essential. The push toward sustainable cities and energy-efficient buildings supports advanced system adoption. Innovation and automation are key features sought by developers.
Latin America Air Handling Units Market Trends
The AHU market in Latin America is shaped by growing urban development and attention to climate control needs. Energy efficiency and affordability are central to purchasing decisions in the region. Public sector initiatives are encouraging the modernization of ventilation systems in schools and hospitals. There's also increasing demand from the industrial and hospitality sectors.
The Brazil air handling units market shows steady demand for AHUs due to its expanding commercial construction sector and hot climate conditions. The market favors systems that offer both cooling efficiency and low operational cost. There’s increased interest in systems with smart controls and easy maintenance features. Regulatory focus on energy conservation supports the transition to modern HVAC units.
Key Air Handling Units Company Insights
Some of the key players operating in the market include Carrier Corporation, Trane Inc., Rheem Manufacturing Company, Johnson Controls, and LG Electronics, among others.
-
Trane is a member of the Ingersoll Rand family of brands. The company operates its business in two segments, namely climate and industrial. The industrial segment offers products and services that enhance energy efficiency, operations, and productivity. It includes power tools, compressed air & gas systems, fluid management systems, material handling systems, and utility & low-speed consumer vehicles. The climate segment provides energy-efficient products and services, including heating, ventilation, and air conditioning (HVAC) systems. The company is engaged in the manufacturing of residential, industrial, and commercial HVAC systems. It offers products, such as HVAC accessories, thermostat controls, ductless systems, geothermal systems, packaged systems, heat pumps, coils, gas & oil furnaces, air handlers, and air conditioners.
-
Carrier provides heat pumps, air conditioners, boilers, furnaces, air purifiers, humidifiers, dehumidifiers, ventilators, air scrubbers, thermostats, UV lamps, energy services, and building controls to the retail, commercial, transport, and foodservice sectors. The company was acquired by United Technologies Corporation in 1979; however, it was separated into a separate business in April 2020.
-
Johnson Controls designs, manufactures, and offers solutions that enhance the operational efficiencies of buildings and various systems related to the automotive industry. The company supplies building control systems, automation, HVAC equipment, seating and interior systems, and integrated facility management services. It operates through four business segments, namely building solutions EMEA/LA, building solutions North America, building solutions Asia Pacific, and global products.
Nortek Global HVAC, STULZ GMBH, and Hastings HVAC Inc. are some of the emerging market participants in the air handling units market.
-
Nortek Global HVAC is a leading manufacturer of heating, ventilation, and air conditioning (HVAC) equipment for residential and light commercial applications. The company offers a wide range of products, including air conditioners, heat pumps, furnaces, and air handlers, under well-known brands such as Frigidaire, Maytag, and Westinghouse. Nortek Global HVAC has a strong presence in North America and employs over 1,000 people across its manufacturing facilities and sales offices.
-
Hastings HVAC Inc. is a Canadian company that designs, manufactures, and distributes HVAC equipment for commercial and industrial applications. The company's product range includes air handling units, rooftop units, and custom-engineered solutions. Hastings HVAC serves customers across North America and has a reputation for providing high-quality, energy-efficient products and exceptional customer service. The company operates manufacturing facilities in Canada and the U.S. and employs a team of experienced engineering, sales, and customer support professionals.
Key Air Handling Units Companies:
The following key companies have been profiled for this study on the air handling unit market.
-
Carrier Corporation
-
Rheem Manufacturing Company
-
Johnson Controls
-
Lennox International Inc.
-
LG Electronics
-
Midea
-
Trane Inc.
-
Systemair AB
-
Munters AB
-
Lowe’s
-
Sephora
-
Target
-
Nortek Global HVAC
-
STULZ GMBH
-
Hastings HVAC Inc.
-
VTS Group
-
Evapoler Eco Cooling Solutions
- TROX GmbH
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (e.g., Carrier Corporation, Rheem Manufacturing Company, Johnson Controls, Lennox International Inc., LG Electronics, Midea, Trane Inc., Systemair AB, Munters AB)
- Expansion of integrated ventilation, cooling, and indoor air quality solutions
- Increasing adoption of IoT-enabled AHUs and automation-based HVAC management systems
- Extensive global distribution, installation, and aftermarket service networks
- Strong global brand recognition and diversified HVAC product portfolios
- Advanced technological capabilities in energy-efficient air handling and climate control systems
- Strong penetration across commercial, industrial, healthcare, and institutional sectors
- Premium pricing compared to regional manufacturers
- High dependence on construction and commercial real estate cycles
- Complex product installation and maintenance requirements
Emerging & Regional Players (e.g., STULZ GMBH, Hastings HVAC Inc., VTS Group, Evapoler Eco Cooling Solutions, Lowe’s, Sephora)
- Focus on cost-effective and application-specific AHU solutions for regional commercial and industrial markets
- Increasing emphasis on energy-efficient cooling systems, compact designs, and customized air handling configurations
- Expansion into retrofit projects and sustainable cooling applications
- Competitive pricing and flexibility in offering customized HVAC solutions
- Growing adoption in mid-sized commercial and industrial projects
- Faster responsiveness to localized customer requirements
- Comparatively lower global market penetration and brand visibility
- Limited financial scale for large R&D investments
- Lower presence in highly integrated smart building ecosystems
Recent Developments
-
In February 2024, Modine announced that it had entered into a definitive agreement to acquire Scott Springfield Manufacturing, a manufacturer of AHUs. Through this transaction, Modine gained immediate access to a complementary product portfolio and a customer base across several industries, such as telecommunications, hyperscale & colocation data centers, healthcare, and aerospace.
-
In January 2024, Carrier expanded its HVAC product portfolio manufactured in India with the introduction of air handling units (AHUs) and fan coil units (FCUs) tailored to meet the diverse needs of India's commercial buildings. These new additions, designed to provide custom solutions for healthy indoor environments with high-efficiency air filtering, affirm Carrier's more than five-decade presence in India and underscore the company's commitment to the country's growth under the 'Make in India' initiative.
Air Handling Units Market Report Scope
Report Attribute
Details
Market size in 2025
USD 11.3 billion
Estimated market size in 2026
USD 11.9 billion
Projected market size by 2033
USD 18.1 billion
Growth rate
CAGR of 6.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, capacity, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; Italy; UK; Spain; China; Japan; India; South Korea; Australia; Brazil; Argentina; South Africa; Saudi Arabia; UAE
Key companies profiled
Carrier Corporation; Rheem Manufacturing Company; Johnson Controls; Lennox International Inc.; LG Electronics; Midea; Trane Inc.; Systemair AB; Munters AB; Nortek Global HVAC; STULZ GMBH; Hastings HVAC Inc.; VTS Group; Evapoler Eco Cooling Solutions; TROX GmbH
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Air Handling Units Market Report Segmentation
This report forecasts revenue growth at global, regional & country levels and provides an analysis on the industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global air handling units market report on the basis of product, type, capacity, application, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Single Flux
-
Double Flux
-
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Packaged
-
Modular
-
-
Capacity Outlook (Revenue, USD Billion, 2021 - 2033)
-
Up to 5,000 m3/h
-
5,001 to 10,000 m3/h
-
10,001 to 30,000 m3/h
-
30,001 to 50,000 m3/h
-
Above 50,001 m3/h
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Residential
-
Commercial
-
Industrial
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
-
Research Methodology
The air handling units Market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each air handling units segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Application
Revenue Capture Definition
Single Flux
Revenue is generated through the sale of single flux air handling units designed for supply or exhaust ventilation in residential and small commercial applications.
Double Flux
Revenue is generated through the sale of double flux air handling units with heat recovery capabilities for energy-efficient commercial, institutional, and industrial buildings.
Type
Revenue Capture Definition
Packaged
Revenue is generated through the sale of factory-assembled packaged air handling units that offer integrated ventilation and climate control solutions for commercial and industrial facilities.
Modular
Revenue is generated through the sale of modular air handling units that can be configured to meet customized airflow, filtration, and capacity requirements across large-scale projects.
Capacity
Revenue Capture Definition
Up to 5,000 m³/h
Revenue is generated through the sale of low-capacity air handling units for residential buildings, small offices, retail outlets, and light commercial applications.
5,001 to 10,000 m³/h
Revenue is generated through the sale of medium-capacity air handling units for hotels, schools, healthcare clinics, and medium-sized commercial buildings.
10,001 to 30,000 m³/h
Revenue is generated through the sale of high-capacity air handling units for hospitals, office complexes, shopping malls, and manufacturing facilities.
30,001 to 50,000 m³/h
Revenue is generated through the sale of very high-capacity air handling units for airports, data centers, pharmaceutical facilities, and large industrial plants.
Above 50,001 m³/h
Revenue is generated through the sale of ultra-high-capacity air handling units for power plants, petrochemical facilities, mega infrastructure projects, and heavy industrial applications.
Segment - End Use
Revenue Capture Definition Residential
Revenue is generated through the sale of air handling units for homes and residential complexes to provide ventilation, air circulation, and indoor air quality management.
Commercial
Revenue is generated through the sale of air handling units for offices, hospitals, hotels, airports, educational institutions, and other commercial buildings.
Industrial
Revenue is generated through the sale of air handling units for manufacturing plants, cleanrooms, food processing facilities, pharmaceutical plants, and other industrial environments requiring controlled air handling.
Estimation Model
Layer Name
Key Question
Description
HVAC Infrastructure Demand Layer
Where are air handling units required?
Analyze demand across commercial, industrial, institutional, and residential buildings. Assess new construction, building modernization, HVAC installations, indoor air quality requirements, and ventilation needs to establish the addressable demand for air handling units.
Building Construction & Infrastructure Investment Layer
Where is new equipment demand being created?
Evaluate investments in commercial buildings, hospitals, data centers, educational institutions, manufacturing facilities, airports, hotels, and other infrastructure projects. Assess greenfield construction, retrofit projects, and replacement of aging HVAC systems that drive procurement of new air handling units.
Product Adoption Layer
Which air handling unit technologies are being deployed?
Segment demand by product type, capacity, configuration, mounting type, application, and end-use industry. Apply adoption rates based on airflow requirements, energy efficiency standards, filtration performance, climate conditions, and building specifications.
Revenue Generation Layer
How much market revenue is generated?
Estimate annual shipments of air handling units by product type, capacity, application, end-use industry, and region. Quantify revenues generated exclusively from the sale of new air handling units supplied to OEMs, HVAC contractors, distributors, and building developers.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Benchmarking
Detailed benchmarking of leading AHU manufacturers based on product portfolio, airflow efficiency, smart HVAC integration, energy-saving capabilities, regional presence, and strategic initiatives.
Enable competitive intelligence and strategic differentiation. Support product positioning, partnership evaluation, and innovation benchmarking.
Regional Segmentation
Detailed market estimates and forecasts for the Air Handling Units (AHU) Market across North America, Europe, Asia Pacific, Latin America, and Middle East & Africa. Country-level demand analysis covering commercial buildings, healthcare facilities, industrial plants, data centers, hospitality, and institutional infrastructure.
Identify high-growth regional markets and infrastructure investment hotspots. Support regional expansion planning, distributor network optimization, and HVAC demand forecasting.
Opportunity assessment
Identification of emerging growth opportunities driven by smart building adoption, green infrastructure development, rising demand for indoor air quality management, expansion of data centers, and increasing healthcare infrastructure investments.
Enable competitive intelligence and strategic differentiation. Support product positioning, partnership evaluation, and innovation benchmarking.
Frequently Asked Questions About This Report
Asia Pacific dominated the air handling units market with the largest revenue share of 47.0% in 2025.
The commercial segment led the market with the largest revenue share of 46.6% in 2025.
The single flux segment led the market with the largest revenue share of 53.9% in 2025.The need for efficient and cost-effective HVAC solutions in various applications drives the demand for single-flux and double-flux air handling units.
The packaged segment accounted for the largest revenue share of 58.5% in 2025 while modular air handling units segment is expected to be the fastest-growing market.
The global air handling units market size was valued at USD 11.3 billion in 2025 and is estimated at USD 11.9 billion in 2026.
The global air handling units market is expected to grow at a CAGR of 6.2% from 2026 to 2033, reaching USD 18.1 billion by 2033.
Key factors include increasing investments in commercial and industrial infrastructure, growing demand for energy-efficient HVAC systems, rising awareness regarding indoor air quality, and stringent building energy-efficiency regulations across developed and emerging economies.
Some of the key players operating in the air handling unit (AHU) market include Carrier Corporation, Rheem Manufacturing Company , Johnson Controls, Lennox International Inc., LG Electronics, Midea, Trane Inc., Systemair AB, Munters AB, Nortek Global HVAC, STULZ GMBH, Hastings HVAC Inc., VTS Group, Evapoler Eco Cooling Solutions, TROX GmbH
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


