
- Home
- »
- Advanced Interior Materials
- »
-
Anchoring Fasteners Market Size & Share Report 2026-2033GVR Report cover

Anchoring Fasteners Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Mechanical Anchors, Chemical Anchors), By Substrate (Concrete, Solid Masonry), By End Use, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$3.3BMarket Estimate, 2026
$3.4BMarket Forecast, 2033
$4.5BCAGR, 2026–2033
4.2%Anchoring Fasteners Market Summary
The global anchoring fasteners market size was valued at USD 3.3 billion in 2025 and is projected to grow from USD 3.4 billion in 2026 to USD 4.5 billion by 2033, at a CAGR of 4.2% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 30.0% in 2025. The industry’s growth is driven by the acceleration of construction and infrastructure activities worldwide.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Mechanical anchors held the largest share of around 42.0% in 2025.
- By substrate: Concrete segment led the market, with a share of around 43.0% in 2025.
- By end use: Construction & real estate held the largest share of around 53.0% in 2025.
- By distribution channel: Indirect segment dominated the market, with a share of around 70.0% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (30.0% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 3.3 Billion
- Estimated market size in 2026: USD 3.4 Billion
- Projected market size by 2033: USD 4.5 Billion
- CAGR (2026-2033): 4.2%
Prism AI by Grand View Research Free to tryAsk a question about the anchoring fasteners marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
As governments invest in modernizing roads, bridges, commercial buildings, and urban housing, demand for reliable anchoring solutions has soared. These fasteners are crucial for ensuring structural stability and load distribution, especially in high-rise buildings, modular infrastructure systems, and prefabricated construction. Emerging economies, in particular, are fueling demand through massive smart-city initiatives and transit-corridor projects, which require specialized anchors that meet both safety and regulatory benchmarks. Developed regions, meanwhile, are focused on retrofitting aging infrastructure, further augmenting the use of high-performance anchors in restoration and reinforcement works.Industrial expansion is another significant factor fueling the anchoring fasteners market. Heavy machinery installations in manufacturing plants, energy facilities, and processing units require anchoring systems that can withstand vibration, high loads, and environmental stress. Industries such as oil & gas, mining, and renewable energy are adopting anchoring fasteners in both onshore and offshore settings, often using corrosion-resistant materials such as stainless steel or zinc-plated carbon steel.
Technology and innovation are also reshaping the landscape of the anchoring fasteners industry. Manufacturers are introducing products with improved designs that offer faster installation, higher tensile strength, and better seismic performance. Innovations such as undercut anchors, self-drilling anchors, and expansion bolts with torque-controlled mechanisms are helping contractors reduce project timelines while maintaining structural integrity. Furthermore, advancements in building codes and simulation software are allowing engineers to optimize anchor placement and performance, enhancing the safety profile of construction projects in seismically active regions. The emphasis on green construction is also driving the adoption of recyclable, low-carbon anchoring materials.
Market Concentration & Characteristics
The industry is characterized by moderate to high market concentration, with a few global players such as Hilti Corporation, Fischer Group, Würth, and ITW commanding significant shares, especially in developed regions. These companies maintain their competitive edge through strong distribution networks, proprietary fastening technologies, and compliance with international construction standards. The degree of innovation within the market is notably high, particularly in product design, corrosion resistance, seismic performance, and installation efficiency.
Innovations such as chemical anchors for high-load applications and pre-engineered fastening systems for modular construction have become increasingly prevalent. Furthermore, technological integration, including BIM (Building Information Modeling) compatibility and load simulation software, is reshaping procurement decisions among contractors and structural engineers. This continuous push for technical superiority has created barriers to entry for smaller players lacking in R&D capabilities or certification credentials.
The market also witnesses a moderate level of mergers and acquisitions, primarily driven by the need for portfolio expansion, geographic reach, and regulatory alignment. Companies operating in regions with stringent construction norms, such as North America, Europe, and parts of Asia, must navigate evolving building codes, seismic anchoring standards, and fire resistance guidelines, all of which influence product design and certification timelines.
Regulatory compliance is thus both a challenge and a catalyst for differentiation. Service substitutes are limited due to the critical nature of anchor fasteners in ensuring structural stability, though mechanical anchors may be interchanged with chemical ones depending on application-specific requirements. End-user concentration is relatively high in infrastructure, industrial, and commercial construction sectors, with large EPC firms, government contractors, and facility operators constituting key customer segments.
Analyst Perspective
The global anchoring fasteners market is shifting toward high-performance, corrosion-resistant, and application-specific solutions as demand for safe, durable, and efficient structural connections grows across construction, infrastructure, industrial, and renewable energy projects. Market expansion is supported by rising investment in urban infrastructure, residential and commercial construction, building renovation, and modular and prefabricated construction. Ongoing innovations in mechanical and chemical anchoring solutions, along with advances in seismic resistance, installation efficiency, and engineering software, are expected to further drive adoption. However, stringent regulations, volatile raw material costs, and intense competition may constrain growth, while product launches, geographic expansion, and investments in sustainable construction create growth opportunities.
Product Insights
The mechanical anchors segment held the largest revenue share, at around 42.0%, in 2025, driven by the increasing adoption of concrete-based construction across the residential, commercial, and industrial sectors. Mechanical anchors, including wedge anchors, sleeve anchors, and expansion bolts, are preferred in applications requiring immediate load-bearing capacity and fast installation. These anchors are widely used in reinforced concrete structures because they provide a reliable mechanical interlock without requiring time, unlike chemical anchors. The segment is also benefiting from continuous product innovation by leading manufacturers. For instance, in May 2025, Fischer launched the FWA R2 anchor in India, providing an economical mechanical anchoring solution for the country's expanding construction sector, further strengthening performance and installation flexibility across construction applications.
The chemical anchors segment is expected to grow at the fastest CAGR during the forecast period, driven by its superior load-bearing capabilities and adaptability across diverse construction environments. Unlike mechanical anchors, chemical anchors provide superior load distribution while minimizing expansion stress on the base material, making them ideal for cracked concrete, seismic zones, and applications requiring post-installed rebar connections. This advantage is particularly relevant in retrofitting projects, structural upgrades, and heavy-duty industrial installations where traditional fastening solutions may fall short.
Substrate Insights
The concrete segment held the largest market share of around 43.0% in 2025, driven by its extensive use as a foundational material in both structural and nonstructural applications. Anchoring fasteners play a critical role in ensuring the secure attachment of structural elements, equipment, and support systems to concrete substrates. The continued global growth in construction, industrial facilities, transportation infrastructure, and urban development projects is fueling demand for mechanical and chemical anchors specifically designed for concrete.
Hollow or perforated masonry segments are expected to grow at the fastest CAGR during the forecast period, driven by the rising adoption of lightweight construction materials in both residential and commercial building sectors. Hollow blocks, perforated bricks, and lightweight masonry units are increasingly preferred for their cost-effectiveness, insulating properties, and ease of handling. However, these materials pose unique challenges for load bearing and fastening, thereby necessitating specialized anchoring systems.
End Use Insights
The construction & real estate segment held the largest market share of around 53.0% in 2025, driven by strong demand for structural stability, safety, and long-term durability in buildings and infrastructure. As urbanization continues to accelerate, particularly in emerging economies, there has been a sharp rise in the development of commercial complexes, residential towers, and public infrastructure such as airports, hospitals, and schools. These structures rely extensively on anchoring systems to secure structural elements such as steel beams, façade panels, piping, HVAC units, and foundation reinforcements. The expanding global construction landscape is also encouraging manufacturers to strengthen their regional presence. For instance, in February 2025, Fischer established a new national subsidiary in Saudi Arabia, reinforcing its presence in one of the Middle East's fastest-growing construction markets and enhancing the supply and technical support for its fastening and anchoring solutions across large-scale infrastructure and building projects.
The energy & utilities (solar and green roofs) segment is expected to grow at the fastest CAGR over the forecast period. The global push toward renewable energy adoption has led to a rise in solar panel installations across residential, commercial, and utility scale projects. These installations require precise and durable anchoring solutions to secure solar racking systems to concrete, metal, or membrane surfaces. Fasteners must provide long-term structural stability while resisting corrosion, UV exposure, and thermal expansion stresses.
Distribution Channel Insights
The indirect segment held the largest market share, at around 70.0%, in 2025. The increasing specialization and technical expertise of third-party distributors are enhancing the value proposition of the indirect channel. Many distributors now provide technical advisory services, guidance on anchor selection, and even on-site training, enabling customers to make informed decisions based on substrate type, load requirements, and environmental conditions. In markets such as Europe and North America, where adherence to building codes and certifications is critical, distributors often carry pre-approved, regionally certified anchoring products, thereby streamlining procurement processes for contractors.
The direct segment is expected to grow significantly at a CAGR during the forecast period, driven by the increasing preference of large-scale contractors, industrial buyers, and government agencies for customized, high-performance anchoring solutions. Direct sales enable manufacturers to establish long-term relationships with end users, allowing for a deeper understanding of technical requirements, project timelines, and compliance standards. This channel also facilitates tailored offerings, such as project-specific anchor bolt assemblies or special coatings for corrosive environments, which are often not feasible through third-party distributors.
Regional Insights
The North America anchoring fasteners market is supported by the renovation and retrofitting of aging infrastructure, particularly in the U.S. and Canada. Increasing federal funding for infrastructure upgrades such as roads, bridges, and public utilities is driving demand for seismic anchors and high-performance fastening systems. The region’s strict adherence to building and seismic codes, such as the International Building Code (IBC) and ACI standards, requires the use of approved anchoring systems, which, in turn, support market development. In addition, the surge in warehousing, data centers, and industrial expansion, driven by the e-commerce boom, is fueling demand for fasteners used in structural steel and concrete fixtures.
U.S. Anchoring Fasteners Market Trends
The anchoring fasteners market in the U.S. is driven by a combination of commercial construction activity, robust industrial investment, and stringent safety regulations. Major infrastructure programs such as the Bipartisan Infrastructure Law are catalyzing nationwide upgrades of transportation and utility infrastructure. These developments require certified, performance-tested anchors for critical applications such as bridge joints, energy installations, and seismic zones. Moreover, the growth of the renewable energy sector and warehouse automation in logistics hubs is generating increased demand for custom-engineered anchoring products designed for durability and ease of installation.
Asia Pacific Anchoring Fasteners Market Trends
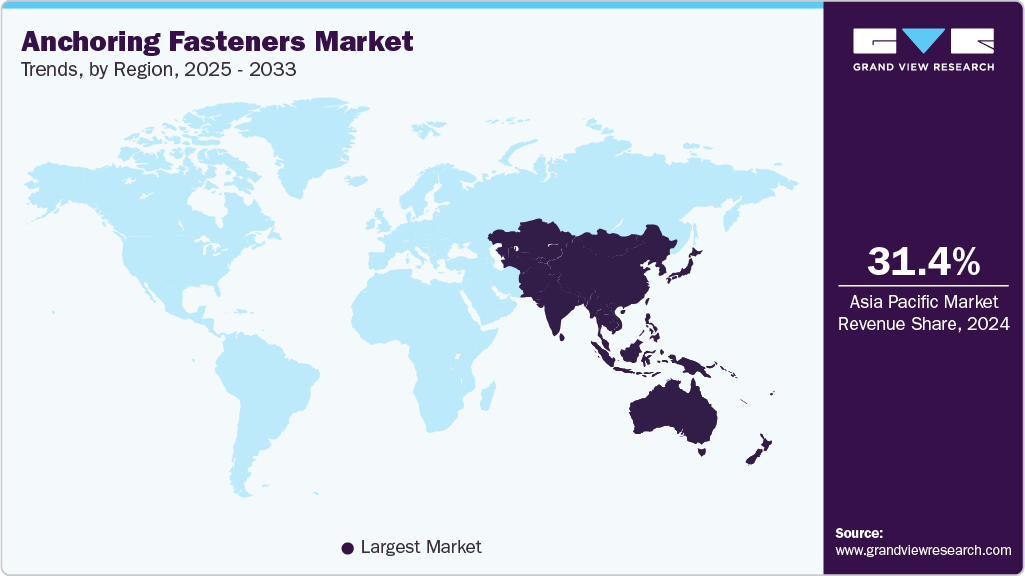
The Asia Pacific dominated the global industry, accounting for the largest revenue share of approximately 30.0% in 2025, driven by large-scale infrastructure development and rising urbanization across countries such as China, India, Indonesia, and Vietnam. The region is witnessing increased government spending on smart cities, public transportation networks, commercial real estate, and residential housing, all of which require high-strength and reliable anchoring systems. In addition, the proliferation of modular and prefabricated construction in countries such as Japan and Australia is accelerating demand for mechanical and chemical anchors that offer speed and precision. The growing adoption of international building codes and earthquake-resistant structures is also driving increased use of certified and advanced anchoring solutions.
 To learn more about this report, Download Free Sample Report
Anchoring fasteners market in China is primarily driven by its massive construction sector, backed by government stimulus and ongoing industrial expansion. The country continues to invest heavily in new infrastructure projects, including high-speed rail, airports, power plants, and logistics parks, generating consistent demand for anchoring systems. Furthermore, China's shift toward high-rise construction and sustainable green buildings is fostering demand for advanced, corrosion-resistant, and load-bearing fasteners. Domestic manufacturers are also investing in innovation to comply with new national codes and to reduce reliance on imports, boosting local production and technological capabilities.
Europe Anchoring Fasteners Market Trends
The anchoring fasteners market in Europe is shaped by sustainability-driven construction, refurbishment of old buildings, and compliance with unified Eurocodes. The European Union’s emphasis on green construction and energy-efficient buildings has led to a surge in retrofitting projects where anchoring fasteners are used to support insulation panels, façade systems, and structural reinforcements. In addition, growing investment in wind energy and public transportation projects across Germany, France, and Scandinavia is boosting demand for fasteners that can withstand mechanical stress and environmental corrosion. European firms also prioritize anchoring their systems with EOTA and CE certifications, thereby reinforcing the market for high-quality, technically compliant solutions.
Anchoring fasteners market in Germany is driven by the high demand in sectors such as automotive manufacturing facilities, logistics centers, and renewable energy plants. The country’s strict seismic and fire resistance norms in construction drive the use of certified anchor bolts and heavy-duty fastening systems. Moreover, Germany’s leadership in green building initiatives is spurring innovation in recyclable, energy-efficient fastening solutions, creating new avenues for growth in the anchoring systems market.
Latin America Anchoring Fasteners Market Trends
The anchoring fasteners market in Latin America is gaining momentum due to urban development, housing shortages, and rising public infrastructure investment. Countries such as Brazil, Mexico, and Colombia are modernizing their transport networks and energy systems, including hydroelectric and wind energy projects that require stable anchoring in varying terrains. The region’s construction sector is gradually adopting international safety and quality standards, thereby encouraging the use of durable and compliant anchoring solutions. While economic volatility and regulatory inconsistencies pose challenges, ongoing industrialization and urban sprawl continue to drive market demand.
Middle East & Africa Anchoring Fasteners Market Trends
The anchoring fasteners market in the Middle East & Africa is fueled by mega infrastructure and urban development projects, especially in GCC countries such as Saudi Arabia, the UAE, and Qatar. Projects like NEOM, Expo City Dubai, and extensive oil & gas infrastructure expansion require large volumes of heavy-duty anchors for steel structures, pipelines, and prefabricated units. The increasing focus on seismic compliance and fire safety standards in construction has led to greater adoption of advanced anchoring systems. In Africa, improving construction practices and growing FDI in real estate and industrial zones are contributing to a gradual rise in demand for anchoring fasteners, although the market remains price sensitive and fragmented.
Key Anchoring Fasteners Market Company Insights
Key players operating in the anchoring fasteners market are undertaking various initiatives to strengthen their presence and increase the reach of their products and services. Strategies such as expansion activities and partnerships are key in propelling market growth.
Key Anchoring Fasteners Companies
The following key companies have been profiled for this study on the anchoring fasteners market:
-
EJOT Holding GmbH & Co. KG
-
Fischer Group
-
Hilti Corporation
-
Illinois Tool Works Inc. (ITW)
-
MKT Fastening, LLC
-
Rawlplug S.A.
-
Sika AG
-
Simpson Strong-Tie Company Inc.
-
Stanley Black & Decker, Inc.
Recent Developments
-
In January 2026, Simpson Strong-Tie Company Inc. expanded its RFB retrofit bolt product line by introducing new diameters, additional lengths, Grade 55 and Grade 105 steel options, and Stainless Steel 304 and 316 variants for concrete and masonry anchoring applications. The expansion enhances the company's anchoring fasteners portfolio by providing greater installation flexibility, higher load capacities, and improved corrosion resistance for structural retrofit projects.
-
In March 2024, Hilti Corporation introduced the HST4 series as its highest-performing wedge expansion anchors, designed for high static and seismic loads in cracked concrete. The HST4-R variant is made of A4 stainless steel, suitable for both indoor and outdoor applications.
Anchoring Fasteners Market Report Scope
Report Attribute
Details
Market size in 2025
USD 3.3 billion
Estimated market size in 2026
USD 3.4 billion
Projected market size by 2033
USD 4.5 billion
Growth rate
CAGR of 4.2% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, substrate, end use, distribution channel, region
Regional Scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country Scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; China; India; Japan; Australia; Brazil; Saudi Arabia; UAE; Turkey
Key companies profiled
Hilti Corporation; fischer Group; Simpson Strong-Tie Company Inc.; Illinois Tool Works Inc. (ITW); Stanley Black & Decker, Inc.; Sika AG; MKT Fastening, LLC; Rawlplug S.A.; EJOT Holding GmbH & Co. KG
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Anchoring Fasteners Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global anchoring fasteners market report based on product, substrate, end use, distribution channel, and region:
- Product Outlook (Revenue, USD Billion, 2021 - 2033)
- Mechanical Anchors
- Chemical Anchors
- Plastic Anchors
- Substrate Outlook (Revenue, USD Billion, 2021 - 2033)
- Concrete
- Solid Masonry
- Hollow or Perforated Masonry
- Autoclaved Aerated Concrete
- Others
- End Use Outlook (Revenue, USD Billion, 2021 - 2033)
- Construction & Real Estate
- Energy & Utilities (Solar and Green Roofs)
- Industrial & Manufacturing
- Government & Public Sector
- Others
- Distribution Channel Outlook (Revenue, USD Billion, 2021 - 2033)
- Direct
- Indirect
- Regional Outlook (Revenue, USD Billion, 2021 - 2033)
- North America
- U.S.
- Canada
- Mexico
- Europe
- Germany
- UK
- France
- Italy
- Spain
- Asia Pacific
- China
- Japan
- India
- Australia
- Latin America
- Brazil
- Middle East & Africa
- Saudi Arabia
- UAE
- Turkey
- North America
Frequently Asked Questions About This Report
The mechanical anchors accounted for the largest revenue share of around 42.0% in 2025.
The global anchoring fasteners market size was valued at USD 3.3 billion in 2025 and is estimated at USD 3.4 billion for 2026.
Key players in the market include Hilti Corporation; fischer Group; Simpson Strong-Tie Company Inc.; Illinois Tool Works Inc. (ITW); Stanley Black & Decker, Inc.; Sika AG; MKT Fastening, LLC; Rawlplug S.A.; EJOT Holding GmbH & Co. KG, and others.
Asia Pacific dominated with an approximately 30.0% revenue share in 2025.
The global anchoring fasteners market is expected to grow at a CAGR of 4.2% from 2026 to 2033, reaching USD 4.5 billion.
About the Author(s)
Advanced Interior Materials Research Team
Advanced Materials · Advanced Interior MaterialsThis report was authored by the advanced interior materials research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the advanced interior materials segment of the advanced materials industry. All findings are based on proprietary advanced materials databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


