
- Home
- »
- Pharmaceuticals
- »
-
Antiarrhythmic Drugs Market Size & Share Report 2026-2033GVR Report cover

Antiarrhythmic Drugs Market (2026 - 2033)
Size, Share & Trends Analysis Report By Drug Class (Beta Blockers, Sodium Channel Blockers), By Route of Administration (Oral, Parenteral), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies), By Region, And Segment Forecasts
Market Size, 2025
$1,182.3MMarket Estimate, 2026
$1,257.4MMarket Forecast, 2033
$1,934.5MCAGR, 2026–2033
6.3%Antiarrhythmic Drugs Market Summary
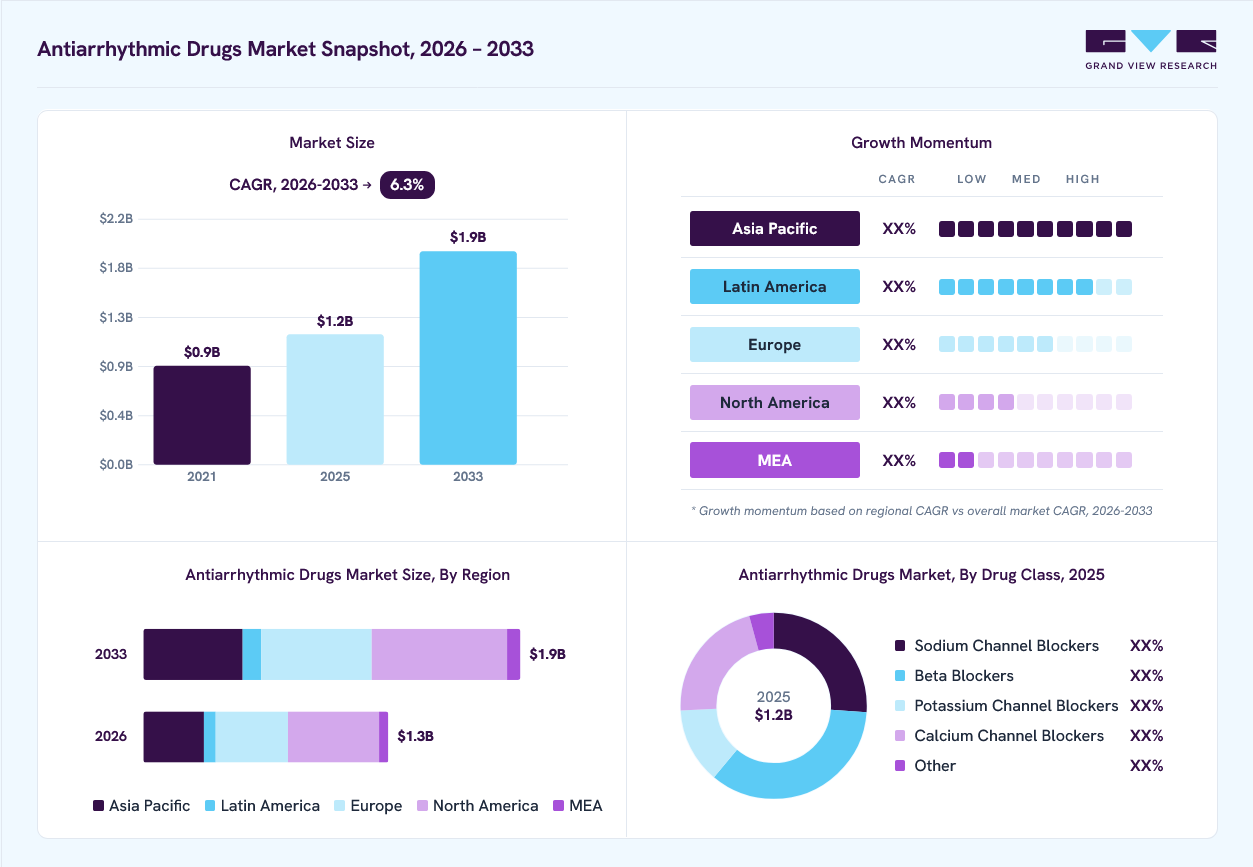
The global antiarrhythmic drugs market size was valued at USD 1,182.3 million in 2025 and is projected to grow from USD 1,257.4 million in 2026 to USD 1,934.5 million by 2033, at a CAGR of 6.3% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 37.4% in 2025. A report from the National Library of Medicine published in June 2023 highlights that the prevalence of arrhythmias in the general population is expected to range from 1.5% to 5%, with atrial fibrillation being the most prevalent type.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By drug class: Beta blockers segment led the market with the largest revenue share of 34.9% in 2025.
- By route of administration: Oral segment led the market with the largest revenue share of 64.2% in 2025.
- By distribution channel: Hospital pharmacies segment led the market with the largest revenue share of 54.3% in 2025.
Regional Highlights
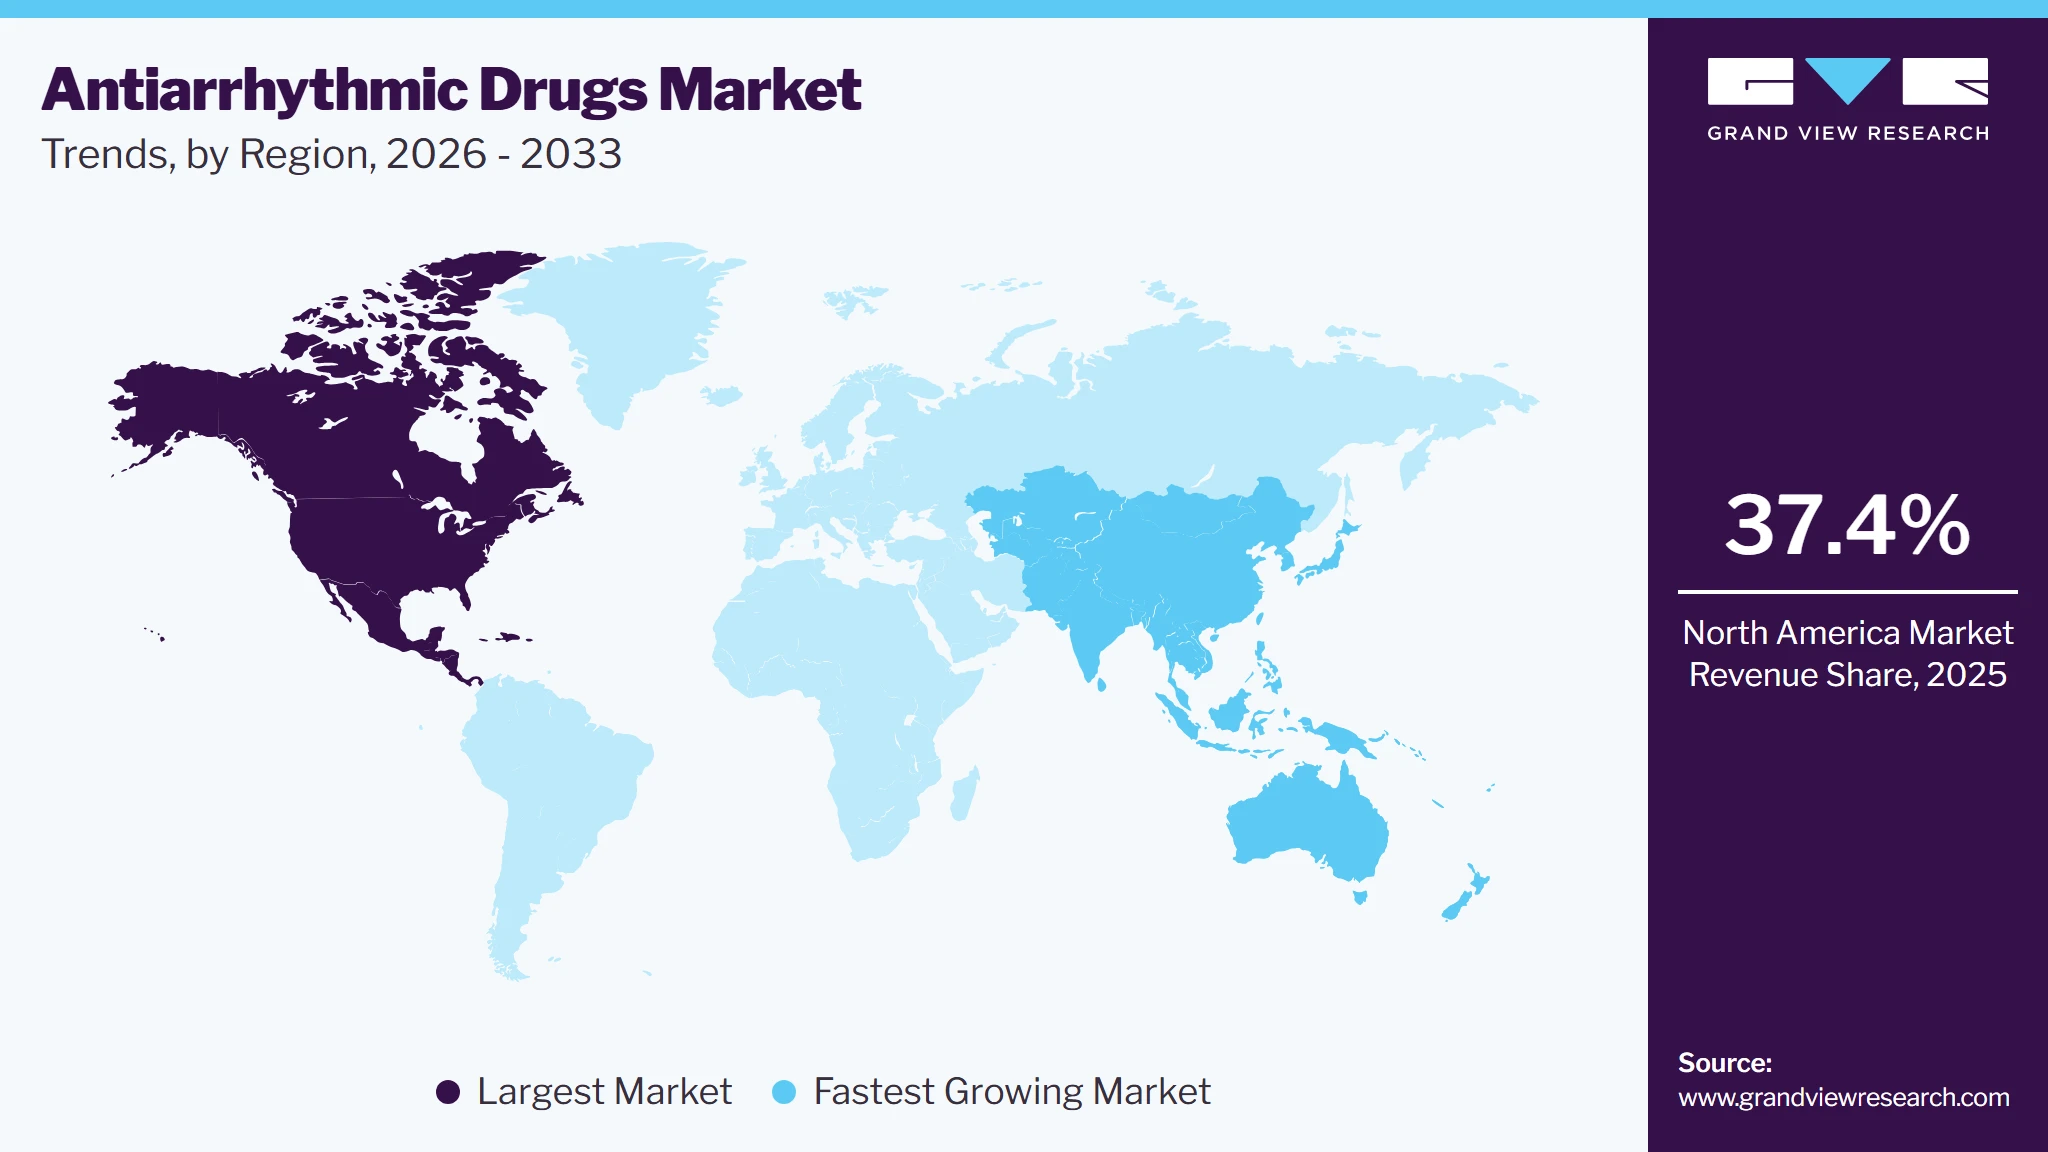
- Largest regional market: North America (37.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 1,182.3 Million
- Estimated market size in 2026: USD 1,257.4 Million
- Projected market size by 2033: USD 1,934.5 Million
- CAGR (2026-2033): 6.3%
Prism AI by Grand View Research Free to tryAsk a question about the antiarrhythmic drugs marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
This increasing incidence underscores the urgent need for effective antiarrhythmic therapies, positioning the market for significant expansion in the coming years. Cardiovascular diseases (CVDs) are a leading cause of morbidity and mortality worldwide, with arrhythmias being a common manifestation. According to the World Health Organization (WHO), CVDs are responsible for approximately 32% of global deaths, highlighting the urgent need for effective treatment options. The prevalence of conditions such as atrial fibrillation (AF), which affects about 33 million people globally, is rising, particularly in aging populations. This demographic shift is projected to continue, as WHO indicates that the number of people aged 60 years and older is expected to reach 2.1 billion by 2050. The increasing incidence of AF and other arrhythmias necessitates the development and use of antiarrhythmic drugs, driving market growth.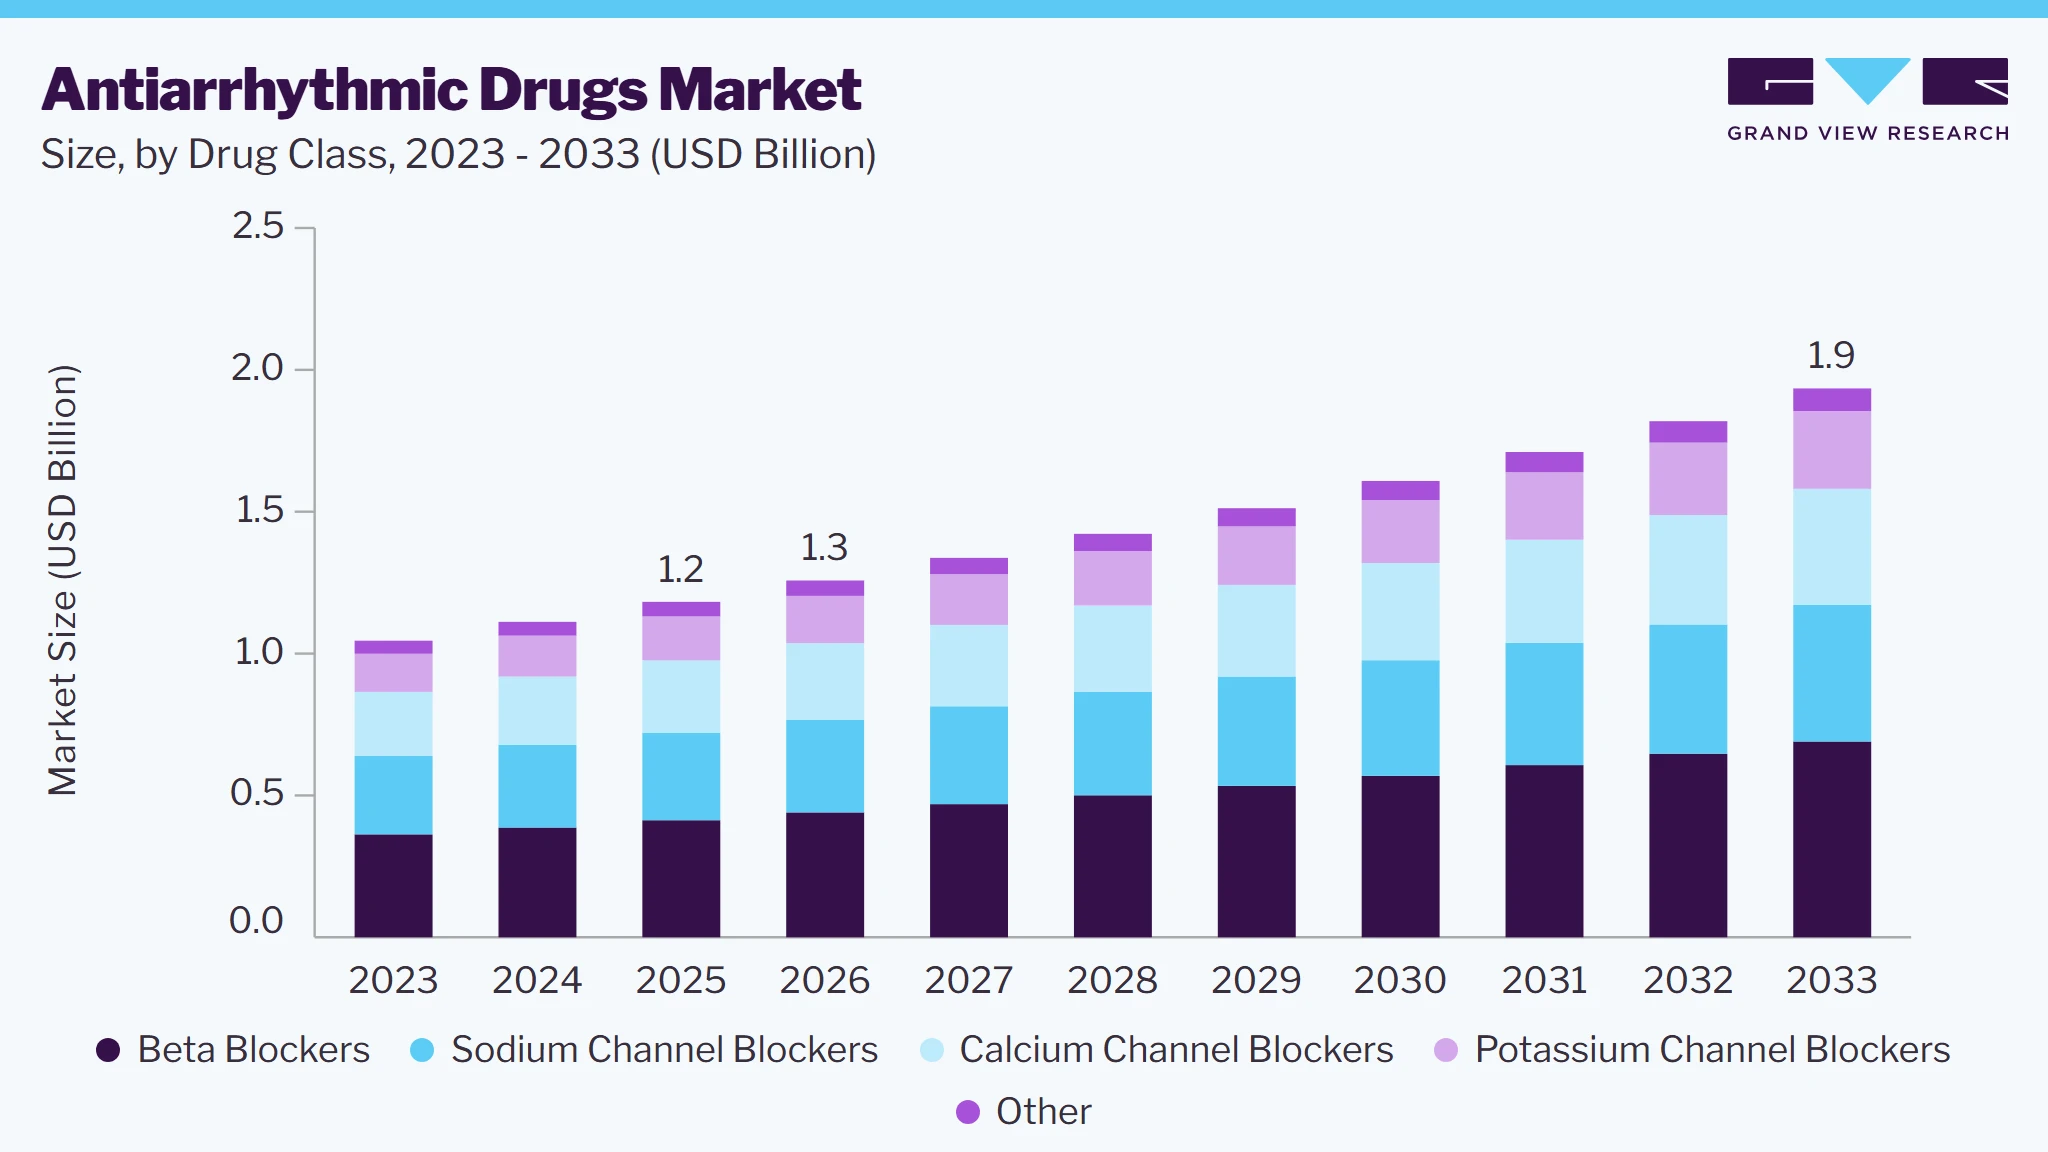 To learn more about this report, Download Free Sample Report
Recent advancements in drug development also play a crucial role in the market's expansion. Pharmaceutical companies are focusing on the innovation of new antiarrhythmic agents that offer improved efficacy and safety profiles. For instance, the introduction of novel medications such as antiarrhythmic agents that target specific ion channels is a significant advancement in personalized medicine. Furthermore, the increasing use of advanced technologies like machine learning in drug discovery is streamlining the development of these drugs, thus accelerating their entry into the market. The U.S. Food and Drug Administration (FDA) and other regulatory bodies are also facilitating faster approvals for these innovations, which helps to meet the growing demand promptly.
Government initiatives aimed at enhancing healthcare infrastructure and accessibility also contribute to market growth. Many countries are investing in healthcare systems to improve diagnosis and treatment options for cardiovascular diseases. For instance, the U.S. government has implemented programs to expand access to cardiac care through telehealth services, which have gained popularity, especially during the COVID-19 pandemic. This increased accessibility facilitates timely diagnosis and treatment of arrhythmias, further driving the demand for antiarrhythmic drugs. Additionally, awareness campaigns focusing on the importance of heart health are encouraging patients to seek treatment earlier, which subsequently increases the market for antiarrhythmic therapies.
Market Dynamics
The antiarrhythmic drugs market is driven by the increasing prevalence of cardiac arrhythmias, rising diagnosis rates, and the continued use of pharmacological therapies for the management of atrial fibrillation, ventricular arrhythmias, and other rhythm disorders. The market is supported by an aging population and the growing burden of cardiovascular diseases, which increase the demand for long-term rhythm control and rate control therapies. Improvements in diagnostic technologies and greater awareness of cardiac rhythm disorders are contributing to earlier diagnosis and timely treatment. Healthcare providers continue to use antiarrhythmic drugs alongside catheter ablation and implantable cardiac devices to improve patient outcomes. Ongoing clinical research focused on improving drug safety, efficacy, and tolerability is expanding treatment options for patients with different types of arrhythmias. In addition, increasing access to cardiovascular care in developing countries and the availability of both branded and generic antiarrhythmic drugs continue to support steady market growth.
The increasing prevalence of atrial fibrillation, ventricular arrhythmias, and other cardiac rhythm disorders is driving demand for antiarrhythmic drugs. The growing elderly population and the rising incidence of hypertension, coronary artery disease, heart failure, and diabetes have increased the number of patients requiring long-term rhythm control therapy. Earlier diagnosis through electrocardiography, ambulatory monitoring, and wearable cardiac devices has also contributed to timely treatment initiation. In addition, updated clinical guidelines supporting rhythm control strategies have strengthened the use of antiarrhythmic drugs alongside catheter ablation and implantable cardiac devices. Pharmaceutical companies continue to invest in products that offer easier administration and rapid symptom relief. For instance, in December 2025, Milestone Pharmaceuticals received U.S. FDA approval for CARDAMYST (etripamil) nasal spray for the conversion of acute symptomatic episodes of paroxysmal supraventricular tachycardia (PSVT) to sinus rhythm in adults. The approval marked the first FDA-approved treatment for PSVT in more than 30 years and the first self-administered nasal spray for the condition. The company stated that more than 2 million people in the United States are affected by PSVT. The approval expanded treatment options for acute arrhythmia management and supported demand for antiarrhythmic drugs.
The use of antiarrhythmic drugs is limited by the risk of adverse effects, including proarrhythmic events, organ toxicity, and clinically significant drug-drug interactions. Several commonly prescribed therapies require regular monitoring because of their effects on cardiac conduction, thyroid function, pulmonary health, liver function, and renal function. These safety concerns may reduce physician preference for long-term drug therapy, particularly in patients with multiple comorbidities. The availability of catheter ablation and implantable cardiac devices as alternative treatment options has also reduced dependence on antiarrhythmic drugs in selected patients. In addition, treatment selection often requires individualized dose adjustments and close clinical follow-up, increasing the complexity of patient management. Strict regulatory requirements for cardiovascular drugs and the need for extensive safety evaluations further increase development timelines and costs. These factors can limit the introduction of new therapies and continue to restrain the growth of the antiarrhythmic drugs market.
The development of novel formulations and patient-friendly drug delivery systems provides opportunities for the antiarrhythmic drugs market. Pharmaceutical companies are focusing on therapies that improve ease of administration, provide rapid symptom control, and reduce the need for prolonged hospital stays. Advances in drug formulation technologies are supporting the development of therapies with improved safety profiles and better patient adherence. The growing adoption of outpatient care and home-based management for selected arrhythmia patients is also creating demand for treatments that can be administered outside hospital settings. In addition, research focused on targeted therapies, precision medicine, and combination treatment approaches is expanding the scope of future treatment options for different types of cardiac arrhythmias. Continued investment in cardiovascular research, supportive regulatory pathways for innovative medicines, and increasing awareness of early arrhythmia diagnosis are expected to create opportunities for product development and market growth over the forecast period.
Market Concentration & Characteristics
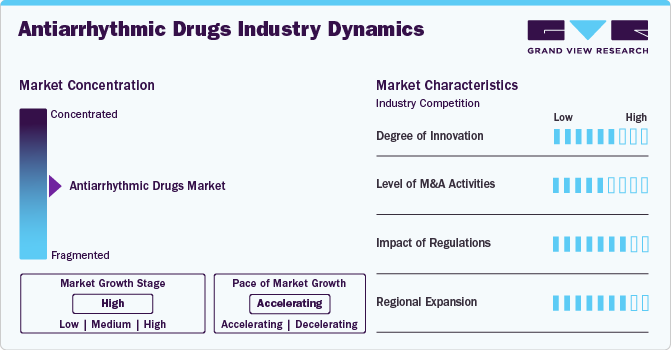
The antiarrhythmic drugs market has seen significant innovation driven by advancements in pharmacology and technology. Recent developments include the introduction of novel agents, such as direct oral anticoagulants (DOACs) and catheter ablation techniques, enhancing the efficacy and safety profiles of treatments. The emergence of precision medicine also plays a crucial role; drugs are increasingly tailored to individual genetic profiles, improving outcomes. Additionally, digital health technologies, including wearable devices that monitor heart rhythms, are providing real-time data to refine treatment protocols.
Mergers and acquisitions (M&A) in the antiarrhythmic drugs market are on the rise as companies seek to expand their product offerings and boost innovation. This trend is driven by the growing demand for effective treatments for cardiovascular diseases, which impact millions worldwide. By integrating innovative start-ups focused on digital health and biotechnology, larger corporations aim to develop new drugs and improve access to advanced therapies.
 To learn more about this report, Download Free Sample Report
Regulatory bodies, including the U.S. Food and Drug Administration (FDA) and the European Medicines Agency (EMA), play a pivotal role in the antiarrhythmic drugs market by establishing guidelines that ensure safety and efficacy. Recent regulatory initiatives have aimed at expediting the approval process for novel therapies through pathways like Breakthrough Therapy Designation and Accelerated Approval, which support rapid access to life-saving medications. Regulatory scrutiny around drug pricing and transparency is also rising, compelling companies to balance innovation with affordability. The global regulatory environment, characterized by harmonization efforts, has enhanced market access for new treatments, fostering competitive dynamics while ensuring patient safety.
The regional expansion of the global antiarrhythmic drugs market is notable, with North America, Europe, and Asia-Pacific being key growth areas. North America remains a leading market due to its advanced healthcare infrastructure, significant investment in research and development, and high prevalence of cardiovascular diseases. The American Heart Association estimates that approximately 121 million adults in the U.S. have some form of cardiovascular disease. In contrast, the Asia-Pacific region is witnessing rapid growth, driven by increasing awareness of heart health, improving healthcare access, and rising geriatric populations. Additionally, government initiatives aimed at enhancing healthcare access and awareness are vital in promoting the use of antiarrhythmic therapies. As a result, the market is expected to see diverse growth patterns across regions, reflecting localized healthcare needs and regulatory environments.
Analyst Perspective
The antiarrhythmic drugs market is shifting toward improved disease management through therapies that provide better rhythm control, improved safety, and greater patient convenience. The market is supported by companies with established cardiovascular portfolios, strong regulatory experience, and broad manufacturing and distribution capabilities. Pfizer, Novartis, Sanofi, and Baxter International continue to maintain their positions through established cardiovascular products and ongoing portfolio management. At the same time, Viatris, Mayne Pharma, Upsher-Smith Laboratories, Amomed Pharma, and Merck are strengthening their presence by expanding product availability through generic medicines, regional expansion, and selected product development activities. Continued research on new formulations and patient-friendly drug delivery systems is expected to support market growth.
Drug Class Insights
Based on drug class, the beta blockers segment led the market with the largest revenue share of 34.9% in 2025. Beta blockers are well-established in the management of cardiovascular conditions, particularly arrhythmias such as atrial fibrillation and ventricular tachycardia. Their efficacy in reducing heart rate and controlling blood pressure has made them a cornerstone in the treatment of these disorders. Research published in the New England Journal of Medicine in August 2024 demonstrates that beta blockers significantly lower the risk of stroke and cardiovascular events in patients with atrial fibrillation, reinforcing their role in treatment protocols. Additionally, the broad acceptance of guidelines from the American Heart Association and the European Society of Cardiology recommends beta blockers as first-line therapy for arrhythmias, ensuring their continued utilization in clinical practice.
Potassium channel blockers is anticipated to experience the fastest CAGR within the global antiarrhythmic drugs market. Primarily, these medications, such as dofetilide and sotalol, are increasingly recognized for their effectiveness in managing various arrhythmias, including atrial fibrillation (AF) and ventricular tachycardia. For instance, Flecainide is a Na+ blocker approved for prevention of both atrial and ventricular arrhythmias and cardioversion of recent-onset AF in patients without known relevant structural heart disease Clinical study published by National Library of Medicines in February 2024 have shown that potassium channel blockers can significantly reduce the incidence of arrhythmic events and improve patient outcomes, which is crucial given the projected rise in AF cases, expected to affect over 12 million individuals in the U.S. by 2030, according to the American Heart Association.
Route of Administration Insights
Based on route of administration,the oral segment led the market with the largest revenue share of 64.2% in 2025. Oral formulations allow patients to self-administer treatments at home, eliminating the need for invasive procedures or hospital visits, which can be particularly appealing in managing chronic conditions such as atrial fibrillation and ventricular tachycardia.Additionally, advancements in drug formulation have led to the development of newer oral agents with improved safety profiles and reduced side effects, further promoting their adoption. Moreover, the recent developments in the market highlight the approval of innovative oral therapies, such as antiarrhythmic drugs that target specific genetic markers, enhancing treatment personalization. For instance, the FDA's approval of drugs like Dronedarone and the introduction of novel oral anticoagulants reflect a shift toward more effective oral options that align with patient needs.
The other segments such as injectable, intranasal, and implantable device segments is expected to grow at a fastest CAGR driven by several key factors. The injectable segment benefits from its ability to provide rapid therapeutic effects, especially in emergency situations. Injectable formulations, such as Amiodarone and Lidocaine, are critical in acute arrhythmias and are commonly administered in hospital settings. Similarly, intranasal administration is gaining traction due to its ease of use and quick onset of action. Recent innovations in nasal delivery systems allow for efficient absorption and the potential for self-administration, making it a promising option for patients who may face barriers to traditional administration routes.
Distribution Channel Insights
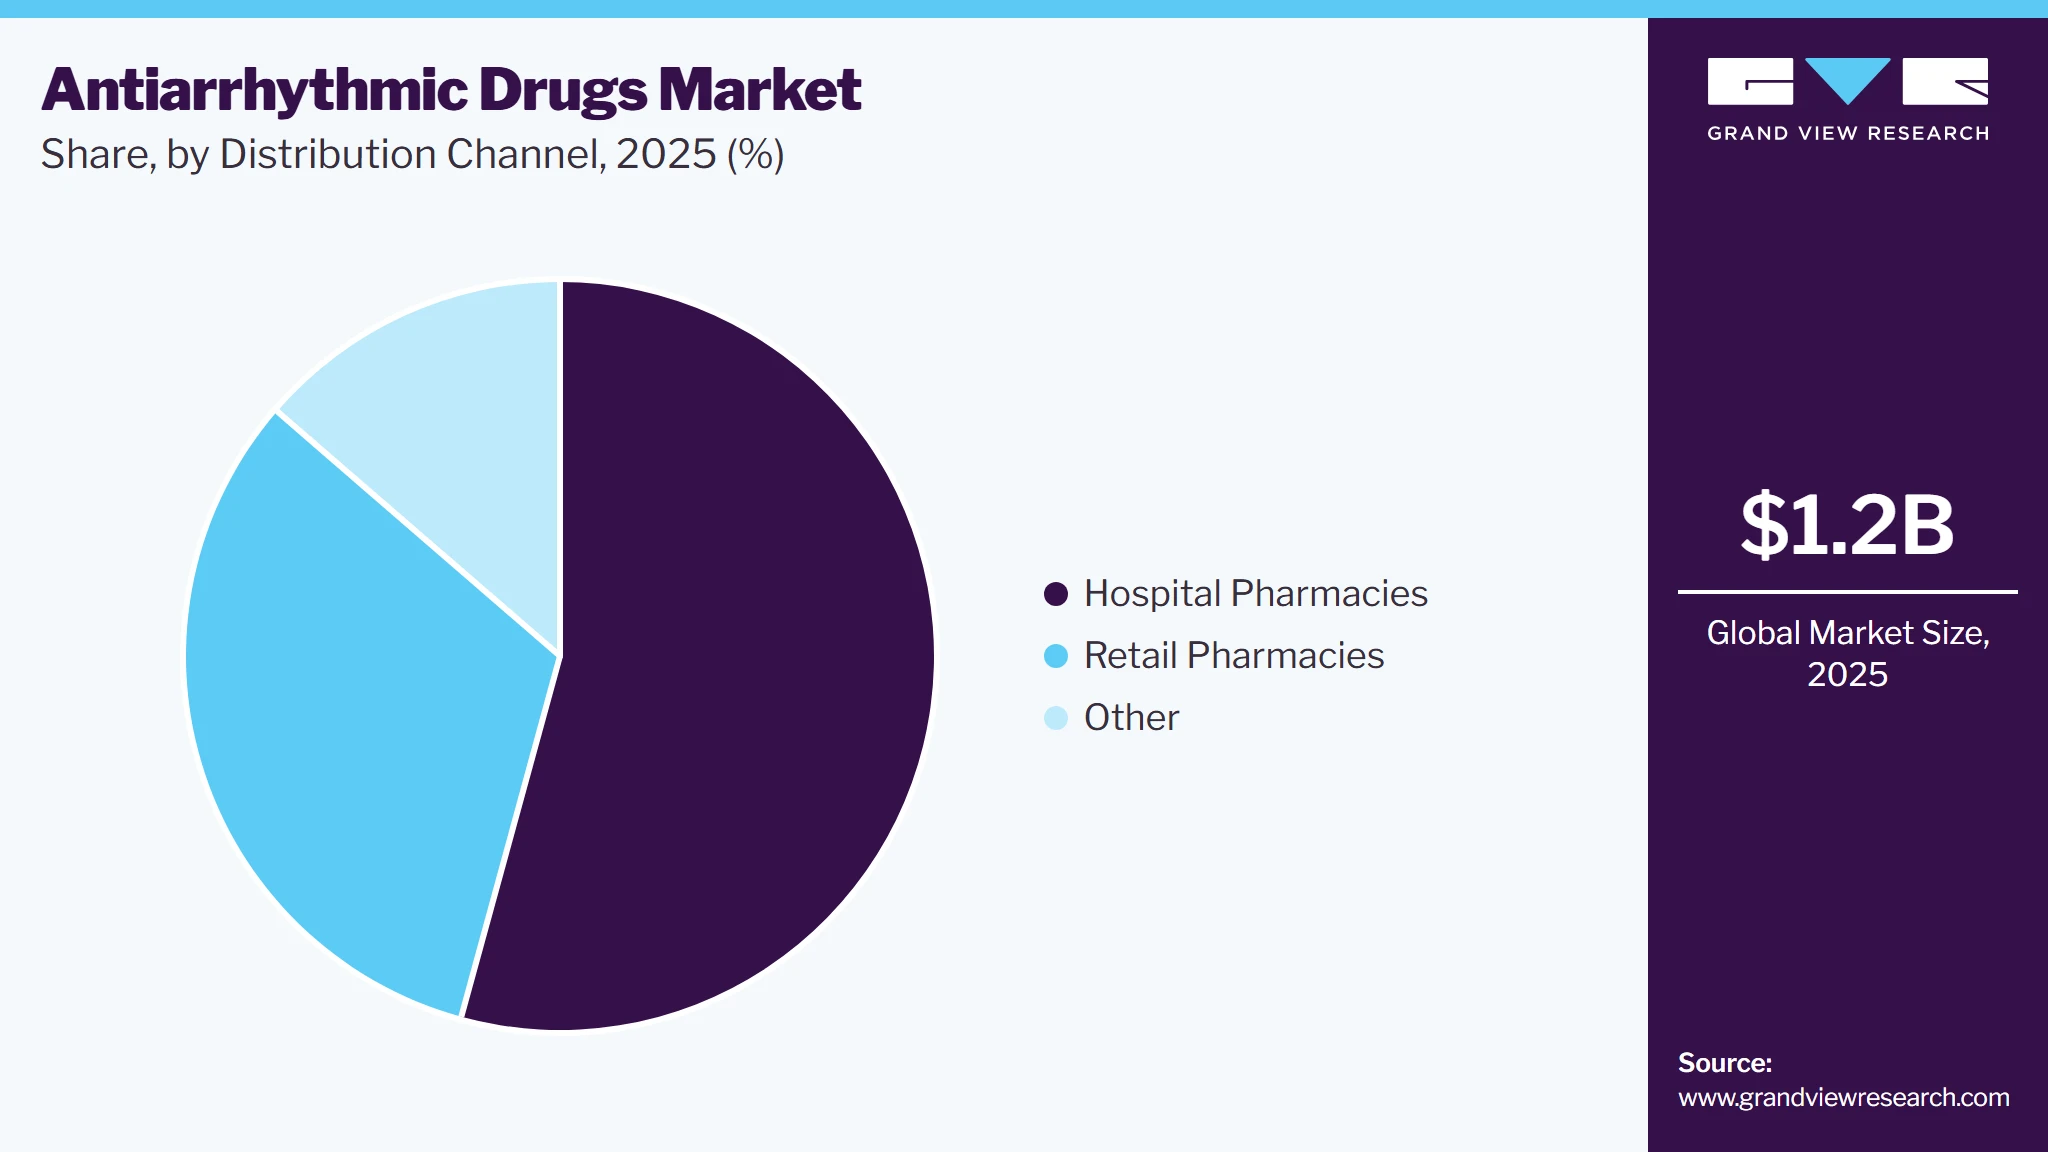
Based on distribution Channel, the hospital pharmacies segment led the market with the largest revenue share of 54.3% in 2025. Hospital pharmacies are often involved in clinical research and trials, leading to the adoption of innovative therapies. As new antiarrhythmic agents are developed and approved, hospitals remain at the forefront of implementing these advancements. Regulatory bodies, such as the FDA, continue to prioritize the approval of novel therapies, which hospital pharmacies are well-positioned to provide. Moreover, the increased investment in hospital infrastructure and technology, alongside the integration of electronic health records (EHRs), has improved medication management and patient outcomes. This technological advancement facilitates better monitoring of patients, ensuring timely administration of antiarrhythmic medications.
 To learn more about this report, Download Free Sample Report
The other distribution channels, including online pharmacies, long-term care pharmacies, and specialty pharmacies, are projected to experience the fastest-growing CAGR in the global antiarrhythmic drugs market. This growth is largely driven by the rising demand for convenient access to medications, technological advancements, and a shift towards patient-centric care. According to the ASOP Foundation 2023 Survey, 52% of Americans aged 18 and older used an online pharmacy in 2022, marking a notable increase of 10 percentage points from 2021 and 17 points from 2020. Furthermore, 71% of respondents reported that they began utilizing online pharmacies within the last 1-3 years, highlighting a significant trend toward digital medication access. Currently, 85% of individuals with online pharmacy experience continue to use these platforms for one or more medications, and 61% report purchasing most or all of their prescriptions online. This shift reflects broader consumer preferences for convenience and accessibility in healthcare. Online pharmacies offer not only ease of ordering but also features like home delivery, telehealth consultations, and user-friendly interfaces, enhancing the overall patient experience
Regional Insights
North America dominated the antiarrhythmic drugs market with the largest revenue share of 37.4% in 2025 and is primarily driven by the U.S., which has a high prevalence of cardiovascular diseases. According to the CDC, about 702,880 Americans died from heart disease in 2022, underscoring a critical need for effective antiarrhythmic therapies. Regulatory support from agencies like the FDA facilitates the rapid approval of innovative drugs, further stimulating market growth.
 To learn more about this report, Download Free Sample Report
U.S. Antiarrhythmic Drugs Market Trends
The antiarrhythmic drugs market in the U.S. held the largest share in the North America region in 2025. The U.S. antiarrhythmic drugs market is characterized by a robust pipeline of innovative treatments and a strong emphasis on research and development. The high prevalence of arrhythmias, with millions affected by conditions like atrial fibrillation, drives significant investment in therapeutic solutions. The FDA has accelerated the approval process for novel antiarrhythmic agents, which has led to the introduction of several new drugs in recent years. Additionally, initiatives to improve healthcare access, such as the Affordable Care Act, have enhanced patient reach, contributing to increased medication adherence and, consequently, market growth.
The antiarrhythmic drugs market in Canada is shaped by a rising incidence of heart disease, with cardiovascular conditions being a leading cause of mortality. The Canadian government’s focus on healthcare reforms, such as the implementation of the Canada Health Act, ensures broader access to essential medications, including antiarrhythmics.
Europe Antiarrhythmic Drugs Market Trends
The antiarrhythmic drugs market in Europe is experiencing rapid growth due to a high prevalence of cardiovascular diseases across the region. The European Society of Cardiology estimated that prevalence rate of atrial fibrillation will increase by 89% by 2060 in Europe. Stringent regulations from the European Medicines Agency (EMA) ensure the safety and efficacy of new drugs, encouraging innovation in antiarrhythmic therapies. Moreover, government initiatives aimed at enhancing cardiovascular health, such as the European Heart Health Initiative, further bolster the market.
The antiarrhythmic drugs market in the UK is bolstered by a strong focus on cardiovascular health, driven by high prevalence rates of conditions such as arrhythmias. The National Health Service (NHS) plays a pivotal role in regulating access to antiarrhythmic medications, ensuring that innovative treatments are available to patients. Recent initiatives, including the NHS Long Term Plan, aim to enhance cardiovascular disease management through better screening and treatment pathways.
The antiarrhythmic drugs market in France is strongly supported by an aging population, with cardiovascular diseases being a leading health concern. According to Foundation de France, every four minutes, someone in France experiences a cardiovascular event. CVD is the second leading cause of death in France, and it's affecting younger people more and more. The French government’s commitment to improving cardiovascular health through the National Health Strategy has led to increased funding for research and development of antiarrhythmic medications. Moreover, the Haute Autorité de Santé (HAS) ensures that new treatments meet high safety and efficacy standards, facilitating market entry for innovative drugs. This regulatory support, coupled with advancements in personalized medicine, is driving market growth.
Asia Pacific Antiarrhythmic Drugs Market Trends
The antiarrhythmic drugs market in the Asia Pacific region is experiencing rapid growth due to a rising incidence of cardiovascular diseases and increasing healthcare expenditure. According to the World Health Organization, heart disease is a leading cause of death in many Asia Pacific countries. The region’s expanding middle class is driving demand for better healthcare services and access to innovative treatments. Regulatory bodies are also streamlining approval processes for new drugs, encouraging pharmaceutical companies to invest in the region. Additionally, initiatives aimed at improving public awareness about heart health are contributing to increased demand for antiarrhythmic medications.
The antiarrhythmic drugs market in India is characterized by rapid growth driven by a significant rise in cardiovascular disease prevalence. The Indian government has implemented various health initiatives, such as the National Health Mission, to improve access to healthcare services, including medications for heart conditions. Additionally, increased investment in healthcare infrastructure and the rising adoption of digital health technologies are facilitating better patient management and adherence to antiarrhythmic therapies.
The antiarrhythmic drugs market in China is heavily influenced by the rising prevalence of cardiovascular diseases (CVD). According to the report published by National Library of Medicines in December 2023, approximately 330 million individuals in China are currently affected by CVD. Key statistics include 245 million with hypertension, 13 million with stroke, and 4.87 million with atrial fibrillation. Contributing factors to CVD include tobacco use, poor diet, lack of physical activity, and environmental issues. Regulatory support from the National Medical Products Administration (NMPA) is expediting the approval of innovative therapies, facilitating the introduction of advanced antiarrhythmic drugs. Furthermore, increasing health awareness among the population is driving demand for effective treatment options for heart conditions.
Latin America Antiarrhythmic Drugs Market Trends
The antiarrhythmic drugs market in Latin America is expanding due to rising cardiovascular disease prevalence and growing healthcare access. According to the Pan American Health Organization, in 2019, 2.0 million people died from CVD in the region. Efforts to improve healthcare infrastructure, alongside government initiatives aimed at increasing access to essential medicines, are facilitating market growth. Moreover, increasing awareness of heart health and the importance of early intervention are driving demand for antiarrhythmic medications. The collaboration between local pharmaceutical companies and international firms is also enhancing the availability of innovative treatments in the region.
The antiarrhythmic drugs market in Brazil is driven by a high incidence of cardiovascular diseases, with studies showing that heart disease is a leading cause of death in the country. The Brazilian government has implemented health programs aimed at reducing mortality from cardiovascular conditions, including improved access to medications. Regulatory bodies like ANVISA play a crucial role in ensuring the safety and efficacy of new antiarrhythmic drugs, fostering a conducive environment for innovation. Furthermore, the growing middle class in Brazil is increasing demand for advanced healthcare solutions, contributing to the expansion of the antiarrhythmic drugs market.
Middle East & Africa Antiarrhythmic Drugs Market Trends
The antiarrhythmic drugs market in the Middle East and Africa is witnessing significant growth driven by an increasing prevalence of cardiovascular diseases and improving healthcare infrastructure. The World Health Organization reports that cardiovascular diseases account for a substantial percentage of mortality in the region. Government initiatives aimed at enhancing healthcare access, such as the African Union’s Agenda 2063, are fostering investments in health systems. Additionally, rising awareness of cardiovascular health among populations is contributing to the demand for antiarrhythmic drugs.
The antiarrhythmic drugs market in Saudi Arabia is characterized by a growing prevalence of cardiovascular diseases, with studies indicating that heart disease accounts for a significant portion of mortality. The Saudi government’s Vision 2030 initiative emphasizes improving healthcare services and increasing access to essential medications, including antiarrhythmic drugs. Recent investments in healthcare infrastructure, along with partnerships with global pharmaceutical companies, are enhancing the availability of advanced treatments and drugs.
Key Antiarrhythmic Drugs Company Insights
The global antiarrhythmic drugs market is dominated by several major pharmaceutical companies that collectively account for a significant market share. These leading players established themselves through extensive research and development efforts, resulting in the introduction of innovative drug class options. They also expanded their product portfolios through strategic collaborations, mergers, and acquisitions.
Key Antiarrhythmic Drugs Companies:
The following are the leading companies in the antiarrhythmic drugs market. These companies collectively hold the largest market share and dictate industry trends.
- Pfizer
- Novartis
- Mylan (now part of Viatris)
- Baxter International
- Sanofi
- GlaxoSmithKline
- Mayne Pharma
- Upsher-Smith Laboratories
- Amomed Pharma
- Merck
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Pfizer, Novartis, Sanofi, Baxter International, GlaxoSmithKline, Merck)
- Focus on maintaining broad cardiovascular portfolios through lifecycle management, product line extensions, and geographic expansion. Strengthen market presence by investing in clinical studies, regulatory approvals, and partnerships with hospitals and healthcare providers to support the use of antiarrhythmic drugs.
- Well-established brands with broad product portfolios and long-standing relationships with hospitals, healthcare providers, and distribution partners. Strong global manufacturing capabilities, regulatory experience, and wide commercial reach support consistent product availability across major markets.
- Dependence on mature products with generic competition can limit product differentiation. Regulatory requirements, product lifecycle challenges, and pricing pressure from generic manufacturers may affect business growth.
Emerging Players (Mayne Pharma, Upsher-Smith Laboratories, Amomed Pharma, Viatris (formerly Mylan))
- Focus on expanding product availability through generic antiarrhythmic drugs, regional market expansion, and targeted licensing agreements. Strengthen market presence by improving product accessibility, optimizing manufacturing efficiency, and addressing unmet needs in selected healthcare markets.
- Ability to offer cost-effective treatment options and respond to regional demand through focused product portfolios. Flexible business strategies and targeted commercial activities support expansion in selected geographic markets.
- Limited global commercial presence compared with established pharmaceutical companies. Smaller product portfolios and lower investment capacity for large clinical development programs may restrict expansion into new markets.
Recent Developments
-
In November 2024, Huyabio International announced new patient data for an antiarrhythmic drug, HBI-300. The drug candidate has a unique profile for the treatment of one of the most serious heart conditions, atrial fibrillation.
-
In May 2024, Milestone Pharmaceuticals Inc. announced a partnership with Arrhythmia Alliance to raise awareness about supraventricular tachycardia (SVT). Milestone, a biopharmaceutical company specializing in innovative cardiovascular medicines, aims to enhance education and understanding of this condition through this collaboration.
-
In December 2023, Acesion Pharma a biotech company pioneering first-in-class novel therapies for atrial fibrillation (the most common cardiac arrhythmia), announced the publication of data in Nature Medicine with the full results from its Phase 2 proof-of-concept trial of AP30663, a first-in-class SK ion channel inhibitor for conversion of AF to normal sinus rhythm.
Antiarrhythmic Drugs Market Report Scope
Report Attribute
Details
Market Size in 2025
USD 1,182.3 million
Estimated market size in 2026
USD 1,257.4 million
Projected Market Size by 2033
USD 1,934.5 million
Growth rate
CAGR of 6.3% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Drug class, route of administration, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Pfizer; Novartis; Mylan (now part of Viatris); Baxter International; Sanofi; GlaxoSmithKline; Mayne Pharma; Upsher-Smith Laboratories; Amomed Pharma; Merck
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Antiarrhythmic Drugs Market Report Segmentation
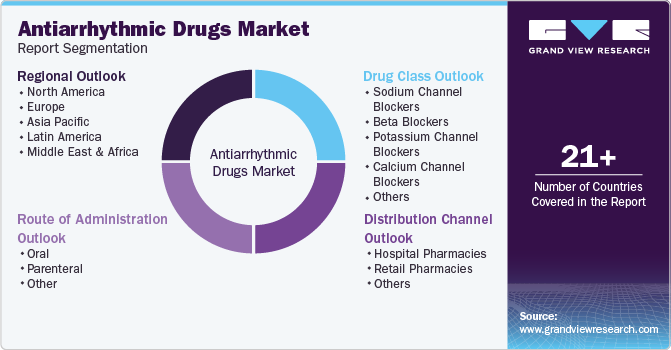
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global antiarrhythmic drugs market report based on drug class, route of administration, distribution channel, and region.
 To learn more about this report, Download Free Sample Report
-
Drug Class Outlook (Revenue, USD Million; 2021 - 2033)
-
Sodium Channel Blockers
-
Beta Blockers
-
Potassium Channel Blockers
-
Calcium Channel Blockers
-
Other
-
-
Route of Administration Outlook (Revenue, USD Million; 2021 - 2033)
-
Oral
-
Parenteral
-
Other
-
-
Distribution Channel Outlook (Revenue, USD Million; 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Other
-
-
Regional Outlook (Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
China
-
Japan
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The Antiarrhythmic Drugs market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each Antiarrhythmic Drugs segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Component
Revenue capture definition
Control and Monitoring Cloud Services
The largest solution category, capturing value through continuous visibility into cloud applications, user activities, data movement, and policy enforcement across multi-cloud environments. Vendors monetize by enabling organizations to detect shadow IT, monitor cloud usage, and maintain centralized governance over expanding SaaS, PaaS, and IaaS deployments.
Risk and Compliance Management
Commercial demand is driven by enterprises seeking automated compliance monitoring, audit readiness, regulatory reporting, and policy management across cloud ecosystems. Providers differentiate through solutions that simplify adherence to data protection regulations while reducing compliance risks and administrative overhead.
Data Security
Market value is derived from capabilities such as data loss prevention (DLP), encryption, tokenization, access governance, and secure data sharing. Organizations invest in these solutions to safeguard sensitive information throughout its lifecycle while maintaining secure collaboration across cloud platforms.
Threat Protection
Revenue opportunities stem from advanced threat detection, malware prevention, user and entity behavior analytics (UEBA), account compromise detection, and AI-driven security intelligence. Growing sophistication of cloud-based cyberattacks continues to accelerate enterprise investment in proactive threat defense capabilities.
Others
This segment includes identity management, cloud security posture management (CSPM), cloud infrastructure entitlement management (CIEM), API security, and workload protection features integrated into CASB platforms. Vendors expand platform value by offering unified cloud security capabilities that reduce complexity and strengthen overall cyber resilience.
Segment - Deployment Mode
Revenue capture definition
IaaS
Demand originates from organizations securing virtual machines, storage resources, containers, and cloud networking environments hosted on public infrastructure platforms. CASB vendors generate value by extending policy enforcement, workload visibility, and access controls across rapidly expanding infrastructure deployments.
PaaS
Spending is focused on protecting cloud-native application development environments, databases, APIs, and DevOps workflows. Enterprises increasingly adopt CASB solutions to secure application lifecycles while maintaining governance over developer access and cloud service consumption.
SaaS
The dominant deployment segment, supported by widespread adoption of enterprise applications such as collaboration tools, CRM, ERP, productivity suites, and file-sharing platforms. Providers benefit from recurring demand for access control, data protection, and user activity monitoring across an expanding SaaS ecosystem.
Segment - Enterprise Size
Revenue capture definition
Large Enterprises
High-value contracts are secured from organizations managing complex hybrid and multi-cloud infrastructures across global operations. Enterprise deployments typically include advanced policy customization, integration with existing security architectures, and centralized governance for thousands of users and cloud applications.
Small and Medium Enterprises (SMEs)
Adoption is fueled by cloud-first business strategies that require enterprise-grade security without significant infrastructure investments. Subscription-based CASB platforms enable SMEs to strengthen cloud protection, meet customer security expectations, and simplify security management with limited IT resources.
Segment - End Use
Revenue capture definition
BFSI
Financial institutions invest heavily in CASB solutions to secure digital banking platforms, payment applications, customer financial records, and cloud-hosted business systems. Strict regulatory obligations and the need to prevent data breaches make cloud access governance a strategic cybersecurity priority.
Government
Public-sector agencies deploy CASB platforms to protect classified information, citizen records, and cloud-based public services. Procurement is driven by national cybersecurity frameworks, digital government initiatives, and requirements for secure cloud adoption across departments.
Healthcare
Healthcare organizations implement CASB solutions to safeguard electronic health records, medical imaging repositories, telehealth applications, and cloud-based clinical systems. Protecting sensitive patient information while maintaining regulatory compliance continues to drive investment in this segment.
IT & Telecom
Technology companies and telecom operators utilize CASB platforms to secure cloud-native applications, distributed workforces, software development environments, and managed cloud services. The rapid expansion of digital infrastructure and SaaS adoption sustains strong demand for cloud security solutions.
Manufacturing
Industrial enterprises adopt CASB technologies to protect cloud-connected production systems, intellectual property, engineering data, and smart manufacturing platforms. Increasing integration between operational technology (OT) and cloud environments is expanding the need for comprehensive cloud security governance.
Retail
Retailers leverage CASB platforms to secure e-commerce applications, customer databases, digital payment systems, and omnichannel operations. Rising online transactions and customer data protection requirements continue to strengthen cloud security investments across the retail sector.
Education
Educational institutions deploy CASB solutions to secure learning management systems, student information platforms, research data, and cloud collaboration tools used by faculty and students. Growth is supported by the ongoing digitalization of education and hybrid learning environments.
Others
This category includes energy, logistics, media, legal services, hospitality, pharmaceuticals, and professional services. Organizations across these sectors implement CASB solutions to gain visibility into cloud usage, strengthen access controls, and protect critical business data as cloud adoption continues to accelerate.
Estimation Model
 To learn more about this report, Download Free Sample Report
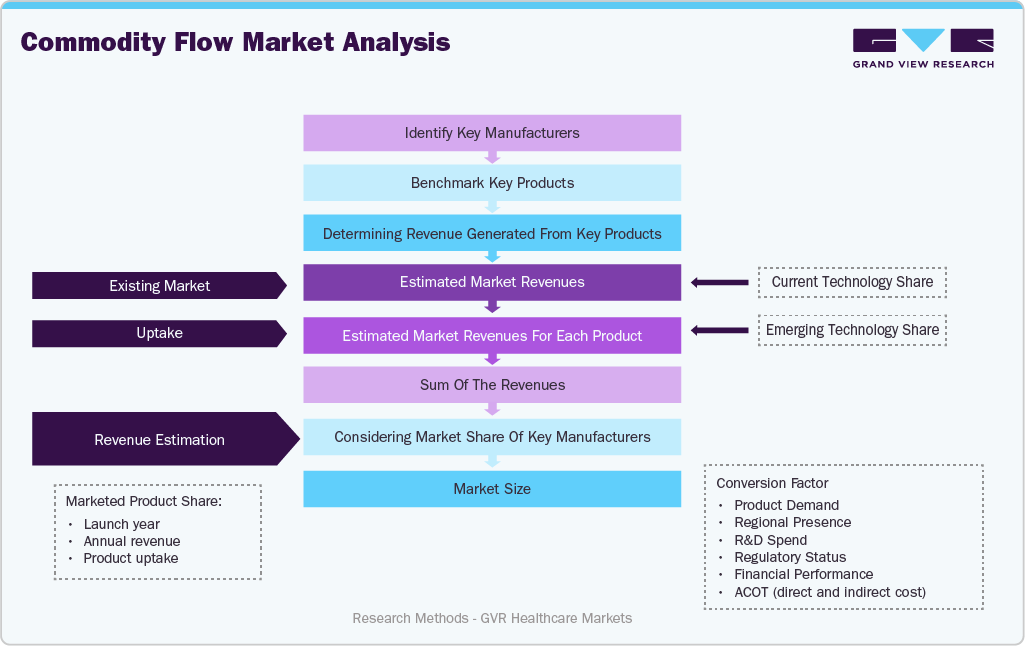
The study adopted a commodity flow market analysis approach to estimate the size of the global antiarrhythmic drugs market. Key manufacturers and marketed antiarrhythmic drugs were identified across sodium channel blockers, beta blockers, potassium channel blockers, calcium channel blockers, and other drug classes. Product benchmarking was conducted using company annual reports, investor presentations, regulatory filings, product labels, and published literature to evaluate product availability, pricing, patent status, and geographic presence. Revenue generated from key products was assessed using publicly available company information and validated through prescription volumes, treatment patterns, healthcare utilization, and regional demand. Market estimates were further verified by analyzing product adoption across hospitals, retail pharmacies, and other distribution channels, along with the market share of leading manufacturers. Primary interviews with industry participants and healthcare professionals were conducted to validate assumptions, product positioning, and regional market trends, ensuring accurate market estimates.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Antiarrhythmic Drugs Competitive Landscape & Product Portfolio Assessment
Conducted a targeted assessment of the global antiarrhythmic drugs market, evaluating marketed products, late-stage pipeline candidates, drug classes, clinical development activities, and competitive positioning. The study analyzed key companies including Pfizer, Novartis, Sanofi, Baxter International, Viatris, Merck, GlaxoSmithKline, Mayne Pharma, Upsher-Smith Laboratories, and Amomed Pharma, along with product availability and development trends across atrial and ventricular arrhythmias.
Helped the client identify key competitors, compare product portfolios, evaluate pipeline activities, and assess partnership, licensing, and acquisition opportunities across the antiarrhythmic drugs market.
Antiarrhythmic Drugs Product Benchmarking Study
Delivered a benchmarking assessment of approved antiarrhythmic drugs based on drug class, route of administration, clinical use, safety profile, treatment duration, and regulatory approvals. The study compared products across sodium channel blockers, beta blockers, potassium channel blockers, calcium channel blockers, and other antiarrhythmic therapies to identify differences in product positioning and clinical application.
Enabled the client to compare product performance, identify portfolio gaps, support product positioning strategies, and evaluate opportunities for lifecycle management and future product development.
Antiarrhythmic Drugs Manufacturing & Supply Chain Assessment
Conducted an assessment of the antiarrhythmic drug manufacturing ecosystem, evaluating active pharmaceutical ingredient (API) suppliers, finished dosage manufacturers, regulatory compliance requirements, contract manufacturing organizations (CMOs), distribution networks, and regional manufacturing capabilities supporting commercial supply. The study also reviewed supply chain challenges affecting product availability across major markets.
Supported manufacturing and supply planning by identifying qualified manufacturing partners, assessing supply chain risks, evaluating outsourcing opportunities, and strengthening long-term product availability across regional and global markets.
Frequently Asked Questions About This Report
The global antiarrhythmic drugs market is expected to grow at a CAGR of 6.3% from 2026 to 2033, reaching USD 1,934.5 million by 2033.
North America dominated the antiarrhythmic drugs market with a 37.4% revenue share in 2025.
The beta blockers segment led the market with the largest revenue share of 34.9% in 2025.
The oral segment accounted for the largest revenue share of 64.2% in 2025, owing to its widespread use for long-term management of cardiac arrhythmias.
The hospital pharmacies segment held the largest revenue share of 54.3% in 2025, supported by the high utilization of antiarrhythmic drugs in inpatient and emergency care settings.
Key players include Pfizer, Novartis, Viatris (formerly Mylan), Baxter International, Sanofi, GlaxoSmithKline (GSK), Mayne Pharma, Upsher-Smith Laboratories, Amomed Pharma, and Merck.
The global antiarrhythmic drugs market size was valued at USD 1,182.3 million in 2025 and is estimated at USD 1,257.4 million for 2026.
Key factors include the rising prevalence of cardiac arrhythmias, increasing diagnosis rates, growing elderly population, rising burden of cardiovascular diseases, advancements in cardiac diagnostic technologies, and continued adoption of rhythm control therapies alongside catheter ablation and implantable cardiac devices.
Asia Pacific is expected to be the fastest-growing regional market during the forecast period, driven by improving healthcare infrastructure, increasing cardiovascular disease burden, and expanding access to cardiac care.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


