
- Home
- »
- Pharmaceuticals
- »
-
Antibody Drug Conjugates Market Size Report, 2026-2033GVR Report cover

Antibody Drug Conjugates Market (2026 - 2033)
Size, Share & Trends Analysis Report By Application (Blood Cancer, Urothelial Carcinoma, Ovarian Cancer, Breast Cancer, Other Cancer), By Product, By Payload, By Technology, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$14.5BMarket Estimate, 2026
$16.7BMarket Forecast, 2033
$32.1BCAGR, 2026–2033
11.5%Antibody Drug Conjugates Market Summary
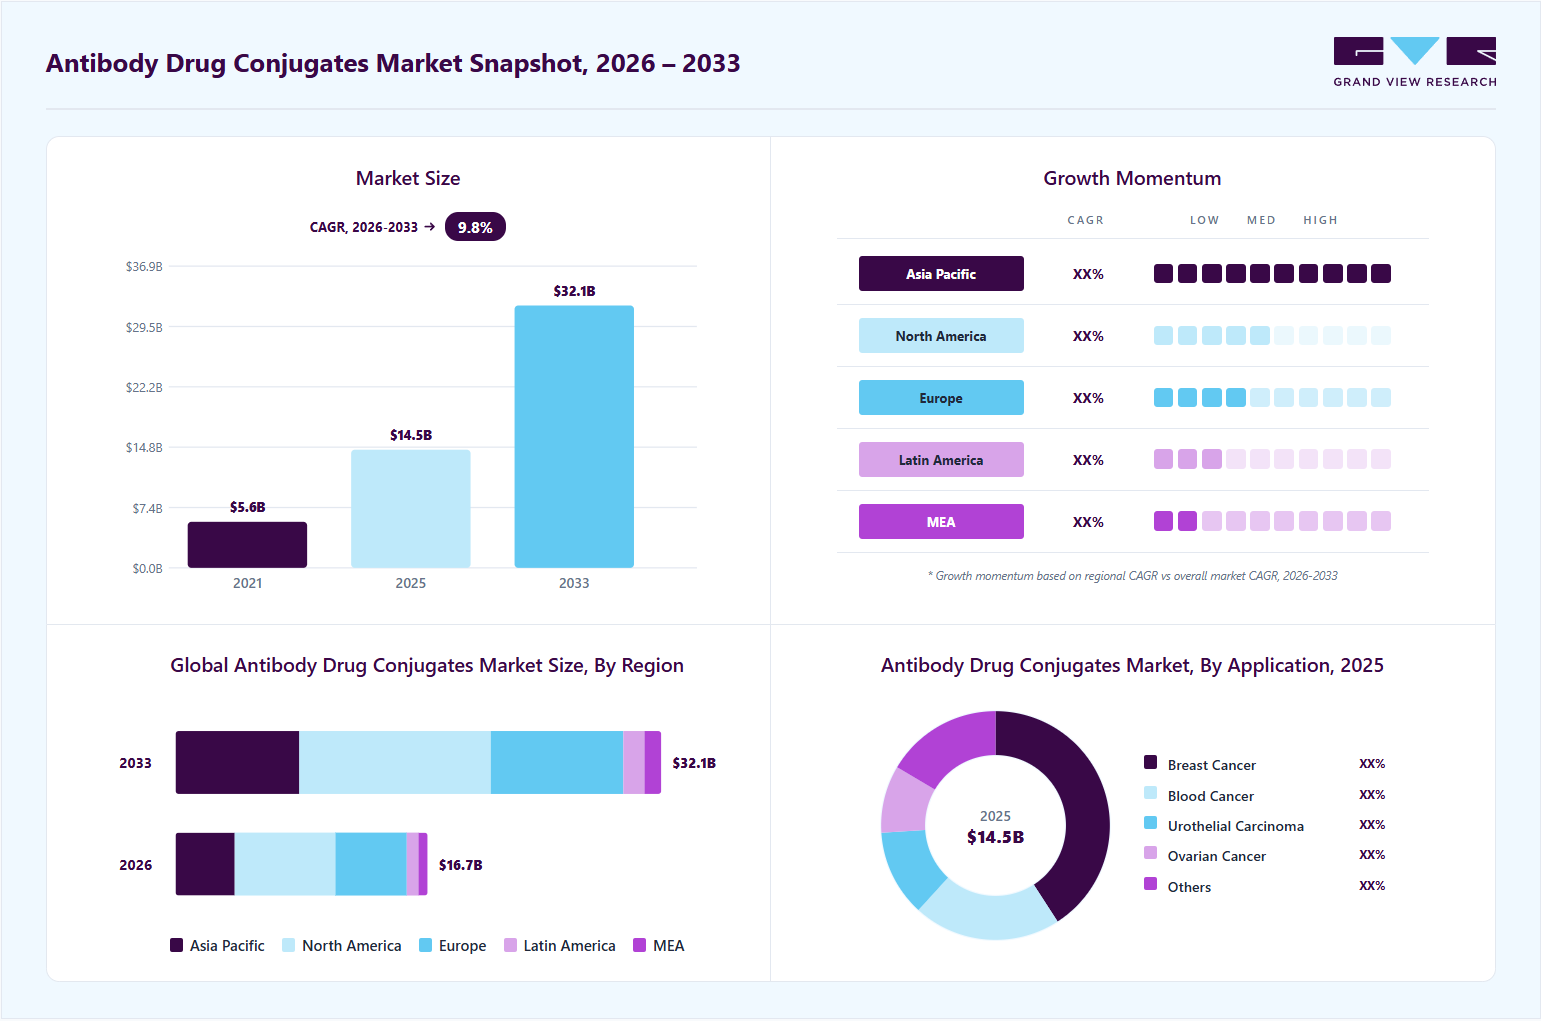
The global antibody drug conjugates market size was valued at USD 14.5 billion in 2025 and is projected to grow from USD 16.7 billion in 2026 to USD 32.1 billion by 2033, at a CAGR of 11.5% from 2026 to 2033. North America dominated the Antibody Drug Conjugate market with the largest revenue share of 39.80% in 2025. This growth is primarily driven by the increasing prevalence of cancer and the growing demand for targeted therapies that offer greater efficacy with reduced systemic toxicity.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By application: Breast Cancer segment held the largest revenue share of 40.8% in 2025.
- By technology: Cleavable Linker segment held the largest revenue share of 67.7% in 2025.
- By payload: Auristatins (MMAE, MMAF) segment held the largest revenue share of 35.9% in 2025.
- By product: Enhertu (trastuzumab deruxtecan) segment held the largest revenue share of 27.9% in 2025.
- By distribution Channel: Hospital Pharmacy segment held the largest revenue share of 52.8% in 2025.
Regional Highlights
- Largest regional market: North America (39.80% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The Antibody Drug Conjugate market in the U.S. held the largest share in 2025.
Market Size & Forecast
- Market size in 2025: USD 14.5 Billion
- Estimated market size in 2026: USD 16.7 Billion
- Projected market size by 2033: USD 32.1 Billion
- CAGR (2026-2033): 11.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The antibody-drug conjugates (ADC) market is experiencing significant growth, driven by advancements in targeted therapies, increasing clinical trials, and strategic investments by pharmaceutical companies. Ongoing research and development activities support this expansion, with ongoing advancements in targeted therapy and precision medicine increasing the appeal of ADCs as a preferred treatment option in oncology. The rising global incidence of various cancer types has created a demand for therapies that offer high efficacy with fewer adverse effects. ADCs address this need by delivering potent cytotoxic agents directly to cancer cells while sparing healthy tissues, thereby improving patient outcomes. The increasing number of clinical trials and regulatory approvals reflects the commitment of pharmaceutical companies to invest in this novel treatment class.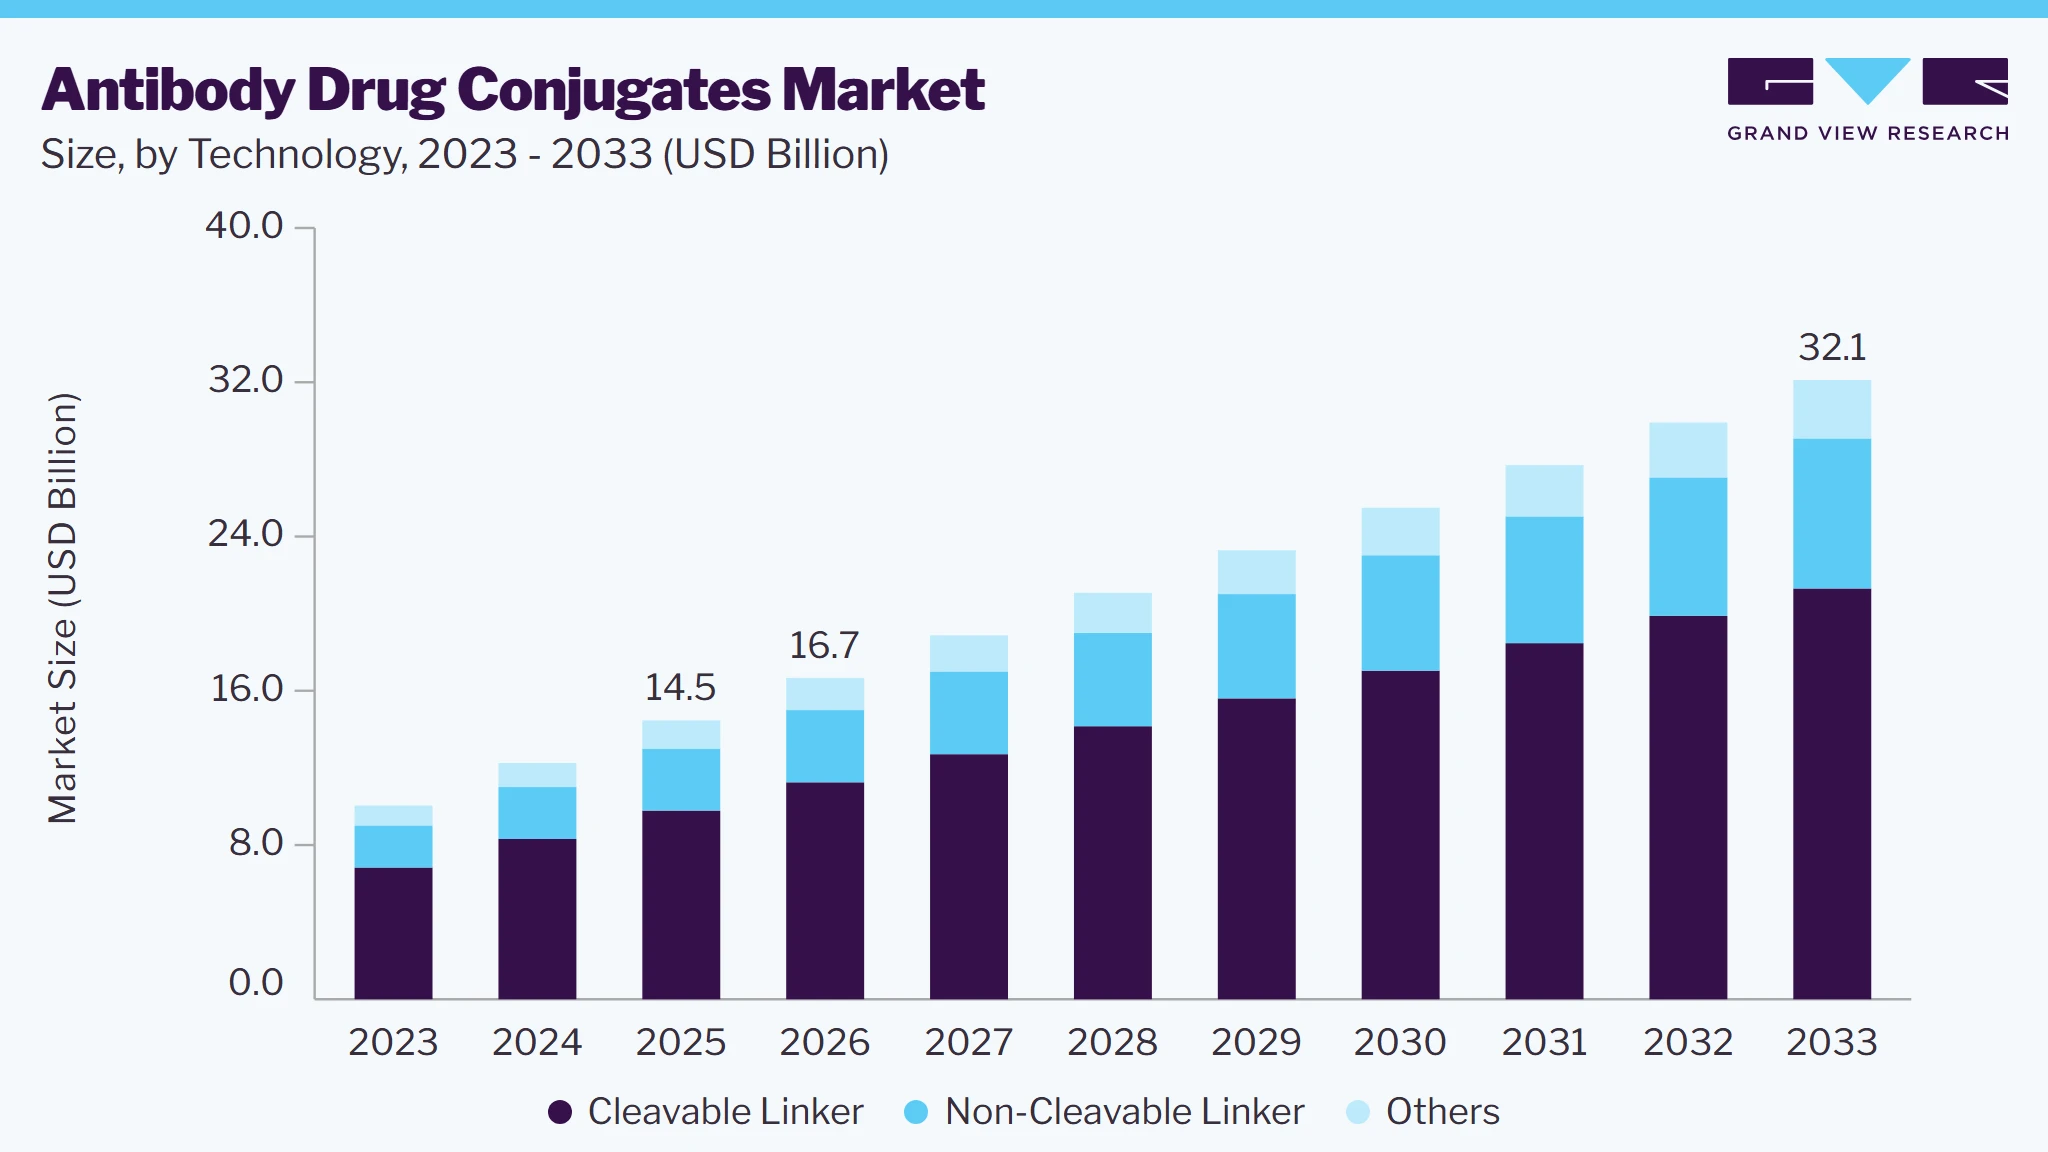 To learn more about this report, Download Free Sample Report
For instance, in June 2025, the U.S. approved Datroway (datopotamab deruxtecan), an ADC targeting the TROP 2 protein, for the treatment of advanced non-small cell lung cancer in adults who had previously undergone treatment. Additionally, in February 2025, the FDA approved Datroway for the treatment of unresectable or metastatic hormone receptor-positive, HER2-negative breast cancer in adults who had undergone prior endocrine-based therapy and chemotherapy. Similarly, in April 2025, GSK received UK regulatory approval for Blenrep, an ADC for the treatment of adults with multiple myeloma in combination with another medication after at least one prior therapy. These developments highlight the continued growth and validation of ADC therapies.
In addition to the pipeline momentum, the availability of several approved ADCs is shaping the current market landscape. Key products include Kadcyla and Polivy by Genentech/Roche, Adcetris by Seattle Genetics, Enhertu from AstraZeneca and Daiichi Sankyo, and Pfizer’s Besponsa and Mylotarg. These drugs have demonstrated clinical success in targeting specific cancer indications, increasing physician confidence and patient acceptance. Furthermore, strategic collaborations and acquisitions are driving market growth. For example, in March 2025, AstraZeneca agreed to acquire biotechnology company EsoBiotec for up to $1 billion to expand its investments in cell therapies for cancer treatment. In June 2025, BioNTech and Bristol Myers Squibb announced a collaboration to co-develop and commercialize BNT327, an experimental ADC, with BioNTech receiving an upfront payment of $1.5 billion and potential milestone payments totaling up to $7.6 billion. ADCs are designed to combine a monoclonal antibody with a chemotherapy drug, connected through a stable chemical linker. This targeted mechanism enables precise treatment delivery to tumor cells while reducing systemic toxicity, differentiating ADCs from traditional chemotherapy. As demand grows for therapies that balance effectiveness with safety, the role of ADCs in cancer care is expected to become even more prominent across global markets.
Market Dynamics
The antibody-drug conjugates (ADCs) market is witnessing strong growth, driven by the rising global cancer burden, increasing demand for targeted therapies, and continuous advancements in linker and payload technologies that improve efficacy while reducing systemic toxicity. Several blockbuster ADCs, including HER2- and TROP2-targeted therapies, have expanded adoption across breast, lung, and hematologic cancers, while major pharmaceutical companies continue to invest heavily through licensing and acquisition deals to strengthen oncology pipelines. However, market growth is constrained by high development and manufacturing costs, complex supply chains, safety concerns related to off-target toxicity, and stringent regulatory requirements. Despite these challenges, a robust clinical pipeline and growing precision oncology adoption continue to support long-term market expansion.
The antibody-drug conjugates (ADCs) market is driven by the increasing clinical validation of ADCs across multiple cancer indications and the growing confidence among oncologists in targeted therapies. Advances in antibody engineering, linker technologies, and payload design have improved therapeutic precision, enabling ADCs to deliver potent cytotoxic agents directly to cancer cells while limiting damage to healthy tissues. As a result, ADCs are increasingly being incorporated into treatment guidelines and clinical practice across solid tumors and hematological malignancies.
In 2025 was the continued expansion of indications for Enhertu, which strengthened the role of ADCs in breast cancer treatment and demonstrated the ability of these therapies to address broader patient populations beyond traditional biomarker-defined groups. Similarly, the approval of Datroway further reinforced industry confidence in next-generation ADC platforms. These developments have encouraged pharmaceutical companies to increase investment in ADC research and development, while healthcare providers have become more willing to adopt ADC-based treatment regimens. The combination of strong clinical outcomes, expanding physician familiarity, and growing regulatory support continues to position ADCs as one of the most important innovation areas within oncology therapeutics.
The ADC market faces notable challenges associated with manufacturing complexity and safety management. ADCs require the integration of biologics manufacturing with highly potent cytotoxic compounds, creating a technically demanding production process that necessitates specialized facilities, advanced quality control systems, and strict regulatory compliance. Even minor variations in conjugation processes can affect product consistency, efficacy, and safety, making commercialization more challenging than for conventional biologics.
Safety concerns also remain a key restraint. Although ADCs are designed to selectively target cancer cells, treatment-related adverse events such as interstitial lung disease, hematologic toxicities, and off-target effects continue to be closely monitored by regulatory authorities and healthcare providers. Furthermore, healthcare providers often require additional monitoring protocols for patients receiving ADC therapies, which may affect treatment adoption in certain clinical settings. These factors collectively represent important barriers that manufacturers must address to support sustainable market expansion.
A major opportunity for the ADC market lies in expanding beyond established oncology indications into a broader range of solid tumors and earlier treatment settings. As scientific understanding of tumor biology continues to improve, researchers are identifying new molecular targets that can be addressed using ADC technology. This has resulted in a rapidly growing development pipeline focused on cancers with significant unmet clinical needs, including lung, gastrointestinal, genitourinary, and gynecologic malignancies.
Industry collaboration has become a critical catalyst for this expansion. In 2025, several pharmaceutical companies entered strategic partnerships to access innovative ADC platforms, novel payload technologies, and emerging cancer targets. For example, Roche's collaboration with Innovent Biologics to develop a DLL3-targeting ADC highlighted the industry's focus on expanding into difficult-to-treat tumor types. Additionally, ongoing clinical studies are evaluating ADCs in earlier lines of therapy, where they have the potential to become foundational treatment options rather than therapies reserved for advanced disease stages. The increasing number of licensing agreements, co-development partnerships, and platform technology collaborations demonstrates strong industry commitment to ADC innovation. These trends are expected to create substantial opportunities for product differentiation, pipeline expansion, and broader clinical adoption across the global oncology landscape.
Market Concentration & Characteristics
The Antibody Drug Conjugates market is marked by a high degree of innovation, with continuous advancements in the linker and payload technologies. Leading firms such as Seagen and Daiichi Sankyo are investing in cleavable and non-cleavable linkers to improve drug stability and precision. Innovation is also seen in payload diversity, expanding beyond MMAE and DM4 to novel cytotoxins. HER2 and CD30 remain prominent targets, but new antigen discoveries push the boundaries of antibody-drug conjugates' applicability. This technological evolution supports pipeline diversification and helps address unmet needs in various cancers.
The antibody drug conjugates market presents significant barriers to entry due to high R&D costs, complex manufacturing processes, and stringent clinical trial requirements. Emerging firms face challenges in developing stable linkers and effective targeting mechanisms. Established players like Roche and AstraZeneca benefit from intellectual property, production expertise, and access to global clinical networks. Regulatory hurdles also require substantial financial and technical resources, limiting new entrants. Moreover, the need for interdisciplinary integration of biologics, small molecules, and drug delivery platforms further restricts easy market access.
 To learn more about this report, Download Free Sample Report
Regulatory frameworks substantially impact the antibody drug conjugates market, particularly concerning safety, efficacy, and manufacturing standards. Agencies like the FDA and EMA require comprehensive data on linker stability, toxicity profiles, and off-target effects. While accelerated approval pathways exist for breakthrough therapies, post-marketing surveillance obligations remain stringent. Regulatory scrutiny favors firms with established compliance infrastructure, such as Pfizer and Gilead Sciences. Additionally, companion diagnostics and biomarker validation are often mandated, influencing development timelines and market readiness.
While antibody drug conjugates offer targeted efficacy, competition from immune checkpoint inhibitors, CAR-T cell therapies, and small molecule inhibitors poses substitution threats. For certain cancers like lymphoma or urothelial carcinoma, these alternatives may offer similar or superior outcomes with differing side effect profiles. However, antibody drug conjugates remain preferred when tumor-specific targeting is crucial, particularly with HER2 and CD30 expression. The presence of existing monoclonal antibodies without payloads also presents internal substitution risks. Despite this, the unique mechanism of antibody drug conjugates sustains their relevance, especially when other therapies fail, or resistance develops.
Geographical expansion in the antibody drug conjugates market is increasing, with key players entering Asia Pacific, Latin America, and Middle East regions to tap into unmet oncology needs. Companies like Astellas and AstraZeneca are forming regional collaborations and investing in localized trials. Japan, China, and India are gaining prominence as clinical trial hubs and commercial targets. Regulatory harmonization efforts are facilitating broader market access, although reimbursement policies vary. This global outreach supports market growth and offsets North America and Europe saturation.
Analyst Perspective
The ADC market is transitioning from a niche oncology segment to a core pillar of precision cancer treatment, driven by continuous innovation in linker chemistry, payload design, and target selection. The market is increasingly consolidating around companies with proven ADC development capabilities and established commercialization infrastructure. AstraZeneca and Daiichi Sankyo continue to set industry benchmarks through the clinical and commercial success of Enhertu, while Pfizer has strengthened its position through the acquisition of Seagen and its established ADC portfolio. Similarly, Roche, Gilead Sciences, and Takeda are leveraging broad oncology franchises to expand the clinical utility of ADCs across multiple tumor types.
Application Insights
Based on application, the Breast Cancer segment led the market with the largest revenue share of 40.8% in 2025. Growth is driven by a large addressable incidence and the expansion of HER2 testing from “positive” to include HER2-low and ultralow categories. In May 2019, ado-trastuzumab emtansine (Kadcyla; Genentech/Roche) received adjuvant approval, establishing an early market position. In July 2022, trastuzumab deruxtecan demonstrated clinical superiority in the DESTINY-Breast04 trial, leading to label expansions during 2024-2025 that extended access in HR-positive disease. Sacituzumab govitecan continues to contribute to demand in metastatic triple-negative breast cancer, including cases with minimal or absent HER2 expression. Favorable inclusion in clinical guidelines, expanded use of companion diagnostics, and established reimbursement mechanisms in the United States, EU5, and Japan are supporting broader adoption.
 To learn more about this report, Download Free Sample Report
Urothelial Carcinoma segment is projected to grow the fastest in the forecast period. Growth is supported by shifts in first-line treatment and the adoption of broader biomarker strategies. In December 2023, the U.S. FDA approved enfortumab vedotin plus pembrolizumab as a first-line regimen, following the pivotal EV-302/KEYNOTE-A39, which showed superior survival outcomes. Expansion of infusion infrastructure, payer alignment, and endorsement in clinical guidelines are improving treatment access. Real-world data are also mitigating prescriber concerns about adverse effects such as rash and neuropathy associated with Nectin-4-targeted MMAE therapies. Regional approvals, including disitamab deruxtecan and other HER2-directed antibody-drug conjugates in Asia and ongoing trials in maintenance, perioperative, and cisplatin-ineligible settings, continue to add momentum.
Product Insights
Based on product, the Enhertu (trastuzumab deruxtecan) segment led the market with the largest revenue share of 27.9% in 2025. Growth is supported by label expansion and increasing clinical adoption. In June 2024, the FDA granted tumor-agnostic approval for previously treated HER2-positive solid tumors. In January 2025, Enhertu received U.S. approval for unresectable or metastatic HR-positive, HER2-low/ultralow breast cancer, significantly expanding its eligible population. Core evidence includes the DESTINY-Breast04 trial, pan-tumor data, and ESMO 2025 results indicating performance advantages over Kadcyla in high-risk early disease and promising neoadjuvant activity.
The AstraZeneca-Daiichi Sankyo collaboration supports global commercialization, with planned ADC manufacturing expansion in Singapore to strengthen supply resilience. Adoption has accelerated as HER2 testing extends to low and ultralow categories, and standardized ILD monitoring has increased clinician confidence. Reimbursement approvals across the U.S., EU5, and APAC markets have improved access and expanded community oncology uptake. With several peri-operative and early-line studies maturing and diagnostic reach growing in emerging markets, Enhertu’s demand outlook remains strong, supported by expanded indications and sustained sponsor investment.
Payload Insights
Based on payload, the Auristatins (MMAE, MMAF) segment led the market with the largest revenue share of 35.9% in 2025, Growth reflects proven clinical performance, regulatory familiarity, and scalable production. Auristatins-monomethyl auristatin E (MMAE) and F (MMAF)-are synthetic analogs of dolastatin 10 that disrupt microtubule assembly and trigger apoptosis in tumor cells. These payloads support leading ADCs such as Adcetris (brentuximab vedotin; Seagen/Pfizer), Polivy (polatuzumab vedotin; Roche), and (enfortumab vedotin; Astellas/Pfizer).
Topoisomerase I Inhibitors (SN-38, DXd) segment is expected to grow the fastest, supported by strong efficacy in solid tumors and evolving safety data. These payloads inhibit topoisomerase I, leading to DNA damage and apoptosis with a differentiated toxicity profile versus microtubule disruptors. In July 2022, trastuzumab deruxtecan achieved landmark results in HER2-low disease, while in June 2024, the TROPION-Breast01 study (Lancet Oncology) validated datopotamab deruxtecan (Datroway; AstraZeneca/Daiichi Sankyo), later approved in 2025 for HR+/HER2- breast cancer. Controlled-release formulations, such as the DXd payload, have improved potency-risk balance and regulatory acceptance. Rapid adoption in breast, lung, gastric, and urothelial cancers, combined with active pipelines for SN-38-based ADCs, indicates a sustained shift toward DNA-targeting payloads. As production efficiency and monitoring frameworks advance, topoisomerase inhibitor-based ADCs are positioned to lead the next phase of oncology payload innovation.
Technology Insights
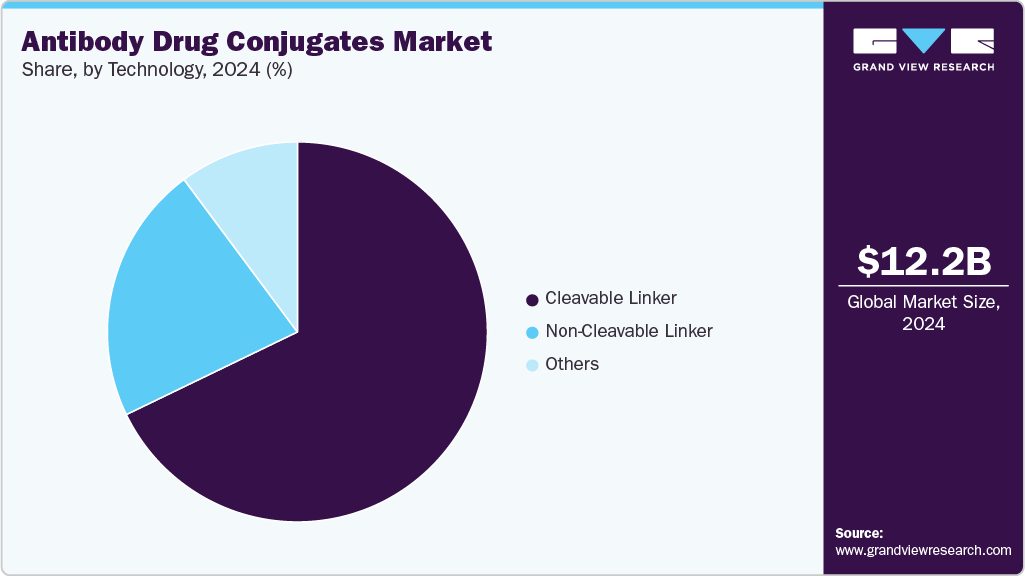
Based on technology, the Cleavable Linker segment led the market with the largest revenue share of 67.7% in 2025, driven by its established role in targeted therapy. Cleavable linkers are designed to release the drug payload selectively within the target cell, enhancing therapeutic efficacy. This segment's growth is supported by the increasing adoption of antibody-drug conjugates (ADCs) in various oncology indications. Additionally, regulatory approvals and the ongoing clinical development of new ADCs using cleavable linkers are contributing to market stability and expansion. Increasing investments in research and development by major pharmaceutical companies, coupled with growing collaborations, are anticipated to further drive the segment’s dominance in the coming years.
Non-Cleavable Linker segment is projected to experience the highest growth during the forecast period, primarily due to advancements in the design of more stable ADCs that are capable of delivering a potent and sustained drug release. Non-cleavable linkers provide greater stability during systemic circulation, which reduces premature release and improves therapeutic outcomes in certain cancer types. The segment is benefitting from increased focus on improving drug delivery systems to overcome challenges related to linker stability and premature payload release. Clinical trials demonstrating the effectiveness of ADCs using non-cleavable linkers, especially in solid tumors, are expected to further accelerate market growth.
Distribution Channel Insights
Based on distribution Channel, the Hospital Pharmacy segment led the market with the largest revenue share of 52.8% in 2025. Growth reflects the concentration of oncology care in hospital settings and the handling standards required for complex biologics. ADCs such as Enhertu (AstraZeneca/Daiichi Sankyo), Polivy (Roche), and Adcetris (Pfizer/Seagen) are administered through intravenous infusion, requiring specialized supervision from pharmacists, oncologists, and nursing staff. Hospital systems manage the storage and reconstitution processes under controlled conditions and operate within established reimbursement frameworks, including Medicare Part B in the U.S. and DRG-based systems across Europe.
The Specialty Pharmacy segment is expected to record the highest growth through 2033, supported by the decentralization of cancer care and the rise of value-based distribution models. Specialty pharmacies are increasingly integrated into oncology care pathways to facilitate patient access and manage high-cost biologics. Their expertise in cold-chain logistics, reimbursement coordination, and adverse event tracking positions them as key intermediaries between manufacturers and payers.
Regional Insights
North America Antibody Drug Conjugates Market Trends
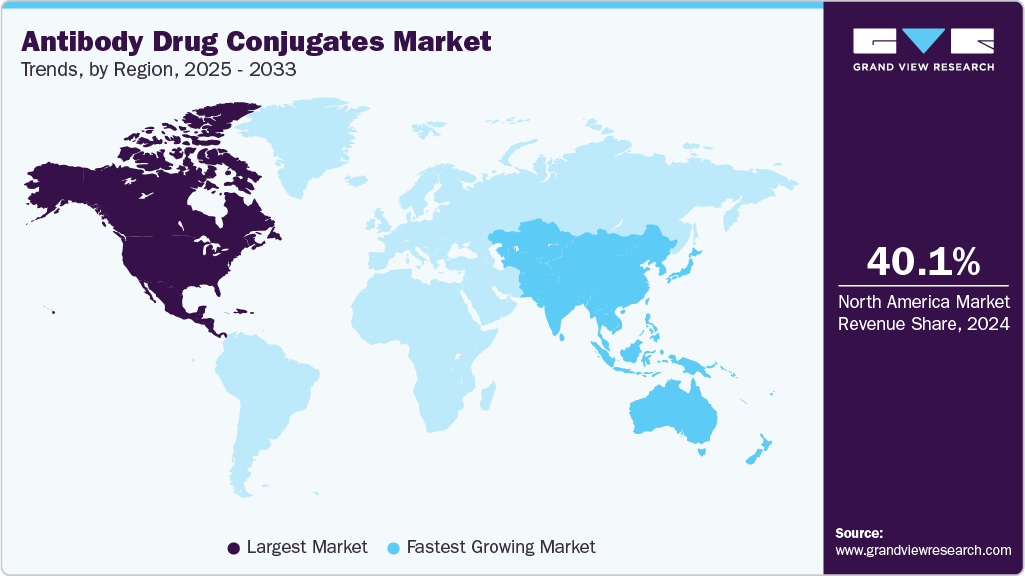
North America dominated the Antibody Drug Conjugate market with the largest revenue share of 39.80% in 2025, due to strong clinical research infrastructure and early adoption of advanced oncology therapies. High prevalence of cancer and increasing use of targeted therapies support sustained demand for antibody drug conjugates. Major pharmaceutical companies such as Seagen, Pfizer, and Gilead Sciences maintain extensive development and commercialization capabilities across the region. Strategic partnerships and continuous innovation in payload and linker technologies enhance regional competitiveness. The presence of experienced regulatory agencies ensures smooth market entry for novel therapeutics. High healthcare spending further drives accessibility and utilization of antibody drug conjugates across various cancer indications.
 To learn more about this report, Download Free Sample Report
U.S. Antibody Drug Conjugates Market Trends
The Antibody Drug Conjugate market in the U.S. held the largest share in the North America region in 2025. High incidence of breast and blood cancers creates steady demand for HER2- and CD-targeted antibody drug conjugates. Companies such as Roche, AstraZeneca, and Daiichi Sankyo have expanded their commercial footprint through key product launches and label expansions. Favorable reimbursement policies for oncology treatments increase patient access to antibody drug conjugates therapies. The market benefits from continuous R&D investment and rapid clinical trial execution. Strong academic-industry collaboration further supports innovation and adoption of next-generation antibody drug conjugates.
Europe Antibody Drug Conjugates Market Trends
Europe represents a significant region in the global antibody drug conjugates market, supported by expanding access to precision oncology therapies. Rising cancer burden across countries such as Germany, France, and Italy boosts clinical demand for targeted treatments. Pharmaceutical companies are increasing their focus on Europe through regulatory approvals and strategic product launches. Widespread use of Kadcyla, Polivy, and Adcetris across major indications strengthens regional adoption. Oncology research centers and academic hospitals support ongoing development of novel antibody drug conjugates. Growing awareness of treatment safety and efficacy is influencing clinical decision-making in favor of antibody drug conjugates.
UK Antibody Drug Conjugates Market Trends
The UK is emerging as a key contributor to the European antibody drug conjugates market, driven by strong cancer research programs and early access schemes. High adoption of antibody drug conjugates in breast and hematologic cancers reflects growing clinical confidence in targeted approaches. Ongoing collaborations between academic institutions and global pharmaceutical firms support innovation in this space. Enhertu and Trodelvy have gained traction in UK oncology clinics through expanding indication approvals. Market expansion is further supported by widespread diagnostic capabilities that aid in biomarker-based patient selection. The UK’s healthcare infrastructure allows for efficient integration of new oncology drugs into treatment pathways.
Germany Antibody Drug Conjugates Market Trends
Germany holds a strong position in the European antibody drug conjugates market due to its advanced pharmaceutical industry and oncology expertise. High patient volumes and demand for personalized therapies contribute to increased antibody drug conjugates utilization. Hospitals and specialty clinics are equipped to administer antibody drug conjugates for both solid and hematologic tumors. Companies such as Roche and Takeda have established deep market penetration through locally approved antibody drug conjugates. The presence of efficient clinical trial networks aids in early product testing and introduction. Germany’s emphasis on treatment precision supports the sustained growth of the antibody drug conjugates segment.
France Antibody Drug Conjugates Market Trends
France holds a strong position in the European antibody drug conjugates market due to high healthcare standards and advanced cancer treatment practices. antibody drug conjugates such as Kadcyla, Enhertu, and Polivy are widely used across cancer centers for indications including breast and blood cancers. The country benefits from a well-organized clinical trial ecosystem that supports innovation and faster product introduction. Leading pharmaceutical companies have a strong presence, ensuring consistent supply and training for antibody drug conjugates use. Adoption is also supported by widespread access to molecular diagnostics, enabling more targeted treatment approaches. France’s emphasis on treatment precision and patient outcomes continues to reinforce market expansion.
Asia-Pacific Antibody Drug Conjugates Market Trends
Asia Pacific antibody drug conjugates market is expected to register the significant CAGR of 11.77% over the forecast period, due to rising cancer incidence and increased adoption of targeted therapies. Expanding healthcare infrastructure and oncology diagnostics are key enablers for market entry and growth. Companies are pursuing aggressive expansion strategies through pricing adjustments, local partnerships, and regulatory approvals. Launches of products such as Kadcyla and Enhertu in Asian countries have accelerated market uptake. Demand is rising for antibody drug conjugates in breast and blood cancers, supported by an evolving treatment landscape. Continued investment in clinical trials and R&D activities is expected to further drive regional expansion.
Japan Antibody Drug Conjugates Market Trends
Japan’s antibody drug conjugates market is gaining traction through strong clinical research and early integration of innovative therapies. High awareness of precision oncology drives adoption of HER2- and CD-targeted antibody drug conjugates across major cancer centers. Collaborations between Japanese pharmaceutical firms and global companies facilitate timely market introductions. Enhertu, co-developed by Daiichi Sankyo, has seen rapid uptake following its domestic approval. Availability of specialized diagnostic tools aids in identifying suitable patients for antibody drug conjugates therapies. Japan’s well-established pharmaceutical sector continues to support both domestic and imported antibody drug conjugates products.
China Antibody Drug Conjugates Market Trends
China is emerging as a major market for antibody drug conjugates due to rapid healthcare modernization and growing cancer treatment demand. The approval of Kadcyla and other antibody drug conjugates has contributed to wider clinical availability and use. Roche’s strategic pricing adjustments and commercial focus have strengthened its position in the Chinese oncology space. Increasing patient access to HER2-targeted therapies is shaping the growth trajectory of the antibody drug conjugates market. Domestic firms are also investing in antibody drug conjugates development, fostering local innovation and competition. China’s rising healthcare consumption and expanding diagnostic capabilities are supporting sustained demand for antibody drug conjugates.
Latin America Antibody Drug Conjugates Market Trends
The antibody drug conjugates market in Latin America is growing steadily, driven by the rising cancer burden and increasing focus on precision oncology. Breast and hematologic cancers are contributing significantly to the regional demand for targeted treatments. Pharmaceutical companies are expanding their operations through collaborations with local healthcare providers and distributors. Access to approved antibody drug conjugates is gradually improving as countries enhance regulatory frameworks and oncology capabilities. Awareness of the clinical benefits of antibody drug conjugates is encouraging oncologists to shift from traditional chemotherapy to targeted options. Ongoing clinical trials and product registrations are expected to support future market growth across Latin America.
Brazil Antibody Drug Conjugates Market Trends
Brazil is the leading market for antibody drug conjugates in Latin America, supported by its large population and increasing incidence of cancer. The country is seeing rising adoption of antibody drug conjugates such as Kadcyla and Adcetris for treating HER2-positive breast cancer and lymphomas. Private and public hospitals are enhancing oncology services, which include targeted therapies as part of standard care. Pharmaceutical firms are actively working to expand product availability through pricing strategies and regulatory approvals. Clinical infrastructure is improving, enabling better patient access to biomarker testing and precision treatments. Brazil’s growing oncology focus is expected to drive continued uptake of antibody drug conjugates.
Middle East & Africa Antibody Drug Conjugates Market Trends
The MEA region is witnessing gradual growth in the antibody drug conjugates market due to increasing cancer burden and improved access to advanced therapies. Major hospitals and specialty centers are expanding oncology services that include antibody drug conjugates administration. International pharmaceutical companies are working with regional stakeholders to introduce approved antibody drug conjugates for breast and blood cancers. Enhancements in diagnostic capabilities are enabling biomarker-driven treatment strategies. Rising awareness among healthcare providers is contributing to a shift toward precision oncology. Although market penetration remains moderate, the outlook for antibody drug conjugates adoption is positive across the region.
Saudi Arabia Antibody Drug Conjugates Market Trends
Saudi Arabia is expanding its presence in the antibody drug conjugates market through increasing adoption of modern oncology therapies. Key hospitals are incorporating antibody drug conjugates into standard cancer treatment regimens for HER2-positive and hematologic malignancies. The demand for innovative therapies is rising in response to growing cancer prevalence and changing treatment protocols. International pharmaceutical firms are establishing collaborations to support the introduction of antibody drug conjugates. Diagnostic improvements are enabling more effective targeting of therapies based on tumor markers. This focus on precision treatment is expected to strengthen the market’s growth in the country.
Key Companies & Market Share Insights
Seagen, Inc. leads the antibody drug conjugates market with strong clinical success and products like Adcetris. Takeda, AstraZeneca, and Roche maintain solid positions through strategic collaborations and targeted oncology portfolios. Pfizer, Gilead, and Daiichi Sankyo continue to expand access with effective distribution and promising label expansions. ADC Therapeutics is emerging with innovative technologies and niche focus. Competitive intensity is rising as companies target broader cancer types and improve therapeutic precision. The market is set for sustained growth driven by innovation and clinical adoption.
Key Antibody Drug Conjugates Companies:
The following key companies have been profiled for this study on the antibody drug conjugates market.
- Seagen, Inc.
- Takeda Pharmaceutical Company Ltd.
- AstraZeneca
- F. Hoffmann-La Roche Ltd.
- Pfizer, Inc.
- Gilead Sciences, Inc.
- Daiichi Sankyo Company Ltd.
- antibody drug conjugates Therapeutics SA
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Large Integrated Pharmaceutical Companies (AstraZeneca, F. Hoffmann-La Roche Ltd., Pfizer, Inc., Gilead Sciences, Inc., Daiichi Sankyo Company Ltd., Takeda Pharmaceutical Company Ltd.)
Expand ADC portfolios through indication expansions, lifecycle management, and global commercialization strategies. Invest in next-generation payloads, linker technologies, and combination regimens with immunotherapies and targeted therapies. Strengthen market presence through strategic collaborations, acquisitions, and broad oncology pipeline development.
Strong global commercial infrastructure, established relationships with oncologists and healthcare systems, extensive clinical development expertise, and robust manufacturing capabilities. Ability to leverage diversified oncology portfolios and significant financial resources to accelerate product development and market penetration.
High operational and manufacturing costs associated with ADC production. Greater exposure to pricing pressures, reimbursement scrutiny, and regulatory requirements across multiple geographies. Larger organizational structures may result in slower decision-making and reduced flexibility in pursuing niche opportunities.
ADC-Focused Specialists (Seagen, Inc.; ADC Therapeutics SA)
Focus on developing and commercializing ADC-centric oncology portfolios. Prioritize innovation in target selection, payload technologies, and clinical differentiation. Pursue licensing agreements, strategic partnerships, and co-commercialization arrangements to expand geographic reach and maximize asset value.
Deep scientific expertise in ADC development, strong intellectual property portfolios, specialized knowledge of linker-payload technologies, and focused oncology R&D strategies. Greater organizational agility enables rapid adaptation to emerging scientific opportunities and market trends.
More limited financial resources and commercial infrastructure compared to multinational pharmaceutical companies. Greater dependence on a concentrated product portfolio, increasing exposure to clinical, regulatory, and competitive risks. Reliance on partnerships for global commercialization and manufacturing scale-up may constrain long-term growth.
Recent Developments
-
In January 2024, Celltrion, Inc. and WuXi XDC entered into a Memorandum of Understanding (MoU) to collaborate on comprehensive antibody-drug conjugate (ADC) services, covering both development and manufacturing activities.
-
In January 2024, Johnson & Johnson Services, Inc. completed the acquisition of Ambrx Biopharma, Inc., a company known for its proprietary antibody-drug conjugate (ADC) technology used in creating advanced cancer therapies. This move is intended to strengthen J&J’s oncology portfolio, particularly in prostate cancer, by leveraging Ambrx’s innovative ADC platform.
-
In January 2024, MediLink Therapeutics entered into a licensing and collaboration agreement with F. Hoffmann-La Roche Ltd. to advance the development of YL211, a next-generation antibody-drug conjugate (ADC).
Antibody Drug Conjugates Market Report Scope
Report Attribute
Details
Market size in 2025
USD 14.5 billion
Estimated market size in 2026
USD 16.7 billion
Projected market size by 2033
USD 32.1 billion
Growth rate
CAGR of 11.5% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Application, technology, payload, product, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; Russia; Iceland; Finland; China; Japan; India; South Korea; Australia; Thailand; Singapore; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait; Israel
Key companies profiled
Seagen, Inc.; Takeda Pharmaceutical Company Ltd.; AstraZeneca; F. Hoffmann-La Roche Ltd.; Pfizer, Inc.; Gilead Sciences, Inc.; Daiichi Sankyo Company Ltd.; antibody drug conjugates Therapeutics SA.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Antibody Drug Conjugates Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global antibody drug conjugates market report based on application, product, payload, technology, distribution channel, and region:
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Breast Cancer
-
Blood Cancer
-
Lymphoma
-
Leukemia
-
-
Urothelial Carcinoma
-
Ovarian Cancer
-
Others
-
-
Product Outlook (Revenue, USD Million, 2021 - 2033)
-
Kadcyla (ado-trastuzumab emtansine)
-
Enhertu (trastuzumab deruxtecan)
-
Trodelvy (sacituzumab govitecan)
-
Adcetris (brentuximab vedotin)
-
Polivy (polatuzumab vedotin)
-
Others (Padcev, Tivdak, Elahere, Zynlonta, Mylotarg, Besponsa)
-
-
Payload Outlook (Revenue, USD Million, 2021 - 2033)
-
Auristatins (MMAE, MMAF)
-
Maytansinoids (DM1, DM4)
-
Calicheamicin Derivatives
-
Topoisomerase I Inhibitors (SN-38, DXd)
-
Pyrrolobenzodiazepine (PBD) Dimers
-
Others
-
-
TechnologyOutlook (Revenue, USD Million, 2021 - 2033)
-
Cleavable Linker
-
Non-Cleavable Linker
-
Others
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacy
-
Specialty Pharmacy
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
Segment Definition
Segment - Type
Revenue capture definition
Breast Cancer
Revenue generated from ADCs prescribed for the treatment of breast cancer, including HER2-positive, HER2-low, HER2-ultralow, hormone receptor-positive/HER2-negative, triple-negative breast cancer (TNBC), and other breast cancer subtypes. All sales associated with breast cancer indications are included exclusively within this segment, irrespective of the molecular target or line of therapy.
Blood Cancer
Revenue generated from ADCs used in hematological malignancies, including Hodgkin lymphoma, non-Hodgkin lymphoma, diffuse large B-cell lymphoma (DLBCL), multiple myeloma, acute lymphoblastic leukemia (ALL), acute myeloid leukemia (AML), and other blood-related cancers. Revenue from these indications is classified solely within this segment and excluded from all solid tumor categories.
Urothelial Carcinoma
Revenue generated from ADCs approved or prescribed for urothelial carcinoma, including bladder cancer and cancers arising from the renal pelvis, ureter, and urethra. All revenue associated with urothelial malignancies is assigned exclusively to this segment regardless of biomarker status or treatment setting.
Ovarian Cancer
Revenue generated from ADCs used for the treatment of ovarian cancer, including epithelial ovarian cancer, fallopian tube cancer, and primary peritoneal cancer where they are clinically managed within ovarian cancer treatment pathways. Revenue from these indications is reported exclusively within this segment.
Others
Revenue generated from ADCs used in all remaining cancer indications not captured under Breast Cancer, Blood Cancer, Urothelial Carcinoma, or Ovarian Cancer. This includes, but is not limited to, lung cancer, gastric cancer, colorectal cancer, cervical cancer, endometrial cancer, pancreatic cancer, prostate cancer, head and neck cancer, and other emerging solid tumor indications. Revenue is allocated here only when it does not belong to any of the predefined segments above.
Segment - Technology
Revenue capture definition
Cleavable Linker
Revenue generated from antibody-drug conjugates that utilize cleavable linker technologies designed to release the cytotoxic payload upon exposure to specific intracellular conditions such as enzymatic activity, acidic pH, or reducing environments within tumor cells. This segment includes ADCs employing peptide-based, hydrazone, disulfide, and other cleavable linker mechanisms. Revenue is attributed to this segment when the ADC's primary commercialized design incorporates a cleavable linker.
Non-Cleavable Linker
Revenue generated from antibody-drug conjugates that utilize non-cleavable linker technologies, where payload release occurs only after complete intracellular degradation of the antibody component. These linkers are designed to remain stable throughout systemic circulation and rely on lysosomal processing within target cells for payload activation. Revenue from ADCs employing non-cleavable linker platforms is exclusively assigned to this segment.
Others
Revenue generated from ADCs utilizing linker technologies that do not fall within conventional cleavable or non-cleavable classifications, including emerging linker architectures, novel proprietary conjugation approaches, conditionally activated linker systems, and next-generation platform technologies under commercialization. This segment also captures future linker innovations introduced during the forecast period that are not adequately represented by the two primary categories.
Segment - Payload
Revenue capture definition
Auristatins (MMAE, MMAF)
Revenue generated from ADCs utilizing auristatin-based payloads, including monomethyl auristatin E (MMAE) and monomethyl auristatin F (MMAF). These payloads function as microtubule inhibitors that disrupt cell division by preventing tubulin polymerization, ultimately inducing cancer cell death. Revenue from all ADCs employing MMAE, MMAF, or related auristatin derivatives is exclusively assigned to this segment.
Maytansinoids (DM1, DM4)
Revenue generated from ADCs incorporating maytansinoid-based payloads, including DM1 and DM4 derivatives. These highly potent microtubule-disrupting agents inhibit mitotic spindle formation and trigger apoptosis in targeted cancer cells. All ADC revenue associated with maytansinoid payload platforms is classified within this segment.
Calicheamicin Derivatives
Revenue generated from ADCs utilizing calicheamicin-based payloads. Calicheamicin derivatives are potent DNA-cleaving agents that induce double-stranded DNA breaks, resulting in irreversible cellular damage and apoptosis. Revenue from ADCs employing calicheamicin or related enediyne antibiotic payloads is attributed exclusively to this category.
Topoisomerase I Inhibitors (SN-38, DXd)
Revenue generated from ADCs incorporating topoisomerase I inhibitor payloads, including SN-38, DXd, and related derivatives. These payloads inhibit DNA replication and transcription by preventing the religation of DNA strands during cell division, leading to tumor cell death. Revenue from all ADCs utilizing topoisomerase I inhibitor payload technologies is assigned solely to this segment.
Pyrrolobenzodiazepine (PBD) Dimers
Revenue generated from ADCs employing pyrrolobenzodiazepine dimer payloads. PBD dimers function through sequence-selective DNA crosslinking, causing highly potent and durable cytotoxic effects even at low concentrations. Revenue associated with ADCs utilizing PBD-based payloads is classified exclusively within this segment.
Others
Revenue generated from ADCs utilizing payload classes not included in the above categories. This includes, but is not limited to, camptothecin derivatives outside conventional classifications, duocarmycins, amanitin-based payloads, exatecan derivatives not separately classified, immune-stimulatory payloads, protein degraders, radionuclides, and other emerging payload technologies. Revenue is allocated to this segment only when the payload does not fall within the predefined categories above.
Segment - Product
Revenue capture definition
Kadcyla (ado-trastuzumab emtansine)
Revenue generated from Kadcyla, a HER2-targeted ADC comprising trastuzumab linked to the maytansinoid payload DM1. This segment includes all revenue derived from Kadcyla across approved breast cancer indications and any future label expansions. Revenue attributable to Kadcyla is reported exclusively within this segment.
Enhertu (trastuzumab deruxtecan)
Revenue generated from Enhertu, a HER2-directed ADC consisting of trastuzumab linked to a DXd-based topoisomerase I inhibitor payload. This segment includes revenue from all approved indications, including breast cancer, gastric cancer, lung cancer, and other future indications. All Enhertu-related sales are classified solely within this segment.
Trodelvy (sacituzumab govitecan)
Revenue generated from Trodelvy, a TROP2-targeted ADC utilizing the SN-38 topoisomerase I inhibitor payload. This segment encompasses revenue from all approved oncology indications and future label expansions. Revenue is attributed exclusively to Trodelvy irrespective of treatment setting or cancer type.
Adcetris (brentuximab vedotin)
Revenue generated from Adcetris, a CD30-targeted ADC containing the MMAE payload. This segment includes all sales associated with approved hematologic malignancies and any future indications. Revenue from Adcetris is reported solely within this category.
Polivy (polatuzumab vedotin)
Revenue generated from Polivy, a CD79b-targeted ADC utilizing the MMAE payload for the treatment of specific B-cell malignancies. All commercial sales associated with Polivy are classified exclusively within this segment regardless of geographic market or treatment line.
Others
Revenue generated from all commercially marketed ADCs not separately identified above. This includes products such as Padcev (enfortumab vedotin), Tivdak (tisotumab vedotin), Elahere (mirvetuximab soravtansine), Zynlonta (loncastuximab tesirine), Mylotarg (gemtuzumab ozogamicin), Besponsa (inotuzumab ozogamicin), Datroway (datopotamab deruxtecan), and future commercial ADC launches. Revenue is assigned to this segment only when it does not belong to the individually reported product categories.
Segment – Distribution Channel
Revenue capture definition
Hospital Pharmacy
Revenue generated from antibody-drug conjugates dispensed, administered, and billed through hospital-based pharmacies and inpatient or outpatient hospital oncology departments. This segment includes ADCs procured and managed by hospitals for use in infusion centers, oncology wards, day-care chemotherapy units, and other hospital-affiliated treatment settings. Revenue is attributed to this segment when the product is distributed through a hospital pharmacy channel.
Specialty Pharmacy
Revenue generated from antibody-drug conjugates distributed through specialty pharmacies that manage high-cost, complex, and specialty oncology therapies. This segment includes products dispensed through accredited specialty pharmacy networks that provide patient support services, reimbursement assistance, therapy management, and coordinated delivery to oncology clinics or eligible patients. Revenue is assigned to this segment when the ADC is supplied through a specialty pharmacy distribution model.
Others
Revenue generated from all remaining distribution channels not included under Hospital Pharmacy or Specialty Pharmacy. This includes physician office dispensing, independent oncology clinics, cancer treatment centers, government procurement programs, academic medical institutions, and other alternative distribution pathways. Revenue is allocated to this segment only when it is not attributable to the predefined channels above.
Estimation Model
The study incorporated a combination of primary and secondary research methodologies to evaluate the global antibody-drug conjugates (ADC) market. Secondary research involved the review of company annual reports, investor presentations, regulatory filings, clinical trial databases, scientific publications, industry journals, and publicly available information from pharmaceutical companies and healthcare agencies. Primary research included interviews and discussions with industry stakeholders, including pharmaceutical manufacturers, oncology experts, researchers, business development executives, and key opinion leaders, to validate market trends, technology adoption, competitive developments, and future growth opportunities.
Market estimates were developed using a combination of top-down and bottom-up approaches. Revenue analysis was conducted at the product, application, payload, technology, distribution channel, and regional levels. The competitive landscape assessment evaluated product portfolios, pipeline assets, strategic collaborations, acquisitions, regulatory approvals, and innovation initiatives. All findings were triangulated through multiple data sources and validated against real-world industry developments to ensure accuracy, consistency, and reliability of the market forecasts and strategic insights.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
ADC Competitive Landscape & Pipeline Assessment
Conducted a targeted assessment of the global ADC landscape, evaluating approved products, late-stage pipeline assets, target antigens, payload technologies, linker platforms, clinical development progress, and competitive positioning. The study analyzed key players including AstraZeneca, Daiichi Sankyo, Pfizer/Seagen, Roche, Gilead Sciences, Takeda, and ADC Therapeutics, along with emerging therapeutic targets and innovation trends across solid tumors and hematologic malignancies.
Helped the client identify high-potential therapeutic targets, evaluate competitive threats, benchmark pipeline differentiation, and prioritize licensing, acquisition, and partnership opportunities within the rapidly evolving ADC market.
ADC Technology & Platform Benchmarking Study
Delivered a comprehensive benchmarking analysis of ADC technologies, focusing on linker platforms, payload classes, conjugation approaches, manufacturing capabilities, and clinical performance. The assessment compared commercially validated technologies with next-generation ADC innovations, evaluating scalability, safety profiles, intellectual property positioning, and platform differentiation across leading ADC developers.
Enabled the client to assess technology competitiveness, identify platform gaps, benchmark innovation strategies, and prioritize investments in next-generation ADC development programs and proprietary platform technologies.
Frequently Asked Questions About This Report
North America dominated the global antibody drug conjugates market with 39.8% share in 2025.
Cleavable linker dominated the global antibody drug conjugates market with a share of 67.7% in 2025.
Enhertu (trastuzumab deruxtecan) dominated the global antibody drug conjugates market with a share of 27.9% in 2025.
The global antibody drug conjugates market is anticipated to grow at a CAGR of 11.5% from 2026 to 2033, to reach USD 32.1 billion in 2033.
The global antibody drug conjugates' application segment was dominated by breast cancer with a share of 40.8% in 2025
Some key players operating in the global antibody drug conjugates market are Seagen, Inc.; Takeda Pharmaceutical Company Ltd.; AstraZeneca; F. Hoffmann-La Roche Ltd.; Pfizer, Inc.; Gilead Sciences, Inc.; Daiichi Sankyo Company Ltd.; antibody drug conjugates Therapeutics SA.
The antibody-drug conjugates (ADC) market is experiencing significant growth, driven by advancements in targeted therapies, increasing clinical trials, and strategic investments by pharmaceutical companies.
The global antibody drug conjugates market was estimated at USD 14.5 billion in 2025 and is expected to reach USD 16.7 billion in 2026.
Hospital pharmacy dominated the global antibody drug conjugates market with a share of 52.8% in 2025.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


