
- Home
- »
- Paints, Coatings & Printing Inks
- »
-
Automotive Coatings Market Size, Share Report, 2026-2033GVR Report cover

Automotive Coatings Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Primer, E-coat), By Technology (Powder Coating, Radiation UV-Cured Coatings), By Application (Metal, Plastic), By End Use (Light Vehicle OEM, Commercial OEM), By Region, And Segment Forecasts
Market Size, 2025
$25.7BMarket Estimate, 2026
$27.0BMarket Forecast, 2033
$38.3BCAGR, 2026–2033
5.1%Automotive Coatings Market Summary
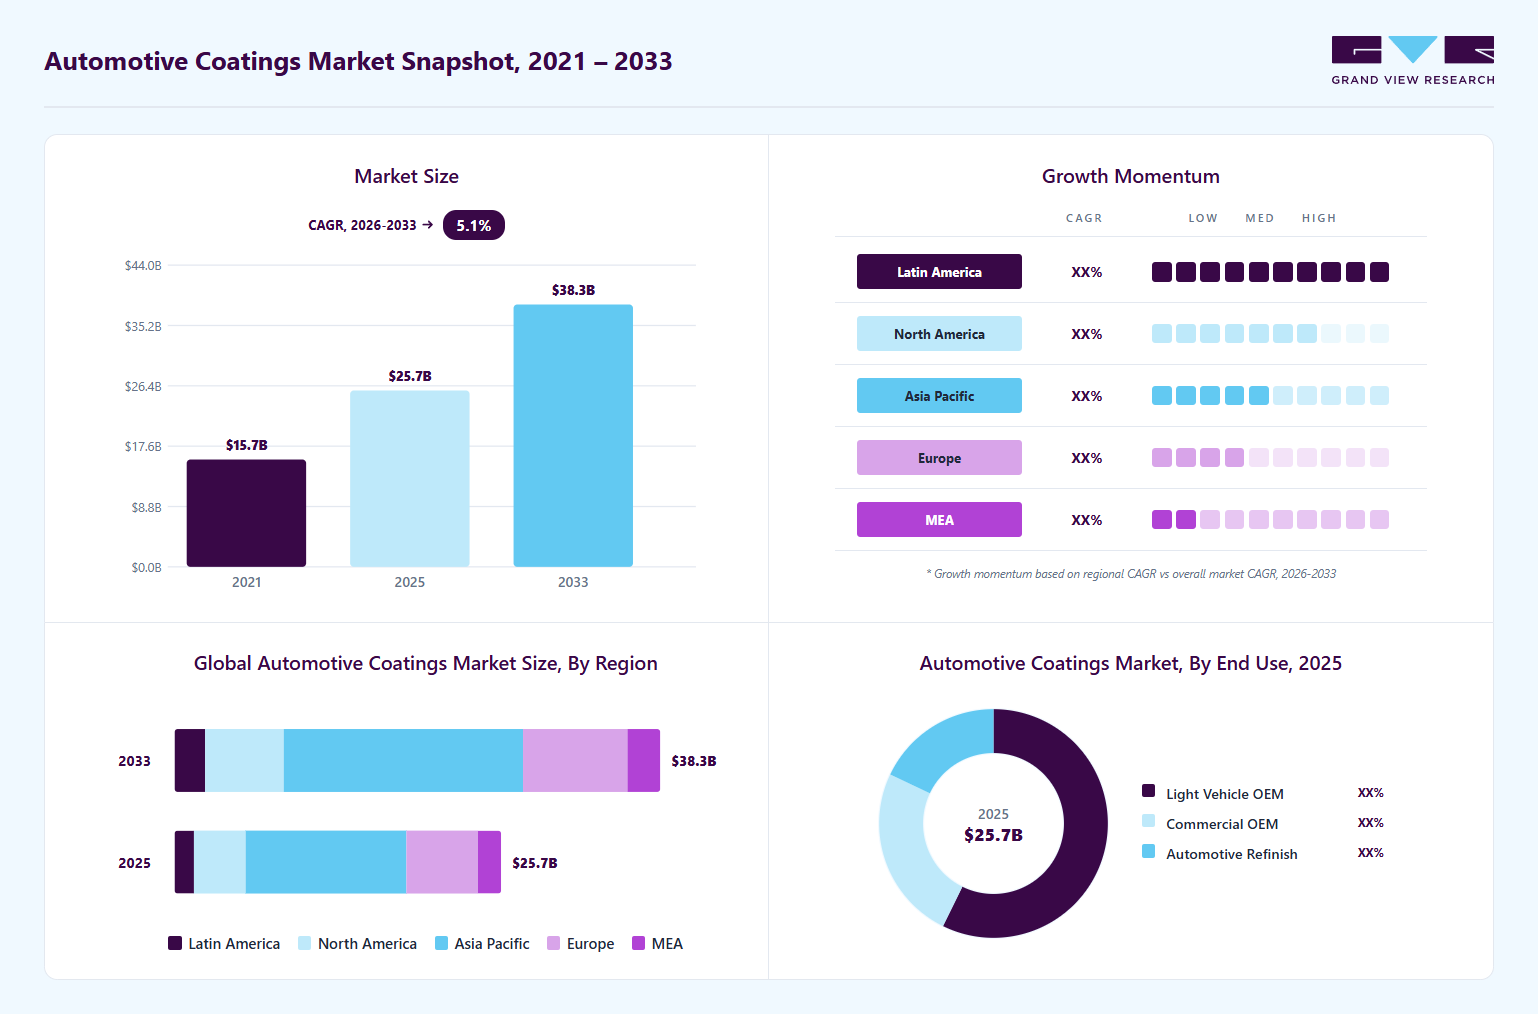
The global automotive coatings market size was valued at USD 25.7 billion in 2025 and is projected to grow from USD 27.0 billion in 2026 to USD 38.3 billion by 2033, at a CAGR of 5.1% from 2026 to 2033. The Asia Pacific dominated the market with the largest revenue share of 49.2% in 2025. This growth is driven by rising global vehicle production, increased demand for enhanced automotive aesthetics, and the growing adoption of electric vehicles.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The basecoat segment dominated the market in 2025, accounting for a revenue share of 40.1%.
- By application: The metal segment held a dominant position in the market with a revenue share of 70.0% in 2025.
- By end use: The light vehicle OEM segment held the largest share of 57.3% in 2025.
- By technology: Solventborne coatings dominated the market, accounting for 63.5% of revenue in 2025.
Regional Highlights
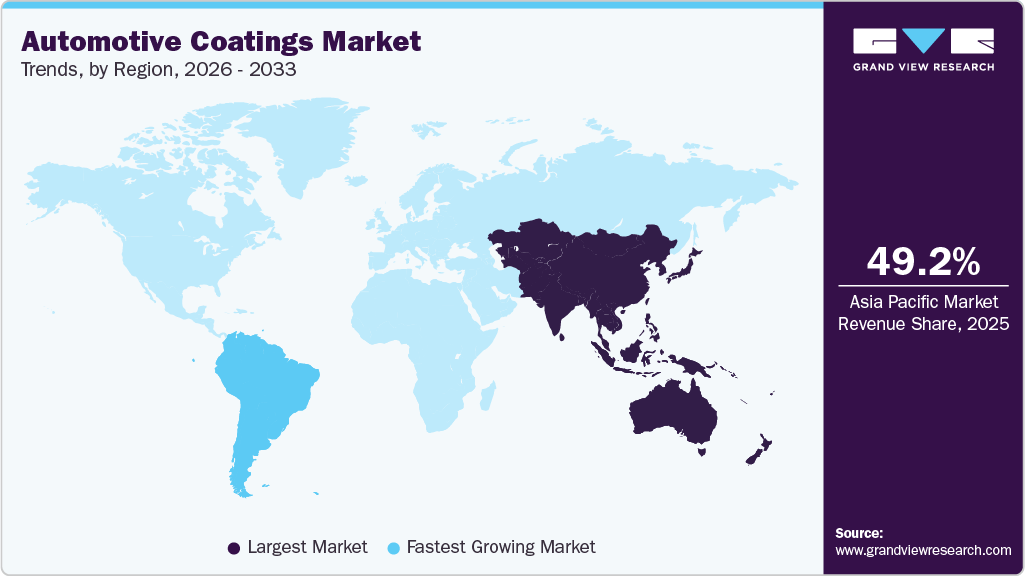
- Largest regional market: Asia Pacific (49.2% revenue share, 2025)
- Fastest-growing regional market: Latin America (highest CAGR, 2026-2033)
- By country: The automotive coatings market in China remains a dominant contributor.
Market Size & Forecast
- Market size in 2025: USD 25.7 billion
- Estimated market size in 2026: USD 27.0 billion
- Projected market size by 2033: USD 38.3 billion
- CAGR (2026-2033): 5.1%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The growth is primarily driven by rising global automobile production, increasing consumer demand for enhanced aesthetics, and the rapid expansion of the electric vehicle industry. Manufacturers are increasingly adopting advanced coating solutions that provide superior corrosion resistance, UV protection, scratch resistance, and long-term durability, thereby improving lifespan and brand value. In addition, stringent environmental regulations regarding volatile organic compound (VOC) emissions are accelerating the transition toward sustainable technologies such as waterborne and powder coatings. Growing investments in lightweight manufacturing and the use of advanced materials, including plastics and composites, are further supporting demand for specialized coating systems. The expansion of manufacturing facilities across emerging economies, coupled with rising disposable incomes and urbanization, continues to drive global market growth.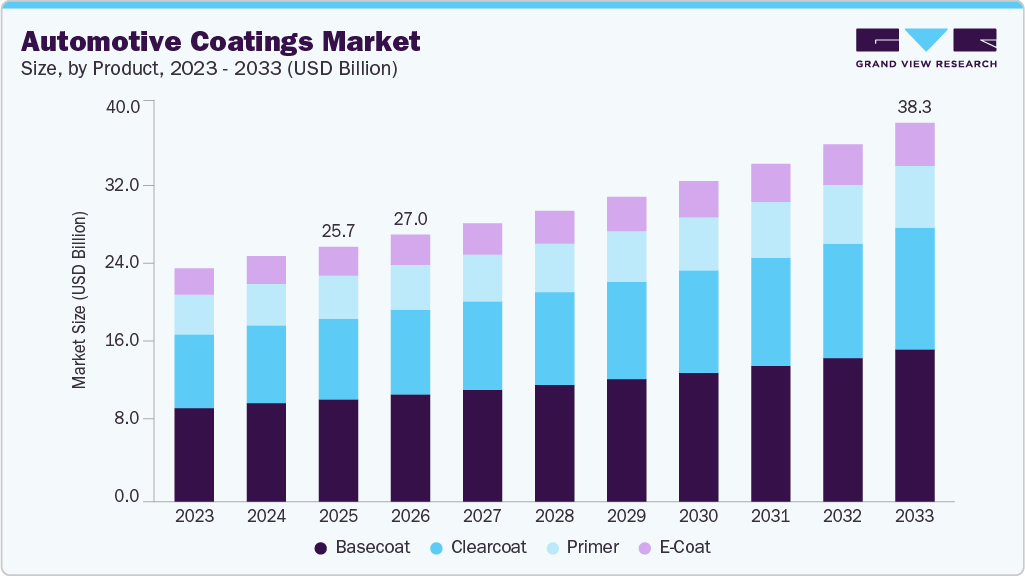 To learn more about this report, Download Free Sample Report
The industry presents opportunities as the adoption of environmentally sustainable, high-performance coating technologies increases. The rising adoption of electric vehicles is driving demand for innovative coatings that provide thermal management, insulation, and lightweight performance. Technological advancements in UV-cured and smart coatings, including self-healing and anti-microbial coatings, are expected to open new avenues for product differentiation and premium applications. Emerging economies in the Asia Pacific, Latin America, and the Middle East are also creating substantial opportunities for market players as production capacity expands, and infrastructure development supports long-term industrial growth.
Market Dynamics
Manufacturers are continually investing in advanced coating solutions to enhance the durability, corrosion resistance, weather protection, and visual appeal of automobiles. Rising consumer preference for premium finishes and long-lasting exterior performance is further supporting demand for high-quality coatings. The growing adoption of electric vehicles is accelerating the need for specialized coatings compatible with lightweight materials and advanced components.
Compliance with evolving environmental standards increases production and formulation costs for coating manufacturers, particularly for solvent-borne technologies. The transition toward sustainable alternatives often requires investments in research, development, and manufacturing upgrades. Fluctuations in raw material prices, especially petrochemical-based ingredients, create cost pressures and affect overall profit margins across the industry.
Market Concentration & Characteristics
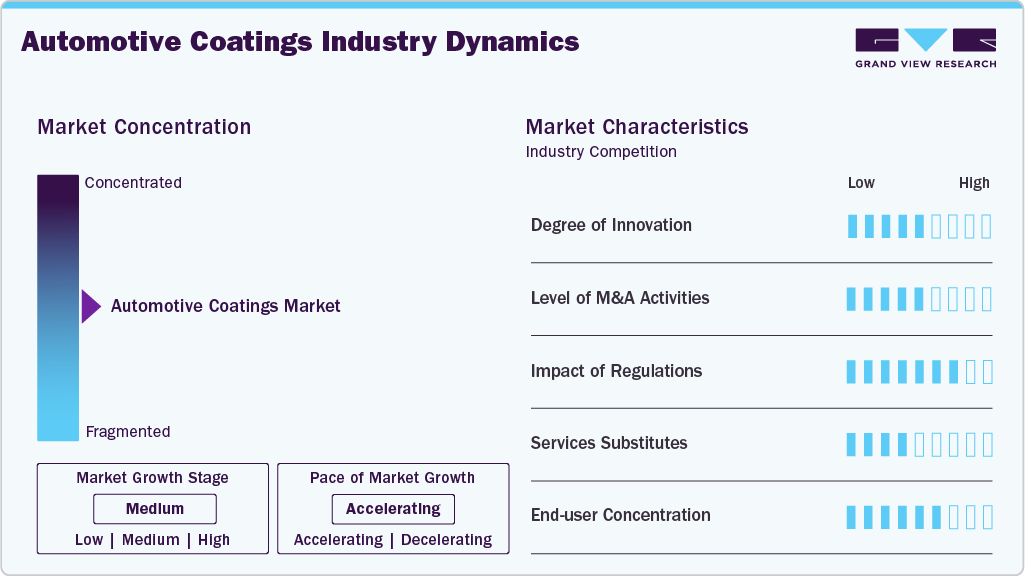
The market is highly competitive, with global and regional manufacturers focusing on innovation, product performance, and sustainable coating technologies to strengthen their market positions. Major companies are actively investing in research and development to introduce advanced coatings that offer improved durability, corrosion resistance, enhanced aesthetics, and lower environmental impact. The growing shift toward waterborne, powder, and UV-cured coatings has increased competition in developing eco-friendly solutions that comply with stringent environmental regulations.
 To learn more about this report, Download Free Sample Report
The players are expanding their manufacturing capacities and distribution networks in emerging production hubs to improve regional penetration and supply chain efficiency. Competitive rivalry is further intensified through mergers, acquisitions, and technology partnerships aimed at strengthening product portfolios and expanding global presence. Regional companies, particularly in the Asia Pacific, are gaining momentum by offering cost-competitive products and leveraging strong domestic demand.
Product Insights
Basecoat held the largest share of 40.1% in 2025 due to its critical role in providing color, visual appeal, and surface aesthetics. Increasing consumer demand for premium finishes, metallic textures, and customized automobile appearances has significantly supported segment growth. Manufacturers are increasingly utilizing advanced basecoat formulations that offer improved color consistency, durability, and resistance to environmental exposure.
The clearcoat segment is expected to grow the fastest, with a CAGR of 5.3% during the forecast period, driven by increasing demand for enhanced surface protection and long-lasting gloss retention. Clearcoats provide superior resistance against scratches, UV radiation, chemicals, and weathering, thereby extending lifespan and maintaining aesthetic quality. The growing adoption of premium finishes and advanced multilayer coating systems is supporting segment expansion.
Application Insights
Metal held the largest market share of 70.0%, due to their extensive use in body structures, frames, and critical components. They can be applied to metal surfaces, providing essential protection against corrosion, moisture, chemicals, and environmental damage, thereby improving durability and operational performance. The continued dominance of metal components in passenger and commercial manufacturing has sustained strong demand for metal-based coating applications.
The plastic segment is expected to grow at a CAGR of 6.0% from 2026 to 2033, driven by the increasing adoption of lightweight components to improve fuel efficiency and electric vehicle performance. Plastic materials are increasingly used in bumpers, dashboards, trims, and exterior motor parts, creating demand for specialized coatings with enhanced adhesion and flexibility. Growing emphasis on weight reduction and emission control regulations is further encouraging the use of coated plastic components. Technological advancements in coating formulations designed specifically for plastic substrates are also contributing to segment growth.
End Use Insights
The light vehicle OEM segment held the largest share of 57.3% in 2025, supported by high global production volumes of passenger cars and utility vehicles. Manufacturers continue to invest in advanced coating technologies to improve appearance, corrosion resistance, and long-term durability. Rising consumer demand for visually appealing, premium exterior finishes has further increased coating consumption in OEM manufacturing operations. The rapid expansion of electric passenger vehicle production is also contributing to segment growth.
The automotive refinish segment is expected to grow at a CAGR 5.4% from 2026 to 2033, due to increasing automobile ownership, rising accident repair activities, and growing demand for maintenance services. Consumers are increasingly opting for refinishing solutions to restore appearance and maintain resale value. The expansion of insurance-supported repair services and collision repair networks is further supporting market demand.
Technology Insights
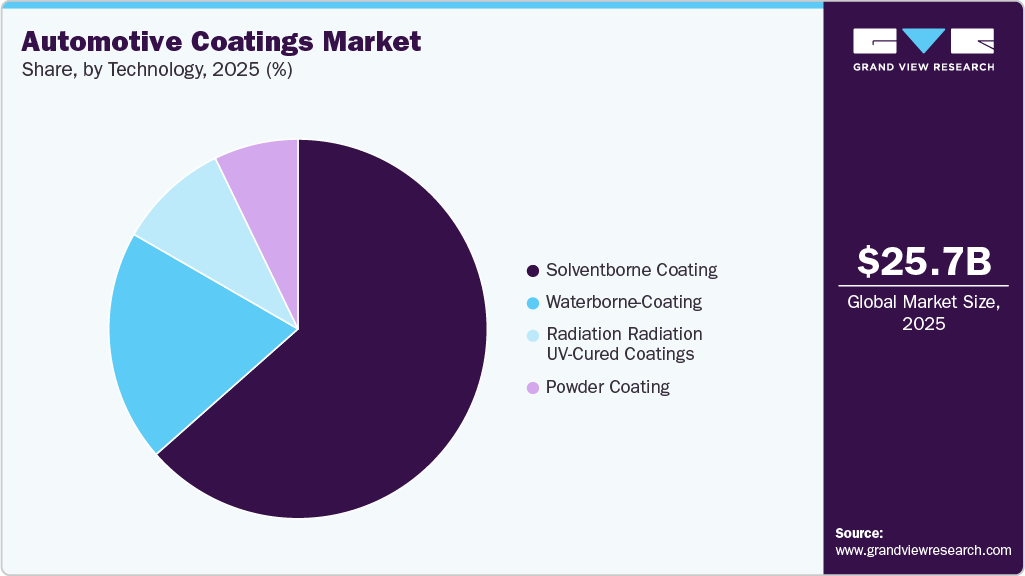
Solventborne coatings dominated the market, accounting for 63.5% of revenue in 2025, due to their strong adhesion, high durability, and superior finish quality across diverse applications. These coatings remain widely preferred in regions where performance requirements and application flexibility outweigh regulatory limitations. Their ability to perform effectively under varying environmental conditions and deliver high-quality finishes continues to support market demand.
 To learn more about this report, Download Free Sample Report
Waterborne coatings is expected to grow the fastest with a CAGR of 7.3% during the forecast period, due to increasing environmental regulations aimed at reducing volatile organic compound (VOC) emissions. Manufacturers are rapidly shifting toward sustainable coating technologies that offer lower environmental impact without compromising coating quality or durability. Rising sustainability initiatives and growing investments in green manufacturing technologies are expected to further accelerate segment growth.
Regional Insights
Asia Pacific held the largest share of 49.2% in 2025 due to the region’s strong manufacturing base, expanding production capacity, and rising consumer demand for passenger vehicles. Countries such as China, India, Japan, and South Korea continue to attract significant investments from OEMs and coating manufacturers owing to lower production costs and favorable industrial policies. Rapid urbanization, increasing disposable incomes, and the growing adoption of electric vehicles are further supporting market expansion.
 To learn more about this report, Download Free Sample Report
China Automotive Coatings Market Trends
The automotive coatings market in China remains a dominant contributor, given its position as the world’s largest automobile producer and consumer. The country’s strong manufacturing ecosystem, extensive automotive supply chain, and government support for electric vehicle adoption are driving significant demand for advanced coating solutions. The rising production of premium and electric vehicles is increasing demand for high-performance coatings with enhanced durability and aesthetic appeal.
Europe Automotive Coatings Market Trends
The automotive coatings market in Europe has a strong presence of premium manufacturers and strict environmental regulations. Demand for sustainable and low-VOC coating technologies has accelerated the adoption of waterborne and powder coatings across manufacturing facilities. The region’s focus on innovation, aesthetics, and high-quality finishing standards continues to support market growth. In addition, increasing investments in electric mobility and lightweight technologies are creating opportunities for advanced solutions.
Germany automotive coatings market plays a critical role due to its strong manufacturing capabilities and presence of globally recognized automobile brands. The country’s emphasis on engineering excellence, premium production, and technological innovation drives significant demand for advanced coating systems. Growing investments in electric vehicles and sustainable manufacturing processes are encouraging the adoption of environmentally friendly coating technologies.
North America Automotive Coatings Market Trends
The automotive coatings market in North America has a strong demand for passenger and commercial vehicles and refinish services. The region benefits from the presence of leading automotive manufacturers, advanced manufacturing technologies, and growing investments in electric vehicle production. Increasing consumer preference for premium finishes and durable coatings is further supporting market demand.
The U.S. automotive coatings market represented a major market because of high ownership rates, strong production, and a well-developed industry. Rising demand for customization, repair, and refinishing services continues to support growth in the refinish coatings segment. The rapid expansion of electric vehicle manufacturing and increasing investments in advanced technologies are also contributing to development.
Middle East & Africa Automotive Coatings Market Trends
The automotive coatings market in MEA is experiencing gradual growth, driven by increasing automobile imports, expanding transportation infrastructure, and rising demand for passenger and commercial vehicles. Growing urbanization and economic diversification initiatives in several countries. The automotive refinish segment is also gaining traction due to harsh climatic conditions, which increase maintenance and repair requirements.
Latin America Automotive Coatings Market Trends
The automotive coatings market in Latin America is experiencing growth due to recovering production activities and increasing automobile ownership. Countries such as Brazil and Mexico continue to serve as important manufacturing hubs, attracting investments from global OEMs and component suppliers. Demand is further supported by rising consumer interest in maintenance, refinishing, and appearance enhancement.
Key Automotive Coatings Company Insights
Companies are increasingly focusing on strategic partnerships, product innovation, and expansion of manufacturing capacities to strengthen their competitive position. Market participants are investing heavily in sustainable technologies, such as waterborne, powder, and UV-cured coatings, to align with evolving environmental regulations and the growing demand for eco-friendly solutions. Firms are enhancing their regional presence through acquisitions, collaborations with OEMs, and investments in advanced research and development to support electric vehicle coatings and next-generation lightweight materials.
-
Asian Paints is a prominent participant, supported by its strong manufacturing capabilities and extensive distribution network. The company offers a diversified portfolio of coatings designed to enhance durability, surface protection, and aesthetic performance across OEM and refinish applications. Asian Paints continues to strengthen its market presence through technological innovation, strategic partnerships, and investments in sustainable coating technologies, including low-VOC and waterborne solutions.
-
The Sherwin-Williams Company is a leading company with a well-established presence in the industry. The company provides advanced coating systems for OEM and refinish applications, focusing on high-performance products that deliver corrosion resistance, color retention, and enhanced finish quality. Sherwin-Williams emphasizes continuous research and development to introduce environmentally responsible coatings aligned with evolving regulatory standards and sustainability objectives.
Key Automotive Coatings Companies:
The following key companies have been profiled for this study on the automotive coatings market.
- The Sherwin-Williams Company
- PPG Industries, Inc.
- Akzo Nobel N.V.
- NIPSEA Group
- RPM International Inc.
- BASF SE
- Kansai Paint Co., Ltd.
- Asian Paints
- Berger Paints India
- Axalta Coating Systems, LLC
- FUJIKURA KASEI CO., LTD.
- KCC Corporation
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players: The Sherwin-Williams Company; PPG Industries, Inc.; Akzo Nobel N.V.; BASF SE; Axalta Coating Systems, LLC; Kansai Paint Co., Ltd.; RPM International Inc.; NIPSEA Group
- Focus heavily on continuous research and development to introduce advanced, sustainable, and high-performance automotive coating technologies.
- These companies actively pursue mergers, acquisitions, and long-term partnerships with automotive OEMs to strengthen their global market presence and supply chain capabilities.
- Established players benefit from strong brand recognition, extensive distribution networks, and diversified product portfolios across multiple automotive coating applications.
- Large-scale manufacturing capabilities and strong financial resources enable them to invest consistently in innovation, regulatory compliance, and global expansion initiatives.
- Large operational structures and complex supply chains can increase operational costs and reduce flexibility in responding to rapidly changing market trends.
- Strict environmental regulations and high dependence on raw material pricing create margin pressures and increase compliance-related expenditures.
Emerging Players: Asian Paints; Berger Paints India; FUJIKURA KASEI CO., LTD.; KCC Corporation
- Emerging companies primarily focus on regional expansion, cost-competitive product offerings, and strengthening local manufacturing capabilities.
- These players increasingly invest in niche technologies and customized coating solutions to target specific customer requirements and underserved markets.
- Emerging players often benefit from greater operational flexibility and the ability to respond quickly to evolving customer preferences and regional demand patterns.
- Competitive pricing strategies and growing presence in high-growth emerging economies support market penetration and customer acquisition.
- Limited global presence and comparatively lower research and development investments can restrict technological advancement and large-scale expansion opportunities.
- Smaller distribution networks and lower brand recognition may reduce their ability to compete with established multinational companies in premium market segments.
Recent Developments
-
In February 2025, the Sherwin-Williams Company revealed plans to acquire BASF’s Brazilian architectural paints division, Suvinil, in a deal valued at nearly USD 1.1 billion, aiming to enhance its market presence in Latin America and broaden its coatings business portfolio. The acquisition supports the company’s long-term strategy to expand in regional markets.
-
In November 2025, Akzo Nobel N.V. and Axalta Coating Systems, LLC signed a merger agreement to form a leading global coatings enterprise with an estimated combined enterprise value of approximately USD 25 billion.
Automotive Coatings Market Report Scope
Report Attribute
Details
Market size in 2025
USD 25.7 billion
Estimated Market size in 2026
USD 27.0 billion
Projected Market size by 2033
USD 38.3 billion
Growth rate
CAGR of 5.1% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/million, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, volume forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, technology, application, end use, region
Regional scope
North America; Europe; Asia Pacific; MEA; Latin America
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; China; India; Japan; South Korea; Brazil; Argentina; South Africa; Saudi Arabia
Key companies profiled
The Sherwin-Williams Company; PPG Industries, Inc.; Akzo Nobel N.V.; NIPSEA Group; RPM International Inc.; BASF SE; Kansai Paint Co., Ltd.; Asian Paints; Berger Paints India; Axalta Coating Systems, LLC; FUJIKURA KASEI CO., LTD.; KCC Corporation
Customization scope
Free report customization (equivalent up to 8 analysts’ working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Coatings Market Report Segmentation
This report forecasts volume & revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global automotive coatings market report based on product, technology, application, end use, and region:
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Primer
-
E-coat
-
Basecoat
-
Clearcoat
-
-
Technology Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Waterborne Coatings
-
Solventborne Coatings
-
Powder Coating
-
Radiation UV-Cured Coatings
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Metal
-
Plastic
-
-
End Use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Light Vehicle OEM
-
Commercial OEM
-
Automotive Refinish
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
Saudi Arabia
-
South Africa
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Pricing Analysis
Comprehensive pricing analysis covering automotive coatings across resin type, coating layer, vehicle type, technology, and regional markets. The assessment includes raw material cost trends for epoxy, polyurethane, acrylic, polyester, pigments, solvents, additives, and curing agents; regional pricing variations; manufacturing and application cost structures; and pricing differentiation across waterborne, solventborne, powder, and UV-cured coating technologies. The analysis also evaluates supply-demand dynamics, OEM pricing trends, energy cost impact, transportation costs, environmental compliance costs, and pricing developments associated with light vehicle OEM, commercial vehicle OEM, and automotive refinish applications.
Support procurement optimization, pricing strategy development, and manufacturing cost planning through enhanced understanding of raw material economics, regional pricing movements, and coating technology cost competitiveness. Help identify raw material volatility risks, margin optimization opportunities, premium pricing potential for low-VOC and sustainable coatings, and strategic sourcing advantages across automotive OEM and refinish markets.
Opportunity Assessment
Detailed evaluation of emerging growth opportunities across electric vehicles (EVs), autonomous vehicles, lightweight materials, smart coatings, low-VOC coatings, automotive refinish, and sustainable coating technologies. The assessment includes analysis of EV production growth, automotive manufacturing expansion, environmental regulations, waterborne coating adoption, high-performance coating demand, and advancements in coating durability, corrosion resistance, and aesthetic finishes. It also highlights high-growth regional automotive manufacturing hubs, evolving OEM coating requirements, sustainability initiatives, and opportunities associated with premium vehicle production and next-generation mobility trends.
Enable prioritization of high-growth application areas and emerging investment opportunities across the automotive coatings value chain. Support strategic planning, product innovation, sustainability positioning, and market expansion initiatives through insights into EV adoption trends, regulatory developments, lightweight vehicle production, and future demand potential for advanced automotive coating technologies.
Competitive Benchmarking
Comparative assessment of key automotive coatings manufacturers based on product portfolio, resin technology capabilities, manufacturing footprint, OEM partnerships, sustainability initiatives, R&D investments, production capacity, distribution network, and regional presence. The analysis also evaluates competitive positioning across primer, e-coat, basecoat, clearcoat, and refinish coating segments, along with benchmarking of waterborne, powder, solventborne, and UV-curable coating technologies. Additional analysis includes innovation strategies, low-VOC product development, EV-focused coating solutions, strategic collaborations, mergers & acquisitions, and capacity expansion activities across major automotive manufacturing regions.
Support benchmarking against leading market participants and identify competitive gaps across coating technologies, OEM integration capabilities, sustainability positioning, and innovation strategies. Enable informed decision-making related to strategic partnerships, product differentiation, investment planning, regional expansion, and long-term competitive positioning within the evolving automotive coatings and mobility ecosystem.
Frequently Asked Questions About This Report
The global automotive coatings market size was valued at USD 25.7 billion in 2025 and is expected to reach USD 27.0 billion in 2026.
Asia Pacific dominated the automotive coatings market with the largest revenue share of 49.2% in 2025.
Latin America is the fastest-growing regional market and is projected to experience rapid expansion over the forecast period from 2026 to 2033.
Basecoat held the largest share of 40.1% in 2025 due to its critical role in providing color, visual appeal, and surface aesthetics.
The market is primarily driven by growth in global automobile production and increasing demand for enhanced vehicle durability and aesthetics. Manufacturers are adopting advanced coating technologies to improve corrosion resistance, weather protection, scratch resistance, and overall vehicle lifespan, which supports market expansion.
The metal segment dominated the global automotive coatings market in 2025, accounting for a 70.0% revenue share in the application category.
The light vehicle OEM segment dominated the market, holding the largest share of 57.3% in 2025.
Solventborne coatings dominated the market, accounting for 63.5% of revenue in 2025, due to their strong adhesion, high durability, and superior finish quality across diverse applications.
Some of the key players operating in the automotive coatings market include The Sherwin-Williams Company, PPG Industries, Inc., Akzo Nobel N.V., NIPSEA Group, RPM International Inc., BASF SE, Kansai Paint Co., Ltd., Asian Paints, Berger Paints India, Axalta Coating Systems, LLC, FUJIKURA KASEI CO., LTD., KCC Corporation.
About the Author(s)
Paints, Coatings & Printing Inks Research Team
Bulk Chemicals · Paints, Coatings & Printing InksThis report was authored by the paints, coatings & printing inks research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the paints, coatings & printing inks segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


