
- Home
- »
- Plastics, Polymers & Resins
- »
-
Automotive Interior Leather Market Size Report, 2026-2033GVR Report cover

Automotive Interior Leather Market (2026 - 2033)
Size, Share & Trends Analysis Report By Material (Genuine, Synthetic), By Vehicle Type (Passenger Car, Light Commercial, Heavy Commercial), By Car Class (Economy, Mid-Segment), By Applications, By Region, And Segment Forecasts
Market Size, 2025
$44.9BMarket Estimate, 2026
$47.6BMarket Forecast, 2033
$78.7BCAGR, 2026–2033
7.4%Automotive Interior Leather Market Summary
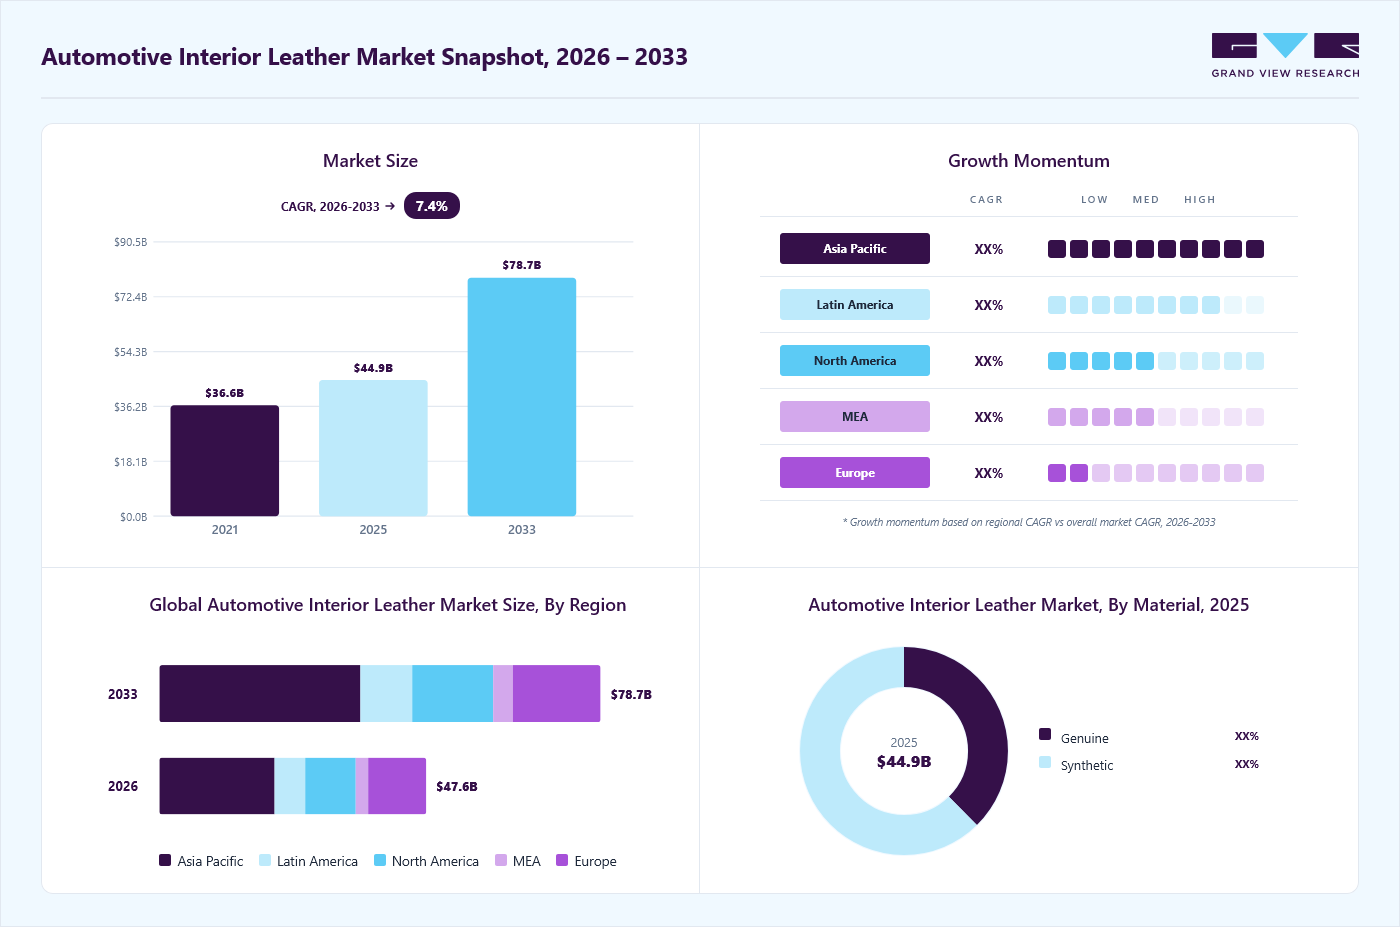
The global automotive interior leather market size was valued at USD 44.9 billion in 2025 and is projected to grow from USD 47.6 billion in 2026 to USD 78.7 billion by 2033, at a CAGR of 7.4% from 2026 to 2033. The market in Asia Pacific dominated with a revenue share of 42.9% in 2025. The increasing demand for premium and durable leather upholstery in passenger and luxury vehicles is positively influencing the automotive interior leather market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By material: Synthetic segment held the largest market share of 62.4% in 2025.
- By vehicle type: Passenger car segment held the largest market share of 71.6% in 2025.
- By car class: Luxury car segment held the largest market share of 70.4% in 2025.
- By application: Seats & center stack segment held the largest market share of 55.2% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (42.9% revenue share, 2025)
- By country: China held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 44.9 Billion
- Estimated market size in 2026: USD 47.6 Billion
- Projected market size by 2033: USD 78.7 Billion
- CAGR (2026-2033): 7.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Moreover, factors such as rising consumer preference for enhanced cabin aesthetics and comfort, growing vehicle production, advancements in leather processing technologies, and expanding applications of automotive interior leather in seats, steering wheels, dashboards, and door panels are driving market demand globally. The automotive interior leather market in the U.S. is predicted to experience significant growth in recent years, with several factors driving this expansion. Consumer desire for high-quality and elegant interior materials is likely to drive market expansion in the country throughout the forecast period. A significant increase in demand for automobile synthetic leather upholstery is likely to push the entire industry in the U.S. Initiatives to enhance the supply chain are expected to benefit the market in the U.S. over the forecast period.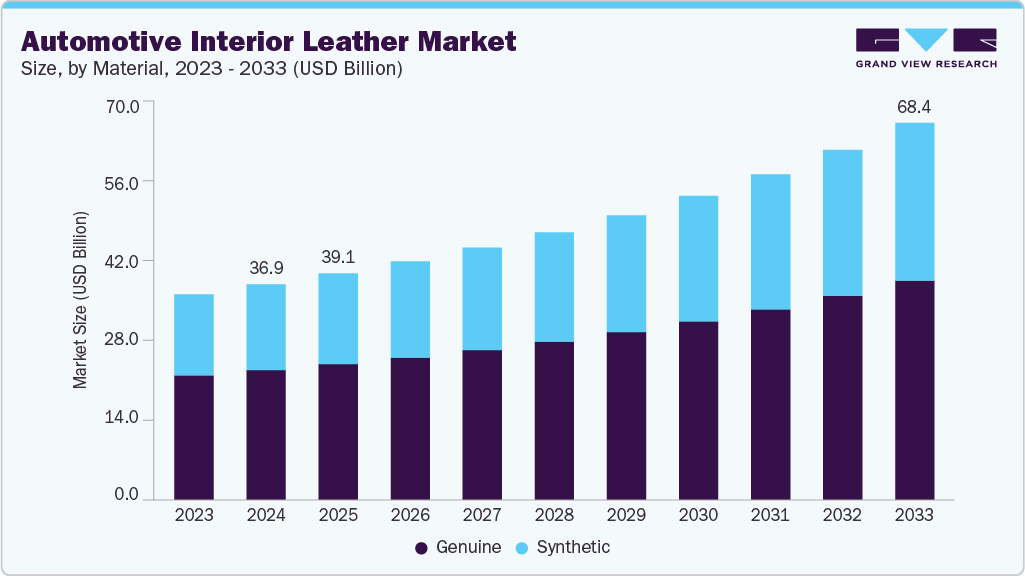 To learn more about this report, Download Free Sample Report
Market Dynamics
The automotive interior leather market is transitioning from a traditional premium trim segment into a strategically important component of modern vehicle interior design and sustainability initiatives. Growing adoption of advanced synthetic leathers and textile-composite materials is reshaping competitive dynamics as manufacturers invest in innovative alternatives that deliver comparable aesthetics, durability, and cost efficiency. Simultaneously, increasingly stringent environmental and animal welfare regulations are influencing sourcing practices, production technologies, and supply chain transparency requirements. While these regulations elevate compliance costs, they also encourage cleaner manufacturing and material innovation. Demand remains concentrated across passenger and luxury vehicles, creating significant growth opportunities alongside intensifying competition among interior material suppliers.
The automotive interior leather market is witnessing strong growth due to rising demand for premium vehicles across emerging economies, supported by increasing disposable incomes and expanding middle- and upper-income consumer groups. As vehicle buyers place greater emphasis on comfort, aesthetics, and luxury features, automakers are increasingly incorporating leather upholstery into passenger cars, SUVs, and premium vehicle segments. Leather interiors offer enhanced visual appeal, durability, and comfort, making them a preferred choice for consumers seeking a more refined in-cabin experience and higher vehicle value.
Premiumization trends remain a key demand driver, particularly as automotive manufacturers differentiate their offerings through advanced interior designs and upscale cabin materials. Original equipment manufacturers (OEMs) are increasingly positioning leather seating, steering wheel wraps, and interior trims as value-added features to support higher vehicle pricing and strengthen brand positioning. Growing demand for luxury and near-luxury vehicles in rapidly developing markets is further accelerating leather adoption, reinforcing its role as a critical component of premium automotive interior strategies.
Regulatory compliance remains a significant restraint for the automotive interior leather market. Leather manufacturing is subject to increasingly stringent environmental regulations governing chemical usage, wastewater treatment, emissions control, and occupational safety standards across major production regions. Compliance with these evolving regulations requires manufacturers to invest in advanced processing technologies, sustainable tanning methods, and comprehensive monitoring systems, leading to higher operational and administrative costs. Additionally, varying regulatory frameworks across countries increase complexity for global suppliers, while stricter sustainability and animal welfare requirements can prolong certification processes and impact production flexibility, creating challenges for market growth and profitability.
The accelerating adoption of electric vehicles is creating significant growth opportunities for the automotive interior leather market. Rising demand for lightweight, low-emission, and sustainable cabin materials is encouraging leather manufacturers to develop eco-friendly tanning processes and bio-based leather alternatives. These innovations align with automakers’ efforts to reduce vehicle lifecycle carbon emissions while enhancing interior aesthetics and performance. Additionally, the expansion of shared mobility services is increasing the need for durable and easily refurbishable interiors, further strengthening the long-term value proposition of advanced automotive leather solutions.
Market Concentration & Characteristics
The growth stage of the automotive interior leather market is moderate, with the pace picking up. The market shows fragmentation, with major players dominating the industry. Key companies like GST Autoleather Inc, Eagle Ottawa, CTL Leather, Alphaline Auto, DK Leather Corporation, Scottish Leather Group, Wollsdorf Leder Schmidt & Co Ges, Classic Soft Trim, Katzkin Leather Inc, Kuraray Plastics, Alfatex Italia, Seiren Co Ltd, Lear Corporation, Bader GmbH & Co. KG, BOXMARK Leather GmbH & Co KG, and others play a crucial role in shaping the market dynamics. These leading companies often push innovation, launching new products, technologies, and applications to meet changing industry needs.
In response to evolving consumer values and cost pressures, automakers are increasingly turning to advanced synthetic leathers and textile‐composite fabrics as alternatives to traditional hides. These substitutes offer tailored performance characteristics such as enhanced abrasion resistance and ease of maintenance while reducing dependence on animal‐derived inputs. Suppliers are investing in micro-fiber and bio-polymer blends that closely mimic the look and feel of genuine leather. This shift is driven by a desire to balance cabin refinement with scalable, cost-effective materials.
 To learn more about this report, Download Free Sample Report
Stringent environmental and animal welfare regulations are transforming production methods and material choices within the automotive leather industry. Regulations aimed at reducing chemical runoff and emissions from tanning compel suppliers to implement closed-loop systems and use environmentally friendly agents. At the same time, tighter import controls on animal products in key markets demand better traceability and certification throughout the supply chain. While compliance costs are increasing, they also promote innovation in cleaner manufacturing and sourcing practices.
Analyst Perspective
The automotive interior leather market is expected to shift over the next few years from a cost-driven, OEM-focused segment to a more value-driven and sustainability-oriented industry. Demand will remain strong in passenger cars, especially in premium and luxury vehicles, while electric vehicles and shared mobility will increase the need for lightweight, durable, and low-emission interiors. Strict environmental regulations and OEM sustainability goals are driving the adoption of chrome-free tanning, bio-based materials, and hybrid leather solutions. Innovation, customization, and strong OEM partnerships will define competitive advantage. However, the market will face challenges from raw material price fluctuations and competition from synthetic alternatives.
Material Insights
Based on material, the synthetic segment led the market with the largest revenue share of 62.4% in 2025. Rapid advances in bio-polymer chemistry and micro-fiber weaving are fueling the swift uptake of synthetic leather. Manufacturers prize its consistent quality, lighter weight, and simplified maintenance, which align with modern design and sustainability agendas. Cost-efficient production scales and shorter lead times further incentivize OEMs to specify synthetics. This material’s evolving eco-credentials and design versatility are accelerating its adoption across vehicle lines.
The genuine material is anticipated to grow at a substantial CAGR of 7.1% during the forecast period. Premium positioning and heritage appeal support genuine leather’s dominance in automotive interiors. Established automakers use authentic hides to showcase craftsmanship and durability, strengthening brand prestige. Long-standing supply chains and proven durability performance build OEM confidence. As consumers value tactile authenticity and long-term cabin comfort, genuine leather remains the top choice for both flagship and mainstream models alike.
Vehicle Type Insights
Based on vehicle type, the passenger car segment led the market with the largest revenue share of 71.6% in 2025. The extensive global passenger car fleet provides the main market for interior leather, driven by economies of scale based on volume. Both mainstream and premium automakers use leather trim to differentiate trim levels and justify price tiers. Consumer expectations for refinement in family sedans and compact SUVs support leather’s widespread use. Consistent replacement cycles and aftermarket upholstery services also help maintain leather demand in this key segment.
Growth in last-mile delivery fleets and ride-hailing vans is spotlighting driver comfort and brand image, boosting leather uptake in light commercial vehicles leading to an expectation of substantial growth at 6.4% throughout the forecast period. Operators seek durable yet professional cabin styling to enhance driver retention and corporate identity. Leather surfaces deliver easy cleaning and perceived quality during high-utilization duty cycles. This operational-driven focus is propelling rapid leather integration into vans and small trucks.
Car Class Insights
Based on car class, the luxury car segment led the market with the largest revenue share of 70.4% in 2025. A strong focus on bespoke interiors maintains leather’s dominance in the luxury car market. High-end brands utilize full-grain hides and artisanal stitching to create an emotional ownership experience. Custom color options and tactile personalization enhance exclusivity, further emphasizing leather’s symbolic value. Consequently, luxury OEMs continue to base cabin design strategies around genuine leather as a sign of sophistication.
The mid-segment car is expected to augment at a significant volume CAGR of 6.8% from 2026 to 2033. Mid-segment models are elevating perceived value by extending leather trim from entry-level to premium-adjacent variants. Automakers strategically introduce partial leather or leather-touch points to bridge the gap between fabric and full leather cabins. This mix-and-match approach meets cost targets while offering aspirational features to price-sensitive buyers. The tactic strengthens trim-level differentiation and drives upsell opportunities.
Applications Insights
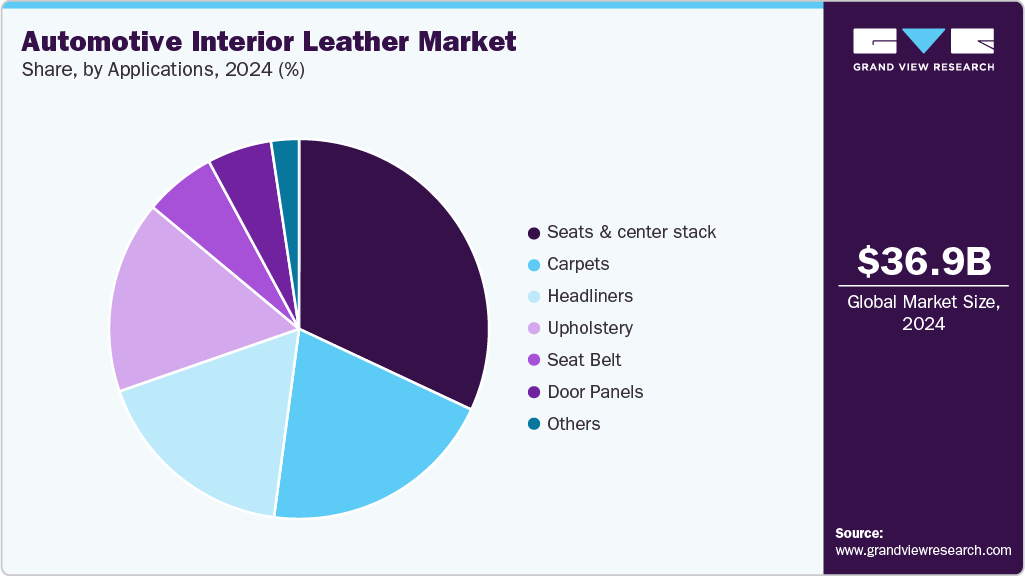
Based on the application, the seats & center stack segment led the market with the largest revenue share of 55.2% in 2025. Leather upholstery on seats and the center stack remains the focal point for visual and tactile cabin luxury.
OEMs concentrate high-wear, high-view areas on premium materials to maximize perceived quality during every touchpoint. Ergonomic shaping and integrated heating or cooling further enhance comfort, leveraging leather’s thermal responsiveness. This strategic material placement ensures leather’s impact is both seen and felt by occupants.
 To learn more about this report, Download Free Sample Report
Carpets are emerging as a niche yet growing applications, expected to grow at 6.6% CAGR over the forecast period, blending underfoot comfort with enhanced stain resistance. By incorporating leather trim around footwells and door sills, automakers deliver a cohesive luxury aesthetic that extends beyond seating surfaces. This approach also improves durability in high-traffic areas, reducing lifecycle maintenance costs. As interior design languages evolve, leather-accented flooring adds a subtle premium touch.
Regional Insights
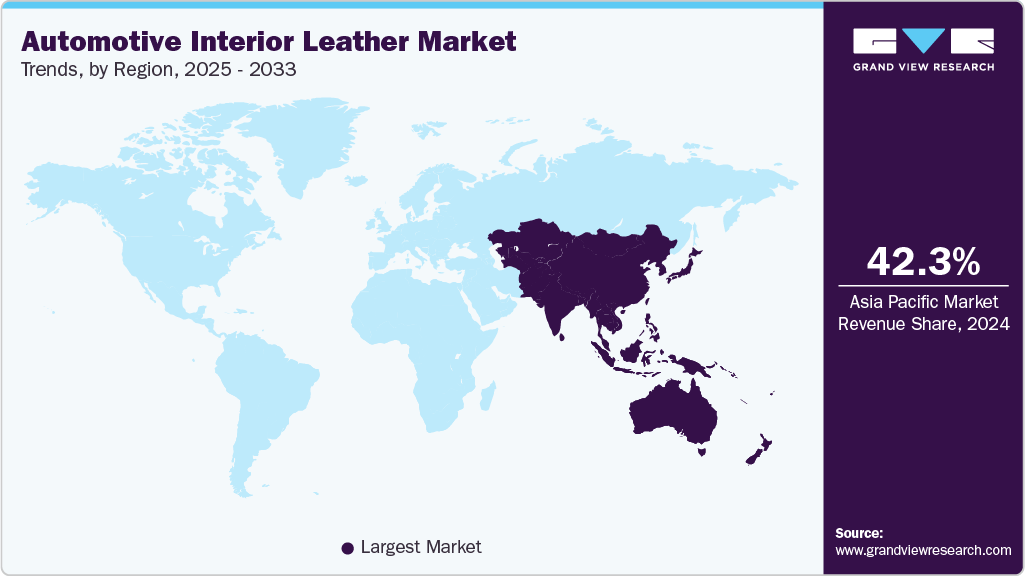
Asia Pacific dominated the automotive interior leather market with the largest revenue share of 42.9% in 2025. Rapid urbanization and rising disposable incomes across Asia Pacific are expanding the addressable market for vehicles equipped with premium interiors. Local OEMs in markets like India and Thailand are upgrading cabin finishes with leather accents to capture upwardly mobile buyers. Simultaneously, joint ventures with global luxury brands introduce novel leather treatment techniques, elevating regional production capabilities. These combined factors are accelerating leather adoption throughout the region.
 To learn more about this report, Download Free Sample Report
China Automotive Interior Leather Market Trends
The automotive interior leather market in China accounted for the largest market revenue share in the Asia Pacific in 2025. China’s aggressive push toward new energy vehicles offers leather suppliers a strategic growth avenue, as domestic EV makers seek to match Western luxury benchmarks. Government incentives for locally sourced materials incentivize partnerships between OEMs and indigenous tanneries, fostering supply-chain localization. Additionally, an emerging middle-class with sophisticated taste profiles is driving demand for dual-tone and perforated leather designs, further diversifying the market.
North America Automotive Interior Leather Market Trends
In North America, the ongoing shift toward electrification and connected vehicles is driving demand for leather interiors that integrate seamlessly with advanced infotainment and comfort systems. OEMs are leveraging premium leather to enhance the perceived value of electric and hybrid models as they compete for early adopters. Concurrently, a strong aftermarket upholstery sector sustains replacement and custom retrofit opportunities. The combination of technological integration and aftermarket vitality underpins leather’s resilience in this region.
The U.S. automotive interior leather market is driven by the country’s robust luxury vehicle market and sustained consumer preference for personalized cabins are fueling leather uptake. Domestic automakers and import brands alike are introducing exclusive leather colorways and bespoke stitching patterns to cater to affluent demographics. At the same time, growing penetration of subscription-based vehicle services elevates the need for durable, easily maintainable leather surfaces. These dynamics reinforce leather’s role as a key differentiator in a crowded market.
Europe Automotive Interior Leather Market Trends
Europe’s stringent sustainability mandates and circular economy initiatives are steering leather producers toward eco-friendly tanning methods and full-traceability supply chains. Premium European automakers are responding by specifying certified low-impact hides in high-end sedans and SUVs, aligning interior materials with broader environmental commitments. This regulatory-driven pivot not only safeguards market access but also bolsters brand equity among increasingly eco-conscious consumers.
Key Automotive Interior Leather Market Company Insights
The automotive interior leather market is highly competitive, with several key players dominating the landscape. Major companies include GST Autoleather Inc, Eagle Ottawa, CTL Leather, Alphaline Auto, DK Leather Corporation, Scottish Leather Group, Wollsdorf Leder Schmidt & Co Ges, Classic Soft Trim, Katzkin Leather Inc, Kuraray Plastics, Alfatex Italia, Seiren Co Ltd, Lear Corporation, Bader GmbH & Co. KG, and BOXMARK Leather GmbH & Co KG.
The automotive interior leather market is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their types.
Key Automotive Interior Leather Companies
The following key companies have been profiled for this study on the automotive interior leather market.
-
GST Autoleather Inc
-
Eagle Ottawa
-
CTL leather
-
Alphaline auto
-
DK leather corporation
-
Scottish leather group
-
Wollsdorf leder schmidt & Co Ges
-
Classic soft trim
-
Katzkin Leather inc
-
Kuraray plastics
-
Alfatex Italia
-
Seiren Co Ltd
-
Lear Corporation
-
Bader GmbH & Co. KG
-
BOXMARK Leather GmbH & Co KG
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Lear Corporation; Eagle Ottawa; GST Autoleather Inc; Scottish Leather Group; Wollsdorf Leder Schmidt & Co Ges; BOXMARK Leather GmbH & Co KG; Bader GmbH & Co. KG; Seiren Co Ltd; Kuraray Plastics; Katzkin Leather Inc)
- Broad portfolios of automotive interior leather solutions spanning genuine leather, synthetic leather, and hybrid material systems used in seats, door panels, upholstery, headliners, and premium interior trims across passenger cars, light commercial vehicles, and luxury automotive platforms.
- Strong presence in OEM supply chains with customized interior design solutions, color-finishing technologies, and performance-enhanced leather materials aligned with evolving automotive styling and sustainability requirements.
- Strong expertise in tanning, finishing, and engineered leather development with deep integration into global automotive OEM supply networks.
- Established capabilities in material innovation including lightweight leather, low-VOC formulations, and enhanced durability coatings tailored for automotive interiors.
- Extensive design-to-delivery capabilities supported by strong relationships with major automotive manufacturers and Tier-1 suppliers, enabling long-term contract stability and co-development programs for next-generation vehicle interiors.
- High dependence on cyclical automotive production trends, particularly passenger and luxury vehicle demand fluctuations.
- Rising pressure from synthetic leather and alternative interior materials impacting pricing competitiveness of genuine leather solutions.
- Increasing regulatory scrutiny on chemical usage, emissions, and environmental impact of tanning and processing operations, along with high operational costs associated with quality compliance, customization, and global supply chain coordination.
Emerging Players (CTL Leather; Alphaline Auto; DK Leather Corporation; Classic Soft Trim; Alfatex Italia)
- Focus on supplying cost-competitive and design-flexible automotive interior leather solutions across synthetic and semi-premium genuine leather categories for passenger cars, light commercial vehicles, and entry-to-mid luxury segments.
- Emphasis on rapid customization capabilities, OEM-aligned product development, and localized manufacturing to serve regional automotive clusters efficiently.
- Increasing focus on synthetic leather innovation (PU/PVC-based), lightweight materials, and value-added surface finishes to meet evolving interior styling and durability requirements.
- Strong agility in responding to OEM design changes, shorter development cycles, and the ability to deliver customized interior leather solutions at scale.
- Competitive positioning in mid-segment and economy vehicle supply chains through cost efficiency and flexible production capabilities.
- Growing capability in synthetic leather innovation supporting sustainability-driven substitution away from genuine leather in price-sensitive segments.
- Limited global scale and weaker brand equity compared to established Tier-1 suppliers restrict penetration into high-end luxury OEM programs.
- Dependence on regional automotive demand cycles and OEM sourcing concentration increases volatility. Lower R&D intensity compared to global leaders may constrain advancement in high-performance, eco-certified, and next-generation sustainable leather alternatives.
- Pricing pressure remains high due to competition from both low-cost synthetic manufacturers and established premium leather suppliers.
Recent Developments
-
In January 2025, Jaguar Land Rover and Maserati joined the Leather Working Group (LWG) in early 2025, marking a significant step for sustainability and responsible sourcing in the automotive leather industry. By becoming members of LWG, a globally recognized organization certifying leather manufacturers on environmental compliance and supply chain transparency, both luxury car makers demonstrated their commitment to aligning with global sustainability standards.
-
In March 2024, Dow introduced a new polyolefin elastomer (POE)-based artificial leather in March 2024, aimed at the automotive industry's shift towards animal-free leather alternatives. The material, commercialized by Dow's partner HIUV Materials Technology in China, has been qualified for use in electric car seatings.
Automotive Interior Leather Market Report Scope
Report Attribute
Details
Market size in 2025
USD 44.9 billion
Estimated market size in 2026
USD 47.6 billion
Projected market size by 2033
USD 78.7 billion
Growth rate
CAGR of 7.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in million sq.ft, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Material, vehicle type, car class, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; France; UK; Italy; Spain; China; Japan; India; South Korea; Australia; Brazil; Argentina; Saudi Arabia; UAE; South Africa.
Key companies profiled
GST Autoleather Inc; Eagle Ottawa; CTL leather; Alphaline auto; DK leather corporation; Scottish leather group; Wollsdorf leder schmidt & Co Ges; Classic soft trim; Katzkin Leather inc; Kuraray plastics; Alfatex Italia; Seiren Co Ltd; Lear Corporation Bader GmbH & Co. KG; BOXMARK Leather GmbH & Co KG
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Automotive Interior Leather Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the automotive interior leather market report on the basis of material, vehicle type, car class, applications, end use, and region:
-
Material Outlook (Volume, Million Sq. Ft; Revenue, USD Million; 2021 - 2033)
-
Genuine
-
Synthetic
-
PU
-
PVC
-
Others
-
-
-
Vehicle Type Outlook (Volume, Million Sq. Ft; Revenue, USD Million; 2021 - 2033)
-
Passenger Car
-
Light Commercial Vehicle
-
Heavy Commercial Vehicle
-
-
Car Class Outlook (Volume, Million Sq. Ft; Revenue, USD Million; 2021 - 2033)
-
Economy Car
-
Mid-Segment Car
-
Luxury Car
-
-
Applications Outlook (Volume, Million Sq. Ft; Revenue, USD Million; 2021 - 2033)
-
Seats & center stack
-
Carpets
-
Headliners
-
Upholstery
-
Seat Belt
-
Door Panels
-
Others
-
-
Regional Outlook (Volume, Million Sq. Ft; Revenue, USD Million; 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The automotive interior leather market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each automotive interior leather segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Material
Revenue capture definition
Genuine Leather
Revenue is captured through the sale of premium-grade natural leather sourced from animal hides and processed for automotive interior applications. Demand is driven by its superior aesthetics, durability, tactile comfort, and premium positioning, making it a preferred material in luxury and high-end vehicle interiors where brand differentiation and perceived quality are critical.
Synthetic Leather
Revenue is captured through the supply of engineered leather alternatives, such as PU and PVC-based materials, used in automotive interiors. Growth is driven by cost-effectiveness, design flexibility, lightweight characteristics, and increasing alignment with vegan and sustainability trends, enabling broad adoption across the economy and mid-segment vehicles.
Segment - Vehicle Type
Revenue capture definition
Passenger Cars
Revenue is captured through the use of automotive interior leather in passenger vehicles, including economy, mid-range, and luxury segments. Demand is supported by rising consumer preference for comfort, aesthetics, and enhanced cabin experience, with increasing integration of both genuine and synthetic leather across seating, trims, and interior surfaces.
Light Commercial Vehicles (LCVs)
Revenue is captured through leather applications in light-duty commercial vehicles used for logistics, passenger transport, and small-scale cargo movement. Growth is driven by improving cabin comfort standards, fleet modernization, and increasing adoption of durable synthetic leather solutions that balance cost efficiency with functionality.
Heavy Commercial Vehicles (HCVs)
Revenue is captured through limited but growing use of leather materials in heavy-duty trucks and buses, primarily in driver seating and cabin interiors. Demand is supported by rising focus on driver comfort, long-haul ergonomics, and durable, easy-to-maintain synthetic leather materials suitable for intensive usage environments.
Segment - Car Class
Revenue capture definition
Economy Car
Revenue is captured through cost-sensitive adoption of synthetic leather materials in entry-level vehicles. Demand is driven by affordability, durability, and ease of maintenance, with manufacturers focusing on functional interior aesthetics while optimizing production costs.
Mid-segment Car
Revenue is captured through a balanced mix of synthetic and select genuine leather applications in mid-range vehicles. Growth is driven by rising consumer expectations for comfort and premium-feel interiors at moderate price points, leading to increasing penetration of upgraded leather trims and hybrid material usage.
Luxury Car
Revenue is captured through high-value usage of premium genuine leather and advanced synthetic alternatives in luxury vehicles. Demand is supported by strong emphasis on craftsmanship, exclusivity, personalization, and superior comfort, making leather a key differentiator in high-end automotive interiors.
Segment - Application
Revenue Capture Definition
Seats & Center Stack
Revenue is captured through the use of leather in seating systems and central interior structures, including armrests and console areas. Demand is driven by the need for comfort, durability, aesthetic appeal, and enhanced tactile experience, making it one of the highest-value application segments in automotive interiors.
Carpets
Revenue is captured through leather and leather-finished materials used in floor coverings and interior carpeting solutions. Growth is supported by demand for durability, sound insulation, and premium interior styling, particularly in mid to high-end vehicles.
Headliners
Revenue is captured through the application of leather or leather-finished materials in roof lining systems. Demand is driven by aesthetic enhancement, acoustic performance, and premium cabin experience, especially in luxury and high-comfort vehicle segments.
Upholstery
Revenue is captured through leather used for interior surface covering across seats, dashboards, armrests, and trim components. Growth is supported by rising consumer preference for premium interiors, customization trends, and improved material performance characteristics.
Seat Belt
Revenue is captured through niche applications where leather or leather-finished coverings are integrated into seat belt systems for enhanced aesthetics and premium positioning. Demand remains limited but is driven by luxury customization trends.
Door Panels
Revenue is captured through leather used in door trims and panels to enhance interior aesthetics and tactile quality. Growth is driven by increasing adoption in mid and luxury vehicles, where interior design consistency and premium feel are key purchasing factors.
Other Applications
Revenue is captured through emerging and specialty uses of automotive leather, including steering wheel covers, pillar trims, instrument panels, and customized interior components. Demand is driven by design innovation, personalization trends, and continuous enhancement of in-cabin user experience.
Estimation Model
Layer Name
Key Question
Description
Top-Down Automotive Interior Leather Demand Scan Layer
What defines market boundaries?
This layer starts with global automotive interior leather demand across passenger cars, light commercial vehicles, and heavy commercial vehicles, then filters consumption intensity based on vehicle production volumes, automotive interior content per vehicle, premiumization trends, OEM material preferences, and regulatory shifts toward sustainable and low-VOC interior materials, influencing material substitution between genuine and synthetic leather.
Application Mix Validation Layer
Where is demand generated?
This layer evaluates demand distribution across seats & center stack, door panels, upholstery, headliners, carpets, seat belts, and other interior components, aligning market revenue with comfort requirements, aesthetic differentiation, durability standards, safety compliance, and premium interior design expectations across economy, mid-segment, and luxury vehicles.
Material & Consumption Conversion Layer
Who captures market revenue?
This layer converts automotive production volumes into leather material revenue by applying material mix ratios between genuine and synthetic leather, usage intensity per vehicle class, thickness and finishing specifications, stitching and surface treatment requirements, and OEM sourcing strategies across global automotive supply chains.
Regional Commercial Cross-Check Layer
How are assumptions validated?
This layer validates demand concentration by comparing Asia Pacific’s large-scale automotive manufacturing base, Europe’s luxury vehicle and premium interior design leadership, and North America’s high SUV penetration and aftermarket customization trends, while also factoring in emerging demand from Latin America and Middle East markets for cost-effective synthetic leather adoption and premiumization trends.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional segmentation
Structured the Automotive Interior Leather market across key geographies such as North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa, with demand interpretation by vehicle production, premiumization, OEM presence, and material preference trends.
Provides a clear regional demand map, highlights high-growth clusters, and supports region-wise market entry and expansion planning.
Cross-segmentation
Built an integrated view across material, vehicle type, car class, and application segments, linking genuine and synthetic leather demand to passenger cars, light commercial vehicles, and heavy commercial vehicles, as well as seats, door panels, upholstery, headliners, carpets, seat belts, and other applications.
Enables multi-dimensional market sizing, reveals high-value segment intersections, and improves precision in identifying revenue pockets.
Opportunity assessment
Identified growth opportunities across premium interiors, vegan and sustainable leather alternatives, EV interior upgrades, lightweight material substitution, and customization-driven OEM programs.
Highlights future demand pockets, supports product innovation planning, and helps prioritize investment in high-potential applications and geographies.
Frequently Asked Questions About This Report
Key factors that are driving the market growth include the rising popularity of synthetic leather owing to the low cost and increasing demand for lightweight passenger cars.
The synthetic segment led with a 62.4% revenue share in 2025.
The global automotive interior leather market size was valued at USD 44.9 billion in 2025 and is estimated at USD 47.6 billion for 2026.
The global automotive interior leather market is expected to grow at a CAGR of 7.4% from 2026 to 2033, reaching USD 78.7 billion by 2033.
Some of the key players operating in the automotive interior leather market includes: GST Autoleather Inc, Eagle Ottawa, CTL leather, Alphaline auto, DK leather corporation, Scottish leather group, Wollsdorf leder schmidt & Co Ges, Classic soft trim, Katzkin Leather inc, Mayur uniquoters, Kuraray plastics, Alfatex Italia, Seiren Co Ltd, Lear Corporation, and Bader GmbH & Co. KG
The Asia Pacific automotive interior leather market accounted for the largest share of 42.9% market size in 2025.
India was the leading automotive interior leather market and is expected to grow at a compound annual growth rate of 9.4%.
The luxury car segment accounted for the largest share of 70.4% market size in 2025. Growing demand for premium comfort, refined aesthetics, and sustainable interior materials in luxury cars is driving the adoption of high-performance automotive interior leather due to its superior tactile quality, design flexibility, durability, and increasing shift toward low-VOC, chrome-free, and bio-based leather alternatives aligned with OEM sustainability goals.
Seats & center stack segment held the largest share (over 55.0%) in 2025.
The passenger car led the automotive interior leather market in 2025 with a 71.6% share. Growing demand for premium, comfortable, and sustainable cabin experiences in passenger cars is driving the adoption of automotive interior leather due to its superior aesthetics, high durability, enhanced tactile comfort, low-VOC compliance, and alignment with OEM sustainability and evolving lightweight interior design requirements.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


