
- Home
- »
- Next Generation Technologies
- »
-
Autonomous Farm Equipment Market Size Report, 2026-2033GVR Report cover

Autonomous Farm Equipment Market (2026 - 2033) Size, Share & Trends Analysis Report By Product, By Automation (Partially-autonomous, Fully Autonomous), By Application (Field Farming, Horticulture, Dairy Farming & Livestock Management), By Region, And Segment Forecasts
Market Size, 2025
$21.1BMarket Estimate, 2026
$22.3BMarket Forecast, 2033
$44.8BCAGR, 2026–2033
10.5%Autonomous Farm Equipment Market Summary
The global autonomous farm equipment market size was valued at USD 21.1 billion in 2025 and is projected to grow from USD 22.3 billion in 2026 to USD 44.8 billion by 2033, at a CAGR of 10.5% from 2026 to 2033. North America held 34.0% revenue share of the global autonomous farm equipment industry. Labor shortages in the farming sector, and an aging rural workforce, which are compelling farmers to seek automated solutions to maintain and enhance productivity, are driving market growth.
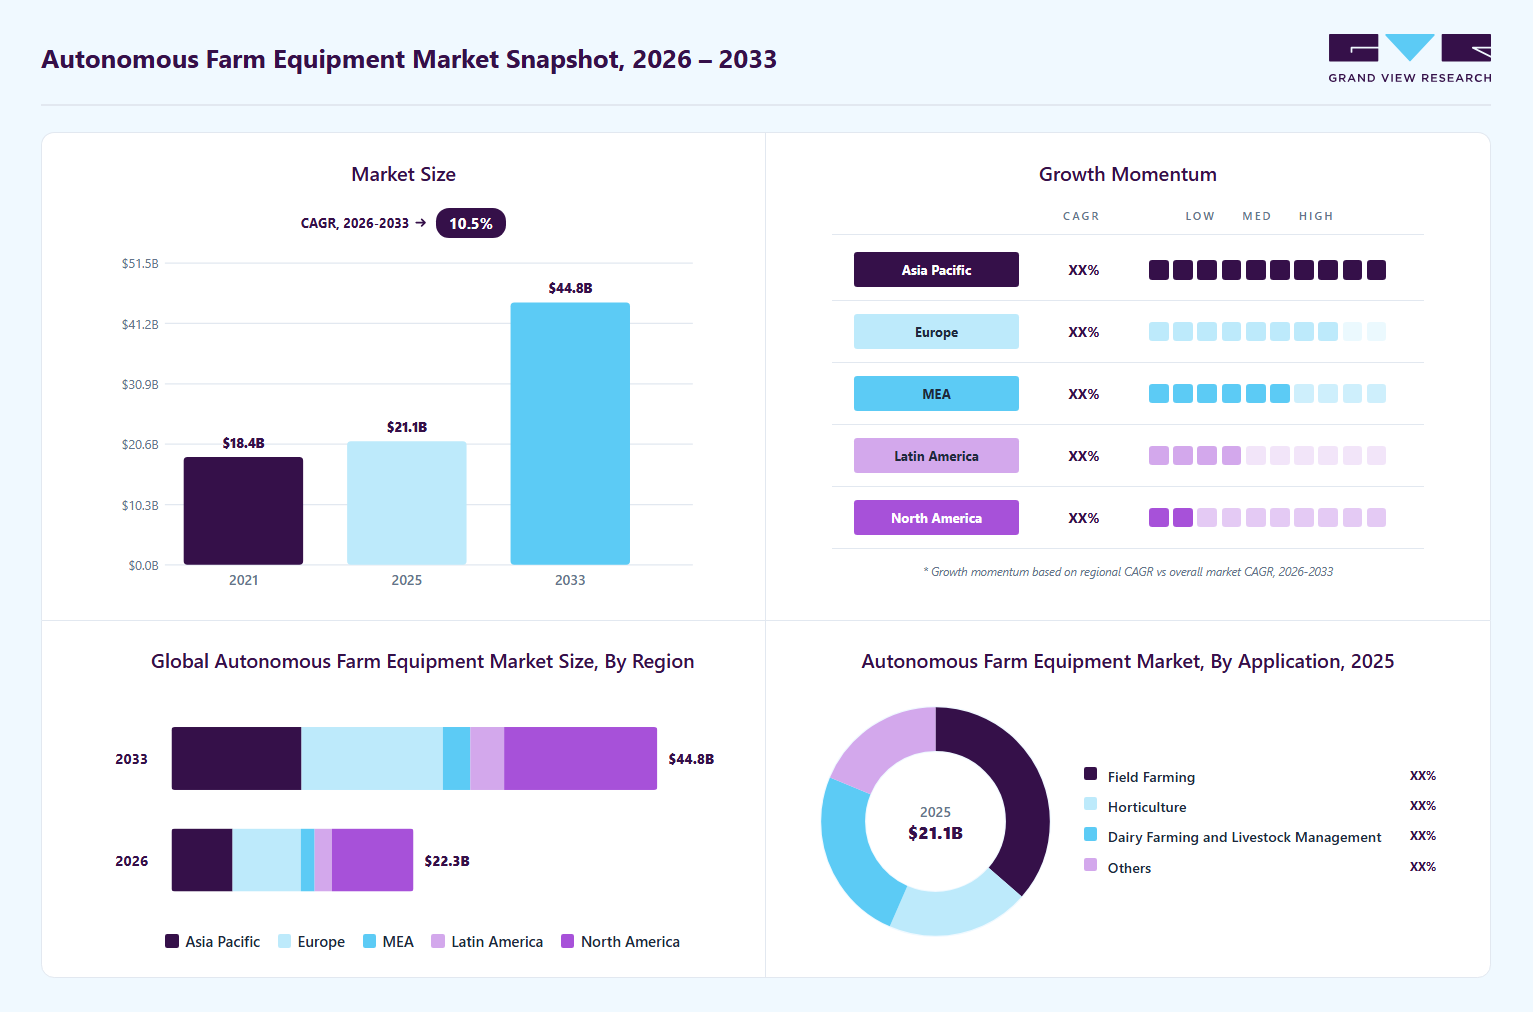 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Unmanned aerial vehicles (UAVs) segment held the largest revenue share of 17.1% in 2025 .
- By automation: Partially- autonomous segment held the largest revenue share in 2025.
- By application: Field farming segment held the largest revenue share in 2025.
Regional Highlights
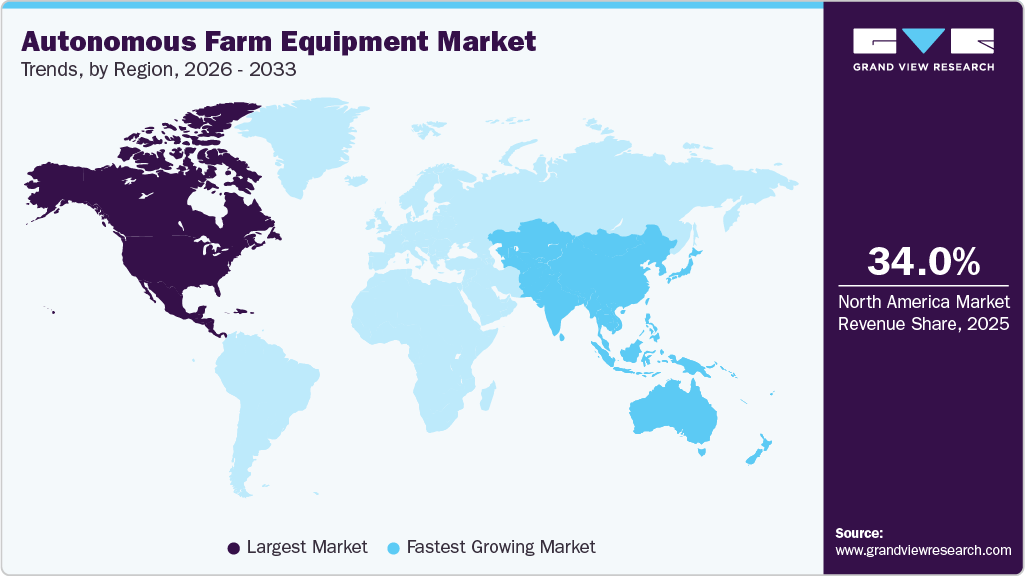
- Largest regional market: North America (34.0% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- The U.S. autonomous farm equipment industry is driven by rapid evolution of artificial intelligence, machine learning, and sensor technologies.
Market Size & Forecast
- Market size in 2025: USD 21.1 Billion
- Estimated market size in 2026: USD 22.3 Billion
- Projected market size by 2033: USD 44.8 Billion
- CAGR (2026-2033): 10.5%
Prism AI by Grand View Research Free to tryAsk a question about the autonomous farm equipment marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The rising adoption of precision agriculture and digital farming technologies is also significantly driving the autonomous farming industry. Modern autonomous systems integrate GPS navigation, sensors, machine learning algorithms, and real-time data analytics to enable accurate, intelligent decision-making. These technologies enable equipment to analyze field conditions and automatically adjust operations for optimal performance. Integration with the Internet of Things further enhances machine-to-machine communication and real-time monitoring capabilities. This improves efficiency in resource utilization, including water, fertilizers, and fuel. As smart farming ecosystems expand, autonomous equipment adoption continues to grow strongly.The increasing focus on reducing operational costs and improving farm profitability is another important driver of the autonomous farming market. Traditional farming operations require significant expenditure on labor, fuel, and equipment maintenance. Autonomous machines help reduce these costs by optimizing fuel consumption, minimizing human errors, and improving operational efficiency. They also enable better utilization of machinery through continuous operation and predictive maintenance features. This leads to higher return on investment for farmers over the long term. As cost pressures in agriculture continue to rise, autonomous equipment becomes a more economically attractive solution.
 To learn more about this report, Download Free Sample Report
The expansion of large-scale commercial farming operations is further supporting the growth of the autonomous farm equipment industry. Large agribusinesses and industrial farms manage extensive land areas that require efficient, scalable, and high-performance machinery. Autonomous equipment allows these operations to standardize farming practices across multiple fields and regions. It also supports centralized monitoring and control through digital farm management platforms. This improves coordination, reduces operational complexity, and enhances overall productivity. As farm consolidation increases globally, demand from commercial farming enterprises continues to strengthen.
The rapid advancement of artificial intelligence and machine learning technologies is also a key driver for the autonomous farm equipment industry. AI-enabled systems allow machines to learn from field data, recognize crop patterns, detect pests or diseases, and optimize operational decisions in real time. This improves accuracy and reduces dependency on manual intervention. Continuous improvements in computing power and sensor technology are making autonomous systems more reliable and cost-effective. Manufacturers are increasingly integrating AI capabilities into agricultural machinery to enhance automation levels. As AI adoption accelerates across industries, it is significantly boosting the evolution of autonomous farming systems.
Market Dynamics
The autonomous farm equipment industry is driven by rapid advancements in artificial intelligence, robotics, and sensor technologies, which are fundamentally transforming how agricultural operations are performed and managed. AI-powered systems enable farm equipment to analyze real-time field data, identify crop conditions, and make autonomous decisions without human intervention. This significantly improves operational precision in activities such as planting, spraying, irrigation, and harvesting. Robotics enhances the physical execution of farming tasks by enabling machines to perform repetitive and labor-intensive operations with high accuracy and consistency. As these technologies become more sophisticated, autonomous farm equipment is increasingly capable of operating in complex and variable agricultural environments. This technological evolution is a core driver accelerating the growth of the market.
The high upfront costs, which limit adoption, especially among small- and medium-scale farmers, are a significant restraint in the autonomous agriculture market. Advanced autonomous systems such as self-driving tractors, robotic harvesters, and AI-enabled sprayers require substantial initial investment because they integrate complex technologies, including sensors, artificial intelligence, robotics, and high-precision navigation systems. These technologies significantly increase the manufacturing cost compared to conventional agricultural machinery. As a result, the purchase price of autonomous equipment is often well beyond the financial capacity of many farmers, particularly in developing, price-sensitive agricultural markets. This high capital requirement creates a strong entry barrier and slows down widespread adoption. Consequently, cost remains one of the most critical challenges restricting market expansion.
The growing adoption of drone-integrated autonomous farming systems presents a significant opportunity for the autonomous farm equipment industry, as agriculture increasingly shifts toward highly connected, data-driven farming ecosystems. Drones equipped with advanced imaging, mapping, and sensing technologies are being integrated with autonomous ground equipment to create coordinated farming operations that improve accuracy and efficiency. This integration allows aerial data collection to directly inform ground-level actions such as seeding, spraying, irrigation, and harvesting. By combining aerial intelligence with autonomous machinery, farmers can achieve a more complete and real-time understanding of field conditions. This synergy enhances decision-making and enables highly precise farm management. In the U.S., the number of Federal Aviation Administration-registered agricultural drones rose significantly from around 1,000 in January 2024 to approximately 5,500 by mid-2025. These drones are mainly used for crop spraying, particularly in corn and soybean cultivation, and are especially useful in areas difficult for tractors or conventional aerial crop-dusting aircraft to reach.
Market Concentration & Characteristics
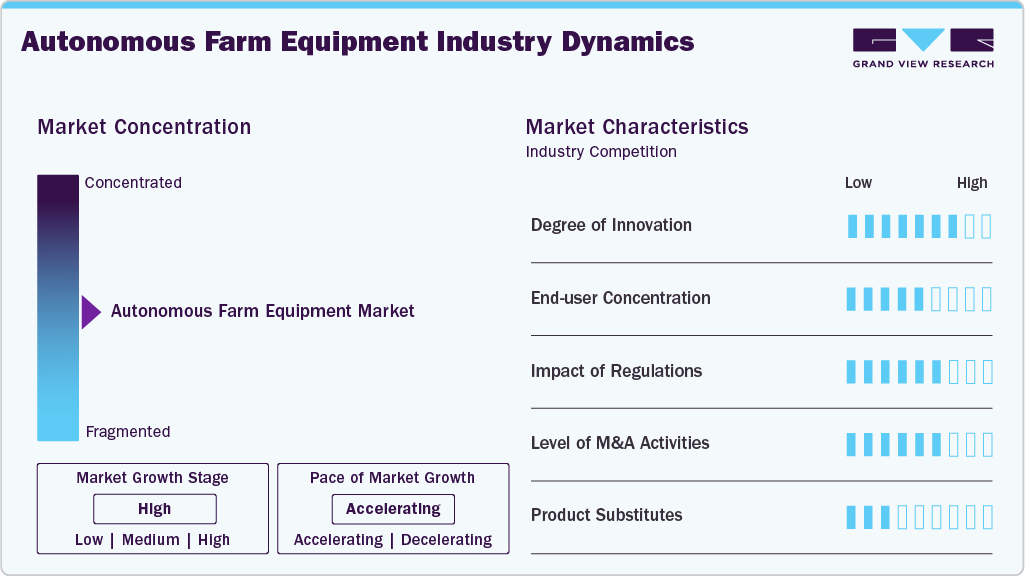
The autonomous farm equipment industry is concentrated, with major agricultural machinery manufacturers and precision farming technology providers leading the competitive landscape. Companies such as Deere & Company and CNH Industrial hold significant positions due to their strong automation capabilities, integrated precision agriculture platforms, and extensive dealer networks. Entry barriers are high because of large R&D investments, advanced AI and sensor requirements, and strict safety and regulatory standards.
The market is highly technology-driven, focusing on autonomous tractors, robotic harvesters, GPS-guided systems, and AI-enabled farm operations. Demand is primarily driven by rising labor shortages in agriculture, increasing pressure to improve farm productivity, and the growing adoption of precision farming practices. Advancements in machine vision, telematics, and autonomous navigation technologies are further accelerating market development.
 To learn more about this report, Download Free Sample Report
The industry is characterized by high upfront equipment costs, long replacement cycles, and dependency on large-scale farming operations for early adoption. Connectivity infrastructure, data accuracy, and compatibility with digital farm management systems are critical factors influencing automation efficiency. Adoption among small farmers remains relatively slow due to affordability challenges and limited technical expertise.
Product Insights
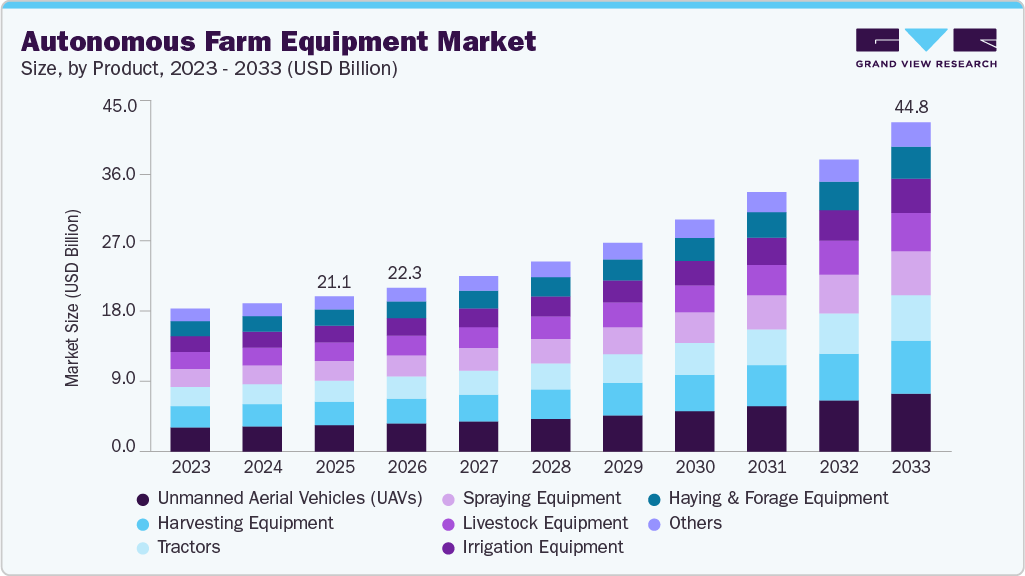
The unmanned aerial vehicles (UAVs) segment accounted for the largest market share of 17.1% in 2025. UAVs offer flexibility and efficiency in agricultural operations, particularly for monitoring and data collection. Their ability to cover large areas quickly and access difficult terrain makes them invaluable for precision agriculture practices. UAVs equipped with advanced sensors and imaging technologies provide farmers with high-resolution data on crop health, soil conditions, and pest infestations, enabling targeted interventions and resource optimization. The relatively lower initial investment compared to that of larger autonomous ground vehicles has accelerated UAV adoption across farms of all sizes.
The harvesting equipment segment is anticipated to grow at the fastest CAGR during the forecast period. The integration of Internet of Things and precision agriculture technologies is driving the harvesting equipment segment. Autonomous harvesters are increasingly connected to farm management platforms that provide real-time operational data, crop analytics, and predictive maintenance capabilities. Sensors integrated into harvesting equipment can monitor crop yield, moisture levels, and machine performance during operations. This data-driven approach helps optimize harvesting schedules and improve decision-making across farm operations. Connected harvesting systems also improve coordination with other autonomous equipment used in planting and crop management. As smart farming ecosystems continue expanding, autonomous harvesting equipment becomes a critical component of integrated agricultural automation.
Automation Insights
The partially- autonomous segment dominated the market in 2025. The advancement of sensor technologies, connectivity solutions, and digital farm management platforms is supporting the growth of the partially autonomous segment. Modern semi-autonomous machinery increasingly integrates with Internet of Things platforms that provide real-time monitoring and operational analytics. Farmers can track machine performance, field conditions, and resource usage through connected digital systems while still maintaining manual oversight when necessary. This hybrid approach improves operational visibility and decision-making without requiring full automation. It also allows farmers to become more familiar with autonomous technologies before transitioning toward fully autonomous operations. As digital agriculture ecosystems continue to evolve, partially autonomous equipment is expected to remain a strong growth driver within the market.
The fully autonomous segment is expected to register the fastest CAGR from 2026 to 2033. The growing demand for precision agriculture and resource optimization is supporting the adoption of fully autonomous farm equipment. Fully autonomous machines can apply fertilizers, pesticides, seeds, and water with extremely high accuracy based on real-time field analysis. This reduces resource wastage, lowers operational costs, and improves environmental sustainability. Precision automation also enhances crop uniformity and overall yield quality by ensuring consistent field operations. Farmers increasingly recognize that autonomous systems can deliver better productivity while minimizing human errors and inefficiencies. As sustainability and productivity optimization become critical agricultural priorities, fully autonomous solutions continue gaining strong market traction.
Application Insights
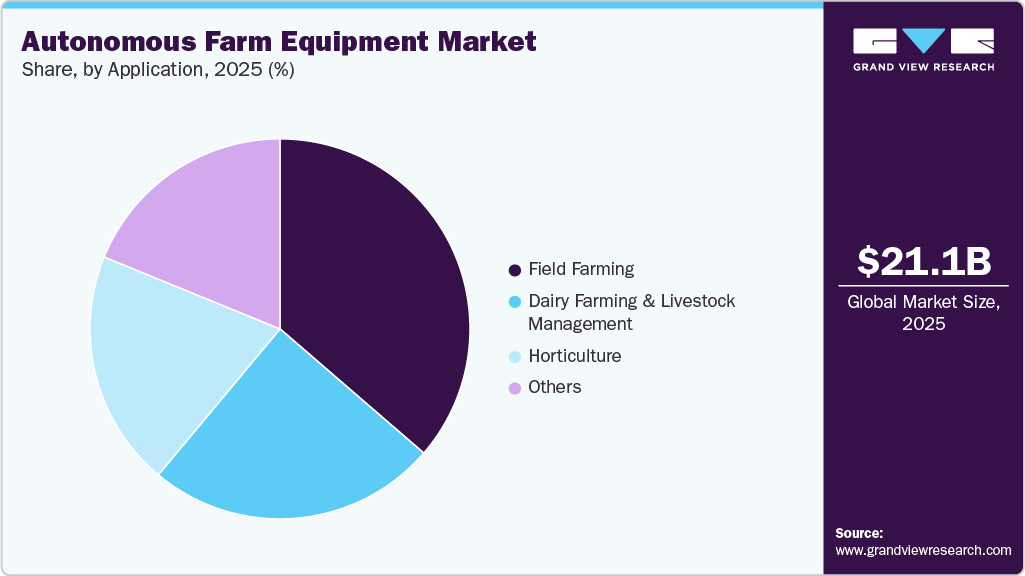
The field farming segment accounted for the largest market share in 2025. Field crops account for the largest share of global agricultural production, necessitating extensive mechanization and automation to meet growing food demands. The vast scale of field farming operations provides a compelling economic case for autonomous equipment adoption, as the potential for efficiency gains and cost savings is significantly amplified. Autonomous technologies in field farming, such as self-driving tractors, automated harvesters, and precision planting systems, have reached a higher level of maturity compared to other agricultural sectors, making them more reliable and attractive to farmers. The relatively uniform and predictable nature of field environments, compared to orchards or livestock farms, facilitates easier implementation and operation of autonomous systems. In addition, field farming faces acute labor shortages in many regions, driving the need for automated solutions. The integration of autonomous equipment with precision agriculture practices in field farming has demonstrated tangible benefits in resource optimization, yield improvement, and environmental sustainability, further cementing its market dominance.
 To learn more about this report, Download Free Sample Report
The dairy farming & livestock management segment is anticipated to register the fastest CAGR during the forecast period. The increasing commercialization and scaling of dairy and livestock farms are driving demand for autonomous equipment. Large-scale dairy farms require highly efficient systems capable of consistently and accurately managing hundreds or thousands of animals. Autonomous technologies help these farms standardize operations, reduce labor-intensive processes, and maintain productivity at scale. Automated systems also improve hygiene standards, feeding precision, and animal comfort, all of which contribute to better production outcomes. Large commercial farms are increasingly investing in robotics and automation to improve competitiveness and profitability. As livestock operations continue to consolidate into larger commercial enterprises, demand for autonomous equipment continues to grow strongly.
Regional Insights
North America autonomous farm equipment market dominated the global industry, accounting for 34.0% of revenue in 2025. This is due to a combination of technological leadership, favorable economic conditions, and structural factors in its agricultural sector. The region's advanced technological ecosystem, with strong research and development capabilities in robotics, AI, and precision agriculture, has fostered early adoption and innovation in autonomous farm equipment. Large-scale farming operations, prevalent in North America, provide an ideal testing ground and market for autonomous solutions, as the potential for efficiency gains and cost savings is significant. The region's acute labor shortages in agriculture accelerated the shift toward automation.
 To learn more about this report, Download Free Sample Report
U.S. Autonomous Farm Equipment Market Trends
The U.S. autonomous farm equipment industry is projected to grow significantly during the forecast period. The market in the U.S. is driven by the country's dominance in AI and machine learning, which enable sophisticated autonomous solutions. Farm consolidation into larger operations has increased the economic viability of high-tech equipment investments. The U.S. market also benefits from strong partnerships between tech companies and traditional agricultural equipment manufacturers, fostering innovation. In addition, the growing emphasis on sustainable farming practices and the need to optimize resource use in drought-prone regions are driving interest in precision agriculture technologies, including autonomous equipment.
Asia Pacific Autonomous Farm Equipment Market Trends
The autonomous farm equipment industry in Asia Pacific is expected to grow at the fastest CAGR from 2026 to 2033. Rapid urbanization and an aging rural population are exacerbating labor shortages in agriculture, driving demand for automated solutions. Governments across the region are implementing supportive policies and providing subsidies to modernize farming practices and boost agricultural productivity, thereby creating a favorable environment for the adoption of autonomous equipment. The region's diverse agricultural landscape, from small-scale farming to large-scale plantations, is spurring the development of scalable, adaptable autonomous technologies. Significant investments in digital infrastructure, including 5G networks, are enhancing connectivity in rural areas and facilitating the implementation of advanced farming technologies. The presence of emerging economies with large agricultural sectors, such as China and India, offers substantial market potential. These countries are experiencing rapid technological advancement and increasing rates of farm mechanization. In addition, the region's growing focus on precision agriculture to address food security concerns and environmental challenges is accelerating the uptake of autonomous farm equipment. As local manufacturers and tech companies enter the market, they are developing cost-effective solutions tailored to regional needs, further driving market growth in the Asia Pacific region.
The China autonomous farm equipment industry is driven by government support for smart agriculture and digital farming technologies. Chinese authorities are investing heavily in agricultural digitization programs, intelligent farming infrastructure, and rural technology development initiatives. Subsidies, financial incentives, and policy support programs encourage farmers and agribusinesses to adopt advanced autonomous machinery. Government-backed pilot projects and smart farming demonstration zones are also accelerating awareness and adoption of autonomous systems. These initiatives aim to improve agricultural efficiency, sustainability, and national food production capacity. As policy support continues to expand, autonomous farm equipment adoption is gaining stronger momentum across the country.
Europe Autonomous Farm Equipment Market Trends
The autonomous farm equipment industry in Europe is anticipated to grow steadily from 2026 to 2033. The region's emphasis on sustainable agriculture and precision farming practices has created a receptive environment for autonomous solutions. European farmers, facing labor shortages and pressure to increase productivity while reducing environmental impact, are increasingly turning to autonomous equipment. The market benefits from strong research and development capabilities, particularly in countries like Germany and the Netherlands, which are at the forefront of agricultural technology. EU policies supporting smart farming and digital agriculture have provided a favorable regulatory framework for market expansion. However, the fragmented nature of European agriculture, with varying farm sizes and products across countries, presents both challenges and opportunities for tailored autonomous solutions. The market is also influenced by stringent environmental regulations, which drive demand for equipment that optimizes resource use and reduces chemical inputs.
The autonomous farm equipment industry in the UK is expected to grow significantly during the forecast period. The increasing focus on sustainable, environmentally responsible agriculture is driving the autonomous farm equipment industry in the UK. Farmers are under growing pressure to reduce chemical use, optimize fuel consumption, and improve land management practices in line with environmental regulations and sustainability goals. Autonomous machinery helps achieve these objectives through precision application systems and optimized field operations. Equipment integrated with the Internet of Things enables real-time monitoring and more efficient use of agricultural inputs. This reduces environmental impact while improving productivity and operational control. As sustainability becomes a central priority in UK agriculture, demand for autonomous and precision-driven equipment is expected to grow steadily.
Key Autonomous Farm Equipment Company Insights
Some of the key companies operating in the autonomous farm equipment industry include Deere & Company and CLAAS KGaA mbH, among others.
-
John Deere, a key company in the agricultural machinery sector, has made significant strides in the autonomous farm equipment industry. John Deere integrates cutting-edge technology across a wide array of products, including autonomous tractors, combines, and precision farming solutions such as AutoTrac. These advancements not only enhance operational efficiency and yield but also reduce labor dependency and optimize resource management. With a strong global presence and extensive dealer network across North and South America, Europe, and Asia, John Deere caters to farmers worldwide, offering robust support and training for adopting autonomous technologies.
Agrobot and Naïo Technologies are some of the emerging market companies in the target market.
-
Agrobot, a robotic solution provider headquartered in Spain, has established itself as one of the emerging companies in the market by developing robots equipped with advanced sensors and AI algorithms for strawberry farms. These robots are designed to selectively pick ripe strawberries, improving efficiency and reducing labor costs for farmers. Agrobot's technology not only enhances productivity but also ensures higher quality and sustainability in berry farming practices. The company is actively expanding its presence globally, focusing on markets where strawberry production is prominent, such as North America and Europe.
Key Autonomous Farm Equipment Companies:
The following key companies have been profiled for this study on the autonomous farm equipment market.
-
AGCO Corporation
-
AgEagle Aerial Systems Inc
-
AGROBOT
-
CLAAS KGaA mbH
-
CNH Industrial
-
Deere & Company
-
Kubota Corporation
-
Mahindra & Mahindra
-
Naio Technologies
-
Raven Industries
-
Yanmar Co., Ltd.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weakness
Mature Players: Deere & Company; CNH Industrial; AGCO Corporation; Kubota Corporation
- Mature players in the autonomous farm equipment market focus on integrating AI, GPS, and precision farming technologies into machinery.
- They invest in autonomous tractors, harvesters, and smart spraying systems. Their solutions support large-scale farming operations and productivity optimization. They also expand through dealer networks and precision agriculture partnerships.
- Mature players benefit from strong global distribution and established farmer trust. Their equipment offers high operational efficiency and advanced automation features.
- Strong R&D capabilities support continuous innovation in autonomous farming systems. Integration with precision agriculture platforms improves long-term customer retention.
- These companies face high manufacturing and equipment development costs. Autonomous systems often require strong connectivity and technical expertise.
- High equipment prices limit adoption among small-scale farmers. Regulatory and safety concerns can also slow automation in some regions.
Emerging Players: AGROBOT; Naio Technologies; AgEagle Aerial Systems Inc
- Emerging players focus on fully autonomous and electric-powered farming equipment. They emphasize robotics, AI vision systems, and autonomous navigation technologies.
- Many target labor-intensive farming activities, such as weeding and spraying. Their strategy centers on sustainable and precision-driven farming operations.
- Emerging players offer innovative, flexible automation solutions for modern farming. Their systems help reduce labor dependency and operational costs.
- Strong focus on AI and robotics enables faster technology development. They also respond quickly to changing precision agriculture needs.
- Emerging players have limited production capacity and distribution reach. Their technologies may face reliability concerns in large-scale field operations.
- Heavy reliance on external funding undermines long-term scalability. Limited brand awareness also reduces adoption in traditional farming markets.
Recent Developments:
-
In April 2026, Kubota Corporation invested in Agtonomy, a company focused on developing automation platforms and precision agriculture solutions. Through this investment, both companies aim to strengthen their collaboration and advance smart farming technologies. Kubota plans to support Agtonomy’s business expansion while accelerating the adoption of intelligent agricultural solutions through strategic partnerships.
-
In February 2024, John Deere launched a substantial lineup of new agricultural equipment at the Commodity Classic tradeshow. This includes high-horsepower autonomy-ready tractors, C-Series air carts designed to boost seeding productivity, AI-enabled weed sensing technology on Hagie STS sprayers, and new features in the S7 Series combined. The launch highlights John Deere's dedication to customer-focused solutions and advancing agricultural technology to address changing industry needs.
-
In February 2024, Naïo Technologies and CAMSO partnered to develop agricultural robots with electrically driven tracks, enhancing flotation, accessibility, and flexibility while reducing carbon emissions. Naïo contributes its expertise in autonomy technologies, while CAMSO brings its materials knowledge to create high-performance, soil-respectful products. This collaboration aims to improve productivity, promote decarbonization, and preserve resources and soil.
Autonomous Farm Equipment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 21.1 billion
Estimated Market size in 2026
USD 22.3 billion
Projected Market size in 2033
USD 44.8 billion
Growth rate
CAGR of 10.5% from 2026 to 2033
Actual data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company share, competitive landscape, growth factors, and trends
Segments covered
Product, automation, application, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; China; India; Japan; Australia; South Korea; Southeast Asia; Brazil; UAE; Saudi Arabia; South Africa
Key companies profiled
Deere & Company; CNH Industrial; AGCO Corporation; Kubota Corporation; CLAAS KGaA mbH; Yanmar Co., Ltd.; Raven Industries; Naio Technologies; AgEagle Aerial Systems Inc.; Mahindra & Mahindra; AGROBOT
Customization scope
Free report customization (equivalent to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Autonomous Farm Equipment Market Report Segmentation
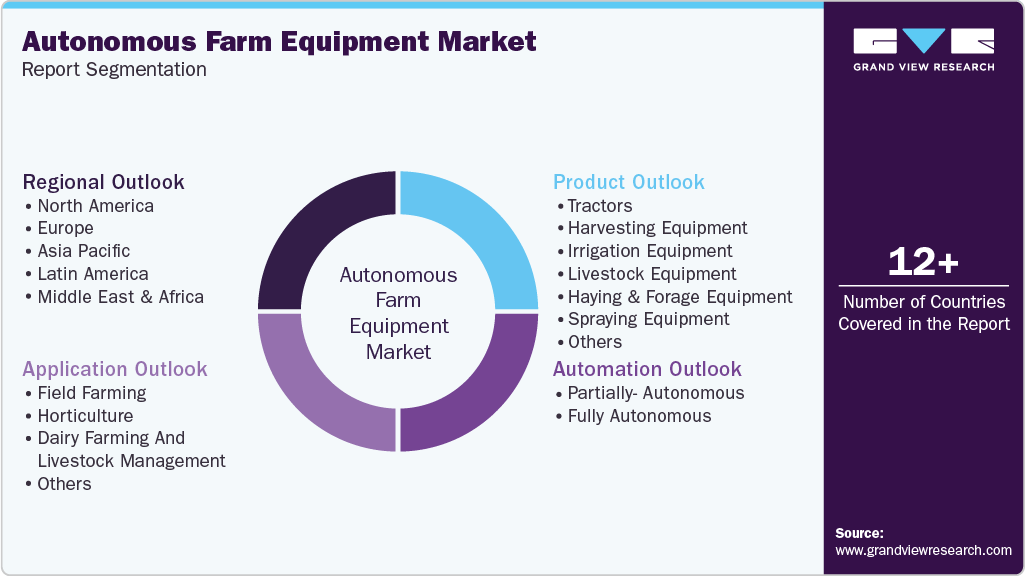
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global autonomous farm equipment market report based on product, automation, application, and region.
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Tractors
-
Harvesting Equipment
-
Irrigation Equipment
-
Livestock Equipment
-
Haying & Forage Equipment
-
Spraying Equipment
-
Unmanned Aerial Vehicles (UAVs)
-
Others
-
-
Automation Outlook (Revenue, USD Billion, 2021 - 2033)
-
Partially- Autonomous
-
Fully Autonomous
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Field Farming
-
Horticulture
-
Dairy Farming and Livestock Management
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
Southeast Asia
-
-
Latin America
-
Brazil
-
-
Middle East & Africa
-
UAE
-
Saudi Arabia
-
South Africa
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Autonomous Farm Equipment Market Opportunity Assessment for Smart Agriculture Technology Provider
Analysis of adoption trends for autonomous tractors, robotic harvesters, and driverless spraying systems across large-scale farming operations
Evaluation of operational challenges including labor shortages, rising fuel costs, inconsistent field productivity, and manual equipment dependency
Assessment of demand for AI-enabled navigation, GPS-guided operations, and sensor-based precision farming systems
Identified high-growth farming segments investing in automation and precision agriculture
Supported positioning around labor efficiency, operational productivity, and input optimization
Enabled prioritization of customers with higher readiness for autonomous farming technologies
Autonomous Machinery Integration Strategy for Agricultural Equipment Manufacturer
Identification of pain points including interoperability limitations, connectivity gaps in rural areas, and high equipment acquisition costs
Evaluation of demand for semi-autonomous and fully autonomous equipment capable of performing plowing, seeding, spraying, and harvesting tasks
Reduced operational inefficiencies using connected and automated field workflows
Enhanced differentiation through multi-machine coordination and precision operation features
Smart Farming Automation Commercialization for Agri-Tech Solutions Provider
Analysis of AI-driven field automation applications including autonomous navigation, obstacle detection, predictive maintenance, and real-time field analytics
Evaluation of adoption barriers such as regulatory uncertainty, farmer training requirements, and limited technical support infrastructure
Expanded commercialization opportunities through service-based automation models
Reduced equipment downtime using predictive maintenance and remote diagnostics
Frequently Asked Questions About This Report
Some key players operating in the autonomous farm equipment market include Deere & Company, CNH Industrial, AGCO Corporation, Kubota Corporation, CLAAS KGaA mbH, Yanmar Co., Ltd., Raven Industries, Naio Technologies, AgEagle Aerial Systems Inc, Mahindra & Mahindra, and AGROBOT.
Asia Pacific is the fastest-growing region over the forecast period.
The global autonomous farm equipment market size was estimated at USD 21.1 billion in 2025 and is expected to reach USD 22.3 billion in 2026.
The global autonomous farm equipment market is expected to grow at a compound annual growth rate of 10.5% from 2026 to 2033 to reach USD 44.8 billion by 2033.
North America dominated with a 34.0%revenue share in 2025.
Key factors include the rising adoption of precision agriculture and digital farming technologies
The unmanned aerial vehicles segment led with a 17.1% revenue share in 2025, while harvesting equipment is the fastest-growing segment.
The partially- autonomous segment held the highest market share in 2025. while fully autonomous is the fastest-growing segment.
The field farming segment held the highest market share in 2025, while the dairy farming & livestock management is the fastest-growing segment.
About the Author(s)
Next Generation Technologies Research Team
Technology · Next Generation TechnologiesThis report was authored by the next generation technologies research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the next generation technologies segment of the technology industry. All findings are based on proprietary technology databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


