
- Home
- »
- Paints, Coatings & Printing Inks
- »
-
Aviation Adhesives & Sealants Market Size, Industry Report, 2018-2025GVR Report cover

Aviation Adhesives and Sealants Market (2018 - 2025) Analysis, By Technology (Solvent Based, Water Based), By Resin (Epoxy, Silicon, PU), By Product, By Region, And Segment Forecasts
Industry Insights
The global aviation adhesives and sealants market size was valued at USD 685.8 million in 2016 and is likely to register a CAGR of over 6.2% over the forecast period. Technological advancements in the sector coupled with increasing demand for aircraft are likely to drive the market by 2025. Changing customer preferences and trends along with growing research and development activities are expected to drive the market over the forecast period.
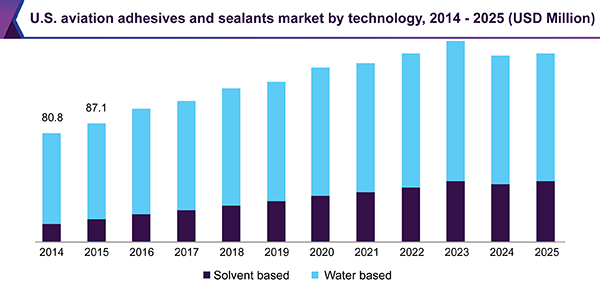 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Product demand for aviation adhesives and sealants is expected to witness substantial growth owing to evolving technology including the use of polyurethanes and silicon, especially due to the heat and pressure bearing attributes offered by these materials. The growing adoption of these new technologies due to the distinct advantages offered by them is likely to drive the market demand over the forecast period. Rising demand for air travel in regions including North America, Europe, and Asia Pacific is expected to positively influence the industry growth.
However, uncertainty in investments in the airline manufacturing sector, especially for commercial and military aviation applications is likely to restrain market growth.
Technology Insights
In terms of technology, the market has been segmented into solvent-based and water-based products. Abundant availability of raw materials for manufacturing water-based adhesives and sealants is a key factor that is likely to boost the segment growth. A large number of consumers are moving toward water-based solvents as the products are ideal for porous and non-porous substrates and find wide application in numerous sectors.
The solvent-based technology segment was valued at USD 226.1 million in 2016. The segment is projected to emerge as the fastest-growing over the forecast period due to the robust initial bond strength depending on the polymer formulation of the product.
Resin Insights
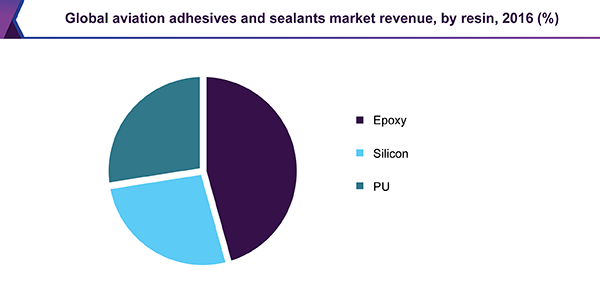
Epoxy resin segment held the maximum share in the global market in 2016 on account of superior mechanical properties, strong anti-corrosion attributes, and high resistance to degradation & thermal stress over a longer period of time. These attributes have significantly contributed toward the increased adoption of epoxy resins in the manufacturing of aviation adhesives and sealants.
 To learn more about this report, Download Free Sample Report
Silicon resin segment is projected to witness a growth of 7.0% by 2025, owing to its increasing adoption in the aircraft manufacturing industry. Silicon resins have a harder surface in comparison to soft rubber coating usually offered by silicone. This attribute gives silicon adhesives and sealants a longer shelf life and stronger glaze in comparison to other variants available in the market. The polyurethane resins segment was valued at USD 187.6 million in 2016. The resins are resistant to oil and chemicals & grease, which makes them nearly impenetrable as adhesives and sealants on aircraft. The resins are abrasion resistant and do not tear away easily.
Product Insights
In terms of product, the market has been segmented into adhesives and sealants. Sealants product segment dominated the market in 2016 and the trend is likely to continue over the forecast period. In terms of revenue, the segment is likely to be valued at USD 696.1 million by 2025. On the other hand, adhesives are projected to register a CAGR of 5.8% over the forecast period due to an increase in aircraft manufacturing.
Sealants typically have a higher elongation in comparison to adhesives, although they have lower strength to corrosion. When sealants are applied between two substrates possessing varied thermal coefficients of expansion, or different elongation under physical stress, they are required to possess suitable elongation and flexibility. Sealants usually contain some inert filler material and are formulated by using elastomer to achieve the required elongation and flexibility.
End-use Insights
General aviation was the fastest-growing end-use application in 2016 and is expected to register a 6.5% CAGR over the forecast period. Increasing per capita income coupled with the willingness of consumers to spend on air travel has significantly triggered the demand for new aircraft, which in turn, is likely to further boost the growth of general and commercial aviation sectors.
Commercial aviation was the largest end-use application in 2016, valued at over USD 270.5 million. The decrease in oil prices has impacted jet fuel prices leading to reduced fuel expenses. In addition, it has also significantly contributed to air travel operators’ bottom-line. The military aviation segment is likely to be valued at USD 390.1 million by 2025. Uncertainty in military spending by countries including the U.S. and France among others is predicted to contribute to sluggish market growth.
Regional Insights
The U.S. market accounted for 77.8% of North American revenue in 2016 due to technological advancements and increasing demand from the military aviation industry. The growing use of solvent-based products in defense and commercial aircraft manufacturing sectors is also likely to boost industry growth over the forecast period.
The demand for aviation adhesives and sealants in Asia Pacific was valued at USD 253.3 million in 2016. The growth can be attributed to the research & development activities undertaken to manufacture high-quality products to cater to increasing demand from aircraft manufacturers, especially in China. Asia Pacific is predicted to be the largest market over the forecast period. Changing consumer preferences for eco-friendly products and government support through incentives and financial aids are expected to positively impact the market growth in Europe.
Competitive Insights
Key players in the market include 3M; Henkel AG; PPG Industries; Illinois Tool Works; Huntsman International; Bostik; Dow Corning; H.B. Fuller; Hexcel Corporation; Royal Adhesives; and Sealants among others.
The aviation adhesives and sealants manufacturers are increasingly focusing on developing innovative and effective products at affordable prices coupled with growing technological advancements. These developments are likely to help in increasing the market share by 2025. Companies are making large-scale investments in research & development to augment the product quality.
Report Scope
Attribute
Details
Base year for estimation
2016
Actual estimates/Historical data
2014 and 2015
Forecast period
2017 - 2025
Market representation
Volume in Kilotons, Revenue in USD Million, and CAGR from 2017 to 2025
Regional scope
North America, Europe, Asia Pacific, South & Central America, and Middle East & Africa
Country scope
U.S., Canada, Germany, U.K., France, Russia, Italy, China, India, Japan, and South Korea, Australia, Iran, Israel, Brazil, and Argentina
Report coverage
Volume forecast, revenue forecast, competitive landscape, growth factors, and trends
15% free customization scope (equivalent to 5 analyst working days)
If you need specific market information, which is not currently within the scope of the report, we will provide it to you as a part of customization
Segments Covered in the ReportThis report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest trends and opportunities in each of the sub-segments from 2014 to 2025. For the purpose of this study, Grand View Research has segmented the Aviation adhesives and sealants market on the basis of technology, resin, product, end use, and region:
-
Technology Outlook (Volume, Kilotons; Revenue, USD Million; 2014 - 2025)
-
Solvent-based
-
Water-based
-
-
Resin Outlook (Volume, Kilotons; Revenue, USD Million; 2014 - 2025)
-
Epoxy
-
Silicon
-
PU
-
-
Product Outlook (Volume, Kilotons; Revenue, USD Million; 2014 - 2025)
-
Adhesives
-
Sealants
-
-
End-use Outlook (Volume, Kilotons; Revenue, USD Million; 2014 - 2025)
-
General aviation
-
Commercial
-
Military
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million; 2014 - 2025)
-
North America
-
The U.S.
-
Canada
-
-
Europe
-
Germany
-
The U.K.
-
France
-
Russia
-
Italy
-
Rest of Europe
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Rest of Asia Pacific
-
-
South & Central America
-
Brazil
-
Argentina
-
-
The Middle East and Africa
-
Iran
-
Israel
-
-
About the Author(s)
Paints, Coatings & Printing Inks Research Team
Bulk Chemicals · Paints, Coatings & Printing InksThis report was authored by the paints, coatings & printing inks research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the paints, coatings & printing inks segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst -

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


