
- Home
- »
- Renewable Chemicals
- »
-
Bio-based Polycarbonate Market Size & Share Report, 2033GVR Report cover
![Bio-based Polycarbonate Market (2026 - 2033)Report]()
Bio-based Polycarbonate Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Optical Grade, General Purpose Grade), By End Use (Transportation, Electrical And Electronics), By Region, And Segment Forecasts
Market Size, 2025
$79.2MMarket Estimate, 2026
$85.9MMarket Forecast, 2033
$189.4MCAGR, 2026–2033
12.0%Bio-based Polycarbonate Market Summary
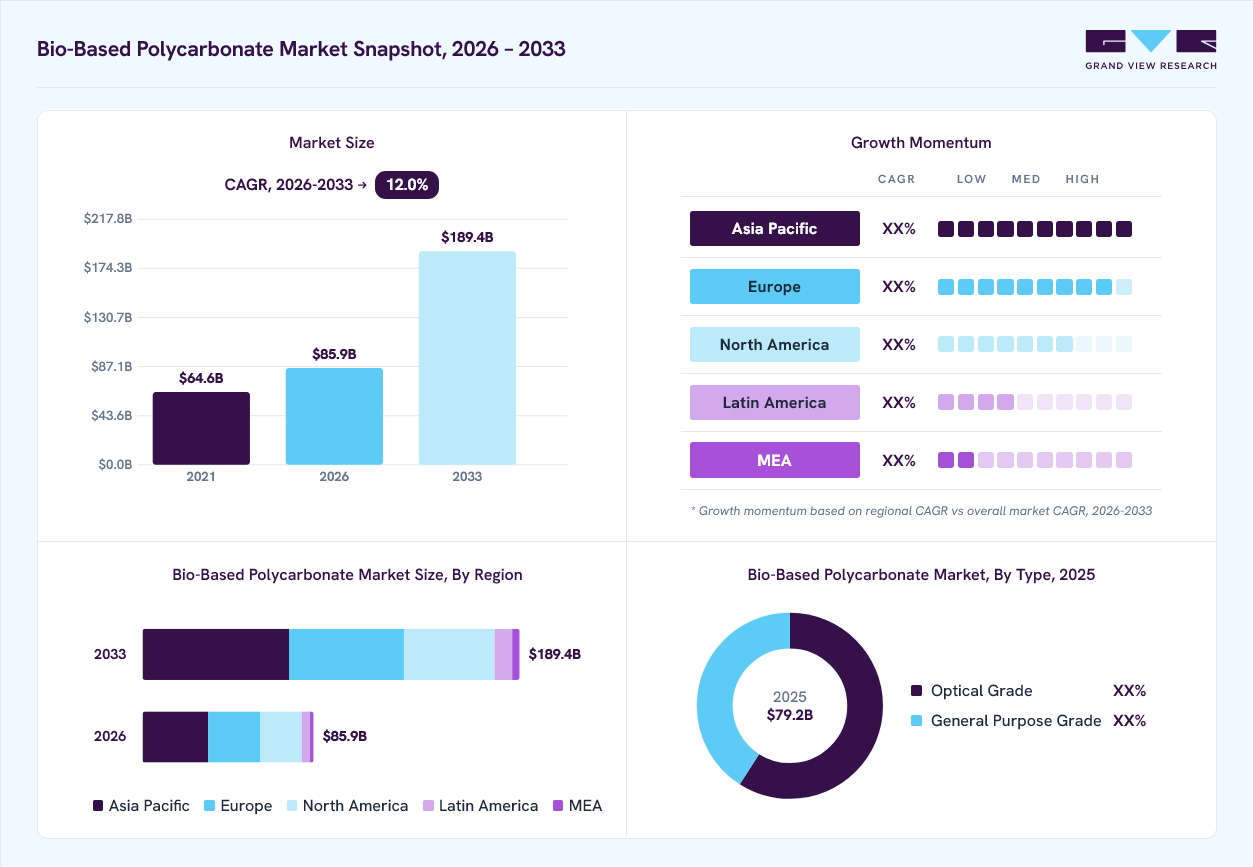
The global bio-based polycarbonate market size was valued at USD 79.2 million in 2025 and is projected to grow from USD 85.9 million in 2026 to USD 189.4 million by 2033, growing at a CAGR of 12.0% from 2026 to 2033. Asia Pacific dominated the market, accounting for a revenue share of 38.2% in 2024. The rising adoption of thermoplastic industrial applications across various end-use industries, along with increasing awareness regarding the environmental impacts of petrochemical waste disposal, is positively influencing the growth of the bio-based polycarbonate (PC) market.
Key Market Trends & Insights
- By type: Optical grade segment dominated the market, with a revenue share of 59.0% in 2025.
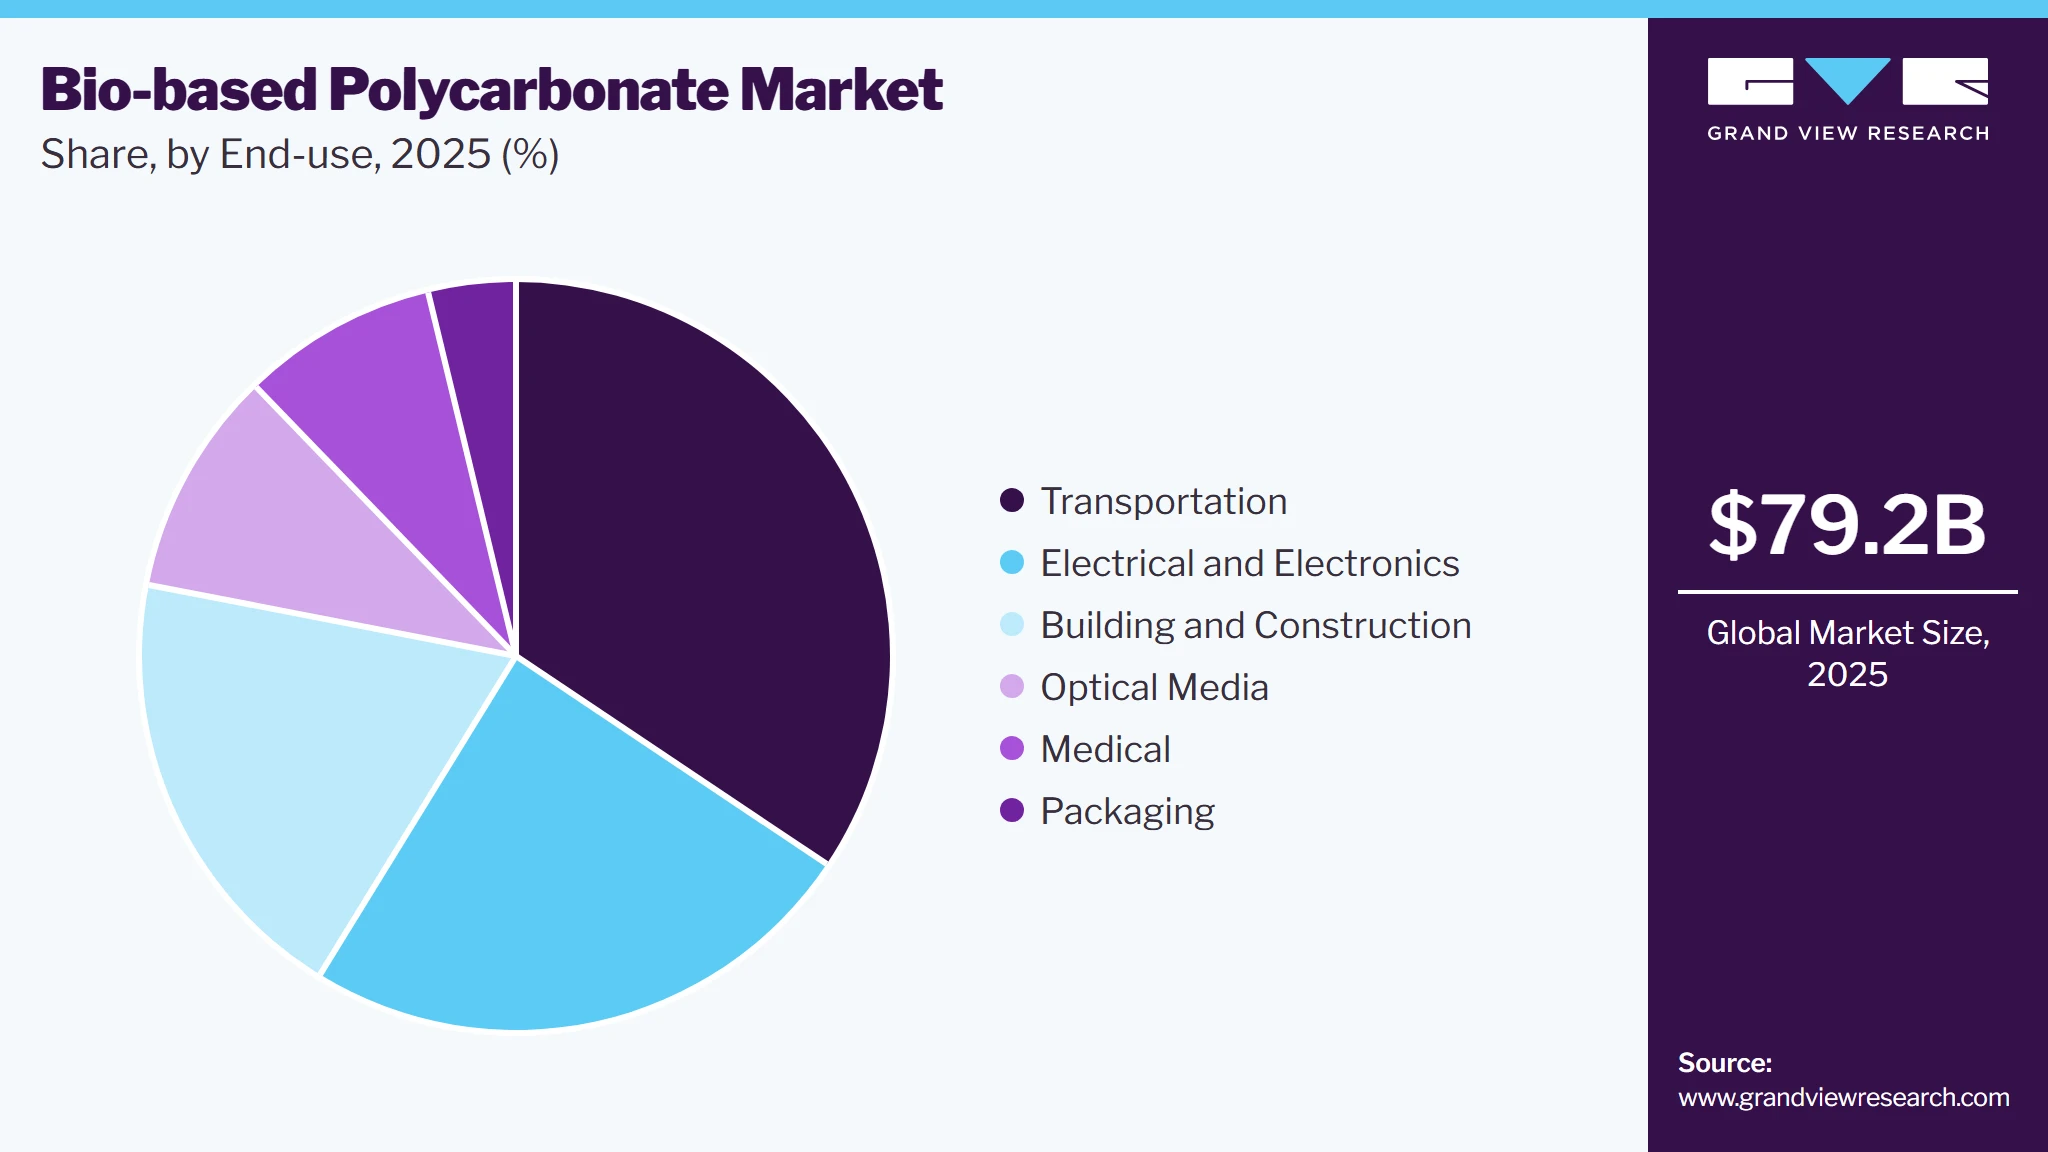
- By end use: Transportation segment accounted for the largest revenue share of 34.4% in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (38.2% revenue share, 2025)
- By country: China held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 79.2 Million
- Estimated market size in 2026: USD 85.9 Million
- Projected market size by 2033: USD 189.4 Million
- CAGR (2026-2033): 12.0%
Three ways to get this report
Buy it, customize it, or ask a question.Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Growing thermoplastic industrial applications and increased awareness about the environmental impact of petrochemical disposals are projected to fuel global bio-based polycarbonate (PC) growth in the coming years. The U.S. market for bio-based PC is projected to witness growth due to awareness regarding environmental concerns, technological improvements, regulatory measures, and the shift in consumer preferences for bio-based products. Bio-based polycarbonate is very effective, accounting for its properties such as high thermal resistance, hardness, and transparency. These products help in reducing the carbon footprint due to their high bio-content.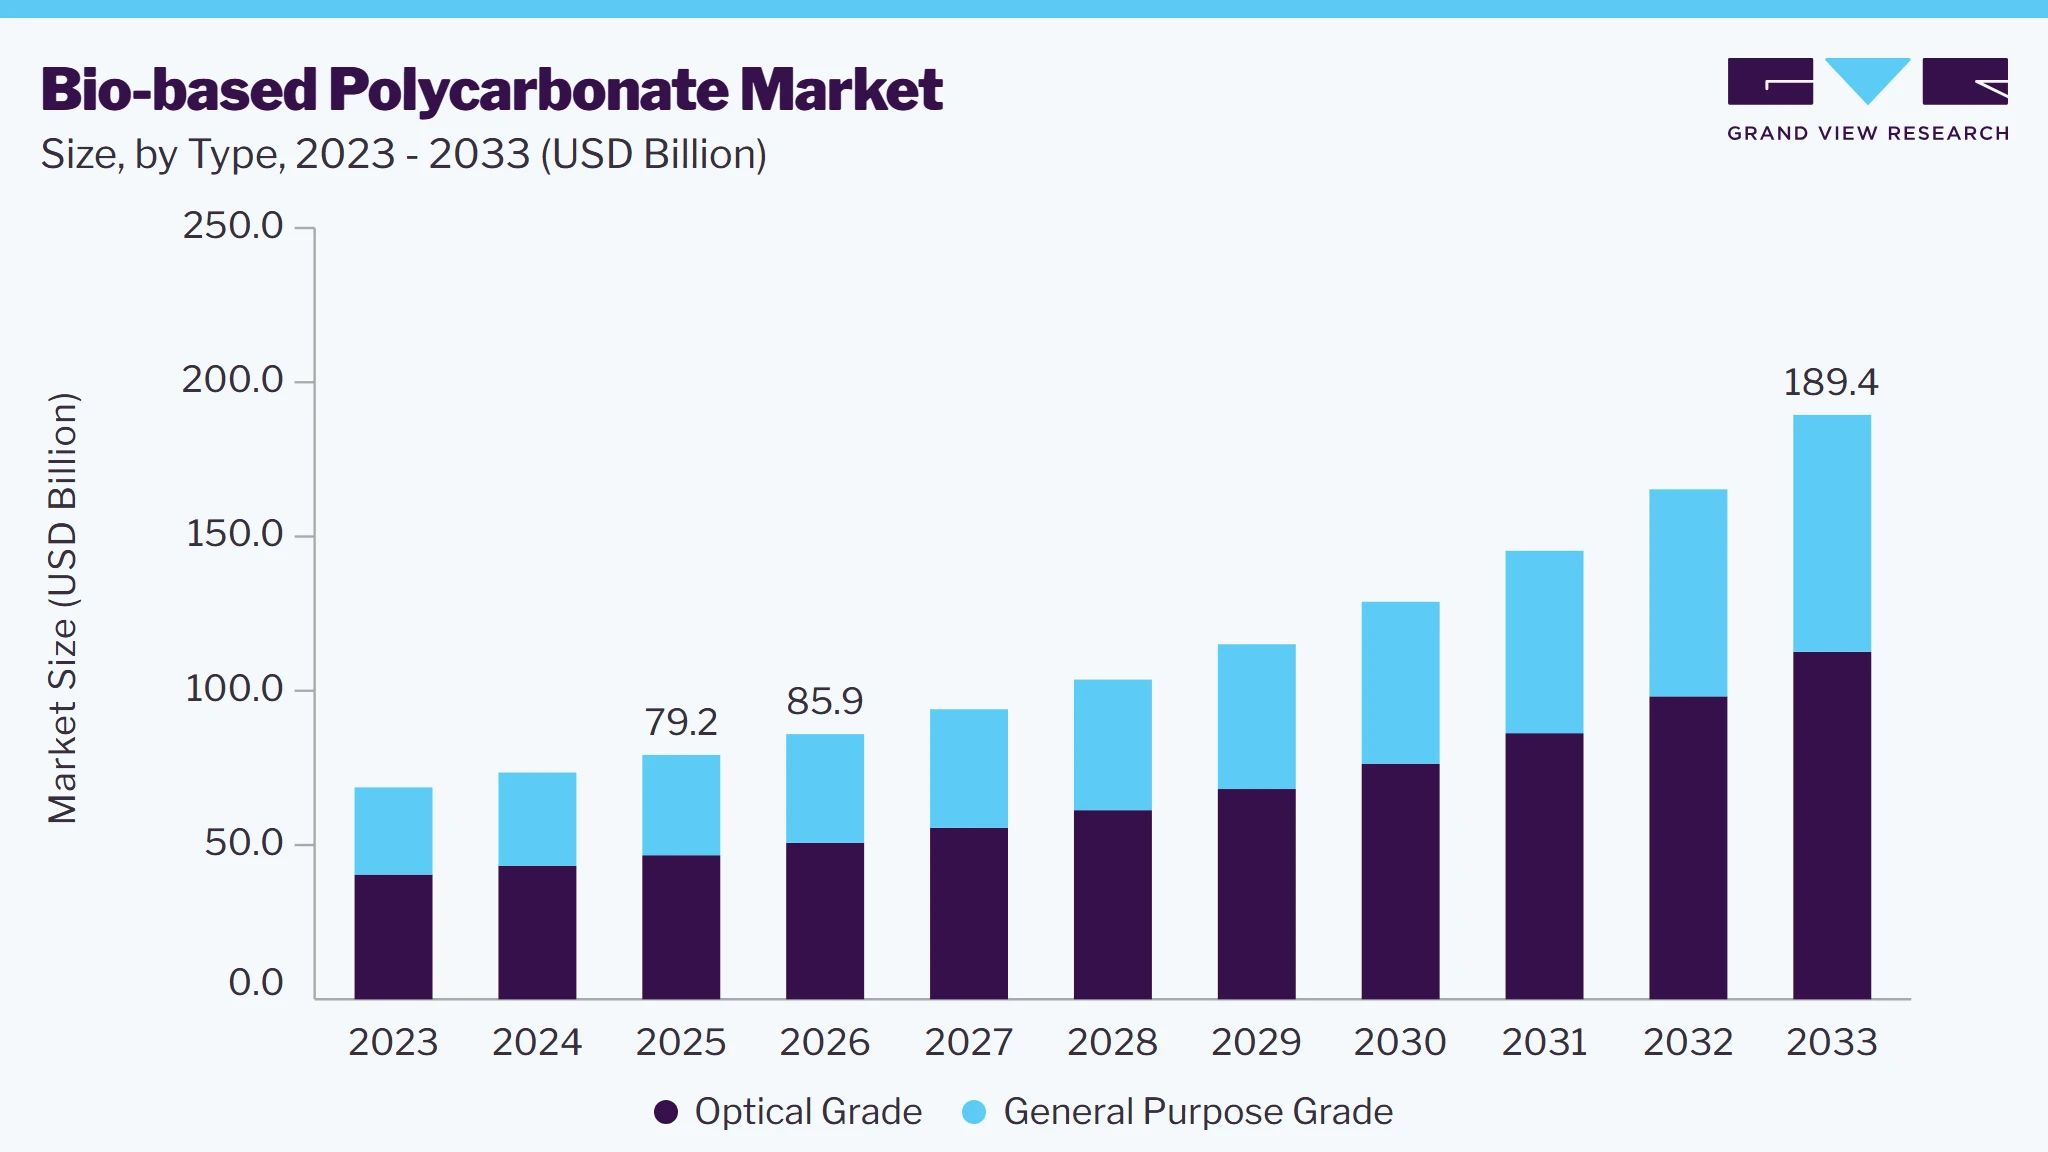
The market is seeing increased traction as industries move toward sustainable alternatives to fossil-based plastics. Bio-based polycarbonate, derived from renewable sources like plant sugars, has been growing in popularity due to its reduced environmental impact and alignment with carbon reduction goals. As consumer awareness and demand for eco-friendly products rise, bio-based polycarbonate is gaining recognition in sectors such as automotive, electronics, and packaging. Furthermore, as regulatory pressures intensify, especially in Europe and North America, manufacturers are increasingly investing in bio-based materials. These shifts are driving R&D activities and partnerships among industry players to create polycarbonate options that offer both performance and environmental advantages.
Market Dynamics
The bio-based polycarbonate market is evolving from an emerging sustainable material segment into an important part of the broader bio-based plastics and circular economy landscape. Increasing environmental concerns, supportive regulations, and technological progress are driving market growth. Rising demand for eco-friendly and low-carbon materials is further supporting adoption across industries. Bio-based polycarbonate offers strong thermal resistance, durability, hardness, and optical clarity, making it a viable alternative to fossil-based options while reducing carbon emissions. However, higher production costs and limited scalability continue to challenge widespread commercialization despite growing use in automotive, electronics, packaging, and consumer goods applications.
The bio-based polycarbonate market is witnessing strong growth due to increasing demand from the consumer electronics and advanced digital device industries, where lightweight, durable, and high-performance materials are essential. Bio-based polycarbonate is widely used in laptops, smartphones, and other smart devices for casings, structural components, and protective layers due to its excellent strength, impact resistance, and optical clarity. In addition, growing adoption in IoT devices, wearables, camera lenses, and display components is further supporting market expansion, particularly where precision and transparency are critical.
The rapid advancement of high-end processors, semiconductors, and connected technologies is further accelerating demand for advanced engineering plastics in miniaturized and high-performance applications. Government incentives promoting electronics manufacturing and domestic production are also encouraging investment in new facilities, boosting material consumption. Moreover, continuous innovation in IoT devices and ongoing technological upgrades across smart consumer electronics are strengthening the long-term adoption of bio-based polycarbonate as a sustainable alternative in this high-growth industry.
High production costs remain a key restraint for the bio-based polycarbonate market. The manufacturing process depends on complex extraction and refining of bio-based feedstocks, along with limited production infrastructure, which increases overall production expenses compared to conventional petrochemical-based polycarbonate. As a result, bio-based polycarbonate often faces a clear cost disadvantage in price-sensitive applications. In addition, the lack of large-scale production and limited economies of scale further restrict cost optimization. Dependency on specific bio-based raw materials, which may experience price and supply fluctuations, also adds to cost instability, thereby limiting faster commercialization and widespread market adoption.
The growing focus on sustainable and high-performance construction materials is creating significant opportunities for the bio-based polycarbonate market. Increasing demand for durable, lightweight, and environmentally responsible materials in modern building applications is driving the adoption of bio-based polycarbonate in roofing panels, glazing systems, skylights, facades, and other structural components. Bio-based polycarbonate offers excellent impact resistance, thermal stability, transparency, and long-term durability, making it well-suited for energy-efficient and sustainable construction projects. As the construction industry advances toward green building standards and carbon reduction goals, collaboration between material manufacturers, construction companies, and sustainable building solution providers is expected to accelerate the development and commercialization of advanced bio-based polycarbonate applications.
Analyst Perspective
The bio-based polycarbonate market is expected to develop from a niche sustainable materials segment into an important part of the bio-based plastics industry over the next decade. Growth will be supported by rising demand from automotive, electronics, construction, packaging, and consumer goods sectors seeking sustainable, high-performance materials. Technological advancements, supportive regulations, and corporate sustainability goals will encourage adoption. Companies with strong innovation capabilities, strategic partnerships, and efficient supply chains will gain a competitive advantage, while high production costs, feedstock limitations, and competition from alternative materials will remain key market challenges.
Type Insights
Based on type, the optical grade segment led the market with the largest revenue share of 59.0% in 2025, owing to its increased adoption in high-precision applications, particularly in the electronics and automotive sectors, where optical clarity and environmental responsibility are crucial. Optical grade bio-based polycarbonate offers similar clarity and light transmission properties as conventional optical plastics but with the added benefit of a reduced environmental impact. This makes it particularly appealing for use in lenses, light covers, and smartphone displays, which demand high-quality, clear materials. As consumer electronics and automotive industries face regulatory and market pressure to reduce carbon emissions, they are increasingly sourcing sustainable materials.
The growing demand for sustainable and versatile materials across a variety of applications is a significant driver for general-purpose bio-based polycarbonate. This type is widely used in products where strength, durability, and environmental compatibility are essential but where optical clarity is not a primary concern, such as in housing parts, containers, and construction materials. The shift toward greener products in consumer goods and industrial applications has increased interest in bio-based alternatives that offer similar durability and heat resistance to traditional polycarbonate but with lower environmental impact.
End Use Insights
Based on the end use, the transportation segment led the market with the largest revenue share of 34.4% in 2025, driven by the shift toward sustainable, lightweight materials that enhance fuel efficiency and reduce emissions. Bio-based polycarbonate provides a robust yet lightweight alternative to metal and traditional petrochemical plastics, making it particularly advantageous for automotive components such as dashboards, headlamp lenses, and interior panels. As regulatory pressures for reduced vehicle emissions grow, especially in North America and Europe, automakers are increasingly integrating materials that support sustainability goals.
In the electrical and electronics industry, the push for environmentally friendly, high-performance materials is a key driver for the use of bio-based polycarbonate. This material’s excellent insulation properties, combined with its durability and resistance to high temperatures, make it well-suited for electronic housings, circuit boards, and components. As consumers increasingly prioritize eco-friendly electronics, manufacturers are under pressure to reduce their carbon footprint across all production stages, from materials to manufacturing processes. Bio-based polycarbonate not only meets the stringent safety and functional requirements for electronic components but also aligns with the growing trend of using sustainable materials in consumer and industrial electronics.
Regional Insights
The North America bio-based polycarbonate market is driven by the corporate and consumer preferences for sustainable materials. Many industries, including automotive, electronics, and packaging, are embracing green materials to meet corporate sustainability targets and align with environmental goals. Furthermore, several major companies in the U.S. and Canada have set ambitious carbon neutrality targets, which are pushing them to explore bio-based alternatives. Bio-based polycarbonate, with its versatility and lower environmental impact, is becoming a favored option, especially as regulatory bodies implement more policies to curb plastic waste. These factors collectively support the growth of bio-based polycarbonate adoption across North America.
U.S. Bio-based Polycarbonate Market Trends
The bio-based polycarbonate market in the U.S. is gaining momentum largely due to federal and state policies that promote the use of sustainable materials. Recent government incentives, grants, and R&D funding are enabling companies to explore renewable materials to replace fossil-fuel-derived plastics. Bio-based polycarbonate offers a strong alignment with these policy trends, making it increasingly popular in sectors like automotive, healthcare, and electronics. Consumer interest in environmentally conscious products further supports this shift, particularly among millennials and Gen Z, who are increasingly driving purchasing trends toward sustainable options. This combination of policy support and changing consumer preferences is propelling bio-based polycarbonate adoption in the U.S.
Europe Bio-based Polycarbonate Market Trends
The bio-based polycarbonate market in Europe is driven by strict environmental regulations and aggressive targets to reduce greenhouse gas emissions. The European Union’s Green Deal and Circular Economy Action Plan emphasize the importance of renewable and recyclable materials, creating a favorable environment for bio-based polycarbonate growth. Industries across Europe, from automotive to packaging, are transitioning to sustainable materials to meet EU targets and avoid penalties associated with excessive carbon emissions.
Asia Pacific Bio-based Polycarbonate Market Trends
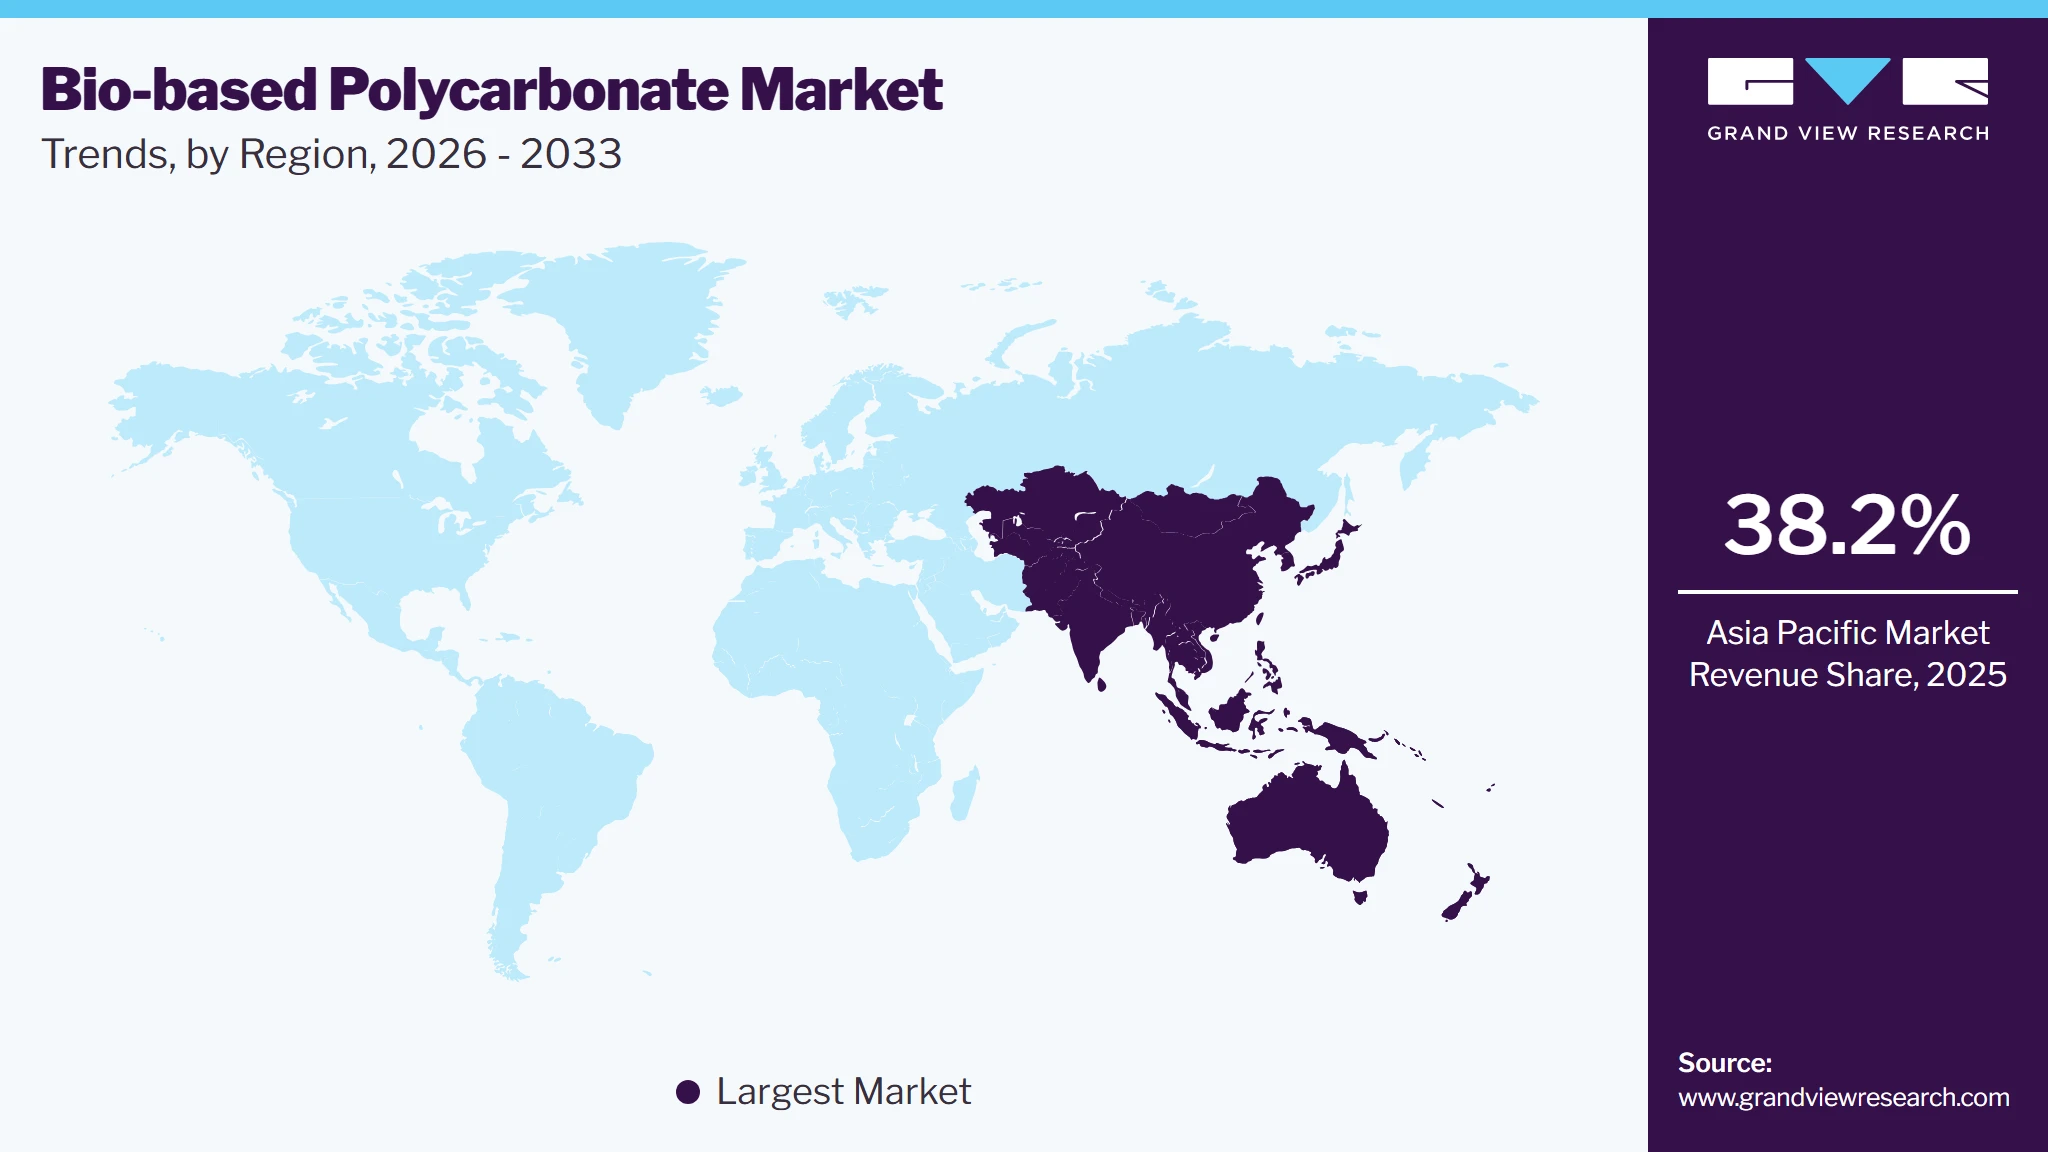
Asia Pacific dominated the bio-based polycarbonate market with the largest revenue share of 38.2% in 2025, which is attributed to the growing focus on sustainable development and eco-friendly materials is a significant driver for the bio-based polycarbonate market. Rapid industrialization, especially in countries like India, Japan, and South Korea, has brought attention to the environmental impact of conventional plastics. Governments are encouraging industries to adopt renewable materials through initiatives promoting greener supply chains and reduced emissions. Bio-based polycarbonate fits well within this framework as it allows manufacturers to produce high-performance products while reducing their carbon footprint.
The bio-based polycarbonate market in China accounted for the largest market revenue share in the Asia Pacific in 2025. China bio-based polycarbonate market is driven by the push for advanced manufacturing and reduced reliance on fossil-based materials. The Chinese government has introduced environmental policies that encourage companies to reduce emissions and invest in cleaner technologies. Bio-based polycarbonate, offering high-performance qualities similar to traditional polycarbonate but with lower environmental impact, is gaining traction in the automotive, electronics, and packaging sectors. As China positions itself as a global leader in sustainable manufacturing, domestic companies are increasingly adopting bio-based materials to enhance their international competitiveness and align with the nation’s environmental goals. This industrial shift is expected to drive significant growth for bio-based polycarbonate within China’s rapidly modernizing economy.
Key Bio-based Polycarbonate Company Insights
The market is highly competitive, with several key players dominating the landscape. Major companies include Mitsubishi Chemical Corp., Covestro AG; SABIC; and TEIJIN LIMITED. The market is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their products.
Key Bio-based Polycarbonate Companies:
The following are the leading companies in the bio-based polycarbonate market.
-
Mitsubishi Chemical Corp
-
Covestro AG
-
SABIC
-
TEIJIN LIMITED
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Covestro AG; SABIC; Mitsubishi Chemical Corp.)
- Broad portfolios of polycarbonate and engineering plastics serving automotive, electronics, construction, consumer goods, medical, and industrial applications.
- Significant investment in bio-based feedstocks, circular economy initiatives, renewable raw materials, and low-carbon polycarbonate technologies.
- Integrated manufacturing capabilities, advanced polymer R&D, and global distribution networks supporting large-scale commercialization of sustainable polycarbonate solutions.
- Strong expertise in polymer science, materials engineering, and high-performance thermoplastics development.
- Established global production footprints, diversified customer bases, and long-term relationships with OEMs, electronics manufacturers, and industrial users.
- Extensive technical capabilities, brand recognition, and vertically integrated operations enhance product quality, innovation capacity, supply chain reliability, and market competitiveness.
- High capital expenditure requirements associated with bio-based raw material sourcing, production scale-up, and sustainability-focused innovation programs.
- Exposure to fluctuations in feedstock availability, raw material costs, and demand cycles across automotive, electronics, and construction industries may impact profitability.
- Regulatory compliance obligations, evolving sustainability standards, and pricing pressures from conventional fossil-based polycarbonate producers may affect margins and commercialization timelines.
Emerging Player (TEIJIN LIMITED)
- Focus on the development and commercialization of advanced engineering plastics and sustainable material solutions for automotive, electronics, construction, and consumer goods applications.
- Significant investment in material innovation, lightweight technologies, bio-based polymer research, and environmentally responsible manufacturing processes.
- Emphasis on strategic collaborations, technology development, and portfolio diversification to strengthen its position in next-generation sustainable materials markets.
- Strong expertise in high-performance materials, advanced polymer engineering, and lightweight solutions.
- Established relationships with automotive and electronics manufacturers support the adoption of sustainable material alternatives.
- Ability to leverage innovation capabilities and sustainability initiatives to address growing demand for low-carbon, high-performance plastics across multiple end-use industries.
- Limited commercial presence in the bio-based polycarbonate segment compared to leading global polycarbonate producers.
- Commercialization of bio-based materials requires substantial R&D investment, regulatory compliance, and long qualification cycles.
- Higher production costs and evolving supply chain requirements for renewable feedstocks may impact large-scale market penetration and competitiveness against conventional polycarbonate materials.
Recent Developments
-
In February 2023, Mitsui Chemicals and Mitsubishi Gas Chemical Company announced a collaboration to produce and market biomass polycarbonate products as part of their commitment to achieving carbon neutrality by 2050. Mitsubishi Gas Chemical (MGC) started manufacturing biomass PC using biomass-derived bisphenol A (BPA) provided by Mitsui Chemicals. This BPA is developed under Mitsui's BePLAYER brand.
-
In January 2023, Teijin Limited announced that it is now producing and marketing polycarbonate resin made from BPA, having received ISCC PLUS certification for these sustainable products. This makes Teijin the first Japanese company to achieve this certification for polycarbonate resin. The new biomass-based resins maintain the same physical properties as traditional petroleum-based resins, making them suitable for applications like automotive headlamps and electronic components.
Bio-based Polycarbonate Market Report Scope
Report Attribute
Details
Market size in 2025
USD 79.2 million
Estimated market size in 2026
USD 85.9 million
Projected market size by 2033
USD 189.4 million
Growth rate
CAGR of 12.0% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD thousand/million, volume in tons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, end use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Netherlands; China; India; Japan; South Korea; Australia; Malaysia; Singapore; Thailand; Vietnam; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
Mitsubishi Chemical Corp.; Covestro AG; SABIC; TEIJIN LIMITED
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Bio-based Polycarbonate Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global bio-based polycarbonate market report based on type, end use, and region:

-
Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Optical Grade
-
General Purpose Grade
-
-
End Use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Transportation
-
Electrical and Electronics
-
Building and Construction
-
Optical Media
-
Medical
-
Packaging
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Netherlands
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
Malaysia
-
Singapore
-
Thailand
-
Vietnam
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The bio-based polycarbonate market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each bio-based polycarbonate segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Optical Grade
Revenue is captured through the sale of bio-based polycarbonate grades designed for applications requiring exceptional optical clarity, light transmission, and dimensional stability. Demand is supported by their use in lenses, lighting components, optical storage media, display panels, transparent glazing, and other high-precision applications where visual performance, durability, and sustainability are critical requirements.
General Purpose Grade
Revenue is captured through the supply of bio-based polycarbonate grades used across a broad range of industrial, consumer, and commercial applications requiring a balance of impact resistance, thermal stability, processability, and durability. Sales are driven by their versatility and suitability for transportation, construction, packaging, electronics, and consumer goods applications seeking sustainable alternatives to conventional polycarbonate materials.
Segment - End Use
Revenue Capture Definition
Transportation
Revenue is captured through the use of bio-based polycarbonate in automotive, rail, aerospace, and mobility applications, including interior components, glazing systems, lighting assemblies, and structural parts. Demand is supported by the material’s lightweight properties, impact resistance, durability, and ability to contribute to vehicle sustainability and fuel-efficiency objectives.
Electrical and Electronics
Revenue is captured through the supply of bio-based polycarbonate used in electronic housings, connectors, display components, electrical enclosures, battery systems, and consumer electronic devices. Growth is driven by demand for materials offering electrical insulation, dimensional stability, heat resistance, mechanical strength, and sustainability benefits in advanced electronic and electrical applications.
Building and Construction
Revenue is captured through the sale of bio-based polycarbonate used in roofing panels, skylights, facades, glazing systems, partitions, and other construction materials. Demand is supported by its transparency, impact resistance, weatherability, thermal performance, and suitability for sustainable and energy-efficient building projects.
Optical Media
Revenue is captured through the use of bio-based polycarbonate in optical storage devices, display technologies, lenses, lighting systems, and other applications requiring superior optical performance. Sales are driven by the material’s high clarity, light transmission, dimensional precision, and durability while supporting the growing preference for renewable and low-carbon materials.
Medical
Revenue is captured through bio-based polycarbonate applications in medical devices, diagnostic equipment, surgical instruments, drug delivery systems, and healthcare packaging. Demand is supported by the material’s strength, transparency, sterilization compatibility, biocompatibility characteristics, and ability to meet stringent healthcare performance and sustainability requirements.
Packaging
Revenue is captured through the use of bio-based polycarbonate in reusable packaging, specialty containers, protective packaging solutions, and high-performance consumer packaging applications. Growth is supported by demand for durable, lightweight, and sustainable materials that provide product protection, extended service life, and alignment with circular economy and environmental objectives.
Estimation Model
Layer Name
Key Question
Description
Top-Down Bio-Based Polycarbonate Demand Scan Layer
What defines market boundaries?
This layer starts with global bio-based polycarbonate demand across automotive, electronics, construction, packaging, consumer goods, and other industrial applications, then filters consumption intensity based on sustainability initiatives, bio-based plastics adoption, manufacturing activity, regulatory support for renewable materials, and investments in low-carbon product development.
End Use Mix Validation Layer
Where is demand generated?
This layer evaluates the demand split between automotive, electronics, construction, packaging, consumer goods, and specialty applications to align market revenue with performance requirements, durability expectations, lightweighting objectives, transparency needs, and end-use-specific material specifications.
Material Consumption Conversion Layer
Who captures market revenue?
This layer converts end-product production volumes into bio-based polycarbonate revenue by applying material consumption rates, bio-based polymer adoption levels, component-specific usage patterns, resin grade requirements, processing technologies, and qualification standards across key end-use industries.
Regional Commercial Cross-Check Layer
How are assumptions validated?
This layer validates demand concentration by comparing Asia Pacific’s manufacturing base and electronics production, North America’s sustainable materials innovation and green building investments, and Europe’s circular economy policies and bio-based plastics adoption trends to verify regional market assumptions and growth forecasts.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Regional Segmentation
Detailed market breakdown across North America, Europe, Asia Pacific, Central & South America, and the Middle East & Africa, including country-level analysis for key markets such as the U.S., Germany, France, China, Japan, South Korea, and India. Assessment of regional demand drivers, regulatory frameworks, sustainability initiatives, and manufacturing capabilities.
Enabled identification of high-growth regions, investment hotspots, regulatory opportunities, and regional demand variations for bio-based polycarbonate applications.
Trade Assessment
Analysis of global trade flows, import-export trends, key producing and consuming countries, supply chain structures, feedstock sourcing patterns, and regional trade dependencies impacting bio-based polycarbonate production and distribution.
Enabled assessment of supply chain risks, sourcing opportunities, trade competitiveness, and regional market accessibility for strategic expansion decisions.
Opportunity Assessment
Identification of high-growth opportunities across sustainable construction materials, lightweight automotive components, consumer electronics, renewable energy applications, and advanced packaging solutions. Evaluation of emerging technologies, regulatory incentives, and sustainability-driven demand trends shaping future market potential.
Delivered actionable insights for market entry, investment prioritization, product development, and long-term growth strategies aligned with evolving sustainability requirements.
Frequently Asked Questions About This Report
Some key players operating in the bio-based polycarbonate market include Mitsubishi Chemical Corp., Covestro AG, SABIC, and TEIJIN LIMITED
Key factors that are driving the bio-based polycarbonate market growth include growing thermoplastics industrial applications and increased awareness about the environmental impact of petrochemical disposals.
The bio-based polycarbonate market was valued at USD 79.2 million in 2025 and is estimated at USD 85.9 billion in 2026.
The global bio-based polycarbonate market is expected to grow at a CAGR of 12.0% from 2026 to 2033, reaching USD 189.4 billion by 2033.
Optical grade segment dominated the market, with a revenue share of 59.0% in 2025, owing to its increased adoption in high-precision applications, particularly in the electronics and automotive sectors, where optical clarity and environmental responsibility are crucial.
The Asia Pacific bio-based polycarbonate market accounted for the largest share of 38.2% market size in 2025.
Transportation segment accounted for the largest revenue share of 34.4% in 2025.
About the Author(s)
Renewable Chemicals Research Team
Specialty & Chemicals · Renewable ChemicalsThis report was authored by the renewable chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the renewable chemicals segment of the specialty & chemicals industry. All findings are based on proprietary specialty & chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst


Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


