
- Home
- »
- Plastics, Polymers & Resins
- »
-
Biodegradable Plastic Films Market Size, Share Report, 2033GVR Report cover

Biodegradable Plastic Films Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Starch Blends, Polylactic Acid, PHA), By Application (Bags, Wrapping Films, Liners), By End-use (Food & Beverage, Healthcare), By Region, And Segment Forecasts
Market Size, 2025
$1.3BMarket Estimate, 2026
$1.4BMarket Forecast, 2033
$2.2BCAGR, 2026–2033
6.8%Biodegradable Plastic Films Market Summary
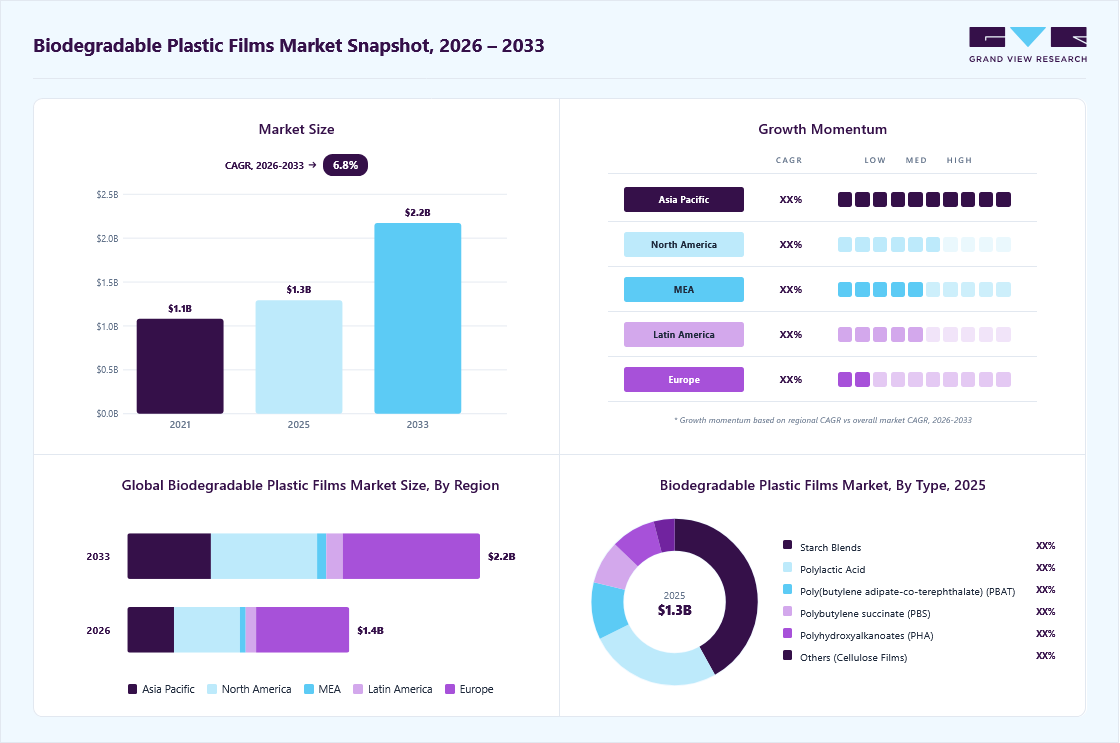
The global biodegradable plastic films market size was valued at USD 1.3 billion in 2025 and is projected to grow from USD 1.4 billion in 2026 to USD 2.2 billion by 2033, at a CAGR of 6.8% from 2026 to 2033. The market in Europe dominated with a revenue share of 42.4% in 2025. Growing environmental awareness and increasingly stringent regulations aimed at reducing plastic waste are positively influencing the biodegradable plastic films market growth.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Starch blends segment held the largest market share of 41.9% in 2025.
- By application: Bags segment held the largest market share of 36.3% in 2025.
- By end use: Food & beverage segment held the largest market share of 33.8% in 2025.
Regional Highlights
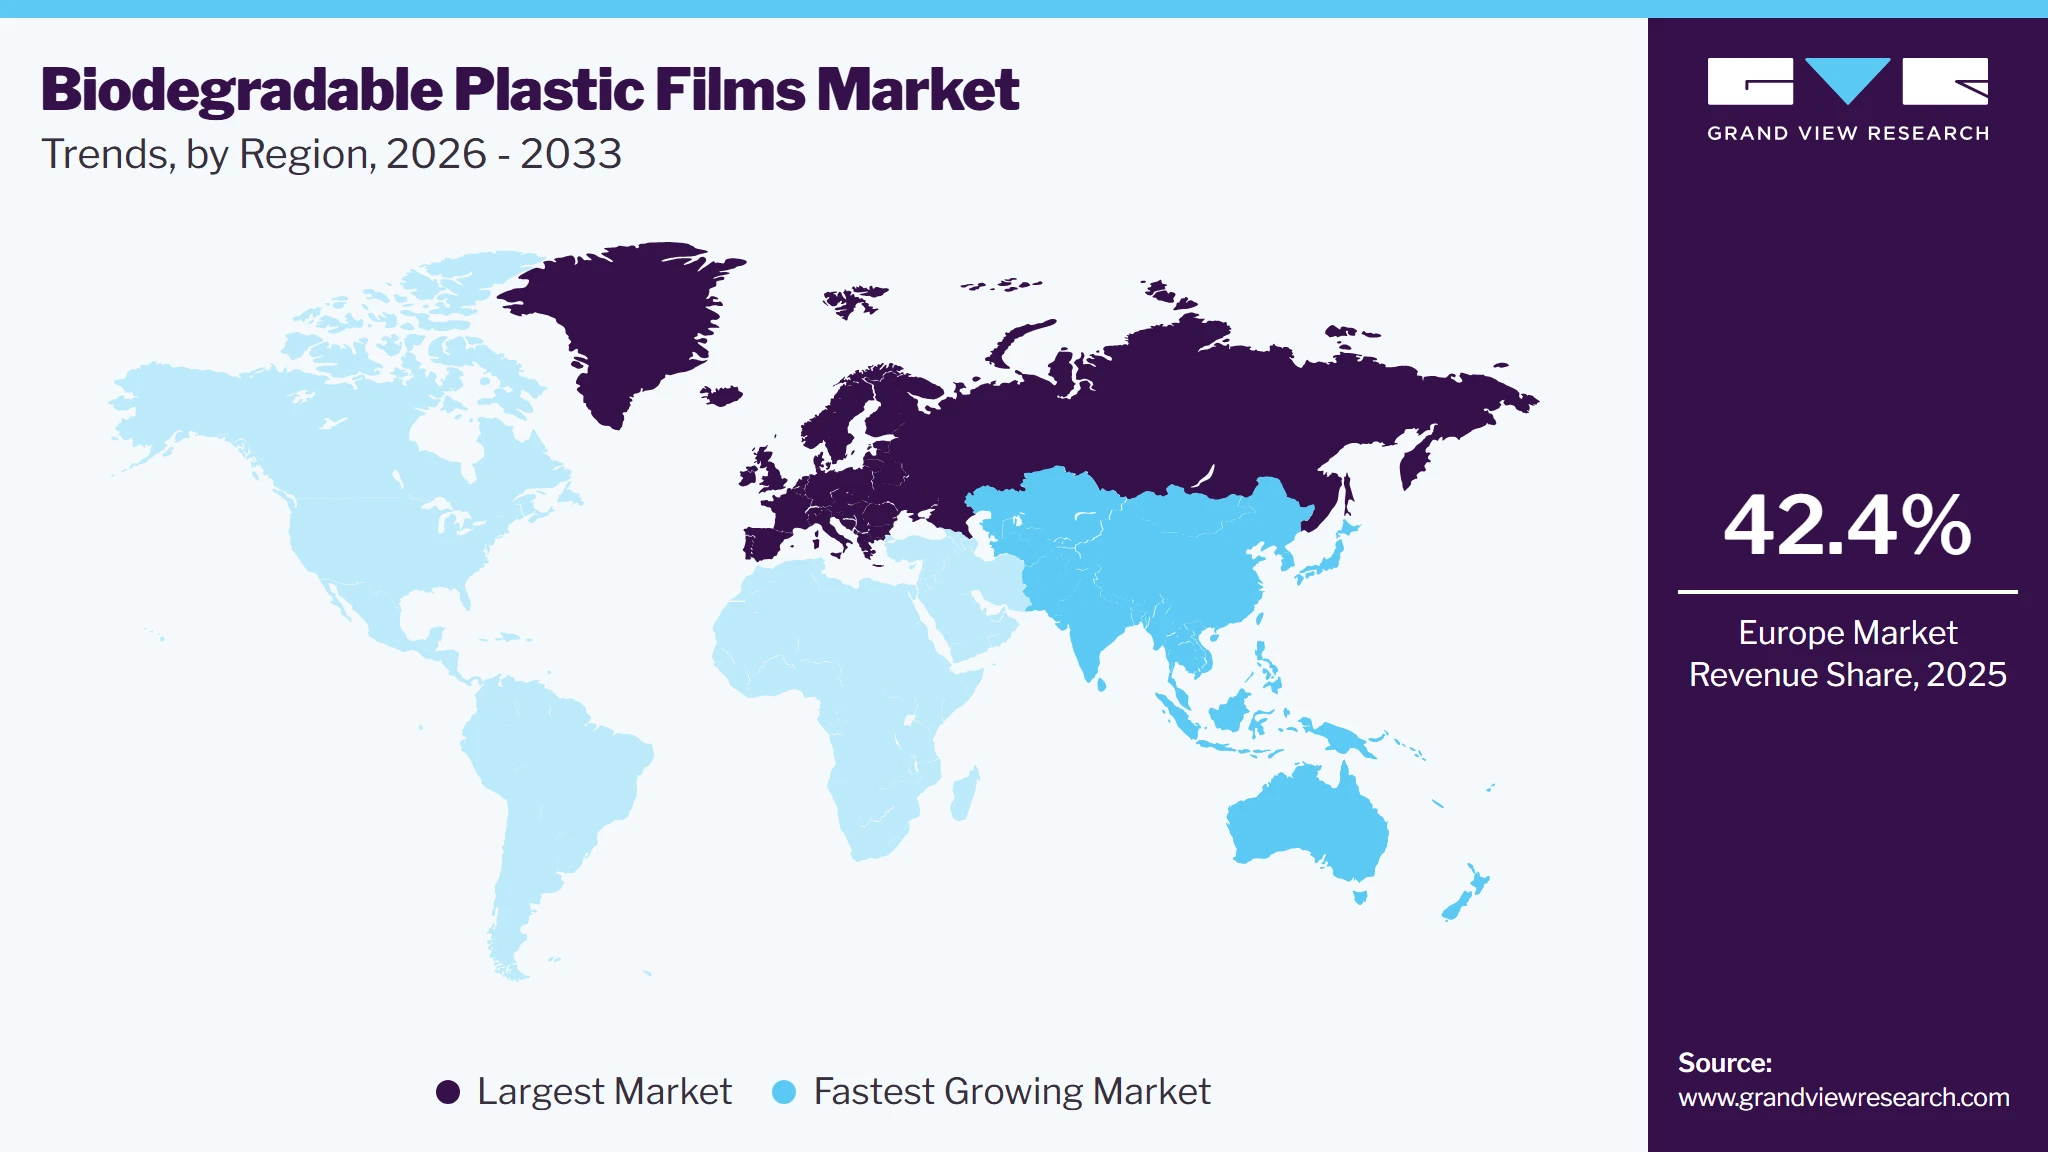
- Largest regional market: Europe (42.4% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: Germany held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 1.3 Billion
- Estimated market size in 2026: USD 1.4 Billion
- Projected market size by 2033: USD 2.2 Billion
- CAGR (2026-2033): 6.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
A direct answer, usually in 1 working day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Moreover, factors such as rising demand for sustainable packaging solutions, expanding adoption of eco-friendly materials across industries, advancements in biodegradable polymer technologies, and increasing applications of biodegradable plastic films in agriculture, packaging, consumer goods, and waste management are driving market demand globally. These films are gaining popularity as a more environmentally friendly alternative to traditional plastic films, which are not biodegradable and contribute to pollution. The biodegradable plastic films industry is witnessing a significant shift driven by consumer demand for sustainable and eco-friendly packaging solutions. As environmental awareness grows globally, consumers increasingly prioritize products with reduced ecological impact.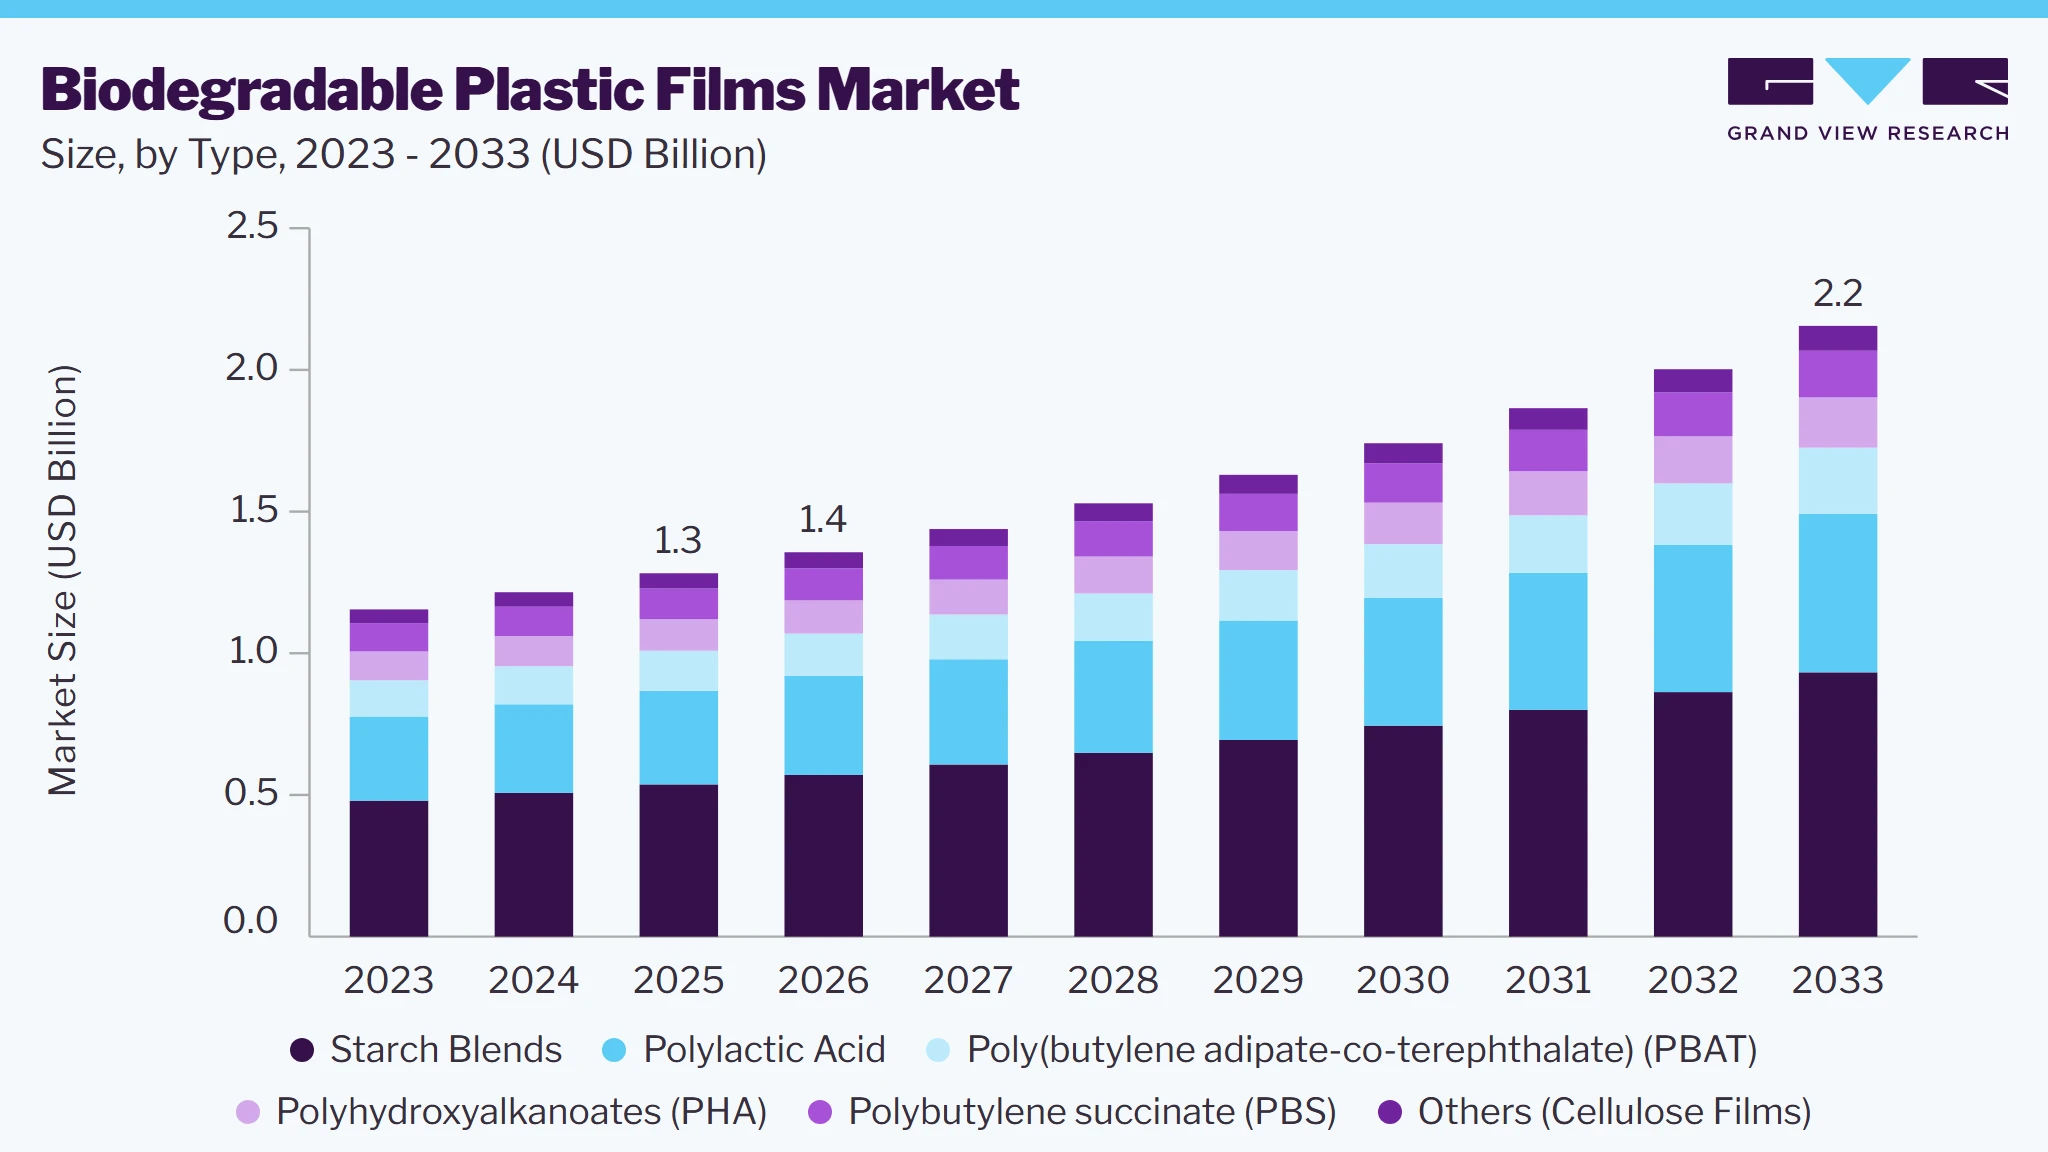 To learn more about this report, Download Free Sample Report
This trend is evident in industries such as food packaging, where biodegradable films are replacing conventional plastics. Retailers and brands are adopting these materials to align with customer expectations and regulatory pressures. The trend is further fueled by the integration of innovative designs and functional properties, such as moisture resistance and durability, ensuring the practicality of these films without compromising sustainability.
Market Dynamics
The biodegradable plastic films are gaining popularity as a more environmentally friendly alternative to traditional plastic films, which are not biodegradable and contribute to pollution. The biodegradable plastic films industry is witnessing a significant shift driven by consumer demand for sustainable and eco-friendly packaging solutions. As environmental awareness grows globally, consumers increasingly prioritize products with reduced ecological impact. This trend is evident in industries such as food packaging, where biodegradable films are replacing conventional plastics. Retailers and brands are adopting these materials to align with customer expectations and regulatory pressures. The trend is further fueled by the integration of innovative designs and functional properties, such as moisture resistance and durability, ensuring the practicality of these films without compromising sustainability.
The biodegradable plastic films market is experiencing robust growth due to expanding demand for sustainable packaging applications across food and beverage, pharmaceutical, e-commerce, and consumer goods industries. The rapid expansion of quick commerce and e-commerce platforms is significantly increasing the need for sustainable, lightweight, and protective packaging materials capable of supporting high-volume product distribution while addressing environmental concerns. At the same time, growing consumption of food-grade certified packaging for beverages, processed foods, and convenience products is accelerating the adoption of biodegradable films as manufacturers seek compliant and eco-friendly packaging alternatives.
Additionally, governments around the globe are enacting strict regulations to reduce plastic waste, increasing the demand for biodegradable plastic films. Initiatives such as bans on single-use plastics, imposition of plastic taxes, and frameworks for extended producer responsibility (EPR) are fostering a supportive environment for biodegradable options. In areas like Europe and North America, regulations such as the EU Plastics Strategy are speeding up the shift towards sustainable materials. Moreover, public investment in research and subsidies for the production of biodegradable films are making these alternatives more economically viable, promoting broader acceptance across multiple industries.
The biodegradable plastic films market faces significant challenges due to high production costs. The creation of biodegradable films depends on relatively costly bio-based raw materials, including polylactic acid, polyhydroxyalkanoates, and other renewable polymers, which tend to be more expensive than traditional petroleum-based plastics. Additionally, the need for specialized processing, lower production outputs, and the evolution of manufacturing technologies lead to heightened operational costs. These financial hurdles can restrict the adoption of biodegradable films in price-sensitive end-user sectors and regions lacking strong regulatory incentives for sustainable materials. Moreover, the premium pricing associated with biodegradable films could hinder their competitiveness against conventional plastic alternatives, posing obstacles to widespread commercialization. Consequently, it is crucial to achieve cost reductions through technological advancements, process efficiencies, and economies of scale to promote market growth and wider industry acceptance.
The increasing focus on sustainable farming methods is initiating substantial growth prospects for the biodegradable plastic films market. The heightened demand for environmentally friendly agricultural solutions is driving the use of biodegradable mulch films, which promote soil health, aid in water conservation, and enhance weed control, all while resolving the disposal issues linked to traditional plastic films. The advantages correspond with the agricultural industry's growing emphasis on environmental responsibility and efficient resource use. Furthermore, the rise in commercial farming operations and favorable sustainability programs in developing countries is driving the need for innovative biodegradable film solutions, thereby enhancing the market's long-term growth prospects
Analyst Perspective
The market for biodegradable plastic films is poised for significant long-term expansion, driven by stricter environmental regulations, growing sustainability pledges from brands, and rising consumer demand for eco-friendly packaging. Although higher production costs and performance limitations relative to traditional plastic films pose challenges to widespread adoption, advances in biodegradable resin technology and economies of scale are likely to improve market competitiveness. The packaging industry will remain the primary source of demand, especially in food packaging and retail, while new opportunities in agriculture, healthcare, and compostable consumer goods will create additional revenue streams. Market players that prioritize product innovation, comply with regulatory standards, and forge strategic partnerships across the value chain are expected to strengthen their market position as the global shift toward sustainable materials accelerates.
Type Insights
Based on type, the starch blends segment led the market with the largest revenue share of 41.9% in 2025. These films are known as more environmentally friendly than traditional polymers due to their qualities, such as renewable and abundant resources. Furthermore, starch blends are considered effective biodegradable fillers due to their thermal stability and minimal interaction with the melt-flow properties of materials.
Polylactic acid is one of the major type of biodegradable plastic films. PLA-based films are biodegradable and compostable alternatives to typical plastics as they are produced from renewable resources such as maize starch and sugarcane.Concerns regarding plastic waste and environmental degradation are driving demand for more sustainable packaging and products.
Cellulose films is another type with a significant market penetration and growth rate.Cellulose films are compostable and biodegradable. It contains agricultural byproducts, water plants, grasses, and other plant compounds. Cellulose films are commonly used in the food & beverage industry for food packaging, which improves both durability and printability.
Application Insights
Based on the application, the bags segment led the market with the largest revenue share of 36.3% in 2025. Biodegradable film-based bags are designed to break down naturally and reduce their environmental effect compared to conventional plastic bags. The growing awareness of plastic pollution and its adverse impact on ecosystems, wildlife, and oceans is the key driver of the growth of biodegradable bags.
The wrapping films application segment is growing with a significant CAGR owing to the increasing demand for sustainable packaging solutions. Moreover, the use of biodegradable wrapping films aids in waste reduction by ensuring that packaging materials degrade organically, lessening the pressure on landfills and ecosystems.
In addition, biodegradable film-based liners are suited for various uses, including food waste collection and general waste management. Furthermore, they are utilized as liners to safeguard sensitive products such as electronics, delicate objects, or perishable goods.
End-use Insights
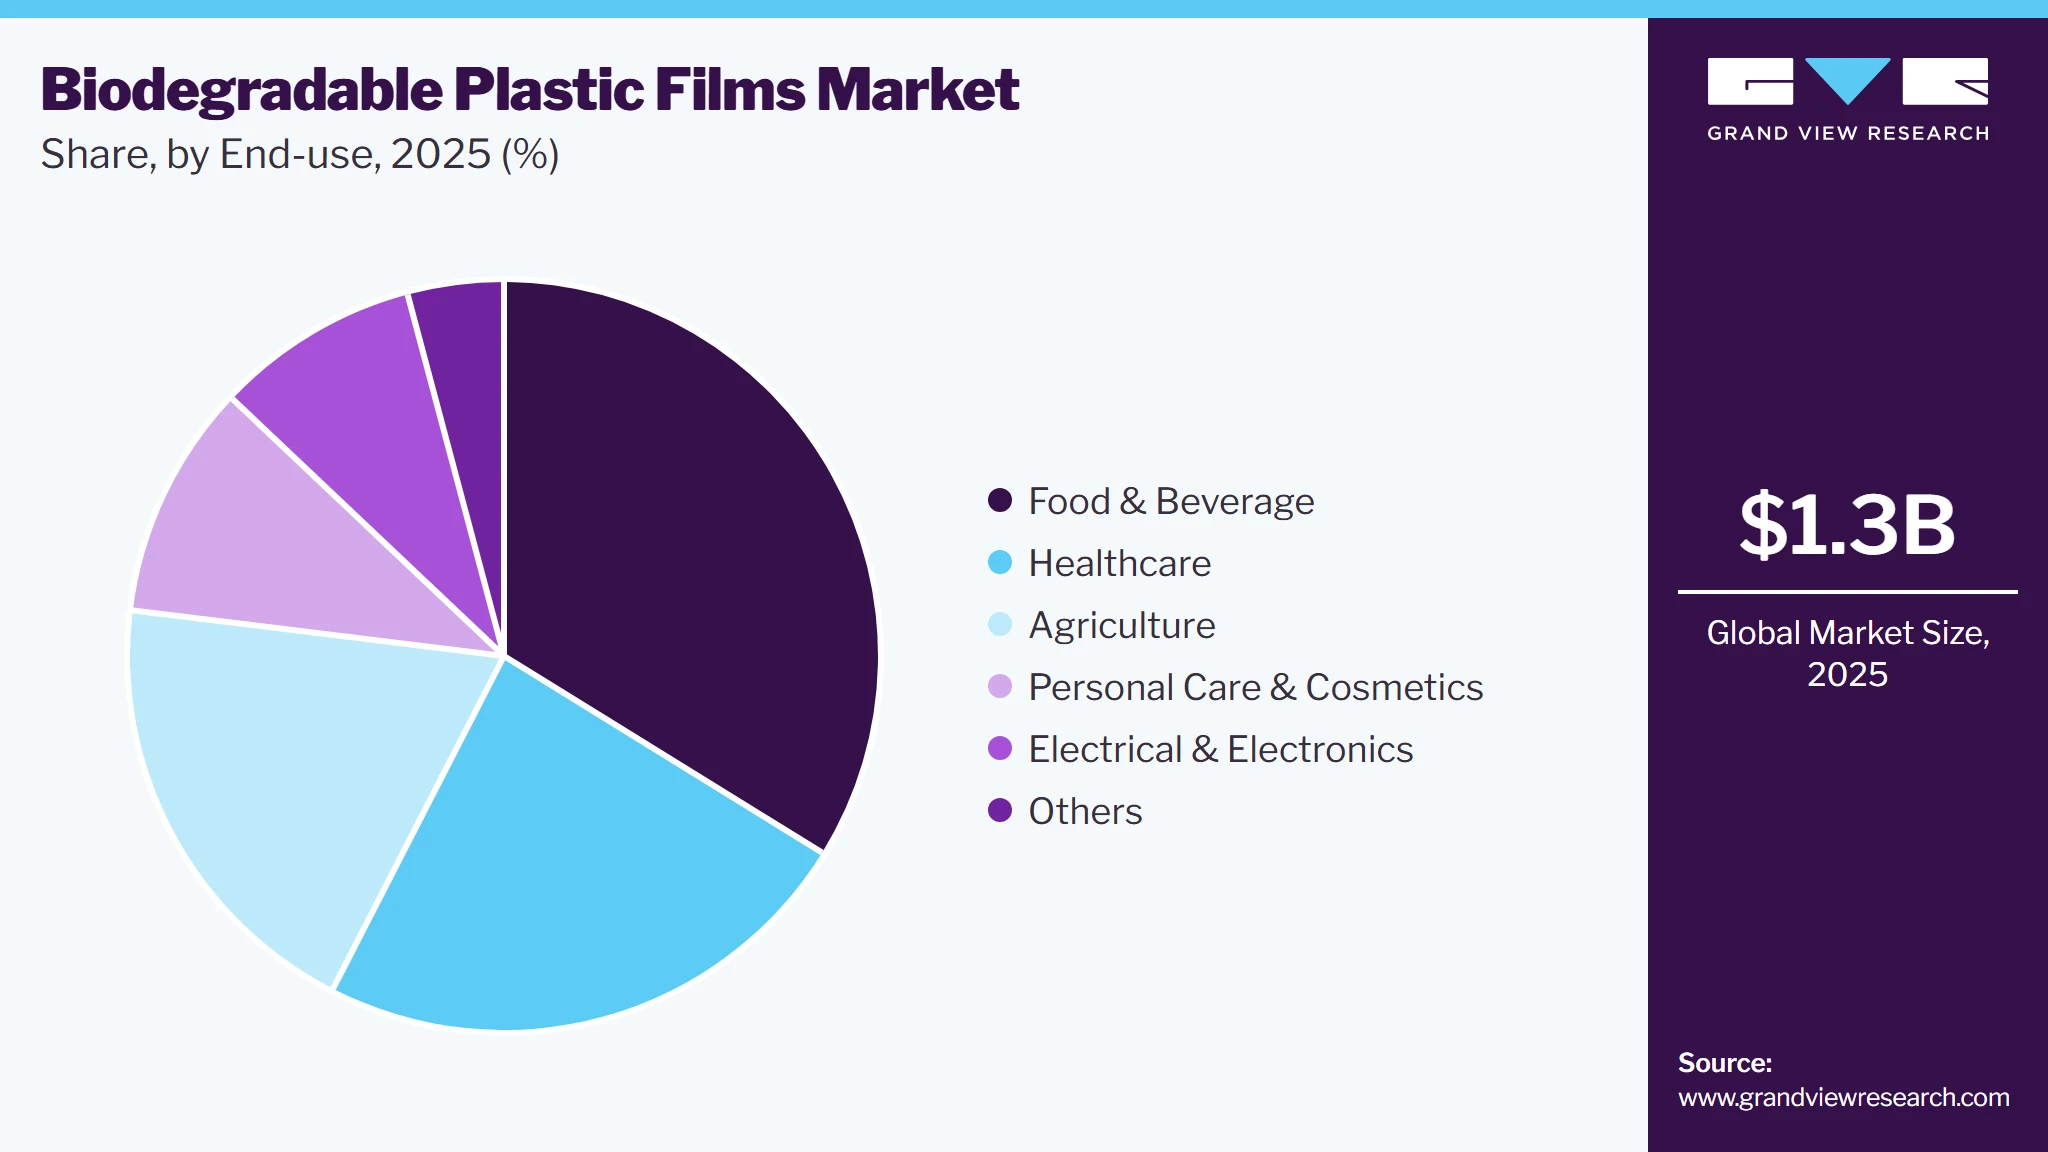
Based on end use, the food & beverage segment led the market with the largest revenue share of 33.8% in 2025. Biodegradable plastic films are commonly used in the food packaging industry for edible coating, wrapping films, egg trays, and food containers. The potential of biodegradable films to improve food quality, shelf life, safety, and usability is expected to propel the demand for biodegradable films in the food & beverage industry.
 To learn more about this report, Download Free Sample Report
The use of biodegradable films is expected to grow in the agriculture industry significantly over the forecast period. Due to their ecological benefits, agricultural biodegradable films are extensively utilized in specialized crop production systems. The usage of biodegradable films enhances soil quality, which promotes the worldwide biodegradable films industry. It may be decomposed without damaging the environment by living creatures, such as bacteria or fungi, with or without oxygen.
Furthermore, the healthcare industry is continuously innovating to improve patient care and safety. Biodegradable films are utilized to provide protective barriers, sterile packing, and controlled discharge features for medical devices owing to their properties, such as mechanical strength and barrier characteristics.
Regional Insights
The North America biodegradable plastic films market is driven by environmental awareness and stringent regulations on plastic usage in agriculture. Canadian agricultural regions, in particular, are facing mounting pressure to reduce plastic waste from farming operations, and both government and environmental organizations advocate for eco-friendly alternatives.
U.S. Biodegradable Plastic Films Market Trends
The U.S. biodegradable plastic films market is driven by increasing regulatory actions at the state level, such as California's single-use plastic bans and other waste reduction laws. These policies encourage businesses to transition to biodegradable materials. Moreover, the rapid growth of the organic food industry in the U.S. is creating a strong demand for biodegradable packaging as consumers prioritize eco-conscious brands.
Europe Biodegradable Plastic Films Market Trends
Europe dominated the biodegradable plastic films market with the largest revenue share of 42.4% in 2025, which is attributed to its comprehensive environmental regulations and a strong emphasis on the European Green Deal. Policies like the EU’s Single-Use Plastics Directive and targets for reducing greenhouse gas emissions push manufacturers to replace conventional plastics with biodegradable alternatives. In addition, the region’s well-developed recycling and composting infrastructure supports the adoption of biodegradable films by ensuring effective disposal. The collaboration between governments, research institutions, and private industries in advancing bio-based materials significantly accelerates market growth.
 To learn more about this report, Download Free Sample Report
The biodegradable plastic films market in Germany accounted for the largest market revenue share in the European biodegradable plastic films market in 2025.Germany’s biodegradable plastic films market is fueled by the country’s leadership in environmental innovation and strict waste management laws. Germany’s Packaging Act (VerpackG) and initiatives promoting the circular economy require businesses to reduce their environmental footprint, leading to a surge in demand for biodegradable solutions.
Asia Pacific Biodegradable Plastic Films Market Trends
The Asia Pacific biodegradable plastic films market is driven by rapid urbanization and growing environmental awareness among middle-income populations. Countries like China and India are introducing policies to reduce plastic waste, such as bans on single-use plastics, which are propelling the adoption of biodegradable materials.
Key Biodegradable Plastic Films Company Insights
The biodegradable plastic films industry is highly competitive, with several key players dominating the landscape. The biodegradable plastic films industry is characterized by a competitive landscape with several key players driving innovation and market growth. Major companies in this sector are investing heavily in research and development to enhance the performance, cost-effectiveness, and sustainability of their types.
Key Biodegradable Plastic Films Companies:
The following key companies have been profiled for this study on the biodegradable plastic films market.
-
BASF SE
-
Cortec Corporation
-
Kingfa Sci. & Tech. Co., Ltd.
-
Futamura Chemicals Co., Ltd
-
BioBag Americas, Inc.
-
Plastchim-T
-
Shreeji Stretch Film Industries
-
Clondalkin Group Holding B.V.
-
Tipa Corp. Ltd.
-
Brentwood Plastics, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (**BASF SE; Cortec Corporation; Kingfa Sci. & Tech. Co., Ltd.; Futamura Chemicals Co., Ltd.; Clondalkin Group Holding B.V.; Plastchim-T)
- Broad portfolios of biodegradable plastic film solutions spanning PLA, PBAT, starch blends, cellulose-based films, and specialty compostable materials used across food packaging, retail bags, agricultural films, liners, wrapping films, and industrial packaging applications.
- Strong focus on product innovation, sustainable material development, and regulatory-compliant packaging solutions aligned with global circular economy initiatives, plastic reduction targets, and evolving compostability standards.
- Extensive investments in production capacity expansion, strategic partnerships, and vertically integrated supply chains to strengthen market presence across packaging, agriculture, healthcare, and consumer goods industries.
- Strong expertise in polymer science, bio-based material engineering, film processing, and large-scale manufacturing capabilities that support the development of high-performance biodegradable film solutions.
- Established global distribution networks, strong relationships with packaging converters and brand owners, and proven ability to meet stringent sustainability, certification, and regulatory requirements across multiple regions.
- Advanced R&D capabilities enabling continuous innovation in barrier performance, mechanical strength, compostability, and renewable-material content, supporting differentiation in a rapidly evolving sustainable packaging market.
- Higher production costs compared to conventional petroleum-based plastic films, creating pricing challenges in cost-sensitive end-use markets.
- Dependence on regulatory support, sustainability mandates, and consumer willingness to pay premium prices for biodegradable packaging solutions, which can vary significantly across regions.
Established Players (TIPA Corp. Ltd.; BioBag Americas, Inc.; Shreeji Stretch Film Industries; Brentwood Plastics, Inc.)
- Focus on expanding biodegradable plastic film portfolios across packaging, agriculture, waste management, and specialty industrial applications through continuous material innovation and capacity enhancement.
- Emphasis on developing certified compostable and bio-based film solutions that comply with evolving global sustainability regulations and circular economy initiatives.
- Strong investment in strategic partnerships with packaging converters, retailers, food & beverage companies, and municipal waste management programs to strengthen market penetration and long-term demand visibility. Increasing focus on advanced film technologies, performance optimization, and scalable manufacturing capabilities to address both premium and high-volume application requirements.
- Strong brand recognition, established customer relationships, and proven expertise in biodegradable and compostable film technologies support leadership across key end-use sectors.
- Extensive manufacturing capabilities, broad distribution networks, and regulatory compliance credentials enable effective participation in global markets. Competitive advantage is reinforced through robust product portfolios, technical support capabilities, and the ability to offer certified sustainable solutions that meet stringent environmental standards.
- Strong positioning in food packaging, compostable bags, agricultural films, and waste management applications supports recurring demand and customer retention.
- Higher production and compliance costs associated with biodegradable raw materials and certification requirements can create pricing challenges relative to conventional plastic films.
- Dependence on evolving regulatory frameworks and composting infrastructure development may affect adoption rates across certain regions. Exposure to fluctuations in bio-based feedstock availability and pricing can impact operational margins.
- Large-scale operations may reduce flexibility in responding rapidly to niche customer requirements, while increasing competition from regional manufacturers and emerging low-cost suppliers continues to place pressure on pricing and market share expansion.
Recent Developments
-
In September 2024, Pester Pac Automation partnered with Solutum Technologies to launch an eco-friendly packaging film designed to replace traditional materials. This innovative film is fully biodegradable, breaking down in soil and water without leaving harmful microplastics behind. Its strong tear resistance enables the use of thinner materials, leading to significant cost savings. In addition, the film is compatible with Pester's existing stretch wrapping and overwrapping systems, enhancing both cost-effectiveness and energy efficiency.
-
In January 2024, CAMM Solutions launched a biodegradable stretch film that serves as a sustainable alternative to traditional plastic films used in logistics. This innovative product is made from a blend of natural materials and advanced PVOH formulations, providing the same performance as conventional stretch films while preventing microplastic pollution. Key benefits include its quick dissolution in nature, making it harmless if it escapes into the environment and its versatility for stabilizing products on pallets and securely attaching items during transport.
Biodegradable Plastic Films Market Report Scope
Report Attribute
Details
Market size in 2025
USD 1.3 billion
Estimated market size in 2026
USD 1.4 billion
Projected market size by 2033
USD 2.2 billion
Growth rate
CAGR of 6.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain, The Netherlands; China; India; Japan; South Korea; Australia; Malaysia; Singapore; Thailand; Vietnam; Brazil; Argentina; Saudi Arabia; UAE; South Africa
Key companies profiled
BASF SE; Cortec Corporation; Kingfa Sci. & Tech. Co., Ltd., Futamura Chemicals Co., Ltd, BioBag Americas, Inc., Plastchim-T, Shreeji Stretch Film Industries, Clondalkin Group Holding B.V., Tipa Corp., Ltd., Brentwood Plastics, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Biodegradable Plastic Films Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global biodegradable plastic films market report based on type, application, end-use, and region:
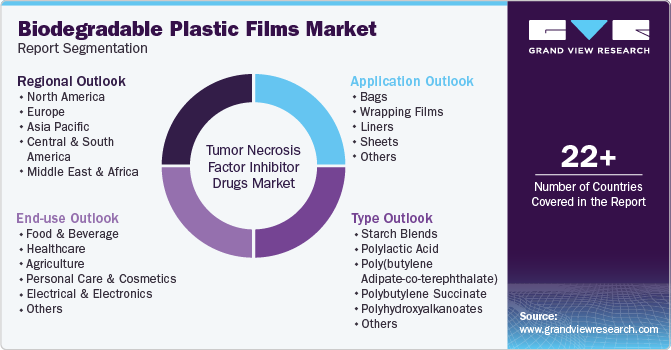 To learn more about this report, Download Free Sample Report
-
Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Starch Blends
-
Polylactic Acid
-
Poly(butylene adipate-co-terephthalate) (PBAT)
-
Polybutylene succinate (PBS)
-
Polyhydroxyalkanoates (PHA)
-
Others (Cellulose Films)
-
-
Application Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Bags
-
Wrapping Films
-
Liners
-
Sheets
-
Others
-
-
End-use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Food & Beverage
-
Healthcare
-
Agriculture
-
Personal Care & Cosmetics
-
Electrical & Electronics
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
The Netherlands
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
Malaysia
-
Singapore
-
Thailand
-
Vietnam
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
UAE
-
South Africa
-
-
Research Methodology
The biodegradable plastic films market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each biodegradable plastic films segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Starch Blends
Revenue is captured through the production and sale of starch blends being used in the formulation of biodegradable plastic films. Demand is driven by cost-effectiveness, renewable feedstock availability, and growing adoption in packaging and agricultural applications where compostability and reduced environmental impact are key purchasing considerations.
Polylactic Acid (PLA)
Revenue is captured through the supply of PLA-based biodegradable films derived from renewable resources such as corn starch and sugarcane. Growth is driven by increasing demand for sustainable packaging solutions, excellent transparency, printability, and compatibility with industrial composting systems, making PLA a preferred material across food packaging and consumer goods applications.
Poly(butylene adipate-co-terephthalate) (PBAT)
Revenue is captured through the sale of flexible biodegradable films manufactured using PBAT resin. Demand is supported by its superior flexibility, toughness, and processability, enabling widespread use in compostable bags, agricultural films, and packaging applications that require performance characteristics similar to conventional plastics.
Polybutylene Succinate (PBS)
Revenue is captured through the commercialization of PBS-based biodegradable films used in packaging and specialty applications. Growth is driven by its balanced mechanical strength, heat resistance, and biodegradability, supporting adoption in products requiring enhanced durability while meeting sustainability objectives.
Polyhydroxyalkanoates (PHA)
Revenue is captured through the supply of biodegradable films produced from naturally occurring microbial polymers. Demand is driven by increasing preference for marine-biodegradable materials, expanding regulatory support for sustainable plastics, and growing use in premium packaging and environmentally sensitive applications.
Others (Cellulose Films)
Revenue is captured through the sale of biodegradable films manufactured from cellulose and other specialty bio-based materials. Growth is supported by excellent transparency, renewable sourcing, and strong environmental credentials, making these films attractive for food packaging, labeling, and niche sustainable packaging applications.
Segment - Application
Revenue capture definition
Bags
Revenue is captured through the use of biodegradable plastic films in shopping bags, compost bags, waste collection bags, and carry bags. Demand is driven by increasing restrictions on conventional plastic bags, rising environmental awareness, and growing adoption of compostable alternatives across retail and municipal waste management sectors.
Wrapping Films
Revenue is captured through biodegradable films used for product wrapping, protective packaging, and food preservation applications. Growth is supported by rising demand for sustainable packaging solutions that provide product protection, shelf-life enhancement, and compliance with evolving environmental regulations.
Liners
Revenue is captured through the application of biodegradable films in bin liners, compost liners, and industrial containment solutions. Demand is driven by increasing organic waste collection programs, composting initiatives, and the need for environmentally responsible waste management systems.
Sheets
Revenue is captured through biodegradable film sheets utilized in packaging, agricultural, industrial, and protective covering applications. Growth is supported by their versatility, ease of processing, and ability to provide sustainable alternatives to conventional plastic sheet materials across multiple industries.
Others
Revenue is captured through specialty and emerging applications of biodegradable plastic films, including labels, mulch films, protective coatings, and customized packaging formats. Demand is driven by ongoing product innovation, expanding sustainability requirements, and the development of new end-use applications.
Segment - End Use
Revenue capture definition
Food & Beverage
Revenue is captured through the use of biodegradable plastic films in food packaging, produce bags, wraps, and beverage-related packaging solutions. Demand is driven by increasing consumer preference for sustainable packaging, regulatory pressure to reduce plastic waste, and the need to maintain product freshness and safety.
Healthcare
Revenue is captured through biodegradable film applications in medical packaging, disposable healthcare products, and pharmaceutical packaging solutions. Growth is supported by rising demand for hygienic, single-use materials combined with increasing focus on reducing environmental impact within healthcare waste streams.
Agriculture
Revenue is captured through the use of biodegradable films in mulch films, crop protection, greenhouse coverings, and agricultural packaging. Demand is driven by the need to improve farming efficiency, reduce plastic residue in soil, and support sustainable agricultural practices.
Personal Care & Cosmetics
Revenue is captured through biodegradable film applications in packaging for cosmetics, skincare, personal hygiene, and beauty products. Growth is supported by increasing consumer demand for eco-friendly packaging, brand sustainability initiatives, and regulatory emphasis on reducing plastic waste in consumer goods.
Electrical & Electronics
Revenue is captured through the use of biodegradable films in protective packaging, component wrapping, and specialty electronic product packaging applications. Demand is driven by growing sustainability commitments within the electronics industry and increasing adoption of environmentally responsible packaging materials.
Others
Revenue is captured through biodegradable plastic film applications across industrial, consumer goods, retail, logistics, and specialty sectors. Growth is supported by expanding awareness of sustainable materials, evolving environmental regulations, and continuous innovation in biodegradable film technologies.
Estimation Model
Layer Name
Key Question
Description
Top-Down Biodegradable Plastic Films Demand Scan Layer
What defines market boundaries?
This layer begins with global biodegradable plastic films demand across packaging, agriculture, consumer goods, and industrial applications, then filters consumption intensity based on end-use industry output, packaging material requirements, sustainability adoption rates, regulatory mandates on plastic waste reduction, and consumer preference for eco-friendly products, influencing the substitution of conventional plastic films with biodegradable alternatives.
Application Mix Validation Layer
Where is demand generated?
This layer evaluates demand distribution across food packaging, shopping & carry bags, agricultural mulch films, compostable waste bags, industrial packaging, and other specialty applications, aligning market revenue with performance requirements such as barrier protection, durability, compostability, shelf-life extension, and compliance with environmental regulations across diverse end-use sectors.
Material & Consumption Conversion Layer
Who captures market revenue?
This layer converts end-use consumption volumes into biodegradable plastic film revenue by applying material mix ratios across PLA, PBAT, starch blends, PHA, and other biodegradable polymers, while accounting for film thickness, mechanical performance specifications, processing technologies, certification standards, and manufacturer pricing strategies across the global value chain.
Regional Commercial Cross-Check Layer
How are assumptions validated?
This layer validates demand concentration by comparing Asia Pacific’s expanding packaging industry and regulatory support for sustainable materials, Europe’s strong circular economy policies and high biodegradable packaging adoption, and North America’s growing demand for compostable products and sustainable retail packaging, while also considering emerging opportunities in Latin America and the Middle East driven by environmental awareness and evolving waste management regulations.
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Regional Segmentation
Detailed market breakdown by North America, Europe, Asia Pacific, Central & South America, and the Middle East & Africa, including country-level analysis for key markets such as the U.S., Germany, France, China, Japan, India, Brazil, and GCC countries.
Identified region-specific demand drivers, regulatory frameworks, biodegradable packaging adoption trends, manufacturing hubs, and investment opportunities to support market entry and expansion strategies.
Opportunity Assessment
Evaluation of emerging growth opportunities across sustainable food packaging, compostable retail packaging, agricultural mulch films, e-commerce packaging, and bio-based material innovations.
Delivered actionable insights on future investment areas, technology adoption trends, regulatory-driven opportunities, and high-potential markets expected to generate long-term growth.
Trade Assessment
Analysis of global import-export patterns, trade flows, key exporting and importing countries, tariff structures, supply chain dependencies, and regional manufacturing competitiveness.
Helped identify supply chain risks, sourcing opportunities, trade advantages, and potential market expansion routes through favorable trade corridors.
Frequently Asked Questions About This Report
The Europe biodegradable plastic films market accounted for the largest share of 42.4% market size in 2025.
Asia Pacific is the leading biodegradable plastic films market and is expected to grow at a compound annual growth rate of 8.7% over the forecast period.
Based on application, the bags segment accounted for the largest share of 36.3% market size in 2025. Growing demand for sustainable, lightweight, and aesthetically appealing packaging and consumer carry solutions is driving the adoption of biodegradable plastic films in bags due to their excellent printability, flexibility, strength, compostability, and ability to support brand sustainability initiatives while reducing dependence on conventional petroleum-based plastics.
Key factors that are driving the biodegradable plastic films market growth include growing environmental awareness and rules demanding the reduction of plastic waste.
The food & beverage dominated the end-use segment with a revenue share of 33.8% in 2025.
The global biodegradable plastic films market size was valued at USD 1.3 billion in 2025 and is estimated at USD 1.4 billion for 2026.
The global biodegradable plastic films market is expected to grow at a CAGR of 6.8% from 2026 to 2033, reaching USD 2.2 billion by 2033.
The starch blends segment led the global biodegradable plastic films market and accounted for 41.9% share of the global revenue in 2025.
Some key players operating in the biodegradable plastic films market include BASF SE, Cortec Corporation, Kingfa Sci. & Tech. Co., Ltd., Futamura Chemicals Co., Ltd, BioBag Americas, Inc., Plastchim-T, Shreeji Stretch Film Industries, and Clondalkin Group Holding B.V.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


