
- Home
- »
- Biotechnology
- »
-
Bioprocess Bags Market Size And Share Report, 2026-2033GVR Report cover

Bioprocess Bags Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (2D Bioprocess Bags, 3D Bioprocess Bags), By Workflow (Upstream Process, Downstream Process, Process Development), By End User, By Region, And Segment Forecasts
Market Size, 2025
$4.8BMarket Estimate, 2026
$5.6BMarket Forecast, 2033
$15.4BCAGR, 2026–2033
15.4%Bioprocess Bags Market Summary
The global bioprocessing bags market size was valued at USD 4.8 billion in 2025 and is projected to grow from USD 5.6 billion in 2026 to USD 15.4 billion by 2033, growing at a CAGR of 15.4% from 2026 to 2033. North America dominated the Bioprocessing Bags Market with the largest revenue share of 35.5% in 2025. Furthermore, the rising demand for personalized medicine is leading to the development of new biologics and other complex therapeutics, which require specialized manufacturing processes that can benefit from bioprocess bags.
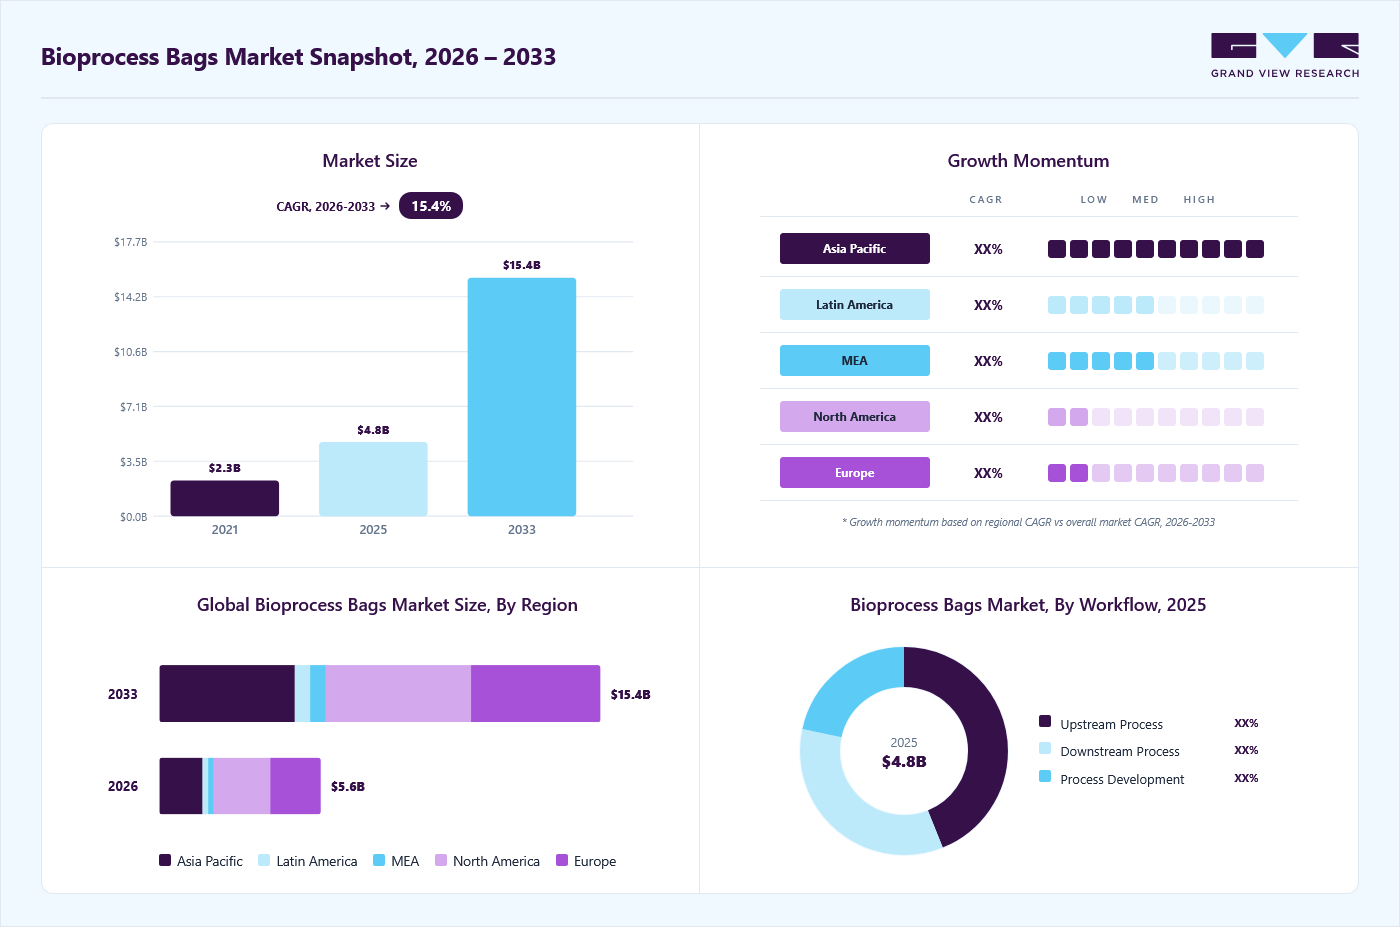 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By workflow: Upstream process segment led the market with the largest revenue share of 43.9% in 2025.
- By type: 2D bioprocess bags segment led the market with the largest revenue share of 46.0% in 2025.
- By end user: 2D bioprocess bags segment led the market with the largest revenue share of 46.0% in 2025.
Regional Highlights
- Largest regional market: North America (35.5% revenue share, 2025)
- By country: The U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 2.4 Billion
- Estimated Market size in 2026: USD 4.2 Billion
- Projected market size by 2033: USD 40.5 Billion
- CAGR (2026-2033): 15.4%
Prism AI by Grand View Research Free to tryAsk a question about the bioprocess bags marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
The COVID-19 pandemic has had a significant impact on the bioprocess bags market. The market is primarily driven by the biopharmaceutical industry, which has seen increased demand due to the development of COVID-19 vaccines and other advanced therapies. The production of vaccines and protein therapeutics requires bioprocess bags for the production, storage and transport of biologics, which has led to a surge in demand for these bags. Furthermore, the pandemic has also resulted in a shift in focus towards single-use bioprocess bags. They are preferred over traditional stainless-steel tanks due to their low risk of contamination, increased flexibility, cost effectiveness, and ease of use.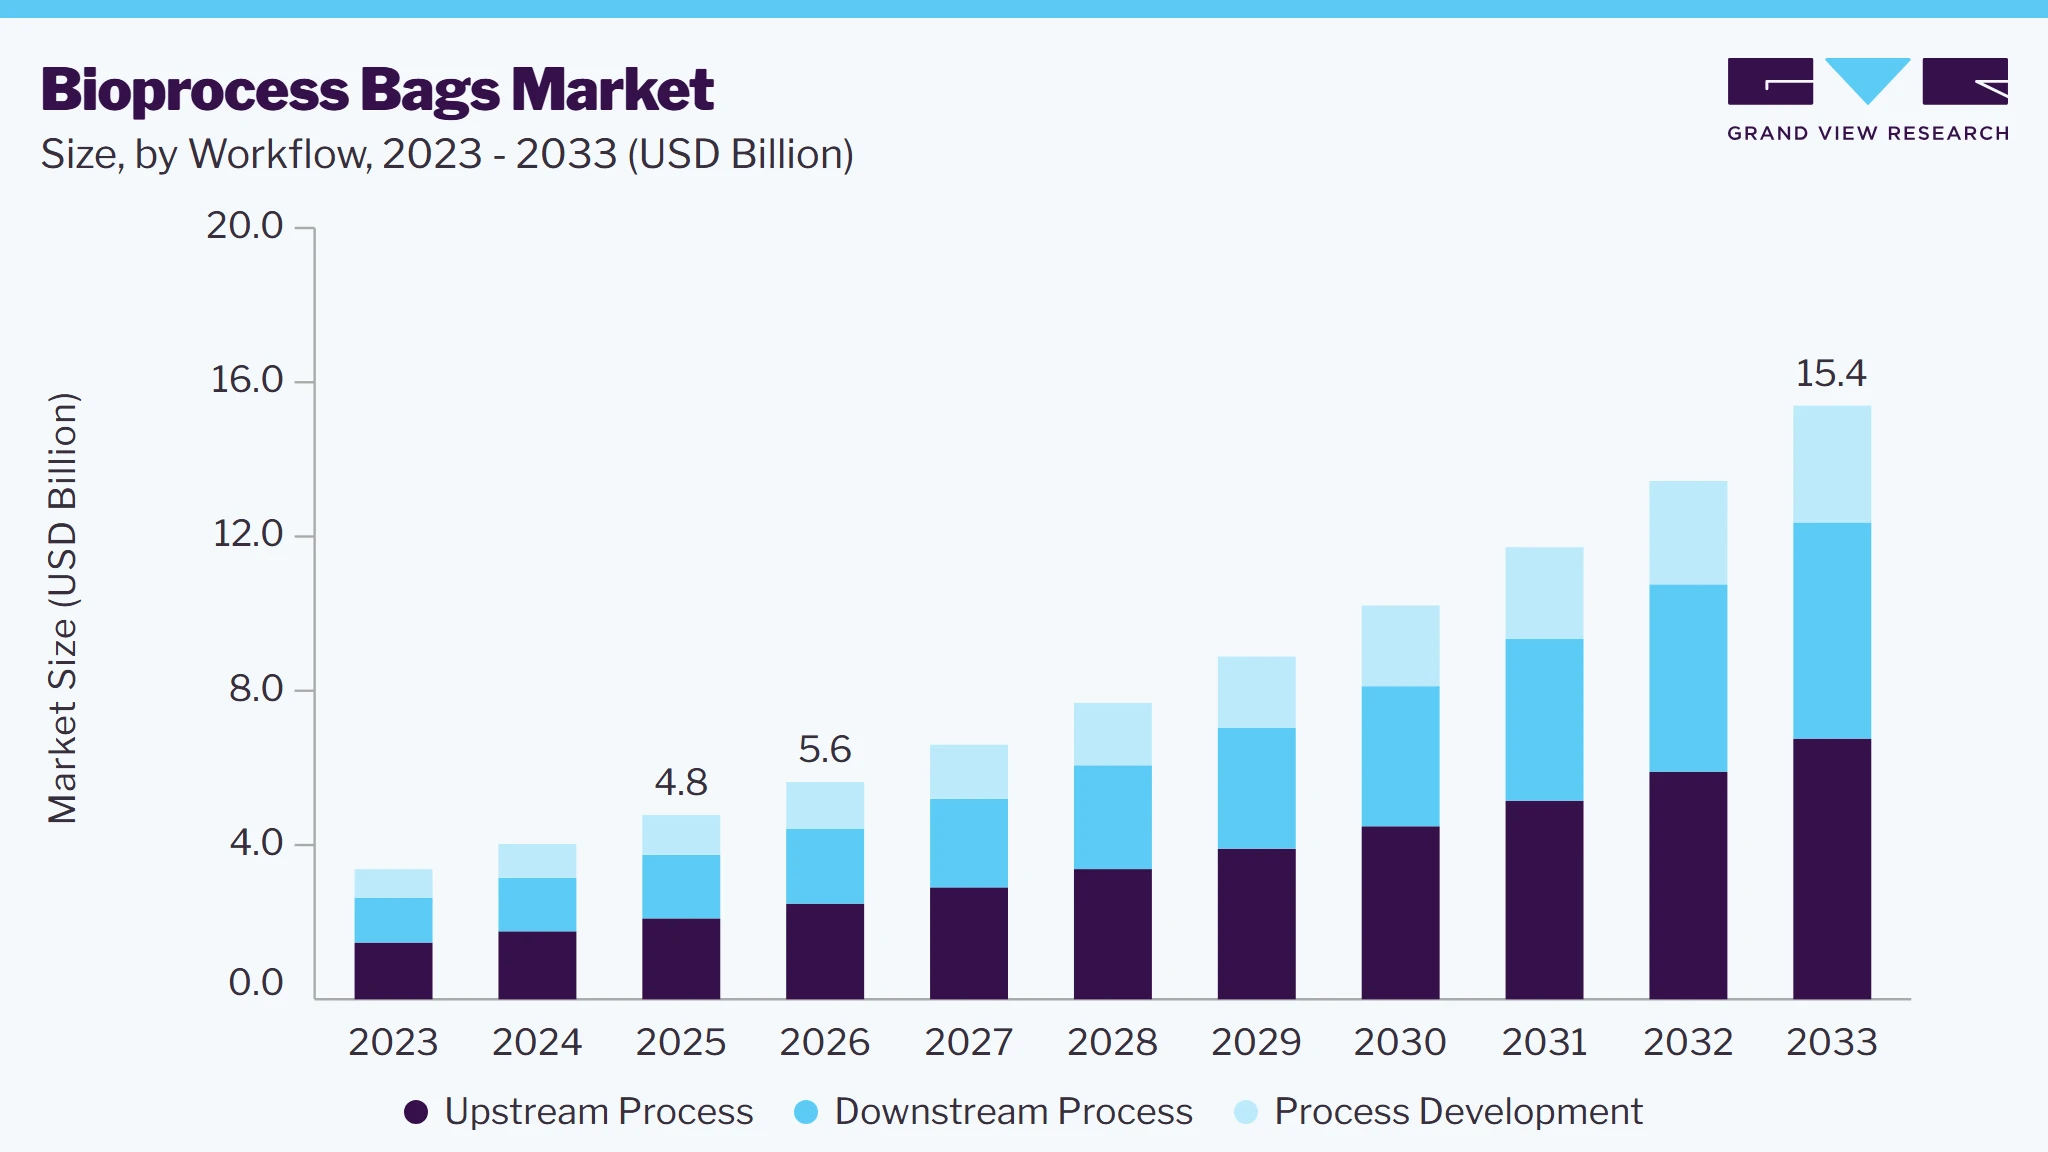 To learn more about this report, Download Free Sample Report
For instance, in February 2022, Dow, Südpack Medica, and Sartorius have joined forces to produce bioprocessing bags that are crucial for manufacturing and transporting vaccines in the global fight against COVID-19. The collaboration involves the production of sterile bioreactor bags made from multi-layered film that can hold up to 2,000 liters. These bags are designed for optimized stirring and high oxygen transfer, making them suitable for mammalian cell culture processes that are microcarrier-based or require high cell density.
These bags are made of flexible plastic materials and are designed to withstand the rigorous demands of the biopharmaceutical manufacturing process. They are available in different sizes and configurations, depending on the specific needs of the manufacturer. The market is expected to see significant growth due to the rising demand for biopharmaceuticals. The demand for biopharmaceuticals is increasing due to several factors, including an aging population, the prevalence of chronic diseases, and a growing demand for personalized medicine. As a result, the bioprocess bags market is expected to grow significantly over the coming years. For instance, in 2022, approximately 340 biologics were approved by the Food and Drug Administration.
Furthermore, the rising outsourcing activity by Contract Manufacturing Organizations (CMOs) and Contract Research Organizations (CROs) is expected to drive the demand for bioprocess bags. CMOs and CROs are companies that provide manufacturing and research services to pharmaceutical and biotech companies. The biopharma giants are increasingly outsourcing their bioprocessing activities, including the production, storage, and transportation of biologics, to third-party service providers. Bioprocessing bags are an essential component of biologics manufacturing, and their demand is expected to grow as more companies outsource their bioprocessing activities. For instance, in July 2021, Pall Corporation announced a contract with Exothera S.A. that is valued at more than $7 million. This new agreement is intended to create a suspension-based manufacturing platform capable of producing up to 2000L of product. The platform will utilize a range of technologies including Allegro STR single-use bioreactors to produce various viral vectors used in gene therapies and viral vector-based vaccines.
Market Dynamics
The bioprocessing bags market is being shaped by the rapid shift toward single-use technologies in biopharmaceutical manufacturing, as companies look to reduce contamination risks and improve production flexibility. Strong demand for biologics and vaccines continues to drive adoption, especially in large-scale cell culture and storage applications. At the same time, supply chain constraints around raw materials and concerns about extractables and leachable are creating cautious procurement behavior. Overall, the market is growing steadily, supported by expanding biologics pipelines and ongoing manufacturing capacity expansions worldwide.
The adoption of single-use technology in bio-manufacturing is strongly driven by its practical advantages in reducing capital expenditure and operational complexity. By eliminating the need for extensive cleaning and sterilization between batches, it significantly shortens turnaround times and improves facility utilization, which is especially valuable in fast-growing biologics and vaccine production. It also lowers the risk of cross-contamination, making it easier to handle multiproduct facilities with greater flexibility. In addition, single-use systems reduce water and energy consumption associated with traditional stainless-steel infrastructure, supporting more sustainable manufacturing practices. Together, these benefits are encouraging both established pharmaceutical players and emerging biotech firms to accelerate their shift toward more agile and cost-efficient production models.
Regulatory concerns around leachable and extractables remain a key restraint in the bioprocessing and single-use systems market, as strict quality standards require manufacturers to ensure that materials used in disposable bags, tubing, and connectors do not release harmful substances into biologics. Regulatory agencies such as the FDA and EMA demand extensive testing and validation, which increases development time and compliance costs for suppliers. Variability in raw materials and differences in supplier testing methodologies can further complicate regulatory approval and create uncertainty for end users. These concerns often make large-scale biopharmaceutical companies cautious about fully replacing traditional stainless-steel systems, particularly for sensitive drug products and late-stage production.
The growing pipeline of biologics, including monoclonal antibodies, cell and gene therapies, and personalized medicines, is creating a strong opportunity for single-use technologies and bioprocessing solutions. These therapies often require flexible, small-to-mid scale production setups with quick changeovers and strict contamination control, making disposable systems highly suitable. As biopharma companies increasingly move toward decentralized and modular manufacturing models, demand for scalable, single-use bioprocessing bags and related consumables is expected to rise. This shift is further supported by rising investments in advanced therapies and contract development and manufacturing organizations (CDMOs), which rely heavily on adaptable infrastructure to serve multiple clients efficiently.
Analyst Perspective
The bioprocessing bags market is positioned for steady expansion, primarily supported by the accelerating shift toward single-use technologies in biopharmaceutical manufacturing. The strong growth in biologics, vaccines, and advanced therapies is driving widespread adoption of flexible, contamination-free, and cost-efficient production systems across upstream, downstream, and storage applications. While large players are strengthening integrated bioprocessing ecosystems through acquisitions and material innovation, smaller and regional manufacturers are gaining traction through customized and cost-competitive offerings. Overall, increasing investments in modular manufacturing facilities and the expansion of CDMO-driven production models are expected to sustain long-term demand momentum.
Type Insights
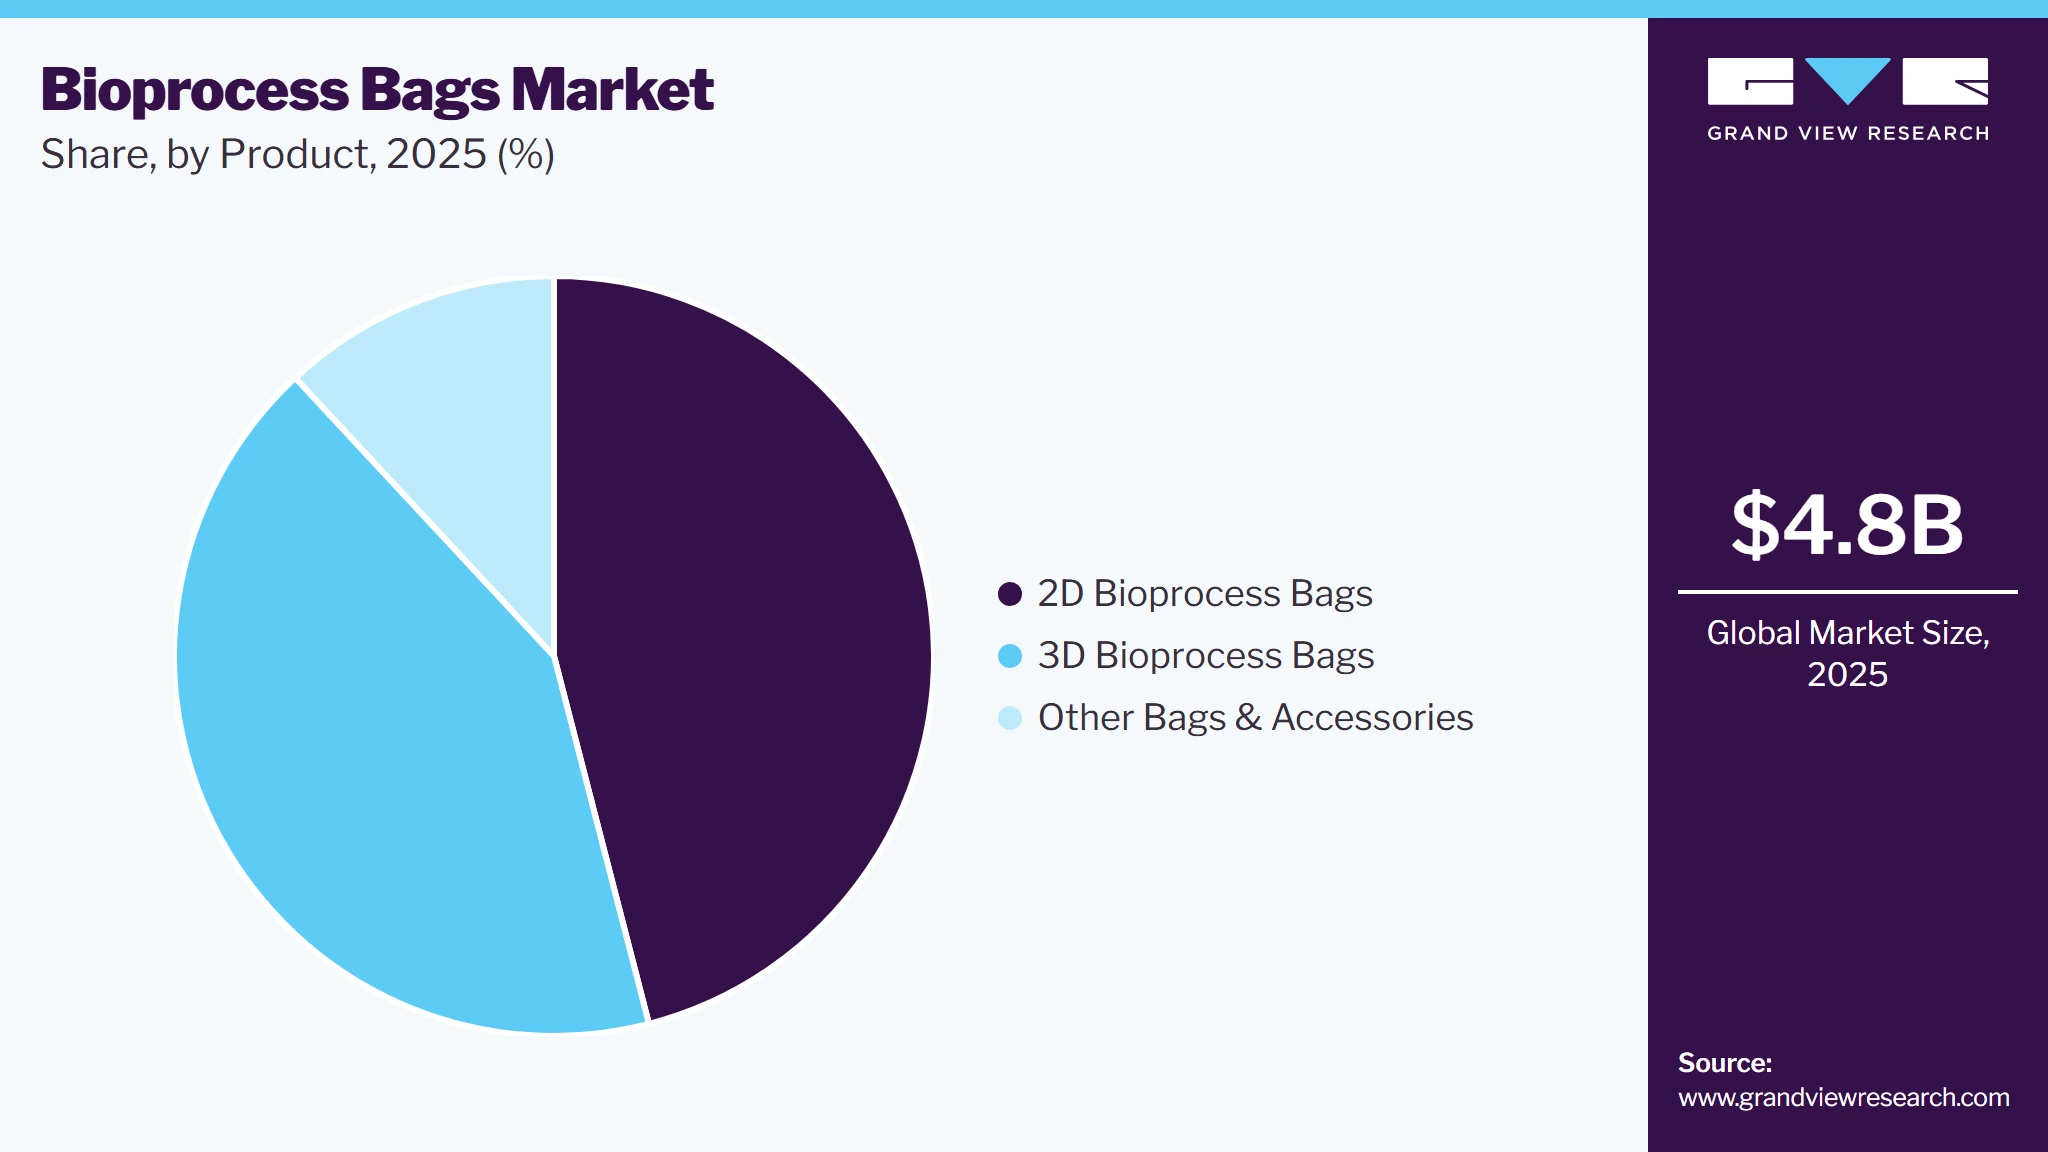
Based on type, the 2D bioprocess bags segment led the market with the largest revenue share of 46.0% in 2025. This is due to the increasing demand for biopharmaceuticals and cell therapies. As the prevalence of chronic diseases such as cancer, diabetes, and autoimmune disorders continues to rise, there is a growing need for innovative and effective treatments. Biopharmaceuticals offer a promising solution, and the use of 2D bioprocess bags can help to streamline the manufacturing process and reduce costs. The 2D bioprocess bags market is also driven by technological advancements in bag design and materials. Manufacturers are developing bags with improved strength, durability, and resistance to punctures and leaks. In addition, there is a growing trend towards customization and scalability, with bags designed to meet specific requirements of different bioprocessing applications.
The 3D bioprocess bags segment is anticipated to grow at the fastest CAGR during the forecast period. They are commonly used in the production and storage of biologics, such as monoclonal antibodies, vaccines, and cell-based therapies. They provide a closed and sterile environment for cell culture, reducing the risk of contamination and ensuring the quality and consistency of the end product.The growing demand for regenerative medicine and increasing government funding for regenerative medicine is driving the growth of the industry. For instance, in 2021, The Regenerative Medicine Innovation Project (RMIP) was introduced in collaboration between the US National Institutes of Health (NIH) and the Food and Drug Administration (FDA) to support the development of safe and effective regenerative medicine products. The project aims to provide guidance to researchers and industry on best practices, develop new tools and standards for evaluating regenerative medicine products, and ensure that these products are developed with rigor to protect patient safety.
Workflow Insights
Based on workflow, the upstream process segment led the market with the largest revenue share of 43.9% in 2025. Bioprocessing bags are widely used in upstream processes for cell culture, media preparation, and fermentation. These bags provide a sterile and controlled environment for cell growth and are designed to optimize cell growth and productivity. They are available in various sizes and configurations, allowing for flexibility and scalability in upstream processes. The demand for bioprocessing bags in upstream processes is driven by several factors, including the increasing demand for biopharmaceuticals and vaccines, the shift towards single-use technologies, and the benefits of using disposable bags in terms of cost, efficiency, and risk reduction.
The downstream process is anticipated to register fastest CAGR during the forecast period. Bioprocess bags are widely used in the downstream process for storing and transporting the product during various stages of purification. They offer several advantages over traditional stainless steel vessels, including lower risk of contamination, reduced cleaning and validation requirements, and faster turnaround times. For instance, Sartorius AG offers Flexsafe bags, which are made from high-quality materials and are available in various sizes, ranging from 50 mL to 1,000 L. The bags are designed to be used with Sartorius' Flexboy and Flexboy Advance disposable bioreactors, providing a complete single-use solution for downstream bioprocessing.
End User Insights
Based on end user, the 2D bioprocess bags segment led the market with the largest revenue share of 46.0% in 2025. The strategic activities adopted key market such as expansion, new product launch, merger & acquisition, and collaboration offer lucrative opportunities. For instance, in February 2021, Saint-Gobain announced launch of highly efficient cell culture bags for T-cell expansion. These new cell culture bags are designed to provide a sterile and controlled environment for the growth and expansion of T-cells, which are an essential component of the immune system and are used in cell-based therapies for the treatment of various diseases.
 To learn more about this report, Download Free Sample Report
The CMOs & CROs segment is anticipated to register fastest CAGR over the forecast period. The adoption of contract services is being fueled by several benefits offered by CROs and CMOs, including scalability, flexibility, reduced internal infrastructure requirements, and dedicated supply channels. As a result, these advantages are expected to have a positive impact on the growth of the industry in the coming years. Also, the outsourcing of bioprocessing activities allows companies to focus on their core competencies, reduce costs, and improve efficiency. This trend has led to an increase in the number of CMOs and CROs, which, in turn, is expected to drive the growth of the market.
Regional Insights
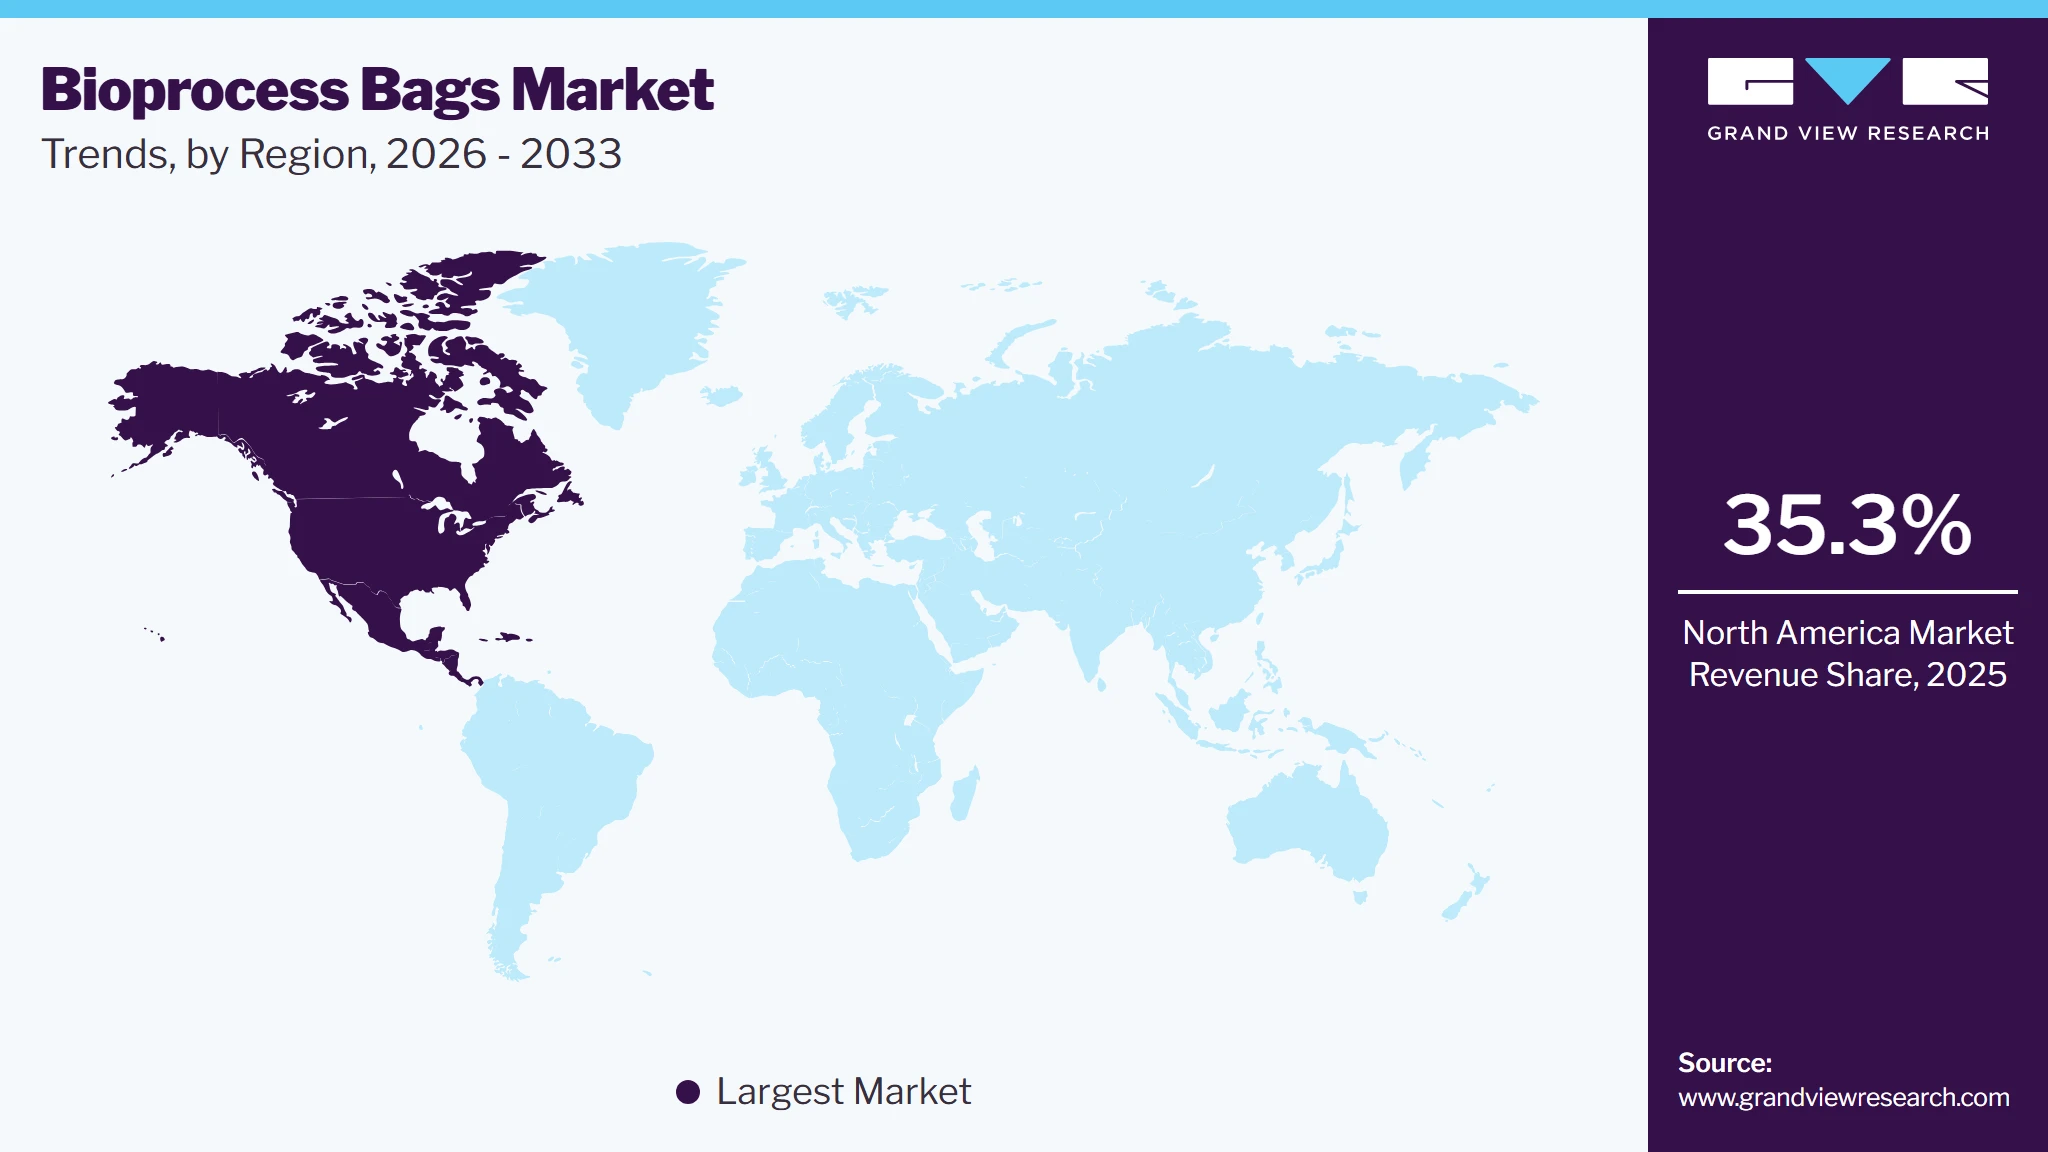
North America dominated the Bioprocessing Bags Market with the largest revenue share of 35.5% in 2025. The increasing demand for biopharmaceuticals is expected to drive the growth of the bioprocess bags market in the region. Other factors that are expected to contribute to the growth of the bioprocess bags market in North America include the increasing adoption of single-use bioprocessing technologies and the growing focus on reducing the high costs associated with bioprocessing of advanced therapies. In addition, the presence of major biopharmaceutical companies and contract manufacturing organizations (CMOs) in North America is expected to drive the growth of the bioprocess bags market in the region. These companies require high-quality bioprocess bags for their operations.
 To learn more about this report, Download Free Sample Report
U.S. Bioprocess Bags Market Trends
The bioprocessing bags market in the U.S. held the largest share in the North America region in 2025. Strong investment in biopharmaceutical R&D and cell and gene therapy production is propelling demand for single-use bioprocess bags. The FDA’s proactive stance on advanced biologics manufacturing also supports the market's growth, with increased focus on modular, cost-effective manufacturing solutions.
Europe Bioprocess Bags Market Trends
The European bioprocess bags market benefits from widespread adoption of single-use technologies in biopharma facilities, particularly to meet environmental sustainability goals. The region’s emphasis on reducing carbon footprints and regulatory compliance in waste disposal further drives this shift toward single-use systems.
The UK’s vibrant biotech ecosystem, bolstered by government funding and initiatives like the Life Sciences Vision, emphasizes modular production techniques. This, alongside the focus on domestic biologics production due to Brexit, is enhancing the adoption of bioprocess bags.
France’s strong government support for the pharmaceutical sector, combined with increasing adoption of single-use bioprocessing to optimize production costs, is driving market demand. The country is focusing on strengthening its biologics and vaccine production capabilities, boosting the need for bioprocess bags.
Germany's highly developed biotech and pharmaceutical sector, which prioritizes efficient manufacturing processes, is spurring the demand for single-use bioprocess bags. Government incentives for innovation and environmental sustainability in production methods are further fostering market growth.
Asia Pacific Bioprocess Bags Market Trends
The Asia Pacific bioprocess bags market is estimated to be the fastest-growing region with CAGR due to the growing population, with increasing healthcare needs. As a result, there is a growing demand for biopharmaceuticals in the region, which is driving the growth of the bioprocess bags market. Another factor driving the growth of the bioprocess bags market in the Asia Pacific region is the increasing investment in the biopharmaceutical industry. Governments and private investors in countries like China, Japan, and South Korea are investing heavily in the biopharmaceutical industry, which is expected to drive the demand for bioprocess bags.
The China bioprocess bags market is expanding due to substantial investments in biopharma manufacturing and the local government’s support of biotech innovation. Demand is also fueled by the rapid scaling of biosimilars and biologics production to cater to domestic and global markets.
Japan bioprocess bags market is driven by technological advancements in the biotech sector and the country's push toward local biopharmaceutical production. In addition, Japan’s focus on efficient, cost-saving manufacturing practices is increasing the adoption of single-use systems.
MEA Bioprocess Bags Market Trends
Growth in the bioprocess bags market is supported by the expansion of pharmaceutical manufacturing in the region, with increased investment from global biotech companies establishing operations. A focus on healthcare infrastructure development is further propelling market interest.
Saudi Arabia’s Vision 2030 plan, aimed at diversifying the economy and boosting local pharmaceutical production, is driving demand for bioprocess bags. The country’s focus on improving healthcare standards and supporting local biotech manufacturing has spurred market growth.
In Kuwait, the demand for bioprocess bags is rising due to increased government investment in healthcare and efforts to develop local biopharma capabilities. The shift toward enhancing pharmaceutical production capabilities is expected to fuel bioprocess bag adoption in the coming years.
Key Bioprocess Bags Company Insights
The market for Bioprocess Bags is highly competitive with the presence of well-established as well as small and mid-sized emerging players. A prominent number of players are rapidly opting for geographical expansion, strategic collaborations, and partnerships through mergers and acquisitions in emerging and economically favorable regions.
Key Bioprocess Bags Companies
The following key companies have been profiled for this study on the bioprocess bags market.
-
Thermo Fisher Scientific Inc.
-
Sartorius AG
-
Danaher Corporation
-
Merck KGaA
-
Saint-Gobain
-
Corning Incorporated
-
Entegris
-
Meissner Filtration Products, Inc.
-
PROAnalytics, LLC
-
CellBios Healthcare And Lifesciences Pvt Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Global Leaders (Thermo Fisher Scientific Inc., Sartorius AG, Danaher Corporation, Merck KGaA)
Focus on expanding end-to-end bioprocessing ecosystems covering upstream, downstream, and fill-finish operations. Drive growth through acquisitions, strategic collaborations with biopharma companies and CMOs, and continuous innovation in single-use assemblies, bioprocessing bags, and integrated workflow solutions. Strong emphasis on scaling capacity for biologics, cell & gene therapies, and vaccine manufacturing.
Extensive global footprint, diversified product portfolios, and strong regulatory compliance capabilities. High R&D investment enables advanced material science, validated single-use systems, and strong customer lock-in through integrated platform offerings.
High operational complexity and cost structures. Slower adaptability in addressing highly customized or price-sensitive regional requirements. Exposure to supply chain dependencies for specialized raw materials used in single-use systems.
Specialized Filtration & Material Science Players (Saint-Gobain, Corning Incorporated, Entegris)
Leverage core expertise in advanced materials, polymers, glass, and contamination control technologies to supply critical components such as films, tubing, connectors, and fluid handling systems used in bioprocessing bags and assemblies. Focus on innovation in high-purity materials and contamination-resistant solutions.
Strong materials engineering capabilities and deep expertise in contamination control and high-performance industrial materials. Strong relationships across semiconductor, life sciences, and industrial sectors enhance cross-sector innovation.
Limited direct exposure to full bioprocessing system integration. Dependence on downstream system integrators reduces value capture in finished single-use solutions.
Recent Development
-
In March 2023, Sartorius AG acquired France-based Polyplus for around USD 26.2 billion. This deal helps company expand its product portfolio in the market.
-
In August 2022, Thermo Fisher Scientific Inc opened its largest single use technology production facility in Greater Nashville, at USD 150 m. The Lebanon, Tennessee plant is the largest manufacturing facilities of company’s biologics production network.
-
In April 2022, Thermo Fischer Scientific, Inc. has announced the opening of a new manufacturing facility in Ogden, Utah, that will manufacture materials and technology needed for the development of new vaccines and therapies. This investment will enable the company to meet the increasing demand for single-use technology and contribute to the development of innovative therapies and vaccines. The facility is state-of-the-art and valued at USD 44 million.
Bioprocess Bags Market Report Scope
Report Attribute
Details
Market size in 2025
USD 4.8 billion
Estimated Market size in 2026
USD 5.6 billion
Projected market size by 2033
USD 15.4 billion
Growth rate
CAGR of 15.4% from 2026 to 2033
Historical data
2021 - 2025
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Workflow, product, end user, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Norway; Denmark; Sweden; China; Japan; India; South Korea; Australia; Thailand; Brazil; Argentina; Saudi Arabia; South Africa; UAE; Kuwait
Key companies profiled
Thermo Fisher Scientific Inc.; Sartorius AG, Danaher Corporation; Merck KGaA; Saint-Gobain; Corning Incorporated; Entegris; Meissner Filtration Products, Inc.; PROAnalytics, LLC; CellBios Healthcare & Lifesciences Pvt Ltd.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Bioprocess Bags Market Report Segmentation
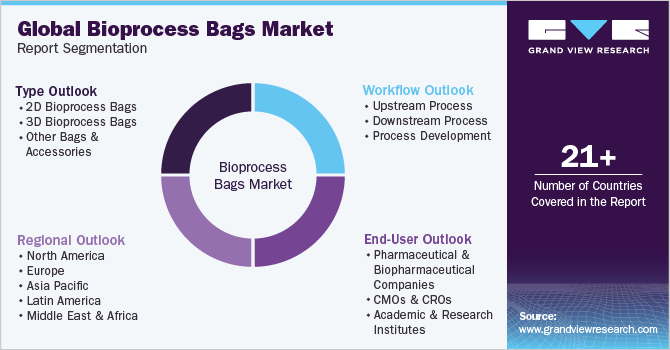
This report forecasts revenue growth and provides an analysis on the latest trends in each of the sub-segments from 2021 to 2033. For the purpose of this report, Grand View Research has segmented the bioprocess bags market based on type, workflow, end user, and region.
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
2D Bioprocess Bags
-
3D Bioprocess Bags
-
Other Bags & Accessories
-
-
Workflow Outlook (Revenue, USD Million, 2021 - 2033)
-
Upstream Process
-
Downstream Process
-
Process Development
-
-
End user Outlook (Revenue, USD Million, 2021 - 2033)
-
Pharmaceutical & Biopharmaceutical Companies
-
CMOs & CROs
-
Academic & Research Institutes
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
UK
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East and Africa (MEA)
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
Segment Definition
Segment - Workflow
Revenue capture definition
Upstream Process
Revenue in this segment is generated from the use of bioprocessing bags in early-stage production activities such as cell culture, media preparation, and seed expansion. Demand is driven by the need for sterile, flexible, and scalable solutions that support high-yield biologics production while minimizing contamination risks and setup time.
Downstream Process
This segment captures revenue from applications in purification, filtration, storage, and transport of biologics after cell harvesting. Bioprocessing bags are increasingly used to ensure closed-system handling, improve process efficiency, and reduce cross-contamination during product recovery and final formulation stages.
Process Development
Revenue here is generated from R&D and pilot-scale biomanufacturing activities where bioprocessing bags are used for process optimization, scalability testing, and experimental production runs. The segment benefits from growing investments in biologics development and the need for flexible, small-batch production systems.
Segment - Product
Revenue capture definition
2D Bioprocess Bags
Revenue in this segment is generated from flat, flexible bioprocessing bags widely used for storage, mixing, sampling, and transport of biopharmaceutical fluids. These bags are preferred for small-to-mid scale applications due to their cost-effectiveness, ease of handling, and compatibility with a wide range of upstream and downstream processes.
3D Bioprocess Bags
This segment captures revenue from single-use, large-volume bioprocessing bags designed for mixing, cell culture, and storage in commercial-scale biomanufacturing. Demand is driven by increasing adoption in large-volume biologics production, where scalability, sterility, and reduced contamination risk are critical.
Other Bags & Accessories
Revenue is generated from supporting consumables such as tubing assemblies, connectors, sampling systems, and ancillary bag components. These accessories are essential for ensuring closed-system operations, process integration, and efficient fluid transfer across biomanufacturing workflows.
Segment - End User
Revenue capture definition
Pharmaceutical & Biopharmaceutical Companies
This segment represents revenue from large pharmaceutical and biotech firms that utilize bioprocessing bags for commercial-scale production of biologics, vaccines, and advanced therapies. Adoption is driven by the need for scalable, compliant, and contamination-free manufacturing solutions.
CMOs & CROs
Revenue in this segment comes from contract manufacturing and research organizations that rely heavily on single-use systems to support multi-client production, rapid changeovers, and flexible capacity management across diverse biologics pipelines.
Academic and Research Institutes
This segment captures demand from universities and research centers using bioprocessing bags for experimental studies, process development, and early-stage biopharmaceutical research, where flexibility and low-volume operations are key requirements.
Estimation Model
Section
Content
Bottom-Up
Market size was estimated by analyzing revenues generated by key bioprocessing bags companies, supported by company annual reports, investor presentations, distributor insights, and premium databases. Revenue contributions from private companies were assessed using industry databases and validated through primary research to derive the overall market value.
Top-Down
Parent Market & Penetration-Based Analysis
The bioprocessing bags market was evaluated by analyzing the broader bioprocessing and related landscape and then allocating a proportionate share based on usage intensity, adoption rates, and workflow penetration. This method is commonly validated using macro drivers such as biologics production growth, installed biomanufacturing capacity, and regional industry trends.Segmentation
Country-Level Segment Share Modeling
Product, workflow, and end-user segments were derived using country-specific adoption patterns, healthcare infrastructure, reimbursement scenarios, and product penetration rates. Weighted average calculations were applied to determine regional and global segment distributions.Validation
Data Triangulation & Validation Model
Market estimates were validated through triangulation of secondary research, primary research, and demand-side adoption analysis to ensure consistency and accuracy across all market segments and geographies.Forecasting
Forecasting & CAGR Model
Market forecasts were developed using historical market trends, technology adoption patterns, product innovation developments, regression-based analysis, and trend modeling to project future market growth.Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Single-Use Bioprocess Bags Market Landscape & Adoption Trends Analysis
Developed a tailored analysis of the bioprocess bags market focusing on adoption trends across upstream, downstream, and fill-finish bioprocessing applications. The study incorporated evaluation of single-use technology penetration in biologics manufacturing, vaccine production, cell and gene therapy workflows, and contract manufacturing organizations (CMOs), along with material innovation trends such as multi-layer films and gamma-sterilized systems.
Enables stakeholders to understand the evolving shift from stainless-steel to single-use systems, identify high-growth application areas, evaluate manufacturing flexibility advantages, and assess cost-efficiency benefits driving adoption in biopharmaceutical production.
Competitive Landscape & Technology Differentiation Assessment
Delivered a customized evaluation of key market participants across bioprocess bag manufacturing, including product portfolio benchmarking, material science advancements, system compatibility (bioreactors, mixing systems, storage), and customization capabilities for sterile fluid handling. The analysis also covered supply chain integration, regulatory compliance, and innovation in scalable single-use solutions.
Provides actionable insights into competitive positioning, technology differentiation, supplier consolidation trends, and innovation gaps, helping clients optimize sourcing strategies, enhance product development pipelines, and strengthen market entry decisions.
Manufacturing Expansion & Supply Chain Optimization Opportunity Assessment
Conducted a focused assessment of global bioprocessing capacity expansion, including demand for flexible manufacturing infrastructure, regional biologics production growth, outsourcing trends to CDMOs, and risk mitigation in sterile fluid handling systems.
Supports strategic investment planning by identifying capacity expansion opportunities, reducing supply chain risks, improving manufacturing efficiency, and strengthening business cases for regional production hubs and integrated single-use system adoption.
Frequently Asked Questions About This Report
The global bioprocess bags market size was estimated at USD 4.8 billion in 2025 and is expected to reach USD 5.6 billion in 2026.
The global bioprocess bags market is expected to grow at a compound annual growth rate of 15.4% from 2026 to 2033 to reach USD 15.4 billion by 2033.
The upstream process segment held the largest share of 43.9% in 2025. Bioprocessing bags are widely used in upstream processes for cell culture, media preparation, and fermentation.
Some key players operating in the bioprocess bags market include Thermo Fisher Scientific Inc., Sartorius AG, Danaher Corporation, Merck KGaA, Saint-Gobain, Corning Incorporated, Entegris, Meissner Filtration Products, Inc., PROAnalytics, LLC, CellBios Healthcare And Lifesciences Pvt Ltd.
The market is being driven by several factors such as, the growing demand for biopharmaceuticals, including monoclonal antibodies and vaccines, advancements in bioprocess technology, such as single-use systems and disposable bioprocess bags, and the increasing adoption of modular manufacturing.
North America dominated the Bioprocessing Bags Market with the largest revenue share of 35.5% in 2025.
Asia Pacific is the fastest growing region.
The 2D bioprocess bags segment led the market with the largest revenue share of 46.0% in 2025
Pharmaceutical & Biopharmaceutical Companies segment led the market with the largest revenue share of 46.0% in 2025
About the Author(s)
Biotechnology Research Team
Healthcare · BiotechnologyThis report was authored by the biotechnology research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the biotechnology segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


