
- Home
- »
- Clinical Diagnostics
- »
-
Blood-based Biomarkers Market Size Report, 2026-2033GVR Report cover

Blood-based Biomarkers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Genetic Biomarkers, Protein Biomarkers), By Application (Cancer, Cardiovascular Diseases), By Technology, By End-use, By Region, And Segment Forecasts
Market Size, 2025
$8.7BMarket Estimate, 2026
$9.3BMarket Forecast, 2033
$15.3BCAGR, 2026–2033
7.4%Blood-based Biomarkers Market Summary
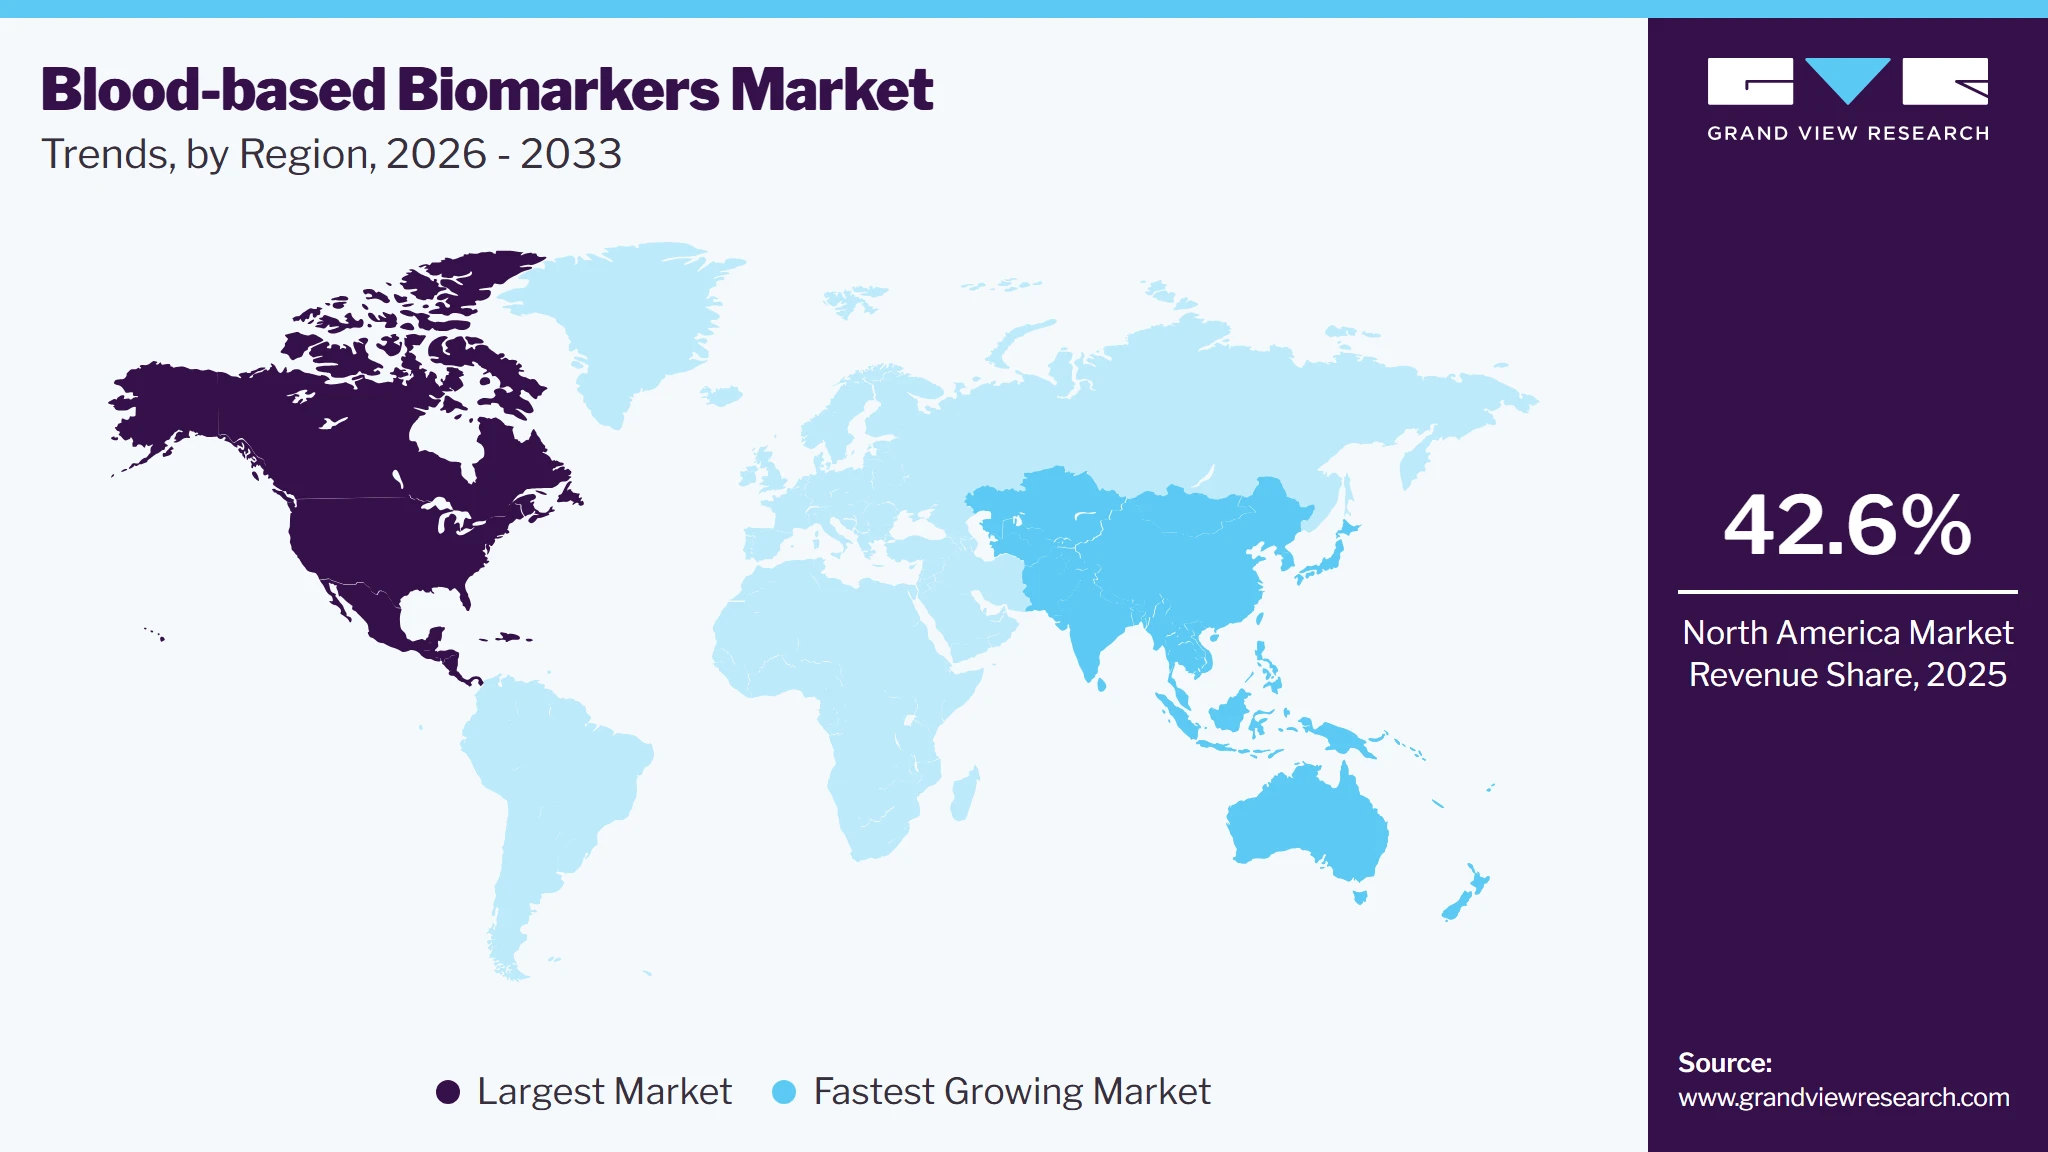
The global blood-based biomarkers market size was valued at USD 8.7 billion in 2025 and is projected to grow from USD 9.3 billion in 2026 to USD 15.3 billion by 2033, at a CAGR of 7.4% from 2026 to 2033. North America dominated the market, accounting for the largest revenue share of 42.6% in 2025. The market is driven by the growing adoption of precision medicine, increasing use of minimally invasive diagnostics, and advancements in molecular diagnostic technologies such as NGS and digital PCR.
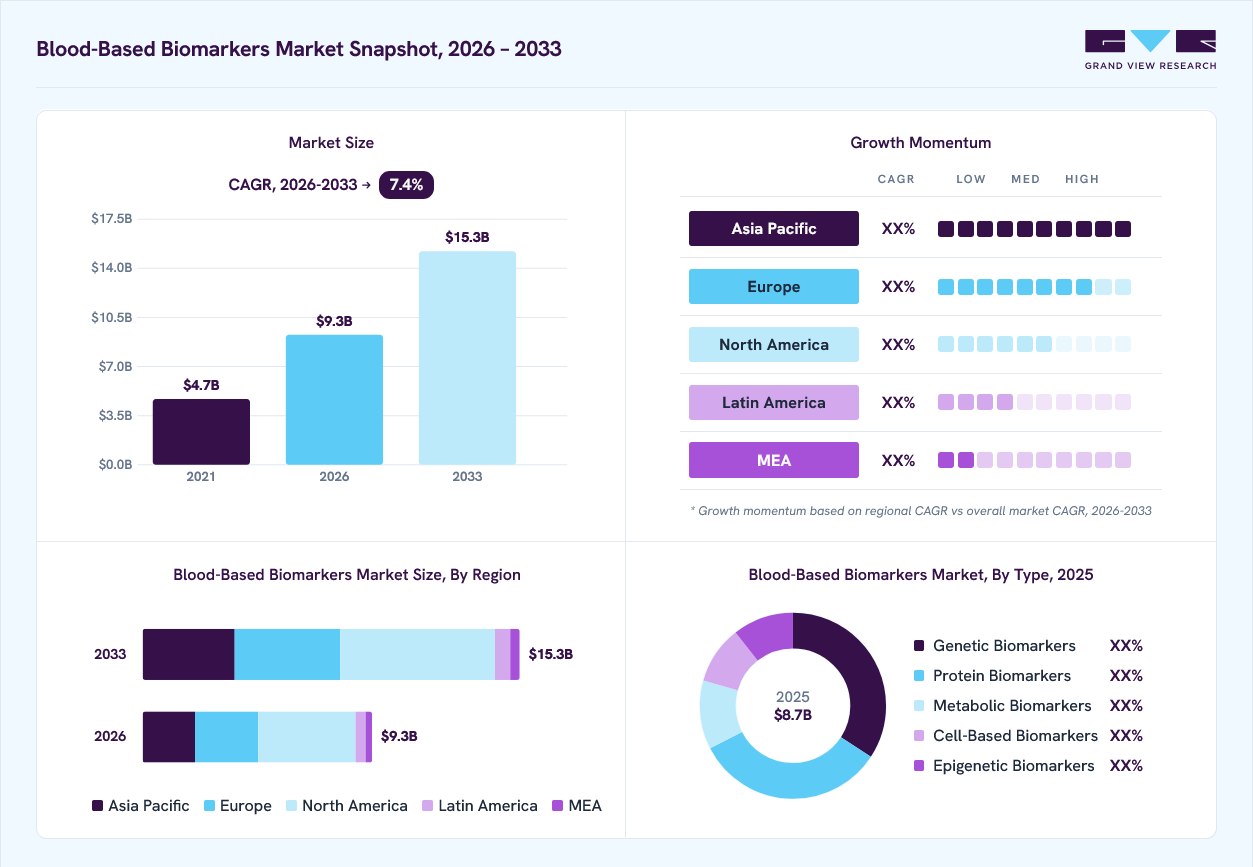 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
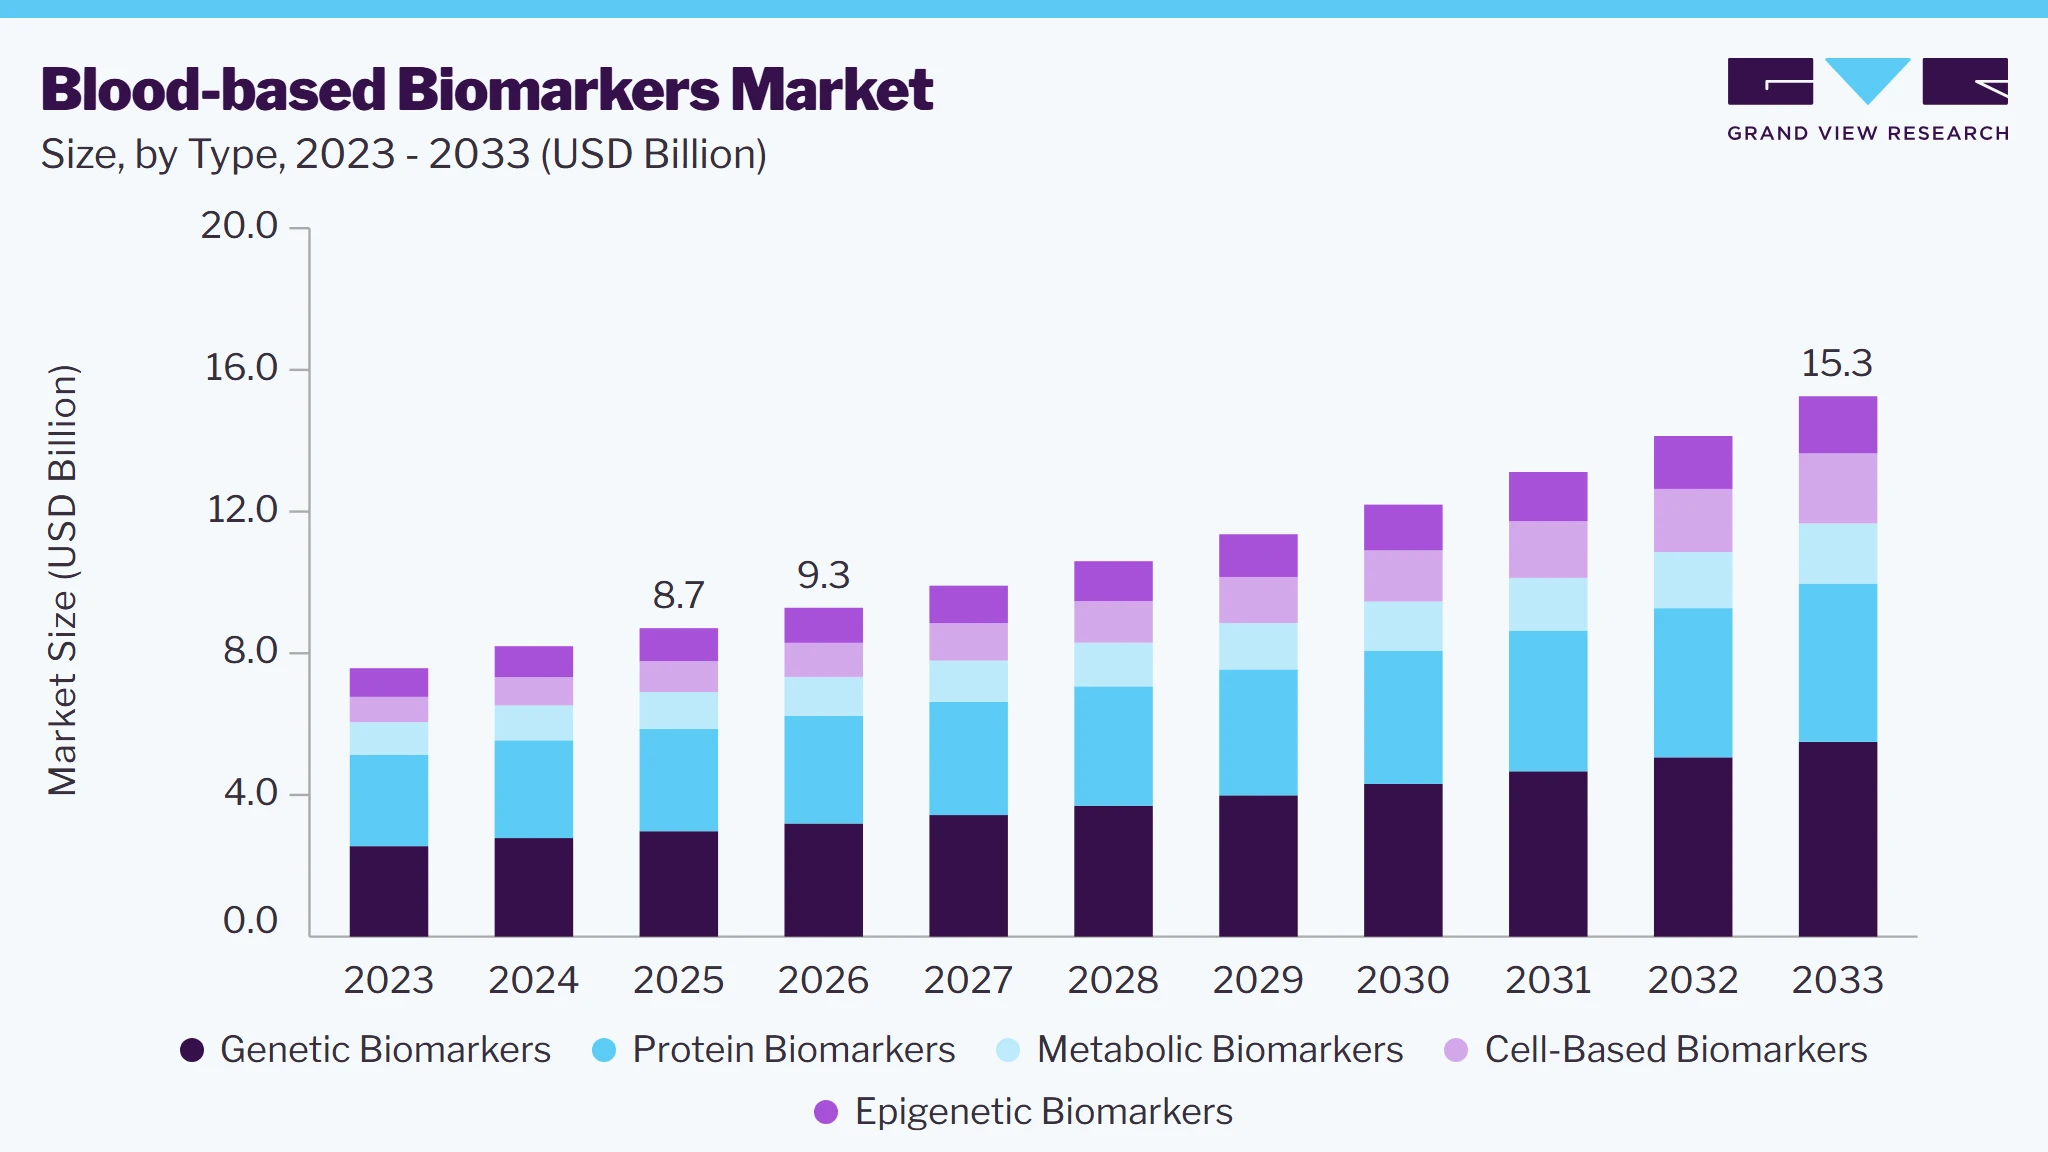
- By type: Genetic biomarkers segment led the market with the largest revenue share of 34.2% in 2025.
- By application: Cancer segment led the market with the largest revenue share of 39.0% in 2025.
- By technology: Next-Generation Sequencing segment led the market with the largest revenue share of 35.6% in 2025.
- By end use: Hospitals & clinics segment led the market with the largest revenue share of 47.3% in 2025.
Regional Highlights
- Largest regional market: North America (42.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 8.7 Billion
- Estimated market size in 2026: USD 9.3 Billion
- Projected market size by 2033: USD 15.3 Billion
- CAGR (2026-2033): 7.4%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
 To learn more about this report, Download Free Sample Report
Furthermore, the rising burden of cancer and neurological disorders, along with the integration of multi-omics platforms and AI-based biomarker analysis, is supporting broader clinical adoption of blood-based biomarkers.Market Dynamics
The growing adoption of precision medicine and companion diagnostics is a primary factor driving the growth of the blood-based biomarkers industry. Healthcare providers are increasingly leveraging biomarker-guided testing to enable personalized treatment strategies based on an individual's molecular and genetic profile. Blood-based biomarkers offer a minimally invasive approach for disease detection, patient stratification, therapy selection, treatment monitoring, and recurrence surveillance, making them an attractive alternative to conventional tissue biopsies. Their ability to support repeated sampling with reduced patient burden has significantly expanded their use across oncology and other chronic disease indications. Furthermore, continuous advancements in molecular diagnostic technologies, including next-generation sequencing (NGS), digital PCR, and comprehensive genomic profiling, have enhanced the analytical performance and clinical utility of blood-based biomarker assays, supporting their broader integration into routine clinical practice.
The increasing emphasis on biomarker-driven drug development and targeted therapies is further accelerating market expansion. Pharmaceutical and diagnostic companies are strengthening collaborations to develop companion diagnostics that improve treatment selection, clinical outcomes, and regulatory success for precision medicines. For instance in January 2026, multi-year strategic collaboration between Guardant Health and Merck was announced to develop companion diagnostics and support the commercialization of targeted oncology therapies using Guardant Health's liquid biopsy platform. The collaboration underscores the growing role of blood-based biomarkers in precision oncology by facilitating the identification of eligible patients and enabling real-time disease monitoring. Such strategic initiatives are expected to accelerate clinical adoption, expand the commercial availability of advanced blood-based biomarker tests, and reinforce the long-term growth trajectory of the global blood-based biomarkers market.
The high cost associated with the discovery, validation, and commercialization of blood-based biomarkers remains a significant restraint on market growth. Developing clinically reliable biomarker assays requires extensive biomarker discovery, large-scale multicenter clinical studies, analytical validation, and regulatory approval, all of which involve substantial investments and lengthy development timelines. Advanced technologies such as next-generation sequencing (NGS), digital PCR, mass spectrometry, and multi-omics platforms further increase testing costs due to expensive instrumentation, specialized reagents, and the need for highly skilled personnel. These factors can limit the widespread adoption of blood-based biomarker tests, particularly in cost-sensitive healthcare systems and emerging markets where laboratory infrastructure and reimbursement support remain limited.
In addition, the lack of standardized validation protocols and variable reimbursement policies continue to hinder market expansion. Blood-based biomarkers must demonstrate consistent analytical performance, clinical validity, and clinical utility across diverse patient populations before they can be routinely implemented in clinical practice. Variability in biomarker expression, differences in assay methodologies, and evolving regulatory requirements often prolong product development and market entry. Furthermore, limited reimbursement for certain novel biomarker tests may discourage healthcare providers from adopting advanced assays despite their clinical benefits. Addressing these challenges through standardized validation frameworks, harmonized regulatory pathways, and broader reimbursement coverage will be critical to accelerating the commercialization and adoption of blood-based biomarker technologies.
The growing integration of multi-omics technologies and artificial intelligence (AI) presents a significant opportunity for the blood-based biomarkers industry. Combining genomics, proteomics, transcriptomics, metabolomics, and epigenomics enables the identification of comprehensive biomarker signatures that improve disease detection, risk stratification, and treatment monitoring. AI-powered analytics further enhance the interpretation of complex biological datasets by identifying clinically relevant patterns and accelerating biomarker discovery. These advancements are expanding the clinical utility of blood-based biomarkers beyond oncology into neurological, cardiovascular, metabolic, and autoimmune diseases, while supporting the development of next-generation precision diagnostics and personalized treatment strategies.
The increasing commercialization of AI-enabled biomarker platforms is reinforcing this growth opportunity. For instance, in May 2026, Guardant Health received U.S. FDA approval for the next-generation Guardant360 Liquid CDx, featuring an approximately 100-fold expanded genomic footprint and integrating genomic and epigenomic biomarkers to improve comprehensive molecular profiling for patients with advanced solid tumors. The enhanced platform strengthens the role of blood-based biomarkers in precision oncology by enabling broader biomarker detection and supporting targeted therapy selection. Such technological advancements are expected to accelerate clinical adoption, expand testing capabilities, and create substantial long-term growth opportunities for the global blood-based biomarkers market.
Moreover, the expanding application of blood-based biomarkers in neurodegenerative, cardiovascular, infectious, and metabolic diseases is expected to unlock significant future market potential. Growing investments in biomarker research, increasing availability of high-throughput analytical platforms, and the adoption of AI-enabled clinical decision support tools are facilitating the discovery and validation of novel biomarkers for early disease detection and longitudinal patient monitoring. Furthermore, collaborations between pharmaceutical companies, diagnostic developers, and research institutions are accelerating the translation of biomarker discoveries into commercially available diagnostic tests. As healthcare systems continue to prioritize early diagnosis, personalized treatment, and preventive care, these innovations are expected to broaden the clinical adoption of blood-based biomarkers and create sustained opportunities for market expansion.
Market Concentration & Characteristics
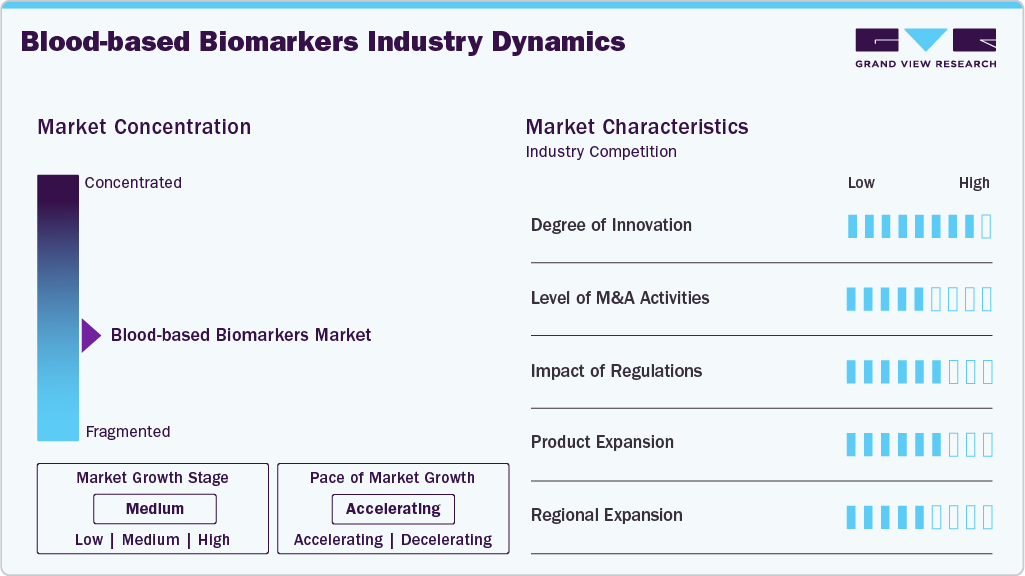
The market for blood-based biomarkers demonstrates a high degree of innovation, driven by advancements in liquid biopsy, multi-omics technologies, and AI-enabled molecular diagnostics. Continuous innovations are enhancing biomarker discovery, disease detection, and precision medicine applications across multiple therapeutic areas. For instance, in January 2026, Illumina launched Illumina Connected Multiomics, a cloud-based platform integrating genomics, transcriptomics, proteomics, and epigenomics with AI-driven analytics. The platform streamlines multi-omics data analysis, accelerates biomarker discovery, and supports the development of next-generation blood-based diagnostic solutions for clinical and research applications.
The blood-based biomarkers industry exhibits a moderate level of mergers and acquisitions, with companies selectively acquiring technologies that strengthen their capabilities in biomarker discovery, molecular diagnostics, and precision medicine. While strategic collaborations and product innovations remain the dominant competitive strategies, targeted acquisitions are enabling market participants to expand their technology portfolios, enhance research capabilities, and accelerate the commercialization of advanced biomarker solutions. For instance: In July 2025, Quanterix completed the acquisition of Akoya Biosciences, creating the industry's first integrated platform for measuring blood- and tissue-based protein biomarkers across the research-to-clinical continuum. The acquisition expanded Quanterix's biomarker portfolio in neurology, oncology, and immunology, strengthening its precision medicine capabilities and accelerating the development and commercialization of advanced blood-based biomarker solutions.
 To learn more about this report, Download Free Sample Report
The market is significantly influenced by stringent regulatory requirements governing the development, validation, approval, and commercialization of biomarker-based diagnostic tests. Regulatory agencies such as the U.S. FDA, European Medicines Agency (EMA), and implementation of the EU In Vitro Diagnostic Regulation (IVDR) require robust analytical and clinical evidence to demonstrate the safety, accuracy, and clinical utility of blood-based biomarker assays. Although these regulations increase development costs and approval timelines, they enhance product quality, standardization, and clinical confidence. Well-defined regulatory pathways also support innovation by facilitating the approval of advanced liquid biopsy, companion diagnostic, and precision medicine solutions, ultimately driving sustainable long-term market growth.
The global blood-based biomarkers industry is witnessing continuous product portfolio expansion as companies introduce advanced blood-based diagnostic solutions to strengthen their precision medicine offerings and address the growing demand for minimally invasive testing. In April 2025, Labcorp expanded its precision oncology portfolio by launching Labcorp Plasma Detect for recurrence assessment in stage III colon cancer and commercializing PGDx elio plasma focus Dx, the first FDA-authorized kitted pan-solid tumor liquid biopsy assay. This expansion strengthened Labcorp's blood-based biomarker testing capabilities, enhanced comprehensive molecular profiling, and supported the broader adoption of precision oncology diagnostics in clinical practice.
The market for blood-based biomarkers is experiencing significant global expansion, as companies strengthen their commercial presence across developed and emerging markets to meet the growing demand for precision diagnostics. Market participants are expanding their distribution networks, laboratory infrastructure, strategic partnerships, and commercialization activities to improve access to advanced blood-based biomarker testing. This geographic expansion supports the broader adoption of minimally invasive diagnostics, enhances the availability of precision medicine solutions, and enables companies to capitalize on emerging growth opportunities. Increasing investments in healthcare infrastructure and molecular diagnostic capabilities across Asia Pacific, Latin America, and the Middle East & Africa are further supporting the market's regional expansion.
Analyst Perspective
The blood-based biomarkers market is poised for sustained growth, driven by the increasing demand for minimally invasive diagnostics, precision medicine, and early disease detection. Advancements in liquid biopsy, next-generation sequencing, proteomics, and AI-enabled biomarker analysis are improving diagnostic accuracy and expanding clinical applications across oncology, cardiovascular, neurological, and infectious diseases. Growing investments in biomarker research, pharmaceutical collaborations, and companion diagnostics are accelerating product innovation and commercialization. While regulatory complexities, reimbursement challenges, and clinical validation requirements remain key hurdles, ongoing technological advancements and broader healthcare adoption are expected to drive market penetration, positioning blood-based biomarkers as a cornerstone of future personalized diagnostics.
Application Insights
The cancer segment accounted for the largest revenue share of 39.0% in 2025, driven by the growing global cancer burden and the increasing adoption of precision oncology and liquid biopsy technologies. According to the International Agency for Research on Cancer (IARC), approximately 20 million new cancer cases and 9.7 million cancer-related deaths were reported worldwide in 2022, highlighting the urgent need for early detection and personalized treatment strategies. Blood-based biomarkers, including circulating tumor DNA (ctDNA), circulating tumor cells (CTCs), and cell-free DNA (cfDNA), are increasingly used for cancer screening, therapy selection, treatment monitoring, and minimal residual disease assessment. For instance, in September 2025, Exact Sciences launched Cancerguard EX, a blood-based multi-cancer screening test that detects signals associated with multiple cancer types from a single blood sample, thereby expanding the adoption of blood-based biomarkers for early cancer detection and precision oncology.
The neurological diseases segment is anticipated to register the fastest CAGR of 9.1% during the forecast period, driven by the growing global burden of neurodegenerative disorders and the increasing demand for minimally invasive diagnostic approaches. According to the World Health Organization (WHO), neurological conditions affect more than 3 billion people worldwide and have become the leading cause of ill health and disability globally, underscoring the need for earlier and more accurate diagnosis. Blood-based biomarkers, including neurofilament light chain (NfL), phosphorylated tau (p-tau), amyloid-beta, and glial fibrillary acidic protein (GFAP), are gaining significant clinical attention for the early detection and monitoring of Alzheimer's disease, Parkinson's disease, multiple sclerosis, and other neurological disorders. For instance, in April 2025, Fujirebio launched the Lumipulse G pTau217/β-Amyloid 1-42 Plasma Ratio assay in Europe, expanding access to blood-based biomarker testing for Alzheimer's disease and strengthening the adoption of minimally invasive neurological diagnostics.
Technology Insights
The Next-Generation Sequencing (NGS) segment dominated the global market with a revenue share of 35.6% in 2025, owing to its ability to simultaneously analyze multiple genetic alterations with high sensitivity, accuracy, and throughput from a single blood sample. NGS has become the preferred technology for liquid biopsy, comprehensive genomic profiling (CGP), companion diagnostics, and minimal residual disease (MRD) monitoring, particularly in oncology. Its expanding adoption is driven by continuous improvements in sequencing speed, declining sequencing costs, advanced bioinformatics capabilities, and the growing integration of precision medicine into clinical practice. For instance, in March 2026, Illumina and Labcorp expanded their precision oncology collaboration to co-commercialize Labcorp's FDA-authorized PGDx elio plasma focus Dx liquid biopsy assay alongside Illumina's TruSight Oncology Comprehensive test, broadening access to NGS-based blood biomarker testing and comprehensive genomic profiling for precision oncology.
The Immunoassays segment is anticipated to witness lucrative growth over the forecast period, owing to the increasing demand for rapid, high-throughput, and cost-effective blood-based biomarker detection across oncology, cardiovascular, neurological, infectious, and autoimmune diseases. Immunoassays remain widely adopted in clinical laboratories due to their high analytical sensitivity, ease of automation, and compatibility with routine diagnostic workflows. Growing emphasis on early disease detection, biomarker-based screening, and precision medicine is further accelerating the adoption of advanced immunoassay platforms. For instance, in April 2025, Labcorp expanded its precision oncology portfolio with the commercial availability of Labcorp Plasma Detect and the FDA-authorized PGDx elio plasma focus Dx liquid biopsy assay, strengthening access to blood-based biomarker testing and supporting the broader adoption of immunoassay- and molecular-based diagnostic workflows in precision oncology.
Type Insights
The genetic biomarkers segment accounted for the largest revenue share of 34.2% in 2025, driven by the growing adoption of precision medicine and the widespread use of genetic biomarker testing for disease diagnosis, prognosis, treatment selection, and therapeutic monitoring. Blood-based genetic biomarkers, including circulating tumor DNA (ctDNA), cell-free DNA (cfDNA), and gene mutation analysis, play a pivotal role in liquid biopsy and precision oncology. Advancements in next-generation sequencing (NGS), digital PCR, and comprehensive genomic profiling have significantly improved analytical sensitivity and clinical utility. For instance, in June 2025, QIAGEN and GENCURIX partnered under the QIAcuityDx Partnering Program to develop digital PCR-based molecular assays, expanding access to highly sensitive blood-based genetic biomarker testing for precision diagnostics.
The cell-based biomarkers segment is anticipated to witness the fastest CAGR during the forecast period, driven by the expanding adoption of liquid biopsy technologies and increasing demand for minimally invasive cancer diagnostics. The segment benefits from continuous advancements in molecular detection technologies, particularly digital PCR, next-generation sequencing (NGS), and high-sensitivity cell isolation platforms, which have significantly improved the detection and characterization of circulating tumor cells (CTCs). These biomarkers are increasingly utilized for early cancer detection, treatment selection, disease monitoring, and recurrence assessment. The growing integration of cell-based biomarker analysis into precision oncology workflows, coupled with ongoing technological innovations that enhance analytical sensitivity and clinical reliability, is expected to accelerate segment growth throughout the forecast period.
End-Use Insights
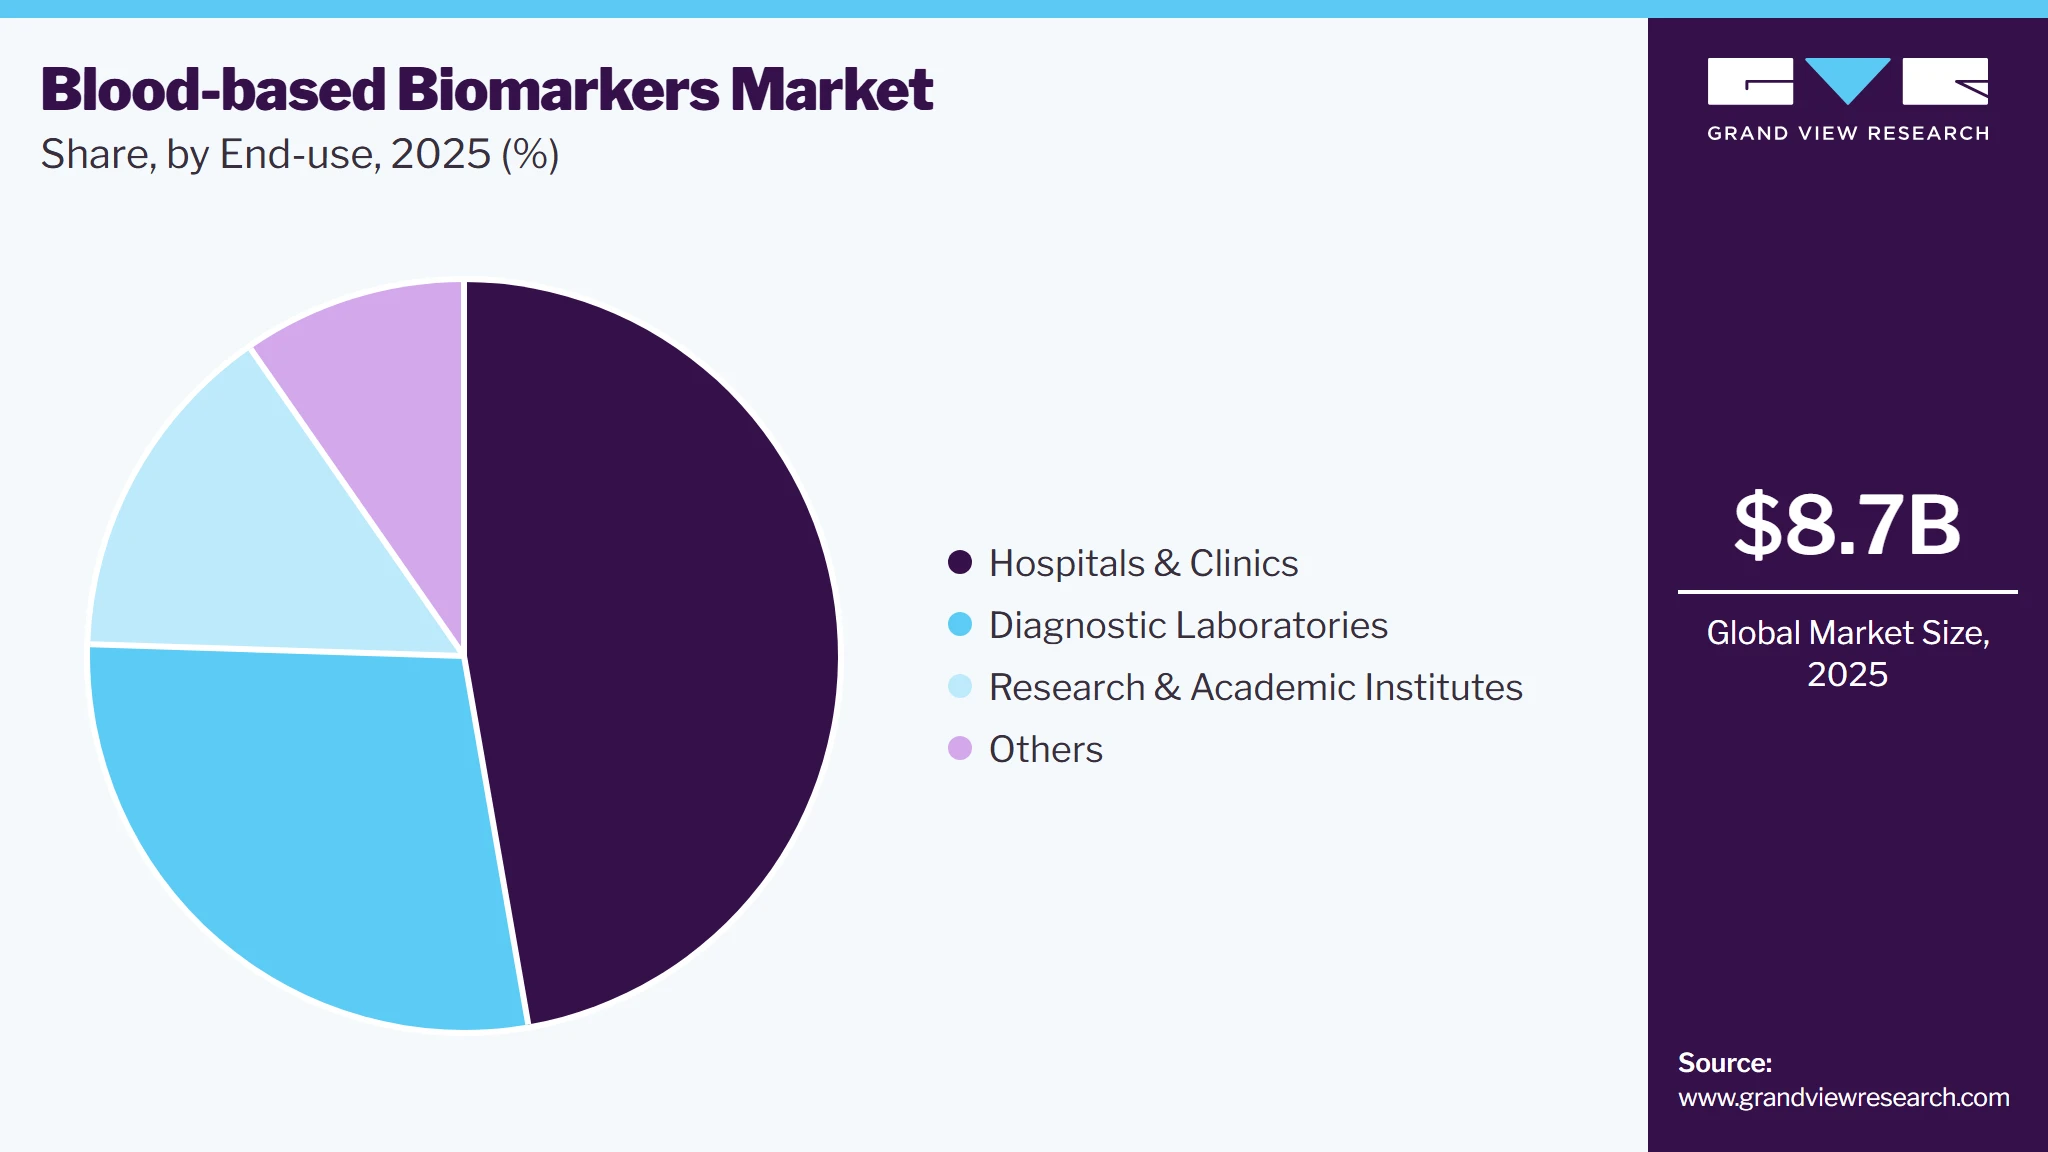
The hospitals & clinics segment held the largest revenue share of 47.3% in 2025, driven by the high volume of diagnostic testing, growing adoption of precision medicine, and the availability of advanced laboratory infrastructure for blood-based biomarker analysis. Hospitals and specialty clinics are the primary settings for cancer screening, chronic disease diagnosis, therapy selection, and treatment monitoring, supported by integrated pathology, molecular diagnostics, and clinical laboratory services. The increasing incorporation of liquid biopsy, next-generation sequencing (NGS), immunoassays, and biomarker-guided clinical decision-making into routine patient care continues to strengthen the adoption of blood-based biomarkers, enabling earlier disease detection, personalized treatment selection, and improved patient management across a wide range of clinical applications.
 To learn more about this report, Download Free Sample Report
The diagnostic laboratories segment is anticipated to witness lucrative growth over the forecast period, driven by the increasing outsourcing of specialized diagnostic testing, rising demand for high-throughput blood-based biomarker analysis, and expanding adoption of precision medicine. Independent and reference laboratories are investing in advanced molecular diagnostics, next-generation sequencing (NGS), digital PCR, and automated immunoassay platforms to deliver highly accurate and scalable biomarker testing services. Growing test volumes for oncology, neurological, cardiovascular, and infectious diseases, coupled with the need for standardized and rapid turnaround times, are further accelerating segment growth. Additionally, the expansion of centralized laboratory networks and increasing collaborations between diagnostic laboratories and healthcare providers are strengthening access to advanced blood-based biomarker testing across routine clinical practice.
Regional Insights
The North America blood based biomarkers industry led with a revenue share of 42.6% in 2025, owing to its highly developed precision medicine ecosystem, widespread adoption of liquid biopsy technologies, and strong integration of biomarker-guided diagnostics into routine clinical care. The region benefits from advanced molecular diagnostic laboratories, robust healthcare reimbursement systems, and extensive investments in genomic research and translational medicine. High prevalence of cancer, cardiovascular, and neurological disorders continues to drive demand for minimally invasive diagnostic solutions. Furthermore, the presence of leading biotechnology and diagnostic companies, increasing clinical validation of blood-based biomarkers, expanding companion diagnostic applications, and strong collaboration between healthcare providers, research institutions, and pharmaceutical companies continue to accelerate innovation and commercialization across the regional market.
 To learn more about this report, Download Free Sample Report
U.S. Blood-based Biomarkers Market Trends
The U.S. blood based biomarkers industry accounted for the major revenue share in 2025, supported by its leadership in precision oncology, genomic medicine, and advanced molecular diagnostics. The country has a well-established network of academic medical centers, clinical laboratories, and biotechnology companies actively developing and commercializing blood-based biomarker assays. Growing adoption of liquid biopsy for cancer detection, treatment selection, and disease monitoring, coupled with increasing use of biomarker-driven companion diagnostics, continues to strengthen market demand. Favorable reimbursement for advanced molecular testing, high healthcare expenditure, continuous clinical research, and rapid integration of artificial intelligence and next-generation sequencing into diagnostic workflows further reinforce the country's dominant market position.
Europe Blood-based Biomarkers Market Trends
Europe blood based biomarkers industry represented a significant share of the global market, driven by growing adoption of personalized medicine, expanding molecular diagnostic capabilities, and supportive regulatory frameworks for innovative in vitro diagnostics. The region continues to strengthen national genomic medicine initiatives and cancer screening programs while investing heavily in biomarker discovery and translational research. Increasing utilization of liquid biopsy, immunoassays, and genomic profiling across oncology and chronic disease management is further supporting market expansion. Collaborative research networks, strong academic-industry partnerships, and increasing healthcare investments are accelerating the clinical adoption of blood-based biomarker testing throughout hospitals, diagnostic laboratories, and specialized healthcare centers across the region.
The UK blood-based biomarkers industry is experiencing steady growth due to increasing emphasis on early disease detection, precision medicine, and genomic healthcare integration. The country's strong clinical research infrastructure, supported by national healthcare initiatives and collaborations between academic institutions and biotechnology companies, has accelerated the adoption of biomarker-based diagnostics. Expanding implementation of liquid biopsy in oncology, growing use of molecular testing for chronic disease management, and continuous investments in genomic sequencing capabilities are strengthening market development. Additionally, increasing demand for minimally invasive diagnostic approaches and broader access to advanced laboratory testing are supporting the integration of blood-based biomarkers into routine clinical practice across the National Health Service.
Germany blood based biomarkers industry remains one of Europe's leading markets owing to its advanced healthcare infrastructure, well-established diagnostic laboratory network, and strong focus on precision medicine. The country benefits from significant investments in molecular diagnostics, clinical genomics, and biomedical research, supporting the rapid adoption of innovative biomarker technologies. Rising incidence of cancer and other chronic diseases has increased demand for liquid biopsy, companion diagnostics, and comprehensive genomic profiling. Furthermore, collaborations between research institutes, hospitals, and diagnostic companies, together with increasing utilization of automated laboratory platforms and advanced sequencing technologies, continue to strengthen Germany's position within the European market.
Asia Pacific Blood-based Biomarkers Market Trends
Asia Pacific blood based biomarkers industry is projected to register the fastest growth during the forecast period, driven by expanding healthcare infrastructure, rising awareness of early disease diagnosis, and increasing investments in precision medicine. Rapid growth in molecular diagnostic laboratories, wider adoption of genomic testing, and government initiatives supporting advanced healthcare technologies are significantly boosting market demand. The growing burden of cancer, cardiovascular diseases, and neurological disorders has accelerated the need for minimally invasive diagnostic solutions. Additionally, increasing healthcare expenditure, improving access to advanced laboratory services, and expanding biotechnology research activities are creating favorable conditions for sustained market growth across the region.
Japan blood based biomarkers industry represents a technologically advanced, supported by its aging population, high burden of chronic diseases, and strong emphasis on precision healthcare. The country has established sophisticated diagnostic infrastructure and continues to invest in molecular diagnostics, genomic medicine, and biomarker-based clinical research. Increasing utilization of liquid biopsy for oncology, adoption of automated laboratory technologies, and growing demand for personalized treatment strategies are driving market expansion. Strong collaboration among academic institutions, pharmaceutical companies, and diagnostic manufacturers, combined with favorable healthcare accessibility and continuous innovation in clinical diagnostics, further supports the growth of blood-based biomarker testing across Japan.
China blood based biomarkers industry is emerging as one of the fastest-growing markets, fueled by rapid healthcare modernization, expanding biotechnology capabilities, and increasing government support for precision medicine initiatives. Rising prevalence of cancer and chronic diseases has accelerated demand for advanced molecular diagnostics and liquid biopsy technologies. Significant investments in genomic sequencing infrastructure, expanding domestic diagnostic manufacturing, and growing adoption of biomarker-guided therapies are contributing to market growth. The country's large patient population, continuous healthcare reforms, increasing clinical research activities, and strengthening partnerships between hospitals and biotechnology companies continue to enhance the commercialization and accessibility of blood-based biomarker diagnostics.
Latin America Blood-based Biomarkers Market Trends
Latin America blood based biomarkers industry is witnessing steady growth, supported by improving healthcare infrastructure, expanding access to molecular diagnostic services, and increasing awareness of early disease detection. Growing prevalence of oncology and chronic diseases is encouraging healthcare providers to adopt minimally invasive diagnostic technologies for timely diagnosis and treatment monitoring. Investments in laboratory modernization, rising healthcare expenditure, and increasing collaborations with international diagnostic companies are strengthening regional testing capabilities. Furthermore, gradual expansion of precision medicine programs, wider availability of advanced laboratory services, and improving access to genomic technologies are expected to create favorable growth opportunities across the Latin American market.
MEA Blood-based Biomarkers Market Trends
The Middle East & Africa blood-based biomarkers industry is expected to experience moderate growth, driven by ongoing healthcare modernization, expanding diagnostic infrastructure, and increasing government focus on early disease detection. Several countries are investing in advanced molecular diagnostic laboratories, precision medicine initiatives, and cancer screening programs to improve healthcare outcomes. Rising prevalence of chronic diseases, improving access to specialized diagnostic services, and growing awareness regarding minimally invasive testing are contributing to increasing adoption of blood-based biomarkers. In addition, expanding collaborations between regional healthcare providers and international diagnostic companies, along with continued investments in laboratory automation and genomic medicine, are supporting long-term market development across the region.
Key Blood-based Biomarkers Company Insights
The global blood-based biomarkers industry is moderately consolidated, with leading companies competing through technological innovation, strategic collaborations, product launches, regulatory approvals, and expansion of precision diagnostic portfolios. Major players are strengthening their positions by investing in liquid biopsy platforms, next-generation sequencing, immunoassays, and companion diagnostics to support early disease detection and personalized treatment. Companies are also expanding global laboratory networks and integrating artificial intelligence and advanced bioinformatics into biomarker analysis. Continuous investments in research and development and collaborations with pharmaceutical companies are expected to further intensify competition and accelerate market growth.
Key Blood-based Biomarkers Companies:
The following key companies have been profiled for this study on the blood-based biomarkers market.
-
Abbott
-
BIOMÉRIEUX
-
F. Hoffmann-La Roche Ltd.
-
Siemens Healthineers AG
-
Thermo Fisher Scientific, Inc.
-
Bio-Rad Laboratories, Inc
-
Cleveland Diagnostics, Inc.
-
Sysmex Corporation
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
- Mature Players: Abbott
- Focus on expanding liquid biopsy, molecular diagnostics, and companion diagnostic portfolios through continuous product innovation and regulatory approvals.
- Invest in strategic collaborations with pharmaceutical companies to strengthen precision medicine and biomarker-driven therapy selection.
- Expand global commercial footprint through acquisitions, laboratory partnerships, and investments in AI-enabled biomarker analytics and next-generation sequencing (NGS).
- Strong global distribution networks, established brand recognition, and broad regulatory approvals across multiple disease areas.
- Comprehensive product portfolios spanning immunoassays, molecular diagnostics, sequencing, and automated laboratory platforms.
- Extensive R&D capabilities, large installed instrument base, and strong relationships with hospitals, diagnostic laboratories.
- High development and commercialization costs associated with advanced biomarker technologies.
- Complex regulatory approval and reimbursement pathways delaying market expansion.
- Dependence on centralized laboratory infrastructure and skilled personnel for advanced blood-based biomarker testing.
- Emerging Players: Sysmex Corporation
- Focus on innovative blood-based biomarker assays for oncology, neurodegenerative disorders, and early disease detection.
- Expand through collaborations with academic institutions, biotechnology companies, and clinical laboratories to accelerate commercialization.
- Develop highly sensitive, AI-enabled, and multiplex biomarker platforms to improve diagnostic accuracy and clinical utility.
- Greater agility in adopting novel biomarker technologies and rapidly developing specialized diagnostic solutions.
- Strong focus on niche applications such as early cancer detection, neurological biomarkers, and precision oncology.
- Ability to deliver differentiated assays with improved analytical sensitivity and workflow efficiency.
- Smaller commercial footprint and limited global distribution compared with established market leaders.
- Challenges related to large-scale clinical validation, regulatory approvals, and reimbursement coverage.
- Financial and operational constraints associated with scaling manufacturing, commercialization, and international market expansion.
Recent Development
-
In May 2026, Guardant Health received U.S. FDA approval for the new Guardant360 Liquid CDx, the largest FDA-approved liquid biopsy panel integrating genomic and epigenomic profiling from a single blood draw, strengthening comprehensive blood-based biomarker testing and precision oncology.
-
In June 2026, Guardant Health received U.S. FDA approval for Guardant360 CDx as a companion diagnostic for Boehringer Ingelheim's HERNEXEOS (zongertinib), enabling blood-based detection of HER2 (ERBB2) mutations in patients with advanced non-small cell lung cancer.
-
In May 2026, Guardant Health received U.S. FDA approval for Guardant360 CDx as a companion diagnostic for Arvinas and Pfizer's VEPPANU (vepdegestrant), enabling blood-based identification of ESR1 mutations to guide treatment decisions in advanced breast cancer.
-
In January 2026, Guardant Health received U.S. FDA approval for Guardant360 CDx as the first liquid biopsy companion diagnostic for patients with metastatic colorectal cancer harboring BRAF V600E mutations, expanding the clinical application of blood-based biomarker testing in precision oncology.
Blood-based Biomarkers Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 8.7 billion
Market size value in 2026
USD 9.3 billion
Revenue forecast in 2033
USD 15.3 billion
Growth rate
CAGR of 7.4% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, application, technology, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; Thailand; South Korea; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Abbott; BIOMÉRIEUX; F. Hoffmann-La Roche Ltd.; Siemens Healthineers AG; Thermo Fisher Scientific, Inc.; Bio-Rad Laboratories, Inc.; Cleveland Diagnostics, Inc.; Sysmex Corporation.
Customization scope
Free report customization (equivalent up to 8 analyst’s working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Blood-based Biomarkers Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global blood-based biomarkers market report based on type, application, technology, end use, and region.
-
Type Outlook (Revenue, USD Billion, 2021 - 2033)
-
Genetic Biomarkers
-
Protein Biomarkers
-
Metabolic Biomarkers
-
Cell-Based Biomarkers
-
Epigenetic Biomarkers
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Cancer
-
Cardiovascular Diseases
-
Neurological Diseases
-
Immunological Diseases
-
Others
-
-
Technology Outlook (Revenue, USD Billion, 2021 - 2033)
-
Next-Generation Sequencing
-
Polymerase Chain Reaction
-
Immunoassays
-
Mass Spectrometry
-
Others
-
-
End Use Outlook (Revenue, USD Billion, 2021 - 2033)
-
Hospitals & Clinics
-
Diagnostic Laboratories
-
Research & Academic Institutes
-
Others
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
South Korea
-
Australia
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The blood-based biomarkers market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing-reconciling supply-side and demand-side estimates-and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each blood-based biomarkers segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Genetic Biomarkers
Genetic biomarkers include DNA- and RNA-based markers detected from blood for identifying inherited or acquired genetic alterations. Market value is primarily captured through sequencing assays, PCR-based tests, mutation detection panels, reagents, bioinformatics software, and laboratory testing services.
Protein Biomarkers
Protein biomarkers comprise circulating proteins, peptides, and antibodies measured in blood to support disease diagnosis, prognosis, and therapy monitoring. Revenue flows from immunoassay kits, antibody reagents, analyzers, consumables, multiplex protein panels, and clinical laboratory testing services.
Metabolic Biomarkers
Metabolic biomarkers consist of metabolites and metabolic signatures present in blood that reflect physiological or pathological processes. Commercial value is derived from metabolomics assay kits, mass spectrometry platforms, chromatography reagents, analytical software, and specialized laboratory testing services.
Cell-Based Biomarkers
Cell-based biomarkers include intact circulating cells, such as circulating tumor cells and immune cells, isolated and analyzed from blood for disease assessment. Market demand translates into spending on cell isolation systems, enrichment kits, imaging platforms, consumables, and associated diagnostic testing services.
Epigenetic Biomarkers
Epigenetic biomarkers include blood-derived DNA methylation patterns, histone modifications, and other epigenetic changes used for disease detection and risk assessment. Revenue streams are supported by methylation assays, sequencing reagents, sample preparation kits, bioinformatics platforms, and molecular diagnostic testing services.
Segment - Application
Revenue capture definition
Cancer
This segment comprises blood-based biomarker tests used for cancer screening, diagnosis, therapy selection, treatment monitoring, and recurrence detection. Market value is primarily captured through liquid biopsy assays, companion diagnostics, molecular testing kits, sequencing platforms, reagents, and clinical testing services.
Cardiovascular Diseases
Covers blood-based biomarkers used to detect, risk stratify, and monitor cardiovascular disorders, including myocardial infarction and heart failure. Revenue flows from cardiac biomarker assays, immunoassay reagents, automated analyzers, point-of-care testing systems, and laboratory diagnostic services.
Neurological Diseases
Includes blood-based biomarker tests for detecting and monitoring neurodegenerative and neurological disorders such as Alzheimer's and Parkinson's disease. Commercial value is driven by protein biomarker assays, immunoassay kits, multiplex panels, laboratory testing, and diagnostic platforms.
Immunological Diseases
Encompasses blood-based biomarkers used for diagnosing, monitoring, and assessing autoimmune and inflammatory disorders. Revenue is primarily derived from cytokine assays, autoimmune biomarker panels, immunoassay reagents, multiplex testing platforms, and specialty diagnostic laboratory services.
Others
Includes blood-based biomarker applications for infectious diseases, metabolic disorders, renal diseases, liver diseases, respiratory conditions, and other clinical indications. Economic contribution comes from disease-specific assay kits, consumables, laboratory-developed tests, analytical instruments, and diagnostic testing services.
Segment - Technology
Revenue capture definition
Next-Generation Sequencing (NGS)
Next-generation sequencing enables comprehensive analysis of multiple genetic and genomic blood biomarkers for disease detection, profiling, and therapy selection. Market value is primarily captured through sequencing instruments, library preparation kits, consumables, bioinformatics software, and clinical sequencing services.
Polymerase Chain Reaction (PCR)
PCR technology amplifies and detects specific nucleic acid biomarkers in blood for targeted disease diagnosis and monitoring. Revenue flows from PCR instruments, assay kits, primers, probes, master mixes, consumables, and molecular diagnostic testing services.
Immunoassays
Immunoassays detect circulating proteins, antibodies, and other blood biomarkers using antigen-antibody interactions for clinical diagnosis and monitoring. Commercial value is driven by immunoassay analyzers, reagent kits, calibrators, controls, consumables, and laboratory testing services.
Mass Spectrometry
Mass spectrometry identifies and quantifies blood-based proteins, peptides, and metabolites with high analytical accuracy for biomarker discovery and validation. Revenue is primarily derived from mass spectrometry systems, chromatography platforms, analytical reagents, software, and specialized laboratory services.
Others
Includes alternative blood biomarker technologies such as microarrays, biosensors, flow cytometry, digital immunoassays, and emerging multi-omics platforms. Economic value stems from specialized instruments, assay consumables, analytical software, custom testing solutions, and research services.
Segment - End use
Revenue capture definition
Hospitals & Clinics
Hospitals and clinics utilize blood-based biomarker tests for routine diagnosis, disease monitoring, treatment selection, and patient management across multiple specialties. Market value is primarily captured through in-house testing, diagnostic instruments, assay kits, consumables, and integrated laboratory services.
Diagnostic Laboratories
Diagnostic laboratories perform high-volume blood-based biomarker testing for hospitals, physicians, and healthcare providers using centralized laboratory infrastructure. Revenue flows from reference testing services, molecular and immunoassay testing, sample processing, reagents, consumables, and automated diagnostic platforms.
Research & Academic Institutes
Research and academic institutes employ blood-based biomarkers for biomarker discovery, translational research, clinical validation, and drug development studies. Commercial value is derived from research-use assay kits, sequencing platforms, analytical instruments, laboratory reagents, software, and contract research activities.
Others
This segment includes pharmaceutical companies, biotechnology firms, contract research organizations (CROs), and public health agencies utilizing blood-based biomarkers for clinical trials, companion diagnostic development, and population health programs. Economic contribution comes from biomarker development services, clinical trial testing, specialized assays, and contract laboratory solutions.
Estimation Model
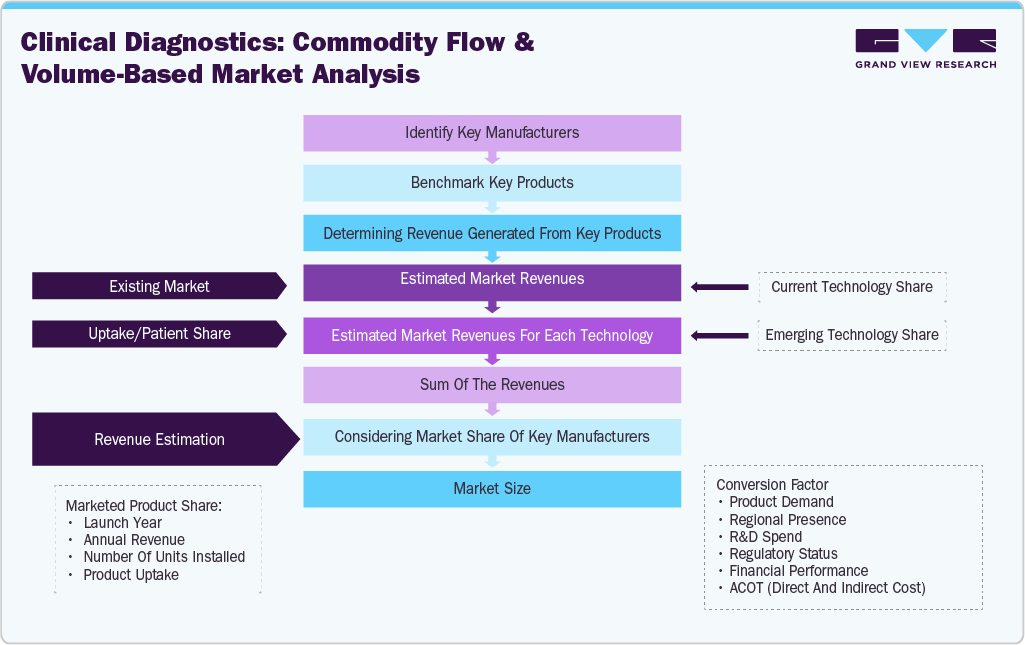
The blood-based biomarkers market size was estimated using a bottom-up approach, beginning with the identification of key manufacturers and benchmarking their blood-based biomarker product portfolios. Revenue generated from major products was analyzed across technologies, followed by estimating segment-wise revenues based on market adoption and patient uptake. The aggregated revenues were validated against the market shares of leading manufacturers to derive the overall market size and ensure accurate market estimation.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following in-depth customizations
Client Request
Customization Delivered
Value Adds
Blood-Based Biomarkers Competitive Landscape & Technology Assessment
Assessed the global blood-based biomarkers market across liquid biopsy, circulating tumor DNA (ctDNA), circulating tumor cells (CTCs), protein biomarkers, exosome-based biomarkers, and multi-omics platforms. Analyzed leading manufacturers, product portfolios, technology advancements, regulatory approvals, commercialization strategies, and competitive positioning across hospitals, diagnostic laboratories, and research institutions.
Enabled the client to identify leading technology innovators, benchmark competitors, evaluate product differentiation, prioritize investments in next-generation blood biomarker platforms, and understand evolving technology adoption trends.
Blood-Based Biomarkers Product Benchmarking Study
Delivered a comprehensive benchmarking assessment of blood-based biomarker products based on biomarker type, analytical performance, clinical utility, disease coverage, sensitivity, specificity, workflow efficiency, regulatory status, reimbursement potential, and commercialization strategies across major diagnostic companies.
Helped the client evaluate product competitiveness, identify innovation opportunities, benchmark advanced liquid biopsy and biomarker platforms, and prioritize investments in high-growth diagnostic technologies.
Blood-Based Biomarkers Commercialization & Market Entry Assessment
Assessed commercialization strategies, regulatory pathways, reimbursement landscape, distribution networks, healthcare adoption trends, strategic collaborations, and market readiness across hospitals, diagnostic laboratories, pharmaceutical companies, and research organizations. Evaluated competitive intensity, procurement practices, and adoption barriers for blood-based biomarker technologies.
Supported commercialization planning by identifying high-potential market opportunities, evaluating partnership and distribution strategies, assessing regulatory and reimbursement requirements, mitigating commercialization risks, and strengthening long-term market expansion strategies within the blood-based biomarkers market.
Frequently Asked Questions About This Report
Asia Pacific is projected to register the fastest growth in the global blood-based biomarkers market during the forecast period, driven by expanding healthcare infrastructure, rising awareness of early disease diagnosis, and increasing investments in precision medicine.
Based on Application, the Cancer segment led the market with the largest revenue share of 39.0% in 2025.
Based on Type, the genetic biomarkers segment led the market with the largest revenue share of 34.2% in 2025.
The growing integration of multi-omics technologies and artificial intelligence (AI) presents a significant opportunity for the blood-based biomarkers market. Combining genomics, proteomics, transcriptomics, metabolomics, and epigenomics enables the identification of comprehensive biomarker signatures that improve disease detection, risk stratification, and treatment monitoring.
The global blood-based biomarkers market size was estimated at USD 8.7 billion in 2025 and is expected to reach USD 9.3 billion in 2026.
North America dominated the blood based biomarkers market with a share of 42.6% in 2025. This is attributable to rising healthcare awareness along with a large number of test approvals in the region
Key factors that are driving the market growth include the increasing prevalence of neurological disorders and cancer across the globe along with growing acceptance of biomarker-based tests
The global blood-based biomarkers market is expected to grow at a compound annual growth rate of 7.4% from 2026 to 2033 to reach USD 15.3 billion by 2033.
Some key players operating in the blood based biomarkers market include Abbott; BIOMÉRIEUX; F. Hoffmann-La Roche Ltd.; Siemens Healthineers AG; Thermo Fisher Scientific, Inc.; Bio-Rad Laboratories, Inc
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


