
- Home
- »
- Clinical Diagnostics
- »
-
Cancer Biomarkers Market Size & Share Report, 2026-2033GVR Report cover

Cancer Biomarkers Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Breast Cancer, Prostate Cancer, Colorectal Cancer , Cervical Cancer ), By Biomolecule (Genetic Biomarkers, Epigenetic Biomarkers), By Application, By Technology, By Region, And Segment Forecasts
Market Size, 2025
$26.9BMarket Estimate, 2026
$29.9BMarket Forecast, 2033
$65.3BCAGR, 2026–2033
11.8%Cancer Biomarkers Market Summary
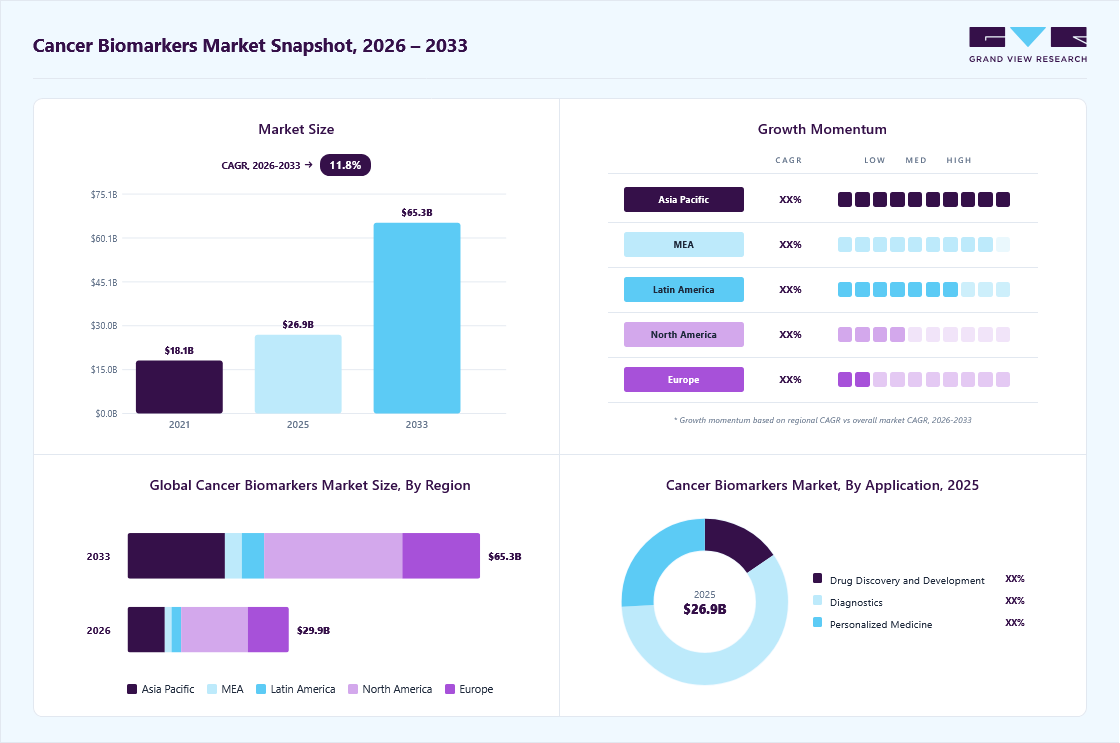
The global cancer biomarkers market size was valued at USD 26.9 billion in 2025 and is projected to grow from USD 29.9 billion in 2026 to USD 65.3 billion by 2033, at a CAGR of 11.8% from 2026 to 2033. The market in North America dominated with a revenue share of 41.6% in 2025. The growth is attributed to rising cancer cases and the increasing focus on early diagnosis and personalized treatment.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Lung cancer segment held the largest market share of 21.7% in 2025.
- By biomolecule: Genetic biomarker segment held the largest market share of 49.7% in 2025.
- By application: Diagnostics segment held the largest market share of 58.5% in 2025.
- By technology: PCR-based technologies segment held the largest market share of 33.4% in 2025.
Regional Highlights
- Largest regional market: North America (41.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: U.S. held the largest market share in 2025
Market Size & Forecast
- Market size in 2025: USD 26.9 Billion
- Estimated market size in 2026: USD 29.9 Billion
- Projected market size by 2033: USD 65.3 Billion
- CAGR (2026-2033): 11.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
Advancements in genomics, proteomics, next-generation sequencing, and molecular diagnostic technologies are accelerating innovation in the cancer biomarker testing market. Hospitals and labs are adopting biomarker-based tests to improve outcomes. Supportive government initiatives and expanding research activities further boost growth, while demand for targeted therapies continues to create new opportunities worldwide.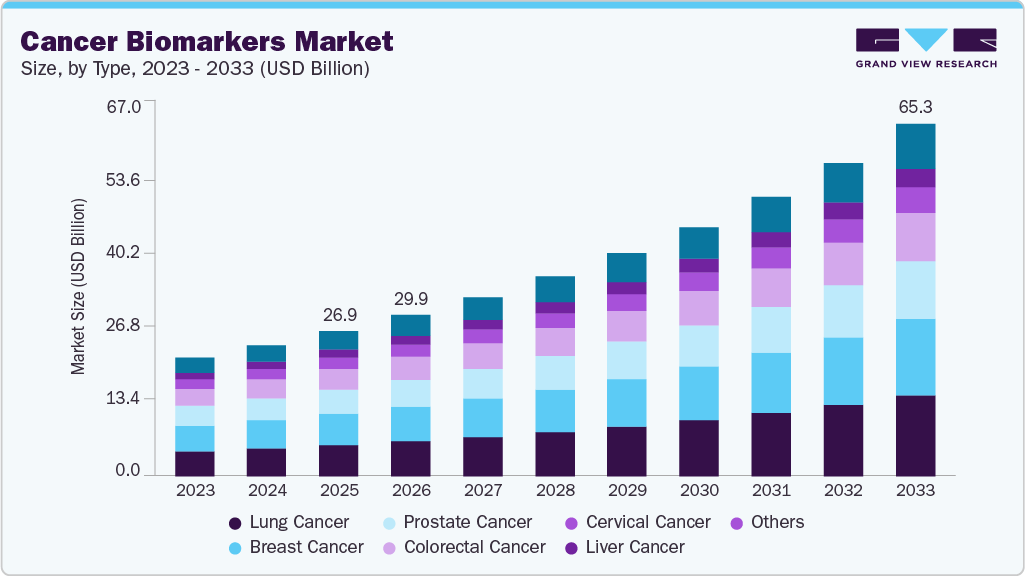 To learn more about this report, Download Free Sample Report
Cancer remains one of the leading global health challenges and a major cause of mortality in the 21st century. According to a study published in The Lancet in September 2025, findings from the Global Burden of Disease (GBD) 2023 study indicate that cancer burden was assessed across 47 cancer types in 204 countries and territories from 1990 to 2023, with projections extending to 2050. Cancer was estimated to be the second leading cause of death globally in 2023, after cardiovascular diseases, with total cancer-related deaths expected to exceed 18 million by 2050. Furthermore, estimates published by the Institute for Health Metrics and Evaluation in September 2025 indicate that there were 18.5 million new cancer cases and more than 10.4 million deaths globally, contributing to approximately 271 million disability-adjusted life years (DALYs) lost. Of these, nearly 60% of cancer cases and over 60% of cancer deaths occurred in low- and middle-income countries, highlighting significant disparities in disease burden and access to care. Lung cancer and colorectal cancer were identified as the leading and second-leading causes of cancer-related deaths in 2023, respectively. The increasing number of patients requiring ongoing care is expected to accelerate the adoption of biomarker-based technologies, thereby supporting the growth of the cancer biomarkers market.
Research plays a critical role in advancing the cancer biomarkers market by supporting the development of innovative technologies for early diagnosis, targeted therapy selection, and disease monitoring. Increasing government funding continues to accelerate oncology research and biomarker discovery initiatives. The National Cancer Institute (NCI) remains a major contributor, supporting research activities across its headquarters in Maryland, academic institutions, and global collaborations. According to data published by the NCI in July 2025, the institute's funds totaled USD 7.2 billion, with 43.3% of the obligated budget allocated to Research Project Grants. These investments are significantly advancing biomarker-based diagnostics, precision oncology, immuno-oncology, and liquid biopsy technologies, thereby supporting innovation and growth in the cancer biomarkers market.
Technological advancements are transforming the cancer biomarkers market by improving precision oncology, early detection, and personalized treatment selection. Increasing integration of biomarker-driven diagnostics with targeted therapies continues to expand clinical applications. For instance, in January 2025, Roche received FDA approval for its PATHWAY HER2 (4B5) companion diagnostic test for identifying patients with HER2-ultralow metastatic breast cancer, highlighting advancements in biomarker-based patient stratification. Continuous innovation in liquid biopsy technologies is also accelerating market growth. In June 2024, Guardant Health expanded the clinical application of its Guardant360 liquid biopsy test for comprehensive genomic profiling and real-time tumor monitoring. Furthermore, in August 2024, Illumina advanced its oncology sequencing platforms, supporting high-throughput genomic profiling and strengthening biomarker-based precision oncology applications across multiple cancer types.
Market Concentration & Characteristics
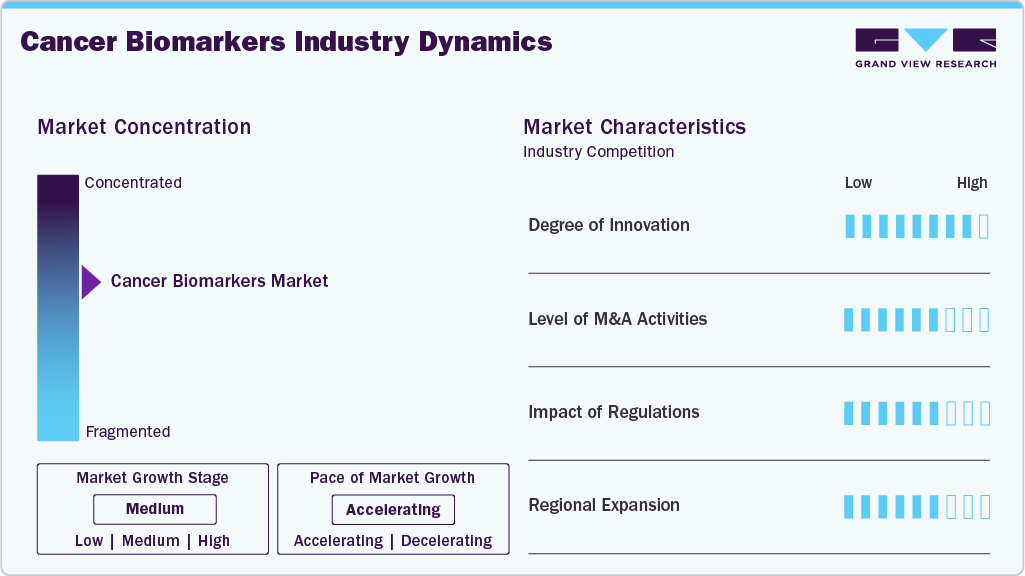
The cancer biomarkers market demonstrates a high degree of innovation, driven by continuous advancements in precision oncology, molecular diagnostics, and biomarker-based therapeutic approaches. Rapid developments in next-generation sequencing (NGS), liquid biopsy, and companion diagnostics are improving early cancer detection, treatment selection, and disease monitoring. The market is witnessing increasing integration of biomarker-driven patient stratification with targeted therapies and immuno-oncology applications. Companies are actively investing in high-sensitivity assays, multi-omics platforms, and AI-supported genomic analysis to enhance diagnostic accuracy and clinical utility. In addition, ongoing regulatory approvals and strategic collaborations are accelerating commercialization of advanced biomarker technologies, further strengthening innovation and expanding the clinical adoption of personalized oncology solutions globally.
The industry exhibits a moderate to high level of M&A activity, driven by increasing investments in precision oncology, molecular diagnostics, liquid biopsy, and AI-enabled biomarker technologies. Companies are actively pursuing acquisitions and strategic collaborations to strengthen companion diagnostics portfolios, expand genomic profiling capabilities, and accelerate commercialization of advanced cancer diagnostic solutions. For instance, in May 2026, Roche agreed to acquire PathAI, a U.S.-based digital pathology and AI diagnostics company, to enhance its AI-driven cancer diagnostics and precision oncology capabilities. Such transactions are enabling market participants to improve biomarker discovery, integrate digital pathology with molecular testing, and strengthen their competitive positioning within the rapidly evolving cancer biomarkers market.
 To learn more about this report, Download Free Sample Report
The cancer biomarkers market is significantly influenced by evolving regulatory frameworks governing companion diagnostics, molecular testing, and precision oncology applications. Regulatory agencies such as the U.S. FDA, EMA, PMDA, and CDSCO play a critical role in ensuring the safety, clinical validity, and effectiveness of biomarker-based diagnostic tests. Increasing regulatory approvals for companion diagnostics and next-generation sequencing assays are supporting market growth and accelerating clinical adoption. However, stringent validation requirements, reimbursement-linked approvals, and complex regulatory pathways can extend product development timelines and increase commercialization costs. Despite these challenges, supportive regulatory initiatives for precision medicine and biomarker-guided therapies continue to strengthen innovation and improve integration of advanced cancer diagnostics into routine clinical practice.
The market is experiencing continuous global expansion due to increasing demand for precision oncology, early cancer detection, and advanced molecular diagnostic technologies. Expanding healthcare infrastructure, improving access to biomarker-based testing, and increasing investments in cancer research are supporting market growth across emerging and developed regions. In addition, growing awareness regarding early cancer detection and personalized medicine is accelerating the adoption of companion diagnostics, liquid biopsy, and genomic profiling technologies. Market participants are further strengthening their regional presence through strategic collaborations, product commercialization, distribution network expansion, and investments in advanced diagnostic capabilities, thereby supporting broader clinical adoption and market penetration globally.
Type Insights
The lung cancer segment dominated the market with the largest revenue share of 21.73% in 2025 and is anticipated to grow at the fastest CAGR. Growth of the segment is driven by broad companion diagnostic requirements and expanding biomarker testing in NSCLC. Commercial testing now includes EGFR, ALK, ROS1, BRAF, MET, RET, KRAS G12C, PD-L1, and TMB, supporting strong demand for NGS, immunoassays, and liquid biopsy technologies. A retrospective analysis of over 34,000 metastatic NSCLC patients showed that 82.1% received at least one biomarker test by 2023, with EGFR testing at 88.7% and ALK testing at 87.7%. In addition, approval of adjuvant osimertinib for EGFR-mutated resected NSCLC is accelerating the adoption of testing in early-stage disease, while combined tissue and ctDNA liquid biopsy testing continues to gain clinical and commercial traction, contributing to sustained growth and adoption across the segment.
The breast cancer segment accounted for a significant share of the market, driven by high disease prevalence, established companion diagnostic frameworks, and increasing adoption of biomarker-based targeted therapies. The segment benefits from strong clinical integration of biomarkers such as HER2, ER, PR, BRCA1/2, Ki-67, and PIK3CA across diagnosis, treatment selection, and disease monitoring applications. A key market development is the expansion of HER2 classification into HER2-low and HER2-ultralow categories following successive FDA approvals of trastuzumab deruxtecan. In January 2025, the FDA approved trastuzumab deruxtecan for HR-positive, HER2-low or HER2-ultralow metastatic breast cancer along with the Ventana PATHWAY anti-HER-2 (4B5) assay as a companion diagnostic. The growing HER2-low patient population is increasing demand for advanced HER2 testing and standardized diagnostic platforms.
Biomolecule Insights
The genetic biomarker segment dominated the market with the largest revenue share of 49.65% in 2025, driven by increasing adoption of personalized medicine, companion diagnostics, and comprehensive genomic profiling for cancer detection and therapy selection. Strong clinical integration of somatic and germline mutation testing across multiple cancer types continues to support recurring testing demand. The segment is further benefiting from growing adoption of NGS-based platforms, which enable simultaneous detection of multiple actionable mutations with improved efficiency and clinical utility. In addition, expanding use of liquid biopsy technologies for ctDNA-based mutation detection is strengthening non-invasive cancer monitoring applications. For instance, in September 2024, Illumina received FDA approval for TruSight Oncology Comprehensive, a pan-tumor companion diagnostic that covers more than 500 biomarkers, supporting broader adoption of comprehensive genomic profiling in oncology diagnostics.
The epigenetic biomarkers segment is projected to grow at a CAGR of 13.78% over the forecast period, driven by increasing adoption of DNA methylation-based assays for early cancer detection, tissue-of-origin analysis, and multi-cancer screening applications. The growing clinical utility of methylation profiling in circulating cell-free DNA is supporting the expansion of liquid biopsy-based diagnostics, particularly in multi-cancer early detection (MCED) testing. In addition, increasing investments in cancer epigenetics research and rising clinical trial activity are accelerating demand for epigenetic biomarker assays in patient stratification and treatment monitoring. For instance, in 2024, there were over 200 clinical trials for epigenetic therapies worldwide, with a 45% increase in phase II/III trials compared to 2023, while cancer epigenetics accounted for nearly 62% of drug development initiatives, contributing to the expanding clinical and commercial adoption of epigenetic biomarker technologies.
Application Insights
The diagnostics segment dominated the market with the largest revenue share of 58.48% in 2025, driven by increasing adoption of biomarker-based testing for cancer screening, early detection, diagnosis, disease monitoring, and prognosis in routine clinical practice. High testing volumes across established biomarkers such as PSA, AFP, CEA, CA-125, and CA 19-9 continue to support recurring diagnostic demand globally. The segment is further benefiting from the growing adoption of blood-based and non-invasive cancer screening technologies. For instance, in July 2024, the FDA approved Guardant Health's Shield blood test as the first blood test approved as a primary screening option for colorectal cancer in adults aged 45 and older at average risk, and the first approved blood test for CRC screening to meet Medicare coverage requirements.
The personalized medicine segment is projected to witness significant growth, driven by increasing adoption of companion diagnostics, targeted therapies, and comprehensive genomic profiling across oncology care. The segment benefits from strong regulatory support for biomarker-guided treatment selection and growing integration of precision medicine into clinical practice. Rising approvals of targeted therapies linked with mandatory biomarker testing continue to accelerate demand for companion diagnostics and multi-gene CGP panels. In addition, increasing adoption of liquid biopsy-based companion diagnostics is supporting minimally invasive cancer profiling and real-time treatment monitoring. For instance, in October 2024, Roche secured FDA approval for its VENTANA Claudin 18 (43-14A) RxDx Assay as the first IHC companion diagnostic for CLDN18 protein expression in gastric and gastroesophageal junction adenocarcinoma, enabling determination of patient eligibility for zolbetuximab. Such advancements are expanding the clinical utility of biomarker-driven therapies and supporting broader adoption of precision oncology approaches across cancer care.
Technology Insights
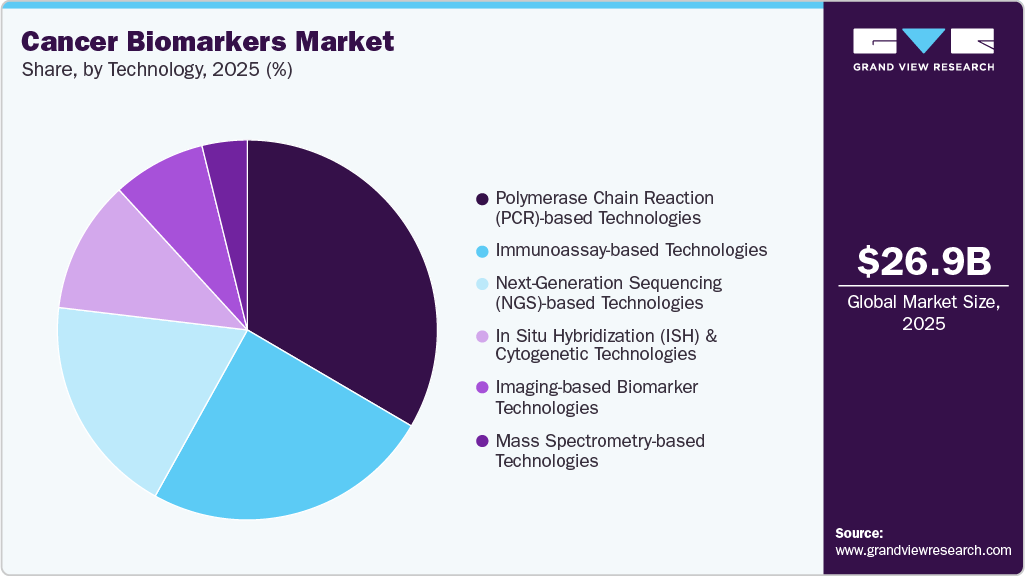
The PCR-based technologies segment accounted for 33.43% of the market share in 2025, driven by widespread adoption across routine clinical diagnostics, companion diagnostics, and oncology molecular testing workflows. The technology continues to maintain strong clinical utilization due to its high specificity, rapid turnaround time, and lower infrastructure requirements compared to sequencing platforms. PCR-based assays are widely used for EGFR, KRAS, BRAF, BRCA mutation testing, HPV detection, and leukemia monitoring, generating consistent, recurring testing demand. In addition, growing adoption of digital PCR is supporting expansion into high-sensitivity liquid biopsy and ctDNA detection applications. For instance, in February 2025, Bio-Rad Laboratories signed an agreement to acquire Stilla Technologies to strengthen its digital PCR portfolio in high-precision molecular diagnostics and oncology testing applications. Such developments are accelerating innovation in amplification-based molecular testing and supporting broader adoption of PCR technologies across precision oncology applications.
 To learn more about this report, Download Free Sample Report
The mass spectrometry-based technologies segment is projected to witness significant growth at a CAGR of 16.43% over the forecast period, driven by increasing adoption in biomarker discovery, proteomic profiling, metabolomics, and pharmaceutical research applications. LC-MS and GC-MS platforms are widely utilized for high-sensitivity analysis, quantitative biomarker profiling, and drug metabolism studies across oncology research workflows. The segment is benefiting from growing demand for multiplex biomarker analysis and advanced translational research capabilities in pharmaceutical and biotechnology industries. In addition, technological advancements are expanding the application potential of mass spectrometry in oncology biomarker exploration. For instance, in June 2025, Bruker introduced the timsTOF Ultra AIP, an ultra-sensitive mass spectrometry system optimized for single-cell proteomics and immunopeptidomics, supporting advanced biomarker discovery and translational oncology research applications.
Regional Insights
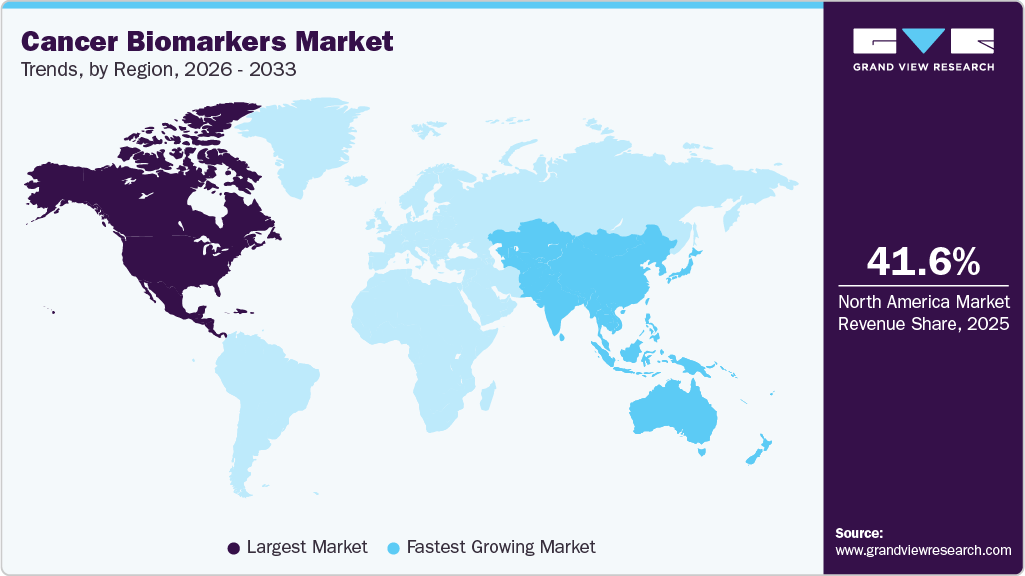
The North America cancer biomarker industry held the largest market share of 41.61% in 2025. The region represents one of the most commercially mature and advanced markets for cancer biomarkers, supported by strong alignment between regulatory approvals, reimbursement coverage, and clinical practice. The United States drives regional leadership through a highly integrated healthcare ecosystem that links biomarker testing with targeted therapy access, creating sustained demand for precision oncology solutions. Canada contributes through advanced clinical research and growing adoption of biomarker-guided therapies, although provincial differences continue to affect market uniformity. Meanwhile, Mexico remains an emerging market, with growth primarily supported by private healthcare investments. A key regional advantage is the rapid commercialization of innovative biomarker technologies. Future growth is expected to be driven by expanding applications in early cancer screening, disease monitoring, genomic profiling, and liquid biopsy testing across routine oncology workflows.
 To learn more about this report, Download Free Sample Report
U.S. Cancer Biomarkers Market Trends
The cancer biomarker industry in the U.S. dominates the North American market, characterized by strong commercialization, advanced diagnostic infrastructure, and broad integration of biomarker testing into oncology care pathways. Market growth is driven by widespread adoption of genomic profiling, liquid biopsy, and companion diagnostics across clinical settings. In addition, favorable reimbursement coverage for molecular diagnostics and targeted therapies continues to support large-scale clinical adoption. The market also benefits from strategic collaborations between diagnostic companies and pharmaceutical firms focused on precision oncology. Furthermore, evolving regulatory frameworks supporting next-generation sequencing and multi-analyte testing are accelerating innovation while maintaining high standards for clinical validation, reliability, and testing accuracy across biomarker-driven oncology applications.
Europe Cancer Biomarkers Market Trends
The cancer biomarker industry in Europe represents a mature yet structurally diverse market, where adoption is strongly influenced by country-specific healthcare systems and reimbursement frameworks. Western European countries demonstrate broad integration of biomarker testing into oncology care pathways, supported by government-led healthcare initiatives and established funding mechanisms. However, adoption levels vary across the region due to differences in healthcare decentralization, reimbursement timelines, and regulatory processes. Centralized healthcare systems generally enable faster and more consistent implementation of advanced diagnostics, while decentralized markets face challenges related to access and standardization. Future market growth is expected to be driven by expanding reimbursement coverage, increasing adoption of molecular diagnostics, and efforts to harmonize biomarker testing access across European countries.
The UK cancer biomarkers industry is expanding due to its centralized healthcare structure and strong integration of biomarker testing within nationally coordinated clinical pathways. The market is supported by genomic testing hubs and standardized laboratory networks that enable consistent adoption of validated biomarker assays across the healthcare system. In addition, regulatory and reimbursement frameworks emphasize clinical utility, cost effectiveness, and alignment with national treatment guidelines, supporting broad implementation of approved tests. The UK cancer biomarker market also benefits from increasing adoption of genomic sequencing and liquid biopsy technologies in oncology care. Furthermore, the growing focus on data-driven clinical decision-making and interoperable diagnostic solutions is driving the adoption of advanced technologies in the cancer biomarker testing market nationwide.
The cancer biomarkers industry in Germany is characterized by a well-established and competitive landscape supported by global diagnostic companies, domestic technology providers, and hospital-based laboratory networks. Market growth is driven by strong adoption of molecular diagnostics, favorable reimbursement coverage, and increasing integration of biomarker testing into oncology care pathways. Unlike more centralized European markets, Germany supports broader participation from private laboratories and diagnostic providers, creating a scalable and innovation-driven environment. In addition, collaborations between pharmaceutical and diagnostic companies are supporting the development of companion diagnostics and precision oncology solutions. The cancer biomarker market in Germany also benefits from a strong clinical research ecosystem, advanced healthcare infrastructure, and increasing adoption of next-generation sequencing and liquid biopsy technologies across routine cancer care.
The France cancer biomarkers industry operates within a centralized and policy-driven healthcare environment, where adoption is closely linked to national healthcare programs and publicly funded diagnostic networks. Market growth is supported by strong integration of molecular diagnostics into coordinated laboratory infrastructure and oncology care pathways. Diagnostic companies compete by aligning with national testing strategies, demonstrating clinical utility, and supporting large-scale implementation across healthcare institutions. In addition, the presence of leading academic cancer centers and research organizations strengthens early validation and adoption of advanced biomarker technologies. The cancer biomarker market in France also benefits from structured reimbursement pathways and national cancer strategies that support broad access to approved biomarker tests. Furthermore, increasing focus on genomic sequencing and advanced biomarker panels is supporting long-term market expansion across precision oncology applications.
Asia Pacific Cancer Biomarkers Market Trends
The cancer biomarker industry in the Asia Pacific is the fastest-growing market, driven by rising cancer incidence, expanding healthcare infrastructure, and growing focus on precision medicine across the region. The market comprises both mature and emerging healthcare systems, creating a diverse growth landscape. Countries such as Japan, South Korea, and Australia demonstrate strong clinical integration and favorable reimbursement support for biomarker testing, while China leads in terms of market scale and domestic innovation. Emerging economies, including India and Southeast Asian countries, offer significant growth opportunities supported by improving diagnostic capabilities and increasing healthcare investments. However, affordability constraints and uneven access to advanced diagnostics continue to present challenges in certain regions. Long-term market growth will depend on expanding reimbursement coverage, strengthening diagnostic infrastructure, and improving awareness of biomarker-driven oncology care.
The Japan cancer biomarkers industry is characterized by a structured and moderately consolidated landscape supported by strong domestic diagnostic capabilities and a highly regulated healthcare environment. Market growth is driven by increasing adoption of precision oncology, companion diagnostics, and molecular testing across established cancer care pathways. Diagnostic companies compete based on clinical validation, reliability, and integration with standardized oncology workflows rather than large-scale commercial expansion. In addition, hospitals and designated cancer centers play a central role in biomarker testing adoption, with strong support from academic and clinical research collaborations. The cancer biomarker market in Japan also benefits from national genomic medicine initiatives and universal healthcare reimbursement for selected molecular diagnostics. Furthermore, growing use of gene panel testing and targeted therapies is supporting long-term expansion of biomarker-driven oncology applications across the country.
The cancer biomarkers industry in China is highly competitive and driven by rapid advancements in molecular diagnostics, particularly in next-generation sequencing and liquid biopsy technologies. Market growth is supported by the strong presence of domestic diagnostic companies alongside international players, creating a dynamic and innovation-focused environment. Major hospitals and urban healthcare centers serve as key hubs for adoption of advanced biomarker testing and precision oncology solutions. Domestic companies benefit from strong integration with local healthcare systems, pricing flexibility, and alignment with national regulatory requirements, while global players compete through advanced technology platforms and extensive clinical validation. Furthermore, government initiatives supporting precision medicine and expanding oncology care are accelerating adoption of biomarker testing, while evolving reimbursement policies are gradually improving access to advanced molecular diagnostics across the country.
Latin America Cancer Biomarkers Market Trends
The cancer biomarker industry in Latin America is driven by the rising cancer burden and gradual expansion of diagnostic capabilities across the region. Market growth is supported by improving healthcare infrastructure, increasing awareness of precision oncology, and broader adoption of molecular diagnostics in selected healthcare settings. Brazil dominates the regional market due to its large patient population and expanding oncology diagnostic network, while Argentina contributes through strong academic research and clinical expertise. However, access to advanced biomarker testing remains uneven, with adoption primarily concentrated in private healthcare facilities. Public healthcare reimbursement limitations, affordability concerns, and infrastructure gaps continue to restrict large-scale implementation of advanced molecular diagnostics. Future market growth will depend on expansion of public healthcare funding, improved diagnostic infrastructure, and stronger alignment between clinical guidelines and reimbursement frameworks.
The Brazil cancer biomarkers industry is driven by the rising cancer burden, expanding oncology infrastructure, and gradual adoption of molecular diagnostics across the healthcare system. Market growth is strongest in major urban centers such as São Paulo and Rio de Janeiro, where private hospitals, oncology centers, and reference laboratories support advanced biomarker testing and precision oncology applications. The market is characterized by a dual healthcare structure, with advanced diagnostics primarily concentrated within private healthcare networks, while the public sector focuses on essential and routine testing. In addition, increasing clinical trial activity and collaborations between diagnostic companies and oncology institutions are supporting adoption of next-generation sequencing and liquid biopsy technologies. However, reimbursement limitations and affordability challenges continue to restrain the growth of the cancer biomarker testing market by restricting broader access to advanced biomarker-based diagnostic tests nationwide.
Middle East & Africa Cancer Biomarkers Market Trends
The cancer biomarker industry in the Middle East and Africa is a developing market characterized by significant variation in healthcare infrastructure, diagnostic capabilities, and access to advanced oncology testing across countries. Market growth is primarily driven by strong government investments and healthcare transformation initiatives in Gulf countries such as Saudi Arabia and the UAE, where precision oncology and advanced molecular diagnostics are gaining rapid adoption. In contrast, several African countries continue to face challenges related to limited healthcare infrastructure, funding constraints, and restricted access to advanced biomarker testing. South Africa represents a mixed landscape, with advanced diagnostic capabilities available in private healthcare settings but lower accessibility within public systems. Future market growth is expected to be supported by expanding healthcare infrastructure, improving insurance coverage, and increasing integration of biomarker-driven oncology care into national cancer management strategies.
The Saudi Arabia cancer biomarkers industry is characterized by rapid adoption of precision oncology and expanding integration of advanced molecular diagnostics across major healthcare institutions. Market growth is supported by strong government investments in healthcare infrastructure, national healthcare transformation initiatives, and increasing focus on early cancer detection and personalized treatment strategies. Adoption of biomarker testing is concentrated within leading public hospitals and specialized oncology centers, where advanced technologies such as genomic profiling and next-generation sequencing are becoming increasingly integrated into clinical workflows. In addition, partnerships between international diagnostic companies and local healthcare organizations are supporting broader access to advanced cancer diagnostics. The market in Saudi Arabia also benefits from expanding insurance coverage and increasing reimbursement support for molecular oncology testing across both public and private healthcare sectors.
Key Cancer Biomarkers Company Insights
The cancer biomarker market is characterized by the presence of established diagnostic companies and emerging precision oncology firms competing through technological innovation and strategic collaborations. Leading players are focusing on next-generation sequencing (NGS), immunohistochemistry (IHC), multiplex assays, and companion diagnostics to strengthen their market position. In addition, partnerships with pharmaceutical companies and research institutions are supporting development of biomarker-driven therapies and advanced diagnostic solutions. Emerging companies are emphasizing liquid biopsy and PCR-based biomarker assays to expand clinical applications. Competitive differentiation is driven by assay accuracy, clinical validation, turnaround time, and integration with oncology workflows, thereby supporting continuous market expansion.
Key Cancer Biomarkers Companies:
The following key companies have been profiled for this study on the cancer biomarkers market.
- Abbott
- QIAGEN
- Thermo Fisher Scientific
- F. Hoffmann-La Roche Ltd.
- Illumina, Inc.
- Agilent Technologies, Inc.
- Merck & Co. Inc.
- Hologic, Inc.
- Sino Biological Inc.
Recent Developments
-
In February 2026, Agilent Technologies, Inc. received FDA approval for PD-L1 IHC 22C3 pharmDx to identify PD-L1-expressing ovarian, fallopian tube, and primary peritoneal carcinoma patients eligible for KEYTRUDA immunotherapy. This approval strengthens adoption of companion diagnostics and biomarker-guided cancer treatment. It also supports demand for advanced immunohistochemistry assays in the cancer biomarker market.
-
In January 2026, Illumina Inc. secured reimbursement from the Centers for Medicare & Medicaid Services (CMS) for its TruSight Oncology Comprehensive test. This development expands access to clinically validated genomic profiling solutions and supports broader adoption of precision oncology testing. It also strengthens demand for advanced cancer biomarker assays used for the identification of actionable genomic alterations and treatment selection.
-
In January 2025, F. Hoffmann-La Roche Ltd. received FDA approval for expanded use of the PATHWAY anti-HER2 (4B5) CDx test to detect HER2-ultralow breast cancer, enabling identification of additional patients eligible for ENHERTU targeted therapy. This approval strengthens the role of companion diagnostics in precision oncology and supports broader adoption of biomarker-based cancer testing across clinical settings.
Cancer Biomarkers Market Report Scope
Report Attribute
Details
Market size in 2025
USD 26.9 billion
Estimated market size in 2026
USD 29.9 billion
Projected market size by 2033
USD 65.3 billion
Growth rate
CAGR of 11.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Type, biomolecule, application, technology, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key company profiled
Abbott; QIAGEN; Thermo Fisher Scientific; F. Hoffmann-La Roche Ltd.; Illumina, Inc.; Agilent Technologies, Inc.; Merck & Co. Inc.; Hologic, Inc.; Sino Biological Inc..
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Cancer Biomarkers Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global cancer biomarkers market report based on type, biomolecule, application, technology, and region
-
Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Breast Cancer
-
Prostate Cancer
-
Colorectal Cancer
-
Cervical Cancer
-
Liver Cancer
-
Lung Cancer
-
Others
-
-
Biomolecule Outlook (Revenue, USD Million, 2021 - 2033)
-
Genetic Biomarkers
-
Epigenetic Biomarkers
-
Metabolic Biomarkers
-
Proteomic Biomarkers
-
-
Application Outlook (Revenue, USD Million, 2021 - 2033)
-
Drug Discovery and Development
-
Diagnostics
-
Personalized Medicine
-
-
Technology Outlook (Revenue, USD Million, 2021 - 2033)
-
Polymerase Chain Reaction (PCR)-based Technologies
-
Next-Generation Sequencing (NGS)-based Technologies
-
Immunoassay-based Technologies
-
In Situ Hybridization (ISH) & Cytogenetic Technologies
-
Mass Spectrometry-based Technologies
-
Imaging-based Biomarker Technologies
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Frequently Asked Questions About This Report
The global cancer biomarkers market size was valued at USD 26.9 billion in 2025 and is estimated at USD 29.9 billion for 2026.
The global cancer biomarkers market is expected to grow at a CAGR of 11.8% from 2026 to 2033, reaching USD 65.3 billion by 2033.
North America dominated with a 41.6% revenue share in 2025.
Key factors that are driving the market growth include the growing geriatric population base, growing prevalence of cancer, increasing government funding for cancer research, and technological advancements.
The lung cancer segment led with a 21.7% revenue share in 2025.
The genetic biomarker segment led with a 49.7% revenue share in 2025, while the epigenetic biomarkers segment is the fastest-growing.
The diagnostics segment led with a 58.5% revenue share in 2025, while the personalized medicine segment is the fastest-growing.
Asia Pacific is the fastest-growing region over the forecast period.
Key players include Abbott; QIAGEN; Thermo Fisher Scientific; F. Hoffmann-La Roche Ltd.; Illumina, Inc.; Agilent Technologies, Inc.; Merck & Co. Inc.; Hologic, Inc.; Sino Biological Inc.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


