
- Home
- »
- Consumer F&B
- »
-
Canola Oil Market Size, Share & Growth Report, 2026-2033GVR Report cover

Canola Oil Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Processed Canola Oil, Virgin Canola Oil), By Application (Food Processing, Food Service, Retail), By Distribution (Supermarkets & Hypermarkets, Franchise Outlet), By Region, And Segment Forecasts
Market Size, 2025
$35.6BMarket Estimate, 2026
$36.8BMarket Forecast, 2033
$45.6BCAGR, 2026–2033
3.1%Canola Oil Market Summary
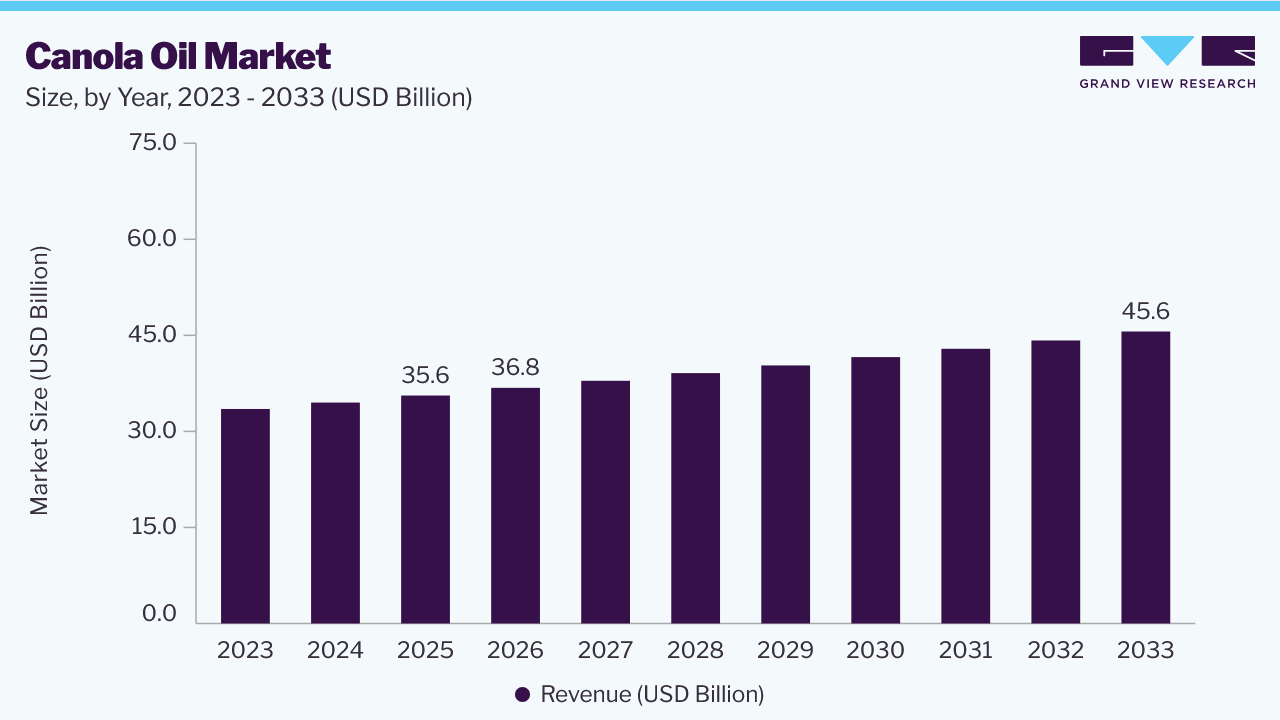
The global canola oil market size was valued at USD 35.6 billion in 2025 and is projected to grow from USD 36.8 billion in 2026 to USD 45.6 billion in 2033, at a CAGR of 3.1% from 2026 to 2033. Asia Pacific dominated the market, accounting for a largest revenue share of 36.0% in 2025. The canola oil industry has experienced significant growth in recent years, driven by several key factors.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: The processed canola oil segment held the largest market share of around 71.0% in 2025.
- By application: The food processing segment held the largest market share of around 37.0% in 2025.
- By distribution: The supermarkets and hypermarkets segment held the largest market share of around 38.0% in 2025.
Regional Highlights
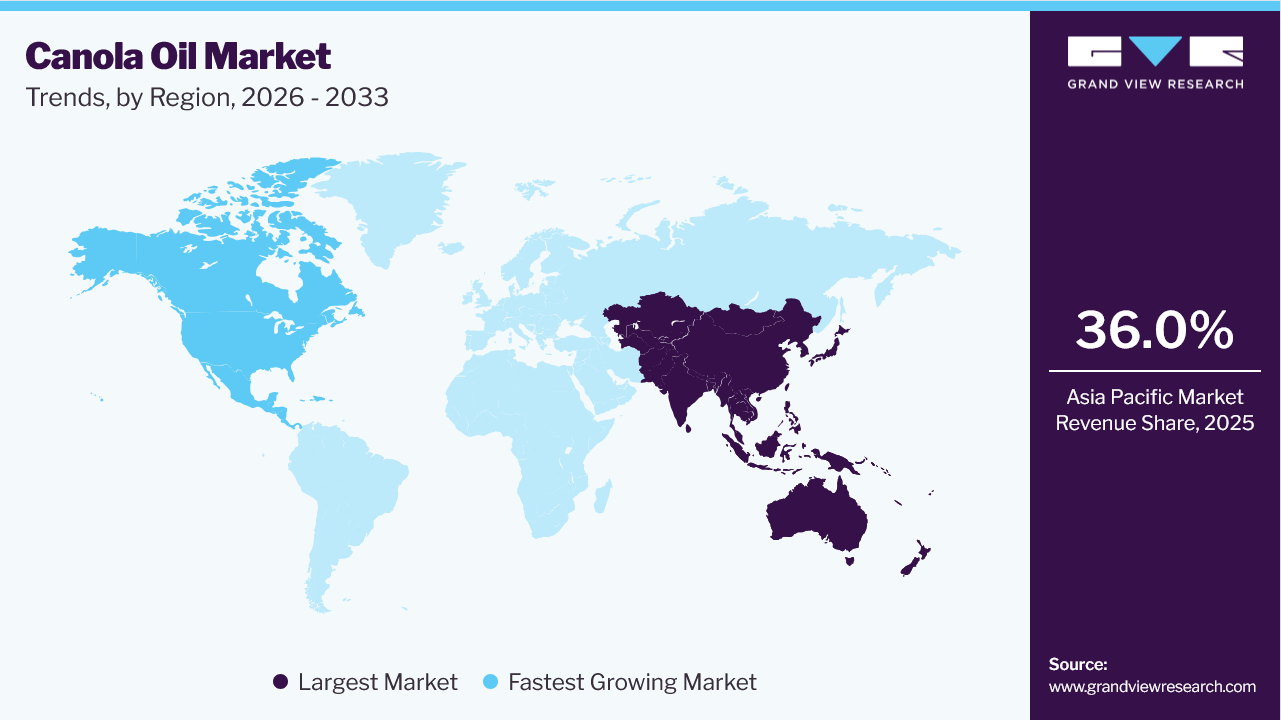
- Largest regional market: Asia Pacific (36.0% revenue share, 2025)
- Fastest-growing regional market: North America (highest CAGR, 2026-2033)
Market Size & Forecast
- Market size in 2025: USD 35.6 Billion
- Estimated market size in 2026: USD 36.8 Billion
- Projected market size by 2033: USD 45.6 Billion
- CAGR (2026-2033): 3.1%
Prism AI by Grand View Research Free to tryAsk a question about the canola oil marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →One of the primary reasons for this growth is the growing consumer awareness of the health benefits of canola oil. Canola oil is known for its low saturated fat content and high levels of omega-3 fatty acids, making it a preferred choice for health-conscious consumers seeking to reduce their risk of chronic diseases like cardiovascular conditions.
The nutritional profile of canola oil, which includes high levels of monounsaturated and polyunsaturated fats, has contributed to its popularity. Consumers are becoming more health-conscious and are actively seeking products that align with their dietary goals. As a result, demand for healthier cooking oils such as canola oil has increased, driving market expansion. The food industry's growing use of canola oil in processed foods further boosts demand, as consumers prioritize their health and actively seek foods that support a balanced diet.
Technological advancements in the canola oil industry have also played a crucial role in its growth. Developing advanced processing facilities and cutting-edge equipment has streamlined production processes, reducing energy consumption and costs. Moreover, canola oil's role in the biodiesel sector has become significant due to its environmental friendliness, making it an attractive option for sustainable energy solutions. This has led to increased innovation and investment in the industry, enhancing competitiveness and market trends.
North America, particularly Canada, dominates the global canola oil industry regionally due to favorable climate conditions, advanced agricultural practices, and strong international trade relationships. Europe is also experiencing significant growth, driven by stringent regulations promoting sustainable agriculture and a strong focus on health-conscious consumer preferences. The Asia Pacific region is expected to grow rapidly due to increasing demand for healthier food options and a rising population. In addition, Latin America is witnessing growth, with countries like Brazil and Argentina leading the way due to their agricultural potential and consumer preference for healthier oils.
Despite the growth, the canola oil industry faces challenges such as volatility in raw material prices due to weather conditions, crop diseases, and geopolitical factors. To mitigate these challenges, companies are adopting advanced agricultural techniques and investing in genetically modified crops that offer higher yields and disease resistance. This helps stabilize supply and enhance the quality of the oil. The market is also supported by government policies and subsidies that encourage the cultivation of canola crops, further boosting demand.
The canola oil industry is poised for continued growth, driven by increasing demand for healthier and sustainable products. Government policies supporting sustainable agriculture and biofuel production will further boost the market. In addition, the expansion of canola oil into new applications, such as cosmetics and biodiesel, presents opportunities for market players to diversify and expand their offerings. As consumer preferences continue to shift toward healthier and more sustainable options, the canola oil industry is well-positioned to capitalize on these trends.
Analyst Perspective
The canola oil market is experiencing steady growth as consumers seek healthier cooking oils with desirable nutritional qualities and broad culinary versatility. The relatively low saturated fat content of canola oil and favorable ratio of total unsaturated fatty acids have strengthened its market position, while its neutral flavor and high smoke point support applications across frying, baking, food processing, and foodservice environments. Increased consumer interest in plant-based and minimally processed food products is further bolstering demand, particularly as canola oil manufacturers expandtheir use in packaged and prepared food offerings. Advances in oilseed breeding, processing technologies, and sustainable agricultural practices are enhancing yield potential, improving oil quality, and refining supply chain efficiencies.
Product Insights
The processed canola oil segment held the largest market share, at around 71.0%, in 2025. The canola oil industry is primarily divided into processed and virgin canola oil. The dominance of processed canola oil is attributed to its lower cost and broader applications in processed foods, snacks, and biofuels. On the other hand, virgin canola oil is gaining popularity for its health benefits and natural qualities.
Several key factors drive the growth of processed canola oil. Its widespread use in processed foods, such as baked goods and snacks, is due to its neutral flavor and high smoke point, making it ideal for frying and baking applications. In addition, processed canola oil is generally cheaper than virgin canola oil, which makes it a preferred choice for large-scale food processing and manufacturing. The increasing demand for biofuels as a sustainable alternative to fossil fuels also contributes to the growth of processed canola oil, as it is used in biodiesel production.
Although it has a smaller market share, Virgin canola oil is experiencing rapid growth due to its health benefits and natural qualities. Consumers increasingly seek natural, unprocessed products, driving demand for virgin canola oil for its perceived health benefits. Its neutral flavor and high smoke point make it suitable for various cooking methods, including frying and baking. The absence of preservatives and solvents in virgin canola oil appeals to consumers looking for organic products, further boosting its demand.
Application Insights
The food processing segment held a significant market share of around 37.0% in 2025. In the food processing sector, canola oil is a preferred choice due to its neutral flavor and ability to maintain a pleasing texture in various food products, such as baked goods, snacks, and salad dressings. The growth in this application is driven by the expanding food processing industry, fueled by consumer demand for convenient, healthy packaged foods. Canola oil's versatility and nutritional profile make it an excellent carrier for fat-soluble vitamins, enhancing the nutritional value of processed foods. In addition, advancements in agricultural practices and investments in canola processing capacity further support the growth of canola oil in this sector.
Canola oil is widely used in food service due to its health benefits, neutral flavor, and high smoke point, making it ideal for frying and baking. The growth in this application is driven by the expanding food service industry, which is adapting to changing consumer lifestyles by offering convenient dining options such as fast food, takeout, and food delivery services. Restaurants and food service providers increasingly opt for canola oil to cater to the growing demand for healthier menu options. This trend is further fueled by the cost-effectiveness and versatility of canola oil, which aligns with the industry's focus on improving nutritional quality while maintaining operational efficiency.
In the retail segment, canola oil is gaining popularity due to growing consumer awareness of its health benefits and its convenience in household cooking. The growth in this application is driven by shifting consumer preferences toward healthier cooking oils, with canola oil a preferred choice for its low saturated fat content and high levels of omega-3 fatty acids. The availability of canola oil in retail outlets and its versatility in cooking make it a preferred choice for health-conscious consumers seeking to incorporate healthier options into their diets. As awareness regarding health benefits continues to rise, the retail segment is likely to continue expanding.
Distribution Insights
The supermarkets and hypermarkets segment held the largest market share, at around 38.0%, in 2025. Supermarkets and hypermarkets are experiencing growth in canola oil sales due to their extensive reach and the convenience they offer consumers. These retail formats provide a wide selection of canola oil products, making it easier for consumers to compare and purchase different brands. In addition, strategic pricing and promotions in these stores attract price-conscious consumers, further boosting sales. The availability of canola oil in these outlets aligns with consumer trends toward healthier cooking options, as canola oil is perceived as a healthier alternative to other oils.
Supermarkets and hypermarkets remain the leading distribution channel due to their broad product assortment, promotional activity, and strong consumer reach. Meanwhile, online retail is expected to register the fastest growth from 2026 to 2033, supported by expanding e-commerce penetration, convenient home delivery, wider availability of organic and specialty canola oils, and consumers' ability to compare products and prices across platforms.
The online segment is expected to grow at the fastest CAGR from 2026 to 2033. The online segment is also witnessing significant growth in canola oil sales, driven by the increasing popularity of e-commerce and digital shopping platforms. Consumers are increasingly turning to online channels for convenience, flexibility, and the ability to easily compare prices and products. The growth in this segment is further fueled by the rise of health-conscious consumers who seek out natural and organic products, which are often readily available online. Moreover, online platforms offer a broader range of specialty and niche products, including organic and non-GMO canola oils, which appeal to consumers seeking specific health benefits or dietary preferences.
Regional Insights
The canola oil industry in North America is anticipated to grow at the fastest CAGR during the forecast period. Several key factors drive the market growth. Firstly, there is a rising health consciousness among consumers, who are increasingly seeking healthier cooking oils with lower saturated fat content. Canola oil's nutritional profile, which includes high levels of monounsaturated and polyunsaturated fats, aligns well with these consumer preferences. Furthermore, government policies supporting sustainable agriculture and biofuel production also contribute to market growth in North America. The U.S. and Canada are significant markets, with the U.S. being a major consumer and Canada being a leading producer and exporter of canola oil. The increasing demand for biofuels, particularly in states like California with low-carbon fuel standards, further boosts the market for canola oil in this region. For instance, in March 2025, the USDA Economic Research Service reported that U.S. biomass-based diesel feedstock use reached 37.2 billion pounds in 2023/24, while imports of feedstocks, including canola oil, increased to supportthe expansion of renewable diesel and biodiesel production. This trend is strengthening demand for canola oil as a renewable fuel feedstock in North America.
U.S. Canola Oil Market Trends
The canola oil industry in the U.S. is anticipated to grow at a significant CAGR during the forecast period. Another significant factor is the expanding food processing industry in the U.S., which widely uses canola oil in various packaged and processed foods due to its neutral flavor and high smoke point. In addition, government policies supporting sustainable agriculture and biofuel production contribute to the growth of canola oil in the U.S. According to the USDA Economic Research Service in May 2025, U.S. canola crush was forecast at approximately 4.78 billion pounds for the 2025/26 marketing year, supported by strong domestic demand for canola oil across food and biofuel applications.. The elimination of tariffs and subsidies under trade agreements has also facilitated the country's expansion of canola and canola oil production.
Asia Pacific Canola Oil Market Trends
The canola oil industry in Asia Pacific dominated the market, accounting for the largest revenue share of approximately 36.0% in 2025. In the Asia-Pacific region, the growth of the canola oil industry is driven by increasing demand for healthier food options and a growing population. Consumers in this region are becoming more health-conscious, leading to a higher demand for cooking oils that offer health benefits, such as canola oil. In addition, the expanding food service and food processing industries in countries like China and India contribute to the growth of canola oil, as these sectors require large quantities of versatile oils for various applications. For instance, according to the Canola Council of Canada, China consumed approximately 39.74 million metric tonnes of vegetable oil for food use in 2025 and imported 120,476 metric tonnes of Canadian canola oil, highlighting the country's large edible-oil consumption base and continued demand for canola products.
 To learn more about this report, Download Free Sample Report
The economic growth and rising disposable incomes in many Asia-Pacific countries also support increased consumption of premium edible oils, including canola oil. Moreover, the region's focus on sustainable agriculture and biofuels provides additional opportunities for canola oil growth as countries seek to reduce their reliance on fossil fuels and promote environmentally friendly energy sources.
Key Canola Oil Company Insights
A high level of competition from established edible oils such as soybean, palm, and sunflower oils characterizes the canola oil industry's competitive landscape. These oils have well-established supply chains and customer bases, often benefiting from economies of scale, which can result in lower manufacturing costs and make it challenging for canola oil producers to compete on price.
Major players in the canola oil industry include Archer Daniels Midland Company (ADM), Bunge Limited, Cargill Inc., CHS Inc., Louis Dreyfus Company, and Richardson International Limited, among others. These companies leverage their extensive agricultural networks and advanced processing technologies to produce high-quality canola oil. They are heavily invested in research and development to improve crop yields and oil extraction processes, ensuring they meet the growing global demand for healthier oils.
Key Canola Oil Companies
The following key companies have been profiled for this study on the canola oil market.
-
Archer Daniels Midland Company (ADM)
-
Associated British Foods plc
-
Bunge Limited
-
Cargill Inc.
-
Jivo Wellness Pvt. Ltd.
-
Louis Dreyfus Company
-
Richardson International Limited
-
Wilmar International Ltd.
-
American Vegetable Oils, Inc.
-
Adani Wilmar
-
The J.M. Smucker Company
-
Arla Foods Amba
-
Highwood Crossing Foods Ltd.
-
La Tourangelle
-
Sunora Foods, Inc.
-
Parrish and Heimbecker, Limited
-
Paterson Grain
-
Huiles TITAN Oils Inc.
-
Dalmia Continental Pvt., Ltd.
-
Fuji Vegetable Oil Inc.
Recent Developments
- In June 2025, Richardson International highlighted the completed expansion of its Yorkton, Saskatchewan canola processing facility, which had increased annual processing capacity to 2.5 million metric tonnes. The expansion strengthens Richardson's ability to supply canola oil and meal to domestic and international markets and supports value-added canola processing in Canada.
- In April 2026, Cargill opened its new canola processing facility in Regina, Saskatchewan, with an annual processing capacity of 1 million metric tonnes. The facility produces canola oil for food and renewable fuel applications as well as canola meal for animal feed, expanding domestic processing capacity and market access for Canadian growers.
Canola Oil Market Report Scope
Report Attribute
Details
Market size in 2025
USD 35.6 billion
Estimated market size in 2026
USD 36.8 billion
Projected market size by 2033
USD 45.6 billion
Growth rate
CAGR of 3.1% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 – 2024
Forecast period
2026 – 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, application, distribution, region
Regional Scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country Scope
U.S; Canada; Mexico; Germany; UK; France; Italy; Spain; China; Japan; India; Australia & New Zealand; South Korea; Brazil; South Africa
Key companies profiled
Archer Daniels Midland Company (ADM); Associated British Foods plc; Bunge Limited; Cargill Inc.; Jivo Wellness Pvt. Ltd.; Louis Dreyfus Company; Richardson International Limited; Wilmar International Ltd.; American Vegetable Oils, Inc.; Adani Wilmar; The J.M. Smucker Company; Arla Foods Amba; Highwood Crossing Foods Ltd.; La Tourangelle; Sunora Foods, Inc.; Parrish and Heimbecker, Limited; Paterson Grain; Huiles TITAN Oils Inc.; Dalmia Continental Pvt., Ltd.; Fuji Vegetable Oil Inc.
Customization scope
Free report customization (equivalent to 8 analyst working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail of customized purchase options to meet your exact research needs. Explore purchase options
Global Canola Oil Market Report Segmentation
This report forecasts revenue growth at the global, regional, and country levels and provides an analysis of the latest industry trends and opportunities across each sub-segment from 2021 to 2033. For this study, Grand View Research has segmented the global canola oil market report based on product, application, distribution, and region:
-
Product Outlook (Revenue, USD Billion, 2021 - 2033)
-
Processed Canola Oil
-
Virgin Canola Oil
-
-
Application Outlook (Revenue, USD Billion, 2021 - 2033)
-
Food Processing
-
Food Service
-
Retail
-
Others
-
-
Distribution Outlook (Revenue, USD Billion, 2021 - 2033)
-
Supermarkets & Hypermarkets
-
Franchise Outlet
-
Specialty Stores
-
Online Retailers
-
-
Regional Outlook (Revenue, USD Billion, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
- Europe
-
-
Germany
-
UK
-
Italy
-
France
-
Spain
-
-
Asia Pacific
-
China
-
Japan
-
India
-
Australia & New Zealand
-
South Korea
-
- Central & South America
-
-
Brazil
-
- Middle East and Africa
-
-
South Africa
-
Frequently Asked Questions About This Report
Asia Pacific dominated with an approximately 36.0% revenue share in 2025.
The global canola oil market size was valued at USD 35.6 billion in 2025 and is estimated at USD 36.8 billion for 2026.
The global canola oil market is expected to grow at a CAGR of 3.1% from 2026 to 2033, reaching USD 45.6 billion.
Key players in the market include Archer Daniels Midland Company (ADM); Associated British Foods plc; Bunge Limited; Cargill Inc.; Jivo Wellness Pvt. Ltd.; Louis Dreyfus Company; Richardson International Limited; Wilmar International Ltd.; American Vegetable Oils, Inc.; Adani Wilmar; The J.M. Smucker Company; Arla Foods Amba; Highwood Crossing Foods Ltd.; La Tourangelle; Sunora Foods, Inc.; Parrish and Heimbecker, Limited; Paterson Grain; Huiles TITAN Oils Inc.; Dalmia Continental Pvt., Ltd.; Fuji Vegetable Oil Inc. and others.
The processed canola oil segment accounted for the largest revenue share of around 71.0% in 2025.
About the Author(s)
Consumer F&B Research Team
Consumer Goods · Consumer F&BThis report was authored by the consumer f&b research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the consumer f&b segment of the consumer goods industry. All findings are based on proprietary consumer goods databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


