
- Home
- »
- Medical Devices
- »
-
Cardiac Monitoring & Cardiac Rhythm Management Devices Market 2026-2033GVR Report cover

Cardiac Monitoring And Cardiac Rhythm Management Devices Market (2026 - 2033) Size, Share & Trends Analysis Report By Product (Cardiac Monitoring Devices, Cardiac Rhythm Management Devices), By End Use (Hospitals, Ambulatory Surgery Centers), By Region, And Segment Forecasts
Market Size, 2025
$30.0BMarket Estimate, 2026
$31.9BMarket Forecast, 2033
$49.8BCAGR, 2026–2033
6.5%Cardiac Monitoring And Cardiac Rhythm Management Devices Market Summary
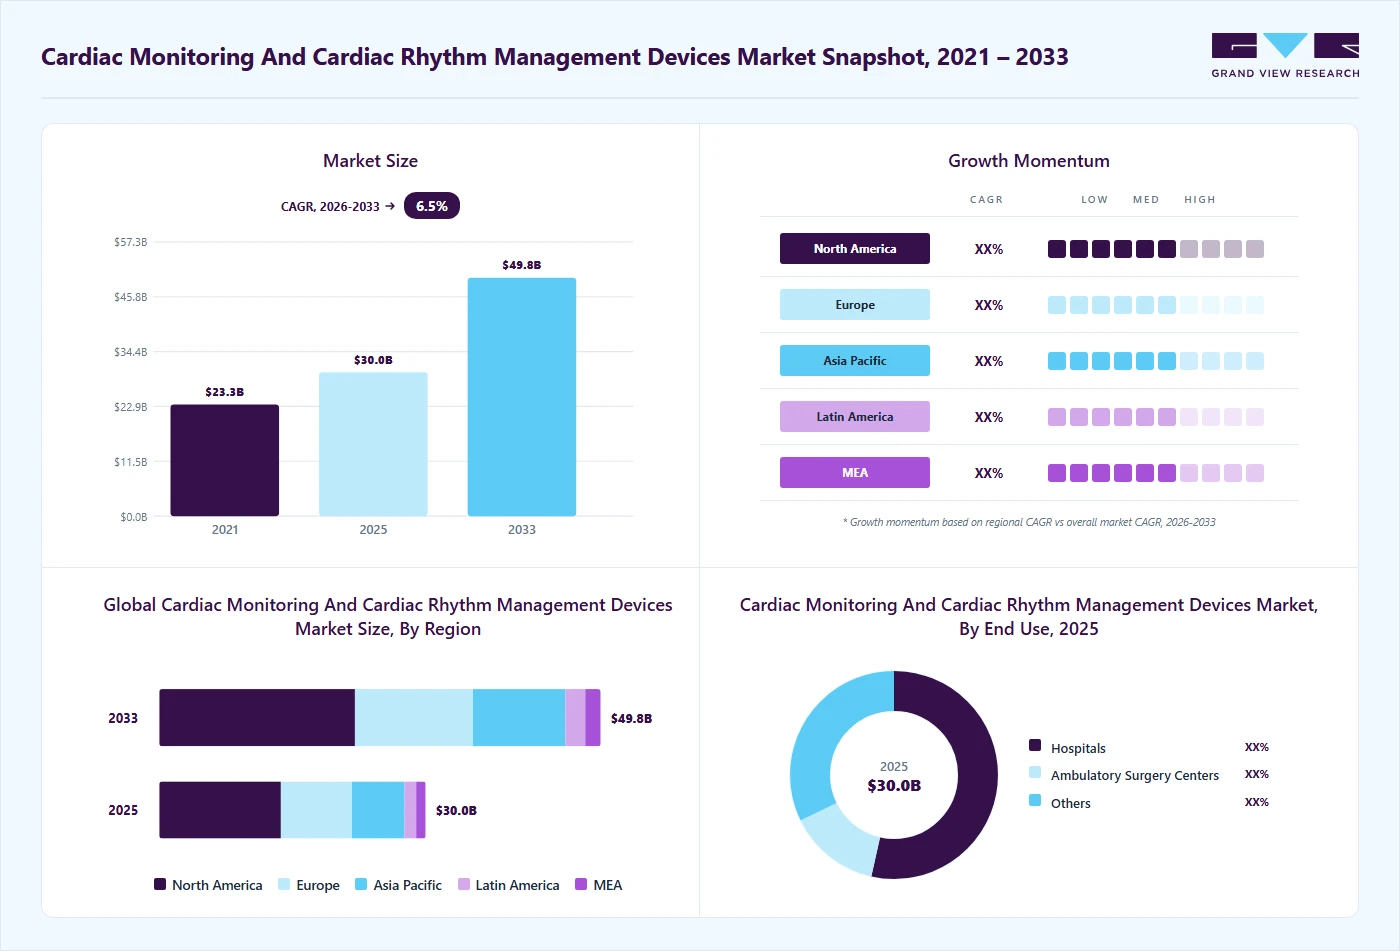
The global cardiac monitoring and cardiac rhythm management devices market size was valued at USD 30.0 billion in 2025 and is projected to grow from USD 31.9 billion in 2026 to USD 49.8 billion by 2033, at a CAGR of 6.5% from 2026 to 2033. The North America cardiac monitoring and cardiac rhythm management devices market held the largest share of 45.6% of the global market in 2025. The market growth is driven by the increasing prevalence of cardiovascular diseases and arrhythmias, the growing aging population, and the rising lifestyle-related risk factors.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By product: Cardiac rhythm management devices led the global cardiac monitoring and cardiac rhythm management devices industry and accounted for a share of 73.6% in 2025.
- By end use: Hospital segment led the market and accounted for a share of 53.4% in 2025.
Regional Highlights
- Largest regional market: North America (45.6% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest revenue share in 2025.
Market Size & Forecast
- Market size in 2025: USD 30.0 Billion
- Estimated market size in 2026: USD 31.9 Billion
- Projected market size by 2033: USD 49.8 Billion
- CAGR (2026-2033): 6.5%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The growing adoption of advanced cardiac monitoring solutions, such as wearable ECG devices, implantable loop recorders, and remote monitoring platforms, is enabling earlier diagnosis and continuous disease management outside of hospital settings. The technological advancements in CRM devices, including leadless and MRI-compatible pacemakers and next-generation ICDs, are enhancing clinical outcomes and device longevity, thereby supporting replacement demand and promoting broader adoption.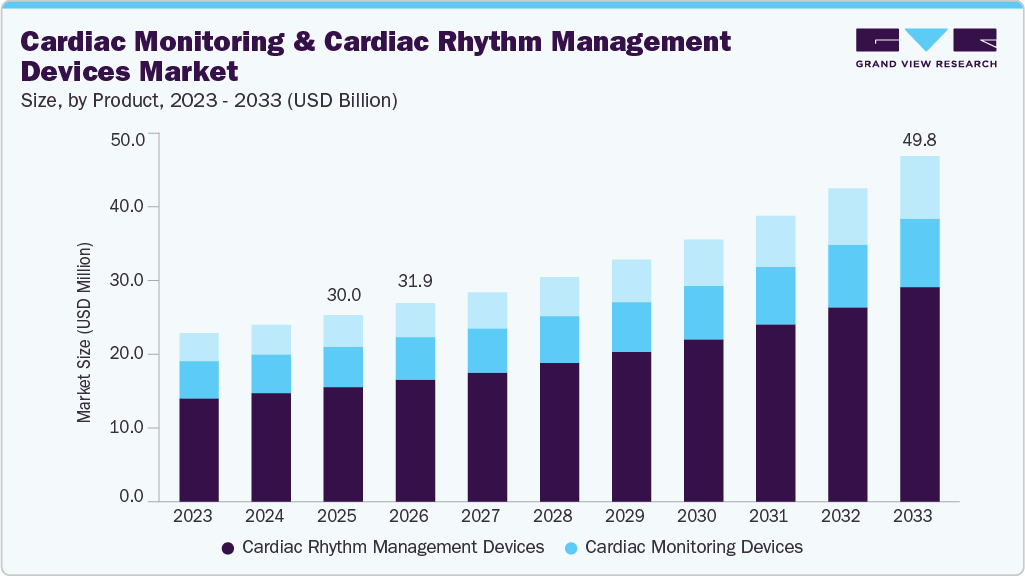 To learn more about this report, Download Free Sample Report
Increasing cardiovascular incidence is one of the key factors driving the growth of the cardiac monitoring and cardiac rhythm management industry. According to an Oxford Academic article published in January 2025, the global age-standardized prevalence of cardiovascular disease reaches approximately 7,179 cases per 100,000 people, highlighting the significant and ongoing impact of heart conditions worldwide. Such widespread prevalence means that millions are living with diseases that require careful monitoring and timely intervention to prevent complications. In September 2025, Philips introduced a new telemetry platform featuring the Telemetry Monitor 5500 to streamline cardiac monitoring and reduce non-actionable alarms. The system supports scalable, wearable monitoring, mobile workflows, and up to 30-day post-discharge cardiac tracking through its MCOT service.
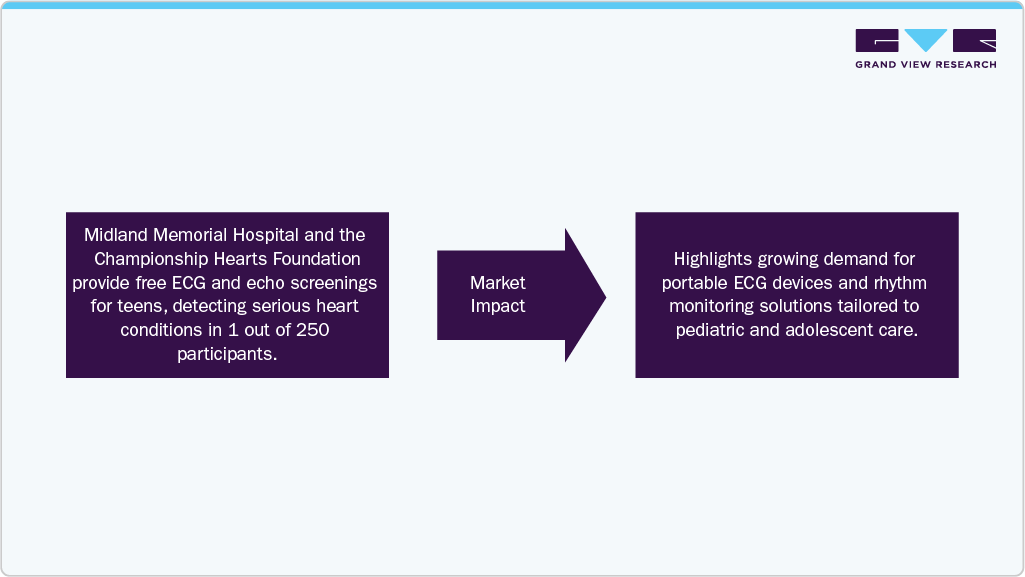
Increasing awareness campaigns and government-initiated screening programs for early detection of CVDs contribute to market expansion by ensuring more patients receive timely diagnosis and treatment. According to an article published by Hearst Newspapers II, LLC in June 2025, Midland Memorial Hospital, in collaboration with the Championship Hearts Foundation, offers free ECG and limited echocardiogram screenings to teenagers between 14 and 18 years old. In previous events, these screenings identified severe, potentially life-threatening heart conditions, such as hypertrophic cardiomyopathy, in approximately 1 out of every 250 participants. Initiatives like this highlight the critical role of early detection in preventing sudden cardiac events among young people. They also emphasize the growing need for portable ECG devices and advanced rhythm-monitoring technologies tailored for pediatric and adolescent populations, thereby contributing to the market expansion.
 To learn more about this report, Download Free Sample Report
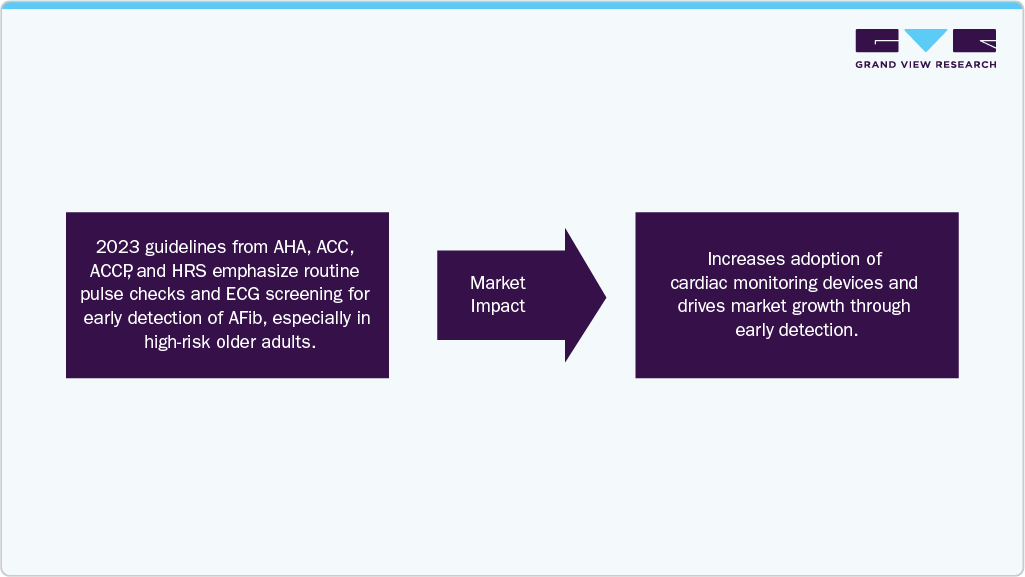
Moreover, according to the American Heart Association, Inc. article published in November 2023, the 2023 guidelines released by the American Heart Association (AHA), American College of Cardiology (ACC), American College of Chest Physicians (ACCP), and the Heart Rhythm Society (HRS) highlight the importance of raising awareness and incorporating routine screening for atrial fibrillation (AFib), especially in high-risk groups such as older adults. These recommendations encourage regular pulse and ECG screenings to support early diagnosis and effective treatment. Detecting and managing AFib promptly is crucial because it can significantly lower the risk of stroke and other serious health issues. This emphasis on proactive screening and education contributes to an increased demand for cardiac monitoring and rhythm management devices, which play a central role in identifying heart rhythm disorders and guiding appropriate medical care, thereby driving the market growth.
 To learn more about this report, Download Free Sample Report
The efficiency of targeted screening programs for CVDs fuels market growth. According to Springer Nature in June 2024, a review of cardiology reports that examines the impact of screening programs highlights findings from multicenter studies, such as AF-SCREEN and STROKESTOP, which demonstrate that targeted screening significantly enhances the detection of CVDs, particularly among older adults. The review strongly supports establishing national screening initiatives to address the growing burden of AFib-related complications, highlighting the critical role of early detection and intervention.
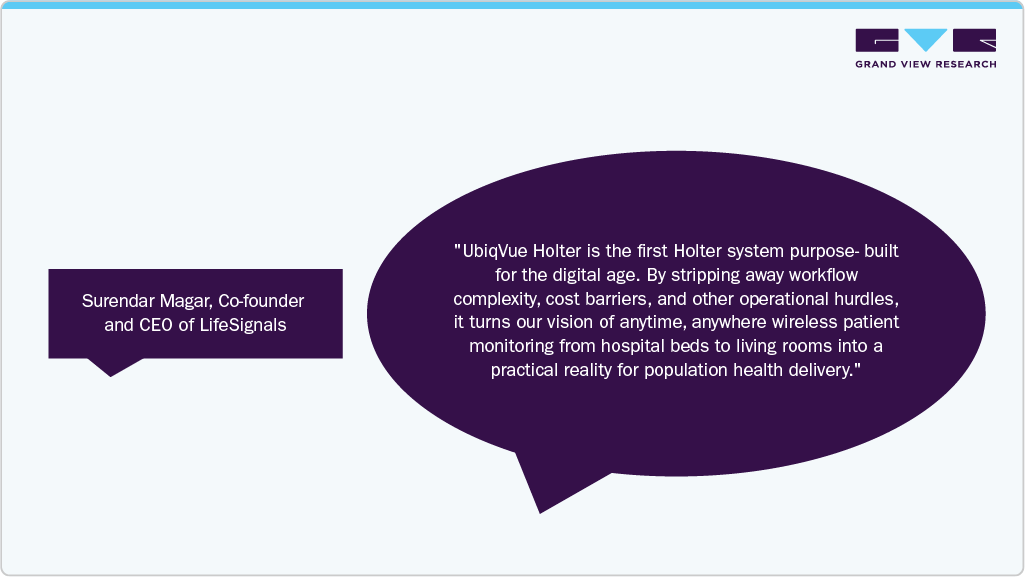
The technologically advanced products offered by the key players drive the market's growth. For instance, in April 2025, LifeSignals, Inc., introduced the UbiqVue 2AYe Holter System at Heart Rhythm 2025. This new Holter monitoring solution, distributed in collaboration with UltraLinQ Healthcare Solutions, is designed to streamline cardiac monitoring workflows by producing diagnostic reports far faster than traditional methods and eliminating the need to mail or physically retrieve the biosensor device.
At the heart of the UbiqVue system is the 2AYe Biosensora, a disposable, chest-worn device capable of continuously recording two-channel ECG and event data for up to five days. Data collected by the biosensor is securely encrypted and sent via a patient-facing mobile app to a cloud-based platform during the monitoring period. Once the Holter test concludes, the patient’s data is quickly analyzed through cloud-based ECG analytics, substantially reducing the review time required by certified cardiac technicians and enabling physicians to access finalized reports within hours.
 To learn more about this report, Download Free Sample Report
Comparison Of Cardiac Monitoring And Rhythm Management Devices
Category
Purpose / Function
Key Technologies
Typical Devices / Platforms
Applications
Cardiac Monitoring
Track heart health, detect abnormalities, support clinical decisions
AI-enhanced echocardiography, wearable patches, implantable sensors, smartphone-based monitoring
Ventripoint VMS+, Future Cardia implantable ECG sensor, Artella remote monitoring
Heart failure, valve dysfunction, congenital heart disease, chemotherapy-related cardiac complications, and post-surgery monitoring
Cardiac Rhythm Management
Detect and correct abnormal heart rhythms
Pacemakers, ICDs (Implantable Cardioverter Defibrillators), leadless devices, ablation systems
Medtronic pacemakers, Boston Scientific ICDs, Abbott rhythm management devices
Bradycardia, tachycardia, atrial fibrillation, ventricular arrhythmias
Data Connectivity In Cardiac Monitoring And Rhythm Management
Modern cardiac monitoring and rhythm management devices rely on advanced data connectivity to enable remote, real-time patient monitoring and seamless clinical workflows. These devices transmit vital signs and electrocardiogram (ECG) data through secure channels such as Wi-Fi, Bluetooth, or cellular networks to cloud-based platforms. Healthcare providers can access patient data via web portals, mobile apps, or integrated hospital systems, enabling timely intervention and longitudinal tracking. Data connectivity also supports integration with electronic health records (EHRs) and third-party analytics platforms, ensuring compliance with security and privacy standards, including HIPAA, GDPR, and regional regulations. This connectivity enhances workflow efficiency, patient adherence, and clinical decision-making while supporting large-scale population health initiatives.
Connectivity Features For Cardiac Monitoring And Cardiac Rhythm Management
Feature
Description
Examples / Notes
Transmission Medium
How device data is sent
Wi-Fi, Bluetooth, Cellular (3G/4G/5G)
Data Type
Information captured and transmitted
ECG, heart rate, rhythm, blood pressure, oxygen saturation
Remote Access
How clinicians view data
Web portal, mobile app, cloud dashboard
Integration
Compatibility with other systems
EHR/EMR systems, analytics platforms, and telehealth systems
Security & Compliance
Measures to protect data
Encryption, HIPAA, GDPR, FDA/CE compliant
Real-time Monitoring
Ability to alert clinicians
Immediate notifications for arrhythmia or abnormal vitals
Patient Engagement
How patients interact
Smartphone apps, wearable feedback, adherence reminders
Market Dynamics
Increasing awareness campaigns and government-led screening programs for early cardiovascular disease (CVD) detection are supporting market growth by enabling timely diagnosis and treatment. According to an article published by Hearst Newspapers II, LLC in June 2025, Midland Memorial Hospital, working alongside the Championship Hearts Foundation, conducts free ECG and limited echocardiogram screenings for teenagers between 14 and 18 years old. These screenings identified severe heart conditions, such as hypertrophic cardiomyopathy, in approximately 1 out of every 250 participants. They also emphasize the growing need for portable ECG devices and advanced rhythm-monitoring technologies tailored for pediatric and adolescent populations, contributing to market growth.
Moreover, 2023 guidelines released by the American Heart Association (AHA), American College of Cardiology (ACC), American College of Chest Physicians (ACCP), and the Heart Rhythm Society (HRS) emphasize routine pulse and ECG screening for atrial fibrillation (AFib), particularly among high-risk populations such as older adults. The focus on early detection and awareness is increasing demand for cardiac monitoring and cardiac rhythm management devices used in diagnosing and managing heart rhythm disorders, thereby driving market expansion.
Product recalls in cardiovascular devices negatively impact the industry by reducing confidence among patients, healthcare professionals, and stakeholders. As these devices are critical for managing cardiac conditions, safety and reliability remain essential.
According to a Dove Medical Press article published in May 2023, 189 Class I recalls involving 79.9% moderate-risk and 18.0% high-risk devices highlighted significant safety concerns. These recalls increase regulatory scrutiny, operational costs, and quality control requirements, thereby restraining growth in the cardiovascular management devices market.
The technologically advanced products offered by the key players drive the market's growth. For instance, in April 2025, LifeSignals, Inc. introduced the UbiqVue 2AYe Holter System at Heart Rhythm 2025. This new Holter monitoring solution, distributed in collaboration with UltraLinQ Healthcare Solutions, is designed to streamline cardiac monitoring workflows by producing diagnostic reports far faster than traditional methods and eliminating the need to mail or physically retrieve the biosensor device.
At the heart of the UbiqVue system is the 2AYe Biosensor—a disposable, chest-worn device capable of continuously recording two-channel ECG and event data for up to five days. Data collected by the biosensor is securely encrypted and sent via a patient-facing mobile app to a cloud-based platform during the monitoring period. Once the Holter test concludes, the patient’s data is quickly analyzed through cloud-based ECG analytics, substantially reducing the review time required by certified cardiac technicians and enabling physicians to access finalized reports within hours.
The high cost of cardiac monitoring and rhythm management devices remains a major challenge for market growth, particularly in cost-sensitive healthcare systems. High device acquisition and implantation costs, along with reimbursement limitations and out-of-pocket expenses, can restrict the adoption of advanced technologies and limit wider market penetration.
This report has been delivered with the following In-depth customizations
Device/Procedure
Cost Range (USD)
Source
CRT Devices
35,000–45,000
TCTMD, August 2024
Pacemaker Implantation
10,000–50,000
Journal of the American College of Cardiology, November 2023
Defibrillator Implantation
25,000–80,000
Journal of the American College of Cardiology, November 2023
Market Concentration & Characteristics
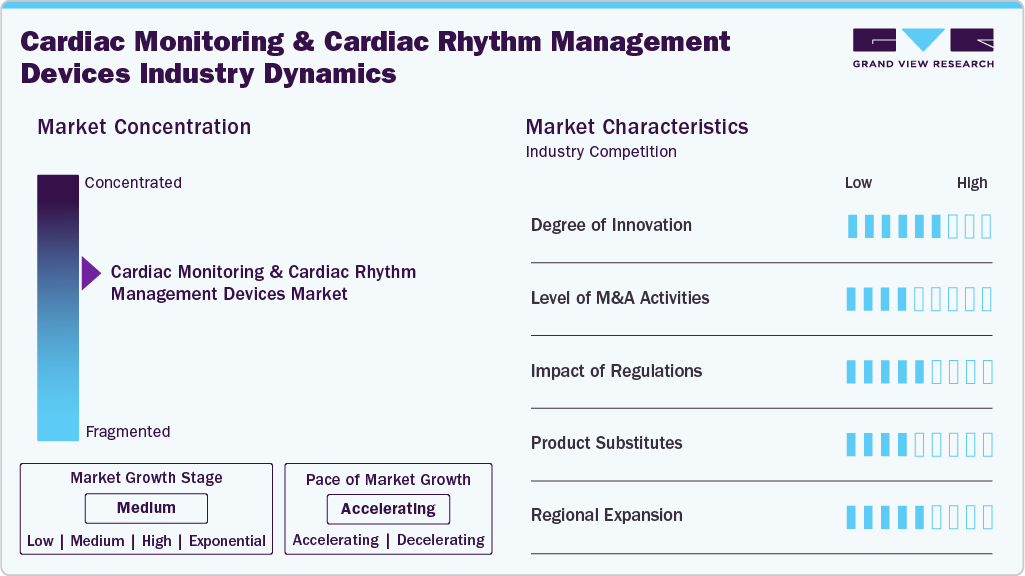
The global cardiac monitoring and cardiac rhythm management devices market is characterized by a high degree of innovation, driven by the development of technologically advanced solutions and continuous advancements in pacemaker technology. For instance, in March 2025, MicroPort Scientific Corporation launched the localized TEN pacemaker family in China through its affiliate MicroPort CRM Shanghai. The TEN series includes six compact, long-life models across T, E, and N categories, offering AutoMRI compatibility and the SAM function for continuous sleep and arrhythmia monitoring.
Several market players, including Stryker, Abbott, Boston Scientific Corporation, and Medtronic, actively engage in mergers and acquisitions within the market. Through these activities, companies pursue key strategies including developing innovative products, forming strategic partnerships, and expanding into new geographic regions. For example, in December 2025, Teleflex Incorporated announced that it had entered into a definitive agreement to acquire substantially all of BIOTRONIK SE & Co. KG's Vascular Intervention business for an estimated cash payment of approximately €760 million (approximately USD 839.04 million).
 To learn more about this report, Download Free Sample Report
Regulatory oversight significantly aligns the cardiac monitoring and cardiac rhythm management industry. Strict evaluation criteria from agencies such as the FDA and EMA ensure that devices meet high standards of patient safety and therapeutic effectiveness, often extending development timelines and approval costs. Nevertheless, evolving regulatory pathways, including expedited review programs and digital health frameworks, enable the faster clearance of innovative technologies such as wearable monitors, implantable loop recorders, and next-generation cardiac rhythm devices. These regulatory shifts enable manufacturers to deliver advanced, patient-centric solutions while maintaining rigorous safety and performance standards.
There are currently no direct substitutes. These systems play a crucial role in continuous heart rhythm assessment, the early detection of abnormalities, and the timely implementation of therapeutic interventions. Tools such as standard ECGs or periodic check-ups help identify cardiac issues; however lack the continuous, high-fidelity monitoring and therapeutic capabilities offered by implantable devices, wearable sensors, and advanced rhythm management solutions. As such, their unique ability to combine diagnostic precision with real-time management remains essential in modern cardiac care.
Key manufacturers in the cardiac monitoring and cardiac rhythm management industry are actively expanding their reach by exploring untapped regional markets, collaborating with local distribution partners, and tailoring their product portfolios to meet the distinct healthcare needs of various geographies. In December 2025, Ventripoint partnered with the Nisga’a Valley Health Authority to launch a hub-and-spoke model utilizing its AI-powered VMS+ ultrasound technology, delivering advanced cardiac imaging to remote and Indigenous communities in British Columbia.
Product Insights
The cardiac rhythm management devices segment dominated the market with the largest revenue share of 73.6% in 2025. Cardiac rhythm management (CRM) devices are designed to regulate heart rhythm in patients with arrhythmias, bradycardia, or heart failure. This segment encompasses implantable devices, including pacemakers, implantable cardioverter-defibrillators (ICDs), and cardiac resynchronization therapy (CRT) systems. These devices restore usual cardiac pacing, prevent sudden cardiac death, and improve ventricular synchrony in patients with reduced ejection fraction or conduction delays. Technological advancement drives the growth of the market. In March 2025, MicroPort Scientific Corporation gained CE Mark approval for its SmartView Connect App Mobile, allowing Android-based remote monitoring of Bluetooth-enabled pacemakers, ICDs, and CRT-Ds. The app securely transmits encrypted data to the SmartView network, replacing bedside monitors and supporting real-time, clinic-connected cardiac care across Europe.
The cardiac monitoring devices segment is anticipated to grow at the fastest CAGR over the forecast period. Cardiac monitoring devices are designed to continuously or intermittently assess electrical and hemodynamic cardiac parameters, enabling early detection of arrhythmias, ischemia, and other cardiac events. These systems are essential in acute and ambulatory care, supporting diagnosis, treatment planning, and long-term disease management. Key products in this category include Holter monitors, event recorders, mobile cardiac telemetry systems, and ECG machines used in hospitals and outpatient settings. Technological advancement drives the growth of the market. In February 2025, CB Scientific launched its next-generation MyCardia AT cardiac event monitor across Southeast Asia, Hong Kong, and Macau. The FDA-cleared device features a lightweight, user-friendly design with smartphone compatibility, allowing for up to 30 days of remote ECG monitoring. As local distributors begin regulatory approvals, the company aims to scale its connected cardiac monitoring ecosystem and expand its presence in key global markets.
End Use Insights
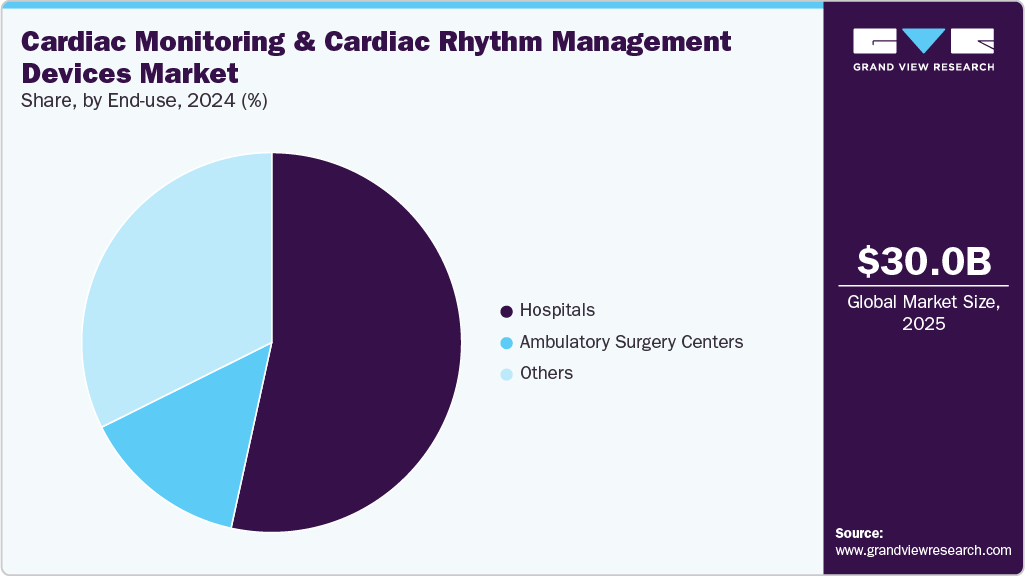
By end use, the hospital segment dominated the cardiac monitoring and cardiac rhythm management devices market, accounting for a revenue share of 53.4% in 2024. Hospitals remain the primary setting for the use and adoption of cardiac monitoring and cardiac rhythm management (CRM) devices, driven by their ability to handle high-acuity patients and deliver device-based interventions. Key devices include Holter monitors, telemetry systems, event monitors, ECG machines, pacemakers, ICDs, and CRT devices. Hospitals rely on continuous cardiac monitoring for patients in emergency, intensive care, and perioperative settings to detect arrhythmias, ischemic events, or heart failure decompensation early and intervene accordingly. In November 2024, BioIntelliSense reported results from a 15-month study showing that its chest-worn BioButton device reduced hospital stays for cardiac patients from 3.07 to 2.75 days. The wearable provided early warnings of deterioration 14.8 hours in advance, improving clinical response times. The device continuously tracked heart rate, respiration, and other vitals in over 12,000 patients, enabling 114 new or modified physician orders during monitoring.
 To learn more about this report, Download Free Sample Report
The ambulatory surgery centers segment is expected to experience significant growth over the forecast period. Ambulatory surgery centers (ASCs) are increasingly involved in the procedural side of cardiac rhythm management, particularly for patients requiring low-risk pacemaker or loop recorder implantation. The shift toward ASCs reflects broader efforts to reduce inpatient burden and procedural costs while maintaining clinical outcomes. These centers typically cater to stable patients and use minimally invasive techniques, supported by portable ECG and device programming tools, to perform device implants and diagnostics with quick turnaround. In February 2024, the American College of Cardiology launched its CV ASC Registry Suite to track the increasing number of cardiac procedures performed in ambulatory surgical centers. The registry tracks interventions such as diagnostic catheterization, pacemaker, and defibrillator implantations, key product types in the cardiac rhythm management and monitoring devices market. It provides benchmarking data that may influence product adoption trends in outpatient cardiac care.
Regional Insights
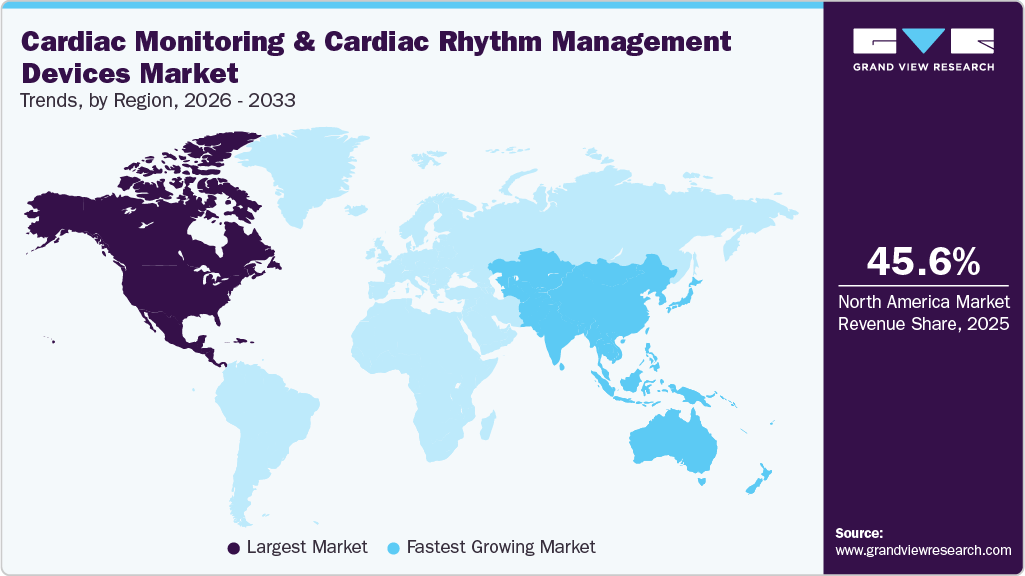
North America dominated the cardiac monitoring and cardiac rhythm management devices market with a revenue share of 45.64% in 2025. Increased prevalence of atrial fibrillation (AFib) drives the growth of the U.S. cardiac monitoring and cardiac rhythm management devices market. According to the American Heart Association article published in March 2025, Atrial fibrillation (AFib), the most prevalent form of irregular heart rhythm, affected about five million individuals across the U.S. in 2024. Projections indicate this number could surpass 12+ million by 2030, reflecting a significant rise in the burden of arrhythmias nationwide. This growing prevalence is a key factor fueling demand for advanced cardiac monitoring tools and cardiac rhythm management devices in North America.
 To learn more about this report, Download Free Sample Report
U.S. Cardiac Monitoring and Cardiac Rhythm Management Devices Market Trends
The U.S. cardiac monitoring and cardiac rhythm management devices industry led North America in 2025. Technologically advanced products launched by key manufacturers drive the market's growth. For instance, in December 2024, HeartBeam, Inc., a medical technology firm dedicated to advancing cardiac care through innovative diagnostic tools, recently announced that it has secured 510(k) clearance from the U.S. Food and Drug Administration (FDA) for its HeartBeam system, designed for comprehensive arrhythmia detection. This marks the first FDA clearance for a device of its kind, featuring a unique, patented approach. The HeartBeam system offers a high-fidelity electrocardiogram (ECG) capability within a compact, credit card-sized, wireless design, enabling the capture of heart activity from three different angles to deliver critical insights into cardiac health.
Europe Cardiac Monitoring and Cardiac Rhythm Management Devices Market Trends
The cardiac monitoring and cardiac rhythm management devices industry in Europe is expected to experience significant growth over the forecast period. The high mortality rate from cardiovascular diseases boosts demand for cardiac monitoring and cardiac rhythm management devices in Europe. According to the WHO article published in May 2024, cardiovascular diseases (CVDs) are the leading cause of disability and premature death in the European Region, responsible for over 42.5% of all deaths annually. This staggering statistic translates to approximately 10,000 deaths every day. The significant impact of CVD emphasizes the urgent need for advanced cardiac monitoring and cardiac rhythm management solutions.
The UK cardiac monitoring and cardiac rhythm management devices market is expected to grow significantly during the forecast period. Growing AFib incidence in the UK drives the growth of the market. According to the British Heart Foundation article published in January 2025, in the UK, over 1.6 million people have been diagnosed with atrial fibrillation (AFib). This communal heart rhythm disorder increases the risk of stroke and other serious complications. Despite many diagnoses, many patients still do not receive optimal treatment or consistent monitoring. This gap in care highlights the urgent need for more advanced solutions to detect, track, and manage AF effectively.
Asia Pacific Cardiac Monitoring and Cardiac Rhythm Management Devices Market Trends
The Asia Pacific cardiac monitoring and cardiac rhythm management devices industry is expected to register the fastest CAGR over the forecast period. Rising elderly population in the Asia Pacific region. According to the United Nations Economic and Social Commission for Asia and the Pacific, in 2023, approximately 697 million individuals aged 60 years or older lived in Asia and the Pacific region, constituting approximately 60% of the global older population. The elderly population is more susceptible to cardiovascular diseases, and the increase in the population is leading to a higher demand for cardiac monitoring and cardiac rhythm management devices.
China's cardiac monitoring and cardiac rhythm management devices market is anticipated to grow considerably during the forecast period. Increasing CVD cases drive the growth of the market. According to an NCBI article published in November 2023, China faces a massive health challenge, with an estimated 330 million people affected by cardiovascular diseases, underscoring the country’s growing burden of heart-related conditions. This vast patient pool is driving demand for advanced cardiac monitoring and rhythm management devices, as healthcare providers seek to enhance early detection, accurate diagnosis, and effective treatment of conditions such as arrhythmias, heart failure, and coronary artery disease.
Latin America Cardiac Monitoring and Cardiac Rhythm Management Devices Market Trends
The Latin America cardiac monitoring and cardiac rhythm management devices industry is anticipated to witness considerable growth over the forecast period, fueled by rising cardiovascular disease incidence, aging populations, and awareness of early diagnosis and preventive care. Countries across the region are increasingly adopting advanced technologies such as implantable monitors, wearable ECG devices, and modern defibrillators to improve patient outcomes. In June 2025, Dong-A ST launched its HiCardi+ remote cardiac monitoring platform in Brazil, introducing a wearable ECG patch connected to a smartphone and entering the Latin American digital health market through a partnership with Cardio Web.
Argentina's cardiac monitoring and cardiac rhythm management devices market is anticipated to register considerable growth during the forecast period. Rising adoption of cardiac rhythm devices drives the development of the market. According to an NCBI article published in December 2024, over 22,000 cardiac rhythm management devices were implanted nationwide in 2022, highlighting the growing reliance on advanced cardiac technologies. Moreover, pacemakers accounted for most of these procedures, with approximately 18,699 units implanted, representing 84.1%. This surge in device utilization reflects the increasing burden of arrhythmias and other heart rhythm disorders, as well as the expanding capacity of Argentina’s healthcare system to adopt life-saving rhythm management solutions.
Middle East & Africa Cardiac Monitoring and Cardiac Rhythm Management Devices Market Trends
The Middle East and Africa cardiac monitoring and cardiac rhythm management devices industry is anticipated to witness considerable growth over the forecast period, driven by rising cases of cardiovascular diseases and arrhythmias, as well as increasing awareness about the benefits of early detection and modern treatments. Countries in the region report higher rates of arrhythmias, heart failure, and other cardiac conditions, prompting a greater demand for technologies that help monitor and regulate heart rhythms. In January 2025, LifeSignals announced that its FDA 510(k)-cleared UbiqVue Multiparameter System would be showcased at Arab Health 2025 in Dubai, UAE. The wireless patient-monitoring system uses a wearable biosensor to continuously collect physiological data, including 2-channel ECG, respiration rate, skin temperature, and motion, supporting remote and continuous patient monitoring.
The UAE cardiac monitoring and cardiac rhythm management devices market is anticipated to grow considerably during the forecast period. Increasing CVD mortality drives the growth of the market. According to the American Heart Association, Inc., an article published in November 2024, in the United Arab Emirates, cardiovascular diseases remain the foremost health challenge, responsible for 36.7% of all deaths, emphasizing the significant impact of heart-related conditions on public health. This high burden of disease highlights the urgent need for advanced diagnostic and therapeutic solutions to detect and manage heart rhythm disorders effectively.
Key Cardiac Monitoring and Cardiac Rhythm Management Company Insights
Key participants in the cardiac monitoring and cardiac rhythm management devices industry focus on devising innovative business growth strategies, such as expanding their product portfolios, forming partnerships and collaborations, engaging in mergers and acquisitions, and expanding their business footprints.
Key Cardiac Monitoring And Cardiac Rhythm Management Devices Companies:
The following are the leading companies in the cardiac monitoring and cardiac rhythm management devices market. These companies collectively hold the largest market share and dictate industry trends.
- Stryker
- Medtronic
- Abbott
- Boston Scientific Corporation
- Koninklijke Philips N.V.
- ZOLL Medical Corporation. (Asahi Kasei company)
- GE HealthCare
- MicroPort Scientific Corporation
- NIHON KOHDEN CORPORATION
- Biotronik SE & Co KG
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Player: Medtronic
- Mature cardiac monitoring and rhythm management players focus on enhancing diagnostic accuracy and device longevity.
- They form alliances to integrate AI and remote monitoring capabilities.
- Operational scale and cost control ensure quality while maintaining pricing flexibility.
- Mature players maintain a competitive edge with clinically validated devices, long-standing physician trust, and integrated service infrastructure.
- Their regulatory expertise and sustained R&D investment enable consistent innovation and early market access.
- Legacy systems hinder agility in adopting disruptive technologies.
- Heavy operational structures and global scale may slow response to niche market shifts.
- Dependence on long replacement cycles can delay revenue from next-gen innovations.
Emerging Player: MicroPort Scientific Corporation
- Emerging players prioritize rapid development of AI-enabled and wearable technologies.
- They pursue strategic alliances to gain clinical validation and market access.
- Agile structures and streamlined teams support cost-effective innovation and scalability.
- Emerging players focus on AI-driven analytics and miniaturized, wearable form factors.
- They leverage speed and specialization to address unmet needs in remote and continuous monitoring.
- Collaborations with hospitals and research institutes help build clinical credibility and accelerate adoption.
- Limited regulatory experience and smaller clinical datasets can delay approvals.
- Narrow portfolios restrict market penetration across care settings.
- Scaling production and support services to meet demand remains a persistent challenge.
Recent Developments
-
In December 2025, SMART in Singapore launched WITEC, a program developing a wearable ultrasound patch for real time, long duration cardiovascular monitoring. Supported by MIT, NTU, NUS, and TTSH, the project aims to enable up to 48 hours of continuous imaging for chronic conditions, with clinical trials set to begin in early 2026.
-
In December 2025, OMRON Healthcare rolled out a global ECG strategy aimed at boosting early heart-failure detection. The plan includes increased investment in Tricog Health India and the acquisition of the Heartnote ECG service business, along with integrating AI-driven cardiac analytics into its ECG devices to expand remote monitoring and faster diagnosis.
-
In December 2025, Chennai-based vTitan launched vCardio, an AI-powered wearable cardiac monitor designed for continuous ECG tracking at home and in clinics. The lightweight patch device pairs with a mobile app and cloud platform, detects over 20 arrhythmias using AI, and supports long-duration remote monitoring to make cardiac screening more accessible.
-
In June 2024, Stryker launched the LIFEPAK 35 monitor/defibrillator to support advanced life support in both EMS and hospital settings. The device features an intuitive touchscreen, real-time data connectivity, and ergonomic design. It aims to reduce cognitive burden and improve response efficiency for frontline providers.
-
In May 2024, Koninklijke Philips N.V. rolled out its wearable ePatch and AI-powered Cardiologs analytics platform to 14 hospitals across Spain. The solution supports long-term ambulatory cardiac monitoring, enabling the early detection of atrial fibrillation and reducing the burden on emergency rooms. Clinical use at Vall d’Hebron Hospital led to shorter stays and cost savings.
-
In April 2024, MicroPort Scientific Corporation launched TALENTIA and ENERGYA, its new Bluetooth-enabled ICD and CRT-D ranges in Europe. These devices offer advanced remote monitoring, MRI compatibility, and the exclusive SonR hemodynamic optimization sensor. A modern tablet programmer interface was also introduced to streamline patient management and follow-up.
Cardiac Monitoring And Cardiac Rhythm Management Devices Market Report Scope
Report Attribute
Details
Market size in 2025
USD 30.0 billion
Estimated Market size in 2026
USD 31.9 billion
Projected Market size by 2033
USD 49.8 billion
Growth rate
CAGR of 6.5% from 2026 to 2033
Actual data
2021 - 2025
Forecast data
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, end use, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Sweden; Norway; China; Japan; India; Australia; South Korea; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
Stryker; Medtronic; Abbott; Boston Scientific Corporation; Koninklijke Philips N.V.; ZOLL Medical Corporation. (Asahi Kasei company); GE HealthCare; MicroPort Scientific Corporation; NIHON KOHDEN CORPORATION; Biotronik SE & Co KG
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Cardiac Monitoring And Cardiac Rhythm Management Devices Market Report Segmentation
This report forecasts revenue growth at the global, regional & country levels and analyzes the latest trends in each sub-segment from 2021 to 2033. For this report, Grand View Research has segmented the global cardiac monitoring and cardiac rhythm management devices market report based on product, end use, and region:
 To learn more about this report, Download Free Sample Report
-
Product Outlook (Unit Volume in ‘000 Units; Average Selling Price in USD per Unit; Revenue in USD Million, 2021 - 2033)
-
Cardiac Monitoring Devices
-
ECG
-
Implantable Cardiac Monitors
-
Holter Monitors
-
Mobile Cardiac Telemetry
-
-
Cardiac Rhythm Management Devices
-
Pulse Generators
-
Cardiac Resynchronization Therapy (CRT)
-
CRT-Defibrillator
-
CRT-Pacemakers
-
-
Defibrillators
-
Implantable Cardioverter Defibrillators (ICD)
-
Transvenous Implantable Cardioverter Defibrillators (TIICDs)
-
Single Chamber
-
Dual Chamber
-
-
Subcutaneous Implantable Cardioverter Defibrillators (S-ICDs)
-
External Defibrillator.
-
-
Pacemakers
-
Conventional Pacemakers
-
Leadless Pacemakers
-
-
-
Leads
-
Pacing Leads
-
Standard RV/LV Leads
-
Conduction System Pacing (CSP) / LBBAP Leads
-
-
Defibrillator Leads
-
Traditional Leads
-
LV Leads
-
-
-
-
-
End Use Outlook (Revenue USD Million, 2021 - 2033)
-
Hospitals
-
Ambulatory Surgery Centers
-
Others
-
-
Regional Outlook (Unit Volume in ‘000 Units; Average Selling Price in USD per Unit; Revenue in USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Delivered Customizations
This report has been delivered with the following In-depth customizations
CLIENT REQUEST
CUSTOMIZATION DELIVERED
VALUE ADDS
Device-level value and procedure volume analysis at country level
Detailed ASP analysis, procedure volume trends, device utilization rates, and implant/adoption assessment for key market players across cardiac monitoring devices and cardiac rhythm management products including ECG monitors, Holter monitors, implantable loop recorders, pacemakers, ICDs, and cardiac resynchronization therapy devices across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa.
Enables pricing benchmark assessment, evaluation of premium vs. value-based device positioning, identification of regional procedure demand trends, reimbursement impact analysis, and assessment of market penetration across cardiac monitoring and rhythm management technologies.
Cardiac Monitoring & Cardiac Rhythm Management Competitive Landscape and Technology Analysis
Comprehensive competitive landscape assessment including device benchmarking, AI-enabled monitoring capability analysis, product portfolio comparison, regulatory approval tracking, hospital partnership evaluation, remote patient monitoring capabilities, and regional market share analysis across leading cardiac device manufacturers.
Supports strategic competitor evaluation, technology differentiation assessment, acquisition and partnership analysis, product positioning evaluation, regional expansion planning, and identification of high-growth arrhythmia management and remote cardiac monitoring segments.
Device-level comparative analysis for the U.S., Europe and the rest of the world at the volume and revenue levels
Detailed comparative analysis of cardiac monitoring and cardiac rhythm management device sales volume, procedure volume, ASP trends, and revenue performance across the U.S., Europe, and Rest of the World for key products, including ECG monitors, Holter monitors, implantable loop recorders, pacemakers, ICDs, and CRT devices.
Enables regional demand comparison, revenue benchmarking, identification of high-growth geographies, evaluation of device adoption trends, competitive positioning assessment, and strategic expansion planning across global cardiac care markets.
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
The cardiac rhythm management devices segment led with a 73.6% revenue share in 2025, while cardiac monitoring devices is the fastest-growing segment.
The hospital segment accounted for the largest share in 2025, while ambulatory surgery centers is the fastest-growing segment.
The global cardiac monitoring and cardiac rhythm management devices market size was estimated at USD 30.0 billion in 2025 and is expected to reach USD 31.9 billion in 2026.
North America dominated with a 45.6% revenue share in 2025.
Key factors driving the cardiac monitoring and cardiac rhythm management devices market growth include increasing influx of established players, rising patient awareness levels, favorable government regulation, and technological advancements.
Some key players operating in the cardiac monitoring and cardiac rhythm management devices market include Stryker, Medtronic, Abbott, Boston Scientific Corporation, Koninklijke Philips N.V., ZOLL Medical Corporation. (Asahi Kasei company), GE HealthCare, MicroPort Scientific Corporation, NIHON KOHDEN CORPORATION, and Biotronik SE & Co KG.
The global cardiac monitoring and cardiac rhythm management devices market is expected to grow at a compound annual growth rate of 6.5% from 2026 to 2033 to reach USD 49.8 billion by 2033.
About the Author(s)
Medical Devices Research Team
Healthcare · Medical DevicesThis report was authored by the medical devices research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the medical devices segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


