
- Home
- »
- Pharmaceuticals
- »
-
Celiac Disease Treatment Market Size Report, 2026-2033GVR Report cover

Celiac Disease Treatment Market (2026 - 2033)
Size, Share & Trends Analysis Report By Treatment (Vitamins & Minerals, Gluten Degrading Enzymes), By Distribution Channel (Hospital Pharmacies, Retail Pharmacies), By Region, And Segment Forecasts
Market Size, 2025
$769.3MMarket Estimate, 2026
$851.9MMarket Forecast, 2033
$1,839.1MCAGR, 2026–2033
11.6%Celiac Disease Treatment Market Summary
The global celiac disease treatment market size was valued at USD 769.3 million in 2025 and is projected to grow from USD 851.9 million in 2026 to USD 1,839.1 million by 2033, at a CAGR of 11.6% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 41.2% in 2025. Foremost among these is the escalating prevalence of diagnosed celiac disease cases globally.
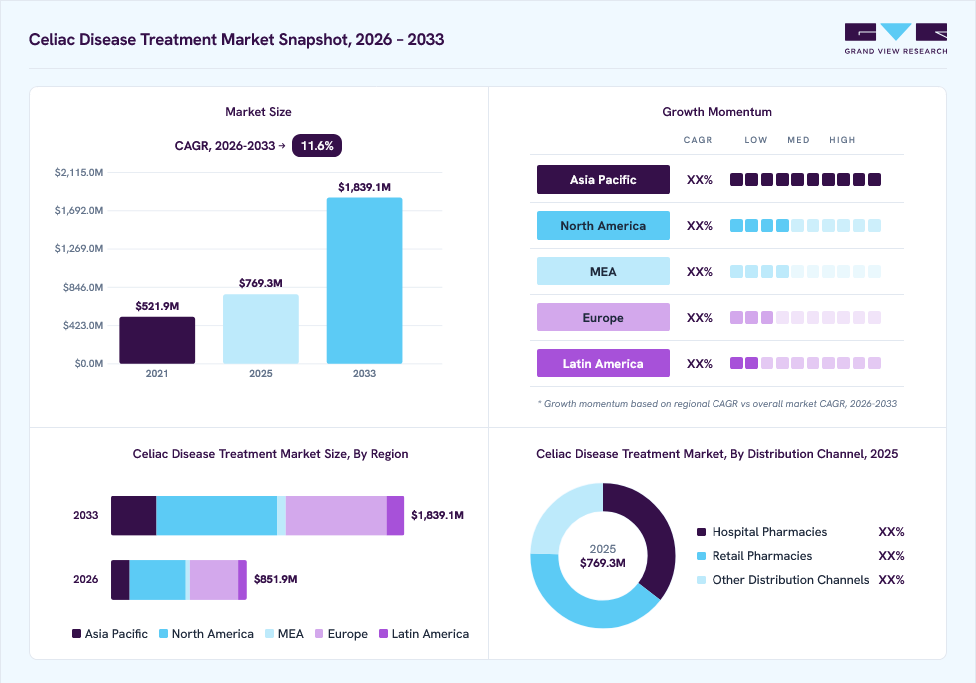 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By treatment: Vitamins & minerals segment dominated the market, with a revenue share of 40.4% in 2025.
- By distribution channel: Retail pharmacies segment held the largest market share of 40.0% in 2025.
Regional Highlights
- Largest regional market: North America (41.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 769.3 Million
- Estimated market size in 2026: USD 851.9 Million
- Projected market size by 2033: USD 1,839.1 Million
- CAGR (2026-2033): 11.6%
Prism AI by Grand View Research Free to tryAsk a question about the celiac disease treatment marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
According to recent estimates, approximately 1 in 100 Americans suffers from celiac disease, although a significant proportion of cases remain undiagnosed. This rise in diagnosed instances, attributed to increased awareness and improved diagnostic capabilities, directly translates into a greater demand for effective treatments and diagnostic methodologies. The market benefits from this increasing patient base, driving pharmaceutical innovation and expanding the need for specialized dietary management.As public knowledge about celiac disease symptoms and the crucial role of early diagnosis continues to grow, individuals are increasingly proactively seeking medical consultations and testing, thereby contributing to the increased identification of cases. Notably, a 2023 survey by Beyond Celiac revealed that only approximately 50% of Americans know anything about celiac disease or gluten sensitivity, indicating a growing awareness gap that needs to be bridged. However, the expanding gluten-free food industry offers a diverse range of dietary options for individuals managing the disease. The availability of these products plays a significant role in patient adherence to dietary restrictions, thereby improving health outcomes and contributing to market growth.
 To learn more about this report, Download Free Sample Report
Improvements in detection methods, such as advancements in point-of-care testing (POCT), have facilitated earlier identification and intervention, leading to quicker and more effective treatment. Government initiatives across numerous nations, including screening programs targeting high-risk demographics, further bolster market development. These proactive measures increase the number of diagnosed cases and provide patients with timely access to diagnostics and treatment options, thereby promoting a more comprehensive and proactive healthcare approach. Notably, various countries have implemented programs to raise awareness about celiac disease and enhance access to diagnostics and treatment, underscoring the commitment to addressing this growing health concern.
Ongoing research into new therapeutic modalities assures novel developments in the treatment of celiac disease in the coming years. The development of anti-inflammatory drugs and therapeutic vaccines is expected to enhance treatment options and expand market opportunities. Furthermore, increasing healthcare expenditure and robust R&D activities, particularly in novel treatment alternatives, are poised to drive market expansion. Key players are increasingly investing in drugs and gluten-free products, indicating an emphasis on improving patient health, driving market penetration, and catering to an expanding consumer base.
Market Dynamics
The celiac disease treatment market is growing steadily as awareness of autoimmune gastrointestinal disorders increases and more patients are diagnosed at an earlier stage. Although a strict gluten free diet remains the primary approach to disease management, its limitations have created a need for therapies that can help patients with persistent symptoms or accidental gluten exposure. This has encouraged pharmaceutical companies to advance treatments targeting immune pathways, intestinal permeability, and gluten degradation to address unmet clinical needs. At the same time, improvements in diagnostic practices and regular patient follow up are supporting earlier intervention and more effective long term disease management. Ongoing clinical research, increasing investment in novel therapeutic approaches, and a stronger focus on improving patient outcomes continue to support product development and expand treatment options. These factors are contributing to the steady growth of the celiac disease treatment market.
The increasing development of targeted therapies for celiac disease is a key factor supporting market growth. Although a lifelong gluten free diet remains the standard of care, many patients continue to experience persistent symptoms or intestinal damage despite following dietary recommendations. This has created a need for therapies that address the underlying disease mechanisms rather than relying solely on dietary management. Pharmaceutical companies are expanding research on treatments that target immune pathways, intestinal permeability, and gluten degradation to improve disease control and patient outcomes. Growing scientific understanding of the disease has also encouraged the development of therapies designed to reduce inflammation and prevent intestinal damage caused by gluten exposure. In addition, regulatory agencies continue to support research for diseases with limited treatment options, encouraging companies to advance innovative drug candidates through clinical development. Increasing investment in research and development, together with advancements in immunology and gastrointestinal medicine, is expanding the therapeutic pipeline. As more investigational therapies progress through clinical studies, the market is expected to benefit from broader treatment options that complement dietary management and address unmet clinical needs.
The continued reliance on a strict gluten free diet remains one of the primary restraints for the celiac disease treatment market. Despite ongoing research, there are currently very few pharmacological treatment options available that directly address the underlying disease process. Maintaining a gluten free diet can be difficult because gluten is present in many processed foods and accidental exposure remains common. This often results in persistent symptoms and reduced quality of life for some patients even when they carefully follow dietary recommendations. In addition, the complex immune mechanisms involved in celiac disease make drug development challenging, requiring extensive clinical studies to establish both safety and long term effectiveness. The absence of approved disease modifying therapies also limits treatment choices for healthcare providers and patients. Regulatory requirements for demonstrating clinical benefit, including symptom improvement and intestinal healing, further extend development timelines. These factors continue to delay the availability of new therapies and slow the expansion of treatment options, limiting the overall growth potential of the celiac disease treatment market.
The development of novel therapeutic approaches presents a significant opportunity for the celiac disease treatment market. Advances in immunology and gastrointestinal research have expanded the understanding of disease mechanisms, encouraging the development of therapies that target immune regulation, intestinal barrier function, and gluten detoxification. These approaches have the potential to complement a gluten free diet and improve disease management for patients who continue to experience symptoms despite dietary compliance. Growing interest in precision medicine is also supporting the identification of patient populations that may benefit from targeted therapies. In addition, increasing collaboration between biotechnology companies, pharmaceutical manufacturers, academic institutions, and research organizations is strengthening clinical development activities. As diagnostic practices continue to improve, earlier identification of patients is likely to increase the number of individuals eligible for emerging treatment options. Continued investment in innovative drug development and advances in clinical research are expected to expand the therapeutic pipeline and create opportunities for new products that address unmet medical needs while improving long term disease management and patient outcomes.
Analyst Perspective
The celiac disease treatment market is gradually shifting from a treatment approach centered on dietary management to one supported by targeted therapeutic development. Growing research on immune targeted therapies, gluten degrading enzymes, and intestinal barrier regulators is expanding the treatment pipeline for patients with unmet medical needs. The market is increasingly supported by companies with expertise in immunology, gastroenterology, and autoimmune diseases that are advancing novel treatment candidates through clinical development. Teva Pharmaceutical Industries has strengthened its position through the development of TEV'53408, while Takeda continues to leverage its gastrointestinal portfolio and research capabilities. Similarly, Amgen, Novartis, and BioLineRx are utilizing their experience in immunology and biologics research to support the development of innovative therapies for immune mediated diseases, contributing to the long term growth of the celiac disease treatment market.
Treatment Insights
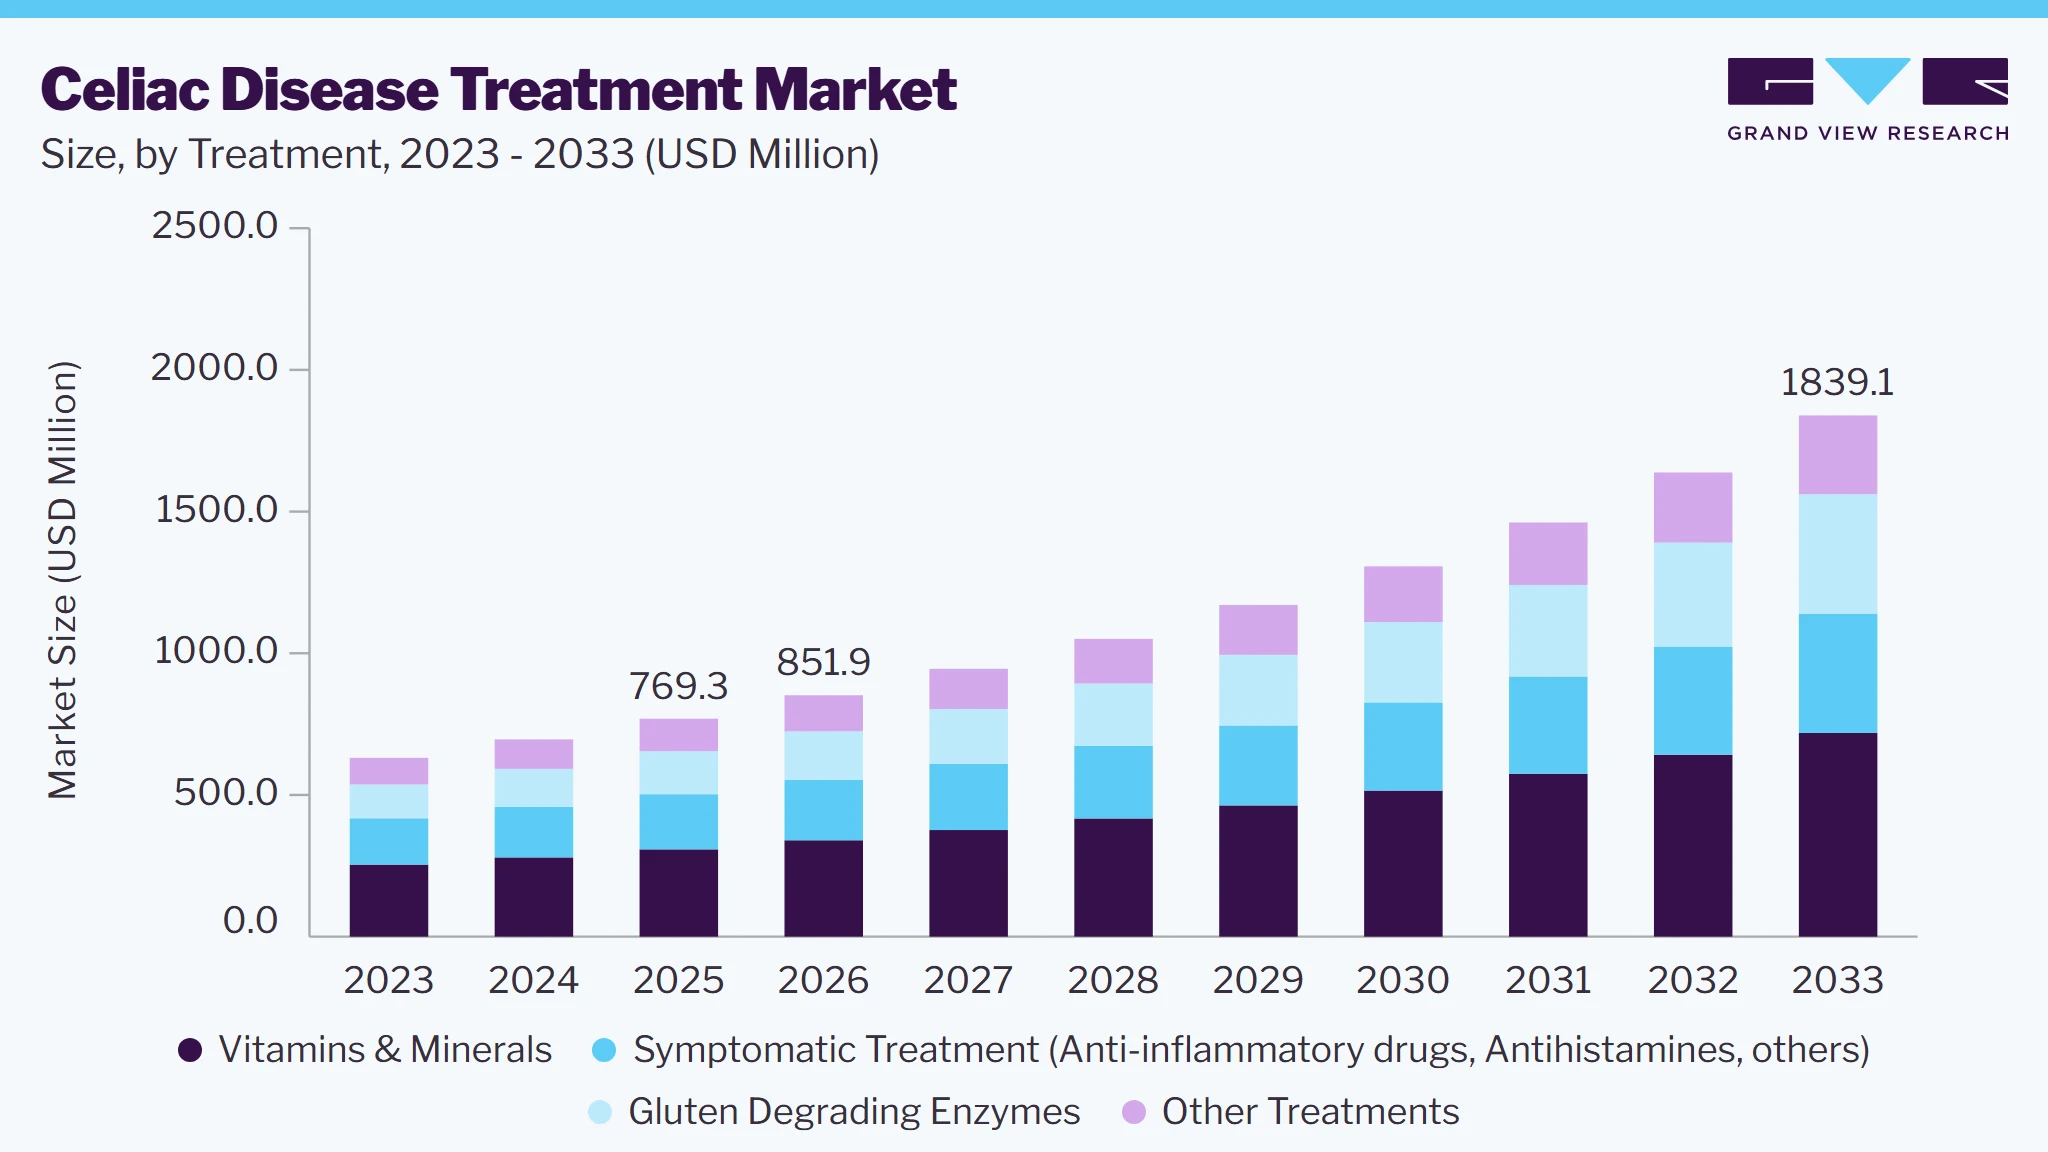
Based on treatment, the vitamins & minerals segment led the market with the largest revenue share of 40.0% in 2025, driven by individuals with celiac disease, who often experience nutrient deficiencies due to the malabsorption of essential vitamins and minerals caused by intestinal damage. Supplementation with targeted vitamins and minerals helps address these deficiencies and supports overall health. Furthermore, the increasing availability of specialized vitamin and mineral supplements formulated for celiac patients has expanded treatment options. Rising awareness of the importance of proper nutrition in celiac disease management further contributes to the segment’s growth.
Gluten degrading enzymes are projected to grow at a CAGR of 13.9% over the forecast period. Individuals with celiac disease require a strict gluten-free diet to manage their symptoms. However, there is a growing demand for gluten-free products worldwide because of the increasing prevalence of celiac disease and other food allergies. Celiac disease is an autoimmune disorder caused by gluten-containing food consumption, leading to gut inflammation and other health issues. Moreover, individuals are increasingly focused on health and wellness, leading to a shift in dietary preferences. The increased consumption of gluten-free products such as bread, cookies, and other bakery items in restaurants, cafés, and home-cooked meals has aided segment growth.
Distribution Channel Insights
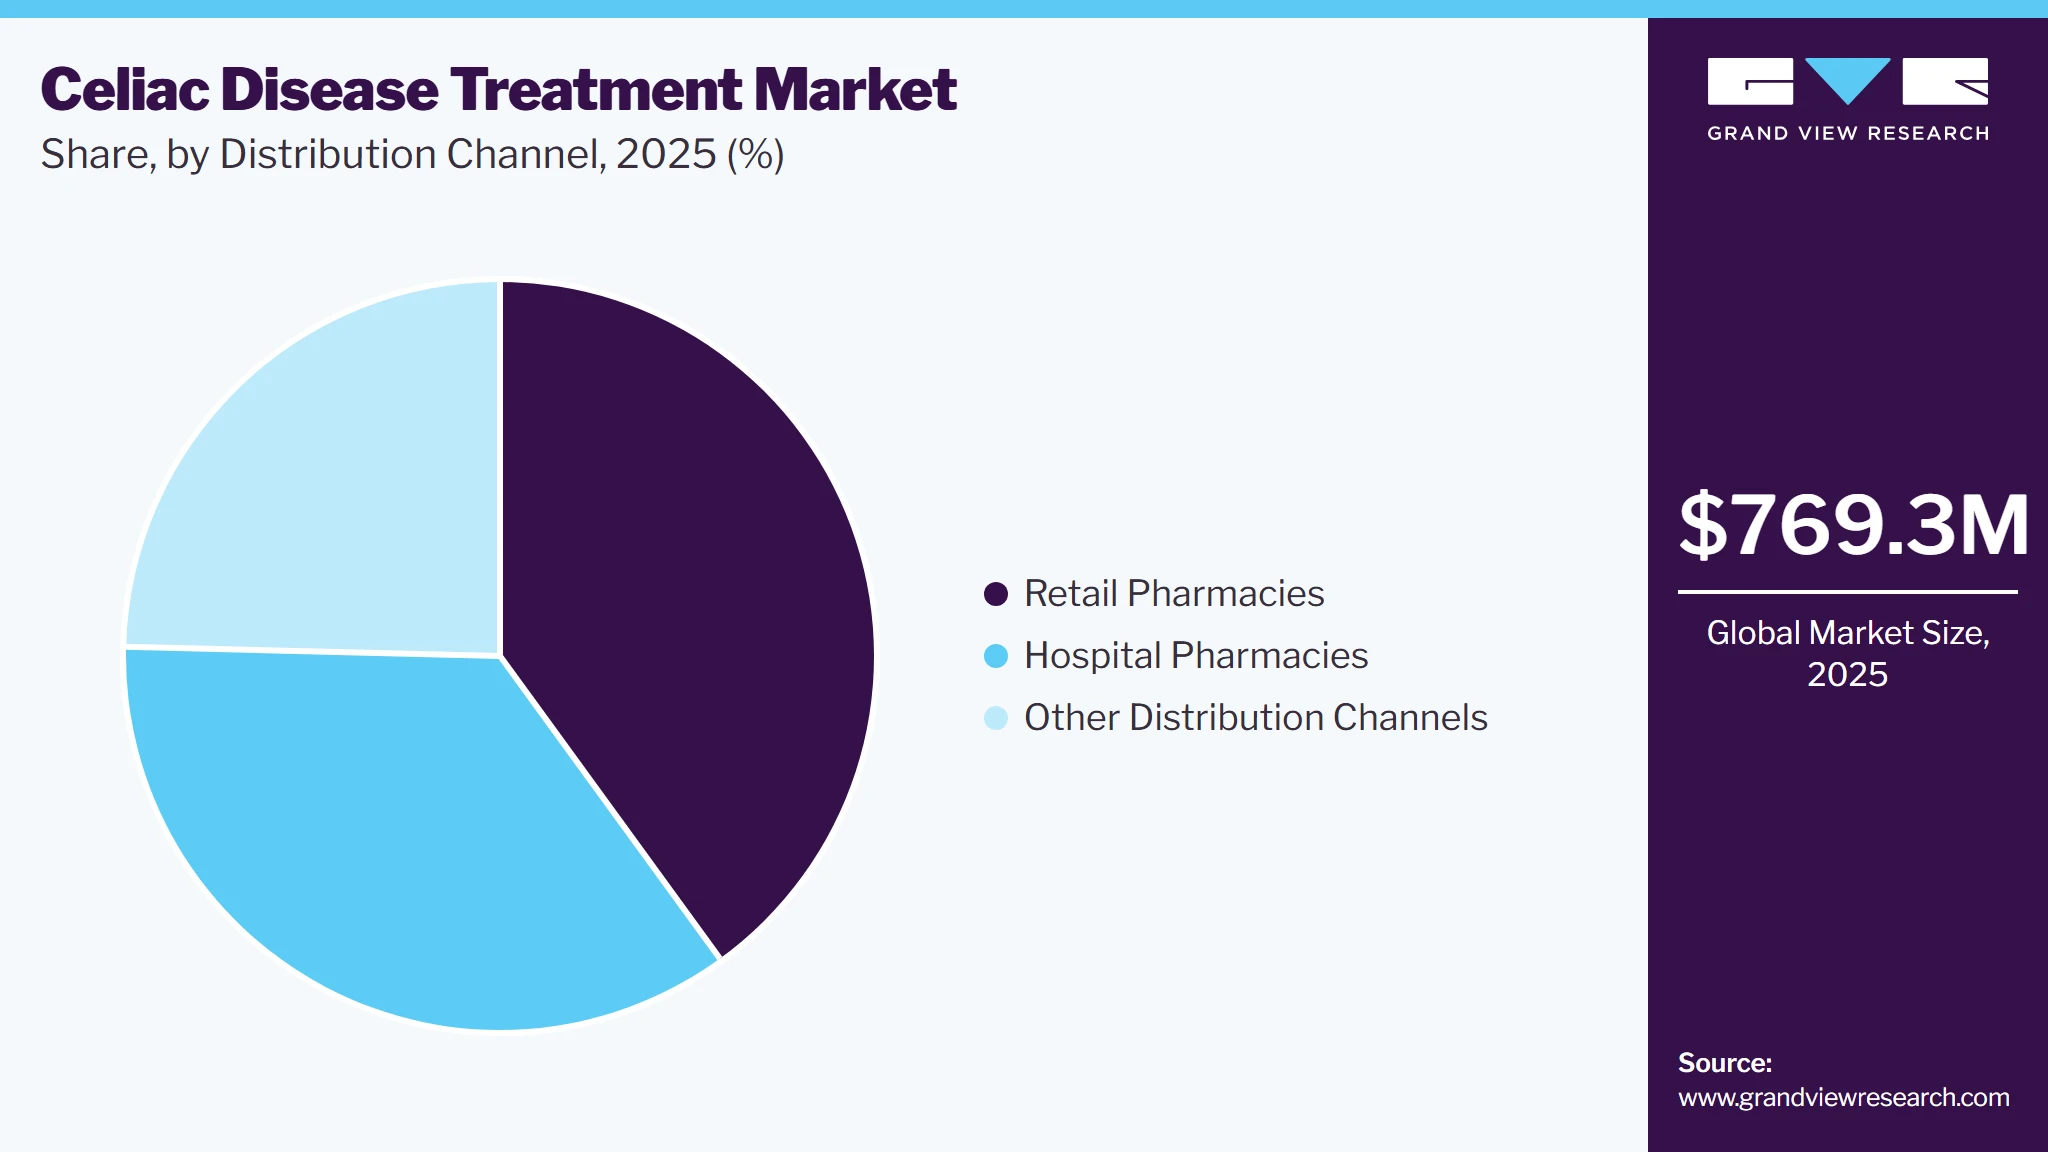
Based on distribution channel, the retail pharmacies segment led the market with the largest revenue share of 40.0% in 2025. Retail pharmacies include independent and chain establishments and are crucial in ensuring accessible access to medications, vitamins, and over-the-counter products for individuals with celiac disease. This sector is anticipated to experience substantial growth fueled by the increasing demand for gluten-free items, nutritional supplements, and essential medicines required for effective management of the condition.
 To learn more about this report, Download Free Sample Report
The healthcare sector is projected to grow at the fastest CAGR of 5.6% over the forecast period. Alternative distribution channels for celiac disease treatment encompass online pharmacies, research centers, homecare services, and specialty clinics. Online pharmacies are experiencing growth due to the convenience of home delivery of gluten-free products and medications, particularly benefiting those in remote areas. Research centers are becoming vital for distributing investigational drugs, leading to increased collaboration with pharmaceutical companies. Moreover, the expertise of clinical research organizations in managing trials supports therapy development. Homecare services are in demand for personalized patient support, while specialty clinics enhance treatment relevance through targeted management strategies.
Regional Insights
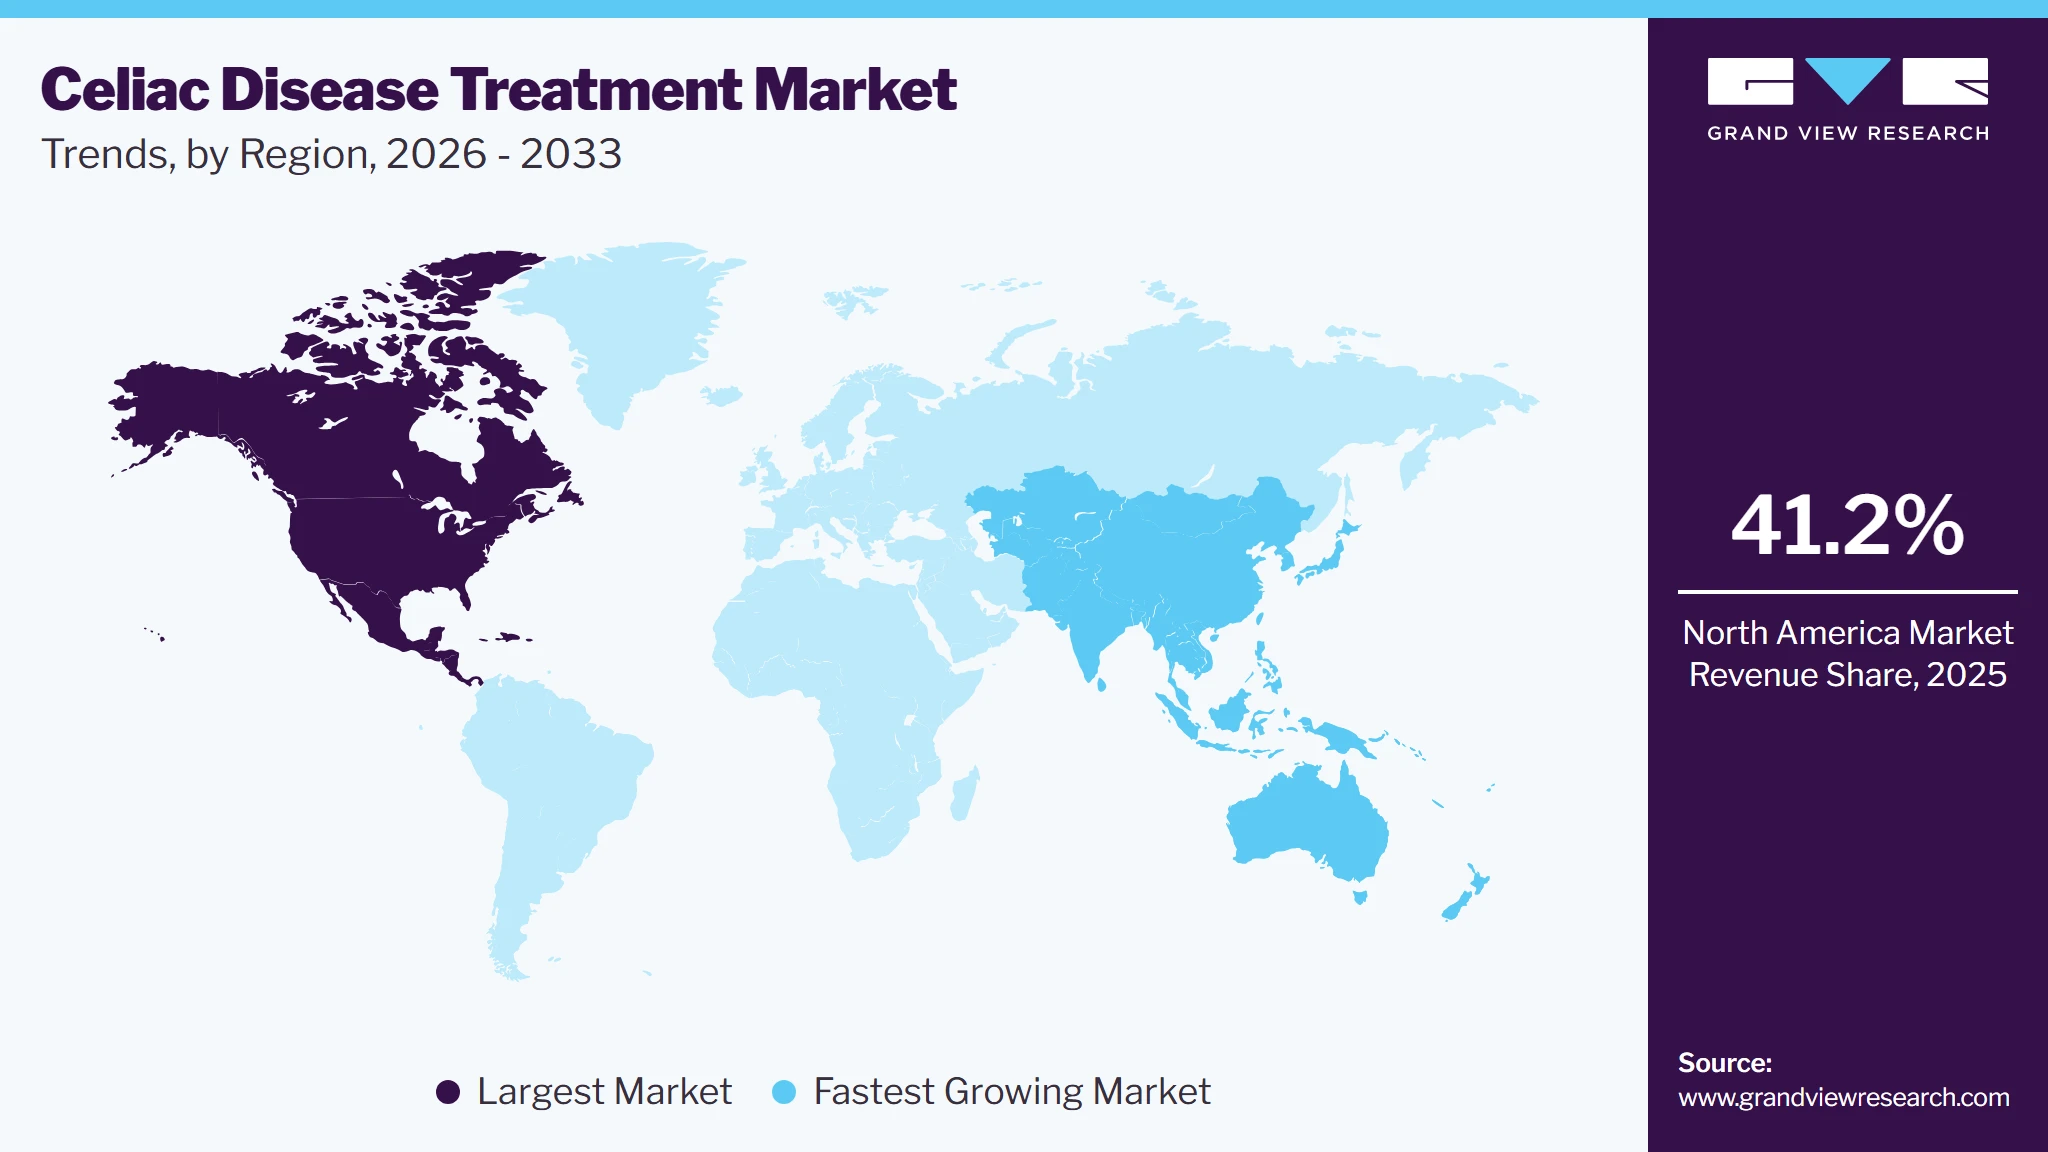
North America dominated the celiac disease treatment market with the largest revenue share of 41.2% in 2025. This growth is attributed to the rising prevalence of celiac diseases, rising awareness among citizens, the presence of major companies, and a strong supply channel of medications in the region. In addition, with the consumption of gluten-containing foods, the prevalence of the disease is growing in the region, resulting in advanced and timely diagnosis of celiac diseases with the requirement of improved treatment options.
 To learn more about this report, Download Free Sample Report
U.S. Celiac Disease Treatment Market Trends
The celiac disease treatment market in the U.S. held the largest share in the North America region in 2025, owing to the consumption of alcoholic beverages, and fast food increasing in the region, which is a major risk factor for all age groups, giving rise to celiac disease. In addition, packaged food with gluten and irregular dietary patterns are due to hectic work life, and an increasing preference for ready-to-eat food results in increasing diseases. Therefore, the high consumption of gluten-containing food and the prevalence of celiac diseases result in the need for celiac disease treatment, fueling the market during the forecast period.
Europe Celiac Disease Treatment Market Trends
Europe celiac disease treatment market held substantial market share in 2024. This growth is driven by the rising number of geriatrics, more active lifestyles in European countries, and technological developments in healthcare. Furthermore, advancements in diagnostic technologies and a growing gluten-free food industry support market expansion. Increased healthcare expenditures further facilitate the development of new treatment options and improved patient care.
The celiac disease treatment market in Germany is expected to grow rapidly over the forecast period. The rise in recognition and diagnosis of celiac disease in Germany is driving treatment demand. A 2025 study published in Therapeutic Advances in Gastroenterology analyzed data from 8,243 celiac disease patients, representing approximately 4.8% of the German population. This confirms that the prevalence of celiac disease in Germany averages 1%-2%. Increased healthcare resource utilization reveals higher costs for diagnosed patients. Advancements in therapeutic options, a growing gluten-free food market, and supportive government initiatives further enhance access to treatment and management strategies for celiac disease, promoting market growth.
Asia Pacific Celiac Disease Treatment Market Trends
Asia Pacific celiac disease treatment market is expected to register the fastest CAGR over the forecast period. The increasing awareness of celiac disease and the increasing elderly population in countries such as India, China, Japan, and South Korea. Furthermore, the expanding gluten-free food industry also contributes significantly, alongside growing healthcare expenditures that support better treatment options and patient care.
The celiac disease treatment market in China dominated the Asia Pacific market in 2024, fueled by the increased awareness of celiac disease and its timely treatment, rising healthcare expenditures, suitable and strong economic conditions, and technical enhancements that drive the market. The major factor that propels the growth of the celiac disease treatment market in the country is the awareness of celiac disease among the citizens and the increasing elderly population. As more people become aware of celiac disease, they are likely to prefer early diagnostics and treatment, which is leading to increased demand for celiac disease treatment.
Key Celiac Disease Treatment Company Insights
Some key companies in the celiac disease treatment market include Teva Pharmaceutical Industries Ltd.; Amgen Inc.; Amneal Pharmaceuticals LLC.; and GLENMARK PHARMACEUTICALS LTD. Key market players are focusing on continuous development and innovation to gain a competitive edge in the industry.
-
Amneal Pharmaceuticals LLC manufactures and distributes generic pharmaceuticals and serves the healthcare sector worldwide. The company offers prescription pharmaceutical products in several forms, including hormonal, potency formulations, soft gelatin capsules, tablets, liquids, and oral solids. They specialize in delivering medical products for central nervous system disorders, parasitic infections, and other therapeutic categories.
-
Zydus Pharmaceuticals, Inc. provides pharmaceutical products and manufactures pharmaceutical ingredients and animal healthcare products. They market, package, and distribute tablets, capsules, soft gel, sterile liquids, and inhalers worldwide. The company also manufactures and markets healthcare solutions, including formulations, active pharmaceutical ingredients, vaccines, diagnostics, health and dietetic foods, cosmeceuticals, and animal healthcare.
Key Celiac Disease Treatment Companies
The following key companies have been profiled for this study on the celiac disease treatment market.
-
Teva Pharmaceutical Industries Ltd.
-
Amgen Inc.
-
Amneal Pharmaceuticals LLC.
-
GLENMARK PHARMACEUTICALS LTD.
-
Takeda Pharmaceutical Company Limited.
-
Hikma Pharmaceuticals PLC
-
Viatris Inc.
-
Zydus Pharmaceuticals, Inc.
-
Novartis Pharmaceuticals Corporation
-
BioLineRx Ltd.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Teva Pharmaceutical Industries Ltd., Takeda Pharmaceutical Company Limited, Amgen Inc., Novartis Pharmaceuticals Corporation)
- Focus on expanding immunology and gastrointestinal portfolios through targeted drug development, clinical research, and strategic collaborations.
- Invest in pipeline therapies that address immune mediated diseases while leveraging established regulatory and commercialization capabilities to support product development.
- Strong research and development capabilities supported by broad therapeutic expertise and established global operations.
- Well-developed regulatory experience, manufacturing capacity, and relationships with healthcare providers support efficient product development and market access.
- High research and development costs and long clinical timelines for autoimmune diseases increase investment risk.
- Dependence on clinical success and regulatory approvals may delay entry of new therapies into the market.
Emerging Players (BioLineRx, Amneal Pharmaceuticals LLC, GLENMARK PHARMACEUTICALS LTD., Hikma Pharmaceuticals PLC, Viatris Inc., Zydus Pharmaceuticals, Inc.)
- Focus on expanding gastrointestinal and specialty pharmaceutical portfolios through generic medicines, specialty products, and selected pipeline programs.
- Strengthen market presence by improving product accessibility, pursuing strategic partnerships, and expanding into regions with increasing demand for gastrointestinal treatments.
- Flexible business models and diversified product portfolios enable faster response to market opportunities.
- Competitive pricing, experience in generic drug development, and growing presence in specialty pharmaceuticals support expansion across different healthcare markets.
- Limited presence in innovative celiac disease specific therapies compared with larger pharmaceutical companies.
- Smaller research pipelines and lower investment in novel autoimmune treatments may restrict long term competitive positioning in the celiac disease treatment market.
Recent Developments
-
In February 2025, AliveDx submitted a 510(k) application to the U.S. FDA for the MosaiQ AiPlex Celiac Disease microarray, aimed at enhancing diagnostic accuracy and efficiency in celiac disease detection.
-
In July 2024, Tampere University, Finlandreported promising progress with ZED1227, a drug designed to manage celiac disease. The clinical trial demonstrated ZED1227’s ability to block harmful immune reactions to gluten, offering hope for enhanced treatment options alongside a gluten-free diet. Continued research was deemed essential for clinical application.
-
In February 2024, Novartis received the FDA approval of Xolair (omalizumab) as the first and only medication for reducing allergic reactions in individuals aged one and older with IgE-mediated food allergies. This approval followed the successful Phase III OUtMATCH study, demonstrating that Xolair significantly helps patients tolerate small amounts of allergens including peanuts and milk.
Celiac Disease Treatment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 769.3 million
Estimated market size in 2026
USD 851.9 million
Projected market size by 2033
USD 1,839.1 million
Growth rate
CAGR of 11.6% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Treatment, distribution channel, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; UK; Germany; France; Italy; Spain; Denmark; Norway; Sweden; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait.
Key companies profiled
Teva Pharmaceutical Industries Ltd.; Amgen Inc.; Amneal Pharmaceuticals LLC.; GLENMARK PHARMACEUTICALS LTD.; Takeda Pharmaceutical Company Limited; Hikma Pharmaceuticals PLC; Viatris Inc.; Zydus Pharmaceuticals, Inc.; Novartis Pharmaceuticals Corporation; BioLineRx
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Celiac Disease Treatment Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global celiac disease treatment market report based on treatment, distribution channel, and region:
 To learn more about this report, Download Free Sample Report
-
Treatment Outlook (Revenue, USD Million, 2021 - 2033)
-
Vitamins & Minerals
-
Gluten Degrading Enzymes
-
Symptomatic Treatment (Anti-inflammatory Drugs, Antihistamines, Others)
-
Other Treatments
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacies
-
Retail Pharmacies
-
Other Distribution Channels
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The celiac disease treatment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each celiac disease treatment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Vitamins & Minerals
Includes vitamin and mineral supplements prescribed to correct nutritional deficiencies caused by impaired nutrient absorption in patients with celiac disease. Common supplements include iron, calcium, vitamin D, vitamin B12, folic acid, and zinc. This segment excludes therapies intended to reduce symptoms or modify the disease process.
Gluten Degrading Enzymes
Includes enzyme based therapies designed to break down gluten proteins in the digestive tract before they trigger an immune response. These products are intended to reduce the effects of accidental gluten exposure and are distinct from nutritional supplements, symptomatic medications, and immune targeted therapies.
Symptomatic Treatment
Includes medications prescribed to manage symptoms and associated complications of celiac disease, such as intestinal inflammation, allergic manifestations, diarrhea, abdominal pain, or skin related conditions. These therapies provide symptomatic relief and do not directly prevent the immune response triggered by gluten ingestion.
Other Treatments
Includes treatment approaches that are not classified under vitamins and minerals, gluten degrading enzymes, or symptomatic treatment. This segment covers immune targeted therapies, biologics, peptide based therapies, tight junction regulators, therapeutic vaccines, and other investigational or emerging pharmacological treatments for celiac disease.
Segment – Distribution Channel
Revenue capture definition
Hospital Pharmacies
Includes treatment products dispensed through pharmacies operating within hospitals and healthcare institutions. These pharmacies primarily supply prescription therapies to inpatients and outpatients receiving treatment under the supervision of healthcare professionals.
Retail Pharmacies
Includes prescription and over the counter treatment products dispensed through community pharmacies, chain pharmacies, and independent retail pharmacies. This segment serves patients managing celiac disease in outpatient settings and through routine prescription refills.
Other Distribution Channels
Includes treatment products distributed through channels other than hospital and retail pharmacies, including specialty pharmacies, online pharmacies, mail order pharmacies, and direct to patient distribution programs, where available
Estimation Model
 To learn more about this report, Download Free Sample Report
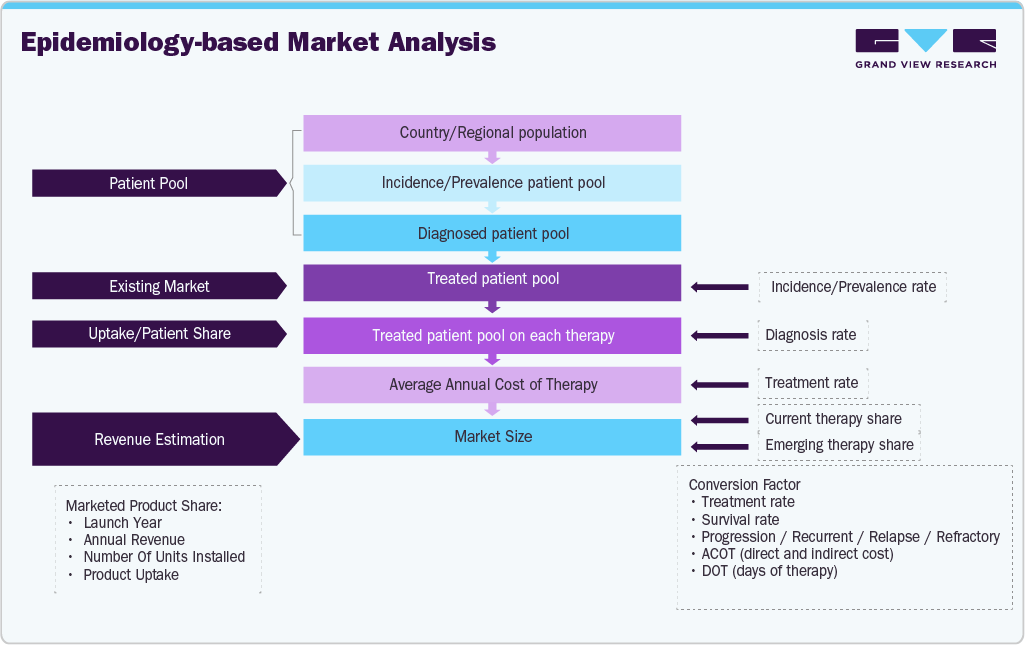
The celiac disease treatment market was estimated using an epidemiology based market analysis approach. The assessment began by identifying the total population across major countries and estimating the prevalence of celiac disease using published epidemiological studies, national health databases, and clinical literature. The diagnosed patient population was then determined based on disease awareness, screening practices, and healthcare access. The treated patient population was estimated by evaluating the proportion of diagnosed patients receiving nutritional supplements, symptomatic medications, gluten degrading enzymes, or other therapies. Treatment utilization was further categorized by therapy type and validated through prescribing patterns, clinical guidelines, physician insights, and secondary research. The average annual treatment cost for each therapy category was established using product pricing, reimbursement information, and healthcare databases. Regional market estimates were aggregated to derive the global market size and validated through discussions with industry experts and healthcare professionals to ensure consistency and accuracy.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Celiac Disease Competitive Landscape & Pipeline Assessment
Conducted a targeted data assessment of the global celiac disease treatment market evaluating and comparing the targets, pipeline, and candidates, the stage of the mechanism, clinical development progress, and competitive positioning. The study analyzed key companies including Takeda Pharma, Anokion, ImmusanT, BioLineRx, and other participants developing therapies for immune-mediated gastrointestinal disorders.
Helped the client identify pipeline opportunities, assess competitive positioning between strategic approaches, and understand ongoing developments in immune-targeted indications applicable to celiac disease.
Celiac Disease Treatment Benchmarking Study
Delivered a comprehensive technical analysis of treatment approaches used in celiac disease, including methods to implement dietary gluten degradation enzymes, symptomatic therapies, and emerging immune-targeted therapies. The assessment encompassed cellular immune targets, mechanisms of action, protective interventions, treatment positioning, and future development opportunities across leading and emerging participants.
Enabled the client to evaluate treatment option evolution, identify areas with limited competition, compare emerging therapeutic approaches, and support strategic planning in gluten-protective enzyme-based therapeutic areas.
Celiac Disease Market Access & Commercial Feasibility Assessment
Conducted a strategic assessment of the celiac disease treatment ecosystem by evaluating global policies, treatment strategies, prescribing practices, distribution channels, reimbursement models, and pricing history across major markets and geographies. The study also assessed facilitation frameworks, patient advocacy, and barriers affecting the adoption of emerging therapies.
Supported commercial planning by identifying market access opportunities, evaluating the market landscape, pricing, and regulatory frameworks for novel therapies, and providing insights into favorable conditions for introducing new celiac disease treatments.
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
The global celiac disease treatment market is expected to grow at a compound annual growth rate of 11.6% from 2026 to 2033 to reach USD 1,839.1 million by 2030.
Based on distribution channel, the retail pharmacies segment led the market with the largest revenue share of 40.0% in 2025 while healthcare sector segment is expected to be the fastest-growing market.
North America dominated the celiac disease treatment market with the largest revenue share of 41.2% in 2025.
Based on treatment, the vitamins & minerals segment led the market with the largest revenue share of 40.0% in 2025.
The global celiac disease treatment market size was estimated at USD 769.3 million in 2025 and is projected to grow to USD 851.9 million in 2026.
Some key players operating in the celiac disease treatment market include Teva Pharmaceutical Industries Ltd.; Amgen Inc.; Amneal Pharmaceuticals LLC.; Glenmark Life Sciences Limited; Takeda Pharmaceutical Company Limited.; Hikma Pharmaceuticals PLC; Viatris Inc.; Zydus Pharmaceuticals, Inc.; Novartis AG; BioLineRx Ltd.
Key factors driving the celiac disease treatment market growth include increasing prevalence of diagnosed cases, which has heightened the demand for effective treatments and diagnostic methods
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


