
- Home
- »
- Renewable Chemicals
- »
-
Cellulose Esters & Ether Market Size & Share Report, 2033GVR Report cover

Cellulose Esters And Ether Market (2026 - 2033)
Size, Share & Trends Analysis Report By Product (Cellulose Acetate, Cellulose Nitrate, Ethyl Cellulose), By Process (Kraft, Sulfite), By Region (North America, Europe, APAC, CSA, MEA), And Segment Forecasts
Market Size, 2025
$6.8BMarket Estimate, 2026
$7.2BMarket Forecast, 2033
$10.4BCAGR, 2026–2033
5.5%Cellulose Esters And Ether Market Summary
The global cellulose esters and ether market size was valued at USD 6.8 billion in 2025 and is projected to grow from USD 7.2 billion in 2026 to USD 10.4 billion by 2033, at a CAGR of 5.5% from 2026 to 2033. Asia Pacific dominated the market, accounting for the largest global share of 54.9% in 2025. The demand for the product is anticipated to be driven by growing demand from food and beverage, photographic films, cigarette filters, and the textile and apparel industry, especially in emerging countries of the Asia Pacific region.
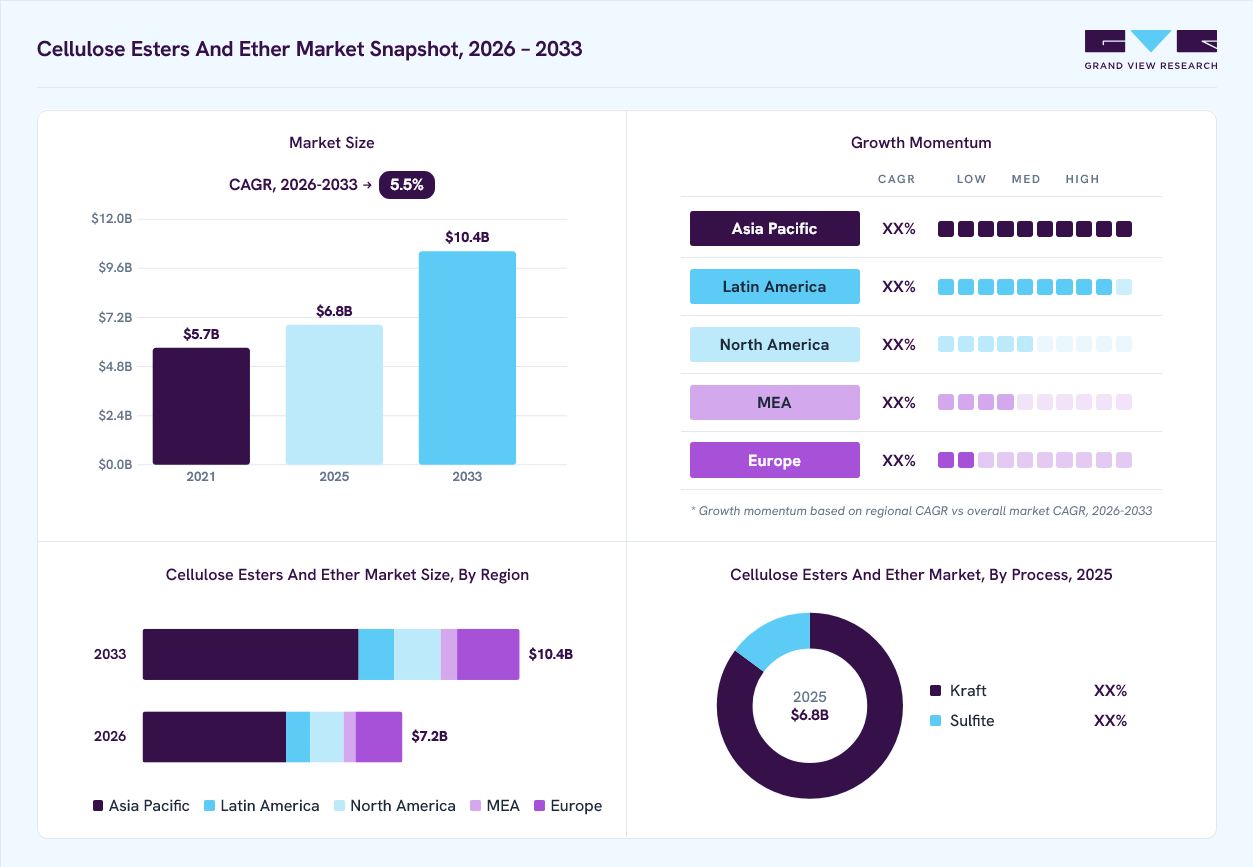 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By process, Kraft dominated the market with a revenue share of 85.0%, in 2025.
- By product, cellulose acetate dominated the market with a revenue share of 45.7%, in 2025.
Regional Highlights
- Largest regional market: Asia Pacific (54.9% revenue share, 2025)
- By country: The China held the largest share of Asia Pacific in 2025.
Market Size & Forecast
- Market size in 2025: USD 6.8 Billion
- Estimated market size in 2026: USD 7.2 Billion
- Projected market size by 2033: USD 10.4 Billion
- CAGR (2026-2033): 5.5%
Prism AI by Grand View Research Free to tryAsk a question about the cellulose esters and ether marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
Cellulose acetate phthalate is an enteric polymer broadly used for the coating of pharmaceutical drugs, whose substitute is chitosan, which is cheap as well as available in abundance. Chitosan acetate phthalate exhibits several properties similar to that of cellulose acetate phthalate and is anticipated to hamper its market growth. Carboxymethyl Cellulose (CMC) is extensively utilized by the food and beverage industry. It is employed as a thickener, emulsifier, and stabilizer, which enables food to maintain its uniform flavor, concentration, and texture. Mounting consumption of emulsifiers in frozen desserts, margarine, chocolates, peanut butter, baked products, and salad dressings has propelled the product demand. The packaged food market has witnessed considerable growth in the past few years on account of changing consumer perceptions toward their eating habits. This change is primarily driven by evolving consumer lifestyle that includes long working hours and quick access to packed foods available in a wide range of cuisines.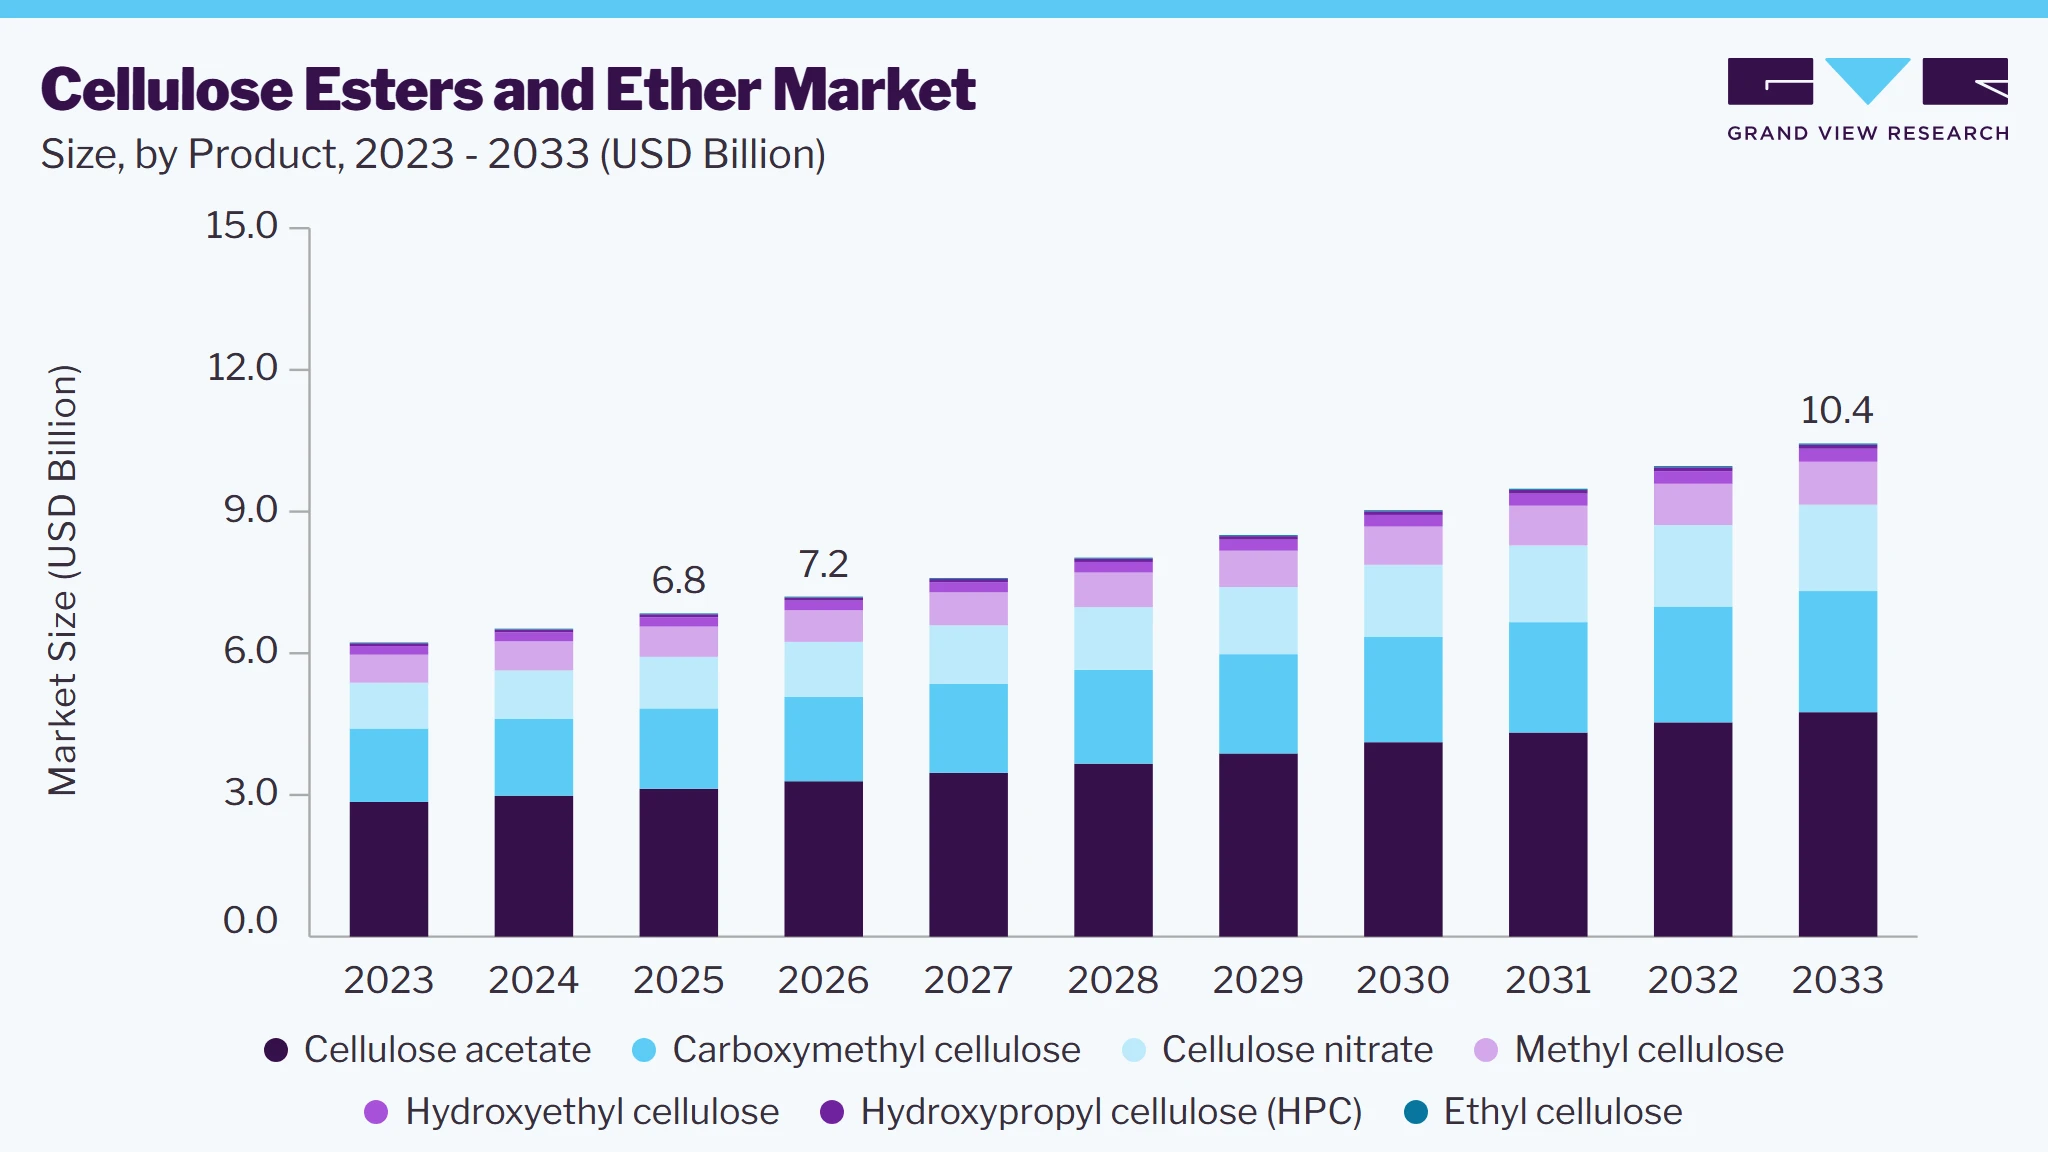 To learn more about this report, Download Free Sample Report
Cellulose is an organic polymer that is derived from wood and can be chemically modified to yield its derivatives such as ethers and esters. Raw materials used mostly include wood, caustic soda, and cotton. The costs of these raw materials are volatile in nature and are prone to increase extensively owing to various factors including changes in climatic conditions, lack of availability, and demand and supply considerations.
Generally, cellulose esters and ethers are used in various industries including paper and pulp, oil and gas, pharmaceuticals, food and beverage, construction, detergents, personal care, mining, and textiles. Finished products such as nitrocellulose, cellulose acetate, carboxymethyl, and methylcellulose are supplied to the aforementioned end-use industries through several distribution channels including distributors, wholesalers, and vendors.
Market Dynamics
The cellulose esters and ethers market is witnessing steady growth driven by increasing demand from pharmaceuticals, construction, paints & coatings, food & beverages, personal care, and specialty industrial applications. These cellulose derivatives are valued for their film-forming ability, thickening properties, water retention, binding characteristics, and biodegradability, making them suitable for a broad range of formulations. Growing emphasis on sustainable, bio-based materials and the gradual replacement of petroleum-derived additives are further supporting market expansion. Continuous product innovation and the development of high-performance cellulose derivatives tailored for specific end-use applications are expected to strengthen market demand over the forecast period.
The increasing shift toward renewable and environmentally friendly materials is a primary factor driving the cellulose esters and ethers market. Derived from natural cellulose obtained from wood pulp and cotton linters, these products offer excellent biodegradability, low toxicity, and versatile functional properties. Industries such as pharmaceuticals, food processing, personal care, and construction are increasingly adopting cellulose derivatives to meet sustainability goals while maintaining high product performance. Growing regulatory support for bio-based ingredients and consumer preference for eco-friendly products continue to accelerate market adoption.
Furthermore, expanding construction activities, increasing pharmaceutical production, and rising demand for high-performance coatings and adhesives are creating new growth opportunities for cellulose esters and ethers. In construction, cellulose ethers are extensively used in cement-based formulations, tile adhesives, and gypsum products to improve water retention and workability. Similarly, cellulose esters are widely utilized in coatings, inks, membranes, and specialty plastics owing to their excellent film-forming and durability characteristics. Continuous investments in research and development to enhance product functionality and application performance are expected to further drive long-term market growth.
The cellulose esters and ethers market faces challenges due to fluctuations in the availability and pricing of cellulose feedstocks such as wood pulp and cotton linters, which directly influence manufacturing costs. In addition, the production of high-purity cellulose derivatives requires specialized processing technologies and stringent quality control, increasing operational expenses. Competition from lower-cost synthetic additives in certain industrial applications and evolving environmental regulations governing chemical processing may further constrain market growth, particularly in price-sensitive regions.
Growing demand for sustainable packaging materials, plant-based pharmaceuticals, controlled drug delivery systems, and advanced personal care formulations presents significant opportunities for the cellulose esters and ethers market. Increasing investments in green building materials, biodegradable polymers, water-based coatings, and specialty food ingredients are expanding the application scope of cellulose derivatives. Furthermore, advancements in modified cellulose technologies, combined with increasing adoption in emerging economies and high-growth sectors such as electric vehicles, battery components, and biomedical materials, are expected to create new avenues for market expansion over the forecast period.
Analyst Perspective
The global cellulose esters and ether market is experiencing steady growth, supported by increasing demand for energy-efficient glazing solutions across the construction, automotive, solar energy, and specialty glass industries. Rising investments in green buildings, stringent building energy efficiency regulations, and growing adoption of low-emissivity (Low-E), solar control, anti-reflective, and self-cleaning coatings are driving market expansion. Continuous advancements in nanotechnology, multifunctional coating systems, and smart glass technologies are enabling manufacturers to enhance product performance while addressing evolving sustainability requirements. While fluctuations in raw material prices and the capital-intensive nature of advanced coating technologies remain key challenges, ongoing innovation and increasing demand for high-performance coated glass are expected to support long-term market growth. Asia Pacific is anticipated to remain the fastest-growing regional market, driven by rapid urbanization, infrastructure development, expanding automotive production, and increasing investments in renewable energy projects.
Product Insights
By product, cellulose acetate dominated the market with a revenue share of 45.7%, in 2025. This is attributed to its wide usage in textile as well as in cigarette production. Factors like the ever-growing textile industry, rising number of cigarette consumers, and higher preference for low-tar cigarettes have a positive impact on the demand. Acetate is a non-flammable plastic produced from natural cellulose with a wide range of applications. In the primary form, it cannot be processed as a thermoplastic and can only be processed by dissolving in a solvent.
It has several physical properties including toughness, transparency, high dielectric constant, and high flexibility. Cellulose nitrate is extremely inflammable. It is widely used in military and civilian industries for manufacturing lacquers and propellants, and explosives. It is a fluffy white solid and is majorly used in paint and wood industries when produced from cotton.
Process Insights
By process, Kraft dominated the market with a revenue share of 85.0%, in 2025. This high share is attributed to its characteristics such as reduction in cooking time and an efficient waste recovery system. Also, the growth in this process can be attributed to the increasing demand for cellulose.
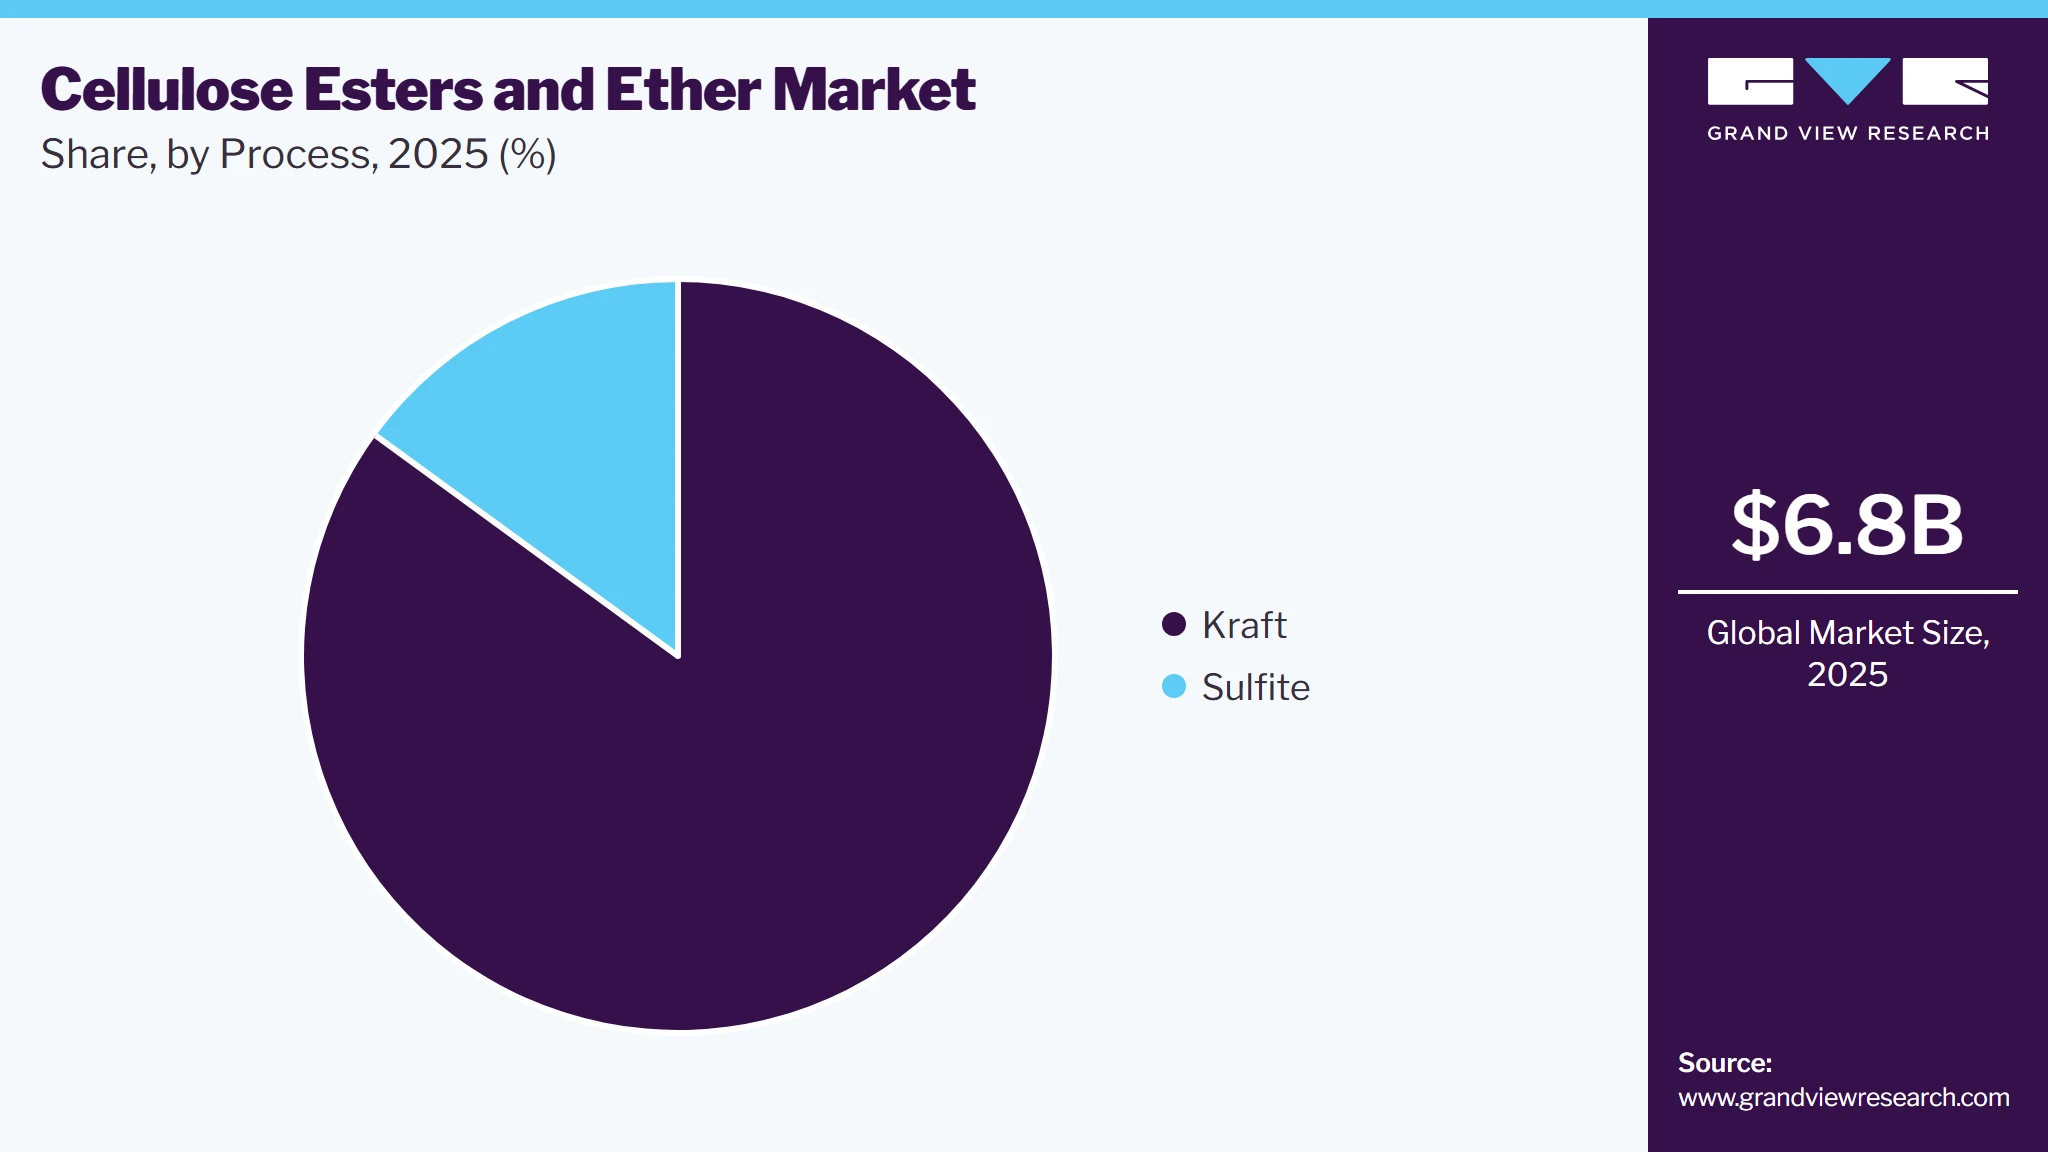 To learn more about this report, Download Free Sample Report
The Kraft process is the most used process for mining cellulose, which is further employed in paper and pulp production. The purified product is mainly manufactured from the bleached wood pulp obtained during the kraft process, which removes most of the related hemicellulose, pectin, lignin, and other composites present in the pulp. This process is a method for the conversion of wood into wood pulp containing pure cellulose fibers, the key component of paper.
The sulfite process is a chemical pulping process for transforming wood chips into paper pulp. The main purpose of pulping is to reduce wood to cellulose fiber. The sulfite process is not as widely utilized as the kraft process. The sulfite process leads to the production of unadulterated cellulose fibers by using several salts of sulfurous acid to extract the lignin in huge pressure vessels. The combination of calcium bisulfite and sulfurous acid dissolves the lignin in wood, thereby releasing cellulose fibers.
Regional Insights
Asia Pacific dominated the cellulose esters and ether market with the highest revenue share of 54.9% in 2025. This is attributed to favorable government rules and regulations for promoting investment in the region’s manufacturing and production industry. These regulations will help in increasing the product demand for adhesives, paints, and coating applications.
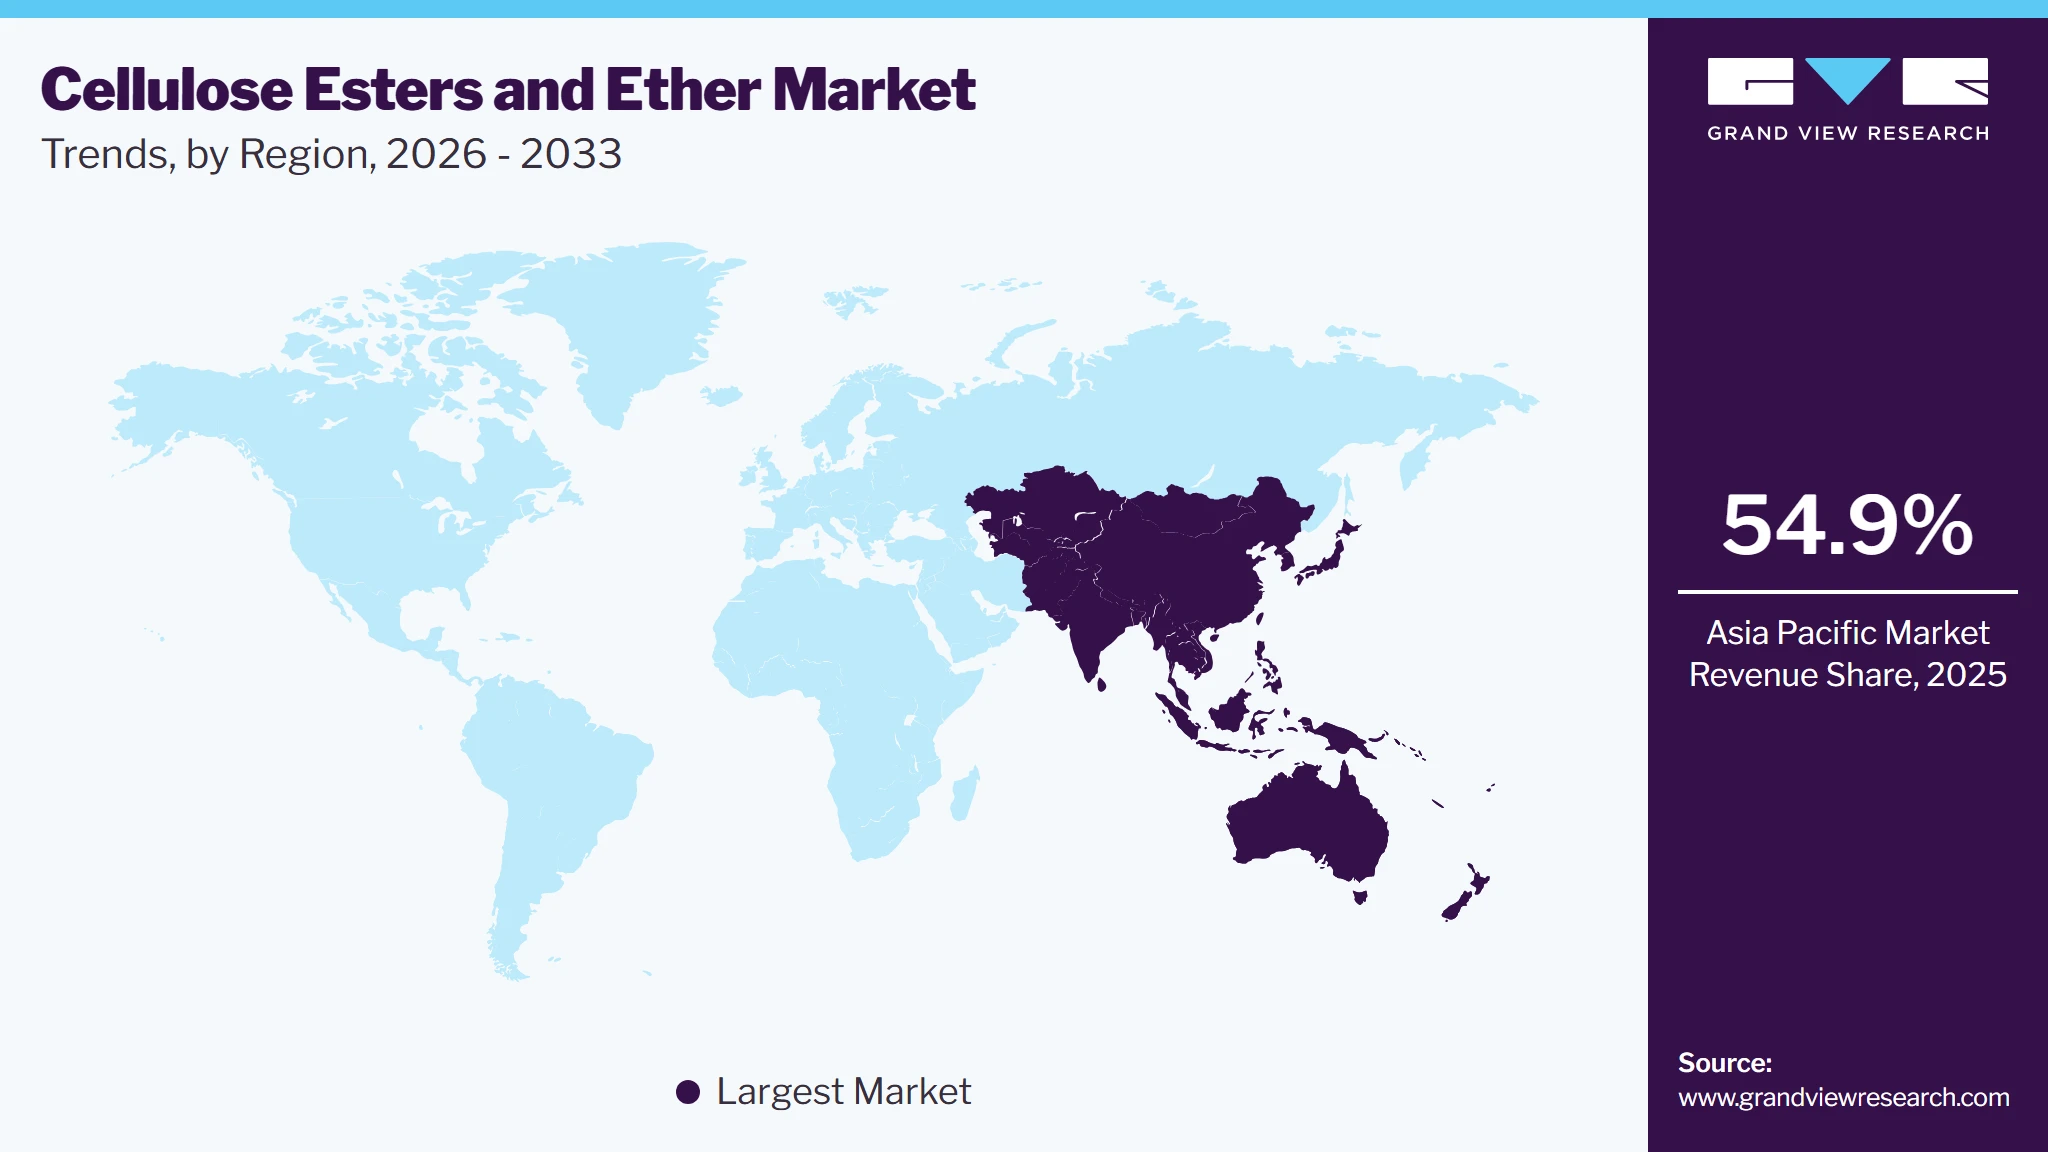 To learn more about this report, Download Free Sample Report
China Cellulose Esters And Ether Market Trends
China dominated the Asia Pacific cellulose esters and ether market in 2025.
Europe Cellulose Esters And Ether Market Trends
Cosmetics, food and beverage, oil and gas, and pharmaceutical industries are the major market drivers of the product market in Europe. The increasing use of cosmetics and personal care products in major countries such as Germany, Italy, the U.K., and France is expected to have a positive impact on the growth of the market for cellulose esters and ethers. Also, the increasing use of synthetic and natural personal care products is also anticipated to boost the growth in the region.
North America Cellulose Esters And Ether Market Trends
In North America, the market for cellulose esters and ethers is projected to witness high consumption of coating binders such as cellulose for coated board and paper applications. Activities related to the recycling and recovery of paper in the U.S. are expected to boost the growth of the paper industry in the near future, followed by the oil and gas industry, which is also one of the emerging industries in the region. Technological advancements in hydraulic fracturing coupled with enhanced oil recovery have propelled the production of tight oil and shale gas in the region.
Key Cellulose Esters And Ether Company Insights
The competition in the market for cellulose esters and ethers is high. Manufacturing companies require significant capital investment owing to the presence of stringent regulations regarding the testing and labeling of a product, which discourages new players from entering the market for cellulose esters and ethers. Companies are heavily investing in R&D activities to meet regulatory guidelines, norms, and specifications. The product manufacturers include Georgia-Pacific, The Dow Chemical Company, Akzo Nobel, Eastman Chemical Corporation, Celanese Corporation, Lamberti S.p.A., Rayonier Advanced Materials, and Ashland Inc.
The manufacturers apply competitive pricing strategies to get a competitive advantage over others. In August 2018, Celanese announced an increase in the price of acetate flake, which is employed in various end-use applications such as textile filament, plastics, films, non-wovens, coatings, and medical. The price rise affected all long-term contracts of the supply of these products by Celanese Corporation. In January 2017, Ashland increased the prices of hydroxyethyl cellulose across the globe. This pricing strategy helped the company focus on minimizing the cost of raw materials, labor, and packaging. Some of the prominent players in the cellulose esters and ethers market include:
Key Cellulose Esters And Ether Companies
The following key companies have been profiled for this study on the cellulose and esters ether market.
-
Lamberti S.p.A.
-
J.M. Huber Corporation
-
The Dow Chemical Company
-
Daicel Corporation
-
Ashland
-
AkzoNobel N.V.
-
Rhodia Acetow International GmbH
-
Eastman Chemical Company
-
Celanese Corporation
-
Rayonier Advanced Materials
-
Georgia-Pacific
-
Borregaard
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (Eastman Chemical Company; Celanese Corporation; Daicel Corporation; Ashland Inc.; Dow Inc.; Shin-Etsu Chemical Co., Ltd.; LOTTE Fine Chemical; Nouryon; SE Tylose GmbH & Co. KG; DKS Co., Ltd.)
- Invest in expanding production capacities for high-value cellulose esters and ethers serving pharmaceutical, construction, food, and personal care industries.
- Focus on continuous R&D to develop high-performance, bio-based, and application-specific cellulose derivatives.
- Strengthen long-term supply agreements with pharmaceutical companies, construction chemical manufacturers, and food ingredient producers.
- Expand global manufacturing and distribution capabilities through strategic acquisitions, partnerships, and regional capacity additions.
- Extensive global manufacturing footprint and integrated supply chains ensure reliable product availability.
- Strong financial capabilities support continuous innovation, process optimization, and capacity expansion.
- Broad product portfolios address diverse applications including pharmaceuticals, food, coatings, construction, oil & gas, and personal care.
- Established customer relationships and regulatory expertise facilitate entry into highly regulated industries.
- High dependence on wood pulp, cotton linters, and specialty chemical feedstocks exposes manufacturers to raw material price volatility.
- Large-scale manufacturing operations require significant capital investment and continuous modernization.
- Regulatory compliance for pharmaceutical and food-grade products increases operating complexity.
- Mature organizational structures may reduce flexibility in responding quickly to niche market requirements.
Emerging / Specialized Players (Lamberti S.p.A.; Shandong Head Group; Zhejiang Kehong Chemical Co., Ltd.; Reliance Cellulose Products Ltd.; Fenchem Biotek Ltd.; Anqiu Eagle Cellulose Co., Ltd.; Fushixin Polymer Fiber Co., Ltd.)
- Focus on niche cellulose derivative grades for pharmaceuticals, food ingredients, construction chemicals, paints & coatings, and specialty industrial applications.
- Expand regional presence through customized formulations and application-specific technical support.
- Strengthen customer relationships via contract manufacturing, private labeling, and strategic distribution partnerships.
- Invest selectively in high-growth segments such as controlled drug delivery polymers, sustainable food additives, and green construction materials.
- Greater operational flexibility enables faster product customization and quicker response to evolving customer requirements.
- Strong technical expertise in specialty cellulose derivatives for targeted applications.
- Competitive production costs and regional manufacturing presence support localized market penetration.
- Ability to develop customized formulations for niche industrial and pharmaceutical applications.
- Greater operational flexibility enables faster product customization and quicker response to evolving customer requirements.
- Strong technical expertise in specialty cellulose derivatives for targeted applications.
- Competitive production costs and regional manufacturing presence support localized market penetration.
- Ability to develop customized formulations for niche industrial and pharmaceutical applications..
Cellulose Esters And Ethers Market Report Scope
Report Attribute
Details
Market size value in 2025
USD 6.8 billion
Market size value in 2026
USD 7.2 billion
Revenue forecast in 2033
USD 10.4 billion
Growth rate
CAGR of 5.5% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion/billion, volume in kilotons, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Product, process, region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S., Canada, Mexico, Germany, UK, France, Italy, Spain, China, India, Japan, South Korea, Brazil, Argentina, Saudi Arabia, and South Africa
Key companies profiled
Borregaard; Georgia-Pacific; Rayonier Advanced Materials; Celanese Corporation; Eastman Chemical Company; Rhodia Acetow International GmbH; AkzoNobel N.V.; Ashland; Daicel Corporation; The Dow Chemical Company; J.M. Huber Corporation; Lamberti S.p.A.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Cellulose Esters And Ether Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For the purpose of this study, Grand View Research has segmented the global cellulose esters and ethers market report on the basis of product, process, and region:
-
Product Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Cellulose Acetate
-
Cellulose Nitrate
-
Carboxymethyl Cellulose
-
Methyl Cellulose
-
Ethyl Cellulose
-
Hydroxyethyl Cellulose
-
Hydroxypropyl Cellulose
-
-
Process Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Kraft
-
Sulfite
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
France
-
-
Asia Pacific
-
China
-
India
-
Japan
-
-
Central & South America
-
Brazil
-
-
Middle East & Africa
-
Saudi Arabia
-
-
Research Methodology
The cellulose esters and ether market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each cellulose esters and ether segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Process
Revenue capture definition
Cellulose Acetate
Revenue is generated through the commercialization of cellulose acetate used in cigarette filters, textiles, films, eyewear frames, membranes, packaging materials, and specialty plastics. Growing demand for sustainable cellulose-based materials and increasing adoption in filtration and consumer goods continue to support market growth
Cellulose Nitrate
Business income is derived from the supply of cellulose nitrate used in printing inks, wood coatings, nail care products, leather finishes, explosives, and specialty coatings. Demand is supported by its excellent film-forming properties, fast drying characteristics, and increasing utilization across industrial and consumer applications
Carboxymethyl Cellulose
Sales are generated through the use of carboxymethyl cellulose as a thickener, stabilizer, binder, rheology modifier, and water retention agent across food & beverages, pharmaceuticals, detergents, oil & gas drilling fluids, paper manufacturing, and personal care products. Growing demand for multifunctional additives continues to strengthen revenue generation
Methyl Cellulose
Commercial value is created through methyl cellulose utilized in construction materials, tile adhesives, cement mortars, pharmaceutical formulations, paints & coatings, food products, and personal care applications. Rising infrastructure development and increasing pharmaceutical production continue to support market demand
Ethyl Cellulose
Revenue is generated through the supply of ethyl cellulose used as a film former, coating agent, binder, and controlled-release polymer in pharmaceutical tablets, food ingredients, printing inks, paints, specialty coatings, and electronics. Increasing demand for sustained drug delivery systems and high-performance coatings supports market expansion
Hydroxyethyl Cellulose
Business income is derived from hydroxyethyl cellulose used as a thickening agent, stabilizer, rheology modifier, and water retention additive in paints & coatings, oilfield chemicals, cosmetics, detergents, adhesives, and construction materials. Growing industrial production and infrastructure investments continue to drive product demand
Hydroxypropyl Cellulose
Sales are generated through hydroxypropyl cellulose utilized in pharmaceutical formulations, food processing, cosmetics, coatings, adhesives, and specialty industrial applications. Increasing demand for controlled-release drug formulations, bio-based additives, and high-performance specialty chemicals continues to support market growth
Segment - Process
Revenue capture definition
Kraft
Revenue is generated through cellulose derivatives manufactured from wood pulp produced using the kraft pulping process. This process provides high-purity cellulose suitable for producing cellulose esters and ethers used across pharmaceuticals, construction, food processing, personal care, and specialty industrial applications. Its widespread commercial availability and efficient production economics support market demand
Sulfite
Business income is derived from cellulose feedstock produced through the sulfite pulping process, enabling the manufacture of high-purity cellulose derivatives with excellent consistency and performance characteristics. These materials are widely utilized in pharmaceutical excipients, specialty chemicals, food additives, coatings, and high-value industrial applications where product purity is critical
Estimation Model
Layer Name
Key Question
Description
Raw Material & Production Layer
What forms the supply base?
Assess the global production landscape for cellulose esters and ethers by evaluating the availability of wood pulp, cotton linters, purified cellulose, acetic acid, acetic anhydride, methyl chloride, ethylene oxide, propylene oxide, sodium hydroxide, and other specialty chemicals used in cellulose modification. The analysis examines feedstock availability, manufacturing technologies, production capacities, supplier integration, regional manufacturing hubs, and quality standards supporting the global supply of cellulose esters and ethers
Application Adoption Layer
Where is cellulose esters and ether utilized?
Evaluate adoption across pharmaceuticals, construction materials, paints & coatings, food & beverages, personal care products, oil & gas, paper & pulp, adhesives, textiles, printing inks, detergents, and other specialty industrial applications. Market adoption is driven by increasing demand for sustainable bio-based materials, expanding pharmaceutical manufacturing, infrastructure development, and growing use of multifunctional additives across industrial formulations
Consumption Intensity Layer
How much cellulose esters and ether is utilized?
Quantify product consumption by analyzing formulation inclusion rates, pharmaceutical production, construction material demand, food processing volumes, paint and coating production, personal care manufacturing, industrial processing throughput, and application-specific dosage levels. The assessment estimates annual consumption intensity across major end-use industries and regional markets
Revenue Layer
How is market revenue generated?
Market revenue is generated through the production, formulation, distribution, and commercialization of cellulose esters and ethers supplied to pharmaceutical manufacturers, construction chemical producers, food ingredient companies, personal care manufacturers, paint and coating formulators, oilfield service providers, and specialty chemical companies. Commercial performance is influenced by cellulose feedstock availability, raw material pricing, manufacturing efficiency, regulatory compliance, product functionality, technological innovation, long-term supply agreements, and expanding demand for sustainable, high-performance bio-based materials across multiple industries
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Cross-segmentation
The assessment evaluates market performance across resin type, coating technology, application, end-use industry, and regional markets. It further analyzes demand for polyurethane, acrylic, epoxy, and specialty resin coatings across architectural glazing, automotive & transportation, solar panels, mirrors, and other specialty glass applications while assessing technology adoption for solvent-borne, water-borne, and nano coatings
Supports detailed market evaluation by identifying high-growth product segments, understanding application-specific demand, benchmarking regional consumption patterns, and developing targeted product development and market expansion strategies
Pricing Assessment
The study provides comprehensive pricing analysis by evaluating wood pulp and cotton linter costs, cellulose feedstock pricing, specialty chemical inputs, manufacturing economics, regional price variations, processing costs, regulatory compliance expenses, and historical pricing trends across major cellulose ester and ether categories
Supports procurement and sourcing decisions by identifying key cost drivers, optimizing supplier negotiations, evaluating regional pricing differences, improving pricing forecasts, and strengthening procurement strategies
Regional Segmentation
The study provides comprehensive country-level analysis across major cellulose esters and ethers markets, covering manufacturing capacity, cellulose feedstock availability, production technologies, regulatory frameworks, import-export dynamics, pricing trends, and demand across pharmaceuticals, food & beverages, construction, paints & coatings, personal care, oil & gas, and specialty industrial applications
Enables stakeholders to identify high-growth regional markets, benchmark demand across major end-use industries, understand regional regulatory landscapes, evaluate manufacturing ecosystems, and formulate market expansion and investment strategies aligned with country-specific opportunities
Frequently Asked Questions About This Report
Some prominent players in the global cellulose esters and ethers market include Borregaard, Georgia-Pacific, Rayonier Advanced Materials, Celanese Corporation, Eastman Chemical Company, Rhodia Acetow International GmbH, AkzoNobel N.V., Ashland, Daicel Corporation, The Dow Chemical Company, J.M. Huber Corporation, Lamberti S.p.A.
The cellulose esters and ethers market is driven by growing demand from food & beverage, photographic films, cigarette filters, and the textile & apparel industry, especially in emerging countries of the Asia Pacific region.
Cellulose esters dominated the cellulose ester and ethers market with a revenue share of 45.7%, in 2025.
The global cellulose esters and ether market size was estimated at USD 6.8 billion in 2025 and is expected to reach USD 7.2 billion in 2026
The global cellulose esters and ether market is expected to grow at a compound annual growth rate (CAGR) of 5.5% from 2026 to 2033 and reach USD 10.4 billion by 2033
The Asia Pacific dominated the market with the highest revenue share of more than 54.9% in 2025. This is attributed to favorable government rules and regulations for promoting investment in the region’s manufacturing and production industry. These regulations will help in increasing the product demand for adhesives, paints, and coating applications.
Asia Pacific is expected to grow the fastest with a compound annua growth rate of 6.0% during the forecast period.
Kraft dominated the cellulose ester and ethers market with a revenue share of 85.0%, in 2025.
Cellulose nitrate segment is expected to grow the fastest with a compound annual growth rate of 6.7% during the forecast period.
About the Author(s)
Renewable Chemicals Research Team
Specialty & Chemicals · Renewable ChemicalsThis report was authored by the renewable chemicals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the renewable chemicals segment of the specialty & chemicals industry. All findings are based on proprietary specialty & chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


