
- Home
- »
- Clinical Diagnostics
- »
-
Cervical Cancer Screening, Diagnostics, And Pre-cancerous Dysplasia Lesion Treatment Market Report 2035GVR Report cover

Cervical Cancer Screening, Diagnostics, And Pre-cancerous Dysplasia Lesion Treatment Market (2026 - 2035)
Size, Share & Trends Analysis Report By Type, By Region, And Segment Forecasts
Market Size, 2025
$8.8BMarket Estimate, 2026
$9.3BMarket Forecast, 2035
$15.7BCAGR, 2026–2035
4.5%Cervical Cancer Screening, Diagnostics, And Pre-cancerous Dysplasia Lesion Treatment Market Summary
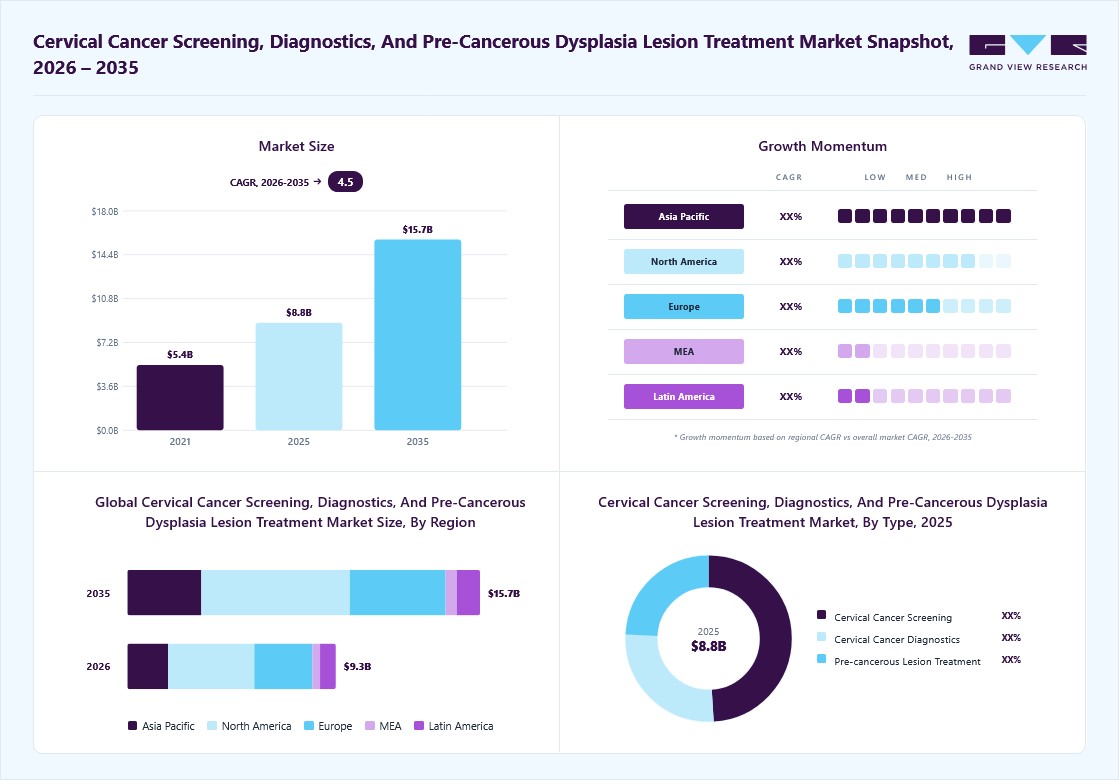
The global cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market size was valued at USD 8.8 billion in 2025 and is projected to grow from USD 9.3 billion in 2026 to USD 15.7 billion by 2035, at a CAGR of 4.5% from 2026 to 2035. North America dominated the market, accounting for a revenue share of 41.2% in 2025. Efforts to enhance early detection and streamline diagnostic workflows are playing a pivotal role in reducing the global burden of cervical cancer.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
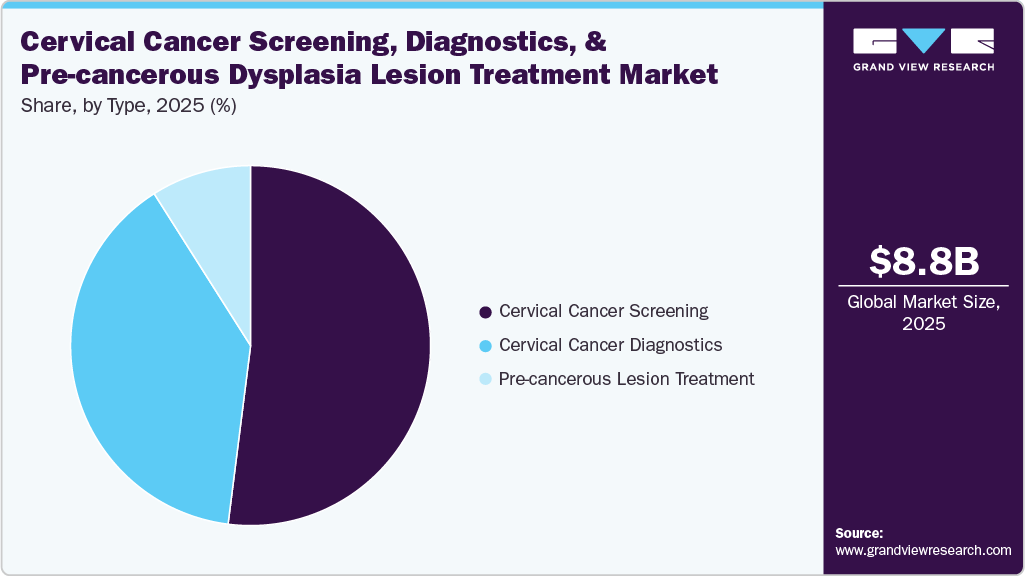
- By type: Cervical cancer screening segment dominated the market, with a revenue share of 49.0% in 2025.
Regional Highlights
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
- Largest regional market: North America (41.2% revenue share, 2025)
Market Size & Forecast
- Market size in 2025: USD 8.8 Billion
- Estimated market size in 2026: USD 9.3 Billion
- Projected market size by 2035: USD 15.7 Billion
- CAGR (2026-2033): 4.5%
Prism AI by Grand View Research Free to tryAsk a question about the cervical cancer Screening, Diagnostics, and pre-cancerous dysplasia lesion treatment marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →
AI is revolutionizing cervical cancer screening by improving accuracy, speed, and scalability. AI-powered algorithms, particularly those based on deep learning, are now being integrated into screening workflows to automatically detect early-stage cellular abnormalities with greater precision. By analyzing large datasets of Pap smear images, these systems can consistently flag potential pre-cancerous lesions, reducing the likelihood of missed early-stage abnormalities and improving patient outcomes.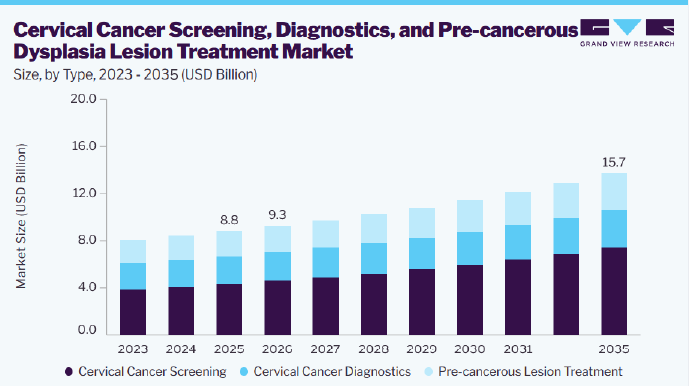 To learn more about this report, Download Free Sample Report
A notable advancement in AI-driven diagnostics is CerviCARE AI, a system introduced in a study published in Scientific Reports in January 2024. Developed to enhance colposcopy efficiency, CerviCARE AI automatically analyzes Tele-cervicography images and differentiates between low-grade and high-grade cervical lesions. In a multicenter retrospective study, the system achieved an impressive 98% sensitivity for high-risk groups (including P2, P3, HSIL, and CIN2 or higher) and a specificity of 95.5%. These findings suggest that AI-powered diagnostic tools, such as CerviCARE AI, could significantly enhance early detection efforts, streamline cervical cancer screening workflows, and reduce diagnostic errors. Although further prospective studies are needed to validate its clinical effectiveness, the integration of AI in cervical cancer diagnostics and the detection of pre-cancerous lesions marks a major advancement in the market.
 To learn more about this report, Download Free Sample Report
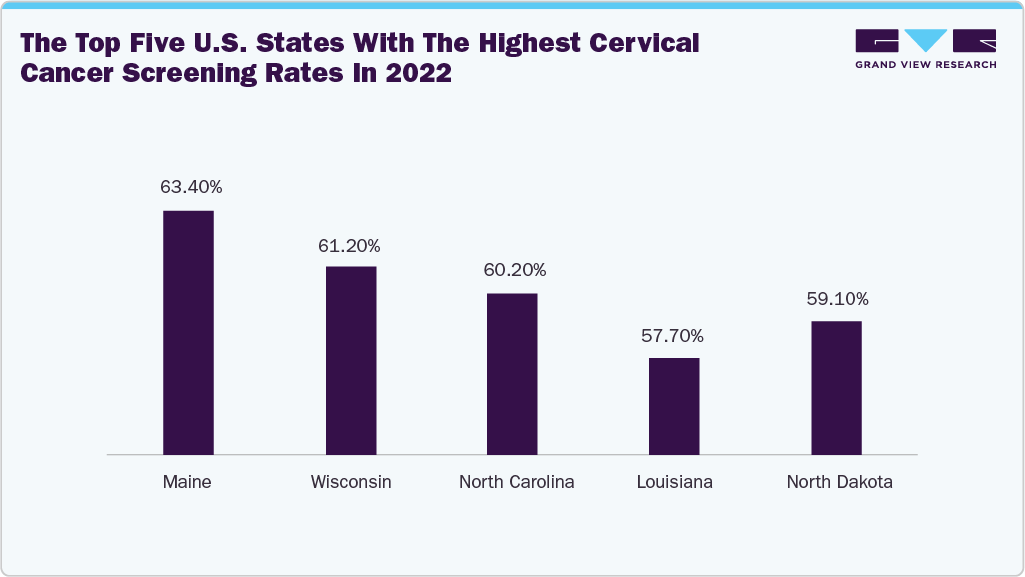
A groundbreaking shift in cervical cancer screening is the rise of self-screening programs, improving accessibility for individuals who may face barriers to traditional testing methods. In British Columbia, a province-wide cervix self-screening program was launched on January 29, 2024, becoming the first at-home self-screening option in Canada. This initiative allows individuals aged 25 to 69 to order a self-collection kit for HPV testing or opt for sample collection by a healthcare provider. Given that HPV is the primary cause of cervical cancer, this innovative screening approach aims to facilitate early detection and intervention, significantly reducing cervical cancer incidence. Premier David Eby highlighted the program’s potential in achieving the goal of eliminating cervical cancer in the province.
Similarly, in May 2024, the Alaska Native Tribal Health Consortium introduced an initiative focused on in-house HPV testing, aimed at improving early detection and timely treatment. With 95% of cervical cancers linked to untreated HPV infections, this program is designed to streamline the screening process, minimize delays, and improve patient outcomes through efficient, localized diagnostics. Both of these innovative screening initiatives underscore the market’s shift toward more accessible, efficient, and patient-centric solutions.
Technology
Description
Application
Thermal ablation
Utilizes heat beams to eradicate precancerous cervical lesions.
Significant potential for cervical cancer prevention.
Liquid-based cytology and automation
Enhances case adequacy and lab productivity, facilitates HPV testing, and is compatible with automated analysis.
Enhanced screening efficiency.
Point-of-care HPV molecular test
Plays a crucial role in allowing the clinical research team to offer post-test counseling to women who tested positive for HPV.
Self-sampling and high-resolution microendoscopy technologies.
Molecular testing advancements
Genomic techniques analyze oncogene and tumor suppressor gene profiles at the DNA level, focusing on clinically relevant biomarkers associated with HPV infections.
Integration of high-risk HPV DNA detection into prevention efforts, potential for improved risk assessment and triage.
Artificial intelligence (AI)
Enhances accuracy and efficiency in interpretation, aids non-invasive differentiation of cervical cancer, and supports triaging of HPV-positive individuals.
Real-time and reliable diagnosis, automated recognition of cervical precancer and cancer.
Biomarkers
Involves HPV DNA testing, miRNAs, proteins, HPV E6/E7 oncogene transcripts, p16INKa/ki-67, M-CSF, VEGF, DNA methylation, PD-L1 status, mismatch repair status, and tumor mutational burden status.
Potential in enhancing early detection and prognosis; further research needed for clinical applicability.
Leading companies are introducing cutting-edge products that enhance early detection, diagnostics, and treatment of pre-cancerous dysplasia lesions. In May 2024, Roche achieved a significant milestone with FDA approval for its HPV self-collection solution, one of the first self-sampling options available in the U.S. This innovative tool allows individuals to collect their own vaginal samples in a healthcare setting, which are then analyzed using Roche’s cobas molecular instrument in a specialized laboratory. By simplifying the screening process and enabling prompt HPV detection, this technology ensures faster diagnosis and early intervention, reducing the progression to pre-cancerous lesions or cervical cancer.
Market Dynamics
The global cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market is growing steadily as healthcare systems place greater emphasis on early screening, accurate diagnosis, and timely treatment of precancerous cervical changes. The continued burden of high-risk human papillomavirus (HPV) infection, which is the primary cause of cervical cancer, is creating strong demand for reliable screening, diagnostic, and lesion treatment solutions. HPV DNA testing, PCR-based assays, Pap cytology, liquid-based cytology, and HPV genotyping are increasingly being adopted because they can identify high-risk infections and abnormal cervical cells at an earlier stage, allowing women to receive appropriate follow-up care before the disease progresses. Market growth is also being supported by the expansion of government-backed cervical screening programs and the gradual shift from conventional Pap smear testing to primary HPV testing. In addition, the wider use of colposcopy, cervical biopsy, biomarker-based triage, and histopathology is improving the detection and classification of cervical dysplasia. The growing use of cryotherapy, thermal ablation, loop electrosurgical excision procedures, and cervical conization is further supporting the treatment of precancerous lesions and reducing the risk of progression to invasive cervical cancer. Growing awareness among women, increasing acceptance of self-collected samples, and the adoption of digital cytology, portable treatment technologies, and artificial intelligence-assisted screening tools are also helping healthcare providers reach under-screened populations and improve the overall screening-to-treatment pathway. Furthermore, industry participants are focused on getting product approvals from regulatory bodies which is expected to drive the growth of global cervical cancer diagnostic and cervical dysplasia market. For instance, in April 2026, Waters Corporation announced that the U.S. Food and Drug Administration (FDA) has cleared the Onclarity HPV Self-Collection Kit and approved the BD Onclarity HPV Assay with extended genotyping for at-home use, marking a significant milestone in expanding access to cervical cancer screening, and removing barriers that currently prevent many individuals from receiving routine screening.
The increasing expansion of government-supported cervical cancer screening programs is becoming one of the strongest growth drivers for the global cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market. Cervical cancer can often be prevented when high-risk human papillomavirus infection and abnormal cervical cells are detected early. However, many women, particularly those living in low-resource, rural, and underserved communities, are either screened irregularly or have never been screened. Government-funded programs help address this gap by offering structured screening invitations, subsidized or free testing, public awareness campaigns, provider training, laboratory support, and referral services for women with abnormal results.
Government-supported programs also create more predictable and recurring demand than opportunistic screening. In an organized program, eligible women are identified through population registries or primary healthcare systems and are invited at defined intervals. Testing therefore becomes a routine public health service rather than a procedure undertaken only when symptoms appear. This increases the number of tests performed, encourages laboratories to invest in automated HPV platforms, and supports long-term procurement contracts for assays, collection devices, reagents, and consumables. It also encourages diagnostic manufacturers to develop scalable solutions that can handle large national screening volumes. For instance, in January 2025, government of Belgium, announced that the it has officially transitioned from cytology-based (Pap test) screening to primary HPV-based screening for cervical cancer. This marks a major advancement in evidence-based cancer prevention and aligns Belgium with the latest European and international screening recommendations. Under the new programme, women aged 30 to 64 will be invited to undergo an HPV test every five years, replacing the previous three-yearly Pap test (cytology). HPV testing has been shown to be more sensitive in detecting precancerous changes, enabling earlier intervention and reducing the burden of cervical cancer.
Limited screening participation and loss to follow-up are major restraints on the growth of the global cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market. The cervical cancer prevention pathway depends on women completing several connected stages, beginning with routine screening and continuing through triage, confirmatory diagnosis, treatment, and post-treatment surveillance. When eligible women do not attend screening, or when those with abnormal results fail to complete the next recommended step, demand is interrupted across the entire market. Screening tests remain unused, diagnostic procedures are not performed, and precancerous lesions that could have been treated early may remain unidentified. Countries with established national screening programs continue to experience participation gaps. For example, in England, cervical screening participation was reported at 68.8% in 2025, below the national target of 80%, leaving more than five million eligible women not up to date with routine screening. This gap directly limits the volume of HPV tests, Pap tests, collection kits, laboratory reagents, and cytology services used within the program. Lower participation also reduces the number of women entering the downstream diagnostic pathway, affecting demand for HPV genotyping, biomarker-based triage, colposcopy, cervical biopsy, and histopathology.
The expansion of HPV self-sampling and decentralized screening models represents an optimistic growth opportunity for the global cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market. Traditional cervical screening generally requires a woman to visit a clinic, undergo a pelvic examination, and have a cervical sample collected by a trained healthcare professional. Although this approach remains clinically important, it can discourage participation among women who experience embarrassment, discomfort, anxiety, cultural concerns, travel difficulties, or limited access to healthcare facilities. Self-sampling offers a more convenient entry point by allowing a vaginal specimen to be collected privately using a simple swab and then tested for high-risk human papillomavirus. For instance, in May 2024, F. Hoffmann-La Roche Ltd., announced, that the company has received the U.S. Food and Drug Administration (FDA) approval of its human papillomavirus (HPV) self-collection solution, one of the first available in the United States. HPV self-collection offers an accessible screening option. In a healthcare setting, an individual collects their own vaginal sample ,which is sent to a laboratory for analysis with Roche’s cobas molecular instrument.
Market Concentration & Characteristics
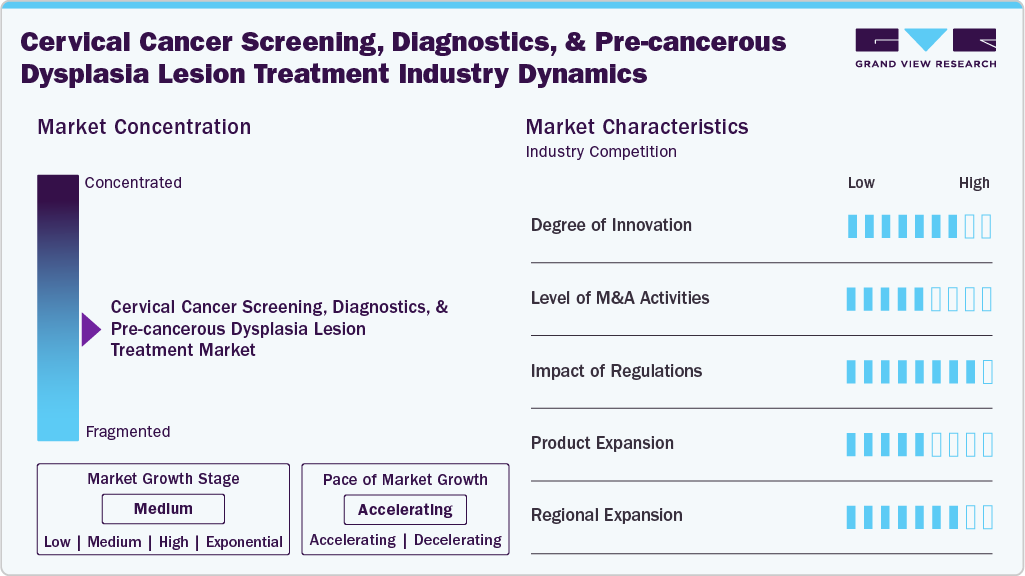
The market is experiencing rapid innovation, driven by advancements in AI-powered diagnostics, self-sampling kits, and molecular testing. Technologies like CerviCARE AI and Roche’s HPV self-collection solution enhance accuracy and accessibility. AI-driven automation, digital pathology, and deep-learning algorithms are transforming early detection, reducing errors, and streamlining clinical workflows to facilitate efficient identification of pre-cancerous lesions.
The market has witnessed an increase in mergers and acquisitions (M&A), with major diagnostic firms acquiring biotech startups to enhance their cervical cancer screening portfolios. Companies are focusing on integrating AI, liquid biopsy, and molecular diagnostics into their offerings. Strategic collaborations and acquisitions are accelerating product innovation, global market penetration, and cost-effective screening solutions in low-resource settings.
 To learn more about this report, Download Free Sample Report
Regulatory frameworks shape product approvals and market adoption. Stringent guidelines from the FDA, CE Mark, and WHO ensure screening tests meet safety and efficacy standards. Policies promoting self-screening and AI integration are driving adoption, while data privacy regulations and reimbursement policies influence market dynamics, ensuring compliance and widespread acceptance of new diagnostic technologies.
Companies are expanding product lines by integrating AI-driven colposcopy, digital cytology, and molecular HPV testing. Innovations include non-invasive self-collection kits, next-generation sequencing (NGS), and telemedicine-compatible screening solutions. With growing emphasis on early detection and precision diagnostics, firms are developing cost-effective, portable, and scalable screening solutions for global healthcare markets.
The market is expanding into emerging economies with high prevalence of cervical cancer. Governments and global health organizations are supporting affordable screening programs in Africa, Asia, and Latin America. Companies are establishing local manufacturing units, distribution partnerships, and regulatory approvals to enhance access. This expansion bridges healthcare gaps, improving screening rates and patient outcomes worldwide.
Analyst Perspective
The global cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market is moving from a collection of standalone tests and treatment devices toward an integrated cervical cancer prevention pathway. From an analyst’s perspective, the market’s long-term value will not be determined solely by the number of HPV assays, Pap collection devices, colposcopes, or lesion treatment systems sold. Growth will increasingly depend on how effectively these products are connected across screening, triage, diagnostic confirmation, treatment, and post-treatment surveillance. Products that reduce the number of clinical visits, simplify sample collection, accelerate reporting, and prevent women from being lost between an abnormal screening result and treatment are likely to gain the strongest adoption.
Type Insights
Based on type, the cervical cancer screening segment led the market with the largest revenue share of 49.0% in 2025. Cervical cancer screening is essential for early detection and prevention, utilizing a variety of devices and technologies to enhance accuracy, accessibility, and patient outcomes. Traditional Pap smear collection tools remain a cornerstone of screening, particularly in areas where advanced diagnostic infrastructure is lacking. However, HPV testing platforms have emerged as the preferred screening method due to their high sensitivity in detecting high-risk HPV strains, which are the leading cause of cervical cancer. Leading products in this category include Roche’s cobas HPV test and Abbott’s Alinity m HR HPV Assay. Cytology sample collection devices, such as cytobrushes, enhance sample quality, while colposcopes facilitate the detection of abnormal lesions during follow-up examinations.
In addition, cervical biopsy devices are critical for histopathological analysis when high-grade lesions are suspected. The rise of self-collection kits, such as Roche’s HPV Self-Collection Solution and Teal Health’s Teal Wand, has significantly increased participation in screening, particularly among underserved populations. Advanced technologies, such as High-Resolution Microendoscopy (HRME) and AI-driven screening tools, are further revolutionizing the segment by improving diagnostic accuracy and efficiency.
Several competitive developments are propelling growth in the cervical cancer screening market. In May 2024, the FDA approved Roche’s HPV Self-Collection Solution for use with the cobas HPV test, allowing private, at-home sample collection and addressing screening barriers. That same month, Teal Health’s Teal Wand received Breakthrough Device Designation from the FDA, reflecting the rising demand for accessible screening options. In November 2023, Abbott’s Alinity m HR HPV Assay was approved, providing genotyping for 14 high-risk HPV strains and strengthening HPV-based screening. The HPV Self-Sampling Initiatives launched in November 2024 under the NHS Cervical Screening Program validated the accuracy and user satisfaction of Aptima Multitest, FLOQswabs, and Evalyn Brush for self-sampling. The YouScreen Trial, conducted by King’s College London in July 2024, demonstrated that HPV self-sampling kits could potentially screen over one million additional women within three years, addressing disparities among ethnic minorities and underserved groups. In January 2024, the UK Government and NHS England integrated digital pathology into screening programs, enhancing diagnostic speed and efficiency through remote slide reviews. In February 2025, BD and Camtech Health launched Singapore’s first at-home HPV testing initiative, combining Camtech’s self-collection test with the BD Onclarity HPV Assay to improve early detection of high-risk HPV genotypes.
 To learn more about this report, Download Free Sample Report
The cervical cancer diagnostics market is witnessing substantial growth, driven by advancements in biopsy devices and colposcopes, alongside increasing adoption and demand for these technologies. In December 2024, the Federal Capital Territory Administration introduced a colposcopy machine designed to enhance early detection and treatment of cervical cancer among women. This groundbreaking initiative is expected to revolutionize healthcare delivery in the region. By incorporating advanced colposcopic technology, healthcare providers can swiftly detect cervical abnormalities and implement timely interventions. The improved diagnostic precision offered by these tools not only enhances patient outcomes but also contributes to broader efforts to lower cervical cancer mortality rates.
Biopsy tools have also undergone significant advancements in recent years. These instruments play a crucial role in obtaining precise tissue samples from suspicious areas in the cervix, enabling accurate histopathological analysis. Modern biopsy devices are designed to be minimally invasive, prioritizing patient comfort while providing clinicians with high-quality specimens for diagnosis. The synergy between advancements in colposcopy and biopsy technology is instrumental in reducing cervical cancer mortality rates by enabling early detection, accurate diagnosis, and prompt intervention. These innovations are reshaping the landscape of cervical cancer management and prevention.
Regional Insights
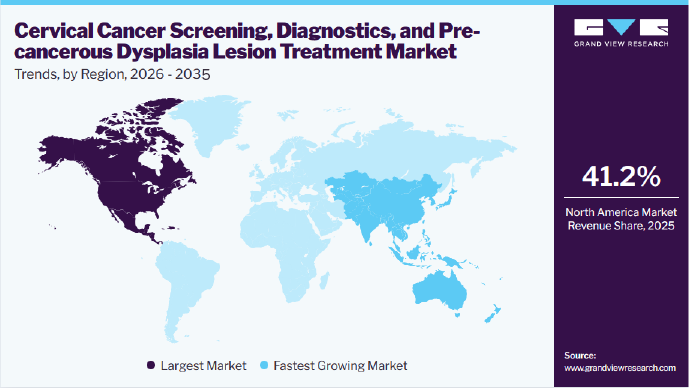
North America Cervical Cancer Screening, Diagnostics, and Pre-cancerous Dysplasia Lesion Treatment Market accounted for the largest revenue share of 41.2% in 2025. North America has made remarkable progress in reducing cervical cancer incidence and mortality over the past several decades, primarily through extensive cervical cancer screening programs. These initiatives rely heavily on Pap smears (cytology) and, increasingly, human papillomavirus (HPV) testing. However, despite high overall screening rates in many regions, disparities persist in screening participation and follow-up care, particularly among underserved populations.
 To learn more about this report, Download Free Sample Report
To address these gaps, healthcare systems across North America are adopting innovative solutions. Recent FDA approvals for HPV self-collection tests, such as the cobas HPV and BD Onclarity HPV assays, present a promising alternative for women who may avoid traditional pelvic exams due to discomfort, cultural sensitivities, or past trauma. These advancements aim to increase screening accessibility and enhance early detection efforts, ensuring that more women receive timely diagnoses and treatment.
U.S. Cervical Cancer Screening, Diagnostics, And Pre-cancerous Dysplasia Lesion Treatment Market Trends
The cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market, U.S. held the largest share in the North America region in 2025. The American Cancer Society estimated 13,360 new invasive cervical cancer cases and 4,320 deaths in the United States for 2025. Cervical cancer primarily affects women aged 35-44, with the average age at diagnosis being around 50. Notably, over 20% of cases are diagnosed in women over 65, particularly among those who were unscreened earlier in life.
In the realm of treatment innovations, several key clinical trials are shaping the future of cervical cancer management. The INTERLACE Trial (2023) evaluated induction chemotherapy followed by chemoradiotherapy (CRT) versus CRT alone in patients with locally advanced cervical cancer, demonstrating improved progression-free survival (HR: 0.65; p=0.013) and overall survival (HR: 0.61; p=0.04). Similarly, the BEATcc Trial (2023) focused on first-line treatment for recurrent or metastatic cervical cancer, comparing a regimen of paclitaxel, carboplatin, and bevacizumab with or without atezolizumab. This trial reported enhanced progression-free survival (HR: 0.62; p<0.0001) and overall survival (HR: 0.68; p=0.0046) with the inclusion of atezolizumab.
Europe Cervical Cancer Screening, Diagnostics, And Pre-cancerous Dysplasia Lesion Treatment Market Trends
The cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment industry in Europe holds the second-largest share of the global market, propelled by robust government initiatives. According to the WHO, more than 66,000 women in the WHO European Region are diagnosed with cervical cancer annually, with over 30,000 succumbing to the disease. Achieving the 90-70-90 global targets by 2030 will require coordinated, cross-country efforts to ensure equitable prevention and care. These ambitious initiatives are driving substantial demand for HPV vaccines, advanced screening technologies, diagnostic tools, and innovative treatment solutions, thereby broadening healthcare infrastructure and expanding market opportunities across the region.
The UK cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment industry is experiencing growth. Government initiatives, enhanced screening programs, and technological advancements in diagnostic tools are driving the increased adoption of these solutions. Innovations in HPV testing and therapeutic treatments further bolster market expansion, improving early detection and patient outcomes. As public health priorities align with industry developments, the market is poised for continued progress, fostering improved care, lowering cervical cancer mortality rates.
The cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment industry in France is expanding in response to the disease’s incidence. Among the 27.9 million at-risk women, there are 3,379 new cases and 1,452 deaths annually. Cervical cancer ranks 12th among female cancers and 4th for ages 15-44, with HPV-16/18 responsible for 75.6% of cases and a 4.7% HPV prevalence in women with normal cytology. Since introducing HPV vaccination in 2007-with 46% receiving the first dose and 37% full-dose by 2021-France has also implemented a national screening program in 2020, targeting women aged 25-65 through cytology (every three years for ages 25-29) and HPV tests (every five years for ages 30-65), achieving a 76% participation rate over the past five years.
Asia Pacific Cervical Cancer Screening, Diagnostics, And Pre-cancerous Dysplasia Lesion Treatment Market Trends
The cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment industry in the Asia Pacific is anticipated to grow at the fastest CAGR from 2026 to 2035. Cervical cancer remains a major public health concern across Asia, with significant variations in prevention efforts and healthcare infrastructure among sub-regions. This form of cancer disproportionately affects women in low- and middle-income countries, where access to vaccination, screening, and treatment is limited. A study published in the Asian Pacific Journal of Cancer Prevention in July 2023 emphasized the critical need for effective screening methods, especially in developing nations. The review highlighted innovative solutions such as HPV-DNA self-tests, portable colposcopes, and smartphone-based tools, which have the potential to improve accessibility and clinical efficiency. These advancements are set to play a pivotal role in enhancing early detection and treatment, thereby propelling market growth across the region.
The Japan cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment industry is witnessing significant growth driven by innovation. In February 2025, the National Cancer Center Japan launched the A-TRAIN study under the ATLAS project, which focuses on personalized treatments for advanced cancers, including cervical cancer, using liquid biopsy. This pioneering study is conducted in collaboration with industry leaders such as Guardant Health, Thermo Fisher, and Roche, highlighting the country's commitment to advancing cancer care.
The cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment industry in India is experiencing significant growth driven by robust awareness programs. In February 2025, Roche Diagnostics India signed an MoU with CAPED to combat cervical cancer through comprehensive early detection and awareness initiatives, which include conducting 100 workshops and distributing HPV DNA self-sampling kits.
The Australia cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment industry is experiencing robust growth fueled by significant investments. In November 2023, the Albanese Labor Government announced a USD 48.2 million investment over four years to implement the National Strategy for the Elimination of Cervical Cancer by 2035, along with an additional USD 12.5 million dedicated to supporting cervical cancer elimination efforts in the Indo-Pacific region. Continuing its proactive approach, in September 2024, the government launched the "Own It" campaign, a USD 10 million initiative designed to promote cervical cancer screening among women aged 25-74. This campaign emphasizes self-collection testing and specifically targets priority groups, including Aboriginal and Torres Strait Islander women.
Latin America Cervical Cancer Screening, Diagnostics, And Pre-cancerous Dysplasia Lesion Treatment Market Trends
The cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment industry in Latin America is expanding due to the high prevalence of the disease. Despite advancements in screening and prevention, cervical cancer remains a major public health challenge in the region, with high incidence and mortality rates. Human papillomavirus (HPV) infection, the leading cause of cervical cancer, is widespread and further exacerbated by limited healthcare access, socioeconomic disparities, and varying awareness levels regarding preventive measures. Argentina and Brazil, two of Latin America’s largest countries, continue to face a substantial cervical cancer burden, though their epidemiological profiles and prevention strategies vary.
The Brazil cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment industry is growing, driven by strong government support and strategic initiatives. In 2023, the Brazilian Federation of Gynecology and Obstetrics Associations (FEBRASGO) introduced targeted measures to combat cervical cancer. These include expanding HPV vaccination campaigns, enhancing screening programs for early detection, ensuring equitable access to treatment nationwide, and launching public awareness campaigns to educate communities on the importance of prevention, vaccination, and regular screenings.
Middle East & Africa Cervical Cancer Screening, Diagnostics, And Pre-cancerous Dysplasia Lesion Treatment Market Trends
The cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment industry in the Middle East & Africa region is experiencing growth due to the high prevalence of the disease. In the Middle East and North Africa region, cervical cancer remains a leading cause of female mortality. According to the ICO/IARC HPV Information Centre (2023), deaths are projected to rise from 8,964 in 2012 to 16,241 by 2030, averaging 44 fatalities per day without intervention. HPV vaccination, particularly for girls aged 9-13, offers up to 99% efficacy with minimal side effects. However, the financial burden of treating advanced cervical cancer remains a significant challenge for many families, underscoring the need for increased preventive measures and accessible healthcare solutions.
The South Africa cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment industry is growing due to the high prevalence of the disease. Among the 22.2 million women at risk, an estimated 10,702 new cases and 5,870 deaths occur annually. Cervical cancer is the second most common cancer among women and the leading cause of cancer-related deaths in those aged 15-44. HPV-16 and HPV-18 are responsible for 64.2% of cases.
South Africa introduced HPV vaccination in 2014, achieving a 34% coverage rate for the final dose by 2021. Screening for cervical cancer is recommended for women aged 25-55, with cytology performed every five years or HPV testing every ten years. Current screening coverage stands at 44% for women aged 25-65 and 52% for those aged 30-49. Additionally, the country faces a high HIV prevalence of 25.8%, which further impacts cervical cancer risk and screening efforts.
Key Cervical Cancer Screening, Diagnostics, And Pre-cancerous Dysplasia Lesion Treatment Company Insights
Some major players catering to the market are F. Hoffmann-La Roche, BD, Abbott, QIAGEN, Hologic, Inc., and CooperSurgical Inc., among others. These companies focus on capturing the market by increasing their presence using various business initiatives, such as collaborations and partnerships with the government. Their well-established product portfolios enable them to capture a significant market share.
SD Biosensor, Inc., Wantai BioPharm., and Lionex GmbH are among the emerging market participants. These companies' prevalent operating strategies include developing and launching improved and new diagnostic tools that offer higher accuracy, faster results, and easier usability.
Key Cervical Cancer Screening, Diagnostics, And Pre-cancerous Dysplasia Lesion Treatment Companies:
The following key companies have been profiled for this study on the cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market.
-
F. Hoffmann-La Roche
-
BD
-
Abbott
-
QIAGEN
-
Hologic, Inc.
-
CooperSurgical Inc.
-
MedGyn Products, Inc
-
WISAP Medical Technology GmbH
-
Liger Medical
-
Utah Medical Products, Inc.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Well-Established Players (F. Hoffmann-La Roche Ltd.; BD; Abbott; QIAGEN; Hologic, Inc.; CooperSurgical Inc.)
- Focus on broad product portfolios covering HPV testing, cytology, colposcopy, biopsy, and precancer lesion treatment. Invest heavily in regulatory approvals, clinical validation, automated platforms, partnerships with national screening programs, direct sales networks, and recurring reagent and consumable revenue models.
- Strong brand recognition, large installed base, extensive regulatory approvals, global distribution networks, high laboratory throughput, established relationships with hospitals and public health agencies, and the ability to provide integrated screening-to-diagnosis solutions.
- High product and maintenance costs, complex procurement processes, slower customization for local requirements, dependence on centralized laboratory infrastructure, and limited affordability in low-resource or rural healthcare settings.
Emerging & Regional / Specialized Players (MedGyn Products, Inc.; WISAP Medical Technology GmbH; Liger Medical; Utah Medical Products, Inc.)
- Concentrate on affordable, portable, and application-specific products such as self-collection kits, digital colposcopes, AI-assisted imaging tools, thermal ablation devices, cryotherapy systems, and localized screening solutions. Use distributor partnerships, public tenders, pilot programs, and collaborations with non-governmental organizations to enter underserved markets.
- Greater pricing flexibility, faster product innovation, localized customer support, simpler device designs, suitability for decentralized and screen-and-treat programs, and the ability to address unmet needs in low- and middle-income countries.
- Limited geographic reach, smaller product portfolios, lower brand recognition, fewer regulatory approvals, restricted clinical evidence, dependence on third-party distributors, and lower capacity to support large national screening contracts.
Recent Developments
-
In October 2025, BD introduced a new self-collection solution for HPV testing in markets outside the U.S. The solution streamlines at-home sample collection while enabling increased automation in laboratory workflows through integration with the BD COR™ System’s advanced robotics. Additionally, the swab’s stability supports reliable mail-in transport from patients’ homes to laboratories, reducing logistical challenges and promoting wider participation in cervical cancer screening programs.
-
In September 2025, PHASE Scientific International Limited announced the launch of the world’s largest clinical study evaluating urine-based cervical cancer (HPV) screening, with the first study site established in Guang’an, Sichuan Province, China. The study is led by Peking University Shenzhen Hospital, with participation from West China Guang’an Hospital of Sichuan University, and is supported by PHASE Scientific through technical and diagnostic expertise. The study utilizes PHASE Scientific’s proprietary PHASiFY urine-based DNA concentration technology to investigate a scalable and accessible cervical cancer screening approach aimed at delivering significant public health impact through scientific innovation.
-
In September 2025, Teal Health expanded its at-home cervical cancer screening program to New York and Florida. This expansion introduces the Teal Wand-the first FDA-authorized self-collection device for at-home cervical cancer screening-to more than 15 million women of screening age across three states. The expansion was driven by strong consumer demand and a growing waitlist of women seeking access to the service.
Cervical Cancer Screening, Diagnostics, And Pre-cancerous Dysplasia Lesion Treatment Market Report Scope
Report Attribute
Details
Market size in 2025
USD 8.8 billion
Market size value in 2026
USD 9.3 billion
Revenue forecast in 2035
USD 15.7 billion
Growth rate
CAGR of 4.5% from 2026 to 2033
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD million/billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, region
Regional scope
North America; Europe; Asia Pacific; Latin America; MEA
Country scope
U.S.; Canada; Mexico; Germany; UK; France; Italy; Spain; Denmark; Sweden; Norway; Japan; China; India; South Korea; Australia; Thailand; Brazil; Argentina; South Africa; Saudi Arabia; UAE; Kuwait
Key companies profiled
F. Hoffmann-La Roche Ltd., BD, Abbott, QIAGEN, Hologic, Inc., CooperSurgical Inc., MedGyn Products, Inc., WISAP Medical Technology GmbH, Liger Medical, and Utah Medical Products, Inc.
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Cervical Cancer Screening, Diagnostics, And Pre-cancerous Dysplasia Lesion Treatment Market Report Segmentation
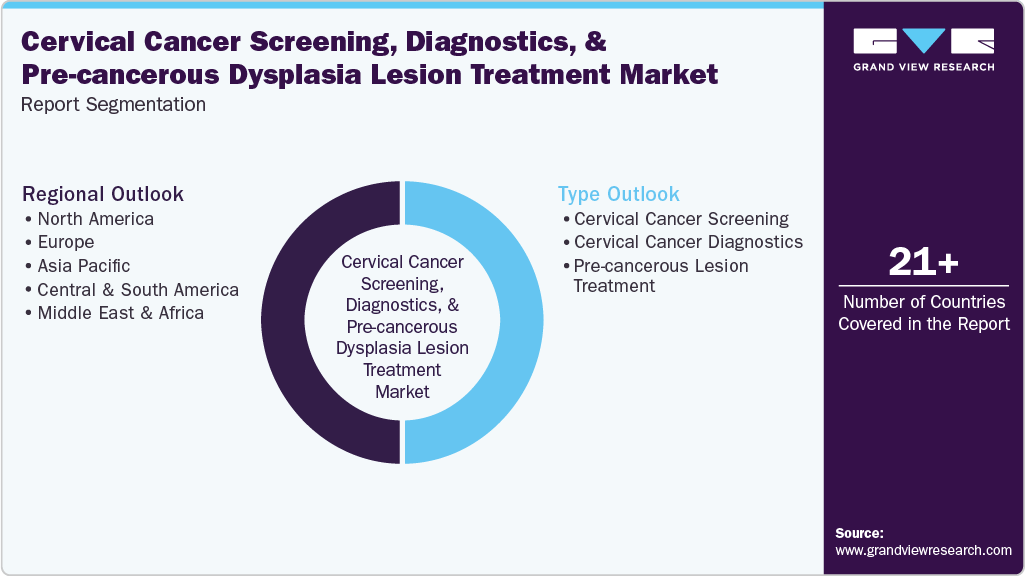
This report forecasts revenue growth and provides at the global, regional, and country levels an analysis of the latest trends in each of the sub-segments from 2021 to 2035. For this report, Grand View Research has segmented the global cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market report based on type, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Revenue, USD Million, 2021 - 2035)
-
Cervical Cancer Screening
-
Pap Smear Collection Devices
-
HPV Testing Platforms
-
Cytobrush
-
Self-collection kits
-
Others
-
-
Cervical Cancer Diagnostics
-
Colposcopes
-
Cervical Biopsy Devices
-
Colposcopes with AI Imaging (Digital)
-
Others
-
-
Pre-cancerous Lesion Treatment
-
LEEP (loop electrosurgical excision procedure) Machine
-
Cryotherapy
-
Thermal Ablation
-
Others
-
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2035)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
The cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Cervical Cancer Screening
The cervical cancer screening segment captures revenue generated from products used for the routine identification of women who may have high-risk HPV infection, abnormal cervical cells, or an elevated risk of developing cervical cancer. Products considered under this segment include Pap smear collection devices, HPV testing platforms, cytobrushes, self-collection kits, and other screening-related products such as cervical cell collection spatulas, specimen collection vials, transport media, sample preservation solutions, and screening-specific consumables.
Cervical Cancer Diagnostics
The cervical cancer diagnostics segment captures revenue generated from products used to evaluate women with positive HPV tests, abnormal cytology results, suspicious cervical findings, or symptoms requiring further clinical investigation. Products considered under this segment include conventional and digital colposcopes, cervical biopsy devices, colposcopes integrated with artificial intelligence-assisted imaging, and other diagnostic products such as biopsy forceps, endocervical curettes, cervical visualization accessories, imaging software, light sources, cameras, and procedure-specific consumables.
Pre-cancerous Lesion Treatment
The pre-cancerous lesion treatment segment captures revenue generated from products used to remove, destroy, or treat confirmed precancerous cervical lesions, including cervical intraepithelial neoplasia and other high-grade dysplastic abnormalities.
Estimation Model
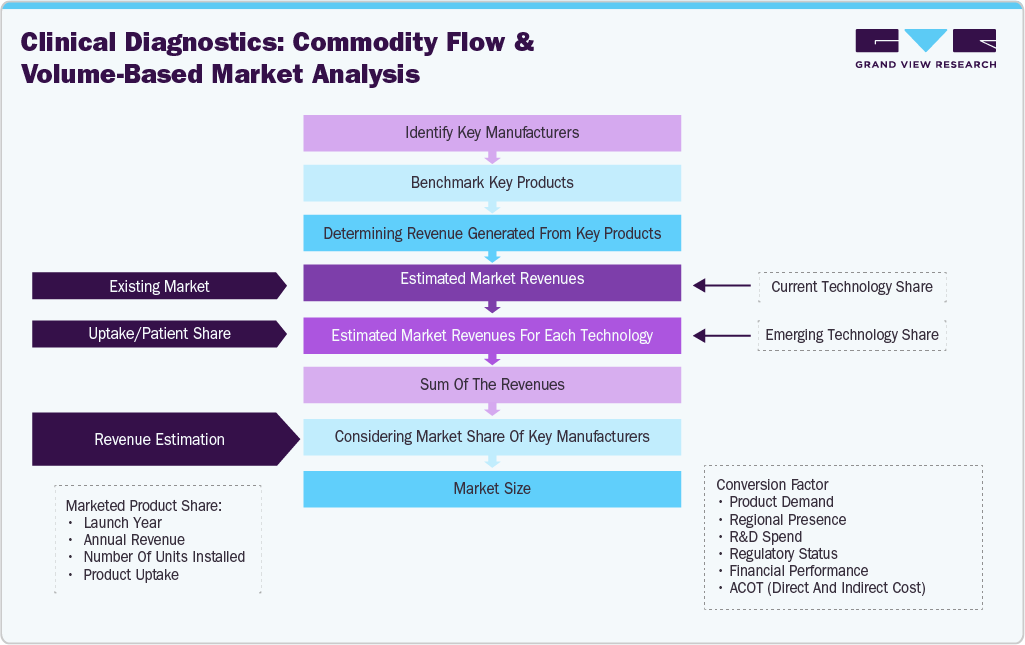
The market size for the global cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market is estimated using a combination of bottom-up and top-down approaches. The model captures manufacturer-level revenue generated from products used across the complete cervical cancer prevention pathway, including screening, diagnostic confirmation, and treatment of precancerous cervical lesions. Revenue from physician consultations, hospital service charges, laboratory service fees, surgery costs, and cancer treatment is excluded unless directly bundled with the sale of an eligible product.
The bottom-up approach begins with the eligible female population across each country and the number of women recommended for cervical cancer screening based on national age criteria and screening guidelines. This population is adjusted for screening coverage, screening frequency, healthcare access, program participation, and the proportion of women undergoing organized or opportunistic screening. The resulting number of annual screening procedures is used to estimate demand for Pap smear collection devices, cytobrushes, HPV testing assays, self-collection kits, specimen vials, transport media, reagents, cartridges, controls, and other associated consumables.
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Competitive Landscape & Technology Assessment – Cervical Cancer Screening, Diagnostics, Molecular HPV Testing & Pre-cancerous Lesion Treatment
Assessed the global cervical cancer prevention ecosystem across HPV testing platforms, Pap smear collection devices, cytobrushes, self-collection kits, colposcopes, cervical biopsy devices, digital and AI-enabled colposcopy systems, LEEP machines, cryotherapy systems, thermal ablation devices, diagnostic laboratories, hospitals, gynecology clinics, and public screening programs.
Enabled benchmarking of established and specialized market participants, identified growth opportunities in HPV self-sampling, molecular screening, digital colposcopy, AI-assisted imaging, and portable treatment systems, and mapped integrated screening-to-treatment solutions across different healthcare settings.
Cervical Cancer Screening & Dysplasia Treatment Regulatory, Clinical Guidelines & Reimbursement Assessment
Analyzed evolving regulatory frameworks, product approval requirements, cervical screening recommendations, HPV testing guidelines, colposcopy and biopsy protocols, precancer treatment eligibility criteria, quality assurance standards, reimbursement policies, and government procurement models across major global markets.
Supported regulatory and commercialization risk assessment, identified reimbursement and market-access barriers, evaluated the impact of changing screening intervals and HPV-first testing guidelines, and provided strategic direction on product registration, public tenders, clinical adoption, and geographic expansion.
Comprehensive Screening-to-Treatment Technology Assessment – HPV Testing, Self-collection, Digital Colposcopy, AI, LEEP, Cryotherapy & Thermal Ablation
Evaluated advancements in HPV DNA and mRNA testing, genotyping, liquid-based cytology, self-sampling, digital and AI-assisted colposcopy, cervical biopsy devices, LEEP systems, cryotherapy, thermal ablation, portable treatment technologies, and decentralized screen-and-treat models used across the cervical cancer prevention pathway.
Highlighted high-growth innovation areas, identified emerging technology progression screening and diagnostic accuracy, assessed competitive positioning across screening, diagnosis, and treatment categories, and provided strategic insights into integrated care pathways, patient follow-up, workflow efficiency, and future product-development opportunities.
Frequently Asked Questions About This Report
Asia Pacific is the fastest-growing region over the forecast period.
Cervical cancer screening segment dominated the market, with a revenue share of 49.0% in 2025.
North America dominated with a 41.2% revenue share in 2025.
The global cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market size was valued at USD 8.8 billion in 2025 and is estimated at USD 9.3 billion in 2026.
Some key players operating in the cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market include Hoffmann-La Roche; BD; Abbott; QIAGEN; Hologic, Inc.; CooperSurgical Inc.; MedGyn Products, Inc; WISAP Medical Technology GmbH; Liger Medical; Utah Medical Products, Inc.
Key factors that are driving the market growth include artificial intelligence (AI), awareness, and patient-centric screening programs. Efforts to enhance early detection and streamline diagnostic workflows are playing a pivotal role in reducing the global burden of cervical cancer.
The global cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market is expected to grow at a CAGR of 4.5% from 2026 to 2035, reaching USD 15.7 billion by 2035.
North America dominated the cervical cancer screening, diagnostics, and pre-cancerous dysplasia lesion treatment market with a share of 41.2% in 2025.
About the Author(s)
Clinical Diagnostics Research Team
Healthcare · Clinical DiagnosticsThis report was authored by the clinical diagnostics research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the clinical diagnostics segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


