
- Home
- »
- Plastics, Polymers & Resins
- »
-
Chemical Recycling of Plastics Market Size Report 2026-2033GVR Report cover

Chemical Recycling Of Plastics Market (2026 - 2033)
Size, Share & Trends Analysis Report By Type (Depolymerization, Dissolution, Conversion), By Product (PE, PET, PP, PVC, PS), By End-use (Packaging, Automotive, Textiles, Building & Construction), By Region, And Segment Forecasts
Market Size, 2025
$16.8BMarket Estimate, 2026
$18.1BMarket Forecast, 2033
$39.5BCAGR, 2026–2033
11.8%Chemical Recycling Of Plastics Market Summary
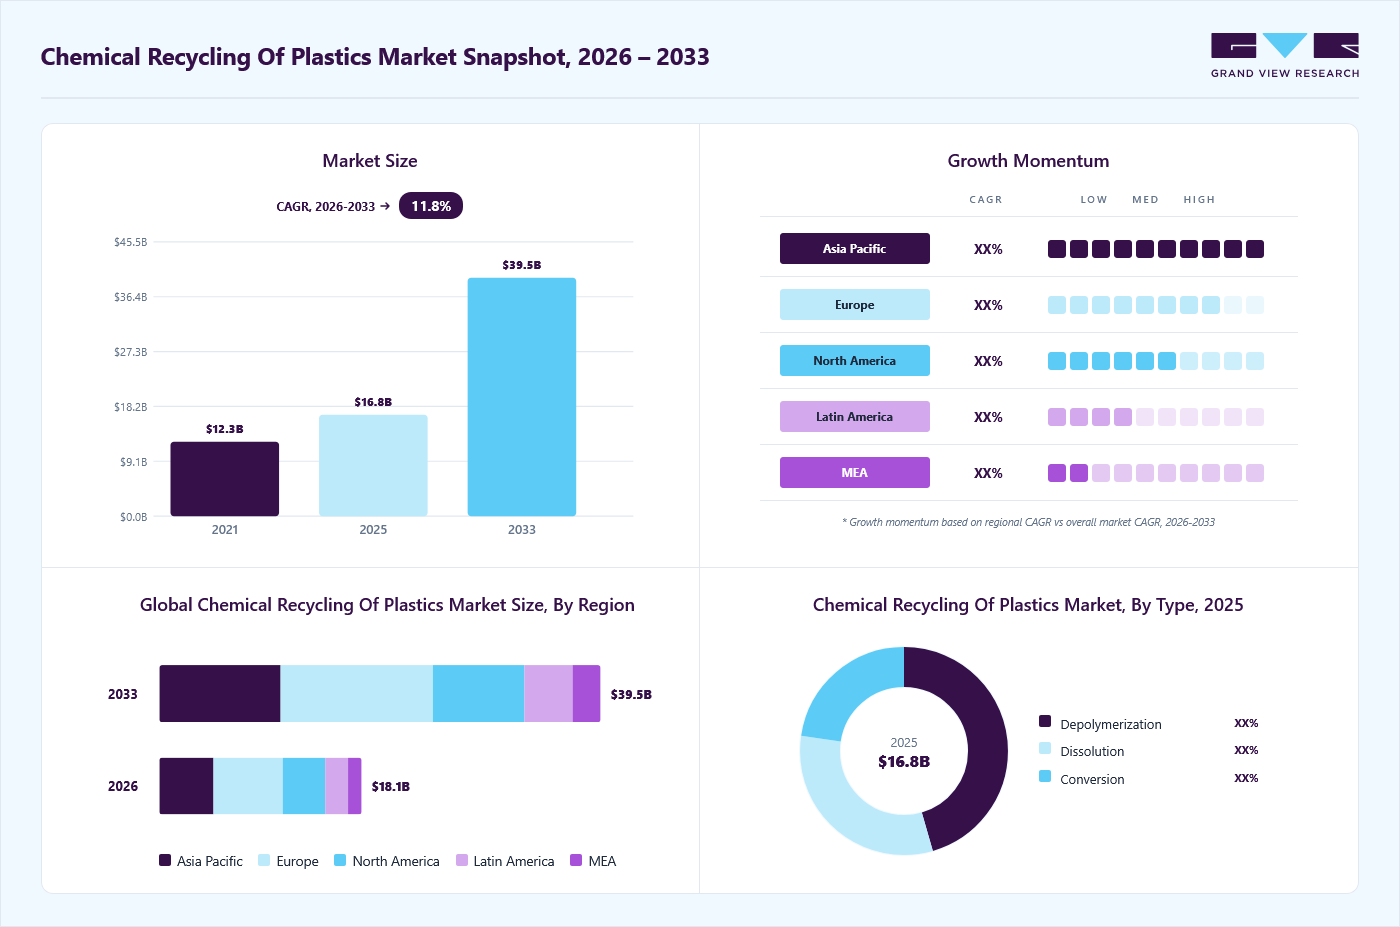
The global chemical recycling of plastics market size was estimated at USD 16.8 billion in 2025 and is projected to grow from USD 18.1 billion in 2026 to USD 39.5 billion by 2033, growing at a CAGR of 11.8% from 2026 to 2033. Europe dominated the global market, accounting for the largest revenue share of 34.2% in 2025. The chemical recycling of plastics market is experiencing strong growth driven by rising demand from packaging and FMCG brands, healthcare and medical device manufacturers, automotive and transportation companies, electronics producers, and textile and apparel industries to reduce dependence on virgin plastics and meet sustainable development goals.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By type: Depolymerization segment led the market with the largest revenue share of 45.5% in 2025.
- By product: PE segment dominated the market with the largest revenue share of 32.6% in 2025
- By end use: Packaging segment dominated the market with the largest revenue share of 34.6% in 2025.
Regional Highlights
- Largest regional market: Europe (34.2% revenue share, 2025)
- By country: The Germany chemical recycling of plastics market is a major contributor to the global market.
Market Size & Forecast
- Market size in 2025: USD 16.8 Billion
- Estimated market size in 2026: USD 18.1 Billion
- Projected market size by 2033: USD 39.5 Billion
- CAGR (2026-2033): 11.8%
Three ways to get this report
Buy it, customize it, or ask a question.Ask an Analyst
Analyst response in 1 business day
- AccessReport author, directly
- Reply timeWithin 1 working day
- No sales callDirect answer only
- FormatEmail reply
- CostFree, no cost
Get the Full Report
What the study covers
- FormatsPDF · Excel · Dashboard
- Timeline2026–2033 annual, 2025 base
- Coverage20+ countries, 5 regions
- Companies10+ key players profiled
Customize the Report
20% free customization
- IncludeCountries, segments, points
- TailorTo your product definition
- ExtendDeeper competitor detail
- OrA fully bespoke study
- Turnaround5–10 working days
The market is witnessing lucrative growth owing to growing global plastic waste crisis and the demand for more sustainable waste management solutions. Chemical recycling is a process of converting plastic waste into chemical feedstocks and other valuable goods using various chemical processes. The market is predicted to witness significant growth over the forecast period, with several factors driving this expansion. Various government initiatives toward recycling of plastics coupled with high investments is likely to propel demand for chemical recycling of plastics, thus boosting the market growth. Moreover, changing consumer behavior towards sustainability is driving the market.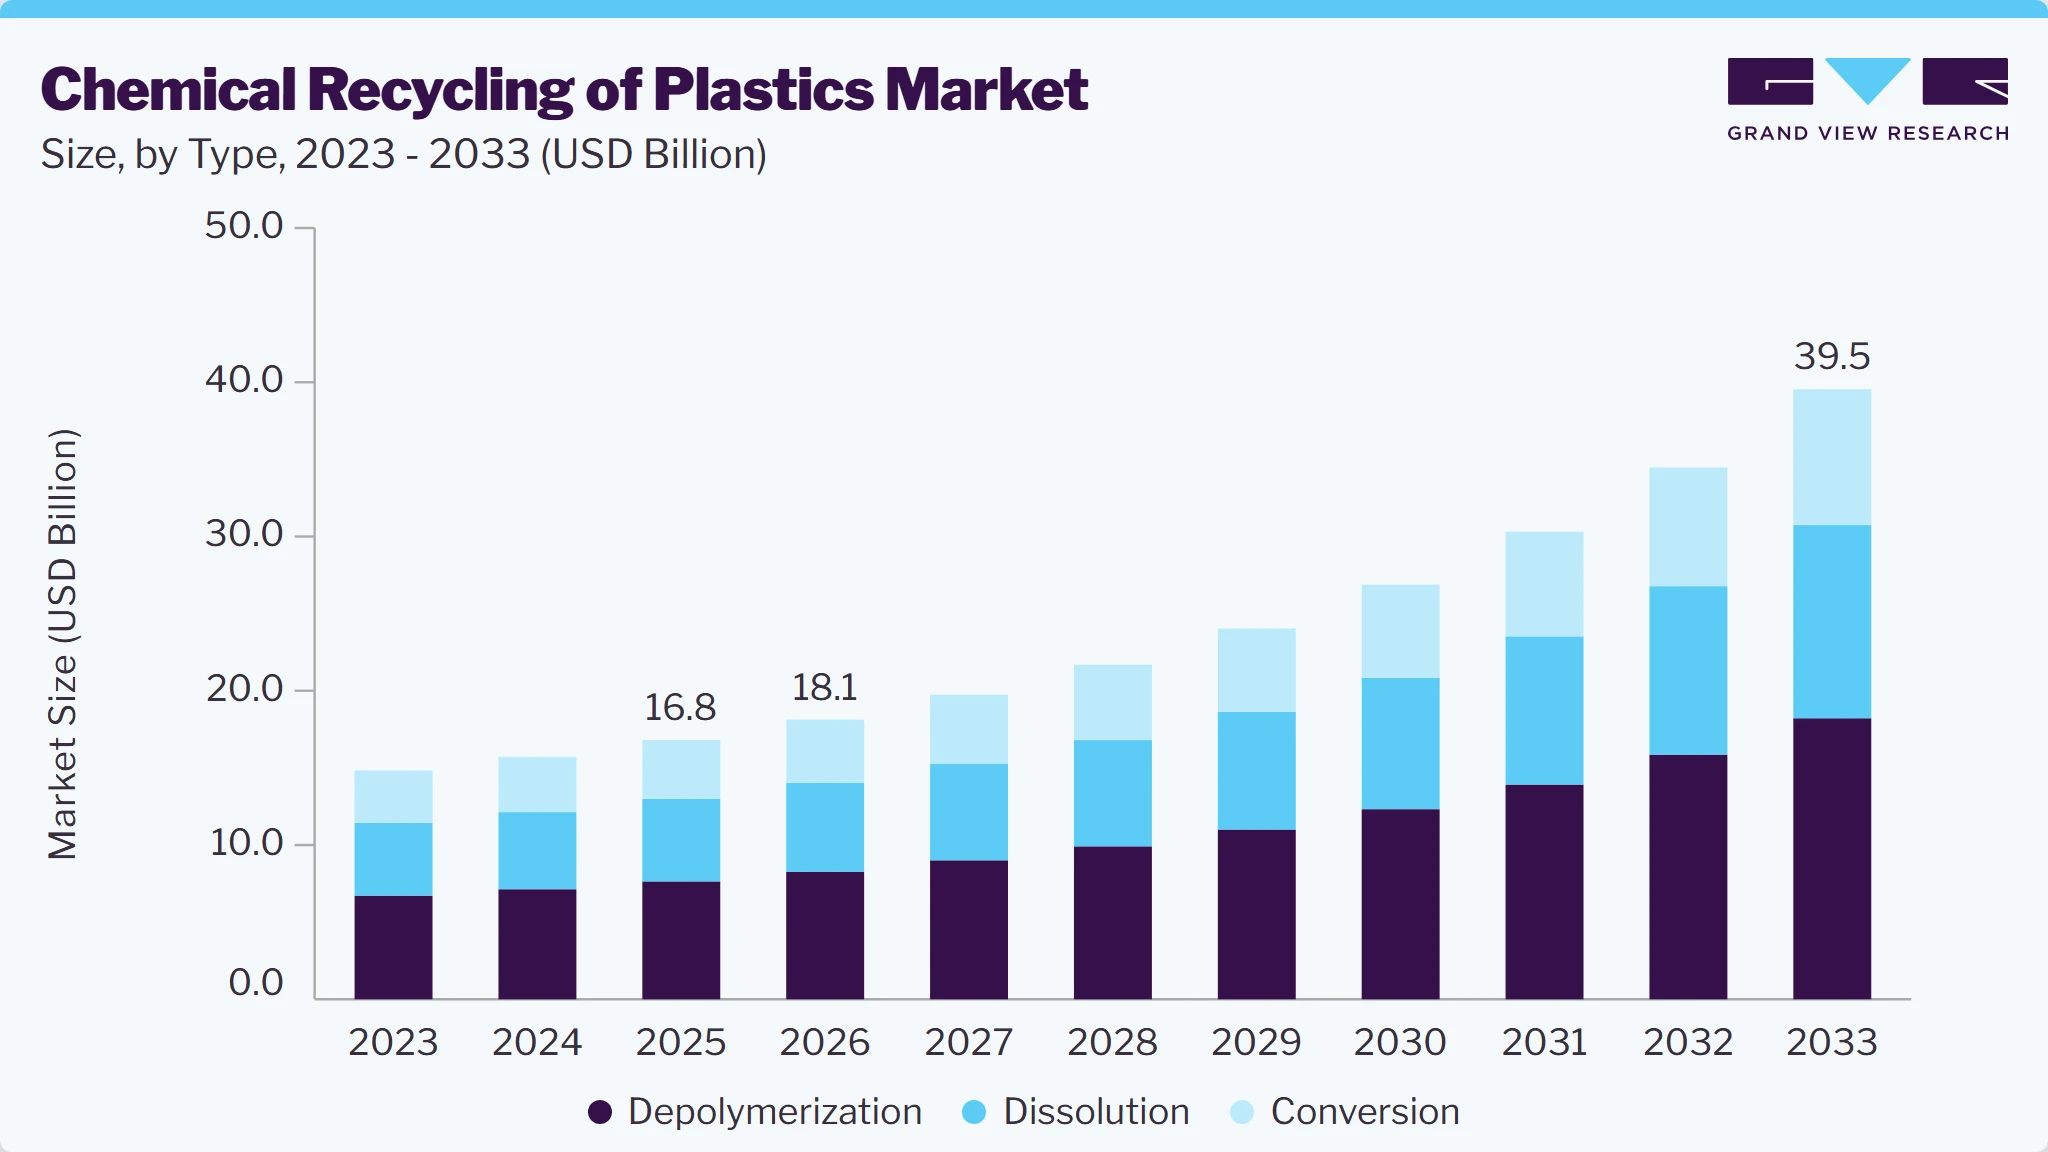 To learn more about this report, Download Free Sample Report
Increasing use of chemical recycled plastics in various industries such as automotive, electrical & electronics, packaging, textiles, and building and construction is anticipated to boost demand for chemical recycling of plastics. Additionally, increasing government investment in advanced plastics recycling technologies is anticipated to create lucrative opportunities for local market players. For instance, in September 2023, the U.S. Environmental Protection Agency announced an investment of over USD 100 million in grants to increase recycling and trash management, marking agency's first big effort in these areas in 30 years. This aims for a 50% recycling rate by 2030. Recycling rate for plastic garbage is only about 5%. These factors are creating opportunities for the growth of chemical recycling of plastics.
Market Dynamics
The chemical recycling of plastics market is witnessing a shift toward advanced process technologies that improve conversion efficiency and reduce operating costs. The adoption of advanced catalysts, including organocatalysts and tandem catalysis systems, is enabling depolymerization and feedstock recovery processes to operate at lower temperatures and pressures. This significantly reduces energy consumption and carbon emissions while improving product yields. At the same time, plasma-based recycling is emerging as a high-potential technology that uses ultra-high temperature plasma to break mixed plastic waste directly into fundamental molecular building blocks. These innovations support circular economy objectives, expand the range of recyclable plastics, and enhance the commercial viability of chemical recycling facilities.
The chemical recycling of plastics market is experiencing strong growth, supported by rising demand from the packaging industry, particularly for food-grade containers, flexible packaging, and beverage bottles. Rapid growth in e-commerce and quick commerce platforms is increasing the consumption of packaged food, beverages, and household products, creating substantial demand for high-quality recycled plastics. Brand owners and packaging manufacturers are increasingly adopting chemically recycled polymers to secure recycled content while maintaining product performance and regulatory compliance. This trend is accelerating investments in advanced recycling technologies and commercial-scale processing facilities.
Market demand is further reinforced by the expanding food and beverage sector, including energy drinks, ready-to-drink teas, fruit juices, soy beverages, yogurt drinks, sports beverages, as well as alcoholic beverages and beer. These applications require packaging materials that meet stringent food-contact safety standards and quality requirements. Unlike mechanical recycling, chemical recycling can produce polymers with virgin-grade characteristics suitable for direct food-contact applications. As regulatory pressure for circular economy adoption intensifies, chemical recycling is becoming a critical solution for achieving recycled content targets while ensuring packaging safety, material quality, and long-term resource sustainability.
The chemical recycling of plastics market faces challenges due to the strict feedstock quality requirements of many recycling technologies, especially depolymerization processes that require clean and uniform plastic waste streams. Contaminants such as PVC, multilayer plastics, pigments, and additives can reduce process efficiency, damage catalysts, and lower the quality of recovered materials. As a result, companies must invest more in sorting and feedstock preparation, increasing operational costs and affecting the economic feasibility of recycling projects. In addition, inadequate waste collection and segregation systems often limit the supply of suitable feedstock, leading to operational challenges and restricting the large-scale expansion of chemical recycling facilities.
The chemical recycling of plastics market is gaining opportunities from the increasing demand for medical-grade plastics. Advanced recycling technologies can convert recycled plastic feedstocks into high-purity polymers that meet the quality requirements of healthcare applications. Growing emphasis on circular economy goals, reducing medical waste, and adopting sustainable raw materials is driving investments in these technologies. As a result, chemical recyclers can expand into high-value healthcare markets and enhance their revenue potential and profit margins.
Market Concentration & Characteristics
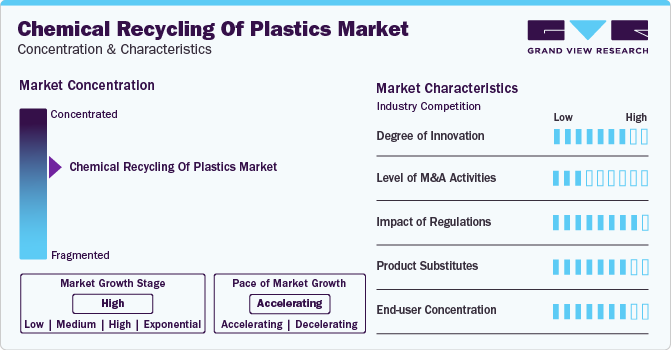
The chemical recycling of plastics market is highly consolidated, with key participants involved in R&D and technological innovations. Notable companies include Agilyx, BASF SE, Veolia, SABIC, JEPLAN, INC, among others. Several players are engaged in framework development to improve their market share.
Regulations aimed at reducing single-use plastics are likely to drive innovation in the development of alternative materials, affecting the global market. Modifications and updates in the directives are done to increase and improve the process of recycling plastic waste and facilitate several incentives and plans to move toward a circular economy.
 To learn more about this report, Download Free Sample Report
Chemically recycled plastics are mainly used as raw materials in production of new polymers, fuels, and other important items. Chemical recycling offers ability to process a larger range of plastic waste streams and generate high-quality feedstocks for production of new polymers. Furthermore, market is being driven by severe environmental regulations, increased consumer concerns about plastic pollution, and a desire for recycled plastic products.
Furthermore, ongoing R&D efforts are aimed at enhancing efficiency and scalability of chemical recycling processes. Advanced technologies such as pyrolysis, de-polymerization, and solvent-based recycling are gaining popularity in the market.
Analyst Perspective
The chemical recycling of plastics market is moving from pilot validation toward industrial integration, with value creation shifting from waste diversion to certified circular polymer supply. Over the coming years, demand is likely to strengthen in packaging, consumer goods, automotive, and electrical applications where recycled content commitments and regulatory pressure are reshaping procurement. Depolymerization will remain important for condensation polymers, while dissolution and conversion will compete for mixed and contaminated polyolefin streams that mechanical recycling cannot reliably process. Market leaders are likely to differentiate through feedstock security, process selectivity, energy efficiency, traceability, and customer integration. At the same time, profitability will remain exposed to feedstock inconsistency, collection bottlenecks, energy costs, capex intensity, and pricing pressure from virgin resin and mechanical recycling alternatives. The market is likely to become more partnership-led, technology-driven, and compliance-oriented over the forecast horizon.
Product Insights
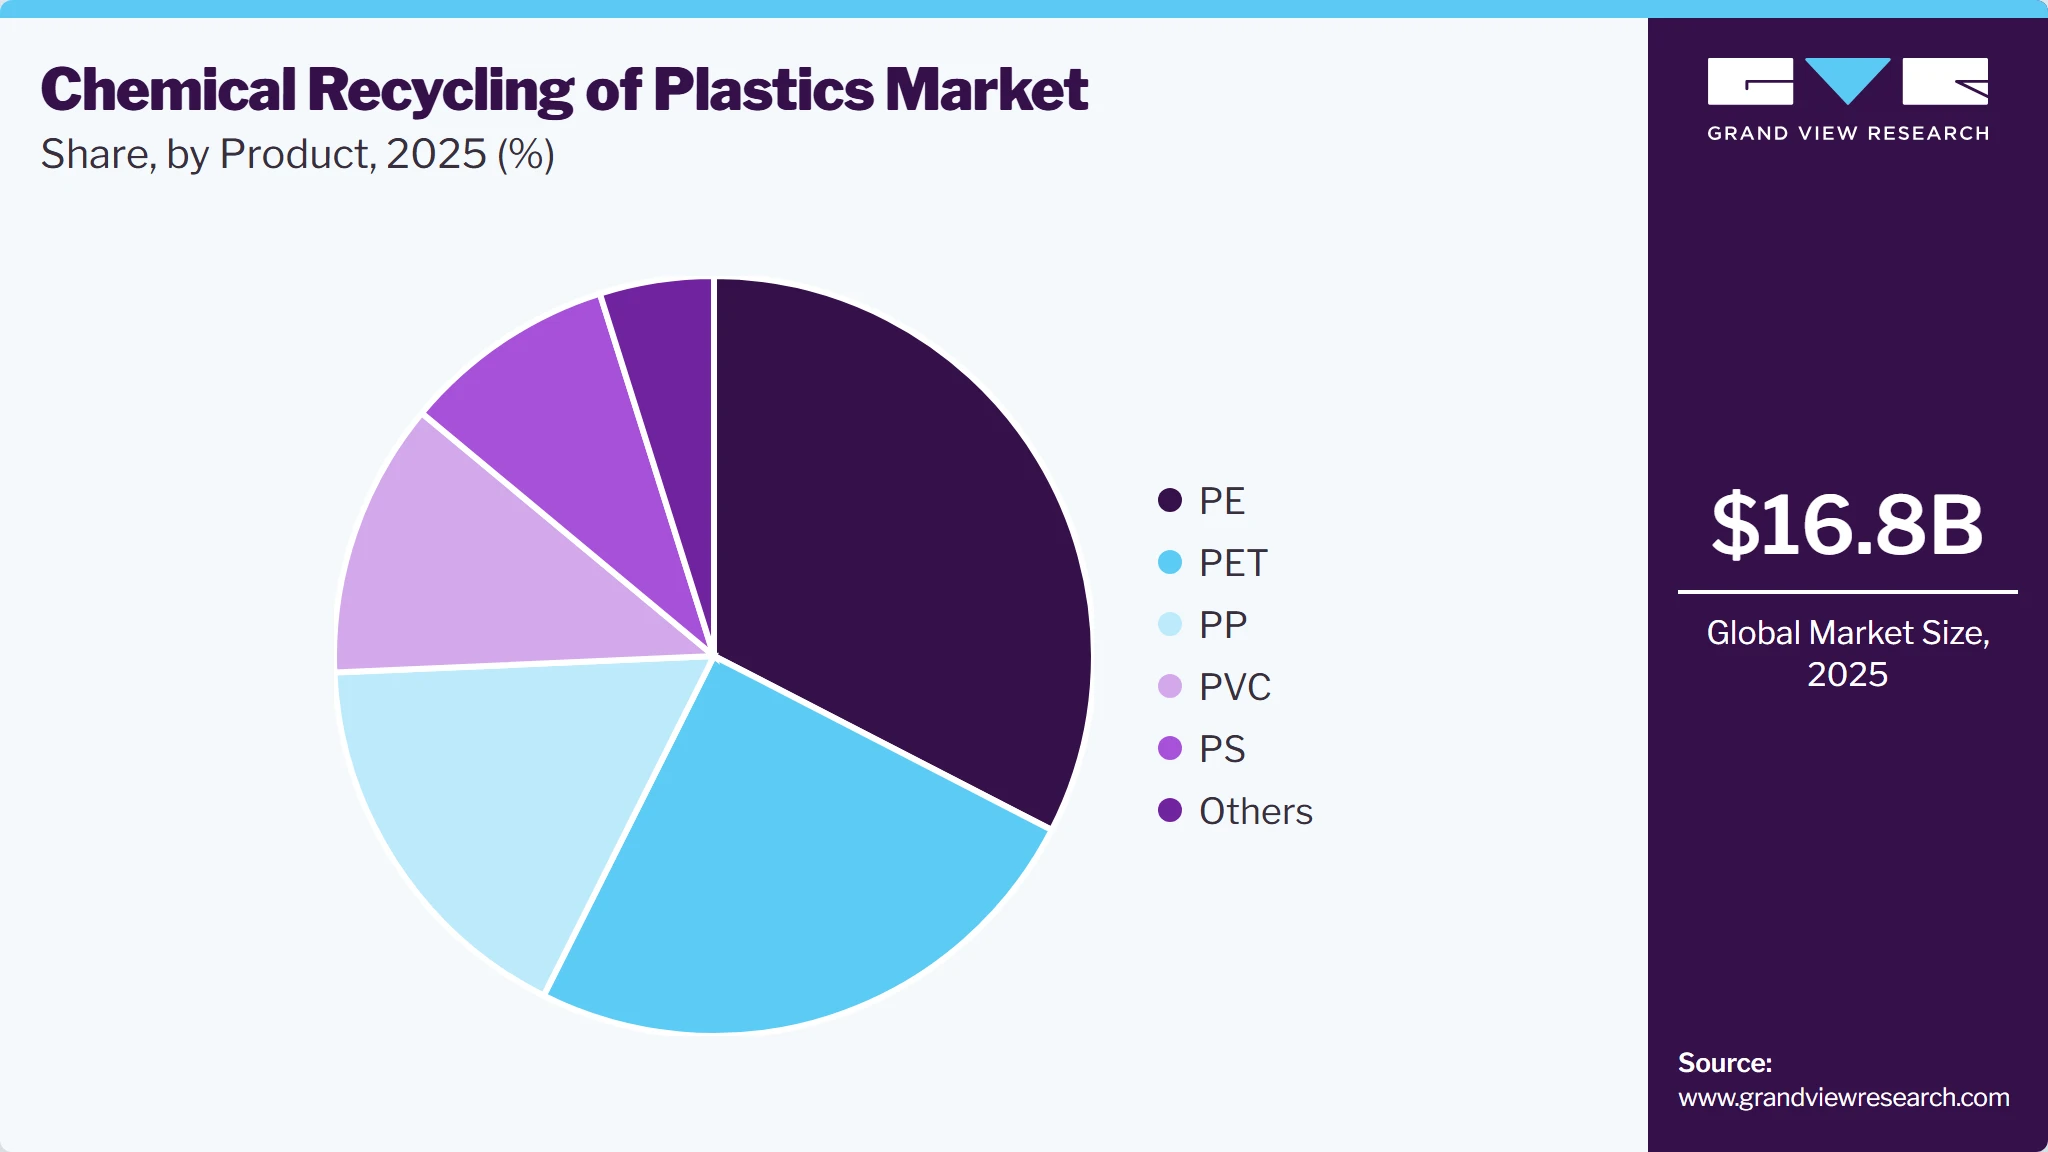
Based on product, the PE segment dominated the market with the largest revenue share of 32.6% in 2025. Demand is growing as the packaging industry is increasingly adopting circular polyethylene. Chemically recycled plastics are being widely used in flexible packaging applications such as food wraps, pouches, films, and rigid containers, helping companies achieve sustainability goals and meet regulatory standards. The expansion of e-commerce and quick commerce is also increasing the need for high-quality recycled packaging materials due to higher packaging consumption. Additionally, the rising demand for food-grade certified packaging is supporting market growth, as chemically recycled plastics offer virgin-like quality and help manufacturers comply with strict food-contact regulations.
 To learn more about this report, Download Free Sample Report
Chemically recycled polyethylene provides a high moisture barrier, and cost-effectiveness to product making it suitable in production for prototype development in CNC (Computer Numerical Control) machines and 3D printers. Polyethylene offers high stiffness, making it suitable for industrial applications, primarily packing automotive and electrical replacement parts.
End-use Insights
Based on end use, the packaging segment dominated the market with the largest revenue share of 34.6% in 2025. The packaging industry is witnessing strong demand due to the rapid expansion of e-commerce and quick commerce channels, which are increasing the consumption of plastic packaging across food, beverage, pharmaceutical, and consumer goods applications. Growing demand for food-grade certified packaging materials is encouraging investment in advanced recycling technologies that can produce high-quality recycled feedstock suitable for direct food contact applications. Rising consumption of functional beverages, including energy drinks, ready-to-drink teas, fruit juices, sports drinks, and dairy-based beverages, is further supporting packaging demand.
Plastics are widely used due to their high performance, low cost, and long durability. Plastics are used in a variety of packaging materials, including food, beverage, and oil. Furthermore, designed plastic is resistant to extreme environmental conditions and does not degrade under high temperatures, keeping integrity of products such as cosmetics and food and beverages. Furthermore, low cost and high printability of plastic make it a profitable packaging material.
Automotive end-use segment is expected to grow at a significant growth rate in the coming years, owing to the wide usage of recycled plastics in several automotive applications. The growing trend of using eco-friendly and recyclable plastic solutions in vehicles to meet environmental regulations and consumer demand for environmentally friendly products is expected to drive the market growth over the forecast period.
Type Insights
Based on type, the depolymerization segment led the market with the largest revenue share of 45.5% in 2025. The growth is due to increasing demand from the automotive and electronics industries for high-quality recycled polymers that offer performance similar to virgin materials. Automotive manufacturers are adopting recycled engineering plastics and polyurethanes in vehicle components to meet recycling regulations and sustainability goals. The expansion of electric and hybrid vehicle production is further supporting demand for recycled feedstocks. In addition, rising automation in manufacturing and increasing commercial vehicle production are driving material consumption. The electronics sector is also contributing to growth as companies use chemically recycled plastics to meet sustainability requirements and reduce electronic waste.
Plastic waste is depolymerized into oligomers or monomers using procedures such as hydrolysis, glycolysis, methanolysis, heat pyrolysis, among others. Monomers obtained are purified and depolymerized into a product. Demand for recycled materials is increasing in a variety of industries, including food and beverage and consumer goods. Consumption of recyclable polymers is increasing in several sector of economy due to high need for packaging materials that are safe for use in food and drinks.
Furthermore, growing concern about plastic waste, as well as crucial need for more environmentally friendly waste management solutions, are projected to fuel expansion of plastic chemical recycling market. The depolymerization need for plastics chemical recycling is likely to boost market growth.
Regional Insights
North America market is expected to grow significantly over the forecast period, with market share of 21.0% in 2023, owing to the high demand of chemically recycled plastics from the automotive, electrical & electronics, packaging, and construction sectors.
U.S. Chemical Recycling Of Plastics Market Trends
The U.S. market is expected to grow over the forecast period, due to rising awareness regarding sustainability. However, the plastic recycling rate in the U.S. is low as the plastic waste generated in the country is exported to other countries for recycling.
Asia Pacific Chemical Recycling Of Plastics Market Trends
Asia Pacific Chemical Recycling of Plastics Market is expected to grow at the fastest CAGR of 12.2% over the forecast period. Asian countries such as China, Vietnam, Indonesia, India, and Thailand, Japan are expected to emerge as primary markets for chemical recycling of plastics. Rising demand from various industries such as building & construction, packaging, and automotive, which are more inclined toward adoption of recycled plastics, is expected to drive the market growth.
Chemical Recycling of Plastics Market in China is anticipated to grow at a substantial rate due to its substantial manufacturing sector and population. China has a robust and growing market for recycled plastics due to its substantial manufacturing sector and population. As the government emphasizes environmental sustainability and circular economy principles, there is increasing demand for recycled plastics in various industries.
India Chemical Recycling of Plastics Market is anticipated to grow at a notable CAGR over the forecast period. The introduction of the chemical-based plastic recycling technology to recycle plastic waste to promote sustainability and the circular economy is expected to drive the growth of chemical-based plastic recycling market in the country.
Europe Chemical Recycling Of Plastics Market Trends
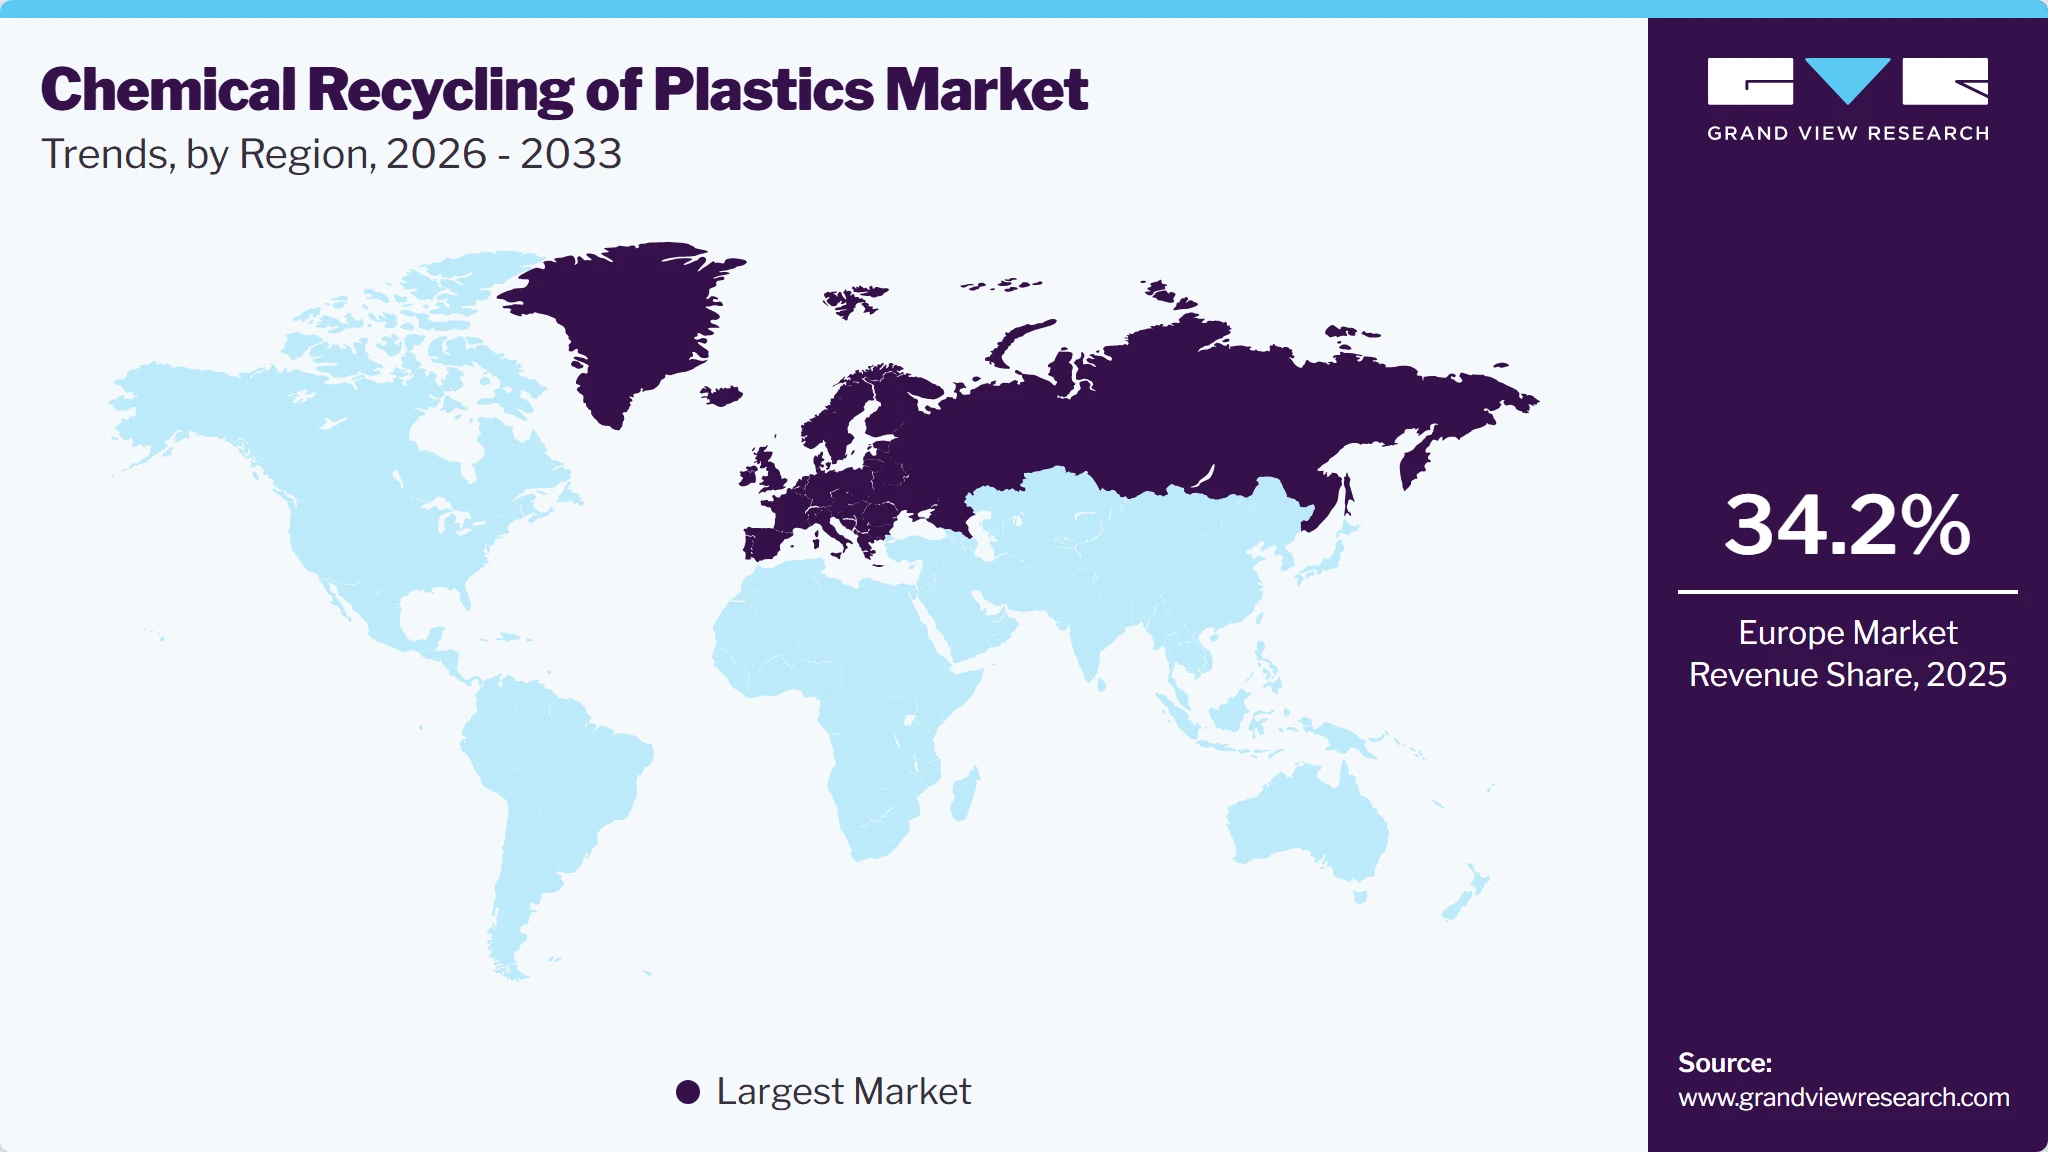
Europe dominated the chemical recycling of plastics market with the largest revenue share of 34.2% in 2025 and is expected to grow at the fastest CAGR of 11.9% over the forecast period. The rising adoption of a sustainable economy by the European Commission for reducing plastic waste is propelling market growth in the region. According to the European Commission, the region recycles and manufactures recycled plastics for about 45% of its plastic waste. These recovered plastics are employed in several industries, including building & construction, automotive, packaging, and electrical and electronics.
 To learn more about this report, Download Free Sample Report
The Germany chemical recycling of plastics market held the largest share, accounting for 26.4% in 2025. Germany has high plastic recycling rates compared to other European countries. This is due to the introduction of the Packaging Ordinance (VerpackV), which came into force in December 1991, and a new Packaging Law (VerpackG) that came into force in January 2019 (further amended in 2021).
UK Chemical Recycling of Plastics Market is anticipated to grow over the forecast period. Governmental initiatives such as the Plastic Pact 2025 are expected to positively influence the market in the country.
Central & South America Chemical Recycling Of Plastics Market Trends
Central & South America market is expected to witness significant growth over the forecast period. The region includes Argentina, Brazil, Chile, Colombia, Venezuela, Peru, Ecuador, and others. The emergence of construction companies in Chile and Peru is expected to create growth potential for the market over the forecast period.
Middle East & Africa Chemical Recycling Of Plastics Market Trends
Middle East & Africa market is expected to witness significant growth over the forecast period. A shift in focus toward the non-oil private sector in the region is predicted to boost manufacturing and other end-use industries, as well as diversify the economy of the region. The efforts taken by various governments in the region to support the growth of plastic recycling in the industrial sector and achieve sustainability goals are anticipated to contribute to the growth of the market in the forecast period.
Key Chemical Recycling Of Plastics Company Insights
Key companies are adopting several organic and inorganic growth strategies, such as new product development, mergers & acquisitions, and joint ventures, to maintain and expand their market share.
-
In April 2023, NextChem completed the acquisition of Biorenova's proprietary continuous chemical recycling technology, known as CATC. Biorenova transferred CatC patents, assets, including a demonstration plant, and contracts to MyRemono S.r.l., a newly formed business in which NextChem owns a controlling stake of 51%.
Key Chemical Recycling Of Plastics Companies
The following key companies have been profiled for this study on the chemical recycling of plastics market.
-
Agilyx
-
BASF SE
-
MaireTecnimont S.p.A.
-
INEOS AG
-
Recycling Technologies
-
Veolia Environnement SA
-
JEPLAN, INC.
-
Eastman Chemical Company
-
SABIC
-
LyondellBasell Industries Holdings B.V.
Competitive Benchmarking
Category
Operating Strategies
Competitive Edge
Weakness
Established Players (BASF SE, INEOS AG, Veolia Environnement SA, Eastman Chemical Company, SABIC, LyondellBasell Industries Holdings B.V., MaireTecnimont S.p.A.)
- Build integrated value chains through feedstock access, processing capability, and long-term offtake structures.
- Use joint ventures, licensing, and project partnerships to reduce commercialization risk.
- Prioritize large-scale deployments in regions with policy support and strong polymer demand.
- Larger balance sheets and better access to project finance.
- Stronger downstream relationships with resin buyers and converters.
- Greater ability to manage scale-up, permitting, and certification requirements.
- Slower commercialization cycles and higher execution complexity.
- Greater exposure to feedstock, energy, and plant utilization risk.
- More visible margin pressure when virgin resin prices weaken.
Emerging Players (Agilyx, Recycling Technologies, JEPLAN, INC.)
- Focus on niche conversion routes and narrower waste streams.
- Advance commercialization through pilot plants, partnerships, and modular deployment.
- Target differentiated output quality or specialized feedstock compatibility.
- Faster product iteration and technology adaptation.
- Stronger focus on specific recycling pathways and process IP.
- Greater flexibility in serving underserved market niches.
- Limited global scale and weaker access to capital.
- Higher dependence on strategic partners for feedstock and market access.
- Greater risk around ramp-up, yield consistency, and long-term economics.
Chemical Recycling Of Plastics Market Report Scope
Report Attribute
Details
Market size in 2025
USD 16.8 billion
Estimated Market size in 2026
USD 18.1 billion
Projected Market size by 2033
USD 39.5 billion
Growth rate
CAGR of 11.8% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Volume in Kilotons, Revenue in USD million/billion, and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, and trends
Segments covered
Type, product, end use, region
Regional scope
North America; Europe; Asia Pacific; Central & South America; Middle East & Africa
Country scope
U.S.; Canada; Mexico; Germany; U.K.; France; Italy; Spain; Denmark; Norway; Sweden; China; India; Japan; Brazil; Argentina; Saudi Arabia; South Africa
Key companies profiled
Agilyx; BASF SE; MaireTecnimont S.p.A.; INEOS AG; Recycling Technologies; Veolia Environnement SA; JEPLAN, INC.; Eastman Chemical Company; SABIC; LyondellBasell Industries Holdings B.V
Customization scope
Free report customization (equivalent up to 8 analysts' working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Chemical Recycling Of Plastics Market Report Segmentation
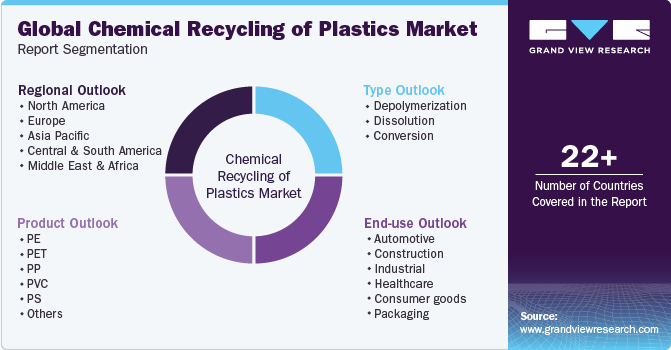
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global chemical recycling of plastics market report based on type, product, end-use, and region:
 To learn more about this report, Download Free Sample Report
-
Type Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Depolymerization
-
Dissolution
-
Conversion
-
-
Product Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
PE
-
PET
-
PP
-
PVC
-
PS
-
Others
-
-
End-use Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
Packaging
-
Automotive
-
Building & Construction
-
Electrical & electronics
-
Textiles
-
Others
-
-
Regional Outlook (Volume, Kilotons; Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
Germany
-
U.K.
-
France
-
Italy
-
Spain
-
Denmark
-
Norway
-
Sweden
-
-
Asia Pacific
-
China
-
India
-
Japan
-
South Korea
-
Australia
-
-
Central & South America
-
Brazil
-
Argentina
-
-
Middle East and Africa
-
Saudi Arabia
-
South Africa
-
-
Research Methodology
The chemical recycling of plastics market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each chemical recycling of plastics segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Type
Revenue capture definition
Depolymerization
Revenue is generated through the chemical recycling of plastics by breaking polymer chains into their original monomers, which are then purified and reused to manufacture new plastics. Demand is driven by the increasing need for food-grade recycled materials, circular economy initiatives, regulatory requirements for recycled content, and growing adoption of recycled PET, polyamide, and polyurethane in packaging, automotive, and textile applications.
Dissolution
Revenue is captured through the recycling of plastics using selective solvent-based processes that separate polymers from additives, contaminants, and multilayer structures while preserving polymer quality. Market growth is supported by rising demand for high-purity recycled plastics, increased use of flexible and multilayer packaging, stricter waste management regulations, and the need for recycled materials with properties comparable to virgin resins.
Conversion
Revenue is generated through the conversion of plastic waste into valuable products such as pyrolysis oil, synthetic feedstocks, chemicals, fuels, and waxes. Demand is fueled by the growing focus on landfill diversion, increasing investments in advanced recycling technologies, rising demand for circular feedstocks from petrochemical producers, and corporate sustainability targets aimed at reducing dependence on fossil-based raw materials.
Segment - Product
Revenue capture definition
PE
Revenue is generated through the chemical recycling of polyethylene used in packaging films, rigid containers, pipes, and industrial liners. Demand is driven by high collection volumes, broad end-use demand, and the need to convert mixed PE waste into feedstock for new polymers, fuels, and chemical intermediates.
PET
Revenue is captured through the recycling of PET bottles, trays, textile fibers, and packaging materials into monomers and recycled resin. Growth is supported by strong demand from beverage packaging, fiber applications, and brand owner commitments to increase recycled content and circular packaging use.
PP
Revenue is generated from the recycling of polypropylene used in caps, closures, automotive parts, consumer goods, and food packaging. Demand is supported by the large installed base of PP products, rising collection from post-consumer and industrial waste, and the need for high-quality recycled feedstock for durable applications.
PVC
Revenue is captured through the chemical recycling of PVC from pipes, cables, flooring, films, and construction materials. Demand is influenced by the need to process complex waste streams, recover valuable feedstock, and reduce landfill disposal while supporting circular use in construction and industrial applications.
PS
Revenue is generated through the recycling of polystyrene from food service items, protective packaging, insulation products, and consumer goods. Market growth is driven by the need to handle lightweight but bulky waste, improve material recovery, and produce reusable chemical inputs from difficult-to-recycle PS waste.
Others
Revenue is captured through the chemical recycling of mixed and specialty plastics such as ABS, PA, multilayer materials, and composite waste. Demand is supported by the processing of hard-to-recycle streams, recovery of value from mixed plastic waste, and growing interest in advanced recycling solutions for complex applications.
Segment - End Use
Revenue capture definition
Packaging
Revenue is generated through the chemical recycling of plastics used in flexible packaging, rigid containers, films, pouches, and multilayer packs. Demand is driven by high packaging waste volumes, rising brand owner commitments to recycled content, and the need to convert post-consumer plastic into circular feedstock for new packaging applications.
Automotive
Revenue is captured through the recycling of plastics used in interior trims, bumpers, dashboards, under-the-hood parts, and structural components. Demand is supported by vehicle lightweighting initiatives, growing use of recycled materials in auto manufacturing, and the need to improve sustainability while maintaining performance and durability.
Building & Construction
Revenue is generated from the chemical recycling of plastics used in pipes, insulation, panels, flooring, roofing, and construction films. Market growth is supported by high material demand in infrastructure projects, the need to manage durable plastic waste streams, and the increasing focus on circular building materials.
Electrical & Electronics
Revenue is captured through the recycling of plastics used in housings, casings, circuit-related components, appliances, and cable insulation. Demand is driven by rapid electronics turnover, rising e-waste volumes, and the need to recover valuable plastic feedstock from complex and mixed material streams.
Textiles
Revenue is generated through the recycling of synthetic plastic-based textiles, fibers, apparel waste, carpets, and nonwoven materials. Demand is supported by growing textile waste generation, brand sustainability targets, and the need to convert polyester and other polymer-based fibers into usable raw materials.
Others
Revenue is captured through the chemical recycling of mixed and specialty plastic waste from sectors such as healthcare, agriculture, consumer goods, and industrial applications. Demand is supported by the processing of hard-to-recycle waste streams, recovery of value from contaminated plastics, and broader adoption of advanced recycling solutions.
Estimation Model
Layer Name
Key Question
Description
Demand Sizing Layer
Where is demand generated?
Captures the overall demand for chemical recycling of plastics across packaging formats such as flexible films, rigid containers, multilayer packs, pouches, bottles, and trays, where the need for circular feedstock, recycled content compliance, and brand sustainability targets is strongest.
Feedstock Access Layer
Can supply support growth?
Identifies packaging applications where chemical recycling of plastics is preferred due to contamination tolerance, ability to handle mixed and multilayer waste, and suitability for producing high-purity feedstock for food packaging, non-food packaging, and industrial packaging uses.
Conversion Economics Layer
Are projects commercially viable?
Defines the realistic adoption pool where chemically recycled plastics compete with virgin resin, mechanical recycling, paper-based packaging, bio-based materials, and compostable alternatives, based on performance, cost, recyclability, and regulatory requirements.
Regional Commercialization Layer
Which regions monetize fastest?
Represents actual market revenue generated from chemically recycled plastics consumed in packaging production, adjusted for collection efficiency, sorting losses, recycling yield, end-user acceptance, packaging conversion volumes, and pricing premiums for recycled-content materials.
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
Regional Segmentation
Detailed market sizing and forecast analysis across North America, Europe, Asia Pacific, Latin America, and the Middle East & Africa. Further country-level breakdown for key markets such as the U.S., Germany, France, the U.K., China, Japan, South Korea, India, and Brazil.
Helps identify high-growth regions, investment hotspots, regulatory developments, feedstock availability, and demand centers for chemical recycling technologies.
Cross-Segmentation
Market analysis by technology (Pyrolysis, Gasification, Depolymerization, Solvent-Based Recycling, Others) cross-tabulated with polymer type (PE, PP, PET, PS, PVC, Others), end-use industry, and region.
Enables identification of high-revenue pockets, technology adoption trends, and the most attractive polymer-technology combinations across regions and applications.
Competitive Benchmarking
Comparative assessment of major chemical recycling companies based on technology portfolio, processing capacity, geographic footprint, feedstock sourcing strategy, partnerships, commercialization stage, and expansion activities.
Provides a clear view of competitive positioning, market leadership, technology differentiation, and strategic opportunities for partnerships, acquisitions, or market entry.
Frequently Asked Questions About This Report
The key players in the chemical recycling of plastic market Agilyx; BASF SE; MaireTecnimont S.p.A.; INEOS AG; Recycling Technologies; Veolia Environnement SA; JEPLAN, INC.; Eastman Chemical Company; SABIC; LyondellBasell Industries Holdings B.V.
The market is witnessing lucrative growth owing to growing global plastic waste crisis and the demand for more sustainable waste management solutions.
The Depolymerization led the chemical recycling of plastic market in 2025 with a 45.5% share, the growth is supported by rising demand from packaging industry.
The Europe Chemical Recycling of Plastic market accounted for the largest share of 34.2% market size in 2025.
Asia Pacific was the leading Chemical Recycling of Plastic market and is expected to grow at a compound annual growth rate of 12.2%.
Based on the end use, the packaging segment accounted for the largest share of 34.6% market size in 2025. Growth is supported by rapid demand from the food and beverage, consumer goods, and personal care industries.
The PE segment based on product is expected to grow at a CAGR of 12.2% over the forecast period.
The chemical recycling of plastic market was estimated at around USD 16.8 billion in the year 2025 and is expected to reach around USD 18.1 billion in 2026.
The chemical recycling of plastic market is expected to grow at a compound annual growth rate of 11.8% from 2026 to 2033 to reach around USD 39.5 billion by 2033.
About the Author(s)
Plastics, Polymers & Resins Research Team
Bulk Chemicals · Plastics, Polymers & ResinsThis report was authored by the plastics, polymers & resins research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the plastics, polymers & resins segment of the bulk chemicals industry. All findings are based on proprietary bulk chemicals databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


