
- Home
- »
- Pharmaceuticals
- »
-
Chronic Inflammatory Demyelinating Polyneuropathy Market 2033GVR Report cover

Chronic Inflammatory Demyelinating Polyneuropathy Market (2026 - 2033)
Size, Share & Trends Analysis Report By Treatment Type (Immunoglobulin Therapy, Corticosteroid Therapy), By Route of Administration, By Patient Type, By Distribution Channel, By Region, And Segment Forecasts
Market Size, 2025
$2.2BMarket Estimate, 2026
$2.3BMarket Forecast, 2033
$3.8BCAGR, 2026–2033
7.6%Chronic Inflammatory Demyelinating Polyneuropathy Market Summary
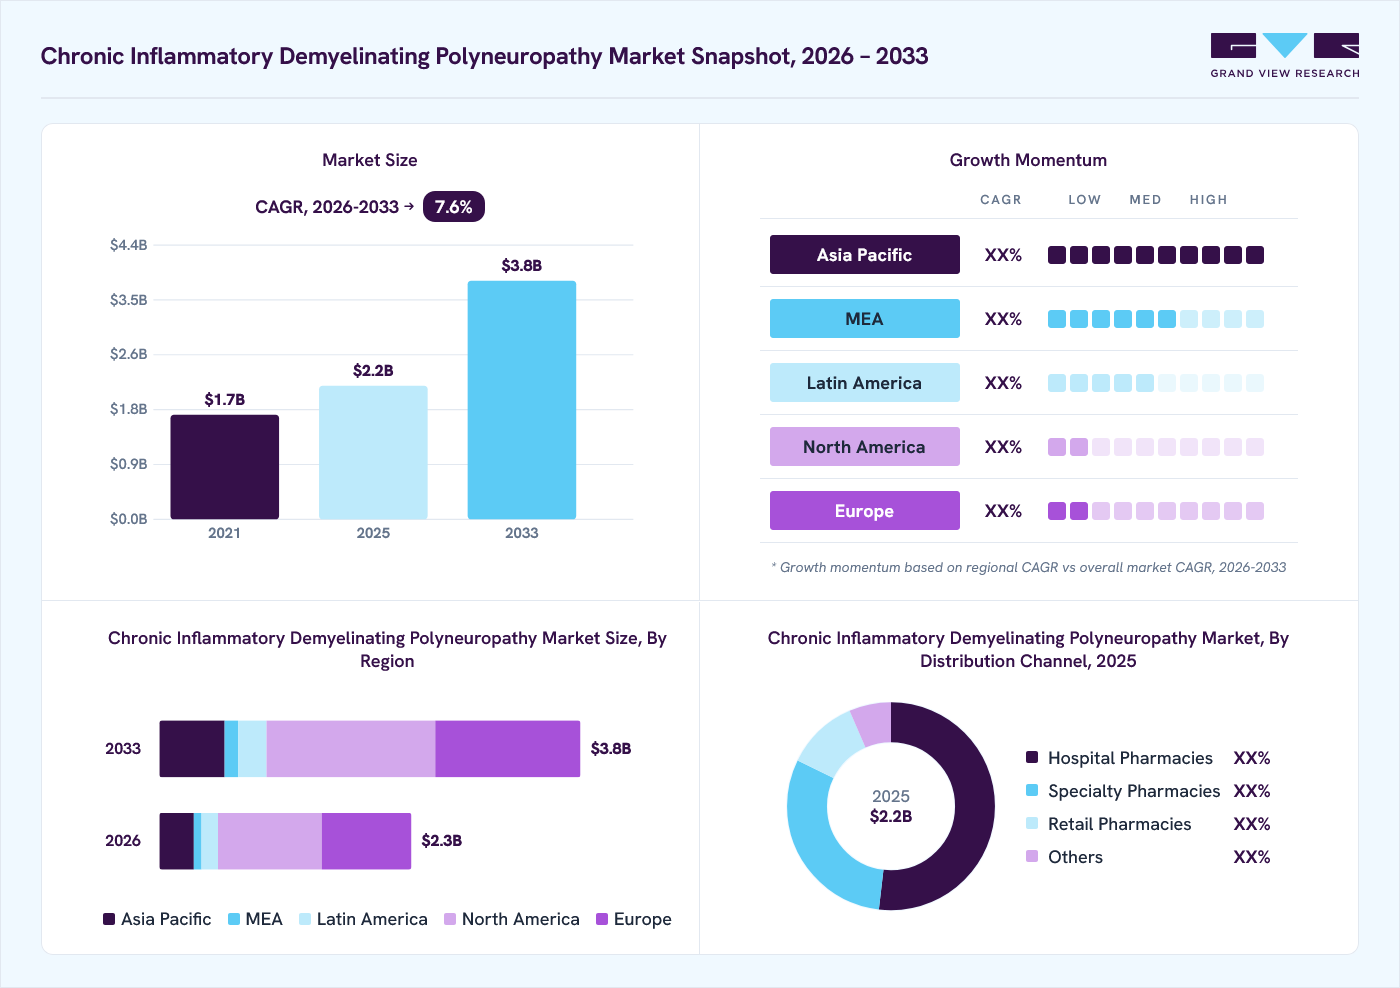
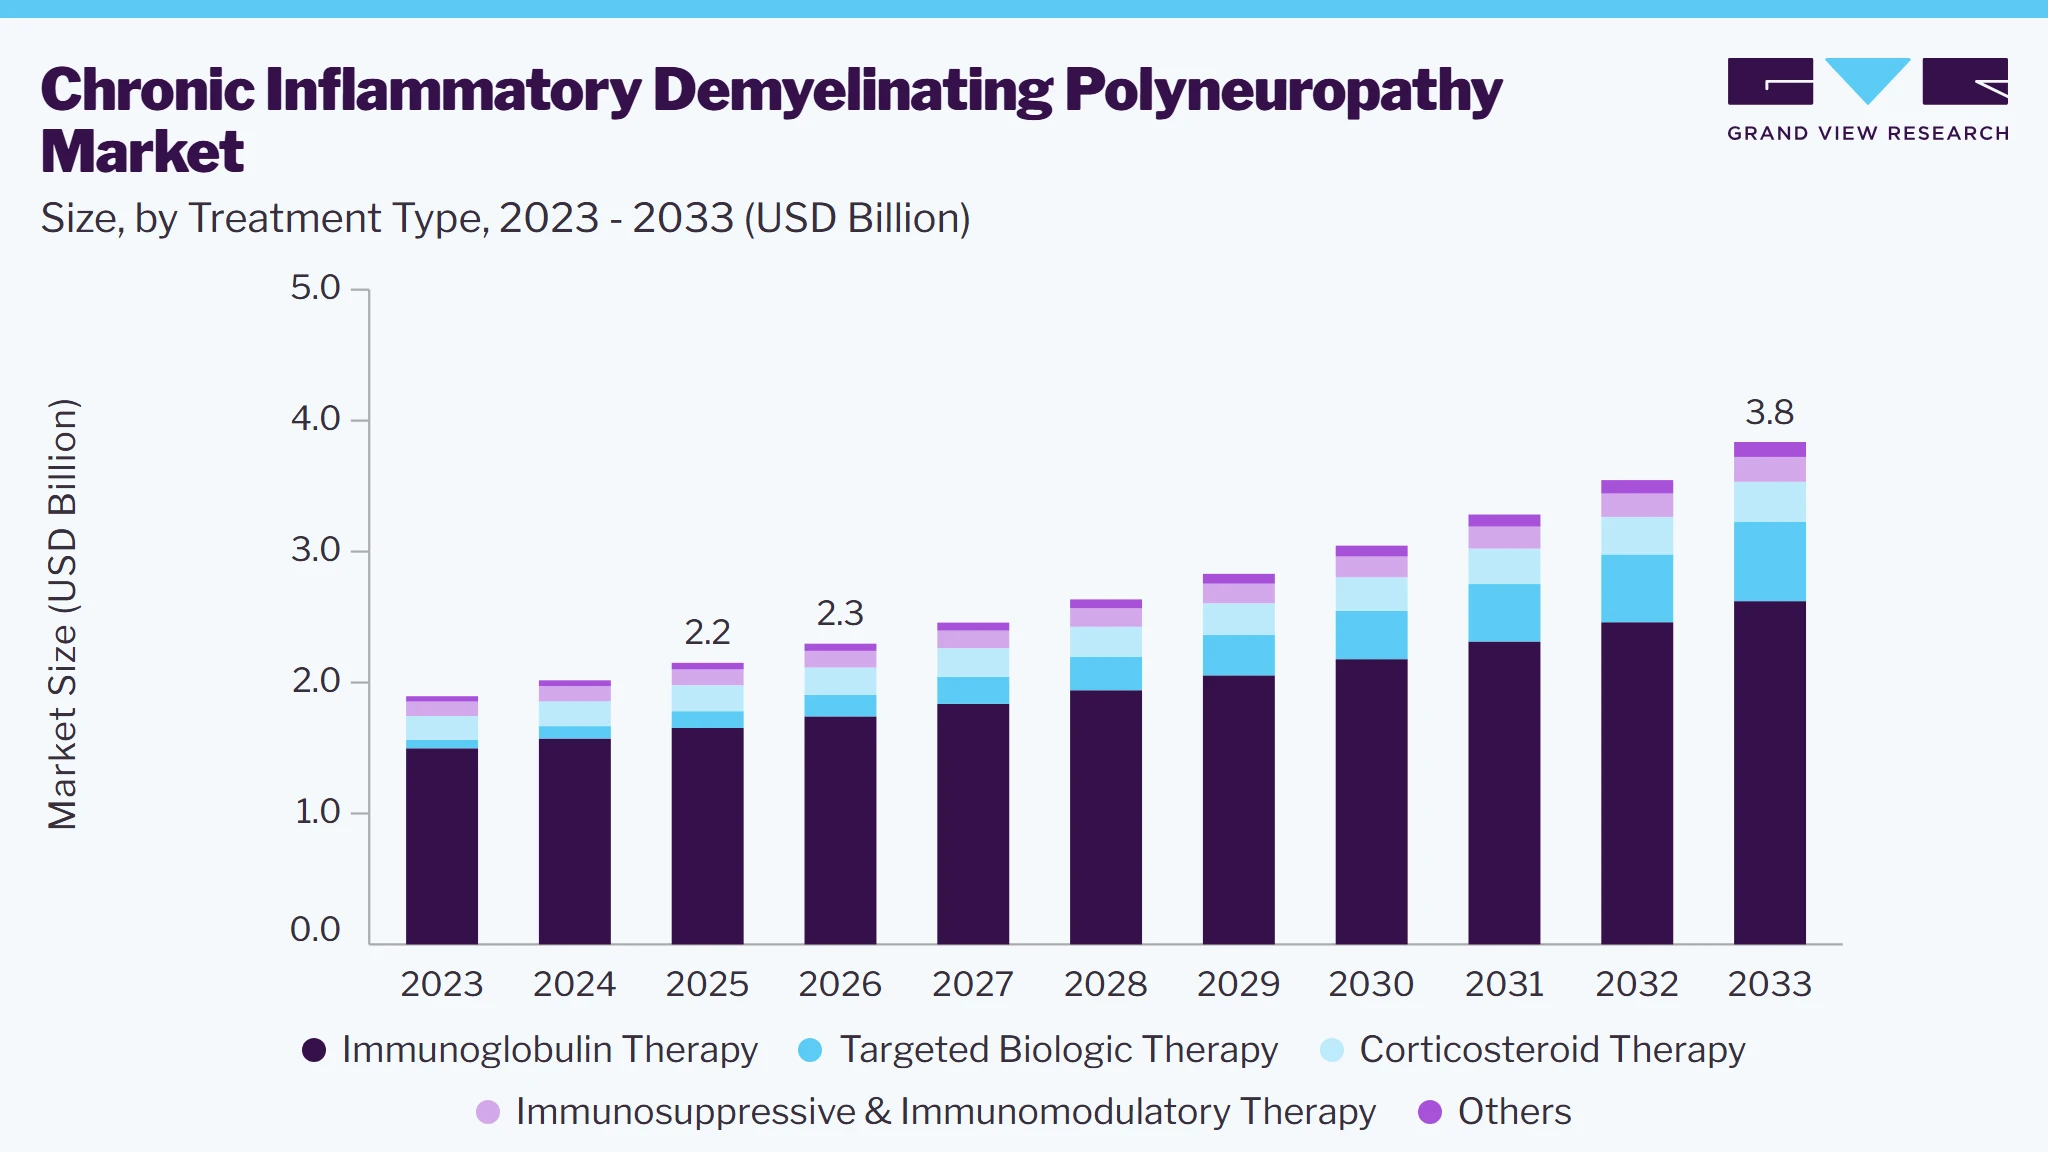
The global chronic inflammatory demyelinating polyneuropathy market size was valued at USD 2.2 billion in 2025 and is projected to reach USD 2.3 billion in 2026 to USD 3.8 billion by 2033, at a CAGR of 7.6% from 2026 to 2033. North America dominated the market, accounting for a revenue share of 41.2% in 2025.
 Source: Grand View Research, IR Documents, Primary Interviews, Paid DatabasesTo learn more about this report,
 Download Free Sample Report
Key Market Trends & Insights
- By treatment type: Immunoglobulin therapy segment held the highest market share of 76.9% in 2025.
- By route of administration: Intravenous segment held the highest market share of 80.6% in 2025.
- By patient type: Adult patients segment held the highest market share of 90.8% in 2025.
- By distribution channel: Hospital pharmacies segment held the highest market share in 2025.
Regional Highlights
- Largest region market: North America (41.2% revenue share, 2025)
- Fastest-growing regional market: Asia Pacific (highest CAGR, 2026-2033)
- By country: The U.S. held the largest market share in 2025.
Market Size & Forecast
- Market size in 2025: USD 2.2 Billion
- Estimated market size in 2026: 2.3 Billion
- Projected market size by 2033: USD 3.8 Billion
- CAGR (2026-2033): 7.6%
Prism AI by Grand View Research Free to tryAsk a question about the chronic inflammatory demyelinating polyneuropathy marketTry asking✓Every figure cited from GVR research Prefer the report? Download free sample →In this condition, the immune system attacks the myelin sheath, the protective covering around nerves, disrupting the transmission of signals between the brain, spinal cord, and muscles. Patients commonly experience muscle weakness, numbness, reduced reflexes, and difficulty walking. Treatment focuses on controlling the immune response, improving nerve function, and maintaining physical independence. Key treatment options include intravenous immunoglobulin (IVIg), subcutaneous immunoglobulin (SCIg), corticosteroids, and plasma exchange. Targeted therapies also contribute to the market by addressing specific immune mechanisms involved in chronic inflammatory demyelinating polyneuropathy (CIDP). Demand for treatment is associated with disease recognition, access to neurological care, availability of approved therapies, and the need for continued disease management. Treatment selection depends on clinical response, patient condition, tolerability, and access to healthcare services.
 To learn more about this report, Download Free Sample Report
The prevalence of CIDP is an important factor in assessing the patient population requiring treatment. A study published in 2025 in the Journal of the Peripheral Nervous System examined CIDP prevalence, incidence, clinical characteristics, treatment, and outcomes among different ethnic groups in Birmingham, United Kingdom. The study reported a prevalence of 6.18 cases per 100,000 people as of July 2025. Disease identification remains a challenge because symptoms overlap with other neurological conditions, and diagnosis requires clinical assessment and supporting tests. Differences in diagnostic practices, specialist availability, and access to neurological services affect the identification of patients. These factors influence the number of patients receiving treatment and the demand for medicines. The need for continued disease management also supports demand for therapies that maintain symptom control and reduce functional limitations.
Treatment options and regulatory developments continue to shape the CIDP market. Immunoglobulin therapies remain important because they help regulate the immune response, while corticosteroids and plasma exchange provide additional treatment options. Subcutaneous immunoglobulin offers a maintenance option for eligible patients who require ongoing therapy. Targeted treatments are also expanding available choices by acting on specific components of the immune system. Treatment decisions depend on disease severity, previous response, safety considerations, patient preference, and reimbursement coverage. However, high treatment costs, the need for repeated administration, and differences in healthcare access affect patient access. Market development therefore depends on clinical outcomes, treatment availability, diagnosis rates, and payer decisions across countries.
Market Dynamics
Immunoglobulin therapies are a key driver of the chronic inflammatory demyelinating polyneuropathy (CIDP) market because they help regulate immune activity and improve neurological function. Intravenous immunoglobulin (IVIg) remains an established treatment option, while subcutaneous immunoglobulin (SCIg) provides an alternative for maintenance therapy in eligible patients. Many patients require repeated treatment to maintain symptom control and reduce the risk of relapse, supporting continued demand for these medicines. Treatment requirements depend on disease severity, clinical response, patient weight, dosage, and treatment duration. Improved disease recognition and diagnosis also support demand by helping identify patients who require medical intervention. Physicians assess treatment response and tolerability to determine whether continued therapy or a change in treatment is appropriate. For instance, in March 2025, Takeda Canada Inc. announced that Health Canada had expanded the authorization for human immunoglobulin with recombinant human hyaluronidase for maintenance treatment of adults with CIDP following stabilization with IVIg. The treatment can be administered every 2, 3, or 4 weeks. In the Phase 3 ADVANCE-1 trial, relapse rates were 15.5% in the treatment group and 31.7% in the placebo group. This development supports the role of immunoglobulin therapies in ongoing disease management and expands maintenance treatment options.
High treatment costs limit access to CIDP therapies, particularly in healthcare systems with restricted reimbursement coverage. Intravenous immunoglobulin (IVIg) and subcutaneous immunoglobulin (SCIg) require repeated administration for many patients, increasing medicine expenses, clinical visits, infusion services, and monitoring costs. Total treatment expenses vary according to patient weight, dosage, administration frequency, disease severity, and treatment duration. These costs place pressure on patients and healthcare payers when long-term disease management is required. Access also depends on the availability of immunoglobulin products, specialist facilities, and trained healthcare professionals. In some regions, patients face delays in diagnosis and treatment because neurological services are concentrated in major healthcare centers. Differences in insurance coverage and public reimbursement further affect access to approved therapies. The cost of targeted medicines also influences prescribing decisions and payer coverage. Healthcare providers assess treatment response, safety, and disease progression to determine whether continued therapy is appropriate. Limited awareness of CIDP among healthcare professionals and patients can delay diagnosis and treatment initiation, increasing the risk of prolonged functional impairment. These factors restrict access to care, affect treatment continuity, and limit the number of patients receiving appropriate therapy. The financial burden associated with long-term treatment remains a constraint on market growth, particularly in countries with limited funding for rare neurological disorders and specialist care.
The development of targeted therapies provides an opportunity for the CIDP market by expanding treatment options for patients who require alternatives to established therapies. Traditional treatments, including IVIg, SCIg, corticosteroids, and plasma exchange, remain important, but treatment response and tolerability vary among patients. Targeted medicines act on specific components of the immune system and provide additional options for managing disease activity. Subcutaneous administration also offers flexibility for eligible patients by supporting treatment outside infusion centers. Pharmaceutical companies can expand access by obtaining approvals in additional countries and generating clinical evidence on treatment efficacy and safety. For instance, in June 2025, argenx SE announced that the European Commission had approved efgartigimod alfa for subcutaneous injection as monotherapy for adults with progressive or relapsing active CIDP following prior treatment with corticosteroids or immunoglobulins. In the ADHERE clinical trial, 214 of 322 patients (66.5%) receiving treatment showed clinical improvement, and treatment reduced the risk of relapse by 61% compared with placebo. This approval expanded treatment options for eligible patients in Europe and supports the development of targeted therapies within the CIDP market. Further opportunities depend on clinical outcomes, physician awareness, reimbursement coverage, and patient access.
Market Concentration & Characteristics
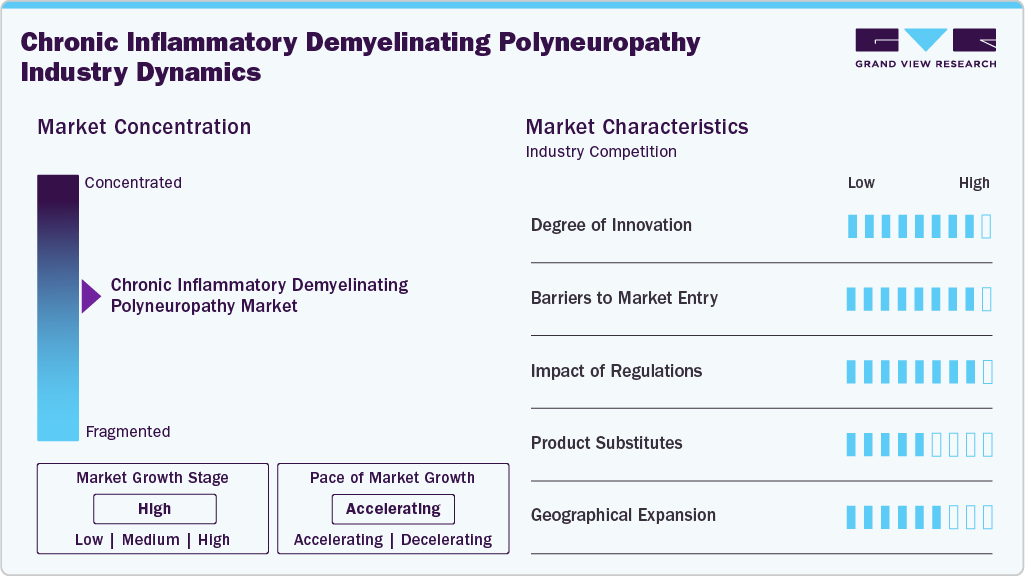
The degree of innovation in the CIDP market is high because pharmaceutical companies are developing targeted therapies and alternative treatment formulations to address patient needs. Established treatments, including intravenous immunoglobulin (IVIg), corticosteroids, and plasma exchange, remain important, while subcutaneous immunoglobulin provides an alternative for maintenance treatment. Targeted therapies acting on specific immune mechanisms have expanded treatment choices for eligible patients. Research also focuses on improving administration convenience, treatment response, and disease control. Clinical trials assess the safety and efficacy of new therapies and support regulatory submissions. Innovation in this market depends on clinical evidence, regulatory approval, and the ability to address limitations associated with existing treatments. Continued research into immune mechanisms and treatment delivery supports product development and competition among pharmaceutical companies.
Entry barriers in the CIDP market are high because new treatments require clinical development, regulatory approval, and evidence of safety and efficacy. Companies must conduct clinical trials to demonstrate treatment benefits in a rare neurological disorder with specific diagnostic and clinical requirements. Biologic therapies also require controlled manufacturing processes, quality assurance, and reliable product supply. Regulatory submissions involve detailed clinical and manufacturing documentation, increasing development costs and time. Established companies benefit from approved products, physician relationships, distribution networks, and experience in neurological and immunological treatments. New entrants must also establish reimbursement access and demonstrate the value of their products to healthcare providers and payers. These requirements limit entry for companies without relevant expertise, manufacturing capabilities, and financial resources. Partnerships and licensing agreements provide alternative routes into the market.
 To learn more about this report, Download Free Sample Report
Regulatory requirements have a high impact on the CIDP market because medicines must demonstrate safety, efficacy, and manufacturing quality before receiving approval. Regulatory agencies assess clinical trial results, product quality, dosage information, and safety risks before authorizing treatments. Changes to approved indications, administration methods, or patient eligibility also require regulatory review. These requirements affect the time and cost involved in developing and introducing new therapies. Post-marketing safety monitoring further influences product management and prescribing information. Regulatory decisions also affect competition by determining which treatments are available to patients in each country. Companies must comply with different national requirements and maintain product quality throughout manufacturing and distribution. Approval of targeted therapies and additional formulations can expand treatment choices, while regulatory delays can restrict product availability and market entry.
The CIDP market has a moderate level of product substitution because several treatment options are available, although their suitability varies by patient. IVIg, SCIg, corticosteroids, and plasma exchange are established options used according to clinical needs and treatment response. Targeted therapies provide additional alternatives for eligible patients, including those who require different treatment strategies. However, these treatments are not fully interchangeable because they differ in mechanisms of action, administration requirements, safety profiles, and clinical evidence. Physicians select treatments based on disease severity, previous response, patient preference, and reimbursement coverage. Switching therapies also requires clinical assessment and monitoring. The availability of multiple treatment options creates competition within the market, but differences in treatment indications and patient eligibility limit direct substitution across all products. These factors support a moderate classification.
Geographical expansion in the CIDP market is moderate because access to approved treatments varies across countries. North America and Europe have established regulatory systems and specialist neurological services that support access to immunoglobulin and targeted therapies. In other regions, treatment availability depends on healthcare infrastructure, reimbursement policies, diagnostic capacity, and access to trained neurologists. Pharmaceutical companies can expand geographically by obtaining national approvals, establishing distribution agreements, and working with healthcare providers and payers. However, high treatment costs and differences in public funding can limit access to therapies in some countries. Immunoglobulin supply and the availability of specialist treatment centers also affect expansion. Wider physician awareness and improvements in diagnostic services can support patient identification and treatment access. The rate of expansion therefore depends on regulatory approvals, affordability, product supply, and healthcare system capacity.
Analyst Perspective
The CIDP market is shaped by the use of immunoglobulin therapies, growing adoption of targeted biologics, and ongoing clinical research. Market growth depends on disease diagnosis rates, treatment access, reimbursement coverage, and annual therapy costs. Subcutaneous formulations offer an alternative to intravenous administration, while new clinical studies support treatment development. Companies focus on expanding product indications, improving treatment delivery, and assessing therapies that address patient needs across different healthcare markets.
Treatment Type Insights
The immunoglobulin therapy segment dominated the CIDP market with the largest market share of 76.9%, supported by established clinical use, evidence of treatment efficacy, and its role in improving neuromuscular function. Additional drivers include repeated treatment requirements, physician familiarity, availability of intravenous and subcutaneous formulations, and use in patients requiring long-term disease management. Immunoglobulin therapy also provides an established treatment option for patients whose symptoms require active control, while maintenance formulations support continued treatment after stabilization. Treatment selection depends on clinical response, tolerability, patient condition, and reimbursement coverage. Established manufacturing and distribution networks also support product availability across healthcare systems. Although treatment costs and supply constraints affect access, immunoglobulin therapy remains central to CIDP management. These factors support its leading market position, while improvements in administration options help maintain demand among eligible patients.
The targeted biologic therapy segment is projected to register the fastest CAGR of 20.5%, driven by demand for additional treatment options, new mechanisms of action, and treatment choices for patients who do not respond adequately to established therapies. Targeted biologics act on specific immune mechanisms involved in CIDP and support treatment approaches beyond conventional immunoglobulin therapy. Growth is also supported by clinical research, regulatory approvals, and the development of subcutaneous formulations that offer greater flexibility in administration. Pharmaceutical companies are investing in clinical studies to assess treatment response, safety, and relapse prevention. For instance, in November 2025, argenx Canada Inc. announced that Health Canada authorized efgartigimod alfa as monotherapy for adults with active CIDP, including administration through a prefilled syringe for self-injection. This authorization expanded access to a targeted treatment option in Canada and supports further development of the segment.
Route of Administration Insights
The intravenous segment dominated the CIDP market with the largest market share of 80.6%, supported by established clinical use, physician familiarity, and evidence of efficacy in managing disease symptoms. Additional drivers include its role in initial treatment, use in patients requiring active disease control, established dosing protocols, availability through specialist healthcare facilities, and extensive clinical experience. Intravenous immunoglobulin (IVIg) is used to improve symptoms and help manage disease activity. Hospital and infusion-center infrastructure supports administration and patient monitoring, while established prescribing practices contribute to continued demand. Treatment selection depends on disease severity, clinical response, safety, and reimbursement coverage. Although intravenous administration requires healthcare resources and regular patient visits, its established role in CIDP treatment supports its leading position. Continued product availability and clinical use help maintain demand across healthcare systems.
The subcutaneous segment is projected to register the fastest CAGR of 14.9%, driven by demand for flexible administration, reduced dependence on intravenous infusion facilities, and options for ongoing treatment outside hospitals. Subcutaneous immunoglobulin and targeted biologic therapies support different treatment needs and offer alternatives for eligible patients. Growth is also supported by home administration after appropriate training, fewer travel requirements, and treatment schedules that fit patients' daily routines. Pharmaceutical companies are developing delivery devices and formulations to improve ease of use and support treatment continuity. Subcutaneous administration can reduce the need for repeated visits to infusion centers, supporting patient convenience and continuity of care. Adoption depends on clinical suitability, physician recommendations, reimbursement coverage, product availability, and patient preference. These factors support the segment's growth as healthcare providers expand access to maintenance treatment options for eligible CIDP patients.
Patient Type Insights
The adult patients segment dominated the CIDP market with the largest revenue share of 90.8%, supported by the greater representation of adults in diagnosed CIDP populations and the established use of immunoglobulin therapies in adult disease management. Additional drivers include the need for long-term symptom control, established clinical treatment protocols, specialist experience in adult neurology, and access to approved therapies. Adults also account for a broad range of treatment needs associated with disease progression, relapse prevention, and maintaining daily functioning. The availability of intravenous immunoglobulin, subcutaneous immunoglobulin, corticosteroids, and targeted therapies supports treatment selection according to clinical response and patient condition. Established diagnostic practices and access to specialist care also contribute to treatment demand. Reimbursement coverage and medicine availability influence access across countries. These factors support the dominant position of adult patients in the CIDP market.
The pediatric patients segment is projected to register the fastest CAGR of 11.0%, supported by improvements in disease recognition, access to specialist neurological assessment, and greater attention to treatment needs among children with CIDP. Although pediatric CIDP is less common than adult CIDP, affected children require timely diagnosis and appropriate treatment to manage weakness, mobility difficulties, and functional limitations. Growth is supported by clinical assessment methods that help distinguish CIDP from other childhood neurological disorders, alongside the use of immunoglobulin therapy in suitable patients. Greater awareness among pediatric neurologists and access to specialized care also support patient identification. Research into pediatric disease characteristics and treatment response can help inform clinical decisions. However, limited pediatric-specific clinical evidence, differences in treatment response, and access to specialist services affect treatment decisions. Continued improvements in diagnosis and access to appropriate therapies support the development of this segment.
Distribution Channel Insights
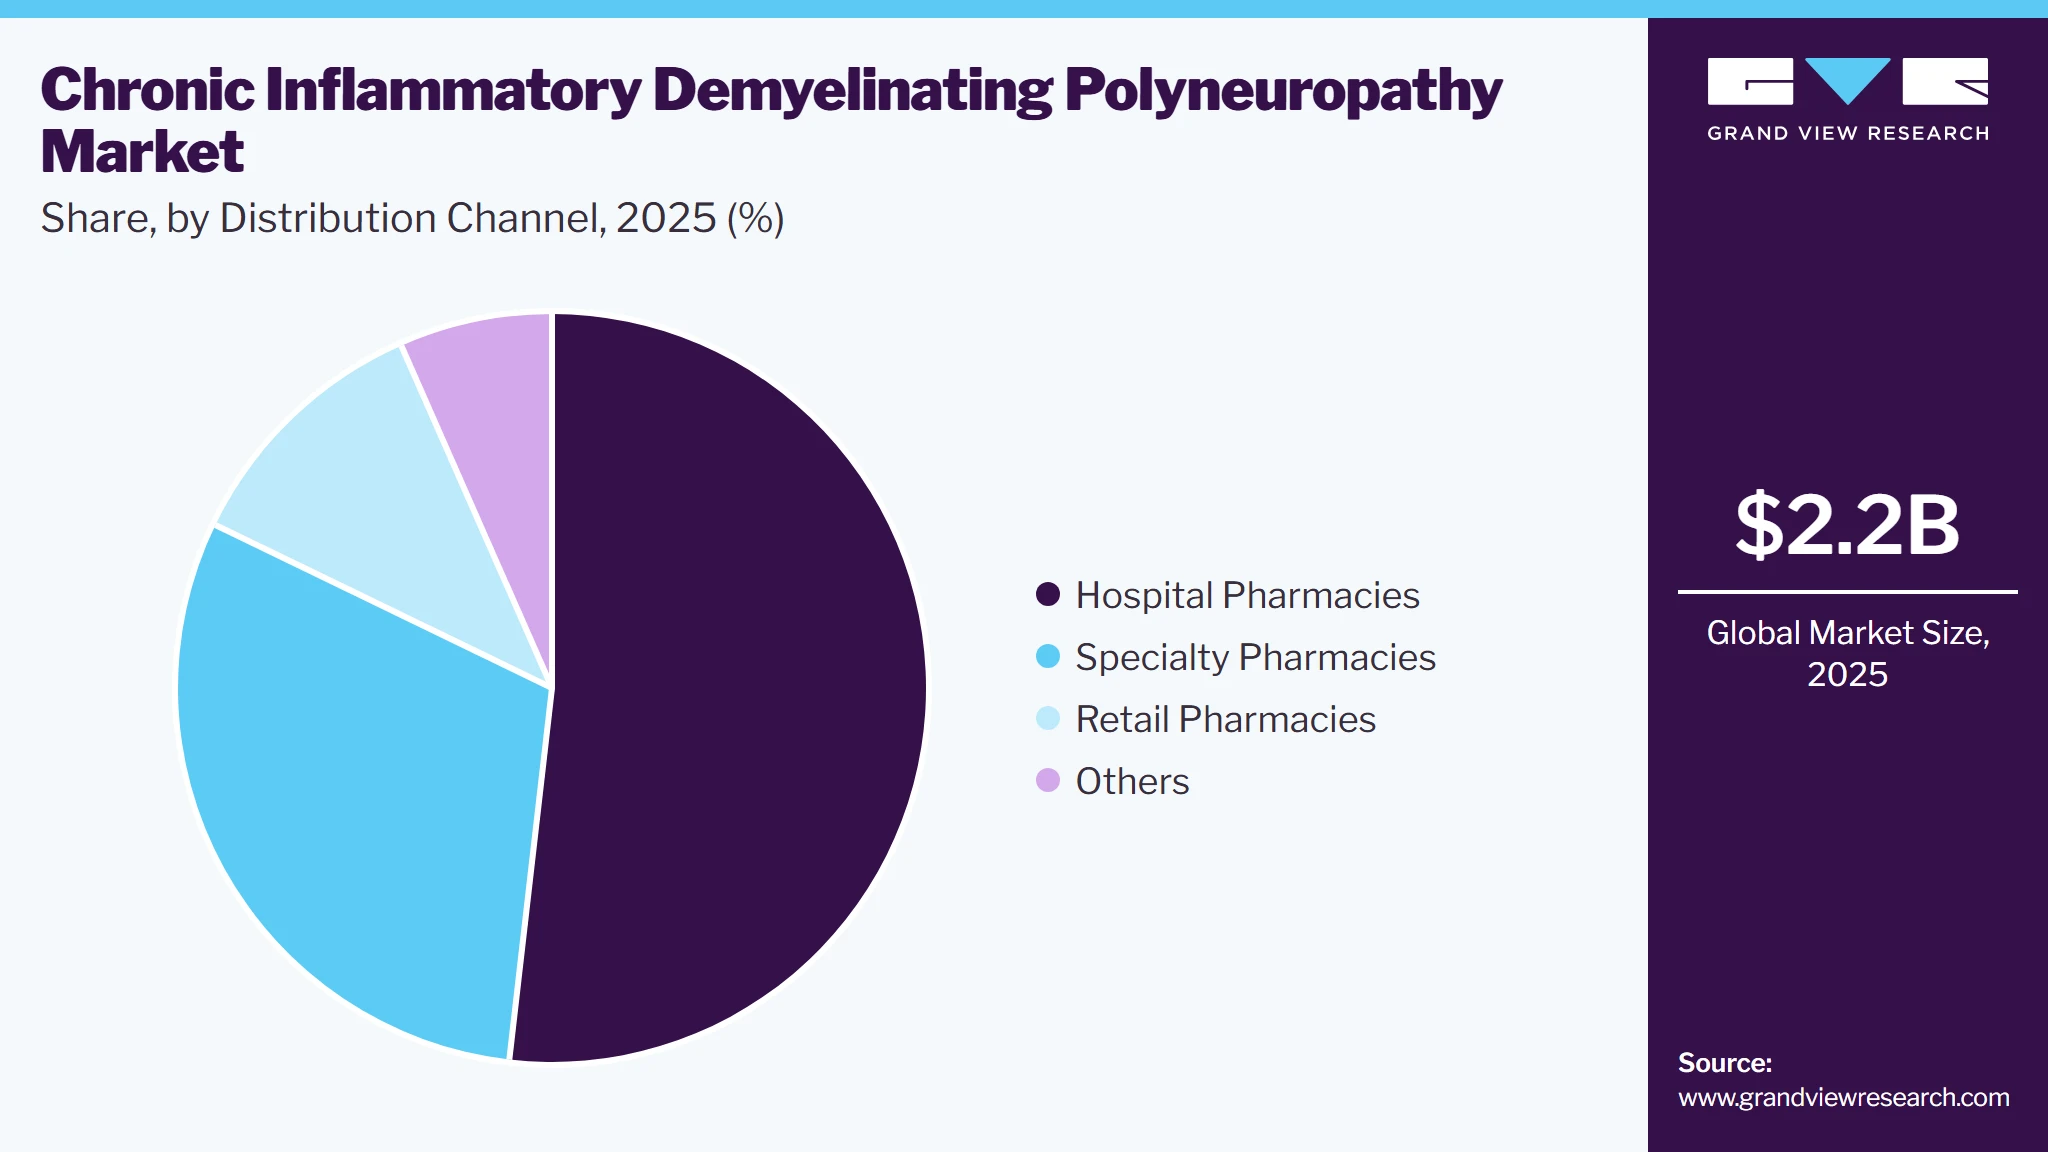
The hospital pharmacies segment dominated the CIDP market with the largest market share of 51.8%, supported by the need for supervised treatment, specialist involvement, and access to intravenous immunoglobulin (IVIg). Hospitals provide facilities for infusion administration, patient monitoring, and management of treatment-related reactions. Additional drivers include established procurement systems, coordination between neurologists and pharmacy departments, access to prescribed biologics, and reimbursement procedures linked to hospital-based care. Patients requiring initial treatment or assessment of disease response often receive medicines through hospital services. Hospital pharmacies also support the storage and handling requirements of immunoglobulin products and coordinate medicine supply with clinical teams. These factors maintain the role of hospital pharmacies in CIDP treatment distribution. Demand depends on treatment protocols, hospital infrastructure, product availability, and payer coverage across healthcare systems.
 To learn more about this report, Download Free Sample Report
The specialty pharmacies segment is projected to register the fastest CAGR of 11.2%, driven by demand for coordinated medicine access, patient support services, and treatment management for chronic neurological conditions. Specialty pharmacies help arrange prescription fulfillment, medicine delivery, adherence support, and coordination with healthcare providers. Their role is relevant for patients receiving subcutaneous immunoglobulin or targeted therapies that require ongoing treatment and monitoring. Growth is also supported by home-based treatment options, patient education, and assistance with insurance authorization and reimbursement processes. Specialty pharmacies can help patients manage repeat prescriptions and reduce administrative barriers to treatment access. Their ability to coordinate with prescribers and payers supports continuity of care for eligible patients. Expansion depends on distribution networks, reimbursement policies, product handling requirements, and access to specialty pharmacy services across regions.
Regional Insights
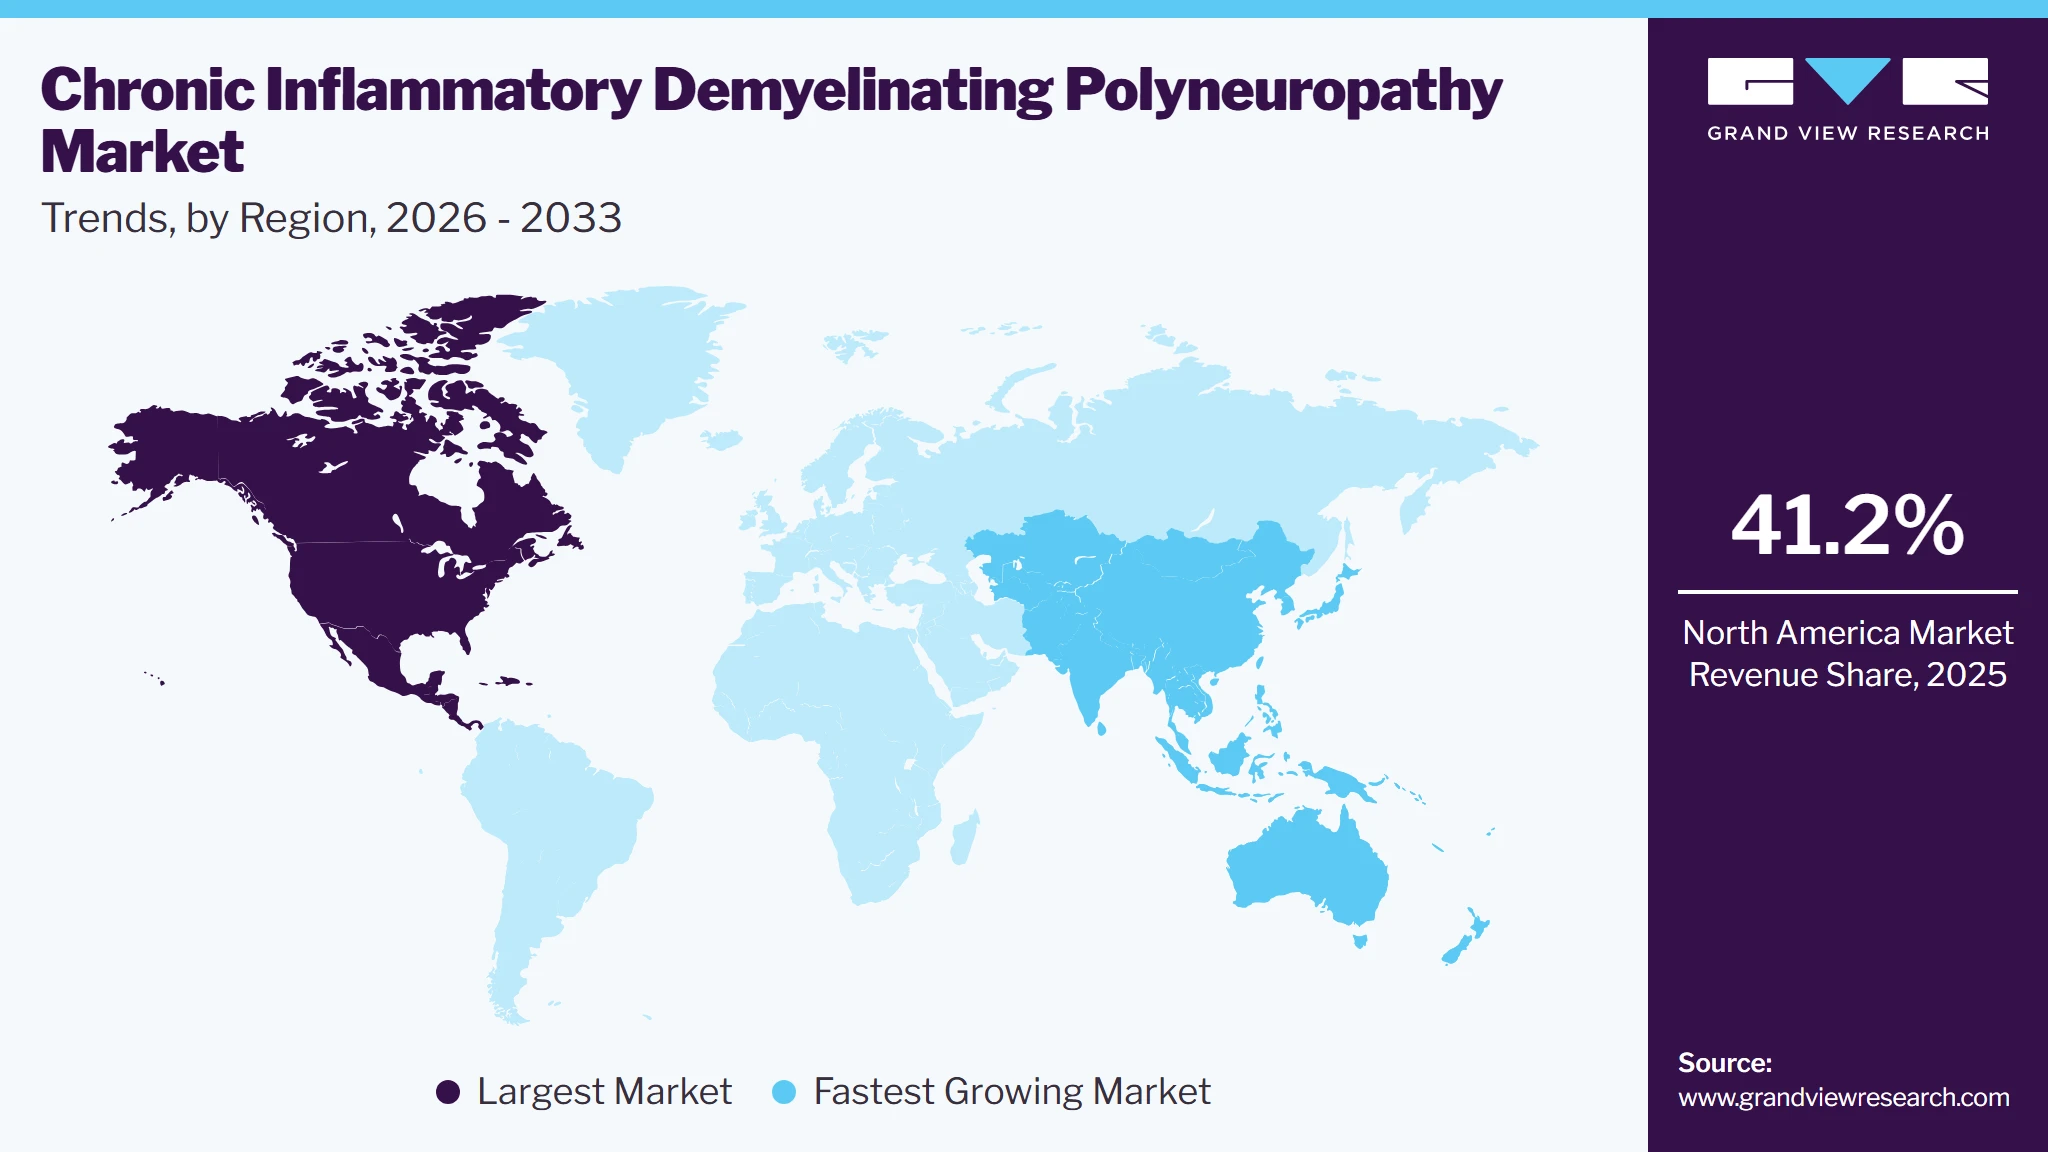
North America dominated the CIDP market with a market share of 41.2% in 2025, supported by access to immunoglobulin therapies and targeted biologics. Established neurological care services support disease diagnosis and treatment. The presence of pharmaceutical companies developing CIDP therapies contributes to product availability. Specialist clinics and infusion centers support the administration of intravenous immunoglobulin and other treatments. Insurance coverage and established treatment protocols influence patient access to approved medicines. Continued research and clinical trial activity also support the development of treatment options.
 To learn more about this report, Download Free Sample Report
U.S. Chronic Inflammatory Demyelinating Polyneuropathy Market Trends
The United States is a key contributor to the North American CIDP market due to the availability of approved immunoglobulin products and targeted therapies. Access to neurologists and specialized treatment centers supports diagnosis and disease management. Established clinical practices contribute to the use of intravenous and subcutaneous immunoglobulin. Pharmaceutical companies continue to develop treatments that address different patient needs. Insurance coverage and specialty pharmacy services influence access to long-term therapies. Clinical research also supports the evaluation of treatment safety, efficacy, and administration options.
Europe Chronic Inflammatory Demyelinating Polyneuropathy Market Trends
Europe represents a major regional market for CIDP, supported by established neurology services and access to immunoglobulin treatments. The availability of approved therapies supports treatment selection for eligible patients. Specialist hospitals and neurological clinics contribute to disease recognition and ongoing care. Clinical research and pharmaceutical development support the introduction of additional treatment options. Differences in reimbursement policies and healthcare access influence treatment availability across countries. Demand is also linked to long-term disease management and the need to maintain mobility and daily functioning.
The United Kingdom CIDP market is supported by specialist neurological services and established use of immunoglobulin therapy. Neurologists assess symptoms, nerve conduction studies, and other clinical findings to distinguish CIDP from similar neurological disorders. Access to intravenous immunoglobulin supports treatment for eligible patients. Subcutaneous treatment options provide additional flexibility for maintenance care. Clinical research helps improve understanding of disease presentation and treatment response. Access to specialist services, medicine availability, and local treatment protocols influence the number of patients receiving therapy.
Germany's CIDP market benefits from established hospital infrastructure, specialist neurology services, and access to immunoglobulin treatments. Neurological assessment and diagnostic testing support the identification of patients requiring treatment. Hospitals and infusion facilities provide services for intravenous immunoglobulin administration and monitoring. Access to approved therapies supports treatment selection according to clinical needs. Pharmaceutical research contributes to the availability of additional treatment options. Reimbursement arrangements, treatment costs, and access to specialist care influence the use of medicines across the country.
France's CIDP market is supported by specialist neurological care and access to established immunoglobulin therapies. Neurologists use clinical examinations and diagnostic tests to assess disease progression and guide treatment decisions. Hospital-based services support intravenous treatment and patient monitoring. Subcutaneous immunoglobulin provides an additional maintenance option for eligible patients. Pharmaceutical research and clinical studies contribute to the development of treatment alternatives. Medicine access, reimbursement arrangements, and the availability of specialist services influence treatment continuity across the country.
Asia-Pacific Chronic Inflammatory Demyelinating Polyneuropathy Market Trends
Asia Pacific is projected to register the fastest CAGR of 9.5% in the CIDP market, supported by improvements in neurological diagnosis and wider access to specialist care. Growing awareness of rare neurological disorders supports patient identification. Expansion of hospital services increases access to immunoglobulin treatment in selected markets. Pharmaceutical companies are working to expand the availability of approved therapies across the region. Differences in healthcare infrastructure, reimbursement coverage, and medicine affordability influence treatment access. Further market development depends on diagnostic capacity, product availability, and access to long-term neurological care.
Japan's CIDP market is supported by established neurological services and access to immunoglobulin-based treatment. Specialist assessment helps identify patients with progressive weakness, sensory changes, and reduced reflexes. Hospital infrastructure supports treatment administration and clinical monitoring. Continued disease management contributes to demand for maintenance therapies. Pharmaceutical research and clinical evaluation support the use of additional treatment options. Patient access depends on diagnosis, treatment availability, reimbursement conditions, and the ability to receive ongoing specialist care.
China's CIDP market is supported by improvements in neurological assessment and increased attention to rare peripheral nerve disorders. Access to specialist hospitals contributes to diagnosis and treatment planning. Immunoglobulin therapies remain important for patients requiring disease control. Expansion of clinical research supports the evaluation of treatment efficacy and safety. Pharmaceutical manufacturing and distribution capabilities influence the availability of medicines across healthcare facilities. Differences in diagnostic access, treatment costs, and specialist availability continue to affect patient access across regions.
Latin America Chronic Inflammatory Demyelinating Polyneuropathy Market Trends
The Latin American CIDP market is influenced by access to specialist neurological services and the availability of immunoglobulin therapies. Large urban hospitals provide diagnostic testing and treatment for patients with suspected CIDP. Demand is associated with the need for long-term disease control and prevention of functional decline. Access to intravenous immunoglobulin varies according to healthcare infrastructure and reimbursement arrangements. Limited specialist availability in some areas can delay diagnosis and treatment. Market development depends on medicine affordability, product distribution, and access to trained neurologists.
Brazil's CIDP market is supported by specialist neurological services in major cities and the use of immunoglobulin therapies for disease management. Clinical assessment and nerve conduction studies help support diagnosis. Hospital-based treatment facilities provide access to intravenous immunoglobulin and patient monitoring. Demand is influenced by the need to manage chronic symptoms and maintain physical function. Access to medicines varies across regions according to healthcare resources and reimbursement arrangements. Greater diagnostic awareness and improved access to specialist treatment can support patient identification and continuity of care.
Middle East & Africa Chronic Inflammatory Demyelinating Polyneuropathy Market Trends
The MEA CIDP market is influenced by differences in neurological care infrastructure, medicine access, and specialist availability across countries. Major urban healthcare centers provide diagnostic services and treatment for eligible patients. Immunoglobulin therapy remains an important option for disease management where products are available. Demand is linked to the need for timely diagnosis and continued treatment. High medicine costs and limited access to specialist services restrict treatment in some areas. Market development depends on diagnostic capacity, distribution networks, and access to approved therapies.
Saudi Arabia's CIDP market is supported by specialist hospitals, neurological services, and access to immunoglobulin treatment. Clinical evaluation and diagnostic testing help identify patients who require disease management. Hospital-based services support infusion administration and monitoring. Demand is influenced by the need to control symptoms and maintain mobility among patients requiring long-term care. Access to targeted therapies and subcutaneous formulations can expand treatment choices for eligible patients. Medicine availability, treatment costs, reimbursement arrangements, and access to trained neurologists influence market development across the country.
Key Chronic Inflammatory Demyelinating Polyneuropathy Company Insights
The Chronic Inflammatory Demyelinating Polyneuropathy (CIDP) market is competitive, with established immunoglobulin manufacturers and companies developing targeted therapies. CSL Behring LLC, Takeda Pharmaceutical Company Limited, Octapharma AG, and Grifols, S.A. maintain positions through immunoglobulin products used in CIDP treatment. argenx SE is expanding its presence through targeted biologic therapy, providing an additional treatment option for eligible patients. Kedrion S.p.A., ADMA Biologics, Inc., Biotest AG, LFB S.A., and GC Biopharma Corp. contribute through plasma-derived therapies and immunoglobulin products. Competition depends on product approvals, clinical evidence, manufacturing capacity, distribution networks, treatment costs, and reimbursement coverage. Companies focus on product availability, treatment access, and therapy development to address patient needs across regional markets and healthcare systems.
Key Chronic Inflammatory Demyelinating Polyneuropathy Companies
-
CSL Behring LLC
-
Takeda Pharmaceutical Company Limited
-
Octapharma AG
-
Grifols, S.A.
-
argenx SE
-
Kedrion S.p.A.
-
ADMA Biologics, Inc.
-
Biotest AG
-
LFB S.A.
-
GC Biopharma Corp.
Competitive Benchmarking
Operating Strategies
Competitive Edge
Weaknesses
Mature Players
- Octapharma AG.
- Player 2
- Player 3
- Player 4
- Player 5
- Mature players maintain and expand portfolios of immunoglobulin therapies and targeted biologic treatments to address different CIDP treatment requirements.
- Companies invest in clinical research to assess treatment efficacy, safety, dosing schedules, and administration methods..
- Companies focus on manufacturing capacity, plasma collection, product quality, and distribution networks to maintain the supply of therapies used in ongoing CIDP treatment.
- Mature players have approved therapies and clinical evidence supporting their use in CIDP management.
- Experience in plasma collection, fractionation, biologics production, and quality control supports product supply and regulatory compliance.
- Existing distribution networks and relationships with neurologists, hospitals, specialty pharmacies, and payers support product access across regional markets.
- Immunoglobulin therapies and targeted biologics involve substantial treatment costs, which can affect affordability and reimbursement access.
- Product approvals, manufacturing standards, safety monitoring, and post-approval obligations require sustained investment and operational resources.
Emerging Players
- Kedrion S.p.A
- Player 2
- Player 3
- Player 4
- Player 5
- Emerging and expanding players work to increase product availability across additional countries and healthcare channels.
- This includes obtaining regulatory approvals, developing distribution partnerships, and meeting local market requirements.
- Companies invest in production capacity, process efficiency, and quality systems to support immunoglobulin supply and address demand from hospitals and specialty treatment centers.
- Several players have experience in plasma collection, fractionation, and immunoglobulin production, providing relevant capabilities for CIDP treatment.
- Existing manufacturing facilities and quality systems support the supply of plasma-derived therapies and provide a base for expanding output.
- Established operations in selected countries and relationships with local distributors support access to regional markets and healthcare providers.
- Limited distribution coverage or fewer established relationships with healthcare providers and payers can restrict access in some markets.
- Companies compete with established immunoglobulin suppliers and targeted biologic therapies on clinical evidence, product availability, pricing, and reimbursement.
Recent Developments
-
In July 2026, Grifols, S.A. initiated its Phase 3 XPERT study by dosing the first patients to evaluate subcutaneous immunoglobulin XEMBIFY against intravenous immunoglobulin GAMUNEX-C as maintenance therapy for CIDP, supporting the assessment of subcutaneous treatment as an alternative to intravenous administration.
-
In March 2026, argenx SE announced plans to present additional CIDP evidence at the American Academy of Neurology annual meeting, including biomarker analyses, real-world evidence, and post-hoc analyses of efgartigimod, while continuing Phase 3 development of empasiprubart for CIDP.
-
In July 2025, Takeda Pharmaceutical Company Limited received U.S. FDA 510(k) clearance for its HyHub and HyHub Duo devices, which simplify HYQVIA infusion preparation by reducing the steps required to transfer the product from vials, supporting home-infusion administration for patients with CIDP.
Chronic Inflammatory Demyelinating Polyneuropathy Market Report Scope
Report Attribute
Details
Market size in 2025
USD 2.2 billion
Estimated market size in 2026
USD 2.3 billion
Projected market size by 2033
USD 3.8 billion
Growth rate
CAGR of 7.6% from 2026 to 2033
Base year for estimation
2025
Historical data
2021 - 2024
Forecast period
2026 - 2033
Quantitative units
Revenue in USD billion and CAGR from 2026 to 2033
Report coverage
Revenue forecast, company ranking, competitive landscape, growth factors, trends
Segments covered
Treatment type, route of administration, patient type, distribution channel and region
Regional scope
North America; Europe; Asia Pacific; Latin America; Middle East & Africa
Country scope
U.S., Canada, Mexico, UK, Germany, France, Italy, Spain, Denmark, Sweden, Norway, China, Japan, India, Australia, South Korea, Thailand, Brazil, Argentina, South Africa, Saudi Arabia, UAE, Kuwait
Key company profiled
CSL Behring LLC, Takeda, Octapharma, Grifols, argenx, Kedrion, ADMA Biologics, Biotest, LFB, GC Biopharma
Customization scope
Free report customization (equivalent up to 8 analysts working days) with purchase. Addition or alteration to country, regional & segment scope.
Pricing and purchase options
Avail customized purchase options to meet your exact research needs. Explore purchase options
Global Chronic Inflammatory Demyelinating Polyneuropathy Market Report Segmentation
This report forecasts revenue growth at global, regional, and country levels and provides an analysis of the latest industry trends in each of the sub-segments from 2021 to 2033. For this study, Grand View Research has segmented the global chronic inflammatory demyelinating polyneuropathy market report based on treatment type, route of administration, patient type, distribution channel, and region:
-
Treatment Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Immunoglobulin Therapy
-
Corticosteroid Therapy
-
Immunosuppressive & Immunomodulatory Therapy
-
Targeted Biologic Therapy
-
Others
-
-
Route of Administration Outlook (Revenue, USD Million, 2021 - 2033)
-
Intravenous
-
Subcutaneous
-
Oral
-
Others
-
-
Patient Type Outlook (Revenue, USD Million, 2021 - 2033)
-
Adult Patients
-
Pediatric Patients
-
-
Distribution Channel Outlook (Revenue, USD Million, 2021 - 2033)
-
Hospital Pharmacies
-
Specialty Pharmacies
-
Retail Pharmacies
-
Others
-
-
Regional Outlook (Revenue, USD Million, 2021 - 2033)
-
North America
-
U.S.
-
Canada
-
Mexico
-
-
Europe
-
UK
-
Germany
-
France
-
Italy
-
Spain
-
Denmark
-
Sweden
-
Norway
-
-
Asia Pacific
-
Japan
-
China
-
India
-
Australia
-
South Korea
-
Thailand
-
-
Latin America
-
Brazil
-
Argentina
-
-
Middle East & Africa
-
South Africa
-
Saudi Arabia
-
UAE
-
Kuwait
-
-
Research Methodology
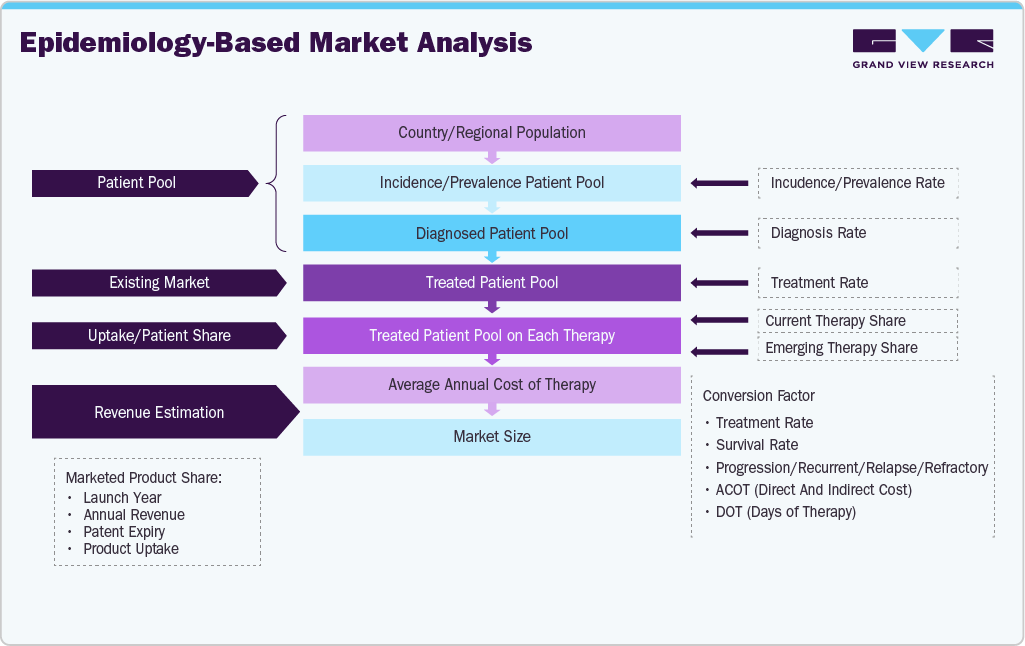
The chronic inflammatory demyelinating polyneuropathy market figures in this report are based on a proven research process that combines executive interviews with secondary research from proprietary databases, company filings, and recognized regulatory and institutional sources. Market size is built through value-chain sizing - reconciling supply-side and demand-side estimates - and triangulated with bottom-up and top-down approaches. Every estimate passes multiple levels of expert validation before publication, with each chronic inflammatory demyelinating polyneuropathy segment quantified using the revenue-capture definitions in the table below.
Segment Definition
Segment - Treatment Type
Revenue capture definition
Immunoglobulin Therapy
Includes immunoglobulin products used to treat CIDP by modulating immune activity. This segment covers intravenous immunoglobulin (IVIg) and subcutaneous immunoglobulin (SCIg) therapies, classified by therapeutic type regardless of administration route.
Corticosteroid Therapy
Includes corticosteroid drugs prescribed for CIDP to reduce inflammation and suppress immune activity. This segment covers oral and injectable corticosteroids used in CIDP treatment, classified by therapeutic type regardless of administration route.
Immunosuppressive & Immunomodulatory Therapy
Includes non-corticosteroid and non-immunoglobulin drugs used to suppress or modify immune activity in CIDP. This segment covers immunosuppressive and immunomodulatory medicines, excluding targeted biologic therapies classified separately.
Targeted Biologic Therapy
Includes biologic drugs designed to act on specific immune targets involved in CIDP. This segment covers targeted biologic treatments approved for CIDP, including FcRn-targeting therapies, classified by therapeutic type rather than administration route.
Others
Includes plasma exchange and other treatment modalities used to manage CIDP that are not classified under immunoglobulin therapy, corticosteroid therapy, immunosuppressive and immunomodulatory therapy, or targeted biologic therapy.
Segment - Route of Administration
Revenue capture definition
Intravenous
Includes CIDP drug therapies administered directly into a vein through infusion or injection. This segment covers intravenous immunoglobulin, intravenous corticosteroids, and other eligible drugs administered through this route.
Subcutaneous
Includes CIDP drug therapies administered by injection into the tissue beneath the skin. This segment covers subcutaneous immunoglobulin and targeted biologic therapies administered through this route, including doses administered by patients or healthcare professionals.
Oral
Includes CIDP drug therapies administered by mouth as tablets, capsules, or oral liquids. This segment covers oral corticosteroids, immunosuppressive drugs, and other eligible oral therapies used for CIDP treatment.
Others
Includes CIDP drug therapies administered through intramuscular injection and other applicable administration routes used in CIDP treatment that are not classified under intravenous, subcutaneous, or oral administration.
Segment - Patient Type
Revenue capture definition
Adult Patients
Includes patients aged 18 years and older diagnosed with CIDP and receiving treatment during the reporting period. This segment covers treated patients across all therapy types and administration routes.
Pediatric Patients
Includes patients younger than 18 years diagnosed with CIDP and receiving treatment during the reporting period. This segment covers treated patients across all therapy types and administration routes.
Segment - Distribution Channel
Revenue capture definition
Hospital Pharmacies
Includes CIDP therapies dispensed through pharmacies operated by hospitals or their pharmacy departments. This segment covers medicines supplied for inpatient and outpatient treatment when the hospital pharmacy dispenses the product.
Specialty Pharmacies
Includes CIDP therapies dispensed through pharmacies that manage specialty medicines requiring specific handling, patient support, treatment coordination, or reimbursement assistance. This segment covers specialty medicines supplied to patients for home administration or treatment at healthcare facilities.
Retail Pharmacies
Includes CIDP therapies dispensed through community or chain retail pharmacies that fill prescriptions for patients. This segment covers medicines supplied through retail pharmacy outlets.
Others
Includes CIDP therapies supplied through direct-to-patient distribution programs, home delivery services operated outside hospital, specialty, or retail pharmacy channels, and other non-pharmacy distribution arrangements used to supply treatment to patients.
Estimation Model
 To learn more about this report, Download Free Sample Report
Delivered Customizations
This report has been delivered with the following In-depth customizations
Client Request
Customization Delivered
Value Adds
CIDP Treatmeant Market Assessment and Growth Opportunity Analysis
Conducted a detailed assessment of the CIDP treatment market, focusing on disease prevalence, diagnosis rates, treated patient populations, and treatment patterns across key countries. The study assessed immunoglobulin therapies, corticosteroids, immunosuppressive and immunomodulatory therapies, and targeted biologic therapies. It also examined treatment costs, administration routes, reimbursement policies, and patient access to CIDP therapies.
Helped the client assess market opportunities by identifying patient population trends, treatment adoption patterns, and revenue potential across therapy categories. The study supported pricing and market entry decisions by examining treatment costs, reimbursement coverage, unmet treatment needs, and differences in access to CIDP therapies across countries.
CIDP Therapeutic Pipeline and Competitive Benchmarking
Delivered a competitive assessment of established CIDP treatments and emerging therapies in clinical development. The study reviewed product approvals, clinical trial progress, efficacy and safety findings, regulatory milestones, product formulations, and administration routes. It also assessed company portfolios, research and development activities, strategic collaborations, licensing agreements, and product positioning across the CIDP treatment market.
Enabled the client to assess pipeline opportunities, benchmark competing therapies, and identify potential areas for product development and partnerships. The analysis supported investment prioritization by examining clinical progress, treatment differentiation, regulatory developments, and opportunities to address limitations associated with existing CIDP therapies.
CIDP Market Access, Pricing, and Treatment Infrastructure Assessment
Conducted a country-level assessment of CIDP diagnosis, treatment access, and healthcare infrastructure across selected markets. The study examined neurologist availability, diagnostic capabilities, immunoglobulin supply, access to targeted biologic therapies, treatment costs, reimbursement policies, and healthcare funding. It also assessed differences in patient access, distribution networks, and treatment availability across developed and emerging healthcare markets.
Supported market planning by identifying access barriers, reimbursement differences, and opportunities to improve treatment availability. The analysis helped the client evaluate country-level expansion opportunities, assess pricing and reimbursement requirements, and prioritize markets based on diagnosed patient populations, treatment access, healthcare infrastructure, and demand for CIDP therapies.
About the Author(s)
Pharmaceuticals Research Team
Healthcare · PharmaceuticalsThis report was authored by the pharmaceuticals research team at Grand View Research - comprising two research analysts, one senior research analyst, and one industry expert - with specialized expertise in the pharmaceuticals segment of the healthcare industry. All findings are based on proprietary healthcare databases, executive interviews, and regulatory analysis, subject to internal peer review prior to publication.
Last Updated:
Speak to Analyst

Customize this report to your needs - add regions, segments, or data points, with 20% free customization.
Or view our licence options:


ISO 9001:2015 & 27001:2022 Certified
We are GDPR and CCPA compliant! Your transaction & personal information is safe and secure. For more details, please read our privacy policy.


